
- Home
- »
- Medical Devices
- »
-
Orthopedic Navigation Systems Market Size Report, 2033GVR Report cover

Orthopedic Navigation Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Knee, Hip, Spine), By Technology (Electromagnetic, Optical), By End-use (Hospitals, Ambulatory Surgical Centers), By Region, And Segment Forecasts
Market Size, 2025
$2.9BMarket Estimate, 2026
$3.3BMarket Forecast, 2033
$7.8BCAGR, 2026–2033
13.6%Orthopedic Navigation Systems Market Summary
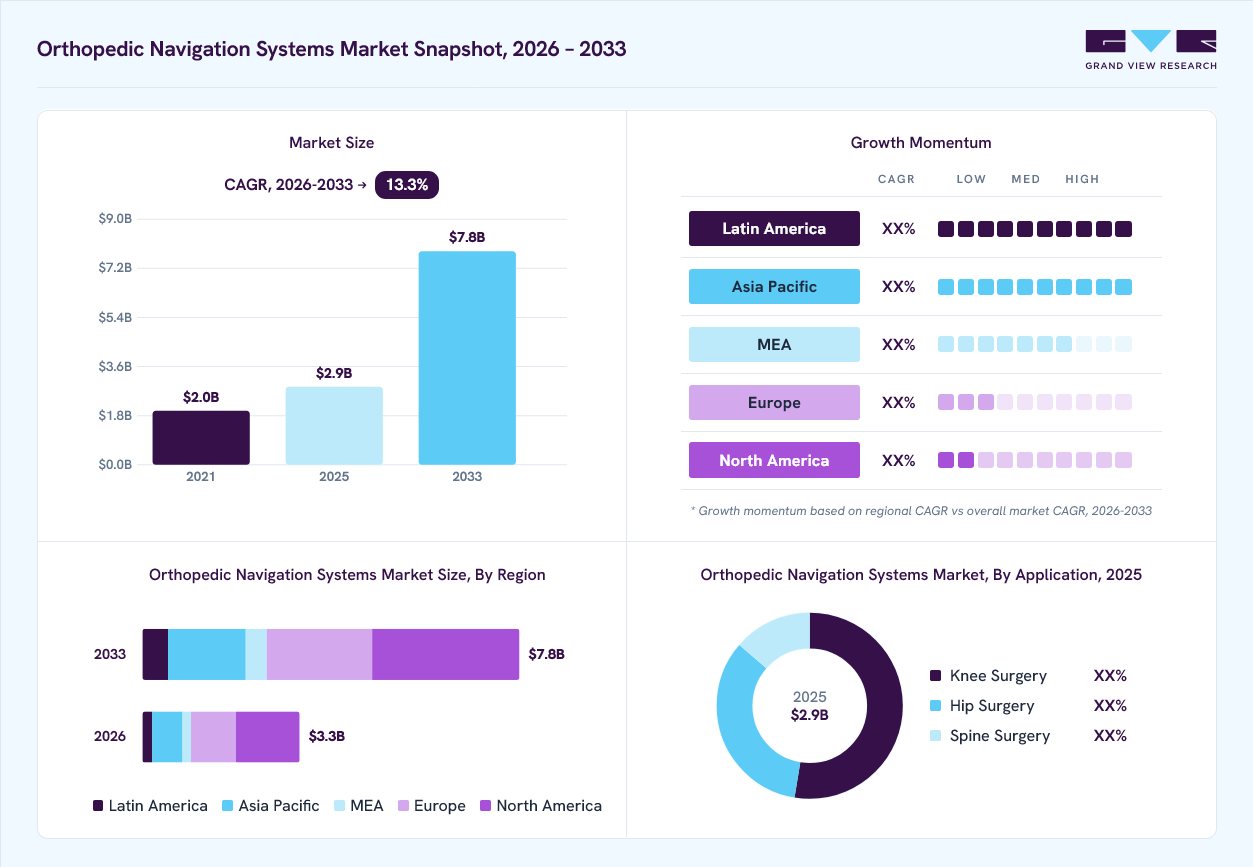
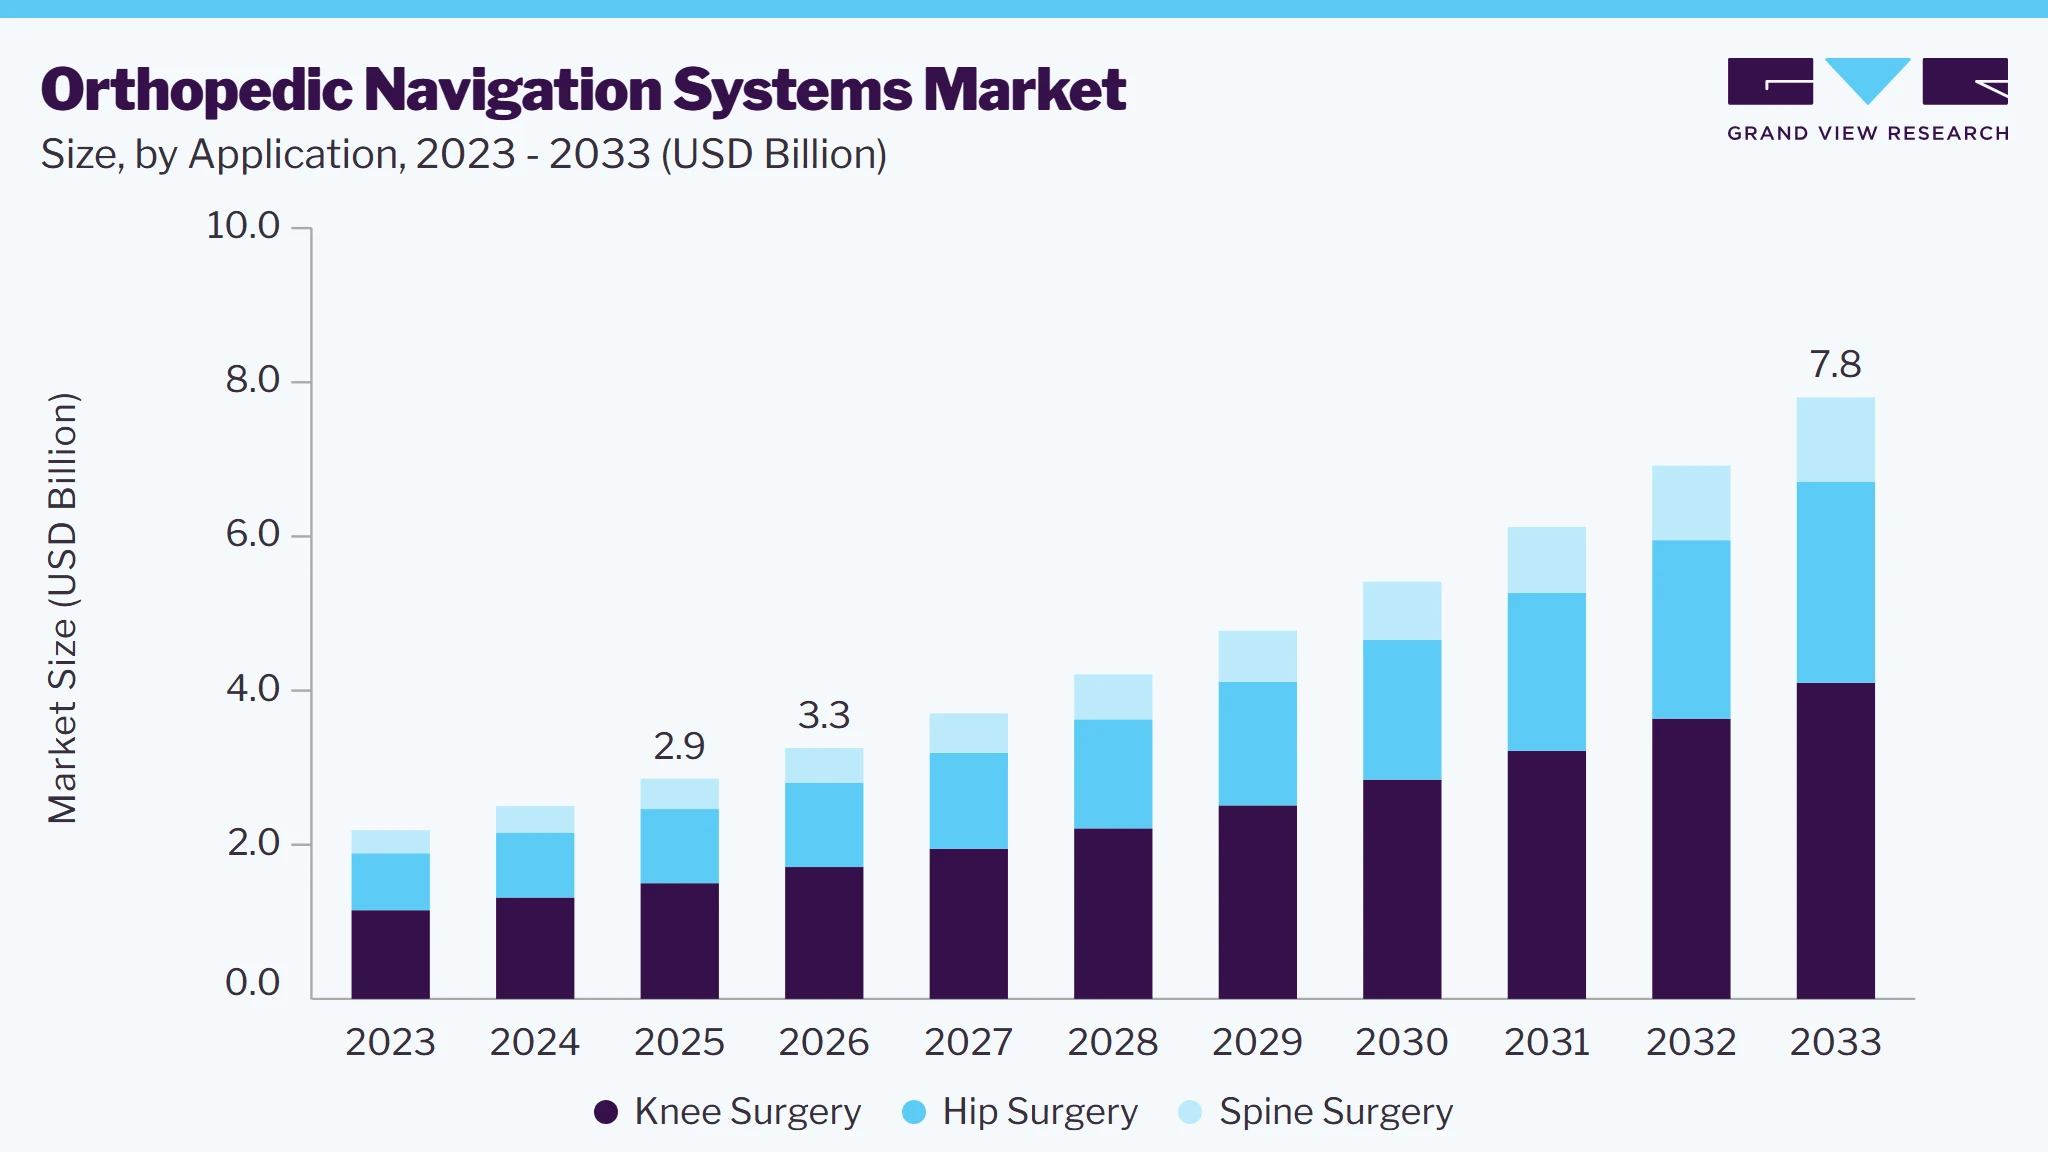
The global orthopedic navigation systems market size was valued at USD 2.9 billion in 2025 and is projected to grow from USD 3.3 billion in 2026 to USD 7.8 billion by 2033, at a CAGR of 13.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 44.2% in 2025. The market growth is primarily driven by increased adoption of minimally invasive surgeries, technological advancements, initiatives by key market players, and a high prevalence of orthopedic disorders.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Knee surgery held the largest revenue share of 52.6% in 2025
- By technology: Optical segment held the largest revenue share of 41.7% in 2025
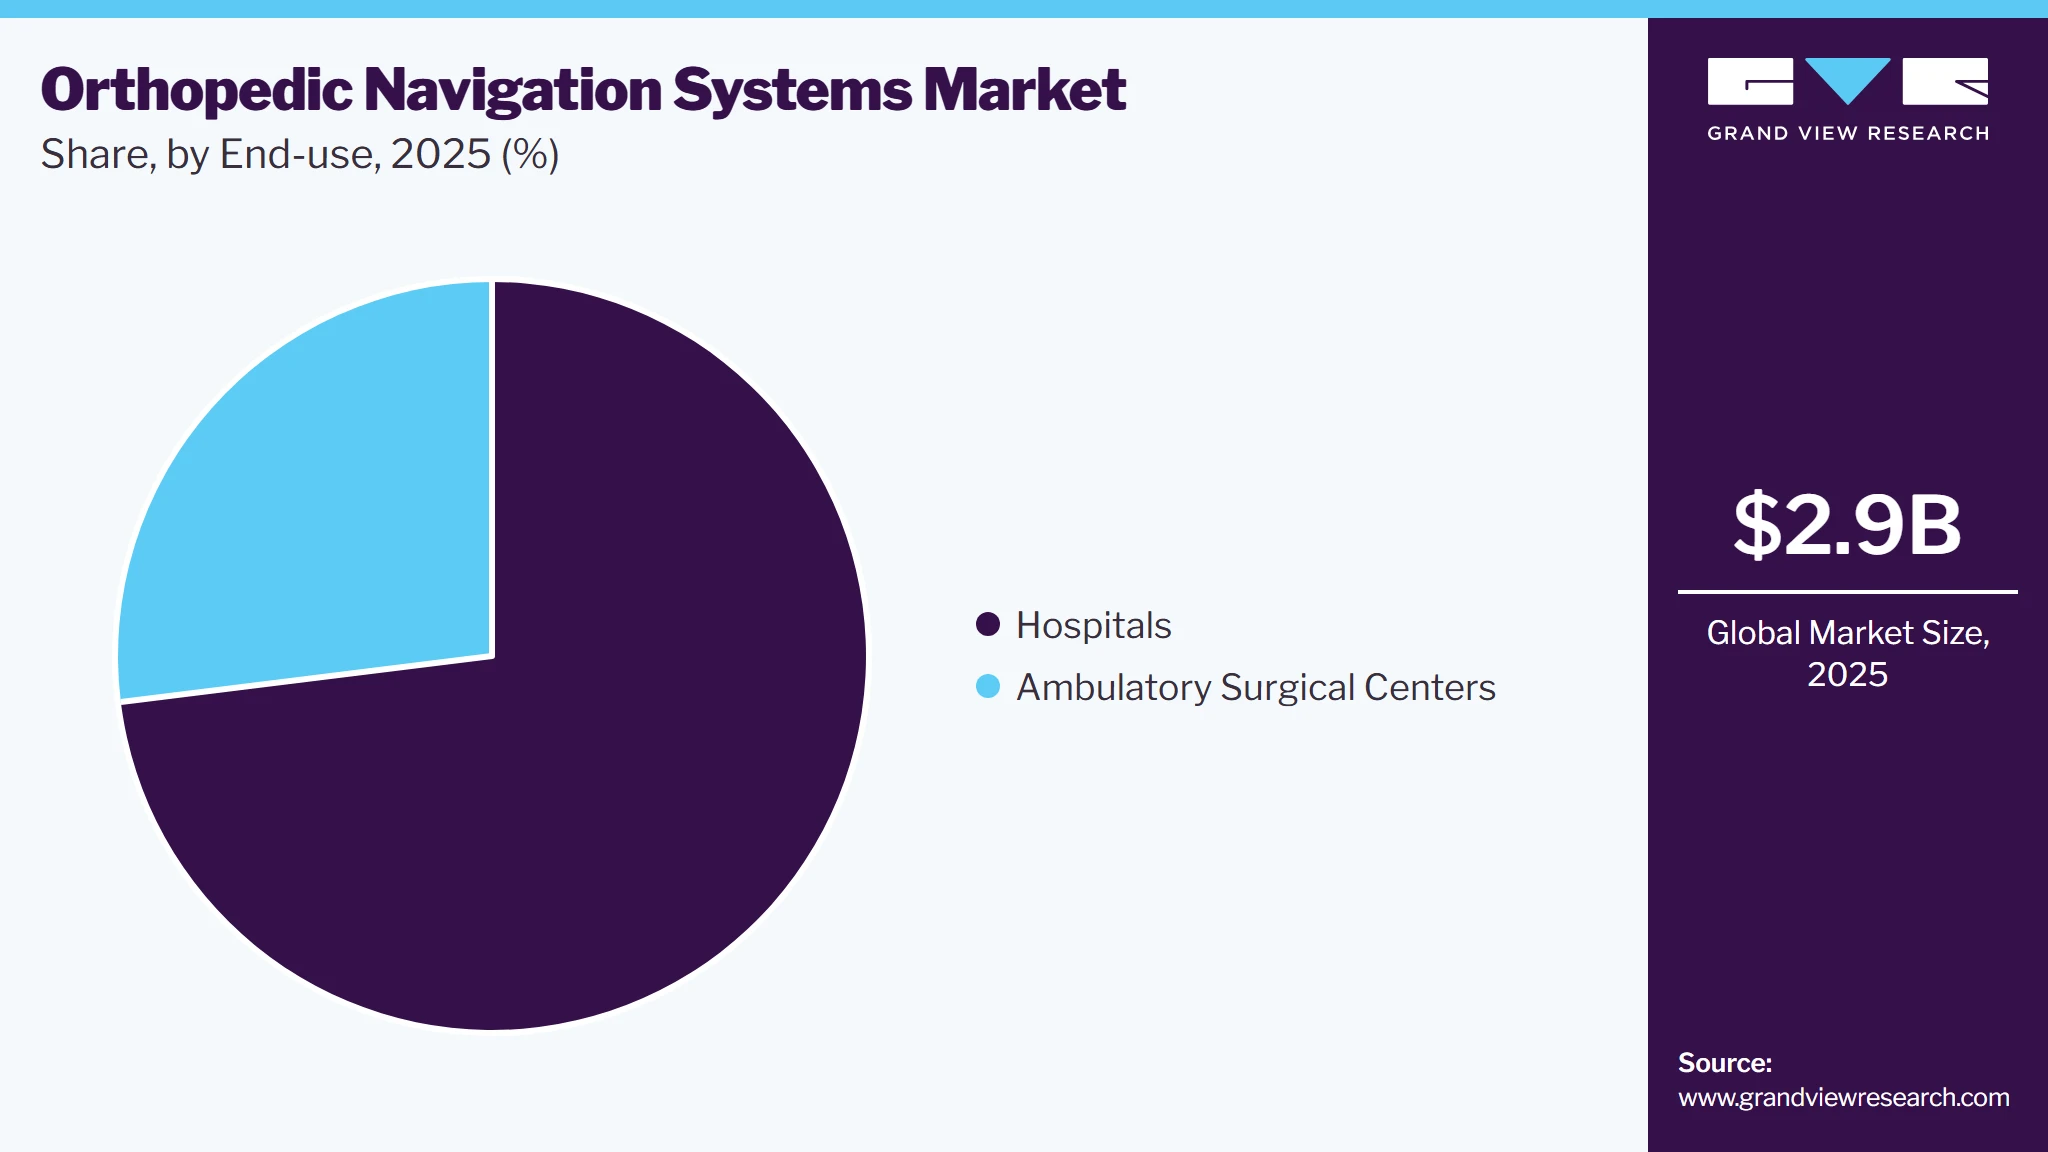
- By end use: Hospitals segment held the largest revenue share of 73.0% in 2025
Regional Highlights
- Largest regional market: North America (44.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.9 billion
- Estimated market size in 2026: USD 3.3 billion
- Projected market size by 2033: USD 7.8 billion
- CAGR (2026-2033): 13.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
The integration of augmented reality (AR), artificial intelligence (AI), and computer vision into orthopedic navigation systems is expected to drive market growth by improving surgical visualization, precision, and workflow efficiency. In April 2025, Medivis received FDA 510(k) clearance for its Spine Navigation platform, which combines AI segmentation, computer vision algorithms, real-time data analysis, and advanced image processing to provide surgeons with holographic image guidance during open and minimally invasive spine procedures.
Market Dynamics
As the volume of orthopedic procedures continues to increase, healthcare providers are increasingly adopting navigation systems to improve surgical precision and implant alignment. The growing integration of robotic-assisted surgery is further enhancing the accuracy and efficiency of orthopedic procedures. In addition, the shift of joint replacement and other orthopedic surgeries to ambulatory surgery centers (ASCs) is creating new opportunities for the adoption of navigation systems. However, the high capital investment and recurring maintenance costs limit the widespread implementation of the systems. Ongoing technological innovation and the increasing focus on value-based healthcare are expected to support the sustained market growth during the forecast period.
The increasing preference for precision-based surgery and rising hospital investments in advanced operating room technologies and digital surgical infrastructure, is accelerating the adoption of robotic-assisted and navigation-enabled systems across orthopedic specialties. The growing utilization and installed base of robotic platforms further demonstrate the increasing integration of these technologies into routine joint replacement procedures. According to Carrothers Orthopaedics, approximately 13,000 patients worldwide undergo Mako robotic-arm-assisted surgery each month, while more than 1,000 Mako systems have been installed globally. The platform has also been featured in more than 200 peer-reviewed studies, reflecting the expanding clinical experience and evidence base surrounding robotic-assisted orthopedic surgery.
The increasing adoption of robotic systems is supported by their ability to generate patient-specific 3D anatomical models, enable detailed preoperative planning, and provide real-time intraoperative feedback to support precise bone preparation and implant positioning. These capabilities can improve surgical accuracy and support better implant alignment and positioning, potentially contributing to improved patient recovery and long-term joint outcomes. As robotic-assisted procedures become increasingly established across hip and knee replacement, the expanding installed base and procedure volumes are expected to create a broader addressable opportunity for orthopedic navigation and robotic technologies.
The table below highlights key companies operating in the robotic-assisted orthopedic surgery space and their leading systems across major anatomical applications. The landscape includes both proprietary robotic platforms designed around specific implants or surgical ecosystems and open-system platforms that offer greater compatibility with third-party implants, instruments, or imaging technologies.
Table 1: Key Players and Robotic-Assisted Orthopedic Surgical Systems
Company Name
Product
Stryker
Mako Total Knee SmartRobotics, Mako Partial Knee SmartRobotics, Mako Total Hip SmartRobotics and Mako Shoulder
Zimmer Biomet
ROSA Knee, ROSA Partial Knee, ROSA Hip, and ROSA Shoulder
Johnson & Johnson MedTech (DePuy Synthes)
VELYS Robotic-Assisted Solution
Smith+Nephew
CORI Surgical System
MicroPort Scientific Corporation
Honghu Orthopedic Surgical Robot
Think Surgical, Inc.
TSolution-One and TMINI Miniature Robotic System
Brainlab AG
Cirq
Meril Life Sciences Pvt. Ltd.
MISSO Robotic System
Case Study: Robotic-Assisted Surgery Implementation at St. Elizabeth Healthcare
Overview
St. Elizabeth Healthcare expanded its robotic-assisted surgery program to support acute and emergency care, improve operating room efficiency, and increase patient access to minimally invasive procedures.Key Challenges
- Rising emergency and acute-care surgical volumes
- Limited operating room capacity and staffing constraints
- Delays in transferring patients from the emergency department to the OR
- Need to improve surgical throughput while maintaining clinical quality
Strategy & Implementation
- Expanded use of the da Vinci Surgical System for acute and emergency procedures
- Standardized robotic surgery workflows and patient selection
- Established a multidisciplinary robotic surgery team
- Optimized OR scheduling and robotic system utilization
- Implemented ongoing surgeon and staff training
Outcomes
- 36% increase in robotic procedure volumes within two quarters
- Improved OR utilization and scheduling efficiency
- Faster coordination across emergency, surgical, anesthesia, and nursing teams
- Expanded access to minimally invasive surgery despite workforce constraints
- Improved capacity to manage growing acute-care demand
The case demonstrates how structured robotic-surgery programs can improve technology utilization, workflow efficiency, and surgical capacity. As hospitals increasingly integrate robotic systems into digitally enabled operating rooms, the need for complementary navigation technologies for preoperative planning, intraoperative guidance, and precise implant positioning is expected to increase, supporting growth opportunities for the orthopedic navigation systems market.
The high capital investment required for orthopedic navigation systems remains a significant barrier to market growth, particularly for small and medium-sized hospitals and ambulatory surgery centers. In addition to the initial purchase cost, healthcare providers must bear recurring expenses for software upgrades, maintenance contracts, staff training, and disposable accessories, increasing the total cost of ownership. These financial constraints often delay procurement decisions and limit the adoption of navigation technologies in cost-sensitive healthcare settings.
According to an article published by the National Center for Biotechnology Information in September 2025, the high upfront investment required for robotic-assisted total joint arthroplasty (RA-TJA) remains a major barrier to adoption. The study reported that the purchase price of robotic surgical systems ranges from USD 500,000 to over USD 1 million per unit, depending on the platform and service agreements. In addition, healthcare providers incur annual maintenance costs of USD 40,000–150,000. These substantial capital and recurring expenses significantly increase the overall cost of orthopedic procedures, thus limiting the adoption of robotic-assisted orthopedic navigation systems.
As more orthopedic procedures shift from hospitals to ASCs, the demand for orthopedic navigation systems is expected to increase significantly. ASCs are increasingly adopting advanced navigation technologies to improve surgical precision, optimize operating room efficiency, reduce procedure times, and facilitate same-day discharge for joint replacement and sports medicine procedures. Furthermore, the growing emphasis on value-based healthcare and cost-effective surgical care is accelerating the integration of navigation systems into outpatient orthopedic facilities, thus creating substantial growth opportunities for the orthopedic navigation systems market.
According to the Centers for Medicare & Medicaid Services (CMS) CY 2026 Proposed Rule, CMS proposed adding 276 procedures to the ASC Covered Procedures List (ASC-CPL) and 271 additional procedures following the removal of services from the Inpatient-Only (IPO) list. This expansion significantly broadens the range of orthopedic and other complex procedures eligible for reimbursement in ASCs, creating greater demand for precision-guided surgical technologies, including orthopedic navigation systems. As more joint replacement and spine procedures migrate to outpatient settings, the adoption of navigation systems is expected to increase to support accurate implant placement and enhance operational efficiency.
Market Characteristics
Continuous innovation in navigation-compatible orthopedic technologies is expected to drive market growth by enhancing surgical precision, visualization, and procedural efficiency. In May 2026, SurGenTec received FDA 510(k) clearance for ION-C navigation instruments compatible with Medtronic’s StealthStation platform, enabling real-time anatomical guidance during posterior cervical fusion procedures and supporting more precise implant placement and minimally invasive surgical workflows.
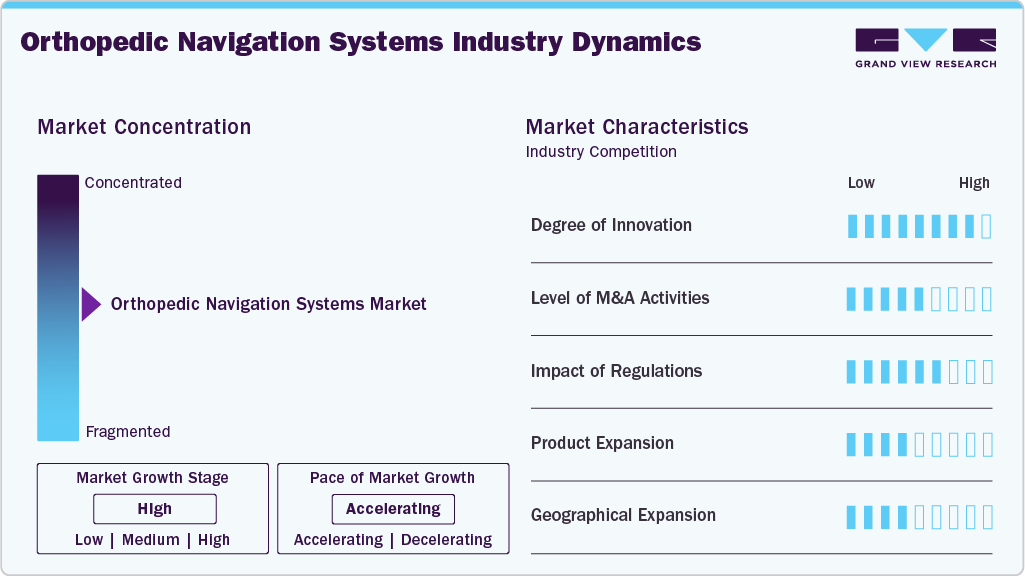
The orthopedic navigation systems market is characterized by a medium level of merger and acquisition (M&A) activity, facilitating access to complementary technologies and distribution channels to capture a larger market share. For instance, in October 2025, Zimmer Biomet completed its acquisition of Monogram Technologies, an AI-driven orthopedic robotics company. The acquisition added Monogram’s surgeon-guided semi-autonomous and fully autonomous robotic technologies to Zimmer Biomet’s existing portfolio of orthopedic robotics and navigation solutions.
 To learn more about this report, Download Free Sample Report
Regulations significantly impact the orthopedic navigation systems industry by ensuring patient safety, product quality, and efficacy. Market players are investing substantial resources in developing technologically advanced products and regulatory submissions to obtain regulatory approval for pipeline products.
Several market players are expanding their business by launching new solutions in the market to expand their product portfolio. For instance, in September 2025, Brainlab received U.S. FDA 510(k) clearance and launched its Spine Mixed Reality Navigation system in the U.S. The system combined Brainlab’s optical navigation technology with mixed-reality visualization to provide extended guidance for pedicle screw placement during minimally invasive spine surgery.
Companies are implementing various strategies, such as distribution agreements, geographic expansion, and new product development, to improve their market penetration. In November 2025, HRS Navigation raised USD 5 million in a Pre-Series A funding round to support global market expansion and scale its manufacturing capabilities. The Indian surgical navigation company planned to use the funding to expand internationally and develop next-generation navigation technologies for complex cranial, spine, and ENT procedures.
Analyst Perspective
The increasing demand for precision-based orthopedic surgeries and the growing adoption of robotic-assisted surgical technologies are expected to drive the widespread adoption of orthopedic navigation systems over the forecast period. Continuous advancements in artificial intelligence and image-guided navigation are improving surgical accuracy and implant positioning. The growing shift of orthopedic procedures to ambulatory surgery centers is further expanding market opportunities for navigation-enabled surgical solutions. Manufacturers are increasingly focusing on technological innovation and product portfolio expansion to strengthen their market position. These developments are expected to accelerate the adoption of next-generation orthopedic navigation systems across hospitals and outpatient surgical facilities.
Application Insights
The knee surgery segment led the orthopedic navigation systems industry with the largest revenue share of 52.6% in 2025. An increasing number of total knee replacement procedures and rising awareness regarding associated benefits contribute to its dominance. In addition, wider applications in multiple surgical conditions, such as total knee arthroplasty, unicompartmental (partial) knee replacement, kneecap replacement (patellofemoral arthroplasty), and revision knee replacement, further support segment growth. Increasing technological advancements, such as minimally invasive surgeries, accompanied by the availability of improved implant materials, are anticipated to boost knee surgery procedure volumes, thereby supporting segment growth. For instance, in May 2025, Pixee Medical launched its FDA-approved Knee+ NexSight system for total knee arthroplasty and completed its first U.S. procedure at Trinity Health Oakland Hospital in Michigan. The AR-based navigation system was designed to integrate into existing surgical workflows without requiring preoperative CT scans, physical disposables, percutaneous pins, or intramedullary rods. The system had also supported more than 10,000 procedures worldwide with its underlying technology and was designed for use in ASCs, supporting broader adoption of cost-efficient navigation solutions in outpatient knee replacement surgery.
The spine segment in the orthopedic navigation systems market is anticipated to grow at the fastest CAGR over the forecast period. This growth is attributed to the increasing volume of spine surgeries as the prevalence of spinal disorders increases. Spinal injuries are the main reason for mortality and morbidity resulting from either weakening of the neurological injury or bony spine to the spinal nerves or spinal cord. Moreover, the launch of technologically advanced products fuels segment growth over the forecast period. For instance, in February 2026, Medtronic received FDA 510(k) clearance for the Stealth AXiS Surgical System with its Spine clinical application. The system integrates surgical planning, navigation, and robotics into a single platform for spine procedures, representing a shift toward integrated navigation-robotics systems.
Technology Insights
The optical segment led the market with the largest revenue share of 41.7% in 2025. An optical surgical navigation system is built on the principle of stereo vision with high precision. These systems are used in medical procedures that require high precision and major access paths. Some optical navigation systems, such as optical coherence tomography (OCT) and Raman Spectroscopy, are used to assess the bone's inheritance capability, and surgeons benefit from visual images of the bone. For example, Stryker offers the NAV3i Platform, an optical surgical navigation system, for spinal, cranial, ENT, and orthopedic procedures. Such advantages associated with the technology are attributed to segment growth.
The electromagnetic segment in the orthopedic navigation systems industry is anticipated to witness the fastest CAGR growth over the forecast period. Electromagnetic navigation systems use electromagnetic techniques, including magnetic field generators and magnetic field detectors, to create a real-time image of the body. This navigation system is essential for older people, who are highly vulnerable to numerous physical conditions. According to the National Cancer Institute, electromagnetic external shock wave therapy (ESWT) systems are designed for orthopedic procedures. Orthopedic ESWT systems are used for orthopedic procedures to alleviate pain; moreover, they are intended for treating chronic orthopedic diseases such as plantar fasciitis, lateral epicondylitis, and calcifying tendonitis of the rotator cuff. This is expected to support the segment growth over the forecast period.
End Use Insights
The hospitals segment led the market with the largest revenue share of 73.0% in 2025. Hospitals offer a wide array of treatment options for pain management and orthopedic procedures. Moreover, the presence of technologically advanced medical devices and the increased patient footfall under these facilities further drive segment growth. For instance, U.S. News evaluated nearly 1,000 hospitals providing orthopedic care and ranked the top 50 hospitals based on their capabilities in spinal surgeries and fusions, limb and joint procedures, and other musculoskeletal and connective-tissue care. The extensive evaluation of orthopedic hospitals highlights the substantial concentration of complex orthopedic procedures within hospital settings, supporting demand for advanced surgical navigation systems.
 To learn more about this report, Download Free Sample Report
The ambulatory surgical centers (ASCs) segment is anticipated to grow at the fastest CAGR over the forecast period, owing to the growing number of ASCs, adoption of enabling technologies for orthopedic surgeries, and cost-effectiveness. For instance, the Ambulatory Surgery Center Association states that more than 6,300 Medicare-certified ASCs are in the U.S. Moreover, factors such as reduced wait times, personalized care, and shorter stay duration have increased the demand for these centers. Innovative surgical methods in such settings allow tests and procedures to be performed without hospital admission. This is expected to support segment growth.
Regional Insights
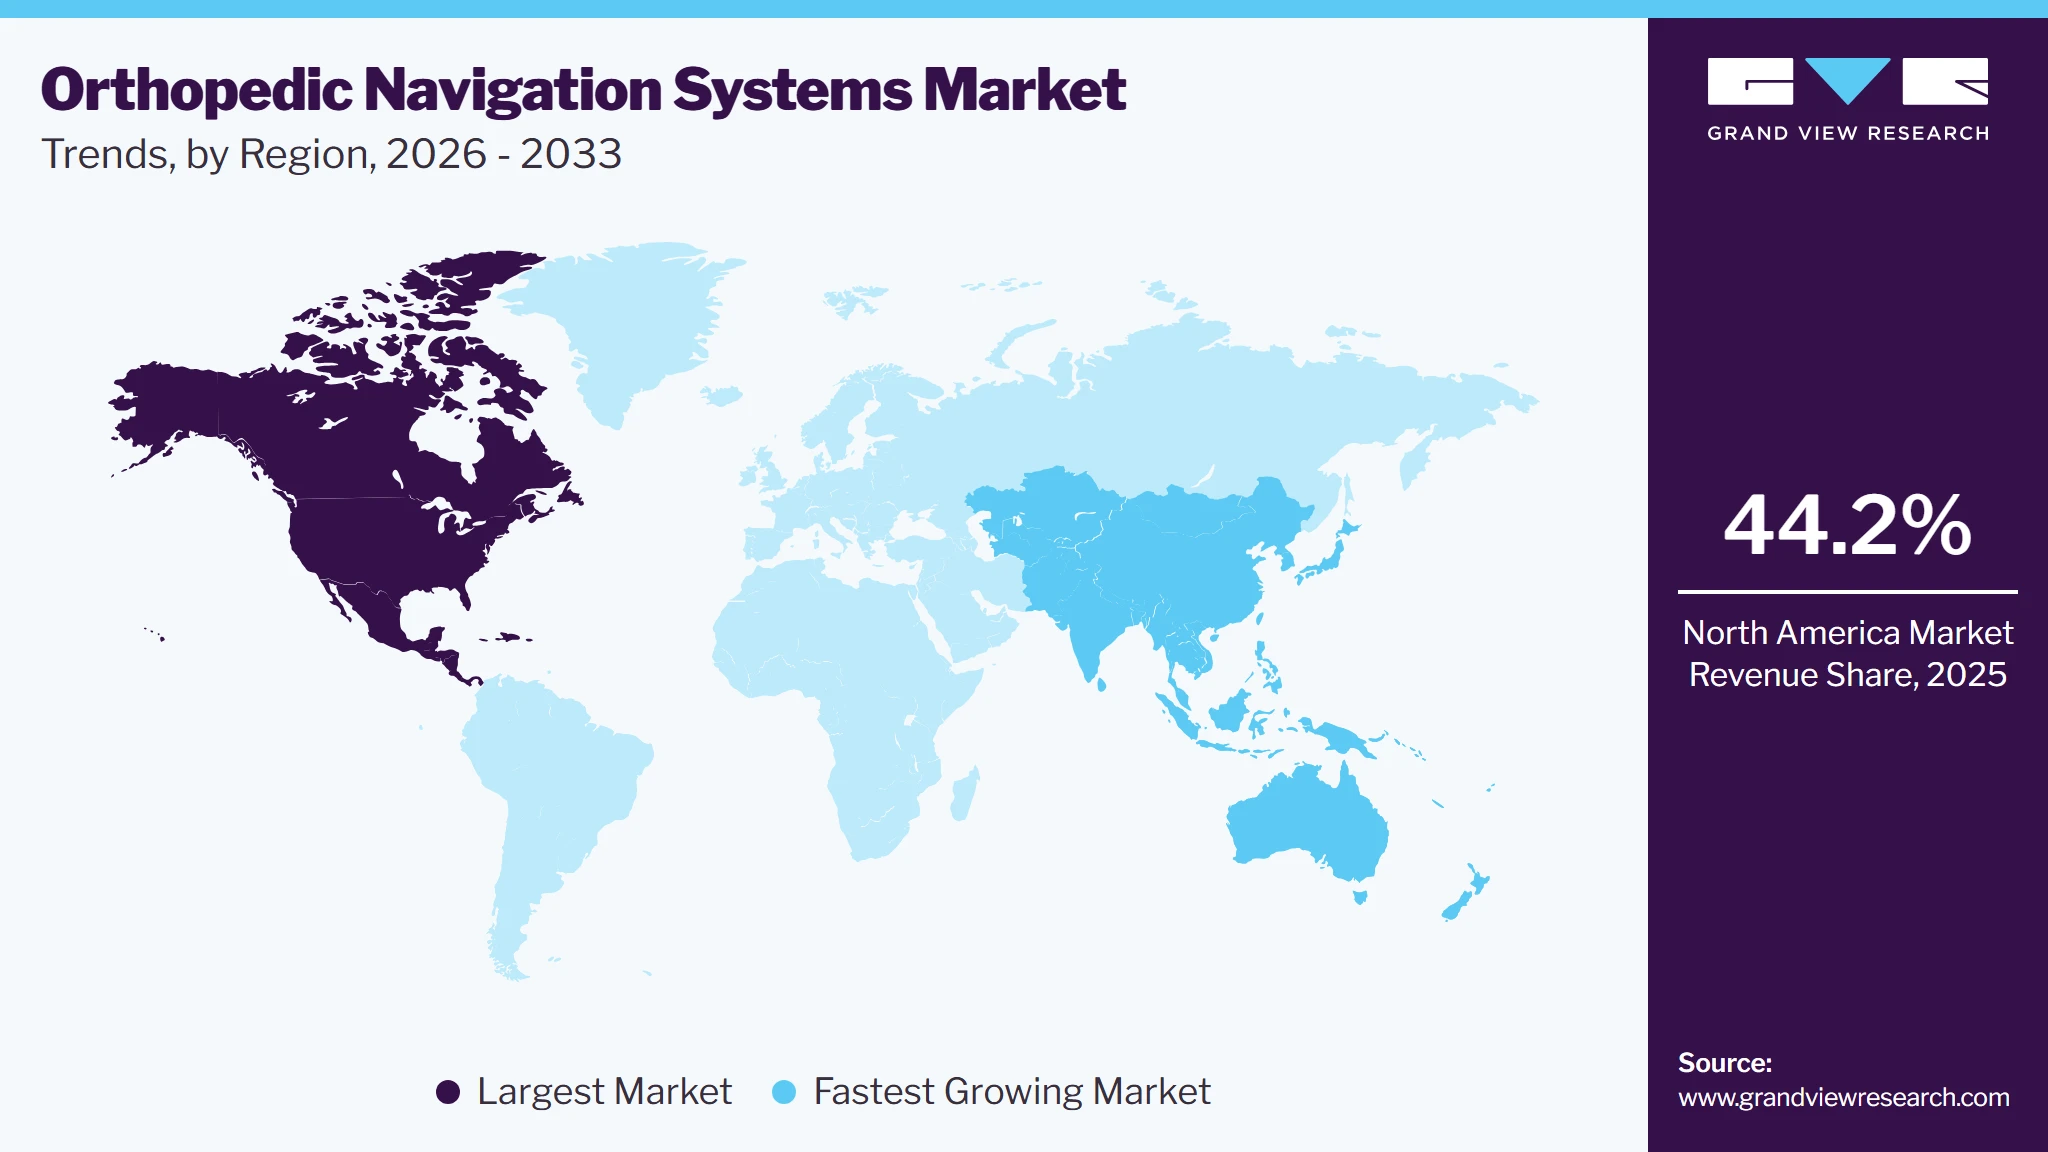
North America dominated the orthopedic navigation systems market with the largest revenue share of 44.2% in 2025. The availability of improved healthcare infrastructure, high levels of awareness, and favorable government initiatives promoting orthopedic navigation systems are factors contributing to the growth of this region. In addition, factors such as the growing geriatric population, high government healthcare spending, a well-developed reimbursement structure, the presence of established manufacturers, and the launch of new products in the region contribute to the region’s growth. For instance, in 2024, DePuy Synthes introduced and received the U.S. FDA 510(k) clearance for its VELYS Active Robotic-Assisted System (VELYS SPINE) for use in instrumenting and planning spinal fusion procedures in the thoracolumbar, cervical, and sacroiliac spine.
 To learn more about this report, Download Free Sample Report
U.S. Orthopedic Navigation Systems Industry Trends
The U.S. orthopedic navigation systems industry held the largest share of North America in 2025. Total joint replacement is one of the most performed elective surgical procedures in the country. The number of primary and revision total joint replacement procedures has continuously increased in recent years. According to the American Academy of Orthopedic Surgeons, in the U.S., over 450,000 total hip replacement and 700,000 total knee replacement procedures are performed each year. Thus, the demand for orthopedic navigation systems has increased recently.
Growing use of robotic-assisted and computer-navigated procedures is also driving demand for orthopedic navigation systems. For instance, in February 2026, Gyder Surgical announced the first commercial U.S. surgeries using its GYDER Hip Navigation System at an outpatient joint replacement center in New Jersey. The pinless and imageless system offers real-time guidance during anterior approach total hip arthroplasty, highlighting the growing adoption of advanced navigation technologies in the U.S.
Europe Orthopedic Navigation Systems Market Trends
The Europe orthopedic navigation systems industry is anticipated to grow at a significant CAGR during the forecast period. The growing incidence of osteoarthritis and rising demand for minimally invasive surgeries for joint replacement are expected to boost the demand for orthopedic navigation systems over the forecast period in this region. Moreover, rising healthcare expenditure, growing awareness of computer-assisted orthopedic navigation systems, and increasing adoption of these techniques are factors driving market growth in this region.
The orthopedic navigation systems market in Germany is anticipated to register a considerable growth rate during the forecast period. The market is anticipated to register a considerable growth rate during the forecast period. The increasing adoption of advanced image-guided and navigation technologies in hospitals is expected to drive market growth by improving surgical precision and enabling real-time visualization during complex orthopedic procedures. For instance, in June 2025, SRH Klinikum Karlsbad-Langensteinbach introduced an O-arm 2D/3D intraoperative imaging system integrated with Medtronic's StealthStation navigation system for spine surgery. The system provided real-time 2D and 3D imaging and supported precise implant placement, with applications planned to expand into other orthopedic and trauma procedures.
The UK orthopedic navigation systems market is anticipated to grow at a considerable CAGR during the forecast period. Strategic expansion by orthopedic technology companies is expected to support the market growth by increasing access to advanced surgical technologies, strengthening orthopedic infrastructure, and expanding the availability of technology-enabled procedures. For instance, in June 2025, Smith+Nephew entered into a strategic partnership with Standard Health to support the development of the first dedicated Orthopaedic Ambulatory Surgery Centre in the UK. The center, located in Poole, Dorset, was planned to provide NHS and private patients with access to advanced technologies for joint replacement and repair procedures, including knee and hip replacements. Standard Health also planned to develop 10 additional UK sites within three years and 20 sites by 2033, creating a broader network to deliver technology-enabled orthopedic procedures. Smith+Nephew planned to supply its orthopedic medical technology portfolio to the centers, supporting wider adoption of advanced orthopedic solutions in the UK.
Asia Pacific Orthopedic Navigation Systems Market Trends
The Asia Pacific orthopedic navigation systems industry is anticipated to grow at the fastest CAGR over the forecast period. The market growth can be attributed to the rising prevalence of orthopedic conditions such as rheumatoid arthritis and osteoarthritis due to lifestyle changes and the aging population. Moreover, rising healthcare expenditure and advancements in healthcare infrastructure in countries such as India, China, and Japan are driving the adoption of navigation systems.
The Australia orthopedic navigation systems market is anticipated to register a considerable growth rate during the forecast period. In July 2026, Medacta introduced NextAR Hip, an augmented reality navigation system for total hip arthroplasty, with the first clinical cases conducted in Australia and the U.S. The system provided real-time guidance for bone preparation, cup positioning, screw placement, and assessment of leg length and offset. It supported both CT-based and CT-free workflows and was designed to potentially reduce reliance on intraoperative fluoroscopy, supporting the adoption of advanced navigation technology in Australian orthopedic surgery.
Latin America Orthopedic Navigation Systems Market Trends
The Latin America orthopedic navigation systems industry is witnessing steady growth. Factors such as increasing awareness regarding the benefits of orthopedic navigation systems among patients and healthcare professionals, and the rising prevalence of osteoporosis, propel market growth. For instance, according to the International Osteoporosis Foundation, approximately 655,645 cases of hip fractures are expected to be registered in Latin America by 2050.
The orthopedic navigation systems market in Brazil is anticipated to register considerable growth during the forecast period. One major factor boosting the market is the increasing prevalence of osteoporosis in the country. For instance, according to an article published in the Scientific Electronic Library Online (SciELO), osteoporosis and associated fractures are very common in Brazil, owing to a growing geriatric population affected by musculoskeletal disorders and an active youth attracted to high-intensity sports.
Middle East & Europe Orthopedic Navigation Systems Market Trends
The Middle East and Africa orthopedic navigation systems industry is experiencing lucrative growth. A significant increase in the prevalence of arthritis and chronic disorders in the geriatric population in the region is anticipated to drive the market over the forecast period. There are various risk factors of chronic orthopedic diseases, such as obesity, overweight, chronic back pain, arthritis, and osteoporosis. Furthermore, the rising incidence of sports injuries and road accidents is a key driver of market growth.
The UAE orthopedic navigation systems market is anticipated to register a considerable growth rate during the forecast period. The increase in amputations due to age-related diseases such as rheumatoid arthritis, osteoarthritis, bursitis, and tendinitis, and the acquisition of privately developed models, accelerate market growth. Moreover, the rise in the incidence of co-morbidities, including obesity and diabetes, leads to an increase in the risk of degenerative joint diseases, especially in the elderly population, which fuels the market growth.
Key Orthopedic Navigation Systems Company Insights
Key participants in the orthopedic navigation systems market are focusing on developing innovative business growth strategies in the form of product portfolio expansions, partnerships & collaborations, mergers & acquisitions, and business footprint expansions.
Key Orthopedic Navigation Systems Companies
The following key companies have been profiled for this study of the orthopedic navigation systems market.
-
B. Braun SE
-
Stryker
-
Medtronic
-
Smith+Nephew
-
Zimmer Biomet
-
DePuy Synthes (Johnson & Johnson Services, Inc.)
-
Kinamed Incorporated
-
Amplitude Surgical
-
Globus Medical
-
OrthAlign
-
Exactech, Inc.
-
Pixee Medical
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., B. Braun SE, Stryker, Medtronic, Smith+Nephew)
- Expand orthopedic navigation portfolios through continuous product innovation, robotic-assisted surgery integration, and AI-enabled navigation technologies.
- Strengthen market presence through strategic acquisitions, partnerships with hospitals and ASCs, global distribution networks, and investment in surgeon training programs.
- Strong global brand recognition, diversified orthopedic product portfolios, and well-established relationships with hospitals, surgeons, and healthcare providers.
- Robust R&D capabilities, extensive financial resources, advanced manufacturing infrastructure, and comprehensive after-sales service support enable sustained market leadership.
- High dependence on capital-intensive products and exposure to pricing pressure from hospitals and reimbursement changes.
- Lengthy regulatory approval processes, high R&D investments, and slower adoption in price-sensitive emerging markets may limit growth.
Emerging Players (e.g., Globus Medical, OrthAlign, Pixee Medical)
- Focus on developing innovative, AI-enabled, portable, and cost-effective orthopedic navigation systems tailored for specific orthopedic procedures and outpatient settings.
- Expand market presence through strategic collaborations with hospitals, ambulatory surgery centers (ASCs), distributors, and technology partners while strengthening regional expansion initiatives.
- Greater operational agility, faster adoption of emerging technologies, and the ability to develop specialized navigation solutions for niche orthopedic applications.
- Flexible business models, shorter innovation cycles, and competitive pricing enable quicker response to evolving customer needs and market trends.
- Limited global market presence, smaller sales and distribution networks, and lower financial resources compared to established competitors.
- Challenges in achieving large-scale commercialization, obtaining regulatory approvals across multiple regions, and competing with well-established brands for hospital procurement contracts.
Recent Developments
-
In March 2025, Pixee Medical announced the U.S. launch of its Knee+ NexSight augmented reality (AR) navigation platform during the AAOS 2025 Annual Meeting. The next-generation solution provides real-time guidance for total knee arthroplasty (TKA) through a streamlined three-step workflow, enabling accurate implant positioning without the need for complex robotic infrastructure. The launch strengthened Pixee Medical's presence in the U.S. orthopedic navigation market and expanded its AR-based surgical navigation portfolio.
-
In June 2026, OrthAlign, Inc. received U.S. FDA 510(k) clearance for its Lantern ASC System, a handheld orthopedic navigation platform designed for ambulatory surgery centers (ASCs). The system delivers real-time navigation for total knee, partial knee, and revision arthroplasty, while reducing the cost and complexity of robotic-assisted surgery. The approval expanded OrthAlign's navigation portfolio and supported the growing shift toward outpatient joint replacement procedures.
-
In May 2026, DePuy Synthes introduced AI-assisted VELYS Hip Navigation on the VELYS Hub and acquired Gemtrack radiofrequency tracking technology. Gemtrack uses miniature RF signals to track surgical instruments and implants, overcoming optical line-of-sight blockages common in conventional infrared navigation cameras.
-
For instance, in September 2025, Yenepoya Specialty Hospital in India introduced the SkyWalker orthopedic robotic system for knee replacement surgery, becoming the first institution in South Asia to adopt the technology.
-
In August 2024, DePuy Synthes introduced a unique dual-use robotics and standalone navigation platform created in partnership with eCential Robotics. The platform, known as the VELYS SPINE (VELYS Active Robotic-Assisted System), recently received 510(k) clearance from the U.S. Food and Drug Administration (FDA).
-
In April 2024, DePuy Synthes (Johnson & Johnson Services, Inc.) showcased innovations and technological advancements across its comprehensive Spine portfolio, such as the TriALTIS Spine System. It is combined with TriALTIS Navigation-Enabled Instruments.
-
In May 2023, Stryker launched the Ortho Q Guidance system, which supports advanced planning and guidance for hip and knee surgeries. This system integrates new optical tracking capabilities through a redesigned, high-tech camera along with advanced algorithms in the newly launched Ortho Guidance software.
Orthopedic Navigation Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.9 billion
Estimated market size in 2026
USD 3.3 billion
Projected market size by 2033
USD 7.8 billion
Growth rate
CAGR of 13.6% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; Spain; Italy; France; Norway; Denmark; Sweden; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
B. Braun SE; Stryker; Medtronic; Smith+Nephew; Zimmer Biomet; DePuy Synthes (Johnson & Johnson Services, Inc.); Kinamed Incorporated; Amplitude Surgical; Globus Medical; OrthAlign; Exactech, Inc.; Pixee Medical
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Orthopedic Navigation Systems Market Report Segmentation
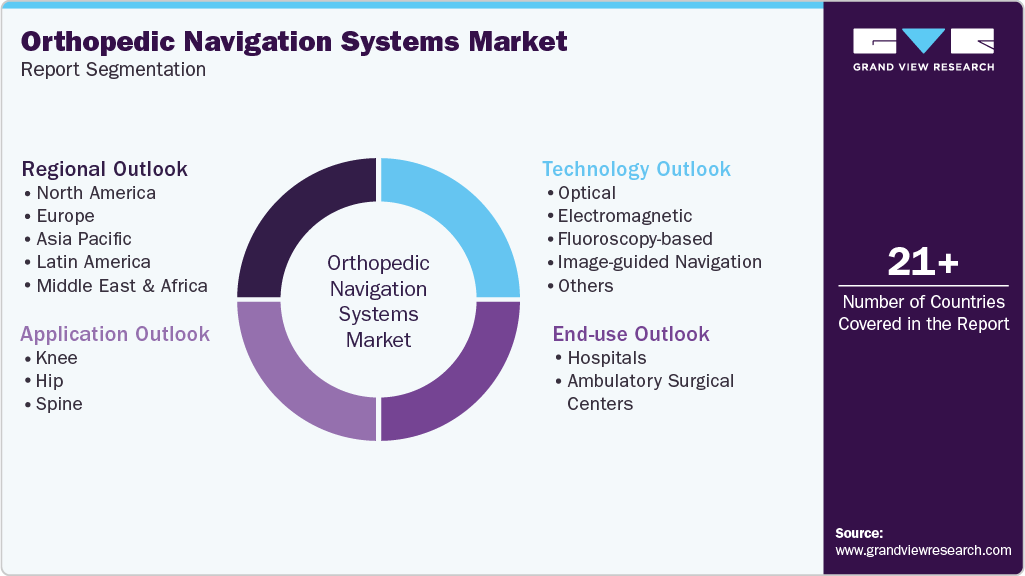
This report forecasts revenue growth at the global, regional, and country level and provides an analysis of industry trends in each of the sub segments from 2021 to 2033. For this study, Grand View Research, Inc. has segmented the orthopedic navigation systems market report based on application, technology, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Knee
-
Hip
-
Spine
-
-
Technology Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Optical
-
Electromagnetic
-
Fluoroscopy-based
-
Image-guided navigation
-
Others
-
-
End Use Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Spain
-
Italy
-
France
-
Denmark
-
Norway
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The orthopedic navigation systems market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with eachorthopedic navigation systems segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Revenue capture definition
Knee
Knee orthopedic navigation systems assist surgeons in performing total and partial knee replacement procedures by providing real-time guidance for accurate bone alignment and implant positioning. These systems improve surgical precision, reduce alignment errors, and enhance long-term implant performance.
Hip
Hip navigation systems are used during total and revision hip arthroplasty to optimize implant placement, leg length restoration, and acetabular cup positioning. They help improve joint stability and enhance postoperative outcomes.
Spine
Spine navigation systems provide real-time three-dimensional guidance during spinal procedures, including pedicle screw placement, spinal fusion, and deformity correction. They improve surgical accuracy while minimizing radiation exposure and the risk of neurological complications.
Optical
Optical navigation systems use infrared cameras and reflective markers to track surgical instruments and patient anatomy in real time. They provide high-precision navigation and are widely used in joint replacement and spine surgeries.
Electromagnetic
Electromagnetic navigation systems utilize electromagnetic fields to track surgical instruments without requiring a direct line of sight. They are particularly useful in complex procedures where optical tracking may be obstructed.
Fluoroscopy-based
Fluoroscopy-based navigation systems use real-time X-ray imaging to guide orthopedic procedures and verify implant placement during surgery. These systems improve procedural accuracy while supporting minimally invasive surgical techniques.
Image-guided navigation
Image-guided navigation systems integrate preoperative CT, MRI, or intraoperative imaging with navigation software to provide detailed anatomical visualization and surgical planning. They enhance implant positioning and improve decision-making during orthopedic procedures.
Others
This segment includes emerging navigation technologies such as robotic-integrated navigation, augmented reality (AR)-based navigation, ultrasound-guided navigation, and hybrid tracking systems designed to improve surgical precision and workflow efficiency.
Hospitals
Hospitals utilize orthopedic navigation systems to support orthopedic and spine surgeries by providing real-time surgical guidance and accurate implant positioning. These systems enhance surgical precision, improve clinical decision-making, and facilitate the management of both routine and complex orthopedic procedures.
Ambulatory Surgical Centers
Ambulatory Surgical Centers (ASCs) are outpatient healthcare facilities that use orthopedic navigation systems to perform minimally invasive and same-day orthopedic procedures. Navigation technologies help enhance surgical precision, optimize operating room efficiency, and support faster patient recovery.
Estimation Model
Model Details
This research methodology outlines the process for estimating the size of the global orthopedic navigation systems market for the period from 2021 to 2033. The study covers key application segments, including knee, hip, and spine; technology segments such as optical, electromagnetic, fluoroscopy-based, image-guided navigation, and other navigation technologies; and major geographic regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Bottom-Up Analysis
-
Collected country-level data on the installed base of orthopedic navigation systems across hospitals and ASCs.
-
Assessed annual orthopedic procedure volumes, including knee, hip, and spine surgeries.
-
Estimated navigation system penetration rates across different applications and end users.
-
Determined the average selling price (ASP) of navigation systems, software licenses, maintenance contracts, and consumables.
-
Incorporated replacement demand, new system installations, and recurring service revenues into the analysis.
-
Aggregated country-level market estimates to derive regional and global market values.
Commodity Flow Analysis
-
Evaluated the value chain of the orthopedic navigation systems market from manufacturers to end users to estimate market revenue.
-
Analyzed company revenues, product portfolios, and commercial sales of orthopedic navigation systems across major manufacturers.
-
Assessed regional market presence, distribution networks, and procurement patterns across hospitals, ambulatory surgery centers (ASCs), and specialty orthopedic clinics.
-
Evaluated product adoption across technology types, surgical applications, and end-user segments to estimate regional revenue distribution.
-
Analyzed pricing trends, average selling prices (ASPs), and product mix to derive revenue estimates by geography and market segment.
-
Validated market revenue estimates through triangulation of manufacturer sales, end-user demand, pricing analysis, and regional adoption patterns, ensuring consistency across country, regional, and global-level market estimates.
Primary Research
-
Conducted interviews with orthopedic surgeons, spine surgeons, and sports medicine specialists to assess technology adoption trends.
-
Interviewed hospital procurement managers and ASC administrators to understand purchasing behavior and investment plans.
-
Engaged with medical device manufacturers and distributors to validate pricing, sales volumes, and competitive positioning.
-
Consulted regulatory experts and key opinion leaders (KOLs) to understand regulatory developments and market dynamics.
-
Gathered insights on reimbursement policies, technological advancements, and future demand trends.
-
Used primary research findings to validate secondary data and refine historical market estimates and forecast projections.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered Value Adds Procedure Volume Analysis by Orthopedic Application
Developed a comprehensive analysis of orthopedic navigation system adoption across knee, hip, and spine surgeries, including procedure volumes, navigation utilization rates, robotic-assisted surgery penetration, and regional demand trends.
Enables stakeholders to identify high-growth application areas, prioritize product development, optimize sales strategies, and target specialties with the highest adoption potential.
Technology Benchmarking and Competitive Assessment
Conducted an in-depth comparison of optical, electromagnetic, fluoroscopy-based, image-guided, and emerging navigation technologies, evaluating their clinical applications, technological advancements, accuracy, advantages, and adoption across healthcare settings.
Helps manufacturers and investors assess technology competitiveness, identify innovation opportunities, support R&D investments, and develop differentiated product strategies.
Hospital and ASC Adoption Analysis
Assessed the adoption of orthopedic navigation systems across hospitals and ASCs, covering purchasing trends, procedure migration, reimbursement landscape, infrastructure readiness, and future demand potential.
Supports strategic expansion by identifying high-growth end-user segments, evaluating investment opportunities, optimizing commercialization strategies, and strengthening market positioning in outpatient orthopedic care.
Frequently Asked Questions About This Report
Some key players operating in the orthopedic navigation systems market include B. Braun SE, Stryker, Medtronic, Smith+Nephew, Zimmer Biomet, DePuy Synthes (Johnson & Johnson Services, Inc.), Kinamed Incorporated, Amplitude Surgical, and Globus Medical.
Key factors driving the orthopedic navigation systems market growth include increased adoption of minimally invasive surgeries, technological advancements, initiatives by key market players, and a high prevalence of orthopedic disorders.
North America dominated with a 44.2% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Hospitals segment held the largest revenue share of 73.0% in 2025, while ambulatory surgical centers is the fastest-growing area.
Optical segment held the largest revenue share of 41.7% in 2025 and electromagnetic segment is the fastest-growing segment.
The global orthopedic navigation systems market size was estimated at USD 2.9 billion in 2025 and is projected to grow from USD 3.3 billion in 2026.
The global orthopedic navigation systems market is expected to grow at a compound annual growth rate of 13.6% from 2026 to 2033 to reach USD 7.8 billion by 2033.
Knee surgery held the largest revenue share of 52.6% in 2025. An increasing number of total knee replacement procedures and rising awareness regarding associated benefits contribute to its dominance.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


