
- Home
- »
- Automotive & Transportation
- »
-
Passenger Cars Market Size, Growth Report, 2026-2033GVR Report cover

Passenger Cars Market (2026 - 2033)
Size, Share & Trends Analysis Report By Propulsion Type (ICE, Electric), By Vehicle Class (Luxury, Economy), By Type (Hatchback, MUV, Sedan, SUV), By Region, And Segment Forecasts
Market Size, 2025
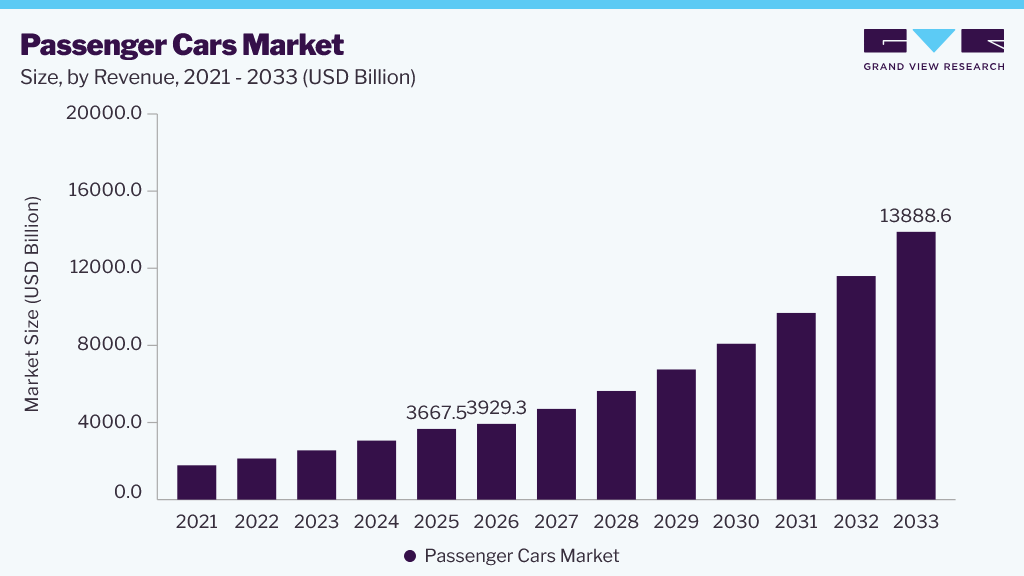
$3,667.5BMarket Estimate, 2026
$3,929.3BMarket Forecast, 2033
$13,888.6BCAGR, 2026–2033
19.8%Passenger Cars Market Summary
The global passenger cars market was estimated at USD 3,667.5 billion in 2025 and is projected to grow from USD 3,929.3 billion in 2026 to USD 13,888.6 billion in 2033, at a CAGR of 19.8 % from 2026 to 2033. The Asia Pacific dominated the market, accounting for the largest revenue share of over 60.0% in 2025. The market growth is attributed to the rapid development and integration of Advanced Driver Assistance Systems (ADAS) and autonomous driving technologies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By propulsion type: The ICE segment held the largest market share of over 75.0% in 2025.
- By vehicle class: The economy segment accounted for the largest revenue share of around 85.0% in 2025.
- By type: The SUV segment accounted for the largest revenue share of around 50.0 % in 2025.
Regional Highlights
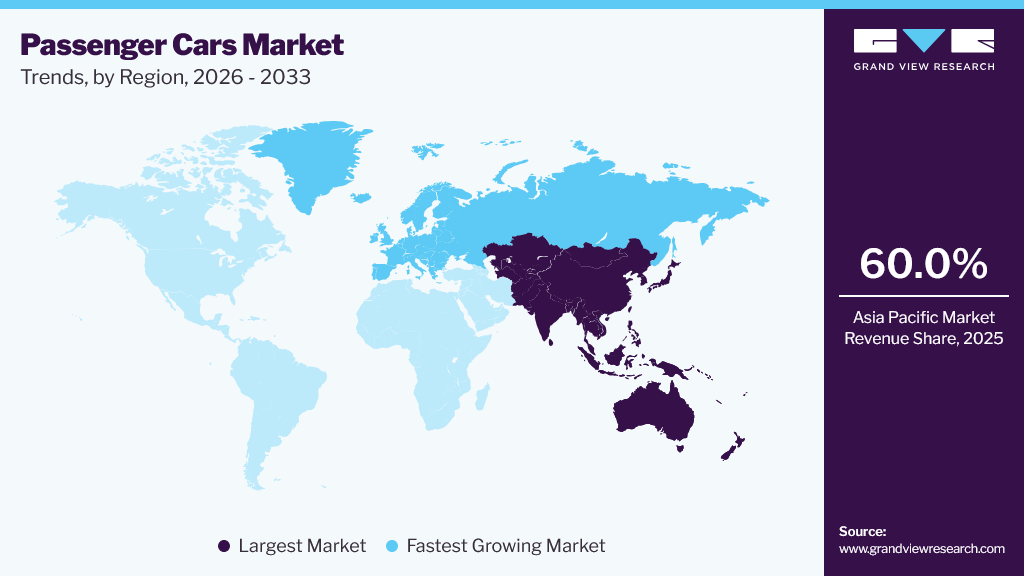
- Largest regional market: Asia Pacific (60.0% revenue share, 2025)
- Fastest-growing regional market: Europe (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 3,667.5 Billion
- Estimated market size in 2026: USD 3,929.3 Billion
- Projected market size by 2033: USD 13,888.6 Billion
- CAGR (2026-2033): 19.8 %
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advanced driver assistance systems (ADAS) are fundamentally reshaping the passenger car market. Features such as adaptive cruise control, lane-keeping assistance, autonomous parking, and collision avoidance are no longer exclusive to premium vehicles; they are increasingly becoming standard in mid-range models as well. As these technologies mature, consumers place greater emphasis on safety, convenience, and driving comfort when making purchasing decisions. The growing reliability of autonomous driving technologies is also boosting consumer confidence. In February 2026, the California Department of Motor Vehicles reported that autonomous vehicles operating under testing permits collectively traveled over 9 million miles between December 2024 and November 2025. Such milestones demonstrate continuous technological progress and reinforce the perception of software-enabled vehicles as safer and more reliable transportation solutions.
Additionally, rapid economic expansion in emerging economies is driving significant market growth. Rising household incomes are enhancing vehicle affordability, while increased urbanization is heightening the demand for personal mobility. Countries in the Asia Pacific and Latin America regions are experiencing steady growth in their middle-income populations, leading to higher discretionary spending and a greater willingness to purchase passenger vehicles. Consumer preferences are shifting away from shared and traditional modes of transportation towards private vehicle ownership, supported by easier access to financing, expanding road infrastructure, and improving living standards. These structural trends are expected to sustain long-term demand in emerging automotive markets.
However, the industry faces ongoing cost-related challenges. Manufacturing passenger vehicles heavily relies on raw materials such as steel, aluminum, plastics, and petroleum-based components. Price volatility in these commodities directly impacts production costs and places pressure on manufacturers' operating margins. While leading automakers are improving supply chain efficiency and optimizing sourcing strategies, sustained increases in raw material costs can raise vehicle prices, potentially limiting consumer demand, especially in price-sensitive markets.
Software is rapidly becoming a key competitive differentiator. Modern consumers increasingly expect their vehicles to serve as connected digital platforms rather than just traditional modes of transportation. Infotainment systems, over-the-air software updates, cloud connectivity, AI-enabled voice assistants, and personalized digital services have become important factors in purchasing decisions alongside traditional vehicle attributes such as performance and fuel efficiency. Recognizing this shift, automakers are investing heavily in software-defined vehicle architectures to deliver continuously evolving user experiences. For example, in January 2025, BMW Group introduced the BMW Operating System X and Panoramic iDrive at CES 2025, integrating advanced infotainment capabilities, AI-powered interactions, and enhanced digital services into its next-generation vehicle portfolio.
The growing integration of connected technologies is expected to serve as a long-term catalyst for growth in the passenger car industry. Features such as advanced navigation systems, real-time traffic intelligence, remote diagnostics, predictive maintenance, and personalized entertainment ecosystems are improving convenience and vehicle functionality. As software capabilities continue to evolve alongside electrification and autonomous driving technologies, connected digital experiences will increasingly influence consumer purchasing decisions and shape the future competitiveness of global passenger car manufacturers.
Market Concentration & Characteristics
The market growth stage is medium, and growth is accelerating. The passenger cars market is characterized by a high degree of innovation, driven by the integration of smart technologies that enable connectivity and communication with other components in the system. The integration often includes features such as remote monitoring and control through Internet of Things (IoT) platforms.
The market is also characterized by high levels of merger and acquisition (M&A) activity among leading players. This is due to several factors, including a focus on developing energy-efficient passenger cars and customizable passenger cars with modular designs, as well as the need to consolidate in a rapidly growing market.
The market for passenger cars is also subject to several regulatory considerations. The regulations are essential for manufacturers and users to ensure propulsion-type safety, reliability, and legal compliance. Manufacturers need to comply with regulations on propulsion-type safety standards, environmental regulations, energy-efficiency standards, CE marking, and labeling, among others.
The threat of substitutes for passenger cars is higher in the market. Linear passenger cars are chosen based on factors such as precision, speed, force capacity, and environmental considerations. The threat of substitutes varies across industries and applications within the passenger cars market. Market players need to continually innovate and offer unique value propositions to mitigate the impact of potential substitutes.
End user concentration is a significant factor in this market. Several end user industries are driving demand for passenger cars. Staying abreast of technological developments and market trends is crucial for businesses operating in this space.
Analyst Perspective
The passenger cars market is undergoing a structural shift as technology, sustainability, and changing mobility preferences redefine the competitive landscape. While vehicle demand continues to be supported by rising incomes and urbanization in many regions, purchasing decisions are increasingly influenced by safety, connectivity, fuel efficiency, and digital features rather than price alone. Automakers are investing heavily in electric vehicles, advanced driver assistance systems, and software-enabled services to differentiate their offerings and strengthen customer loyalty. At the same time, supply chain resilience and manufacturing flexibility have become important competitive factors as companies respond to changing regulations and evolving consumer demand.
Propulsion Type Insights
The ICE segment accounted for the largest market share of over 75.0% in 2025. The global automotive industry has been significantly influenced by the continued demand for personal transportation, especially in developing economies, and has remained a primary driving force. ICE cars have historically been more affordable than electric vehicles, making them a preferred choice for many consumers, particularly in regions where electric vehicle infrastructure is still developing. The existing infrastructure for gasoline and diesel fuel distribution has played a crucial role in sustaining the dominance of ICE passenger cars globally. Additionally, the versatility of ICE cars, including their ability to operate in various weather conditions and terrains, has further bolstered their global demand.
The electric segment is expected to register the fastest CAGR from 2026 to 2033. The stringent environmental regulations and ambitious carbon emissions targets set by various countries have compelled automakers to prioritize EV production, thereby accelerating the shift away from traditional combustion engines. Automakers are accelerating their dedicated electric-vehicle investments to align production strategies with evolving regulatory requirements. For instance, in February 2025, Mahindra unveiled a dedicated EV manufacturing and battery assembly facility in Chakan to produce its Electric Origin SUVs using highly automated production systems. Furthermore, advancements in battery technology, which have led to longer driving ranges and shorter charging times, have alleviated range anxiety, fostering greater confidence in the feasibility of electric vehicles and encouraging wider adoption.
Vehicle Class Insights
The economy segment accounted for the largest share of the global passenger car market, representing around 85.0% of revenue in 2025. Demand remains strong as expanding middle-income populations, particularly across emerging economies, continue to prioritize affordable personal mobility. Economy cars offer an attractive balance of competitive pricing, fuel efficiency, and low maintenance costs, making them well-suited for first-time buyers and budget-conscious consumers. Rising fuel price volatility has further strengthened the appeal of fuel-efficient models, encouraging automakers to expand their affordable vehicle portfolios while incorporating improved safety and comfort features. For instance, in June 2025, Maruti Suzuki launched the 2025 Grand Vitara S-CNG, featuring enhanced safety technologies and a fuel efficiency of 26.6 km/kg, further strengthening its value-oriented passenger vehicle portfolio.
The luxury segment is expected to register significant growth from 2026 to 2033, driven by rising disposable incomes and the expanding affluent population, particularly in emerging markets. Consumer demand is increasingly shifting beyond premium aesthetics toward vehicles that deliver advanced technology, superior comfort, and personalized driving experiences. Luxury automakers are responding by integrating sophisticated driver assistance systems, AI-enabled infotainment platforms, connected services, and electrified powertrains into their flagship models. In addition, the growing availability of premium electric vehicles is broadening the segment's appeal among environmentally conscious, high-income consumers. As technological innovation increasingly defines the luxury ownership experience, the segment is expected to maintain strong growth throughout the forecast period.
Type Insights
The SUV segment accounted for the largest share of the global passenger car market, exceeding 50.0% in 2025. Consumer preference continues to shift toward SUVs due to their versatility, spacious interiors, elevated driving position, and ability to accommodate both urban commuting and long-distance travel. The segment has also benefited from growing demand for vehicles equipped with advanced safety systems, connected technologies, and premium comfort features. Automakers are responding by expanding their SUV portfolios across multiple price points while integrating next-generation driver assistance and digital capabilities. For instance, in June 2025, Mahindra & Mahindra introduced Level 2 Advanced Driver Assistance Systems (ADAS) in the Scorpio-N, reinforcing the model's safety, technology, and premium positioning within the SUV segment.
The sedan segment is expected to register the fastest CAGR from 2026 to 2033. Demand is being supported by consumers seeking vehicles that combine driving comfort, fuel efficiency, aerodynamic performance, and advanced technology at competitive price points. Modern sedans are increasingly being equipped with connected infotainment systems, electrified powertrains, and enhanced safety features, improving their appeal among urban commuters and family buyers. In addition, the growing availability of electric and hybrid sedan models is broadening the segment's addressable market. In December 2023, BYD launched the fully electric BYD SEAL in Mexico, featuring the company's Blade Battery technology, designed to deliver enhanced safety, durability, and driving performance.
Regional Insights
The Asia Pacific passenger cars market accounted for a revenue share exceeding 60.0% in 2025. The Asia Pacific region has witnessed a surge in demand for passenger cars, driven by rapid economic growth in countries such as China, India, and Southeast Asian nations, which has expanded the middle class and increased disposable incomes.
 To learn more about this report, Download Free Sample Report
China Passenger Cars Market Trends
The passenger cars market in China accounted for a significant revenue share in 2025. The growth of passenger cars in China is attributed to the region's burgeoning urbanization, which has increased the need for convenient, reliable transportation, spurring a preference for passenger cars over public transportation.
The Japan passenger cars market is projected to grow at a notable CAGR from 2026 to 2033. The cultural emphasis on individual mobility and the convenience of personal transportation are particularly contributing to a high demand for passenger cars in Japan.
The passenger cars market in India is expected to grow during the forecast period. The growing infrastructural development, including the construction of improved roads and highways, has further facilitated the adoption of cars, making them a more practical mode of commuting in India.
North America Passenger Cars Market Trends
The North America passenger cars market is expected to grow at a notable CAGR in 2026-2033. A robust economy plays a significant role in driving the demand for passenger cars in North America. Rising disposable income and higher employment rates are driving consumers' purchasing power and willingness to invest in personal cars in North America.
The U.S. passenger cars market is driven by innovations in automotive technology, such as electric vehicles, advanced safety systems, autonomous driving features, and infotainment options. These technological advancements attract customers seeking modern, feature-rich vehicles. Consumers are increasingly prioritizing safety, comfort, and fuel efficiency, driving demand for SUVs, crossovers, and fuel-efficient cars.
Europe Passenger Cars Market Trends
The passenger cars market in Europe is anticipated to register the fastest CAGR from 2026 to 2033. Stringent environmental regulations imposed by the European Union have prompted an accelerated shift towards electric and hybrid vehicles. As a result, this is anticipated to increase the demand for passenger cars in Europe over the forecast period.
The passenger cars market in the UK is projected to grow at a notable CAGR from 2026 to 2033. The push for reduced carbon emissions and the implementation of ambitious targets for a greener future have led the UK to offer incentives and subsidies for electric car purchases, fostering a surge in demand for sustainable vehicles.
The Germany passenger cars market is projected to grow at a notable CAGR from 2026 to 2033. The proliferation of smart mobility solutions, including ride-sharing services and integrated transport networks, has influenced how Germany perceives car ownership, with many opting for shared mobility over traditional car ownership.
The passenger cars market in France is expected to grow from 2026 to 2033. Growing concerns over rising levels of vehicular emissions have triggered a paradigm shift from conventional vehicles to EVs, and automotive incumbents are responding promptly by introducing innovative EVs for both personal and commercial applications in France.
Latin America Passenger Cars Market
The Latin America passenger cars market accounted for a notable share of the global revenue in 2025. In recent years, Latin America has witnessed a notable shift in EV buyer trends, reflecting growing awareness of environmental concerns and advances in EV technology.
The Brazil passenger cars market is anticipated to grow during the forecast period. The primary drivers of passenger car sales in Brazil are a robust economy and rising urbanization. The demand for passenger cars in the country is experiencing significant growth due to a burgeoning middle class and a shift towards a more consumer-driven economy.
Middle East & Africa Passenger Cars Market
The Middle East & Africa passenger cars market is expected to grow owing to rising government expenditures in infrastructure development and large infrastructure projects. The construction industry is expanding, particularly in emerging nations, driven by numerous opportunities in residential, infrastructure, and non-residential development.
The passenger cars market in Saudi Arabia is driven by government initiatives to promote the manufacturing and adoption of EVs in the country. As a result, manufacturers recognize the region's potential for EVs, owing to its rising urbanization and population growth. This increases demand for passenger cars in the country.
The South Africa passenger car market is projected to grow steadily from 2026 to 2033, driven by increasing investments in electric mobility and an expanding automotive ecosystem. Growing consumer awareness, supportive government initiatives, and improved charging infrastructure are boosting the adoption of electric and hybrid vehicles. Global automakers are also enhancing their presence to tap into the region's growth. For instance, in November 2025, Geely Auto launched the all-electric E5 and the plug-in hybrid E5 EM-i, with plans to expand its dealership network, further supporting EV adoption and market growth.
Key Passenger Cars Company Insights
Some of the leading companies operating in the global passenger car market include Volkswagen AG, General Motors Company, Tesla, Inc., Ford Motor Company, Mercedes-Benz Group AG, AUDI AG, and BMW AG.
- General Motors Company continues to expand its portfolio of electric and hybrid vehicles, supported by investments in battery technology, software-defined vehicles, and advanced mobility solutions to address the growing demand for sustainable transportation.
- Tesla, Inc. remains a key industry innovator, driving competition through advancements in electric vehicle technology, autonomous driving capabilities, and connected software platforms, prompting traditional automakers to accelerate their electrification strategies.
Emerging participants in the market include Hyundai Motor India Limited, Suzuki Motor Corporation, Nissan Motor Co., Ltd., Renault Group, Tata Motors Limited, and Kia India Private Limited.
- Suzuki Motor Corporation continues to strengthen its global presence through competitively priced, fuel-efficient vehicles, strategic alliances, and an expanding portfolio of hybrid models.
- Renault Group offers a diversified vehicle portfolio spanning passenger cars, SUVs, MPVs, commercial vehicles, and electric vehicles, marketing its products under the Renault, Dacia, Alpine, Mobilize, and Lada brands.
Key Passenger Cars Companies
The following key companies have been profiled for this study on the passenger cars market:
-
AUDI AG
-
BMW AG
-
Ford Motor Company
-
General Motors Company
-
Honda Cars India Limited
-
Suzuki Motor Corporation
-
Hyundai Motor India Limited
-
Kia India Pvt. Limited
-
Mercedes-Benz Group AG
-
Nissan Motor Co., Ltd.
-
Renault Group
-
TATA Motors Limited
-
Tesla, Inc.
-
Volkswagen AG
Recent Developments
-
In January 2025, Kia India commenced mass production of the Kia Syros SUV at its manufacturing facility in Anantapur, Andhra Pradesh. Developed specifically for the Indian market, the Syros features advanced driver-assistance technologies, connected-vehicle capabilities, and a spacious cabin, strengthening Kia's passenger-vehicle portfolio in the fast-growing SUV segment.
-
In June 2024, Tata Motors launched the Altroz Racer, a performance-oriented hatchback powered by a 1.2L turbocharged petrol engine. The model features a 360-degree camera, six airbags, connected-car technologies, and enhanced performance specifications, expanding Tata Motors' premium hatchback portfolio.
-
In January 2023, BYD launched its premium Yangwang brand, introducing the U8 luxury off-road SUV and the U9 all-electric supercar. The launch, built on the company's e⁴ Platform, marked BYD's expansion into the premium electric passenger vehicle segment with high-performance, technology-focused models.
Passenger Cars Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3,667.5 Billion
Estimated market size in 2026
USD 3,929.3 Billion
Projected market size by 2033
USD 13,888.6 Billion
Growth Rate
CAGR of 19.8 % from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Propulsion Type, Vehicle Class, Type, And Region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand, South Korea; Brazil; Argentina, South Africa, UAE
Key companies profiled
AUDI AG; BMW AG; Ford Motor Company; General Motors Company; Honda Cars India Limited; Suzuki Motor Corporation; Hyundai Motor India Limited; Kia India Pvt. Limited; Mercedes-Benz Group AG; Nissan Motor Co., Ltd.; Renault Group; TATA Motors Limited; Tesla, Inc.; Volkswagen AG
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Passenger Cars Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global passenger cars market report based on propulsion type, vehicle class, type, and region:
-
Propulsion Type Outlook (Volume, Units; Revenue, USD Billion, 2021 - 2033)
-
ICE
-
Electric
-
-
Vehicle Class Outlook (Volume, Units; Revenue, USD Billion, 2021 - 2033)
-
Luxury
-
Economy
-
-
Type Outlook (Volume, Units; Revenue, USD Billion, 2021 - 2033)
-
Hatchback
-
MUV
-
Sedan
-
SUV
-
Others
-
-
Region Outlook (Volume, Units; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global passenger cars market size was valued at USD 3,667.5 billion in 2025 and is estimated at USD 3,929.3 billion for 2026.
The global passenger cars market is expected to grow at a CAGR of 19.8 % from 2026 to 2033, reaching USD 13,888.6 billion
Key players in the market include AUDI AG; BMW AG; Ford Motor Company; General Motors Company; Honda Cars India Limited; Suzuki Motor Corporation; Hyundai Motor India Limited; Kia India Pvt. Limited; Mercedes-Benz Group AG; Nissan Motor Co., Ltd.; Renault Group; TATA Motors Limited; Tesla, Inc.; Volkswagen AG; and others
The SUV segment accounted for the largest revenue share of approximately 50.0% in 2025.
Asia Pacific dominated with an over 60.0% revenue share in 2025
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


