
- Home
- »
- Medical Devices
- »
-
Peptide Contract Manufacturing Market Report, 2026-2033GVR Report cover

Peptide Contract Manufacturing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Category, By Service (API Manufacturing, Finished Drug Products Manufacturing), By Workflow, By Therapeutic Area, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$1.5BMarket Estimate, 2026
$1.6BMarket Forecast, 2033
$3.6BCAGR, 2026–2033
12.1%Peptide Contract Manufacturing Market Summary
The global peptide contract manufacturing market size was valued at USD 1.5 billion in 2025 and is projected to grow from USD 1.6 billion in 2026 to USD 3.6 billion by 2033, at a CAGR of 12.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 45.2% in 2025. The market is driven by rising demand for GLP-1 therapies, expanding oncology applications, increasing outsourcing by pharmaceutical and biotechnology companies, growing clinical peptide production requirements, and greater demand for complex and modified peptides.
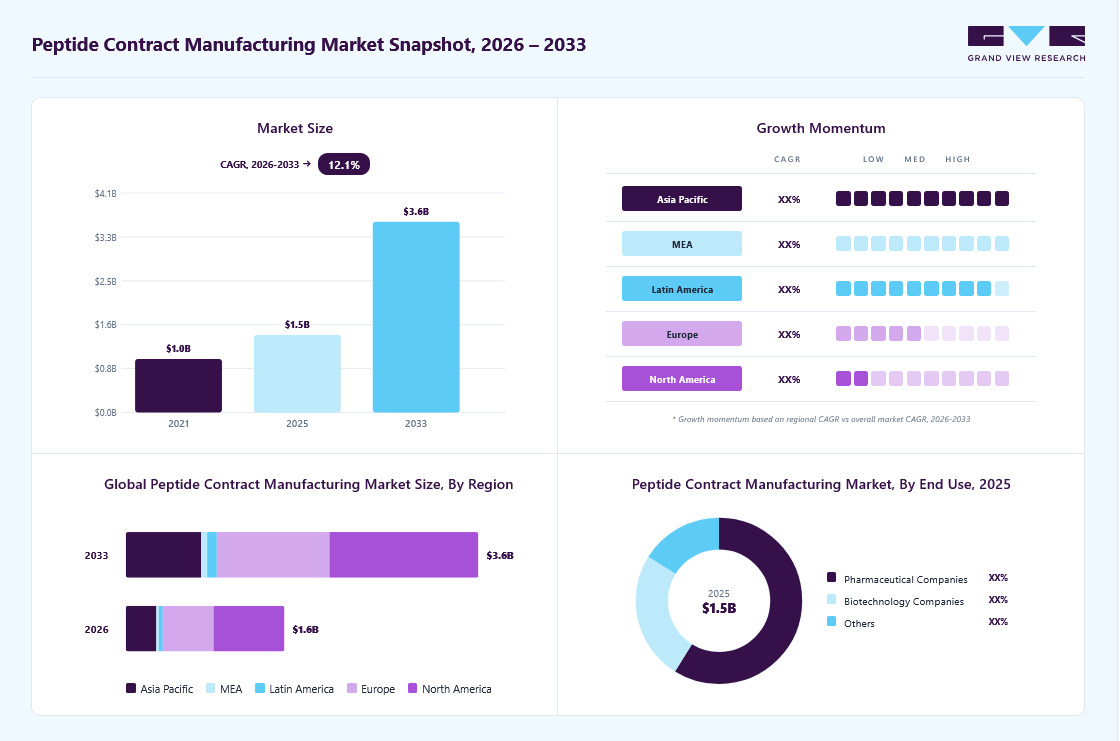 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By category: Therapeutic peptides segment led the market with the largest revenue share of 64.7% in 2025.
- By service: API manufacturing segment led the market with the largest revenue share of 54.6% in 2025.
- By workflow: Commercial segment led the market with the largest revenue share of 76.9% in 2025.
- By therapeutic area: Metabolic disorders segment led the market with the largest revenue share of 56.4% in 2025.
- By end use: Pharmaceutical companies segment led the market with the largest revenue share of 58.8% in 2025.
Regional Highlights
- Market size in 2025: North America (45.2% revenue share, 2025)
- Estimated market size in 2026: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.5 Billion
- Estimated market size in 2026: USD 1.6 Billion
- Projected market size by 2033: USD 3.6 Billion
- CAGR (2026-2033): 12.1%
GVR research-powered AIAsk Prism AI about the peptide contract manufacturing marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
Furthermore, recurring commercial manufacturing requirements support sustained procurement of peptide APIs and finished drug products. Moreover, sponsors seeking qualified capacity and diversified supply arrangements are expected to create new opportunities for manufacturers offering reliable synthesis, purification, and batch delivery. In addition, research-grade, preclinical, diagnostic, and imaging applications broaden demand for customized peptide production. Thus, these factors are expected to drive the growth of the peptide contract manufacturing market over the forecast period.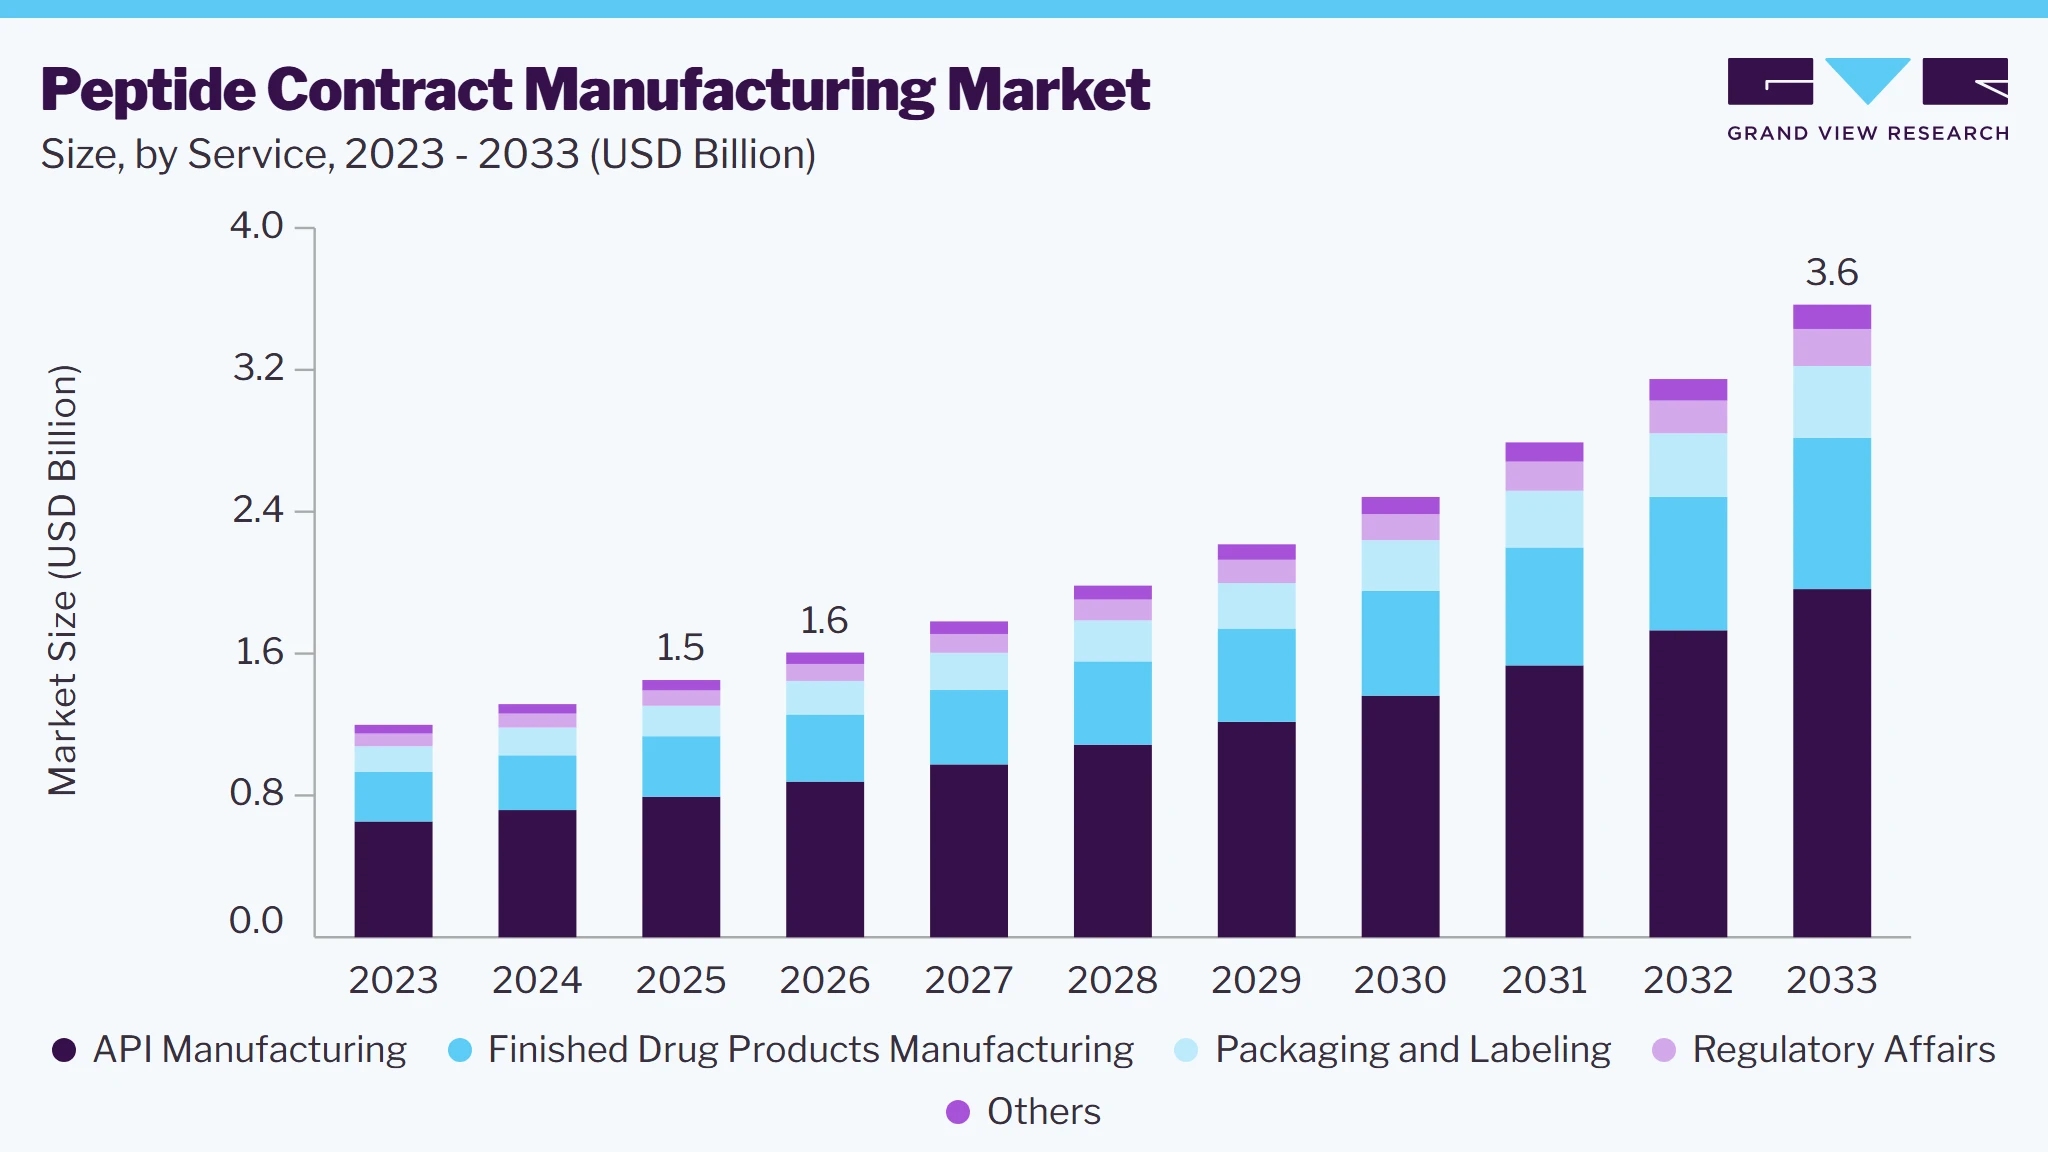 To learn more about this report, Download Free Sample Report
The market growth is due to the advancement of peptide candidates from clinical trials toward commercialization, which increases requirements for manufacturing capacity, larger production batches, and consistent supply. Besides, biotechnology companies with limited in-house manufacturing capacity rely on contract manufacturers to meet clinical and commercial production requirements. Currently, most pharmaceutical companies outsourcing selected manufacturing activities to supplement in-house capacity, diversify their supplier base, and maintain supply continuity. In addition, demand for peptide fragments, APIs, finished drug products, and packaging services create opportunities across multiple stages of contract manufacturing. Geographic diversification further supports outsourcing as pharmaceutical and biotechnology companies seek alternative suppliers and reduce reliance on individual manufacturing sites. However, market growth remains dependent on clinical program progression, customer funding, and the utilization of newly qualified capacity through commercial manufacturing contracts.
Moreover, technological advancements, including automated peptide synthesis, hybrid synthesis methods, advanced chromatography, in-process monitoring, and solvent recovery, support market growth by improving production efficiency, product quality, and cost control. Automated synthesis enables precise control over repetitive steps, helping manufacturers maintain batch consistency and reduce manual intervention. In addition, advanced chromatography improves the separation of closely related impurities and increases the recovery of peptide APIs that meet quality specifications. These capabilities help contract manufacturers address complex production requirements and support reliable clinical and commercial supply.
The peptide contract manufacturing market comprises established peptide manufacturers, diversified pharmaceutical service providers, and companies expanding their peptide production capabilities. Key players compete on manufacturing expertise, qualified capacity, regulatory compliance, pricing, and delivery reliability. Capacity expansions, acquisitions, and partnerships support efforts to broaden service offerings and strengthen geographic presence. In addition, manufacturers offering both API and finished drug product production can attract customers seeking coordinated supply across manufacturing stages. Specialist providers differentiate through capabilities in complex sequences, modified peptides, and flexible batch production. Maintaining a competitive position requires consistent product quality, efficient capacity utilization, and long-term customer relationships, while managing pricing pressure and changes in customer production requirements.
Market Dynamics:
The expansion of GLP-1 manufacturing requirements drives the peptide contract manufacturing market by increasing demand for commercial API production, repeat manufacturing batches, and qualified capacity. The ongoing treatment requirements associated with these therapies support recurring supply needs, while additional product launches can increase production volumes. Besides, specialized synthesis, purification, and impurity control requirements can constrain pharmaceutical companies’ ability to expand output within existing facilities. Thus, outsourcing enables these companies to access additional capacity and technical expertise without establishing every manufacturing stage internally.
In addition, pharmaceutical companies may engage qualified contract manufacturers to diversify their supplier base and reduce dependence on individual production sites. Contracts can cover peptide fragment production, bulk API manufacturing, and finished dosage manufacturing, depending on the company’s sourcing strategy. Thus, rising production volumes, manufacturing complexity, capacity constraints, and supply diversification are expected to support the growth of the peptide contract manufacturing market.
High manufacturing costs can restrain the peptide contract manufacturing market by increasing the cost of outsourced production. Complex peptides require specialized raw materials, reagents, resins, and solvents, which contribute to overall manufacturing expenses. Lower production yields further increase material requirements, while additional purification steps extend processing time and raise costs. In addition, manufacturers must invest in quality testing, qualified equipment, and waste management to meet customer specifications. These expenses can limit pricing flexibility, particularly for small batches and complex peptide products. Pharmaceutical and biotechnology companies with limited budgets may postpone orders or retain selected manufacturing activities internally when this is more economical. Contract manufacturers must therefore balance competitive pricing with consistent product quality and reliable delivery. Thus, high production costs can limit outsourcing opportunities and affect the commercial viability of certain peptide manufacturing contracts.
The development of complex and cyclic peptide therapies creates opportunities for contract manufacturers with specialized synthesis and purification capabilities. These peptides ideally require cyclization, modified amino acids, and additional processing steps that pharmaceutical and biotechnology companies lack within existing facilities. Besides, strict purity requirements increase the need for experienced suppliers capable of producing consistent batches and controlling impurities. In addition, the progression of peptide candidates into clinical trials creates demand for qualified APIs and investigational drug products. Manufacturers that establish reliable supply during early clinical stages may secure further contracts as production requirements increase. Besides, the market opportunities are due to analytical testing and finished drug product manufacturing when included in customer agreements. Thus, suppliers offering specialized technical expertise, flexible batch production, and dependable quality can strengthen their position in this segment. The conversion of these opportunities into commercial revenue remains dependent on clinical outcomes and customers’ outsourcing decisions.
Maintaining consistent product quality during scale-up remains a key challenge in peptide contract manufacturing. Changes in batch size, equipment, and processing conditions can affect impurity levels and purification performance. Peptide-related impurities may closely resemble the intended product, making their separation and measurement difficult. Besides, higher synthesis volumes require sufficient purification and testing capacity to prevent delays in batch release. In addition, transferring production between facilities requires manufacturers to demonstrate that the process consistently meets agreed quality specifications. Failure to maintain these standards can result in batch rejection, additional processing, higher costs, and delayed deliveries. Besides, contract manufacturers must align synthesis, purification, and analytical testing capacity with increasing production volumes. Reliable process controls, validated testing methods, and qualified equipment help maintain consistent product quality and timely batch release. Thus, scaling production while meeting quality specifications and delivery schedules is essential to fulfilling customer contracts and maintaining commercial supply.
Impact of U.S. Tariffs on the Global Peptide Contract Manufacturing Market
U.S. tariffs influence the peptide contract manufacturing market by affecting the cost of importing peptide APIs and finished drug products. The impact varies according to product classification, country of origin, and eligibility for exemptions or preferential treatment. Under the pharmaceutical section 232 framework, covered patented products and associated ingredients face different tariff treatment from qualifying generic medicines and clinical or research materials. Pharmaceutical companies must therefore assess the applicable duties when comparing domestic and overseas manufacturing options.
Higher import costs may encourage companies to renegotiate supply agreements, qualify alternative manufacturers, or consider U.S. production. However, transferring peptide manufacturing requires process qualification, impurity assessment, and regulatory coordination, which can delay changes in sourcing. Overseas suppliers may remain competitive where lower manufacturing costs or applicable tariff exemptions offset import duties. Contract negotiations may also place greater emphasis on responsibility for duties and adjustments to manufacturing prices. Thus, tariffs can influence supplier selection, production locations, and contract terms, while the extent of any shift depends on product-specific tariff exposure, qualified manufacturing capacity, and the cost of transferring production.
Technological Advancements
 To learn more about this report, Download Free Sample Report
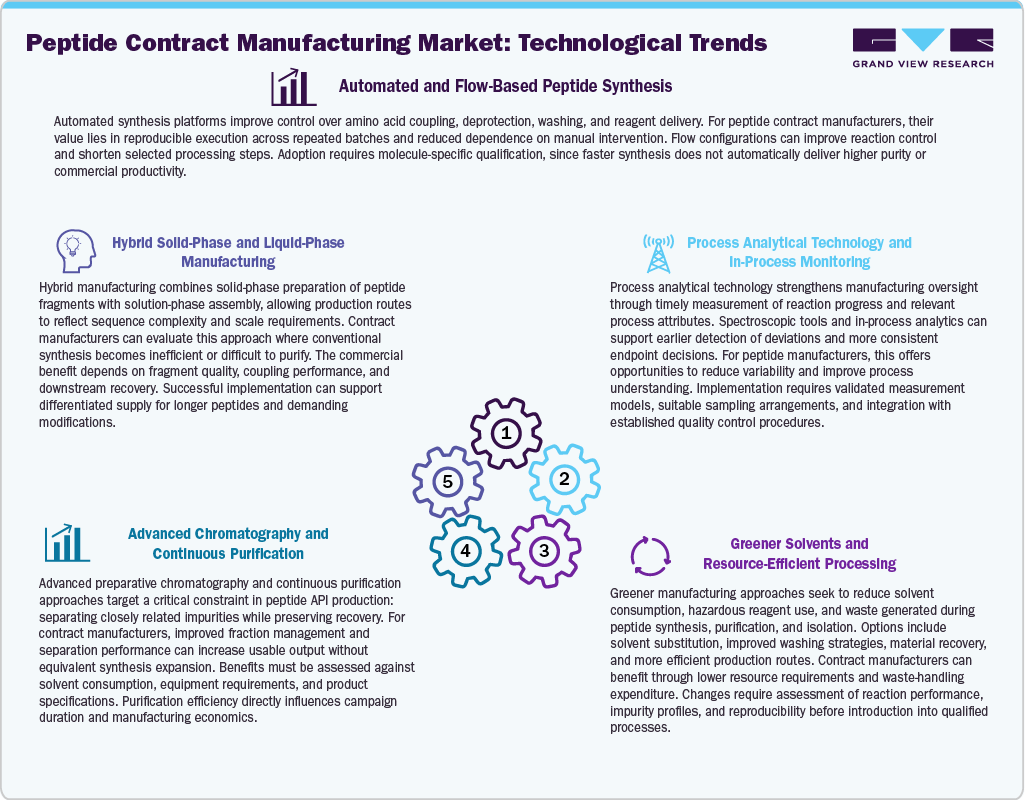
Technological advancements in peptide contract manufacturing focus on improving production yields, maintaining consistent batch quality, and reducing manufacturing costs. These advancements include automated synthesis, flow processing, hybrid synthesis methods, advanced purification, and process analytical technology. Automated synthesis improves control over repetitive production steps, while flow processing enables closer control of reaction conditions. Hybrid methods combine solid-phase and liquid-phase synthesis to support the manufacture of complex peptide sequences.
In addition, advanced chromatography and continuous purification help manufacturers separate closely related impurities and improve the recovery of peptide APIs that meet quality specifications. Process analytical technology supports the monitoring of manufacturing conditions and the early identification of deviations. Improvements in solvent selection, washing methods, and material recovery can also reduce resource consumption and waste-handling costs.
Thus, the commercial benefits of these technologies depend on their suitability for the peptide, production scale, and required quality standards. Manufacturers must therefore evaluate investments against customer demand, existing production constraints, and expected operating savings. Integrating appropriate technologies across synthesis, purification, and isolation can help contract manufacturers improve efficiency, maintain product quality, and meet clinical and commercial supply requirements. These factors are expected to drive the market growth over the estimated time period.
Pricing Model Analysis
 To learn more about this report, Download Free Sample Report
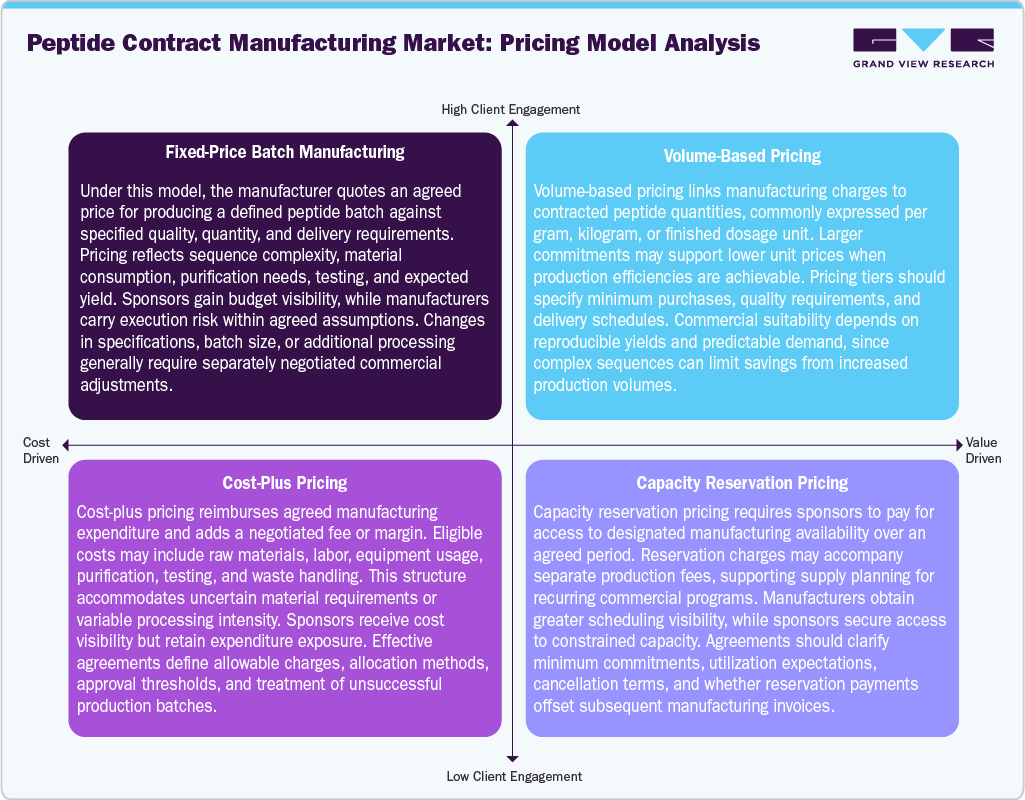
Pricing in the peptide contract manufacturing market depends on production volumes, peptide complexity, material costs, quality requirements, and capacity commitments. Manufacturers and pharmaceutical companies select pricing arrangements according to the predictability of production costs and the scope of contracted services. Fixed-price batch contracts establish an agreed charge for a specified quantity and quality, providing budget certainty when manufacturing requirements are clearly defined. Volume-based pricing links charges to the quantity of API or finished dosage units supplied, with larger commitments potentially supporting lower unit costs.
Cost-plus pricing allows manufacturers to recover agreed production expenses and earn a negotiated margin. This approach accommodates variable processing requirements but requires transparent cost reporting and approval of additional charges. Capacity reservation agreements secure manufacturing availability over a defined period, usually through reservation payments and separate production charges.
In addition, contracts must clearly assign responsibility for raw materials, testing costs, unsuccessful batches, specification changes, and cancellations. The suitability of each model depends on process maturity, demand visibility, and supply requirements. Companies may combine capacity reservation with batch or volume-based pricing to secure production access while maintaining clear terms for manufacturing costs and delivery commitments.
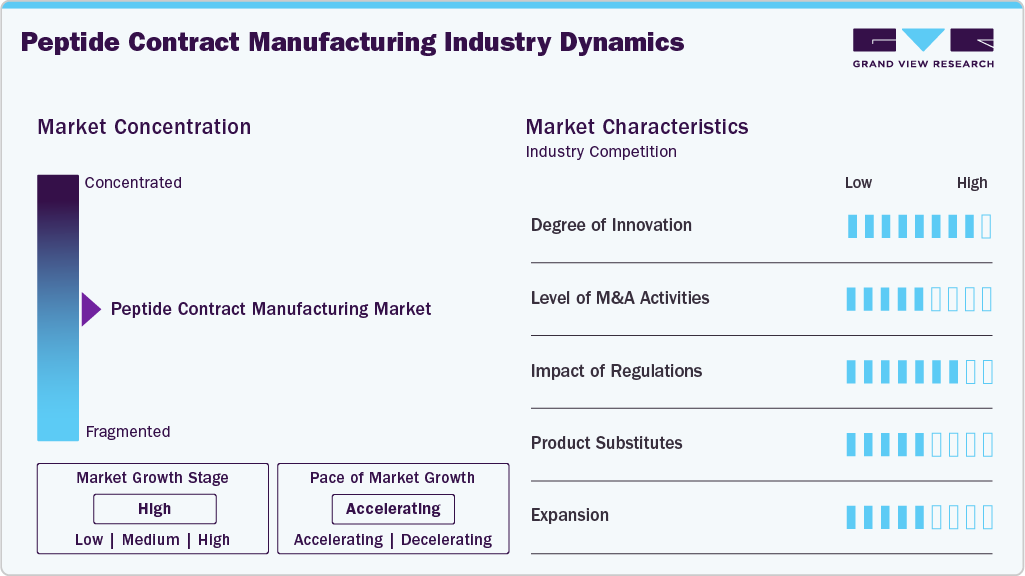
Market Concentration & Characteristics
Acquisitions and strategic partnerships enable manufacturers to expand technical capabilities, access qualified facilities, and strengthen customer relationships. Combining complementary synthesis, purification, and finished drug product operations allows providers to address a broader range of manufacturing requirements. In addition, these transactions can extend geographic coverage and improve supply options. Their commercial benefits depend on successful integration, retention of technical expertise, and effective coordination across facilities.
Regulatory requirements influence supplier qualification, production timelines, and manufacturing costs. Peptide manufacturers must maintain effective impurity controls, validated analytical methods, raw material traceability, and consistent batch quality. Besides, new facilities and transferred processes require appropriate qualification before supporting customer supply. Thus, regulatory readiness and complete manufacturing documentation are important to securing contracts and maintaining reliable clinical and commercial production.
 To learn more about this report, Download Free Sample Report
Manufacturers are broadening their offerings to include peptide API production, purification, manufacturing-related testing, finished dosage manufacturing, packaging, and regulatory support. The availability of connected services can simplify supplier management and improve coordination between production stages. In addition, broader capabilities allow manufacturers to pursue more activities within customer supply agreements. Revenue from standalone discovery and development services remains separate from the defined contract manufacturing market.
Manufacturers are expanding their geographic presence to improve customer access, diversify production locations, and address regional supply requirements. Additional facilities can provide alternative sourcing options and accommodate different production scales. Besides, investment decisions depend on access to skilled personnel, raw materials, utilities, and suitable downstream infrastructure. Thus, regional expansion supports business growth when facilities achieve qualifications and secure sufficient customer contracts to sustain production.
Analyst Perspective
The peptide contract manufacturing market is driven by rising demand for specialized manufacturing expertise, reliable supply, scalable production, and consistent product quality. Therapeutic, research, diagnostic, and specialty applications create different requirements for peptide synthesis, purification, and testing. Besides, growing production requirements for metabolic therapies support outsourcing where sponsors need additional capacity or specialized capabilities. Oncology programs also create opportunities for manufacturers experienced in complex sequences and structural modifications. Supplier selection depends on manufacturing efficiency, impurity control, regulatory compliance, pricing, and delivery performance. Moreover, capacity expansion must align with customer commitments and sufficient purification and testing capabilities to support production volumes.
Category Insights
Based on category, the therapeutic peptides segment led the market with the largest revenue share of 64.7% in 2025. The segment is driven by rising demand for GLP-1 medicines, expanding oncology applications, the progression of peptide candidates toward commercialization, and outsourcing of specialized peptide production. The ongoing demand for approved peptide medicines supports recurring orders for APIs and finished drug products. Besides, the production of complex and modified peptides requires specialized synthesis and purification capabilities, encouraging pharmaceutical companies to engage qualified contract manufacturers. In addition, the need to supplement internal capacity and diversify supply creates opportunities for long-term manufacturing agreements. Thus, recurring commercial orders and the progression of therapeutic peptide candidates toward commercialization are expected to support segment growth.
On the other hand, the research-grade & preclinical peptides segment is projected to grow at a significant CAGR during the forecast period. The segment is driven by peptide-based drug discovery, target validation studies, preclinical testing, and demand for modified or labeled peptides used in biological assays. Research programs require custom peptide sequences to evaluate biological activity and compare potential drug candidates, supporting demand for small-batch manufacturing. Moreover, labeled and structurally modified peptides require specialized synthesis and characterization, creating opportunities for contract manufacturers with relevant technical capabilities. In addition, further testing and sequence modifications can generate repeat orders as research progresses. Thus, ongoing peptide research and preclinical studies are expected to support segment growth, with supplier selection influenced by sequence accuracy, application-specific purity, and delivery timelines.
Service Insights
The API manufacturing segment led the market with the largest revenue share of 54.6% in 2025. The segment is driven by rising demand for GLP-1 APIs, recurring commercial supply requirements, increasing clinical peptide production, and outsourcing of complex synthesis and purification activities. Approved peptide medicines require repeated manufacturing batches, supporting ongoing orders from pharmaceutical companies. Besides, complex sequences and strict impurity specifications encourage customers to engage manufacturers with specialized production capabilities. In addition, companies seeking to supplement internal capacity and qualify alternative suppliers create opportunities for long-term API supply agreements. Thus, sustained commercial demand and advancing clinical programs support the segment’s leading position.
The finished drug products manufacturing segment is anticipated to register the fastest growth during the forecast period. The segment is supported by increasing peptide injectable production, the commercialization of clinical candidates, demand for specialized sterile manufacturing, and outsourcing by companies with limited in-house dosage manufacturing capacity. Peptide APIs require further processing into finished medicines through compounding, filtration, filling, and, where applicable, lyophilization. Moreover, product stability and compatibility with vials, cartridges, or prefilled syringes require suitable equipment and controlled manufacturing conditions. In addition, providers offering both API and finished drug product manufacturing can simplify supply coordination. These requirements are expected to support demand for qualified finished dosage manufacturing services.
Workflow Insights
The commercial segment accounted for the largest share of 76.9% in 2025. The segment is supported by recurring demand for approved peptide medicines, larger production volumes, long-term supply agreements, and outsourcing to supplement internal manufacturing capacity. In addition, approved products ideally require repeated API and finished drug product batches, creating ongoing opportunities for contract manufacturers. Besides, pharmaceutical companies prioritize consistent quality, reliable delivery, and supply continuity when selecting commercial manufacturing partners. In addition, manufacturers with sufficient synthesis, purification, and testing capacity can support repeat orders under longer-term agreements. However, production volumes remain dependent on product demand, customer inventory levels, and the share of manufacturing retained in-house.
On the other hand, the clinical segment is projected to grow at a significant CAGR duringthe forecast period. The segment is driven by the advancement of peptide candidates into human trials, increasing material requirements across trial phases, demand for specialized manufacturing, and outsourcing by biotechnology companies with limited internal capacity. Clinical contracts can include peptide APIs, investigational drug products, packaging, and labeling. Moreover, changes in patient enrollment, dosing, and study schedules require manufacturers to accommodate different batch quantities and delivery timelines. Suppliers offering flexible production and timely batch release may secure additional orders as programs progress.
Therapeutic Area Insights
The metabolic disorders segment accounted for the largest share of 56.4% in 2025. The metabolic disorders segment is driven by demand for diabetes treatments, the use of GLP-1 therapies for obesity, recurring commercial supply requirements, and outsourcing to supplement internal production capacity. Ongoing treatment supports repeated orders for peptide APIs and finished drug products. Besides, specialized synthesis and purification requirements create new growth opportunities for manufacturers capable of maintaining consistent quality on a commercial scale. Moreover, pharmaceutical companies seeking alternative suppliers can further support longer-term manufacturing agreements. Thus, growing sustained demand and rising need for reliable production capacity are expected to drive the market growth.
On the other hand, the neurological disorders segment is projected to grow at a significant CAGR duringthe forecast period. The segment is driven by peptide-based neurological research, the progression of candidates into clinical trials, demand for structurally modified peptides, and outsourcing of specialized manufacturing activities. Clinical programs require accurately characterized materials and consistent batches for evaluating investigational treatments. Moreover, complex sequences and modifications can require specialized synthesis, purification, and analytical capabilities. As candidates advance, manufacturing requirements may increase with trial enrollment, dosing, and study duration. Suppliers offering reliable quality and flexible production can secure further contracts, although segment growth remains dependent on clinical outcomes, program funding, and customer sourcing decisions. Thus, these factors are expected to support market growth over the estimated time.
End Use Insights
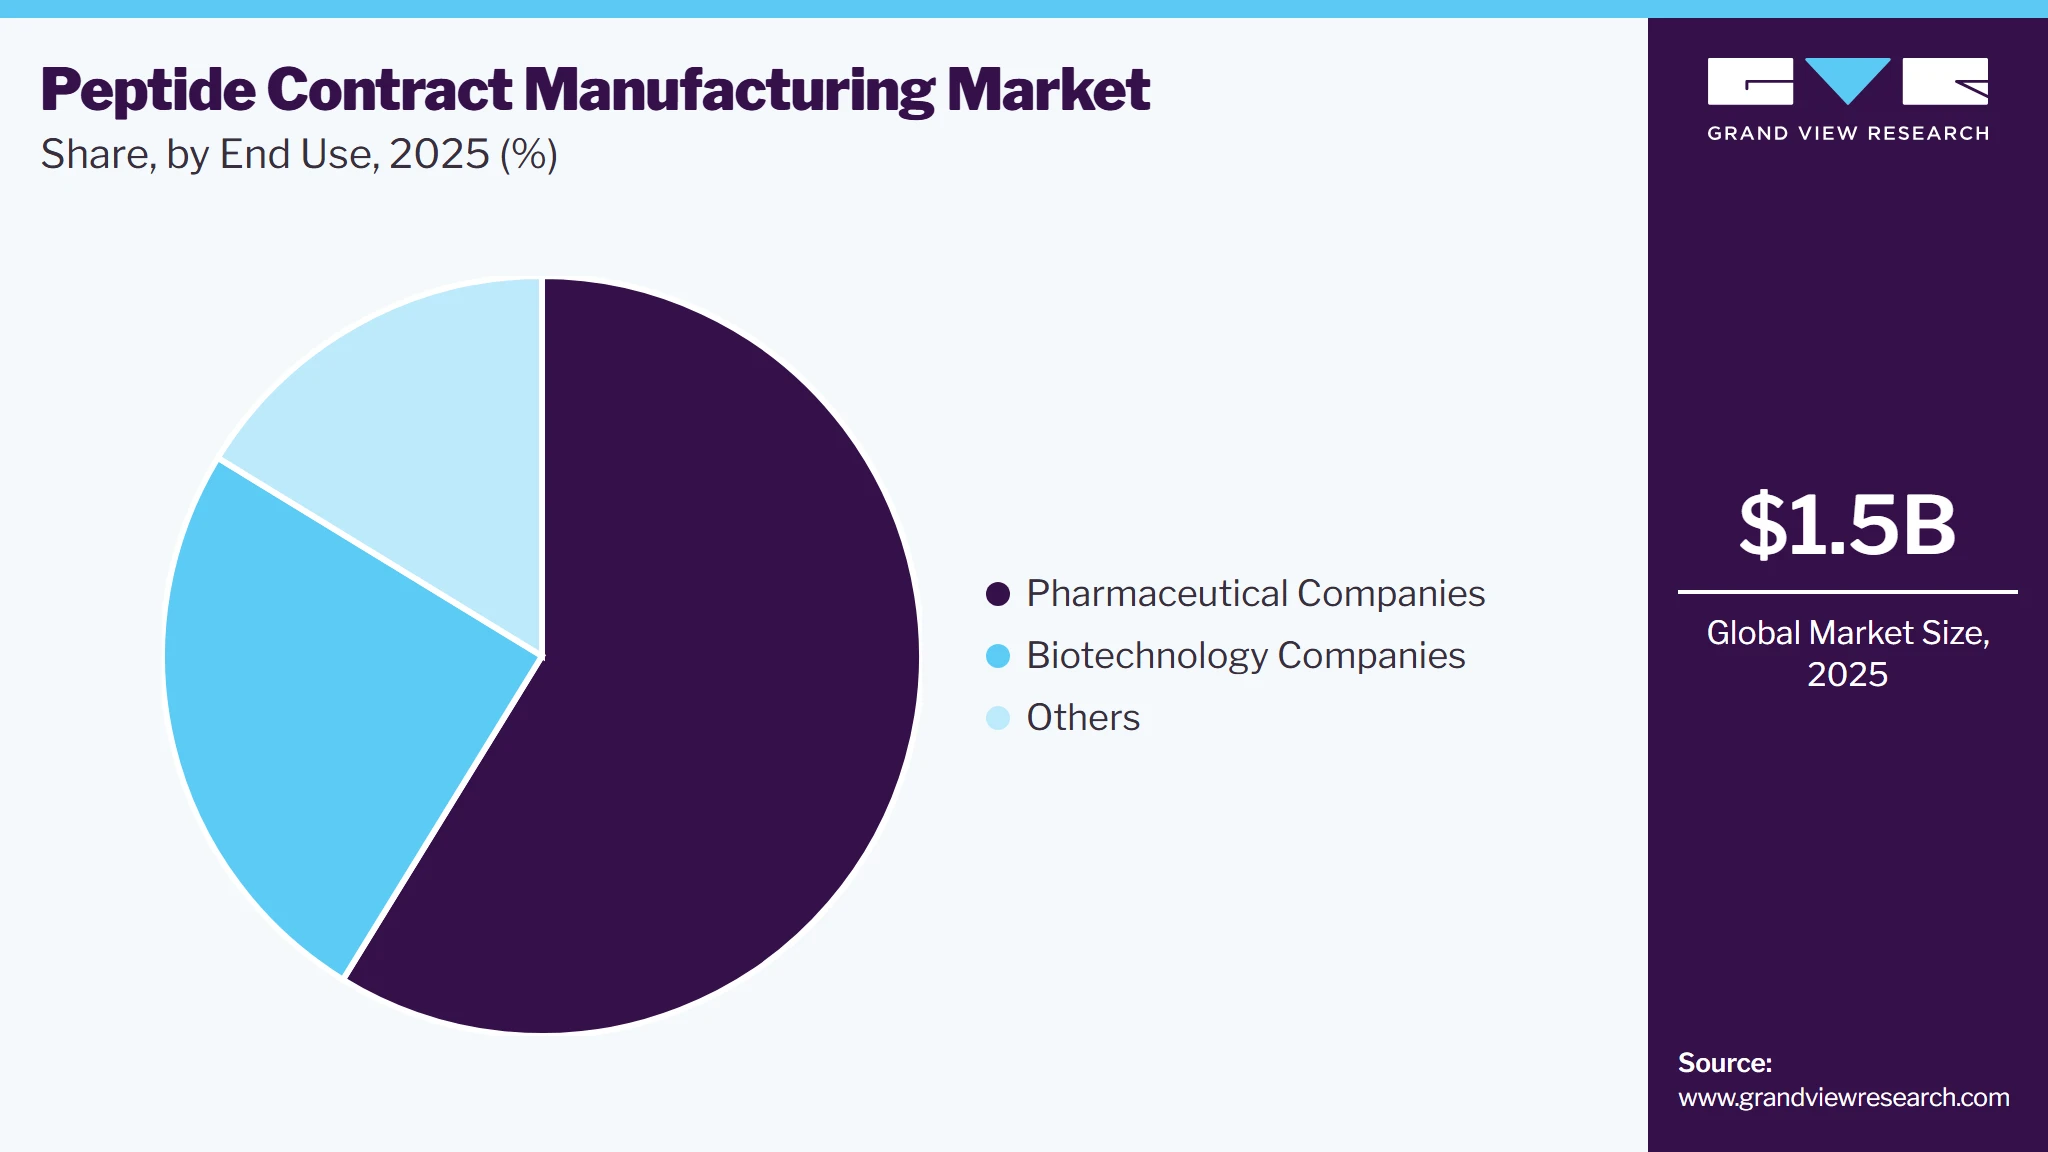
The pharmaceutical companies segment led the market with the largest revenue share of 58.8% in 2025. The segment is driven by established peptide product portfolios, recurring commercial production requirements, outsourcing specialized manufacturing, and supplier diversification. Currently, most pharmaceutical companies are engaging in contract manufacturers to supplement internal capacity and support the production of clinical materials, APIs, and finished drug products. Besides, approved peptide medicines generate repeat manufacturing orders, creating opportunities for long-term supply agreements. In addition, new product launches can increase requirements for qualified external capacity. Supplier selection depends on product quality, manufacturing expertise, pricing, and the ability to meet agreed production volumes and delivery schedules.
 To learn more about this report, Download Free Sample Report
The biotechnology companies’ segment is anticipated to register the fastest growth during the forecast period due to growing peptide-focused research programs, the progression of candidates into clinical trials, limited in-house manufacturing capacity, and demand for specialized production expertise. Biotechnology companies engage external suppliers to manufacture clinical APIs and investigational drug products without investing in dedicated facilities. Moreover, advancing candidates may require larger batches and additional manufacturing services as trials progress. Providers offering flexible production, consistent quality, and reliable delivery can retain customers across successive clinical stages. However, manufacturing demand remains dependent on customer funding, clinical outcomes, and the continuation of individual programs.
Regional Insights
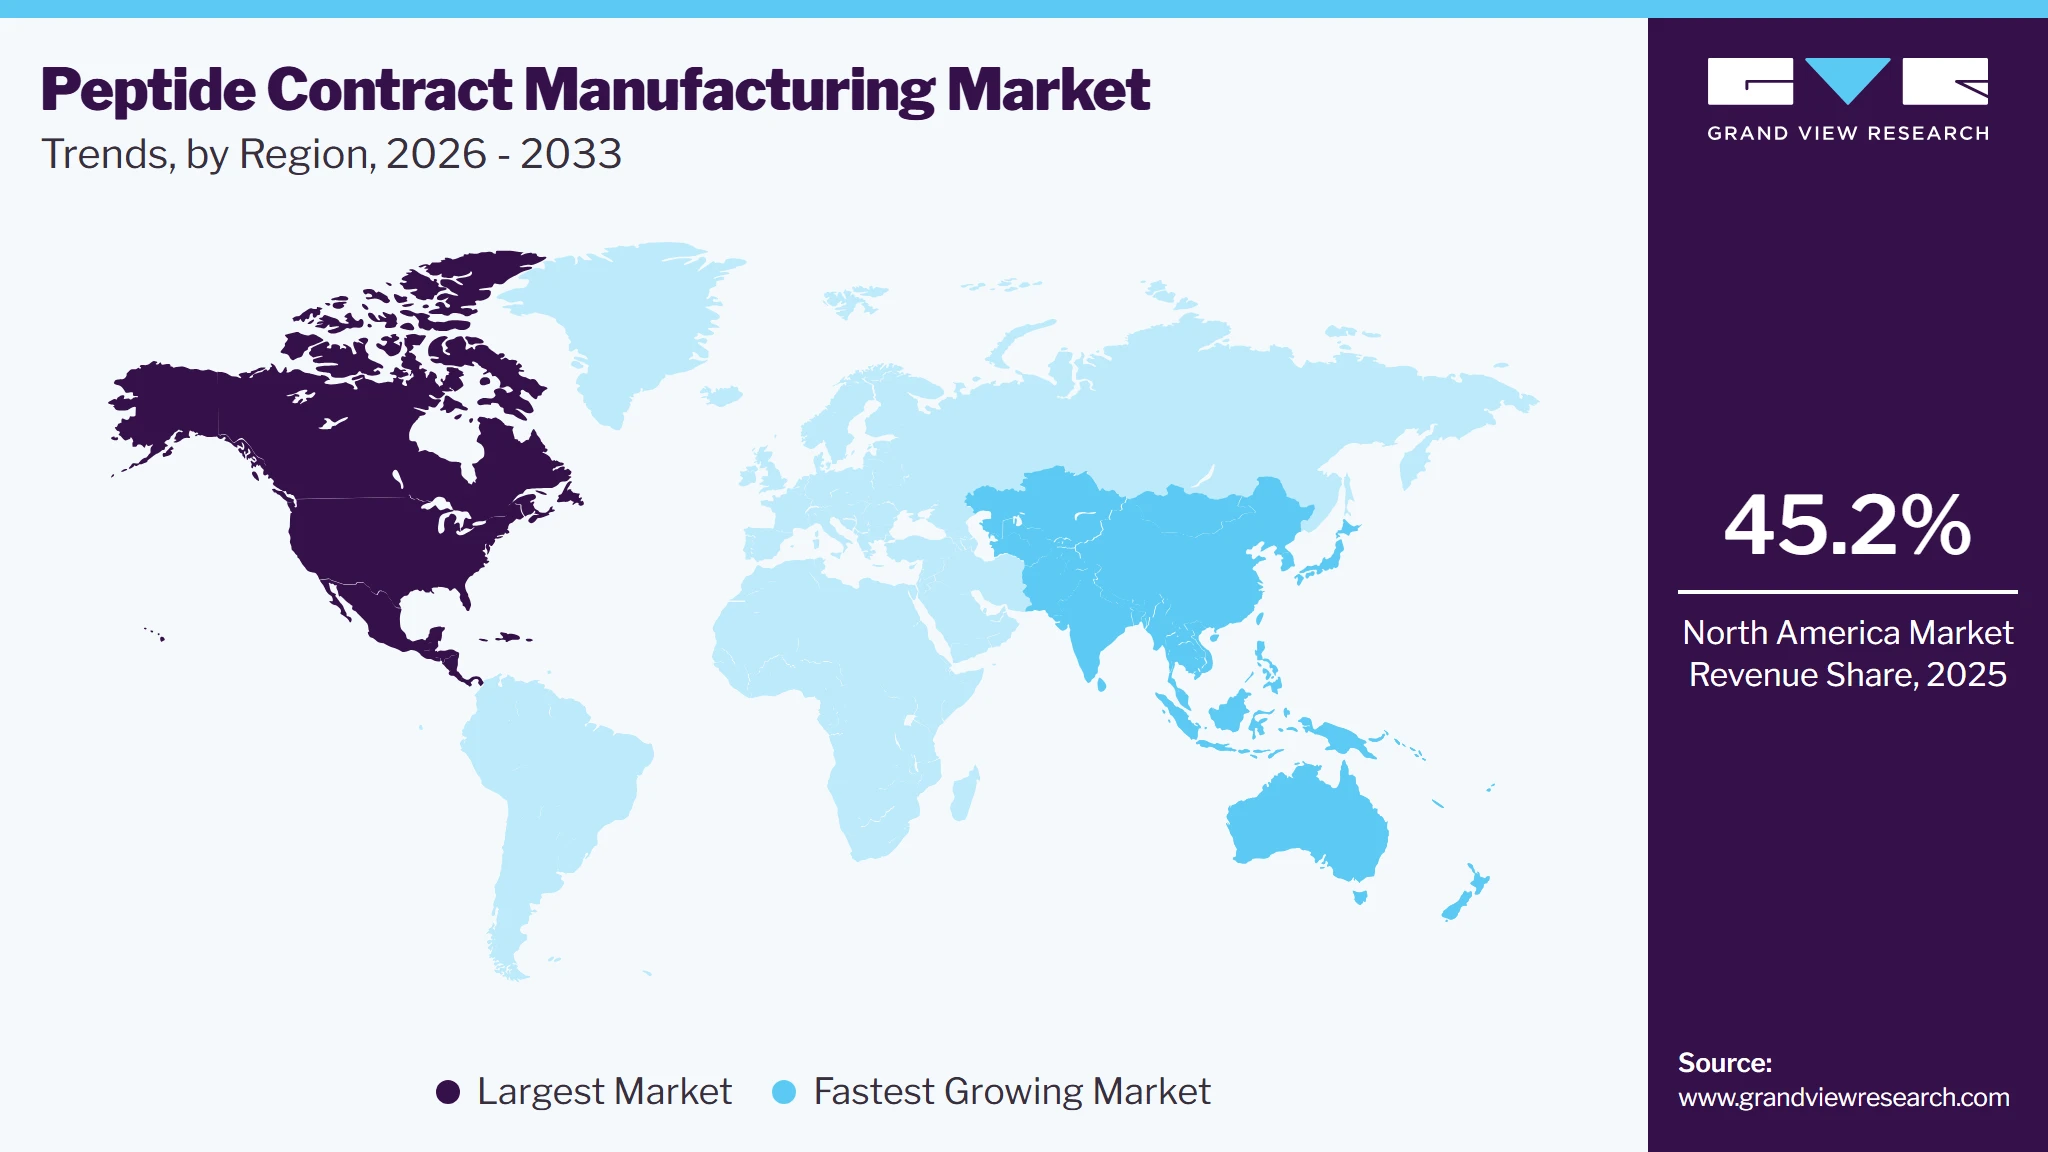
North America dominated the peptide CMO market with the largest revenue share of 45.2% in 2025,driven by commercial peptide production requirements, demand for GLP-1 medicines, clinical manufacturing activity, and outsourcing of specialized production. The region’s pharmaceutical and biotechnology customers require suppliers capable of supporting both investigational materials and recurring commercial batches. Besides, supply diversification encourages the qualification of additional manufacturing partners. In addition, demand for complex and modified peptides supports contracts requiring specialized synthesis and purification. The market is supported by manufacturers’ ability to coordinate API production, quality testing, and finished drug product supply while meeting customer delivery schedules.
 To learn more about this report, Download Free Sample Report
U.S. Peptide Contract Manufacturing Market Trends
The peptide CMO market in the U.S. held the largest share in the North America region in 2025. The country’s growth is driven by commercial demand for metabolic therapies, peptide development programs, specialized manufacturing requirements, and efforts to strengthen domestic supply. Pharmaceutical companies engage external manufacturers to supplement internal production and support additional product launches. Besides, biotechnology companies require clinical manufacturing partners as candidates advance through development. Moreover, contracts covering peptide fragments, APIs, and injectable products create opportunities across production stages. The growth is attributed to demand for qualified capacity that combines consistent product quality with reliable commercial delivery.
The peptide CMO market in Canada is expected to grow steadily over the forecast period, supported by clinical research activity, rising demand for customized peptides, specialized small-batch production, and access to North American pharmaceutical customers. Canadian suppliers can address programs requiring flexible batch quantities and close coordination between API manufacturing and clinical supply. Besides, customers progressing through early trials may require additional production campaigns and manufacturing support. In addition, proximity to U.S. customers can facilitate project coordination and delivery planning. Growth will depend on securing repeat contracts and maintaining consistent quality as customer production requirements increase.
Europe Peptide Contract Manufacturing Market Trends
Europe accounted for a significant share of the global peptide CMO market in 2025, driven by established peptide manufacturing expertise, recurring commercial API requirements, clinical production activity, and demand for alternative supply locations. The region’s manufacturing network supports customers requiring specialized synthesis, purification, and quality testing across different production scales. Besides, pharmaceutical companies seeking continuity between clinical and commercial supply create opportunities for long-term manufacturing agreements. Moreover, demand for complex peptides increases the importance of process efficiency and impurity control. The market is supported by qualified facilities capable of maintaining consistent output across successive manufacturing campaigns.
The peptide CMO market in Germany held the largest share of the European market in 2025. The country’s growth is supported by pharmaceutical manufacturing infrastructure, process chemistry expertise, clinical supply requirements, and demand for specialized API production. German suppliers can serve programs requiring detailed manufacturing documentation, reproducible processes, and coordination with subsequent drug product operations. Besides, pharmaceutical customers seeking European production partners create opportunities for clinical and commercial contracts. In addition, expertise in analytical testing and impurity characterization supports technically demanding peptide assignments. The growth is attributed to manufacturers’ ability to combine production capabilities with reliable quality performance and effective technology transfer.
The UK peptide CMO market is expected to grow significantly over the forecast period. The market growth is driven by biotechnology research, clinical oncology programs, demand for customized sequences, and specialized manufacturing requirements for personalized therapies. These applications can involve multiple peptide sequences, small production batches, and closely coordinated delivery schedules. Besides, clinical programs require accurate characterization and traceability as manufacturing specifications evolve. Moreover, suppliers offering flexible synthesis and responsive production planning can support customers with successive studies. The market is supported by demand for peptide-specific expertise, although manufacturing volumes will depend on clinical progression and continued program funding.
Asia Pacific Peptide Contract Manufacturing Market Trends
Asia Pacific is projected to register the fastest CAGR during the forecast period is driven by expanding peptide production capacity, process chemistry expertise, demand for commercial APIs, and international outsourcing requirements. China, India, and Japan offer different combinations of manufacturing scale, production economics, and specialized synthesis capabilities. Besides, sponsors seeking geographically diversified supply networks can create opportunities for qualified regional suppliers. In addition, increasing production requirements encourage investment in purification, analytical testing, and manufacturing controls. The growth is attributed to suppliers’ ability to translate these capabilities into consistent product quality, competitive manufacturing costs, and dependable delivery.
The peptide CMO market in China is supported by established synthesis infrastructure, commercial API production capabilities, integrated manufacturing services, and demand from domestic and international sponsors. The country’s supplier base can address both customized clinical batches and larger production requirements. Besides, contracts involving peptide fragments and complete APIs allow manufacturers to participate at different stages of customer supply chains. Moreover, production efficiency and purification capacity influence suppliers’ ability to accommodate repeat commercial orders. Market growth depends on maintaining consistent impurity profiles, meeting customer quality requirements, and providing reliable supply as sponsors assess manufacturing costs and geographic sourcing exposure.
The peptide CMO market in Japan is driven by specialized synthesis expertise, demand for complex peptide structures, qualified manufacturing infrastructure, and pharmaceutical customers’ quality requirements. Manufacturing opportunities include modified and cyclic peptides that require careful selection of synthesis routes and purification methods. Besides, suppliers with expertise in alternative production approaches can address sequences that are difficult to manufacture efficiently using conventional methods. In addition, consistent analytical performance supports customer confidence in clinical and commercial supply. The market is supported by manufacturers’ ability to convert technical expertise into reproducible production while maintaining acceptable costs and meeting agreed delivery schedules.
India Peptide CDMO market is driven by process chemistry expertise, expanding API manufacturing capabilities, international outsourcing demand, and investment in peptide-specific infrastructure. Suppliers can address clinical and commercial contracts requiring synthesis, purification, isolation, and associated quality testing. Besides, pharmaceutical customers seeking additional sourcing locations create opportunities for manufacturers offering competitive production economics. Moreover, capabilities across solid-phase and solution-phase synthesis allow suppliers to evaluate different manufacturing routes. The growth is attributed to increasing opportunities for qualified Indian manufacturers, although contract retention will depend on consistent quality, successful scale-up, regulatory readiness, and reliable delivery across repeated production campaigns.
Latin America Peptide Contract Manufacturing Market Trends
The peptide CMO market in Latin America is expected to witness significant growth, is supported by pharmaceutical localization initiatives, demand for diabetes and obesity medicines, manufacturing partnerships, and interest in regional supply arrangements. Opportunities are likely to develop around selected activities, including outsourced API supply, injectable production, and packaging. Besides, technology-transfer agreements can help regional manufacturers establish product-specific capabilities. In addition, local registration requirements and procurement arrangements influence the selection of production partners. Market growth will depend on converting these requirements into external manufacturing contracts supported by sufficient production volumes and qualified facilities.
Brazil Peptide CDMO market is driven by growing demand for metabolic medicines, efforts to strengthen domestic pharmaceutical production, manufacturing partnerships, and requirements for injectable drug products. Opportunities can arise when local pharmaceutical companies purchase peptide APIs or contract selected production activities to supplement their facilities. Besides, technology transfer can support the establishment of product-specific manufacturing processes and quality controls. Moreover, packaging and finished drug production may provide additional opportunities where these services are outsourced. The growth is attributed to the development of qualified local supply arrangements, with contract volumes determined by procurement commitments and production responsibilities.
Middle East & Africa Peptide Contract Manufacturing Market Trends
The Middle East and Africa peptide CMO market is projected to grow steadily, driven by growing demand for metabolic therapies, pharmaceutical localization policies, regional supply partnerships, and interest in expanding injectable manufacturing. Opportunities differ across countries according to their pharmaceutical infrastructure, procurement systems, and local production priorities. Besides, partnerships with external manufacturers can support API and finished product supply where domestic peptide capabilities remain limited. In addition, selected technology transfers may create opportunities for local production activities. Market growth will depend on product registration, purchasing commitments, qualified facilities, and clearly defined responsibilities between regional customers and manufacturing partners.
The UAE Peptide CDMO market is supported by pharmaceutical investment, demand for diabetes and obesity medicines, regional distribution requirements, and partnerships intended to develop local production capabilities. Opportunities may initially involve outsourced API procurement, injectable manufacturing, and packaging, depending on product-specific facility capabilities. Besides, the country’s logistics infrastructure can support coordination between international suppliers and regional pharmaceutical customers. Moreover, technology-transfer agreements may broaden local manufacturing activities where production volumes justify investment. The growth is attributed to the development of qualified supply arrangements, while expansion into peptide synthesis will require dedicated equipment, specialized expertise, and validated manufacturing processes.
Key Peptide Contract Manufacturing Company Insights
The key players operating across the market are adopting strategic initiatives such as service launches, mergers & acquisitions, partnerships & agreements, and expansions to gain a competitive edge in the market. For instance, in May 2026, CordenPharma announced an agreement to acquire AmbioPharm, strengthening its peptide API manufacturing platform through facilities in North Augusta, South Carolina, and Shanghai, China. The acquisition is expected to add purification and lyophilization capabilities in the U.S., alongside synthesis capacity in China, complementing CordenPharma’s existing operations in Colorado. The acquisition was intended to broaden manufacturing options for complex peptide programs and support clinical and commercial supply across multiple geographies.
Key Peptide Contract Manufacturing Companies:
The following key companies have been profiled for this study on the peptide contract manufacturing market.
-
Bachem Holding AG
-
PolyPeptide Group AG
-
CordenPharma
-
WuXi AppTec (WuXi TIDES)
-
CPC Scientific Inc.
-
Asymchem Laboratories
-
Pharmaron
-
Piramal Pharma Solutions
-
Neuland Laboratories
-
BCN Peptides
-
Sinopep Biopharma
-
Senn Chemicals AG (Granules India)
-
Aurigene Pharmaceutical Services
-
USV Private Limited
-
CSBio
Market Participant Categorization:
Category
Operating Strategies
Competitive Edge
Weakness
Established Players - Bachem Holding AG, PolyPeptide Group AG, CordenPharma, WuXi AppTec (WuXi TIDES)
Expand peptide synthesis and purification capacity, strengthen clinical-to-commercial manufacturing capabilities, and secure long-term customer relationships. Investments emphasize automation, production efficiency, advanced purification, and supply continuity. Depending on the provider, strategies include integrated API and finished drug product manufacturing, geographic expansion, and acquisitions that broaden manufacturing capabilities.
Extensive manufacturing infrastructure, peptide process expertise, regulatory experience, and established customer relationships support technically demanding programs and recurring commercial supply. Scale and investment capacity can support larger production requirements, while integrated service offerings reduce coordination across suppliers. Capabilities differ: API specialization and finished drug product integration are not equally developed across all providers.
Large infrastructure commitments create utilization and investment-recovery risks if customer demand or product launches fall below expectations. Major commercial contracts may constrain scheduling flexibility for smaller programs. Multisite operations also require coordinated quality systems, process transfers, and regulatory documentation. These are potential operating challenges rather than evidence of weaknesses at every listed company.
Emerging Players - Asymchem Laboratories, Pharmaron, Piramal Pharma Solutions, Neuland Laboratories, Aurigene Pharmaceutical Services, USV Private Limited
Combine broader pharmaceutical manufacturing experience with peptide-specific investments in synthesis, purification, analytical testing, and qualified production infrastructure. Strategies vary from expanding existing commercial peptide operations to building additional capabilities and attracting new outsourcing customers. Public examples include peptide manufacturing offerings at Asymchem, Piramal, and Aurigene, alongside capacity expansion at Neuland and capability development at Pharmaron.
Broader process chemistry, quality systems, regulatory support, and pharmaceutical customer relationships can support entry into additional peptide contracts. Manufacturers may combine peptide expertise with complementary capabilities in complex APIs, conjugates, or drug products. Existing infrastructure can support scale-up, although peptide-specific experience, qualified capacity, and commercial execution must be evaluated separately for each supplier.
General API manufacturing experience does not automatically establish expertise in complex peptide synthesis or purification. Providers expanding their peptide operations may face qualification timelines, customer validation requirements, and production ramp-up costs. Investment priorities across multiple business lines can also compete for resources. Competitiveness depends on demonstrated peptide performance rather than the overall size of the parent organization.
Recent Developments:
-
In September 2026, Neuland announced its first commercial peptide manufacturing module had initiated the operations, following an approximately USD 30 million investment. The module provides 7,000 L of reactor capacity, combining solid-phase and liquid-phase synthesis with purification and lyophilization capabilities. The initiative expands its ability to support complex peptide APIs and larger manufacturing assignments. In addition, the expansion is aligned with customer requirements, linking capacity investment to potential production contracts.
-
In August 2026, CordenPharma completed its acquisition of AmbioPharm, adding manufacturing facilities in South Carolina, and China. It will strengthen downstream purification and lyophilization capabilities in the U.S. while adding upstream peptide production capacity in China. In addition, the acquisition broadens manufacturing location options and enables CordenPharma to address a wider range of clinical and commercial peptide supply requirements.
-
In July 2026, Bachem announced a large-volume peptide supply agreement supporting an investment of more than USD 599.7 million (CHF 500 million) in its Switzerland facility. The collaboration includes long-term commitments, with commercial production expected to begin in 2030. The initiative demonstrates a customer-backed expansion strategy that improves demand visibility while supporting future large-scale peptide manufacturing requirements.
-
In July 2026, Samsung Biologics announced an approximately USD 1.75 billion (CHF 1.46 billion) proposed acquisition to PolyPeptide Group accelerating multi-modality strategy and expanding global network across U.S., Europe, and India. The acquisition would add specialized peptide API manufacturing capabilities and expand Samsung Biologics’ service portfolio beyond its existing biologics operations. The initiative will target outsourcing opportunities associated with peptide medicines, including GLP-1 therapies.
Peptide Contract Manufacturing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.5 billion
Estimated market size in 2026
USD 1.6 billion
Projected market size by 2033
USD 3.6 billion
Growth rate
CAGR of 12.1% from 2026 to 2033
Actual data
2021 – 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Category, services, workflow, therapeutic area, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; India; Japan; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; UAE; Saudi Arabia; Kuwait; Qatar; Oman
Key companies profiled
Bachem Holding AG; PolyPeptide Group AG; CordenPharma; WuXi AppTec (WuXi TIDES); CPC Scientific Inc.; Asymchem Laboratories, Pharmaron, Piramal Pharma Solutions, Neuland Laboratories, BCN Peptides, Sinopep Biopharma, Senn Chemicals AG (Granules India), Aurigene Pharmaceutical Services, USV Private Limited, CSBio
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Peptide Contract Manufacturing Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global peptide CMO market report based on category, service, workflow, therapeutic area, end use, and region.
-
Category Outlook (Revenue, USD Billion, 2021 - 2033)
-
Therapeutic Peptides
-
Research-Grade & Preclinical Peptides
-
Diagnostic & Imaging Peptides
-
Specialty & Modified Peptides
-
Others
-
-
Service Outlook (Revenue, USD Billion, 2021 - 2033)
-
API Manufacturing
-
Finished Drug Products Manufacturing
-
Packaging and Labeling
-
Regulatory Affairs
-
Others
-
-
Workflow Outlook (Revenue, USD Billion, 2021 - 2033)
-
Clinical
-
Commercial
-
-
Therapeutic Area Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oncology
-
Metabolic Disorders
-
Cardiovascular Diseases
-
Infectious Diseases
-
Neurological Disorders
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pharmaceutical Companies
-
Biotechnology Companies
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
The peptide contract manufacturing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each peptide contract manufacturing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Category
Definition
Therapeutic Peptides
The segment captures revenue generated by providing contract manufacturing services for peptides intended for disease treatment or prevention. Services include the production, purification, associated quality testing, and clinical or commercial supply of therapeutic peptide APIs and finished drug products, where included within the study scope.
Research-Grade & Preclinical Peptides
The segment captures revenue generated by providing contract manufacturing services for peptides used in laboratory research and preclinical investigations. Services include custom synthesis, purification, characterization, and production of peptides for biological assays, target evaluation, experimental studies, and preclinical testing. Peptides manufactured for human clinical administration are excluded from this category.
Diagnostic & Imaging Peptides
The segment captures revenue generated by providing contract manufacturing services for peptides intended for diagnostic testing and medical imaging applications. Services include synthesis, purification, modification, associated quality testing, and production of peptide substrates, diagnostic reagents, targeting ligands, and peptide precursors for imaging agents, where included within the study scope.
Specialty & Modified Peptides
The segment captures revenue generated by providing contract manufacturing services for peptides requiring specialized structural modifications or functional features. Services include the production and purification of cyclic, conjugated, lipidated, PEGylated, labeled, and other modified peptides. Revenue is included only where these products are not already assigned to therapeutic, research-grade and preclinical, or diagnostic and imaging categories.
Other Categories
The segment captures revenue generated by providing contract manufacturing services for peptides used in applications not covered by the preceding categories. These may include cosmetic, personal care, nutritional, agricultural, and industrial applications, where included within the study scope. Services include custom synthesis, purification, associated quality testing, and production of peptides for these applications.
Service
Definition
API Manufacturing
The segment captures revenue generated by providing contract manufacturing services for peptide active pharmaceutical ingredients used in clinical or commercial drug production. Services include peptide synthesis, cleavage, purification, isolation, drying, associated quality testing, and bulk API supply. Standalone process development and finished drug product manufacturing revenues are excluded from this segment.
Finished Drug Products Manufacturing
The segment captures revenue generated by providing contract manufacturing services that convert peptide APIs into finished pharmaceutical dosage forms. Services include compounding, formulation preparation using established processes, sterile filtration, filling, lyophilization, and production of injectable, oral, or other peptide dosage forms. Standalone formulation development revenues are excluded from this segment.
Packaging and Labeling
The segment captures revenue generated by providing contract packaging and labeling services for peptide APIs and finished drug products. Services include primary and secondary packaging, container labeling, clinical trial labeling, serialization, tamper-evident packaging, and preparation of packaged products for distribution. Revenue already included within other manufacturing service charges is not counted separately.
Regulatory Affairs
The segment captures revenue generated by providing separately attributable regulatory affairs services directly associated with contracted peptide manufacturing. Services include preparation and maintenance of manufacturing-related regulatory documentation, drug master file support, chemistry, manufacturing and controls documentation, and responses to manufacturing-related regulatory queries. Broader regulatory consulting unrelated to the contracted manufacturing activity is excluded.
Others
The segment captures revenue generated by providing other separately attributable services directly supporting peptide contract manufacturing that are not covered by the preceding service segments. Services may include standalone manufacturing-related analytical testing, stability testing, storage, and supply chain support, where included within the study scope. Charges already included in API or finished drug product manufacturing revenues are excluded to avoid double counting.
Workflow
Definition
Clinical
The segment captures revenue generated by providing contract manufacturing and associated services for peptides intended for use in human clinical trials. Services include clinical-grade peptide API production, investigational drug product manufacturing, associated quality testing, packaging, labeling, and manufacturing-related regulatory support. Materials manufactured exclusively for laboratory research or preclinical investigations are excluded from this segment.
Commercial
The segment captures revenue generated by providing contract manufacturing and associated services for peptides supplied for commercial use. Services include routine peptide production, commercial-scale API and finished drug product manufacturing, associated quality testing, packaging, labeling, and ongoing manufacturing-related regulatory support. Revenue from investigational materials supplied exclusively for clinical trials is excluded from this segment.
Therapeutic Area
Definition
Oncology
The segment captures revenue generated by providing contract manufacturing services for peptides intended for oncology applications. Services include the production of peptide APIs, finished drug products, research peptides, and diagnostic or imaging peptides associated with cancer, where included within the study scope. Manufacturing revenue is assigned according to the peptide’s intended oncology application.
Metabolic Disorders
The segment captures revenue generated by providing contract manufacturing services for peptides intended for metabolic disorder applications, including diabetes, obesity, and related metabolic conditions. Services include the production of peptide APIs, finished drug products, and associated research or diagnostic peptides, where included within the study scope. Revenue is allocated according to the intended metabolic application.
Cardiovascular Diseases
The segment captures revenue generated by providing contract manufacturing services for peptides intended for cardiovascular disease applications. Services include the production of peptide APIs, finished drug products, and associated research, diagnostic, or imaging peptides used in cardiovascular applications, where included within the study scope. Revenue from products serving multiple indications is allocated by application where identifiable.
Infectious Diseases
The segment captures revenue generated by providing contract manufacturing services for peptides intended for infectious disease applications. Services include the production of antimicrobial or antiviral peptides, peptide-based therapeutic products, and associated research or diagnostic peptides, where included within the study scope. Non-peptide anti-infective products and unrelated vaccine manufacturing revenues are excluded.
Neurological Disorders
The segment captures revenue generated by providing contract manufacturing services for peptides intended for neurological disorder applications. Services include the production of peptide APIs, finished drug products, and associated research, diagnostic, or imaging peptides related to neurological conditions, where included within the study scope. Manufacturing revenue is assigned according to the peptide’s intended neurological application.
Others
The segment captures revenue generated by providing contract manufacturing services for peptides intended for applications outside the preceding therapeutic areas. These include gastrointestinal, reproductive, bone, dermatological, immunological, and other conditions. Non-therapeutic or unassigned peptide applications are also included where the therapeutic-area segmentation covers the entire market and such revenues fall within the study scope.
End Use
Definition
Pharmaceutical Companies
The segment captures revenue generated by providing peptide contract manufacturing services to pharmaceutical companies. Services include the production and supply of peptide APIs, clinical materials, finished drug products, and associated packaging, labeling, and manufacturing-related regulatory support. Revenue is classified according to the pharmaceutical company purchasing the contracted services.
Biotechnology Companies
The segment captures revenue generated by providing peptide contract manufacturing services to biotechnology companies developing or commercializing peptide-based products. Services include custom peptide production, clinical and commercial API manufacturing, finished drug product manufacturing, and associated manufacturing support.
Others
The segment captures revenue generated by providing peptide contract manufacturing services to customers other than pharmaceutical and biotechnology companies. Customers may include academic institutions, research institutes, contract research organizations, diagnostic companies, and cosmetic or industrial product companies, where included within the study scope.
Estimation Model
OUTSOURCING PENETRATION-BASED ESTIMATION MODEL
BOTTOM-UP APPROACH
DEMAND-SIDE ESTIMATION
CAPACITY AND UTILIZATION MODEL
- This model estimates the peptide contract manufacturing market by assessing total peptide manufacturing expenditure and applying outsourcing penetration rates across relevant categories, services, therapeutic areas, and geographies.
- Manufacturing expenditure is derived from production volumes, manufacturing costs, and procurement benchmarks.
- Assumptions regarding outsourcing are applied to API production, finished drug products, and associated services.
- Captive manufacturing and standalone development revenues are excluded to establish the addressable outsourced market.
- This approach estimates market size by aggregating revenues attributable to peptide contract manufacturing across identified suppliers.
- Company revenues are adjusted to exclude unrelated businesses, standalone development activities, and products outside the defined scope.
- Estimates for private manufacturers are developed using disclosed capacity, customer portfolios, interviews, and comparable supplier benchmarks.
- Revenues are standardized by currency and reporting period, with adjustments for uncovered suppliers and acquisition-related double counting.
- This model estimates manufacturing demand using commercial peptide consumption, clinical material requirements, and research or diagnostic applications.
- Commercial API volumes are calculated from treated patient populations, annual dosing, treatment duration, and adherence assumptions.
- Volumes are multiplied by manufacturing transfer prices and outsourcing shares. Finished product manufacturing and associated services are assessed separately, excluding intermediate material pass-through charges to avoid duplication across the manufacturing value chain.
- This model estimates peptide manufacturing revenue using installed, qualified production capacity, annual utilization, saleable output, and manufacturing prices.
- Capacity is assessed across synthesis, purification, and downstream operations, recognizing the limiting production step.
- Theoretical output is adjusted for yield and the proportion serving external customers.
- Facility-level estimates are aggregated across manufacturers and regions, while announced capacity is incorporated only when commissioning and qualification timelines support its availability.
Customization Table
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Extensive Cross-Segmentation Analysis
Provides detailed analysis across peptide category, service, workflow, therapeutic area, end use, and regional combinations. Evaluates manufacturing demand, outsourcing intensity, and revenue contribution across therapeutic, research-grade and preclinical, diagnostic and imaging, and specialty peptides. Examines clinical and commercial requirements to identify commercially attractive segment combinations.
Helps clients identify high-growth applications, underserved customer groups, and attractive outsourcing opportunities. Supports portfolio prioritization, customer targeting, pricing decisions, and alignment of manufacturing capabilities with demand across peptide categories and therapeutic areas.
Regional Extension & Market Entry Strategy
Extends the study to additional countries, subregions, or local markets. Analyzes market attractiveness, regulatory requirements, peptide manufacturing infrastructure, local demand, outsourcing preferences, entry barriers, and potential partners. May compare acquisition, partnership, joint venture, technology transfer, and greenfield entry strategies.
Enables clients to prioritize markets and select suitable entry routes based on demand, competition, regulatory requirements, and investment needs. Supports partner identification, regional capacity planning, supply chain diversification, and customer acquisition strategies.
Competitive Dynamics & Supplier Benchmarking
Evaluates established and emerging peptide contract manufacturers based on synthesis capabilities, peptide complexity, manufacturing scale, purification expertise, quality certifications, regulatory track record, geographic presence, and service portfolios. May assess pricing models, partnerships, acquisitions, customer concentration, and capacity expansion strategies, subject to data availability.
Supports supplier selection, competitive benchmarking, acquisition screening, and strategic positioning. Identifies capability gaps, differentiation opportunities, and potential partnerships. Helps clients assess manufacturers’ suitability for specific peptide products and clinical or commercial supply requirements.
Volume, Capacity & Emerging Technology Analysis
Assesses peptide production volumes, installed and qualified capacity, utilization, outsourcing penetration, manufacturing costs, and demand by application, subject to data availability. Evaluates solid-phase, liquid-phase, and hybrid synthesis, continuous manufacturing, automated synthesis, purification technologies, and greener production processes by manufacturer, geography, or peptide category.
Supports capacity planning, cost optimization, production scalability, and technology investment decisions. Helps assess whether existing capabilities can meet future demand and identifies opportunities to improve yield, purity, throughput, and manufacturing efficiency while reducing material consumption and waste.
Frequently Asked Questions About This Report
The global peptide contract manufacturing market size was valued at USD 1.5 billion in 2025 and is estimated at USD 1.6 billion for 2026.
North America peptide contract manufacturing market held the largest share of 45.2% of the global market in 2025.
Key factors driving market growth include rising demand for GLP-1 therapies, expanding oncology applications, increasing outsourcing by pharmaceutical and biotechnology companies, growing clinical peptide production requirements, and greater demand for complex and modified peptides. Furthermore, recurring commercial manufacturing requirements support sustained procurement of peptide APIs and finished drug products. Moreover, sponsors seeking qualified capacity and diversified supply arrangements are expected to create new opportunities for manufacturers offering reliable synthesis, purification, and batch delivery.
Some of the key players operating in the peptide contract manufacturing market include Bachem Holding AG, PolyPeptide Group AG, CordenPharma, WuXi AppTec (WuXi TIDES), CPC Scientific Inc., Asymchem Laboratories, Pharmaron, Piramal Pharma Solutions, Neuland Laboratories, BCN Peptides, Sinopep Biopharma, Senn Chemicals AG (Granules India), Aurigene Pharmaceutical Services, USV Private Limited, and CSBio among others.
API manufacturing segment dominated the market with the largest revenue share of 54.6% in 2025 while finished drug products manufacturing segment is expected to be the fastest-growing market.
The commercial segment accounted for the largest share of 76.9% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global peptide contract manufacturing market is expected to grow at a CAGR of 12.1% from 2026 to 2033, reaching USD 3.6 billion by 2033.
Therapeutic peptides segment led the market with the largest revenue share of 64.7% in 2025.The segment is driven by rising demand for GLP-1 medicines, expanding oncology applications, the progression of peptide candidates toward commercialization, and outsourcing of specialized peptide production.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


