
- Home
- »
- Plastics, Polymers & Resins
- »
-
Photopolymers Market Size & Share Report, 2026-2033GVR Report cover

Photopolymers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Performance (Low, Mid, High), By Technology (SLA, DLP, cDLP), By Application (Dental, Medical, Audiology, Jewellery), By Region and Segment Forecasts
Market Size, 2025
$3.5BMarket Estimate, 2026
$3.8BMarket Forecast, 2033
$8.1BCAGR, 2026–2033
11.3%Photopolymers Market Summary
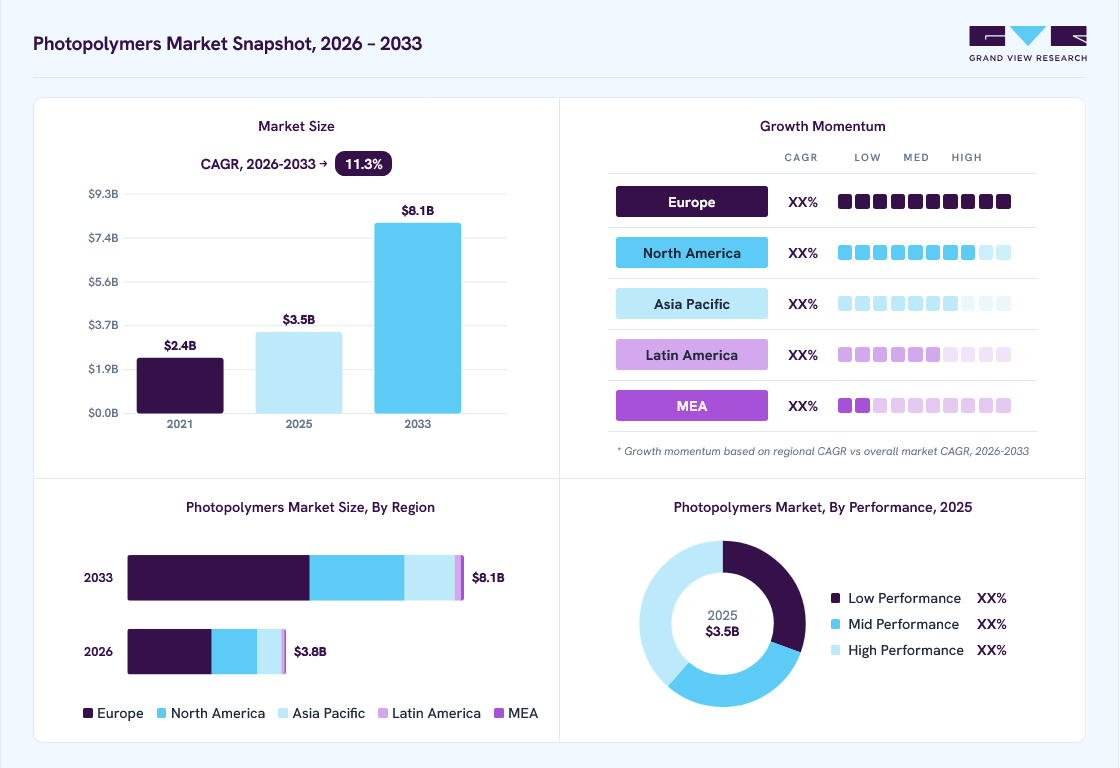
The global photopolymers market size was valued at USD 3.5 billion in 2025 and is projected to grow from USD 3.8 billion in 2026 to USD 8.1 billion by 2033, at a CAGR of 11.3% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 53.1% in 2025. The photopolymers market is witnessing robust growth, driven by the increasing adoption of high-speed printing technologies and the rising demand for durable, complex, and high-precision 3D printed components.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By performance: High performance segment led the market with the largest revenue share of 38.6% in 2025.
- By technology: Stereolithography (SLA) segment led the market with the largest revenue share of 57.2% in 2025.
- By application: Dental segment led the market with the largest revenue share of 32.5% in 2025.
Regional Highlights
- Largest regional market: Europe (53.1% revenue share, 2025)
- By country: The Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.5 Billion
- Estimated market size in 2026: USD 3.8 Billion
- Projected market size by 2033: USD 8.1 Billion
- CAGR (2026-2033): 11.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The ability of photopolymers to deliver superior design accuracy, fine detail resolution, rapid production capabilities, and enhanced mechanical performance is accelerating their use across various industrial applications. Additionally, growing requirements for efficient additive manufacturing processes and customized product development are further supporting market expansion worldwide.
Rising demand for prototyping across automotive industry and designs for understanding complex surgical procedures have increased the demand for photopolymer for 3D printing. Furthermore, increasing demand for artificial jewelry and prosthetics across the global population are further propelling the market growth. The U.S. dominated photopolymers market in North America in 2024 owing to the rising demand for photopolymers from the automotive industry in the country. Original equipment manufacturers (OEMs) in the U.S. are focusing on upgrading traditional prototyping and component-developing methods.
 To learn more about this report, Download Free Sample Report
The requirement for manufacturing automotive components such as high-performance components at a large scale, ensuring an abundant supply of spare parts using 3D printing, and easing general component manufacturing is anticipated to propel the demand for photopolymers used for 3D printing of components across the U.S. during the forecast period.
Market Dynamics
The photopolymers market is witnessing strong growth, driven by the increasing adoption of 3D printing technologies across automotive, healthcare, and consumer goods applications. Rising demand for rapid prototyping, high-precision component development, and detailed surgical planning models is accelerating the use of photopolymer materials. Additionally, the growing production of artificial jewelry, prosthetics, and customized products is further supporting market expansion. The U.S. remains a key regional market, supported by automotive manufacturers increasingly replacing conventional prototyping methods with advanced additive manufacturing solutions. The need for large-scale production of high-performance automotive components, efficient spare parts manufacturing, and streamlined component development processes is expected to further strengthen demand for photopolymers throughout the forecast period.
The photopolymers market is experiencing significant growth due to the increasing demand for sustainable and environmentally responsible printing materials across packaging, labeling, publishing, and commercial printing industries. Photopolymers offer advantages such as low solvent content, reduced volatile organic compound emissions, and improved recyclability potential, enabling manufacturers to comply with evolving environmental regulations while supporting corporate sustainability initiatives. These benefits are encouraging wider adoption of photopolymers in modern printing applications.
Demand is further supported by the rising complexity of packaging designs and the growing need for high-quality graphics in premium product labeling. Photopolymers provide excellent image fidelity, fine detail reproduction, durability, and printing precision, making them well suited for intricate printing requirements. As industries increasingly prioritize sustainable production, enhanced visual appeal, and operational efficiency, photopolymers are strengthening their position as a preferred material solution, driving continued market expansion globally.
High production costs and complex formulation processes continue to hinder the growth of the photopolymers market. Manufacturing photopolymers requires specialized raw materials, advanced curing technologies, and carefully controlled production conditions, which increase overall production expenses. Additionally, strict quality standards and ongoing process improvements add to operational challenges and costs. Market expansion is also limited by a lack of awareness and technical knowledge among small and medium-sized businesses, especially in developing regions. Many end-users still prefer conventional materials because of their lower costs and established manufacturing processes. Therefore, improving cost efficiency and simplifying processing technologies are important for increasing the adoption of photopolymers across various industries.
The growing adoption of photopolymers in healthcare and biomedical applications is creating significant growth opportunities for the photopolymers market. Increasing demand for biocompatible materials, microfluidic devices, printed circuit boards, and precision-engineered components is driving the utilization of photopolymers due to their excellent dimensional accuracy, light-responsive properties, and ability to produce complex structures. The market is further supported by ongoing advancements in 3D printing and additive manufacturing technologies, which are expanding the use of photopolymers in specialized applications. As industries increasingly seek customized, high-performance, and precision-manufactured solutions, photopolymers are strengthening their position as a critical material for next-generation manufacturing and product development.
Market Concentration & Characteristics
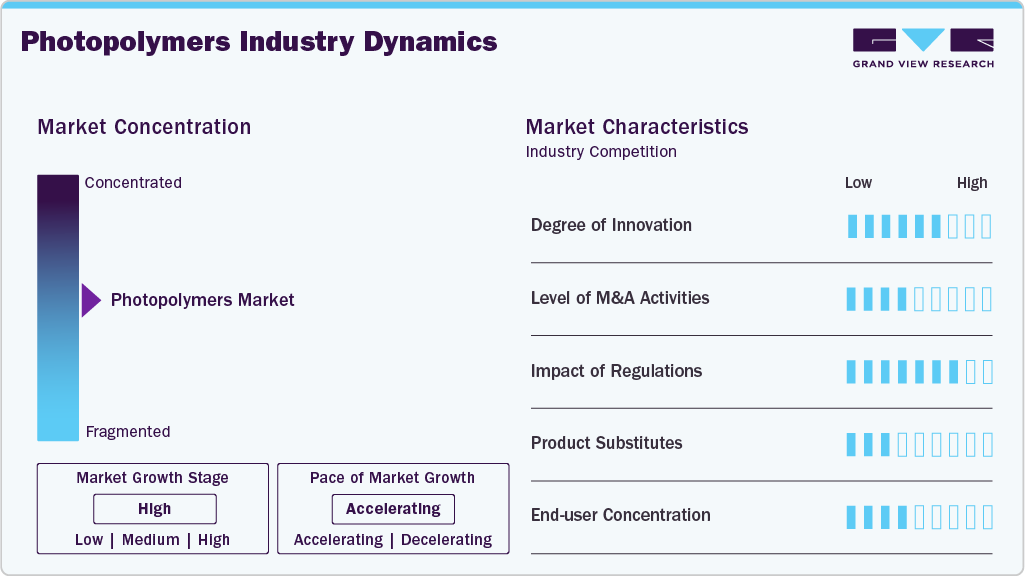
The market growth stage of the photopolymers market is high, and the pace is accelerating. The market exhibits slight consolidation, with key players dominating the industry landscape. Major companies like Henkel AG & Co. KGaA, Arkema, Stratasys, BASF SE, Keystone Industries, Formlabs, Carbon, Inc., Evonik Industries AG, Liqcreate, ANYCUBIC Technology Co., Ltd., RAHN AG, polySpectra, and others play a significant role in shaping the market dynamics. These leading players often drive innovation within the market, introducing new products, technologies, and applications to meet evolving industry demands.
 To learn more about this report, Download Free Sample Report
The photopolymers market faces moderate pressure from alternative materials such as traditional thermoplastics, epoxy resins, and UV-curable inks that can fulfill similar functional requirements in certain applications. While substitutes often offer lower costs, they generally lack the high-resolution printing capability and precision molding advantages inherent to photopolymers. Companies seeking performance-critical or highly customized outputs continue to favor photopolymers, though price-sensitive segments may temporarily shift toward conventional materials, influencing market adoption patterns.
Regulatory frameworks concerning chemical safety, environmental compliance, and biocompatibility significantly influence the photopolymers market. Stricter standards on VOC emissions, hazardous substances, and medical-grade material certifications drive manufacturers to innovate safer and more sustainable formulations. Compliance with these regulations not only adds operational complexity but also creates a competitive advantage for companies that can deliver certified, high-performance photopolymers, reinforcing trust among end-users in critical applications like healthcare and electronics.
Analyst Perspective
The photopolymers market is expected to evolve from a cost-driven materials market toward a more innovation- and application-focused industry. Demand will be supported by growing applications in 3D printing, dental and medical products, electronics, packaging, automotive prototyping, and advanced manufacturing. Technological advancements in high-performance resins, bio-based photopolymers, low-shrinkage formulations, and recyclable materials will create new opportunities and support sustainability goals. Market leaders are likely to differentiate through R&D capabilities, proprietary technologies, strategic partnerships, integrated production networks, and global reach. Customers will increasingly demand materials offering performance, durability, sustainability, and ease of processing. However, profitability may face pressure from raw material cost fluctuations, regulatory requirements, regional competition, and alternative materials. Companies balancing innovation, cost efficiency, supply security, and sustainable development will be best positioned for long-term growth.
Drivers, Opportunities & Restraints
A key driver of the photopolymers market is the growing demand for sustainable and eco-friendly printing solutions across multiple industries. Photopolymers offer low solvent content, reduced volatile organic compound emissions, and the potential for recyclability, making them attractive for companies aiming to meet environmental standards. Additionally, the rising complexity of packaging designs and the need for intricate patterns in high-end product labeling are fueling the shift toward photopolymers, which provide high fidelity and durability in printed materials.
Emerging applications in healthcare, electronics, and biomedical devices present a significant growth opportunity for the photopolymers market. With increasing demand for biocompatible materials, microfluidic devices, and printed circuit boards, photopolymers can serve as critical materials due to their precision molding capabilities and light-sensitive properties. Expanding research in 3D printing and additive manufacturing further enhances the potential for photopolymers to penetrate niche segments, where conventional materials often fall short in meeting accuracy, customization, and material performance requirements.
High production costs and complex formulation processes pose a notable restraint for the photopolymers market. The requirement for specialized raw materials, stringent quality control, and advanced curing technologies increases capital investment and operational expenses. Additionally, limited awareness and technical expertise among smaller end-users can slow adoption, particularly in emerging economies where conventional printing and molding solutions remain more cost-effective, thereby restricting broader market penetration.
Performance Insights
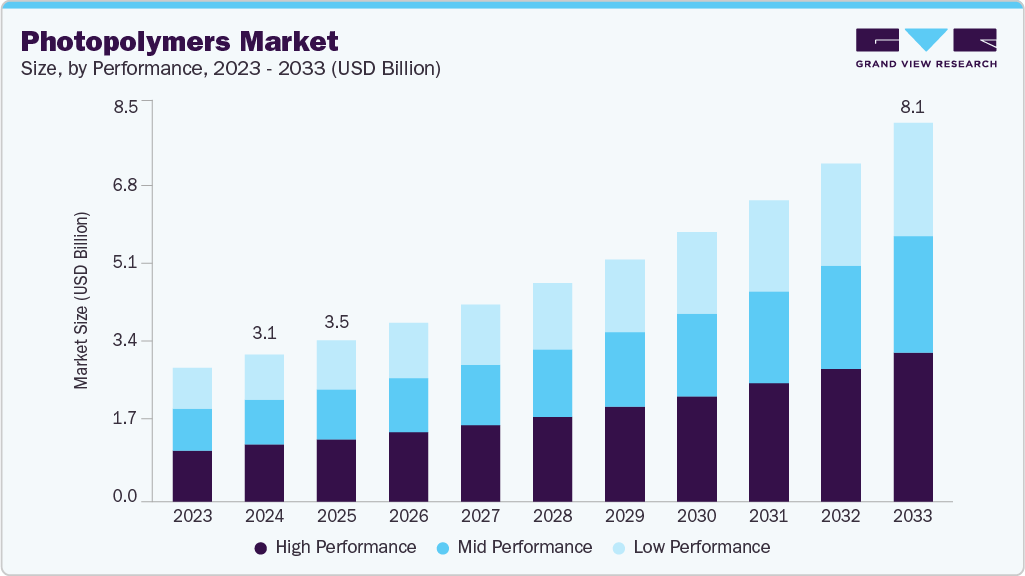
Based on performance, the high performance segment led the market with the largest revenue share of 38.6% in 2025. The high-performance 3D printing refers to technologies that offer exceptional capabilities in terms of high speed, precision, material options, and the highest print quality. These high-performance 3D printing technologies include selective laser melting (SLM), electron beam melting (EBM), continuous liquid interface production (CLIP), and multi-material 3D printing.
The Mid Performance segment is anticipated to grow at a substantial CAGR of 11.2% through the forecast period. Mid-performance 3D printing refers to technologies that can balance affordability and performance. These technologies include Digital Light Processing (DLP), Multi Jet Fusion (MJF), Poly Jet, and Bound Metal Deposition (BMD) by Desktop Metal, which can provide decent printing speed, accuracy, and material options without reaching the highest levels of performance in advanced or industrial-grade systems.
Technology Insights
Based on technology, the stereolithography (SLA) segment led the market with the largest revenue share of 57.2% in 2025. SLA is the most commonly used 3D printing technology across the world. It utilizes laser light sources to carry out 3D printing of objects. The global demand for SLA-based 3D printing has rapidly increased in recent years owing to its ability to print 25-300-micron components at a high XY resolution utilizing plastic resins and photopolymers.
The Digital Light Processing (DLP) segment is anticipated to grow at a substantial CAGR of 10.4% through the forecast period. DLP photopolymer technology is gaining traction due to its high-speed production capabilities, making it ideal for small-batch manufacturing and rapid prototyping. By projecting light across entire layers simultaneously, DLP reduces print time without compromising resolution, which is particularly valuable for industries focused on short lead times and agile product development. The technology’s adaptability to both functional and aesthetic applications is encouraging companies to integrate DLP into their production workflows, driving its growth in competitive markets.
Application Insights
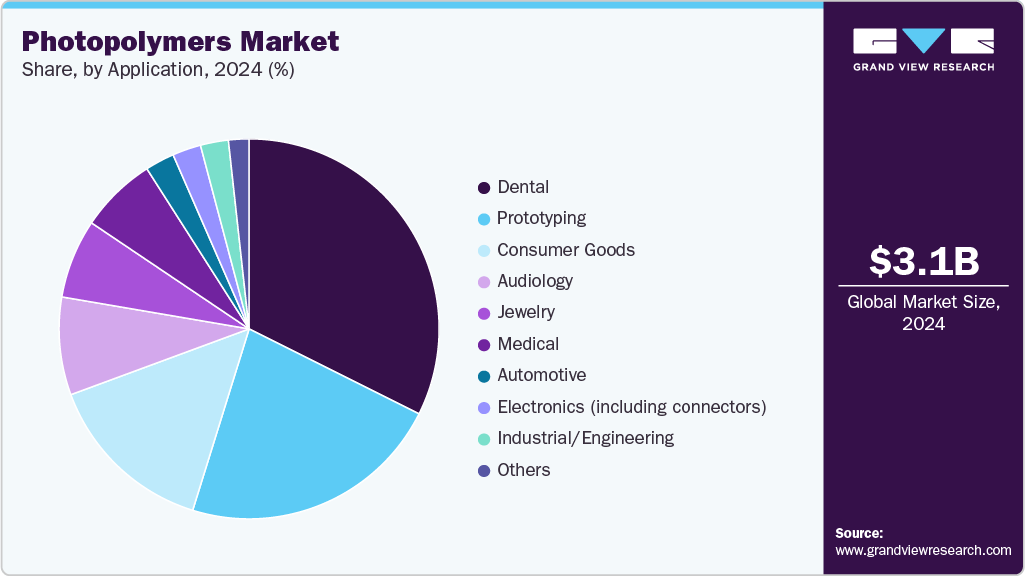
Based on application, the dental segment led the market with the largest revenue share of 32.5% in 2025. The photopolymers in 3D printing across the dental industry have witnessed a rise in demand in the past few years on account of their benefits, such as high-quality molds, perfect & precise designs, smoother surfaces, and higher durability, in comparison to the traditional process of manufacturing molds using thermoforming.
 To learn more about this report, Download Free Sample Report
The prototyping segment is expected to expand at a substantial CAGR of 10.9% through the forecast period. Prototyping applications drive the photopolymers market as industries increasingly prioritize rapid product development and design iteration. Photopolymers enable engineers and designers to quickly fabricate complex geometries with high dimensional accuracy, allowing for early-stage testing and validation. The push for shorter time-to-market and reduced development costs in sectors such as automotive, consumer electronics, and industrial equipment underlines the strategic importance of photopolymers in prototyping workflows.
Regional Insights
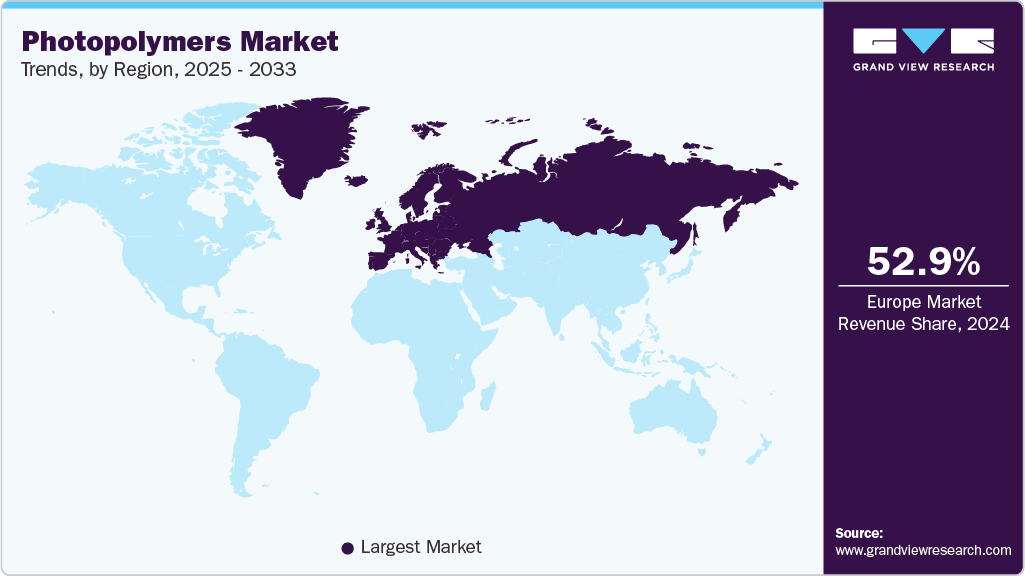
Europe dominated the photopolymers market with the largest revenue share of 53.1% in 2025 and is expected to grow at the fastest CAGR of 11.6% over the forecast period. The photopolymers market in Europe is being driven by the region’s strong focus on sustainable manufacturing and eco-friendly printing solutions. Companies are increasingly adopting photopolymers due to their low solvent content, recyclability, and compatibility with UV and LED curing technologies. Growth is particularly fueled by demand from the packaging and labeling industries, where stringent environmental regulations and brand emphasis on sustainable packaging are pushing the shift from conventional inks and resins to advanced photopolymers.
 To learn more about this report, Download Free Sample Report
North America Photopolymers Market Trends
In North America, the photopolymers market is propelled by the growing adoption of 3D printing in healthcare, electronics, and aerospace applications. The region’s investment in research and development for photopolymer formulations tailored for medical devices, surgical guides, and microfluidics is significant. Additionally, the focus on reducing lead times and achieving high-resolution, durable prints across industrial sectors is accelerating the integration of photopolymers into production and prototyping workflows.
U.S. Photopolymers Market Trends
The U.S. photopolymers market benefits from increasing demand for personalized and on-demand manufacturing solutions, particularly in healthcare, dental, and consumer electronics sectors. Advanced digital printing and additive manufacturing adoption are expanding the use of photopolymers in creating patient-specific medical components and high-precision prototypes. Moreover, the U.S. market is supported by a strong ecosystem of photopolymer suppliers and end-users focused on innovation, which encourages the development of specialized, high-performance resin solutions.
Asia Pacific Photopolymers Market Trends
The Asia Pacific photopolymers market is driven by rapid industrialization, expanding electronics and automotive sectors, and the growing adoption of additive manufacturing technologies. Countries such as China, Japan, and South Korea are increasingly utilizing photopolymers for high-resolution printing, flexible packaging, and precision prototyping. Additionally, rising demand from medical and dental applications in the region, coupled with cost advantages in manufacturing and material production, is fueling significant growth opportunities for photopolymer suppliers.
The photopolymers market in Germany accounted for the largest market revenue share in Europe in 2025. The Germany photopolymers market is primarily driven by the country’s advanced industrial and automotive sectors, which demand high-precision, durable components for prototyping and end-use applications. The strong presence of additive manufacturing facilities and innovation hubs focused on Industry 4.0 initiatives encourages the adoption of SLA and DLP-based photopolymer solutions. German manufacturers are leveraging photopolymers for rapid prototyping, tooling, and functional parts, reflecting the nation’s emphasis on quality, precision, and technological competitiveness.
Key Photopolymers Company Insights
The Photopolymers Market is highly competitive, with several key players dominating the landscape. Major companies include Henkel AG & Co. KGaA, Arkema, Stratasys, BASF SE, Keystone Industries, Formlabs, Carbon, Inc., Evonik Industries AG, Liqcreate, ANYCUBIC Technology Co., Ltd., RAHN AG, polySpectra. The photopolymers market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their types.
Key Photopolymers Companies
The following key companies have been profiled for this study on the photopolymers market.
-
Henkel AG & Co. KGaA
-
Arkema
-
Stratasys
-
BASF SE
-
Keystone Industries
-
Formlabs
-
Carbon, Inc.
-
Evonik Industries AG
-
Liqcreate
-
ANYCUBIC Technology Co., Ltd.
-
RAHN AG
-
polySpectra
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Henkel AG & Co. KGaA, Arkema, Stratasys, BASF SE, Keystone Industries, Formlabs, Carbon, Inc., Evonik Industries AG, RAHN AG)
- Broad portfolios of photopolymer resins and materials serving dental, medical, audiology, jewelry, automotive, prototyping, industrial engineering, electronics, and consumer goods applications.
- Strong focus on the development of high-performance, biocompatible, engineering-grade, and application-specific photopolymers compatible with Stereolithography (SLA), Digital Light Processing (DLP), and Continuous Digital Light Processing (CDLP) technologies.
- Continuous investments in material innovation, additive manufacturing research, product customization, regulatory compliance, and advanced resin formulations support evolving customer requirements. Strategic partnerships with 3D printer manufacturers, healthcare providers, research institutions, industrial manufacturers, and distribution networks further strengthen technology adoption, market reach, and commercial growth across global markets.
- Extensive expertise in photopolymer chemistry, additive manufacturing technologies, material science, and application development enables the commercialization of highly specialized resins with superior precision, mechanical performance, surface quality, and reliability.
- Strong research and development capabilities, intellectual property portfolios, regulatory certifications, and established relationships with dental laboratories, healthcare organizations, industrial manufacturers, and engineering firms support recurring demand and long-term customer retention.
- Advanced manufacturing infrastructure, global distribution networks, technical support capabilities, and brand recognition provide significant competitive differentiation while supporting innovation across rapidly evolving additive manufacturing markets.
- Dependence on specialized raw materials, photoinitiators, and advanced chemical formulations exposes manufacturers to supply chain disruptions, raw material price fluctuations, and procurement challenges.
- Significant investments are required for research and development, regulatory approvals, product validation, advanced manufacturing infrastructure, and continuous material innovation, increasing operational expenditures.
- The market is also influenced by intense technological competition, evolving industry standards, alternative additive manufacturing materials, intellectual property challenges, and adoption barriers among cost-sensitive end users, which may impact profitability and limit penetration across certain price-sensitive applications and emerging markets.
Emerging & Specialized Players (Liqcreate; ANYCUBIC Technology Co., Ltd.; polySpectra)
- Focus on strengthening their position in the photopolymers market through the development and commercialization of specialized photopolymer resins for dental, medical, engineering, prototyping, jewelry, electronics, and consumer goods applications.
- Emphasis is placed on expanding material portfolios, improving resin performance characteristics, enhancing compatibility with SLA, DLP, and CDLP printing technologies, and addressing the growing demand for high-precision additive manufacturing solutions.
- Strategic collaborations with 3D printer manufacturers, research institutions, healthcare providers, distributors, and industrial end-users support product innovation and market penetration. Continuous investments in material science research, advanced resin formulations, application-specific product development, and performance optimization further reinforce competitiveness in both regional and global markets.
- Strong expertise in niche photopolymer formulations, rapid product development capabilities, and flexibility in addressing emerging application requirements support participation across diverse additive manufacturing markets.
- Competitive advantage is enhanced through specialized material offerings tailored for engineering-grade, dental, medical, and high-performance industrial applications. Their ability to rapidly respond to evolving customer needs, introduce innovative resin technologies, and support customized printing solutions strengthens market positioning.
- In addition, growing focus on advanced material properties, precision manufacturing, and next-generation additive manufacturing technologies enables these companies to compete effectively in specialized market segments where performance differentiation is critical.
- Exposure to fluctuations in raw material costs, evolving regulatory requirements for medical and industrial applications, and rapid technological advancements may increase operational complexity and development expenses. Dependence on relatively niche application segments and emerging additive manufacturing adoption rates can create demand uncertainty.
- Compared with large multinational photopolymer and specialty chemical manufacturers, limited production scale, distribution networks, brand recognition, and research resources may restrict access to high-volume customers and global market opportunities.
- Furthermore, challenges associated with achieving broad material certifications, maintaining consistent product performance, and scaling manufacturing capabilities may limit long-term growth and competitive differentiation.
Recent Developments
-
In April 2025, polySpectra and Tethon 3D jointly launched ThOR 10, a new composite photopolymer resin engineered for industrial 3D printing. ThOR 10 combined polySpectra’s thermally stable, impact-resistant Cyclic Olefin Resin (COR) with Tethon 3D’s ceramic fillers to create a highly rugged material with improved impact strength and stiffness.
-
In April 2023, Henkel launched a new high-performance photopolymer resin called Loctite 3D IND249 for industrial 3D printing. The resin featured high stiffness, high temperature resistance, and strong mechanical properties, making it ideal for production applications like mold tooling and manufacturing aids.
Photopolymers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.5 billion
Estimated market size in 2026
USD 3.8 billion
Projected market size by 2033
USD 8.1 billion
Growth rate
CAGR of 11.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Performance, technology, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; Austria; UK; France; Spain; Italy; Netherlands; Belgium; China; Australia; South Korea; Southeast Asia; India; Japan; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Henkel AG & Co. KGaA; Arkema; Stratasys; BASF SE; Keystone Industries; Formlabs; Carbon, Inc.; Evonik Industries AG; Liqcreate; ANYCUBIC Technology Co., Ltd.; RAHN AG; polySpectra
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Photopolymers Market Report Segmentation
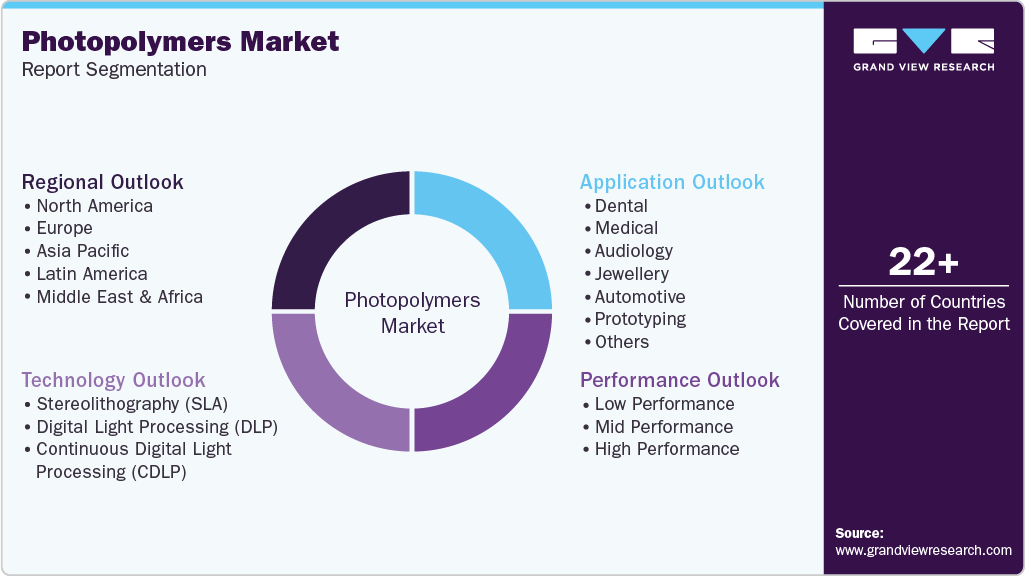
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global photopolymers market report on the basis of performance, technology, application, and region:
 To learn more about this report, Download Free Sample Report
-
Performance Outlook (Revenue, USD Million; Volume, Tons; 2021 - 2033)
-
Low Performance
-
Mid Performance
-
High Performance
-
-
Technology Outlook (Revenue, USD Million; Volume, Tons; 2021 - 2033)
-
Stereolithography (SLA)
-
Digital Light Processing (DLP)
-
Continuous Digital Light Processing (CDLP)
-
-
Application Outlook (Revenue, USD Million; Volume, Tons; 2021 - 2033)
-
Dental
-
Medical
-
Audiology
-
Jewellery
-
Automotive
-
Prototyping
-
Industrial/Engineering
-
Electronics (including connectors)
-
Consumer Goods
-
Others
-
-
Regional Outlook (Revenue, USD Million; Volume, Tons; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
Austria
-
UK
-
France
-
Spain
-
Italy
-
The Netherlands
-
Belgium
-
-
Asia Pacific
-
China
-
Australia
-
South Korea
-
Southeast Asia
-
India
-
Japan
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The photopolymers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each photopolymers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Performance
Revenue capture definition
Low Performance
Revenue is captured through the production and sale of low-performance photopolymers utilized in concept modeling, visual prototypes, educational models, consumer products, and non-functional demonstration parts. Demand is driven by their cost-effectiveness, ease of processing, rapid curing capabilities, and suitability for applications where high mechanical strength, thermal resistance, and long-term durability are not critical requirements.
Mid Performance
Revenue is captured through the commercialization of mid-performance photopolymers used in functional prototypes, tooling components, consumer goods, automotive parts, and industrial models requiring balanced mechanical properties and dimensional accuracy. Growth is supported by their ability to provide improved strength, surface finish, durability, and design flexibility while maintaining cost-efficient production across various additive manufacturing applications.
High Performance
Revenue is captured through the supply of high-performance photopolymers utilized in medical devices, dental applications, aerospace components, engineering parts, electronics, and specialized industrial products. Demand is driven by their superior mechanical strength, biocompatibility, thermal stability, chemical resistance, precision, and ability to meet stringent regulatory and performance requirements in high-value applications.
Segment – Technology
Revenue Capture Definition
Stereolithography (SLA)
Revenue is captured through the commercialization of photopolymers used in stereolithography systems for producing highly detailed prototypes, dental models, medical devices, jewelry patterns, and engineering components. Demand is driven by its exceptional surface finish, high dimensional accuracy, material versatility, and ability to manufacture complex geometries with fine feature resolution.
Digital Light Processing (DLP)
Revenue is captured through the production and sale of photopolymers designed for digital light processing technologies utilized across healthcare, consumer goods, automotive, and industrial manufacturing applications. Growth is supported by faster printing speeds, excellent resolution, production efficiency, and the ability to manufacture multiple components simultaneously while maintaining consistent quality.
Continuous Digital Light Processing (CDLP)
Revenue is captured through the supply of photopolymers utilized in continuous digital light processing systems for high-throughput additive manufacturing applications. Demand is driven by continuous layer production capabilities, reduced manufacturing time, enhanced productivity, superior surface quality, and increasing adoption in medical, dental, consumer goods, and industrial-scale production environments.
Segment – Application
Revenue capture definition
Dental
Revenue is captured through the utilization of photopolymers in the production of dental models, crowns, bridges, dentures, aligners, surgical guides, and orthodontic appliances. Demand is driven by growing adoption of digital dentistry, requirements for customized patient-specific solutions, high precision manufacturing, and increasing demand for efficient dental treatment workflows.
Medical
Revenue is captured through the commercialization of photopolymers used in medical devices, anatomical models, surgical planning tools, prosthetics, orthotics, and patient-specific healthcare applications. Growth is supported by rising demand for personalized medicine, biocompatible materials, rapid prototyping, and advancements in healthcare additive manufacturing technologies.
Audiology
Revenue is captured through the production and sale of photopolymers utilized in hearing aids, earmolds, custom ear protection devices, and audiology components. Demand is driven by the need for highly customized products, superior fit and comfort, rapid manufacturing capabilities, and increasing prevalence of hearing-related disorders globally.
Jewelry
Revenue is captured through the supply of photopolymers used in jewelry prototyping, casting patterns, custom ornament production, and intricate design development. Growth is supported by increasing demand for personalized jewelry, complex design capabilities, superior surface quality, and cost-effective manufacturing of detailed patterns for investment casting processes.
Automotive
Revenue is captured through the utilization of photopolymers in automotive prototyping, design validation, tooling, functional testing components, and low-volume production parts. Demand is driven by accelerating product development cycles, lightweight component design, improved manufacturing efficiency, and growing adoption of additive manufacturing technologies within the automotive industry.
Prototyping
Revenue is captured through the commercialization of photopolymers used in rapid prototyping applications across multiple industries, including healthcare, aerospace, consumer goods, electronics, and manufacturing. Growth is supported by increasing demand for faster product development, design verification, reduced development costs, and enhanced engineering flexibility.
Industrial/Engineering
Revenue is captured through the production and sale of photopolymers utilized in engineering prototypes, tooling, jigs, fixtures, functional components, and industrial manufacturing applications. Demand is driven by requirements for precision manufacturing, improved mechanical performance, operational efficiency, and cost-effective production of complex industrial parts.
Electronics (including connectors)
Revenue is captured through the supply of photopolymers used in electronic components, connectors, housings, printed circuit board applications, microfluidic devices, and precision electronic assemblies. Growth is supported by miniaturization trends, increasing demand for high-precision manufacturing, and expanding utilization of additive manufacturing technologies within the electronics sector.
Consumer Goods
Revenue is captured through the utilization of photopolymers in customized consumer products, household items, sports equipment, fashion accessories, and lifestyle products. Demand is driven by increasing personalization trends, rapid product innovation, enhanced design flexibility, and growing adoption of on-demand manufacturing solutions.
Others
Revenue is captured through the commercialization of photopolymers across diverse applications including aerospace components, educational models, architectural models, art and design products, research applications, and specialty manufacturing solutions. Growth is supported by continuous material innovation, expanding end-use opportunities, and increasing adoption of additive manufacturing technologies across emerging industries.
Estimation Model
Layer Name
Key Question
Description
Top-Down Photopolymers Demand Scan Layer
What defines market boundaries?
This layer begins with global demand for photopolymers used across additive manufacturing, 3D printing, printing plates, dental devices, medical products, jewelry casting patterns, electronics components, consumer goods, and industrial engineering applications. Demand is filtered based on 3D printer installations, additive manufacturing adoption rates, healthcare digitization trends, industrial production activity, prototyping requirements, electronics manufacturing growth, customization trends, and investments in advanced manufacturing technologies across key end-use industries.
End-Use Application Validation Layer
Where is demand generated?
This layer evaluates demand distribution across dental, medical, audiology, jewelry, automotive, prototyping, industrial/engineering, electronics, consumer goods, and other specialty applications. Market revenue is aligned with key performance requirements such as dimensional accuracy, mechanical strength, biocompatibility, surface finish quality, chemical resistance, durability, printing speed, design flexibility, and compliance with industry-specific regulatory standards across diverse application segments.
Performance & Technology Conversion Layer
Who captures market revenue?
This layer converts application-level consumption into photopolymers revenue by applying performance and technology mix ratios across low-performance, mid-performance, and high-performance photopolymers, as well as Stereolithography (SLA), Digital Light Processing (DLP), and Continuous Digital Light Processing (CDLP) technologies. The analysis incorporates material formulations, resin pricing structures, printing efficiency, curing performance, technological advancements, production economics, application-specific material requirements, and supplier positioning throughout the photopolymer value chain.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing North America’s leadership in healthcare innovation, industrial additive manufacturing, and advanced prototyping activities; Europe’s strong adoption of digital manufacturing technologies and stringent quality standards; and Asia Pacific’s rapidly expanding manufacturing sector, growing healthcare infrastructure, and increasing investment in 3D printing technologies. It also evaluates emerging opportunities in Latin America, the Middle East, and Africa, driven by industrial modernization, rising adoption of digital production methods, expanding healthcare applications, growing electronics manufacturing capabilities, and increasing investment in advanced manufacturing ecosystems.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Delivered detailed market analysis across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including country-level assessments for key markets such as the U.S., Germany, the U.K., France, China, Japan, South Korea, and India. Analysis covered photopolymer demand patterns, technology adoption, regulatory environment, manufacturing activity, and end-use industry trends.
Enabled identification of high-growth regions, investment hotspots, emerging demand centers, regional regulatory influences, and market entry opportunities while supporting strategic expansion planning and resource allocation decisions.
Cross-Segmentation Analysis
Delivered comprehensive cross-segmentation of the photopolymers market by Performance (Low Performance, Mid Performance, High Performance), Technology (SLA, DLP, CDLP), and Application (Dental, Medical, Audiology, Jewelry, Automotive, Prototyping, Industrial/Engineering, Electronics, Consumer Goods, Others).
Provided deeper visibility into revenue concentration, application-specific demand trends, technology adoption patterns, and high-value growth pockets, enabling targeted product development and portfolio optimization strategies.
Opportunity Assessment
Delivered comprehensive evaluation of emerging opportunities across healthcare, dental, electronics, industrial engineering, automotive, consumer goods, and advanced additive manufacturing applications. Analysis included technology trends, adoption barriers, unmet customer requirements, sustainability developments, and future innovation pathways.
Helped identify high-growth investment areas, new product development opportunities, emerging application segments, strategic partnership prospects, and long-term revenue generation potential within the evolving photopolymers ecosystem.
Frequently Asked Questions About This Report
Some key players operating in the photopolymers market include Henkel AG & Co. KGaA, Arkema, Stratasys, BASF SE, Keystone Industries, Formlabs, Carbon, Inc., Evonik Industries AG, Liqcreate, ANYCUBIC Technology Co., Ltd., RAHN AG, and polySpectra.
The growth of the market can be attributed to increasing utilization of high-speed printing, durable complex 3D printed objects, along with design precision are anticipated to propel the demand for the market.
The Europe Photopolymers market accounted for the largest share of 53.1% market size in 2025.
Based on applications, the Dental segment accounted for the largest share of 32.5% market size in 2025. Growing demand for highly accurate, customized, and efficient dental solutions is driving the adoption of photopolymers in dental applications due to their ability to deliver superior dimensional accuracy, fine detail resolution, biocompatibility, and rapid production capabilities.
Germany was the leading Photopolymers market and is expected to grow at a compound annual growth rate of 12.0%.
The stereolithography (SLA) segment based on technology is expected to grow at a CAGR of 11.8% for the forecast period.
The photopolymers market was valued at around USD 3.5 billion in the year 2025 and is expected to reach around USD 3.8 billion in 2026.
The photopolymers market is expected to grow at a compound annual growth rate of 11.3% from 2026 to 2033 to reach around USD 8.1 billion by 2033.
The stereolithography (SLA) led the photopolymers market in 2025 with a 57.2% share. Growing demand for highly accurate, complex, and customized 3D printed components across healthcare, dental, jewelry, automotive, and industrial applications is driving the adoption of Stereolithography (SLA) technology due to its ability to deliver exceptional surface finish, dimensional accuracy, and fine feature resolution.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


