
- Home
- »
- Plastics, Polymers & Resins
- »
-
Plastics in Personalized Drug Delivery Systems Market Report 2033GVR Report cover

Plastics In Personalized Drug Delivery Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (PLA, PLGA, PEG, PU, PEEK), By End Use (Pharmaceuticals & Drug Delivery, Medical Devices & Implants, Healthcare & Clinics), By Region, And Segment Forecasts
Market Size, 2025
$2.1BMarket Estimate, 2026
$2.3BMarket Forecast, 2033
$5.4BCAGR, 2026–2033
12.7%Plastics In Personalized Drug Delivery Systems Market Summary
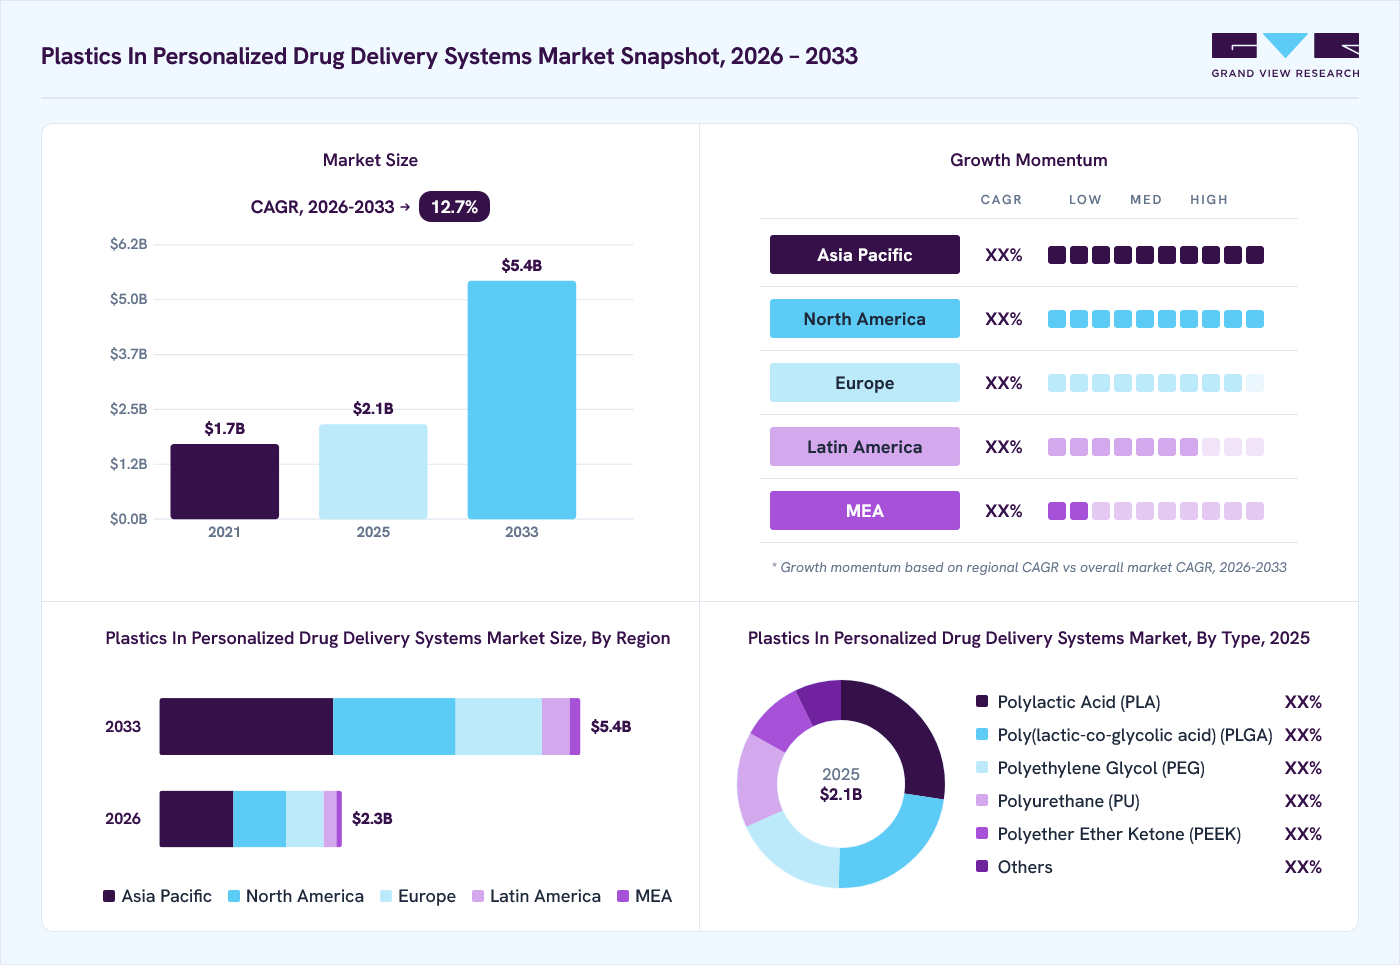
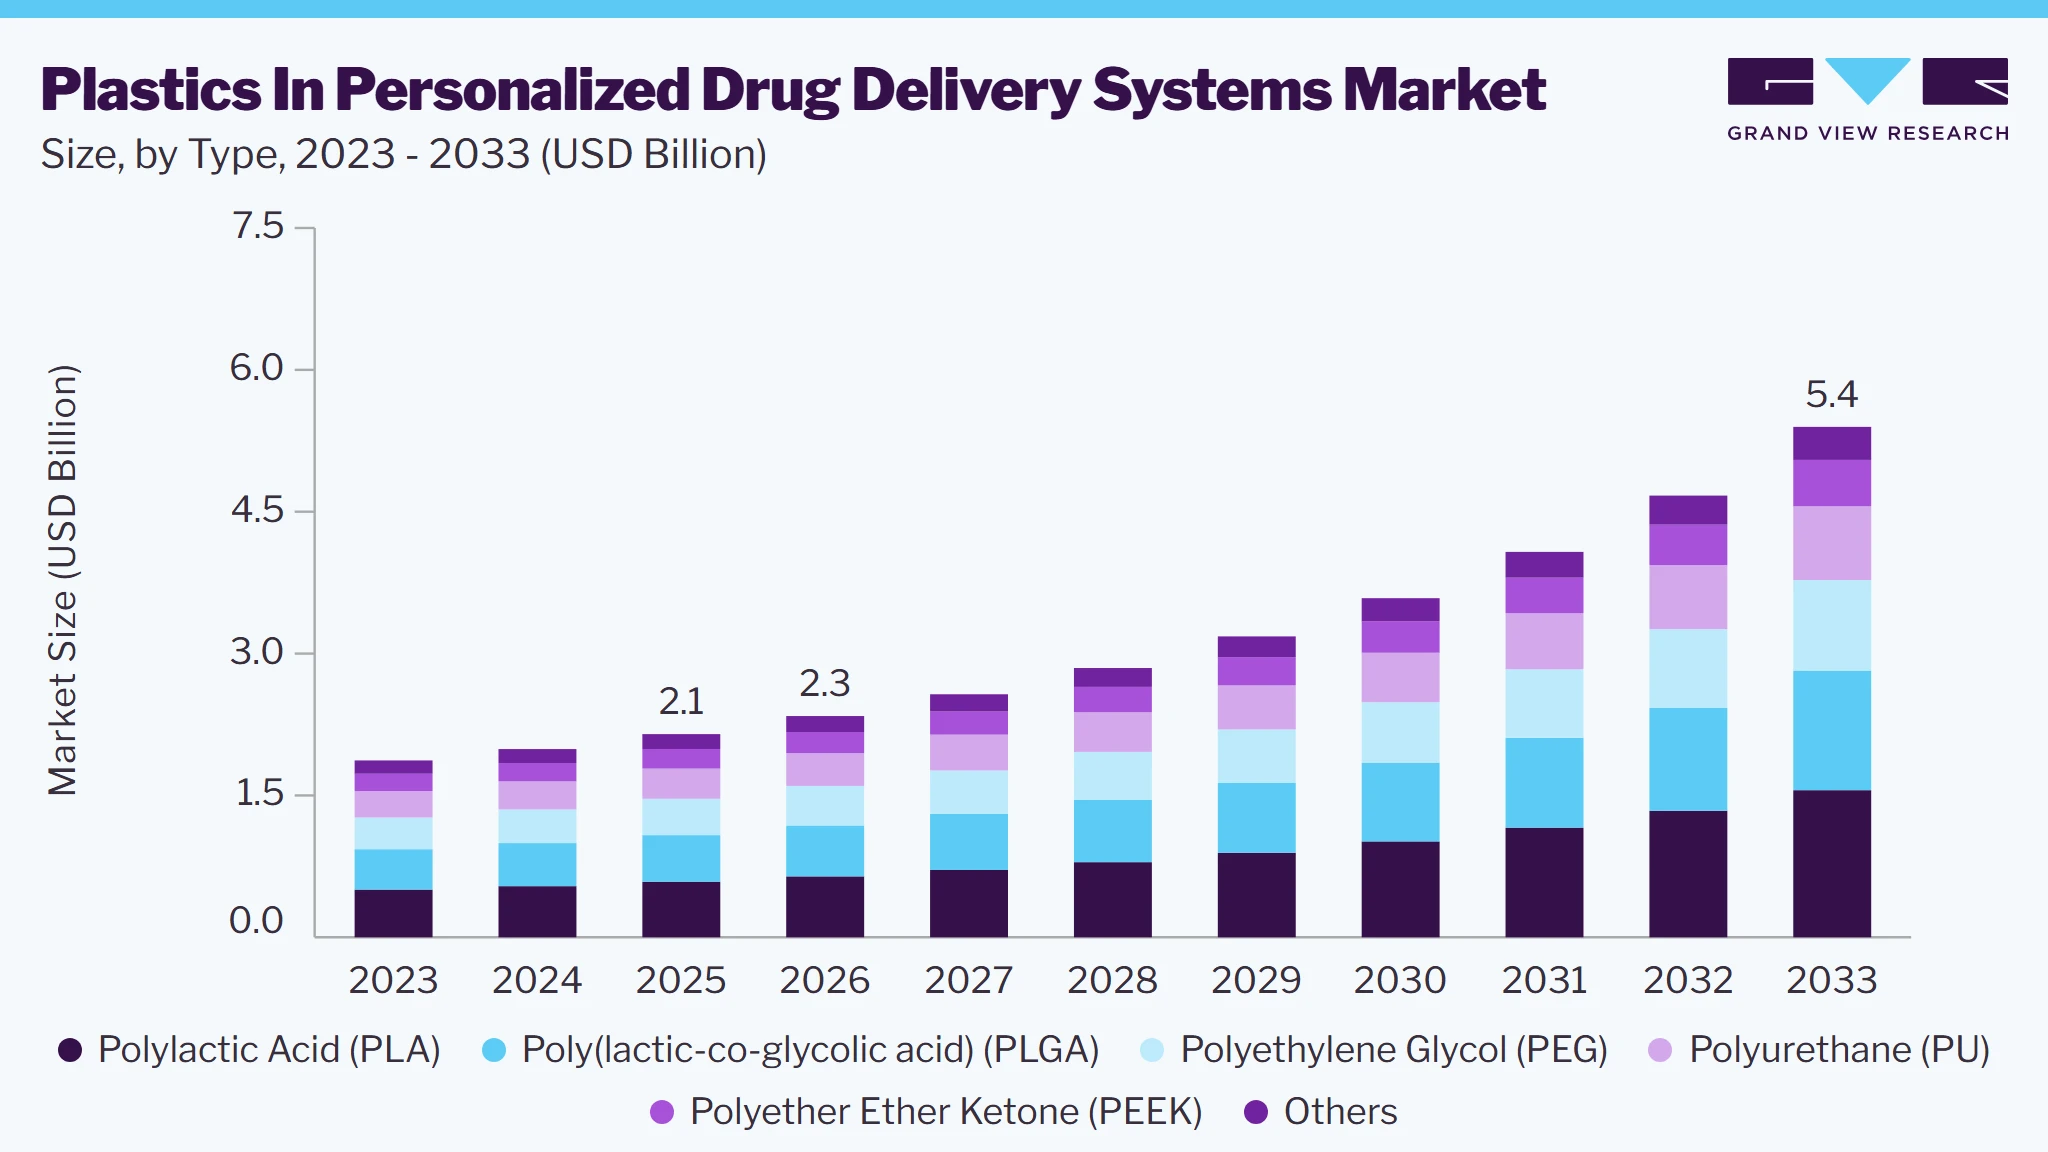
The plastics in personalized drug delivery systems market size was valued at USD 2.1 billion in 2025 and is projected to grow from USD 2.3 billion in 2026 to USD 5.4 billion by 2033, at a CAGR of 12.7% from 2026 to 2033. Asia Pacific dominated the plastics in personalized drug delivery systems market with the largest revenue share of 40.5% in 2025. Increasing adoption of smart and biodegradable polymers across targeted drug delivery, controlled-release formulations, implants, and advanced delivery devices is driving market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Polylactic acid (PLA) segment held the largest market share of 27.4% in 2025.
- By end-use: Pharmaceuticals & drug delivery segment held the largest market share of 38.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.5% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.1 Billion
- Estimated market size in 2026: USD 2.3 Billion
- Projected market size by 2033: USD 5.4 Billion CAGR (2026-2033): 12.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rising demand for personalized therapies further supports expansion through advances in polymer chemistry, stimulus-responsive materials, nanotechnology, and microneedle technologies that improve drug stability, release precision, biocompatibility, and patient compliance.Continuous innovations in polymer chemistry are enabling the development of highly functional, biocompatible, and responsive plastics for more efficient and targeted drug delivery. These materials enhance drug stability, controlled release, and patient compliance, driving market growth.
 To learn more about this report, Download Free Sample Report
The plastics in personalized drug delivery systems industry is witnessing a significant shift towards smart polymer integration, enabling precise, time-controlled drug release mechanisms. These polymers, designed to respond to physiological stimuli such as pH, temperature, and enzymatic activity, are revolutionizing patient-centric treatment approaches. The development of biodegradable and bioresorbable plastic materials is particularly gaining momentum, as they eliminate the need for device retrieval post-administration. This trend aligns with the broader healthcare transition towards precision medicine, ensuring optimized therapeutic outcomes and reducing systemic side effects. Additionally, the convergence of nanotechnology and polymer science is fostering innovations such as polymeric nanoparticles and microneedle patches, further strengthening the role of plastics in next-generation personalized drug delivery systems.
Market Dynamics
Demand for plastics in the personalized drug delivery systems market is being shaped by the shift toward biocompatible, responsive, and biodegradable polymers that support targeted release, sustained dosing, and better patient compliance. End-use intensity is highest in pharmaceutical delivery and implantable systems, where polymeric nanocarriers, microneedle patches, and degradable matrices are being used to improve stability and therapeutic precision. Asia Pacific remains the main demand center, while North America and Europe contribute high-value demand through R&D, regulation, and sustainability-led adoption. Commercial activity is concentrated among qualified material suppliers, pharma partners, and contract developers that can commercialize validated formulations.
The strongest driver is the rising use of biodegradable polymer carriers for long-acting injectables, localized implants, and controlled-release formulations. PLA and PLGA are gaining preference because they combine biocompatibility with predictable degradation, reducing retrieval needs and improving dosing adherence. This is especially relevant for chronic therapies, vaccines, protein drugs, and oncology treatments that require precise release profiles. Pharmacogenomics and 3D printing are also expanding the use of custom polymer structures that can match patient-specific dosing and delivery needs.
Demand is further reinforced by the commercial shift toward nano-enabled delivery systems, where polymeric nanoparticles, microneedles, and smart matrices are used to improve bioavailability and site-specific targeting. Pharma companies increasingly prefer materials that support regulatory acceptance, scalable processing, and sustainability goals at the same time. As a result, suppliers with validated biodegradable grades and formulation support are securing deeper integration into drug development pipelines and contract manufacturing workflows.
The market faces a heavy qualification burden because polymer-based delivery platforms must clear biocompatibility, degradation, toxicity, and stability testing before commercialization. FDA, EMA, and other regional reviews often extend development timelines and raise clinical and documentation costs. The restraint is amplified by concerns over microplastic residues, polymer-drug interaction, and long-term tissue compatibility, which are especially sensitive in implantable and injectable systems. Smaller suppliers also struggle with the cost of GMP-grade production, reproducibility, and scale-up, limiting the speed at which new materials move from laboratory use to approved commercial deployment.
The next opportunity lies in sustainable, bio-based polymers for implantable and injectable drug delivery. Demand is rising for PLA, PLGA, and other biodegradable grades that can support controlled release while aligning with healthcare waste reduction goals. Growth is also opening in 3D-printed implants, polymeric nanomedicine, and microfluidic drug dispensers, especially in Europe and the Asia Pacific, where sustainability and precision medicine are converging. Suppliers that combine materials science with regulatory support can build durable formulation partnerships.
Analyst Perspective
The market for Plastics in Personalized Drug Delivery Systems is projected to see significant growth, propelled by the rising use of patient-specific treatments, biologics, and precision medicine. There is a growing demand for high-performance medical-grade polymers that facilitate intricate drug delivery systems, such as wearable injectors, autoinjectors, implantable devices, inhalers, and microfluidic apparatus, where factors like dimensional accuracy, biocompatibility, chemical resilience, and compatibility with sterilization processes are essential. Innovations in materials are increasingly aimed at improving drug compatibility, supporting miniaturization, and advancing manufacturing methods like micro-molding and additive manufacturing. While strict regulatory demands, comprehensive validation requirements, and lengthy material qualification processes will continue to pose challenges, these conditions are likely to benefit established polymer suppliers who possess strong regulatory knowledge and consistent quality standards.
Type Insights & Trends
Based on type, the polylactic acid (PLA) plastics in the personalized drug delivery systems segment led the market with the largest revenue share of 27.4% in 2025. This growth can be attributed to the rising regulatory emphasis on sustainable medical materials. As a biodegradable and bioabsorbable polymer, PLA aligns with global sustainability goals, addressing both environmental concerns and patient safety.
The increasing need for single-use, biocompatible drug carriers-especially in applications such as injectable nanoparticles, microspheres, and transdermal patches-is accelerating PLA’s integration into advanced drug delivery mechanisms. Furthermore, leading pharmaceutical firms and medical device manufacturers are investing in PLA-based solutions to comply with stringent EU MDR (Medical Device Regulation) and FDA biocompatibility standards, reinforcing its market growth.
The rising prevalence of chronic diseases, such as diabetes, cancer, and autoimmune disorders, is driving the demand for Poly(lactic-co-glycolic acid) (PLGA)-based drug delivery systems that enable long-acting injectable (LAI) therapies. PLGA’s excellent biodegradability, controlled drug-release properties, and regulatory approval by the FDA make it the preferred polymer for formulating sustained-release drugs, protein therapeutics, and vaccine carriers.
The ongoing expansion of mRNA-based vaccines and monoclonal antibody therapies has further positioned PLGA as a critical material for precise, controlled, and patient-friendly drug administration. With major pharmaceutical players intensifying their focus on reducing dosing frequency and improving treatment adherence, PLGA-based formulations continue to gain momentum in next-generation personalized drug delivery.
End Use Insights & Trends
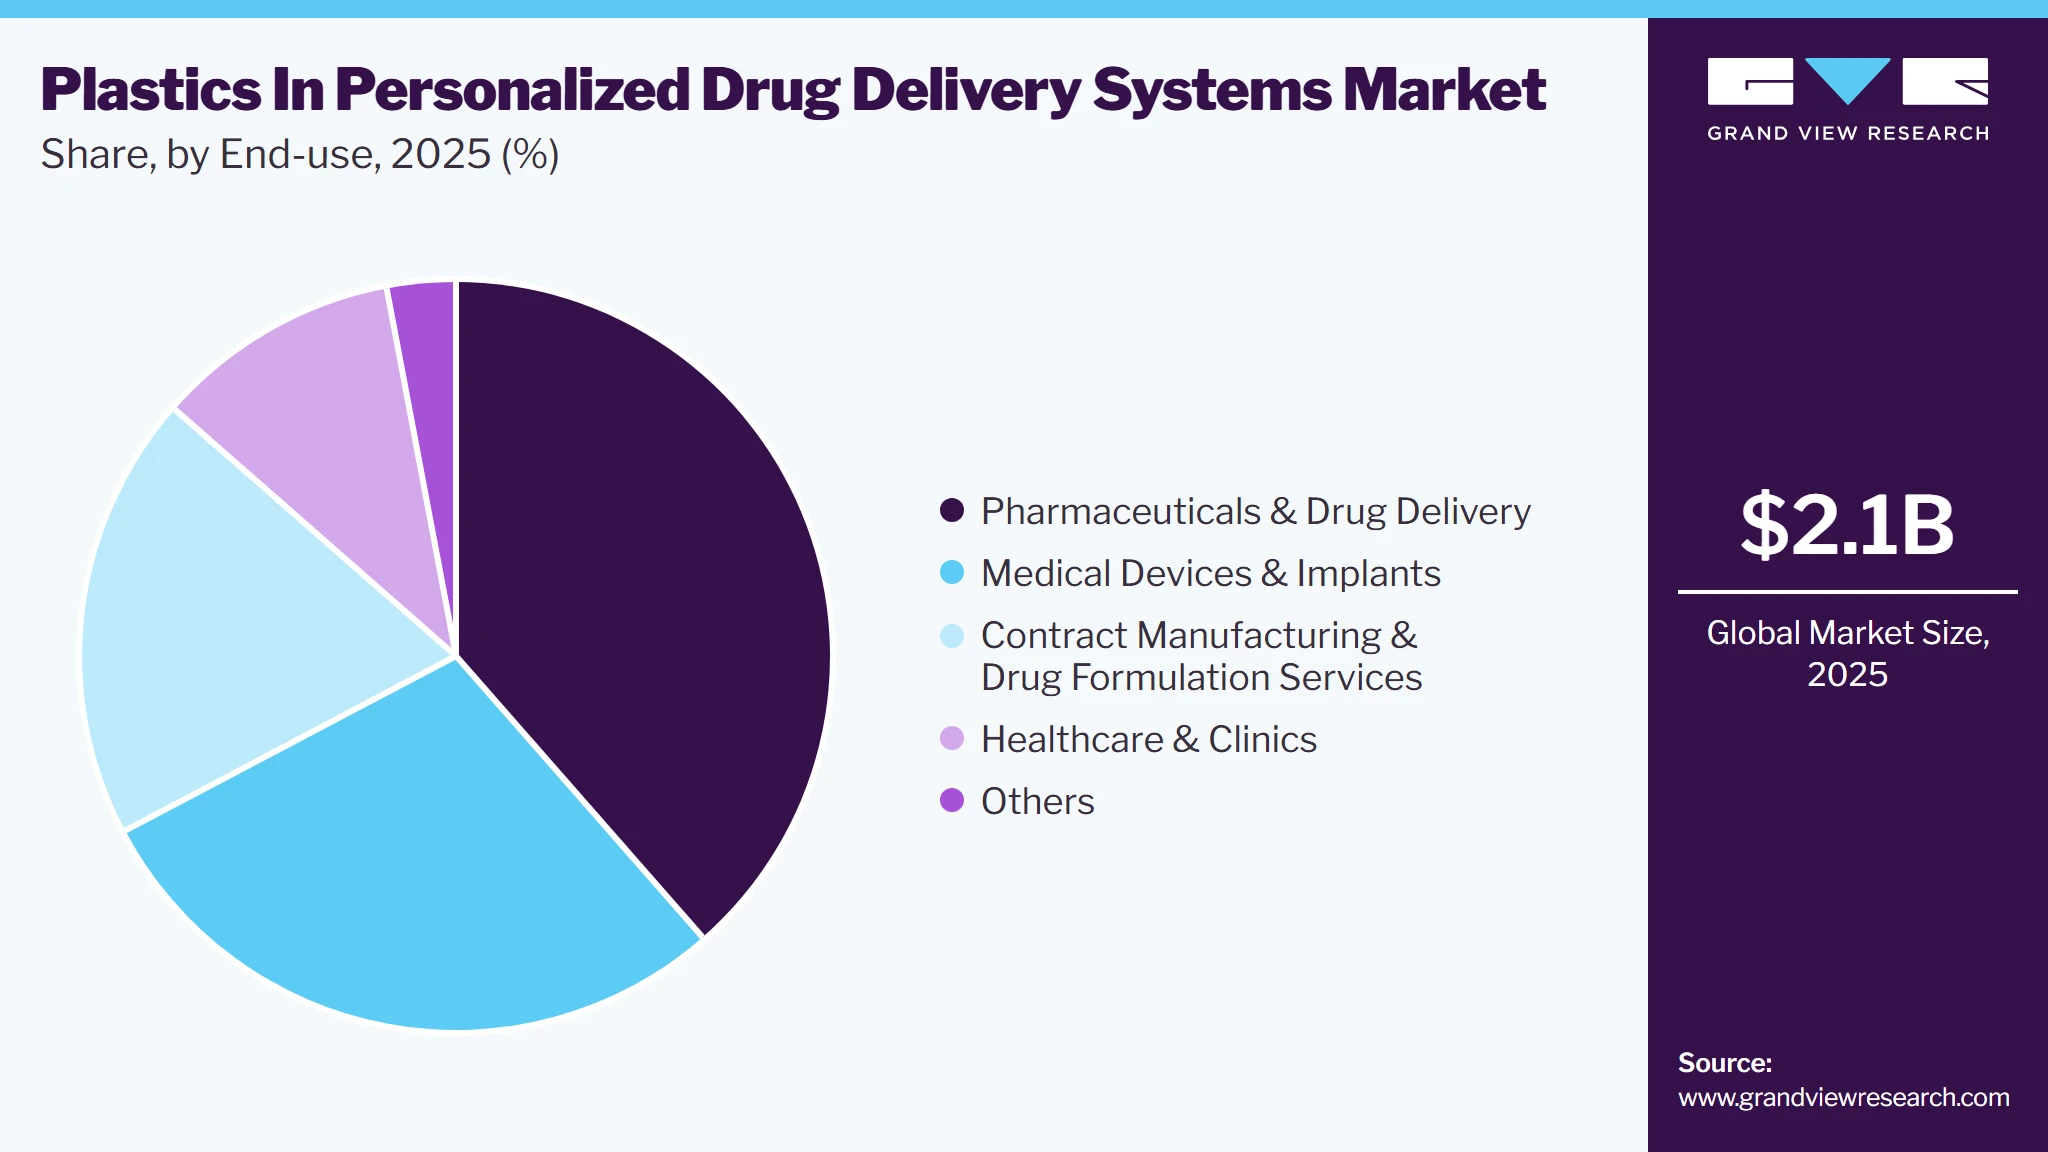
Based on end-use, the pharmaceuticals & drug delivery segment led the market with the largest revenue share of 38.5% in 2025. This is attributable to the growing shift towards nano-enabled drug delivery systems. Advances in polymeric nanocarriers, including liposomes, dendrimers, and polymeric micelles, are transforming drug bioavailability, solubility, and cellular uptake.
Leading biotech firms are actively investing in smart polymeric matrices, leveraging plastics to improve drug encapsulation, site-specific release, and patient compliance. Additionally, strategic partnerships between pharma giants and material science companies are accelerating the commercialization of plastic-based nano-formulations, positioning this segment for rapid expansion amid the demand for precision medicine and biologics.
 To learn more about this report, Download Free Sample Report
The increasing adoption of biodegradable polymer-based implants for localized and sustained drug delivery is a major growth driver within the Medical Devices & Implants segment. Advanced polymer-based implants-such as drug-eluting stents, intraocular lenses, and orthopedic scaffolds-are gaining traction due to their ability to enhance therapeutic efficacy while eliminating the need for secondary surgical removal.
The integration of 3D printing technologies with polymeric biomaterials is further enabling the customization of implantable drug delivery systems tailored to individual patient needs. As regulatory bodies push for safer, more effective implant materials, medical device manufacturers are increasingly shifting towards biodegradable polymer solutions that provide controlled, localized treatment while improving patient outcomes.
Regional Insights & Trends
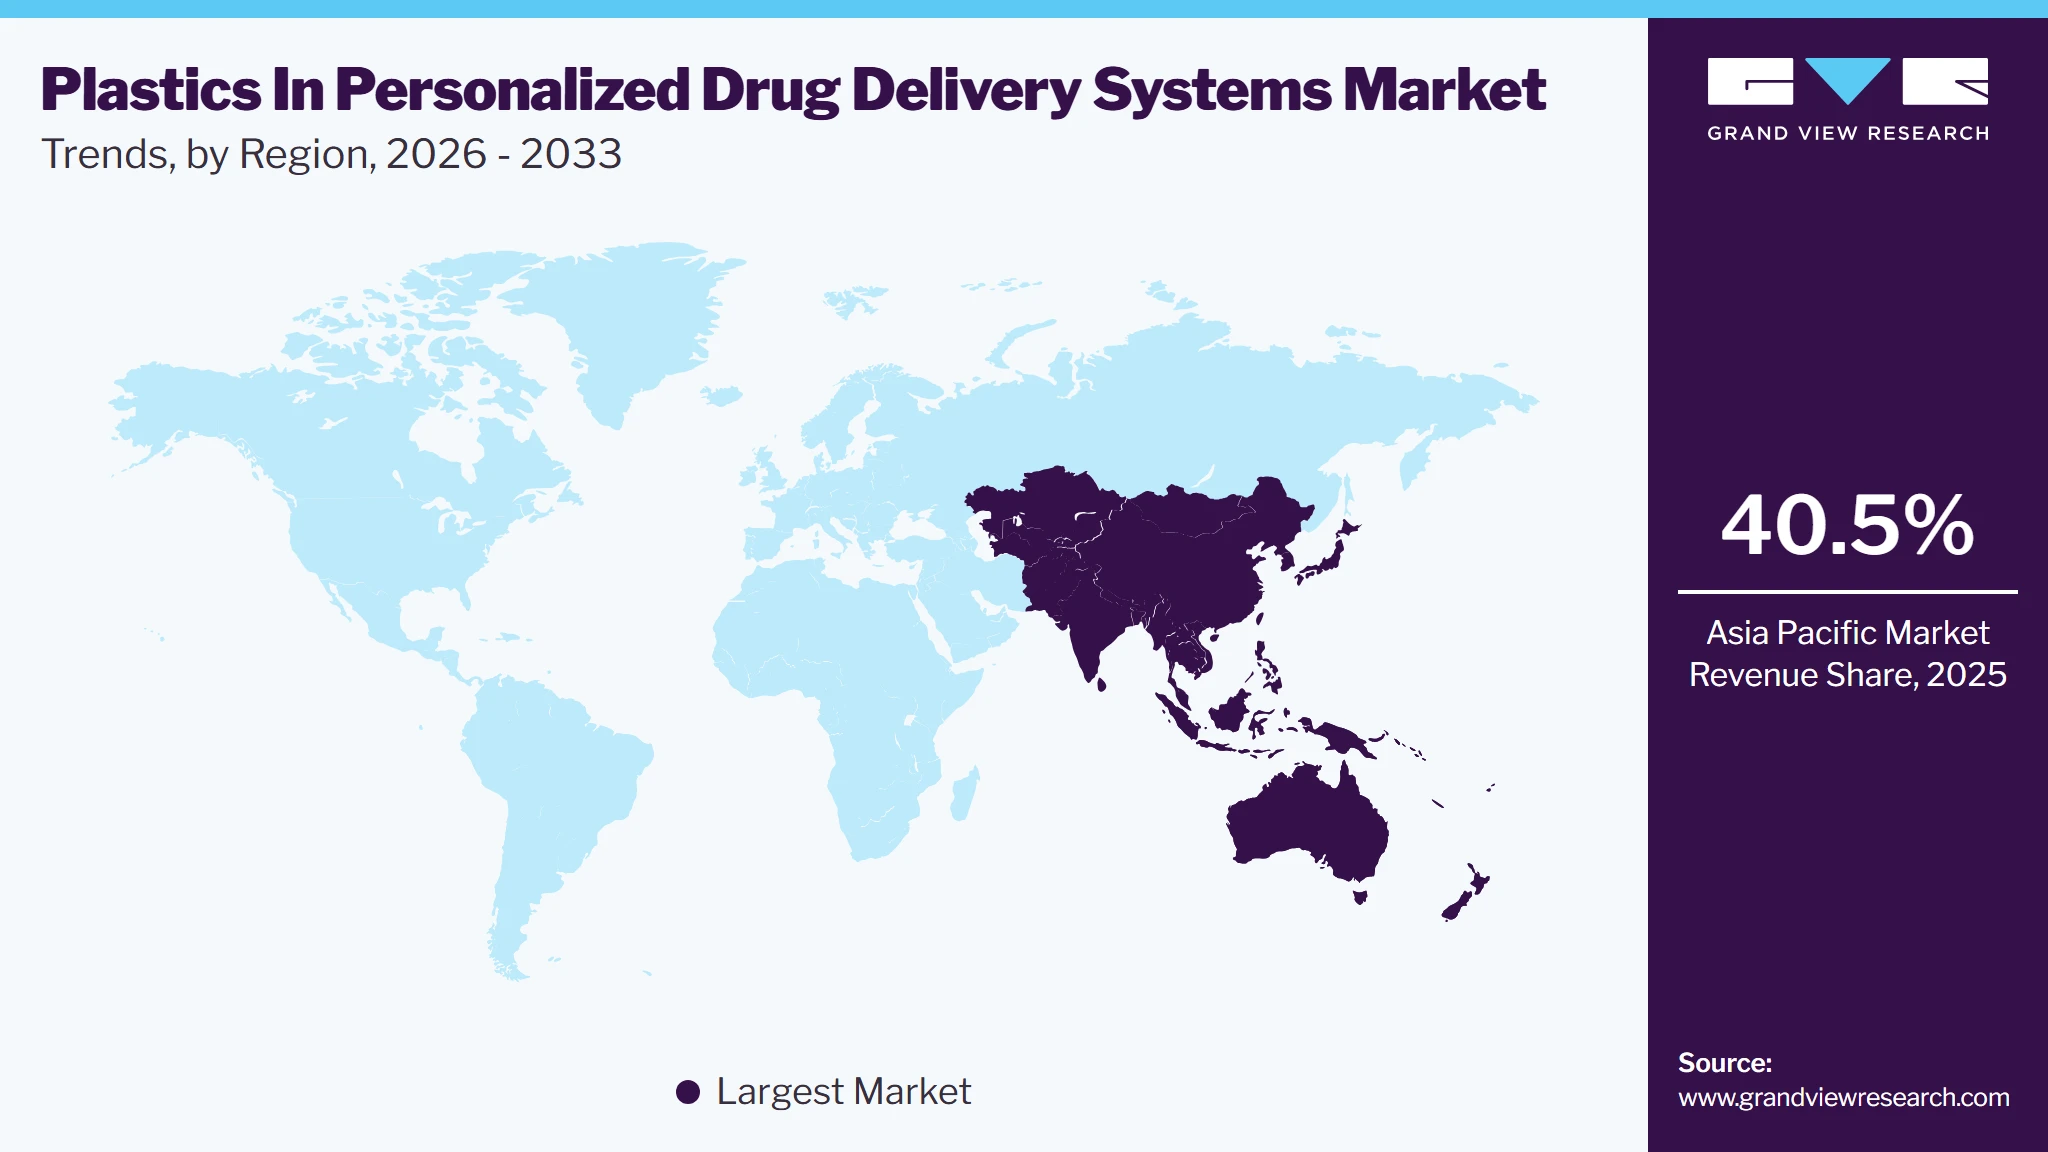
Asia Pacific dominated the plastics in personalized drug delivery systems market with the largest revenue share of 40.5% in 2025. Asia Pacific is emerging as a high-growth region for polymer-based personalized drug delivery, driven by the increasing adoption of precision medicine and advancements in polymer engineering.
 To learn more about this report, Download Free Sample Report
The plastics in personalized drug delivery systems market in China accounted for the largest market revenue share in the Asia Pacific in 2025. The region's rapidly evolving pharmaceutical and biotech sectors, particularly in India, Japan, and South Korea, are fostering innovations in smart, stimuli-responsive polymeric drug carriers for targeted and controlled drug release applications. The rising burden of chronic diseases, an aging population, and government-backed healthcare digitization programs have fueled investments in next-generation polymeric drug delivery technologies, including self-regulating polymeric implants and microfluidic polymer drug dispensers.
North America Plastics In Personalized Drug Delivery Systems Market Trends
North America is experiencing a significant rise in biopharmaceutical research and polymer-based drug delivery innovations, driven by strong funding in precision medicine and advanced material sciences. The region's well-established healthcare infrastructure, coupled with high R&D investments from pharmaceutical giants such as Pfizer, Moderna, and Johnson & Johnson, is fueling the adoption of biodegradable and bioresponsive plastics in personalized drug delivery.
U.S. Plastics In Personalized Drug Delivery Systems Market Trends
In the U.S., the regulatory landscape is a key driver accelerating the adoption of plastics in personalized drug delivery systems, particularly due to the FDA’s progressive stance on innovative polymer-based drug carriers. The expedited approval pathways for novel drug delivery technologies, such as 3D-printed polymer-based implants and biodegradable polymeric nanoparticles, have encouraged pharmaceutical companies to explore cutting-edge polymer formulations. The presence of leading biotech startups and material science companies specializing in biodegradable polymers for sustained and targeted drug release is further fueling market expansion.
Europe Plastics In Personalized Drug Delivery Systems Market Trends
Europe is witnessing a strong push toward sustainability in healthcare, which is significantly driving the adoption of bio-based and biodegradable plastics in personalized drug delivery systems. With the EU Medical Device Regulation (MDR) tightening safety and environmental standards, pharmaceutical and medical device manufacturers are investing in biocompatible, eco-friendly polymer materials such as polyhydroxyalkanoates (PHAs) and polylactic acid (PLA) for drug encapsulation and controlled-release applications. The region’s strong biotechnology ecosystem, particularly in Germany, France, and the Netherlands, is fostering advancements in polymeric nanomedicine and biodegradable polymeric scaffolds for targeted therapies.
China plastics In personalized drug delivery systems market is expected to grow during the forecast period. China is actively driving the adoption of polymer-based personalized drug delivery solutions through strategic government initiatives, local biotech advancements, and regulatory reforms supporting high-tech pharmaceutical manufacturing. The Made in China 2025 policy has prioritized biopolymer research and innovation, encouraging the development of biodegradable, bioresorbable, and intelligent polymer materials for long-acting injectables, targeted therapies, and transdermal drug patches. With the China National Medical Products Administration (NMPA) accelerating approvals for novel polymer-based drug delivery systems, domestic pharmaceutical giants and biotech startups are rapidly investing in polymeric nanocarriers, smart hydrogel-based drug release systems, and personalized polymer implants.
Key Plastics In Personalized Drug Delivery Systems Company Insights
The plastics in personalized drug delivery systems market is highly competitive, with several key players dominating the landscape. Major companies include BASF SE; Evonik Industries; Corbion; Eastman Chemical Company; DuPont de Nemours, Inc.; DSM; Lubrizol Corporation; Arkema; Celanese Corporation; and Avient Corporation. The market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their types.
Key Plastics In Personalized Drug Delivery Systems Companies
The following key companies have been profiled for this study on the plastics in personalized drug delivery systems market.
-
BASF SE
-
Evonik Industries
-
Corbion
-
Eastman Chemical Company
-
DuPont de Nemours, Inc.
-
DSM
-
Lubrizol Corporation
-
Arkema
-
Celanese Corporation
-
Avient Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, Evonik Industries, Eastman Chemical Company, DuPont de Nemours, Inc., DSM, Lubrizol Corporation, Arkema, Celanese Corporation)
Build medical-grade polymer platforms for delivery systems, implants, and formulation support.
Use direct partnerships with pharma, device makers, and CMOs to secure preferred-supplier roles.
Expand specialty processing, compounding, and technical service capabilities to raise switching costs.
Broad manufacturing scale and established regulatory credibility.
Strong R&D depth across specialty plastics and healthcare materials.
Better customer trust in validated, high-specification applications.
Slower portfolio shifts because of large legacy businesses.
Higher compliance and operating costs.
Less agility in small niche programs than focused specialists.
Emerging Players (Corbion, Avient Corporation)
Focus on niche biodegradable grades, customized compounding, and application-specific support.
Target partnerships with device makers, formulation developers, and outsourced manufacturers.
Use faster product tailoring and selective geographic expansion.
Greater agility in targeted use cases.
Stronger fit for unmet needs in sustainable or custom delivery systems.
Faster collaboration cycles with smaller development teams.
Smaller scale and narrower validation base.
Greater dependence on partner ecosystems for commercial reach.
Higher exposure to pricing pressure and customer concentration.
Recent Developments
-
In November 2024, Avantium and SCGC strengthened their partnership to advance the development of PLGA polyester, a biodegradable and recyclable material. They signed a multi-year agreement to pilot PLGA production using Avantium's Volta Technology, which converts CO2 into glycolic acid, a key component of PLGA.
-
In July 2023, CD Bioparticles, a company experienced in pharmaceuticals and life sciences, recently launched a new line of PLGA-based drug delivery systems. These systems are designed for both in vitro and in vivo applications and include biocompatible and biodegradable PLGA nanoparticles with various surface modifications. These nanoparticles can transport different types of drugs, protect them from degradation, and enhance interaction with biological materials. The new product line includes Streptavidin Coated PLGA Nanoparticles, Functionalized PLGA Nanoparticles, and Functionalized Fluorescent Magnetic PLGA Nanoparticles.
Plastics In Personalized Drug Delivery Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.1 billion
Estimated market size in 2026
USD 2.3 billion
Projected market size by 2033
USD 5.4 billion
Growth rate
CAGR of 12.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S., Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
BASF SE; Evonik Industries; Corbion; Eastman Chemical Company; DuPont de Nemours, Inc.; DSM; Lubrizol Corporation; Arkema; Celanese Corporation; Avient Corporation
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase-addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Plastics In Personalized Drug Delivery Systems Market Report Segmentation
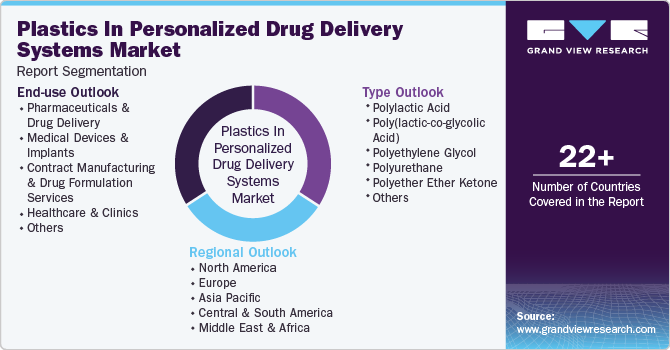
This report forecasts volume & revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented plastics in personalized drug delivery systems market report based on type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polylactic Acid (PLA)
-
Poly(lactic-co-glycolic acid) (PLGA)
-
Polyethylene Glycol (PEG)
-
Polyurethane (PU)
-
Polyether Ether Ketone (PEEK)
-
Others
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Pharmaceuticals & Drug Delivery
-
Medical Devices & Implants
-
Contract Manufacturing & Drug Formulation Services
-
Healthcare & Clinics
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The plastics in personalized drug delivery systems Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each plastics in personalized drug delivery systems Market segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
PLA
Revenue is captured through sales of medical-grade PLA resins and compounds used in injectable microspheres, transdermal patches, temporary implants, and drug-eluting carriers for pharma and device customers.
PLGA
Revenue is generated from high-purity PLGA grades supplied for long-acting injectables, sustained-release carriers, vaccine delivery, and nanoparticle formulations that require controlled degradation.
PEG
Revenue is captured through functional PEG derivatives and surface-modifying materials used to improve solubility, circulation time, and carrier stability in customized delivery systems.
PU
Revenue comes from polyurethane formulations used in flexible implant housings, catheter-based systems, and controlled-release components where durability and processability are required.
PEEK
Revenue is earned from high-performance PEEK grades used in load-bearing implants, durable delivery devices, and precision components that require chemical resistance and structural strength.
Others
This segment captures revenue from specialty blends, niche biomedical polymers, and application-specific formulations not covered in the main type categories.
Segment - End-use
Revenue capture definition
Pharmaceuticals & Drug Delivery
Revenue is captured through polymer carriers, nano-formulations, encapsulation matrices, and development partnerships with pharma and biotech companies for targeted and sustained release applications.
Medical Devices & Implants
Revenue is generated from implantable drug-eluting devices, scaffolds, stents, intraocular lenses, and customized delivery hardware using biodegradable or durable plastics.
Contract Manufacturing &
Drug Formulation Services
Revenue is captured through toll compounding, custom formulation, scale-up support, sterile processing, and outsourced manufacturing linked to branded drug delivery programs
Healthcare & Clinics
Revenue is earned from hospital-administered delivery products, clinic-led treatment kits, and procedure-linked materials used in localized therapy and patient management.
Others
This residual segment includes research, diagnostics-adjacent, and specialty service uses that do not fit the main commercial end-use buckets.
Estimation Model
Layer Name
Key Question
Description
Type Layer
Why segment by polymer type?
Revenue is mapped by polymer family first because PLA, PLGA, PEG, PU, and PEEK carry different approval paths, processing limits, and pricing power.
End-use Layer
Why segment by end use?
End-use allocation follows because pharmaceuticals, implants, contract manufacturing, and clinics consume plastics at different intensities and with different validation burdens.
Regional Layer
Why assess regional demand?
Regional scaling reflects Asia Pacific manufacturing depth, North American R&D intensity, and Europe’s sustainability-led shift toward bio-based and biodegradable polymers.
Company Layer
Why benchmark key companies?
Supplier shares are inferred from medical-grade portfolios, regulatory readiness, integration strength, and the ability to support downstream formulation and commercialization.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country-level coverage
Expanded the analysis across selected countries in North America, Europe, and the Asia Pacific, with demand commentary aligned to localized regulation, pharma capacity, and implant adoption patterns.
Improves regional prioritization and supports sharper market-entry planning.
Type-level ranking
Added a more detailed view of PLA, PLGA, PEG, PU, PEEK, and other polymers, with revenue logic tied to processing suitability, compliance needs, and application depth.
Clarifies which materials deserve portfolio focus.
Company benchmarking
Benchmarked leading suppliers on integration, regulatory readiness, medical-grade capability, and downstream collaboration strength to show where competitive advantage is forming.
Helps position suppliers against peers more precisely.
Frequently Asked Questions About This Report
The global plastics in personalized drug delivery systems market size was valued at USD 1.9 billion in 2024 and is estimated at USD 2.3 billion for 2026.
The global plastics in personalized drug delivery systems market is expected to grow at a CAGR of 10.8% from 2025 to 2030, reaching USD 3.6 billion by 2030.
Which segment accounted for the largest plastics in personalized drug delivery systems market share?Polylactic acid (PLA) dominated the plastics in personalized drug delivery systems market across the type segmentation in terms of revenue, accounting for a market share of 27.16% in 2024, driven the by rising regulatory emphasis on sustainable medical materials. As a biodegradable and bioabsorbable polymer, PLA aligns with global sustainability goals, addressing both environmental concerns and patient safety.
Some key players operating in the plastics in personalized drug delivery systems market include BASF SE, Evonik Industries, Corbion, Eastman Chemical Company, DuPont de Nemours, Inc., DSM, Lubrizol Corporation, Arkema, Celanese Corporation, and Avient Corporation
Continuous innovations in polymer chemistry are enabling the development of highly functional, biocompatible, and responsive plastics for more efficient and targeted drug delivery. These materials enhance drug stability, controlled release, and patient compliance, driving market growth.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


