
- Home
- »
- Advanced Interior Materials
- »
-
Pneumatic Tools Market Size And Share Report, 2026-2033GVR Report cover

Pneumatic Tools Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Impact Wrenches, Nailers & Staplers, Grinders & Sanders, Pneumatic Drills, Ratchet Wrenches, Others), By End Use (Automotive, Construction), By Region, And Segment Forecasts
Market Size, 2025
$9.2BMarket Estimate, 2026
$9.8BMarket Forecast, 2033
$17.3BCAGR, 2026–2033
8.5%Pneumatic Tools Market Summary
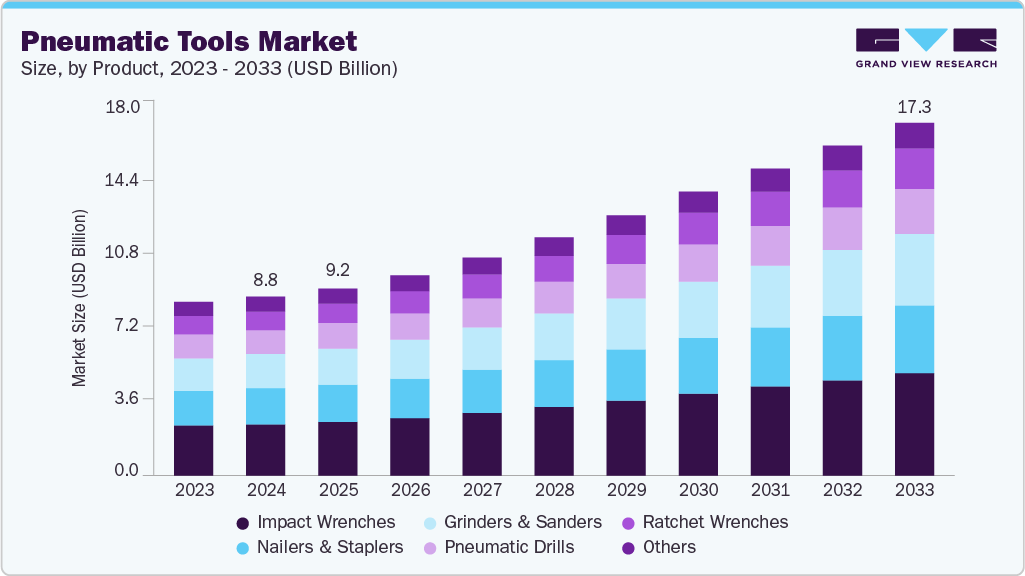
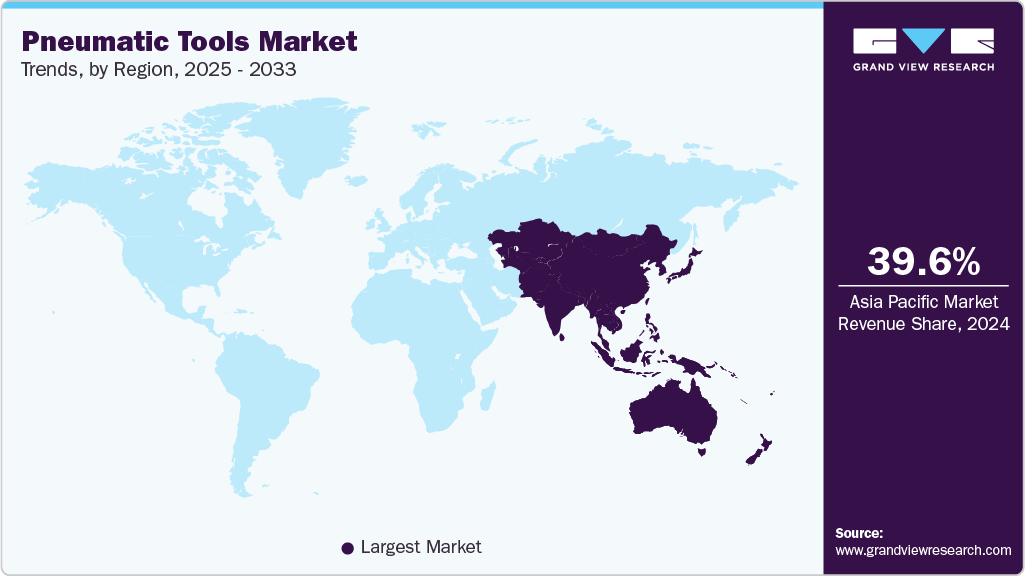
The global pneumatic tools market size was valued at USD 9.2 billion in 2025 and is projected to grow from USD 9.8 billion in 2026 to USD 17.3 billion by 2033, at a CAGR of 8.5% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 39.7% in 2025. The market is witnessing steady growth due to increasing industrial automation and the need for high-efficiency assembly and fabrication operations.
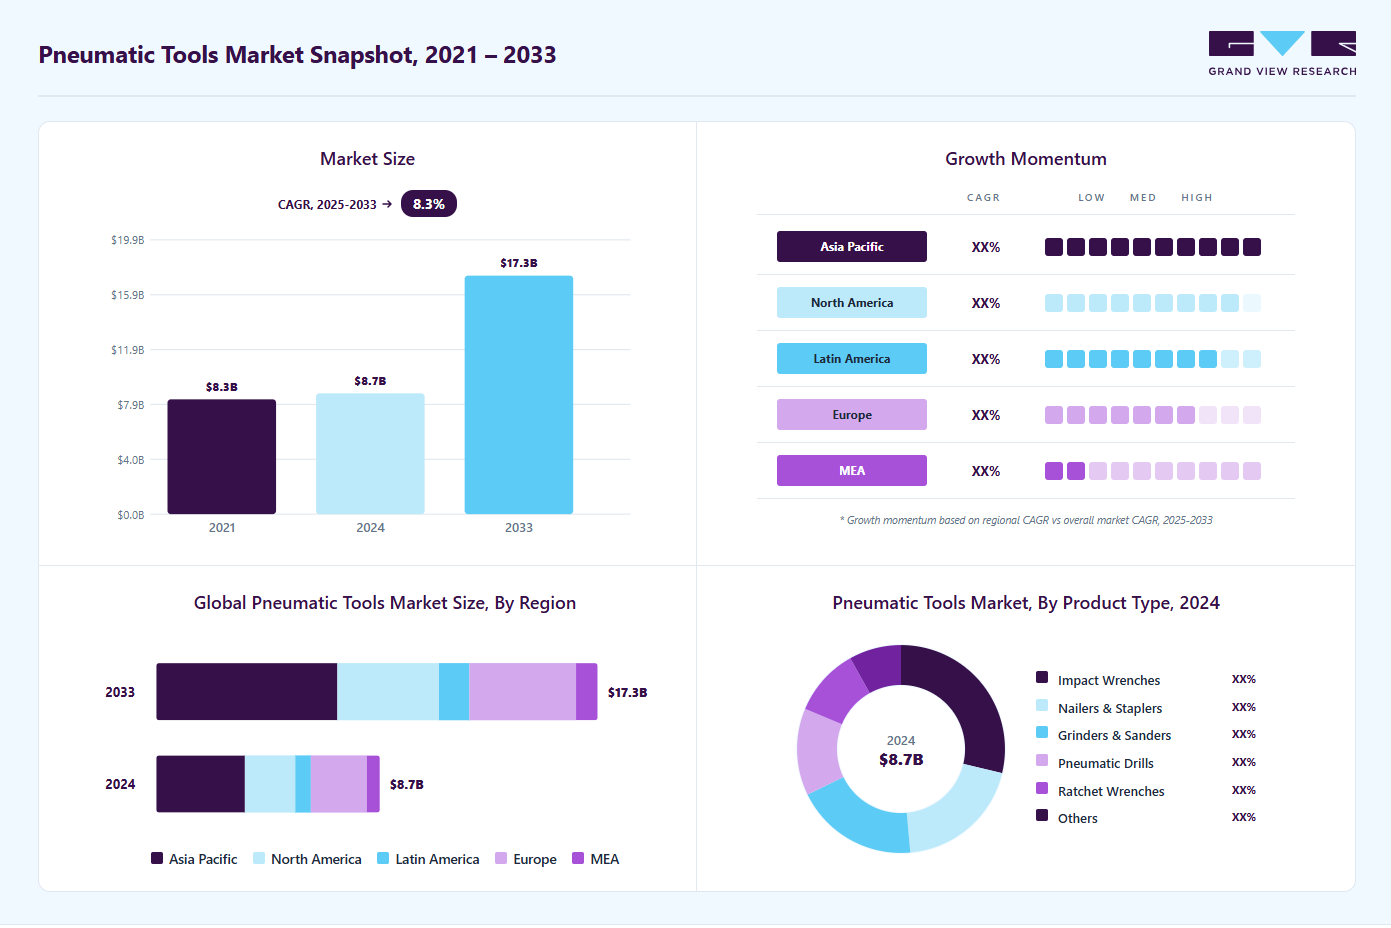 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Impact wrenches segment held the largest market share of 28.8% in 2025.
- By end use: Automotive segment held the largest market share of 34.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (39.7% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 9.2 Billion
- Estimated market size in 2026: USD 9.8 Billion
- Projected market size by 2033: USD 17.3 Billion
- CAGR (2026-2033): 8.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Pneumatic tools are preferred in sectors such as automotive, aerospace, construction, and manufacturing for their durability, consistent torque, and ability to perform heavy-duty tasks. Growing infrastructure projects and expanding production facilities in developing economies are further driving adoption. In addition, industries are focusing on reducing manual labor fatigue and improving workplace safety, making air-powered tools a practical choice.Major factors driving demand include the increasing adoption of lightweight and energy-efficient tools, the growth of the automotive aftermarket, and continuous technological improvements in compressor and air management systems. Pneumatic tools provide operational advantages such as higher speed, reduced maintenance, and longer service life compared to electric tools. Industries seeking sustainable solutions are turning to pneumatic systems due to their lower energy consumption and fewer emissions. Moreover, rapid expansion in manufacturing units and the growing demand for precision in metalworking and fabrication activities are key demand accelerators in the global market.
 To learn more about this report, Download Free Sample Report
Technological innovations such as integration of IoT-enabled smart pneumatic systems, noise-reduction mechanisms, and oil-free operation designs are reshaping the market landscape. Manufacturers are investing in portable and compact pneumatic tools to cater to small and medium enterprises. The trend of combining digital monitoring with pneumatic technology is gaining traction, allowing predictive maintenance and performance optimization. Moreover, advancements in composite materials are resulting in lighter yet more powerful tools. Automation in automotive assembly lines and the introduction of hybrid air-electric tools are further setting new benchmarks in productivity and sustainability.
Market Dynamics
The pneumatic tools market is influenced by increasing industrial automation, expanding manufacturing activities, and growing demand for lightweight, durable, and high-performance tools across automotive, construction, aerospace, and metal fabrication applications. The widespread adoption of compressed air-powered tools is supported by their reliability, high power-to-weight ratio, and suitability for continuous industrial operations. Technological advancements in ergonomic designs, vibration reduction, noise control, and energy-efficient air systems are further enhancing product performance and workplace productivity. At the same time, fluctuations in raw material prices, maintenance requirements for compressed air infrastructure, stringent workplace safety regulations, increasing demand for sustainable manufacturing practices, and competition from electric and cordless power tools continue to influence product innovation, procurement decisions, and competitive dynamics across the market.
The growing adoption of industrial automation and the expansion of manufacturing activities are driving demand for pneumatic tools across a wide range of industries. Automotive, aerospace, metal fabrication, construction, and industrial assembly facilities increasingly rely on pneumatic tools for their durability, high power-to-weight ratio, and ability to support continuous operations. The ongoing modernization of production facilities and the emphasis on improving operational efficiency, precision, and productivity continue to strengthen demand for advanced pneumatic tools. Furthermore, increasing investments in smart manufacturing and factory automation are encouraging industries to replace conventional tools with high-performance pneumatic solutions that offer consistent performance and reliability.
The performance of pneumatic tools depends on a reliable compressed air system, requiring investment in compressors, air distribution networks, and regular maintenance. Installation and operating costs associated with compressed air infrastructure can increase the total cost of ownership, particularly for small and medium-sized enterprises. In addition, air leakage, energy losses, and maintenance requirements may reduce operational efficiency and influence purchasing decisions. Competition from battery-powered cordless tools, which offer greater mobility and lower infrastructure requirements, is further challenging market adoption in certain applications.
Increasing investments in construction projects and the expanding maintenance, repair, and operations (MRO) sector are creating significant growth opportunities for pneumatic tool manufacturers. Industries continue to adopt pneumatic impact wrenches, drills, grinders, sanders, and fastening tools to improve productivity and reduce operator fatigue in demanding work environments. As infrastructure development, industrial maintenance activities, and equipment servicing continue to expand globally, demand for reliable and high-performance pneumatic tools is projected to increase steadily.
Market Concentration & Characteristics
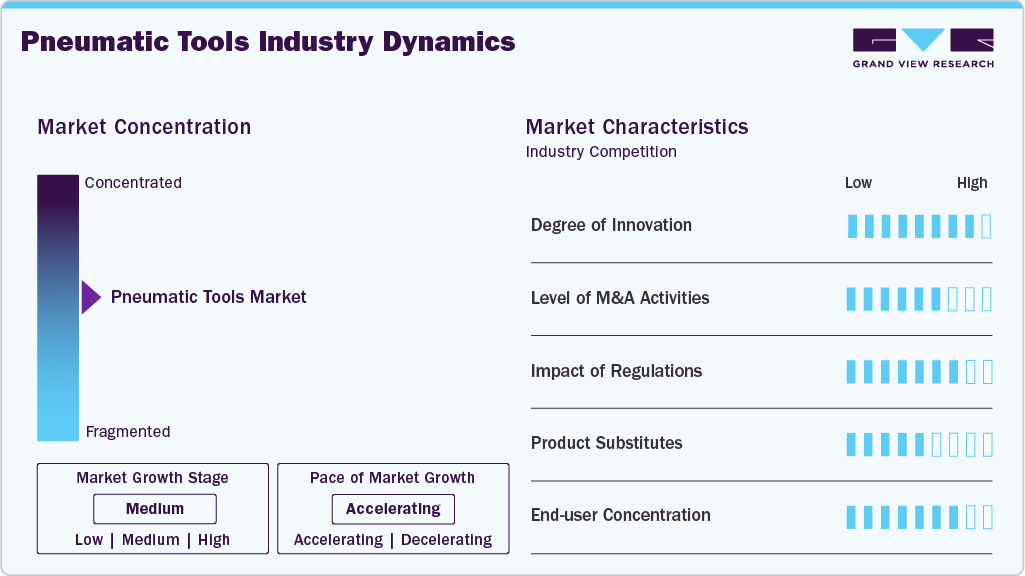
The pneumatic tools industry is moderately consolidated, with major players such as Ingersoll Rand, Chicago Pneumatic, and Bosch dominating the global landscape. These companies hold a significant share due to extensive product portfolios, strong brand presence, and wide distribution networks. However, numerous regional manufacturers are entering the market, especially in the Asia Pacific, intensifying price competition. Strategic mergers, product differentiation, and aftermarket service offerings have become key focus areas for leading firms to sustain competitiveness and customer loyalty.
 To learn more about this report, Download Free Sample Report
Electric and battery-operated tools are emerging as strong substitutes for pneumatic tools due to advancements in lithium-ion battery technology, cordless operation, and lower infrastructure requirements. However, pneumatic tools still maintain an edge in heavy-duty industrial and continuous-use environments due to their higher torque and reliability. The threat of substitution is moderate, as industries with high productivity demands continue to prefer air-powered tools for their consistent performance, longer lifespan, and lower risk of overheating.
Analyst Perspective
The pneumatic tools market is growing steadily as industries continue to prioritize productivity, reliability, and operational efficiency in manufacturing and maintenance operations. Demand remains strong across automotive, aerospace, construction, metal fabrication, oil & gas, and general industrial sectors, where pneumatic tools are valued for their high power-to-weight ratio, durability, and ability to operate continuously in demanding environments. In addition, increasing investments in industrial automation, assembly line modernization, and infrastructure development are supporting the adoption of advanced pneumatic tools with improved ergonomics, lower vibration levels, and enhanced energy efficiency. As manufacturers focus on improving worker safety and reducing downtime, suppliers offering lightweight, high-performance, and application-specific pneumatic tools are expected to benefit from sustained long-term market growth.
Product Type Insights
Based on product type, the impact wrenches segment led the market with the largest revenue share of 28.8% in 2025, due to their ability to deliver high torque efficiently for heavy-duty fastening and loosening tasks. They are widely used in automotive, industrial, and construction applications where speed and reliability are critical. The durability, ease of use, and consistent performance of pneumatic impact wrenches make them the preferred choice over electric alternatives in high-volume operations. Their dominance is further supported by ongoing innovations in lightweight designs and ergonomic handling.
The ratchet wrenches segment is expected to grow at the fastest CAGR of 9.4% over the forecast period, as industries increasingly seek compact, precise, and user-friendly tools for assembly and maintenance tasks. Their ability to access tight spaces and provide controlled torque makes them ideal for automotive, aircraft, and machinery applications. Technological improvements such as cordless integration, vibration reduction, and energy-efficient operation are accelerating adoption. The growth of small and medium enterprises and increased focus on workplace ergonomics also contribute to rising demand.
End Use Insights
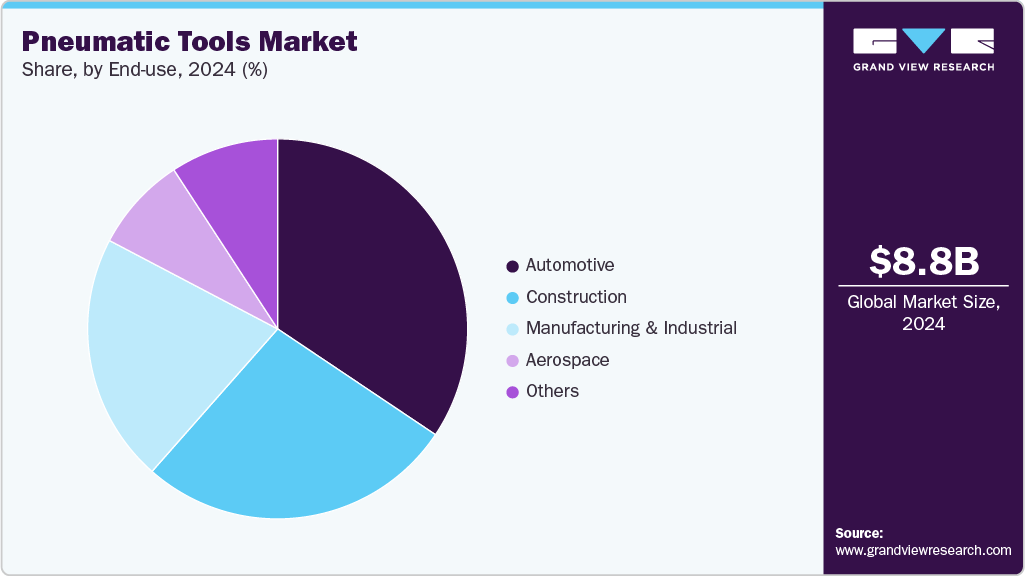
Based on end use, the automotive segment led the market with the largest revenue share of 34.5% in 2025, driven by the need for fast, reliable, and high-precision assembly in manufacturing and repair operations. Pneumatic tools are essential for wheel alignment, engine assembly, and chassis construction due to their high torque output and consistent performance. Growing vehicle production globally, coupled with the rise of electric vehicles requiring specialized assembly tools, continues to strengthen the dominance of automotive applications in the market.
 To learn more about this report, Download Free Sample Report
The construction segment is expected to grow at the fastest CAGR of 9.1% over the forecast period, fueled by expanding infrastructure projects, urbanization, and industrial development. Tools like nailers, grinders, and air hammers improve productivity and reduce manual effort in building, renovation, and heavy-duty tasks. Rising demand for energy-efficient and durable equipment, along with increasing adoption of pneumatic systems for precision work, is driving substantial growth in this sector. Construction companies are increasingly integrating pneumatic tools to enhance operational efficiency and safety.
Regional Insights
Asia Pacific dominated the pneumatic tools market with the largest revenue share of 39.7% in 2025, owing to rapid industrialization, growing automotive production, and a surge in construction activities. China, India, and Japan are the leading contributors due to significant investment in manufacturing and automation infrastructure. Increasing labor costs have also encouraged industries to adopt pneumatic systems for efficiency. The presence of local manufacturers offering affordable products and the availability of skilled labor further support regional growth. Expanding electronics and consumer goods sectors continue to create new opportunities for pneumatic tool suppliers.
 To learn more about this report, Download Free Sample Report
China Pneumatic Tools Market Trends
The pneumatic tools market in China held the largest share in the Asia Pacific region in 2025. China’s pneumatic tools industry is witnessing robust growth due to the expanding automotive manufacturing base and government-backed initiatives to modernize industrial facilities. The shift toward smart manufacturing and robotics integration has accelerated demand for precision pneumatic systems. Domestic brands are investing in R&D to compete with international players by introducing energy-efficient, cost-effective solutions. Rising construction activities and export-oriented industrial output continue to drive the adoption of high-performance pneumatic equipment across various end-use sectors.
North America Pneumatic Tools Market Trends
The North America pneumatic tools industry is experiencing steady growth driven by technological innovation and automation across automotive, aerospace, and oil & gas industries. The U.S. and Canada are witnessing increasing adoption of advanced pneumatic assembly tools integrated with IoT monitoring capabilities. Demand for lightweight, ergonomic tools with noise-reduction features is also high due to strict workplace safety standards. Moreover, the strong presence of key global manufacturers and a growing focus on sustainable manufacturing practices support long-term market expansion.
The U.S. pneumatic tools industry benefits from continuous industrial upgrades, infrastructure redevelopment projects, and high demand for durable, maintenance-free equipment. The resurgence of domestic manufacturing, supported by the Inflation Reduction Act and federal infrastructure funding, is further driving tool adoption. The market also sees growing interest in hybrid pneumatic-electric tools for flexible operation across assembly lines. Strong innovation ecosystems and collaborations between toolmakers and automation firms keep the U.S. at the forefront of pneumatic technology advancement.
Europe Pneumatic Tools Market Trends
Europe’s pneumatic tools industry is characterized by a strong emphasis on worker safety, energy efficiency, and automation compliance. Germany, Italy, and the U.K. lead adoption due to their advanced industrial sectors. EU directives on sustainable manufacturing and carbon footprint reduction are driving the shift toward eco-friendly pneumatic systems. The rise of Industry 4.0 initiatives and demand for precision assembly tools in the automotive and aerospace sectors continues to strengthen market potential across the region.
Germany pneumatic tools industry remains a significant hub for pneumatic tool innovation due to its strong engineering base and manufacturing excellence. The country’s automotive and mechanical engineering industries extensively use pneumatic systems for assembly and production automation. German manufacturers are investing in smart, sensor-integrated pneumatic tools that align with Industry 4.0 standards. Government support for sustainable industrial practices and energy-efficient solutions further enhances the growth prospects of the pneumatic tools industry in the nation.
Central & South America Pneumatic Tools Market Trends
Central & South America’s pneumatic tools industry is gaining traction due to the revival of manufacturing and construction sectors in countries such as Brazil and Mexico. Growing industrial automation and the expansion of the automotive supply chain are key factors driving demand. The availability of affordable imported products and increasing awareness of tool efficiency are boosting market penetration. Although economic fluctuations pose challenges, industrial growth initiatives and FDI inflows are supporting the regional market outlook.
Middle East & Africa Pneumatic Tools Market Trends
The Middle East & Africa pneumatic tools industry is witnessing gradual growth driven by infrastructure development and the expansion of the oil & gas and construction industries. Countries such as Saudi Arabia, the UAE, and South Africa are investing in industrial automation and modernization projects, creating demand for durable pneumatic tools. The focus on diversification away from oil-based economies is encouraging investments in manufacturing, logistics, and renewable energy industries-all of which rely heavily on pneumatic systems.
Key Pneumatic Tools Company Insights
Some of the key players operating in the market include Atlas Copco and Bosch.
-
A Swedish industrial powerhouse, Atlas Copco specializes in compressors, vacuum solutions, air and gas treatment systems, and pneumatic tools. The company is known for innovation, energy-efficient products, and a strong global presence in industrial automation and construction sectors.
-
A German multinational, Bosch, produces a wide range of power tools, including pneumatic tools, electric tools, and accessories. It focuses on technological innovation, ergonomics, and durable solutions for industrial, construction, and professional applications.
Nitto Kohki and HiKoki Power Tools are some of the emerging market participants in the pneumatic tools industry.
-
A Japanese manufacturer, Nitto Kohki, is recognized for its high-quality pneumatic tools, couplings, and assembly equipment. The company emphasizes precision engineering and reliability for industrial and manufacturing applications.
-
Formerly known as Hitachi Power Tools, HiKoki is a Japanese brand offering pneumatic and electric tools for construction and industrial use. It is known for robust, high-performance tools and innovative technology integration.
Key Pneumatic Tools Companies
The following key companies have been profiled for this study on the pneumatic tools market.
-
Makita
-
Fuji Industrial Technique
-
Nitto Kohki
-
HiKoki Power Tools
-
Ingersoll Rand
-
Chicago Pneumatic
-
Bosch
-
Pneumatic Components Ltd
-
ATS ELGI
-
Atlas Copco
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Ingersoll Rand, Atlas Copco, Makita Corporation, Robert Bosch GmbH, Chicago Pneumatic
- Focus on high-volume manufacturing, continuous product innovation, and expansion of pneumatic tool portfolios across industrial applications.
- Invest in R&D, automation, global distribution networks, and strategic acquisitions to strengthen technological capabilities and market presence.
- Extensive manufacturing capabilities, strong global distribution networks, and established relationships with industrial OEMs and distributors.
- Broad product portfolios, strong brand recognition, proven product reliability, and comprehensive after-sales service capabilities.
- High capital investment requirements for manufacturing, R&D, and global operations.
- Exposure to raw material price fluctuations, supply chain disruptions, and increasing competition from cordless electric power tools.
Emerging & Regional Players (e.g., Fuji Industrial Technique, Nitto Kohki Co., Ltd., HiKOKI Power Tools, Desoutter Industrial Tools, AIMCO)
- Focus on specialized pneumatic tools for automotive, aerospace, assembly, and precision manufacturing applications.
- Leverage product customization, regional partnerships, and innovation in lightweight and ergonomic tool designs to expand market presence.
- Greater flexibility in developing application-specific solutions and responding quickly to customer requirements.
- Strong technical expertise, shorter product development cycles, and competitive pricing in niche industrial segments.
- Limited manufacturing scale and financial resources compared to established competitors.
- Lower global brand recognition and greater dependence on regional markets and distributor networks for growth.
Recent Developments
-
In May 2025, MAKITA released new 18V LXT 21° and 30° framing nailers. These new LXT Framing Nailers deliver the power of pneumatic without the hassles of air hoses.
-
In October 2025, Atlas Copco acquired SUTO iTEC, a specialist in measurement/monitoring for compressed air and gases.
Pneumatic Tools Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.2 billion
Estimated market size in 2026
USD 9.8 billion
Projected market size by 2033
USD 17.3 billion
Growth rate
CAGR of 8.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Japan; China; India
Key companies profiled
Ingersoll Rand; Chicago Pneumatic; Atlas Copco; Fuji Industrial Technique (Fuji Air Tools); Nitto Kohki Co., Ltd.; Makita Corporation; HiKOKI Power Tools; Robert Bosch GmbH; Desoutter Industrial Tools; AIMCO (Assembly Tools Inc.)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pneumatic Tools Market Report Segmentation
This report forecasts revenue growth at regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pneumatic tools market report based on product type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Impact Wrenches
-
Nailers & Staplers
-
Grinders & Sanders
-
Pneumatic Drills
-
Ratchet Wrenches
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Construction
-
Manufacturing & Industrial
-
Aerospace
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central & South America
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
Egypt
-
Qatar
-
Kuwait
-
-
Research Methodology
The pneumatic tools market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pneumatic tools segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue Capture Definition
Impact Wrenches
The segment refers to air-powered impact wrenches used for high-torque fastening and loosening of bolts and nuts across industrial applications. The segment captures revenue generated from the sale of pneumatic impact wrenches across all end-use industries.
Nailers & Staplers
The segment refers to pneumatic nailers and staplers designed for fastening applications in construction, woodworking, furniture manufacturing, and packaging. The segment captures revenue generated from the sale of pneumatic nailers and staplers across all end-use industries.
Grinders & Sanders
The segment refers to air-powered grinders and sanders used for grinding, polishing, deburring, finishing, and surface preparation applications. The segment captures revenue generated from the sale of pneumatic grinders and sanders across all end-use industries.
Pneumatic Drills
The segment refers to air-powered drills used for drilling, reaming, and hole-making applications in industrial and commercial operations. The segment captures revenue generated from the sale of pneumatic drills across all end-use industries.
Ratchet Wrenches
The segment refers to pneumatic ratchet wrenches used for rapid fastening and loosening of fasteners in confined spaces. The segment captures revenue generated from the sale of pneumatic ratchet wrenches across all end-use industries.
Others
The segment refers to other pneumatic tools including air hammers, chisels, screwdrivers, riveters, polishers, shears, cut-off tools, scalers, and similar air-powered hand tools. The segment captures revenue generated from the sale of all other pneumatic tools not classified under the above product segments.
Segment - End Use
Revenue Capture Definition
Automotive
The segment captures revenue generated from pneumatic tools supplied for automotive manufacturing, assembly, maintenance, repair, body shops, and aftermarket service applications.
Construction
The segment captures revenue generated from pneumatic tools supplied for residential, commercial, and infrastructure construction applications including fastening, drilling, grinding, demolition, and finishing activities.
Manufacturing & Industrial
The segment captures revenue generated from pneumatic tools supplied for manufacturing, metal fabrication, machinery production, industrial assembly, maintenance, and general factory operations.
Aerospace
The segment captures revenue generated from pneumatic tools supplied for aircraft manufacturing, component assembly, maintenance, repair, overhaul (MRO), drilling, fastening, and finishing applications.
Others
The segment captures revenue generated from pneumatic tools supplied for shipbuilding, mining, railways, agriculture, energy, utilities, woodworking, and all other end-use industries not covered under the above segments.
Estimation Model
Layer Name
Key Question
Description
Industrial Tool Demand Layer
Where are pneumatic tools required?
Analyze demand across automotive, aerospace, construction, manufacturing, metal fabrication, shipbuilding, oil & gas, mining, and maintenance, repair, and operations (MRO).
Industrial Production & Infrastructure Investment Layer
Where is new equipment demand being created?
Evaluate investments in manufacturing facilities, automotive production plants, construction projects, aerospace manufacturing, mining operations, and industrial infrastructure.
Product Adoption Layer
Which pneumatic tool technologies are being deployed?
Segment demand by product type, tool function, mobility, end-use industry, and distribution channel. Apply adoption rates based on operating efficiency, torque requirements, durability, compressed air availability, safety standards, and application-specific performance.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of pneumatic tools by product type, application, end-use industry, and region. Quantify revenues generated exclusively from the sale of new pneumatic tools supplied to industrial manufacturers, construction contractors, automotive OEMs, distributors, and MRO service providers.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
A competitive benchmarking analysis was conducted by evaluating leading pneumatic tool manufacturers based on product portfolio, technological capabilities, manufacturing footprint, strategic initiatives, financial strength, innovation focus, and competitive positioning within the pneumatic tools market.
This benchmarking enabled stakeholders to assess competitive strengths, identify product and technology differentiation opportunities, understand evolving competitive strategies, and develop informed market positioning and growth plans.
Regional Segmentation
A comprehensive regional analysis was conducted across key markets, highlighting industrial manufacturing activity, construction and infrastructure investments, end-use demand, distribution networks, regulatory standards, and the contribution of major countries to the pneumatic tools market.
The regional assessment helped stakeholders identify high-growth markets, optimize expansion strategies, allocate investments effectively, and align product offerings with regional industrial requirements and market demand.
Opportunity Assessment
A detailed opportunity assessment was conducted by evaluating industrial automation trends, manufacturing expansion, infrastructure development, technological advancements, and evolving demand across automotive, aerospace, construction, and MRO applications. The analysis identified high-growth opportunities across pneumatic tool categories and industrial end-use sectors to support strategic decision-making.
This assessment enabled stakeholders to prioritize high-potential investment areas, align product development with evolving industrial requirements, and capitalize on opportunities driven by factory automation, infrastructure development, and increasing demand for efficient and durable pneumatic tools across industrial applications.
Frequently Asked Questions About This Report
Asia Pacific dominated the pneumatic tools market with the largest revenue share of 39.7% in 2025.
The key factor driving the pneumatic tools market is the increasing demand for high-efficiency, durable, and productivity-enhancing tools across industrial, automotive, and construction sectors.
Asia Pacific is anticipated to be one of the fastest-growing regional markets over the forecast period, driven by rapid industrialization, expanding manufacturing capacity, increasing automotive production, and growing infrastructure development.
The impact wrenches segment led the market with the largest revenue share of 28.8% in 2025.
The automotive segment accounted for the largest revenue share of 34.5% in 2025.
Key trends include increasing adoption of ergonomic and lightweight pneumatic tools, integration of Industry 4.0-enabled manufacturing, growing demand for energy-efficient compressed air systems, and rising use of high-performance tools for automated assembly and maintenance applications.
The global pneumatic tools market size was valued at USD 9.2 billion in 2025 and is estimated at USD 9.8 billion for 2026.
The global pneumatic tools market is expected to grow at a CAGR of 8.5% from 2026 to 2033, reaching USD 17.3 billion by 2033.
Some of the key players operating in the pneumatic tools market include Ingersoll Rand; Chicago Pneumatic; Atlas Copco; Fuji Industrial Technique (Fuji Air Tools); Nitto Kohki Co., Ltd.; Makita Corporation; HiKOKI Power Tools; Robert Bosch GmbH; Desoutter Industrial Tools; AIMCO (Assembly Tools Inc.)
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


