
- Home
- »
- Plastics, Polymers & Resins
- »
-
Polyethylene Thermoform Packaging Market Report, 2033GVR Report cover

Polyethylene (PE) Thermoform Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Polyethylene Type (Low-Density Polyethylene (LDPE), High-Density Polyethylene (HDPE)), By Packaging Format, By Rigidity, By End Use Industry, By Region, And Segment Forecasts
Market Size, 2025
$11.0BMarket Estimate, 2026
$11.4BMarket Forecast, 2033
$16.0BCAGR, 2026–2033
4.9%Polyethylene (PE) Thermoform Packaging Market Summary
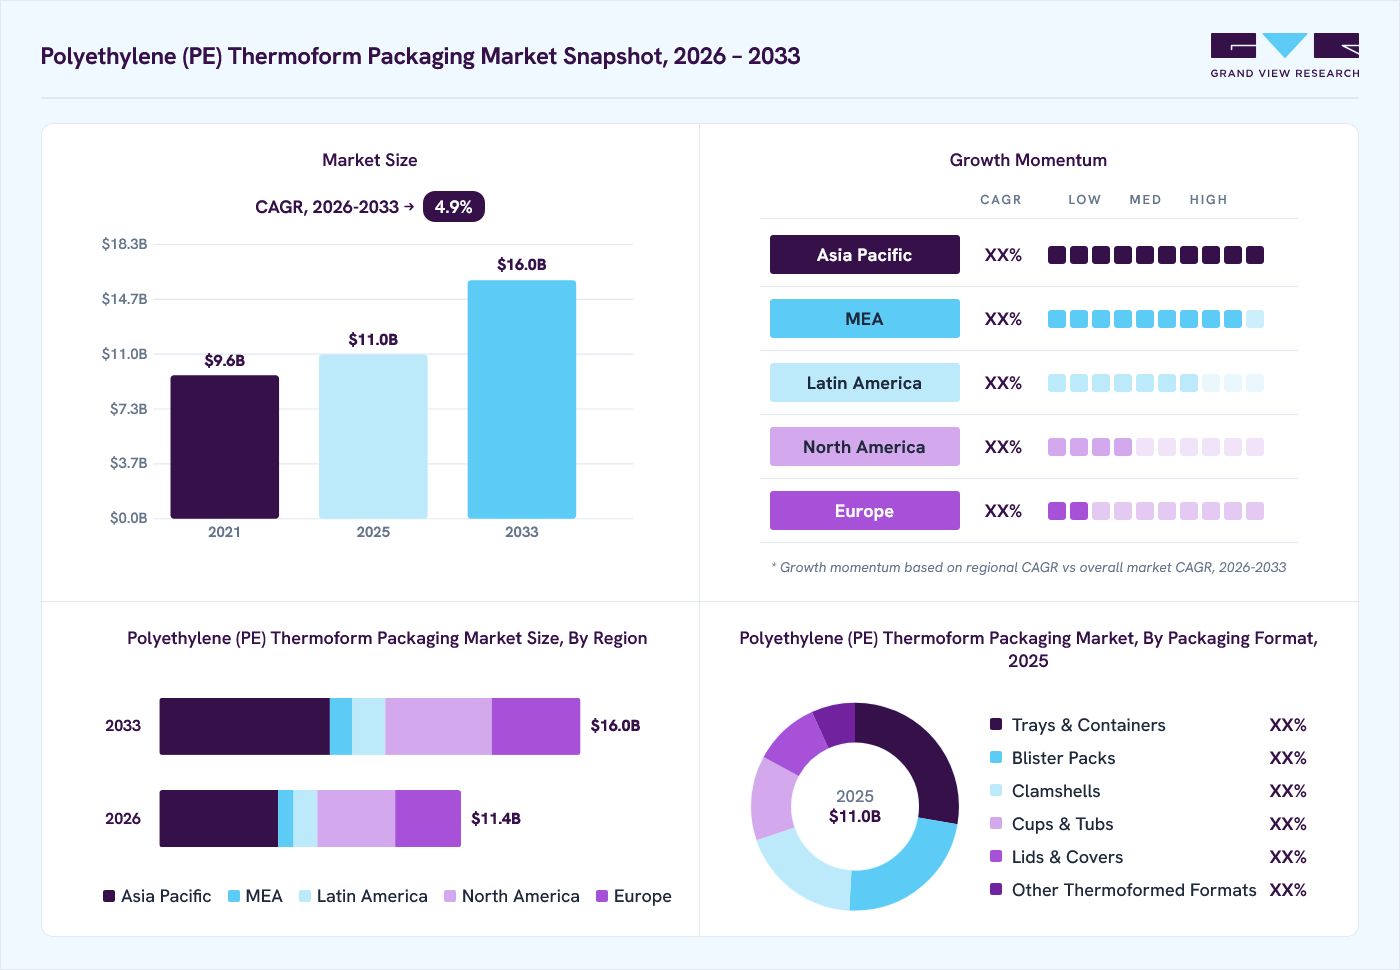
The global polyethylene (PE) thermoform packaging market size was valued at USD 11.0 billion in 2025 and is projected to grow from USD 11.4 billion in 2026 to USD 16.0 billion by 2033, at a CAGR of 4.9% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 39.2% in 2025. The market is primarily driven by the growing demand for durable, lightweight, and cost-effective packaging solutions across food & beverage, healthcare, pharmaceuticals, and consumer goods industries, supported by the increasing adoption of thermoformed polyethylene packaging for product protection, hygiene, and efficient material handling.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By polyethylene type: Low-density polyethylene (LDPE) segment held the largest market share of 60.8% in 2025.
- By packaging format: Trays and containers segment held the largest market share of 27.7% in 2025.
- By rigidity: Rigid thermoformed packaging segment held the largest market share of 47.0% in 2025.
- By end use industry: Food and beverage segment held the largest market share of 47.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (39.2% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 11.0 Billion
- Estimated market size in 2026: USD 11.4 Billion
- Projected market size by 2033: USD 16.0 Billion
- CAGR (2026-2033): 4.9%
GVR research-powered AIAsk Prism AI about the polyethylene (PE) thermoform packaging marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
Asia Pacific dominated the market in 2025 and is expected to maintain its leading position, driven by expanding manufacturing activities, rising packaged food consumption, and growing demand for flexible and customized packaging solutions. The polyethylene (PE) thermoform packaging market is driven by growing demand for lightweight, durable, and cost-effective packaging across food and beverage, healthcare, and consumer goods industries. Polyethylene’s moisture resistance, flexibility, and protective properties make it suitable for thermoformed trays, containers, lids, and other packaging formats. The expansion of packaged food consumption and the need for efficient product protection are further supporting market demand.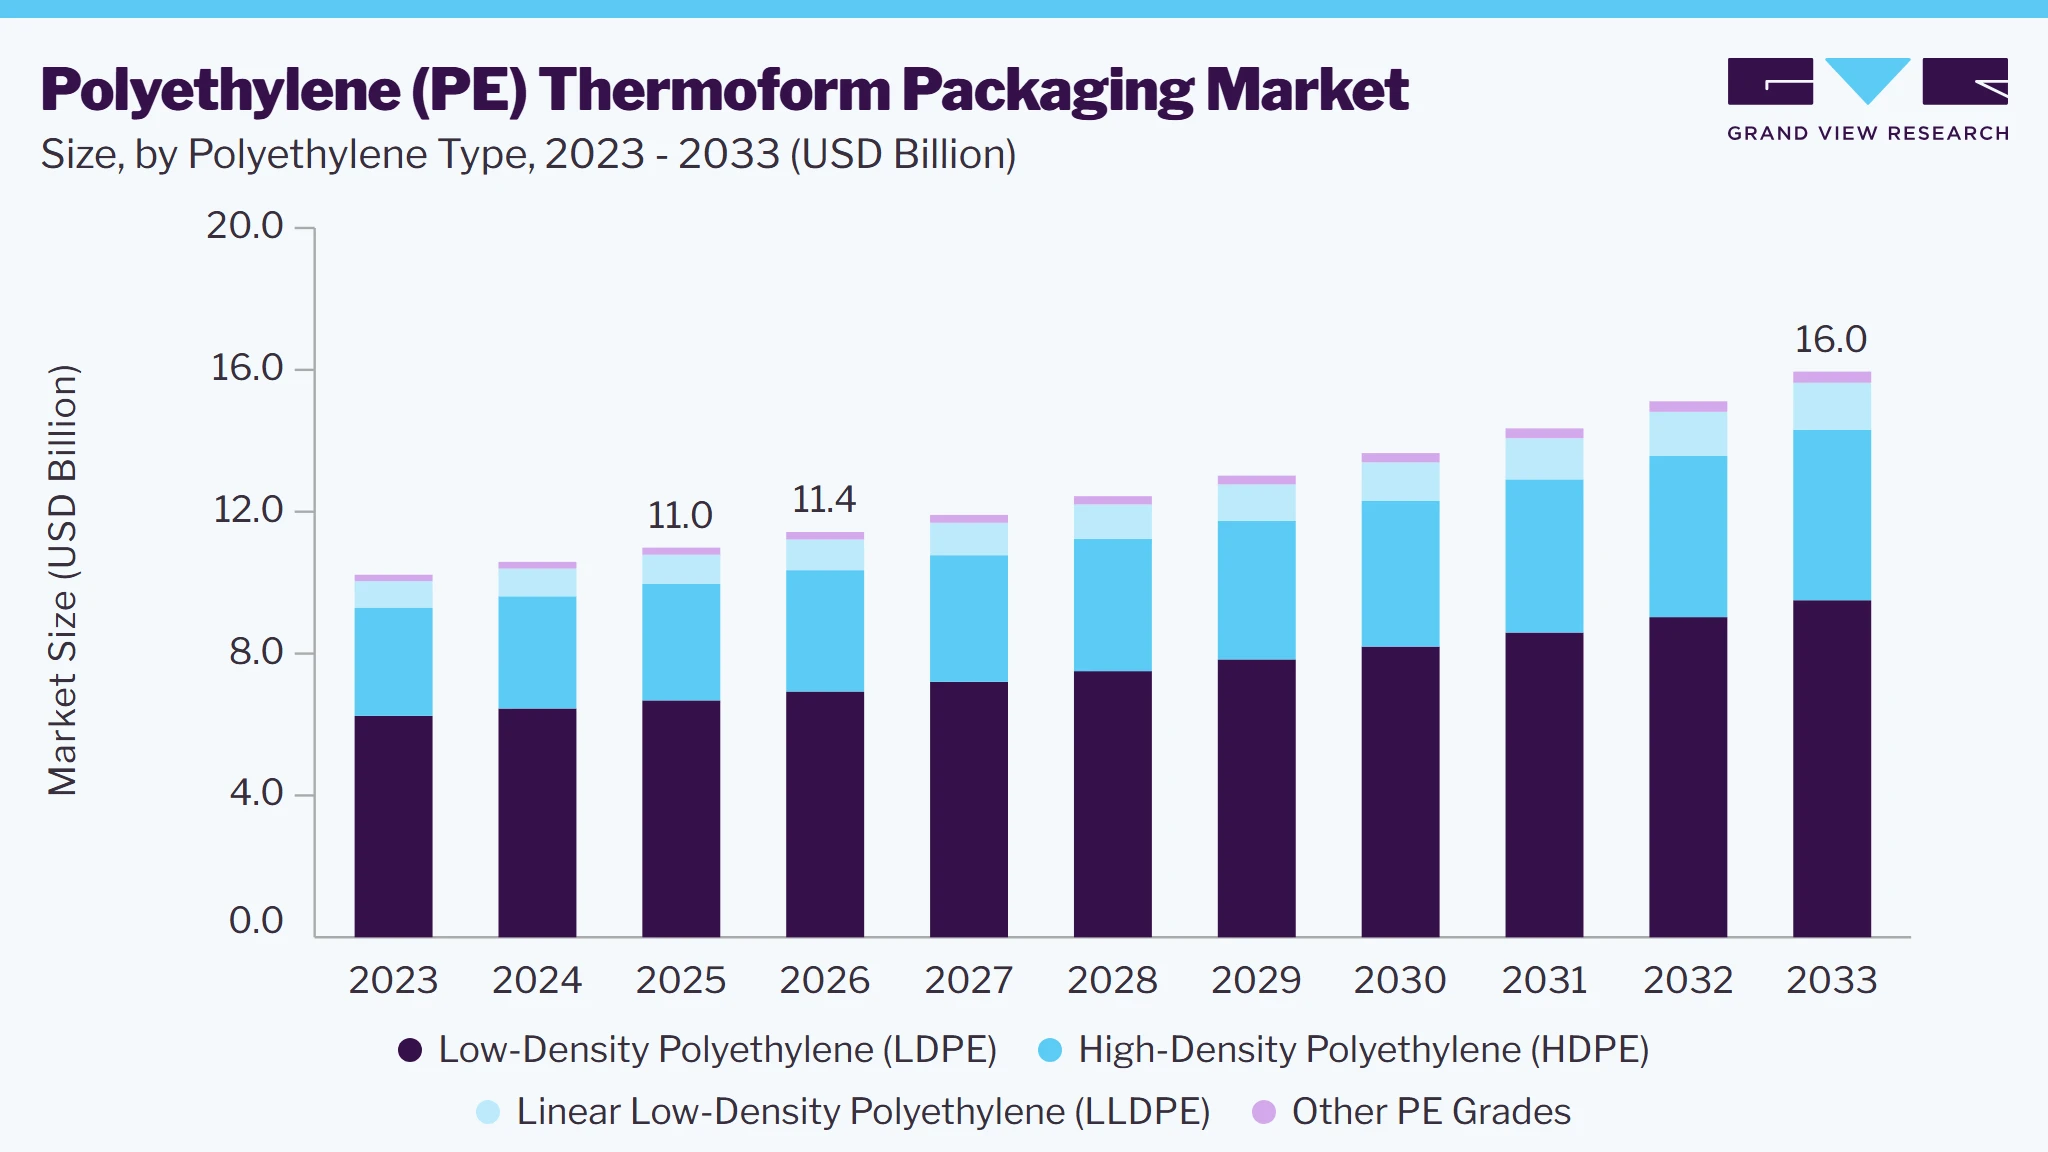 To learn more about this report, Download Free Sample Report
Increasing emphasis on hygiene, product safety, and reliable packaging is also creating opportunities for PE thermoformed solutions, particularly in food and pharmaceutical applications. Manufacturers are focusing on packaging designs that meet specific protection requirements while improving material efficiency and handling performance. The growing need for specialized healthcare packaging is expected to further support market development.
Sustainability and material innovation are shaping the market as manufacturers explore lightweight designs, reduced material consumption, and recyclable packaging solutions. Different polyethylene grades enable producers to balance flexibility, strength, and cost according to application needs. While LDPE remains the dominant material, LLDPE is expected to gain traction due to its favorable growth outlook, reflecting continued demand for versatile and performance-oriented thermoform packaging.
Market Dynamics
The polyethylene (PE) thermoform packaging market is driven by increasing demand for lightweight, adaptable, and cost-efficient packaging across food and beverage, healthcare, pharmaceutical, and consumer goods applications. The material’s moisture resistance, formability, and ability to provide protective packaging in different shapes and thicknesses make it suitable for a wide range of thermoformed products. Growing requirements for product protection, efficient transportation, and packaging designs tailored to specific applications are further supporting market development. At the same time, sustainability expectations and evolving material requirements are encouraging manufacturers to improve packaging efficiency and recyclability.
The expanding use of packaged food and consumer products is a key driver of the PE thermoform packaging market. Food manufacturers and retailers require packaging that helps preserve product quality, supports hygienic handling, and withstands storage and distribution conditions. Polyethylene’s flexibility and moisture-barrier properties make it suitable for trays, containers, lids, and other thermoformed formats designed for varied product requirements.
Demand from healthcare and pharmaceutical applications is also contributing to market growth, as packaging manufacturers seek materials that can be adapted to different protective and handling needs. Improvements in thermoforming processes enable manufacturers to produce customized packaging designs with consistent dimensions and efficient material use. These advantages support the adoption of PE thermoformed packaging across both high-volume consumer applications and specialized end uses.
Environmental concerns surrounding plastic waste present a key restraint for the PE thermoform packaging market. Although polyethylene is recyclable, the recovery of thermoformed packaging can be limited by contamination, mixed-material structures, and inadequate collection and sorting infrastructure. Manufacturers also face pressure to comply with evolving environmental regulations and customer expectations for recyclable designs and recycled content. Adapting packaging structures and production processes to meet these requirements may increase development costs and operational complexity.
The growing emphasis on circular packaging creates opportunities for PE thermoform packaging manufacturers to develop lightweight designs, reduce material consumption, and improve recyclability. Simplified packaging structures and the use of recycled polyethylene, where suitable for the intended application, can help support resource efficiency. Advances in thermoforming technology also enable manufacturers to optimize material use and create application-specific packaging with reliable protective performance, strengthening opportunities across food, healthcare, and consumer goods markets.
Market Concentration & Characteristics
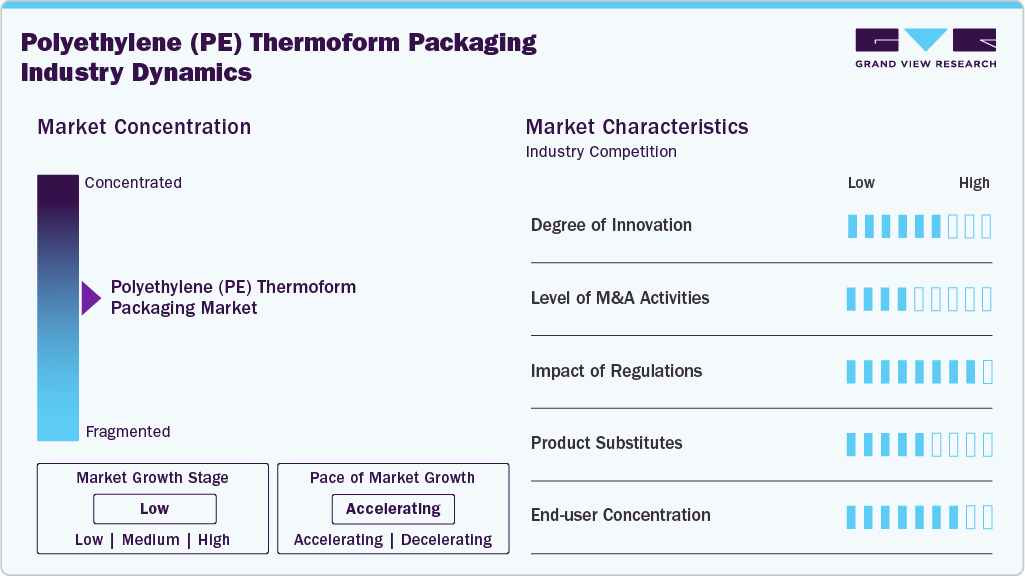
The polyethylene (PE) Thermoform Packaging market is characterized by demand for cost-efficient, lightweight, and application-specific packaging solutions across food and beverage, healthcare, pharmaceuticals, and consumer goods industries. The market relies on thermoforming processes that shape polyethylene sheets into trays, containers, lids, and other packaging formats. Manufacturers prioritize material utilization, production consistency, forming efficiency, and product protection to meet varied packaging requirements. Low-density polyethylene (LDPE) accounts for the largest share of the market, supported by its flexibility and moisture-resistant properties, while demand for other PE grades reflects the need for different levels of strength, rigidity, and toughness.
 To learn more about this report, Download Free Sample Report
A defining characteristic of the industry is its reliance on polyethylene’s versatility and adaptability to different thermoformed packaging designs. LDPE remains the dominant material, while linear low-density polyethylene (LLDPE) is expected to record faster growth as manufacturers seek materials suited to flexible and durable packaging applications. At the same time, sustainability requirements are influencing product development, with greater attention to lightweight designs, material reduction, recyclable packaging structures, and the potential use of recycled polyethylene where application requirements permit. However, the practical adoption of these solutions depends on packaging performance, material quality, recycling infrastructure, and compliance with end-use requirements
Analyst Perspective
The global polyethylene (PE) thermoform packaging market has evolved from conventional plastic packaging toward lightweight, durable, and application-specific solutions. Demand is primarily driven by the food and beverage industry, where thermoformed trays, containers, clamshells, and lids provide moisture resistance, product protection, and convenient handling. Healthcare, pharmaceuticals, and industrial applications are further broadening market opportunities. Looking ahead, the market is expected to grow steadily, supported by rising demand for packaged products, manufacturing efficiency, and expanding consumption across Asia Pacific. However, recyclability, plastic waste management, and material efficiency will remain key industry priorities, encouraging manufacturers to develop more resource-efficient designs and recyclable PE packaging structures
Polyethylene Type Insights
Based on polyethylene type, the low-density polyethylene (LDPE) segment dominated the polyethylene (PE) thermoform packaging market, accounting for the largest revenue share of 60.8% in 2025. LDPE is widely used in thermoformed packaging because of its flexibility, moisture resistance, and ease of processing. These properties make it suitable for packaging formats requiring adaptable shapes and reliable product protection. Its established use across food packaging and consumer applications, combined with its suitability for high-volume manufacturing, supports its leading market position.
The linear low-density polyethylene (LLDPE) segment is expected to grow at the fastest CAGR of 6.2% during the forecast period. LLDPE offers a combination of flexibility, toughness, and resistance to punctures, making it suitable for packaging applications that require durability and material performance. Its growing use in flexible packaging structures and applications requiring improved mechanical properties is expected to support segment growth. Increasing demand for adaptable packaging designs and efficient material utilization may further strengthen LLDPE adoption in the PE thermoform packaging market.
Packaging Format Insights
Based on packaging format, the trays and containers segment dominated the polyethylene (PE) thermoform packaging market, accounting for the largest revenue share of 27.7% in 2025. These formats are widely used across food, healthcare, and consumer goods applications because they provide structured product protection, convenient handling, and adaptable designs. Their suitability for high-volume packaging operations and ability to accommodate different product sizes and shapes support their widespread adoption across industries.
The lids and covers segment is expected to grow at the fastest CAGR of 5.4% during the forecast period. Demand is supported by the need for secure closures that help protect packaged products from contamination, moisture exposure, and handling-related damage. PE thermoformed lids and covers can be designed for different container shapes and application requirements, making them suitable for food packaging and other uses requiring reliable coverage. Increasing emphasis on packaging functionality, product protection, and compatibility with existing containers is expected to support segment growth.
Rigidity Insights
Based on rigidity, the rigid thermoformed packaging segment dominated the polyethylene (PE) thermoform packaging market, accounting for the largest revenue share of 47.0% in 2025. Rigid thermoformed packaging is widely used because of its structural strength, shape retention, and ability to protect products during storage, handling, and transportation. It is suitable for food trays, containers, and other packaging formats that require stability and reliable product containment. Its established use across food and consumer goods applications, along with its compatibility with high-volume manufacturing processes, supports its leading market position.
The flexible thermoformed packaging segment is expected to grow at the fastest CAGR of 5.3% during the forecast period. Growth is supported by increasing demand for lightweight, adaptable packaging that can accommodate different product shapes while optimizing material usage. Polyethylene's flexibility and moisture resistance make it suitable for packaging applications requiring convenient handling and effective product protection. As manufacturers focus on material efficiency and packaging designs tailored to specific end uses, flexible thermoformed solutions are expected to gain further traction.
End Use Industry Insights
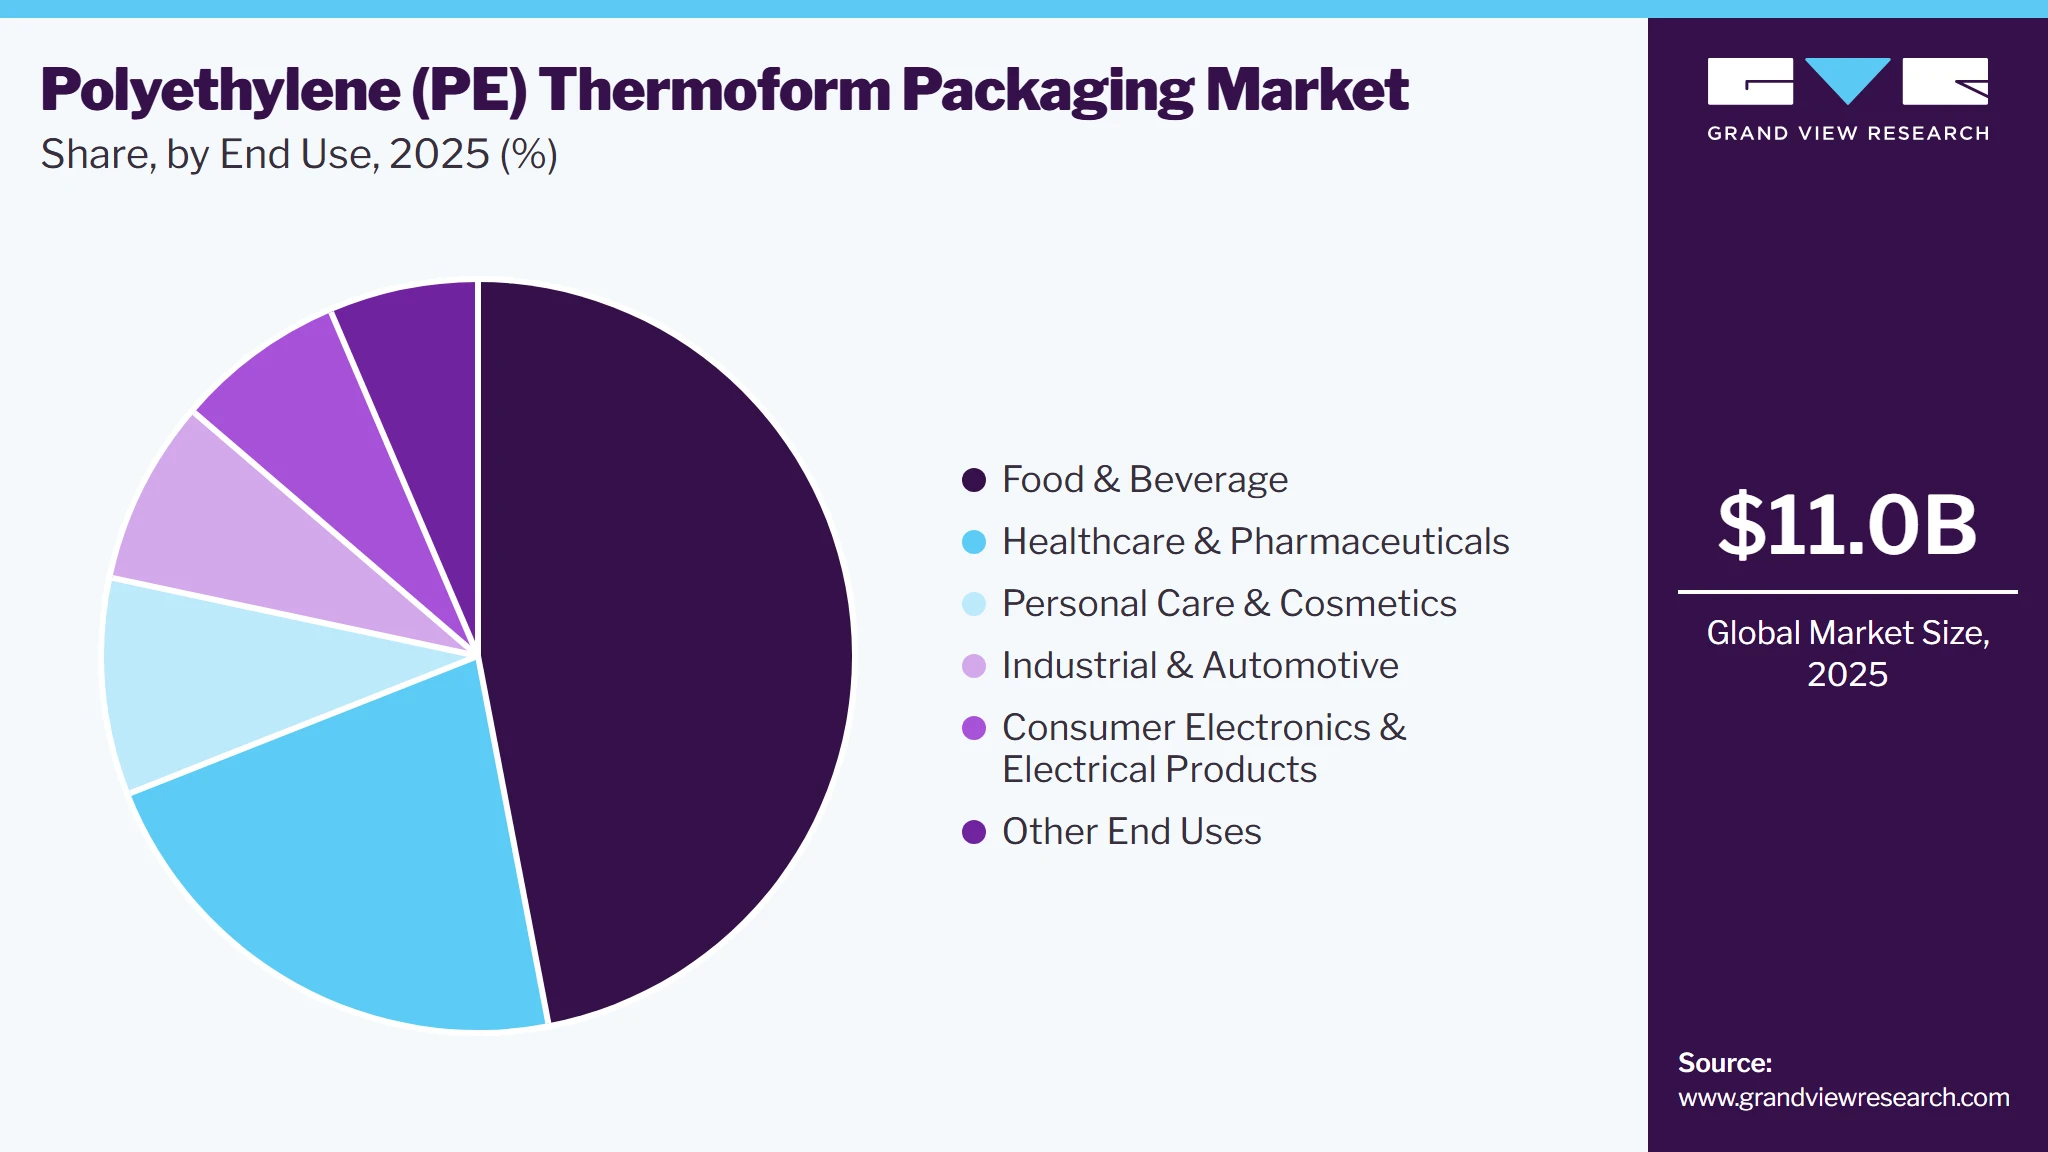
Based on end use industry, the food and beverage segment dominated the PE thermoform packaging market, accounting for the largest revenue share of 47.0% in 2025. Its leading position is supported by the extensive use of thermoformed polyethylene packaging for food trays, containers, lids, and other formats that help protect products from moisture and contamination while supporting convenient storage, handling, and distribution. The material’s flexibility, formability, and suitability for high-volume packaging applications support its widespread adoption across packaged food and beverage products. The segment is expected to maintain its leading position, with its market share projected to reach 47.4% by 2033.
 To learn more about this report, Download Free Sample Report
The healthcare and pharmaceuticals segment is expected to register the fastest growth, at a CAGR of 5.4% during the forecast period. Growth is supported by demand for packaging that provides reliable product protection, hygienic handling, and compatibility with varied medical and pharmaceutical applications. Polyethylene’s moisture resistance and adaptable processing characteristics make it suitable for selected thermoformed packaging formats used for medical supplies, pharmaceutical products, and healthcare components. Increasing requirements for protective packaging and application-specific designs are expected to support segment expansion, with its market share projected to increase from 22.0% in 2025 to 22.9% by 2033.
Regional Insights
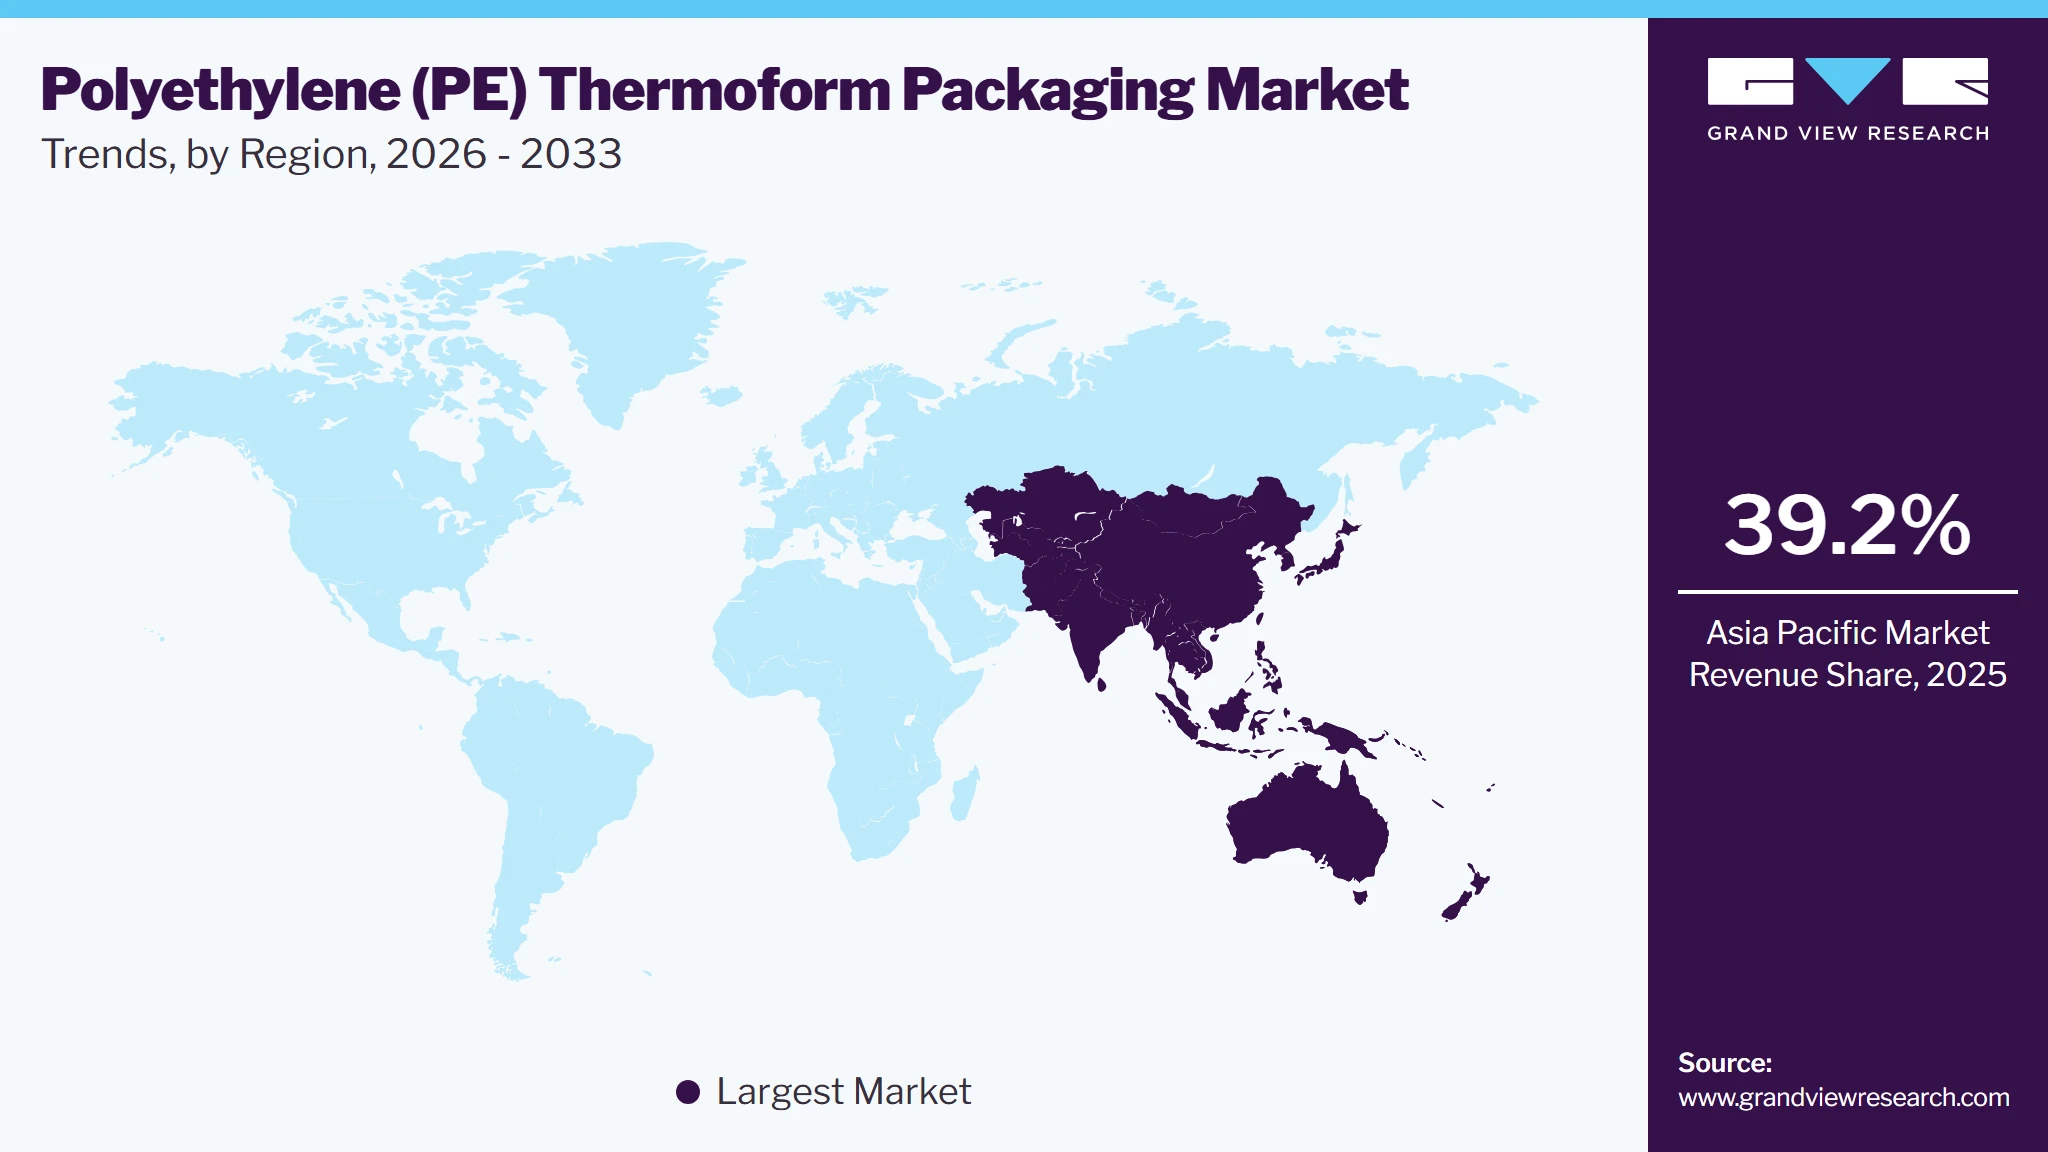
The Asia Pacific PE thermoform packaging market dominated the global market, accounting for a revenue share of 39.2% in 2025, and is also expected to register the fastest CAGR of 5.3% from 2026 to 2033. Regional leadership is supported by expanding packaged food consumption, a large manufacturing base, and rising demand for healthcare and consumer product packaging. Growth across major manufacturing economies is creating demand for cost-efficient thermoformed trays, containers, lids, and other packaging formats. The region's market share is projected to reach 40.5% by 2033, reinforcing its position as the leading regional market.
 To learn more about this report, Download Free Sample Report
China is a key contributor to the Asia Pacific PE thermoform packaging market, supported by its extensive manufacturing activity and large consumer market. Demand from packaged foods, household products, electronics, and healthcare applications supports the use of thermoformed packaging for product containment and protection. The scale of manufacturing and distribution activity is expected to sustain demand for versatile and cost-effective PE packaging formats.
The India PE thermoform packaging market is positioned for continued expansion, supported by growth in packaged food consumption, organized retail, healthcare services, and domestic manufacturing. Increasing demand for convenient packaging formats and protective containers is creating opportunities for thermoformed PE products. The expansion of food processing and pharmaceutical-related activities is also expected to support market development as packaging requirements become more diverse.
North America Polyethylene (PE) Thermoform Packaging Market Trends
The North America PE thermoform packaging market is expected to experience steady growth during the forecast period, supported by sustained demand for protective and convenient packaging across food and beverage, healthcare, and consumer goods applications. The region's established packaging industry and use of thermoformed trays, containers, and lids in commercial packaging operations are expected to support market development. Increasing emphasis on material efficiency, packaging performance, and recyclable designs is also influencing product development across the region.
The U.S. PE thermoform packaging market is expected to grow steadily throughout the forecast period. Demand is supported by the extensive use of packaged food products and the need for protective packaging in healthcare and pharmaceutical applications. Manufacturers are focusing on packaging formats that combine product protection, efficient material use, and suitability for high-volume production. Continued interest in lightweight packaging and designs that support improved recyclability is expected to shape market development.
Europe Polyethylene (PE) Thermoform Packaging Market Trends
The Europe PE thermoform packaging market is projected to register moderate growth over the forecast period. Demand is supported by applications across food packaging, healthcare, personal care, and industrial products, where thermoformed polyethylene offers moisture resistance, flexibility, and adaptable product containment. The region's focus on packaging sustainability and resource efficiency is encouraging manufacturers to explore material reduction, recyclable packaging structures, and production processes that minimize waste.
Germany represents an important market within Europe, supported by its established manufacturing base and demand for protective packaging across food processing, healthcare, automotive, and industrial applications. The need for packaging formats that provide dimensional stability and reliable handling is expected to sustain demand for thermoformed PE solutions.
TheUK PE thermoform packaging market is expected to grow steadily, driven by demand for convenient food packaging and protective formats for healthcare and consumer products. Greater attention to packaging waste, material efficiency, and recyclability is encouraging suppliers to develop designs that balance product protection with evolving sustainability requirements.
Latin America Polyethylene (PE) Thermoform Packaging Market Trends
The Latin America PE thermoform packaging market is projected to grow steadily during the forecast period, with a CAGR of 5.0% from 2026 to 2033. Demand is supported by food processing, consumer product packaging, and the gradual expansion of modern retail and distribution channels. Thermoformed PE formats offer manufacturers adaptable packaging options for products requiring moisture resistance and convenient handling. Greater adoption of packaged goods is expected to contribute to regional market expansion.
Brazil represents a significant market in Latin America, supported by its sizeable food and beverage sector and broad consumer goods market. Demand for trays, containers, and lids is linked to packaged food distribution and the need for practical packaging formats across retail and food-service applications. Continued activity in food processing and consumer product manufacturing is expected to support the use of PE thermoform packaging.
The Argentina PE thermoform packaging market is expected to record gradual growth during the forecast period. Demand from food and beverage producers, along with applications in personal care and household products, supports the use of thermoformed packaging. Manufacturers' need for adaptable formats and efficient material utilization is expected to influence product demand across the market.
Middle East & Africa Polyethylene (PE) Thermoform Packaging Market Trends
The Middle East & Africa PE thermoform packaging market is expected to expand at a CAGR of 5.2% from 2026 to 2033, making it the second-fastest-growing regional market. Growth is supported by rising demand for packaged foods, development of retail and distribution networks, and increasing requirements for protective packaging across healthcare and consumer goods. Investments in food processing and broader manufacturing activities are expected to create additional opportunities for thermoformed PE trays, containers, and lids. Although the region accounts for a comparatively smaller share of global revenue, these demand drivers are expected to support continued market expansion.
Key Companies & Market Share Insights
Some key companies in the polyethylene (PE) thermoform packaging market include Indepak, Amcor plc, Nefab Group, TOPPAN Packaging Americas Holdings, Inc., Indu Thermoformers Pvt. Ltd., ITC Packaging, Global Thermoforming, Universal Plastics Group, Inc., Prent Corporation, VisiPak, Universal Protective Packaging, Inc. , Janco, Inc. The Polyethylene (PE) Thermoform Packaging market is characterized by demand for lightweight, durable, and application-specific packaging across food and beverage, healthcare, consumer goods, and industrial applications. Key participants include thermoforming specialists, packaging manufacturers, and diversified packaging companies that provide trays, containers, clamshells, blisters, and protective packaging solutions. Companies compete through forming capabilities, product customization, material efficiency, protective performance, and the development of packaging designs that support recyclability and evolving customer requirements.
-
Indepak specializes in custom thermoformed packaging, including trays, clamshells, blister packs, tubs, and lidded containers for food, medical, pharmaceutical, electronics, and industrial applications. Its capabilities in material selection, precision tooling, and recycled-content packaging support the development of application-specific packaging solutions.
-
Amcor plc is a global packaging company offering thermoformed trays, cups, blisters, and lids for food and other consumer applications. Its thermoforming capabilities include materials such as HDPE alongside PET, PP, and other plastics, allowing packaging designs to be tailored to product protection, forming requirements, and production efficiency.
Key Polyethylene (PE) Thermoform Packaging Companies:
The following key companies have been profiled for this study on the polyethylene (PE) thermoform packaging market
-
Indepak
-
Amcor plc
-
Nefab Group
-
TOPPAN Packaging Americas Holdings, Inc.
-
Indu Thermoformers Pvt. Ltd.
-
ITC Packaging
-
Global Thermoforming
-
Universal Plastics Group, Inc.
-
Prent Corporation
-
VisiPak
-
Universal Protective Packaging, Inc.
-
Janco, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Amcor plc; TOPPAN Packaging Americas Holdings, Inc.; Prent Corporation; Nefab Group; ITC Packaging)
- Focus on expanding thermoformed packaging portfolios, improving production efficiency, offering customized trays, containers, clamshells, and protective packaging, and developing material-efficient solutions for food, healthcare, electronics, and industrial applications.
- Established customer relationships, broad packaging capabilities, technical expertise, custom tooling, and scalable manufacturing support competitiveness across multiple end-use industries.
- High tooling and equipment investments, exposure to plastic resin price fluctuations, and growing pressure to improve recyclability and reduce material consumption may affect operating costs and margins.
Specialized and Emerging Players (Indepak; Indu Thermoformers Pvt. Ltd.; Global Thermoforming; Universal Plastics Group, Inc.; VisiPak; Universal Protective Packaging, Inc.; Janco, Inc.)
- Emphasize custom thermoforming, application-specific packaging designs, rapid prototyping, specialized trays and clamshells, and tailored solutions for medical, food, retail, and industrial customers.
- Flexibility in custom designs, responsiveness to customer requirements, specialized thermoforming capabilities, and the ability to serve niche packaging applications.
- Comparatively narrower product portfolios or geographic reach may limit market access. Dependence on specific customer industries, tooling costs, and competition from large packaging suppliers can constrain expansion.
Recent Development
-
In June 2026, Prent Corporation began construction of a new medical packaging facility in Heredia, Costa Rica. The facility is expected to double Prent’s production capacity in the country and include six thermoforming machines, an expanded production line for large trays, and a Class 7 cleanroom. The expansion is intended to strengthen manufacturing capacity for specialized medical thermoformed packaging.
-
In February 2026, TOPPAN and PureCycle Technologies announced a partnership to advance the use of recycled-content materials in flexible films and thermoformed packaging applications. The collaboration reflects growing efforts to incorporate recycled polypropylene into packaging while maintaining the performance requirements of food and consumer product applications. Although the initial demonstrated product was a snack-bar wrapper, the partnership also targets broader thermoformed packaging applications relevant to sustainable packaging development.
Polyethylene (PE) Thermoform Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.0 billion
Estimated market size in 2026
USD 11.4 billion
Projected market size by 2033
USD 16.0 billion
Growth Rate
CAGR of 4.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million/Billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Polyethylene type, packaging format, rigidity, end use industry, region
Regional Scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Indepak, Amcor plc, Nefab Group, TOPPAN Packaging Americas Holdings, Inc., Indu Thermoformers Pvt. Ltd. , ITC Packaging, Global Thermoforming, Universal Plastics Group, Inc., Prent Corporation, VisiPak, Universal Protective Packaging, Inc. , Janco, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Polyethylene (PE) Thermoform Packaging Market Report Segmentation
This report forecasts revenue growth at the regional, and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the Polyethylene (PE) Thermoform Packaging market report on the basis of polyethylene type, packaging format, rigidity, end use, and region:
-
Polyethylene Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Low-Density Polyethylene (LDPE)
-
High-Density Polyethylene (HDPE)
-
Linear Low-Density Polyethylene (LLDPE)
-
Other PE grades
-
-
Packaging Format Outlook (Revenue, USD Million, 2021 - 2033)
-
Trays and Containers
-
Blister Packs
-
Clamshells
-
Cups and Tubs
-
Lids and Covers
-
Other Thermoformed Formats
-
-
Rigidity Outlook (Revenue, USD Million, 2021 - 2033)
-
Rigid Thermoformed Packaging
-
Flexible Thermoformed Packaging
-
Semi-Rigid Thermoformed Packaging
-
-
End Use Industry Outlook (Revenue, USD Million, 2021 - 2033)
-
Food & Beverages
-
Healthcare and Pharmaceuticals
-
Personal Care & Cosmetics
-
Consumer Electronics and Electrical Products
-
Industrial and Automotive
-
Other End Uses
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The polyethylene (PE) thermoform packaging market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each polyethylene (PE) thermoform packaging segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Polyethylene Type
Revenue capture definition
Low-Density Polyethylene (LDPE)
Revenue generated from the sale of LDPE-based thermoformed packaging products, including trays, containers, lids, covers, and other formed packaging formats. Includes packaging manufactured using LDPE for applications requiring flexibility, moisture resistance, lightweight construction, and adaptable product containment across food and beverage, healthcare, personal care, and consumer goods industries.
High-Density Polyethylene (HDPE)
Revenue generated from the sale of HDPE-based thermoformed packaging products, including rigid trays, containers, protective packaging components, and other formed formats. Includes products manufactured using HDPE for applications requiring stiffness, strength, impact resistance, and moisture protection across food, healthcare, industrial, and consumer product markets.
Linear Low-Density Polyethylene (LLDPE)
Revenue generated from the sale of LLDPE-based thermoformed packaging products used in applications requiring flexibility, toughness, puncture resistance, and reliable product protection. Includes trays, containers, covers, and other specialized packaging formats supplied to food and beverage, healthcare, consumer goods, and industrial end users.
Other PE Grades
Revenue generated from the sale of thermoformed packaging products manufactured using other polyethylene grades, including specialty or modified PE materials not classified as LDPE, HDPE, or LLDPE. Includes customized trays, containers, protective components, and other formed packaging solutions designed to meet specific requirements for flexibility, strength, moisture resistance, and processing performance across various end-use industries.
Packaging Format
Revenue capture definition
Trays and Containers
Revenue generated from the sale of PE thermoformed trays and containers designed to hold, protect, store, and transport products across food and beverage, healthcare, personal care, and industrial applications. Includes packaging formats manufactured from polyethylene to provide moisture resistance, product containment, and convenient handling.
Blister Packs
Revenue generated from the sale of PE-based thermoformed blister packaging used to secure and protect individual products or components within formed cavities. Includes packaging supplied for healthcare products, consumer goods, electronics, and industrial components where product visibility, separation, and protection are required.
Clamshells
Revenue generated from the sale of PE thermoformed clamshell packaging featuring hinged or two-piece designs that enclose products for storage, display, and transportation. Includes packaging used for food, retail goods, electronics, and other consumer products requiring secure closure, visibility, and protection during handling.
Cups and Tubs
Revenue generated from the sale of PE thermoformed cups and tubs used for containing, storing, and distributing food products, personal care items, and other consumer goods. Includes packaging designed to provide lightweight construction, moisture resistance, convenient filling, and compatibility with suitable lids or closure systems.
Lids and Covers
Revenue generated from the sale of PE-based thermoformed lids and covers designed to seal or protect trays, cups, tubs, and containers. Includes packaging components intended to reduce contamination, limit exposure to external conditions, and support product handling and storage across food, healthcare, and consumer applications.
Other Thermoformed Formats
Revenue generated from the sale of other PE thermoformed packaging formats not classified as trays and containers, blister packs, clamshells, cups and tubs, or lids and covers. Includes customized inserts, protective components, formed separators, and specialty packaging products developed for specific product shapes, handling requirements, and end-use applications.
Rigidity
Revenue capture definition
Rigid Thermoformed Packaging
Revenue generated from the sale of rigid PE thermoformed packaging products designed to maintain structural stability and retain their shape during filling, storage, handling, and transportation. Includes rigid trays, containers, and protective packaging formats used in food and beverage, healthcare, consumer goods, and industrial applications where strength and product containment are important.
Semi-rigid Thermoformed Packaging
Revenue generated from the sale of semi-rigid PE thermoformed packaging products that balance structural support with flexibility. Includes trays, tubs, containers, covers, and customized packaging formats designed to provide product protection while allowing practical handling, forming, and storage across food, personal care, healthcare, and consumer product applications.
Flexible Thermoformed Packaging
Revenue generated from the sale of flexible PE thermoformed packaging products designed to accommodate product shapes while allowing greater deformation than rigid packaging formats. Includes flexible formed components, thin-wall packaging, covers, and specialized packaging structures used where lightweight construction, adaptability, and material efficiency are required.
End Use Industry
Revenue capture definition
Food and Beverage
Revenue generated from the sale of PE thermoformed packaging products used for packaging, storing, displaying, and transporting food and beverage products. Includes trays, containers, cups, tubs, lids, and covers designed to provide moisture resistance, product containment, and convenient handling for fresh food, ready meals, processed foods, and other packaged food products.
Healthcare and Pharmaceuticals
Revenue generated from the sale of PE thermoformed packaging used for healthcare products, pharmaceutical items, medical supplies, and related components. Includes trays, containers, protective inserts, and specialized packaging formats designed to support product protection, hygienic handling, and safe storage during distribution and use.
Personal Care and Cosmetics
Revenue generated from the sale of PE thermoformed packaging used for personal care products, cosmetics, toiletries, and beauty accessories. Includes trays, containers, covers, and protective packaging components designed to organize, contain, and protect products while supporting convenient handling and retail presentation.
Consumer Electronics and Electrical Products
Revenue generated from the sale of PE thermoformed packaging used to protect electronic devices, electrical components, accessories, and related products. Includes trays, clamshells, inserts, and customized protective formats designed to secure components, minimize movement during transportation, and support organized storage and product handling.
Industrial and Automotive
Revenue generated from the sale of PE thermoformed packaging used for industrial equipment, automotive parts, mechanical components, and manufacturing supplies. Includes heavy-duty trays, component holders, separators, containers, and protective packaging formats designed to support part organization, handling, storage, and transportation.
Other End Uses
Revenue generated from the sale of PE thermoformed packaging for applications outside food and beverage, healthcare and pharmaceuticals, personal care and cosmetics, consumer electronics and electrical products, and industrial and automotive sectors. Includes customized packaging for household products, retail goods, agriculture-related products, and other commercial applications requiring product containment, protection, and efficient handling.
Estimation Model
Layer Name
Key Question
Description
End-use Industry Layer
What drives demand?
Estimate demand from key end-use industries, including food and beverage, healthcare and pharmaceuticals, personal care and cosmetics, consumer electronics, and industrial and automotive sectors that use PE thermoformed packaging for product containment, protection, storage, and transportation.
Packaging Format Adoption Layer
Which packaging formats are being used?
Assess the adoption of PE thermoformed trays and containers, blister packs, clamshells, cups and tubs, lids and covers, and other formed formats based on product characteristics, packaging functionality, moisture resistance, handling requirements, and end-use specifications.
Polyethylene Consumption Layer
Which material types generate demand?
Evaluate the consumption of LDPE, HDPE, LLDPE, and other PE grades across thermoformed packaging applications, considering material flexibility, rigidity, toughness, formability, processing suitability, and performance requirements for different packaging formats.
Revenue Estimation Layer
How is market revenue generated?
Estimate market revenue from the sale of PE thermoformed packaging products across packaging formats, rigidity categories, polyethylene types, end-use industries, and geographic regions. Revenue assessment considers the value of finished packaging products supplied to end users, rather than the value of raw polyethylene resin alone.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Comparative assessment of leading PE thermoform packaging manufacturers based on product portfolios, polyethylene grades (LDPE, HDPE, and LLDPE), packaging formats, manufacturing capabilities, material efficiency, sustainability initiatives, geographic presence, and strategic developments.
Identifies competitor positioning, product differentiation, capability gaps, and opportunities to strengthen market presence across key applications and regions.
Cross-Segmentation Analysis
Comprehensive analysis of market opportunities across combinations of Polyethylene Type (LDPE, HDPE, LLDPE, Other PE Grades), Packaging Format (Trays and Containers, Blister Packs, Clamshells, Cups and Tubs, Lids and Covers), Rigidity (Rigid, Semi-Rigid, Flexible), End Use (Food and Beverage, Healthcare and Pharmaceuticals, Personal Care and Cosmetics, Consumer Electronics, Industrial and Automotive), and regional markets.
Helps identify high-potential segment combinations, application-specific demand patterns, and attractive growth areas to support targeted product development and market-entry strategies.
Opportunity Assessment
Evaluation of growth opportunities arising from increasing demand for packaged food, healthcare and pharmaceutical packaging, lightweight thermoformed formats, material-efficient designs, recyclable PE structures, and expanding manufacturing and consumption across high-growth regional markets.
Supports investment prioritization, product portfolio optimization, identification of emerging application opportunities, and development of strategies aligned with evolving customer requirements and sustainability expectations.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


