
- Home
- »
- Plastics, Polymers & Resins
- »
-
Polymer Membranes For Energy Storage Market Report 2033GVR Report cover

Polymer Membranes For Energy Storage Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Proton Exchange Membranes, Anion Exchange Membranes), By Application (Automotive, Energy & Utilities, Industrial), By Region, And Segment Forecasts
Market Size, 2025
$1.5BMarket Estimate, 2026
$1.6BMarket Forecast, 2033
$2.9BCAGR, 2026–2033
9.1%Polymer Membranes For Energy Storage Market Summary
The global polymer membranes for energy storage market size was valued at USD 1.5 billion in 2025 and is projected to grow from USD 1.6 billion in 2026 to USD 2.9 billion by 2033, at a CAGR of 9.1% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 52.0% in 2025. The growing adoption of renewable energy and electric vehicles is driving demand for polymer membranes in energy storage applications, supported by advances in membrane technologies and government investments in clean energy.
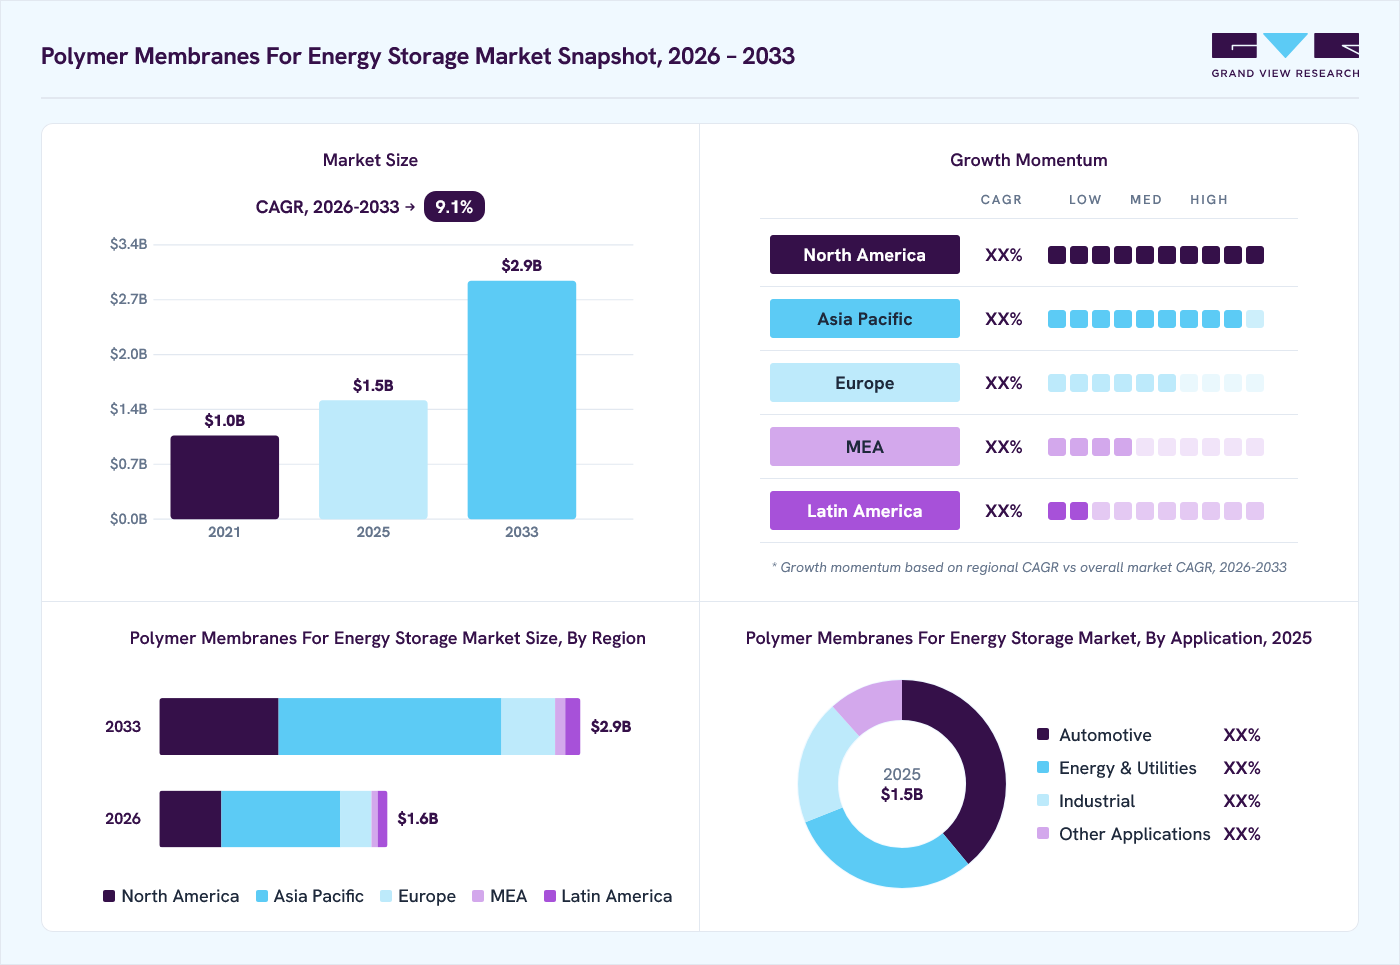 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Proton exchange membranes (PEM) segment dominated the market, with a revenue share of 55.5% in 2025.
- By application: Automotive segment held the largest market share of 39.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (52.0% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.5 Billion
- Estimated market size in 2026: USD 1.6 Billion
- Projected market size by 2033: USD 2.9 Billion
- CAGR (2026-2033): 9.1%
Prism AI by Grand View Research Free to tryAsk a question about the polymer membranes for energy storage marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Rising deployment of lithium-ion and redox flow batteries further supports market growth, as durable membranes enable efficient ion transport, improved safety, higher energy density, and longer operating life. The growing adoption of renewable energy and electric vehicles (EVs) drives demand for polymer membranes in energy storage, supported by advancements in membrane technologies and government funding for clean energy initiatives. In addition, the need for efficient and durable membranes in applications such as redox flow and lithium-ion batteries is boosting market growth. The rapid expansion of renewable energy sources such as solar and wind has driven the need for reliable and efficient energy storage systems to mitigate supply fluctuations. Polymer membranes play a critical role in energy storage technologies, particularly redox flow batteries (RFBs) and lithium-ion batteries, facilitating ion transport and improving system efficiency.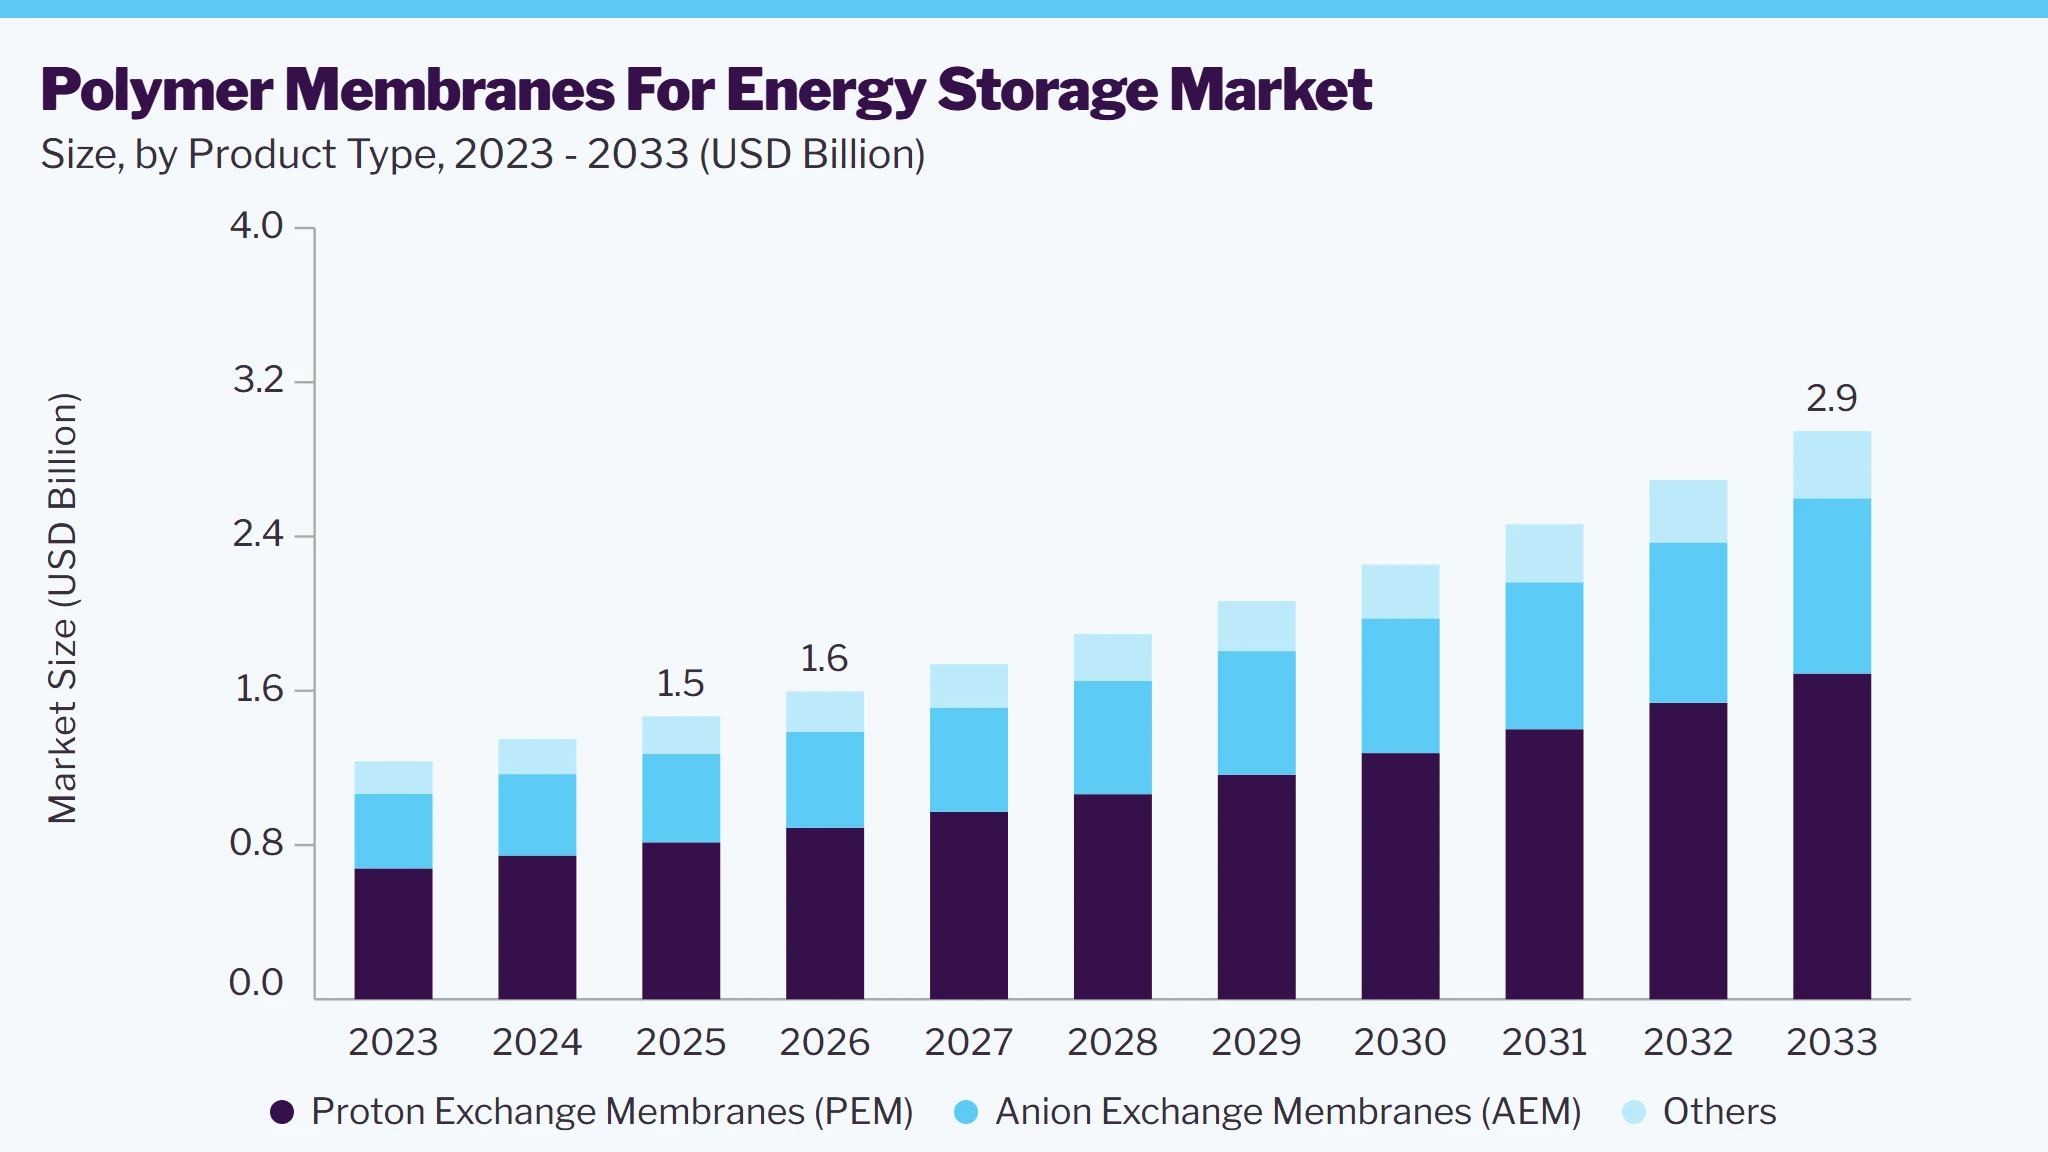 To learn more about this report, Download Free Sample Report
For example, increasingly used for grid-scale energy storage, vanadium redox flow batteries (VRFBs) rely on ion exchange membranes to separate electrolytes and minimize crossover. As governments worldwide aim to meet carbon neutrality goals and integrate more renewable energy sources, the demand for polymer membranes in energy storage is expected to rise significantly.
Ongoing innovations in polymer membrane technologies enhance energy storage systems' efficiency, durability, and cost-effectiveness. Researchers are developing next-generation membranes with higher ionic conductivity, reduced resistance, and improved chemical stability to withstand harsh operating conditions.
For example, perfluorosulfonic acid (PFSA) membranes, such as Nafion, dominate the market due to their high proton conductivity and stability, but emerging alternatives such as sulfonated polyether (ether ketone) (SPEEK) and polybenzimidazole (PBI) are gaining attention due to their lower costs and improved performance at higher temperatures. These advancements are driving the adoption of polymer membranes across various energy storage applications, ensuring longer operational life and greater efficiency.
The global push toward electric mobility has significantly contributed to the rising demand for lithium-ion batteries, where polymer membranes act as separators to prevent short circuits and enhance battery safety. As EV manufacturers focus on increasing energy density and reducing charging time, advanced polymer membranes with superior ion selectivity and thermal stability are becoming essential.
Companies such as Toray Industries are investing heavily in developing high-performance polymer membranes that can improve EV batteries' overall performance and safety. With EV sales projected to grow exponentially, the demand for advanced polymer membranes is expected to follow a similar trajectory.
Government initiatives aimed at accelerating the transition to clean energy and electric mobility are strongly supporting the polymer membranes market. Countries such as the U.S., China, and Germany offer subsidies and incentives to encourage the development of next-generation energy storage technologies, including those utilizing polymer membranes.
In addition, funding for research and development (R&D) in energy storage materials fosters innovation in membrane technologies. For example, the U.S. Department of Energy’s (DOE) support for solid-state battery development has spurred advances in polymer electrolyte membranes, promising to improve future battery technologies' safety and longevity. These policy-driven initiatives are expected to fuel market growth by ensuring continuous innovation and commercializing polymer membranes for energy storage.
Market Dynamics
Polymer membranes for energy storage are moving from niche electrochemical inputs to specification-led materials tied to EV batteries, fuel cells, and grid storage programs. Demand is concentrated in Asia Pacific, which held the largest regional share in 2024, while North America is expanding on the back of EV investment and public funding for storage technologies. The market is commercially structured around qualified suppliers, long development cycles, and collaboration with battery and fuel-cell developers, which favors firms with deep membrane know-how and application support.
Electric vehicle platforms remain the clearest demand engine for polymer membranes, especially where high ionic conductivity, thermal stability, and safety performance are mandatory. The report notes that PEMs lead the product mix and that automotive is the largest application, reflecting heavy use in EVs, HEVs, lithium-ion batteries, and fuel-cell systems. This creates repeat demand for technically qualified membranes rather than commodity substitutes, which strengthens revenue visibility for suppliers that can pass OEM validation.
A second layer of demand comes from renewable power integration and hydrogen-linked storage systems. AEMs are gaining relevance in alkaline fuel cells, redox flow batteries, and water electrolysis because they support non-precious metal catalysts and lower-cost configurations. At the same time, policy support for battery R&D and clean energy deployment, including U.S. DOE-backed storage programs, is accelerating the commercialization of higher-performance membrane platforms.
The market remains restrained by the high technical and commercial burden of membrane qualification. PEMs still dominate because PFSA-based materials deliver strong conductivity and chemical stability, but they also anchor the market to premium chemistries and strict performance benchmarks. Emerging AEM and alternative polymer systems remain under pressure to prove durability, reduced resistance, and long-life operation under harsh electrochemical conditions. This slows adoption outside pilot and early commercial programs and limits substitution across end uses.
The clearest opportunity lies in cost-down membrane platforms for alkaline fuel cells, water electrolysis, and next-generation storage systems. AEMs are positioned to benefit from the push toward green hydrogen because they can operate with non-precious catalysts and support lower-cost system design. Suppliers that combine durability gains with application-specific engineering can capture early commercial programs as customers seek alternatives to PFSA-heavy architectures.
Analyst Perspective
The market is entering a more value-driven phase, where growth will depend less on broad material adoption and more on membrane performance, system compatibility, and application-specific qualification. Automotive remains the largest demand pool, but energy and utilities, especially grid storage and hydrogen-linked systems, will increasingly shape product direction. Asia Pacific will likely stay the center of volume demand, while North America and Europe support higher-value innovation through EV, renewable, and clean-hydrogen programs. The main competitive divide will be between suppliers that can prove long-life conductivity, chemical stability, and thermal resistance, and those still stuck in pilot-scale development. The source page already signals a market shaped by established players, emerging innovators, and active collaboration, which suggests that partnerships, intellectual property, and manufacturing reliability will matter as much as raw membrane chemistry. Pricing pressure and substitution risk will remain real where lower-cost AEM or alternative polymer systems mature.
Product Insights
Based on product, the proton exchange membranes (PEM) segment led the market with the largest revenue share of 55.5% in 2025 and is projected to grow at the fastest CAGR of 9.4% during the forecast period. PEMs are widely used in fuel cells and energy storage systems, allowing protons to pass through while blocking gases such as hydrogen and oxygen. These membranes are typically made from perfluorosulfonic acid (PFSA) polymers, such as Nafion, which offer high ionic conductivity and chemical stability. PEMs are essential in applications requiring rapid energy delivery and high power density, including automotive, stationary power, and portable electronic devices.
Anion exchange membranes (AEM) facilitate the transfer of hydroxide ions (OH⁻) across the membrane and are commonly used in alkaline fuel cells, redox flow batteries, and water electrolysis systems. They offer a cost-effective alternative to PEMs, as they can operate with non-precious metal catalysts, making them attractive for low-cost energy storage applications. The push toward green hydrogen through electrolysis fuels the demand for AEMs due to their compatibility with alkaline electrolyzers.
Application Insights
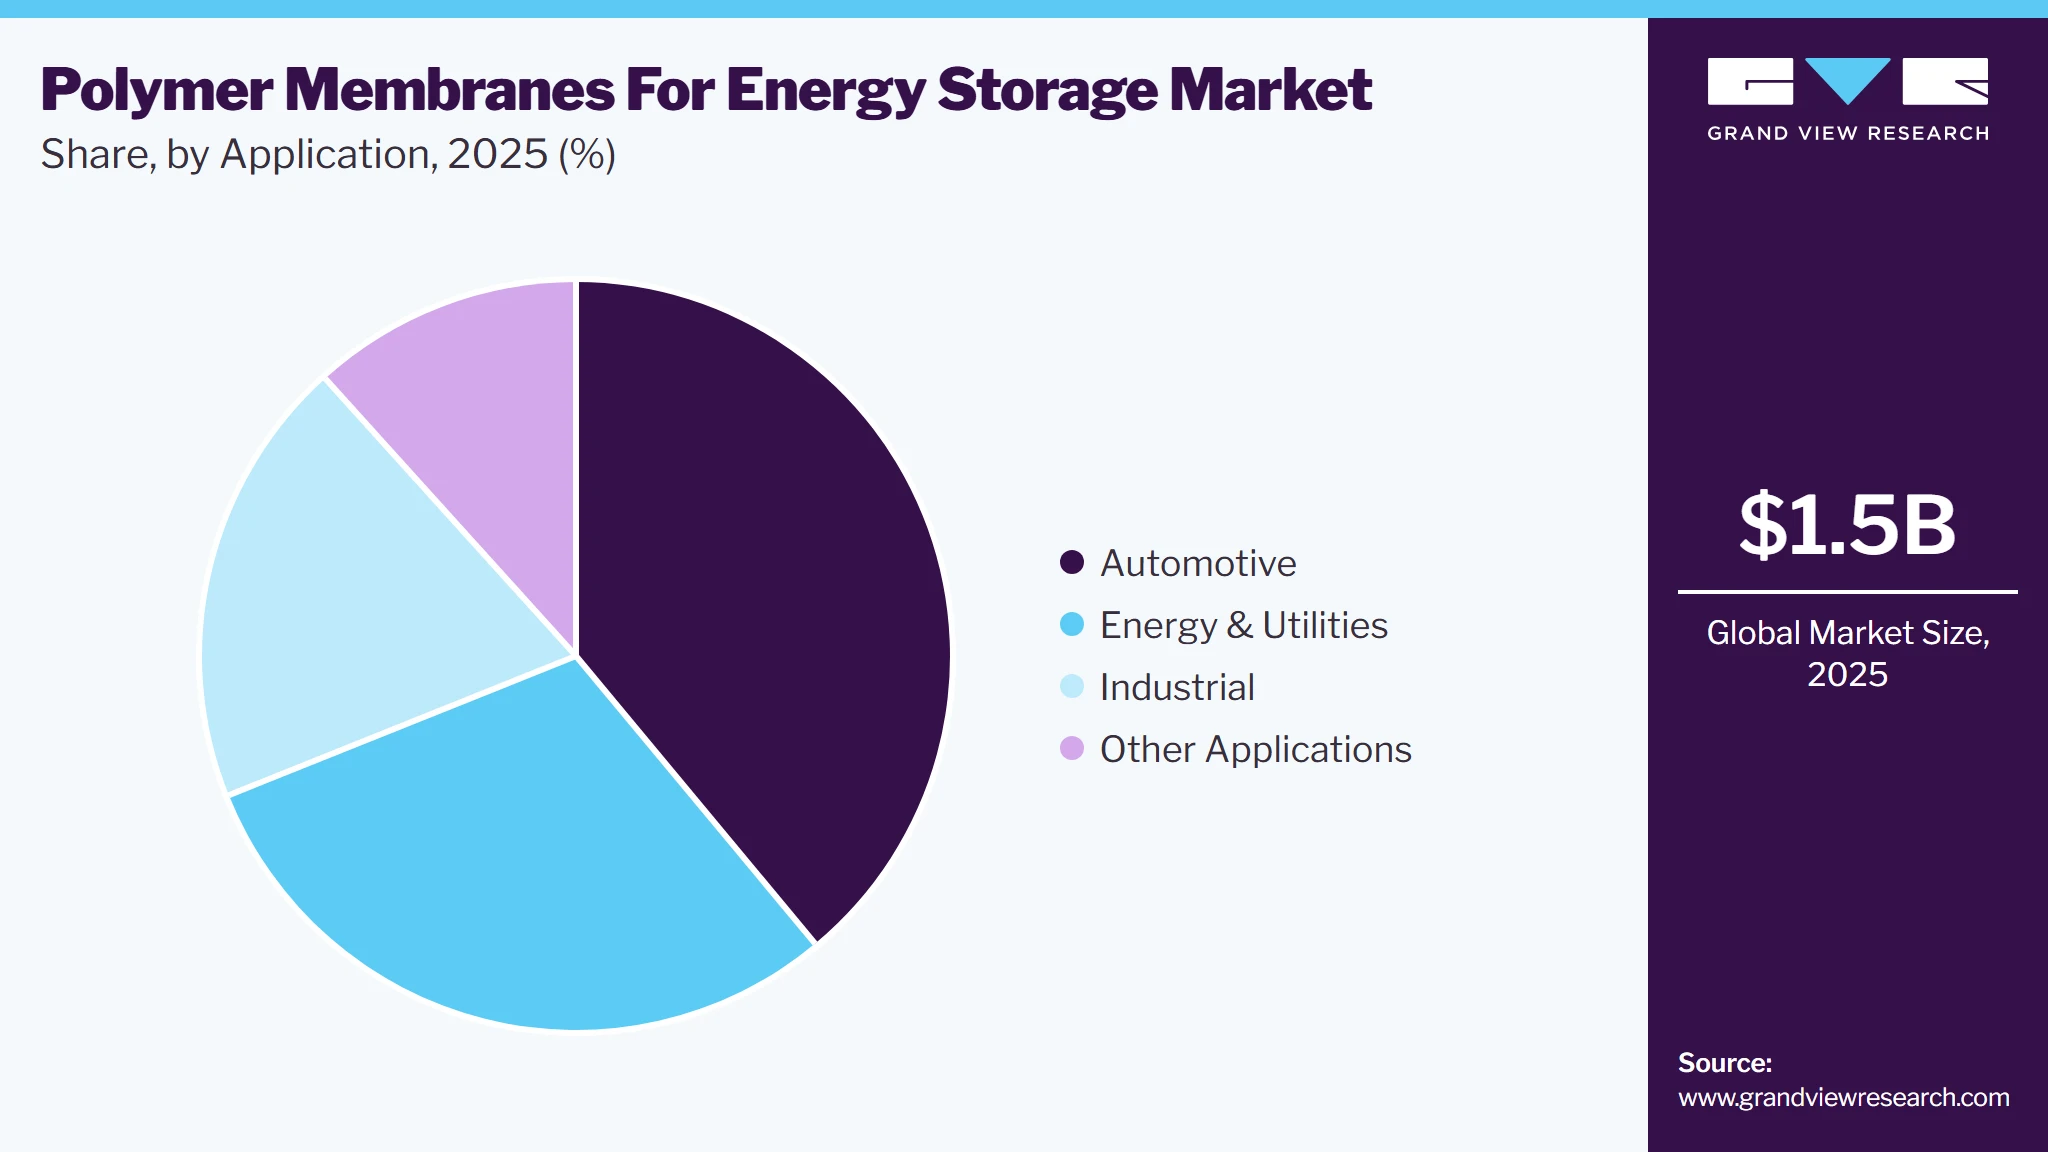
Based on application, the automotive segment led the market with the largest revenue share of 39.0% in 2025. Polymer membranes are widely used in automotive applications, particularly in electric vehicles (EVs) and hybrid electric vehicles (HEVs), where they are integral to the performance of fuel cells and lithium-ion batteries. The growing adoption of electric vehicles due to stringent government regulations on emissions and increasing consumer preference for eco-friendly transportation is driving the demand for polymer membranes.
 To learn more about this report, Download Free Sample Report
Polymer membranes are extensively used in energy and utility applications, including grid-scale energy storage, renewable energy systems, and fuel cells for power generation. These membranes facilitate efficient energy storage in flow batteries and hydrogen fuel cells, ensuring stable energy supply and enhanced performance of energy storage systems, especially in peak demand scenarios. The global shift towards renewable energy and the need to stabilize intermittent power sources, such as solar and wind, drive the demand for polymer membranes in energy and utility applications.
Polymer membranes are used in various energy-intensive industrial applications that require effective energy storage and management. They play a crucial role in electrochemical processes, industrial battery systems, and backup power solutions to ensure continuous operation and prevent downtime. Industries such as chemical processing, manufacturing, and power generation rely on these membranes to improve operational efficiency.
Region Insights
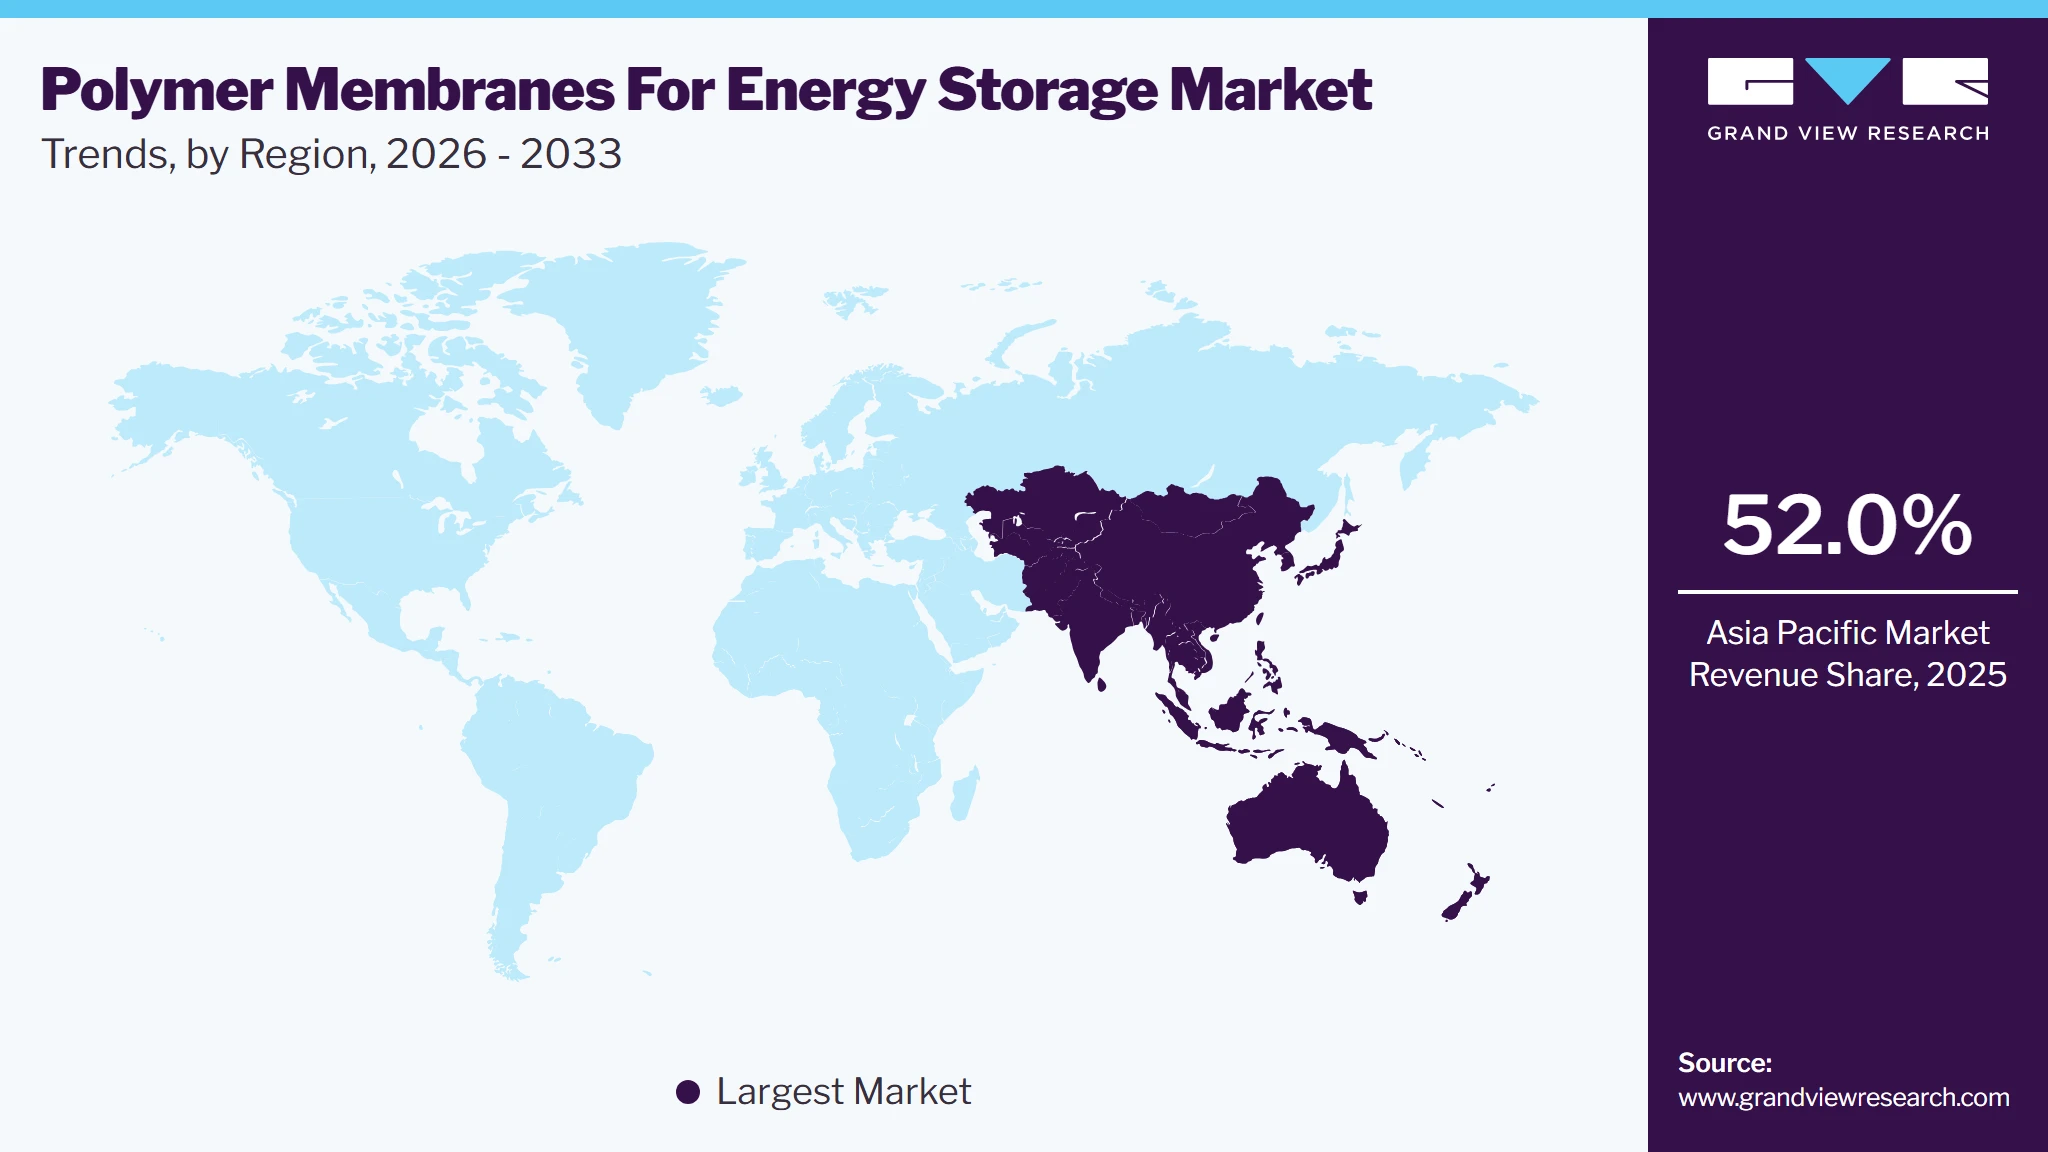
Asia Pacific dominated the polymer membranes for energy storage market with the largest revenue share of 52.0% in 2025. This positive outlook is due to the region’s growing emphasis on renewable energy sources and energy storage systems (ESS). Countries such as China, India, Japan, and South Korea actively invest in solar and wind energy projects, which require efficient and durable energy storage solutions. Moreover, Asia Pacific's booming electric vehicle (EV) industry is another significant driver. According to the International Energy Agency (IEA), China, the largest EV market globally, accounted for nearly 60% of global EV sales in 2023, followed by strong growth in Japan and South Korea.
 To learn more about this report, Download Free Sample Report
China Polymer Membranes For Energy Storage Market Trends
The polymer membranes for energy storage market in China accounted for the largest market revenue share in the Asia Pacific in 2025. The polymer membranes for energy storage market in China is experiencing robust growth, largely driven by strong government policies and investments to promote renewable energy and energy storage technologies. China has been actively expanding its energy storage capabilities through initiatives such as the 14th Five-Year Plan (2021-2025) and the Dual Carbon Goals of peaking carbon emissions by 2030 and achieving carbon neutrality by 2060. Hence, government-backed programs, including subsidies, tax benefits, and funding for research and development, have accelerated the growth of polymer membrane technologies in the country.
North America Polymer Membranes For Energy Storage Market Trends
The polymer membranes for energy storage market in North America is anticipated to grow at the fastest CAGR of 9.6% over the forecast period. The region’s market growth is primarily due to its strong investments in renewable energy infrastructure and the growing need for efficient energy storage solutions. The U.S. Department of Energy (DOE) has invested heavily in advancing energy storage technologies, allocating billions of dollars through initiatives such as the Energy Storage Grand Challenge to improve battery efficiency, lifespan, and cost-effectiveness. This has driven research and development (R&D) efforts focused on polymer membrane innovations that improve ionic conductivity and durability in battery applications.
The U.S. polymer membranes for energy storage market growth is majorly driven by the surge in electric vehicle (EV) adoption, which is driven by federal incentives, state-level policies, and ambitious goals to phase out internal combustion engine vehicles. EVs heavily rely on advanced lithium-ion batteries that utilize polymer membranes to enhance performance, durability, and safety. According to the U.S. Department of Energy (DOE), battery production capacity in the U.S. is expected to reach over 1,000 GWh annually by 2030, further fueling the demand for high-performance polymer membranes.
Europe Polymer Membranes For Energy Storage Market Trends
The polymer membranes for energy storage market in Europe is growing primarily due to its aggressive policies and investments in renewable energy and energy storage technologies. The European Union (EU) has set ambitious goals to achieve net-zero emissions by 2050 under the European Green Deal, which promotes the adoption of renewable energy sources such as solar and wind. Efficient energy storage technologies, including batteries and fuel cells, are essential to ensure a stable energy supply from these intermittent sources. Countries such as Germany and France are heavily investing in advanced energy storage systems, further boosting demand for polymer membranes.
Germany polymer membranes for energy storage market is primarily driven by its aggressive renewable energy policies and commitments toward reducing carbon emissions. Through its Energiewende (energy transition) strategy, Germany has set ambitious targets to transition from fossil fuels to renewable energy sources. With a goal to achieve 80% renewable electricity by 2030 and carbon neutrality by 2045, the country is investing heavily in energy storage technologies to stabilize the grid and support the integration of renewable energy.
Key Polymer Membranes For Energy Storage Company Insights
The market's competitive environment is characterized by the presence of established players and emerging innovators focusing on advanced membrane technologies. Major players dominate the market with a strong focus on research and development to enhance the efficiency and durability of polymer membranes used in applications such as lithium-ion batteries, flow batteries, and fuel cells.
Startups and niche companies are introducing next-generation membranes with improved ionic conductivity and thermal stability to meet the growing demand for high-performance energy storage systems. Strategic collaborations, mergers, and acquisitions are common as companies aim to strengthen their portfolios and expand their global footprint. The increasing emphasis on renewable energy integration and the transition to electric mobility drive heightened competition and innovation in this rapidly evolving market.
Key Polymer Membranes For Energy Storage Companies:
The following key companies have been profiled for this study on the polymer membranes for energy storage market.
-
Evonik AG
-
The Chemours Company
-
Compact Membrane Systems, Inc.
-
TORAY INDUSTRIES, INC.
-
Ionomr Innovations Inc.
-
Conventus Polymers LLC
-
PolyCera
-
UBE Corporation
-
DuPont
-
Celgard
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Evonik AG, The Chemours Company, TORAY INDUSTRIES, INC., UBE Corporation, DuPont, Celgard.)
Build scale through integrated membrane chemistry, qualification support, and multi-region supply coverage.
Focus on OEM partnerships, long-term supply agreements, and application-specific product development.
Use R&D to improve conductivity, durability, and thermal stability while protecting pricing in premium grades.
Strong brand recognition and established procurement trust across energy storage and adjacent materials markets.
Broader technical portfolios and deeper validation history with automotive and utility customers.
Better access to capital, manufacturing scale, and global commercial channels.
Higher cost base and slower response to niche applications or fast-changing chemistries.
Greater exposure to price pressure as membrane performance becomes more standardized.
Longer internal approval cycles can slow entry into emerging platforms.
Emerging Players (Compact Membrane Systems, Inc., Ionomr Innovations Inc., Conventus Polymers LLC, PolyCera.)
Target specific membrane gaps such as lower-cost AEM systems, custom membranes, and pilot-scale applications.
Use partnerships, demonstration projects, and direct technical engagement to accelerate market entry.
Compete with focused product development rather than broad portfolio coverage.
Greater agility in product iteration and customer-specific customization.
Better positioning in next-generation membrane chemistries and emerging use cases.
Leaner structures can support faster collaboration with developers and pilots.
Limited scale and narrower customer reach than established suppliers.
Higher dependence on external validation, partnerships, and funding.
Commercial expansion can be slow when qualification cycles extend across OEM programs.
Recent Developments
-
In March 2024, Toray Industries developed an innovative ion-conductive polymer membrane that addresses critical challenges in lithium-metal batteries, potentially revolutionizing electric vehicle (EV) range and battery performance. This breakthrough technology achieves 10 times higher ion conductivity than previous solutions while preventing dendrite formation, a major cause of battery degradation and safety risks.
-
In April 2022, Compact Membrane Systems (CMS) and Braskem launched the Optiperm demonstration plant at Braskem's Marcus Hook facility. This project represents a significant milestone in developing CMS’s proprietary Optiperm technology, which focuses on olefin-paraffin separation. The technology is designed to improve efficiency, reduce waste, lower carbon emissions, and enhance sustainability in petrochemical processes.
Polymer Membranes For Energy Storage Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.5 billion
Estimated market size in 2026
USD 1.6 billion
Projected market size by 2033
USD 2.9 billion
Growth rate
CAGR of 9.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Evonik AG; The Chemours Company; Compact Membrane Systems, Inc.; TORAY INDUSTRIES, INC.; Ionomr Innovations Inc.; Conventus Polymers LLC; PolyCera; UBE Corporation; DuPont; Celgard
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase—addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Polymer Membranes For Energy Storage Market Report Segmentation
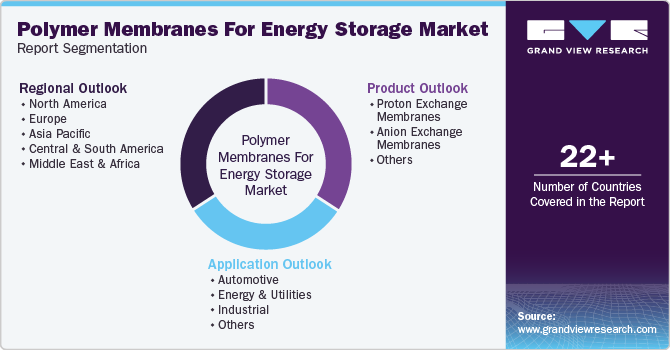
This report forecasts volume & revenue growth at a global level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global polymer membranes for energy storage market report based on product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Proton Exchange Membranes (PEM)
-
Anion Exchange Membranes (AEM)
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Energy & Utilities
-
Industrial
-
Others
-
-
Region Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The polymer membranes for energy storage market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each polymer membranes for energy storage segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Proton Exchange Membranes (PEM)
Revenue is captured through premium sales of high-conductivity PFSA and similar proton-conducting membranes for fuel cells, lithium-ion battery interfaces, and stationary power systems, including qualified grades, conversion support, and technical service.
Anion Exchange Membranes (AEM)
Revenue is generated through sales of hydroxide-conducting membranes for alkaline fuel cells, redox flow batteries, and water electrolysis, where pricing is tied to catalyst compatibility, durability, and cost reduction in low-precious-metal systems.
Others
Revenue comes from specialty and emerging membrane formats, including composite, reinforced, and custom architectures used in pilot systems, niche storage applications, and R&D programs that do not fit standard PEM or AEM commercial grades.
Segment - Application
Revenue capture definition
Automotive
Revenue is captured through supply contracts for EV, HEV, and fuel-cell programs, where membranes are specified for battery safety, ion transport, and power density, typically under model-linked qualification and long-term OEM sourcing arrangements.
Energy & Utilities
Revenue is earned from grid-scale storage, renewable balancing, flow batteries, and hydrogen power systems, with monetization driven by project-based procurement, replacement demand, and utility efforts to stabilize intermittent solar and wind output.
Industrial
Revenue is captured through membranes used in industrial battery systems, electrochemical processes, and backup power infrastructure, where buyers value uptime, chemical stability, and operating efficiency more than lowest-unit pricing.
Other Applications
Revenue includes portable electronics, laboratory systems, pilot installations, and other specialty uses that purchase lower volumes but often require customized membrane geometry, performance tuning, or early-stage technology validation.
Estimation Model
Layer Name
Key Question
Description
Top-Down Screen
Why start with the total market?
The model begins with the total addressable membrane revenue pool and allocates it across product, application, and region using reported adoption patterns and supplier presence.
Application Weighting
Why weight by application?
Application demand is adjusted by EV intensity, grid storage deployment, and industrial uptime needs, because these channels determine qualification depth, order frequency, and pricing power.
Product Validation
Why validate product splits?
Product splits reflect technical fit, with PEM leading on conductivity and AEM gaining on cost structure, while other membranes capture custom or early-stage demand.
Regional Triangulation
Why triangulate by region?
Regional allocation is cross-checked against Asia Pacific dominance and North America’s faster growth profile, then reconciled with policy support, EV buildout, and storage investment.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country-level coverage
Added country-level commentary for the most relevant demand centers, with sharper references to EV buildout, renewable storage deployment, and membrane qualification activity in each market.
Improves buyer relevance and geographic prioritization.
Product split
Broadened the product logic beyond PEM and AEM to include other membrane formats, pilot-grade systems, and custom architectures used in niche applications.
Helps capture emerging revenue pockets.
Competitive benchmarking
Added an analyst-led company split with operating strategies, competitive edge, and weaknesses for mature and emerging players.
Clarifies positioning and supplier strength.
Frequently Asked Questions About This Report
Based on application, the automotive segment led the market with the largest revenue share of 39.0% in 2025.
The key players in the polymer membranes for energy storage market include Evonik AG, The Chemours Company, Compact Membrane Systems, Inc., TORAY INDUSTRIES, INC., Ionomr Innovations Inc., Conventus Polymers LLC, PolyCera, UBE Corporation, DuPont, and Celgard.
The polymer membranes for energy storage market is driven by the rising adoption of electric vehicles (EVs) and growing demand for efficient and durable energy storage solutions. Additionally, advancements in membrane technologies and increasing investments in renewable energy systems further boost market growth.
Asia Pacific dominated with a 52.0% revenue share in 2025.
The polymer membranes for energy storage market in China accounted for the largest market revenue share in the Asia Pacific in 2025.
The polymer membranes for energy storage market size was valued at USD 1.5 billion in 2025 and is estimated at USD 1.6 billion in 2026.
The global polymer membranes for energy storage market is expected to grow at a CAGR of 9.1% from 2025 to 2030, reaching USD 2.9 billion by 2033.
The proton exchange membranes (PEM) segment dominated with the largest revenue share of 55.5% in 2025 .PEMs are widely used in fuel cells and energy storage systems, allowing protons to pass through while blocking gases such as hydrogen and oxygen.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


