
- Home
- »
- Catalysts & Enzymes
- »
-
Polymerization Initiators Market Size Report, 2026-2033GVR Report cover

Polymerization Initiators Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Persulfate, Peroxide, Azo compounds), By Application (Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride), By Region and Segment Forecasts
Market Size, 2025
$4.1BMarket Estimate, 2026
$4.3BMarket Forecast, 2033
$5.8BCAGR, 2026–2033
4.4%Polymerization Initiators Market Summary
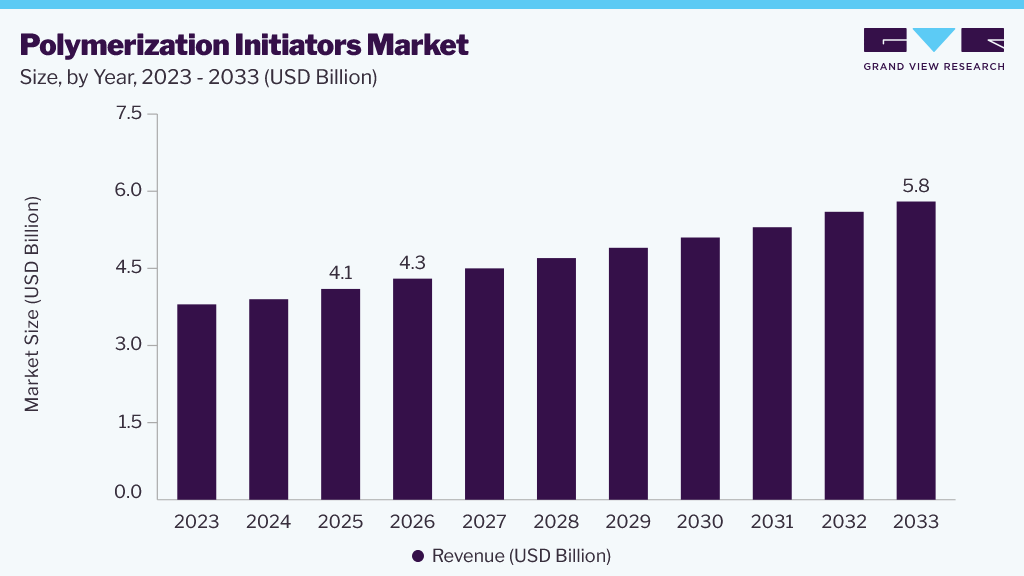
The global polymerization initiators market size was valued at USD 4.1 billion in 2025 and is projected to grow from USD 4.3 billion in 2026 to USD 5.8 billion by 2033, at a CAGR of 4.4% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 45.0% in 2025. The growing demand for advanced polymer materials with superior properties, including enhanced durability, flexibility, thermal stability, and chemical resistance, is driving the adoption of polymerization initiators across multiple industries. This trend is supporting market expansion, particularly in the automotive, electronics, packaging, construction, and consumer goods sectors, where high-performance polymers are increasingly required. Rising preference for peroxide-based polymerization initiators, owing to their high efficiency, reliable polymerization performance, and ability to improve product quality and process productivity, is further contributing to market growth.
Key Market Trends & Insights
- By type: Peroxides segment held the largest market share of around 40.0% in 2025.
- By application: Polyethylene (PE) segment held the largest market share of over 30.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (45.0% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 4.1 Billion
- Estimated market size in 2026: USD 4.3 Billion
- Projected market size by 2033: USD 5.8 Billion
- CAGR (2026-2033): 4.4%
Prism AI by Grand View Research Free to tryAsk a question about the polymerization initiators marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The polymerization initiator market is being driven by increasing investments in research and development to improve polymerization technologies, enhance reaction efficiency, and develop advanced polymer materials. At the same time, rising global polymer production is creating sustained demand for high-performance initiators that enable consistent product quality and optimized manufacturing processes. Growing consumption across end-use industries such as automotive, construction, packaging, healthcare, electronics, and consumer goods continues to expand the adoption of polymerization initiators worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The increasing use of polymers in applications ranging from automotive components and lightweight vehicle parts to medical devices, packaging materials, textiles, sports equipment, and consumer products is further supporting market growth. In the automotive sector, polymers are increasingly utilized in tires, interior trims, exterior body panels, bumpers, wheel covers, and under-the-hood components to improve fuel efficiency, durability, and design flexibility. This rising polymer consumption is directly boosting the demand for efficient polymerization initiators used during resin manufacturing.
Furthermore, expanding construction activities, increasing demand for lightweight engineering materials, and growing consumption of plastics and specialty polymers are accelerating market growth. Continuous technological advancements in polymer chemistry, particularly across the Asia Pacific, along with increasing investments in sustainable materials, controlled polymerization technologies, and high-performance resin production, are expected to further strengthen demand for polymerization initiators during the forecast period.
Analyst Perspective
The polymerization initiator market is witnessing steady growth, supported by rising demand for high-performance polymers, specialty plastics, and advanced chemical synthesis technologies. Manufacturers are increasingly utilizing polymerization initiators in the production of engineering plastics, automotive components, coatings, adhesives, elastomers, and medical materials owing to their ability to improve reaction efficiency, control molecular weight distribution, and enhance polymer stability and product performance. Growing adoption of sustainable polymers, controlled radical polymerization techniques, UV-curable systems, and specialty resin formulations is further driving market expansion. As demand for highly engineered polymer materials continues to rise, companies investing in next-generation initiator chemistries, process optimization, and application-specific innovations are expected to gain significant long-term growth opportunities.
Type Insights
The peroxides type segment dominated the market with a revenue share of around 40.0% in 2025. Organic peroxides are the most widely used polymerization initiators due to their high efficiency in generating free radicals required to produce polyethylene, polyvinyl chloride (PVC), polystyrene, acrylics, and other specialty polymers. Their broad applicability across plastics, rubber, thermoset resins, coatings, adhesives, and composite materials continues to drive demand. In addition to polymerization, organic peroxides are extensively used as curing agents and crosslinking agents, enhancing the mechanical strength, thermal stability, and durability of finished polymer products. The rising production of engineering plastics, packaging materials, automotive components, and construction products is expected to further support the growth of this segment over the forecast period.
The azo compounds segment is expected to register the fastest CAGR over the forecast period. Growing demand for specialty polymers, precision polymer synthesis, and advanced material applications is driving the adoption of azo initiators across the chemical and polymer industries. Compared with conventional peroxide initiators, azo compounds offer predictable decomposition rates, controlled free-radical generation, and lower processing temperatures, making them particularly suitable for acrylic polymers, high-performance coatings, adhesives, and controlled radical polymerization technologies. Increasing investments in specialty chemicals, electronic materials, biomedical polymers, and sustainable polymer manufacturing are further accelerating demand. The expanding use of azo initiators in research, pharmaceutical intermediates, and high-value polymer applications is expected to support robust growth in the segment throughout the forecast period.
Application Insights
The polyethylene (PE) segment dominated the market and accounted for the largest revenue share of over 30.0% in 2025. The segment's growth is driven by the extensive use of polymerization initiators, particularly organic peroxides, in the production of low-density polyethylene (LDPE) through free-radical polymerization. Polyethylene remains one of the world's most widely consumed polymers owing to its extensive applications in flexible packaging, films, containers, pipes, consumer goods, electrical insulation, and industrial products. Rising demand from the packaging, construction, automotive, and healthcare industries, coupled with increasing investments in polyethylene production capacity, continues to drive the consumption of polymerization initiators. Furthermore, the growing demand for recyclable, high-performance polyethylene materials is expected to support segment growth throughout the forecast period.
The ABS (Acrylonitrile Butadiene Styrene) segment is expected to register the fastest CAGR over the forecast period. Growing demand for lightweight, impact-resistant engineering plastics across the automotive, consumer electronics, electrical, and appliance industries is driving the consumption of ABS resins, thereby increasing the demand for polymerization initiators. Polymerization initiators play a critical role in the emulsion and suspension polymerization processes used to manufacture ABS by enabling efficient free-radical polymerization and consistent polymer properties. The rapid expansion of electric vehicle production, increasing adoption of 3D printing materials, and rising demand for durable plastic components with excellent mechanical strength and surface finish are further supporting market growth.
Regional Insights
The North America polymerization initiators market is expected to witness steady growth over the forecast period, driven by increasing demand for high-performance polymers across the automotive, packaging, healthcare, and construction industries. The growing emphasis on lightweight and fuel-efficient vehicles has accelerated the adoption of advanced polymer materials, thereby increasing the consumption of polymerization initiators used in engineering plastics and specialty resins. In addition, ongoing investments in sustainable polymer technologies, specialty chemicals, and advanced manufacturing processes are supporting market expansion across the region.
Asia Pacific Polymerization Initiators Market Trends
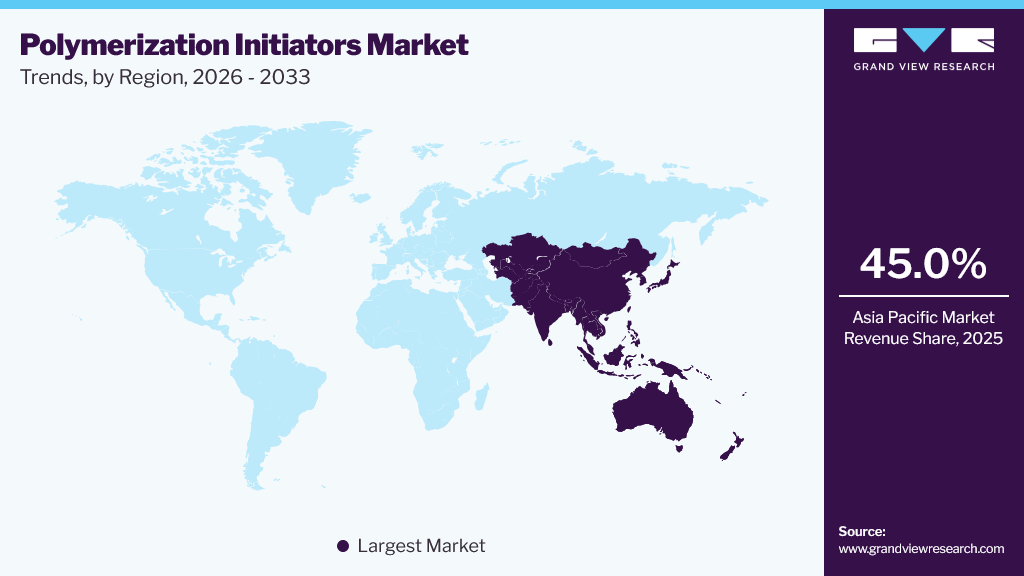
Asia Pacific dominated the global polymerization initiators market, accounting for the largest revenue share of around 45.0% in 2025. The region serves as the world's largest producer and consumer of polymerization initiators, supported by a well-established chemical manufacturing base and strong polymer production capacity. Countries such as China, Japan, India, and South Korea host numerous leading manufacturers and benefit from abundant raw material availability, cost-competitive production, and expanding downstream industries. Rapid industrialization, growing plastics consumption, increasing automotive production, and rising investments in specialty polymers continue to strengthen the region's leadership in the global market.
 To learn more about this report, Download Free Sample Report
China accounted for the largest share of the Asia Pacific polymerization initiators market in 2025. The country's dominant position is supported by its extensive petrochemical industry, integrated polymer manufacturing ecosystem, and strong presence of domestic chemical producers. Availability of raw materials, competitive manufacturing costs, and ongoing investments in advanced polymer production technologies are driving market growth. Furthermore, increasing demand from the automotive, electronics, packaging, construction, and consumer goods industries continues to accelerate the adoption of polymerization initiators across the country.
Europe Polymerization Initiators Market Trends
The Europe polymerization initiators market is expected to grow steadily over the forecast period, supported by increasing demand for sustainable polymer manufacturing and specialty chemical products. The region is witnessing a growing preference for bio-based and environmentally friendly polymerization initiators as manufacturers seek to reduce emissions and comply with stringent environmental regulations. Rising investments in green chemistry, recyclable plastics, advanced coatings, and high-performance polymers are further driving market growth. In addition, ongoing innovation in controlled polymerization technologies and specialty resin production is expected to strengthen demand for polymerization initiators across Europe.
Key Polymerization Initiators Company Insights
Some of the key players operating in the market include Arkema S.A., LANXESS AG, BASF SE, LyondellBasell Industries, AkzoNobel, Celanese Corporation, United Initiators, Adeka Corporation, Akkim Kimya, and Nouryon.
-
Arkema S.A. is a global company that specializes in the production of specialty chemicals, advanced materials, and coating solutions. The company is headquartered in Colombes, France, and operates in over 55 countries worldwide. Arkema's products are used in diverse sectors, including transportation, oil extraction, renewable energy, consumer goods, electronics, construction, coatings, water treatment, and more.
-
LANXESS AG is a prominent player in the specialty chemicals industry, with a focus on the development, manufacturing, and marketing of a diverse range of products, including plastics, rubber, intermediates, and specialty chemicals. The company operates globally, with a presence in Europe, Asia Pacific, Latin America, and North America.
Key Polymerization Initiators Companies
The following key companies have been profiled for this study on the polymerization initiators market:
-
Arkema S.A.
-
LANXESS AG
-
BASF SE
-
LyondellBasell Industries
-
AkzoNobel
-
Celanese Corporation
-
United Initiators
-
Adeka Corporation
-
Akkim Kimya
-
Nouryon
Recent Developments
- In November 2024, Nouryon completed a capacity expansion for organic peroxides at its Ningbo, China, manufacturing facility, doubling the production capacity of Perkadox® 14 and Trigonox® 101 to 6,000 metric tons each annually. These organic peroxides are widely used as polymerization initiators, crosslinking agents, and polymer modifiers for plastics, rubbers, and recycled polypropylene, strengthening Nouryon's supply capabilities for the growing global polymer industry.
Polymerization Initiators Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.1 billion
Estimated market size in 2026
USD 4.3 billion
Projected market size by 2033
USD 5.8 billion
Growth rate
CAGR of 4.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, and region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; Italy; France; Spain; China; India; Japan, South Korea; Brazil; Argentina; South Africa, Saudi Arabia
Key companies profiled
Arkema S.A; LANXESS AG; BASF SE; LyondellBasell Industries; AkzoNobel; Celanese Corporation; United Initiators; Adeka Corporation; Akkim Kimya; Nouryon
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Polymerization Initiators Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global polymerization initiators market report based on type, application, and region:
-
Type Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Persulfate
-
Peroxides
-
Azo Compounds
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Polyethylene
-
Polypropylene
-
Polyvinyl Chloride
-
Polystyrene
-
ABS (Acrylonitrile Butadiene Styrene)
-
Other Applications
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The polyethylene (PE) segment led with an over 30.0% revenue share in 2025, while the ABS (acrylonitrile butadiene styrene) segment is the fastest-growing.
Key players include Arkema S.A; LANXESS AG; BASF SE; LyondellBasell Industries; AkzoNobel; Celanese Corporation; United Initiators; Adeka Corporation; Akkim Kimya; Nouryon
The global polymerization initiators market size was valued at USD 4.1 billion in 2025 and is estimated at USD 4.3 billion for 2026.
The global polymerization initiators market is expected to grow at a CAGR of 4.4% from 2026 to 2033, reaching USD 5.8 billion by 2033.
Asia Pacific dominated with a 45.0% revenue share in 2025.
About the Author(s)
Catalysts & Enzymes Research Team
Specialty & Chemicals · Catalysts & EnzymesThis report was authored by the catalysts & enzymes research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the catalysts & enzymes segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


