
- Home
- »
- Next Generation Technologies
- »
-
Power-to-X Market Size, Share & Trends Report, 2026-2033GVR Report cover

Power-to-X Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Power-to-H2, Power-to-NH3, Power-to-Methane, Power-to-Methanol), By End Use (Agriculture, Manufacturing), By Region, And Segment Forecasts
Market Size, 2025
$380.0MMarket Estimate, 2026
$418.2MMarket Forecast, 2033
$945.2MCAGR, 2026–2033
12.4%Power-to-X Market Summary
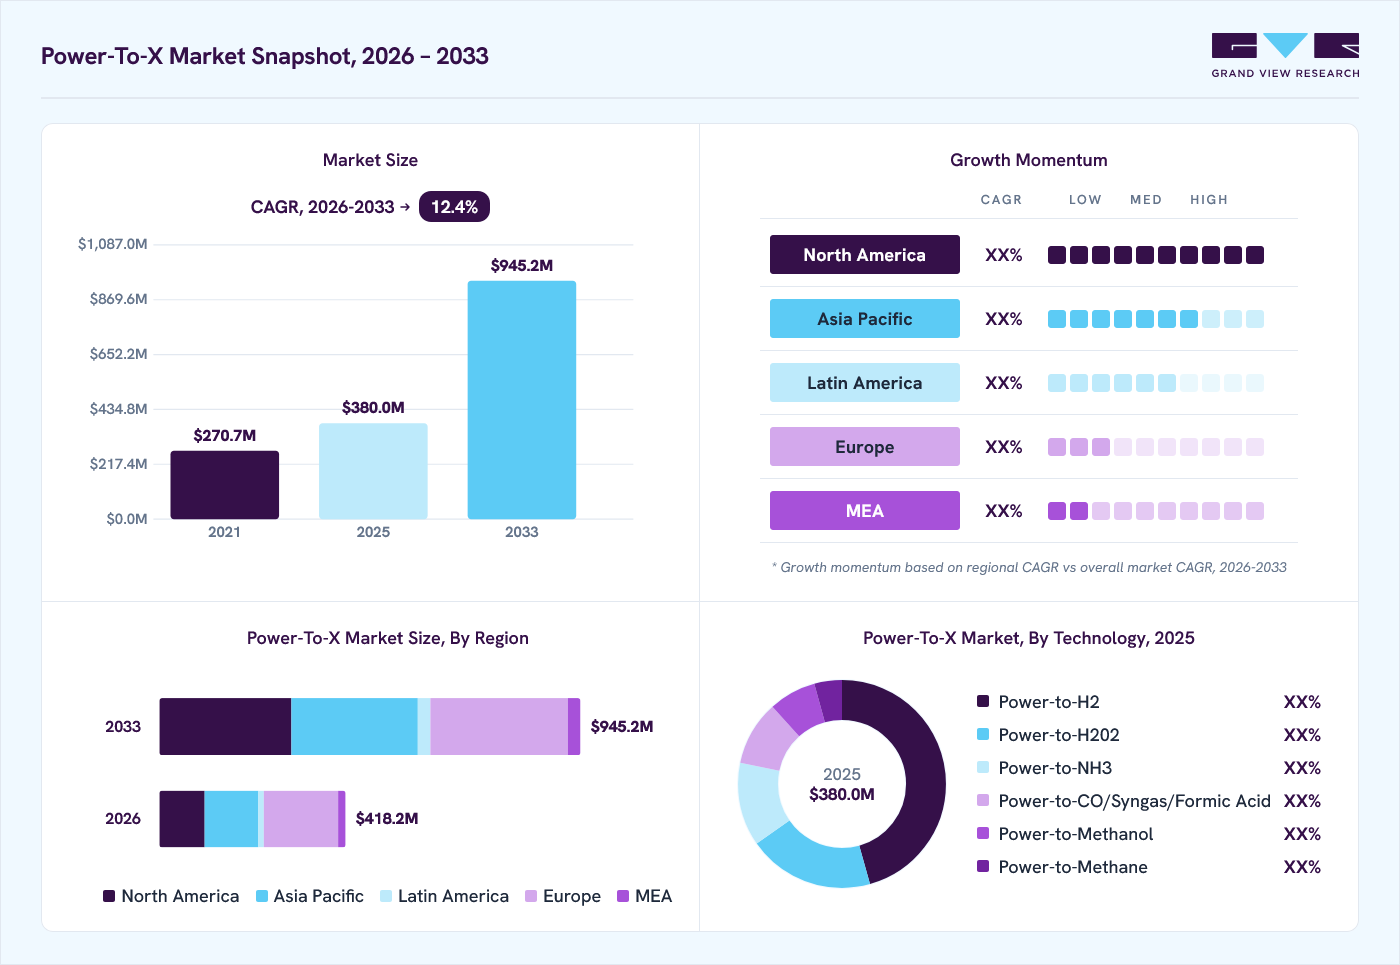
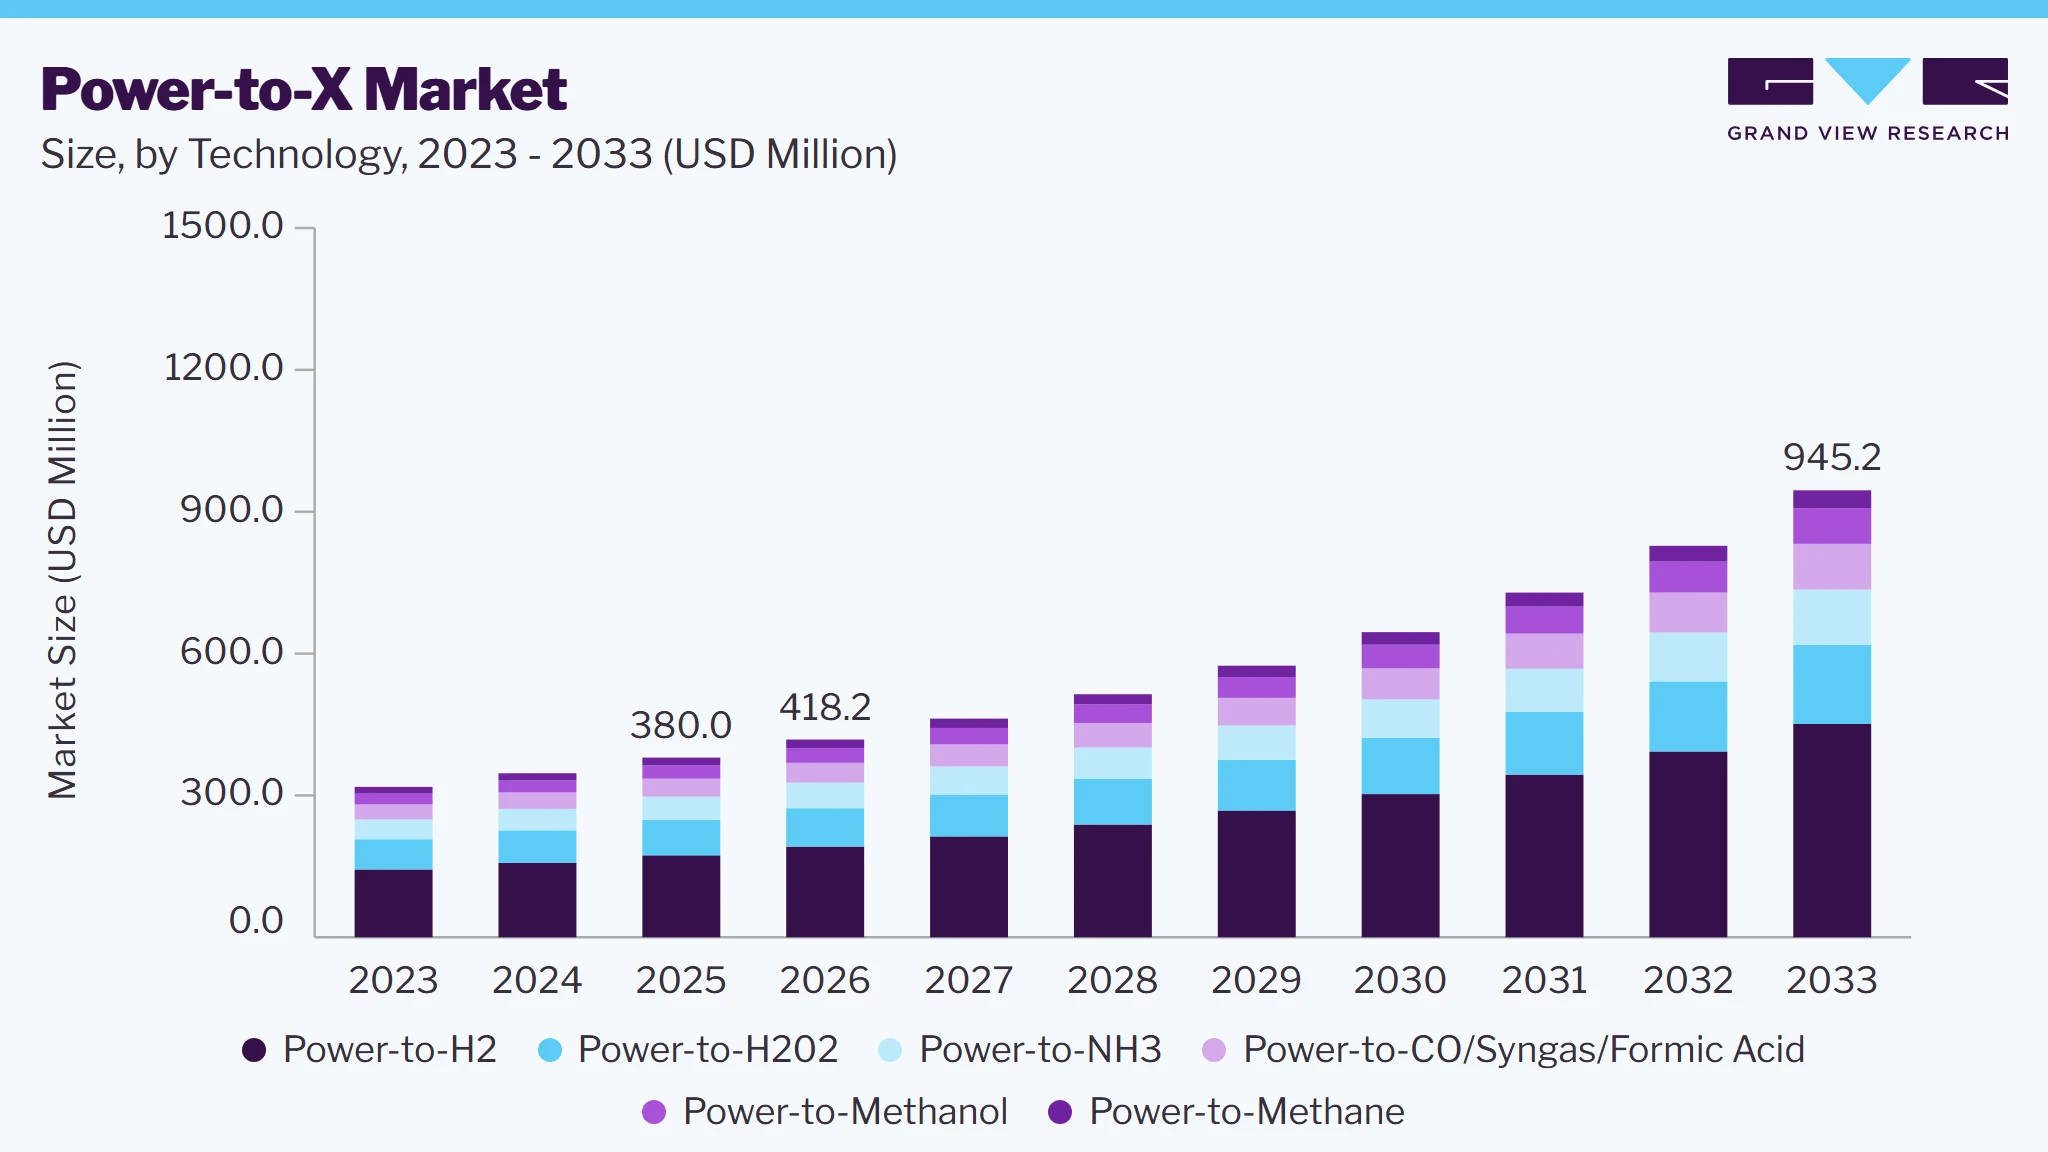
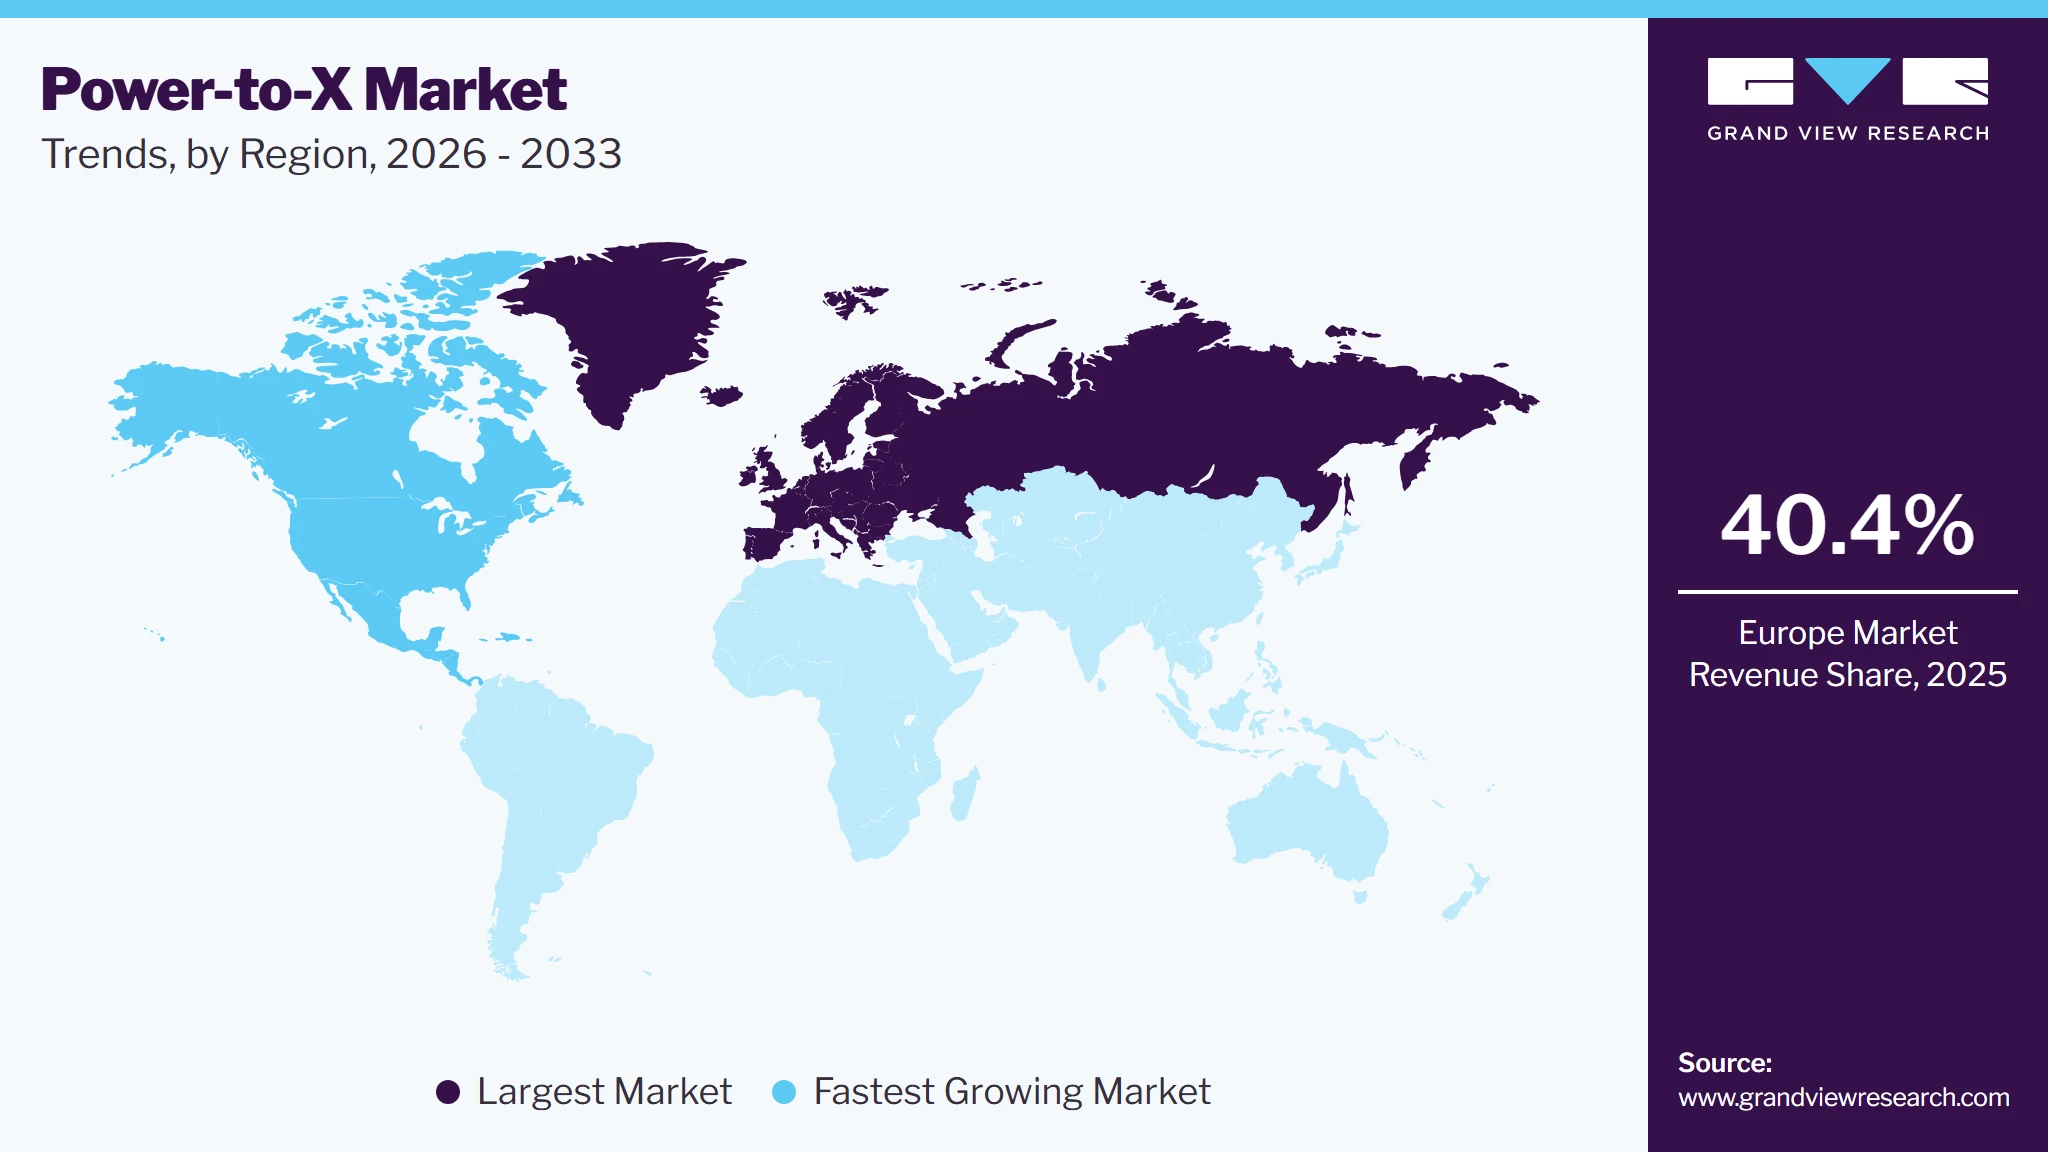
The global power-to-X Market size was valued at USD 380.0 million in 2025 and is projected to grow from USD 418.2 million in 2026 to USD 945.2 million by 2033, at a CAGR of 12.4% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 40.4% in 2025. The region's leadership is driven by ambitious decarbonization targets, robust investments in renewable energy infrastructure, supportive government policies for green hydrogen production, and the rapid deployment of large-scale power-to-x projects.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Power-to-H2 segment dominated the market, with a revenue share of 45.6% in 2025.
- By end use: Transportation segment held the largest market share of 39.6% in 2025.
Regional Highlights
- Largest regional market: Europe 40.4% (revenue share, 2025)
- Fastest regional market: North America (Highest CAGR,2025)
- By country: Germany held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 380.0 Million
- Estimated market size in 2026: USD 418.2 Million
- Projected market size by 2033: USD 945.2 Million
- CAGR (2026-2033): 12.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Countries across Europe are increasingly utilizing renewable electricity to produce green hydrogen, synthetic fuels, ammonia, and other sustainable energy carriers to decarbonize hard-to-abate sectors such as transportation, chemicals, steel, and aviation. Furthermore, Strong policy support under the European Green Deal, expanding electrolyzer capacity, and strategic collaborations among energy companies, technology providers, and industrial manufacturers continue to accelerate the commercialization and adoption of Power-to-X technologies across the region.
 To learn more about this report, Download Free Sample Report
Power-to-X (P2X) technologies offer a pathway to decarbonize sectors that are challenging to electrify directly. These include heavy transportation and industrial processes. Climate change poses a significant threat to the planet, necessitating urgent action to reduce GHG emissions. The market plays a crucial role in addressing this challenge by enabling the decarbonization of sectors that heavily rely on fossil fuels, such as transportation and industrial processes.
These sectors account for significant global carbon emissions and pose a challenge to electrify using conventional means. Power-to-X technologies offer innovative solutions to decarbonize these challenging sectors, encompassing processes like power-to-hydrogen, power-to-ammonia, power-to-methane, and power-to-liquids. These technologies involve using renewable or low-carbon electricity to produce hydrogen, ammonia, methane, or synthetic fuels, which can then be used as clean energy carriers or feedstocks in transportation and industrial applications. Governments are engaging in international collaboration and agreements to promote the adoption of power-to-X technologies, which include partnerships and knowledge-sharing platforms to exchange best practices, research findings, and policy approaches.
International agreements, such as the Paris Agreement, set global targets for reducing GHG emissions, further driving the adoption and implementation of power-to-X solutions worldwide. Regulatory bodies are enacting policies and regulations that promote the use of low-carbon fuels and chemicals, often derived from power-to-X processes. These regulations may include blending mandates for low-carbon fuels in transportation sectors, setting emission reduction targets, or incentivizing the adoption of cleaner alternatives in industrial applications. Such regulations create a market demand for power-to-X-derived products and drive the growth of the industry.
The continuous R&D efforts in P2X technologies drive significant advancements in electrolysis technologies, catalyst development, system integration, and process optimization. These innovations are expected to improve the efficiency, scalability, and cost-effectiveness of power-to-X processes. The ongoing collaboration, knowledge sharing, and technological advancements contribute to accelerating industry growth, supporting the global transition to a low-carbon and sustainable future.
Market Dynamics
The power-to-x market is experiencing significant growth, driven by the global transition toward clean energy, increasing renewable electricity generation, and growing efforts to decarbonize hard-to-abate sectors. Power-to-X technologies enable the conversion of renewable electricity into green hydrogen, synthetic fuels, ammonia, methanol, and other energy carriers, supporting long-term energy storage and sector coupling. Governments and private organizations are making substantial investments in green hydrogen projects, electrolyzer manufacturing, and integrated renewable energy infrastructure to achieve carbon neutrality and strengthen energy security. Furthermore, supportive policy frameworks, declining renewable energy costs, and increasing industrial demand for low-carbon fuels are accelerating market expansion. However, high capital investment requirements, limited infrastructure for hydrogen transportation and storage, and relatively high production costs continue to restrain market growth. Nevertheless, continuous advancements in electrolyzer technologies, expanding hydrogen economies, and increasing commercialization of sustainable aviation fuels and green chemicals are expected to create substantial growth opportunities during the forecast period.
The primary driver of the Power-to-X Market is the rapid expansion of renewable energy capacity and increasing investments in green hydrogen production. Governments worldwide are implementing hydrogen strategies, financial incentives, and decarbonization policies to promote the development of Power-to-X facilities. Industries such as steel, chemicals, refining, aviation, shipping, and heavy transportation are increasingly adopting green hydrogen and synthetic fuels to reduce carbon emissions and comply with stringent environmental regulations. The declining cost of solar and wind power, combined with advancements in electrolyzer efficiency, is further improving the economic viability of Power-to-X technologies, driving large-scale commercial deployment.
Despite strong growth prospects, the Power-to-X Market faces challenges related to the high capital expenditure associated with electrolyzers, renewable power integration, and hydrogen storage and transportation infrastructure. Green hydrogen and synthetic fuels remain more expensive than conventional fossil-based alternatives, limiting widespread adoption in cost-sensitive industries. Additionally, inadequate hydrogen distribution networks, limited refueling infrastructure, energy conversion losses, and regulatory uncertainties in several regions continue to hinder market expansion. These factors can delay project implementation and affect the commercial scalability of Power-to-X technologies.
The increasing focus on industrial decarbonization and the growing demand for sustainable fuels present significant opportunities for the Power-to-X Market. Sectors such as aviation, maritime shipping, chemicals, and heavy manufacturing are actively investing in green hydrogen, e-fuels, renewable ammonia, and e-methanol to achieve net-zero emissions. Furthermore, rising investments in hydrogen hubs, cross-border renewable energy projects, and carbon-neutral fuel production facilities are creating new growth avenues for market participants. Technological advancements in high-efficiency electrolyzers, carbon capture integration, and renewable fuel synthesis processes are expected to enhance production efficiency, reduce costs, and accelerate the commercialization of Power-to-X solutions globally.
Market Concentration & Characteristics
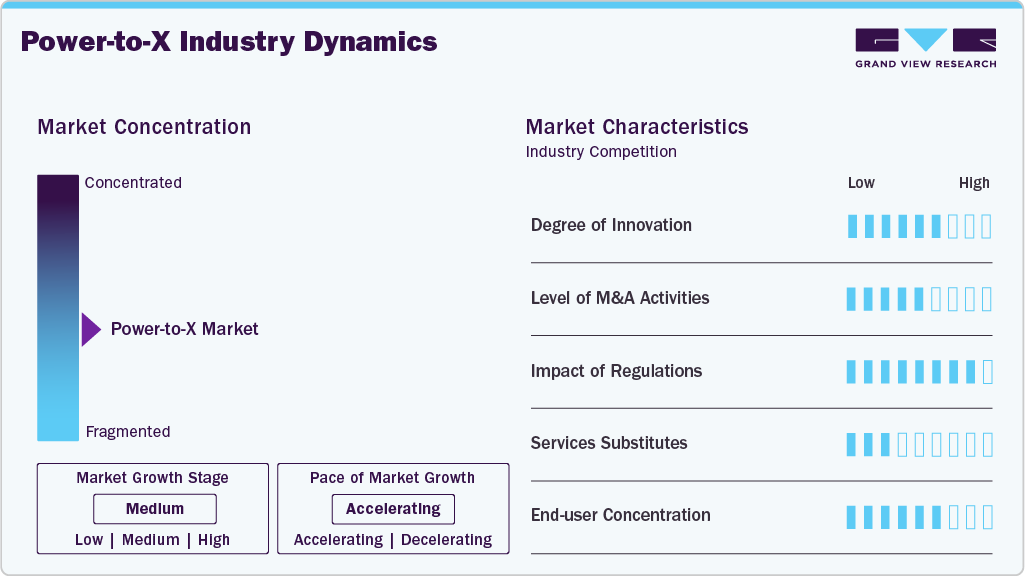
The power-to-X Market is moderately concentrated, with competition led by global engineering companies, industrial gas providers, renewable energy developers, electrolyzer technology manufacturers, and industrial automation solution providers. Market participants compete based on electrolyzer technologies, hydrogen production capabilities, renewable energy integration, process efficiency, large-scale project execution, engineering expertise, and end-to-end Power-to-X solutions. Continuous advancements in electrolysis systems, green hydrogen production, synthetic fuel technologies, carbon capture integration, and renewable ammonia and e-methanol production are reshaping the competitive landscape. Strategic investments in hydrogen infrastructure, renewable energy projects, industrial partnerships, and large-scale demonstration plants are further strengthening market competitiveness.
 To learn more about this report, Download Free Sample Report
Key market participants include Air Liquide Engineering & Construction, Alfa Laval, Copenhagen Infrastructure Partners, ENGIE SA, ITM Power PLC, Linde plc, Mitsubishi Power, Siemens Energy, thyssenkrupp Uhde GmbH, Valmet, and Weidmüller GmbH & Co. KG. These companies are focused on expanding their Power-to-X portfolios through investments in green hydrogen production, advanced electrolyzer technologies, renewable fuel synthesis, engineering and EPC services, hydrogen infrastructure, industrial decarbonization solutions, and strategic collaborations. Their strategies emphasize technological innovation, capacity expansion, renewable energy integration, and partnerships across the hydrogen value chain to accelerate the commercialization of Power-to-X technologies and support the global transition toward a low-carbon energy economy.
Analyst Perspective
The Power-to-X market is witnessing strong growth as governments and industries accelerate investments in renewable energy, green hydrogen, and low-carbon fuels to achieve decarbonization goals. Power-to-X technologies convert renewable electricity into green hydrogen, synthetic methane, green methanol, green ammonia, and other sustainable energy carriers. Growing adoption across transportation, chemicals, steel, refining, power generation, and agriculture is driven by the need to reduce emissions and replace fossil fuels. Advancements in electrolyzers, carbon capture and utilization, renewable fuel synthesis, and large-scale renewable energy integration are further supporting market growth. Government incentives, hydrogen strategies, and investments in infrastructure are accelerating commercialization. Rising demand for sustainable aviation fuels, green shipping fuels, renewable chemicals, and long-duration energy storage is expected to create significant opportunities, positioning Power-to-X as a key technology for the future low-carbon energy system.
Technology Insights
Based on technology, the power-to-H2 segment led the market with the largest revenue share of 45.6% in 2025. Hydrogen produced through power-to-H2 can be used as a clean fuel for various applications, including transportation and industrial processes. By substituting fossil fuels with hydrogen, emissions of greenhouse gases can be significantly reduced, leading to the decarbonization of sectors that are difficult to electrify directly, such as heavy-duty transportation, aviation, and industrial heating.
The power-to-methanol segment is predicted to foresee the highest growth in the coming years. The methanol produced through power-to-X processes offers a pathway for decarbonizing the transportation sector. Utilizing renewable electricity to produce methanol, carbon emissions associated with conventional methanol production from fossil fuels can be significantly reduced or eliminated. In addition, methanol can serve as a convenient carrier of hydrogen, allowing for the storage and transportation of hydrogen without the challenges associated with handling and storing pure hydrogen.
End Use Insights
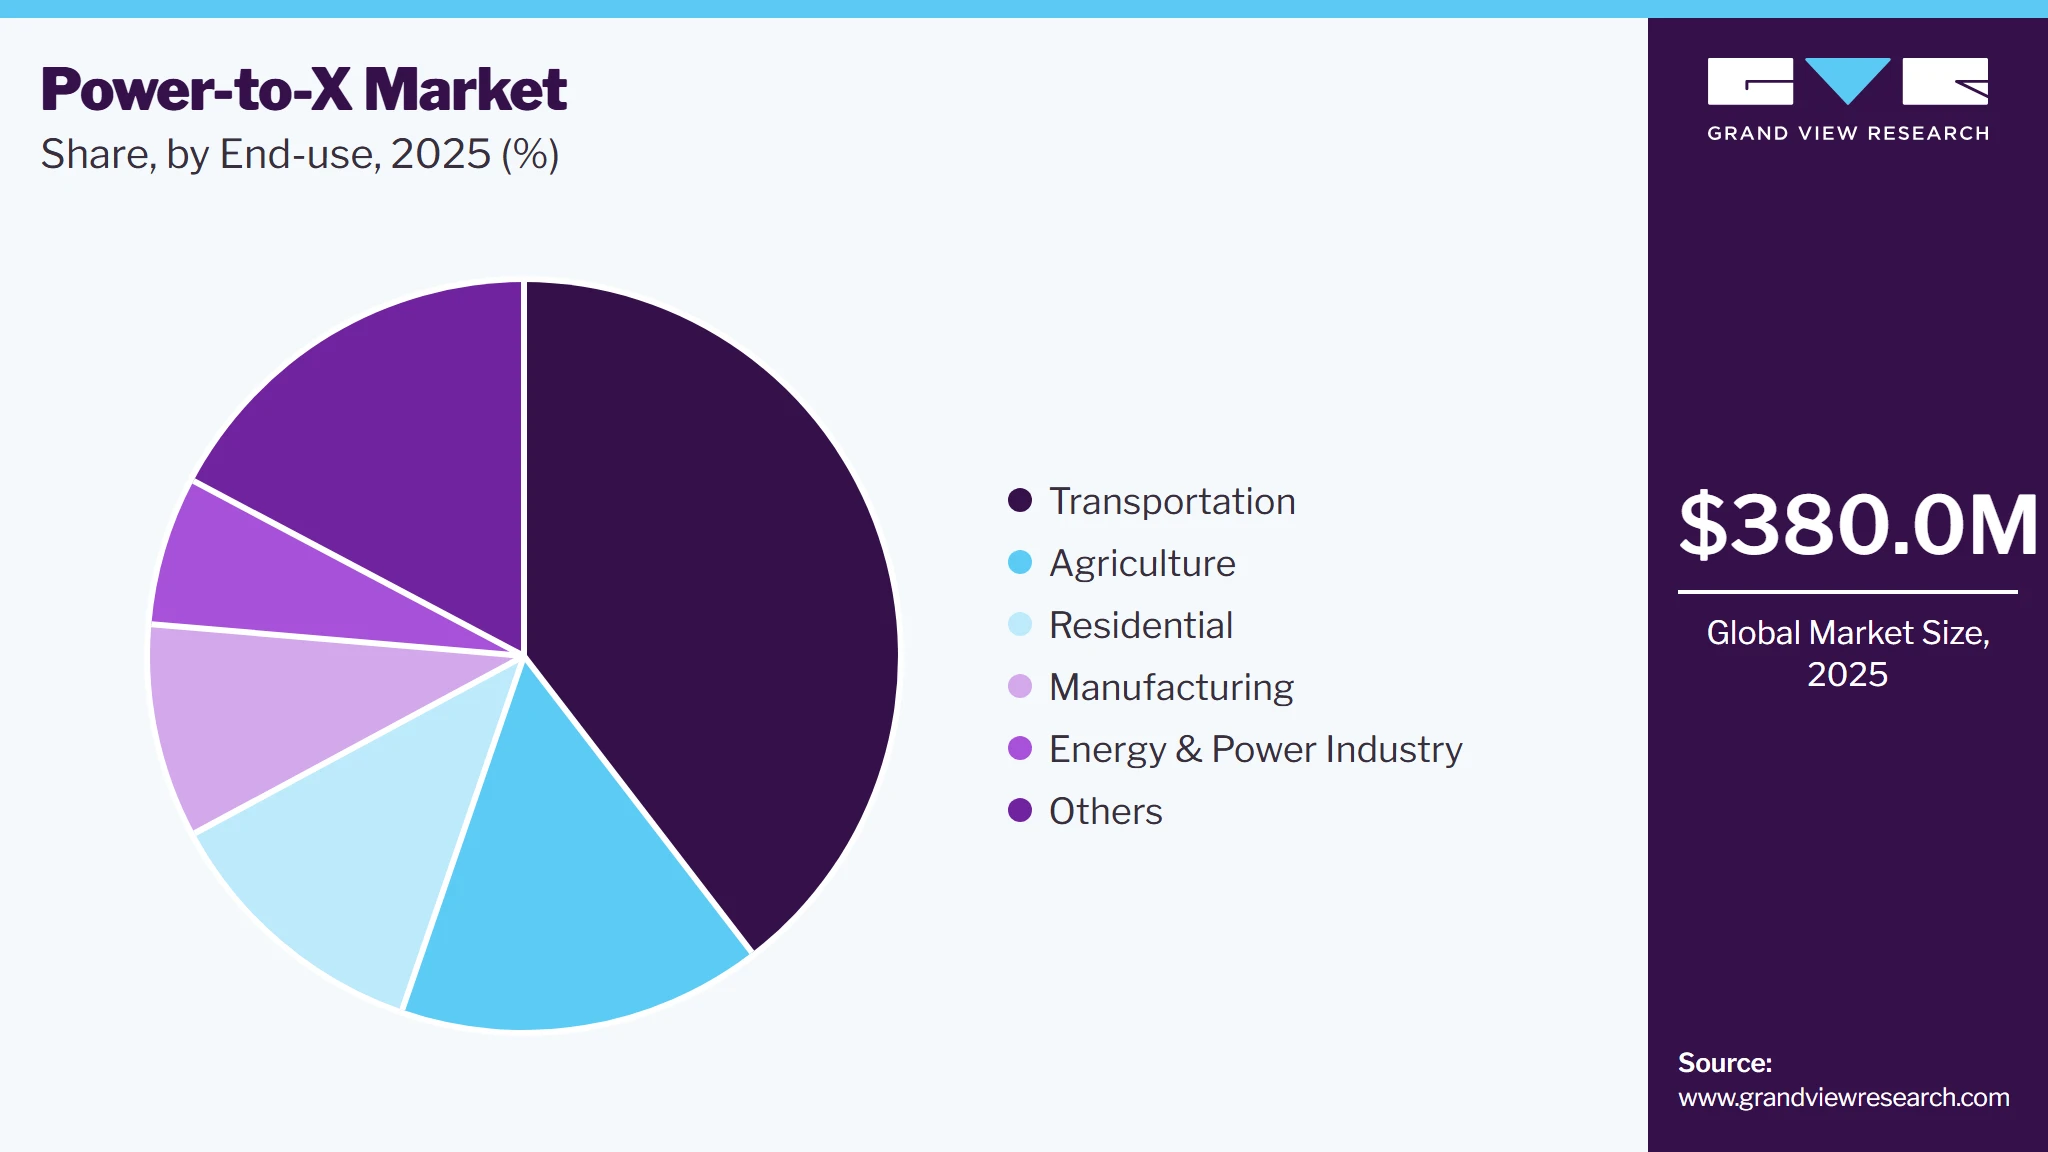
Based on end use, the transportation segment led the market with the largest revenue share of 39.6% in 2025. Power-to-X provides a diversified energy transition pathway in the transportation sector. While battery electric vehicles (EVs) are gaining popularity, power-to-X technologies offer an alternative for applications where batteries may not be the most suitable solution due to factors such as energy density, weight, or recharging time. By providing multiple options, power-to-X contributes to a balanced and comprehensive approach to decarbonizing transportation. The residential segment is predicted to foresee significant growth in the forecast years.
 To learn more about this report, Download Free Sample Report
The agriculture segment is anticipated to exhibit a significant CAGR over the forecast period. Various factors such as decarbonization of agriculture, green ammonia production, and sustainable irrigation and operations are primarily driving the growth of the agriculture segment. Moreover, power-to-X technologies support a circular economy model in agriculture by enabling the production of bio-based chemicals and energy from agricultural waste or CO2 capture, closing resource loops, and minimizing waste. Furthermore, increasing global emphasis on climate action, as well as financial support from governments and institutions for green technologies, is spurring the adoption of Power-to-X in agriculture, particularly in Europe and North America.
Regional Insights
North America power-to-X market is expected to witness fastest CAGR over the forecast period. In North American PtX market is expanding rapidly due to a combination of supportive government policies and private-sector investments. Supportive government policies are creating a favorable environment for the increased adoption of PtX technologies, which are considered essential for achieving ambitious climate targets and reducing greenhouse gas emissions.
U.S. Power-to-X Market Trends
The power-to-X market in the U.S. held a dominant position in 2024. Increased investments in green hydrogen are driving the growth of the PtX market in the U.S. Collaborations on large-scale green hydrogen projects are poised to drive the energy transition. The commitment to producing green hydrogen in large volumes can be indicative of the potential economic and environmental benefits of PtX technologies.
Europe Power-to-X Market Trends
The Europe power-to-X Market accounted for the highest share, with over 40.4% of the global revenue in 2025. The growing use of PtX technologies to substitute conventional, high-emission fuels with cleaner options is a prominent trend in the energy shift being pursued across Europe. The approach aims to produce low-carbon fuels, which offer substantial reductions in overall emissions compared to conventional energy sources, supporting Europe's broader goal of achieving a more sustainable and eco-friendly energy industry. offering up to 90% reduction in life cycle emissions compared to conventional jet fuel.
 To learn more about this report, Download Free Sample Report
Germany Power-to-X Market Trends
The power-to-X market in the Germany held a dominant position in 2025. Germany’s Power-to-X industry is witnessing rapid growth, supported by strong government focus on green hydrogen and industrial decarbonization. Growing investments in electrolyzers, renewable hydrogen production, and synthetic fuels are accelerating Power-to-X deployment. Rising demand from chemicals, steel, mobility, aviation, and shipping is driving adoption of low-carbon fuels and feedstocks. Expanding hydrogen infrastructure and renewable energy capacity are expected to further support the growth of Germany’s Power-to-X industry.
Asia Pacific Power-to-X Market Trends
The power-to-X market in Asia Pacific is anticipated to register a significant CAGR over the forecast period. The PtX market in Asia Pacific is experiencing rapid growth, driven by several key factors. As countries in the region strive to meet their energy demands while transitioning to sustainable practices, PtX technologies are becoming increasingly vital. Continued urbanization and industrialization are leading to higher energy consumption, prompting governments to invest in renewable energy infrastructure and PtX solutions essential for converting surplus renewable energy into usable forms, such as hydrogen, synthetic fuels, and chemicals.
Middle East & Africa Power-to-X Market Trends
The power-to-X market in the Middle East & Africa region is anticipated to register a significant CAGR over the forecast period. Various countries in the Middle East and Africa (MEA) are prioritizing PtX technologies to enhance their energy security and reduce dependence on imported fossil fuels. By investing in the development of local green hydrogen and other PtX products, these nations aim to create a more self-sufficient and resilient energy system. This strategic focus mitigates the risks associated with global energy market fluctuations and helps countries manage their energy resources more effectively.
Key Power-to-X Company Insights
Some key players in the power-to-X market, such as Siemens Energy, Engie SA, and Valmet. These companies focus on scalable, industrial-grade electrolysis and complete renewable energy-to-hydrogen systems, positioning themselves as key players in green hydrogen for heavy industries. Moreover, these companies are integrating P2X solutions with industrial processes, particularly in biomass and waste-to-energy sectors, using its advanced automation technology to optimize energy production and sustainability.
-
Siemens Energy provides comprehensive P2X solutions from renewable energy generation, such as wind and solar, to energy conversion and grid integration, creating a holistic system that can support green hydrogen and other P2X technologies.
-
Engie SA specializes in decarbonization strategies for industries and regions, applying P2X technologies to help customers achieve their net-zero goals by converting renewable power into storable and usable forms of energy.
Key Power-to-X Companies:
The following key companies have been profiled for this study on the power-to-X market.
-
Air Liquide Engineering & Construction
-
Alfa Laval
-
Copenhagen Infrastructure Partners
-
ENGIE SA
-
ITM Power PLC
-
Linde plc
-
Mitsubishi Power
-
Siemens Energy
-
thyssenkrupp Uhde GmbH
-
Valmet
-
Weidmüller GmbH & Co KG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players: Air Liquide Engineering & Construction, Linde plc, Siemens Energy, Mitsubishi Power, thyssenkrupp Uhde GmbH, Alfa Laval
- Focus on delivering integrated Power-to-X solutions through electrolyzer technologies, hydrogen production systems, renewable fuel synthesis, engineering, procurement and construction (EPC) services, industrial gas infrastructure, and process optimization. These companies emphasize large-scale project execution, strategic partnerships, technology innovation, and expanding global hydrogen and renewable energy infrastructure.
- Extensive engineering expertise, established industrial customer base, strong global presence, comprehensive hydrogen and gas processing capabilities, advanced process technologies, robust EPC experience, and the ability to execute large-scale Power-to-X projects across multiple industries.
- High capital investment requirements, long project development cycles, dependence on government incentives and regulatory support, exposure to fluctuating renewable energy costs, and increasing competition from emerging hydrogen technology providers.
Emerging & Innovation-Focused Players: Copenhagen Infrastructure Partners, ENGIE SA, ITM Power PLC, Valmet, Weidmüller GmbH & Co. KG
- Focus on expanding renewable hydrogen production, electrolyzer innovation, digital industrial solutions, renewable energy integration, and investments in large-scale Power-to-X infrastructure. Their strategies emphasize strategic collaborations, commercialization of green hydrogen projects, smart automation, industrial electrification, and accelerating the deployment of sustainable fuels and low-carbon chemicals.
- Strong focus on clean energy innovation, expertise in renewable energy development, advanced electrolyzer technologies, flexible project financing capabilities, industrial automation solutions, and growing participation in integrated hydrogen value chains.
- Dependence on policy incentives and renewable energy availability, relatively limited global project portfolios compared with established engineering companies, high technology commercialization costs, supply chain constraints, and project execution risks associated with large-scale infrastructure development.
Recent Developments
-
In June 2024, Mitsubishi Power signed a Memorandum of Understanding (MoU) to research the development of hydrogen co-firing technologies for Thailand’s gas turbine power generation facilities. The study focuses on finding ways of easing the adoption of clean fuels in thermal power plants, assisting Thailand in its objective to reach carbon neutrality by 2050 and net-zero emissions by 2065.
-
In May 2024, Copenhagen Infrastructure Partners signed an agreement with GE Vernova's Onshore Wind division for the delivery, commissioning, and installation of 125 GE Vernova 6.1-158 wind turbines at Spain’s Teruel wind project. GE Vernova is an energy equipment manufacturing company. The agreement, valued at nearly USD 761 million (EUR 700 million), ranks among the most significant contracts for wind power initiatives in Spain and is anticipated to significantly boost the Spanish wind power sector.
-
In March 2024, ABB collaborated with Green Hydrogen International Corp., a green hydrogen provider, to establish a large-scale green hydrogen facility in southern Texas, U.S. ABB would utilize its automation, electrification, and digital solutions for Green Hydrogen International Corp.’s Hydrogen City initiative. The project includes a Power-to-X facility that will harness solar and onshore wind resources to operate a 2.2 GW electrolyze unit. This setup is expected to generate 280,000 tons of green hydrogen every year, which will subsequently be transformed into one million tons of green ammonia.
Power-to-X Market Report Scope
Report Attribute
Details
Market size in 2025
USD 380.0 million
Estimated market size in 2026
USD 418.2 million
Projected market size by 2033
USD 945.2 million
Growth rate
CAGR of 12.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; France; China; India; Japan; South Korea; Australia; Brazil; Mexico; KSA; UAE; South Africa
Key companies profiled
Air Liquide Engineering & Construction; Alfa Laval; Copenhagen Infrastructure Partners; ENGIE SA; ITM; Power PLC; Linde plc; Mitsubishi Power; Siemens Energy; thyssenkrupp Uhde GmbH; Valmet; Weidmüller GmbH & Co KG
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Power-to-X Market Report Segmentation
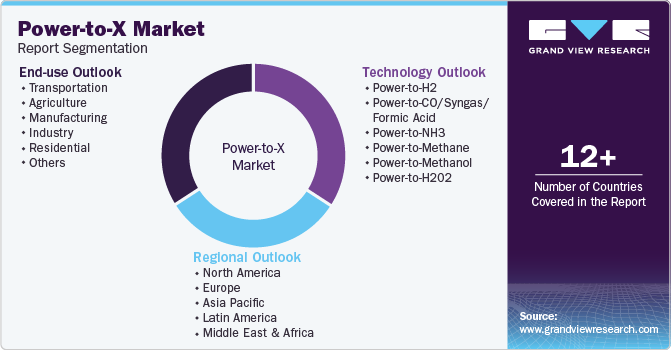
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global power-to-X market report based on technology, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Power-to-H2
-
Power-to-CO/Syngas/Formic Acid
-
Power-to-NH3
-
Power-to-Methane
-
Power-to-Methanol
-
Power-to-H202
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Transportation
-
Agriculture
-
Manufacturing
-
Industry
-
Residential
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
MEA
-
UAE
-
South Africa
-
KSA
-
-
Research Methodology
The Power-to-X market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Power-to-X segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment -Technology
Revenue capture definition
Power-to-H2
Revenue in this segment is generated through technologies and systems that convert renewable electricity into green hydrogen (H₂) via water electrolysis. This includes electrolyzers (alkaline, PEM, and solid oxide), hydrogen production plants, water treatment systems, power electronics, compression and storage equipment, and balance-of-plant components required for hydrogen generation.
Power-to-CO/Syngas/Formic Acid
Revenue in this segment is generated through technologies and systems that convert renewable electricity and captured carbon dioxide (CO₂) into carbon monoxide (CO), syngas (a mixture of hydrogen and carbon monoxide), and formic acid using electrochemical and catalytic conversion processes. This includes CO₂ electrolyzers, electrochemical reactors, catalytic conversion systems, carbon capture integration technologies, power electronics, gas separation and purification equipment, and balance-of-plant components required for carbon utilization.
Power-to-NH3
Revenue in this segment is generated through technologies and systems that convert renewable electricity into green ammonia (NH₃) by combining green hydrogen produced via water electrolysis with nitrogen extracted from air through the Haber-Bosch process or emerging electrochemical ammonia synthesis technologies. This includes electrolyzers, air separation units (ASUs), ammonia synthesis reactors, hydrogen compression and storage systems, process control equipment, and balance-of-plant components required for ammonia production.
Power-to-Methane
Revenue in this segment is generated through technologies and systems that convert renewable electricity into synthetic methane (e-methane) by combining green hydrogen produced via water electrolysis with captured carbon dioxide (CO₂) through methanation processes. This includes electrolyzers, methanation reactors, carbon capture and utilization (CCU) systems, gas purification units, hydrogen compression and storage equipment, process control systems, and balance-of-plant components required for methane synthesis.
Power-to-Methanol
Revenue in this segment is generated through technologies and systems that convert renewable electricity into green methanol (e-methanol) by combining green hydrogen produced via water electrolysis with captured carbon dioxide (CO₂) through catalytic methanol synthesis processes. This includes electrolyzers, carbon capture and utilization (CCU) systems, methanol synthesis reactors, gas purification units, hydrogen compression and storage equipment, process control systems, and balance-of-plant components required for methanol production.
Power-to-H202
Revenue in this segment is generated through technologies and systems that convert renewable electricity into hydrogen peroxide (H₂O₂) via electrochemical synthesis processes. This includes electrochemical reactors, electrolyzers, catalytic electrodes, power electronics, process control systems, purification equipment, storage units, and balance-of-plant components required for hydrogen peroxide production. Renewable hydrogen peroxide is utilized across water and wastewater treatment, pulp and paper bleaching, chemical manufacturing, healthcare, electronics, mining, and environmental remediation applications
Segment -End Use
Revenue capture definition
Transportation
Revenue in this segment is generated through the deployment of Power-to-X products across the transportation sector, where renewable electricity is converted into sustainable fuels such as green hydrogen, e-methanol, e-methane, green ammonia, and synthetic aviation fuels. These energy carriers are utilized to decarbonize road transport, railways, maritime shipping, and aviation by replacing conventional fossil fuels with low-carbon alternatives
Agriculture
Revenue in this segment is generated through the use of Power-to-X products in the agriculture sector, primarily for the production of green ammonia and other sustainable chemicals used as low-carbon fertilizers. Power-to-X technologies convert renewable electricity into hydrogen and ammonia, reducing dependence on fossil fuel-based fertilizer production while lowering greenhouse gas emissions
Manufacturing
Revenue in this segment is generated through the adoption of Power-to-X products across manufacturing industries to replace fossil fuel-based energy sources and feedstocks with low-carbon alternatives. This includes the use of green hydrogen, synthetic methane, green ammonia, e-methanol, and other renewable energy carriers for high-temperature industrial heating, process energy, and chemical production
Energy & Power Industry
Revenue in this segment is generated through the deployment of Power-to-X technologies and products across industrial sectors to decarbonize energy-intensive operations and reduce reliance on fossil fuels. This includes the use of green hydrogen, synthetic fuels, green ammonia, e-methanol, and other renewable energy carriers as feedstocks, reducing agents, and process fuels in industries such as chemicals, refining, steel, cement, mining, pulp and paper, and glass manufacturing.
Residential
Revenue in this segment is generated through the adoption of Power-to-X solutions in residential buildings, where renewable electricity is converted into clean energy carriers such as green hydrogen and synthetic methane for domestic energy applications. These energy carriers are used for space heating, water heating, cooking, and backup power generation through fuel cells or hydrogen-ready heating systems.
Others
Revenue in this segment is generated through the adoption of Power-to-X technologies across additional end-use sectors not covered under the primary categories. These include commercial buildings, utilities, power generation, data centers, district heating, research institutions, and defense applications, where renewable electricity is converted into green hydrogen, synthetic fuels, and other low-carbon energy carriers.
Estimation Model
Layer Name
Key Question
Description
Addressable End-user Base Layer
Which industries generate demand for Power-to-X technologies?
Identify the global addressable base of industries investing in Power-to-X solutions. This includes transportation, manufacturing, agriculture, utilities, residential, commercial, and other sectors adopting renewable energy carriers to decarbonize operations, improve energy security, and integrate renewable electricity into their energy systems.
Power-to-X Product Layer
Which Power-to-X products drive market demand?
Assess demand across key Power-to-X products, including green hydrogen (Power-to-H₂), green ammonia (Power-to-NH₃), synthetic methane (Power-to-Methane), green methanol (Power-to-Methanol), carbon monoxide/syngas/formic acid (Power-to-CO/Syngas/Formic Acid), hydrogen peroxide (Power-to-H₂O₂), and other renewable fuels and chemicals produced using renewable electricity.
Technology & Deployment Layer
How extensively are Power-to-X technologies being deployed?
Estimate adoption based on the deployment of water electrolysis technologies (alkaline, PEM, and solid oxide electrolyzers), carbon capture and utilization (CCU) systems, methanation and methanol synthesis technologies, ammonia synthesis systems, hydrogen storage and compression, renewable power integration, and supporting production, storage, and distribution infrastructure.
Revenue Generation Layer
How much revenue is generated?
Calculate market revenue by assessing spending on Power-to-X production facilities, electrolyzers, synthesis reactors, carbon capture systems, hydrogen storage and transportation infrastructure, engineering, procurement and construction (EPC) services, plant operation and maintenance, and the commercial sale of renewable hydrogen, synthetic fuels, ammonia, methanol, methane, and other Power-to-X products across end-use industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Competitive Intelligence & Market Positioning Assessment
Delivered a comprehensive assessment of leading Power-to-X technology providers, engineering companies, electrolyzer manufacturers, and renewable energy developers, evaluating their market positioning, technology capabilities, project portfolios, strategic partnerships, geographic presence, production capacities, and recent developments.
Helps stakeholders benchmark competitors, identify strategic growth opportunities, evaluate partnership and investment prospects, and gain a comprehensive understanding of the competitive landscape within the Power-to-X Market.
Technology Adoption & End-user Analysis
Conducted a detailed analysis of Power-to-X technology adoption across key end-use industries, including transportation, manufacturing, agriculture, utilities, and residential sectors, highlighting deployment trends, investment priorities, and evolving decarbonization use cases.
Enables organizations to identify high-growth application areas, understand end-user adoption patterns, prioritize target industries, and make informed decisions regarding market entry, product development, and business expansion.
Technology Advancements & Future Growth Potential Evaluation
Evaluated the impact of advancements in electrolyzer technologies, carbon capture and utilization (CCU), renewable fuel synthesis, hydrogen infrastructure, and integrated renewable energy systems on market growth while identifying emerging opportunities across the global Power-to-X value chain.
Assists decision-makers in prioritizing technology investments, identifying emerging revenue opportunities, strengthening innovation strategies, and preparing for future developments in the global Power-to-X Market.
Frequently Asked Questions About This Report
The global Power-to-X market size was valued at USD 380.0 Million in 2025 and is estimated at USD 418.2 Million for 2026.
The global Power-to-X market is expected to grow at a CAGR of 12.4% from 2026 to 2033, reaching USD 945.2 million by 2033.
Key factors that are driving the power-to-X market growth include the urgent need to mitigate climate change by reducing greenhouse gas emissions.
Some key players operating in the automation testing market include Air Liquide Engineering & Construction; Alfa Laval; Copenhagen Infrastructure Partners; ENGIE SA; ITM Power PLC; Linde plc; Mitsubishi Power; Siemens Energy; thyssenkrupp Uhde GmbH; Valmet; and Weidmüller GmbH & Co KG.
Power-to-H2 leads the technology segment with revenue share of 45.6% in 2025, While Power-to-Methanol is the fastest growing technology segment on the market.
Transportation leads the end use segment with revenue share of 39.6% in 2025.
North America is the fastest-growing region over the forecast period.
Europe dominated the power-to-X market with a share of 40.4% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


