
- Home
- »
- Clothing, Footwear & Accessories
- »
-
Pre-owned Luxury Watches Market Size Report, 2026-2033GVR Report cover
![Pre-Owned Luxury Watches Market (2026 - 2033)Report]()
Pre-Owned Luxury Watches Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Automatic, Manual), By Price Tier (Mid Luxury, High Luxury, Ultra Luxury & Collectible), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$32.3BMarket Estimate, 2026
$35.7BMarket Forecast, 2033
$85.4BCAGR, 2026–2033
13.3%Pre-Owned Luxury Watches Market Summary
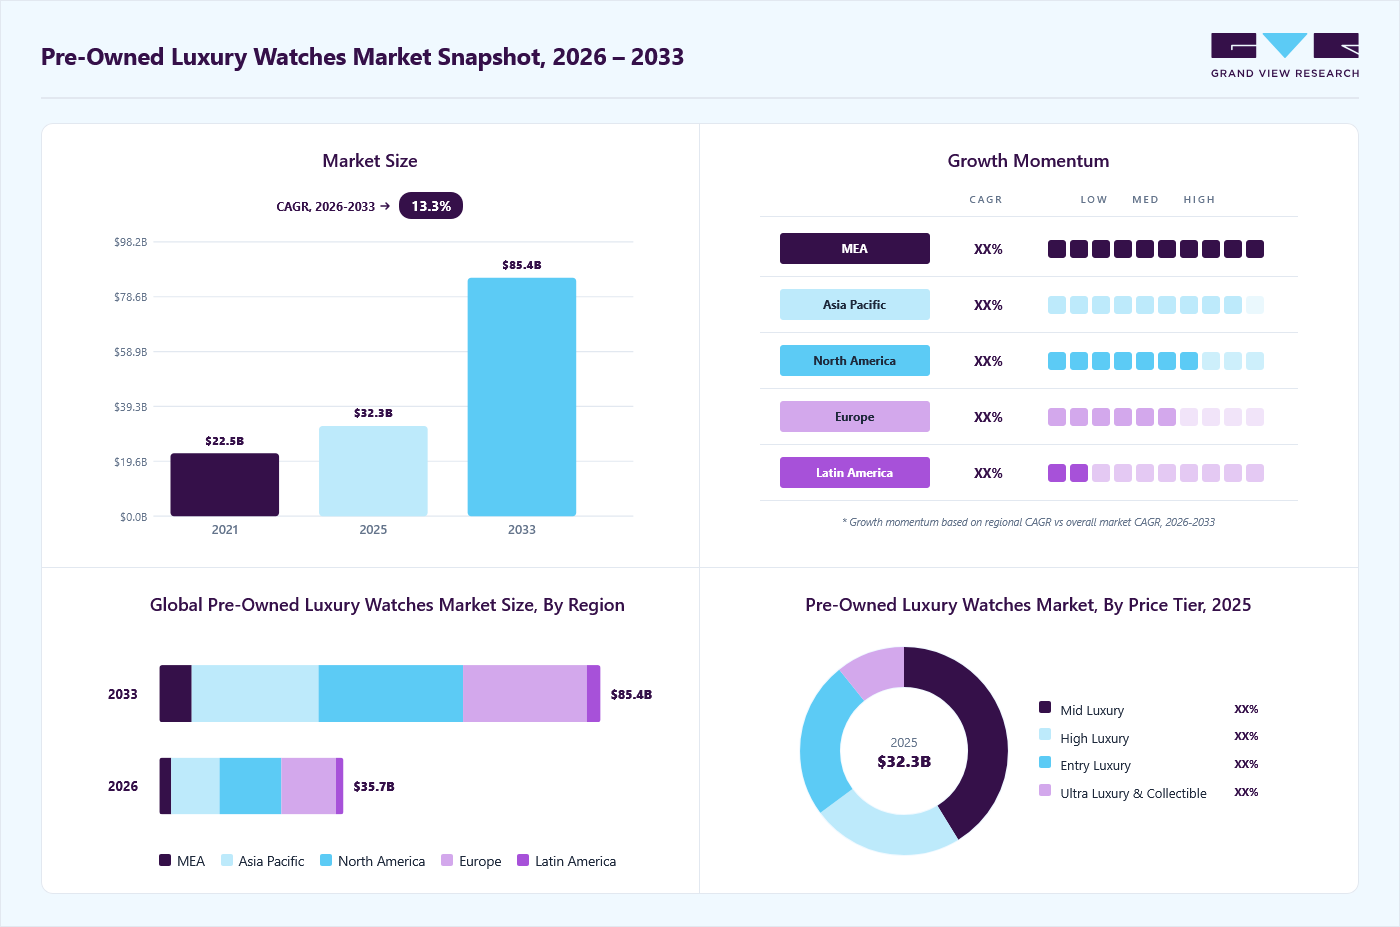
The global pre-owned luxury watches market size was valued at USD 32.3 billion in 2025 and is projected to grow from USD 35.7 billion in 2026 to USD 85.4 billion by 2033, at a CAGR of 13.3% from 2026 to 2033. North America held the largest global revenue share of 33.6% in 2025. The growth of the pre-owned luxury watches industry is driven by the growing institutionalization of the secondary watch ecosystem, supported by the expansion of certified pre-owned programs, improved authentication and verification standards, constrained availability of high-demand new luxury watches, increasing collector- and investor-driven demand, and greater resale price transparency across online marketplaces and auction platforms.
Key Market Trends & Insights
- By type: Automatic pre-owned luxury watches held the largest revenue share of 83.4% in 2025.
- By price tier: Mid luxury watches held the largest revenue share of 41.2% in 2025.
- By distribution channel: Online marketplaces held the largest market share of 39.0% in 2025.
- By price tier: Ultra luxury & collectible watches are expected to grow at the fastest CAGR of 15.4% from 2026 to 2033.
Regional Highlights
- Largest regional market: North America (33.6% revenue share, 2025)
- Fastest-growing regional market: Middle East & Africa (fastest CAGR, 2026-2033)
- By country: The U.S. led North America with a 82.9% share in 2025
Market Size & Forecast
- Market size in 2025: USD 32.3 Billion
- Estimated market size in 2026: USD 35.7 Billion
- Projected market size by 2033: USD 85.4 Billion
- CAGR (2026-2033): 13.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is witnessing robust growth as consumers increasingly view luxury timepieces as both wearable assets and long-term investments. Persistent supply constraints for highly sought-after models from brands such as Rolex, Patek Philippe, and Audemars Piguet have significantly increased demand in the secondary market, where buyers can access discontinued, limited-edition, and highly allocated references without multi-year waiting lists. For example, the Rolex Daytona, GMT-Master II, and Submariner continue to command premiums in the resale market due to limited primary market availability. Rising disposable incomes, expanding high-net-worth populations, and growing interest in collectible luxury assets are further supporting market expansion.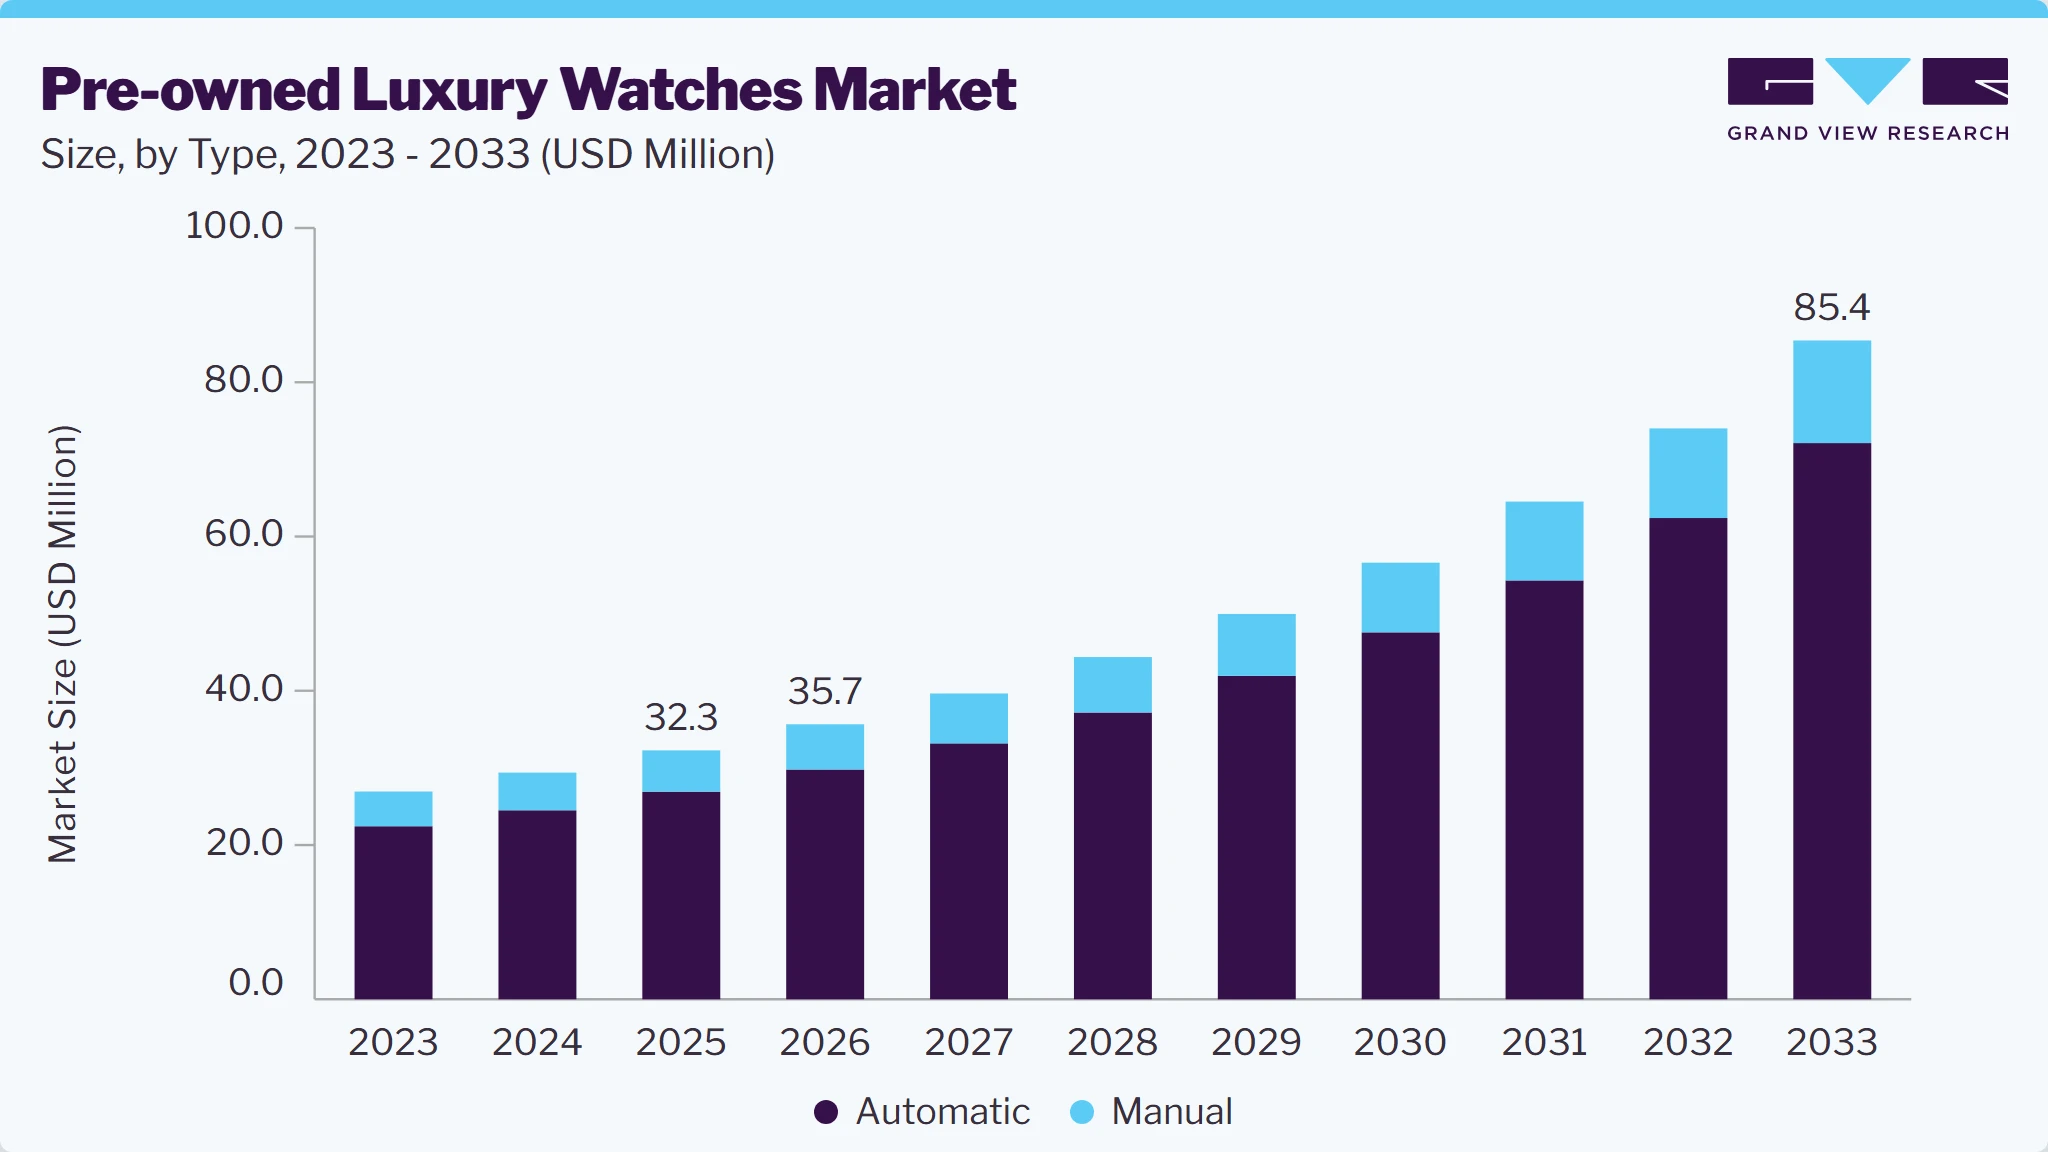
The pre-owned luxury watches market is also benefiting from the rapid institutionalization of the secondary luxury watch ecosystem. Major luxury groups and authorized retailers have significantly expanded certified pre-owned (CPO) programs to improve consumer confidence through authentication, servicing, and manufacturer-backed warranties. In 2022, Rolex launched its global Certified Pre-Owned program through its authorized dealer network, while Bucherer, Watches of Switzerland Group, and Tourneau | Bucherer have expanded dedicated CPO offerings across Europe and North America. At the same time, leading digital platforms such as Chrono24, WatchBox, and eBay's Authenticity Guarantee program have strengthened buyer confidence through escrow payment systems, independent authentication, transparent pricing, and condition grading, making cross-border transactions safer and more accessible.
Another major driver is the increasing participation of Millennials and Generation Z, who are reshaping luxury purchasing behavior by embracing circular luxury and investment-oriented consumption. According to Bain & Company, younger consumers are expected to account for more than 75% of global luxury purchases by 2030, with a growing preference for pre-owned products that combine sustainability, heritage, and long-term value retention. Social media platforms, collector communities, and auction houses such as Phillips, Sotheby's, and Christie's have further accelerated market awareness by showcasing record-breaking watch sales and educating new collectors about rarity, provenance, and investment potential. As a result, the pre-owned luxury watch market has evolved from an informal resale channel into a transparent, professionally managed global marketplace supported by luxury brands, specialized retailers, auction houses, and digital resale platforms.
Market Dynamics
The growing perception of luxury watches as alternative investment assets is a key driver of the global pre-owned luxury watches market. Increasing numbers of collectors, high-net-worth individuals, and retail investors are purchasing pre-owned luxury watches not only for their craftsmanship and exclusivity but also for their long-term value appreciation. According to the Knight Frank Luxury Investment Index, luxury watches delivered cumulative returns of approximately 125% between 2013 and 2023, making them one of the best-performing collectible asset classes.
The investment appeal is further demonstrated by the strong price appreciation of iconic models in the secondary market. For instance, the Rolex Submariner "Hulk" (Ref. 116610LV) appreciated from approximately USD 11,000 in 2020 to USD 19,000-22,000 in recent years, while the Audemars Piguet Royal Oak Jumbo Extra-Thin (Ref. 15202ST) increased from around USD 39,000 to over USD 68,000 during the same period. Growing pricing transparency through platforms such as Chrono24, WatchCharts, and specialist auction houses has further strengthened investor confidence, accelerating transaction volumes across the global pre-owned luxury watch market.
The increasing sophistication of counterfeit luxury watches remains a major restraint for the global market by undermining buyer confidence and increasing transaction complexity. Counterfeit manufacturers now produce highly engineered "superfakes" that closely replicate the design, movement, serial engravings, and packaging of premium watches from brands such as Rolex, Patek Philippe, Omega, and Audemars Piguet, making authentication significantly more challenging.
According to estimates from the OECD and EUIPO, counterfeit goods account for 3-4% of global trade, valued at approximately USD 500 billion annually, with luxury watches among the most frequently counterfeited product categories. Consequently, leading resale platforms including WatchBox, Chrono24, and Watchfinder & Co. have invested heavily in specialized authentication laboratories, certified horologists, and multi-stage verification processes to ensure product authenticity. While these measures enhance consumer trust, they also increase operational costs, extend transaction timelines, and create barriers to market scalability, particularly in cross-border and high-value transactions.
Analyst Perspective
The pre-owned luxury watches market is transitioning from an informal resale ecosystem to a professionally authenticated and investment-oriented marketplace. Consumer confidence is increasingly driven by certified pre-owned (CPO) programs, blockchain-enabled provenance, and third-party authentication, reducing counterfeit risks and supporting premium pricing. Supply remains constrained for highly sought-after references from brands such as Rolex, Patek Philippe, and Audemars Piguet, thereby sustaining secondary-market demand despite broader fluctuations in luxury spending. Digital-first marketplaces are capturing greater transaction volumes by offering transparent pricing, escrow services, and trade-in programs, while younger affluent buyers increasingly view pre-owned timepieces as both collectible assets and an accessible entry point into luxury watch ownership.
Consumer Insights
Consumer behavior in the pre-owned luxury watches market is shaped by a combination of investment motives, exclusivity, and growing acceptance of the circular luxury economy. Purchasing decisions are increasingly driven by buyers seeking iconic timepieces that offer long-term value retention, immediate availability, and access to discontinued or highly allocated models. As authentication standards improve and certified pre-owned (CPO) programs expand, consumers are becoming more comfortable purchasing high-value luxury watches through digital platforms and authorized resale channels.
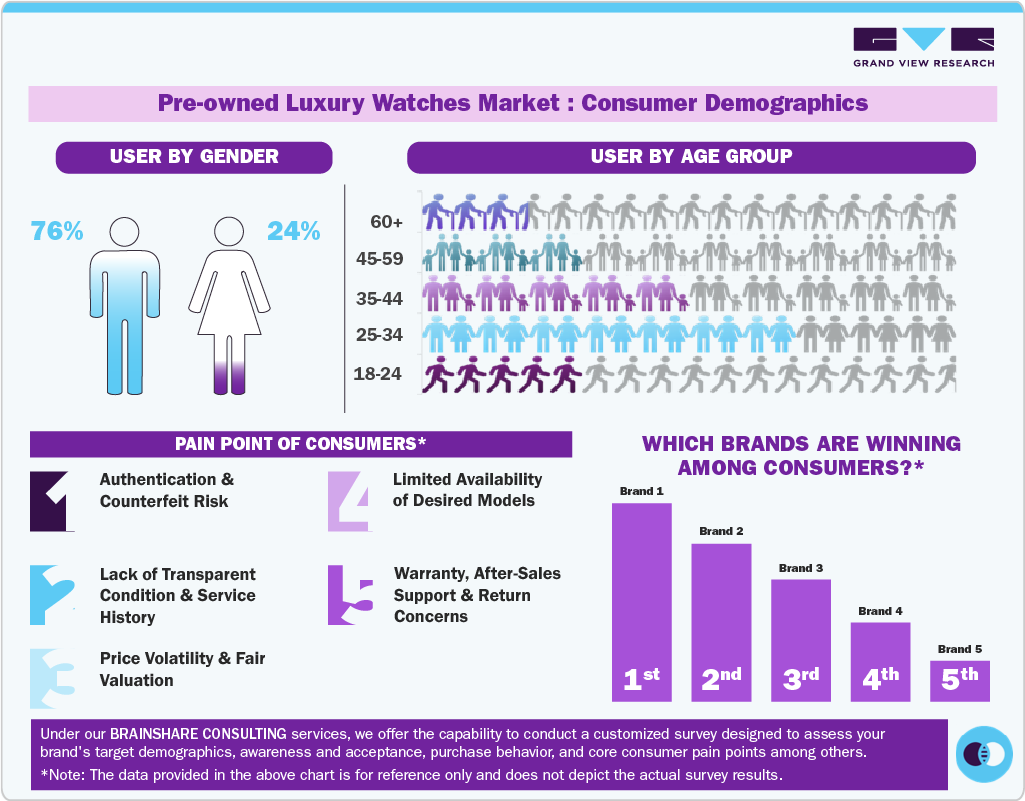
Gender-wise consumer behavior reflects a predominantly male buyer base, although female participation is steadily increasing.
-
Male consumers account for approximately 75-80% of the market, driven by strong interest in collecting, horology, alternative investments, and ownership of iconic references from brands such as Rolex, Patek Philippe, Audemars Piguet, and Omega.
-
Female consumers represent around 20-25% of the market, with demand rising for both classic luxury models and smaller case-size watches, supported by increasing financial independence, luxury spending, and growing participation in watch collecting.
-
Luxury watch ownership is also becoming more lifestyle-oriented, with younger consumers purchasing pre-owned watches for self-expression, sustainability, and wealth preservation rather than solely as status symbols.
By age group, consumers aged 25 to 34 years constitute the largest buyer segment. This demographic includes high-income professionals, entrepreneurs, executives, and experienced collectors who possess greater purchasing power and increasingly view luxury watches as investment-grade assets. Consumers aged 50 years and above continue to drive demand for rare vintage, heritage, and ultra-luxury collectible timepieces through auction houses and specialist dealers. Meanwhile, the 18-24-year age group represents the fastest-growing consumer base, driven by Millennials and Generation Z entering the luxury market through certified pre-owned platforms that offer more affordable access to premium brands and align with sustainability and circular consumption trends.
Consumers in the pre-owned luxury watches market commonly face several challenges throughout the purchasing journey.
-
Authenticity concerns remain the primary pain point, particularly due to the growing sophistication of counterfeit luxury watches.
-
Limited transparency regarding service history, replaced components, and watch condition often creates uncertainty about long-term value and reliability.
-
Price volatility for highly sought-after references makes it difficult for buyers to determine fair market value, while the limited availability of iconic models frequently results in significant resale premiums.
- Buyers also seek stronger warranty coverage, after-sales service, and return policies, particularly for high-value transactions conducted online.
In response to these concerns, purchasing behavior is shifting toward trusted and professionally managed resale ecosystems. Consumers increasingly prefer Certified Pre-Owned (CPO) programs, authenticated online marketplaces, and specialist retailers that provide manufacturer-backed warranties, detailed inspection reports, escrow payment systems, and transparent pricing. Digital platforms such as Chrono24, WatchBox, Watchfinder & Co., and Bob's Watches, along with AI-enabled authentication technologies and real-time market price tracking tools, are improving buyer confidence and making online purchases of pre-owned luxury watches more secure, transparent, and convenient.
Type Insights
Automatic pre-owned luxury watches accounted for the largest revenue share of 83.4% in 2025. The segment's leadership is driven by strong consumer preference for mechanical craftsmanship, heritage, and long-term value retention. Automatic timepieces from brands such as Rolex, Patek Philippe, Audemars Piguet, Omega, and Vacheron Constantin consistently command higher resale values than quartz counterparts due to their collectability and investment appeal. According to the Federation of the Swiss Watch Industry (FH), mechanical watches account for the overwhelming majority of the value of Swiss watch exports despite representing a smaller share of shipment volumes, reflecting their premium positioning and strong secondary-market demand. The expansion of Certified Pre-Owned (CPO) programs by Rolex, Watches of Switzerland Group, and Bucherer has further strengthened buyer confidence in high-value automatic watches.
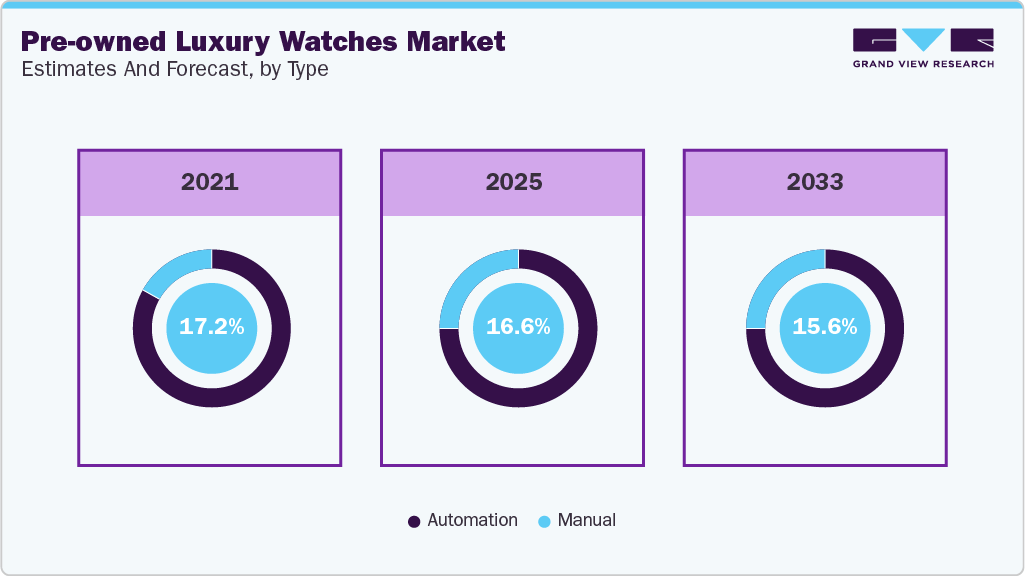
The automatic watches segment is expected to grow at the fastest CAGR of 13.5% from 2026 to 2033. The growth is supported by increasing collector participation, rising demand for discontinued references, and the continued perception of mechanical luxury watches as alternative investment assets. The growing popularity of auction houses such as Phillips, Sotheby's, and Christie's, together with digital platforms including Chrono24 and WatchBox, is expected to further enhance liquidity and global demand for investment-grade automatic watches.
Price Tier Insights
Mid luxury pre-owned luxury watches dominated the market, accounting for the largest revenue share of 41.2% in 2025. The segment's dominance is supported by its broad consumer base and strong availability of premium watches priced within an accessible luxury range. Brands such as Omega, Tudor, Breitling, Cartier, TAG Heuer, and select Rolex references dominate this category, attracting both first-time luxury watch buyers and experienced collectors. The segment benefits from a balanced combination of affordability, brand heritage, and resale value, making it the most actively traded category across online marketplaces and specialist retailers. The growing availability of financing options and certified pre-owned inventory has further expanded the addressable customer base for mid-luxury watches.
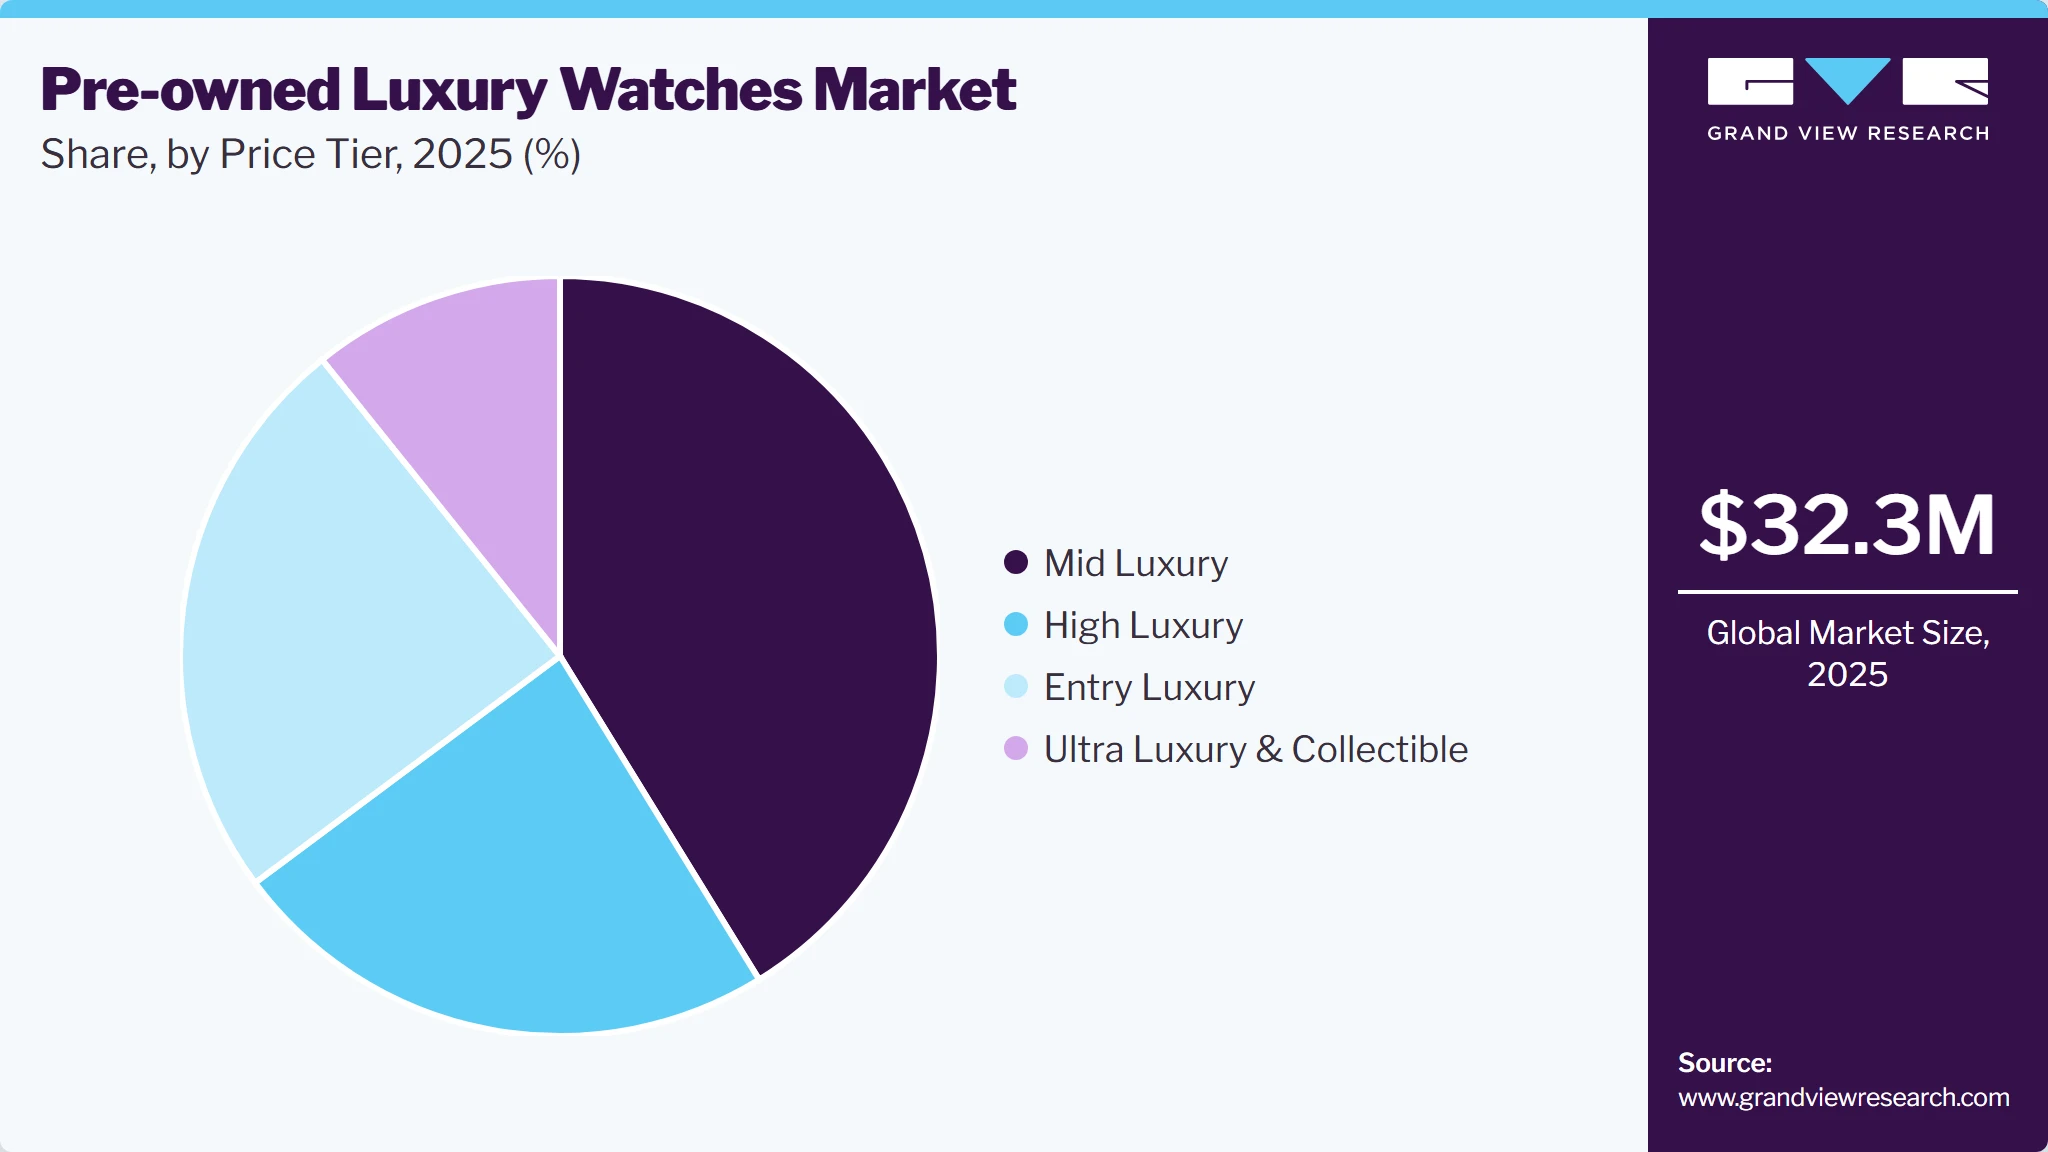
The demand for ultra-luxury & collectible watches is projected to be the fastest-growing price tier, expanding at a 15.4% CAGR from 2026 to 2033. Rising wealth creation, a growing number of high-net-worth individuals, and increasing investor interest in rare and limited-production watches are driving demand for brands such as Patek Philippe, Audemars Piguet, Richard Mille, and F.P. Journe. Record-breaking auction results and continued appreciation of iconic references have reinforced the investment appeal of this segment, encouraging greater participation from collectors and alternative asset investors worldwide.
Distribution Channel Insights
Online marketplaces dominated the pre-owned luxury watches industry, accounting for the largest revenue share of 39.0% in 2025. The segment's leadership is driven by expanding digital adoption, global inventory access, and greater pricing transparency. Platforms such as Chrono24, WatchBox, Bob's Watches, eBay, and Watchfinder & Co. enable buyers to compare prices across thousands of listings while providing authentication services, escrow payment systems, and international shipping. The availability of real-time market data, historical price tracking, and verified seller networks has significantly improved consumer confidence and accelerated online transaction volumes across both established and emerging luxury markets.
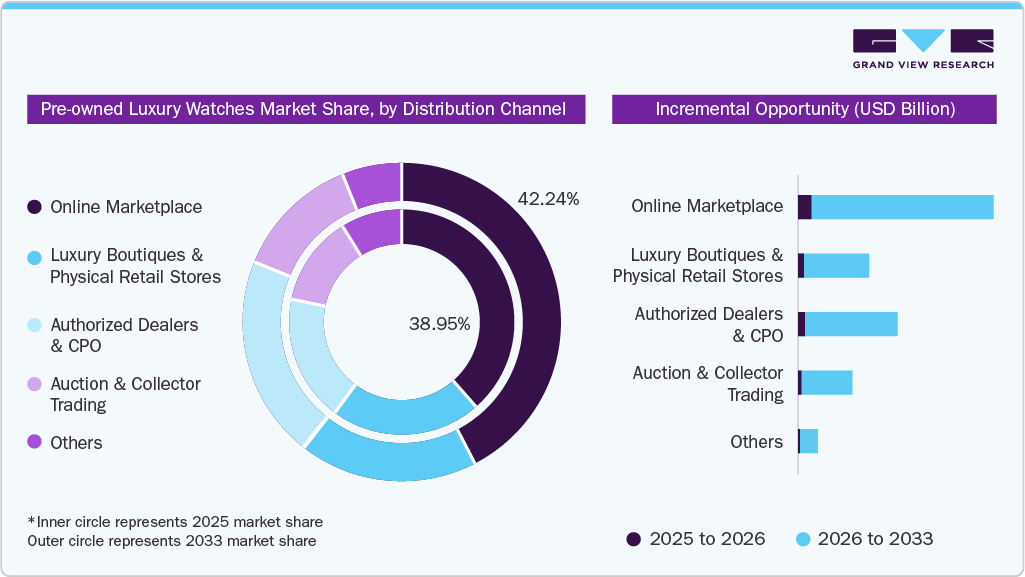
The authorized dealers & Certified Pre-Owned (CPO) segment is expected to grow at the fastest CAGR of 15.0% from 2026 to 2033, driven by increasing consumer preference for manufacturer-backed authenticity, professional servicing, and extended warranties when purchasing high-value luxury watches. Rolex's global Certified Pre-Owned program, along with the expansion of CPO offerings by Bucherer, Watches of Switzerland Group, and Richemont-owned Watchfinder & Co., has strengthened trust in the secondary market while attracting buyers who previously preferred purchasing new watches. As luxury brands continue integrating resale into their long-term distribution strategies, authorized CPO channels are expected to capture a growing share of premium secondary-market transactions.
Regional Insights
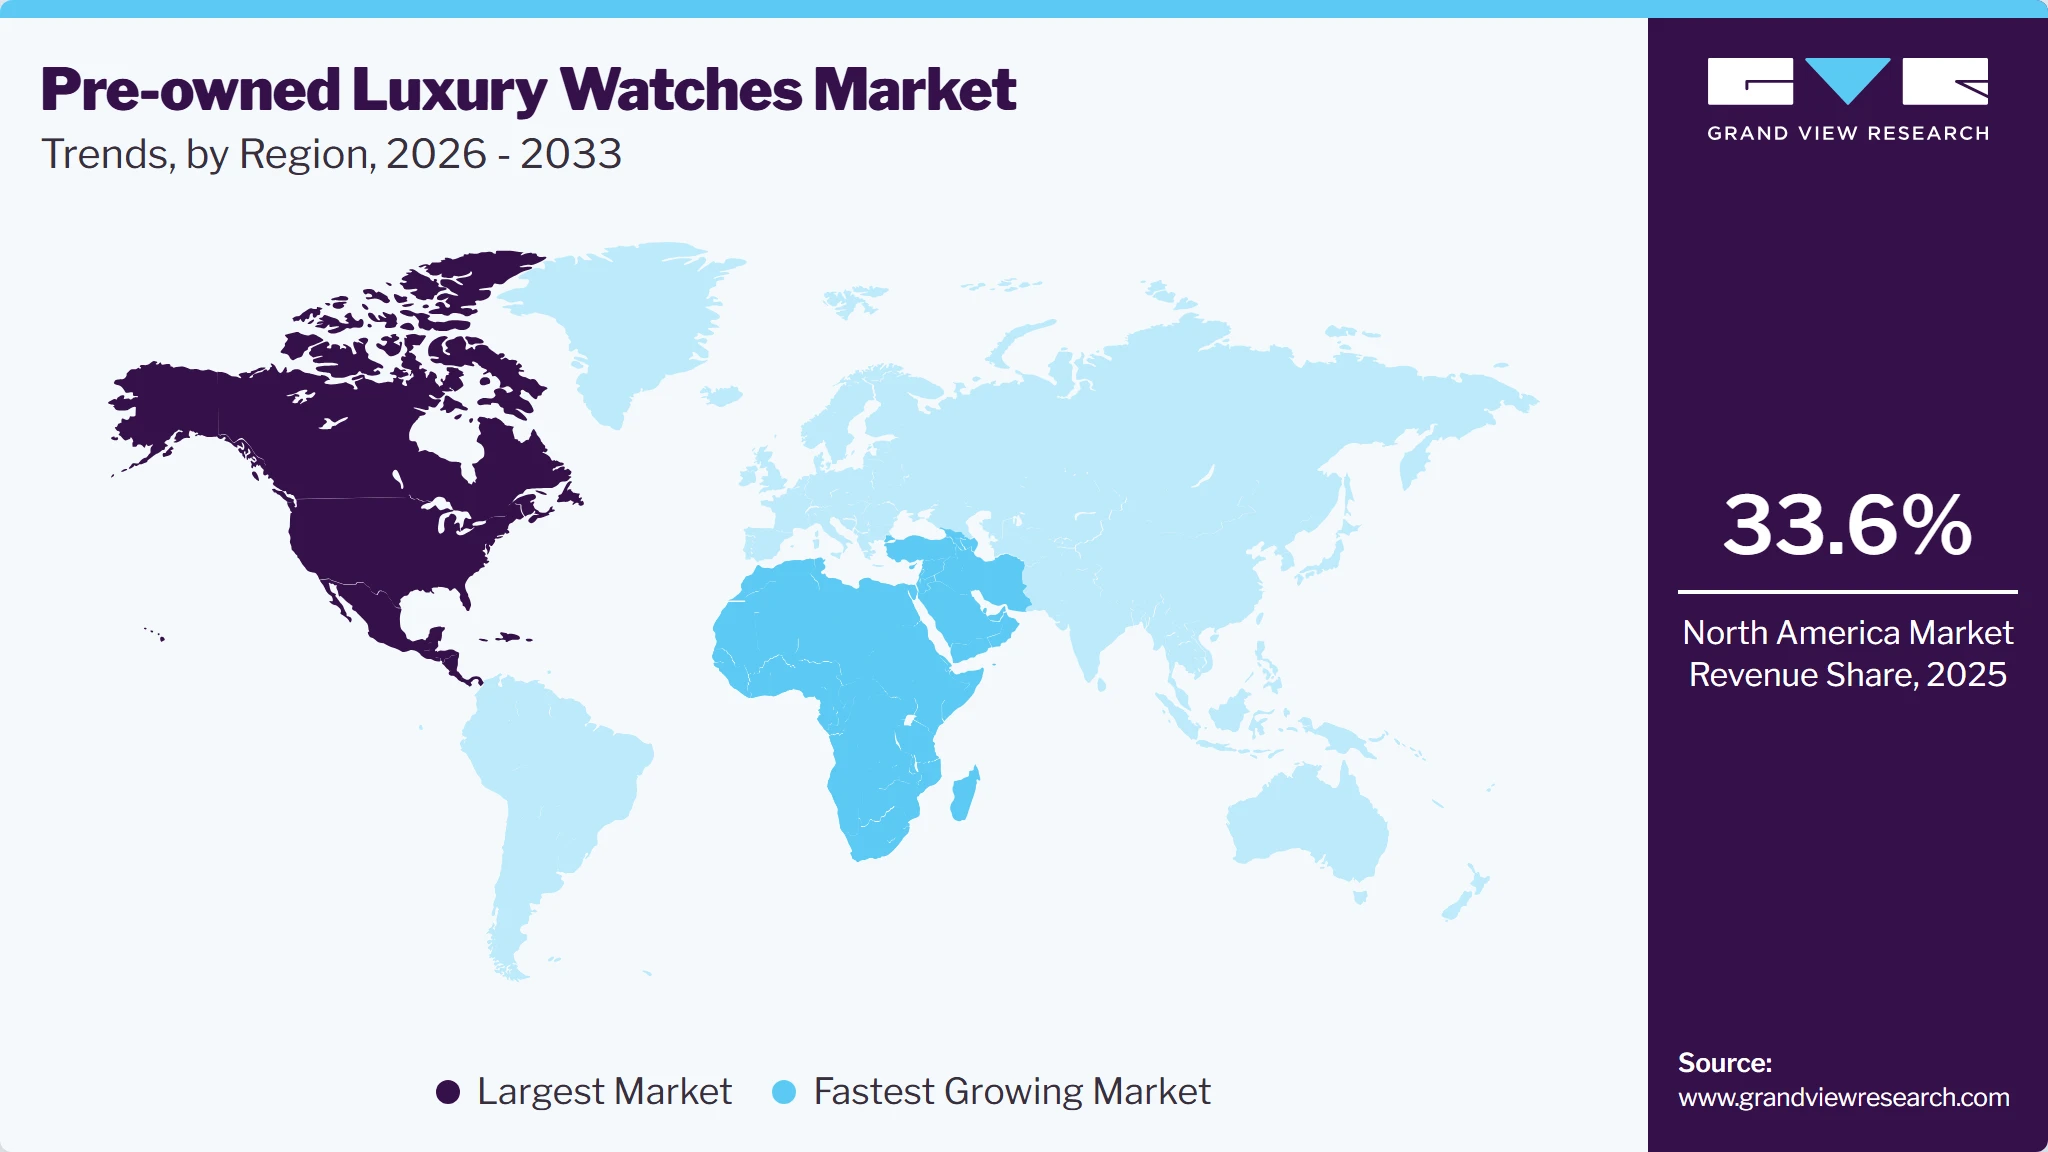
The North America pre-owned luxury watches market accounted for the largest revenue share of 33.6% in 2025, driven by a mature collector ecosystem, high disposable incomes, and strong consumer acceptance of certified pre-owned (CPO) luxury goods. The region benefits from the presence of leading resale platforms such as Chrono24, WatchBox, Bob's Watches, and Tourneau | Bucherer, alongside expanding manufacturer-backed CPO programs from Rolex and other luxury brands. Strong investment demand for collectible timepieces and well-established authentication infrastructure continue to support market leadership.
U.S. Pre-Owned Luxury Watches Market Trends
The U.S. pre-owned luxury watches industry dominated North America with an 82.9% revenue share in 2025, supported by its large base of luxury consumers, developed resale infrastructure, and strong demand for collectible Swiss timepieces. The country is home to leading resale platforms, including WatchBox and Bob's Watches, while auction houses such as Sotheby's and Phillips continue to record robust demand for rare and investment-grade watches. Growing participation from younger affluent consumers and increasing online luxury transactions are expected to sustain market expansion.
The Canada pre-owned luxury watches market is projected to grow at a CAGR of 11.9% from 2026 to 2033, driven by rising luxury spending, growing adoption of authenticated online resale platforms, and increasing consumer interest in sustainable luxury consumption. Expanding access to international luxury marketplaces and higher awareness of certified pre-owned offerings are expected to support long-term market growth.
Middle East & Africa Pre-Owned Luxury Watches Market Trends
The Middle East & Africa pre-owned luxury watches industry is projected to grow at the fastest CAGR of 15.4% from 2026 to 2033, driven by expanding luxury retail infrastructure, increasing numbers of ultra-high-net-worth individuals, and rising demand for collectible timepieces across the Gulf region. The expansion of luxury shopping destinations, international watch exhibitions, and premium resale channels is further strengthening regional market growth.
The Saudi Arabia pre-owned luxury watches market is expected to register the fastest CAGR of 19.2% from 2026 to 2033, supported by rapid wealth creation, strong luxury consumption, and continued economic diversification under Vision 2030. Growing investments in luxury retail, tourism, and premium lifestyle sectors are increasing demand for authenticated pre-owned luxury watches.
The pre-owned luxury watches market in the UAE led Middle East & Africa held the largest revenue sahre of 44.9% in 2025, driven by Dubai's position as a global luxury shopping destination, a high concentration of affluent consumers, and a vibrant international collector community. The presence of leading luxury retailers, auction houses, and premium watch boutiques continues to support strong secondary-market activity.
Europe Pre-Owned Luxury Watches Market Trends
The Europe pre-owned luxury watches industry is expected to grow at a CAGR of 12.4% from 2026 to 2033, supported by the region's deep-rooted luxury watch culture, established collector community, and strong presence of premium retailers and auction houses. Europe also benefits from the expansion of manufacturer-backed resale programs and increasing demand for vintage and heritage timepieces among both domestic and international buyers.
The Germany pre-owned luxury watches market accounted for a 16.8% share of the European market in 2025, driven by strong purchasing power, growing interest in investment-grade watches, and an expanding network of luxury retailers and specialist dealers. Increasing online transactions and demand for authenticated collectible watches continue to support market growth.
The pre-owned luxury watches market in the UK accounted for the largest share in Europe at 19.9% in 2025, supported by London's position as one of the world's leading luxury trading hubs. Strong auction activity, established secondary-market dealers, and rising demand for scarce Swiss watches continue to drive transaction volumes across the country.
The France pre-owned luxury watches market is projected to grow at a CAGR of 12.8% from 2026 to 2033, supported by increasing luxury consumption, strong appreciation for heritage watchmaking, and expanding participation in authenticated resale channels. Paris remains one of Europe's major luxury retail destinations, contributing significantly to demand for premium pre-owned timepieces.
Asia Pacific Pre-Owned Luxury Watches Market Trends
The Asia Pacific pre-owned luxury watches industry is projected to grow at a rapid CAGR of 14.8% from 2026 to 2033, driven by rapid wealth creation, expanding high-net-worth populations, increasing digital adoption, and growing acceptance of the circular luxury economy. Rising demand from younger collectors and continued expansion of online luxury marketplaces across the region are further accelerating secondary-market growth.
The China pre-owned luxury watches market led Asia Pacific, accounting for the largest revenue share of 29.6% in 2025, supported by the country's large affluent consumer base and strong demand for premium Swiss watches. Growing participation in luxury resale, increasing collector activity, and improving authentication infrastructure continue to strengthen China's position as the region's largest market.
The pre-owned luxury watches market in India is expected to grow at the fastest CAGR of 17.8% from 2026 to 2033, driven by rapid growth in the number of high-net-worth individuals, rising luxury awareness among younger consumers, and the expanding adoption of online luxury resale platforms. Rising disposable incomes, greater acceptance of certified pre-owned products, and increasing demand for entry-level luxury watches are expected to accelerate market growth throughout the forecast period.
Central & South America Pre-Owned Luxury Watches Market Trends
The Central & South America pre-owned luxury watches industry is expected to grow at a CAGR of 9.1% from 2026 to 2033, supported by the gradual expansion of luxury consumption, the growth of digital commerce, and increasing access to international resale platforms. Although the region accounts for a relatively small share of the global market, rising affluent populations and growing awareness of certified pre-owned luxury goods continue to create long-term growth opportunities.
The Brazil pre-owned luxury watches market accounted for 64.1% of Central & South America in 2025, driven by the country's large luxury consumer base, expanding premium retail sector, and growing adoption of authenticated online resale platforms. Increasing collector participation and improving access to international luxury marketplaces continue to strengthen Brazil's leadership within the region.
Key Pre-Owned Luxury Watches Company Insights
The global pre-owned luxury watches market is characterized by a fragmented competitive landscape comprising digital resale marketplaces, certified pre-owned (CPO) retailers, auction houses, luxury watch dealers, and manufacturer-backed resale programs. Competition is increasingly centered on authentication capabilities, inventory breadth, global sourcing networks, pricing transparency, and after-sales services as companies seek to strengthen consumer trust in high-value secondary-market transactions.
-
Online Marketplaces & Digital Resale Platforms: Companies such as Chrono24, WatchCharts, eBay, and Chrono Hunter have established themselves as major digital platforms by connecting buyers and sellers across global markets. These companies compete through extensive inventory, real-time pricing transparency, secure payment systems, authentication services, and international logistics. Continuous investments in AI-powered pricing tools, digital verification technologies, and user experience have further accelerated online adoption.
-
Certified Pre-Owned Retailers & Luxury Watch Specialists: Companies including WatchBox, Watchfinder & Co., Bob's Watches, Bucherer, and Watches of Switzerland Group dominate the professionally authenticated resale segment. These firms differentiate themselves through rigorous inspection processes, certified authenticity, refurbishment services, extended warranties, financing options, and strong after-sales support. Their vertically integrated business models have significantly increased buyer confidence, particularly for high-value investment-grade timepieces.
-
Auction Houses & Collector-focused Platforms: Leading auction houses such as Phillips Watches, Sotheby's, Christie's, and Antiquorum specialize in rare, vintage, and collectible luxury watches. These companies cater primarily to collectors and high-net-worth individuals seeking limited-production, discontinued, or historically significant references. Record-breaking auction sales and increasing participation from global investors continue to reinforce the role of auction houses in establishing benchmark pricing and market liquidity for investment-grade watches.
-
Luxury Watch Brands & Manufacturer-backed Certified Programs: Luxury watch manufacturers are becoming increasingly active participants in the secondary market through official Certified Pre-Owned initiatives. Rolex, in partnership with Bucherer and Watches of Switzerland Group, has expanded its global Certified Pre-Owned program, while Richemont, through Watchfinder & Co., continues to strengthen manufacturer-supported resale operations. These initiatives enhance consumer trust by offering factory-approved authentication, servicing by certified watchmakers, and manufacturer-backed warranties, further legitimizing the pre-owned luxury watch market as a mainstream luxury retail channel.
Key Pre-Owned Luxury Watches Companies
The following key companies have been profiled for this study of the pre-owned luxury watches market.
-
Chrono24
-
The 1916 Company
-
eBay Inc.
-
Bob’s Watches
-
Bezel, Inc.
-
Watchfinder & Co
-
TrueFacet, LLC
-
The RealReal, Inc.
-
The Watch Club
-
Watches of Switzerland
Recent Developments
-
In May 2026, The 1916 Company launched the second edition of its "Coast to Coast Roadshow," showcasing more than 200 Rolex Certified Pre-Owned timepieces across multiple U.S. cities, expanding consumer access to authenticated luxury watches and strengthening engagement with collectors.
-
In May 2026, Watches of Switzerland launched a dedicated online luxury boutique, enabling customers to browse and purchase premium timepieces through a digital platform while combining the convenience of e-commerce with the trust of an authorized luxury watch retailer.
-
In May 2026, eBay Inc. partnered with Enquirus, the global database for lost and stolen watches, to integrate provenance verification into its authentication process, enhancing buyer confidence, transaction security, and transparency across its pre-owned luxury watch marketplace.
-
In April 2026, Watches of Switzerland Group opened its first Rolex-anchored showroom in the American Midwest with a new multi-brand boutique at Southdale Center in Edina, Minnesota, reinforcing the company's U.S. expansion strategy and enhancing its presence in the luxury watch retail market.
-
In March 2026, The RealReal Inc. partnered with Motorola Solutions to deploy AI-enabled video security technology across its luxury resale operations, improving inventory tracking, asset protection, and operational efficiency while strengthening the authentication and management of high-value luxury goods.
Pre-Owned Luxury Watches Market Report Scope
Report Attribute
Details
Market size in 2025
USD 32.3 billion
Estimated market size in 2026
USD 35.7 billion
Projected market size by 2033
USD 85.4 billion
Growth rate
CAGR of 13.3% from 2026 to 2033
Base year
2025
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, price tier, distribution channel, and region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Switzerland; China; Japan; India; South Korea; Australia & New Zealand; Singapore; Brazil; UAE; South Africa; Saudi Arabia
Key companies profiled
Chrono24; The 1916 Company; eBay Inc.; Bob's Watches; Bezel, Inc.; Watchfinder & Co.; TrueFacet, LLC; The RealReal, Inc.; The Watch Club; Watches of Switzerland Group
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pre-owned Luxury Watches Market Report Segmentation
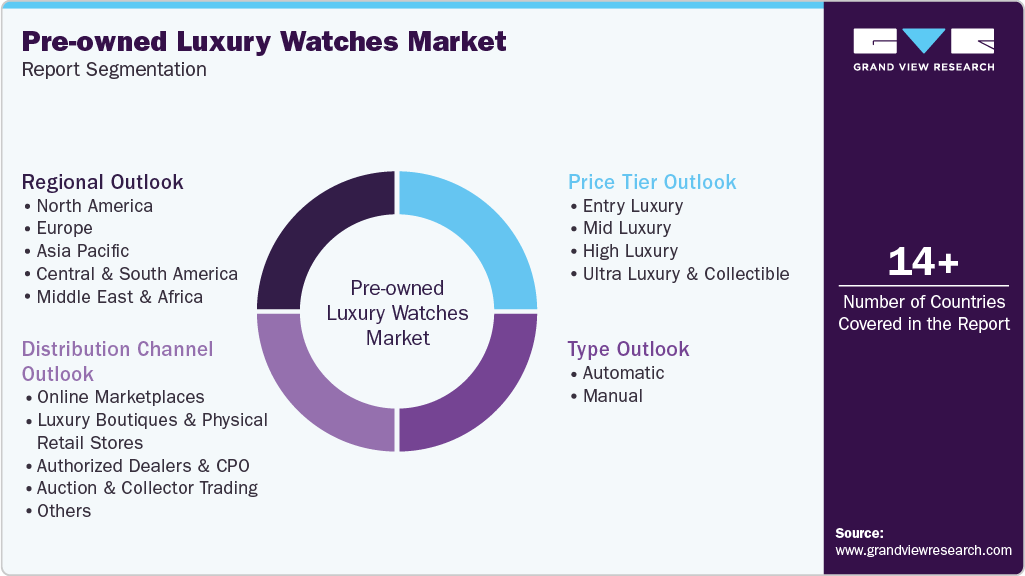
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2026 to 2033. For this study, Grand View Research has segmented the pre-owned luxury watches market report based on type, price tier, distribution channel, and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Automatic
-
Manual
-
-
Price Tier Outlook (Revenue, USD Billion, 2021 - 2033)
-
Entry Luxury
-
Mid Luxury
-
High Luxury
-
Ultra Luxury & Collectible
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Online Marketplaces
-
Luxury Boutiques & Physical Retail Stores
-
Authorized Dealers & CPO
-
Auction & Collector Trading
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Switzerland
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia & New Zealand
-
Singapore
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
United Arab Emirates (UAE)
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The pre-owned luxury watches market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pre-owned luxury watches segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Automatic
Covers pre-owned luxury watches powered by self-winding mechanical movements that operate through wrist motion. The scope includes sports, dress, dive, pilot, GMT, and complication models from premium watchmakers, along with certified and non-certified used watches traded across online and offline resale channels.
Manual
Covers pre-owned luxury watches equipped with hand-wound mechanical movements requiring manual winding for operation. The scope includes vintage, heritage-inspired, dress, chronograph, and limited-edition models offered through auctions, collectors, authorized resale programs, boutiques, and digital marketplaces within the secondary luxury watch ecosystem.
Segment - Price tier
Revenue capture definition
Entry Luxury
Covers pre-owned luxury watches positioned within the accessible premium price bracket, including entry-level collections from established Swiss, Japanese, and German luxury brands. The scope includes mechanical and quartz models, certified and non-certified offerings, and transactions across online platforms, dealers, boutiques, and secondary retail stores.
Mid Luxury
Covers pre-owned luxury watches positioned in the mid-premium segment, featuring higher-grade mechanical craftsmanship, advanced movements, and established luxury collections. The scope includes sports, dress, and professional watches traded through certified pre-owned programs, luxury retailers, online marketplaces, auction houses, and independent watch dealers.
High Luxury
Covers pre-owned luxury watches representing premium flagship collections with sophisticated complications, precious materials, and superior craftsmanship. The scope includes certified pre-owned inventory, limited-production references, iconic luxury models, and resale transactions conducted through specialist boutiques, authorized dealers, collectors, auctions, and digital platforms.
Ultra Luxury & Collectible
Covers pre-owned ultra-premium luxury watches comprising rare, limited-edition, discontinued, vintage, and investment-grade timepieces. The scope includes independent watchmakers, prestigious haute horlogerie brands, historically significant references, collectible complications, and high-value transactions facilitated through auction houses, specialist collectors, private sales, and exclusive retailers.
Segment - Distribution Channel
Revenue capture definition
Online Marketplaces
Covers digital platforms facilitating the buying and selling of pre-owned luxury watches through direct listings, managed marketplaces, and authenticated resale services. The scope includes certified and non-certified inventory, cross-border transactions, pricing tools, escrow services, authentication, shipping, and digital customer engagement.
Luxury Boutiques & Physical Retail Stores
Covers brick-and-mortar luxury retailers and specialist boutiques offering pre-owned luxury watches through curated showroom experiences. The scope includes authenticated inventory, trade-in services, inspections, servicing, warranty support, customer consultations, and sales of premium second-hand watches across organized physical retail networks.
Authorized Dealers & CPO
Covers authorized luxury watch retailers and manufacturer-backed Certified Pre-Owned (CPO) programs offering inspected and authenticated pre-owned watches. The scope includes refurbishment, servicing, certification, official warranties, provenance verification, and resale of eligible timepieces meeting brand-established quality and authenticity standards.
Auction & Collector Trading
Covers pre-owned luxury watch transactions conducted through auction houses, private collector networks, watch fairs, and specialist trading platforms. The scope includes vintage, rare, collectible, and investment-grade timepieces, along with bidding processes, provenance documentation, valuation, authentication, and private high-value secondary market transactions.
Others
Covers additional pre-owned luxury watch sales channels not classified under primary distribution categories, including pawn retailers, estate sales, consignment stores, peer-to-peer transactions, social commerce, and regional independent resellers. The scope also includes niche resale formats serving localized and specialized secondary market demand.
Estimation Model
Layer Name
Key Question
Description
Luxury Watch Ownership Base Layer
Who owns or aspires to own luxury watches?
Begin with the global base of luxury watch owners and high-potential buyers, including HNWIs, affluent consumers, collectors, professionals, and luxury enthusiasts. Apply luxury watch ownership rates, Swiss watch exports, and luxury consumer demographics to estimate the population participating in the luxury watch ecosystem.
Secondary Market Accessibility Layer
Who has access to authenticated pre-owned luxury watches?
Filter the eligible consumer base using penetration of authenticated resale platforms, certified pre-owned (CPO) programs, luxury boutiques, auction houses, and digital marketplaces. Account for internet penetration, luxury retail infrastructure, and regional acceptance of pre-owned luxury goods to derive the addressable market.
Pre-owned Purchase & Trading Layer
Who actively purchases pre-owned luxury watches?
Apply adoption rates among first-time luxury buyers, collectors, investors, and repeat purchasers. Consider factors such as brand scarcity, long retail waitlists, investment appeal, sustainability preferences, and authentication services to estimate active buyers participating in the secondary luxury watch market.
Monetisation Layer
How much revenue is generated?
Multiply annual transaction volume by blended average selling prices across Automatic and Manual watches and across Entry Luxury, Mid Luxury, High Luxury, and Ultra Luxury & Collectible price tiers. Include revenue generated through online marketplaces, certified pre-owned dealers, auction commissions, authentication, servicing, and refurbishment services to estimate total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Brand & Reference-Level Demand Analysis Across Price Tiers and Regions
Comprehensive analysis of the pre-owned luxury watch market by benchmarking demand across leading brands (Rolex, Patek Philippe, Audemars Piguet, Omega, Cartier, Richard Mille, etc.) and their most actively traded references. The study maps brand performance across Entry Luxury, Mid Luxury, High Luxury, and Ultra Luxury & Collectible segments while evaluating regional demand variations across North America, Europe, Asia Pacific, the Middle East, and other key markets.
Helps identify which brands and collections demonstrate the strongest liquidity, resale demand, and collector interest across different price tiers and geographies. The analysis supports inventory planning, pricing strategy, and market-entry decisions by highlighting where investment-grade watches outperform aspirational luxury models.
Resale Value Retention & Investment Performance Benchmarking
Detailed assessment of historical resale performance across major luxury watch brands and collections, including value retention, appreciation/depreciation trends, rarity premiums, production scarcity, and collector demand. The study evaluates factors influencing secondary market pricing, including limited editions, discontinued references, provenance, condition grading, and authentication standards.
Enables investors, dealers, and luxury platforms to distinguish collectible assets from depreciation-driven products. It identifies watches with stronger long-term appreciation potential and provides insight into how scarcity, brand heritage, and certified authenticity influence resale performance.
Distribution Channel & Authentication Ecosystem Analysis
Comprehensive evaluation of online marketplaces, luxury boutiques, authorized Certified Pre-Owned (CPO) programs, auction houses, collector trading platforms, and independent dealers. The assessment compares channel performance based on pricing transparency, authentication processes, buyer confidence, inventory availability, cross-border transactions, and digital platform adoption.
Identifies how authenticated digital marketplaces and brand-backed CPO programs are reshaping the competitive landscape. The analysis helps stakeholders determine the most effective sales channels while highlighting the growing importance of authentication, warranty services, provenance verification, and trust in driving premium valuations.
Frequently Asked Questions About This Report
North America dominated the market with a 33.6% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period, expanding at a CAGR of 14.8% from 2026 to 2033.
The Mid Luxury segment held the largest revenue share of 41.2% in 2025, while the Ultra Luxury & Collectible segment is expected to witness the fastest growth during the forecast period.
Online Marketplaces held the largest share (39.0%) in 2025 and are expected to remain the dominant distribution channel throughout the forecast period, while Authorized Dealers & Certified Pre-Owned (CPO) is projected to be the fastest-growing channel.
The Automatic watches segment led the market with an 83.4% revenue share in 2025, while the Manual watches segment is expected to witness steady growth during the forecast period.
Key players include Rolex, Patek Philippe, Audemars Piguet, Omega SA, Cartier, Breitling SA, TAG Heuer, Richard Mille, Chrono24 GmbH, WatchBox, The RealReal, Bob's Watches, Crown & Caliber, Watchfinder & Co., and eBay Inc.
Key factors include increasing consumer acceptance of certified pre-owned luxury goods, rising investment demand for collectible watches, rapid growth of online resale platforms, advancements in authentication and certification services, increasing focus on sustainable luxury consumption, and strong demand for iconic heritage watch brands.
The global pre-owned luxury watches market size was valued at USD 32.3 billion in 2025 and is estimated at USD 35.7billion in 2026.
The global pre-owned luxury watches market is expected to grow at a CAGR of 13.3% from 2026 to 2033, reaching USD 85.4 billion by 2033.
About the Author(s)
Clothing, Footwear & Accessories Research Team
Consumer Goods · Clothing, Footwear & AccessoriesThis report was authored by the clothing, footwear & accessories research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clothing, footwear & accessories segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


