
- Home
- »
- Backup Power Solutions
- »
-
PV Inverter Market Size & Share Report, 2026-2033GVR Report cover

PV Inverter Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (String PV Inverter, Central PV Inverter), By End-use (Commercial & Industrial, Utilities, Residential), By Region, And Segment Forecasts
Market Size, 2025
$17.6BMarket Estimate, 2026
$20.6BMarket Forecast, 2033
$49.6BCAGR, 2026–2033
13.4%PV Inverter Market Summary
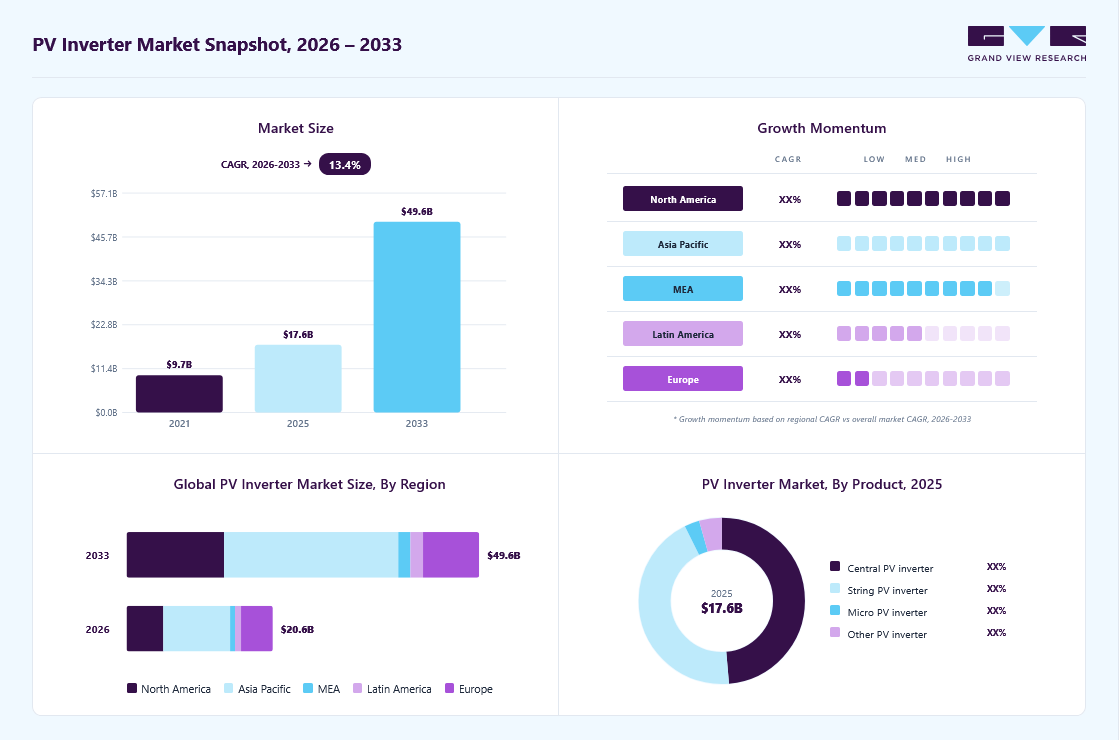
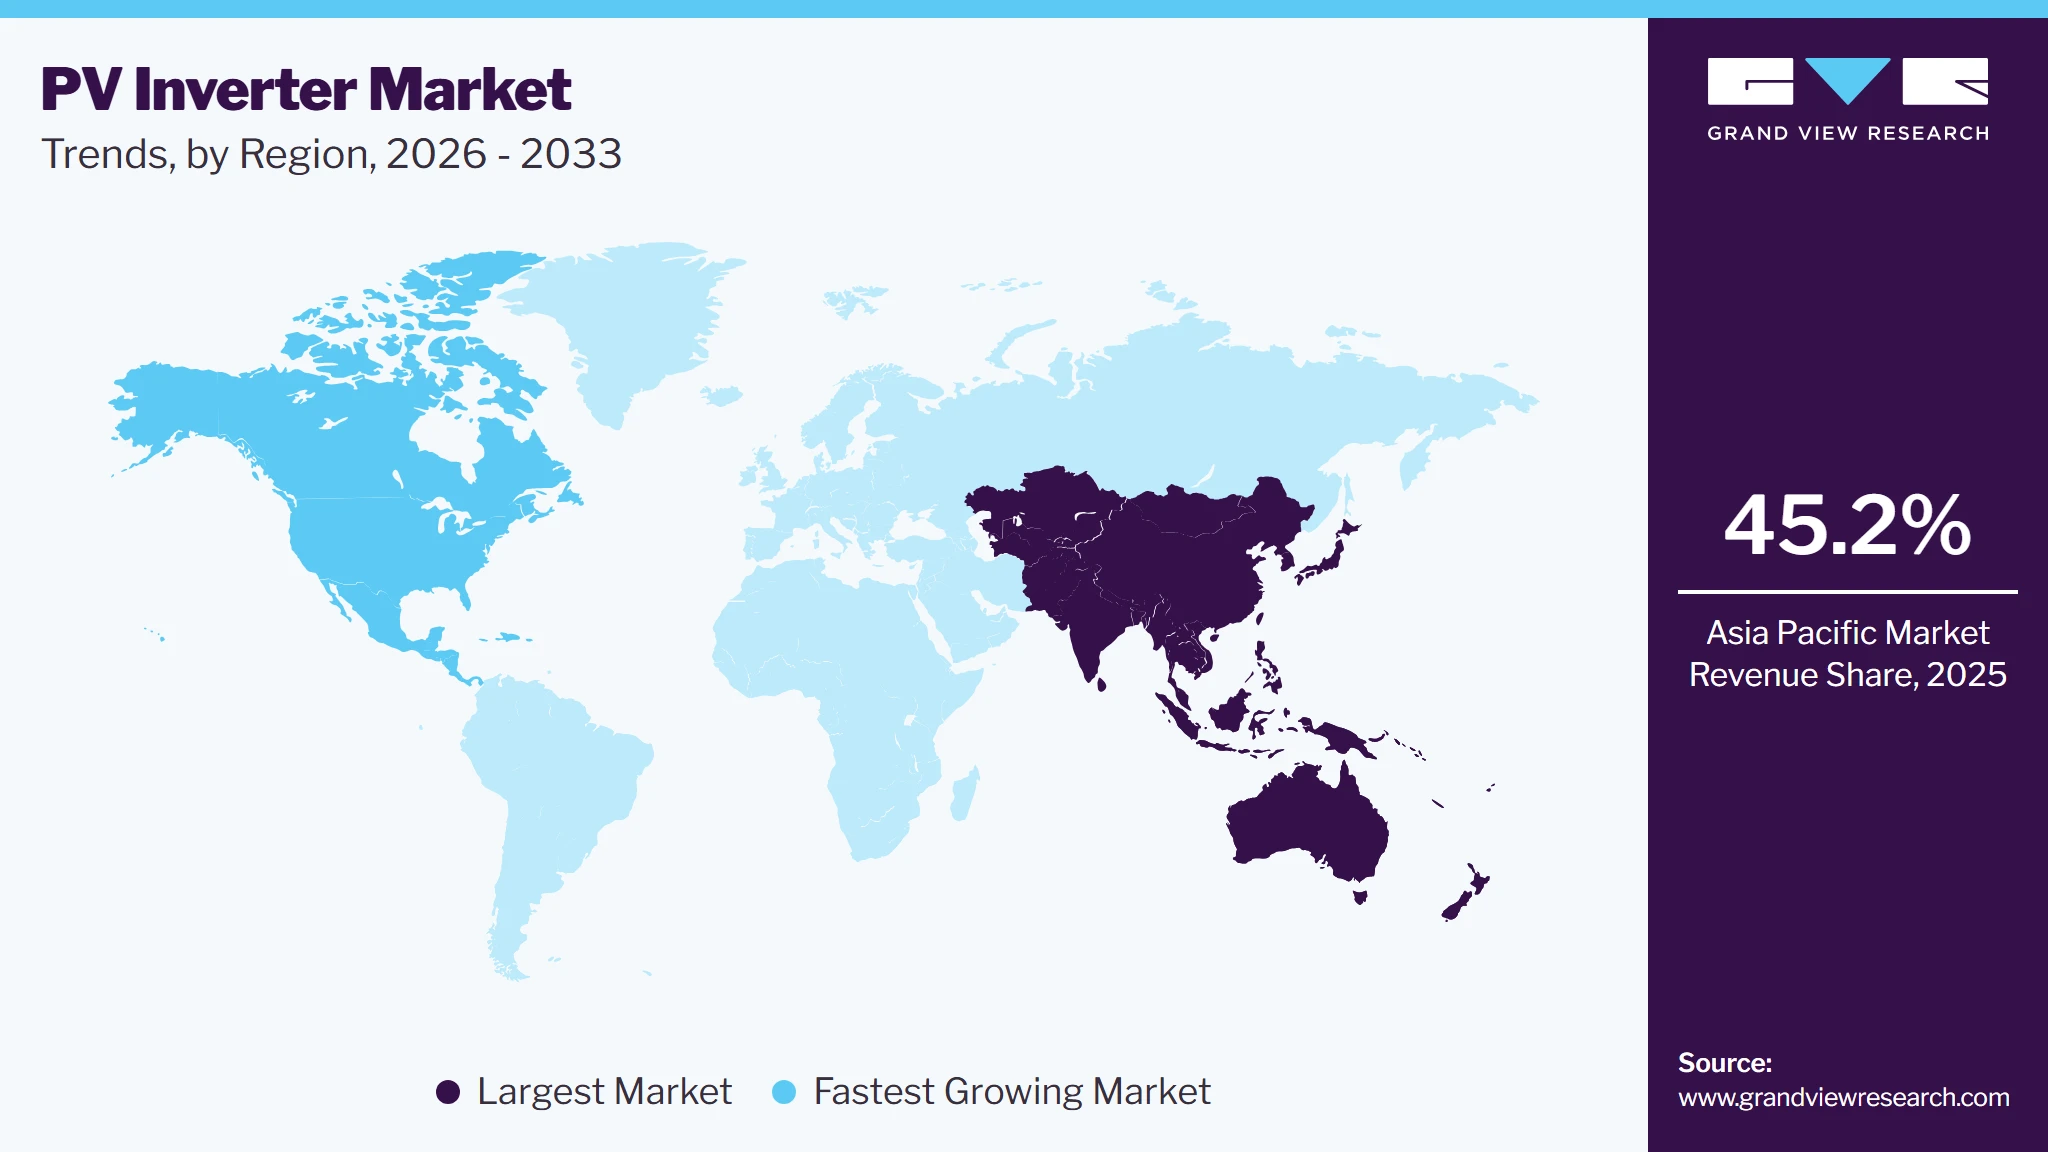
The global PV inverter market size was valued at USD 17.6 billion in 2025 and is projected to grow from USD 20.6 billion in 2026 to USD 49.6 billion by 2033, at a CAGR of 13.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 45.2% in 2025. The growing awareness regarding environmental issues and the need to reduce carbon emissions is driving demand for clean energy solutions, which in turn is expected to drive demand for various energy equipment, including PV inverters.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- Central PV inverter held the largest revenue share of 48.6% in 2025.
- Utilities held the largest revenue share of 44.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (45.2% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
Market Size & Forecast
- Market Size in 2025: USD 17.6 Billion
- Estimated Market Size in 2026: USD 20.6 Billion
- Projected Market Size by 2033: USD 49.6 Billion
- CAGR (2026-2033): 13.4%
Prism AI by Grand View Research Free to tryAsk a question about the PV inverter marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →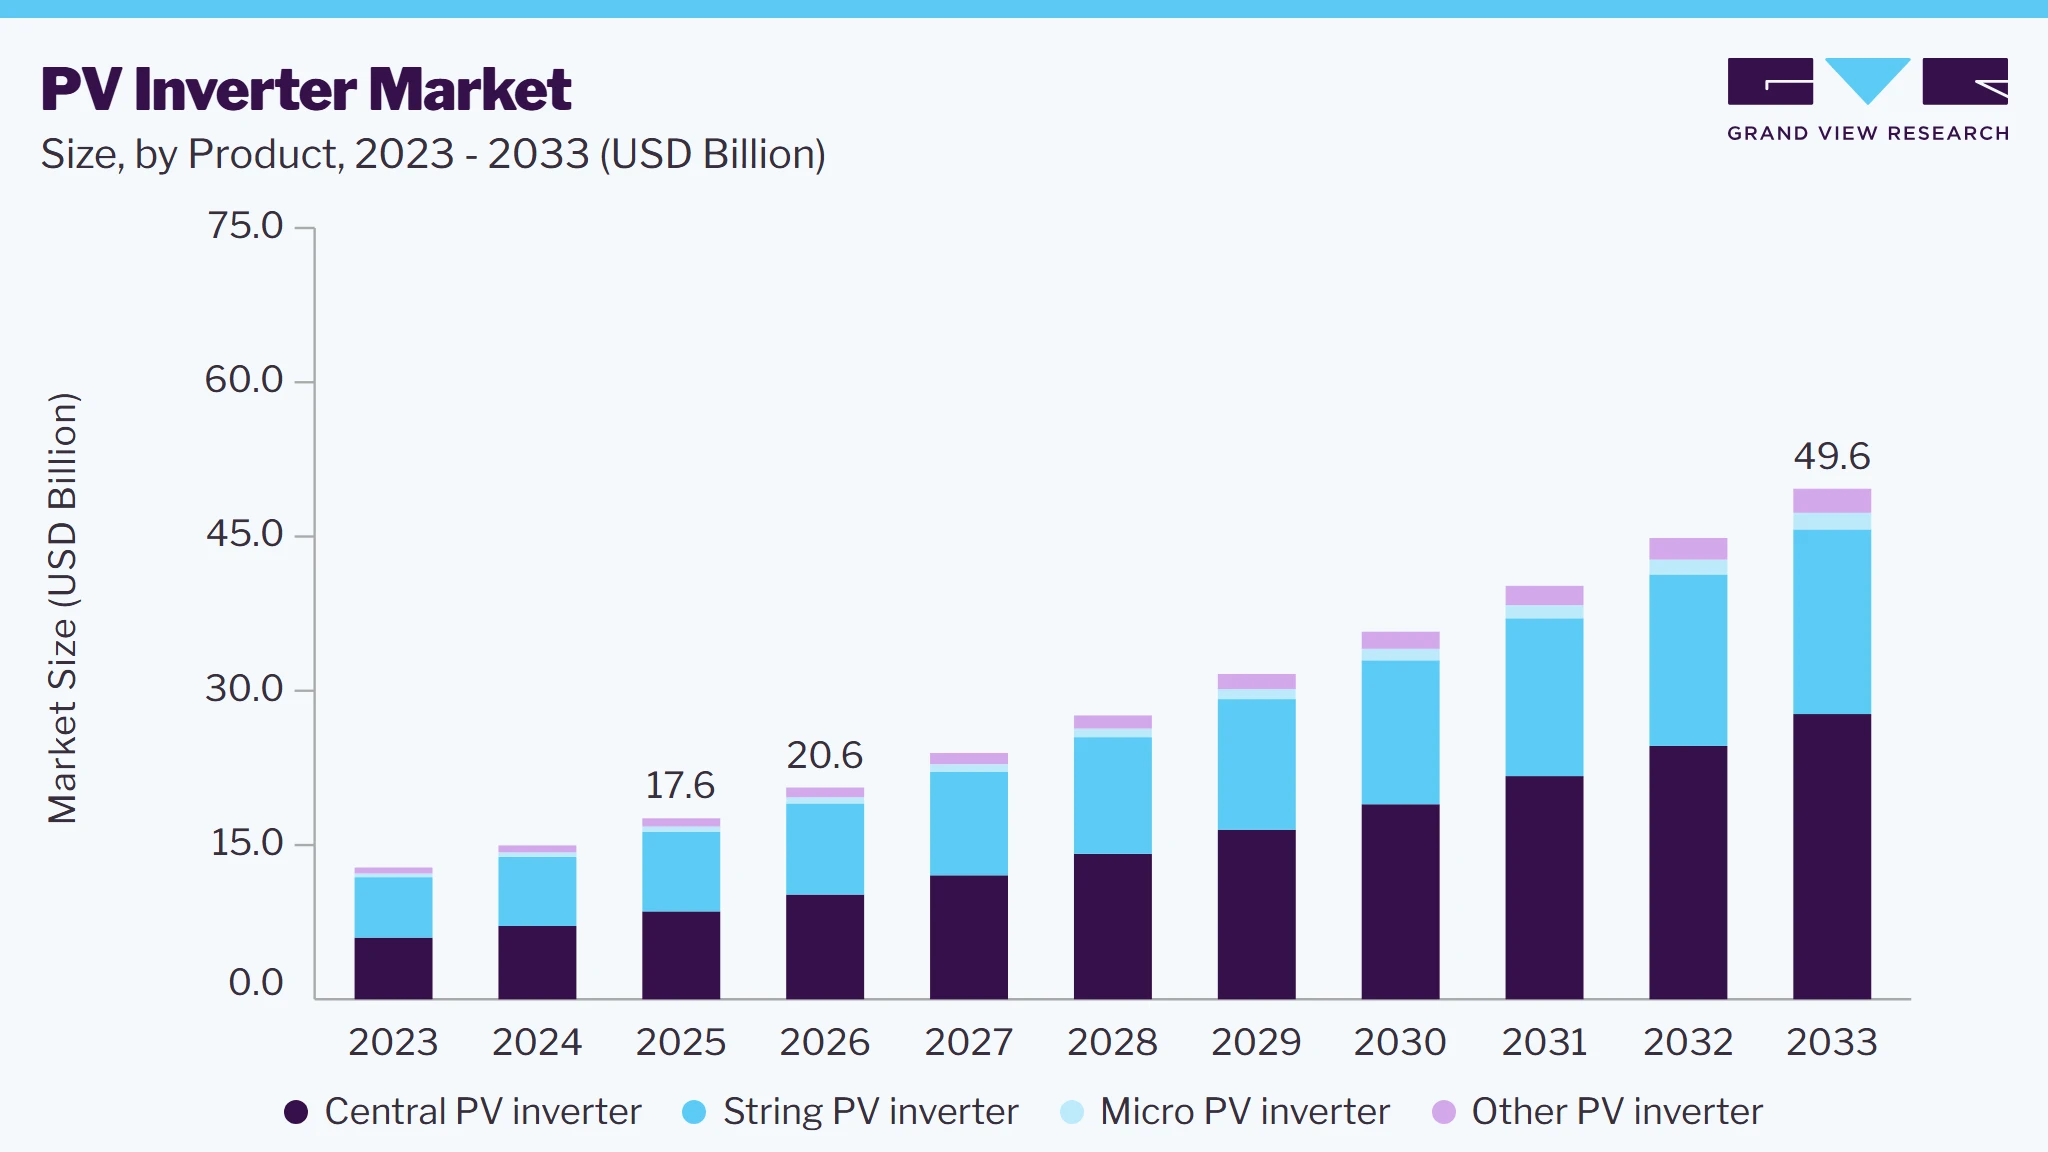 To learn more about this report, Download Free Sample Report
Market Dynamics
The PV inverter market is driven by increasing solar power installations, supportive government policies, and rising investments in renewable energy. Growing adoption of rooftop solar systems and utility-scale solar projects is increasing demand for string and central inverters. Technological advancements in inverter efficiency, smart monitoring, and grid integration are shaping product development. However, price competition, supply chain constraints, and evolving grid requirements pose challenges for manufacturers. The adoption of hybrid inverters and solar-plus-storage systems is creating new growth opportunities.
The increasing installation of solar photovoltaic (PV) capacity is a key driver of the PV inverter market, as inverters are essential for converting the direct current (DC) electricity generated by solar panels into alternating current (AC) electricity for grid integration and end-use applications. The expansion of utility-scale solar farms, commercial and industrial installations, and residential rooftop systems is increasing demand for string and central inverters. In addition, government incentives, renewable energy targets, and growing investments in clean power generation are supporting new solar project development, creating demand for inverter systems across different capacity ranges.
According to the International Energy Agency's Global Energy Review 2026, global solar PV capacity additions exceeded 600 GW in 2025 for the first time, while the IEA PVPS Snapshot of Global PV Markets 2026 estimated that approximately 698 GW of new PV capacity was installed worldwide during the year. This substantial expansion of solar installations increased the need for associated power conversion equipment, including PV inverters, to support electricity generation and grid connection.
The PV inverter market faces challenges from varying grid interconnection standards, electrical safety regulations, and certification requirements across countries. Manufacturers must adapt inverter hardware, firmware, protection functions, and grid-support capabilities to meet regional requirements for voltage and frequency regulation, fault ride-through, and power quality. These differences increase product development, testing, certification, and compliance costs, while extending time to market. Frequent regulatory updates also require manufacturers to invest in ongoing product modifications, creating additional challenges for companies seeking to expand across international markets.
The integration of PV inverters with battery energy storage systems (BESS) is creating new business opportunities for manufacturers as residential, commercial, and industrial users seek greater control over electricity consumption and energy costs. Hybrid inverters enable solar power and battery storage to operate within a coordinated system, allowing excess daytime generation to be stored for later use, reducing peak-period grid consumption, and providing backup power where supported. Growing adoption of rooftop solar, time-of-use electricity tariffs, and distributed energy systems is increasing demand for integrated inverter and storage solutions. Manufacturers can capitalize on this opportunity by developing hybrid inverters with advanced energy management, monitoring, and grid-interaction capabilities.
Analyst Perspective
The PV inverter market is evolving from conventional power conversion toward intelligent systems that support grid stability, energy optimization, and storage integration. The adoption of hybrid inverters, higher-capacity string inverters, 2,000 V architectures, and grid-forming technologies is shaping product development. Digital monitoring, predictive maintenance, and AI-enabled energy management are gaining importance in improving system performance and reducing operating costs. However, manufacturing overcapacity and intense price competition are putting pressure on supplier margins. Manufacturers that combine efficient power conversion, battery compatibility, and advanced grid-support capabilities are better positioned to differentiate their offerings and strengthen market competitiveness.
Product Insights
The central PV inverter held the largest revenue share of 48.6% in 2025. Its leading position reflects the widespread deployment of utility-scale solar power projects, where central inverters efficiently convert electricity from large arrays of solar panels and support high-capacity power generation. Their ability to manage substantial power output, reduce equipment requirements per unit of capacity, and simplify system integration makes them suitable for large solar installations. Continued investments in utility-scale solar farms and grid-connected renewable energy projects are supporting demand for central inverters.
The micro PV inverter segment is anticipated to register a CAGR of 15.0% during the forecast period. Growth is supported by increasing adoption of residential rooftop solar systems, rising demand for module-level power optimization, and the growing preference for flexible solar installations. Microinverters operate independently at the solar panel level, improving energy generation under partial shading and enabling easier system monitoring. Their modular design also supports system expansion and reduces the impact of individual panel failures, encouraging adoption among residential and small commercial users.
End-use Insights
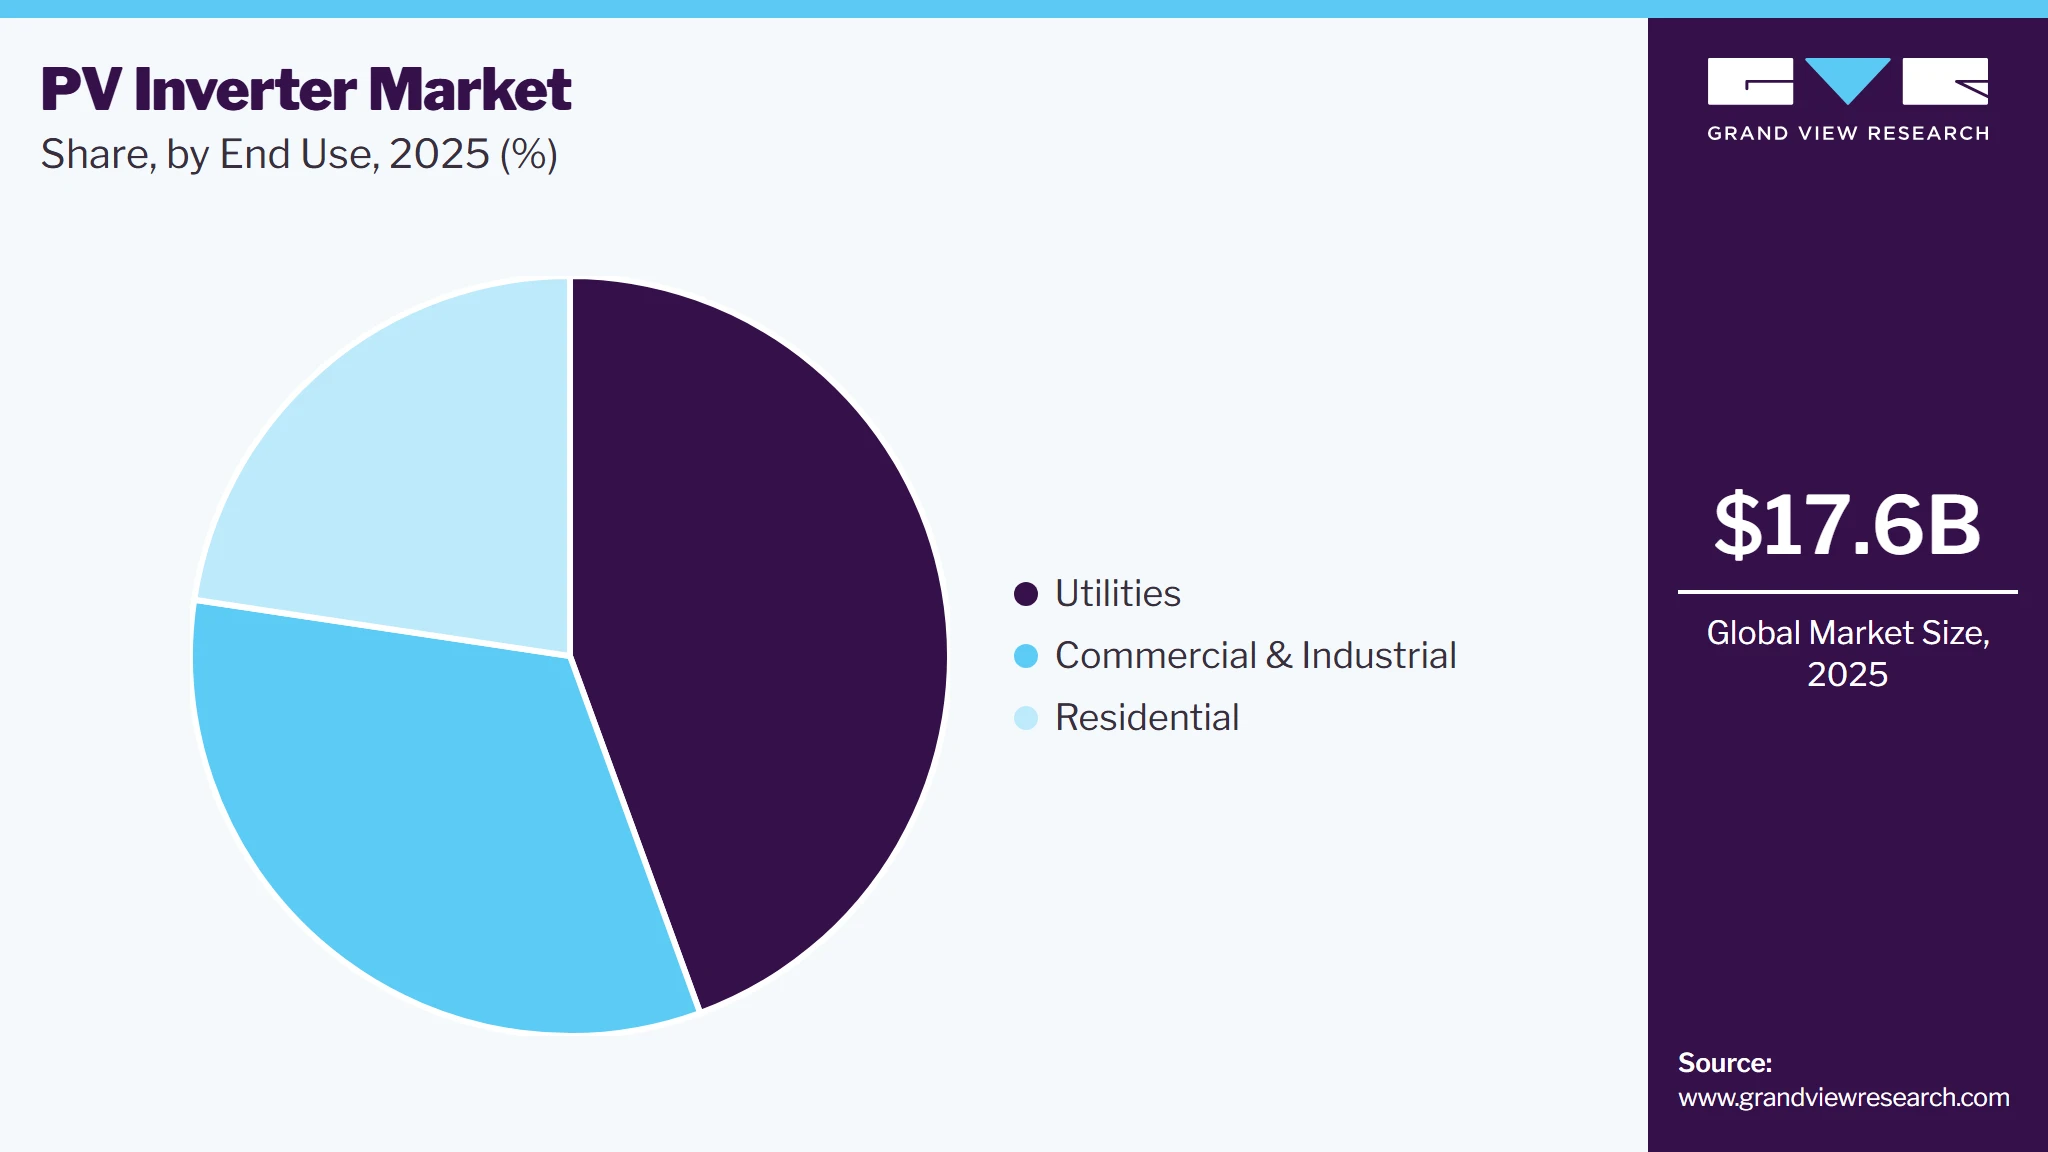
The utilities segment dominated the market with a revenue share of 44.4% in 2025, supported by the expansion of large-scale solar power projects and rising investments in grid-connected renewable energy infrastructure. Utility-scale installations require high-capacity inverters to convert solar-generated DC electricity into AC power for grid transmission. Government renewable energy targets, competitive solar generation costs, and increasing investments in large solar parks are further supporting demand. The preference for central inverters in high-capacity projects also contributes to the segment's leading position.
 To learn more about this report, Download Free Sample Report
The residential segment is expected to register the fastest CAGR of 14.5% from 2026 to 2033. This growth is attributed to the increasing adoption of rooftop solar systems, rising household electricity costs, and government incentives promoting residential solar installations. Growing interest in energy independence, lower electricity bills, and backup power solutions is encouraging homeowners to invest in solar systems with advanced PV inverters. The increasing availability of microinverters and hybrid inverters compatible with battery storage is further supporting residential adoption.
Regional Insights
The Asia Pacific PV inverter market is supported by large-scale solar capacity additions, expanding rooftop installations, and government initiatives to increase renewable energy generation. China and India are major demand centers, while Japan, Australia, and Southeast Asian countries contribute through utility-scale and distributed solar projects. Demand spans central inverters for large solar farms and string and hybrid inverters for commercial, residential, and storage-integrated applications. According to IEA PVPS, China installed approximately 415 GW of new solar PV capacity in 2025, while India added around 54 GW, reinforcing the region's position as a major market for PV inverter suppliers.
 To learn more about this report, Download Free Sample Report
The China PV inverter market is driven by large-scale solar capacity additions, strong domestic manufacturing capabilities, and government support for renewable energy deployment. The expansion of utility-scale solar farms and distributed PV installations is sustaining demand for central and string inverters. Domestic manufacturers, including Huawei and Sungrow, benefit from established supply chains, technological development, and strong competition in both domestic and international markets.
North America PV Inverter Market Trends
The North America PV inverter market is influenced by utility-scale solar development, residential and commercial rooftop installations, and increasing integration of battery storage. Demand is also shaped by grid interconnection requirements, domestic manufacturing initiatives, and changes in federal and state-level energy policies. According to the U.S. Solar Energy Industries Association, the U.S. installed approximately 43.2 GWdc of solar capacity in 2025, despite policy uncertainty and project delays. The continued development of utility-scale projects and growing deployment of solar-plus-storage systems are expected to sustain demand for high-capacity inverters and hybrid inverter solutions.
The U.S. PV inverter market is supported by utility-scale solar development, residential rooftop installations, and increasing integration of battery energy storage systems. Federal and state-level policies, domestic manufacturing investments, and demand for energy resilience influence market development. The growing adoption of solar-plus-storage systems is also increasing interest in hybrid inverters, advanced monitoring, and grid-support capabilities.
Europe PV Inverter Market Trends
The Europe PV inverter market is supported by decarbonization targets, energy security priorities, and the continued deployment of utility-scale and rooftop solar systems. Germany, Spain, Italy, and other European markets contribute to the demand for string, central, and hybrid inverters. Increasing renewable energy penetration is also raising the importance of grid-support functions, energy management, and battery integration. SolarPower Europe reported that the EU installed 65.1 GW of new solar PV capacity in 2025, taking cumulative capacity to approximately 406 GW. However, slower residential installations and grid-integration challenges may influence demand patterns across individual countries.
Latin America PV Inverter Market Trends
The Latin American PV inverter market is driven by favorable solar resources, rising electricity demand, and investments in utility-scale solar farms and distributed generation. Brazil is a major regional market, while Mexico, Chile, and other countries offer opportunities for inverter manufacturers through commercial installations and large renewable energy projects. Demand varies with financing conditions, grid connection capacity, import costs, and national energy policies. Manufacturers offering cost-effective inverters, remote monitoring, and reliable performance under high temperatures are positioned to serve the region's varied operating conditions.
Middle East & Africa PV Inverter Market Trends
The Middle East and Africa PV inverter market is supported by utility-scale solar investments, renewable energy diversification programs, and rising demand for reliable electricity. Countries such as Saudi Arabia, the UAE, and South Africa are developing solar projects to diversify energy sources and address growing power requirements. Large installations favor central and high-capacity string inverters, while commercial rooftops and off-grid systems create demand for smaller and hybrid solutions. High ambient temperatures, dust exposure, grid limitations, and maintenance requirements increase the importance of thermal management, equipment durability, and remote monitoring capabilities.
Key PV Inverter Company Insights
Some of the key players operating in the global PV inverter market include SMA Solar Technology AG and Enphase Energy, Inc., among others.
-
SMA Solar Technology AG participates in the PV inverter market through the development and manufacture of solar inverters for residential, commercial, industrial, and utility-scale applications. Its product portfolio includes string and central inverters designed to support efficient power conversion and grid integration across different system sizes. The company also provides digital monitoring, system management, and service solutions to support solar plant performance and operational reliability. SMA continues to develop inverter technologies with advanced grid-support functions and compatibility with battery energy storage systems, positioning its offerings across distributed solar generation and large-scale photovoltaic projects.
-
Enphase Energy, Inc. participates in the PV inverter market primarily through the development and manufacture of microinverters for residential and commercial solar installations. Its IQ Microinverter product family converts DC electricity into AC electricity at the individual solar module level, supporting module-level monitoring, system optimization, and improved performance under varying shading conditions. The company also offers energy management software, monitoring platforms, and integrated battery storage solutions that support solar-plus-storage deployments. Its focus on modular inverter technology and integrated energy systems positions Enphase within the distributed solar generation and residential energy management segments.
Key PV Inverter Companies
The following key companies have been profiled for this study on the PV inverter market:
-
AISWEI (Solplanet)
-
Enphase Energy, Inc.
-
Fronius International GmbH
-
Ginlong Technologies (Solis)
-
GoodWe Technologies Co., Ltd.
-
Huawei
-
SMA Solar Technology AG
-
SolarEdge Technologies, Inc.
-
Sungrow Power Supply Co., Ltd.
-
TMEIC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Enphase Energy, Inc., Fronius International GmbH, Ginlong Technologies (Solis), GoodWe Technologies Co., Ltd., Huawei, SMA Solar Technology AG, SolarEdge Technologies, Inc., Sungrow Power Supply Co., Ltd., TMEIC)
- Expand product portfolios across residential, commercial, industrial, and utility-scale PV applications.
- Invest in inverter efficiency, smart monitoring, grid-support functions, and hybrid inverter technologies.
- Strengthen global distribution networks and local service capabilities to reach key solar markets.
- Integrate PV inverters with battery storage and energy management platforms to offer complete solar solutions.
- Established brand recognition and extensive global sales and service networks.
- Broad product portfolios covering different system capacities and installation requirements.
- Strong R&D capabilities in power conversion, digital monitoring, and grid integration.
- Established relationships with solar developers, installers, distributors, and project owners.
- Intense price competition, particularly in utility-scale and string inverter segments.
- Exposure to changes in solar installation rates, government policies, and trade restrictions.
- High investment requirements for product development, certification, and technological upgrades.
- Dependence on semiconductor and other electronic component supply chains.
Emerging Players (AISWEI (Solplanet))
- Focus on residential and commercial string inverters and distributed solar applications.
- Expand product offerings with hybrid inverters and battery storage compatibility.
- Strengthen distribution partnerships and after-sales support in international markets.
- Develop cost-competitive products tailored to regional requirements and installation conditions.
- Focused product portfolio targeting distributed PV installations.
- Flexibility in addressing regional customer requirements and installer needs.
- Opportunities to expand through distribution partnerships and localized service networks.
- Potential to compete through product pricing and simplified installation.
- Smaller global market presence relative to leading inverter manufacturers such as Huawei and Sungrow.
- Lower brand visibility and distribution reach in some international markets.
- Need to expand service infrastructure and customer support as international sales grow.
- Competitive pressure from established manufacturers with broader product portfolios and greater scale.
Recent Developments
-
In April 2025, Sungrow introduced its 1+X 2.0 Modular Inverter for utility-scale solar applications, featuring a scalable design that combines 800 kW units to achieve capacities of up to 9.6 MW. The inverter incorporates AI-driven fault detection, DC arc protection, terminal overheating protection, and grid-forming capabilities to improve system safety, reliability, and grid stability. Its thermal management system enables operation without derating at temperatures up to 52°C, while its modular architecture allows individual components to be replaced more quickly, reducing maintenance downtime. The inverter also supports AC- and DC-coupled solar-plus-storage configurations, enabling integration with battery energy storage systems. These capabilities are designed to improve operational efficiency, reduce project costs, and support the deployment of large-scale PV projects under demanding environmental and grid conditions.
PV Inverter Market Report Scope
Report Attribute
Details
Market Definition
The PV inverter market represents revenue generated from the sale of string, central, micro, and other PV inverters used to convert solar-generated DC electricity into AC electricity across residential, commercial and industrial, and utility-scale applications.
Market size in 2025
USD 17.6 billion
Estimated market size in 2026
USD 20.6 billion
Projected market size by 2033
USD 49.6 billion
Growth rate
CAGR of 13.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Product, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; U.K.; Italy; Spain; Poland; Netherlands; China; Japan; India; South Korea; Australia; Malaysia; Indonesia; Thailand; Taiwan; Vietnam; Brazil; Argentina; Chile; Saudi Arabia; UAE; South Africa
Key companies profiled
AISWEI (Solplanet), Enphase Energy, Inc., Fronius International GmbH, Ginlong Technologies (Solis), GoodWe Technologies Co., Ltd., Huawei, SMA Solar Technology AG, SolarEdge Technologies, Inc., Sungrow Power Supply Co., Ltd., TMEIC
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global PV Inverter Market Report Segmentation
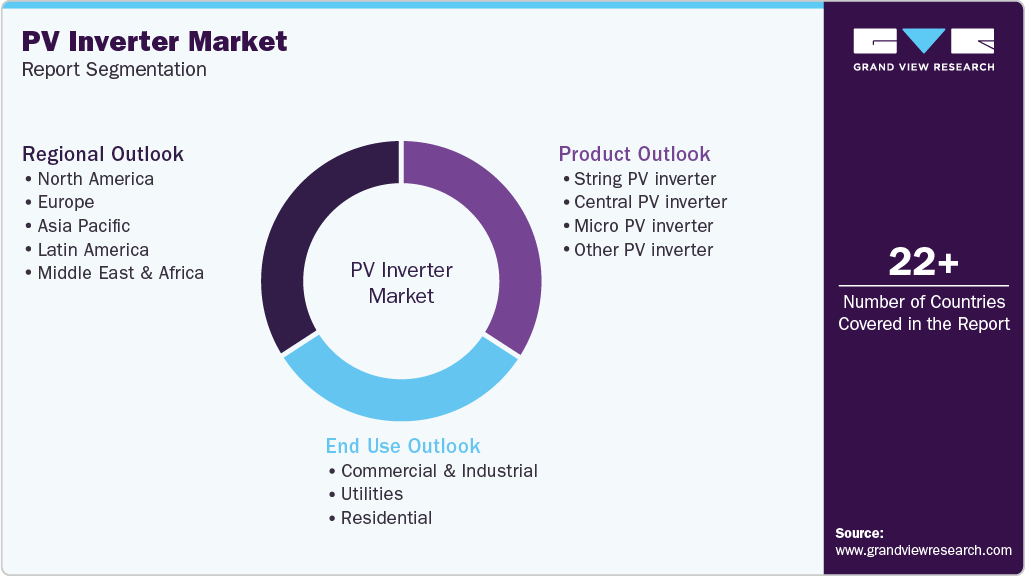
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global PV inverter market report on the basis of product, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
String PV inverter
-
Central PV inverter
-
Micro PV inverter
-
Other PV inverter
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Commercial & Industrial
-
Utilities
-
Residential
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Poland
-
Netherlands
-
-
Asia Pacific
-
China
-
Japan
-
South Korea
-
Taiwan
-
Indonesia
-
India
-
Malaysia
-
Thailand
-
Vietnam
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
Chile
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The PV inverter market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before
publication, with each PV inverter segment quantified using the revenue-capture
definitions in the table below.Segment Definition
Segment - Product
Revenue capture definition
String PV inverter
Revenue includes sales of string inverters that convert DC electricity from a group of solar panels into AC electricity for grid-connected or onsite use.
Central PV inverter
Revenue includes sales of centralized, high-capacity inverters used to convert DC electricity from large solar arrays in utility-scale and other large PV installations.
Micro PV inverter
Revenue includes sales of module-level inverters that convert DC electricity into AC electricity at individual solar panels or small groups of modules.
Other PV inverter
Revenue includes sales of PV inverter types not classified as string, central, or micro inverters, including other specialized inverter configurations.
Segment - End-use
Revenue capture definition
Commercial & Industrial
Revenue includes sales of PV inverters deployed in commercial buildings, industrial facilities, warehouses, factories, and other business premises for onsite solar power generation.
Utilities
Revenue includes sales of PV inverters used in utility-scale solar farms and large grid-connected solar power plants for electricity generation and grid supply.
Residential
Revenue includes sales of PV inverters used in residential solar installations, including rooftop PV systems and home solar-plus-storage applications.
Estimation Model
Layer Name
Key Question
Description
Demand Layer
Which factors generate demand for PV inverters?
Assess demand arising from increasing solar PV installations, renewable energy targets, government incentives, rising electricity consumption, rooftop solar adoption, utility-scale solar projects, and investments in distributed energy generation and battery storage systems.
Product Layer
Which PV inverter products generate market revenue?
Evaluate revenue across string PV inverters, central PV inverters, micro PV inverters, and other PV inverters based on power capacity, conversion efficiency, system configuration, installation requirements, grid compatibility, and integration with energy storage systems.
End-use Layer
Which end-use segments generate market revenue?
Quantify revenue across commercial and industrial, utilities, and residential applications based on solar installation capacity, project scale, inverter requirements, deployment volumes, and demand for grid-connected and onsite power generation.
Revenue Layer
How is PV inverter market revenue generated?
Market revenue is quantified through the sale of PV inverter products supplied for residential, commercial and industrial, and utility-scale solar installations. Revenue varies by inverter type, capacity, product specifications, application, and geographic market, with the analysis focused on equipment sales rather than solar project development, installation services, electricity generation, or energy sales.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Product Technology Opportunity Assessment
Market analysis was conducted across string, central, micro, and other PV inverter technologies by evaluating power capacity, conversion efficiency, system configuration, grid compatibility, monitoring capabilities, storage integration, and technological advancements.
Identified high-potential inverter technologies based on adoption trends, efficiency improvements, scalability, installation flexibility, cost competitiveness, and compatibility with solar-plus-storage systems.
End-use Opportunity Assessment
Market analysis was performed across commercial and industrial, utilities, and residential applications by assessing solar installation capacity, project scale, inverter requirements, deployment trends, and demand for onsite and grid-connected power generation.
Identified end-use segments with strong growth potential based on rooftop solar adoption, utility-scale project pipelines, electricity cost considerations, and increasing demand for integrated energy storage solutions.
Regional Opportunity Assessment
Country-level analysis was conducted to assess PV inverter demand based on solar PV capacity additions, renewable energy targets, government incentives, grid infrastructure, domestic manufacturing capabilities, and investment activity across key markets.
Identified countries and regions with strong market potential based on solar installation growth, supportive policies, manufacturing capacity, distributed generation adoption, and utility-scale project development.
Frequently Asked Questions About This Report
The PV inverter market is expected to grow at a CAGR of 13.4% from 2026 to 2033 to reach USD 49.6 billion by 2033.
The Asia Pacific region dominated the PV inverter market with a revenue share of 45.2% in 2025.
The PV inverter market is driven by increasing solar power installations, supportive government policies, rising demand for renewable energy, grid modernization, and advancements in inverter efficiency and smart monitoring technologies.
China dominated the Asia Pacific region market with a revenue share of 45.8% in 2025.
North America is anticipated to register the fastest CAGR of 15.0% over the forecast period.
Based on product, the central PV inverter accounted for the largest revenue share of 48.6% in 2025.
Based on end-use, the utilities segment accounted for the largest revenue share of 44.4% in 2025.
The PV inverter market size was estimated at USD 17.6 billion in 2025 and is expected to reach USD 20.6 billion in 2026.
The key players operating in the PV inverter market are AISWEI (Solplanet), Enphase Energy, Inc., Fronius International GmbH, Ginlong Technologies (Solis), GoodWe Technologies Co., Ltd., Huawei, SMA Solar Technology AG, SolarEdge Technologies, Inc., Sungrow Power Supply Co., Ltd., and TMEIC.
About the Author(s)
Backup Power Solutions Research Team
Energy & Power · Backup Power SolutionsThis report was authored by the backup power solutions research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the backup power solutions segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


