
- Home
- »
- Next Generation Technologies
- »
-
Rapid Application Development Platform Market Report, 2033GVR Report cover

Rapid Application Development Platform Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Low-code development platforms), By Component (Tools), By Business Function (Sales and Marketing), By Deployment, By Enterprise Size, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$62.6BMarket Estimate, 2026
$85.6BMarket Forecast, 2033
$773.8BCAGR, 2026–2033
37.0%Rapid Application Development Platform Market Summary
The global rapid application development platform market size was valued at USD 62.6 billion in 2025 and is projected to grow from USD 85.6 billion in 2026 to USD 773.8 billion by 2033, at a CAGR of 37.0% from 2026 to 2033. The market in North America dominated with a revenue share of 35.3% in 2025. This growth is driven by the rapid adoption of AI-powered low-code/no-code platforms and enterprise digital transformation initiatives, enabling organizations to accelerate application development, modernize legacy systems, and automate business processes.
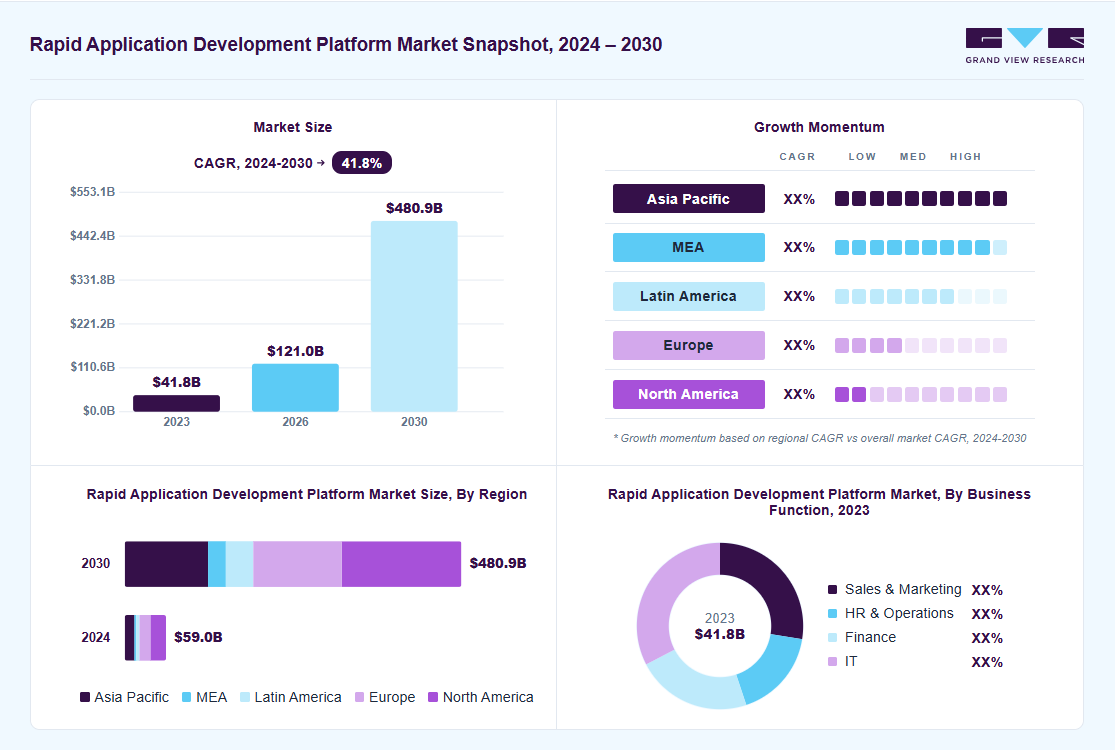 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By business function: IT segment held the largest market share of 33.6% in 2025.
- By type: Low-code development platforms segment held the largest market share of 65.9% in 2025.
- By component: Tools segment held the largest market share of 60.9% in 2025.
- By deployment: Cloud segment held the largest market share of 74.3% in 2025.
- By enterprise size: Large enterprises segment held the largest market share of 63.8% in 2025.
- By end use: BFSI segment held the largest market share of 21.9% in 2025.
Regional Highlights
- Largest regional market: North America (35.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 62.6 Billion
- Estimated market size in 2026: USD 85.6 Billion
- Projected market size by 2033: USD 773.8 Billion
- CAGR (2026-2033): 37.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increasing demand for faster software delivery drives market growth. Companies are pressured to deliver software solutions quickly to remain competitive in today's fast-paced business environment. Traditional development methodologies often involve long development cycles, delaying the time-to-market. Rapid application development (RAD), emphasizing iterative development, prototyping, and early testing, allows businesses to accelerate development, reduce time-to-market, and quickly respond to changing market demands. This agility is critical for businesses looking to stay ahead of competitors and rapidly address customer needs. Moreover, modern businesses face increasingly complex and dynamic requirements driven by digital transformation, globalization, and evolving customer expectations. Rapid application development methodologies support software's iterative and incremental development, allowing developers to adapt to changing requirements throughout the project lifecycle. This adaptability is crucial for managing complexity and ensuring that the final product meets the evolving needs of the business.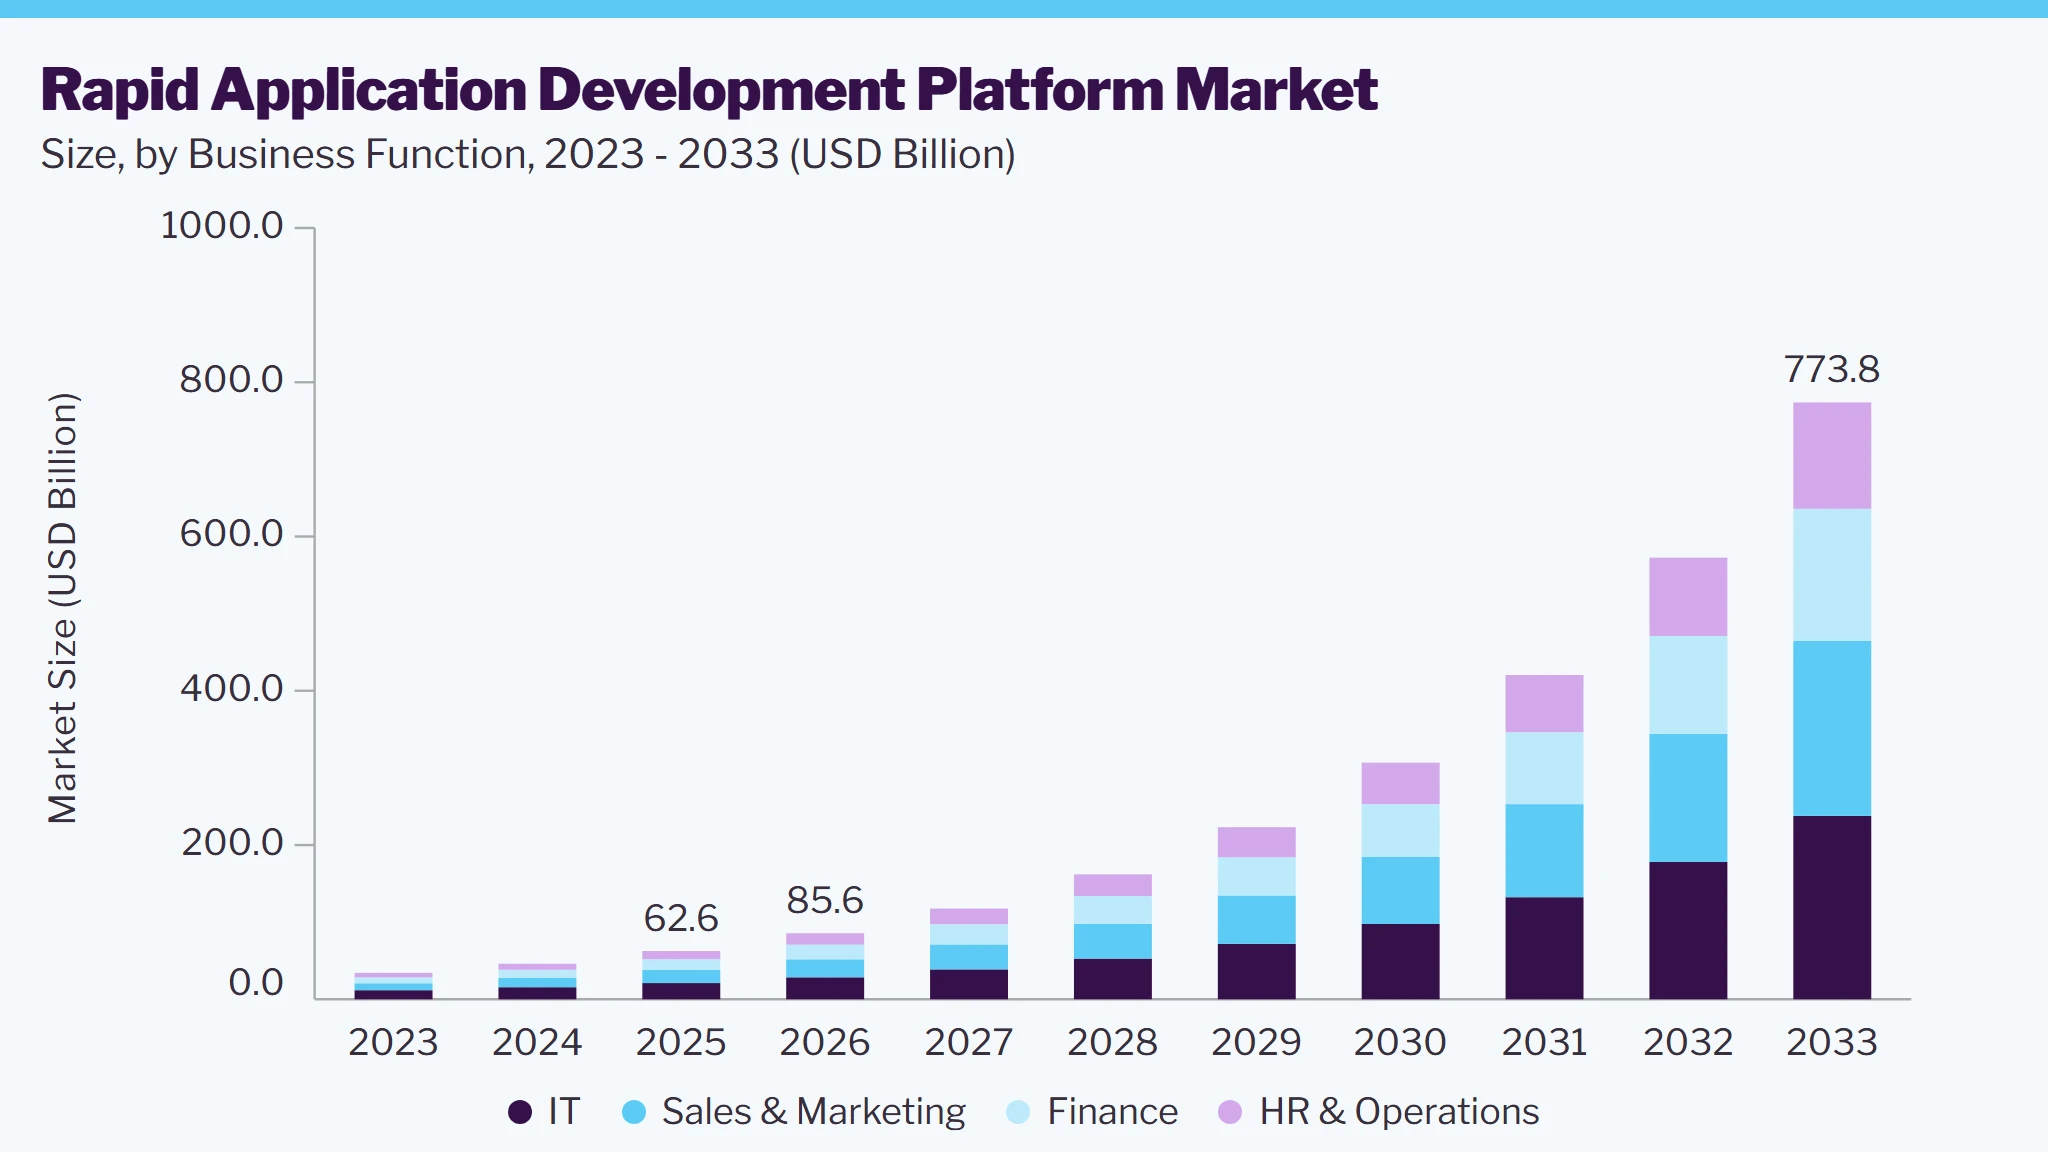 To learn more about this report, Download Free Sample Report
In addition, traditional development methods often involve significant upfront planning and lengthy development cycles, which can lead to increased costs and resource allocation. On the other hand, a rapid application development platform emphasizes iterative development and early testing, which helps identify and address issues early in the project lifecycle. This approach reduces the likelihood of costly post-release fixes and modifications. Furthermore, using low-code/no-code platforms and reusable components in rapid application development can reduce development costs by minimizing the need for extensive custom coding and streamlining the development process.
Market Dynamics
The global rapid application development (RAD) platform market is experiencing strong growth as organizations accelerate digital transformation initiatives and seek faster application delivery with minimal coding requirements. Enterprises across banking, healthcare, manufacturing, retail, government, IT & telecom, and other industries are increasingly adopting RAD platforms to streamline software development, automate business processes, modernize legacy applications, and improve operational agility. Modern RAD platforms integrate low-code/no-code development, visual application modeling, workflow automation, artificial intelligence (AI), cloud-native deployment, API integration, DevOps capabilities, and reusable components into a unified development environment. The growing demand for rapid application deployment, citizen development, digital process automation, cross-platform compatibility, and scalable enterprise applications is driving adoption of cloud-based RAD platforms that reduce development time, lower costs, enhance collaboration, and accelerate innovation.
The increasing focus on enterprise digital transformation and the rising adoption of low-code/no-code development technologies are major drivers of the global Rapid Application Development Platform market. Organizations are deploying RAD platforms to rapidly build, test, and deploy business applications while reducing dependence on traditional software development cycles. These platforms enable visual development, drag-and-drop interfaces, reusable components, workflow automation, API connectivity, and seamless integration with enterprise systems such as ERP, CRM, and cloud services. AI-powered development assistants, automated code generation, real-time collaboration, and DevOps integration further enable enterprises to improve developer productivity, accelerate time-to-market, optimize IT resources, and respond quickly to changing business requirements. In April 2026, OutSystems announced findings from its 2026 State of AI Development research, revealing that 96% of organizations are already using AI agents to accelerate software development and business automation. The announcement reflects the growing enterprise shift toward AI-assisted, low-code application development platforms that enable faster digital transformation, streamlined workflows, and improved developer productivity, supporting continued growth in the global RAD platform market.
Integration complexity, customization limitations, and security challenges remain significant restraints for the global Rapid Application Development Platform market. While RAD platforms simplify application development, organizations often face difficulties integrating new applications with legacy systems, proprietary databases, and complex enterprise environments. Highly customized business processes may require advanced coding beyond the capabilities of standard low-code tools, increasing implementation complexity and development costs. Additionally, concerns related to data security, regulatory compliance, application governance, vendor lock-in, and scalability for mission-critical workloads may limit adoption, particularly among large enterprises operating in highly regulated industries.
The rapid advancement of artificial intelligence, generative AI, intelligent automation, and cloud-native technologies presents a significant growth opportunity for the global Rapid Application Development Platform market. Organizations are increasingly investing in AI-enabled RAD platforms that automate application design, code generation, testing, debugging, and workflow optimization while enabling predictive analytics and intelligent decision-making. The expansion of cloud computing, hybrid work environments, hyperautomation, composable business architectures, and enterprise application modernization is driving demand for scalable RAD platforms capable of supporting diverse development requirements. Furthermore, continued innovation in AI-assisted development, natural language application creation, robotic process automation (RPA), mobile-first development, API management, and multi-cloud deployment is enabling vendors to deliver intelligent, flexible, and future-ready RAD platforms that support evolving enterprise digital transformation strategies.
Analyst Perspective
The rapid application development (RAD) platform market is positioned at the intersection of digital transformation, cloud computing, artificial intelligence, and enterprise application modernization. Organizations across industries are increasingly adopting RAD platforms to accelerate application development, automate business processes, and reduce software delivery timelines while improving operational agility. Unlike traditional software development approaches, RAD platforms provide integrated low-code and no-code environments that unify visual development, workflow automation, API integration, AI-assisted development, testing, deployment, and application lifecycle management within a centralized platform. Modern RAD platforms leverage cloud-native architectures, generative AI, intelligent automation, DevOps integration, and multi-cloud deployment capabilities to enable rapid application delivery, seamless enterprise integration, improved developer productivity, and scalable digital transformation initiatives.
Business Function Insights
Based on business function, the IT segment led the market with the largest revenue share of 33.6% in 2025. Modern businesses rely heavily on data to make informed decisions and drive strategic initiatives. RAD enables IT functions to quickly develop and deploy data-driven applications that provide real-time insights and analytics. By integrating data sources and leveraging advanced analytics, RAD applications help businesses make better decisions, optimize operations, and improve customer experiences. The ability to rapidly develop and deploy data-driven solutions is a significant factor driving the growth of the rapid application development platform market in IT functions.
The sales and marketing segment is expected to grow at the fastest CAGR of 38.4% over the forecast period. Customer engagement and retention are critical for long-term business success. RAD enables the development of applications that facilitate ongoing communication and interaction with customers. It includes customer relationship management systems, loyalty programs, and feedback tools. By maintaining regular engagement, businesses can build stronger customer relationships, understand their needs better, and foster loyalty. RAD’s iterative development approach ensures that these engagement tools can continuously improve based on user feedback and evolving business goals.
Type Insights
Based on type, the low-code development platforms segment led the market with the largest revenue share of 65.9% in 2025. The shortage of skilled software developers has created a pressing need for solutions bridging the gap between demand and supply. Low-code platforms empower a broader range of individuals, including those with limited coding experience, to develop applications. By lowering the barrier to entry for application development, these platforms enable business users, often referred to as "citizen developers," to contribute to the development process.
The no-code development platforms segment is expected to grow at the fastest CAGR of 37.8% during the forecast period. Modern no-code platforms offer robust integration capabilities, allowing applications built on these platforms to connect seamlessly with existing systems and third-party services. This interoperability is crucial for organizations looking to enhance their digital ecosystems without overhauling their IT infrastructure. No-code platforms often come with pre-built connectors and APIs, enabling easy integration with popular enterprise software, cloud services, and databases. This feature enhances the versatility of no-code solutions, making them an attractive option for businesses seeking to streamline processes and improve operational efficiency.
Component Insights
Based on component, the tools segment led the market with the largest revenue share of 60.9% in 2025. Effective collaboration between development teams and business stakeholders is crucial for successful software projects. RAD tools often include features that facilitate real-time collaboration, such as integrated project management, version control, and communication platforms. These tools enable seamless interaction among team members, ensuring everyone is aligned with the project goals and can contribute effectively. Enhanced collaboration leads to better decision-making, faster problem-solving, and higher-quality applications.
The services segment is expected to grow at the highest CAGR of 37.8% during the forecast period. Businesses often require customized solutions tailored to their specific needs and workflows. RAD services offer the expertise needed to customize applications beyond the capabilities of standard RAD tools and platforms. This customization ensures that applications align closely with business processes, enhancing efficiency and effectiveness. In addition, integrating new applications with existing systems and third-party services is critical for many organizations. RAD service providers offer the necessary skills and experience to ensure seamless integration, enabling businesses to create cohesive and interoperable solutions.
Deployment Insights
Based on deployment, the cloud segment led the market with the largest revenue share of 74.3% in 2025. Cloud RAD platforms facilitate seamless collaboration among development teams, regardless of their geographical location. With an internet connection, developers can access development environments, tools, and resources from anywhere, promoting remote work and global collaboration. This accessibility enhances productivity and accelerates development by enabling real-time collaboration, code sharing, and version control across distributed teams.
The on-premise segment is expected to grow at a CAGR of 36.2% over the forecast period. Data security is paramount for industries handling sensitive or confidential data, such as healthcare, finance, and government sectors. On-premise deployment allows organizations to retain full control over their data and infrastructure. By keeping data in their secure environment, businesses can implement stringent security measures tailored to their needs. This includes implementing access controls, encryption protocols, and monitoring mechanisms to safeguard against unauthorized access and data breaches. The assurance of data security provided by on-premise deployment is a critical factor driving its adoption in the market.
Enterprise Size Insights
Based on enterprise size, the large enterprises segment led the market with the largest revenue share of 63.8% in 2025. Large enterprises operate in dynamic and competitive markets where innovating and responding quickly to changing customer needs is crucial. RAD methodologies enable enterprises to accelerate the development and deployment of software applications, allowing them to bring new products and services to market faster. By adopting RAD, large enterprises can iterate rapidly, experiment with new ideas, and incorporate feedback from users and stakeholders early in the development process. This agility helps enterprises stay ahead of competitors and seize new business opportunities swiftly.
The SMEs segment is expected to grow at the fastest CAGR of 37.4% over the forecast period. Compared to larger enterprises, SMEs often operate with limited budgets and resources. RAD methodologies offer cost-effective solutions by reducing development time and minimizing the need for extensive technical expertise. Low-code/no-code platforms within RAD enable SMEs to develop applications with reduced reliance on professional developers, lowering development costs while maintaining quality. This affordability makes RAD accessible to SMEs that may not have the financial capacity for traditional development approaches.
End Use Insights
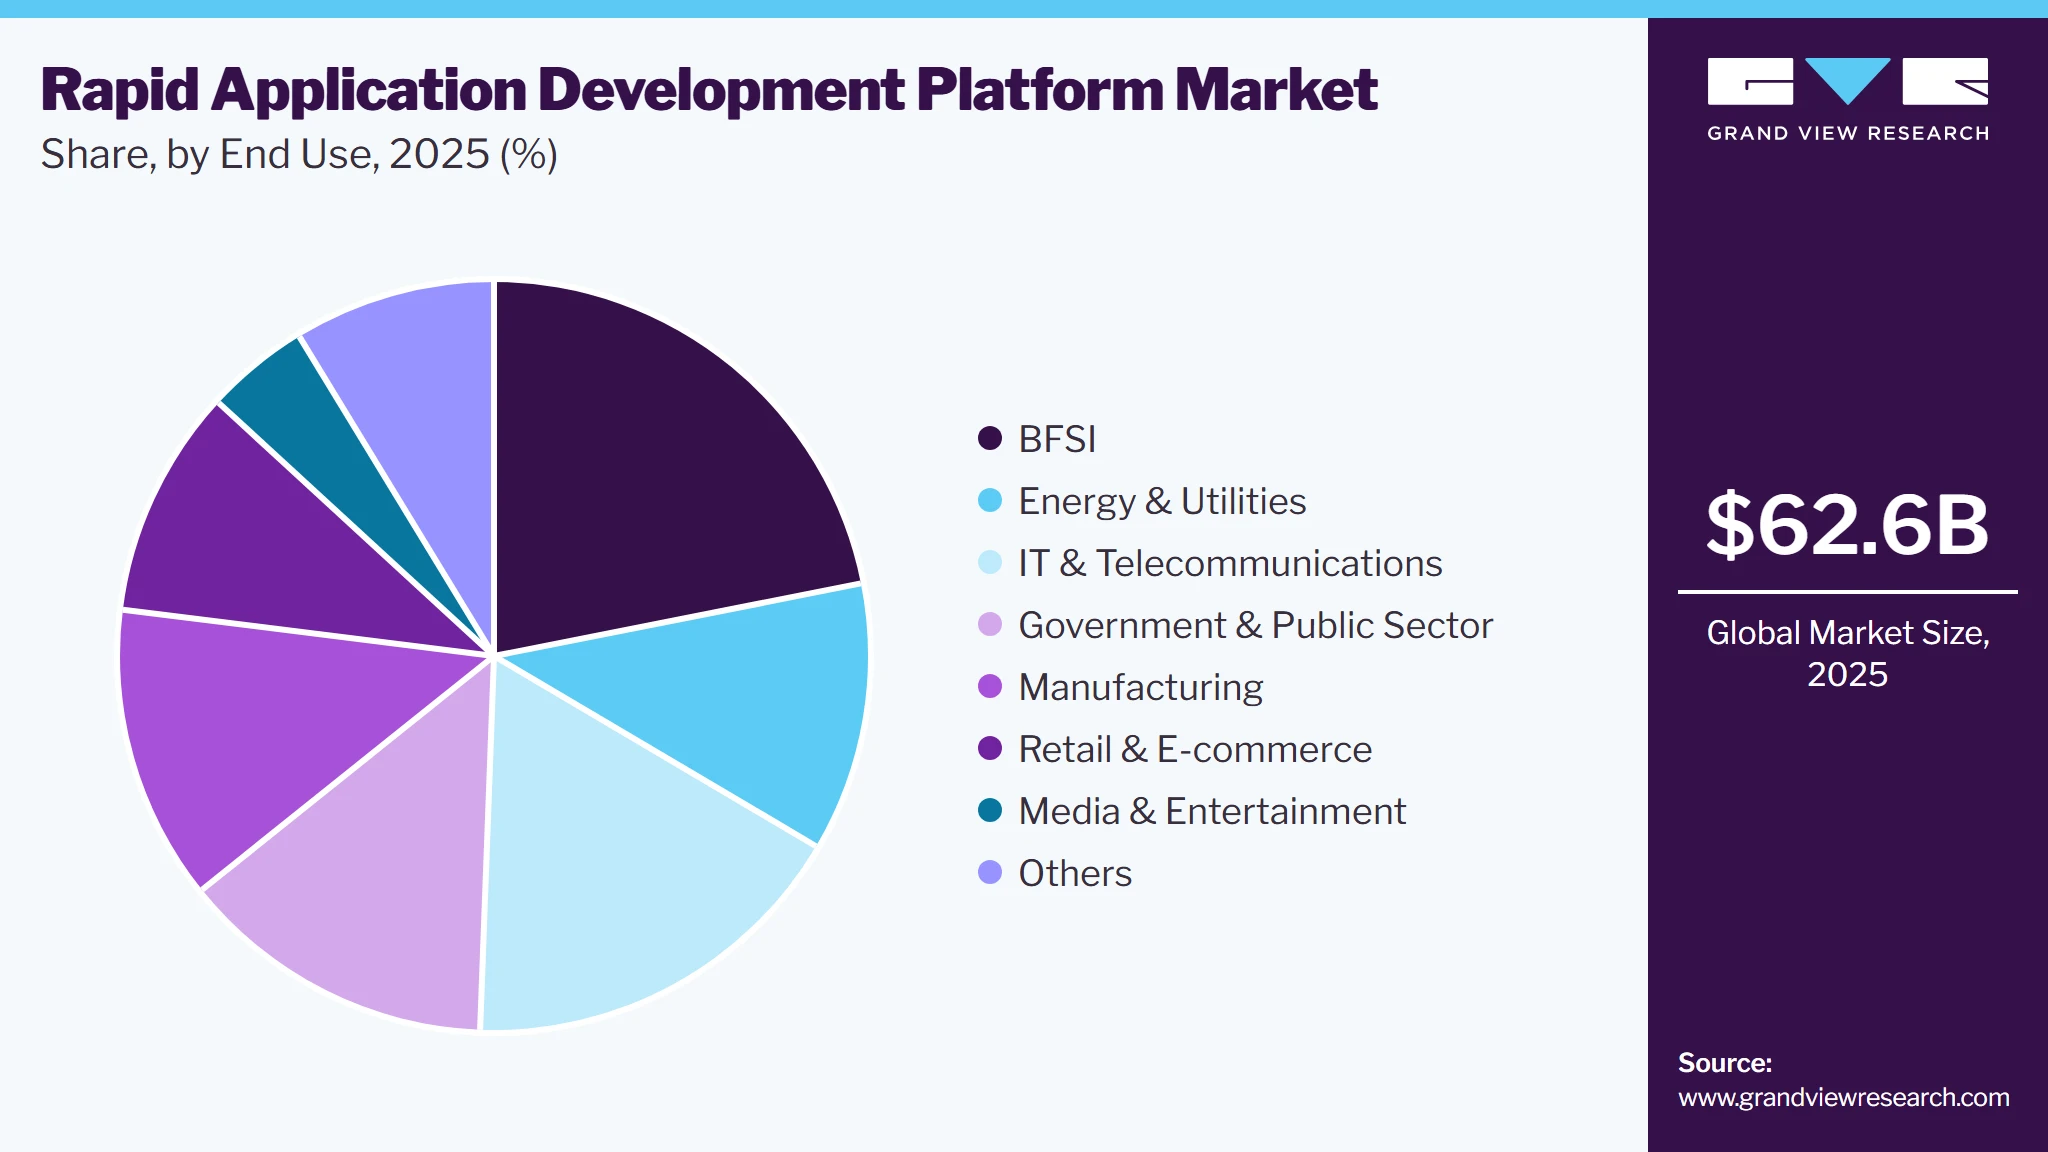
Based on end use, BFSI segment led the market with the largest revenue share of 21.9% in 2025. Compliance with stringent regulatory requirements is a top priority for the BFSI sector. RAD frameworks facilitate compliance by providing structured development processes and documentation that adhere to regulatory standards such as GDPR, PCI-DSS, and Basel III. RAD platforms often include built-in security features and compliance controls, ensuring that applications meet regulatory guidelines from the outset.
 To learn more about this report, Download Free Sample Report
The retail and e-commerce segment is expected to grow at a CAGR of 25.8% during the forecast period. Retail and e-commerce businesses increasingly focus on delivering seamless and personalized customer experiences. RAD enables these businesses to quickly develop and deploy applications that enhance user interfaces, streamline checkout processes, and make customized recommendations based on customer behavior and preferences. By rapidly iterating and testing new features, RAD allows retailers to adapt their digital platforms to meet evolving consumer expectations, ultimately improving customer satisfaction and loyalty.
Regional Insights
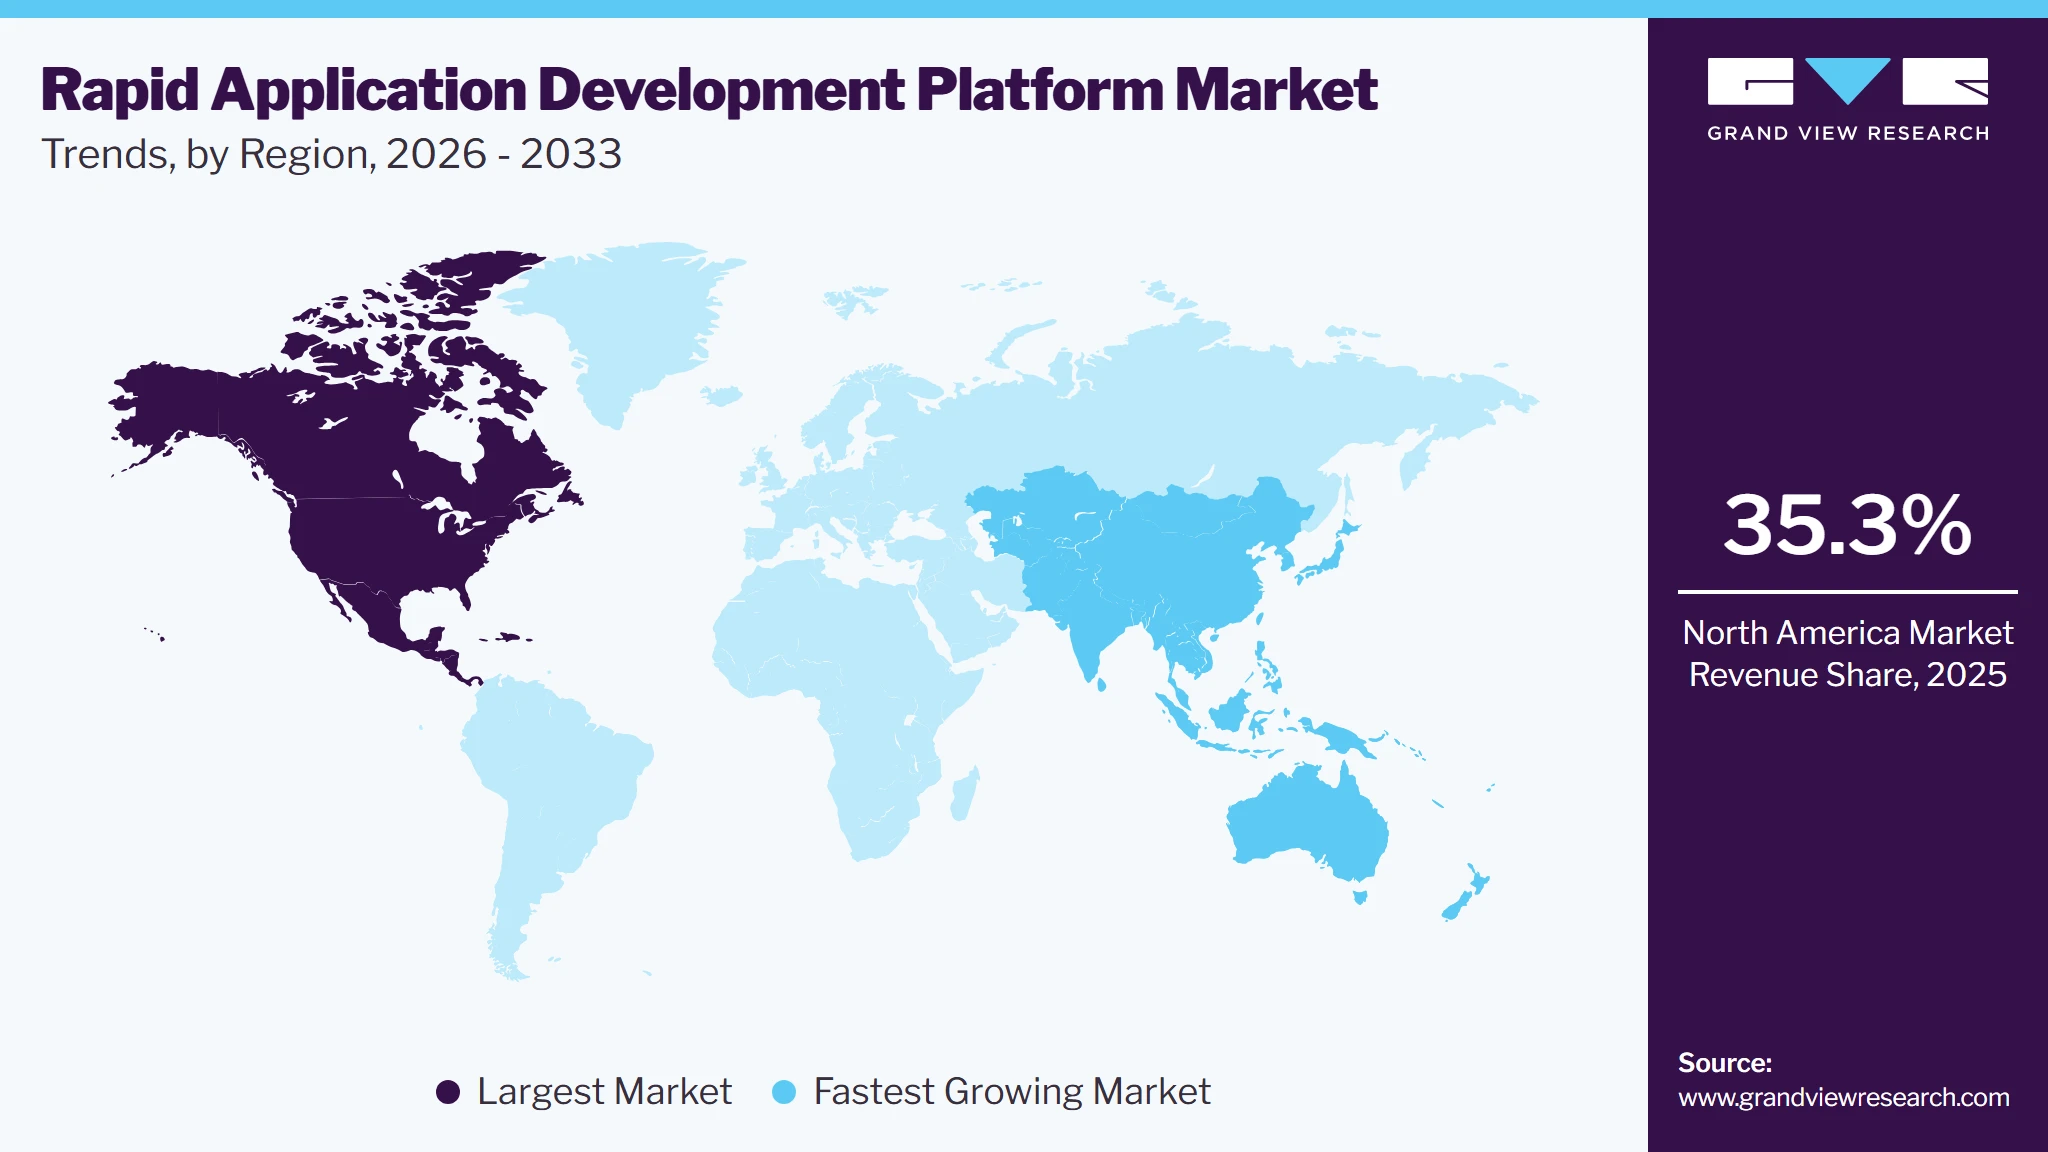
North America dominated the global rapid application development platform market with the largest revenue share of 35.3% in 2025. North America has a mature and robust IT infrastructure with widespread access to high-speed internet, cloud computing services, and advanced digital technologies. This infrastructure provides a strong foundation for RAD implementation, facilitating seamless integration with existing systems and supporting the scalability of RAD-driven applications.
 To learn more about this report, Download Free Sample Report
U.S. Rapid Application Development Platform Market Trends
The rapid application development platform market in the U.S. held the largest share in the North America region in 2025. The competitive landscape in the U.S. demands agility and innovation from businesses to respond quickly to market changes and customer expectations. RAD enables organizations to shorten development cycles, iterate rapidly, and experiment with new ideas. This flexibility allows businesses to innovate, launch new products and services quickly, and seize market opportunities before competitors.
Asia Pacific Rapid Application Development Platform Market Trends
The rapid application development platform market in Asia Pacific is expected to grow at the fastest CAGR of 38.6% from 2026 to 2033. With a high penetration of mobile devices and internet connectivity, the Asia Pacific region has become a hotspot for mobile-first applications. RAD tools support the development of mobile applications that cater to the preferences and behaviors of mobile-centric populations. These applications are designed to provide seamless user experiences, optimize performance for diverse mobile devices, and leverage mobile-specific features such as location-based services and mobile payments.
Europe Rapid Application Development Platform Market Trends
The rapid application development platform market in Europe is growing significantly at a CAGR of 36.5% from 2026 to 2033. Europe comprises diverse markets with varying cultural, linguistic, and regulatory landscapes. RAD's flexibility and customization capabilities enable businesses to tailor applications to meet specific market needs and localized requirements across European countries. Whether developing consumer-facing applications, enterprise solutions, or public sector services, RAD allows organizations to adapt quickly to local market conditions, user preferences, and regulatory frameworks.
Key Rapid Application Development Platform Company Insights:
Key players operating in the include Appian, Google LLC, International Business Machines Corporation, Microsoft, N-iX LTD; Oracle, OutSystems, Pegasystems Inc., Salesforce, Inc., and Zoho Corporation Pvt. Ltd. The companies are focusing on various strategic initiatives, including new product development, partnerships & collaborations, and agreements to gain a competitive advantage over their rivals. The following are some instances of such initiatives.
Key Rapid Application Development Platform Companies
The following key companies have been profiled for this study on the rapid application development platform market.
-
Appian
-
Google LLC
-
International Business Machines Corporation
-
Microsoft
-
N-iX LTD
-
Oracle
-
OutSystems
-
Pegasystems Inc.
-
Salesforce, Inc.
-
Zoho Corporation Pvt. Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Microsoft, Salesforce, Inc., Oracle, IBM Corporation)
- Deliver cloud-native low-code platforms with AI, workflow automation, API integration, and enterprise application development.
- Continuously invest in generative AI, cloud innovation, and application modernization capabilities.
- Expand through strategic partnerships, global partner ecosystems, and industry-specific solutions.
- Strong global brand recognition, extensive enterprise customer base, and mature product portfolios.
- Broad cloud ecosystems with advanced AI, security, compliance, and integration capabilities.
- Significant R&D investment and comprehensive implementation, consulting, and support services.
- Higher licensing, implementation, and customization costs than many competitors.
- Complex platforms may require skilled developers and longer deployment timelines.
- Continuous investment is needed to support AI innovation, security, compliance, and legacy modernization.
Emerging Players (OutSystems, Appian, Pegasystems Inc., Google LLC)
- Focus on agile, cloud-native low-code platforms with AI-assisted application development.
- Prioritize rapid innovation, user-friendly development tools, and workflow automation.
- Target enterprise digital transformation through flexible deployment and cloud integration.
- Faster implementation, strong low-code capabilities, and developer-friendly platforms.
- Competitive pricing with rapid feature releases and AI-driven productivity enhancements.
- Flexible deployment models that accelerate application delivery and business agility.
- Smaller enterprise customer base compared with established vendors.
- Limited global implementation partners and regional support coverage.
- Face intense competition from larger vendors with broader ecosystems and resources.
Recent Developments
-
In May 2024, FPT Software partnered with Siemens to offer the low-code application development platform Mendix in the South Korean and Japanese markets. As part of this collaboration, FPT Software will serve as a reseller and delivery partner for Mendix, allowing clients to achieve faster time-to-market and more cost-effective software projects. This partnership aims to enhance FPT Software's portfolio with rapid application prototyping, development, and deployment services while exploring opportunities to expand market reach through Mendix's partner ecosystem.
-
In April 2024, Comviva, a customer experience and data monetization solutions company, launched an innovative Low-Code/No-Code platform for digital payments and banking. The new platform, an extension of Comviva's existing mobility platform, is designed to revolutionize the development landscape for financial institutions, including FinTechs, banks, and digital wallet providers. The platform enables these organizations to quickly adapt to market regulations, changes, and evolving customer demands by visually constructing user journeys and workflows, as well as seamlessly integrating with third-party systems
Rapid Application Development Platform Market Scope
Report Attribute
Details
Market size in 2025
USD 62.6 billion
Estimated market size in 2026
USD 85.6 billion
Projected market size by 2033
USD 773.8 billion
Growth rate
CAGR of 37.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share analysis, competitive landscape, growth factors, and trends
Segments covered
Type, component, business function, deployment, enterprise size, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Appian; Google LLC; International Business Machines Corporation; Microsoft; N-iX LTD; Oracle; OutSystems; Pegasystems Inc.; Salesforce, Inc.; Zoho Corporation Pvt. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Rapid Application Development Platform MarketThis report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends from 2021 to 2033 in each of the sub-segments. For this study, Grand View Research has segmented the global rapid application development platform market report based on type, component, enterprise size, deployment, business function, end use, and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Low-code development platforms
-
No-code development platforms
-
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Tools
-
Services
-
-
Business Function Outlook (Revenue, USD Billion, 2021 - 2033)
-
Sales and Marketing
-
HR and Operations
-
Finance
-
IT
-
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
On-premise
-
Cloud
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Small & Medium Enterprises (SMEs)
-
Large Enterprises
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
BFSI
-
IT and Telecommunications
-
Government and Public Sector
-
Energy and Utilities
-
Manufacturing
-
Retail and E-commerce
-
Media & Entertainment
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The rapid application development platform market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each rapid application development platform segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Type
Revenue capture definition
Low-code development platforms
Revenue is generated from the licensing or subscription of Rapid Application Development (RAD) platforms that provide visual application development, drag-and-drop interfaces, workflow automation, reusable components, AI-assisted development, API integration, mobile application development, database management, testing, deployment, and application lifecycle management capabilities. Revenue includes perpetual licenses, SaaS subscriptions, platform upgrades, and software maintenance associated with low-code RAD platforms.
No-code development platforms
Revenue is generated from the licensing or subscription of no-code Rapid Application Development platforms that enable business users and citizen developers to build, deploy, and manage applications using visual interfaces without requiring traditional programming. Revenue includes SaaS subscriptions, platform licensing, upgrades, maintenance, and integrated automation, forms, workflow, and business application development capabilities.
Component
Revenue capture definition
Tools
Revenue includes software platforms and development tools used for visual application development, workflow automation, UI/UX design, application integration, API management, testing, deployment, monitoring, and lifecycle management offered as licensed or subscription-based solutions
Services
Revenue includes professional and managed services related to RAD platform implementation, consulting, customization, integration, migration, training, technical support, maintenance, and managed application development services
Business Function
Revenue capture definition
Sales and Marketing
Revenue generated from RAD platform deployments used to develop CRM applications, sales automation, customer engagement, marketing automation, campaign management, and customer service applications.
HR and Operations
Revenue generated from applications supporting employee onboarding, payroll, workforce management, workflow automation, asset management, procurement, and operational process automation.
Finance
Revenue generated from applications used for financial management, budgeting, accounting, invoicing, compliance, expense management, risk management, and financial reporting.
IT
Revenue generated from RAD platform deployments used for enterprise application development, legacy modernization, internal business applications, IT service management, DevOps automation, and digital transformation initiatives.
Deployment
Revenue capture definition
On-premise
Revenue generated from RAD platform deployments hosted within an organization's own IT infrastructure, including perpetual software licenses, implementation, maintenance, upgrades, and support services.
Cloud
Revenue generated from cloud-hosted RAD platforms delivered through Software-as-a-Service (SaaS), Platform-as-a-Service (PaaS), or hybrid cloud models, including subscription fees, managed services, platform updates, and cloud-based support.
Enterprise Size
Revenue capture definition
Small & Medium Enterprises (SMEs)
The SMEs segment, with respect to the number of employees, generally includes organizations employing between 10 and 999 employees.
Large Enterprises
The large enterprises segment, with respect to the number of employees, typically comprises organizations employing more than 1,000 employees for multinational corporations.
End Use
Revenue capture definition
BFSI
Revenue generated from RAD platform deployments used to develop banking, insurance, financial services, customer onboarding, loan processing, compliance, fraud management, and digital banking applications.
IT and Telecommunications
Revenue generated from application development platforms used for OSS/BSS systems, customer portals, service management, network operations, and enterprise software development.
Government and Public Sector
Revenue generated from RAD platform deployments supporting citizen services, e-governance, licensing, taxation, case management, public administration, and regulatory compliance applications.
Energy and Utilities
Revenue generated from applications supporting asset management, field service management, smart grid operations, maintenance workflows, regulatory reporting, and operational process automation.
Manufacturing
Revenue generated from RAD platform deployments used for production management, quality control, supply chain management, inventory tracking, maintenance, and factory workflow automation.
Retail and E-commerce
Revenue generated from applications supporting omnichannel commerce, order management, inventory management, customer engagement, loyalty programs, and retail operations.
Media & Entertainment
Revenue generated from RAD platform deployments used for digital content management, advertising operations, subscription management, media workflow automation, audience engagement, and content delivery applications.
Others
Revenue generated from RAD platform adoption across healthcare, education, transportation, logistics, hospitality, construction, real estate, and other industry verticals for custom business application development and process automation.
Estimation Model
Layer No.
Layer
Question
Analysis
01
Enterprise Demand Layer
Who can benefit from rapid application development (RAD) platforms?
Identify organizations that require rapid application development capabilities to accelerate digital transformation, automate business processes, modernize legacy applications, and improve operational efficiency. These include enterprises across BFSI, IT & telecommunications, government, manufacturing, healthcare, retail, energy & utilities, education, and other industries. Organizations seeking faster application delivery, reduced development costs, improved business agility, and enhanced customer experiences represent the core demand base for RAD platforms.
02
Digital Readiness & IT Infrastructure Layer
Who can deploy RAD platforms?
Evaluate organizations based on their digital transformation maturity, cloud adoption, IT infrastructure, API readiness, cybersecurity capabilities, DevOps maturity, availability of skilled developers and citizen developers, and integration capabilities with ERP, CRM, databases, cloud services, and legacy enterprise systems. Organizations investing in cloud-native architectures, automation, AI, and enterprise modernization demonstrate greater readiness for RAD platform implementation.
03
Adoption & Utilization Layer
Who actively uses RAD platforms?
Analyze RAD platform adoption across SMEs and large enterprises in industries such as BFSI, manufacturing, retail, healthcare, government, telecommunications, and media. Active users leverage RAD platforms to rapidly build web, mobile, and enterprise applications, automate workflows, digitize business processes, develop customer portals, modernize legacy systems, integrate enterprise applications, and support internal digital transformation initiatives using low-code and no-code technologies.
04
Monetization Layer
How much revenue is generated?
Assess revenue generated through software licensing, SaaS subscriptions, and cloud-based Rapid Application Development platforms offering visual development tools, workflow automation, application lifecycle management, AI-assisted development, API integration, testing, deployment, and DevOps capabilities. Additional revenue streams include implementation, customization, consulting, system integration, migration, training, managed services, technical support, maintenance, platform upgrades, cloud migration, AI-powered development features, and long-term subscription and support contracts associated with RAD platform deployments.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Low-Code/No-Code Adoption & Enterprise Digital Transformation Trends
Conducted a comprehensive analysis of low-code and no-code RAD platform adoption across industries, covering cloud-native deployment, AI-assisted development, workflow automation, DevOps integration, API connectivity, and legacy application modernization.
Helps stakeholders identify growth opportunities in enterprise digital transformation, evaluate platform adoption trends, and assess scalable RAD solutions that accelerate application delivery and operational efficiency.
Competitive Benchmarking of RAD Platform Vendors
Conducted a detailed benchmarking of leading RAD platform vendors based on product portfolio, AI capabilities, deployment models, pricing, integration capabilities, geographic presence, customer base, partnerships, and product roadmap.
Helps stakeholders compare vendor strengths, identify competitive gaps, evaluate strategic positioning, and support vendor selection and partnership decisions.
Regional Digital Transformation & Low-Code Adoption Analysis
Conducted an analysis of enterprise digital transformation initiatives, government digitization programs, cloud adoption, regulatory frameworks, and low-code/no-code adoption trends across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Helps stakeholders identify high-growth regional markets, understand policy- and technology-driven demand, and prioritize market expansion strategies.
Frequently Asked Questions About This Report
The global rapid application development platform market size was valued at USD 62.6 billion in 2025 and is estimated at USD 85.6 billion for 2026.
North America dominated with 35.3% revenue share in 2025.
The low-code development platforms segment led with a 65.9% revenue share in 2025, while no-code development platforms segment is the fastest-growing segment.
The tools segment led with a 60.9% revenue share in 2025, while the services segment is the fastest-growing segment.
The BFSI segment held the largest share (over 21.0%) in 2025, while the energy and utilities segment is the fastest-growing segment.
Key players operating in the rapid application development platform market include Appian; Google LLC; International Business Machines Corporation; Microsoft; N-iX LTD; Oracle; OutSystems; Pegasystems Inc.; Salesforce, Inc.; Zoho Corporation Pvt. Ltd.
The global rapid application development platform market is expected to grow at a CAGR of 37.0% from 2026 to 2033, reaching USD 773.8 billion by 2033.
Key factors include as organizations accelerate digital transformation initiatives and seek faster application delivery with minimal coding requirements
Asia Pacific is the fastest-growing region over the forecast period.
The cloud segment led with a 74.3% revenue share in 2025, and is the fastest-growing deployment.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


