
- Home
- »
- Healthcare IT
- »
-
Real World Evidence Solutions For Oncology Market Report, 2033GVR Report cover

Real World Evidence Solutions For Oncology Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Services, Data Sets), By Data Type (Clinical Data, Claims Data, Pharmacy Data, Genomic & Biomarker Data), By Cancer Type, By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$703.2MMarket Estimate, 2026
$761.8MMarket Forecast, 2033
$1,437.1MCAGR, 2026–2033
9.5%Real World Evidence Solutions For Oncology Market Summary
The global real world evidence solutions for oncology market size was valued at USD 703.2 million in 2025 and is projected to grow from USD 761.8 million in 2026 to USD 1,437.1 million by 2033, at a CAGR of 9.5% from 2026 to 2033. North America dominated the market, accounting for the largest share of 43.1% in 2025. The market growth is primarily driven by the increasing global cancer burden, rising adoption of real-world data (RWD) and real-world evidence (RWE) in oncology drug development and regulatory decision-making, growing demand for value-based healthcare, and expanding use of RWE to support precision oncology, post-market surveillance, and reimbursement decisions.
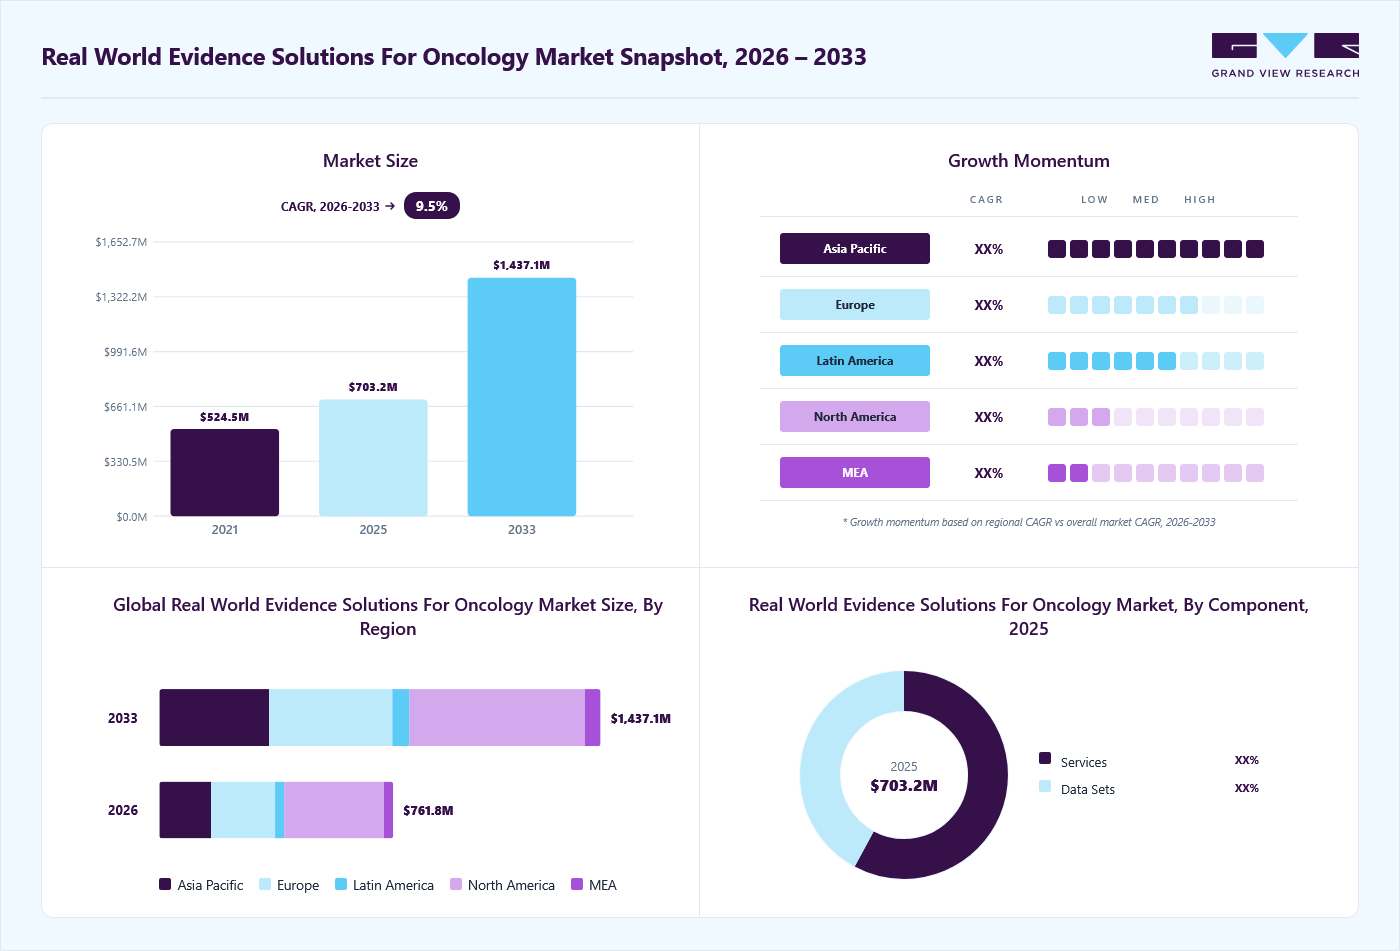 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Services segment held the largest market share of 57.8% in 2025.
- By data type: Clinical data segment held the highest market share in 2025.
- By cancer type: Breast cancer segment held the highest market share of 25.1% in 2025.
- By application: Drug development & clinical research segment held the highest market share in 2025.
- By end use: Healthcare companies segment held the highest market revenue share in 2025.
Regional Highlights
- Largest regional market: North America (43.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By Country: The U.S. dominated the North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 703.2 Million
- Estimated market size in 2026: USD 761.8 Million
- Projected market size by 2033: USD 1,437.1 Million
- CAGR (2026-2033): 9.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
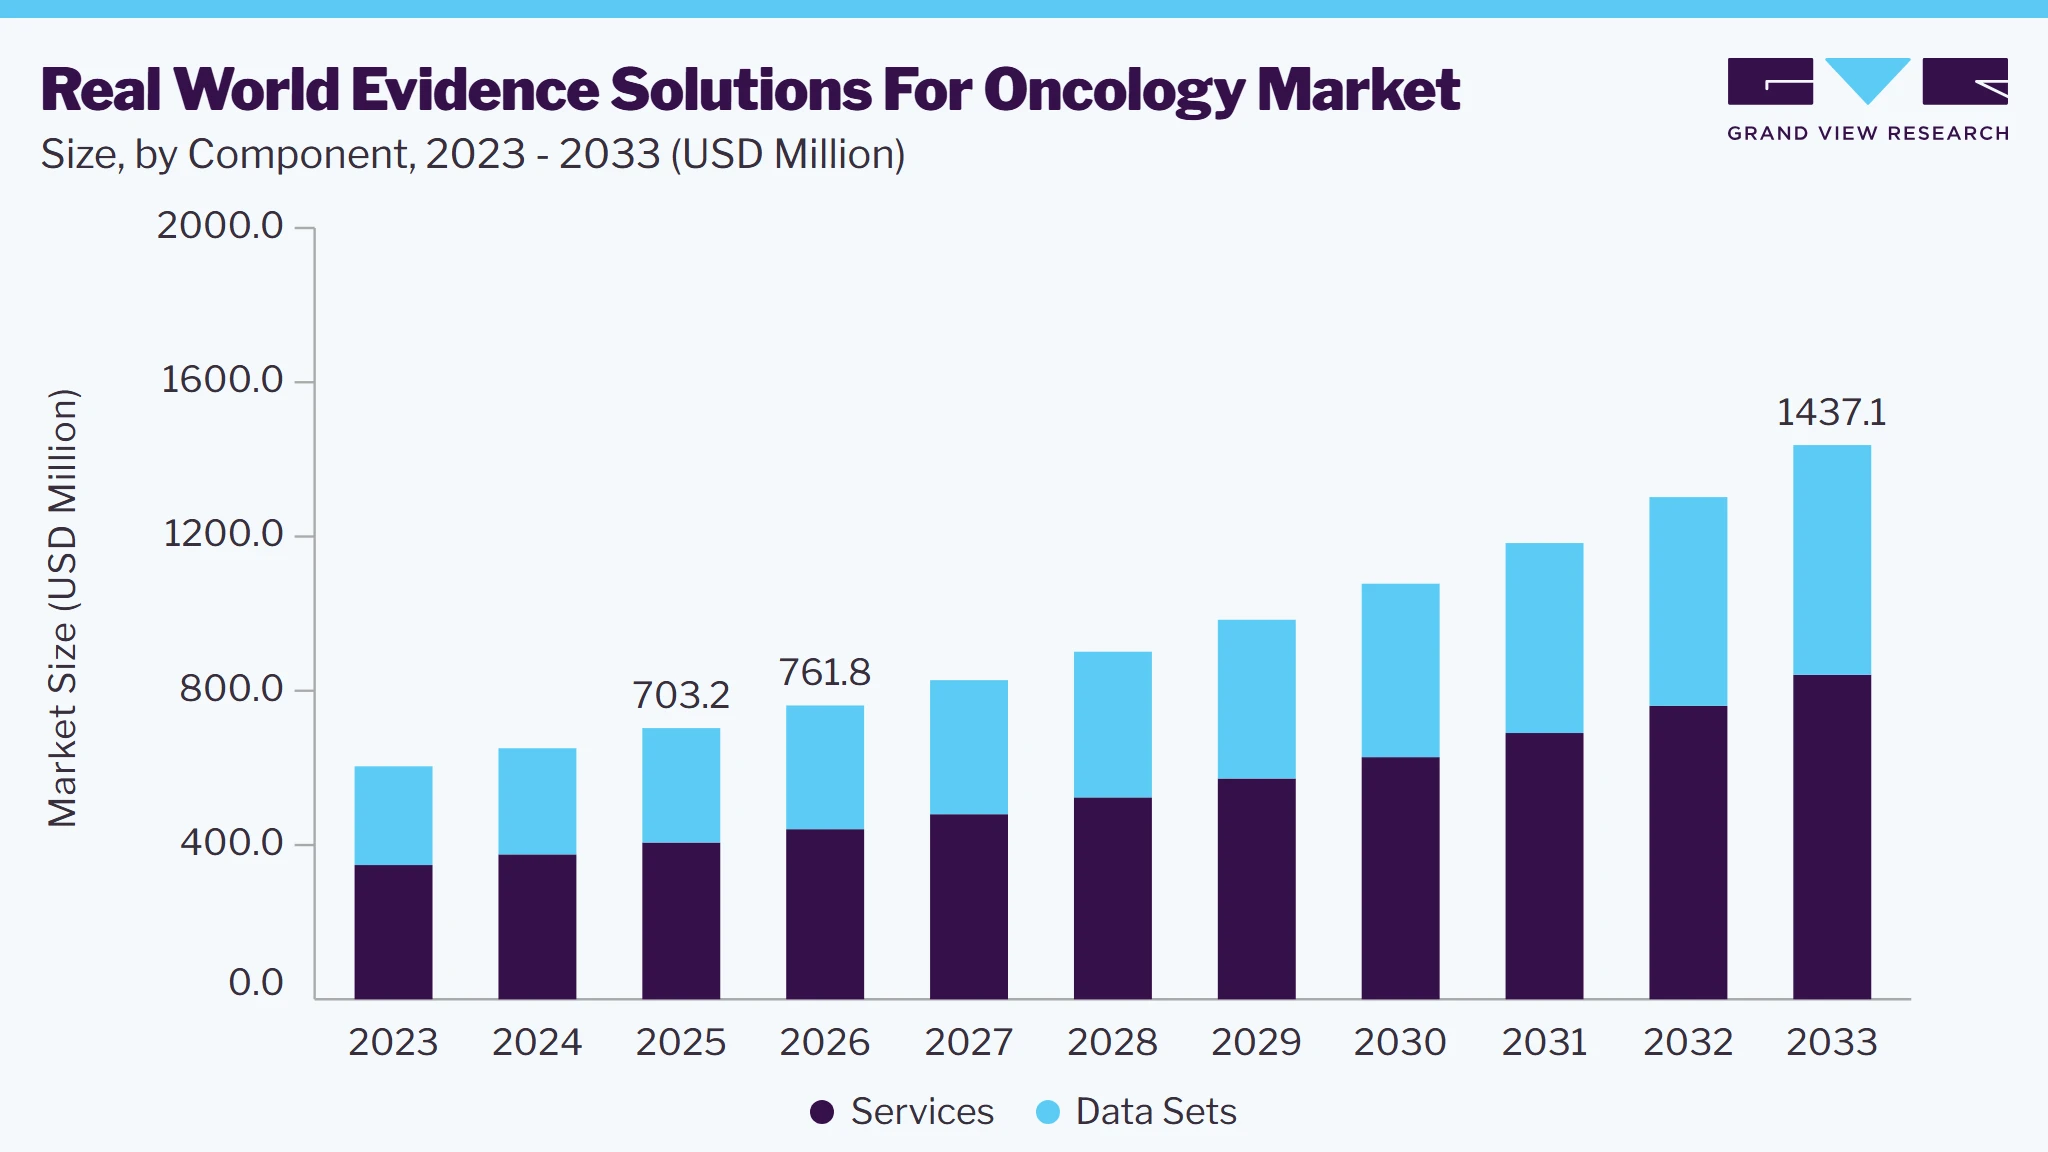 To learn more about this report, Download Free Sample Report
Market Dynamics
The real world evidence solutions for oncology market is growing due to the increasing adoption of real-world data from electronic health records, cancer registries, and genomic databases for treatment evaluation, regulatory decision-making, and personalized oncology care. Advancements in AI-driven analytics, precision medicine, and healthcare data infrastructure, along with growing collaborations among life science companies and research organizations, are further supporting market expansion.
The rising demand for cost-effective drug development is a key driver of the real-world evidence solutions for oncology market, as pharmaceutical and biotechnology companies face increasing pressure to accelerate the development of innovative cancer therapies while optimizing research costs. The growing global cancer burden has intensified the need for more efficient, data-driven development strategies. According to the American Cancer Society, 2,041,910 new cancer cases and 618,120 cancer-related deaths are projected to occur in the U.S. in 2025. Moreover, according to the WHO, the global cancer burden is expected to reach approximately 35 million new cases by 2050, with a significant increase anticipated across low- and middle-income countries. This escalating disease burden has increased the adoption of real-world evidence (RWE) solutions to generate clinically meaningful insights throughout the oncology drug development process.
Traditional clinical trials remain resource-intensive, time-consuming, and often limited in capturing diverse patient populations and long-term clinical outcomes. According to the Tufts Center for the Study of Drug Development held in October 2023, a single day of delay in drug development can cost approximately USD 800,000 in lost prescription drug or biologic sales, underscoring the economic impact of development inefficiencies. By leveraging real-world data (RWD), oncology-focused RWE solutions support improved trial design, optimized patient recruitment, treatment effectiveness assessments, and post-market evidence generation. These capabilities enable pharmaceutical and biotechnology companies to shorten development timelines, reduce costs, strengthen regulatory submissions, and support reimbursement decisions, thereby accelerating patient access to innovative oncology therapies.
Data privacy concerns are a key restraint for the real-world evidence solutions for oncology market, as oncology RWE relies on sensitive patient data from electronic health records (EHRs), cancer registries, claims databases, and genomic data. Regulations such as HIPAA in the U.S., GDPR in the EU, and evolving data protection laws in China and India impose strict requirements on data access, storage, and cross-border sharing, increasing compliance costs and research timelines. In addition, stricter patient consent requirements and data anonymization standards limit data accessibility and interoperability, creating operational challenges and slowing the generation of real-world evidence for oncology research and regulatory decision-making.
Market Concentration & Characteristics
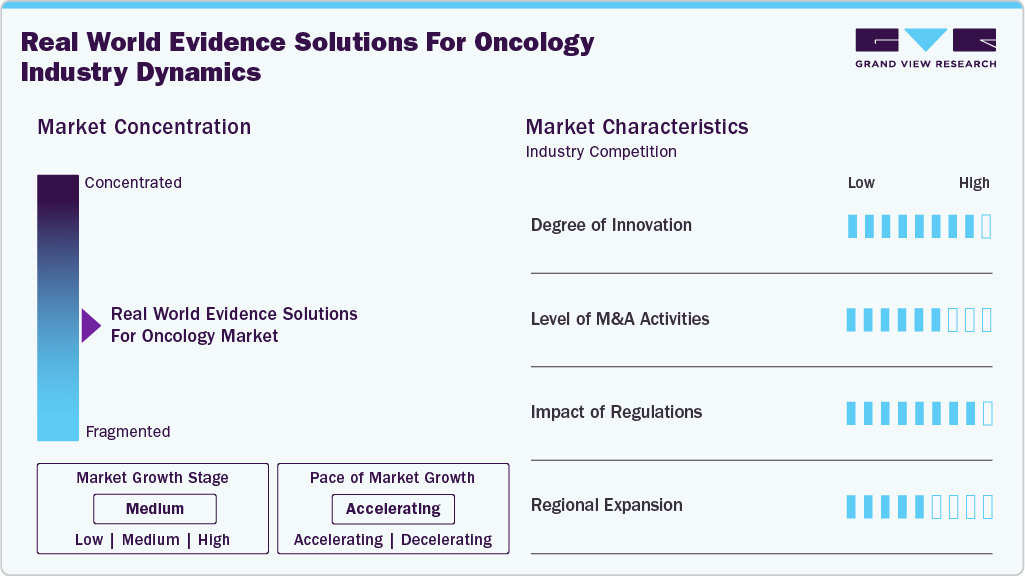
The real world evidence solutions for oncology industry is characterized by a high degree of innovation, driven by the integration of artificial intelligence (AI), machine learning, natural language processing (NLP), and multi-omics data analytics to generate robust clinical evidence. These technologies are improving patient stratification, treatment outcome analysis, and biomarker discovery, supporting precision oncology and regulatory decision-making. For instance, in May 2026, Tempus AI announced initial results from its multimodal foundation model efforts, leveraging clinical, genomic, imaging, and molecular data to generate AI-driven insights for precision oncology and real-world evidence generation.
 To learn more about this report, Download Free Sample Report
The real world evidence solutions for oncology industry is witnessing a moderate to high level of mergers, acquisitions, and strategic partnerships as companies seek to expand oncology data assets, strengthen real-world evidence capabilities, and accelerate evidence generation for drug development and market access. For instance, in March 2025 , Flatiron Health and NRG Oncology expanded their collaboration to integrate real-world data with clinical trial research, improving oncology evidence generation and supporting more efficient cancer clinical studies. This trend is expected to strengthen competitive positioning and enhance the adoption of oncology-focused RWE solutions.
“Collaborating with NRG Oncology, a leading research consortium within the National Clinical Trials Network, is an incredible opportunity to create a new trial experience—unlocking higher data quality and more efficient data acquisition with Flatiron Clinical Pipe.”
- Alex Deyle, General Manager of Clinical Research at Flatiron Health.
The regulatory impact on the real world evidence solutions for oncology market is high, as regulatory agencies increasingly recognize real-world evidence (RWE) to support oncology drug approvals, label expansions, post-marketing surveillance, and regulatory decision-making. Regulatory frameworks established by agencies such as the U.S. FDA and the European Medicines Agency (EMA) are promoting the standardized use of real-world data (RWD) while emphasizing data quality, transparency, patient privacy, and methodological rigor. These evolving guidelines are expected to improve the reliability and acceptance of oncology RWE in clinical and regulatory applications.
The real world evidence solutions for oncology market is witnessing significant regional expansion, driven by increasing adoption of electronic health records (EHRs), cancer registries, and precision oncology initiatives across developed and emerging markets. Supportive government policies promoting health data interoperability are further accelerating market growth. For instance, in January 2025, the Council of the European Union formally adopted the European Health Data Space (EHDS) Regulation to enable secure cross-border access to health data for research, innovation, and regulatory decision-making, strengthening the regional real-world evidence ecosystem.
Analyst Perspective
The real world evidence solutions for oncology market is expected to witness strong growth, driven by increasing adoption of real-world data in oncology research, clinical decision-making, and drug development. Growing focus on precision oncology, evidence-based therapies, and advanced analytics platforms is supporting market expansion. Rising integration of artificial intelligence and healthcare data solutions is further enabling efficient analysis of oncology datasets, encouraging companies to develop scalable and innovative RWE platforms.
Case Study: Leveraging Real-World Data and Machine Learning to Identify Pre-Diagnosis Lung Cancer Patients
Background:
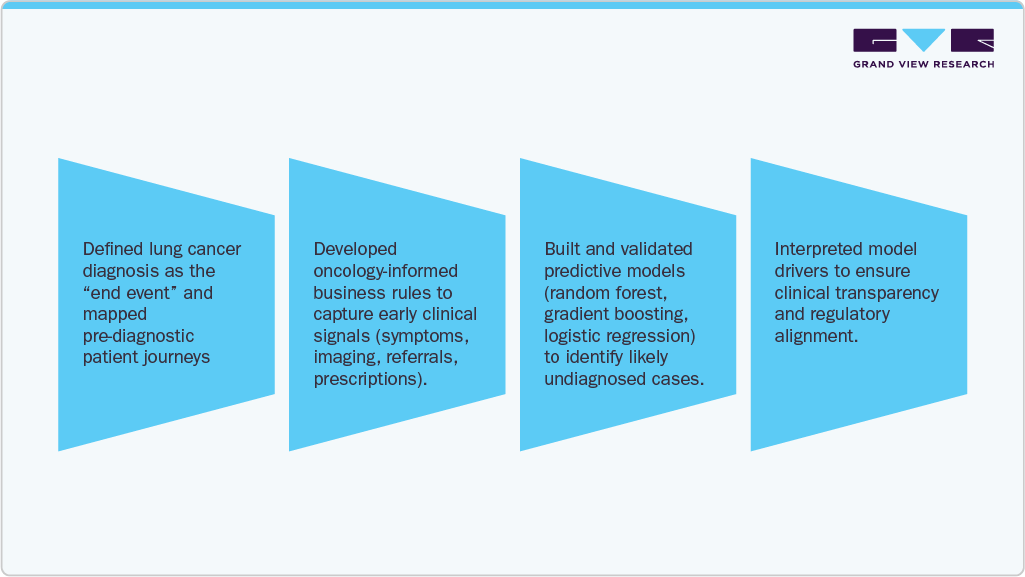
Early cancer detection is a key determinant of patient outcomes, yet lung cancer is frequently diagnosed at advanced stages. A leading life sciences company partnered with Symphony Health (ICON plc) to leverage large-scale real-world claims data and machine learning to identify patients exhibiting early signals of lung cancer prior to formal diagnosis, enabling targeted deployment of a proprietary diagnostic tool.
Key Challenges:
The client sought to proactively identify high-risk, undiagnosed lung cancer patients to support early diagnostic intervention. Traditional retrospective analyses lacked predictive capability, and there was a need to detect subtle clinical patterns earlier in the care pathway. The client required a scalable, data-driven framework to flag eligible patients before diagnosis and attribute them to relevant healthcare providers.
Solution:
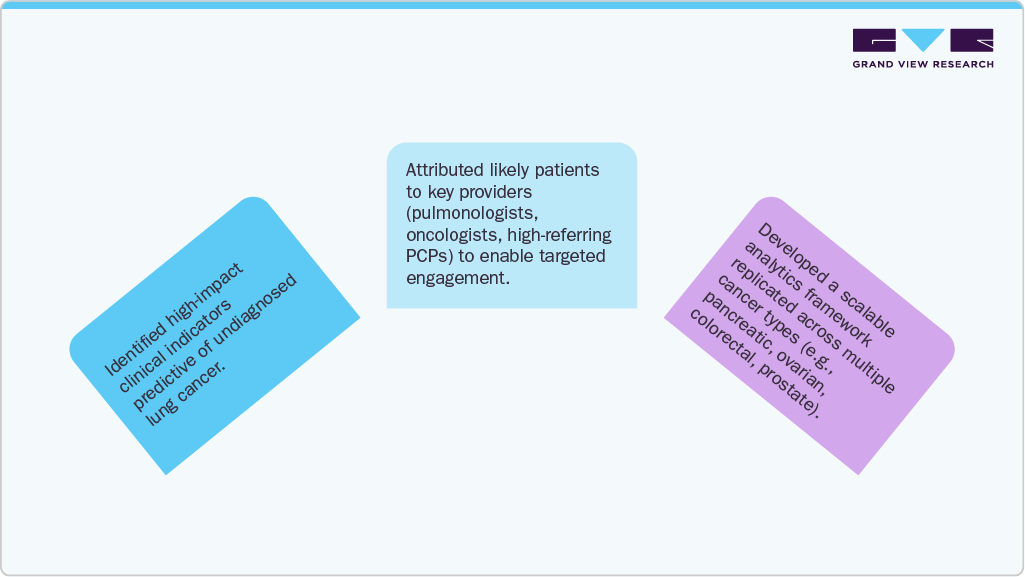
Symphony applied a data science-driven approach using the Integrated Dataverse (IDV) claims database, covering over 300 million de-identified U.S. patient lives:
 To learn more about this report, Download Free Sample Report
 To learn more about this report, Download Free Sample Report
Component Insights
The services segment dominated the market in 2025 with a share of 57.8% and is expected to grow at the fastest CAGR during the forecast period. The segment's growth is driven by the increasing demand for oncology-focused real-world evidence study design, data analytics, health economics and outcomes research (HEOR), regulatory consulting, and post-market evidence generation services. Growing outsourcing of RWE activities by pharmaceutical and biotechnology companies, coupled with the rising use of real-world evidence to support clinical development, regulatory submissions, and reimbursement decisions, is further expected to drive segment growth over the forecast period.
The data sets segment is expected to register a significant CAGR over the forecast period, driven by the increasing availability of oncology real-world data from electronic health records (EHRs), cancer registries, claims databases, and genomic databases. Rising adoption of precision oncology, AI-enabled analytics, and real-world evidence for clinical research, regulatory decision-making, and reimbursement is expected to further drive demand for high-quality oncology datasets.
Data Type Insights
The clinical data segment dominated the market with a share of 27.3% in 2025, driven by the increasing use of electronic health records (EHRs), oncology-specific clinical databases, laboratory results, pathology reports, and treatment records for real-world evidence generation. Growing adoption of precision oncology, value-based care, and regulatory acceptance of real-world evidence has further increased the demand for high-quality clinical data to support drug development, clinical decision-making, post-market surveillance, and reimbursement decisions.
The patient-generated data segment is expected to register the fastest CAGR over the forecast period, driven by the increasing adoption of wearable devices, mobile health applications, remote patient monitoring, and patient-reported outcome (PRO) platforms in oncology care. Growing emphasis on continuous monitoring of treatment response, quality of life, and symptom management is expected to accelerate the use of patient-generated data for real-world evidence generation, personalized treatment, and value-based care. For instance, in October 2025, OutcomeMD launched the first healthcare data intelligence network powered by patient-reported outcomes (PROs), enabling the integration of standardized patient-reported data with advanced analytics to support real-world evidence generation and clinical decision-making.
Cancer Type Insights
The breast cancer segment dominated the market with a share of 25.1% in 2025, driven by the high disease burden, widespread screening programs, and increasing adoption of precision oncology. The growing use of real-world evidence to evaluate long-term treatment outcomes, support regulatory decision-making, and optimize personalized care has further contributed to segment growth. According to the World Health Organization (WHO) in July 2026, an estimated 2.4 million women were diagnosed with breast cancer and approximately 694,000 deaths were reported globally, making breast cancer the most common cancer among women.
The lung cancer segment is expected to register the fastest CAGR from 2026 to 2033, driven by the increasing global burden of lung cancer, growing adoption of precision oncology, and expanding use of real-world evidence to evaluate treatment effectiveness and long-term outcomes. Rising utilization of electronic health records, genomic data, and biomarker-driven therapies is further supporting segment growth. According to the World Health Organization (WHO) in July 2026, lung cancer was the most commonly diagnosed cancer globally, accounting for approximately 2.6 million new cases and 1.86 million deaths, highlighting the growing need for oncology real-world evidence solutions.
Application Insights
The drug development & clinical research segment dominated the market with a share of 26.0% in 2025. The segment's growth is driven by the increasing use of real-world evidence to optimize clinical trial design, improve patient recruitment, evaluate treatment effectiveness, and support regulatory submissions. Growing investments in oncology drug development, coupled with the rising adoption of precision medicine and decentralized clinical trials, are further expected to drive demand for RWE solutions in clinical research.
The market access & reimbursement segment is expected to register the fastest CAGR over the forecast period, driven by the increasing use of real-world evidence to demonstrate the clinical and economic value of oncology therapies for reimbursement and pricing decisions. Growing emphasis on value-based healthcare, health technology assessments (HTAs), and payer demand for long-term effectiveness and safety data is accelerating the adoption of RWE to support market access strategies, reimbursement negotiations, and coverage decisions for innovative cancer treatments.
End Use Insights
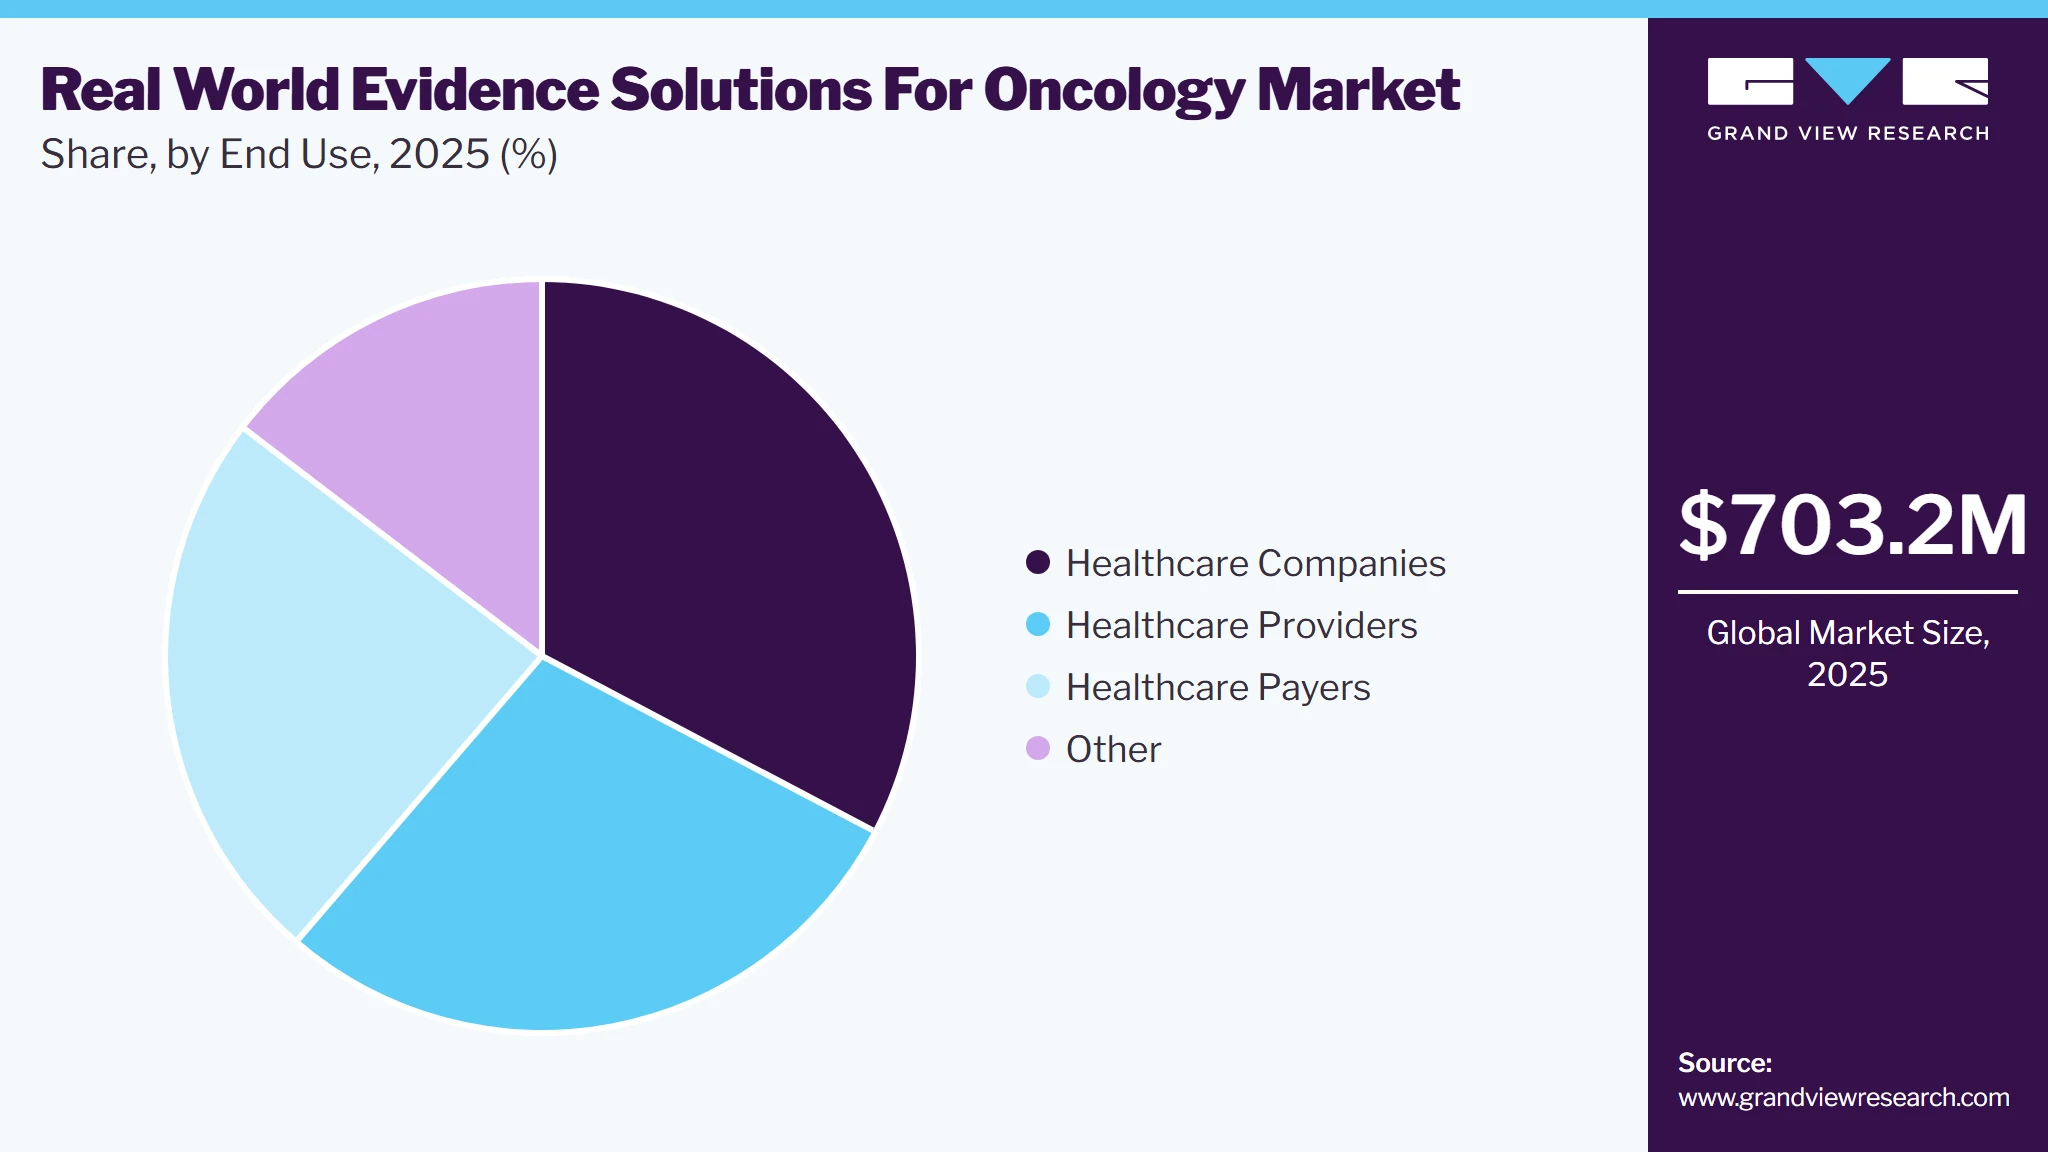
The healthcare companies segment dominated the market with a share of 32.7% in 2025, driven by the increasing adoption of real-world evidence by pharmaceutical, biotechnology, and medical device companies to support oncology drug development, regulatory submissions, post-marketing surveillance, and market access strategies. Rising investments in precision oncology and growing demand for data-driven clinical and commercial decision-making are further accelerating segment growth. For instance, in March 2026 , Guardant Health announced that real-world evidence generated through its InfinityAI platform supported the regulatory approval of ENHERTU for HER2-positive metastatic solid tumors in Japan, highlighting the growing adoption of oncology RWE by healthcare companies for regulatory decision-making.
 To learn more about this report, Download Free Sample Report
The healthcare payers segment is projected to witness the fastest CAGR over the forecast period, owing to the growing emphasis on value-based reimbursement models and cost-effective oncology care. Healthcare payers are increasingly leveraging real-world evidence to assess the comparative effectiveness, long-term safety, and economic value of cancer therapies, enabling informed coverage, pricing, and reimbursement decisions. The rising adoption of health technology assessments (HTAs) and outcomes-based payment models is further expected to support segment growth.
Regional Insights
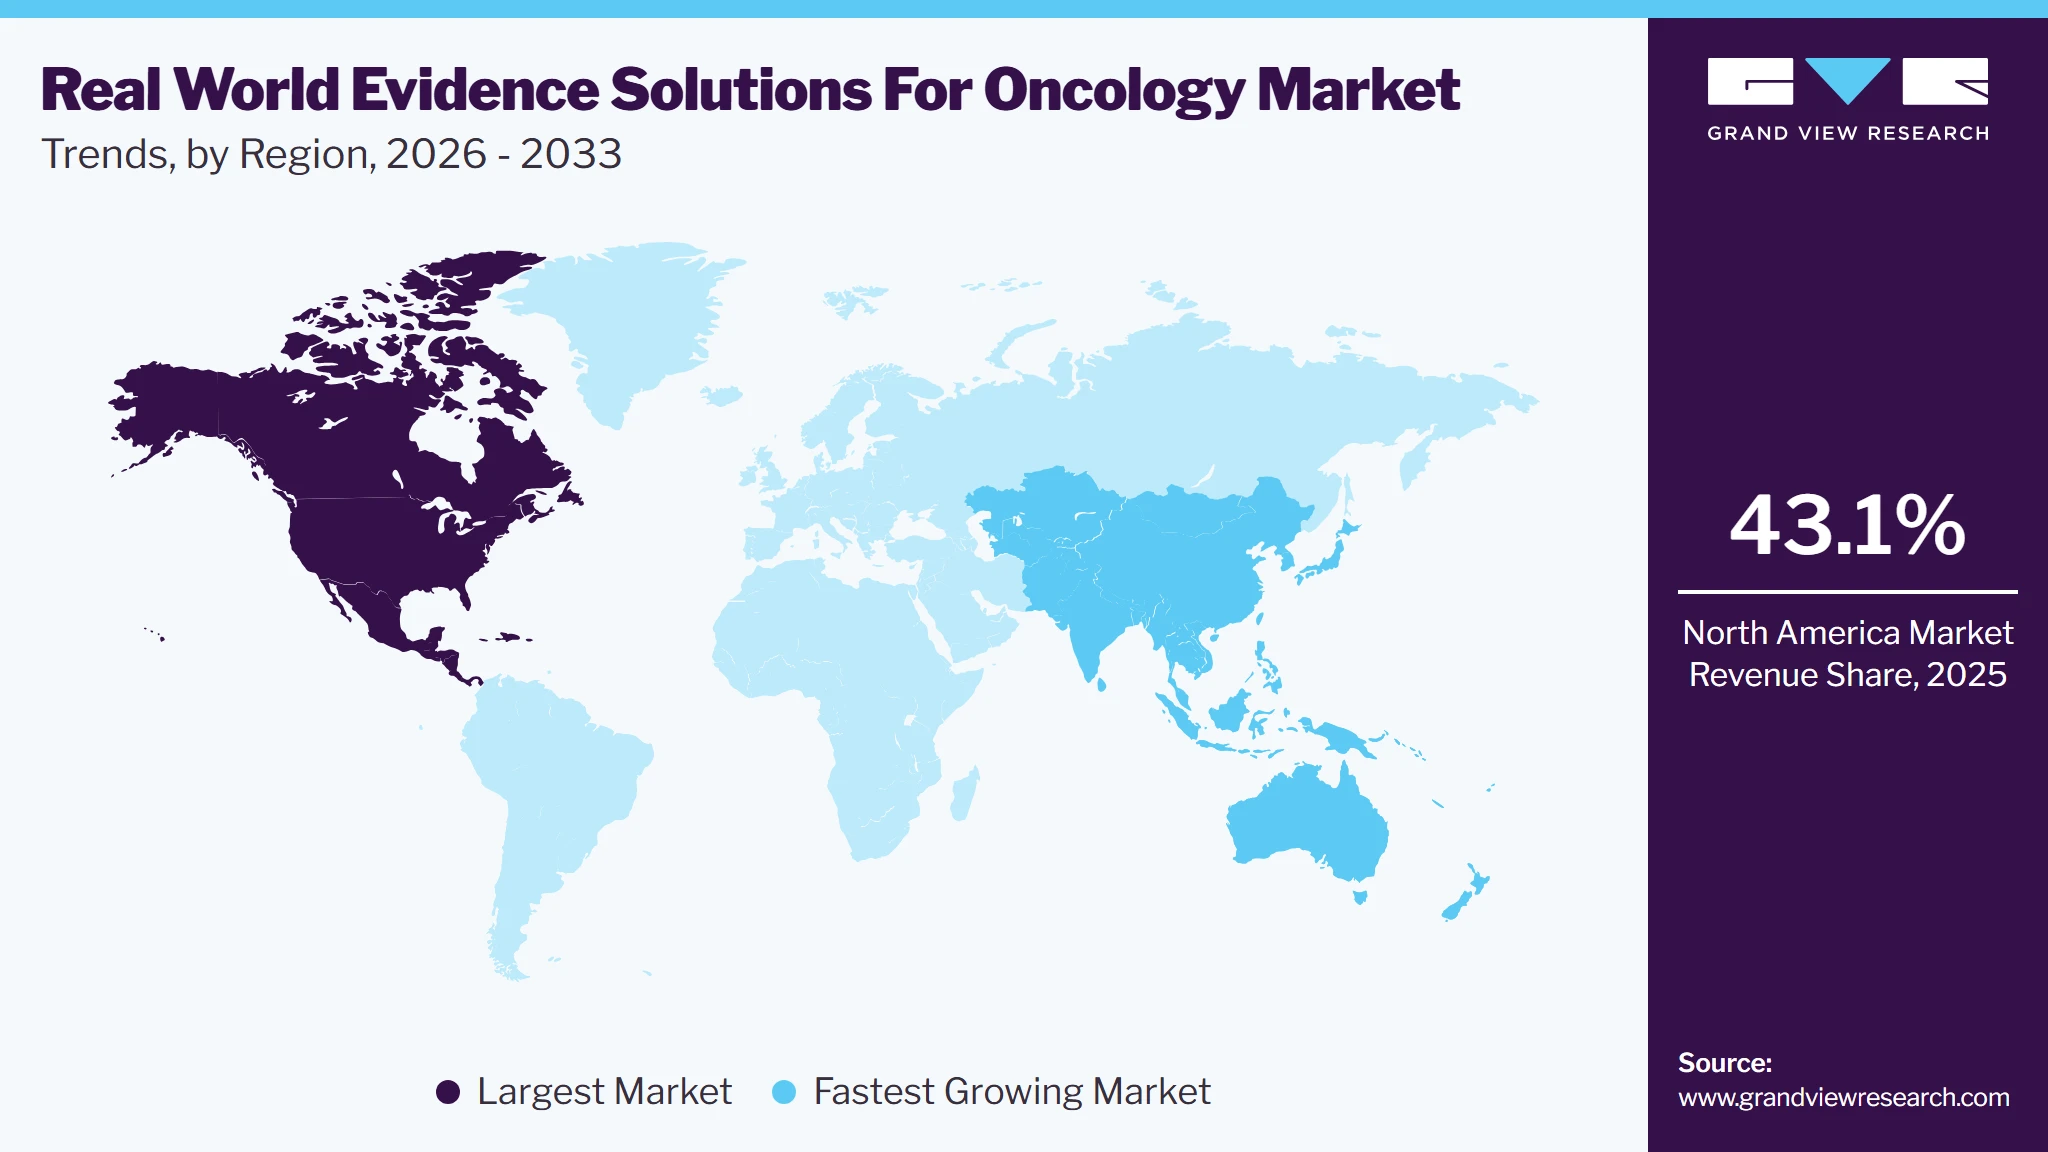
North America real world evidence solutions for oncology industrydominated the global market, accounting for the largest revenue share of 43.1% in 2025, driven by favorable regulatory support, global adoption of electronic health records (EHRs), and increasing investments in oncology research and precision medicine. According to the National Center for Science and Engineering Statistics in February 10, 2026, R&D expenditures in health sciences reached USD 38.5 billion in 2024, reflecting a USD 2.8 billion increase, while biological and biomedical sciences accounted for USD 20.8 billion, marking a USD 1.3 billion increase from 2023. Together, these fields represented 50% of total higher education R&D spending. Rising research funding and expanding clinical research activities are accelerating the generation of oncology real-world data, supporting the adoption of advanced real-world evidence solutions across the region.
 To learn more about this report, Download Free Sample Report
U.S. Real World Evidence Solutions For Oncology Market Trends
The U.S. real world evidence solutions for oncology market is witnessing significant growth, driven by increasing adoption of AI-enabled analytics, global use of electronic health records (EHRs), and growing investments in precision oncology research. The expanding use of real-world evidence to support oncology drug development, regulatory decision-making, and value-based care is further accelerating market growth. For instance, in May 2024 , Atropos Health raised USD 33 million to expand its AI-powered evidence generation platform, enabling faster production of personalized, real-world clinical insights and supporting broader adoption of RWE across healthcare providers, life sciences companies, and research organizations.
Europe Real World Evidence Solutions For Oncology Market Trends
The real world evidence solutions for oncology market in Europe was identified as a lucrative region in this industry, driven by increasing regulatory emphasis on integrating real-world data into oncology drug evaluation, reimbursement decisions, and post-market surveillance. Growing collaboration among regulatory agencies, health technology assessment (HTA) bodies, and research organizations is strengthening the adoption of real-world evidence across the region. For instance, in July 2025, the Innovative Health Initiative (IHI) launched the GREG project to develop practical guidance and tools for the use of real-world evidence in regulatory and HTA decision-making, supporting the evaluation of oncology medicines and medical devices.
The UK real world evidence solutions for oncology market held a significant share, attributed to the increasing adoption of real-world evidence in oncology research, strong government support for health data integration, and the growing use of electronic health records and cancer registries. Rising investments in precision oncology, clinical research, and data-driven healthcare decision-making are further supporting the adoption of RWE solutions across the country.
Real world evidence solutions for oncology market in Germany is anticipated to grow significantly over the forecast period, driven by the increasing adoption of real-world data to support oncology research, treatment outcome evaluation, and regulatory decision-making. Growing investments in health data infrastructure and the integration of electronic health records are strengthening the country's real-world evidence ecosystem. For instance, in November 2023 , Cegedim Health Data expanded its European THIN database to include German electronic health record data, enhancing access to longitudinal real-world datasets for clinical research and evidence generation across Europe.
Asia Pacific Real World Evidence Solutions For Oncology Market Trends
Asia-Pacific is expected to grow at the fastest CAGR of 11.3% during the forecast period, driven by the rising burden of cancer, increasing adoption of precision oncology, expanding healthcare digitalization, and growing investments in oncology research. The increasing availability of oncology-specific real-world data and supportive initiatives to strengthen evidence generation are further accelerating market growth. According to an article published by Springer Nature in April 2026, the J-CONNECT Consortium in Japan introduced the J-CONNECT database, a multi-institutional real-world oncology database integrating electronic medical records with hospital cancer registry data from Ministry of Health, Labour and Welfare-designated cancer care hospitals to support oncology research, post-marketing surveillance, and regulatory decision-making.
The China real world evidence solutions for oncology market is growing significantly, driven by increasing adoption of hospital-based real-world data, expanding oncology research, and growing regulatory acceptance of real-world evidence in drug development and evaluation. Rising collaborations between healthcare institutions and life sciences companies are further strengthening the country's oncology RWE ecosystem. For instance, in June 2024 , Parexel collaborated with Ruijin Hainan Hospital to advance real-world evidence generation in China by leveraging hospital data to support clinical research, regulatory decision-making, and evidence-based medicine, reinforcing the adoption of RWE in oncology and other therapeutic areas.
The real world evidence solutions for oncology market in Japan is witnessing rapid growth, driven by increasing adoption of oncology data platforms, expanding precision medicine initiatives, and growing use of real-world evidence for treatment evaluation and clinical research. The availability of large-scale cancer datasets and integration of genomic and clinical information are further strengthening the country’s oncology RWE ecosystem. For instance, in July 2024, the National Cancer Center Japan reported findings from the SCRUM-Japan MONSTAR project, which utilized integrated molecular profiles, treatment outcomes, and survival data from 16,144 cancer patients to support precision oncology research and evidence generation.
Latin America Real World Evidence Solutions For Oncology Market Trends
The Latin America real world evidence solutions for oncology market is growing steadily, supported by increasing cancer burden, expanding clinical research activities, improving healthcare data infrastructure, and growing adoption of digital health technologies. Rising investments in precision oncology and efforts to enhance cancer registries and electronic health record systems are improving the availability of real-world data, thereby supporting evidence generation and treatment optimization across the region.
MEA Real World Evidence Solutions For Oncology Market Trends
The real world evidence solutions for oncology industry in MEA is expected to grow gradually over the forecast period, driven by the rising cancer burden, healthcare digitalization, and increasing adoption of data-driven oncology research. However, limited healthcare infrastructure, fragmented health data systems, and restricted access to advanced research facilities may impact market growth in some countries.
Key Real World Evidence Solutions For Oncology Company Insights
The real world evidence solutions for oncology industry is characterized by the presence of established players offering advanced RWE platforms, healthcare databases, analytics solutions, and evidence-generation services. Companies such as IQVIA, Merative, PPD, Inc. (a subsidiary of Thermo Fisher Scientific Inc.), Parexel International Corporation, and ICON Plc maintain strong market positions through their comprehensive RWE capabilities supporting oncology research, regulatory submissions, and clinical decision-making. Other key players, including Oracle, Syneos Health, Cegedim group, Optum, Inc. (a subsidiary of UnitedHealth Group), SAS Institute Inc., Aetion, Inc. (acquired by Datavant), Flatiron Health, and Trinity Partners, LLC., are strengthening their presence through data analytics, AI-driven solutions, and expansion of real-world data platforms.
Key Real World Evidence Solutions For Oncology Companies
The following key companies have been profiled for this study on the real world evidence solutions for oncology market.
-
IQVIA
-
Merative
-
PPD, Inc. (a subsidiary of Thermo Fisher Scientific Inc.)
-
Parexel International Corporation
-
ICON Plc
-
Oracle
-
Syneos Health
-
Cegedim group
-
Optum, Inc. (a subsidiary of UnitedHealth Group)
-
SAS Institute Inc.
-
Aetion, Inc. (acquired by Datavant)
-
Flatiron Health
-
Trinity Partners, LLC.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IQVIA, Merative, PPD Inc. (Thermo Fisher Scientific), Parexel International Corporation, etc.)
Focus on developing integrated real-world evidence (RWE) platforms combining healthcare data sources, analytics, AI, and clinical research capabilities to support oncology decision-making.
Strong access to diverse oncology datasets, including clinical, claims, genomic, and patient-level data, enabling comprehensive evidence generation.
High complexity in managing diverse healthcare data sources and ensuring data quality, interoperability, and regulatory compliance.
Emerging Players (Aetion, Inc. (acquired by Datavant), Flatiron Health, Cegedim Group, Trinity Partners LLC)
Focus on specialized oncology-focused RWE platforms, advanced analytics, and evidence generation solutions for targeted clinical and commercial applications.
Greater flexibility and specialization in developing customized RWE solutions compared with large diversified providers.
Limited global scale, resources, and data coverage compared with large CRO and healthcare technology companies.
Recent Developments:
-
In July 2026, Flatiron Health expanded its global oncology network through its first partnership in Scotland. The collaboration aimed to enhance oncology real-world evidence generation by connecting healthcare data resources, supporting clinical research, and advancing data-driven cancer care initiatives.
-
In May 2026, Omny Health surpassed the 175-million patient milestone and launched an oncology product suite designed to address complex real-world evidence gaps by enhancing data accessibility and analytics capabilities for clinical research and healthcare decision-making across oncology applications globally.
-
In May 2026, Flatiron Health launched Flatiron Telescope, an AI-powered platform delivering rapid oncology insights from real-world data to support evidence generation, clinical research, and decision-making. The platform enabled users to access oncology intelligence efficiently through analytics and data integration.
-
In May 2026, Parexel presented real-world oncology research and introduced a patient-focused campaign at ASCO 2026. The initiative highlighted the company’s efforts in leveraging real-world evidence to advance oncology research, improve patient engagement, and support evidence-based healthcare decision-making.
-
In March 2026, Massive Bio launched NexusPulse, an AI-powered real-time signal engine designed for oncology markets. The platform enabled advanced analytics, evidence generation, and actionable insights by leveraging healthcare data to support oncology research, clinical decision-making, and market intelligence.
-
In December 2023, Syapse renewed its collaboration with the U.S. Food and Drug Administration (FDA) to utilize real-world data in oncology research. The initiative supported regulatory science, enhanced evidence generation, and advanced the evaluation of cancer treatments through real-world oncology data analytics.
Real World Evidence Solutions For Oncology Market Report Scope
Report Attribute
Details
Market size in 2025
USD 703.2 million
Estimated Market size in 2026
USD 761.8 million
Projected market size by 2033
USD 1,437.1 million
Growth rate
CAGR of 9.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, data type, cancer type, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
IQVIA; Merative; PPD, Inc. (a subsidiary of Thermo Fisher Scientific Inc.); Parexel International Corporation; ICON Plc; Oracle; Syneos Health; Cegedim group; Optum, Inc. (a subsidiary of UnitedHealth Group); SAS Institute Inc.; Aetion, Inc. (acquired by Datavant); Flatiron Health; Trinity Partners, LLC.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Real World Evidence Solutions For Oncology Market Report Segmentation
This report forecasts revenue growth and provides an analysis on the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global real world evidence solutions for oncology market report on the basis of component, data type, cancer type, application, end use, and region:
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Services
-
Data Sets
-
-
Data Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Clinical Data
-
Claims Data
-
Pharmacy Data
-
Patient-Generated Data
-
Cancer Registry Data
-
Genomic & Biomarker Data
-
-
Cancer Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Breast Cancer
-
Lung Cancer
-
Colorectal Cancer
-
Prostate Cancer
-
Hematologic Malignancies
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Drug Development & Clinical Research
-
Regulatory Decision Making
-
Market Access & Reimbursement
-
Post-Market Safety Monitoring
-
Precision Oncology
-
Comparative Effectiveness Research
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Healthcare Companies
-
Clinical research
-
Commercial (inclusive of marketing, etc.)
-
HEOR
-
Others (market access, etc.)
-
-
Healthcare Payers
-
Healthcare Providers
-
Other
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The real world evidence solutions for oncology marketfigures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with eachreal world evidence solutions for oncology segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Component
Revenue Capture Definition
Services
Revenue generated from real world evidence (RWE) services that support the collection, integration, analysis, and interpretation of oncology-related real-world data. These services include evidence generation, data analytics, regulatory support, clinical research services, health economics and outcomes research (HEOR), and consulting solutions that help stakeholders derive actionable insights for oncology decision-making.
Data Sets
This segment captures income from oncology-focused real-world data repositories and datasets used for evidence generation and clinical insights. These datasets include structured and unstructured healthcare information collected from multiple sources such as electronic health records, claims databases, registries, and other healthcare information platforms used for oncology research and analysis.
Segment- Data Type
Revenue Capture Definition
Clinical Data
Revenue derived from RWE solutions utilizing clinical data generated during routine patient care, including electronic health records, clinical documentation, laboratory results, treatment patterns, and outcomes data. These datasets support oncology research, treatment evaluation, clinical decision-making, and evidence generation activities.
Claims Data
This segment reflects income from solutions that analyze healthcare claims information, including diagnosis codes, treatment procedures, healthcare utilization patterns, and reimbursement records. Claims-based RWE supports studies related to treatment pathways, healthcare costs, resource utilization, and outcomes assessment in oncology.
Pharmacy Data
Market value in this category stems from real-world evidence solutions leveraging pharmacy-related datasets, including prescription records, medication dispensing information, adherence patterns, and treatment histories to evaluate oncology drug utilization and patient outcomes.
Patient-Generated Data
Revenue originates from platforms and services that incorporate patient-generated information, including patient-reported outcomes, wearable device data, digital health records, and other patient-driven sources. These data types support treatment monitoring, quality-of-life assessment, and personalized oncology care approaches.
Cancer Registry Data
This segment captures income from solutions utilizing cancer registry datasets containing information on cancer incidence, diagnosis, treatment patterns, survival outcomes, and epidemiological trends. These datasets support population-level oncology research, surveillance, and clinical studies.
Genomic & Biomarker Data
Revenue is generated from RWE solutions integrating genomic information, molecular profiles, and biomarker data with clinical datasets to enable precision oncology research, patient stratification, treatment response analysis, and targeted therapy development.
Segment- Cancer Type
Revenue Capture Definition
Breast Cancer
Revenue generated from real-world evidence solutions focused on breast cancer research, including treatment pattern analysis, patient outcomes evaluation, therapy effectiveness assessment, and healthcare resource utilization studies.
Lung Cancer
This segment captures income from RWE platforms and analytics solutions supporting lung cancer research through evaluation of treatment outcomes, biomarker-driven therapies, clinical pathways, and real-world treatment effectiveness.
Colorectal Cancer
Market value in this category arises from oncology RWE solutions used to analyze colorectal cancer treatment patterns, disease progression, therapeutic outcomes, and comparative effectiveness of available interventions.
Prostate Cancer
Revenue originates from real-world evidence applications focused on prostate cancer management, including treatment utilization analysis, patient outcomes research, therapy sequencing, and evaluation of clinical effectiveness.
Hematologic Malignancies
This segment reflects earnings from RWE solutions supporting research in blood cancers such as leukemia, lymphoma, and myeloma through analysis of treatment response, disease progression, and real-world clinical outcomes.
Others
Includes revenue from real-world evidence solutions applied across additional cancer types, including rare and less prevalent malignancies, where real-world datasets are used for clinical research, treatment evaluation, and evidence generation.
Segment- Application
Revenue Capture Definition
Drug Development & Clinical Research
Revenue generated from RWE solutions used to support oncology drug development, clinical trial optimization, patient recruitment, treatment outcome analysis, and evidence generation throughout the research and development lifecycle.
Regulatory Decision Making
This segment captures income from real-world evidence platforms used to support regulatory submissions, safety assessments, post-approval evidence generation, and evaluation of treatment effectiveness by regulatory stakeholders.
Market Access & Reimbursement
Market value in this category stems from RWE solutions that provide evidence for healthcare value assessments, pricing strategies, reimbursement decisions, payer negotiations, and evaluation of healthcare economic outcomes.
Post-Market Safety Monitoring
Revenue originates from solutions used for continuous monitoring of oncology therapies after commercialization, including adverse event identification, long-term safety evaluation, and assessment of real-world treatment performance.
Precision Oncology
This segment reflects earnings from RWE solutions integrating clinical, molecular, and genomic data to support personalized treatment selection, biomarker-driven therapies, patient segmentation, and targeted oncology approaches.
Comparative Effectiveness Research
Revenue is generated from analytical solutions that compare treatment outcomes, safety profiles, healthcare utilization, and effectiveness of oncology therapies across different patient populations and care settings.
Segment- End Use
Revenue Capture Definition
Healthcare Companies
Revenue generated from real-world evidence solutions adopted by pharmaceutical and biotechnology companies, medical technology companies, and other healthcare organizations for oncology research, clinical development, commercial strategy, health economics and outcomes research (HEOR), market access planning, and evidence-based decision-making activities.
Healthcare Payers
This segment captures income from RWE solutions utilized by insurance providers, government healthcare programs, and other payer organizations to evaluate treatment value, reimbursement strategies, healthcare costs, and patient outcomes in oncology care.
Healthcare Providers
Market value in this category stems from RWE platforms used by hospitals, cancer centers, and healthcare delivery organizations to analyze clinical outcomes, optimize treatment pathways, improve quality of care, and support evidence-based oncology practices.
Other
Includes revenue from government agencies, research organizations, contract research organizations (CROs), and other stakeholders utilizing real-world evidence solutions for oncology research, healthcare planning, and population health initiatives.
Estimation Model
Section
Title
Description
Top-Down
Commodity Flow Analysis
Market size was estimated by analyzing revenues generated by real world evidence (RWE) solution providers offering oncology-focused data analytics, clinical data management solutions, and consulting services. Data were collected from company annual reports, investor presentations, product offerings, industry databases, and secondary sources. Revenue contributions from private companies were assessed through market intelligence sources and validated through primary interviews to derive the overall market value.
Parent Market
Parent Market & Penetration-Based Analysis
The real world evidence solutions market was evaluated within the broader real world evidence solutions market. Adoption rates of RWE platforms across oncology research, clinical trials, regulatory submissions, post-market surveillance, and healthcare decision-making were analyzed. The penetration of oncology-specific RWE applications among pharmaceutical companies, healthcare providers, payers, and research organizations was assessed to estimate the addressable market and segment-level opportunities.
Segmentation
Country-Level Segment Share Modeling
Market shares for component, data type, cancer type, application, and end-use segments were derived using country-specific oncology burden, availability of healthcare databases, electronic health record (EHR) adoption, clinical research activity, regulatory acceptance of real world data, and pharmaceutical R&D investments. Weighted average calculations were applied to determine regional and global segment distributions.
Validation
Data Triangulation & Validation Model
Market estimates were validated through triangulation of secondary research, primary interviews, company-level revenue assessments, oncology data utilization analysis, healthcare database adoption trends, and demand-side evaluations to ensure consistency and accuracy across all market segments and geographies.
Forecasting
Forecasting & CAGR Modeling
Market forecasts were developed using historical trends in oncology research, increasing adoption of precision medicine, growth in clinical data generation, rising demand for evidence-based healthcare decisions, regulatory acceptance of real world evidence, and expansion of AI-driven healthcare analytics. Regression-based analysis and trend modeling were applied to project future market growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis of Data Types by Application
Developed a customized cross-segmentation analysis mapping clinical, claims, pharmacy, patient-generated, cancer registry, and genomic & biomarker data across key applications including drug development & clinical research, regulatory decision-making, market access & reimbursement, post-market safety monitoring, precision oncology, and comparative effectiveness research. The assessment identifies data utilization patterns, evidence requirements, and adoption trends across each application area.
Enables clients to identify the most valuable data–application combinations, optimize evidence generation strategies, prioritize investments in high-growth oncology RWE use cases, and align data acquisition with regulatory, clinical, and commercial objectives.
Stakeholder & End User Adoption Assessment
Delivered a comprehensive analysis of RWE adoption across healthcare companies (clinical research, commercial, HEOR, and market access), healthcare providers, payers, and other stakeholders. Included evaluation of evidence requirements, purchasing behavior, reimbursement priorities, and real-world data utilization across the oncology ecosystem.
Helps clients understand stakeholder-specific demand, refine commercial and HEOR strategies, strengthen value demonstration for payers and providers, and optimize customer targeting and product positioning.
Competitive Intelligence & Regional Opportunity Assessment
Conducted detailed benchmarking of leading oncology RWE solution providers based on service offerings, proprietary data assets, technology capabilities, AI/analytics platforms, oncology partnerships, geographic presence, regulatory expertise, and strategic collaborations. Complemented with regional and country-level assessment of oncology research activity, regulatory landscape, and RWE adoption trends.
Supports competitive positioning, identifies whitespace opportunities, evaluates partnership and acquisition prospects, prioritizes high-growth regional markets, and enables informed commercialization and expansion strategies.
Frequently Asked Questions About This Report
The global real world evidence solutions for oncology market size was estimated at USD 703.2 million in 2025 and is expected to reach USD 761.8 million in 2026.
The global real world evidence solutions for oncology market is expected to grow at a compound annual growth rate of 9.5% from 2026 to 2033 reach USD 1,437.1 million by 2033.
The services segment held the highest market share of 57.8% in 2025.
The North America real world evidence solutions for oncology market held the largest share of 43.1% of the global market in 2025.
Key factors that are driving the market growth include increasing global cancer burden, rising adoption of real-world data (RWD) and real-world evidence (RWE) in oncology drug development and regulatory decision-making, growing demand for value-based healthcare, and expanding use of RWE to support precision oncology, post-market surveillance, and reimbursement decisions
Some key players operating in the real world evidence solutions for oncology market include IQVIA; Merative; PPD, Inc. (a subsidiary of Thermo Fisher Scientific Inc.); Parexel International Corporation; ICON Plc; Oracle
Asia Pacific is the fastest-growing region over the forecast period.
The clinical data segment held the highest market share in 2025.
The breast cancer segment held the highest market share of 25.1% in 2025.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


