
- Home
- »
- Electronic Devices
- »
-
RF Interconnect Market Size And Share Report, 2026-2033GVR Report cover
![RF Interconnect Market (2026 - 2033)Report]()
RF Interconnect Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (RF Cable, RF Cable Assembly), By Frequency (Upto 6GHz, Upto 50GHz, Above 50GHz), By End Use (Aerospace & Defense, Medical), By Region, And Segment Forecasts
Market Size, 2025
$35.3BMarket Estimate, 2026
$37.8BMarket Forecast, 2033
$66.4BCAGR, 2026–2033
8.4%RF Interconnect Market Summary
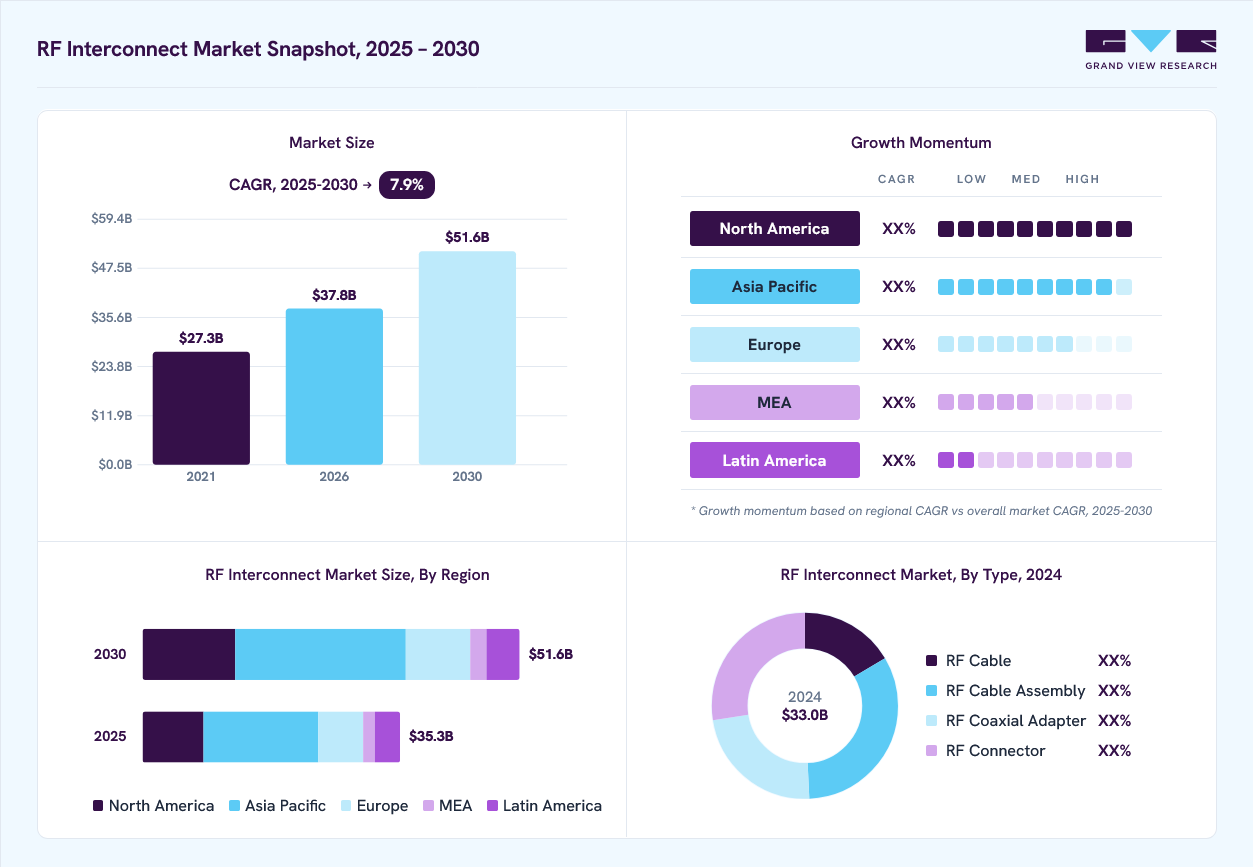
The global RF interconnect market size was valued at USD 35.3 billion in 2025 and is projected to grow from USD 37.8 billion in 2026 to USD 66.4 billion by 2033, at a CAGR of 8.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 44.6% in 2025. The growing deployment of 5G networks, satellite communication systems, and high-frequency wireless technologies is accelerating demand for advanced RF interconnects, RF connectors, and coaxial cable assemblies that enable reliable, low-loss, and high-speed signal transmission across telecommunications, aerospace, defense, and data center applications.
Key Market Trends & Insights
- By type: RF cable assembly segment dominated the market, with a revenue share of 32.6% in 2025.
- By frequency: Upto 50 GHz segment held the largest market share of 41.2% in 2025.
- By end user: Industrial segment held the significant revenue share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (44.6% revenue share, 2025)
- Fastest growing regional market: North America (highest CAGR, 2026–2033)
- By country: China held the largest market share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 35.3 Billion
- Estimated market size in 2026: USD 37.8 Billion
- Projected market size by 2033: USD 66.4 Billion
- CAGR (2026–2033): 8.4%
Their performance is defined by attributes such as low insertion loss, high shielding, mechanical stability, and environmental resistance. As frequency demands increase with the adoption of 5G, interconnect precision efficiency becomes critical. High-power and mission-critical systems often rely on custom-engineered interconnects for secure data transmission. The global RF interconnect market is growing due to the widespread deployment of 5G networks. High-frequency infrastructure requires precise, low-loss signal routing between antennas and radio units. RF interconnects are critical in supporting massive MIMO and beamforming applications in 5G systems. Telecom operators are scaling up small cell installations, boosting demand for compact and high-performance types.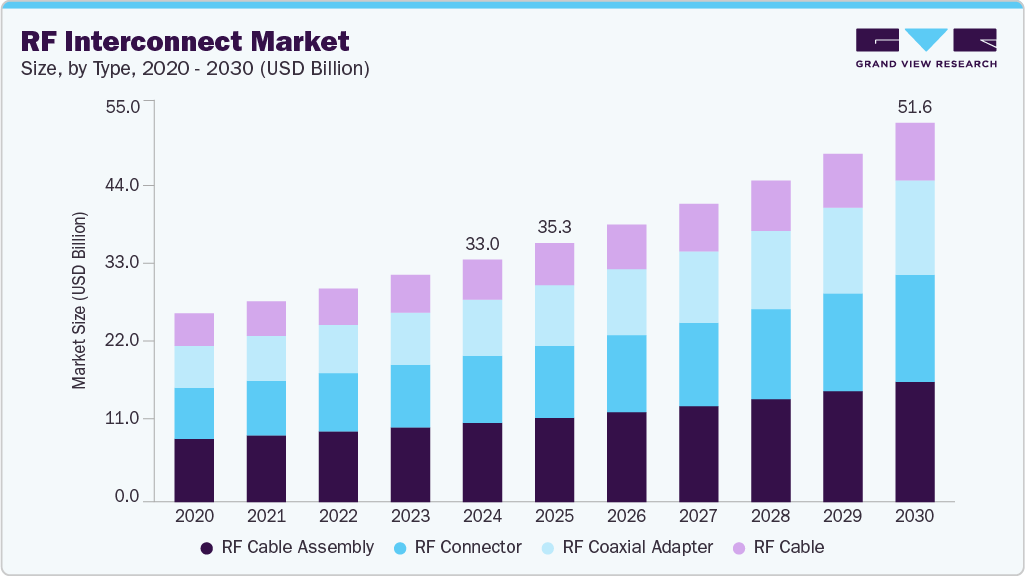
RF interconnects are now required to perform consistently across broader bandwidths and higher data rates. Emerging technologies such as active phased arrays and compact radar systems are increasing system density, which requires smaller, more efficient types. Environmental factors such as vacuum conditions, radiation exposure, and thermal cycling make material selection and mechanical design critical. Regulatory bodies also mandate compliance with standards like MIL-STD, IPC, and RoHS, especially in defense and aerospace. The shift toward modular, software-defined platforms adds pressure to deliver compact, reconfigured interconnect systems.
Furthermore, market participants include global RF type manufacturers, regional suppliers, and specialized contract assemblers. Many companies are investing in R&D to support next-generation telecom, defense, and satellite systems. Strategic collaborations are forming between OEMs and RF specialists to accelerate product development and integration. Government funding for space programs and communication infrastructure continues to drive market expansion. Suppliers are responding by offering localized manufacturing, faster prototyping, and vertically integrated capabilities. Differentiation is shifting toward advanced materials, tighter manufacturing tolerances, and shorter lead times. Companies with diverse products and certifications are preferred for large-scale procurement.
Market Dynamics
The RF Interconnect Market is driven by the rapid expansion of 5G infrastructure, increasing adoption of wireless communication systems, and growing demand for high-performance RF connectors, RF cable assemblies, and coaxial interconnect solutions across telecommunications and networking applications. Rising investments in aerospace and defense electronics, satellite communication networks, and radar systems are accelerating the deployment of advanced RF components capable of supporting high-frequency and low-loss signal transmission. The proliferation of connected devices, Internet of Things (IoT) technologies, and next-generation data centers is further strengthening demand for reliable radio frequency interconnects that ensure superior signal integrity and bandwidth performance. Additionally, expanding semiconductor manufacturing activities and the increasing integration of RF technologies in automotive electronics, autonomous vehicles, and industrial automation systems are creating new growth opportunities for market participants. Continuous innovation in high-speed connectivity solutions, miniaturized RF products, and advanced communication infrastructure is expected to sustain the long-term growth of the RF interconnects industry.
The rapid expansion of 5G networks is emerging as a key growth driver for the RF interconnect market, creating substantial demand for high-performance RF connectors, RF cable assemblies, and microwave interconnect solutions. Telecom operators are increasing investments in network densification, small-cell deployment, and high-frequency spectrum utilization to support rising mobile data traffic. This trend is driving the adoption of advanced radio frequency components capable of delivering low insertion loss and superior signal integrity. Growing implementation of private 5G networks across industrial and enterprise environments is further strengthening market demand. As communication networks become more complex, the need for reliable RF connectivity solutions continues to increase across both developed and emerging economies.
The deployment of next-generation wireless technologies is also accelerating demand for coaxial connectors, RF adapters, and high-bandwidth communication systems. Network equipment manufacturers are focusing on upgrading infrastructure to support higher frequencies and faster data transmission speeds. The expansion of smart cities, connected transportation systems, and IoT ecosystems is creating additional requirements for robust RF transmission architectures. Increasing investments in telecom modernization projects are encouraging innovation across the RF interconnect industry. These developments position advanced RF connectivity technologies as a critical component of future communication infrastructure.
Persistent supply chain disruptions and fluctuating raw material prices continue to challenge the growth of the RF interconnect market. Manufacturers of RF cable connectors, precision interconnects, and high-frequency assemblies face increasing procurement costs for specialty metals and engineered materials. Extended lead times for critical electronic components can delay production schedules and impact delivery commitments. These challenges place pressure on profit margins and increase operational complexity for market participants. Smaller suppliers are particularly vulnerable to cost inflation and inventory management risks.
The growing technical complexity of advanced RF communication components further amplifies manufacturing challenges. High-performance interconnect solutions require stringent quality standards, specialized testing processes, and precision engineering capabilities. Rising production costs can limit adoption among cost-sensitive customers, particularly in developing markets. In addition, geopolitical uncertainties and trade restrictions continue to influence global sourcing strategies. These factors collectively act as a restraint on the broader expansion of the radio frequency interconnect market.
The increasing commercialization of space and expansion of satellite communication networks present a significant opportunity for the RF interconnects industry. Demand for advanced RF coaxial assemblies, high-reliability connectors, and microwave transmission components is rising across satellite, launch vehicle, and ground station applications. Governments and private companies are investing heavily in low-earth-orbit (LEO) satellite constellations to enhance global connectivity. These initiatives require highly durable RF solutions capable of operating in demanding environmental conditions. As satellite deployments increase, manufacturers are expected to benefit from a growing addressable market.
The evolution of space-based broadband services is creating new opportunities for suppliers of specialized high-frequency interconnect systems. Emerging applications in earth observation, defense communications, and satellite-enabled IoT networks are generating sustained demand for advanced connectivity technologies. Increasing investments in national space programs and commercial aerospace projects are expanding procurement activity across the RF value chain. Product innovation focused on lightweight, miniaturized, and high-performance interconnect designs is enabling broader adoption in next-generation spacecraft platforms. This trend is expected to unlock substantial long-term growth opportunities for the global RF interconnect market.
Market Concentration & Characteristics
The RF Interconnect Market exhibits a moderately concentrated competitive landscape, characterized by the presence of established global manufacturers alongside numerous specialized regional suppliers. Leading companies compete through product innovation, broad product portfolios, and strong relationships with telecommunications, aerospace, defense, and industrial customers. Market participants are increasingly investing in advanced RF connectors, RF cable assemblies, and high-frequency interconnect solutions to strengthen their market position. The combination of technological expertise and stringent performance requirements creates moderate barriers to entry for new competitors.
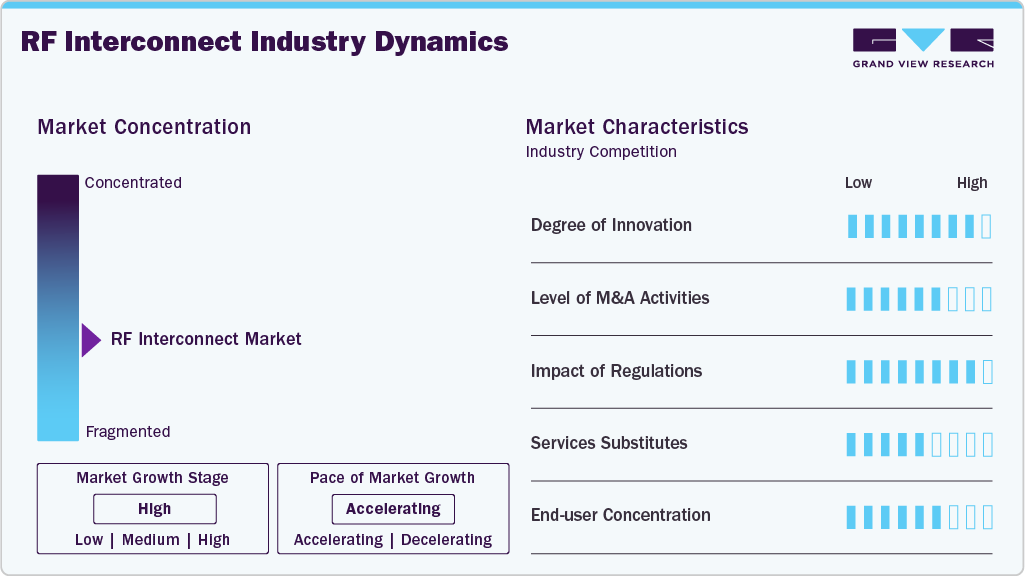
The market is characterized by a high degree of innovation driven by the rapid evolution of 5G infrastructure, satellite communications, and next-generation wireless technologies. Industry participants focus on developing low-loss, high-bandwidth, and miniaturized RF interconnect solutions to address emerging application requirements. Regulatory compliance, quality certifications, and reliability standards play a significant role in product development and commercialization strategies. Furthermore, growing demand from telecommunications, aerospace, defense, automotive electronics, and data center applications continues to accelerate market growth and competitive differentiation.
Analyst Perspective
The RF interconnect market is experiencing strong growth driven by the expansion of 5G infrastructure, satellite communications, and high-frequency communication systems. Increasing demand for RF connectors, cable assemblies, coaxial adapters, and cables is supporting reliable, low-loss signal transmission. Advancements in wireless technologies, mmWave networks, and next-generation connectivity, along with rising investments in aerospace & defense, industrial automation, medical devices, and data centers, are expected to drive sustained market growth throughout the forecast period.
Type Insights
Based on Type, the RF Cable Assembly segment led the market with the largest revenue share of 32.6% in 2025, driven by trends for miniaturization and the adoption of advanced materials to address the needs of high-frequency, high-bandwidth applications. The rollout of 5G and the upcoming shift to 6G networks are driving a sharp increase in demand for dependable, high-performance assemblies that can support resilient telecom and IoT infrastructures.To meet these requirements, manufacturers are focusing on innovative designs and material technologies aimed at improving signal integrity, minimizing attenuation, and ensuring compatibility with smaller, next-generation electronic devices. For instance, in June 2024, ConductRF presented its high-performance MIL-STD D38999 and SOSA-compliant VITA 67 cable assemblies at IMS2024 in Washington, DC. These versatile, custom-engineered solutions offer outstanding reliability and signal integrity, making them ideal for military and aerospace applications. With an extensive selection of connectors and cables, ConductRF provides focused assemblies designed to meet stringent environmental and performance demands.
The RF coaxial adapter segment is expected to grow at the fastest CAGR during the forecast period, driven by new technologies that deliver high-frequency, low-loss performance, meeting the escalating demands of 5G, satellite communications, and radar systems. Growing mobile data consumption, the spread of IoT, and the development of smart cities are driving this demand, with miniaturization and high reliability becoming design priorities. The integration of advanced materials such as low-loss dielectrics and high-conductivity metals enhances signal integrity and reduces attenuation, supporting high-performance requirements. Flexibility and customization are increasingly important, enabling cables to adapt to intricate designs and specific industry needs, from robotics to healthcare.
Frequency Insights
Based on Frequency, the Upto 50 GHz segment led the market with the largest revenue share of 41.2% in 2025, due to the growth of advanced 5G networks, backhaul communications, radar systems, and the rollout of Wi-Fi 6E/7 technologies operating in the 6 GHz range and beyond. This frequency range is crucial for meeting the higher data rate and bandwidth demands of next-generation wireless and aerospace applications. Industry innovations are centered on creating connectors and cables that deliver low insertion loss and exceptional reliability at these frequencies, as well as automating the production of micro-miniature connectors. Additionally, regulatory initiatives around spectrum sharing and dynamic coordination are influencing adoption, particularly in areas managing the balance between satellite services and unlicensed Wi-Fi use.
The upto 6GHz segment is expected to grow at the fastest CAGR over the forecast period, as it offers unprecedented bandwidth and reduced interference, enabling faster and more reliable wireless connectivity essential for modern high-bandwidth applications. This surge in demand necessitates significant RF interconnect solutions capable of handling higher data rates and supporting advanced Wi-Fi standards like Wi-Fi 6E and Wi-Fi.Prominent initiatives by major players aredriving market expansion. For instance, in February, Anritsu Corporation launched the new software for its Radio Communication Test Station MT8000A, known as NR Licensed 6GHz Band Measurement MX800010A-014, which enables RF testing in the 6 GHz band (5.925 GHz to 7.125 GHz) for 5G Frequency Range 1 (FR1) devices. This enhancement supports the expanded licensed bands introduced in 3GPP Release 17 to address increasing mobile data traffic. Following the World Radio Communication Conference 2023 (WRC-23) agreement, the software facilitates compliance testing in countries deploying 6 GHz licensed bands for 5G FR1.
End Use Insights
Based on end user, the industrial segment has a significant revenue share of over 20% in 2025, as the automation, IoT, and smart manufacturing continue to expand to support dependable wireless communication and sensor networks in demanding environments such as oil and gas, manufacturing, and energy. There is a growing need for strong, high-frequency RF cables and connectors that can endure extreme temperatures, vibration, and corrosive conditions. Moreover, the adoption of Industry 4.0 technologies is driving demand for high-speed, low-latency data transmission, a key advantage of RF interconnects. Market trends are also being influenced by regulatory requirements and the push for scalable, adaptable solutions, positioning industrial applications as a major growth area for RF interconnect technologies.
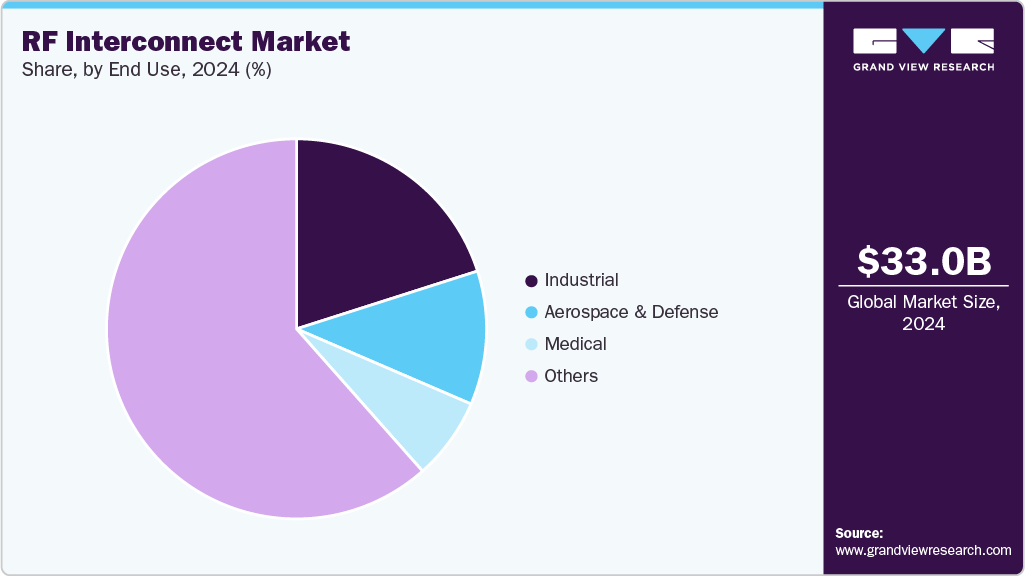
The medical segment is anticipated to grow at a significant CAGR during the forecast period, driven by the trend of miniaturizing interconnect components for developing more efficient, compact, and reliable medical devices that enhance diagnostics, monitoring, and treatment. Miniaturized connectors play a vital role in improving the performance and patient comfort of various applications, including MRI machines, implantable devices like pacemakers, wearable health monitors, portable diagnostic tools, and minimally invasive surgical instruments. These smaller, high-quality interconnects enable better signal transmission, reduced power consumption, and greater device portability, all of which contribute to improved healthcare outcomes. As medical technology continues to evolve with a focus on safety and precision, the demand for innovative, miniaturized RF interconnect solutions is driving significant growth in this sector.
Regional Insights
North America held a significant revenue share of the RF interconnect market in 2025 and is expected to register the fastest CAGR during the forecast period, driven by the strong focus on expanding high-speed internet infrastructure and rolling out 5G networks, which require RF interconnect solutions capable of handling higher data rates and frequencies. Additionally, new oil and gas projects across North America are expanding the need for strong RF communication systems that can operate in harsh environments. The other drivers for this market are partnership and collaboration between the companies for a strong focus on the RF interconnectors. For instance, in November 2023, Amphenol Corporation acquired Q Microwave, a designer and producer of mission-critical RF components, strengthening its harsh environment solutions segment. Q Microwave is known for its RF filters and subsystems, particularly for military and space applications. This acquisition merges Amphenol’s extensive global presence with Q Microwave’s specialized technical capabilities, aiming to advance RF solutions.
U.S. RF Interconnect Market Trends
The RF interconnect market in the U.S. held the largest share in the North America region in 2025, driven due to the strong aerospace and defense sectors, as they require dependable, high-performance RF interconnects for critical operations. Moreover, continuous innovation and R&D in wireless technologies and electronics drive the creation of specialized RF solutions to meet emerging connectivity demands. The rising use of satellite communications and the use of IoT devices further demand the need for interconnect technologies.
Europe RF Interconnect Market Trends
The RF interconnect market in Europe is witnessing steady growth over the forecast period,due to the growing need for high-frequency, high-performance connectivity across key sectors like defense, aerospace, and telecommunications.European industries depend on solutions such as GORE Microwave/RF Assemblies, known for their exceptional flexibility, low loss, and consistent phase and amplitude performance up to 70 GHz, which enable dependable long-distance signal transmission while minimizing downtime from cable failures. Furthermore, the rising need for rugged, vapor-sealed, and compact interconnects addresses challenges related to limited installation space, extreme temperatures, vibration, and contamination frequently encountered in European aerospace and defense environments. Together, these factors fuel the demand for advanced RF interconnect products that offer mission-critical reliability, improved system performance, and adherence to strict regional regulations.
Asia Pacific RF Interconnect Market Trends
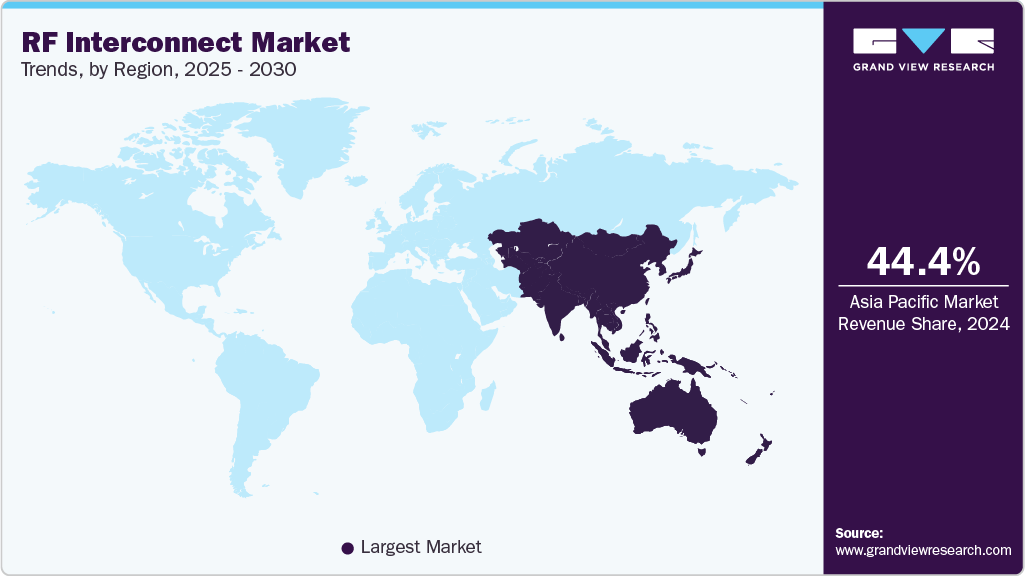
Asia Pacific dominated the RF interconnect market with the largest revenue share of 44.6% in 2025, driven by the rapid growth of the telecommunications sector in the region. Higher smartphone usage and expanding internet connectivity are substantially increasing the demand for RF interconnect solutions. Additionally, rising investments in manufacturing plants, digital infrastructure, and construction projects are supporting market expansion. The extreme automotive industry, along with the growing use of IoT and wireless communication technologies, is also accelerating the need for dependable RF interconnect components. The RF interconnect market in the China held the largest share in the Asia Pacific region in 2025.
For instance, in May 2024, Corning Incorporated, operating in APAC, introduced a gold-plated plastic microwave connector, using Corning Gilbert POLYLINK technology, at IMS 2024. It provides a lightweight, flexible, and cost-effective option for telecommunications and aerospace applications, with reliable performance up to 26.5 GHz. POLYLINK connectors are up to 33% lighter than conventional beryllium copper interconnects and benefit from shorter manufacturing lead times.
Key RF Interconnect Companies Insights
Key players operating in the RF interconnect market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key RF Interconnect Companies
The following key companies have been profiled for this study on the RF interconnect market.
-
Amphenol RF
-
Corning Incorporated
-
Flann Microwave Ltd.
-
HUBER+SUHNER
-
Radiall
-
Samtec
-
Rosenberger
-
Smith’s Interconnect
-
W. L. Gore & Associates, Inc.
-
ETL Systems Ltd
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players (Amphenol RF, Corning Incorporated, HUBER+SUHNER, Radiall, Rosenberger)
- Mature players focus on expanding high-frequency RF connector portfolios, strengthening aerospace and defense partnerships, advancing 5G connectivity solutions, and enhancing precision manufacturing capabilities.
- Their competitive advantage stems from strong global brand recognition, extensive distribution networks, diversified product portfolios, and significant investments in RF engineering and connectivity technologies.
- These companies often face challenges related to rising raw material costs, complex regulatory compliance requirements, and slower responsiveness to niche market opportunities compared to specialized vendors.
Emerging Players (Samtec, Smiths Interconnect, W. L. Gore & Associates, Inc., Flann Microwave Ltd., ETL Systems Ltd.)
- Emerging players focus on specialized RF interconnect solutions, rapid product innovation, customized designs, and application-specific offerings targeting high-growth communication and defense sectors.
- Their competitive edge is driven by agile product development, technical specialization, faster customization capabilities, and strong focus on high-frequency RF applications.
- Limited global presence, narrower distribution channels, and lower financial resources may restrict their ability to compete with established market leaders on a large scale.
Recent Developments
-
In July 2025, Amphenol RF introduced new FAKRA to SMA adapters designed to facilitate seamless integration between automotive FAKRA systems and SMA-based RF devices. These precision-engineered, durable adapters offer a high-performance solution that ensures secure and reliable signal transmission across various demanding applications, thereby enhancing connectivity within automotive and RF environments.
-
In February 2025, Samtec appointed TTI, Inc. Europe, as an authorized global distributor for its full range of cables and connectors. This partnership enables TTI, Inc., to leverage its extensive international supply chain and inventory management expertise to deliver Samtec's high-performance connector, cable, and fiber optic products to electronic manufacturers worldwide.
-
In July 2024, Radiall, a prominent player in the design and manufacture of advanced interconnect solutions, introduced a new SP8T coaxial switch operating at 40 GHz. Available in both terminated and non-terminated configurations, these switches feature SMA 2.9 mm connectors, complementing Radiall’s existing portfolio of 40 GHz switches and addressing high frequency switching requirements in demanding RF and microwave applications.
RF Interconnect Market Report Scope
Report Attribute
Details
Market size in 2025
USD 35.3 billion
Estimated Market size in 2026
USD 37.8 billion
Projected Market size by 2033
USD 66.4 billion
Growth rate
CAGR of 8.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, frequency, end user, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Amphenol RF; Corning Incorporated; Flann Microwave Ltd.; HUBER+SUHNER; Radiall; Samtec; Rosenberger; Smith’s Interconnect; W. L. Gore & Associates, Inc.; ETL Systems Ltd
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global RF Interconnect Market Report Segmentation
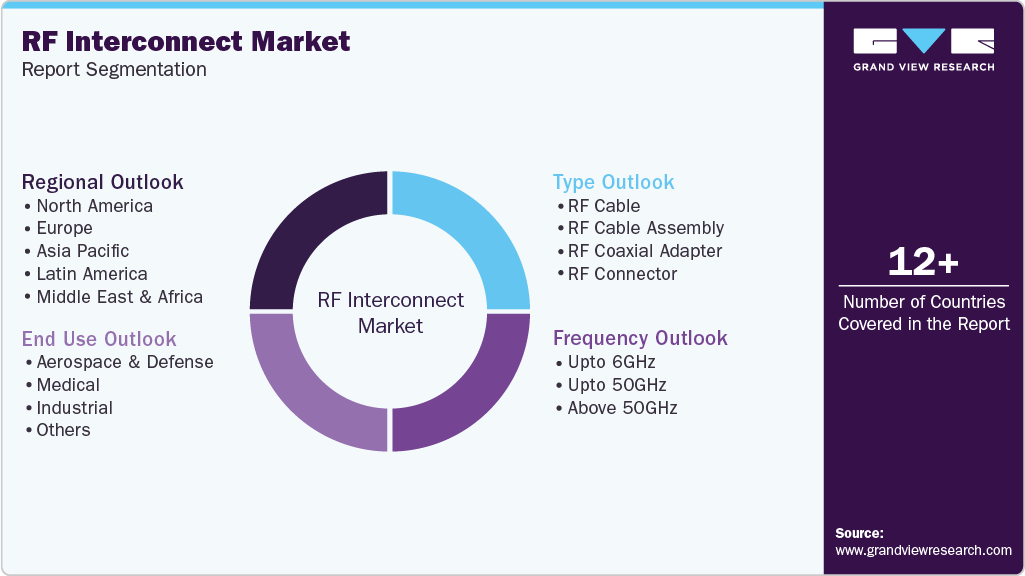
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global RF interconnect market report based on the type, frequency, end use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
RF Cable
-
RF Cable Assembly
-
RF Coaxial Adapter
-
RF Connector
-
-
Frequency Outlook (Revenue, USD Million, 2021 - 2033)
-
Upto 6GHz
-
Upto 50GHz
-
Above 50GHz
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Aerospace & Defense
-
Medical
-
Industrial
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The rf interconnect market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each rf interconnect segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Type
Revenue capture definition
RF Cable
RF cable refers to a transmission medium designed to carry radio frequency signals between electronic devices with minimal signal degradation. It is widely utilized in telecommunications, broadcasting, military systems, and wireless communication infrastructure.
RF Cable Assembly
RF cable assembly consists of a pre-configured combination of RF cables and terminated connectors engineered for specific connectivity requirements. These assemblies provide reliable signal transmission across communication, aerospace, and testing applications.
RF Coaxial Adapter
RF coaxial adapter is a connectivity component that enables the interconnection of RF interfaces with differing connector configurations. It facilitates signal continuity while maintaining electrical performance across communication systems.
RF Connector
RF connector is a precision-engineered interface used to join transmission lines and electronic equipment operating at radio frequencies. It ensures secure mechanical attachment and consistent signal integrity in high-frequency environments.
Segment – Frequency
Revenue capture definition
Upto 6GHz
This category encompasses RF interconnect products designed to support frequencies up to 6 GHz. It primarily serves conventional wireless communication, networking equipment, industrial electronics, and broadcast applications.
Upto 50 GHz
This segment includes RF interconnect solutions capable of operating at frequencies above 6 GHz and up to 50 GHz. These products are commonly deployed in advanced telecommunications, aerospace systems, radar platforms, and test instrumentation.
Above 50 GHz
This category comprises high-performance RF interconnect technologies developed for frequencies exceeding 50 GHz. It addresses the requirements of mm Wave communications, satellite systems, advanced defense applications, and next-generation wireless networks.
Segment – End User
Revenue capture definition
Aerospace & Defence
This segment includes the utilization of RF interconnect solutions in aircraft, satellites, military communication systems, radar equipment, and electronic warfare platforms. The sector demands highly reliable components capable of operating in mission-critical and extreme environments.
Medical
Medical applications involve the integration of RF interconnect products within diagnostic imaging systems, patient monitoring equipment, and healthcare communication devices. These solutions support accurate signal transmission and dependable equipment performance in clinical settings.
Industrial
The industrial segment covers the deployment of RF connectivity components across automation systems, manufacturing equipment, energy infrastructure, and industrial communication networks. Such applications require durable and stable signal transmission under demanding operating conditions.
Others
This category encompasses additional end-use sectors including telecommunications, consumer electronics, transportation, research laboratories, and data centers. It represents diverse applications where RF interconnect technologies facilitate efficient high-frequency communication and connectivity.
Estimation Model
Layer Name
Key Question
Description
Wireless Communication Infrastructure Layer
Who creates demand for RF interconnect solutions?
Identify demand originating from telecommunications operators, network equipment manufacturers, aerospace organizations, defense agencies, industrial enterprises, and data center operators. This layer establishes the addressable demand base by assessing communication infrastructure deployments and high-frequency connectivity requirements.
RF System Integration Layer
Where are RF interconnect components incorporated?
Apply adoption rates of RF-enabled systems including 5G base stations, satellite communication platforms, radar systems, wireless networking equipment, test and measurement instruments, and industrial communication networks. This layer estimates the integration of RF connectivity technologies across end-use applications.
RF Interconnect Deployment Layer
Which RF interconnect products are deployed?
Measure the installation of RF cables, RF cable assemblies, RF connectors, and RF coaxial adapters across commercial, industrial, aerospace, defense, and telecommunications environments. This layer captures the active deployment volume of RF interconnect products supporting signal transmission infrastructure.
RF Interconnects Revenue Realization Layer
How much revenue is generated from RF interconnect adoption?
Estimate market revenue by combining installed product volumes with average selling prices across various RF interconnect categories and frequency ranges. This layer quantifies total revenue generated through the procurement, deployment, replacement, and expansion of RF interconnect solutions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
RF Interconnects Adoption Assessment
Analyzed adoption trends of RF interconnect solutions across 5G infrastructure, aerospace & defense systems, satellite communications, industrial automation, and wireless networking applications.
Helps stakeholders identify high-growth demand areas, evaluate technology adoption patterns, and support strategic investment decisions.
RF Interconnects End-User Analysis
Assessed demand across telecommunications, aerospace & defense, industrial, medical, and other end-use sectors, including key high-frequency connectivity and signal transmission requirements.
Provides insights into end-user purchasing behavior, application trends, and emerging revenue opportunities across major industries.
Advanced Connectivity & High-Frequency Opportunity Assessment
Evaluated market opportunities associated with mmWave communications, satellite networks, next-generation wireless infrastructure, high-speed data transmission, and advanced RF connectivity technologies.
Supports product innovation, portfolio expansion, and competitive positioning strategies in rapidly evolving communication markets.
Frequently Asked Questions About This Report
The global RF interconnect market size was valued at USD 35.3 billion in 2025 and is estimated at USD 37.8 billion in 2026.
The global RF interconnect market is expected to grow at a CAGR of 8.4% from 2026 to 2033, reaching USD 66.4 billion by 2033.
The RF cable assembly segment dominated the overall market, holding a 32.6% share in 2025, driven by increasing deployment of 5G infrastructure, growing demand for high-frequency signal transmission, and expanding adoption across telecommunications, aerospace, defense, and automotive applications.
Asia Pacific dominated the RF interconnect market, accounting for over 44% of the market share in 2025, driven by the rapid expansion of semiconductor manufacturing, increasing deployment of 5G and next-generation communication infrastructure, and rising production of consumer electronics, automotive electronics, and industrial automation systems.
North America is the fastest-growing region over the forecast period.
The Upto 50 GHz segment led with over 41.2% revenue share in 2025, while the Upto 6 GHz segment is the fastest-growing.
The industrial segment accounted for over 20.0% of the market revenue in 2025 and remained the fastest-growing segment.
Some key players operating in the RF Interconnect market include Amphenol RF, Corning Incorporated, Flann Microwave Ltd., HUBER+SUHNER, Radiall, Samtec, Rosenberger, Smith’s Interconnect, W. L. Gore & Associates, Inc., and ETL Systems Ltd
Key factors driving growth in the RF interconnect market include expanding 5G infrastructure deployment, increasing semiconductor and consumer electronics production, and rising adoption of high-frequency communication technologies across automotive, aerospace, defense, and data center applications.
About the Author(s)
Electronic Devices Research Team
Semiconductors & Electronics · Electronic DevicesThis report was authored by the electronic devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic devices segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs — add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


