
- Home
- »
- Next Generation Technologies
- »
-
Robotic Palletizers And De-Palletizers Market Report, 2033GVR Report cover

Robotic Palletizers And De-palletizers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Robotic Palletizers, Robotic De-palletizers), By End-use, By Payload Capacity, By Region, And Segment Forecasts
Market Size, 2025
$2.4BMarket Estimate, 2026
$2.6BMarket Forecast, 2033
$3.9BCAGR, 2026–2033
6.2%Robotic Palletizers And De-palletizers Market Summary
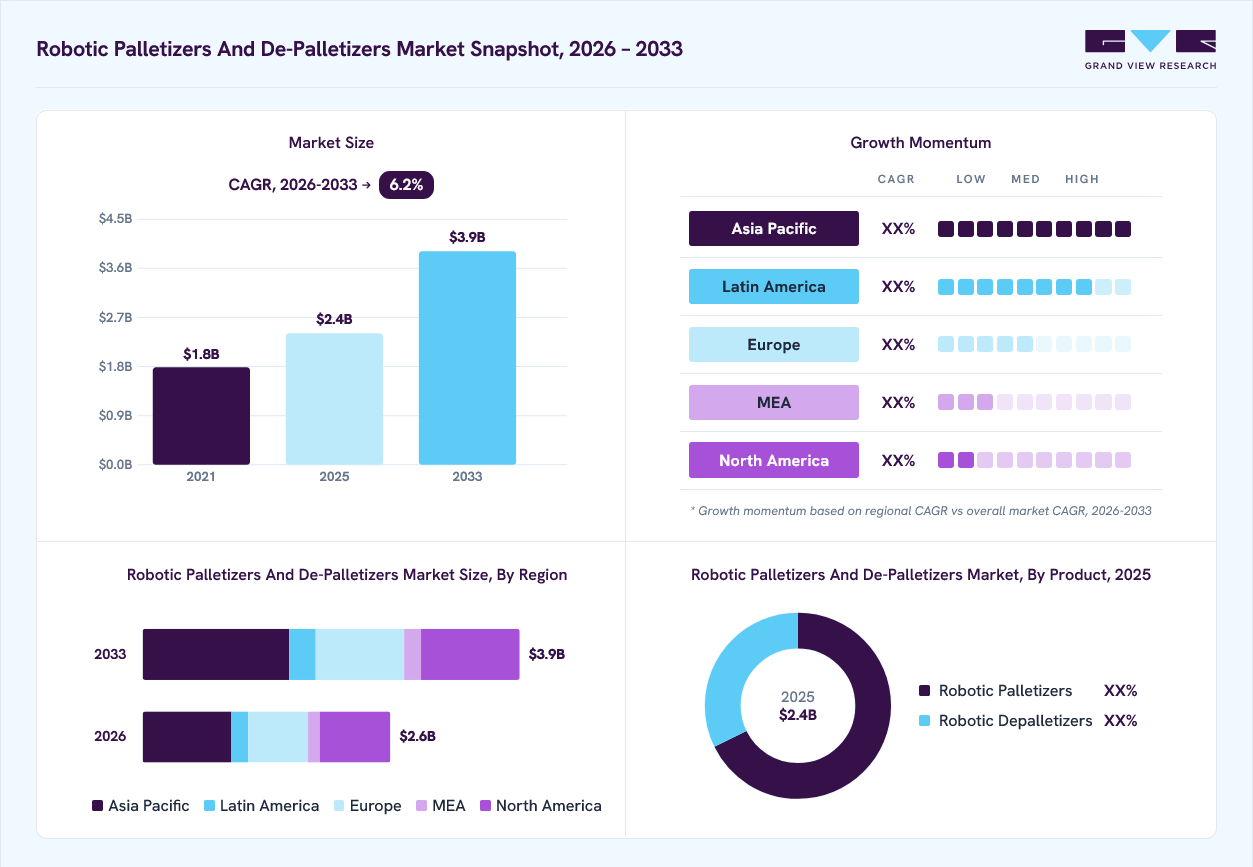
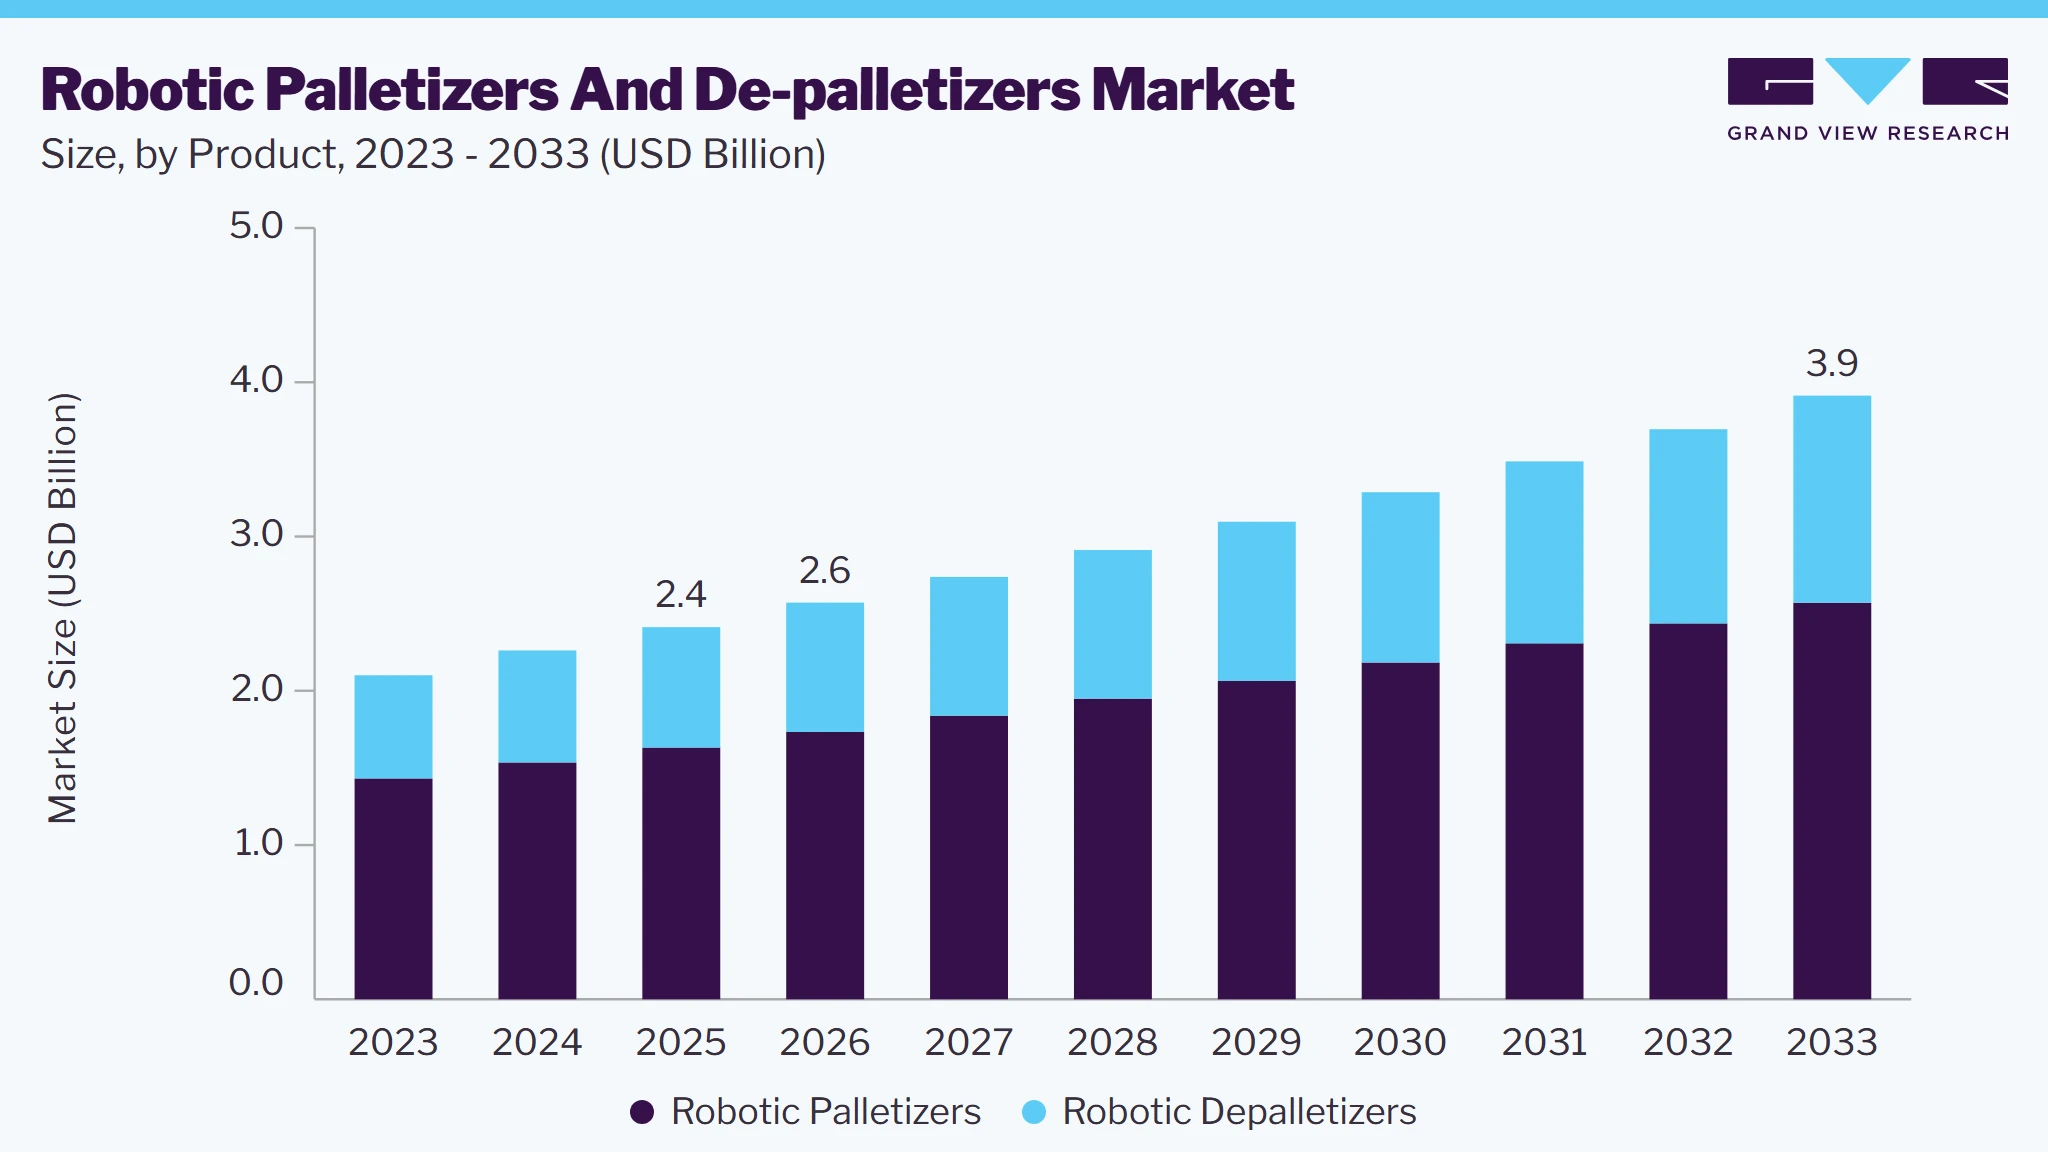
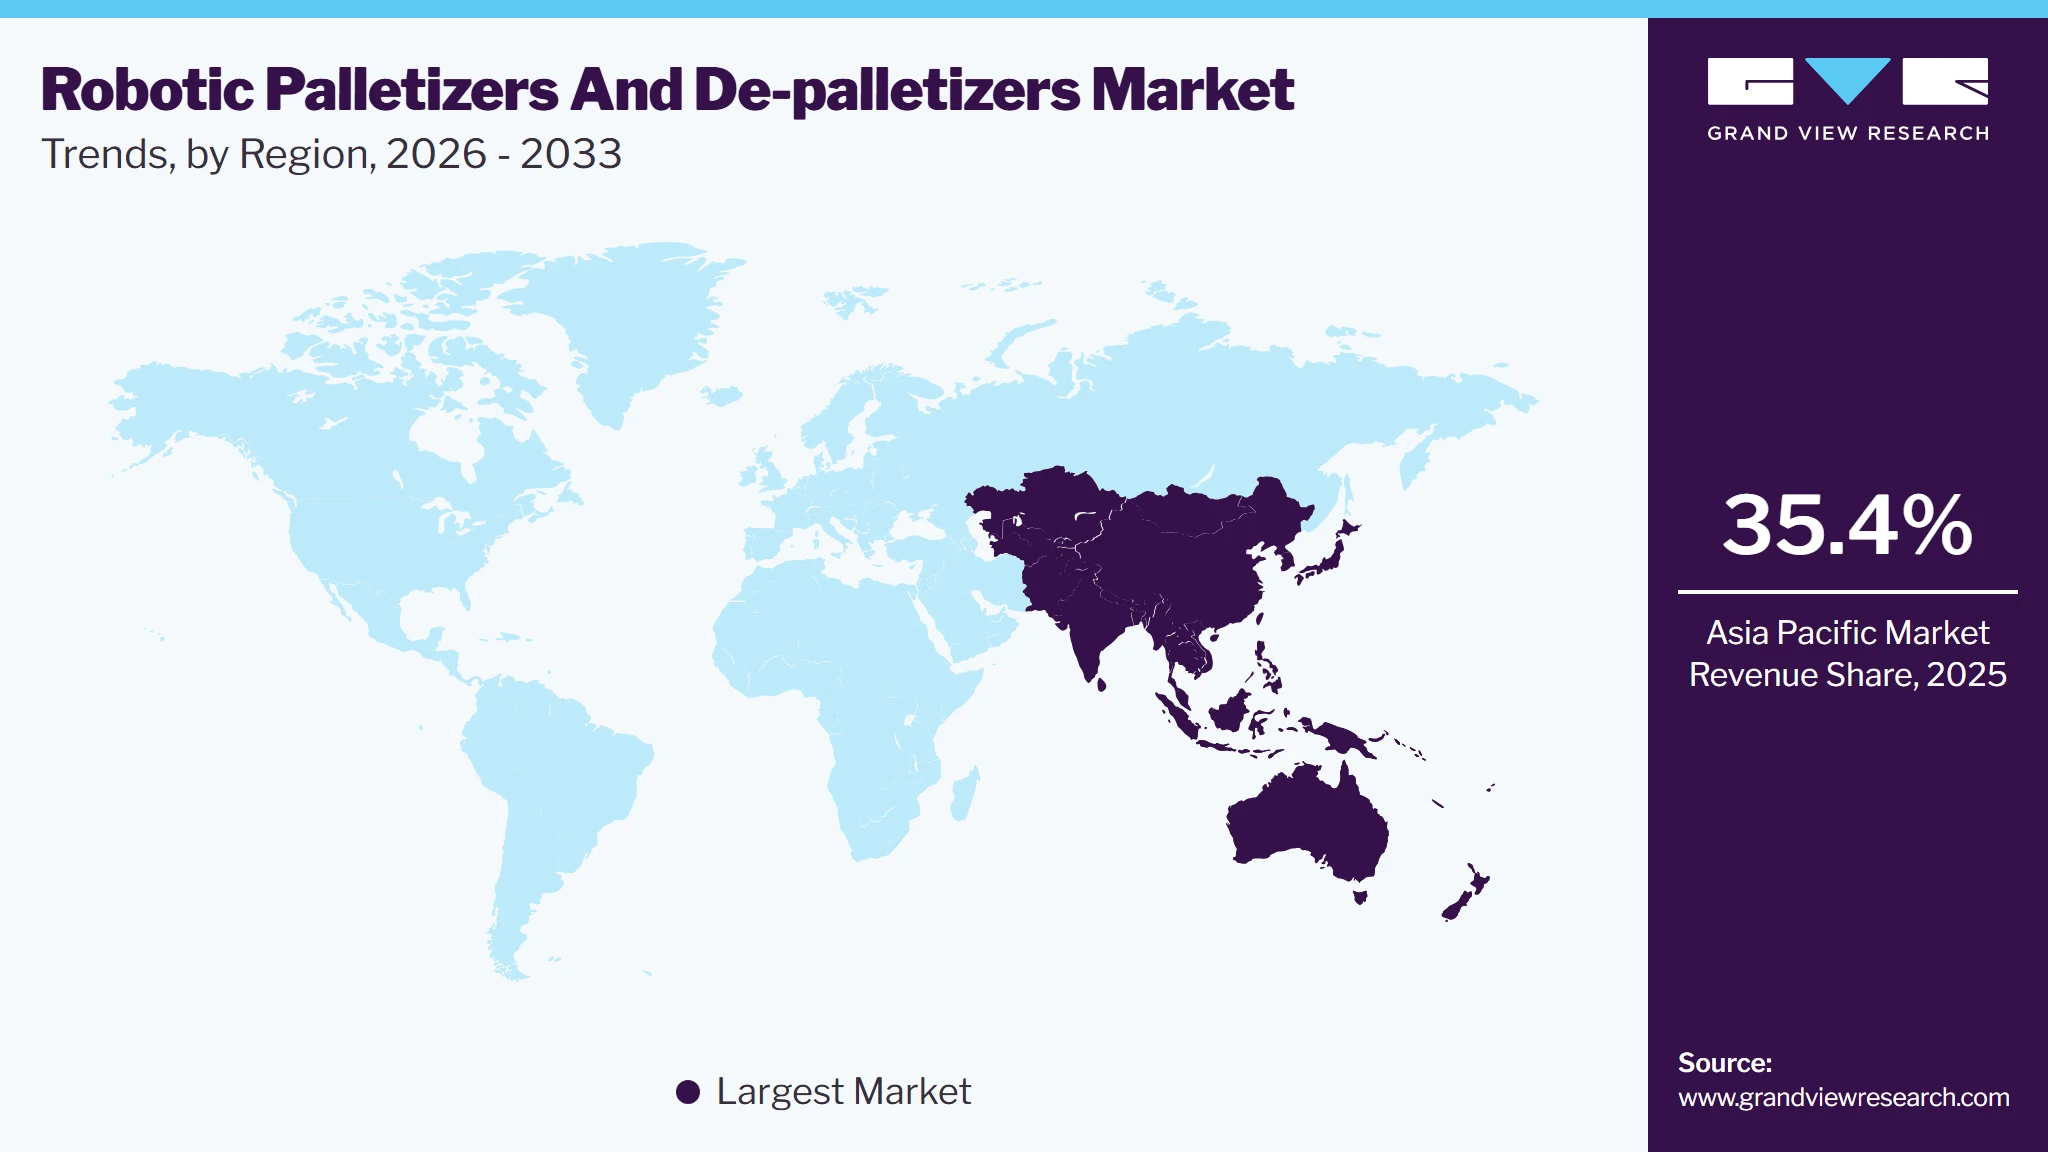
The global robotic palletizers and de-palletizers market size was valued at USD 2.4 billion in 2025 and is projected to grow from USD 2.6 billion in 2026 to USD 3.9 billion by 2033, at a CAGR of 6.2% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 35.4% in 2025. The robotic palletizers and de-palletizers market is driven by the increasing adoption of warehouse and end-of-line automation, the growing deployment of industrial robots to address labor shortages and improve operational efficiency, and the rising demand for high-speed, accurate pallet handling across manufacturing, logistics, and distribution facilities.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The robotic palletizers segment dominated the market, with a share of 67.7% in 2025.
- By payload capacity: The medium payload (50 kg to 500 kg) segment accounted for the largest market share of 55.9% in 2025.
- By end use, the food and beverage segment accounted for the largest market share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.4% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 7.4%, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.4 Billion
- Estimated market size in 2026: USD 2.6 Billion
- Projected market size by 2033: USD 3.9 Billion
- CAGR (2026-2033): 6.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The expanding adoption of robotic palletizing and depalletizing systems across food & beverage, consumer goods, pharmaceuticals, e-commerce, chemicals, and warehousing operations is significantly accelerating market growth. These technological advancements are improving throughput, minimizing manual intervention, reducing workplace injuries, and supporting automated material handling, thereby creating growth opportunities for the robotic palletizers and de-palletizers market. Companies are increasingly adopting automated solutions to enhance operational efficiency, reduce labor costs, and improve safety in their facilities. The need for faster production rates and the ability to handle high volumes of products with precision are pushing manufacturers to invest in robotic systems that can streamline their packaging processes, which is expected to further fuel the market growth in the coming years.
 To learn more about this report, Download Free Sample Report
The rapid growth of e-commerce has created a surge in demand for efficient warehousing and distribution solutions. Retailers are increasingly relying on automated systems to manage inventory levels effectively while ensuring timely order fulfillment. Robotic palletizers and de-palletizers are essential components in modern warehouses as they facilitate the quick handling of products from storage to shipping areas. This trend is expected to continue as online shopping becomes more prevalent, driving investments in automation technologies within the retail sector.
Innovations such as artificial intelligence (AI), machine learning, and advanced vision systems have significantly improved the capabilities of robotic systems. These technologies enable robots to perform complex tasks with greater accuracy and flexibility, allowing them to adapt to varying product sizes, shapes, and weights. As these technologies continue to evolve, they will further enhance the functionality of robotic palletizers and de-palletizers, making them more attractive to businesses seeking efficient solutions.
The ongoing labor shortages and rising labor costs is significantly driving the market growth across various industries.With the global workforce facing challenges such as aging populations and a declining number of workers willing to take on physically demanding jobs, companies are turning to robotic solutions to fill the gap. Robotic palletizers and de-palletizers not only reduce the need for manual labor but also minimize the risk of workplace injuries, making them an attractive option for businesses looking to maintain operational efficiency while managing labor-related challenges.
Moreover, companies are seeking eco-friendly packaging solutions that reduce waste and lower carbon footprints. Robotic systems that can efficiently handle recyclable or biodegradable packaging materials are in high demand. In addition, the ability to optimize pallet patterns to maximize space utilization and reduce shipping costs aligns with broader environmental sustainability goals, making robotic systems an integral part of green logistics strategies. Such strategies by companies are expected to further drive market growth in the coming years.
Market Dynamics
The robotic palletizers and de-palletizers market is experiencing significant growth owing to the increasing adoption of automated end-of-line packaging systems, the persistent shortage of warehouse and manufacturing labor, and the rising demand for high-throughput material handling across production and distribution facilities. Growing investments in smart factories, warehouse automation, and Industry 4.0 initiatives are encouraging manufacturers to deploy robotic palletizing and depalletizing solutions to improve operational efficiency. Advancements in machine vision, AI-enabled robotic guidance, collaborative robotics, and flexible gripper technologies are enabling faster product handling, reduced downtime, enhanced palletizing accuracy, and seamless mixed-SKU processing, thereby creating opportunities for sustained market growth.
The increasing adoption of automated warehousing has become one of the primary factors driving demand for robotic palletizers and de-palletizers. Distribution centers and manufacturing facilities are investing in robotic systems to improve pallet handling speed, maintain consistent stacking quality, and reduce dependence on manual labor. These systems enable continuous operation, improve order fulfillment efficiency, and support higher throughput, making them an essential component of modern end-of-line automation.
The rapid expansion of e-commerce, third-party logistics, and omnichannel fulfillment has further intensified the need for automated pallet handling solutions. Robotic palletizers and de-palletizers can manage diverse packaging formats, optimize pallet configurations, and integrate seamlessly with conveyors, warehouse management systems, and automated storage solutions. Their ability to enhance productivity while minimizing workplace injuries and operational errors is encouraging widespread deployment across high-volume facilities.
The substantial upfront investment required for robotic palletizers and de-palletizers remains a significant restraint for market adoption. Organizations must allocate considerable budgets for robotic arms, end-of-arm tooling, safety equipment, vision systems, software integration, installation, and workforce training. For many small and medium-sized enterprises, these costs can delay automation initiatives despite the long-term operational advantages.
The equipment costs; businesses often incur expenses for facility modifications, system integration, routine maintenance, and technical support. Production interruptions during installation and commissioning may further increase implementation costs. Companies with low production volumes or frequently changing operational requirements may find it difficult to justify a return on investment, thereby slowing adoption in cost-sensitive manufacturing and warehousing environments.
The integration of artificial intelligence with advanced machine vision is creating significant opportunities for robotic palletizers and de-palletizers. AI-powered vision systems enable robots to identify product dimensions, detect irregular package orientations, and adjust handling strategies without extensive manual programming. This capability improves automation efficiency for facilities processing mixed products, damaged cartons, or variable packaging configurations.
Growing demand for flexible manufacturing and customized order fulfillment is accelerating investments in intelligent robotic solutions capable of adapting to changing production requirements. AI-driven palletizing systems support faster product changeovers, optimize stacking patterns, and improve handling accuracy across multiple stock-keeping units. These advancements allow businesses to automate complex pallet handling tasks while maintaining operational efficiency in dynamic production and distribution environments.
Market Concentration & Characteristics
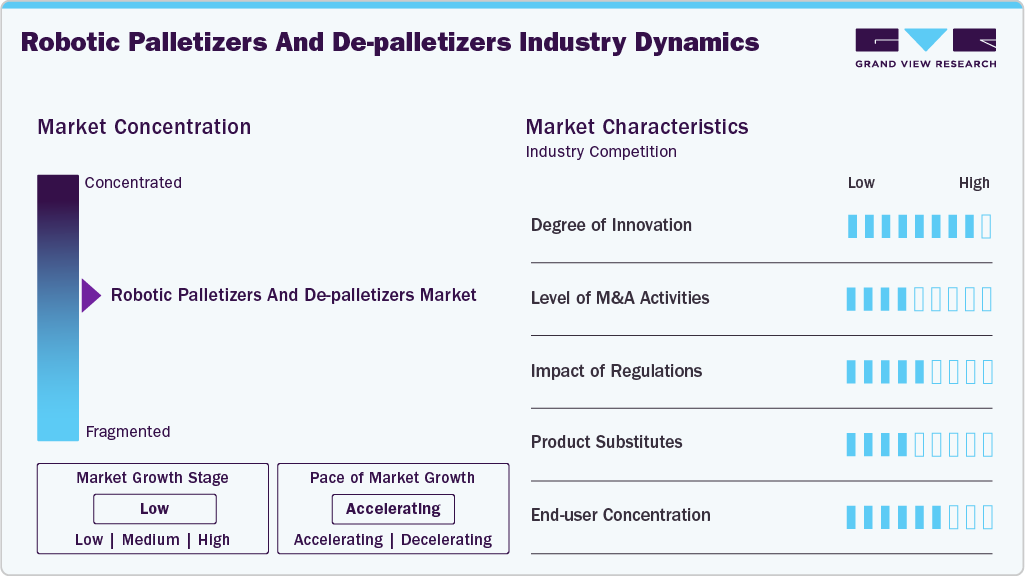
The robotic palletizers and de-palletizers market is moderately concentrated, with leading industrial robotics manufacturers, automation solution providers, and system integrators competing across warehouse automation, end-of-line packaging, pallet handling, and distribution applications. Rising investments in smart factories, increasing demand for high-speed material handling, and persistent labor shortages are accelerating market adoption. Companies are strengthening their market positions through strategic collaborations, robotics portfolio expansion, AI-enabled vision technologies, and investments in flexible automation systems.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation, driven by advancements in machine vision, AI-powered robotic guidance, collaborative robots, adaptive grippers, and digital automation platforms. Merger and acquisition activity remains moderately high as automation companies expand technological capabilities and geographic reach. Regulatory impact is moderate due to industrial safety standards, machinery compliance requirements, and workplace automation regulations. The threat of substitutes remains relatively low, as manual palletizing and conventional handling equipment cannot deliver comparable productivity, flexibility, or operational consistency.
Analyst Perspective
The robotic palletizers and de-palletizers market is experiencing significant expansion, driven by increasing warehouse automation, persistent labor shortages, and the growing adoption of robotic material-handling solutions across manufacturing, logistics, and distribution facilities. The growing adoption of AI-enabled machine vision, collaborative robots, adaptive grippers, and intelligent motion control systems is improving pallet-handling accuracy, operational efficiency, throughput, and workplace safety. Manufacturers and logistics providers are increasingly prioritizing flexible automation, high-speed end-of-line operations, and smart factory initiatives. Automation solution providers are well-positioned to capitalize on these evolving requirements, thereby reinforcing long-term market expansion and sustainable revenue generation across the global industrial automation ecosystem.
Product Insights
Based on product, the robotic palletizers segment led the market with the largest revenue share of 67.7% in 2025 and is expected to grow at a considerable CAGR over the forecast period, owing to the widespread adoption of these systems across various industries for their efficiency in automating the stacking of products on pallets. Moreover, the increasing demand for automation to enhance production efficiency, reduce labor costs, and ensure consistency in product handling is fueling the market growth. The versatility of robotic palletizers to adapt to different packaging types and sizes also makes them indispensable in modern supply chains, thereby driving segmental growth.
The robotic de-palletizers segment is expected to witness at a significant CAGR of over 4% from 2024 to 2033, driven by the growing need for efficient and automated solutions in the unpacking and handling of goods across various industries. In addition, advancements in robotic technology, such as improved vision systems and AI-driven software, are enhancing the capabilities of robotic de-palletizers, making them more adaptable and efficient in handling a wide range of products. This growing demand for automation in de-palletizing operations is expected to propel the segment's growth in the coming years.
End-use Insights
Based on end use, the food & beverage development segment dominated the market with a revenue share of 23.7% in 2025. This growth can be attributed to the sector's continuous need for efficiency, hygiene, and consistency in handling products. The industry deals with a high volume of goods, often packaged in various sizes and materials, requiring precise and reliable automation solutions. Robotic palletizers and de-palletizers are essential in maintaining the speed and accuracy needed to keep up with production demands, while also adhering to strict hygiene standards.
The logistics and warehousing segment is anticipated to record at the fastest CAGR from 2024 to 2033, owing to the explosive growth of e-commerce and the increasing complexity of global supply chains. Robotic palletizers and de-palletizers play a critical role in automating the handling of a wide variety of goods, reducing labor costs, and improving throughput in fulfillment centers. This growing need for automation to manage increasing volumes and optimize warehouse space is driving the rapid adoption of robotic solutions in the logistics and warehousing sector.
Payload Capacity Insights
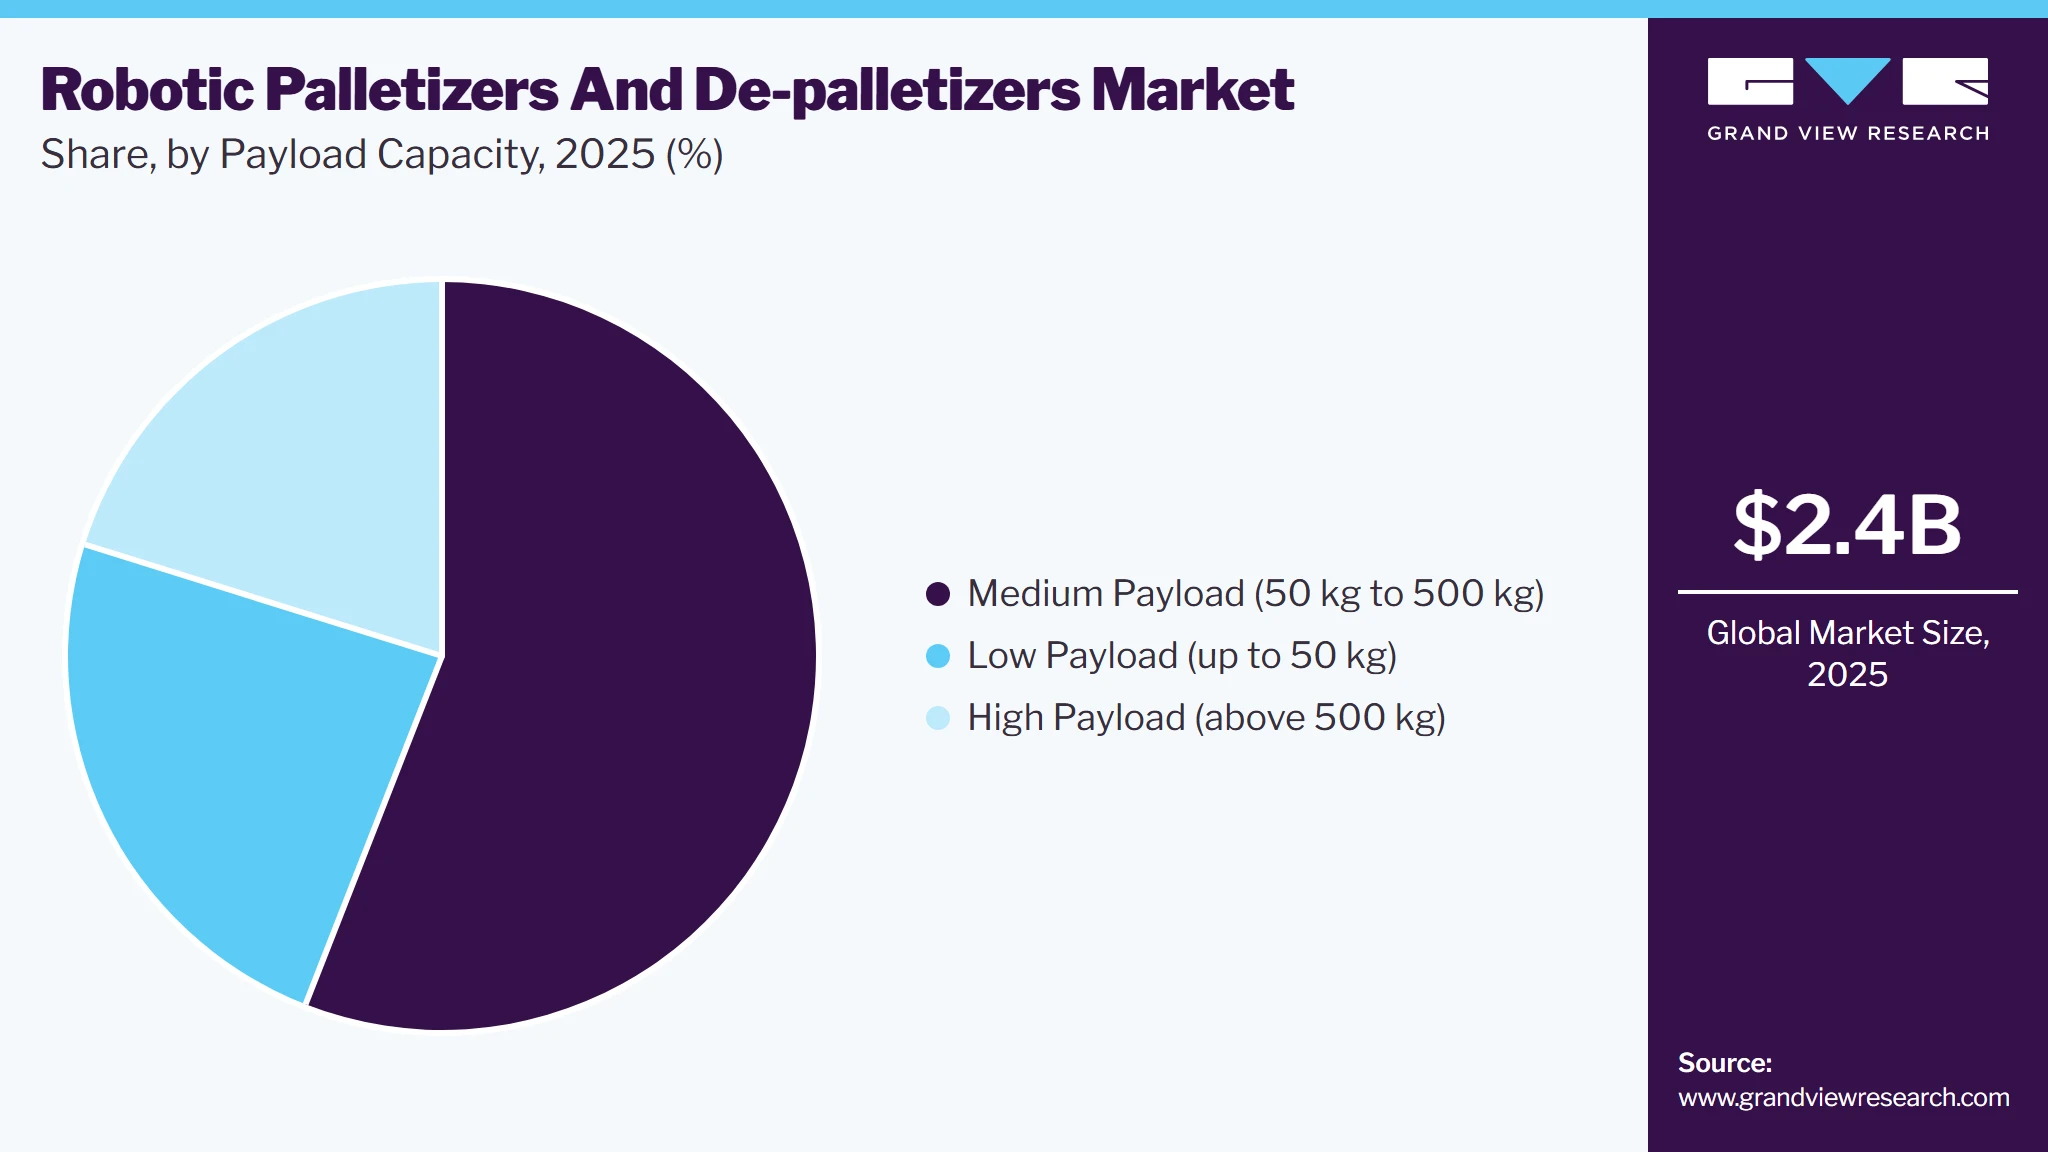
Based on payload capacity, the medium payload (50 kg to 500 kg) segment led the market with the largest revenue share of 55.9% in 2025. This growth can be attributed to its versatility and widespread application across various industries. This segment is particularly favored in industries such as food and beverage, pharmaceuticals, and consumer goods, where handling larger and heavier packages is common. The medium payload robots offer a balance between strength and speed, making them ideal for operations that require the efficient handling of moderate to heavy loads. Their ability to manage a broad range of packaging types and sizes has made them a preferred choice for companies seeking to optimize their palletizing and de-palletizing processes, thereby driving segmental growth.
 To learn more about this report, Download Free Sample Report
The low payload (up to 50 kg) segment is expected to grow at the fastest CAGR from 2024 to 2033. This growth can be attributed to the increasing demand for automation in sectors dealing with lighter products and smaller packages. The rise of e-commerce, which often involves the handling of lightweight parcels, is a key factor contributing to the growth of this segment. In addition, advancements in robotics technology are making low payload robotic systems more affordable and accessible to small and medium-sized enterprises (SMEs), which are increasingly adopting these systems to enhance operational efficiency.
Regional Insights
The robotic palletizers and de-palletizers market in North America accounted for the revenue share of 29% in 2023. The market is driven primarily by the increasing demand for automation in the manufacturing and logistics sectors. Companies are investing in advanced technologies to enhance operational efficiency, reduce labor costs, and improve safety standards. The presence of major players in the robotics industry, along with a strong focus on innovation and technological advancements, further propelling the market growth.
U.S. Robotic Palletizers And De-palletizers Market Trends
The robotic palletizers and de-palletizers market in U.S. is projected to grow at the fastest CAGR of 4% from 2024 to 2033. The rising trend of e-commerce has led to increased warehousing activities, necessitating efficient palletizing solutions to manage high volumes of goods, thereby driving the market growth in the region.
Europe Robotic Palletizers And De-palletizers Market Trends
The robotic palletizers and de-palletizers market in Europe is anticipated to grow at a CAGR of 5% from 2024 to 2033. This growth is driven by stringent regulations regarding workplace safety and labor conditions. European manufacturers are increasingly adopting automation solutions to comply with these regulations while also addressing labor shortages in various sectors. The region’s emphasis on sustainability and reducing carbon footprints drives investments in energy-efficient robotic systems.
Asia-Pacific Robotic Palletizers And De-palletizers Market Trends
Asia Pacific dominated the robotic palletizers and de-palletizers market with the largest revenue share of 35.4% in 2025, owing to the rapid industrialization and urbanization. The robotic palletizers and de-palletizers market in China held the largest share in the Asia Pacific region in 2025. Countries of the region are witnessing a surge in manufacturing activities across various sectors such as food & beverage, pharmaceuticals, and consumer goods. This industrial expansion creates a substantial need for automated solutions to streamline production processes and enhance supply chain efficiency. In addition, increasing foreign investments in manufacturing facilities within this region contributes to the adoption of advanced robotics technology.
 To learn more about this report, Download Free Sample Report
Key Robotic Palletizers And De-palletizers Company Insights
Some of the key players operating in the market include FANUC CORPORATION and KION Group AG, among others.
-
FANUC CORPORATION is a global manufacturer of automation products and solutions, including robotics. The company specializes in industrial robots, CNC systems, and factory automation technologies. The company’s robotic palletizers and de-palletizers are designed to enhance efficiency in material handling processes across various industries such as food and beverage, pharmaceuticals, and consumer goods
-
KION Group AG is a German manufacturer of industrial trucks and supply chain solutions. The company operates under several well-known brands including Linde Material Handling and STILL. The company has expanded its portfolio to include automated systems such as robotic palletizers and de-palletizers that optimize logistics operations within warehouses and distribution centers. Their solutions are characterized by advanced technology that enhances productivity while ensuring safety and flexibility in material handling tasks
Doosan Robotics, Inc. and Omron Corporation are some of the emerging market participants in the market.
-
Doosan Robotics, Inc., specializes in collaborative robots (cobot) designed for various applications including palletizing. Established with a vision to revolutionize automation through user-friendly robotic solutions, Doosan Robotics focuses on creating robots that can work alongside humans safely
-
Omron Corporation is a company operating in automation technology. The company offers a wide range of products including sensors, controllers, and industrial robots tailored for various sectors such as automotive, electronics, food processing, and logistics. Omron’s robotic palletizing solutions leverage sophisticated control algorithms and machine learning techniques to improve operational efficiency while reducing labor costs
Key Robotic Palletizers And De-palletizers Companies
The following key companies have been profiled for this study on the robotic palletizers and de-palletizers market.
-
FANUC CORPORATION
-
KION GROUP AG
-
KUKA AG
-
ABB Ltd.
-
Krones AG
-
Schneider Packaging Equipment Company, Inc.
-
Honeywell International Inc.
-
Kaufman Engineered Systems
-
Doosan Robotics, Inc.
-
Omron Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (FANUC CORPORATION, KION GROUP AG,
ABB Ltd.)
Focus on expanding integrated robotic automation portfolios through partnerships in vision systems, software, and system integration.
Invest heavily in R&D to develop flexible, high-speed palletizing solutions supporting diverse industrial applications.
Strong global distribution networks, established customer relationships, and extensive expertise in industrial automation support market leadership.
Ability to deliver reliable, end-to-end robotic palletizing solutions with advanced software and lifecycle support.
Dependence on complex product portfolios may slow down responsiveness to rapidly changing customer automation requirements.
Higher equipment and integration costs can limit competitiveness in price-sensitive small and medium enterprises.
Emerging Players (Kaufman Engineered Systems, Doosan Robotics, Inc., Omron Corporation)
Emerging players focus on developing flexible robotic palletizing solutions tailored for small and mid-sized manufacturing facilities.
Expand market presence through automation partnerships, regional distributors, and application-specific robotic integration services.
Agile product development enables rapid customization to meet diverse pallet-handling and packaging requirements.
Cost-effective robotic solutions attract manufacturers seeking affordable automation with shorter deployment timelines.
Limited global distribution networks restrict expansion into large multinational manufacturing and logistics operations.
Smaller R&D budgets constrain the development of advanced vision systems and intelligent automation capabilities.
Recent Developments
-
In June 2024, Doosan Robotics, Inc. partnered with Rocketfarm AS to enhance palletizing efficiencies by integrating Rocketfarm's Pally software with Doosan's collaborative robots (cobots). This collaboration aims to streamline operations across various industries, including automotive and food and beverage, by providing a user-friendly and flexible palletizing solution
-
In January 2024, FANUC CORPORATION launched several new products, including the M-950iA/500 palletizing robot, the M-710iD/50M with advanced vision and AI capabilities, and the LASER SCANNER LS3Di-A. Other notable additions include the CRX-10iA/L Paint collaborative robot and enhancements to its CNC and IoT systems, showcasing the company's commitment to innovation across its robotics and automation divisions
-
In March 2023, Omron Corporation launched a new cobot palletizing solution designed to enhance flexibility in production while minimizing programming time. Built on the NX1 series modular machine controller, this solution features a specialized Palletizing Function Block that allows for quick pallet pattern definition and easy setup through a step-by-step teaching process. The cobot can operate safely alongside humans without additional safety fencing, making it suitable for various industries
Robotic Palletizers And De-palletizers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.4 billion
Estimated market size in 2026
USD 2.6 billion
Projected market size by 2033
USD 3.9 billion
Growth rate
CAGR of 6.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end-use, payload capacity, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy, Spain, China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
FANUC CORPORATION; KION GROUP AG; KUKA AG; ABB Ltd.; Krones AG; Schneider Packaging Equipment Company, Inc.; Honeywell International Inc.; Kaufman Engineered Systems; Doosan Robotics, Inc.; Omron Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Robotic Palletizers And De-palletizers Market Report Segmentation
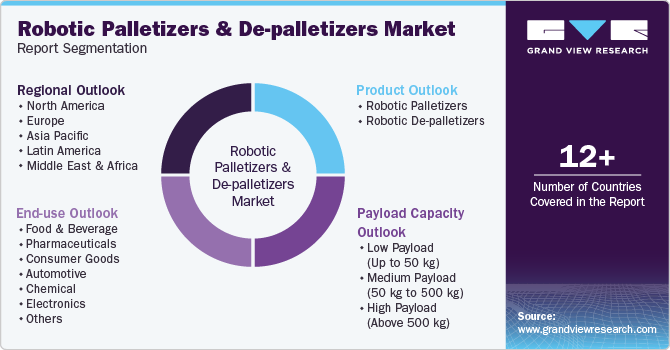
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global robotic palletizers and de-palletizers market report based on product, end-use, payload capacity, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Robotic Palletizers
-
Robotic De-palletizers
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Food & Beverage
-
Pharmaceuticals
-
Consumer Goods
-
Automotive
-
Chemical
-
Electronics
-
Logistics and Warehousing
-
Others
-
-
Payload Capacity Outlook (Revenue, USD Million, 2021 - 2033)
-
Low Payload (up to 50 kg)
-
Medium Payload (50 kg to 500 kg)
-
High Payload (above 500 kg)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Australia
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
Robotic Palletizers And De-palletizers Market, Robotic Palletizers And De-palletizers Market Size, Robotic Palletizers And De-palletizers Market Share, Robotic Palletizers And De-palletizers Market Analysis, Robotic Palletizers And De-palletizers Market Trends, Robotic Palletizers And De-palletizers Industry Insights, Robotic Palletizers And De-palletizers Market Report, Robotic Palletizers And De-palletizers Industry Report, Robotic Palletizers And De-palletizers Market Research, Robotic Palletizers And De-palletizers Market Growth, Robotic Palletizers And De-palletizers Industry Growth, Robotic Palletizers And De-palletizers Market Forecast, Robotic Palletizers And De-palletizers Industry Forecast, Robotic Palletizers And De-palletizers Industry Analysis
Segment Definition
Segment - Product
Revenue capture definition
Robotic Palletizers
Revenue is generated through robotic systems that automatically stack cartons, bags, cases, drums, and other packaged products onto pallets with high speed and precision. This segment is driven by increasing warehouse automation, labor shortage mitigation, higher production throughput requirements, and demand for flexible end-of-line packaging solutions.
Robotic De-palletizers
Revenue is captured through robotic systems that automatically unload products from pallets for manufacturing, packaging, warehousing, and distribution operations. This segment is driven by rising demand for automated material handling, improved workplace safety, reduced manual labor, and efficient handling of mixed-load or high-volume palletized goods.
Segment - End Use
Revenue capture definition
Food & Beverage
Revenue is generated through robotic palletizing and de-palletizing solutions deployed in food processing, beverage production, dairy, bakery, and packaged food facilities. This segment is driven by high production volumes, hygiene requirements, rapid packaging operations, and increasing adoption of automated end-of-line handling systems.
Pharmaceuticals
Revenue is generated through robotic pallet-handling systems used for medicines, medical devices, vaccines, and other healthcare products that require precise, contamination-free handling. This segment is driven by stringent quality standards, traceability requirements, operational accuracy, and growing pharmaceutical manufacturing capacity.
Consumer Goods
Revenue is generated through robotic solutions handling packaged household products, personal care items, and retail consumer goods across manufacturing and distribution facilities. This segment is driven by increasing product volumes, diverse packaging formats, faster order fulfillment requirements, and warehouse automation initiatives.
Automotive
Revenue is generated through robotic palletizing and de-palletizing systems used for automotive components, spare parts, and assembly materials. This segment is driven by high-volume manufacturing, just-in-time production practices, improved material flow, and increasing investments in factory automation.
Chemical
Revenue is captured through robotic systems that handle chemical containers, bags, drums, and industrial packaging, minimizing manual intervention. This segment is driven by workplace safety requirements, hazardous material handling, operational efficiency, and demand for reliable pallet movement within chemical production facilities.
Electronics
Revenue is generated through robotic pallet-handling solutions for electronic components, consumer electronics, and electrical equipment that require careful handling. This segment is driven by precision requirements, increasing electronics production, product protection needs, and automated warehouse operations.
Logistics and Warehousing
Revenue is captured through robotic palletizing and de-palletizing systems deployed across fulfillment centers, distribution hubs, and third-party logistics facilities. This segment is driven by expanding e-commerce, high-volume order processing, warehouse automation, and demand for faster material movement.
Others
Revenue is generated through robotic pallet handling solutions deployed across industries such as paper, textiles, agriculture, construction materials, and industrial manufacturing. This segment is driven by increasing adoption of automation, labor optimization initiatives, and the need for efficient material handling across diverse production environments.
Segment - Payload Capacity
Revenue capture definition
Low Payload (up to 50 kg)
Revenue is generated through robotic palletizing and depalletizing systems designed to manage lightweight packages, cartons, trays, and consumer products. This segment is driven by food, pharmaceutical, and consumer goods applications that require high-speed operation, precise handling, and flexible packaging automation.
Medium Payload (50 kg to 500 kg)
Revenue is captured through robotic systems designed to oversee medium-weight bags, cases, crates, containers, and industrial products across manufacturing facilities. This segment is driven by increasing automation across consumer goods, chemicals, logistics, and general industrial material-handling operations.
High Payload (above 500 kg)
Revenue is generated through heavy-duty robotic palletizing and de-palletizing systems capable of handling oversized loads, industrial components, bulk materials, and heavy packaged goods. This segment is driven by increasing automation in automotive, construction materials, chemicals, and heavy manufacturing applications requiring high-load material handling.
Estimation Model
Layer Name
Key Question
Description
Automation Adoption Layer
Who are the potential adopters?
Identifies organizations that are adopting robotic palletizers and depalletizes, including food manufacturers, pharmaceutical companies, consumer goods producers, automotive plants, chemical manufacturers, logistics providers, warehouses, distribution centers, and e-commerce fulfillment facilities.
Automation Infrastructure Layer
What enables deployment?
Deployment depends on robotic arms, end-of-arm tooling, machine vision systems, conveyors, pallet conveyors, programmable logic controllers, warehouse management software, safety systems, and industrial automation infrastructure that support continuous material-handling operations.
Operational Application Layer
Where are robotic systems actively utilized?
Robotic palletizers and depalletizers are deployed across manufacturing lines, packaging facilities, warehouses, cold storage units, distribution centers, fulfillment hubs, production plants, and automated end-of-line material-handling operations.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through robotic palletizing systems, de-palletizing solutions, system integration services, software platforms, maintenance contracts, aftermarket upgrades, spare parts, vision systems, installation services, and technical support agreements.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Robotic Palletizing Automation Performance & Throughput Assessment
Conducted detailed evaluation of robotic palletizing systems across food, beverage, pharmaceutical, consumer goods, and logistics facilities, integrating machine vision, robotic arms, conveyor automation, and intelligent pallet pattern optimization to improve end-of-line material handling efficiency.
Improves throughput, reduces labor dependency, enhances pallet accuracy, minimizes downtime, and increases operational efficiency.
De-palletizing Workflow Optimization & Warehouse Integration Strategy
Assessed deployment of robotic de-palletizing solutions across distribution centers, warehouses, manufacturing plants, and fulfillment facilities, integrating vision-guided robotics, warehouse management systems, automated conveyors, and flexible handling technologies to streamline inbound material flow.
Enhances warehouse productivity, improves handling accuracy, reduces manual operations, and supports continuous automated material flow.
AI-Enabled Vision Systems & Flexible Material Handling Strategy
Evaluated implementation of AI-powered machine vision, adaptive grippers, intelligent robotic controls, and mixed-load handling capabilities across automated palletizing and de-palletizing operations to improve product recognition, operational flexibility, and handling precision.
Enables intelligent automation, improves handling flexibility, enhances product recognition, increases accuracy, and supports scalable operations.
Frequently Asked Questions About This Report
The global robotic palletizers and de-palletizers market size was estimated at USD 2.4 billion in 2025 and is expected to reach USD 2.6 billion in 2026.
The global robotic palletizers and de-palletizers market is expected to grow at a compound annual growth rate of 6.2% from 2026 to 2033 to reach USD 3.9 billion by 2033.
Asia Pacific accounted for a market revenue share of 35.4% in 2025.
Some key players operating in the robotic palletizers and de-palletizers market include FANUC CORPORATION, KION GROUP AG, KUKA AG, ABB Ltd., Krones AG, Schneider Packaging Equipment Company, Inc., Honeywell International Inc., Kaufman Engineered Systems, Doosan Robotics, Inc., Omron Corporation.
The key factors driving the robotic palletizers & de-palletizers market include growing demand for automation across various industries, innovations such as artificial intelligence (AI), machine learning, and advanced vision systems, and ongoing labor shortages and rising labor costs.
The Asia Pacific is the fastest-growing region with a CAGR of over 7% from 2026 to 2033.
The robotic palletizers segment dominated with a 67.7% revenue share in 2025.
The medium payload (50 kg to 500 kg) segment dominated the market with a share of 55.9% in 2025.
Which end use segment held for the largest share in the robotic palletizers & de-palletizers market?The food & beverage segment accounted for the largest share, with 23.7% of revenue in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


