
- Home
- »
- Medical Devices
- »
-
Sacroiliac Joint Fusion Surgery Market Size Report, 2033GVR Report cover

Sacroiliac Joint Fusion Surgery Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (MIS, Open), By Indication, By Approach, By Product, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$419.3MMarket Estimate, 2026
$500.2MMarket Forecast, 2033
$2,047.8MCAGR, 2026–2033
22.3%Sacroiliac Joint Fusion Surgery Market Summary
The global sacroiliac joint fusion surgery market size was valued at USD 419.3 million in 2025 and is projected to grow from USD 500.2 million in 2026 to USD 2,047.8 million in 2033, at a CAGR of 22.3% from 2026 to 2033. North America dominated the market, accounting for a largest revenue share of 40.0% in 2025. The market is primarily driven by the rising global prevalence of chronic low back pain, one of the leading causes of disability worldwide.
Key Market Trends & Insights
- By indication: The degenerative sacroiliitis segment held the largest market share of over 35.0% in 2025.
- By type: The minimally invasive surgery (MIS) segment accounted for the largest revenue share in 2025.
- By end-use: The hospitals segment accounted for the largest revenue share in 2025.
- By approach: The minimally invasive surgery (MIS) segment accounted for the largest revenue share in 2025.
- By product: The implants segment accounted for the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 419.3 Million
- Estimated market size in 2026: USD 500.2 Million
- Projected market size by 2033: USD 2,047.8 Million
- CAGR (2026-2033): 22.3%
Prism AI by Grand View Research Free to tryAsk a question about the sacroiliac joint fusion surgery marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →According to research by the University of California, San Francisco (UCSF) and the Institute for Health Metrics and Evaluation (IHME), around 619 million people were living with low back pain globally in 2020, with this number projected to reach 843 million by 2050. A recent international clinical consensus published in 2025 estimates that 15%–30% of cases of chronic low back pain originate from the sacroiliac (SI) joint, supporting the growing demand for accurate diagnosis and minimally invasive sacroiliac joint fusion procedures.
Technological innovation continues to reshape the sacroiliac joint fusion market. Advances in implant design, biomaterials, and minimally invasive surgical techniques are improving procedural precision, accelerating patient recovery, and enhancing long-term clinical outcomes. The growing adoption of additive manufacturing and 3D-printed titanium implants is further strengthening implant stability and promoting better osteointegration, supporting broader clinical acceptance of SI joint fusion procedures.
Favorable reimbursement policies and continued product innovation are also accelerating market expansion. Leading manufacturers are investing in next-generation implant systems, clinical evidence generation, and commercialization initiatives to improve physician adoption and expand treatment options across hospitals and ambulatory surgery centers. For instance, in February 2026, SI-BONE, Inc. announced a strategic partnership with Smith+Nephew to distribute its iFuse TORQ portfolio across Level I and Level II trauma centers in the U.S. The company also launched the INTRA Ti minimally invasive fusion system and reported continued progress in reimbursement, further supporting the adoption of sacroiliac joint fusion procedures.
Market Concentration & Characteristics
The sacroiliac joint fusion surgery market is characterized by a high degree of innovation, driven by continuous advances in implant technology, biomaterials, and minimally invasive surgical techniques. Modern navigation systems, intraoperative imaging, and 3D-printed titanium implants are improving surgical precision, implant stability, and long-term fusion outcomes while reducing recovery time and procedure-related complications. These technological developments continue to enhance physician confidence and support broader adoption of minimally invasive sacroiliac joint fusion procedures.
The market is witnessing moderate merger and acquisition activity as companies strengthen their product portfolios and expand their presence in the spine surgery market. Strategic acquisitions enable manufacturers to broaden their technological capabilities and accelerate the commercialization of innovative SI joint solutions. For instance, in December 2023, Nevro Corp. acquired Vyrsa Technologies in a transaction valued at up to USD 75 million (including an upfront payment of USD 40 million), expanding its portfolio of sacroiliac joint fusion technologies.
The industry operates under a stringent regulatory framework. SI joint fusion devices must obtain approval from regulatory authorities, such as the U.S. FDA, and comply with requirements for quality systems, product registration, labeling, post-market surveillance, adverse event reporting, and product modifications. While these regulations increase development costs and approval timelines, they also help ensure product safety, clinical effectiveness, and long-term market credibility.
Non-surgical treatment options continue to serve as alternatives for selected patients with sacroiliac joint dysfunction. Physical therapy, corticosteroid injections, radiofrequency ablation, platelet-rich plasma (PRP), and stem cell therapies are commonly used to manage pain and improve joint function, particularly in the early stages of the disease. However, patients with persistent symptoms or structural instability increasingly require minimally invasive fusion procedures for durable pain relief.
Companies are also expanding geographically through commercialization initiatives and continued investment in research and development. For instance, in July 2023, PainTEQ secured USD 35 million in non-dilutive growth capital to accelerate the commercialization of its LinQ minimally invasive sacroiliac joint stabilization system, expand market access, and support ongoing product development and clinical research.
Analyst Perspective
The sacroiliac joint fusion surgery market is expanding as the diagnosis of sacroiliac joint disorders becomes more accurate and awareness among spine specialists continues to improve. Growing clinical evidence supporting minimally invasive fusion procedures is encouraging surgeons to adopt these techniques for patients with chronic sacroiliac joint pain who do not respond to conservative treatments. Compared to traditional open surgery, minimally invasive approaches offer shorter hospital stays, reduced blood loss, and faster recovery, making them an increasingly preferred option. Companies that provide clinically proven implants, surgeon education, and advanced surgical navigation technologies are likely to strengthen their market position. In the coming years, market growth will be supported by continued improvements in surgical techniques, favorable reimbursement in key markets, and the ability to demonstrate long-term clinical outcomes that enhance patient quality of life.
Indication Insights
The degenerative sacroiliitis segment accounted for the largest revenue share, over 35.0%, in 2025. Degenerative changes remain one of the leading causes of chronic sacroiliac joint pain, particularly among the aging population and individuals with osteoarthritis or long-standing mechanical stress. Initial treatment typically involves conservative approaches such as physical therapy, non-steroidal anti-inflammatory drugs (NSAIDs), and muscle relaxants. However, these interventions often provide limited relief in chronic cases. Patients with persistent symptoms may require corticosteroid injections or radiofrequency ablation for pain management, while minimally invasive sacroiliac joint fusion is increasingly recommended for individuals who fail to respond to non-surgical therapies. Growing awareness, improved diagnostic capabilities, and wider adoption of minimally invasive procedures continue to support the segment's dominance.
The trauma segment is expected to register the fastest CAGR from 2026 to 2033. Rising incidences of pelvic trauma, sports injuries, and high-impact accidents are increasing the number of patients with sacroiliac joint injuries requiring surgical intervention. Clinical studies indicate that sacroiliac joint trauma commonly results from high-energy injuries such as motor vehicle accidents, falls, and repetitive mechanical stress, while athletes and pregnant women also face an elevated risk due to repetitive loading and biomechanical changes. Severe cases, including sacroiliac joint fracture-dislocations and pelvic ring instability, frequently require prompt surgical stabilization. As trauma care continues to advance and access to specialized orthopedic procedures improves, demand for sacroiliac joint fusion surgery is expected to increase steadily over the forecast period.
End Use Insights
The hospitals segment accounted for the largest share of revenue in 2025. Hospitals remain the primary setting for sacroiliac joint fusion procedures due to their advanced surgical infrastructure, availability of multidisciplinary spine care teams, and ability to manage complex cases. The segment also benefits from favorable reimbursement policies, higher patient volumes, and the continued expansion of healthcare infrastructure across both developed and emerging markets. In addition, patients undergoing sacroiliac joint fusion often require post-operative monitoring and rehabilitation, further reinforcing hospitals as the preferred treatment setting. According to the American Hospital Association, there were approximately 6,120 hospitals in the U.S. in 2024.
The ambulatory surgical centers (ASCs) segment is expected to register the fastest CAGR from 2026 to 2033. The shift toward minimally invasive sacroiliac joint fusion procedures is increasing the suitability of ASCs, where patients benefit from lower treatment costs, shorter procedure times, and same-day discharge. Growing physician preference for outpatient care, improved surgical technologies, and expanding ASC infrastructure are further supporting segment growth. According to Olympus, the U.S. had approximately 6,223 ambulatory surgery centers in 2023, a number that continues to rise as outpatient surgical care expands.
Type Insights
The minimally invasive surgery (MIS) segment accounted for the largest revenue share in 2025 and is expected to register the fastest CAGR from 2026 to 2033. Growing clinical preference for minimally invasive procedures, driven by smaller incisions, reduced blood loss, shorter hospital stays, and faster recovery, continues to support segment growth. As surgical technologies advance, physicians are increasingly adopting MIS techniques for sacroiliac joint fusion to improve procedural efficiency and patient outcomes. Reflecting this trend, SI-BONE, Inc. launched INTRA Ti in February 2026, a minimally invasive sacroiliac joint fusion system designed to enhance procedural flexibility and workflow efficiency, particularly in ambulatory surgery centers.
The open surgery segment is expected to witness steady growth over the forecast period. Although minimally invasive procedures are becoming the standard of care, open surgery remains necessary for complex cases involving severe trauma, deformities, revision procedures, or extensive pelvic reconstruction. The rising elderly population and increasing prevalence of degenerative spine and sacroiliac joint disorders are expected to sustain demand for open surgical interventions. According to the Population Reference Bureau, the U.S. population aged 65 years and older is projected to increase from 58 million in 2022 to 82 million by 2050, expanding the population at greater risk of orthopedic and spinal conditions that may require surgical treatment.
Approach Insights
The lateral segment accounted for the largest revenue share in 2025. The lateral transiliac approach remains the most widely adopted technique for minimally invasive sacroiliac joint fusion due to its strong clinical evidence, established surgical workflow, and favorable long-term outcomes. The procedure involves placing implants across the sacroiliac joint to stabilize the ilium and sacrum, promoting durable fusion while minimizing tissue disruption. Its lower complication and revision rates compared with alternative approaches have further strengthened clinical adoption. Continued product innovation and regulatory approvals are also supporting segment growth. Notable lateral fusion systems include SI-BONE, Inc.'s iFuse and Zimmer Biomet's TriCor.
The dorsal & anterior segment is expected to register the fastest CAGR from 2026 to 2033. Growing interest in posterior and anterior fusion techniques is expanding treatment options for patients with sacroiliac joint dysfunction. These approaches enable direct access to the joint for implant placement and bone grafting while minimizing soft tissue disruption in selected cases. Manufacturers continue introducing dedicated posterior fusion systems to address evolving surgical preferences. For instance, SIGNUS Medizintechnik GmbH offers the DIANA system for posterior (dorsal) sacroiliac joint fusion. In addition, published clinical evidence has demonstrated favorable fusion rates and pain relief with anterior sacroiliac joint arthrodesis in appropriately selected patients, supporting the growing adoption of these approaches.
Product Insights
The implants segment accounted for the largest revenue share in 2025 and is expected to register the fastest CAGR from 2026 to 2033. Growth is driven by continuous advancements in implant materials, design, and manufacturing technologies that improve fusion outcomes and procedural efficiency. The increasing adoption of 3D printing is enabling the development of patient-specific implants with enhanced osseointegration and mechanical performance, while also supporting preoperative planning and surgical precision. Reflecting this trend, Croom Medical introduced a 3D-printed personalized SI Joint Fixation device in January 2023, manufactured using advanced metal laser powder bed fusion technology with titanium, tantalum, and cobalt-chrome materials.
The accessories segment is expected to witness significant growth over the forecast period. Rising procedure volumes are increasing demand for specialized instrumentation and accessory kits that simplify implant placement and improve surgical accuracy. Manufacturers continue enhancing their instrumentation systems to support minimally invasive workflows and optimize clinical outcomes. For example, Zimmer Biomet's TriCor System includes dedicated instruments for joint preparation, bone graft placement, and implant insertion, while the Silex Sacroiliac Joint Fusion System (formerly from X-spine Systems, now part of Camber Spine Technologies) provides procedure-specific instrumentation designed to facilitate efficient implant placement and improve surgical outcomes.
Regional Insights
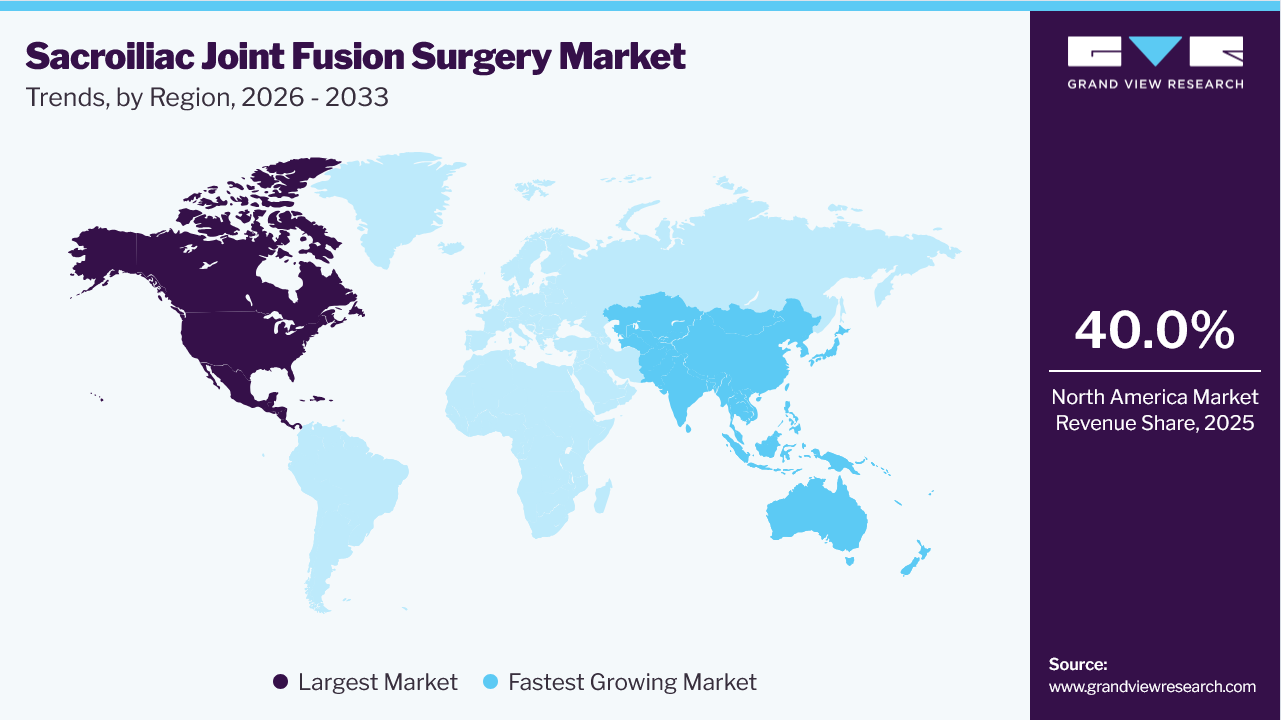
North America dominated the global sacroiliac joint fusion surgery market in 2025, accounting for around 40.0% of total revenue. The region benefits from advanced healthcare infrastructure, favorable reimbursement policies, high adoption of minimally invasive spine procedures, and the strong presence of leading medical device manufacturers. Continued investments in clinical research, product innovation, and commercialization, along with strategic partnerships and regulatory approvals, are further strengthening market growth across the region.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
U.S. Sacroiliac Joint Fusion Surgery Market Trends
The U.S. accounted for the largest share of the North American market in 2025. High procedure volumes, widespread availability of advanced surgical technologies, and supportive reimbursement frameworks continue to drive market expansion. Manufacturers are also introducing next-generation fusion systems to improve clinical outcomes. For instance, in June 2024, Spinal Simplicity received U.S. FDA 510(k) clearance for its Patriot-SI Posterior Fusion System, designed to complement the Liberty-SI lateral fusion system as part of a hybrid sacroiliac joint fusion approach.
Canada is expected to register the fastest CAGR from 2026 to 2033. Increasing recognition of sacroiliac joint dysfunction as a significant cause of chronic lower back pain, improving diagnostic capabilities, and growing adoption of minimally invasive treatment options are supporting market growth. Rising healthcare investments and expanding access to specialized spine care are further expected to accelerate the adoption of sacroiliac joint fusion procedures across the country.
Europe Sacroiliac Joint Fusion Surgery Market Trends
The Europe sacroiliac joint fusion surgery market is expected to register strong growth over the forecast period. Growth is supported by advanced healthcare infrastructure, increasing adoption of minimally invasive spine procedures, favorable clinical evidence, and rising awareness of sacroiliac joint dysfunction as a cause of chronic lower back pain. Ongoing product innovation and commercialization are further strengthening the regional market. Reflecting this trend, in February 2025, SpineGuard and Omnia Medical commercially launched PsiFGuard, a smart drilling solution designed to improve the accuracy and safety of sacroiliac joint fusion procedures.
Germany is expected to witness considerable market growth during the forecast period. The country benefits from a strong medical device industry, growing awareness of sacroiliac joint disorders, and the presence of innovative domestic manufacturers. SIGNUS Medizintechnik GmbH continues to strengthen its position with the DIANA sacroiliac joint fusion system, which combines specialized implants and instrumentation to enable posterior distraction-interference arthrodesis while minimizing disruption to surrounding neurovascular structures and improving implant stability.
The UK market is also expected to grow steadily over the forecast period. The increasing prevalence of chronic lower back pain, coupled with improved diagnosis of sacroiliac joint dysfunction, is supporting demand for fusion procedures. According to the Health Survey for England 2024, published by NHS England in 2026, 26% of adults in England reported living with chronic pain, and 52% of those individuals experienced back pain. The growing burden of chronic musculoskeletal disorders and an aging population are expected to continue driving market growth.
Asia Pacific Sacroiliac Joint Fusion Surgery Market Trends
The Asia Pacific sacroiliac joint fusion surgery market is expected to register the fastest CAGR from 2026 to 2033. Growth is driven by the rising prevalence of chronic lower back pain, a large patient population, improving healthcare infrastructure, increasing healthcare expenditure, and growing awareness of minimally invasive spine procedures. According to projections from the Institute for Health Metrics and Evaluation (IHME), the number of people living with low back pain worldwide is expected to reach 843 million by 2050, with the largest increase anticipated in Asia and Africa, creating substantial demand for advanced treatment options.
China accounted for the largest share of the Asia Pacific market in 2025. Expanding access to specialized spine care, increasing adoption of minimally invasive sacroiliac joint fusion procedures, and the growing availability of advanced implant systems are supporting market growth. As hospitals continue to adopt modern surgical technologies, demand for minimally invasive SI joint fusion is expected to increase steadily.
India is expected to witness considerable growth over the forecast period. Rising investments in healthcare infrastructure, expanding access to orthopedic and spine care services, and increasing awareness of sacroiliac joint disorders are driving market expansion. In addition, growing participation by medical device manufacturers through product launches, partnerships, clinical research, and commercialization initiatives is expected to accelerate further the adoption of sacroiliac joint fusion procedures in the country.
Latin America Sacroiliac Joint Fusion Surgery Market Trends
A progressively aging population drives the sacroiliac joint fusion surgery market in Latin America, and rising awareness of minimally invasive treatment options has increased demand for such procedures. Moreover, increasing investment by market players in the region and free trade agreements with major countries, such as the U.S., Canada, Japan, and several European countries, are expected to boost Latin America’s market during the forecast period.
Brazil sacroiliac joint fusion surgery market is anticipated to grow at a healthy rate over the forecast period. A diagnosis of several medical conditions results in pain in the sacroiliac joint. These include adjacent segment disease, degenerative sacroiliitis, degenerative osteoarthritis, SI joint infection, SI joint inflammation, SI joint disruption, trauma, and tumors. The high prevalence of associated sacroiliac joint pain conditions and the growing availability of various treatment options are estimated to drive market growth in the country.
MEA Sacroiliac Joint Fusion Surgery Market Trends
The MEA sacroiliac joint fusion surgery market is anticipated to grow lucratively during the forecast period. This is due to the development of healthcare infrastructure, the growing prevalence of chronic lower back pain, and the regional expansion of key companies.
South Africa sacroiliac joint fusion surgery market is witnessing growing awareness of the benefits of SI joint fusion in patients who have not responded to conservative care. The development of healthcare infrastructure & services is estimated to fuel market growth in South Africa over the forecast period.
Key Sacroiliac Joint Fusion Surgery Market Company Insights
Key participants in the market are focusing on devising innovative business growth strategies, including product portfolio expansions, partnerships & collaborations, mergers & acquisitions, and business footprint expansions.
Key Sacroiliac Joint Fusion Surgery Companies:
The following key companies have been profiled for this study on the sacroiliac joint fusion surgery market
SI-BONE, Inc.
Globus Medical, Inc.
Orthofix Medical Inc.
Camber Spine Technologies, LLC
Life Spine, Inc.
CoreLink, LLC
PainTEQ, Inc.
Johnson & Johnson MedTech
SIGNUS Medizintechnik GmbH
Medtronic plc
Recent Developments
- In May 2024, PainTEQ was granted two additional U.S. patents covering the LinQ Sacroiliac Joint Stabilization System, strengthening its intellectual property portfolio and supporting continued innovation in minimally invasive treatments for sacroiliac joint dysfunction.
- In June 2023, Genesys Spine launched the SIros O Oblique SI Fusion System, expanding its sacroiliac joint fusion portfolio with an oblique approach that provides surgeons with an additional minimally invasive option for treating sacroiliac joint dysfunction.
Sacroiliac Joint Fusion Surgery Market Report Scope
Report Attribute
Details
Market size in 2025
USD 419.3 million
Estimated market size in 2026
USD 500.2 million
Projected market size by 2033
USD 2,047.8 million
Growth rate
CAGR of 22.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, indication, approach, product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; Brazil; Argentina; South Africa; UAE
Key companies profiled
SI-BONE, Inc.; Globus Medical, Inc.; Orthofix Medical Inc.; Camber Spine Technologies, LLC; Life Spine, Inc.; CoreLink, LLC; PainTEQ, Inc.; Johnson & Johnson MedTech; SIGNUS Medizintechnik GmbH; Medtronic plc
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Sacroiliac Joint Fusion Surgery Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global sacroiliac joint fusion surgery market report based on type, indication, approach, product, end use, and region:
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Degenerative Sacroiliitis
-
Sacral Disruption
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
MIS
-
Open
-
-
Approach Outlook (Revenue, USD Million, 2021 - 2033)
-
Dorsal & Anterior
-
Lateral
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Implants
-
Accessories
-
-
End use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
UAE
-
-
Frequently Asked Questions About This Report
North America dominated with an approximately 40.0% revenue share in 2025.
Key players in the market include SI-BONE, Inc.; Globus Medical, Inc.; Orthofix Medical Inc.; Camber Spine Technologies, LLC; Life Spine, Inc.; CoreLink, LLC; PainTEQ, Inc.; Johnson & Johnson MedTech; SIGNUS Medizintechnik GmbH; Medtronic plc, and others.
The implants segment accounted for the largest revenue share in 2025.
The global sacroiliac joint fusion surgery market size was valued at USD 419.3 million in 2025 and is estimated at USD 500.2 million for 2026.
The global sacroiliac joint fusion surgery market is expected to grow at a CAGR of 22.3% from 2026 to 2033, reaching USD 2,047.8 million.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


