
- Home
- »
- Medical Devices
- »
-
Saudi Arabia Wearable Medical Devices Market Report, 2033GVR Report cover

Saudi Arabia Wearable Medical Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Diagnostic, Therapeutic), By Site (Handheld, Headband, Strap/Clip/Bracelet, Shoe Sensors), By Application, By Grade Type, By Distribution Channel, And Segment Forecasts
Market Size, 2025
$370.8MMarket Estimate, 2026
$447.2MMarket Forecast, 2033
$2,054.7MCAGR, 2026–2033
24.3%Saudi Arabia Wearable Medical Devices Market Summary
The Saudi Arabia wearable medical devices market size was valued at USD 370.8 million in 2025 and is projected to grow from USD 447.2 million in 2026 to USD 2,054.7 million in 2033, at a CAGR of 24.3% from 2026 to 2033. The market is primarily driven by the rapid expansion of remote patient monitoring and home healthcare services, rising consumer adoption of preventive healthcare practices, and the growing demand for connected fitness and wellness devices.
Key Market Trends & Insights
- By product: Diagnostics device segment captured the largest revenue share of over 60.0% in 2025.
- By site: Strap/clap/bracelet site segment held a market share of around 50.0% in 2025.
- By grade type: Consumer-grade wearable medical devices segment held a market share of 75.0% in 2025.
- By application: Home healthcare segment held a market share of around 55.0% in 2025.
- By distribution channel: Pharmacy segment captured the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 370.8 Million
- Estimated market size in 2026: USD 447.2 Million
- Projected market size by 2033: USD 2,054.7 Million
- CAGR (2026-2033): 24.3%
Prism AI by Grand View Research Free to tryAsk a question about the saudi arabia wearable medical devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The rise in lifestyle-related diseases poses a significant threat to the health of Saudi Arabia's population. Increasing obesity rates, which indicate a decline in healthy living practices, are linked to many non-communicable diseases such as hypertension, type 2 diabetes, and dyslipidemia. These conditions can lead to serious cardiovascular disorders. According to the General Authority for Statistics (GASTAT) 2024 Health Determinants Statistics, published in 2025, 23.1% of Saudi citizens aged 15 and older are classified as obese, while 45.1% are considered overweight.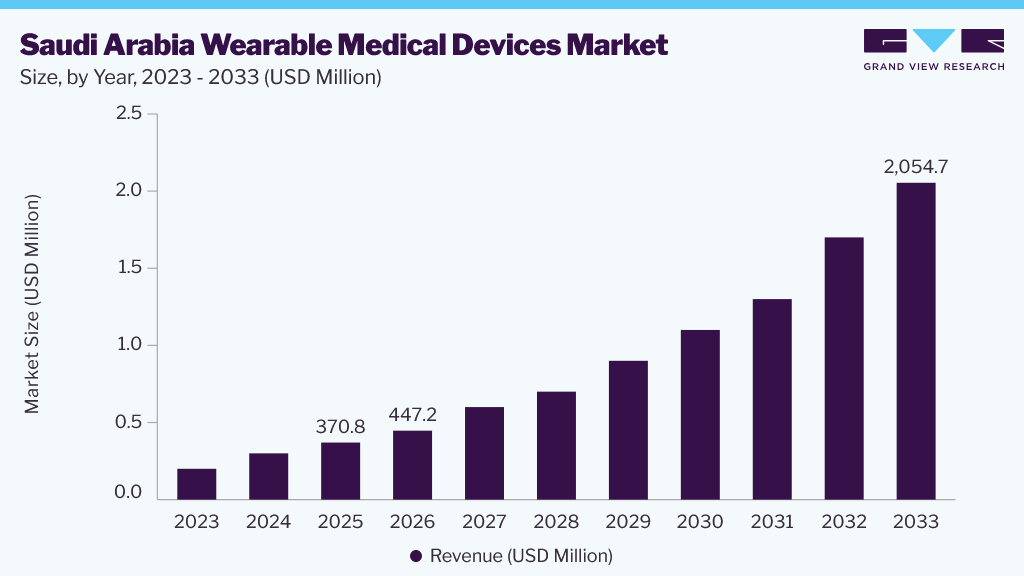 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
In response to this public health challenge, the Saudi government’s Vision 2030 project plans to invest USD 65 million in the healthcare sector, focusing on research and development (R&D) to enhance healthcare infrastructure, including telemedicine and remote patient monitoring. Recent advancements, such as the integration of artificial intelligence (AI), continuous monitoring capabilities, and advanced sensors in wearable medical devices, are transforming healthcare delivery. Leading companies in the wearable medical device industry are also making a significant impact by introducing innovative technologies. For instance, in September 2025, Koninklijke Philips N.V. unveiled its Smart Telemetry Platform, which includes the next-generation Telemetry Monitor 5500. This lightweight wearable patient monitor allows for continuous cardiac monitoring and enterprise-wide connectivity while facilitating AI-enabled clinical workflows. The solution aims to enhance patient mobility, streamline hospital operations, and improve real-time clinical decision-making.
Analyst Perspective
The wearable medical devices market in Saudi Arabia is gaining traction as healthcare delivery shifts toward continuous monitoring, preventive care, and digital health. The increasing prevalence of chronic diseases, coupled with growing awareness of personal health management, is encouraging the adoption of smartwatches, wearable ECG monitors, continuous glucose monitoring systems, and other connected health devices. Government initiatives under Vision 2030 are further supporting this transition by expanding digital healthcare infrastructure and promoting remote patient monitoring. Companies that can offer clinically validated devices, seamless connectivity, and intuitive user experiences are likely to strengthen their market position. As healthcare providers increasingly integrate wearable data into routine clinical care, demand is expected to move toward interoperable and AI-enabled solutions. Over time, market growth will be driven by technological innovation, patient engagement, and the ability to deliver accurate, real-time health insights that improve clinical outcomes and reduce healthcare costs.
Product Insights
The diagnostics device segment led the market in 2025, capturing over 60.0% of the share. According to the World Bank, life expectancy at birth in Saudi Arabia increased from 71 years in 2000 to approximately 79 years in 2024. This rising life expectancy, combined with a growing elderly population and an increasing prevalence of chronic diseases such as diabetes, cardiovascular disorders, and cancer, is driving demand for wearable medical devices. These devices facilitate continuous health monitoring, early disease detection, and remote patient management.
Ischaemic heart disease ranks as the leading cause of death in Saudi Arabia. This highlights the urgent need for early diagnosis of cardiovascular diseases (CVDs), including coronary heart disease, rheumatic heart disease, and cerebrovascular disease. Additionally, growing public awareness of cardiovascular wearables' ability to monitor heart and pulse rates during daily activities continuously is expected to boost this segment further.
The therapeutic device segment is projected to experience the fastest CAGR during the forecast period. A robust pipeline of therapeutic devices, including wearable pain relievers, insulin management devices, and intelligent asthma management products, is anticipated to drive market growth.
Site Insights
The wearable medical devices market is divided into several categories, including handheld devices, headbands, straps/wristbands/bracelets, shoe sensors, and others. The strap/wristband/bracelet segment accounted for the largest revenue share, over 50%, in 2025. Technological advancements, such as ECG tracking, pulse rate monitoring, and respiratory monitoring, along with Bluetooth and cloud connectivity, are expected to drive market growth further. For example, in June 2025, Polar Electro expanded its wearable health portfolio by launching the Polar Grit X2, which utilizes the company's Polar Elixir biosensing platform. This device integrates features such as optical heart rate monitoring, wrist ECG, blood oxygen (SpO₂) tracking, skin temperature monitoring, and advanced recovery analytics, enhancing wearable health monitoring for both fitness and preventive healthcare applications.
The handheld segment is projected to experience the fastest growth in the Saudi Arabian wearable medical devices market during the forecast period. This growth is driven by increasing demand for portable health-monitoring solutions and user-friendly diagnostic devices. Additionally, rising consumer awareness of preventive healthcare, greater adoption of digital health technologies, and the expansion of remote patient monitoring services are supporting this segment's growth. Continuous product innovations and improved connectivity features are also expected to accelerate the adoption of handheld wearable medical devices across Saudi Arabia.
Application Insights
In 2025, the home healthcare segment accounted for approximately 55.0% of the market share. This growth can be attributed to the increasing prevalence of lifestyle-related diseases and the rising demand for remote patient monitoring. For example, in 2025, Saudi Arabia's Seha Virtual Hospital expanded its home healthcare services by integrating wearable patient monitoring devices, telemedicine, and remote clinical monitoring across more than 240 hospitals nationwide. This initiative allows for continuous monitoring of patients with chronic conditions in home settings, reducing the need for hospital visits and improving access to specialized care, as part of the Kingdom's Vision 2030 healthcare transformation program.
The remote patient monitoring segment is projected to experience the fastest CAGR during the forecast period. In 2025, Saudi Arabia continued to enhance the capabilities of the Seha Virtual Hospital (SVH), recognized as the world's largest virtual hospital, by incorporating wearable patient-monitoring technologies, AI-powered clinical decision support, and telemedicine services across more than 220 hospitals nationwide. Saudi Arabia is notable for being the first country in the Middle East to offer e-health services through the SEHA Virtual Hospital.
Grade Type Insights
The consumer-grade wearable medical devices segment accounted for approximately 75.0% of the revenue share in 2025. Factors such as user-friendly functionality, affordability, and convenience contribute to this market growth. Additionally, technological advancements in clinical applications are expected to drive this growth further. The use of artificial intelligence (AI), the Internet of Things (IoT), and cloud computing assists physicians and healthcare providers in diagnosing and treating diseases. For example, in May 2025, Medtronic's HealthCast intelligent patient monitoring solution received the 2025 MedTech Breakthrough Award for "Best Overall Medical Device Solution." This AI-enabled platform integrates wearable patient monitoring, predictive analytics, and real-time clinical insights to enhance patient surveillance and support remote healthcare delivery across hospitals.
The clinical wearable medical devices segment is projected to register the fastest CAGR over the forecast period. This growth is driven by the increasing prevalence of chronic diseases and a growing demand for continuous patient monitoring. Furthermore, the expanding adoption of remote patient monitoring solutions, supportive digital healthcare initiatives, and rising investments in connected medical technologies are all contributing to this segment's growth. Additionally, the increasing integration of wearable devices in hospitals is expected to accelerate the adoption of clinical wearable medical devices across Saudi Arabia.
Distribution Channel Insights
The pharmacy segment dominated the market with the largest revenue share in 2025, owing to the availability and widespread accessibility of pharmacies, providing customers with an easy way to buy these devices. The significant revenue share that pharmacies hold in the wearable medical device market stems from their role as health and wellness centers and their ability to provide expert guidance.
Consumers' growing preference for online shopping is driving growth in the segment. The variety, accessibility, and ease of use of e-commerce platforms support this trend. The market for wearable medical devices is anticipated to grow due to increased demand driven by the ease and effectiveness of online shopping as the online retail industry continues to flourish.
Key Saudi Arabia Wearable Medical Devices Market Company Insights
The Saudi Arabia wearable medical devices industry features a range of global, regional, and local players, making it a competitive market. The world’s leading companies are using partnerships, collaborations, acquisitions, mergers, and agreements as strategies to withstand the intense competition and increase their market share. Saudi Arabia's wearable medical device manufacturers are investing heavily in product enhancements and new product development.
Key Saudi Arabia Wearable Medical Devices Companies
The following key companies have been profiled for this study on the Saudi Arabia wearable medical devices market:
-
Koninklijke Philips N.V.
-
Garmin Ltd.
-
Medtronic plc
-
OMRON Corporation
-
Polar Electro Oy
-
Sotera Wireless, Inc.
-
Huawei Device Co., Ltd.
-
Apple Inc.
-
Fitbit LLC
-
Withings S.A.S.
Recent Developments
-
In January 2025, Huawei Device Saudi Arabia expanded the availability of the HUAWEI WATCH D2 in the country. The wearable integrates ambulatory blood pressure monitoring (ABPM), ECG, SpO₂, heart rate, and sleep monitoring capabilities, supporting the growing adoption of digital health technologies in Saudi Arabia.
Saudi Arabia Wearable Medical Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 370.8 million
Estimated market size in 2026
USD 447.2 million
Projected market size by 2033
USD 2,054.7 million
Growth rate
CAGR of 24.3% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, site, application, grade type, distribution channel
Country scope
Saudi Arabia
Key companies profiled
Koninklijke Philips N.V.; Garmin Ltd.; Medtronic plc; OMRON Corporation; Polar Electro Oy; Sotera Wireless, Inc.; Huawei Device Co., Ltd.; Apple Inc.; Fitbit LLC; Withings S.A.S.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Saudi Arabia Wearable Medical Devices Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Saudi Arabia wearable medical devices market report based on product, site, application, grade type, and distribution channel:
- Product Outlook (Revenue, USD Million, 2021 - 2033)
- Diagnostic Devices
- Vital Sign Monitoring Devices
- Heart Rate Monitors
- Activity Monitors
- Electrocardiographs
- Pulse Oximeters
- Spirometers
- Blood Pressure Monitors
- Others
- Sleep Monitoring Devices
- Sleep Trackers
- Wrist Actigraphs
- Polysomnographs
- Others
- Electrocardiographs Fetal and Obstetric Devices
- Neuromonitoring devices
- Electroencephalographs
- Electromyographs
- Others
- Vital Sign Monitoring Devices
- Therapeutic Devices
- Pain Management Devices
- Neurostimulation Devices
- Others
- Insulin/Glucose Monitoring Devices
- Insulin Pumps
- Others
- Rehabilitation Devices
- Accelometers
- Sensing Devices
- Ultrasound Platform
- Others
- Respiratory Therapy Devices
- Ventilators
- Positive Airway Pressure (PAP) Devices
- Portable Oxygen Concentrators
- Others
- Pain Management Devices
- Diagnostic Devices
- Site Outlook (Revenue, USD Million, 2021 - 2033)
- Handheld
- Headband
- Strap/Clip/Bracelet
- Shoe Sensors
- Others
- Application Outlook (Revenue, USD Million, 2021 - 2033)
- Sports and Fitness
- Remote Patient Monitoring
- Home Healthcare
- Grade Type Outlook (Revenue, USD Million, 2021 - 2033)
- Consumer-Grade Wearable Medical Devices
- Clinical Wearable Medical Devices
- Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
- Pharmacies
- Online Channel
- Hypermarkets
Frequently Asked Questions About This Report
The Saudi Arabia wearable medical devices market size was valued at USD 370.8 million in 2025 and is estimated at USD 447.2 million for 2026.
The Saudi Arabia wearable medical devices market is expected to grow at a CAGR of 24.3% from 2026 to 2033, reaching USD 2,054.7 million.
The diagnostics device segment accounted for the largest revenue share of around 60.0% in 2025.
Key players in the market include Koninklijke Philips N.V.; Garmin Ltd.; Medtronic plc; OMRON Corporation; Polar Electro Oy; Sotera Wireless, Inc.; Huawei Device Co., Ltd.; Apple Inc.; Fitbit LLC; Withings S.A.S.; and others.
Key factors driving the market growth include rapid expansion of remote patient monitoring and home healthcare services, rising consumer adoption of preventive healthcare practices, and the growing demand for connected fitness and wellness devices.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


