
- Home
- »
- Next Generation Technologies
- »
-
Software-Defined Automation Market Report, 2026-2033GVR Report cover

Software-defined Automation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Solution, Services), By Deployment, By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$44.9BMarket Estimate, 2026
$52.0BMarket Forecast, 2033
$131.4BCAGR, 2026–2033
14.2%Software-defined Automation Market Summary
The global software-defined automation market size was valued at USD 44.9 billion in 2025 and is projected to grow from USD 52.0 billion in 2026 to USD 131.4 billion by 2033, at a CAGR of 14.2% from 2026 to 2033. Asia Pacific dominated the global market with a revenue share of 32.6% in 2025. The market growth is primarily driven by the increasing adoption of cloud computing, software-defined infrastructure, and programmable automation platforms that improve operational efficiency and resource utilization.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Solution segment held the largest revenue share of 69.9% in 2025.
- By deployment: On-premises segment held the largest revenue share of 68.5% in 2025.
- By application: Process automation segment dominated the market in 2025.
- By end use: Manufacturing segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (32.6% revenue share in 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR 15.8%, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 44.9 Billion
- Estimated market size in 2026: USD 52.0 Billion
- Projected market size by 2033: USD 131.4 Billion
- CAGR (2026-2033): 14.2%
Prism AI by Grand View Research Free to tryAsk a question about the software-defined automation marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The expansion of DevOps, infrastructure-as-code, and cybersecurity automation is further supporting market growth by enabling faster deployment, streamlined IT operations, and automated threat response. The growth of the software-defined automation industry is driven by the growing adoption of hybrid and multi-cloud environments, DevOps practices, and infrastructure-as-code, which is accelerating investment in software-defined automation. Enterprises are moving beyond manual, hardware-dependent management toward policy-driven automation that supports consistent deployment and centralized control across distributed systems. Infrastructure-as-code enables teams to define and replicate infrastructure configurations through software, while automated workflows reduce provisioning time and support faster application delivery. This transition is particularly relevant for organizations managing large-scale IT environments, frequent software releases, and diverse cloud resources.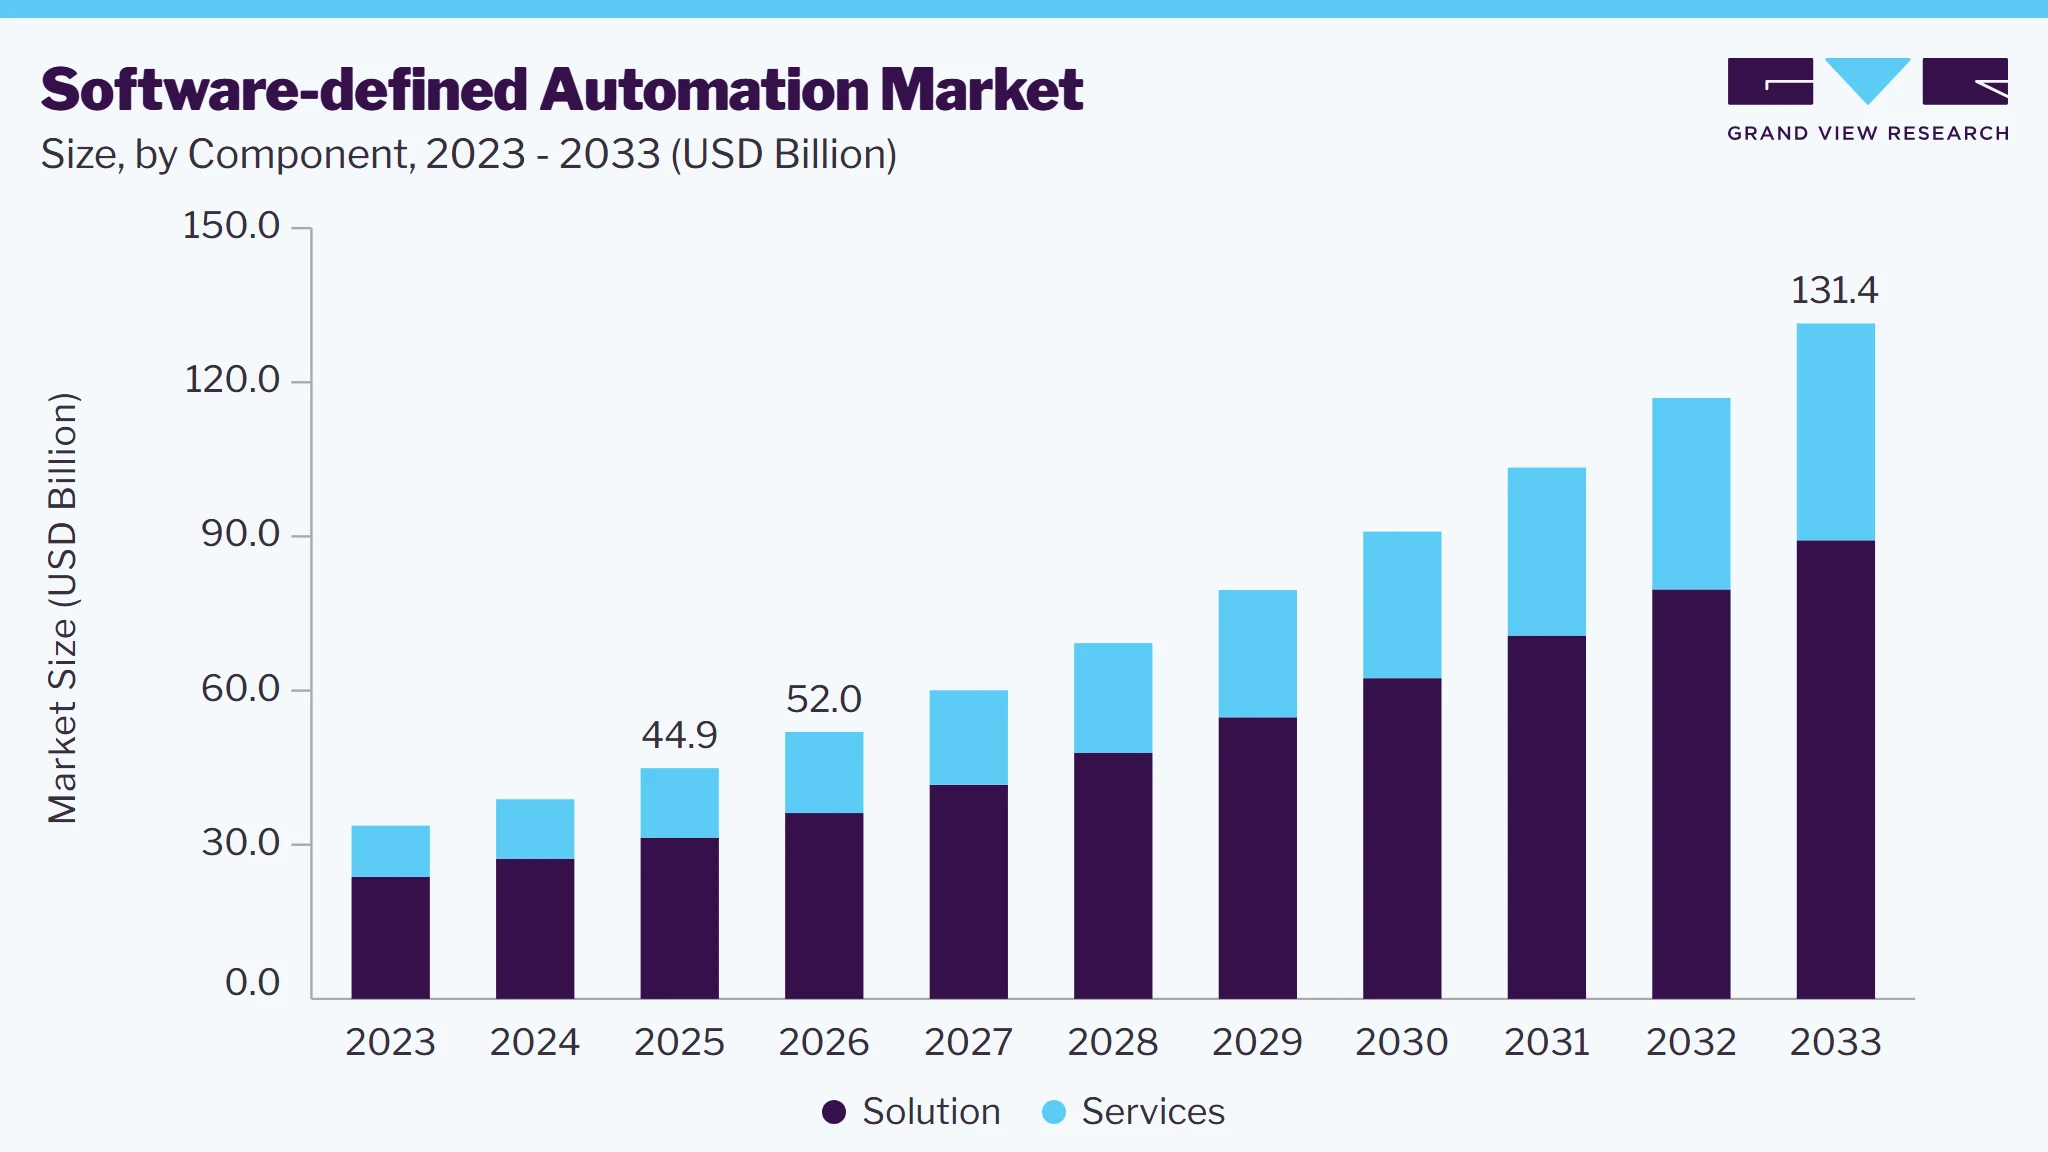 To learn more about this report, Download Free Sample Report
The software-defined automation market is experiencing increasing adoption of network automation and security automation to address the operational complexity of modern digital infrastructure. Software-defined networking enables programmable management of network resources, automated configuration, and dynamic service provisioning. Security automation platforms are being used to streamline threat detection, incident response, vulnerability management, and compliance workflows. Growing cybersecurity requirements, expanding connected infrastructure, and the need for faster response to operational and security events are encouraging enterprises to integrate automation across IT operations and security functions.
Additionally, operational efficiency, scalability, and resource optimization are broadening the scope of software-defined automation investments beyond basic task automation. Enterprises are increasingly evaluating platforms based on their ability to integrate heterogeneous systems, reduce manual intervention, improve service reliability, and support continuous operational improvements. Automation is also being applied across business processes, including workflow management, data processing, application operations, and enterprise service delivery. These developments are increasing the demand for solutions that connect infrastructure, applications, and business processes within a unified automation environment.
Moreover, the market is expected to transition toward intelligent, cloud-native, and increasingly autonomous automation solutions. Artificial intelligence and machine learning are being incorporated into automation platforms to support predictive monitoring, anomaly detection, event correlation, and automated decision-making. Low-code and no-code capabilities are also broadening access to automation by enabling users to design workflows with limited programming expertise. The combination of cloud adoption, cybersecurity requirements, digital transformation, and the need for scalable IT operations is expected to sustain investment in software-defined automation solutions and related services across IT and telecom, BFSI, healthcare, manufacturing, retail, and other industries.
Market Dynamics
The software-defined automation market is experiencing strong growth, driven by the increasing digitalization of industrial operations and rising demand for flexible, scalable, and centrally managed automation architectures. Manufacturers and process industries are increasingly shifting from hardware-dependent control systems to software-defined platforms that decouple automation software from proprietary hardware, enabling control, orchestration, and system updates through virtualized, programmable environments. The ability of software-defined automation to reduce hardware dependency, simplify system upgrades, improve interoperability, accelerate production reconfiguration, and enable real-time operational optimization is encouraging manufacturers to modernize legacy automation infrastructure and adopt more agile, software-centric industrial control environments.
Rising demand for flexible, hardware-independent control architectures is accelerating the adoption of software-defined automation. Traditional automation environments often rely on dedicated controllers that require physical intervention for upgrades or capacity changes. Software-defined approaches decouple control logic from specific hardware, allowing virtual PLCs, applications, and automation functions to be centrally deployed, updated, and scaled. This improves production adaptability while enabling organizations to apply familiar IT-style software management practices to operational technology environments.
Virtualized automation platforms also allow users to consolidate control, visualization, and edge applications on fewer computing systems while managing software across multiple machines or sites. Hardware-independent controllers can be scaled to meet operating requirements, while centralized management simplifies patch management, application deployment, and system maintenance. These capabilities make software-defined automation particularly relevant where rapid production reconfiguration, reduced engineering effort, remote administration, and improved utilization of computing resources are operational priorities.
The adoption of software-defined automation platforms can be constrained by the significant investment required for software licenses, infrastructure upgrades, system integration, and specialized technical expertise. Enterprises often need to assess existing IT environments, redesign workflows, configure automation policies, and establish connections between cloud platforms, on-premises infrastructure, applications, and databases. These activities increase implementation costs and may extend deployment timelines, particularly for organizations with complex or fragmented IT systems.
The shortage of skilled professionals with expertise in cloud architecture, DevOps, infrastructure-as-code, networking, cybersecurity, and automation engineering can further increase deployment costs. Enterprises may require external consultants, system integrators, or managed service providers to design and implement automation environments. Smaller organizations may face greater difficulty allocating resources for these investments, limiting the adoption of comprehensive software-defined automation solutions. Moreover, high upfront costs, integration challenges, and resource requirements can delay purchasing decisions and encourage some enterprises to adopt smaller, application-specific automation tools.
Open, portable automation software creates an important opportunity to reduce dependence on proprietary control hardware and enable reusable applications across different automation environments. Standards-based approaches support distributed control applications that can be separated from underlying hardware and deployed across interoperable platforms. As suppliers expand open automation ecosystems, users can gain greater flexibility when selecting controllers, edge systems, engineering tools, and software components while reducing the engineering effort required for future system changes.
This transition also creates opportunities for software vendors, automation suppliers, and system integrators to develop virtual controllers, orchestration platforms, application marketplaces, lifecycle-management tools, and reusable automation modules. Centralized deployment can support remote updates, fleet-level monitoring, and scalable software distribution across multiple sites. As automation architectures become more software-centric, recurring licensing, subscription models, cybersecurity services, integration support, and application development can become increasingly important components of the software-defined automation value chain.
Market Concentration & Characteristics
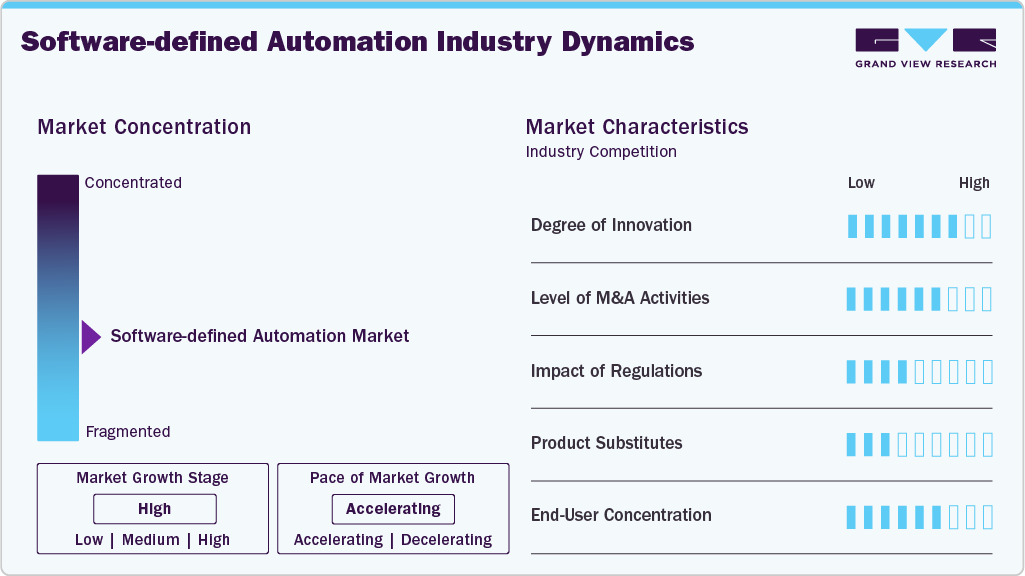
The software-defined automation market is moderately fragmented, comprising global automation vendors, industrial software providers, control-system manufacturers, edge computing companies, virtualization specialists, system integrators, and open automation platform developers competing across programmable control, virtual PLCs, distributed control, industrial edge, orchestration, engineering software, and lifecycle management solutions. The market is shaped by increasing adoption of hardware-independent control, software-defined PLC architectures, open automation standards, industrial virtualization, centralized software management, and IT/OT convergence. Installed automation bases, proprietary engineering ecosystems, long-term customer relationships, cybersecurity capabilities, interoperability expertise, and broad industrial software portfolios enable leading companies to strengthen their positions across complex automation environments.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high level of innovation, supported by advancements in virtual controllers, containerized automation workloads, industrial edge platforms, real-time operating environments, orchestration software, digital twins, AI-enabled control applications, and open interoperability frameworks. Merger and acquisition activity remains moderate, software integration, ecosystem development, joint engineering initiatives, and internal R&D. Competition from conventional hardware-centric PLC and DCS architectures remains significant, although software-defined automation provides greater flexibility, centralized deployment, faster reconfiguration, and reduced dependence on dedicated control hardware. Rising demand for scalable automation, remote lifecycle management, interoperable control systems, faster software deployment, and flexible production architectures continues to intensify competitive development across the market.
Analyst Perspective
The software-defined automation market is advancing through the increasing adoption of hardware-independent control architectures, the expansion of virtualized automation environments, and the rising demand for flexible, software-managed operations. Technology providers are strengthening their portfolios through virtual PLCs, containerized control applications, industrial edge platforms, centralized orchestration tools, open communication frameworks, and remotely deployable automation software. The emergence of cloud-native engineering, open automation ecosystems, and software-based lifecycle management is encouraging enterprises to move beyond fixed hardware-centric systems toward scalable automation infrastructure capable of supporting multiple applications, control functions, and operational requirements across distributed environments.
Component Insights
The solution segment accounted for the largest market share of 69.9% in 2025, propelled by increasing adoption of software-defined controllers, virtual PLCs, industrial edge platforms, and centralized control platforms. Enterprises are increasingly replacing rigid hardware-dependent automation architectures with software-based solutions that enable hardware abstraction, centralized configuration, remote software deployment, and flexible production reconfiguration. Rising adoption of open automation architectures, IT/OT convergence, containerized control applications, real-time edge computing, and interoperable automation platforms is further strengthening demand for software-defined automation solutions.
The services segment is expected to grow at the fastest CAGR of over 15% from 2026 to 2033. The segment is driven by the increasing requirements for system integration, deployment, cybersecurity, maintenance, and lifecycle management services. Transitioning from conventional PLC- and hardware-centric environments to software-defined architectures requires extensive integration across existing control systems and enterprise software. Increasing deployment of virtualized controllers, open automation platforms, and remotely managed automation environments is therefore strengthening demand for specialized implementation, migration, optimization, training, and ongoing technical support services.
Deployment Insights
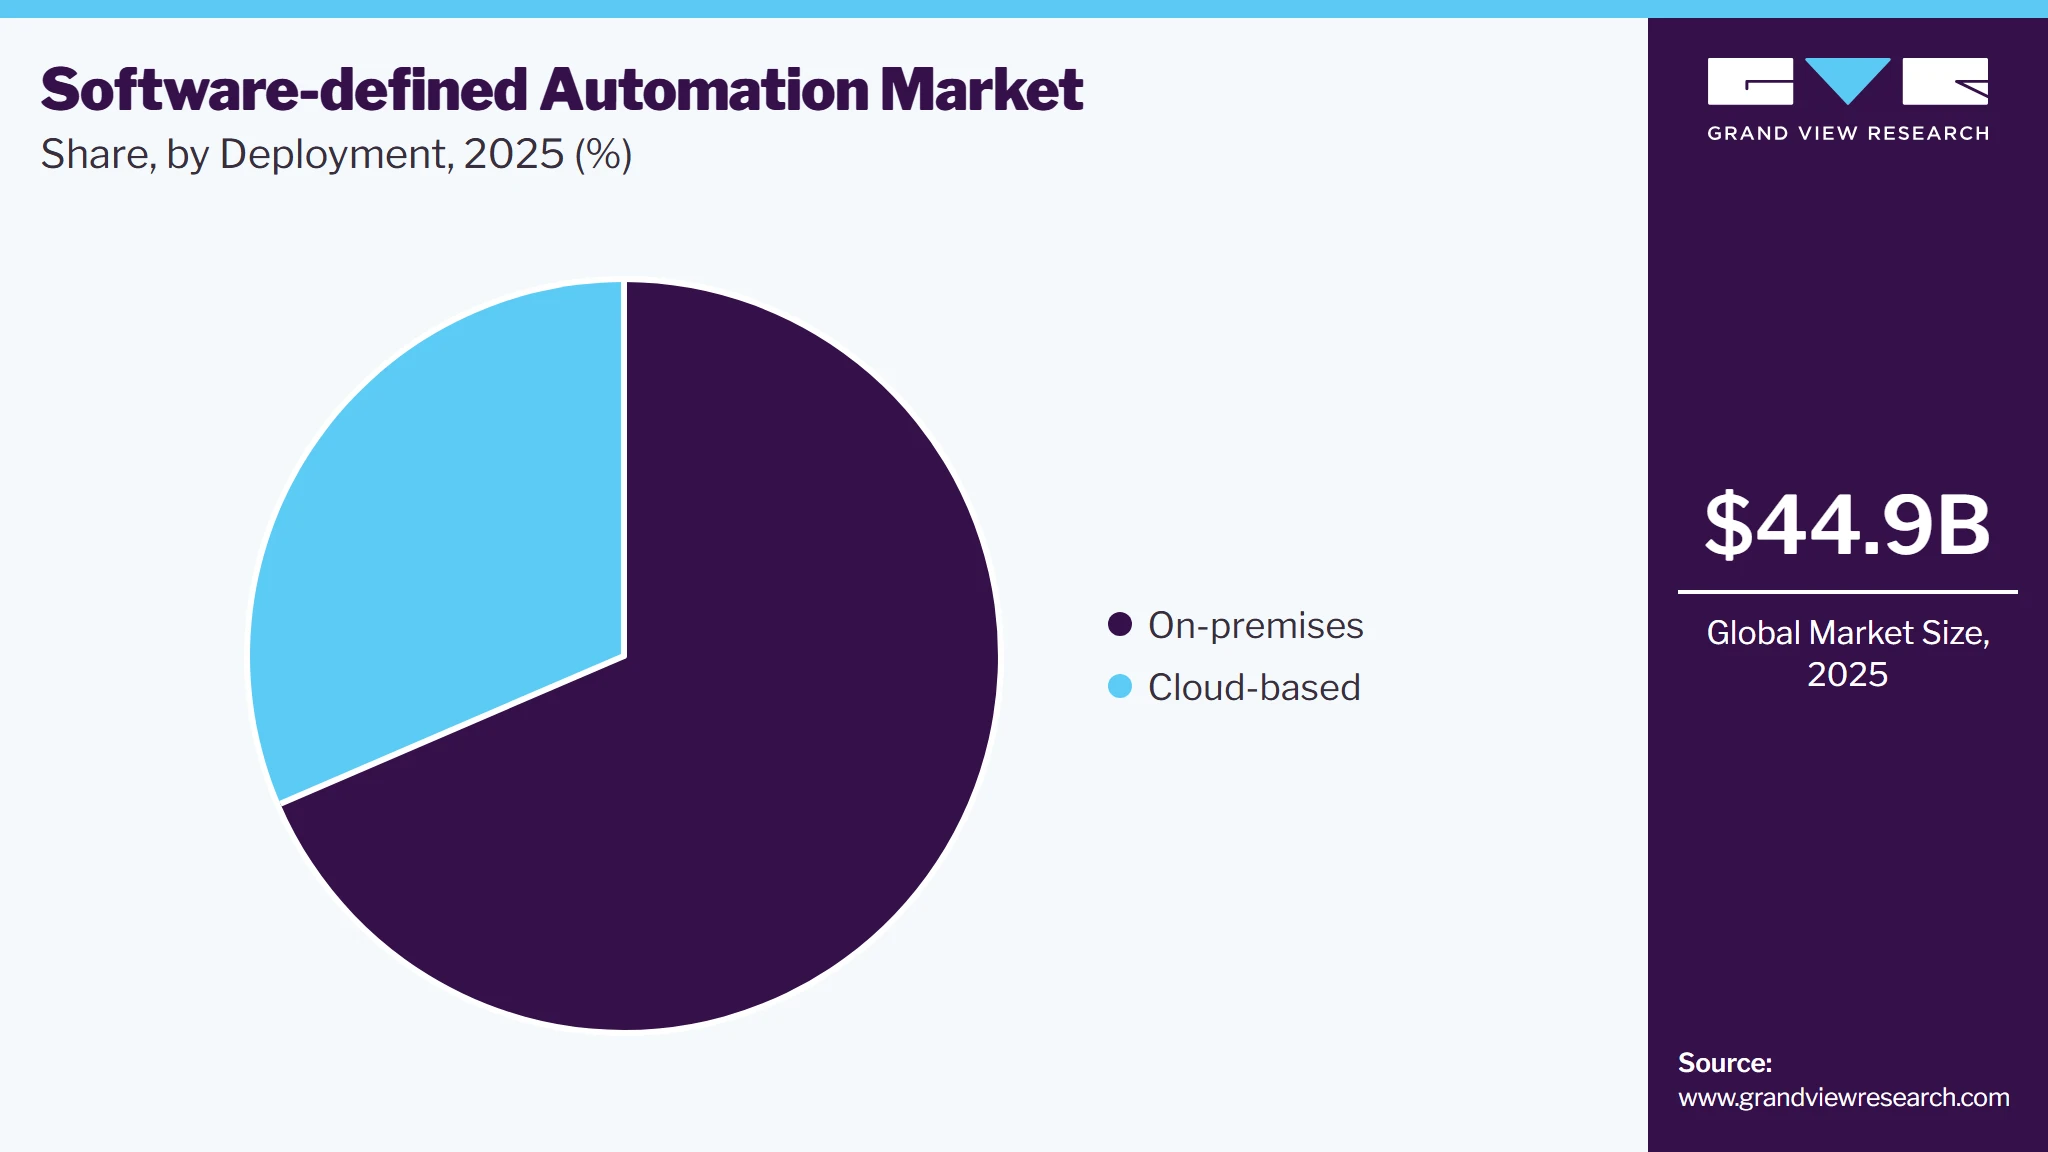
The on-premises segment dominated the software-defined automation industry, accounting for a revenue share of 68.5% in 2025, driven by the need for deterministic control, low-latency processing, data security, and direct integration with existing automation infrastructure. Manufacturers are increasingly deploying software-defined controllers, virtual PLCs, industrial edge platforms, and orchestration software within local facilities to maintain real-time operational control while modernizing legacy systems. Strong requirements for cybersecurity, operational continuity, regulatory compliance, and compatibility with plant-level networks continue to support on-premises deployment across the software-defined automation industry.
 To learn more about this report, Download Free Sample Report
The cloud-based segment is expected to grow at the fastest CAGR from 2026 to 2033, driven by increasing adoption of centralized automation management, remote engineering, software lifecycle management, analytics, and scalable computing resources. Cloud-based platforms enable users to manage distributed automation assets, deploy software updates, monitor system performance, and coordinate applications across multiple locations from centralized environments. Rising adoption of cloud-native engineering tools, containerized applications, subscription-based automation software, and hybrid edge-cloud architectures is expected to accelerate cloud-based deployment across the market.
Application Insights
The process automation segment dominated the software-defined automation market, accounting for a revenue share of 39.1% in 2025, driven by the increasing adoption of software-defined control across continuous and batch operations requiring high availability, real-time process visibility, and flexible control configuration. Virtual PLCs, distributed control software, industrial edge platforms, and centralized orchestration tools enable operators to modify control logic, deploy updates, integrate analytics, and coordinate equipment without extensive hardware changes. Rising demand for operational efficiency, predictive control, remote engineering, and modernization of legacy process environments continues to strengthen adoption across process automation applications.
The security automation segment is expected to grow at the fastest CAGR from 2026 to 2033, fueled by rising cybersecurity requirements in increasingly connected, software-centric automation environments. As virtualized controllers, cloud-connected engineering tools, industrial edge systems, and remote management platforms expand, organizations require automated threat detection, access control, vulnerability management, policy enforcement, and incident response capabilities. Increasing IT/OT convergence, remote software deployment, zero-trust architectures, and stricter protection of critical operational assets are accelerating demand for integrated security automation within software-defined automation platforms.
End Use Insights
The manufacturing segment accounted for the largest market share of 35.2% in 2025, driven by increasing adoption of flexible production systems, virtual PLCs, industrial edge platforms, software-based motion control, and centralized automation orchestration. Manufacturers are shifting toward hardware-independent control architectures to enable faster production-line reconfiguration, reduce dependence on proprietary controllers, and simplify software deployment across multiple facilities. Rising investments in smart factories, modular production, digital twins, and predictive maintenance are further strengthening demand for software-defined automation across manufacturing environments.
The healthcare & life sciences segment is expected to grow at the fastest CAGR from 2026 to 2033, driven by the increasing automation of pharmaceutical production, laboratory workflows, medical device manufacturing, and regulated processing environments. Software-defined automation enables centralized control, standardized software deployment, real-time monitoring, electronic batch management, and flexible reconfiguration of production equipment while supporting traceability requirements. The rising adoption of personalized medicines, continuous manufacturing, automated laboratories, digital validation, and highly configurable production lines is expected to accelerate demand for virtualized and software-managed automation platforms across healthcare and life sciences.
Regional Insights
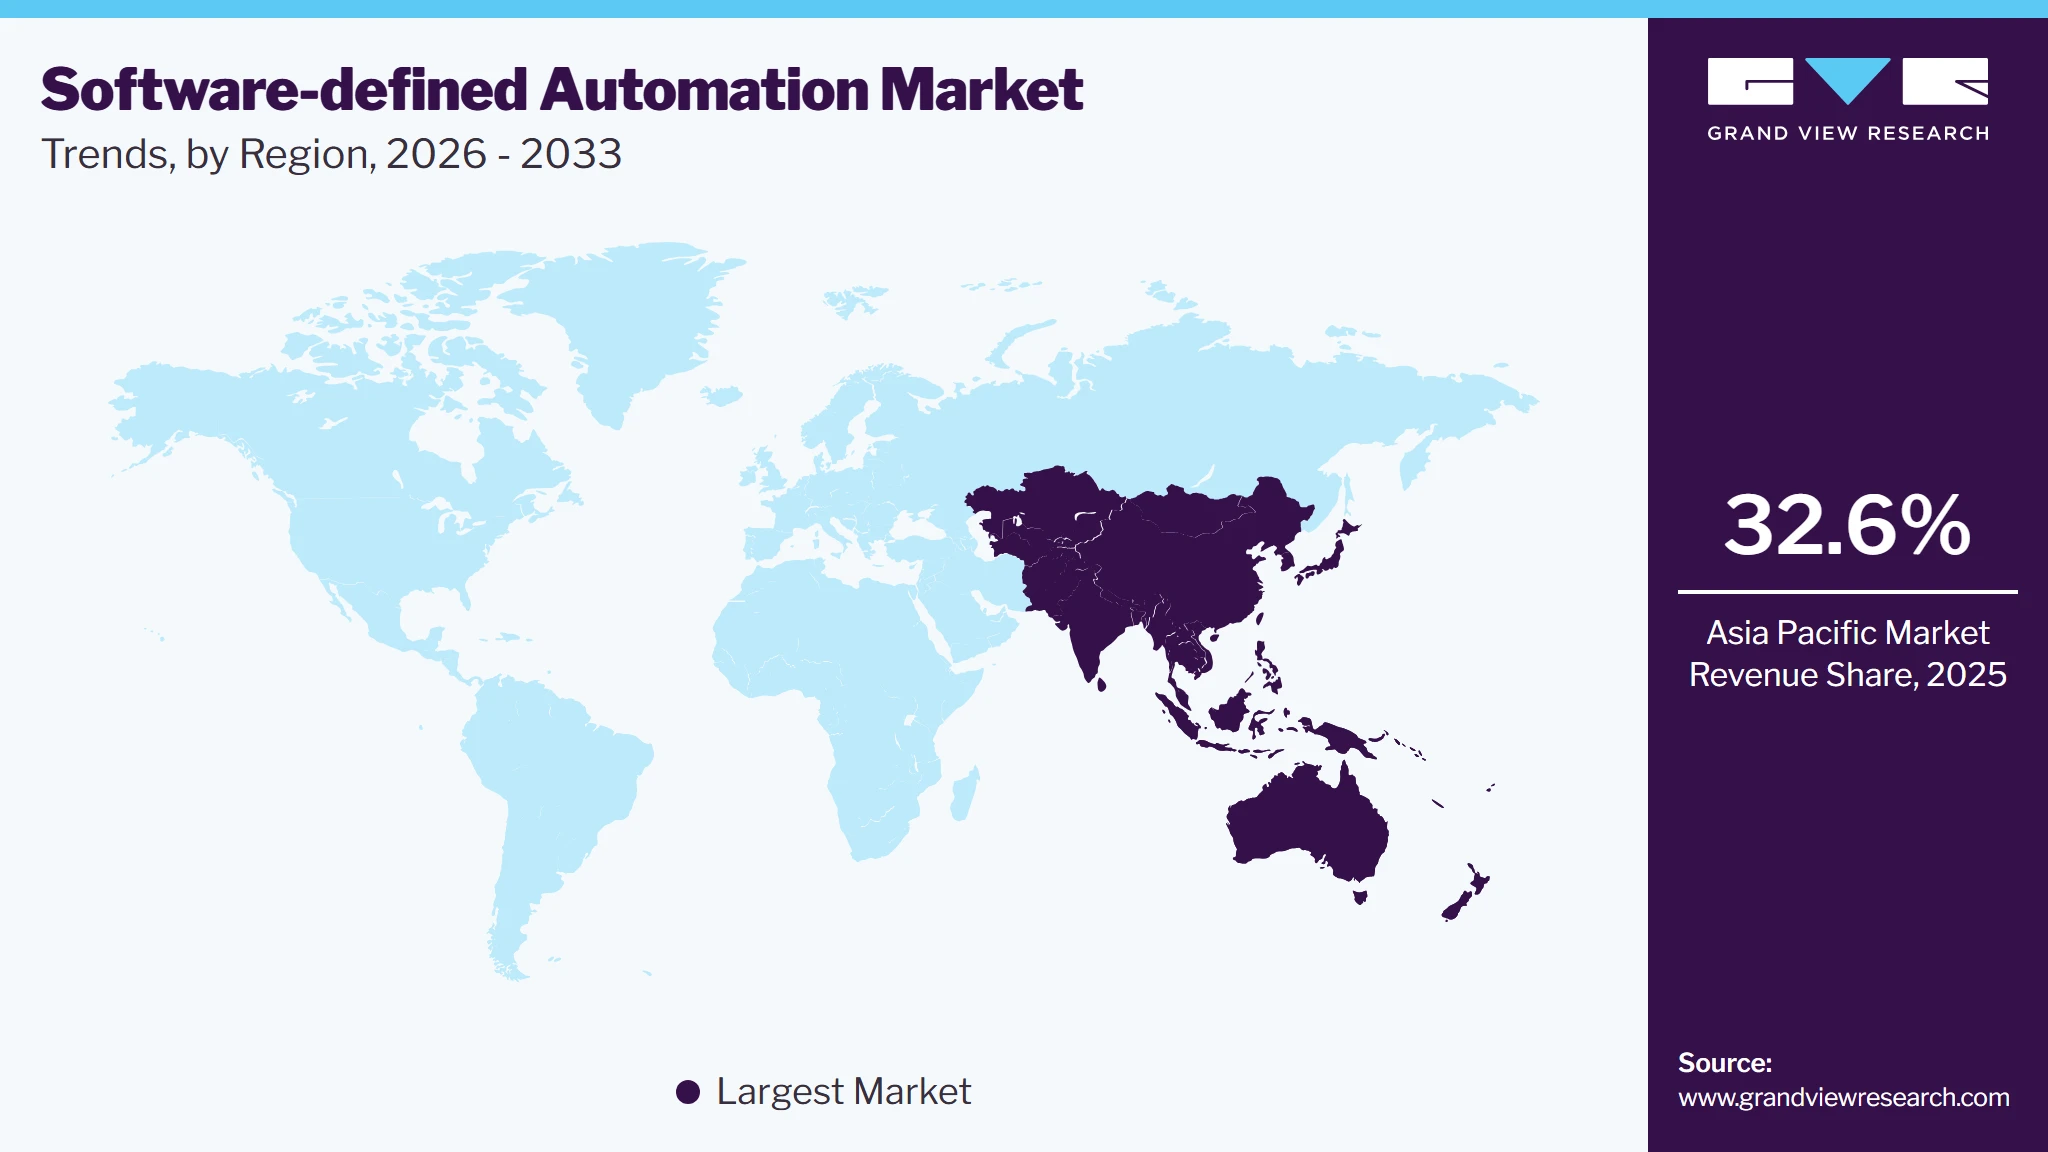
The Asia Pacific software-defined automation market held the largest global revenue share of 32.6% in 2025, and is expected to grow at the fastest CAGR of 15.8% from 2026 to 2033. The market growth is driven by rapid factory digitalization, the expansion of electronics and semiconductor production, rising investment in automation, and the increasing adoption of industrial IoT infrastructure. Enterprises across major regional economies are modernizing production through connected machines, industrial edge computing, AI-based optimization, and centralized software platforms. The need to manage geographically distributed factories, improve production flexibility, reduce engineering complexity, and scale automation applications across multiple facilities is accelerating the adoption of software-defined architectures.
 To learn more about this report, Download Free Sample Report
The Japan software-defined automation market is gaining traction through strong investment in manufacturing digital transformation, factory modernization, AI, and labor-saving technologies. Japan’s 2025 and 2026 manufacturing policy documents emphasize digital technologies and AI as important tools for strengthening industrial competitiveness. Companies are increasingly adopting software-based control, predictive maintenance, digital twins, intelligent robotics, and centralized production management to address workforce constraints, modernize long-life automation assets, and improve operational resilience. These factors are strengthening demand for flexible software-defined automation platforms.
The software-defined automation market in China is expanding through large-scale deployment of industrial internet platforms, smart factories, digitally connected production lines, and domestically developed industrial software. China continues to promote industrial internet infrastructure capable of integrating equipment, production lines, workshops, and factory-level data to optimize manufacturing operations. Increasing adoption of intelligent production, machine connectivity, AI-based process optimization, and centralized factory platforms is supporting the software-defined automation industry that enables flexible application deployment, real-time orchestration, and reduced dependence on dedicated control hardware.
North America Software-defined Automation Market Trends
North America software-defined automation industry held a revenue share of 32.0% in 2025, driven by the region’s large installed base of advanced automation systems, strong industrial software ecosystem, and early adoption of virtualized control architectures. Enterprises are increasingly deploying virtual PLCs, industrial edge platforms, centralized orchestration tools, and software-managed control systems to modernize legacy automation environments. Rising investment in smart factories, reshoring initiatives, IT/OT convergence, cybersecurity modernization, and flexible production architectures is accelerating the adoption of hardware-independent automation across the region.
U.S. Software-defined Automation Market Trends
The U.S. software-defined automation industry dominated, with a share of 82.3% in 2025, driven by extensive investment in industrial digitalization, advanced manufacturing, semiconductor production, data-driven operations, and automation modernization. Organizations are increasingly integrating software-defined controllers, edge computing, digital twins, AI-enabled automation, and cloud-connected engineering platforms to improve production flexibility. Government-supported advanced manufacturing initiatives, the expansion of domestic production capacity, and the demand for centralized software lifecycle management are further encouraging the migration from proprietary hardware-centric control toward programmable, software-managed automation architectures.
Europe Software-defined Automation Market Trends
The Europe software-defined automation industry is expected to grow at a CAGR of 13.4% from 2026 to 2033. The market growth is driven by increasing emphasis on industrial digital sovereignty, interoperable automation, energy-efficient production, and secure edge-to-cloud architectures. European initiatives are supporting distributed computing environments where applications can operate across devices, edge infrastructure, and cloud platforms. Growing adoption of digital twins, AI-driven automation, open communication standards, industrial edge computing, and modular production systems is strengthening demand for flexible software-defined control architectures across the region.
The UK software-defined automation market is expected to grow significantly in the coming years, supported by government-backed industrial digitalization programs and increasing adoption of automation among small and medium-sized manufacturers. The Made Smarter program promotes the adoption of industrial digital technologies through advisory support, transformation roadmaps, skills development, and grant funding. Increasing deployment of robotics, industrial IoT, AI, legacy-system upgrades, and connected production platforms is creating favorable conditions for software-defined automation systems that enable centralized control, remote configuration, and scalable software deployment.
The software-defined automation market in Germany is supported by its strong automation equipment base, highly digitalized manufacturing environment, and emphasis on interoperable Industry 4.0 architectures. German enterprises are increasingly integrating industrial edge computing, digital twins, standardized machine communication, software-based control, and modular production systems to improve flexibility across complex production environments. Growing requirements for energy-efficient manufacturing, shorter production cycles, mass customization, and easier integration of heterogeneous equipment are encouraging migration toward hardware-independent controllers and centrally managed automation software.
Key Companies & Market Share Insights
Some of the key players operating in the market are Siemens AG and Schneider Electric.
-
Siemens AG is a leading participant in software-defined automation through its SIMATIC S7-1500V virtual PLC, WinCC Unified, SIMATIC AX, and Industrial Operations X portfolio. Its S7-1500V provides hardware-independent PLC functionality that can be centrally deployed and managed through Industrial Edge, enabling automation workloads to be virtualized and scaled using software. Siemens is integrating IT-style application management, industrial AI, remote software deployment, and centralized device orchestration into production environments, strengthening its position in software-defined control architectures.
-
Schneider Electric has established a strong position in software-defined automation through EcoStruxure Automation Expert, its hardware-agnostic and application-centric automation platform. The platform supports distributed intelligence across physical and virtual controllers while promoting portability of automation applications through open architectures and IEC 61499-based universal automation principles. Schneider Electric is further expanding its strategy around containerized control, hardware independence, reusable software components, and integration with third-party ecosystems, positioning EcoStruxure Automation Expert as a core platform for open software-defined industrial automation.
Bosch Rexroth Corporation and Beckhoff Automation GmbH & Co. KG are some of the emerging participants in the software-defined automation market.
-
Bosch Rexroth Corporation is expanding its presence in software-defined automation through the ctrlX AUTOMATION platform, which combines control, motion, IoT, engineering, and software functions within an open, app-based architecture. Its Linux-based ctrlX OS decouples automation functions from rigid hardware dependencies and allows users to add Bosch Rexroth, customer-developed, or third-party applications through a common software environment. The ctrlX World ecosystem now includes more than 100 partners, supporting broader development of modular and interoperable automation applications.
-
Beckhoff Automation GmbH & Co. KG is strengthening its relevance in the software-defined automation industry through its TwinCAT software platform and PC-based control architecture. TwinCAT converts PC-based systems into real-time controllers capable of running PLC, motion, CNC, robotics, and other automation workloads within a common software environment. Its modular architecture, support for third-party components, Linux-based real-time control capabilities, and ability to consolidate multiple control functions on standard computing infrastructure align closely with the transition toward flexible, software-centric automation systems.
Key Software-defined Automation Companies
The following key companies have been profiled for this study of the software-defined automation market.
-
ABB
-
Schneider Electric
-
Honeywell International Inc.
-
Microsoft
-
Siemens AG
-
Mitsubishi Electric Corporation
-
Hewlett Packard Enterprise (HPE)
-
Yokogawa Electric Corporation
-
Beckhoff Automation GmbH & Co. KG
-
Bosch Rexroth Corporation
-
Emerson Electric Co.
-
Rockwell Automation, Inc.
-
Cisco Systems, Inc.
-
Juniper Networks
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ABB, Schneider Electric, Siemens AG)
- Expand software-defined automation portfolios through virtual PLCs, edge platforms, and open ecosystems.
- Invest in R&D, cloud integration, cybersecurity, and interoperable industrial software architectures.
- Strong installed bases, global service networks, and broad industrial automation portfolios support leadership.
- Ability to integrate control, edge, cloud, and lifecycle software across complex environments.
- Large legacy hardware portfolios can slow the transition toward fully software-centric automation models.
- Complex product ecosystems may increase integration requirements compared with smaller specialized software vendors.
Emerging Players (Beckhoff Automation GmbH & Co. KG, Bosch Rexroth Corporation, Juniper Networks)
- Emerging players are focusing on open, modular automation platforms with app-based software and hardware-independent control.
- Expand through ecosystem partnerships, developer tools, and flexible edge-to-cloud integration capabilities.
- Agile product development enables faster adoption of virtualized control and open automation architectures.
- Specialized software-centric platforms provide flexibility, interoperability, and simpler customization for modern deployments.
- Smaller installed bases can limit customer reach compared with established automation vendors.
- Limited global service infrastructure may constrain large-scale deployment across multinational operating environments.
Recent Developments
-
In July 2026, Rockwell Automation and Cisco announced a strategic collaboration in India to advance software-defined manufacturing by combining industrial automation with IT technologies. The partnership introduced a Full-Stack Software-Defined Manufacturing reference design and a demonstration pod, supporting the transition from traditional automation toward AI-enabled autonomous operations.
-
In June 2026, Siemens expanded access to Software-Defined Automation by enhancing Simatic AX, adding ladder programming and support for the Simatic S7-1200 G2 controller. The updates combine OT-friendly programming with IT-style engineering workflows, improving collaboration and efficiency across industrial engineering teams.
-
In February 2026, ABB introduced its Automation Extended program to modernize distributed control systems through an open, modular architecture while preserving customers’ existing automation investments. The program enables integration of advanced analytics, AI, and IoT capabilities without disrupting mission-critical control operations, supporting a gradual transition toward software-defined automation.
Software-defined Automation Market Report Scope
Report Attribute
Details
Market size in 2025
USD 44.9 billion
Estimated market size in 2026
USD 52.0 billion
Projected market size by 2033
USD 131.4 billion
Growth rate
CAGR of 14.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, deployment, application, end use, and region
Region scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; Japan; India; South Korea; Australia; Taiwan; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
ABB; Schneider Electric; Honeywell International Inc.; Microsoft; Siemens AG; Mitsubishi Electric Corporation; Hewlett Packard Enterprise (HPE); Yokogawa Electric Corporation; Beckhoff Automation GmbH & Co. KG; Bosch Rexroth Corporation; Emerson Electric Co.; Rockwell Automation, Inc.; Cisco Systems, Inc.; Juniper Networks
Customization scope
Free report customization (equivalent to up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Software-defined Automation Market Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest technological trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the software-defined automation market report based on component, deployment, application, end use, and region:
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Solution
-
Services
-
-
Deployment Outlook (Revenue, USD Billion, 2021- 2033)
-
On-premises
-
Cloud-based
-
-
Application Outlook (Revenue, USD Billion, 2021- 2033)
-
Process Automation
-
Network Automation
-
Security Automation
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021- 2033)
-
Information Technology & Telecom
-
Banking, Financial Services, & Insurance (BFSI)
-
Retail & eCommerce
-
Healthcare & Life Sciences
-
Manufacturing
-
Automotive
-
Transportation & Logistics
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Taiwan
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The software-defined automation market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each software-defined automation segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Solution
Revenue is generated from software-defined automation platforms, virtual controllers, orchestration software, industrial edge platforms, engineering tools, automation management systems, and related software used to configure, deploy, monitor, and manage control functions independently from dedicated hardware environments.
Services
Revenue is generated from consulting, system integration, implementation, migration, maintenance, cybersecurity, training, and lifecycle support services required to deploy and operate software-defined automation environments across existing control systems, industrial networks, edge infrastructure, cloud platforms, and enterprise applications.
Segment - Deployment
Revenue capture definition
On-premises
Revenue is generated from software-defined automation solutions deployed within local facilities, plants, data centers, or operational environments where control applications, virtual PLCs, orchestration software, and edge platforms are hosted on customer-owned infrastructure for low-latency operation, security, reliability, and direct equipment integration.
Cloud-based
Revenue is generated from software-defined automation platforms delivered through public, private, or hybrid cloud environments. These platforms support centralized configuration, remote engineering, software deployment, lifecycle management, analytics, monitoring, and orchestration of distributed automation assets across multiple sites and operational locations.
Segment - Application
Revenue capture definition
Process Automation
Revenue is generated from software-defined automation solutions used to monitor, control, optimize, and coordinate continuous or batch processes through virtual controllers, distributed software applications, industrial edge systems, real-time analytics, and centralized orchestration across interconnected production and processing environments.
Network Automation
Revenue is generated from software platforms that automatically configure, manage, monitor, and optimize industrial and enterprise networks supporting connected automation assets. These solutions enable centralized network orchestration, policy management, traffic optimization, device provisioning, and software-controlled connectivity across distributed operational environments.
Security Automation
Revenue is generated from software-defined tools used to automate cybersecurity monitoring, access control, vulnerability management, policy enforcement, threat detection, and incident response across connected automation infrastructure. These platforms protect virtual controllers, industrial edge systems, networks, cloud services, and remotely managed operational assets.
Others
Revenue is generated from additional software-defined automation applications, including building automation, energy management, infrastructure control, laboratory automation, asset management, remote operations, digital workflow orchestration, and other specialized use cases not classified under process, network, or security automation.
Segment - End Use
Revenue capture definition
Information Technology & Telecom
Revenue is generated from software-defined automation solutions used to automate data centers, network operations, telecom infrastructure, edge environments, and distributed computing resources. These platforms support software-based orchestration, automated provisioning, infrastructure management, monitoring, and scalable control of complex digital environments.
Banking, Financial
Services, & Insurance (BFSI)
Revenue is generated from automation platforms used to manage IT infrastructure, network operations, security workflows, data center environments, and business-critical digital systems. Software-defined automation supports centralized orchestration, automated configuration, compliance management, system monitoring, and resilient operation across a distributed financial infrastructure.
Retail & eCommerce
Revenue is generated from software-defined automation solutions supporting fulfillment centers, distribution networks, store infrastructure, digital commerce platforms, inventory systems, and connected operational technologies. These solutions enable centralized control, automated workflows, flexible system configuration, and scalable management across geographically distributed retail environments.
Healthcare & Life Sciences
Revenue is generated from software-defined automation deployed across pharmaceutical production, laboratories, healthcare IT environments, medical-device manufacturing, and regulated processing systems. These platforms support configurable control, centralized monitoring, automated workflows, traceability, remote management, and integration of software-based automation across complex regulated operations.
Manufacturing
Revenue is generated from software-defined automation solutions used across production lines, machines, industrial edge systems, robotics, motion control, and factory networks. These platforms enable hardware-independent control, virtual PLC deployment, centralized orchestration, flexible production reconfiguration, and software lifecycle management across manufacturing environments.
Automotive
Revenue is generated from software-defined automation deployed across vehicle production, assembly, painting, welding, testing, battery manufacturing, and component operations. These solutions support flexible production cells, virtual control, robotics integration, rapid software updates, centralized engineering, and reconfiguration of automation systems for changing vehicle platforms.
Transportation & Logistics
Revenue is generated from software-defined automation solutions used across warehouses, ports, airports, rail networks, fleet operations, and distribution centers. These platforms automate material handling, routing, asset monitoring, infrastructure control, network management, and operational workflows through centralized software orchestration and connected edge systems.
Others
Revenue is generated from software-defined automation applications across energy, utilities, buildings, public infrastructure, mining, education, government, and other sectors. These deployments use virtualized control, edge computing, centralized orchestration, automated workflows, and software-managed infrastructure to improve flexibility, visibility, and operational coordination.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Automation Demand Layer
Who are the potential end users?
Identifies manufacturers, telecom operators, financial institutions, healthcare organizations, logistics providers, retailers, automotive companies, utilities, and other enterprises requiring software-defined automation for flexible control, infrastructure management, cybersecurity automation, and operational optimization.
02
Software-Defined Automation Development Layer
Who can provide software-defined automation solutions?
Software-defined automation development involves industrial automation vendors, industrial software providers, cloud companies, edge computing vendors, networking companies, control-system manufacturers, cybersecurity providers, open automation frameworks, and software-based control systems.
03
Deployment Infrastructure Layer
Where are software-defined automation solutions deployed?
Software-defined automation solutions are deployed across factories, production facilities, data centers, telecom networks, warehouses, healthcare facilities, enterprise IT environments, edge infrastructure, and cloud platforms requiring centralized control, remote configuration, software lifecycle management, real-time processing, and flexible automation deployment.
04
Revenue Generation Layer
How is revenue generated?
Revenue is generated through software licenses, automation platform subscriptions, virtual controller solutions, orchestration software, industrial edge platforms, cloud-based automation services, system integration, consulting, cybersecurity services, maintenance, training, managed services, and long-term support contracts for on-premises and cloud-based software-defined automation deployments.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Software-Defined Control Architecture Assessment
Evaluated virtual PLCs, hardware-independent controllers, industrial edge platforms, orchestration software, and open automation frameworks to assess deployment flexibility, interoperability, scalability, and modernization requirements.
Improves architecture flexibility, reduces hardware dependency, supports modernization, and simplifies automation lifecycle management.
Legacy Automation Modernization & Migration Strategy
Assessed migration pathways from conventional PLC and hardware-centric environments toward virtualized control, containerized applications, centralized software management, and interoperable software-defined automation architectures.
Reduces migration complexity, improves system interoperability, minimizes disruption, and supports phased automation modernization.
Industrial Edge, Cloud & Orchestration Integration Strategy
Evaluated integration of industrial edge computing, cloud platforms, centralized orchestration, remote software deployment, cybersecurity, and lifecycle management across distributed software-defined automation environments.
Enables centralized management, improves scalability, strengthens cybersecurity, and supports flexible multi-site automation deployment.
Frequently Asked Questions About This Report
The Asia Pacific is the fastest-growing region with a CAGR of over 15% from 2026 to 2033.
The solution segment dominated with a 69.9% revenue share in 2025.
The on-premises segment dominated the market with a share of 66.8% in 2025.
The manufacturing segment accounted for the largest share, with 68.5% of revenue in 2025.
Some key players operating in the software-defined automation market include Siemens AG, Mitsubishi Electric India Pvt.Ltd, Hewlett Packard Enterprise (HPE), Yokagawa India Ltd., Beckhoff Automation GmbH & Co. KG, Bosch Rexroth Corporation, Emerson Electric Co., Rockwell Automation, Inc., Cisco Systems, Inc., Juniper Networks
Key factors that are driving the software-defined automation market growth include the demand for software-defined automation (SDA) solutions, rapid evolution of cloud computing technologies, and growing emphasis on integrating automation technologies.
The global software-defined automation market size was valued at USD 48.1 billion in 2026 and is estimated at USD 51.9 billion for 2026.
The global software-defined automation market is expected to grow at a CAGR of 14.2% from 2026 to 2033, reaching USD 93.6 billion by 2033.
Asia Pacific dominated with a 37.5% revenue share in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


