
- Home
- »
- Advanced Interior Materials
- »
-
Solar Cable Market Size, Share & Growth Report, 2026-2033GVR Report cover

Solar Cable Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Copper, Aluminum), By Type (AC Cables, DC Cables), By End-use (Utility, Residential, Commercial), By Region (North America, Europe, Asia Pacific, CSA, Middle East), And Segment Forecasts
Market Size, 2025
$1.2BMarket Estimate, 2026
$1.4BMarket Forecast, 2033
$3.0BCAGR, 2026–2033
11.5%Solar Cable Market Summary
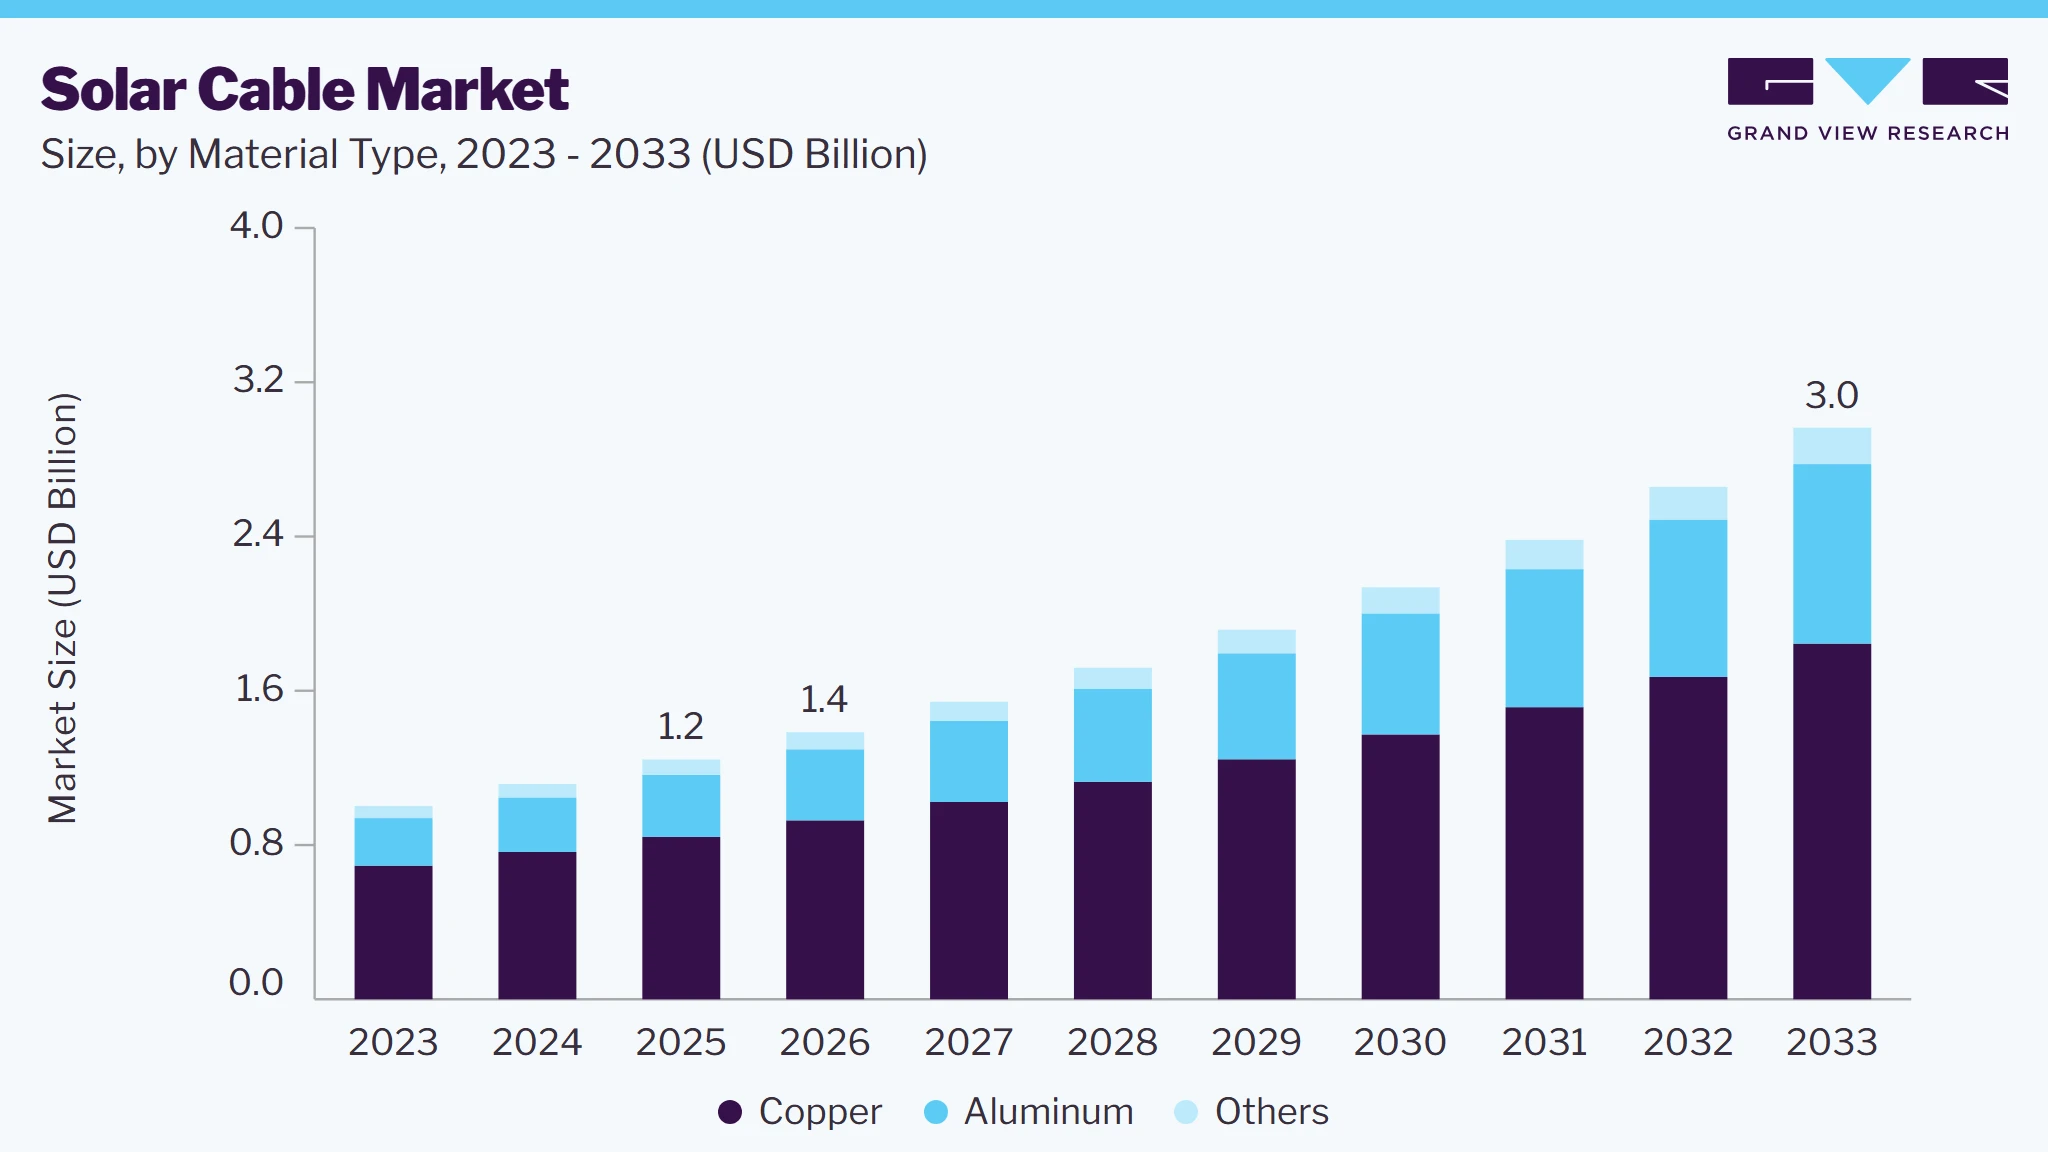
The global solar cable market size was valued at USD 1.2 billion in 2025 and is projected to grow from USD 1.4 billion in 2026 to USD 3.0 billion by 2033, at a CAGR of 11.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 39.3% in 2025. As governments and businesses aim to meet sustainability targets and reduce carbon footprints, solar power has emerged as a leading alternative energy source.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material type: Copper segment led the market with the largest revenue share of 67.7% in 2025.
- By type: DC cables segment led the market with the largest revenue share of 62.3% in 2025.
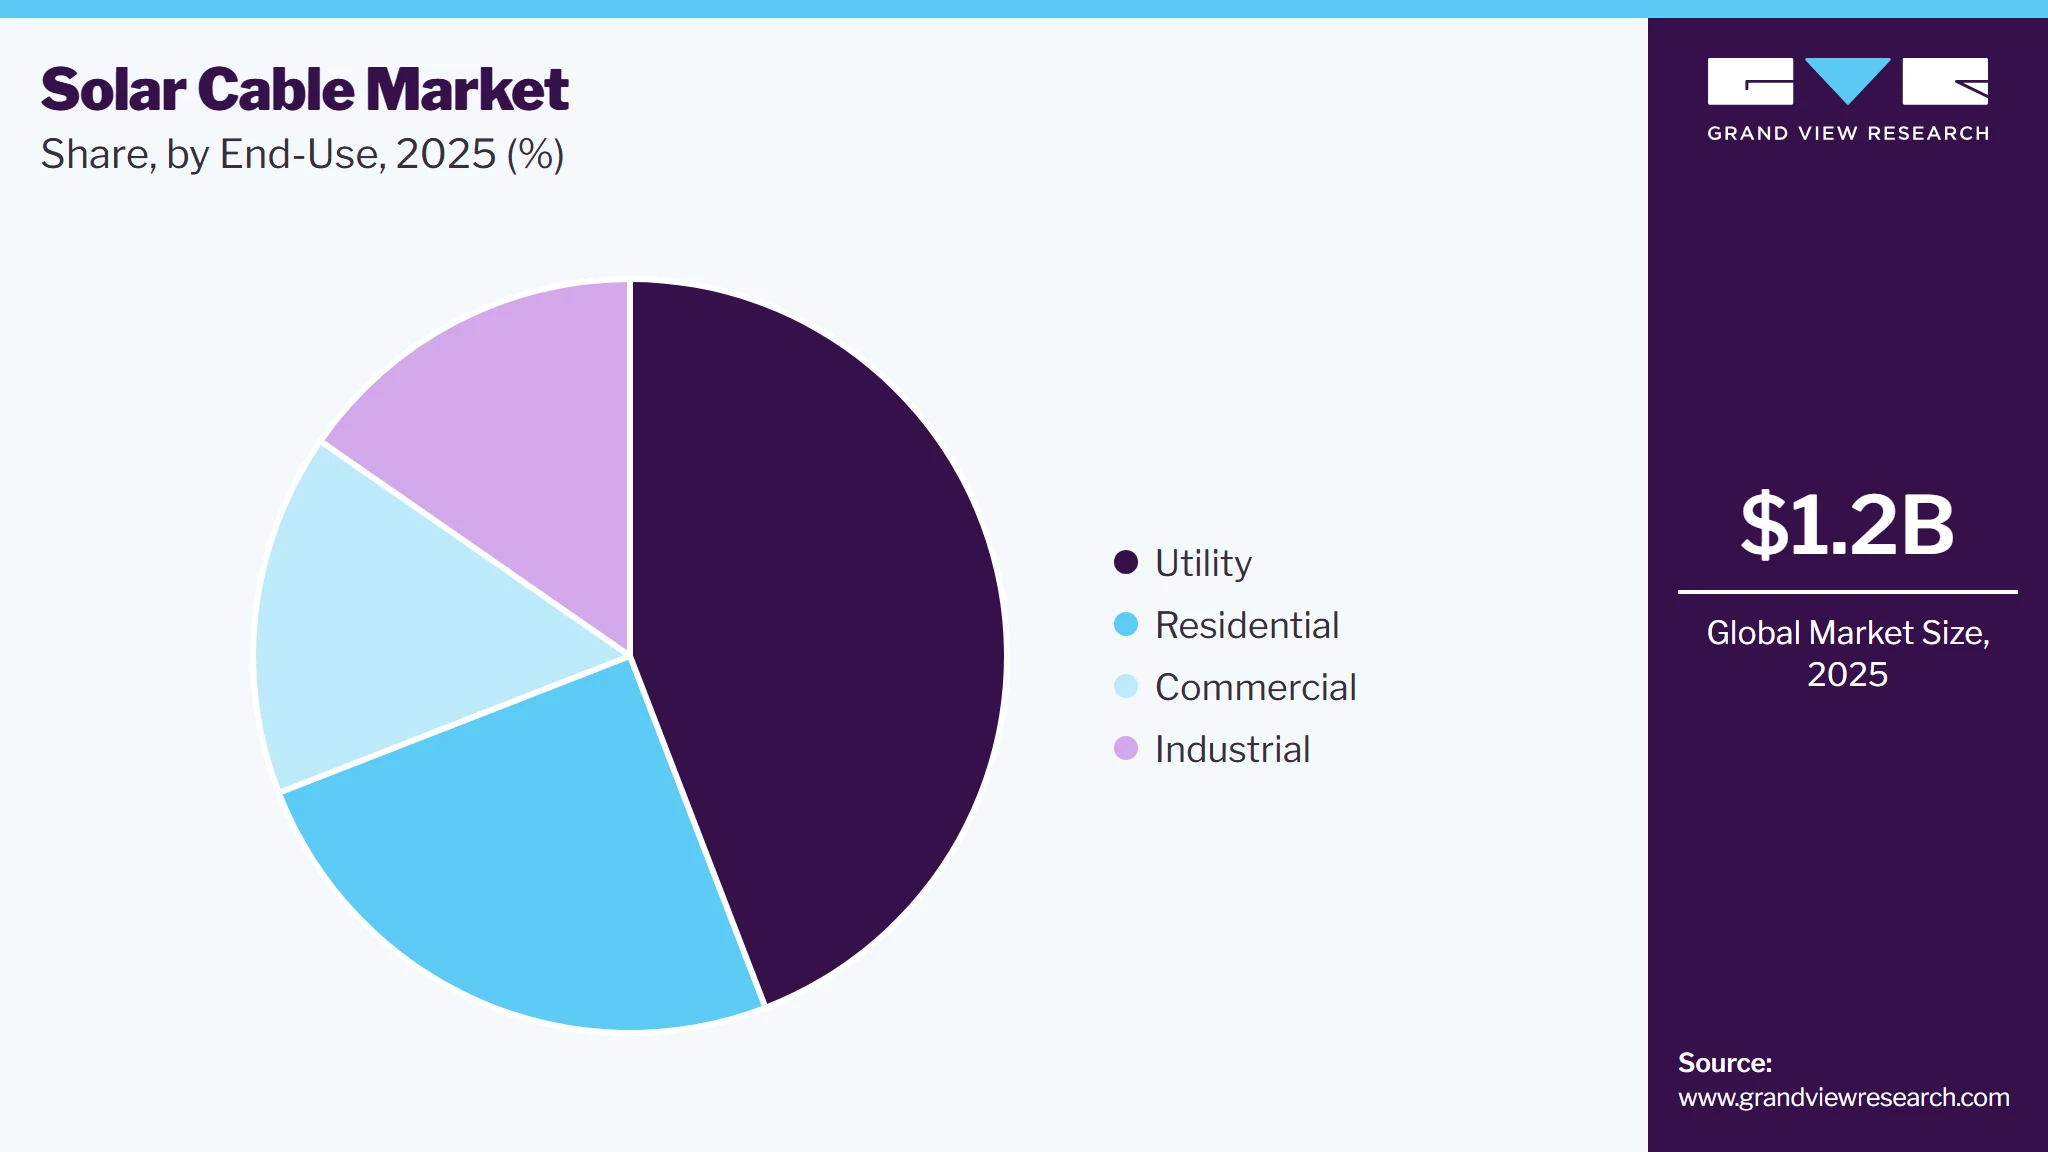
- By end use: Utility segment accounted for the largest share of 44.1% in 2025.
Regional Highlights
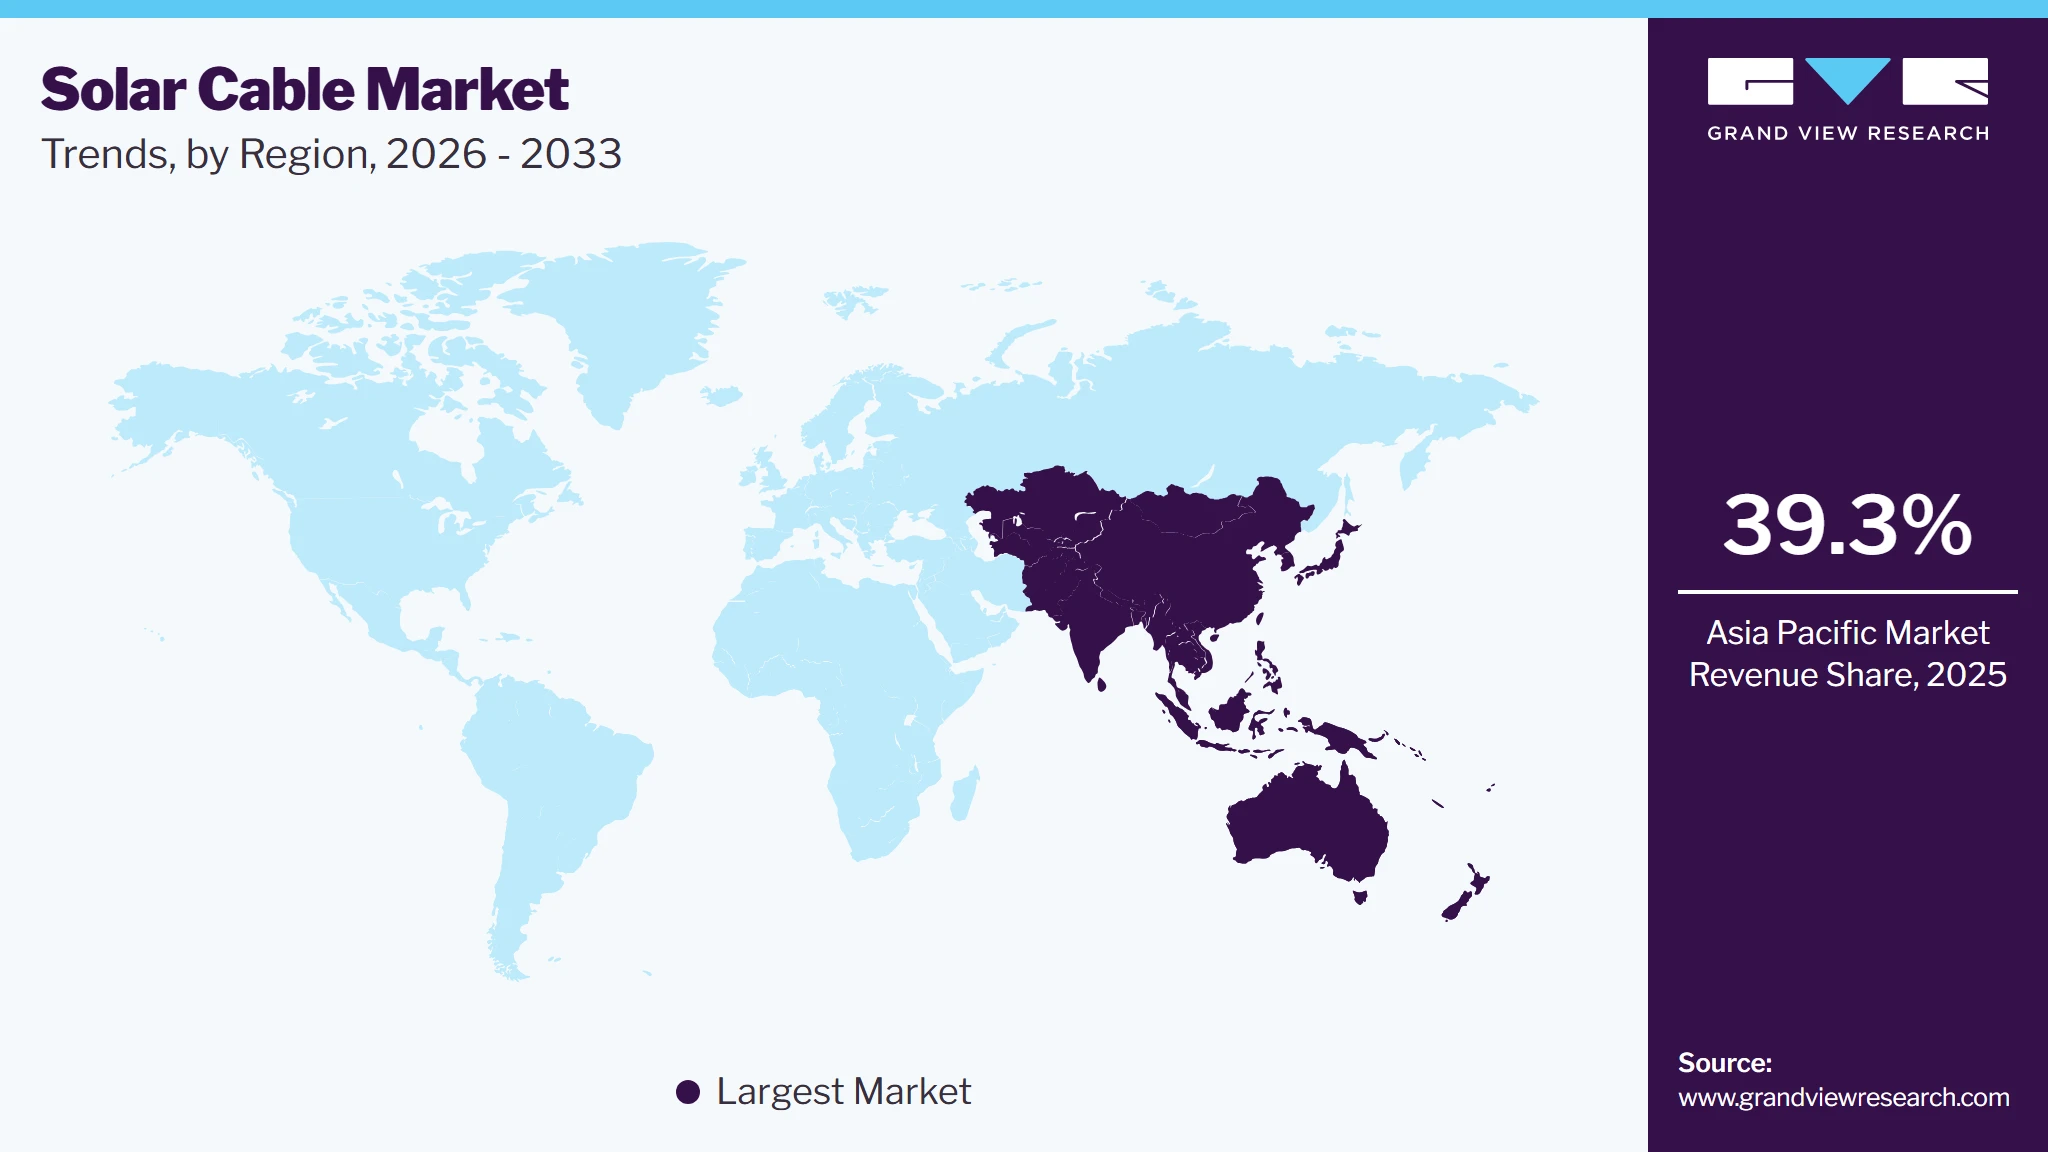
- Largest regional market: Asia Pacific (39.3% revenue share, 2025)
- By country: China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market Size in 2025: USD 1.1 Billion
- Estimated Market Size in 2026: USD 1.4 Billion
- Projected Market Size by 2033: USD 3.0 Billion
- CAGR (2026-2033): 11.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This growing emphasis on clean energy has translated into higher investments in solar installations, thereby driving demand for high-quality solar cables for safe and efficient electricity transmission in photovoltaic (PV) systems. The continuous decline in solar PV system costs has made solar power more affordable and accessible to residential, commercial, and industrial sectors.As solar energy becomes increasingly economical, more consumers and businesses are adopting solar solutions, leading to a surge in demand for solar cables. This price reduction in solar technology has spurred the expansion of the global solar market, further accelerating the need for reliable and durable cable solutions for solar energy systems.
 To learn more about this report, Download Free Sample Report
Technological advancements in solar energy systems have also played a significant role in the growth of the solar cable industry. Developing more efficient solar panels, energy storage systems, and other related technologies has resulted in higher energy generation capacity from solar installations. As a result, the demand for cables that can handle higher electrical loads and operate under varying environmental conditions has increased. Solar cables are designed to withstand harsh weather conditions, including extreme temperatures and UV radiation, making them vital for maintaining the performance and longevity of solar power systems. This need for high-performance cables has driven manufacturers to innovate and produce more robust and efficient solar cables.
Government policies and incentives have been pivotal in promoting the use of solar energy, which directly benefits the solar cables market. Various countries have introduced subsidies, tax incentives, and renewable energy mandates that encourage installing solar power systems. These policies have boosted the demand for solar cables by providing financial incentives to residential and commercial consumers. In regions such as Europe, North America, and parts of Asia-Pacific, governments have implemented ambitious renewable energy targets, further catalysing the growth of the solar power industry and the cables that connect these systems to the grid.
Market Dynamics
Growing investments in solar power projects and the global transition toward renewable energy are driving demand for high-performance solar cables across utility-scale, commercial, and residential installations. Increasing emphasis on efficient power transmission, long-term durability, and compliance with stringent safety standards is encouraging manufacturers to develop advanced cable solutions with improved weather and UV resistance. However, fluctuations in copper and polymer prices and pricing pressure from low-cost suppliers continue to pose challenges. Expanding solar capacity additions and supportive clean energy policies are expected to create strong growth opportunities for the market.
The increasing development of utility-scale solar projects is a major factor driving demand for solar cables. Large solar farms require extensive networks of DC and AC cables to connect solar modules, inverters, transformers, and grid interconnection points, making cables a critical component of the overall project infrastructure. As countries continue to expand renewable energy capacity to meet rising electricity demand and decarbonization targets, investments in large-scale solar installations are increasing, directly supporting the growth of the solar cable market.
According to the International Energy Agency, global solar PV capacity additions increased by around 12% in 2025, surpassing 600 GW for the first time and bringing cumulative installed solar PV capacity to approximately 2,800 GW worldwide. The continued expansion of large-scale solar projects across more than 30 countries has significantly increased the demand for reliable solar cable infrastructure used to connect panels, inverters, and grid systems.
Fluctuations in the prices of copper and specialty polymers are a key restraint for the solar cable market, as these materials account for a significant share of manufacturing costs. Rising raw material prices increase production expenses, squeeze profit margins, and make project budgeting more difficult for manufacturers and solar developers. IEA reported that copper prices reached record levels in early 2026, exceeding USD 14,500 per tonne after first crossing USD 12,000 per tonne in December 2025. The surge, driven by supply disruptions and strong demand from electrification and AI, significantly increased raw material costs for solar cable manufacturers.
The growing adoption of floating solar farms is creating new opportunities for the solar cable market. Unlike conventional ground-mounted systems, floating installations require specialized solar cables with superior water resistance, UV protection, and long-term durability to operate reliably in humid and aquatic environments. As countries seek to maximize renewable energy generation while reducing land use, investments in floating solar projects are expected to drive demand for these high-performance cable solutions. Several countries, including China, India, Japan, and the Netherlands, are expanding floating solar installations on reservoirs, lakes, and other water bodies to increase clean energy capacity without occupying valuable land.
Analyst Perspective
The solar cable market is evolving alongside the rapid expansion of global solar power capacity, with demand extending beyond higher installation volumes to better-performing cable solutions. As utility-scale projects increasingly adopt 1500V DC systems and floating solar installations gain traction, manufacturers are focusing on cables that offer higher voltage ratings, improved weather resistance, and longer service life. Sustainability is becoming a differentiating factor, with growing interest in recyclable insulation materials and low-carbon manufacturing processes. Companies that balance product innovation, cost efficiency, and compliance with global quality standards are expected to strengthen their position as solar infrastructure continues to expand worldwide.
Material Insights
Based on material, the copper segment led the market with the largest revenue share of 67.7% in 2025. Copper is preferred for electrical wiring in solar power applications due to its excellent electrical conductivity and durability. As the demand for solar installations continues to rise, particularly in residential, commercial, and industrial sectors, copper's superior performance in transmitting electricity with minimal energy loss makes it an ideal choice. Additionally, copper cables offer exceptional resistance to environmental factors like corrosion, ensuring the long-term reliability of solar systems.
Aluminum is anticipated to register the fastest CAGR over the forecast period. Aluminum offers a more affordable alternative to copper, commonly used in electrical cables. This makes aluminum cables an attractive choice for solar power systems, especially for large-scale solar installations, where cost savings on materials are crucial for maximizing overall project profitability. Additionally, aluminum’s light weight makes it easier to handle and install, reducing labour costs and time during the setup of solar energy systems, further enhancing its appeal for residential and commercial projects.
Type Insights
Based on type, the DC cables segment led the market with the largest revenue share of 62.3% in 2025. As solar energy continues gaining traction as a clean and renewable energy source, the demand for efficient direct current (DC) electricity transmission has surged. Solar panels generate DC power and require specialized cables to safely and effectively transmit energy to inverters and battery storage systems.
AC cables is anticipated to register the fastest CAGR over the forecast period. Alternating Current (AC) cables are essential for connecting solar inverters to the grid, ensuring the efficient transmission of electricity generated by PV systems. The growing trend of large-scale solar power plants and commercial rooftop solar installations has directly contributed to the rising demand for high-quality AC cables, which are necessary for transferring AC power to the grid.
End Use Insights
Based on end use, the utility segment led the market with the largest revenue share of 44.1% in 2025. As the world shifts away from fossil fuels, utility-scale solar power installations are becoming essential to the energy grid. These solar farms require specialized cables capable of withstanding extreme weather conditions, high voltages, and continuous exposure to solar radiation. The need for robust and durable solar cables in these large-scale projects’ fuels market growth.
 To learn more about this report, Download Free Sample Report
Residential segment is anticipated to register the fastest CAGR over the forecast period. The solar energy adoption by homeowners seeking to reduce their electricity bills and contribute to environmental sustainability proliferates the market. With the cost of solar panels and related equipment continuing to decline, an increasing number of households are investing in solar power systems, necessitating using solar cables to ensure efficient and safe electricity transmission.
Regional Insights
The North America solar cable market is anticipated to grow significantly over the forecast period. The U.S. and Canada have made significant strides in increasing renewable energy adoption, with solar power playing a key role in these efforts. Government incentives such as the Investment Tax Credit (ITC) in the U.S. and various provincial rebates and tax credits in Canada have lowered the financial barrier to entry for solar installations. As more residential, commercial, and industrial solar projects are initiated, the demand for solar cables to support these systems has steadily risen.
Asia Pacific Solar Cable Market Trends
Asia Pacific dominated the solar cable market with the largest revenue share of 39.3% in 2025. As countries such as China, India, Japan, and Australia continue to invest heavily in renewable energy infrastructure, the demand for solar cables is steadily rising. For instance, in January 2025, India issued a significant total of 4,419 megawatts (MW) in renewable energy tenders, marking a crucial step towards achieving its ambitious target of 500 GW renewable energy capacity by 2030. These initiatives have created a surge in the installation of solar panels, and as a result, the need for durable, high-performance solar cables to ensure the efficient transmission of energy has significantly increased.
 To learn more about this report, Download Free Sample Report
The solar cable market in China held the largest share in the Asia Pacific region in 2025.
Europe Solar Cable Market Trends
European countries have set ambitious renewable energy targets, with the European Union (EU) aiming to achieve carbon neutrality by 2050. Solar power is at the forefront of this transition, with large-scale solar farms and residential solar installations rapidly increasing. Government policies such as feed-in tariffs, grants, and tax incentives encourage solar adoption, and this surge in solar energy installations directly drives the demand for solar cables, which are crucial for ensuring the safe and efficient transfer of electricity from solar panels to the grid or storage systems.
Central & South America Solar Cable Market Trends
The expansion of solar power in the commercial and industrial sectors is playing a major role in the growth of the solar cables market in Central & South America. Many businesses and industrial facilities are turning to solar energy to reduce their energy costs and achieve sustainability goals. With the region’s rapid urbanization and industrialization, the demand for large-scale solar installations is rising, which drives the need for solar cables capable of handling the increased power output and ensuring optimal energy transmission.
Middle East & Africa Solar Cable Market Trends
Government initiatives to reduce carbon emissions and increase renewable energy capacity are fueling the growth of the solar cables market in the MEA region. For instance, Saudi Arabia's Vision 2030 plan aims to diversify the country's energy mix, with solar power expected to contribute significantly to generating 50% of the nation's electricity from renewables by 2030. Similarly, the UAE's push for sustainability, with projects like the Mohammed bin Rashid Al Maktoum Solar Park in Dubai, is driving large-scale solar projects. As these projects continue to scale up, the need for high-quality solar cables that can withstand extreme weather conditions, such as high temperatures and dust storms, will continue to grow, further boosting the market.
Key Solar Cable Company Insights
Some of the key players operating in the market include Alpha Wire, Allied Wire and Cable, and others
-
Alpha Wire offers a comprehensive range of solar cable solutions to withstand harsh environmental conditions while ensuring reliable performance. Their photovoltaic wire features include sizes ranging from 14 AWG to 2 AWG and comply with UL 4703 PV wire standards and TUV Pfg 1169 LSZH wire specifications. The cables are engineered with specially formulated PVC jackets that provide resistance against oil, sunlight, ozone layers, and UV radiation.
-
Allied Wire and Cable is a leading distributor and manufacturer of electrical wire, cable, and related products. The company offers a comprehensive selection of solar cables designed specifically for PV systems. Their product line includes both PV wire and other types of cables that are essential for solar installations. The solar cables are engineered to withstand harsh environmental conditions, ensuring durability and reliability over time.
Key Solar Cable Companies
The following key companies have been profiled for this study on the solar cable market.
-
Alpha Wire
-
Allied Wire and Cable
-
Belden
-
Fujikura
-
Furukawa Electric
-
General Cable
-
Havells
-
Helukabel
-
Hellenic Group
-
Kabelwerk Eupen
-
KEI Industries
-
Lapp Group
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Prysmian Group, Nexans, Southwire Company, Furukawa Electric, Havells, LAPP Group, KEI Industries, HELUKABEL, Hellenic Cables, Kabelwerk Eupen AG)
- Offer comprehensive portfolios of AC, DC, and high-voltage solar cables for residential, commercial, industrial, and utility-scale projects.
- Expand manufacturing capacity and strengthen global distribution networks to support growing solar installations.
- Invest in product innovation, certifications, and compliance with international standards to address evolving customer requirements.
- Strong global brand recognition and long-standing customer relationships.
- Broad manufacturing capabilities with proven product quality and regulatory certifications.
- Extensive sales, service, and distribution networks across multiple regions.
- Higher production and operating costs than regional manufacturers.
- Greater exposure to fluctuations in copper and polymer prices.
- Slower response to niche or highly customized project requirements due to larger organizational structures.
Emerging Players (Alpha Wire, Allied Wire & Cable, LS VINA Cable & System)
- Focus on regional markets and specialized cable solutions for selected solar applications.
- Expand partnerships with EPC contractors, distributors, and renewable energy developers.
- Strengthen product portfolios and manufacturing capabilities to increase market presence
- Greater flexibility in serving regional and customized customer requirements.
- Faster decision-making and quicker response to changing market demand.
- Competitive pricing strategies in selected markets.
- Limited global brand recognition and international market presence.
- Smaller manufacturing scale and distribution networks compared to established competitors.
- Lower investment capacity for large-scale R&D and global expansion.
Solar Cable Market Report Scope
Report Attribute
Details
Market Definition
The global solar cable market represents the revenue generated from the sale of cables used for electrical connectivity and power transfer within solar photovoltaic (PV) systems.
Market size in 2025
USD 1.2 billion
Estimated Market size in 2026
USD 1.4 billion
Projected Market size by 2033
USD 3.0 billion
Growth rate
CAGR of 11.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, Type, End Use, Region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; Spain; UK; France; Italy; Russia; China; India; Japan; Indonesia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Allied Wire & Cable, Alpha Wire, FURUKAWA ELECTRIC CO., LTD., Havells, Hellenic Cables, HELUKABEL, Kabelwerk Eupen AG, KEI Industries Limited, LAPP Group, LS VINA Cable & System, Nexans, Prysmian Group, Southwire Company, LLC
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Solar Cable Market Report Segmentation
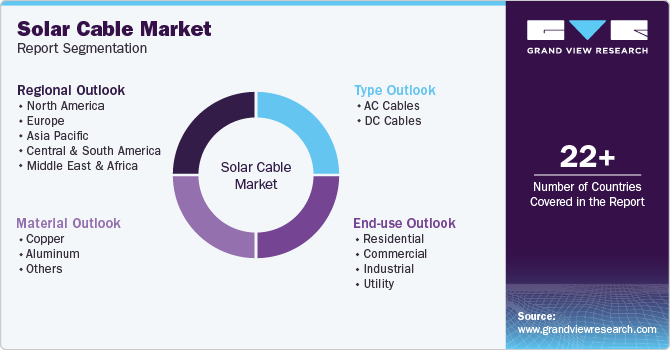
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global solar cable market report on the basis of material, type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Material Outlook (Revenue, USD Million; 2021 - 2033)
-
Copper
-
Aluminum
-
Others
-
-
Type Outlook (Revenue, USD Million; 2021 - 2033)
-
AC Cables
-
DC Cables
-
-
End Use Outlook (Revenue, USD Million; 2021 - 2033)
-
Residential
-
Commercial
-
Industrial
-
Utility
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
Spain
-
France
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Indonesia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The solar cable market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each solar cable segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Material
Revenue capture definition
Copper
Copper solar cables use copper conductors to provide high electrical conductivity, durability, and efficient power transmission in solar PV systems. Revenue is generated through the sale of copper-based solar cables supplied for residential, commercial, industrial, and utility-scale solar installations.
Aluminum
Aluminum solar cables use aluminum conductors as a lightweight and cost-effective alternative to copper for power transmission in solar PV systems. Revenue is generated through the sale of aluminum-based solar cables deployed across commercial, industrial, and utility-scale solar projects.
Others
This segment includes solar cables manufactured using alternative conductor materials or specialized material combinations designed for specific performance requirements. Revenue is generated through the sale of these specialized solar cables for niche and application-specific solar installations.
Segment - Type
Revenue capture definition
AC Cables
AC cables transmit alternating current from solar inverters to transformers, distribution systems, or the electrical grid. Revenue is generated through the sale of AC solar cables used across residential, commercial, industrial, and utility-scale solar projects.
DC Cables
DC cables transmit direct current between solar panels, combiner boxes, and inverters within photovoltaic systems. Revenue is generated through the sale of DC solar cables designed for efficient and reliable power transmission in solar installations.
Segment - End Use
Revenue capture definition
Residential
This segment includes solar cables supplied for rooftop and small-scale residential photovoltaic systems. Revenue is generated from the sale of solar cables used in household solar power installations.
Commercial
This segment includes solar cables used in commercial buildings, offices, retail facilities, and institutional solar projects. Revenue is generated through the supply of solar cables for commercial photovoltaic installations.
Industrial
Industrial segment includes solar cables deployed in manufacturing facilities, warehouses, and industrial premises with captive solar power systems. Revenue is generated through the sale of solar cables for industrial-scale solar energy projects.
Utility
Utility segment includes solar cables supplied for large-scale solar farms and grid-connected photovoltaic power plants. Revenue is generated through the sale of solar cables used in utility-scale solar generation and power transmission infrastructure.
Estimation Model
Layer Name
Key Question
Description
Solar Installation Development Layer
What forms the demand base for solar cables?
Assess global and regional solar PV installations across residential, commercial, industrial, and utility sectors. Evaluate annual capacity additions (MW/GW), project pipeline, government renewable energy targets, and investments in solar infrastructure to determine the underlying demand for solar cables.
Cable Specification & Material Layer
Which cable materials and types are being adopted?
Analyze the adoption of copper, aluminum, and other conductor materials, along with AC and DC cable types used across different solar PV systems. Assess performance requirements, voltage ratings, installation practices, and technology trends influencing segment-wise demand.
End-Use Deployment Layer
Where are solar cables being deployed?
Evaluate the consumption of solar cables across residential, commercial, industrial, and utility-scale installations. Analyze installation patterns, project size, cable length requirements, and end-use demand to determine the contribution of each application segment to overall market consumption.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of solar cables used in photovoltaic power systems. The overall market value is determined by the adoption of different cable materials, AC and DC cable demand, and deployment across residential, commercial, industrial, and utility-scale solar installations, which collectively drive revenue generation in the solar cable market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Technology & Product Benchmarking Assessment
Compared solar cable products based on conductor material, AC/DC configuration, voltage ratings, insulation materials, weather resistance, fire performance, and compliance with international standards. Assessed their suitability across residential, commercial, industrial, and utility-scale solar installations.
Helped identify the most competitive product offerings and evaluate technology adoption across different installation types.
Regional Deployment & Policy Assessment
Assessed regional solar installation trends, utility-scale project pipelines, domestic manufacturing capacity, and renewable energy policies influencing solar cable demand. Evaluated the impact of government incentives, localization initiatives, and grid expansion programs on regional market growth.
Helped identify attractive investment regions and understand policy-driven growth opportunities.
Competitive Landscape Assessment
Evaluated the strategies of major solar cable manufacturers based on product portfolio, manufacturing footprint, distribution network, certifications, pricing strategy, and recent business developments. Assessed their competitive positioning across major regional markets.
Enabled benchmarking of key competitors, identification of market gaps, and formulation of effective competitive strategies.
Frequently Asked Questions About This Report
The global solar cable market size was valued at USD 1.1 billion in 2024 and is estimated at USD 1.4 billion for 2026.
The global solar cable market is expected to grow at a CAGR of 11.5% from 2026 to 2033, reaching USD 3.0 billion by 2033.
The solar cable market is primarily driven by the rapid expansion of solar PV installations worldwide, supported by renewable energy targets and investments in utility-scale and rooftop solar projects. Increasing adoption of high-voltage solar systems and demand for efficient, durable power transmission infrastructure are further accelerating market growth.
The Asia Pacific region dominated the solar cable market with a revenue share of 39.3% in 2025.
China dominated the Asia Pacific region market with a revenue share of 49.7% in 2025.
Latin America is anticipated to register the fastest CAGR of 12.7% over the forecast period.
Based on material, the copper segment accounted for largest revenue share of 67.7% in 2025.
Based on type, the DC cables segment accounted for largest revenue share of 62.3% in 2025.
The key players operating in the solar cable market are Allied Wire & Cable, Alpha Wire, FURUKAWA ELECTRIC CO., LTD., Havells, Hellenic Cables, HELUKABEL, Kabelwerk Eupen AG, KEI Industries Limited, LAPP Group, LS VINA Cable & System, Nexans, Prysmian Group, Southwire Company, LLC, and others.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


