
- Home
- »
- Consumer F&B
- »
-
South Korea Premium Bottled Water Market Report, 2033GVR Report cover

South Korea Premium Bottled Water Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Still Water, Sparkling Water, Functional Water), By Price Point, By Packaging Type, By Distribution Channel, By Pack Size, By Pack Type, And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.1BMarket Forecast, 2033
$1.4BCAGR, 2026–2033
3.6%South Korea Premium Bottled Water Market Summary
The south korea premium bottled water market size was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion in 2026 to USD 1.4 billion by 2033, at a CAGR of 3.6% from 2026 to 2033. The market is supported by rising health awareness, demand for quality hydration, and a growing premiumization trend across beverages.
Key Market Trends & Insights
- By product: Still water segment held the largest market share of 38.5% in 2025.
- By price point: Premium-priced bottled water segment held the largest market share of 60.2% in 2025.
- By packaging type: PET bottles segment held the largest market share of 52.9% in 2025.
- By pack size: Up to 500 ml segment held the largest market share of 42.4% in 2025.
- By pack type: Multi pack segment held the largest market share of 68.1% in 2025.
- By distribution channel: Off-premise segment held the largest market share of 50.9% in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.0 Billion
- Estimated market size in 2026: USD 1.1 Billion
- Projected market size by 2033: USD 1.4 Billion
- CAGR (2026-2033): 3.6%
Prism AI by Grand View Research Free to tryAsk a question about the south korea premium bottled water marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Consumers increasingly prioritize water safety, purity, mineral composition, source provenance, taste, and brand credibility, while convenient formats align with fast-paced urban lifestyles and on-the-go consumption. Premium bottled water is also gaining relevance across upscale hotels, fine-dining restaurants, cafés, and wellness-oriented occasions, as consumers increasingly associate differentiated water products with quality, lifestyle, and elevated consumption experiences.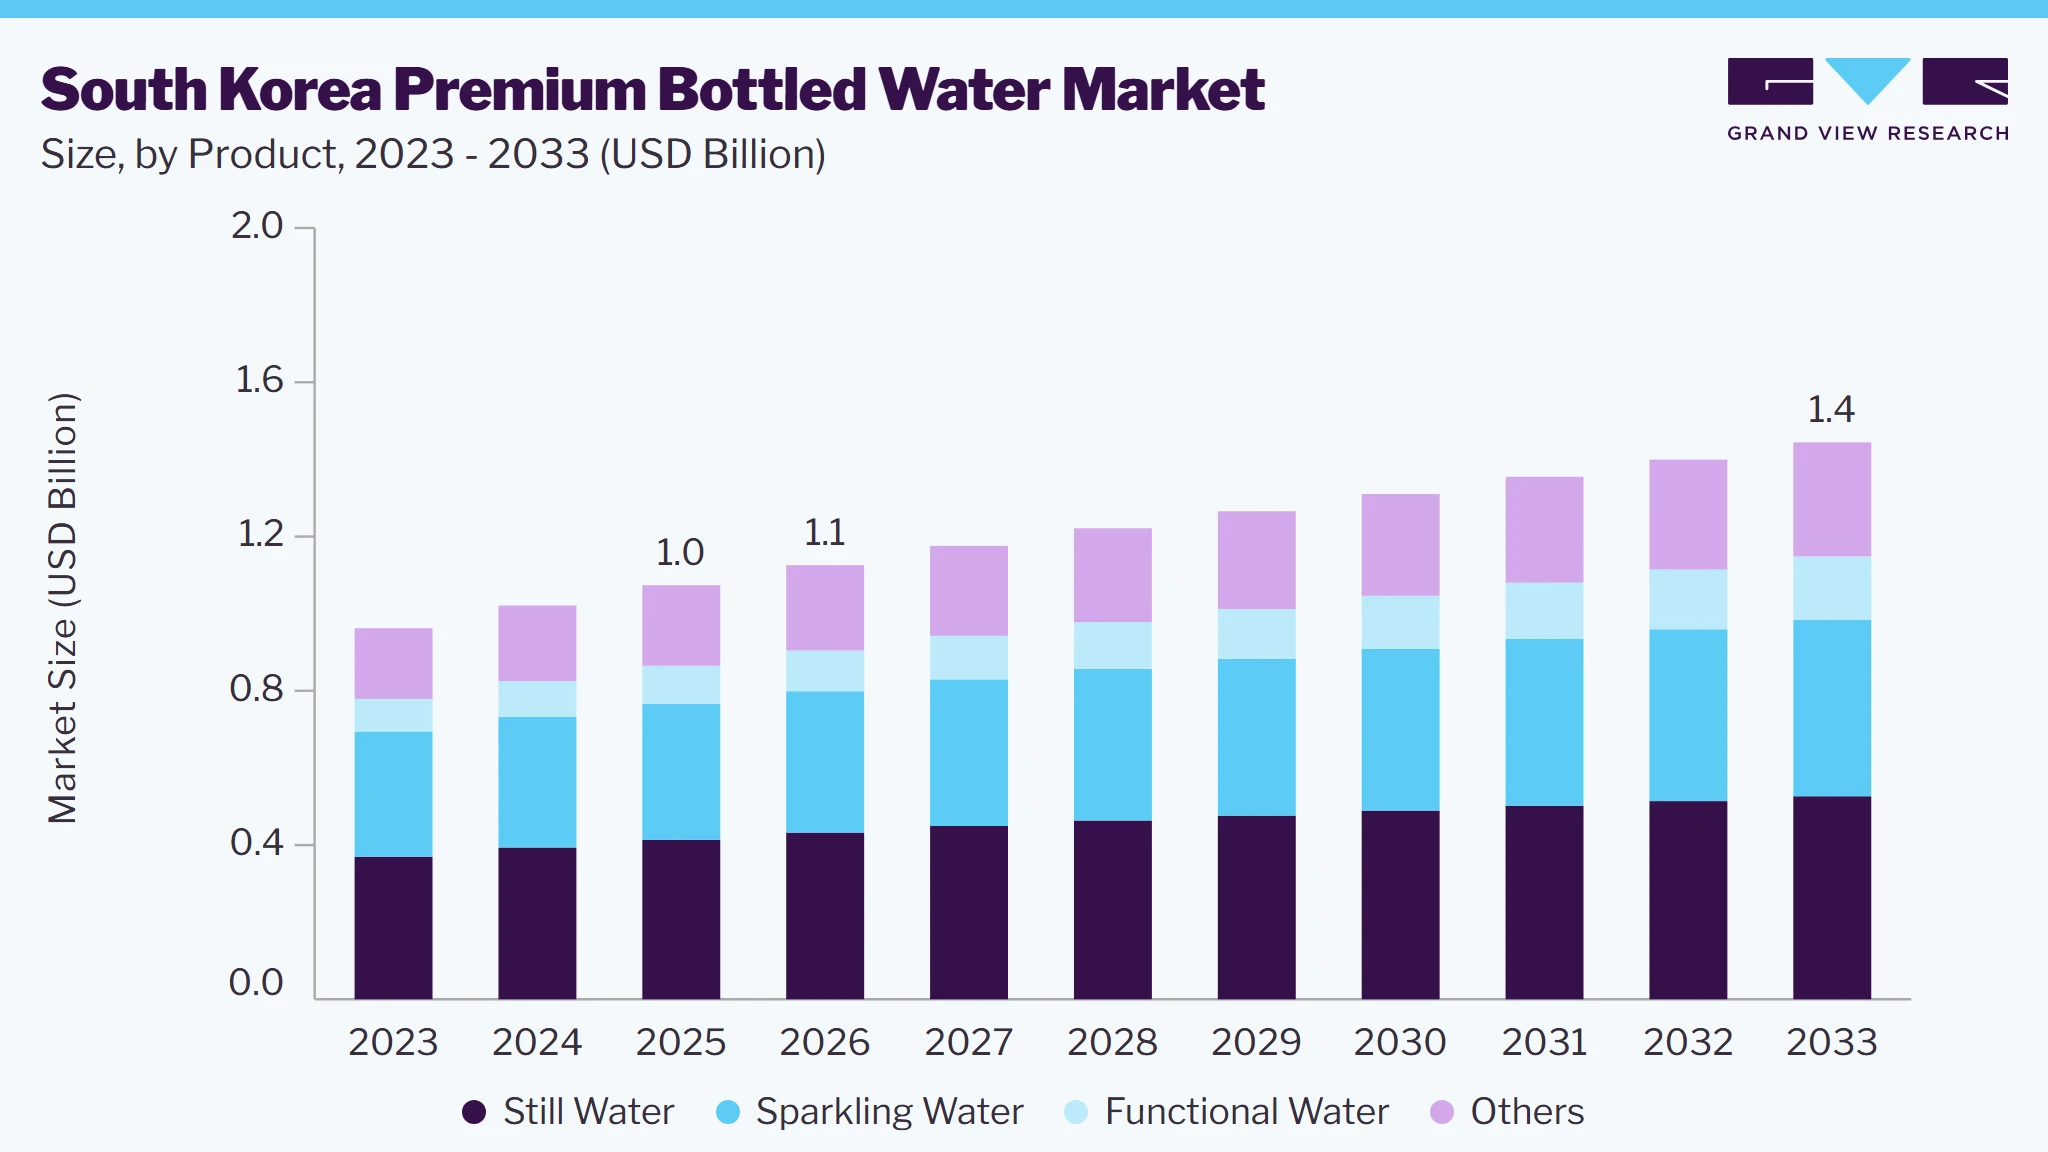 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Rising wellness awareness is supporting demand for water-based alternatives to sugary beverages, while fast-paced urban lifestyles and widespread convenience-store and online retail access continue to favor portable formats. Premiumization is also extending beyond conventional still water, as sparkling and flavored variants help brands create product differentiation, diversify consumption occasions, and attract consumers seeking healthier substitutes for carbonated soft drinks. For instance, in February 2026, Dong-A Otsuka expanded its Limewasser sparkling-water portfolio with Passion Fruit and Cherry variants, combining fruit flavors and carbonation with its water proposition to provide consumers with more differentiated hydration choices.
 To learn more about this report, Download Free Sample Report
Consumer Insights
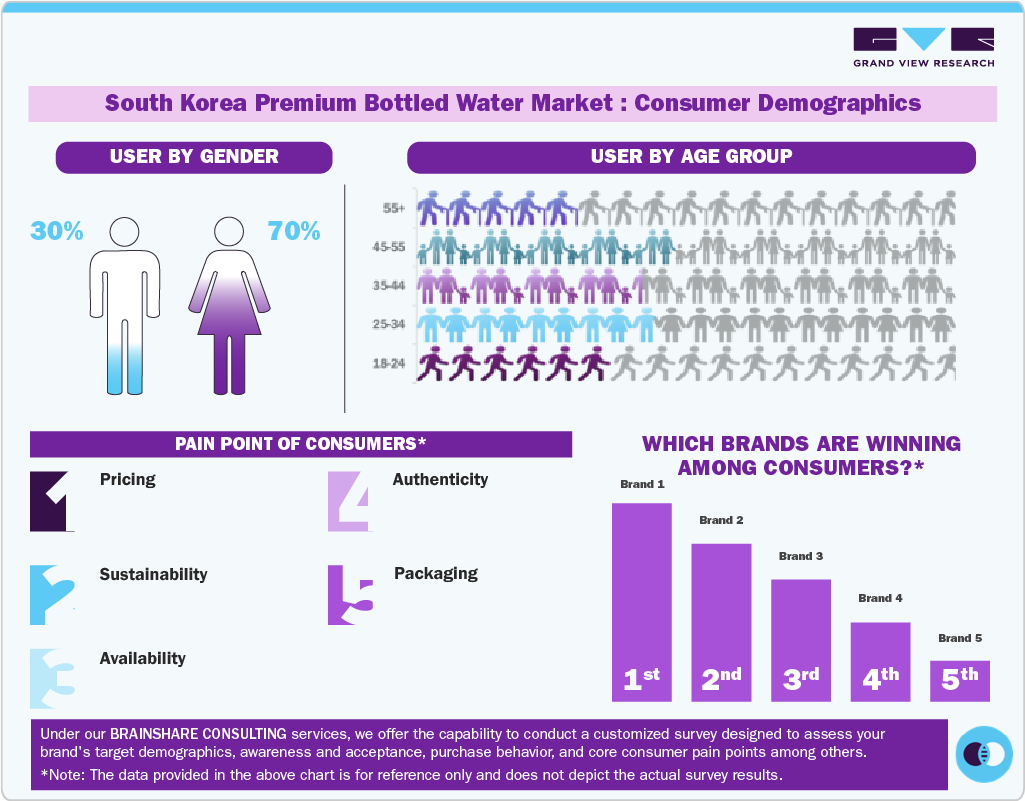
South Korean consumers increasingly view premium bottled water as a higher-quality and health-oriented hydration option, with purchasing decisions influenced by perceived purity, source provenance, taste, mineral content, safety, and brand reputation. Consumption is supported by busy urban lifestyles, on-the-go routines, fitness, wellness, and the growing preference for water as an alternative to sugary beverages. Consumers are also placing greater emphasis on convenience, packaging functionality, sustainability, and product differentiation, supporting demand for still, sparkling, flavored, and functional water formats. These evolving preferences enable premium brands to differentiate through credible water sources, distinctive formulations, convenient pack formats, innovative packaging, and lifestyle-focused positioning.
 To learn more about this report, Download Free Sample Report
Market Dynamics
South Korean consumers are increasingly seeking premium hydration defined by purity, safety, natural provenance, and health-oriented positioning, driving demand for differentiated bottled-water offerings. Manufacturers are responding by leveraging distinctive water sources, premium pricing, selective distribution, and upscale brand positioning to elevate perceived value. For instance, in December 2024, LG Household & Health Care launched Vio Hwio Ullim Water, sourced from Ulleungdo’s natural springs and initially distributed through five-star hotels and department-store VIP lounges at around KRW 2,000 for 450 mL. The launch highlights the market’s shift toward source-led differentiation and experiential premiumization beyond basic hydration.
South Korea’s evolving packaging regulations are creating additional requirements for bottled-water producers. From January 2026, manufacturers using at least 5,000 tons of PET bottles annually are subject to a 10% recycled-material requirement, while the bottled-water sector is also transitioning toward label-free packaging. These measures can constrain packaging flexibility for premium brands that rely on distinctive bottle designs, labels, and visual branding to reinforce product differentiation, while requiring adjustments to packaging specifications and production processes.
South Korea’s market presents opportunities for brands to create value through distinctive water sources, mineral characteristics, provenance, and quality credentials. For instance, in 2026, CY Global secured a 30-year exclusive agreement to import and distribute China’s Taishan Good Water in South Korea, a natural spring water sourced from the bedrock aquifer of Mount Tai. The planned 2027 launch highlights how companies are broadening their portfolios with source-differentiated waters, creating opportunities to build consumer interest around origin, natural characteristics, and product differentiation rather than competing primarily on price.
Analyst Perspective
South Korea’s market is evolving toward higher-value, quality-led consumption, as consumers increasingly seek safe, pure, source-authenticated, and wellness-oriented hydration. Urban lifestyles and strong retail connectivity are supporting demand for convenient single-serve formats, while premium hotels, restaurants, and specialty channels are creating opportunities for elevated consumption occasions. Manufacturers are responding with distinctive water origins, functional propositions, sparkling and flavored variants, sophisticated packaging, and sustainability initiatives to strengthen differentiation and justify premium pricing. Going forward, market growth is expected to depend on brands’ ability to combine credible quality attributes with convenience, innovation, and aspirational positioning, while navigating price sensitivity and intense competition.
Product Insights
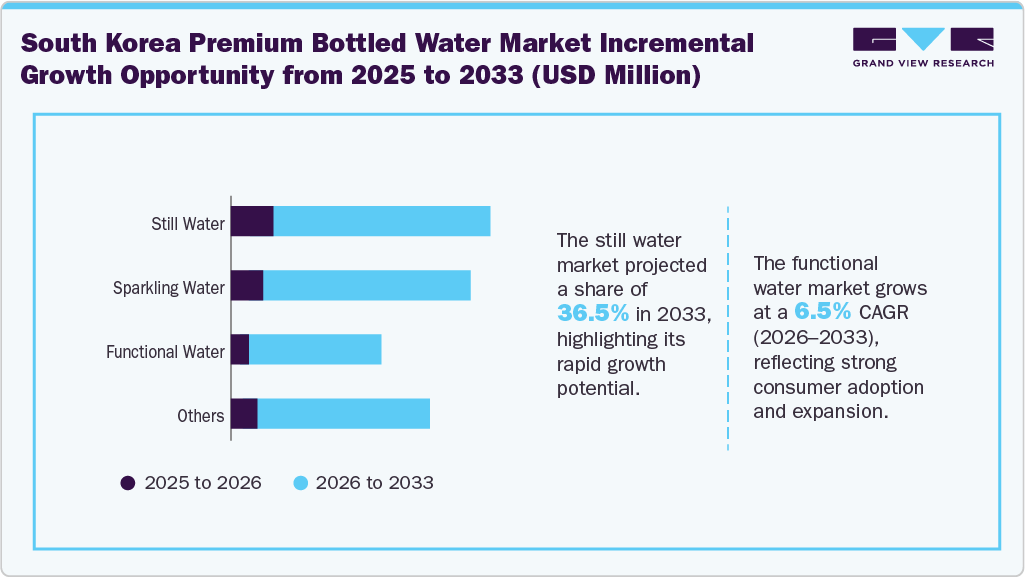
Still water accounted for the largest revenue market share, representing 38.5% of revenue in 2025. The market is supported by continued consumer emphasis on hydration, mineral content, source quality, and purity. For instance, in March 2025, HiteJinro Beverage launched Joy Water, a still bottled-water brand made from natural bedrock water in Cheongju. The company highlighted its moderate hardness, natural mineral content, purity, smooth drinkability, and refreshing taste, while offering 500 mL and 2 L formats. The launch demonstrates how manufacturers are strengthening the still-water category through mineral positioning, source quality, and health-oriented product differentiation.
 To learn more about this report, Download Free Sample Report
Functional water is projected to record the fastest CAGR of 6.5% from 2026 to 2033, supported by rising demand for hydration products that deliver benefits beyond basic thirst relief. Growing interest in blood-sugar management, low-calorie formulations, vitamins, minerals, and convenient wellness solutions is encouraging manufacturers to expand functional offerings. For instance, in August 2026, Binggrae launched “Post-Meal Care Water,” a 500 mL functional beverage containing 64 mg of banaba leaf extract and zero sugar, specifically designed to support post-meal blood-sugar management. The launch demonstrates how manufacturers are integrating targeted wellness benefits into convenient water-based formats.
Price Point Insights
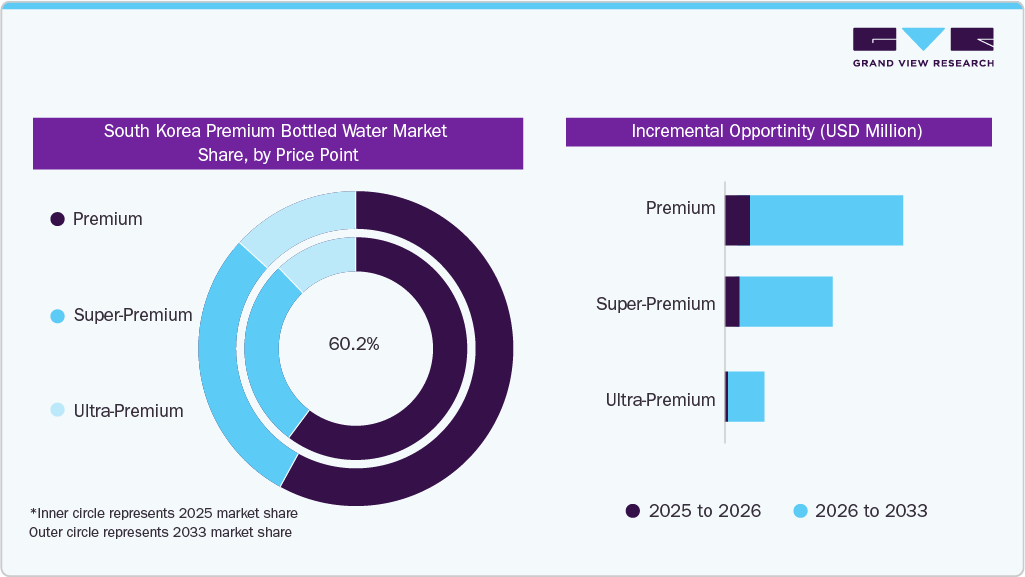
The premium bottled water accounted for the largest share, representing 60.2% of total revenue in 2025. This dominance reflects consumer willingness to pay for superior source quality, mineral characteristics, safety assurance, distinctive packaging, and established brand credentials. Premium brands can therefore capture higher value by differentiating beyond basic hydration and targeting quality-conscious consumers, upscale dining, hospitality, and wellness occasions. For instance, in 2025, Ananti introduced a limited-edition premium bottled water for the APEC CEO Summit, reinforcing premium positioning through natural mineral content, sustainable packaging, and exclusive hospitality distribution.
 To learn more about this report, Download Free Sample Report
The ultra-premium bottled water is projected to record the fastest CAGR of 4.9% from 2026 to 2033, driven by increasing consumer willingness to pay for exceptional source provenance, mineral quality, exclusivity, distinctive packaging, and elevated brand experiences. Growth is further supported by ultra-premium hospitality, fine dining, luxury retail, and wellness consumption, where consumers associate ultra-premium water with quality, status, and sophisticated lifestyles. Brands are increasingly strengthening this positioning through rare or prestigious water sources, premium glass bottles, refined visual identities, limited-edition offerings, and sustainability-led packaging, enabling differentiation beyond basic hydration and supporting higher price points.
Packaging Type Insights
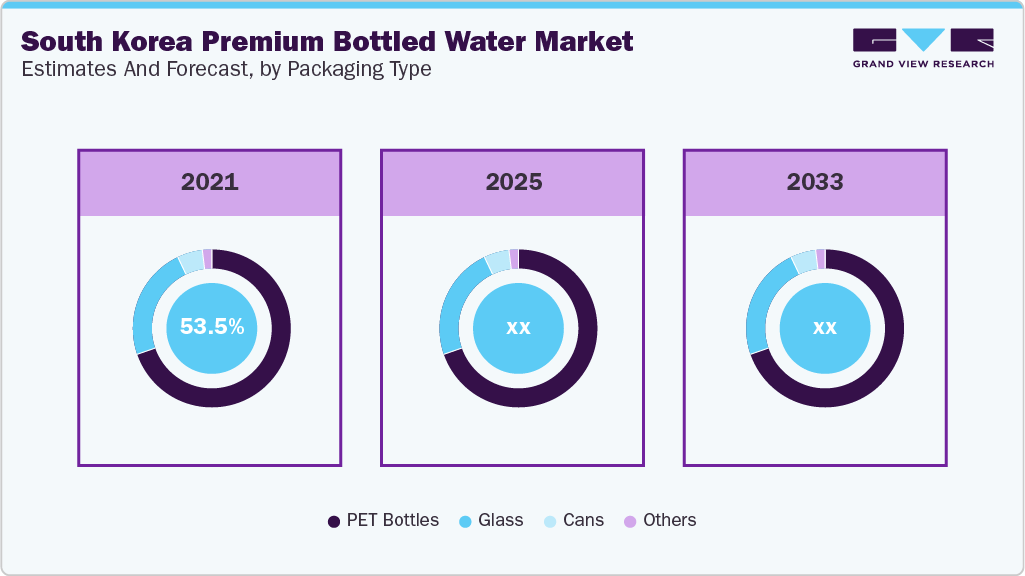
PET bottles held the largest market share, accounting for 52.9% of total revenue in 2025. The market is supported by PET’s lightweight, portable, and widely distributed format. The material remains well-suited to everyday hydration, travel, fitness, and on-the-go consumption, while the shift toward recycled PET is helping brands respond to sustainability expectations. For instance, in 2025, Lotte Chilsung Beverage expanded its lightweight Icis bottled-water packaging, reducing the 500 mL PET bottle weight from 11.6 g to 9.4 g, an approximately 18.9% reduction. The initiative demonstrates how bottled-water producers are optimizing PET packaging to improve material efficiency and strengthen sustainability credentials.
 To learn more about this report, Download Free Sample Report
Cans are projected to record the fastest CAGR of 4.2% from 2026 to 2033. Cans can also provide premium brands with greater format differentiation while supporting consumption across hospitality, food service, workplace, and home occasions. For instance, in August 2025, premium bottled-water brand Montbest launched a 190 mL sparkling-water can, expanding beyond its existing PET range. The compact format was designed for single-serve consumption across bars, cafés, restaurants, hotels, offices, and home-café occasions, highlighting the growing role of alternative packaging in premium water consumption.
Pack Size Insights
Up to 500 mL of premium bottled water, representing 42.4% of revenue in 2025. supported by strong demand for portable, single-serve formats suited to on-the-go hydration. Compact bottles are particularly convenient for fitness, commuting, travel, workplaces, hospitality, and outdoor activities, while their portion size supports controlled consumption and easy handling.
The 501-750 mL of premium bottled water are projected to register a significant CAGR of 3.6% from 2026 to 2033. Growth is supported by consumer preference for mid-sized formats that provide greater hydration capacity while remaining practical for individual consumption. These bottles are well-suited to outdoor activities, travel, fitness, dining, hospitality, and extended periods away from home, offering a balance between portability and volume.
Pack Type Insights
The premium bottled water in multi packs held the largest market position, representing 68.1% of revenue in 2025. Its dominance is supported by the growing preference for value-oriented bulk purchases, household stocking, and regular consumption, particularly among consumers who purchase bottled water for home, workplace, and family use. Multi-pack formats provide greater convenience and reduce the frequency of individual purchases, making them well-suited to routine hydration needs. Demand is further supported by the availability of multi-packs across supermarkets, hypermarkets, wholesale outlets, and online grocery platforms.
The premium bottled water in single packs is projected to register a significant CAGR of 3.1% from 2026 to 2033. Growth is supported by increasing demand for convenient, ready-to-consume hydration across commuting, travel, fitness, workplace, and leisure occasions. Single-pack formats allow consumers to purchase premium water according to immediate consumption needs while providing greater portability and ease of handling. Growth is further supported by the expansion of premium bottled water across food service, hospitality, convenience retail, and on-the-go consumption channels.
Distribution Channel Insights
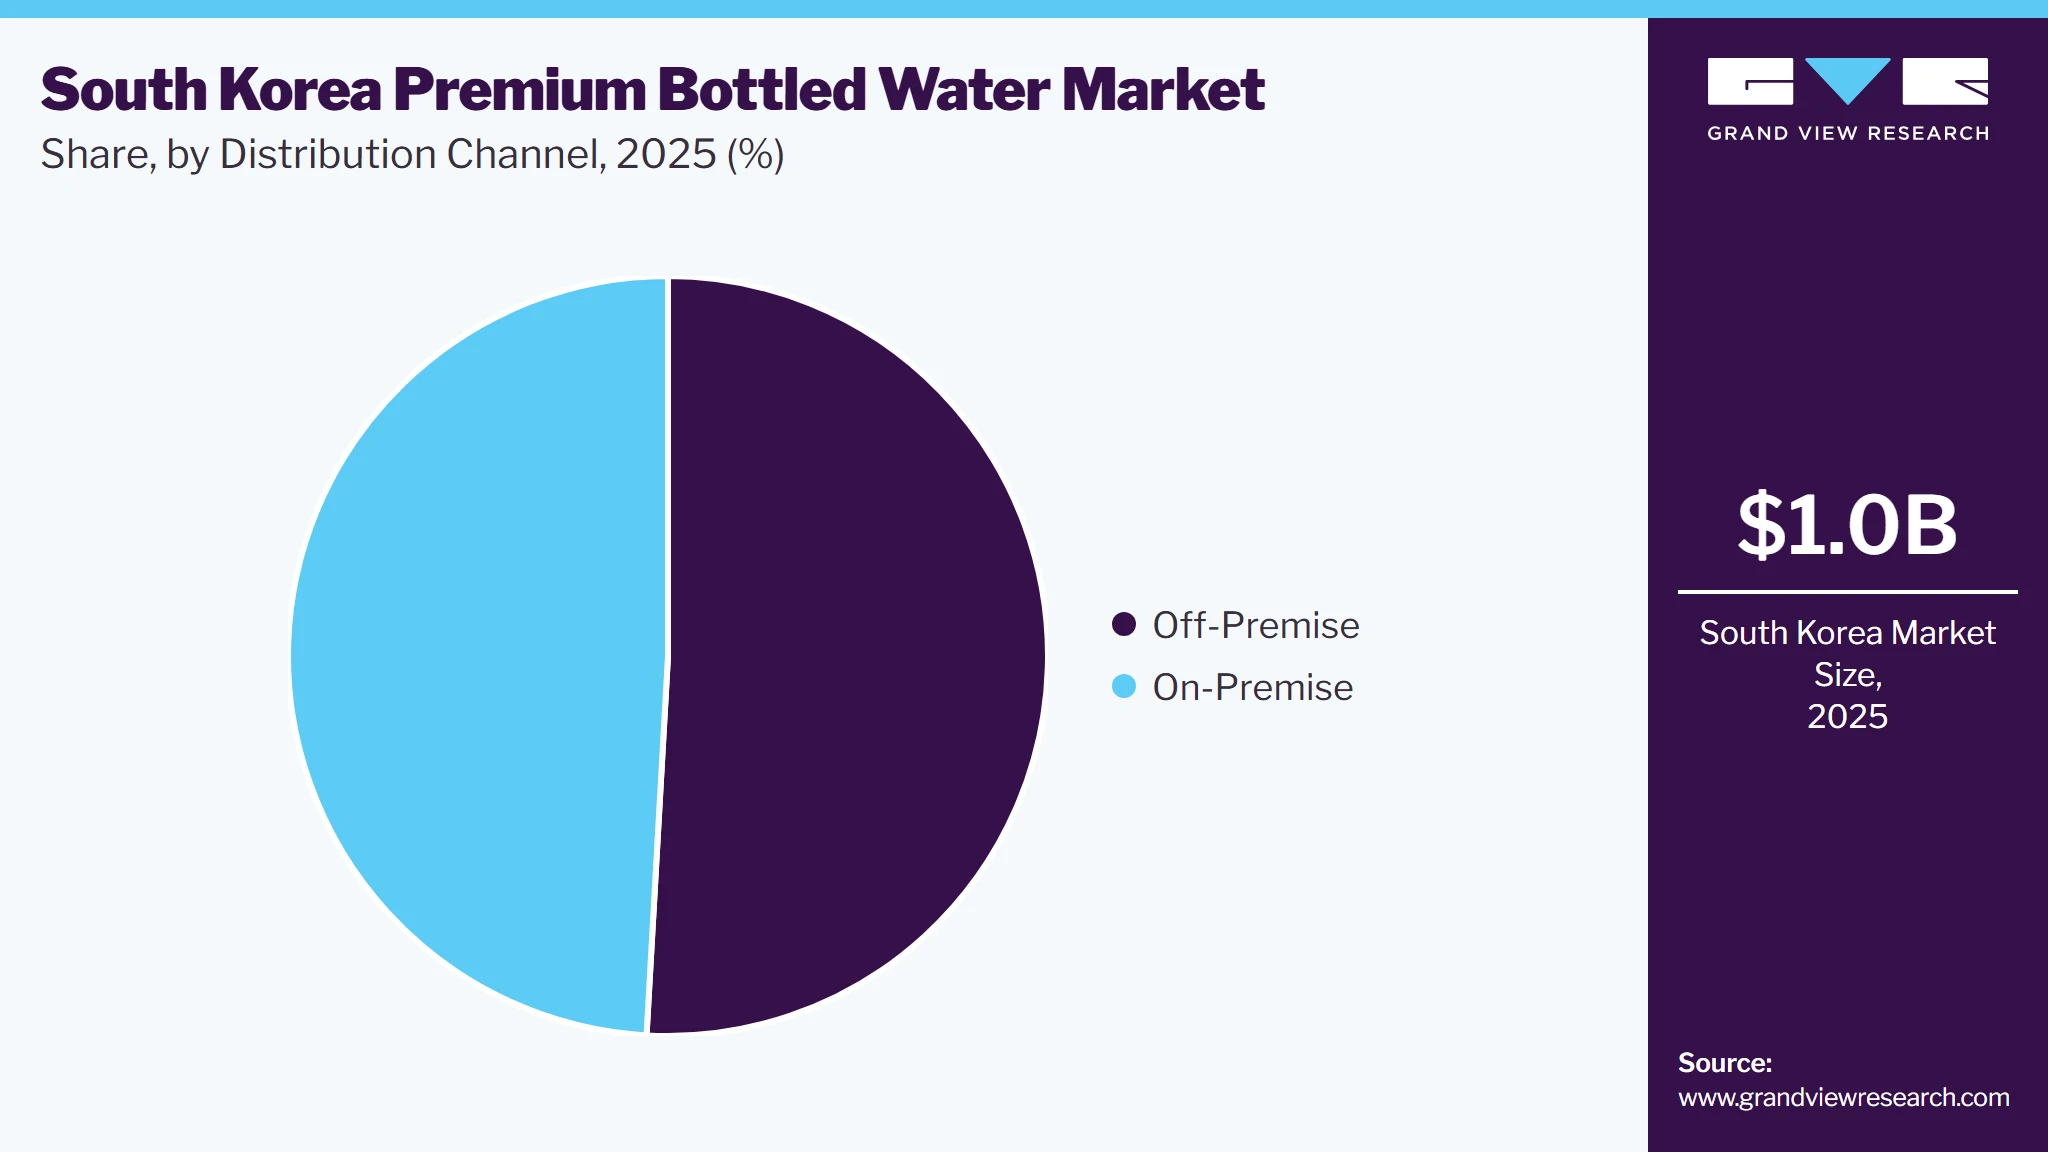
The off-premise channels accounted for the largest share of 50.9% of the revenue in 2025. Its leading position is supported by the broad availability of premium water through supermarkets, hypermarkets, convenience stores, specialty retailers, and online platforms. Retail channels remain important for household stocking and on-the-go purchases, while strong shelf presence enables brands to build visibility through premium packaging, multipacks, varied pack sizes, and new product introductions. The channel also gives manufacturers greater access to health-conscious and premium-oriented consumers, supporting brand expansion, wider product distribution, and repeat purchases beyond restaurant and hospitality settings.
 To learn more about this report, Download Free Sample Report
The on-premise channel is projected to register the fastest CAGR of 3.8% from 2026 to 2033. South Korea’s market is gaining opportunities from the expansion of premium hospitality and fine-dining channels, where bottled water forms part of the overall dining experience. For instance, in March 2026, Evian identified South Korea as one of its top five export markets and announced plans to strengthen its presence across hotels, Michelin-starred restaurants, and fine-dining establishments through Shinsegae L&B, which began handling Evian’s domestic sales in August 2025. The company plans to leverage Shinsegae Group’s hospitality and dining network, highlighting the potential for premium water brands to expand through high-end foodservice partnerships and curated consumption occasions.
Key South Korea Premium Bottled Water Company Insights
The market is competitive, with established multinational brands and emerging premium players competing across retail, foodservice, hospitality, and e-commerce channels. Companies are focusing on product innovation, portfolio expansion, sustainable packaging, strategic partnerships, digital marketing, and channel expansion to strengthen market positioning.
 To learn more about this report, Download Free Sample Report
Key South Korea Premium Bottled Water Companies
-
Evian
-
S.Pellegrino
-
Perrier
-
Acqua Panna
-
MONTBEST
-
Global Deep Sea Water
-
SaRangHae300
-
SEAWANNA
-
VOSS
-
Lauretana
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Evian; S.Pellegrino; Perrier; Acqua Panna; VOSS; Lauretana)
- Expand premium bottled water portfolios through distinctive sources, premium packaging, sustainability initiatives, and broad retail and hospitality distribution.
- Strong brand recognition, established distribution, trusted sources, and premium positioning.
- Higher operating costs, regulatory pressures, and intense competition from private-label and specialist brands.
Emerging Players (MONTBEST; Global Deep Sea Water; SaRangHae300; SEAWANNA)
- Target niche opportunities through flexible production, specialist offerings, differentiated sourcing, and selected retail or hospitality channels.
- Greater flexibility, customer-focused solutions, and differentiated product propositions.
- Limited brand awareness, distribution reach, production scale, and marketing resources.
Recent Developments
-
In April 2026, I'm Eco launched its premium “I'm Eco Sam” bottled water in South Korea, combining a sugarcane-based PLA bottle with enhanced water-safety controls, microplastic and nanoplastic non-detection claims, and a grip-oriented bottle design, demonstrating how manufacturers are using sustainability, safety, and packaging functionality to strengthen premium positioning.
-
In March 2026, Evian identified South Korea as one of its top five export markets and announced plans to strengthen its presence across hotels, Michelin-starred restaurants, and fine-dining establishments through Shinsegae L&B, which began handling Evian’s domestic sales in August 2025.
South Korea Premium Bottled Water Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.0 billion
Estimated market size in 2026
USD 1.1 billion
Projected market size by 2033
USD 1.4 billion
Growth rate (revenue)
CAGR of 3.6% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative (Revenue) units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, price point, packaging type, distribution channel. pack size, pack type
Key companies profiled
Evian; S.Pellegrino; Perrier; Acqua Panna; MONTBEST; Global Deep Sea Water; SaRangHae300; SEAWANNA; VOSS; Lauretana
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
South Korea Premium Bottled Water Market Report Segmentation
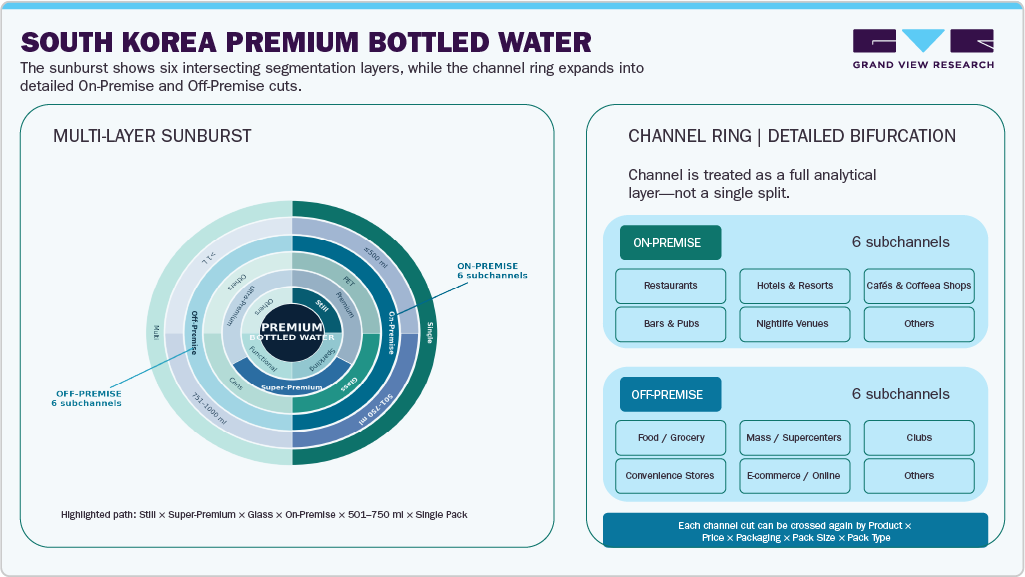
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the South Korea premium bottled water market report based on product, price point, packaging type, distribution channel, pack size, and pack type:
-
Product Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
Still Water
-
Sparkling Water
-
Functional Water
-
Others
-
-
Price Point Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
Premium
-
Super-Premium
-
Ultra-Premium
-
-
Packaging Type Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
PET Bottles
-
Glass
-
Cans
-
Others
-
-
Distribution Channel Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
On-Premise
-
Restaurants
-
Hotels & Resorts
-
Cafés & Coffee Shops
-
Bars & Pubs
-
Nightlife Venues
-
Others
-
-
Off-Premise
-
Food / Grocery
-
Mass (incl. supercenters)
-
Clubs
-
Convenience Stores
-
E-commerce / Online
-
Other
-
-
-
Pack Size Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
Upto 500 ml
-
501-750 ml
-
751-1000 ml
-
Above 1 Liter
-
-
Pack Type Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
Single Pack
-
Multi Pack
-
Research Methodology
The South Korea premium bottled water market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each South Korea premium bottled water segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Still Water
This segment includes the sales of premium still water, including natural spring water, mineral water, artesian water, and purified water without carbonation.
Sparkling Water
This segment includes the sales of premium sparkling water, including naturally sparkling and carbonated water products.
Functional Water
This segment includes the sales of premium water enhanced with functional ingredients, such as electrolytes, vitamins, minerals, antioxidants, and other nutrients intended to support hydration and wellness.
Others
This segment includes the sales of other premium bottled water products, including specialty water products differentiated by unique sourcing, processing, or formulation.
Estimation Model
Layer Name
Key Question
Description
Consumption Profile Layer
Who consumes premium bottled water?
Demand is supported by consumers seeking high-quality hydration, perceived purity, superior taste, natural mineral content, functional benefits, and premium experiences. Wellness awareness, convenience, and interest in sustainable consumption further influence purchasing preferences.
Market Reach Layer
Where are they sold?
Products reach consumers through retail, e-commerce, restaurants, hotels, foodservice, and specialty channels, with distribution breadth supporting market penetration.
Innovation & Differentiation Layer
How do brands differentiate?
Brands differentiate through source provenance, mineral composition, functional benefits, sparkling formats, premium bottle designs, and sustainable packaging.
Value Generation Layer
How does consumption convert into market value?
Revenue is generated through premium-priced product sales, supported by brand equity, differentiated offerings, packaging value, and consumer willingness to pay.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Understand premium bottled water consumer preferences and purchasing behavior
Developed a South Korea-specific consumer assessment covering preferences for natural spring water, mineral content, source origin, purity, taste, packaging format, sustainability, and functional benefits. Evaluated purchasing behavior across supermarkets, convenience stores, specialty retailers, foodservice, and e-commerce.
Helps identify high-value consumer segments, key purchase drivers, and attributes that support premium pricing and brand differentiation in the South Korea market.
Benchmark competitive positioning of leading premium bottled water brands
Assessed major South Korea and international brands based on water source, product positioning, packaging, price point, brand image, sustainability initiatives, distribution footprint, and product portfolio. Evaluated how brands differentiate through provenance, purity, functionality, and premium packaging.
Provides a structured competitive benchmark to identify positioning gaps, whitespace opportunities, and potential strategies for strengthening market presence.
Identify emerging product categories and innovation opportunities
Evaluated emerging trends including still water, sparkling water, functional water and other premium water category. Assessed innovation around ingredients, packaging, sourcing, and consumer experience.
Supports identification of high-potential product opportunities and innovation pathways aligned with evolving South Korea preferences for health, wellness, convenience, sustainability, and premium experiences.
Frequently Asked Questions About This Report
Off-Premise channels accounted for the largest revenue share in 2025, while On-Premise channels are expected to be the fastest-growing segment.
Key players include Evian; S.Pellegrino; Perrier; Acqua Panna; MONTBEST; Global Deep Sea Water; SaRangHae300; SEAWANNA; VOSS; Lauretana
Rising wellness awareness is supporting demand for water-based alternatives to sugary beverages, while fast-paced urban lifestyles and widespread convenience-store and online retail access continue to favor portable formats.
Still water dominated the South Korea premium bottled water market, accounting for a 38.5% revenue share in 2025, while the functional water is expected to register the fastest growth during the forecast period.
The South Korea premium bottled water market size was valued at USD 1.0 billion in 2025 and is estimated at USD 1.1 billion for 2026.
Multi pack bottled water accounted for the largest revenue share in 2025.
The South Korea premium bottled water market is expected to grow at a CAGR of 3.6% from 2026 to 2033, reaching USD 1.4 billion by 2033.
Premium priced bottled water accounted for the largest revenue share in 2025, while ultra-premium priced bottled water are expected to be the fastest-growing segment.
PET bottles accounted for the largest revenue share in 2025, while cans are expected to be the fastest-growing segment.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


