
- Home
- »
- Next Generation Technologies
- »
-
Sports Broadcasting Technology Market Report, 2026-2033GVR Report cover

Sports Broadcasting Technology Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Solutions, Services), By Technology (Analog, Digital), By Platform (OTT, Radio, Television), By End-user (Broadcaster, Distributors), By Region, And Segment Forecasts
Market Size, 2025
$83.5BMarket Estimate, 2026
$88.3BMarket Forecast, 2033
$135.9BCAGR, 2026–2033
6.3%Sports Broadcasting Technology Market Summary
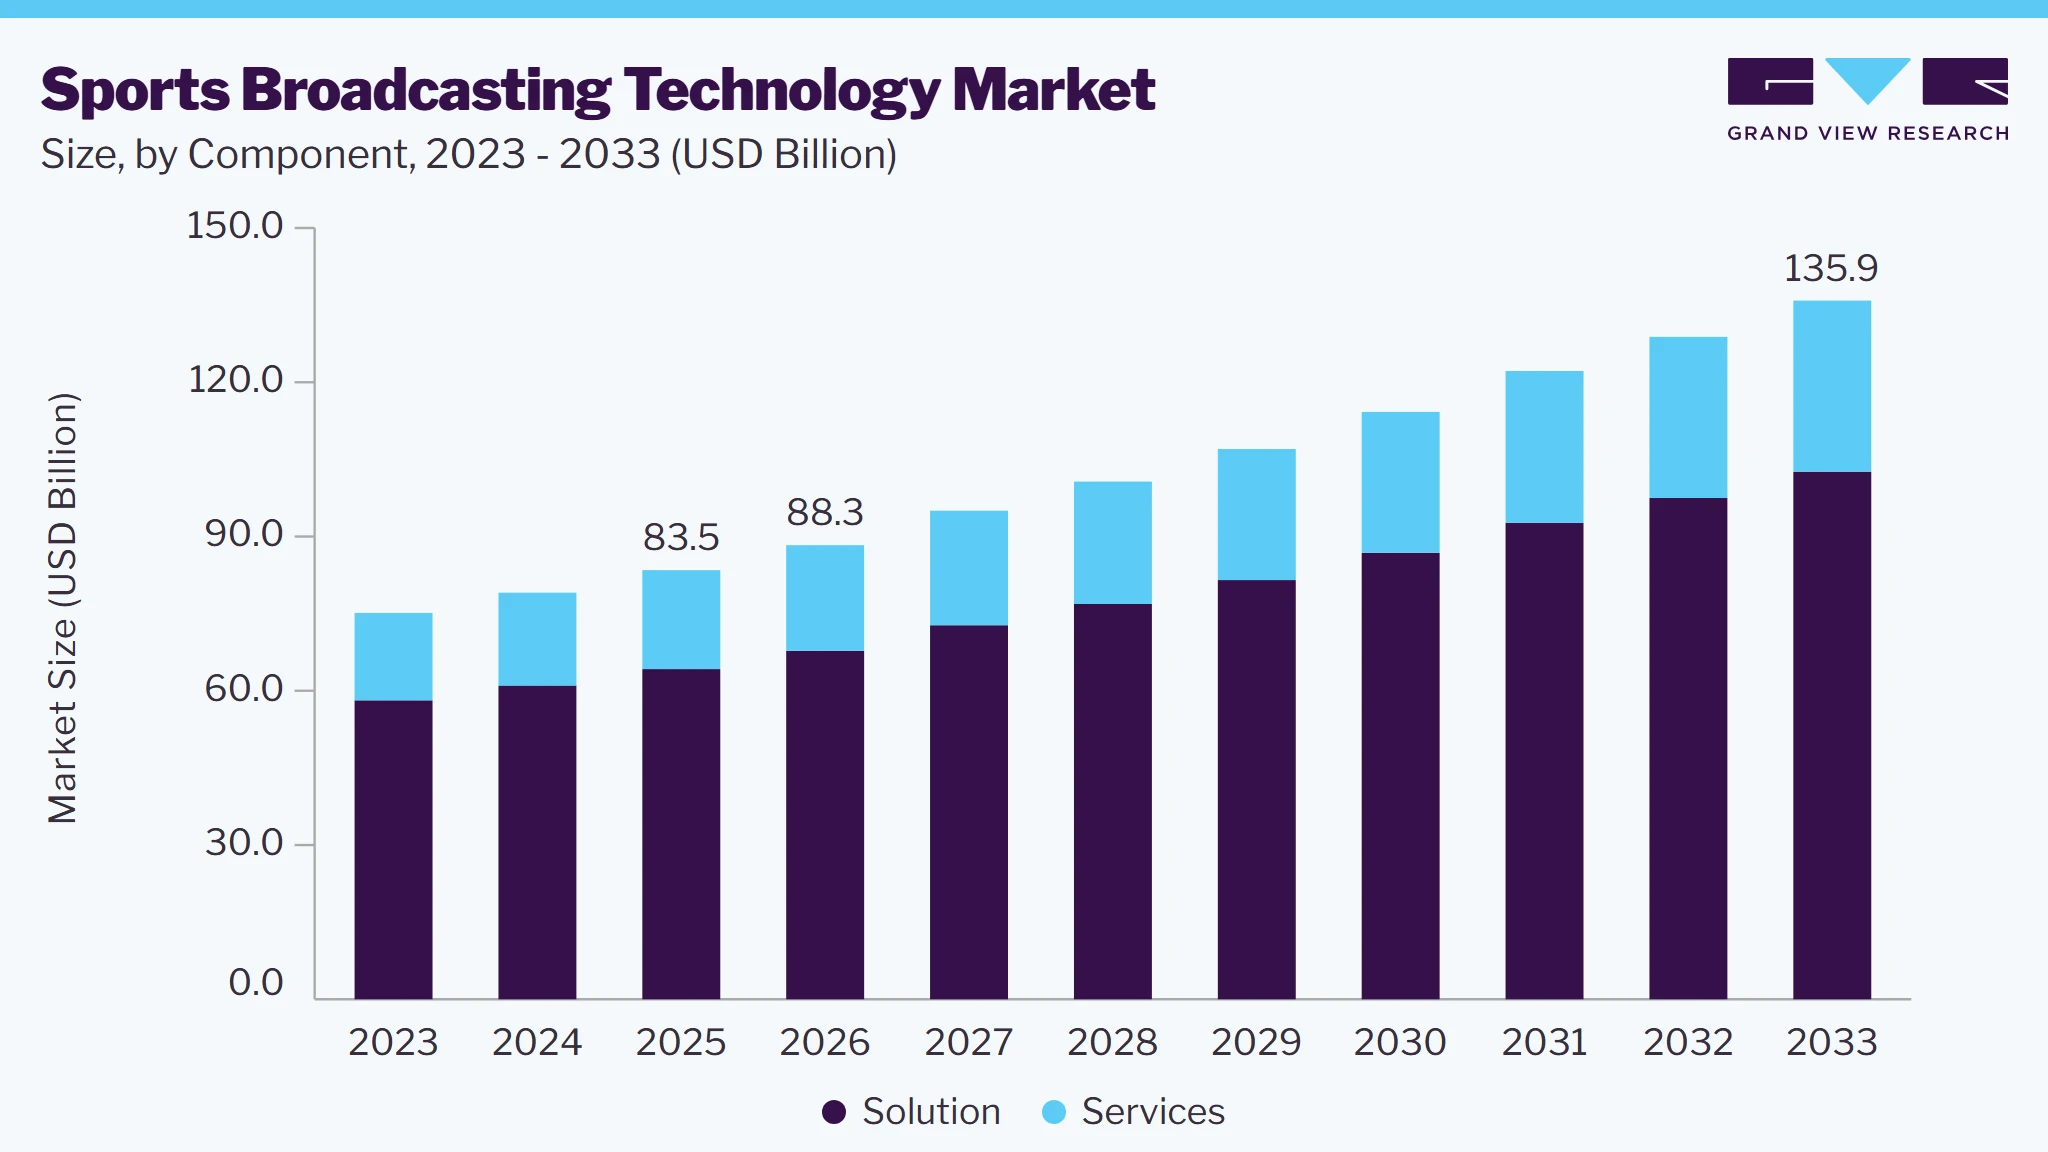
The global sports broadcasting technology market size was valued at USD 83.5 billion in 2025 and is projected to grow from USD 88.3 billion in 2026 to USD 135.9 billion by 2033, at a CAGR of 6.3% from 2026 to 2033. North America dominated the global market with the largest revenue share of 43.5% in 2025. The sports broadcasting technology market is driven by the increasing demand for high-quality live sports coverage, the growing adoption of cloud-based broadcasting solutions, and the rising investment in digital sports media platforms.
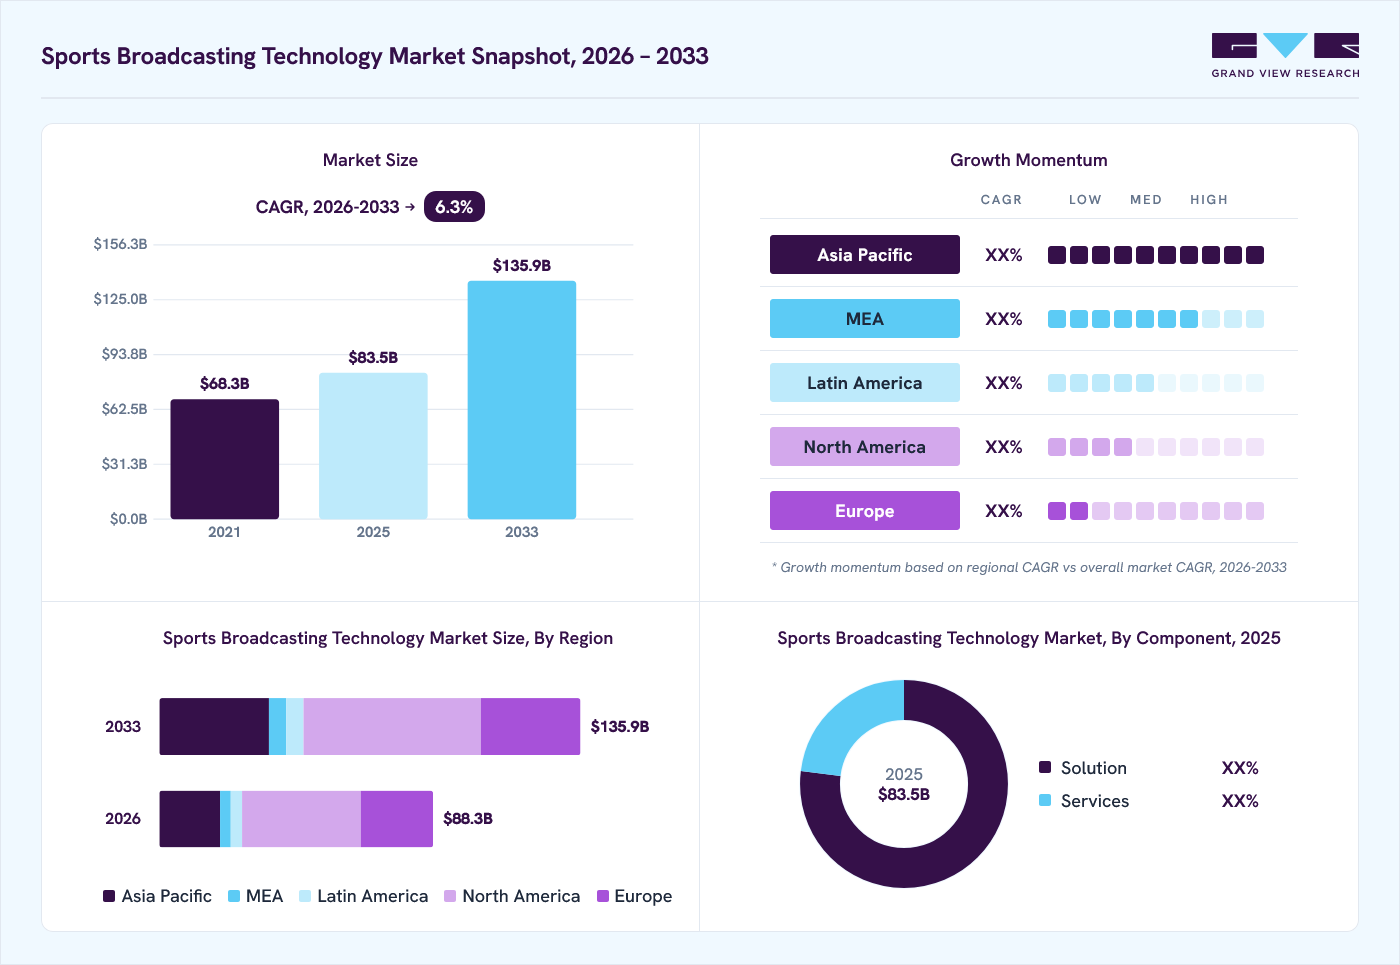 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Solutions segment dominated the market, with a share of 77.0% in 2025.
- By platform: Television segment accounted for the largest market share of 43.9% in 2025.
- By technology: Digital segment held the largest market share in 2025.
- By end use: Broadcaster segment accounted for the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (43.5% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 8.8%, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 83.5 Billion
- Estimated market size in 2026: USD 88.3 Billion
- Projected market size by 2033: USD 135.9 Billion
- CAGR (2026-2033): 6.3%
Prism AI by Grand View Research Free to tryAsk a question about the sports broadcasting technology market✓Every figure cited from GVR research Prefer the report? Download free sample →
The expanding use of advanced broadcasting technologies for live production, remote production, content management, streaming, replay analysis, and immersive fan engagement is significantly accelerating market growth. The increasing integration of artificial intelligence, ultra-high-definition (UHD) video, IP-based broadcasting infrastructure, augmented reality, virtual reality, and low-latency streaming technologies is enhancing production efficiency, improving viewer experiences, and enabling seamless multi-platform content delivery, thereby creating growth opportunities in the market.The technological implementation was expected to boost the way sports are streamed and broadcasted, which provides fans with a seamless and uninterrupted experience of watching sports in real-time. In September 2023, Rohde & Schwarz partnered with Skylo Technologies to enhance the NTN testing for seamless integration of NB-IoT protocol, ensuring 3GPP release 17 compliance and high-quality connectivity solutions.
 To learn more about this report, Download Free Sample Report
The rise of streaming platforms such as Netflix, Amazon Prime Video, and Hulu supports the growth of the market. As consumers are switching their preferences from cable to Over-The-Top (OTT) services, sports broadcasters have had to adapt and invest in new technologies to keep up. One area where this is particularly evident is the use of Augmented Reality (AR) and Virtual Reality (VR) to enhance the viewing experience. For example, AR overlays can provide real-time statistics and player information whereas, VR headsets allow fans to feel the action and experience the game from the perspective of a player or coach. Another area of growth has been the use of Artificial Intelligence (AI) and Machine Learning (ML) to analyze data in real-time and generate insights that can be used to enhance the viewing experience.
Streaming platforms have allowed sports broadcasters to experiment with new technologies, such as AR, Virtual Reality, and AI, and these technologies have enabled broadcasters to provide fans with more immersive and engaging experiences. For example, AR overlays can provide real-time statistics and player profiles. At the same time, AI plays a major role in sports broadcast technology. AI-powered cameras can track the ball and players, while machine learning algorithms can predict game outcomes based on historical data. This experience was great and provided coaches and players with valuable insights, helping them improve their performance.
Market Dynamics
The sports broadcasting technology market is experiencing strong growth, driven by increasing demand for high-quality live sports coverage, rising digital media consumption, and the rapid expansion of streaming platforms across broadcasters, sports leagues, and media organizations. Growing investments in cloud-based production, remote broadcasting, and next-generation content delivery solutions are accelerating the adoption of advanced broadcasting technologies for efficient and engaging live event coverage. The increasing use of artificial intelligence, IP-based broadcasting infrastructure, ultra-high-definition video, real-time analytics, augmented reality graphics, cloud media workflows, and low-latency streaming technologies is enhancing production efficiency, improving viewer engagement, enabling seamless multi-platform content distribution, reducing operational costs, and delivering immersive sports viewing experiences, creating significant long-term growth opportunities for the global market.
The increasing consumer preference for high-quality, immersive live sports viewing is a primary factor accelerating the adoption of advanced broadcasting technologies. Broadcasters are investing in ultra-high-definition video, high dynamic range imaging, multi-camera production, low-latency streaming, and enhanced replay capabilities to deliver superior viewing experiences across television, mobile, and digital platforms while meeting growing audience expectations for seamless, high-quality sports coverage.
The rapid expansion of global sports leagues, international tournaments, and direct-to-consumer streaming services is further encouraging investments in next-generation broadcast infrastructure. Technologies such as cloud-based production, artificial intelligence-driven camera automation, real-time graphics, and personalized content delivery enable broadcasters to improve production efficiency, enhance audience engagement, reduce operational complexity, and deliver consistent live sports experiences across multiple viewing platforms.
The deployment of modern sports broadcasting systems requires substantial investments in cameras, production equipment, IP networking infrastructure, cloud integration, software platforms, and transmission technologies. These capital-intensive requirements pose financial challenges for regional broadcasters, smaller production companies, and emerging sports organizations, which often operate with limited technology budgets and constrained infrastructure modernization plans.
In the initial deployment, organizations must allocate significant resources for equipment upgrades, software licensing, cybersecurity, workforce training, and ongoing system maintenance. Rapid technological advancements further shorten equipment replacement cycles, increasing long-term ownership costs. These financial constraints can delay modernization initiatives, limit technology adoption, and reduce the pace of digital transformation across sports broadcasting operations.
Artificial intelligence is creating new opportunities by enabling automated camera operation, intelligent video production, real-time highlight generation, speech recognition, and metadata tagging throughout live sports broadcasts. These capabilities allow broadcasters to improve production accuracy, accelerate content creation, and deliver personalized viewing experiences while optimizing resource utilization across both large-scale sporting events and regional competitions.
The increasing availability of cloud-native broadcasting platforms combined with AI-powered analytics is enabling remote production workflows, automated content localization, and customized advertising delivery. Broadcasters can efficiently distribute live sports content across multiple digital channels while reducing production complexity and operational costs. This technological evolution supports wider event coverage, faster content delivery, and enhanced audience engagement for diverse sports properties worldwide.
Market Concentration & Characteristics
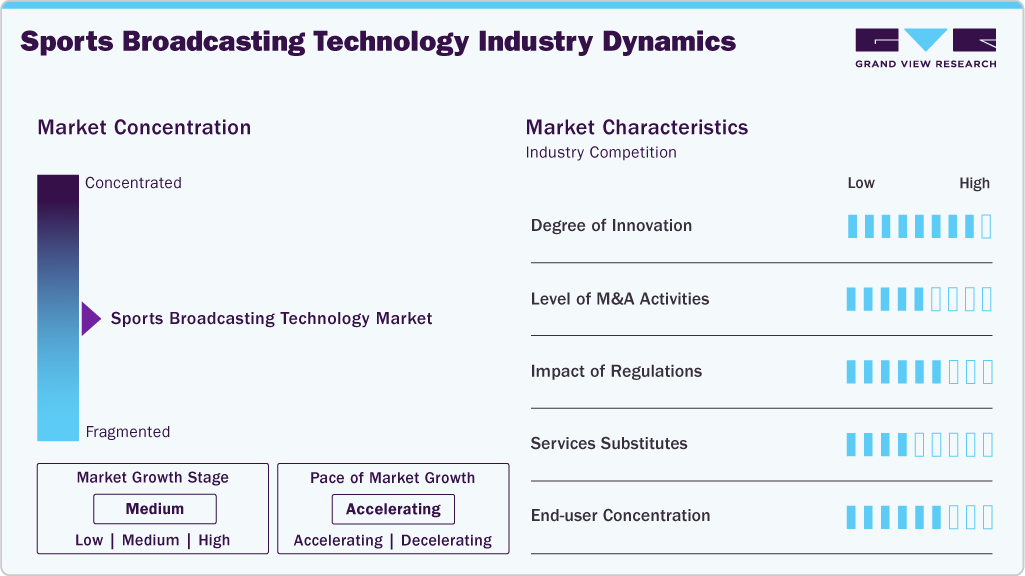
The sports broadcasting technology market is moderately fragmented, with leading broadcast equipment manufacturers, media technology providers, cloud platform vendors, streaming solution providers, software developers, and systems integrators competing across live sports production, content management, remote broadcasting, replay systems, media asset management, and multi-platform content distribution. Rising investments in cloud broadcasting, increasing demand for immersive live sports experiences, and expanding adoption of digital streaming platforms are driving market expansion. Companies are strengthening their competitive positions through strategic partnerships, technology acquisitions, and continuous investments in artificial intelligence, IP-based broadcasting infrastructure, cloud production platforms, ultra-high-definition video technologies, and low-latency streaming solutions.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation, supported by rapid advancements in artificial intelligence, cloud-native production workflows, IP-based media transport, augmented reality graphics, virtual production technologies, and real-time analytics platforms. Merger and acquisition activity remains moderate as companies expand digital broadcasting capabilities and strengthen end-to-end media technology portfolios. Regulatory impact is significant due to broadcasting standards, media rights regulations, spectrum management policies, copyright compliance requirements, and data privacy frameworks. The threat of substitutes remains low because conventional broadcasting infrastructure cannot replicate the scalability, production efficiency, low-latency delivery, and immersive viewing capabilities offered by advanced sports broadcasting technologies for premium live sports coverage.
Analyst Perspective
The sports broadcasting technology market is expanding, driven by rising investments in digital broadcasting platforms, rapid advances in cloud-based production technologies, and the growing adoption of artificial intelligence, IP-based broadcasting, and low-latency streaming solutions for live sports coverage. The expanding implementation of advanced production automation, real-time graphics, ultra-high-definition video, remote production workflows, and cloud-connected media management platforms is improving broadcast efficiency, operational flexibility, content quality, and viewer engagement. Organizations increasingly prioritize immersive viewing experiences, scalable content delivery, and seamless multi-platform distribution to meet evolving audience expectations and media consumption trends. Technology providers are positioned to capitalize on emerging opportunities, thereby reinforcing long-term market expansion and sustainable revenue generation across the global sports broadcasting ecosystem.
Component Insights
Based on component, the solutions segment led the market with the largest revenue share of 77.0% in 2025 and is expected to grow at a considerable CAGR over the forecast period. The solutions segment includes hardware and software used in sports broadcasting activities. While sports broadcasting continues to evolve, the demand for innovative and efficient solution components is expected to increase, leading to further growth in the market as new technologies such as AI and ML result. They have opened up new ways to deliver high-quality and personalized experiences. For example, AI-powered systems can analyze player movements to provide commentators and analysts with real-time insights, enhancing the overall viewing experience.
Technology Insights
Based on technology, the digital segment dominated the market with the largest revenue share of 77.0% in 2025. With the upward push of online streaming structures and social media, sports fans now have access to an exceptional amount of sports content material, inclusive of game highlights and evaluations. As a result, sports leagues and broadcasters are investing heavily in new technology to provide consumers with better quality real-time content material. From digital and augmented reality to superior information analytics and cloud-based video processing, the market is constantly evolving and pushing the boundaries.
Analog technology segment is anticipated to witness a significant CAGR in the forecast period from 2023 to 2030. Many broadcasters have diagnosed the cost of incorporating analog technology into their workflows, offering them numerous advantages, such as progressed photo niches, decreased latency, and improved reliability. As a result, the market is showing high adoption of analog technology in sports activities broadcasting.
Platform Insights
Based on platform, the television segment accounted for the largest market share of 43.9% in 2025. With the development of premium and ultra-high-quality displays, viewers can have an immersive experience while watching sporting events. Besides, advances in camera technology have allowed fans to understand the game better. As technology continues to improve, key players in the market are providing new solutions to give the game a look that will boost fans worldwide.
The OTT platform segment is anticipated to witness a steady CAGR over the forecast period. OTT events have enabled sports organizations to reach new audiences and expand their global reach. With the rise of on-demand streaming services, fans can watch their favorite sports live or on-demand at their convenience. Fans have additional options to acquire sporting information due to the availability of viewing sports on devices such as smart TVs, which has created new revenue sources for sports leagues.
End-user Insights
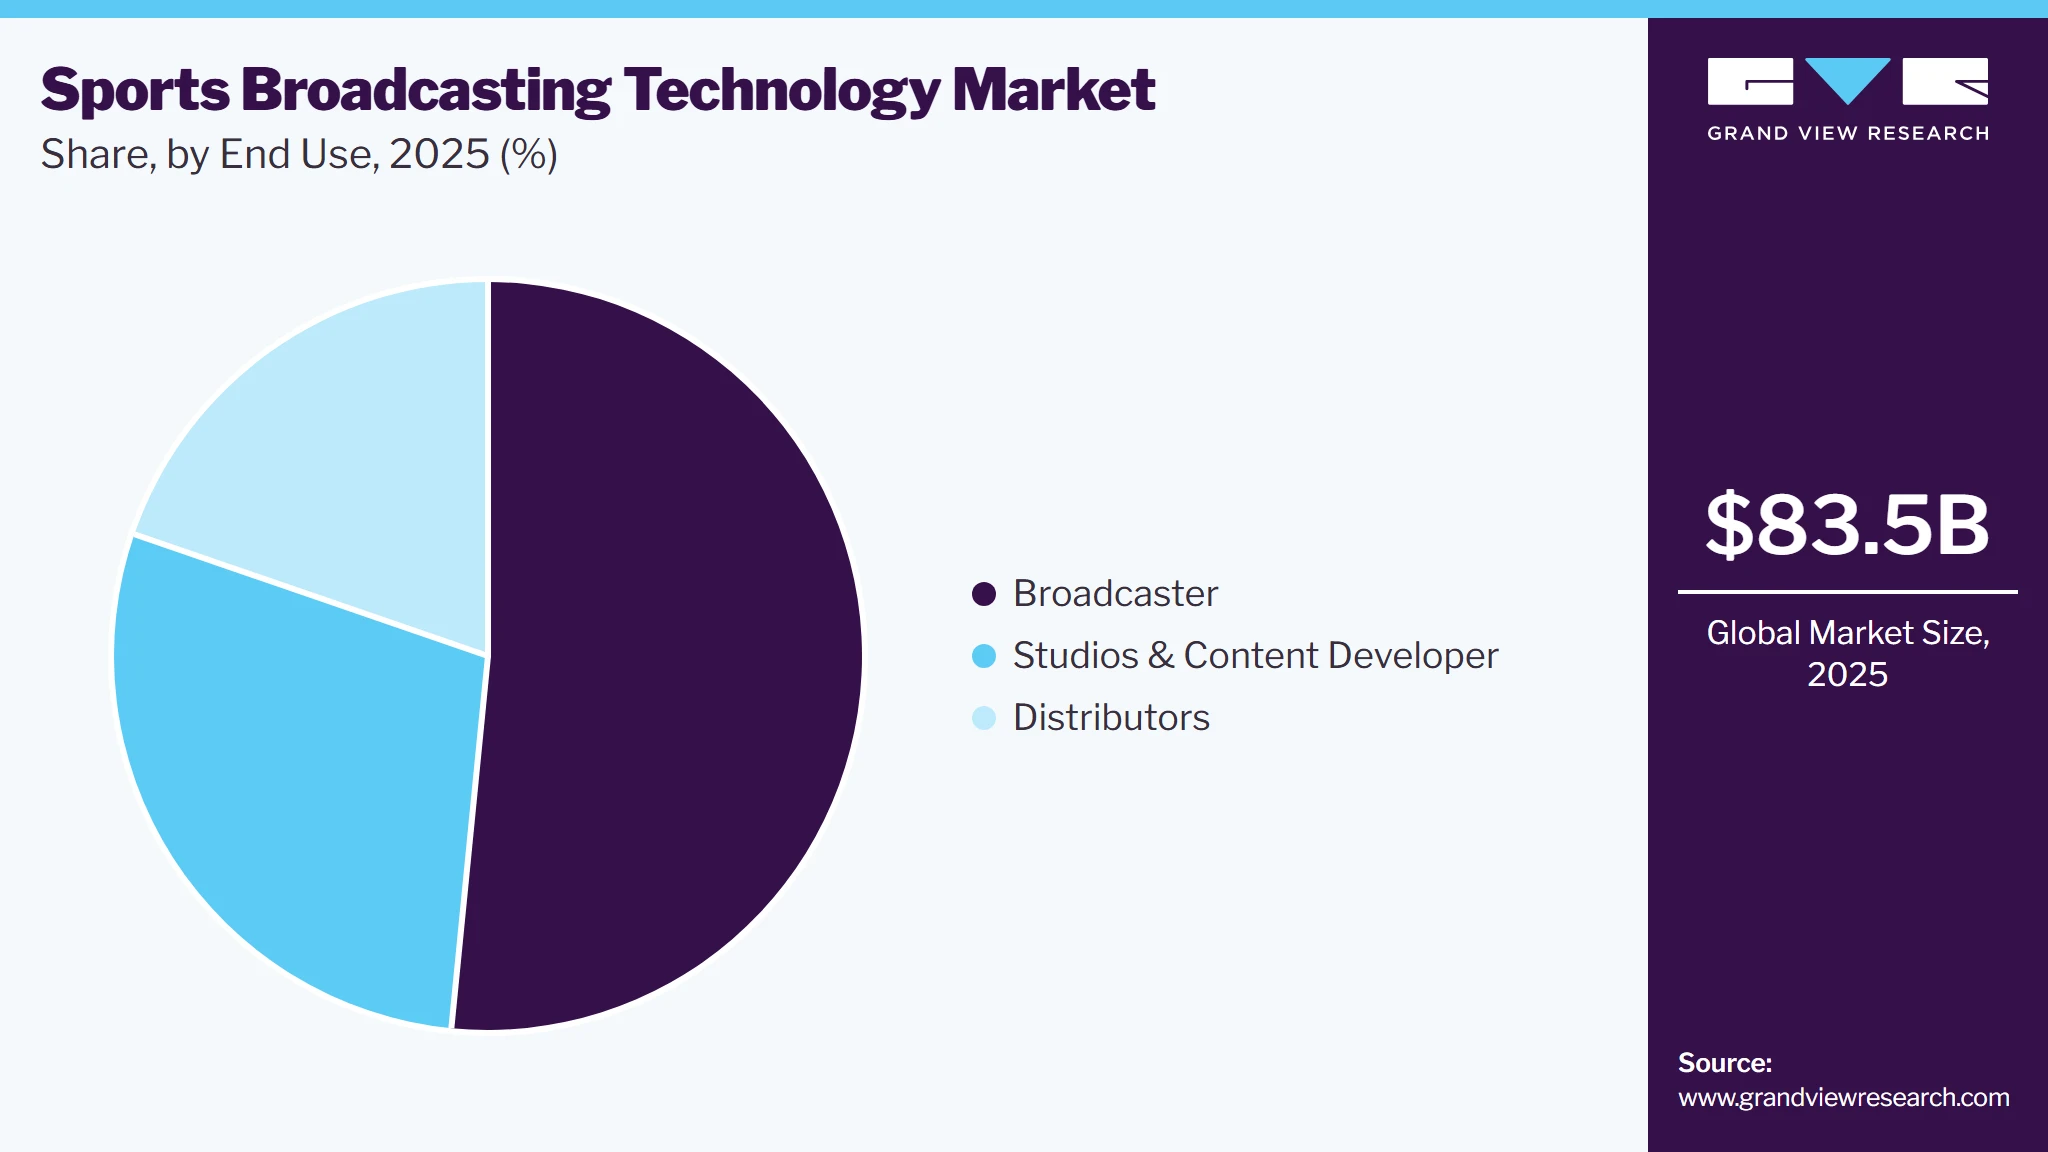
Based on end use, the broadcaster segment dominated the market with a revenue share of 51.6% in 2025. With the growing need for sports activities, content broadcasters are investing heavily in new technology and gadgets to meet the expectations of audiences. This high demand causes a surge in demand for high-end broadcasting cameras, video production software, and other broadcasting equipment that enhance the viewing experience.
 To learn more about this report, Download Free Sample Report
In addition, broadcasters have been able to leverage social media and different digital systems to engage with enthusiasts and promote their content. As a result, the marketplace has experienced a massive increase in recent years.
Regional Insights
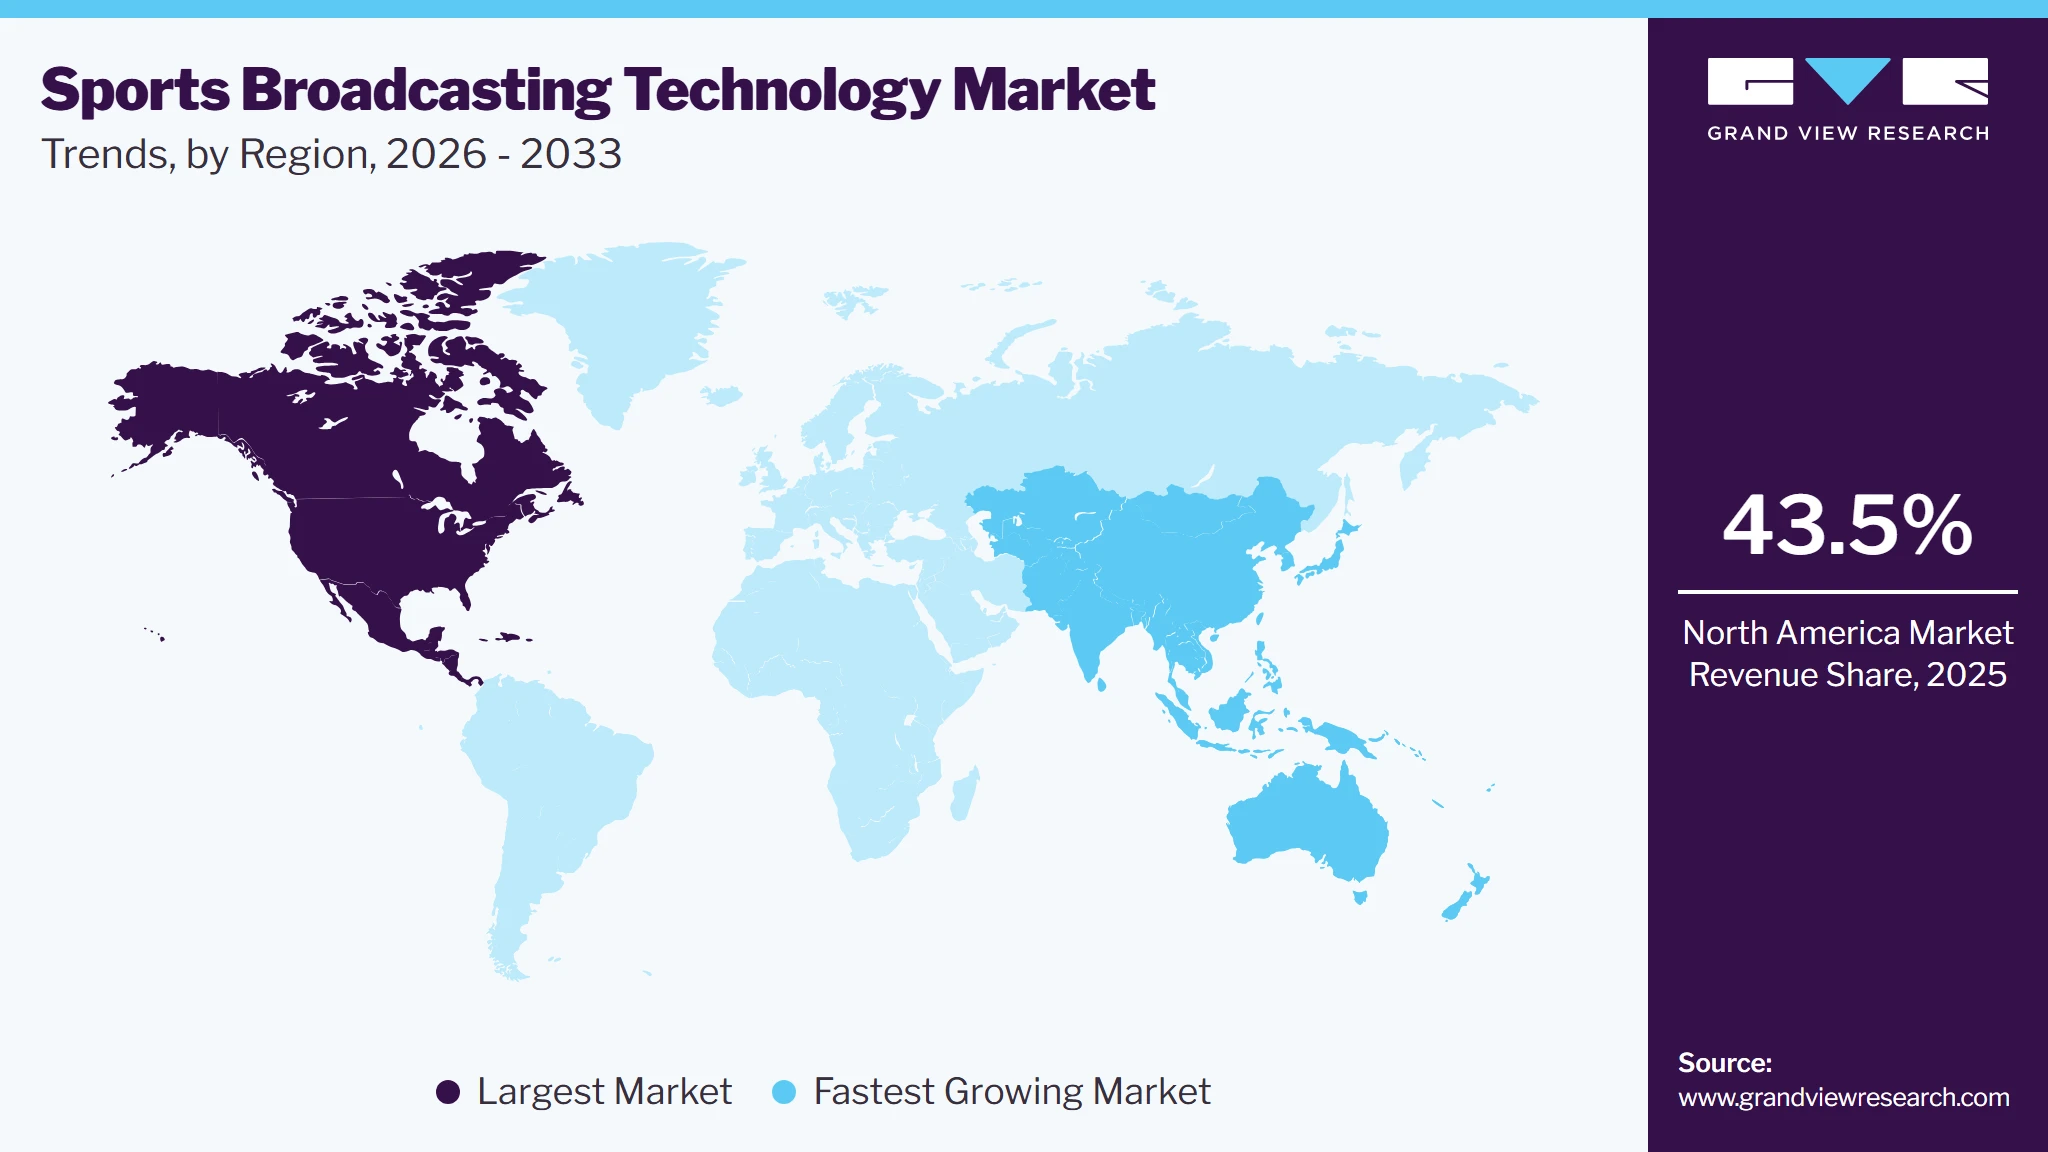
North America dominated sports broadcasting technology market with the largest revenue share of 43.5% in 2025. This may be attributed to the increasing popularity of diverse sports occasions, advancements in broadcasting technology, and the rising demand for tremendous sports content material. The marketplace is also being driven by the emergence of new sports activity leagues and expansion of the current ones, as well as the growing adoption of virtual systems for sports broadcasting. The key developments and elements using the growth of the North American marketplace include the growing call for customized and interactive sports content material, growing reputation of online streaming offerings, and rising adoption of virtual and augmented reality technologies. In addition, the market is being propelled through increasing investments in sports activities', broadcasting infrastructure, and growing demand for amazing sports activities' content across numerous platforms, which include TV, cellular gadgets, and social media.
 To learn more about this report, Download Free Sample Report
U.S. Sports Broadcasting Technology Market Trends
The sports broadcasting technology market in the U.S. held the largest share in the North America region in 2025.
Asia Pacific Sports Broadcasting Technology Market Trends
Asia Pacific is anticipated to witness the fastest CAGR over the forecast period. The area's widespread use of new technology is a factor in the rapid rise of the market. Countries like South Korea, Japan, and China were at the vanguard of this technological revolution, boasting strong infrastructures that have paved the manner for the proliferation of the market. The emergence of recent sports leagues inside the area is using the call for smart stadium infrastructure to compete with international leagues and create new revenue streams.
Key Sports Broadcasting Technology Company Insights
Major players in the market focus on technological development, new product launches, and mergers & acquisitions to strengthen the market position. Strategic collaborations allow these companies to strengthen their product portfolio, providing a broader customer base and a more comprehensive suite of solutions and services.
In October 2023, NEC Corporation collaborated with Freshwave for the Open RAN project to deliver next-generation multi-operator neutral host small cell solutions for high-traffic areas. Project NAVIGATE aims to design, deploy, test, and validate a blueprint for deploying open and sharable, public mobile 4G and 5G capacity in High-Density Deployment (HDD) environments.
Key Sports Broadcasting Technology Companies
The following key companies have been profiled for this study on the sports broadcasting technology market.
-
Broadcast Electronics (Elenos S.r.L.)
-
Belden Inc.
-
ETL System Ltd.
-
NEC Corporation
-
Rohde & Schwarz
-
AvL Technologies
-
OMB Broadcast
-
Global Invacom
-
Hangzhou HAOXUN Technologies Co. Ltd.
-
VSN Video Stream Networks S.L.
-
IBM Corporation
-
Sportradar AG
-
Muvi
-
Evertz Microsystems Ltd.
-
NEP Group Inc.
-
ESPN Sports Media Ltd.
-
NBC Universal
-
EasyBroadcast
-
Orange
-
Staige GmbH
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Staige GmbH, EasyBroadcast, Muvi)
- Focus on expanding integrated sports broadcasting ecosystems through cloud, IP, AI, and streaming partnerships.
- Invest heavily in advanced production infrastructure to deliver scalable, enterprise-grade live sports broadcasting solutions.
- Strong global presence, established broadcaster relationships, and advanced production technologies support market leadership.
- Ability to provide secure, high-performance, end-to-end broadcasting solutions for premium live sports events.
- Dependence on legacy broadcasting infrastructure can slow the adoption of emerging cloud-native production technologies.
- Large organizational structures may reduce operational agility and delay innovation compared to specialized technology providers.
Emerging Players (NEC Corporation, Rohde & Schwarz, Evertz Microsystems Ltd.)
- Emerging players focus on expanding cloud-native sports broadcasting platforms through AI, OTT, and strategic technology partnerships.
- Invest in agile product innovation to deliver scalable, cost-effective live sports production solutions.
- Strong software innovation capabilities enable flexible, cloud-based broadcasting solutions for diverse sports organizations.
- Ability to deliver AI-driven, cost-efficient, and rapidly deployable broadcasting technologies across digital platforms.
- Limited global presence and a smaller customer base limit opportunities for large-scale sports broadcasting projects.
- Resource constraints may delay international expansion and advanced product development compared to established competitors.
Sports Broadcasting Technology Market Report Scope
Report Attribute
Details
Market size in 2025
USD 83.5 billion
Estimated market size in 2026
USD 88.3 billion
Projected market size by 2033
USD 135.9 billion
Growth rate
CAGR of 6.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, technology, platform, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; Australia; South Korea; Brazil; Argentina; UAE; Saudi Arabia; South Africa
Key companies profiled
Broadcast Electronics (Elenos S.R.L.); Belden Inc.; ETL Systems Ltd.; NEC Corporation; Rohde & Schwarz; AvL Technologies; OMB Broadcast; Global Invacom; Hangzhou HAOXUN Technologies Co. Ltd.; VSN Video Stream Networks S.L.; IBM Corporation; Sportradar AG; Muvi; Evertz Microsystems Ltd.; NEP Group Inc.; ESPN Sports Media Ltd.; NBC Universal; EasyBroadcast; Orange; Staige GmbH
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Sports Broadcasting Technology Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global sports broadcasting technology market report based on component, technology, platform, end-user, and region:
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Solutions
-
Software
-
Hardware
-
Dish Antennas
-
Amplifiers
-
Switches
-
Encoders
-
Video Servers
-
Transmitters/Repeaters
-
Modulators
-
Others
-
-
-
Services
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Analog
-
Digital
-
-
Platform Outlook (Revenue, USD Billion, 2021 - 2033)
-
OTT
-
Radio
-
Television
-
Satellite Direct-to-Home
-
Digital Terrestrial Television (DTT)
-
Cable Television
-
IPTV
-
-
-
End-user Outlook (Revenue, USD Billion, 2021 - 2033)
-
Broadcaster
-
Studios & Content Developer
-
Distributors
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The sports broadcasting technology market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each sports broadcasting technology segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Solutions
Revenue is generated through software platforms, production systems, broadcast automation tools, media asset management, graphics solutions, cloud broadcasting platforms, and content delivery technologies used for live sports production, transmission, and multi-platform distribution. This segment is driven by increasing demand for efficient, high-quality, and scalable broadcasting workflows.
Services
Revenue is captured through consulting, system integration, installation, maintenance, managed services, cloud migration, technical support, and broadcast workflow optimization services. This segment is propelled by growing adoption of advanced broadcasting infrastructure and increasing demand for seamless deployment, operational efficiency, and technology upgrades.
Segment - Technology
Revenue capture definition
Analog
Revenue is generated through analog broadcasting equipment and legacy transmission systems utilized by broadcasters supporting conventional sports content production and distribution. This segment is sustained by continued operation of existing infrastructure in selected regions where digital migration remains gradual.
Digital
Revenue is captured through digital broadcasting technologies including IP-based production, cloud broadcasting, UHD transmission, AI-enabled production systems, and low-latency streaming platforms. This segment is driven by increasing adoption of high-quality digital broadcasting, remote production workflows, and multi-platform sports content delivery.
Segment - Platform
Revenue capture definition
OTT
Revenue is generated through over-the-top streaming platforms delivering live sports events, on-demand content, personalized viewing experiences, and interactive broadcasting services across connected devices. This segment is driven by increasing consumer preference for digital streaming, flexible viewing, and direct-to-consumer sports content.
Radio
Revenue is captured through radio broadcasting technologies supporting live sports commentary, event coverage, match analysis, and sports news programming across terrestrial and digital radio networks. This segment is supported by consistent listener demand for accessible, real-time sports coverage.
Television
Revenue is generated through television broadcasting technologies enabling live sports production, premium event coverage, replay systems, graphics integration, and high-definition content distribution across cable, satellite, and terrestrial television networks. This segment is driven by continued demand for large-scale live sports broadcasting.
Segment - End Use
Revenue capture definition
Broadcaster
Revenue is generated through broadcasting organizations utilizing advanced production, transmission, automation, and content management technologies to deliver live sports events across television, radio, and digital platforms. This segment is driven by increasing investments in high-quality, multi-platform sports broadcasting capabilities.
Studios & Content Developer
Revenue is captured through production studios and content developers creating live sports programming, highlight packages, virtual productions, and digital sports content using advanced broadcasting technologies. This segment is propelled by rising demand for engaging sports content across broadcast and streaming platforms.
Distributors
Revenue is generated through distributors utilizing content delivery, transmission, media management, and distribution technologies to provide live sports programming across cable networks, satellite services, OTT platforms, and digital ecosystems. This segment is driven by expanding multi-channel sports content distribution and growing audience reach.
Estimation Model
Layer Name
Key Question
Description
Sports Media Adoption Layer
Who are the potential adopters?
Identifies the primary organizations adopting sports broadcasting technologies, including television broadcasters, sports leagues, streaming platforms, production companies, media organizations, sports federations, and digital content providers seeking high-quality live production, multi-platform distribution, immersive viewer experiences, audience engagement, and efficient broadcast operations.
Broadcast Technology Enablement Layer
Who can deploy sports broadcasting solutions?
Deployment depends on the availability of advanced production equipment, IP-based broadcasting infrastructure, cloud production platforms, media asset management systems, AI-powered production tools, content delivery networks, systems integration expertise, reliable network connectivity, and scalable streaming infrastructure to support efficient live sports broadcasting operations.
Broadcast Application Layer
Where are sports broadcasting solutions actively utilized?
Sports broadcasting technologies are deployed across live sporting events, professional leagues, international tournaments, collegiate competitions, esports events, sports news production, studio programming, highlight creation, digital streaming platforms, and multi-screen content distribution, supporting real-time coverage, audience engagement, content management, and interactive viewing experiences.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through broadcast equipment sales, software licensing, cloud production services, content management platforms, streaming solutions, system integration, maintenance services, consulting, managed broadcasting services, technology licensing, subscription platforms, advertising enablement, and recurring revenue from digital broadcasting and content delivery services.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cloud-Based Sports Production Workflow Assessment
Conducted detailed evaluation of cloud-based sports production workflows across broadcasters, sports leagues, media companies, and streaming platforms, integrating remote production, IP-based broadcasting, media asset management, and AI-enabled automation to improve live event production efficiency.
Improves production efficiency, reduces operational costs, enables scalable broadcasting, and strengthens live event delivery.
AI-Enabled Live Sports Broadcasting & Viewer Engagement Strategy
Assessed implementation of artificial intelligence-powered production automation, real-time highlight generation, player tracking, audience analytics, personalized content delivery, and immersive broadcast technologies to enhance live sports coverage, operational performance, and viewer engagement across digital platforms.
Enhances viewer engagement, improves broadcast quality, enables personalized experiences, and supports intelligent production workflows.
Multi-Platform Sports Content Distribution & Low-Latency Streaming Strategy
Evaluated deployment of multi-platform sports content distribution solutions across television, OTT platforms, mobile applications, and digital channels, integrating low-latency streaming, adaptive bitrate delivery, cloud infrastructure, and content management technologies for seamless audience experiences.
Expands audience reach, improves streaming reliability, enhances content accessibility, and supports seamless multi-platform distribution.
Frequently Asked Questions About This Report
North America dominated with a revenue share of 43.5% in 2025.
The global sports broadcasting technology market is expected to grow at a CAGR of 6.3% from 2026 to 2033, reaching USD 135.9 billion by 2033.
The rapid technological evolvement in sports broadcasting and streaming is set to undergo with the introduction of 5G technology. The technological implementation was expected to boost the way sports are streamed and broadcast, which provides fans with a seamless and uninterrupted experience of watching sports in real time.
The Asia Pacific is the fastest-growing region with a CAGR of over 8% from 2026 to 2033.
The solution segment dominated with a 77.0% revenue share in 2025.
The television segment dominated the market with a share of 43.9% in 2025.
The broadcaster segment accounted for the largest share, with 51.6% of revenue in 2025.
The global sports broadcasting technology market size was valued at USD 83.5 billion in 2025 and is estimated at USD 88.3 billion for 2026.
Some key players operating in the sports broadcasting technology market include Broadcast Electronics (Elenos S.R.L.); Belden Inc.; ETL Systems Ltd.; NEC Corporation; Rohde & Schwarz; AvL Technologies; OMB Broadcast; Global Invacom; Hangzhou HAOXUN Technologies Co. Ltd.; VSN Video Stream Networks S.L.; IBM Corporation; Sportradar AG; Muvi; Evertz Microsystems Ltd.; NEP Group Inc.; ESPN Sports Media Ltd.; NBC Universal; EasyBroadcast; Orange; Staige GmbH, among others.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


