
- Home
- »
- Medical Devices
- »
-
Sterile Injectable Contract Manufacturing Market Report, 2026-2033GVR Report cover

Sterile Injectable Contract Manufacturing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Molecule (Small Molecule, Large Molecule), By Product, By Service, By Therapeutic Area, By Route of Administration, By End Use, By Region, and Segment Forecasts
Market Size, 2025
$24.5BMarket Estimate, 2026
$26.9BMarket Forecast, 2033
$57.2BCAGR, 2026–2033
11.3%Sterile Injectable Contract Manufacturing Market Summary
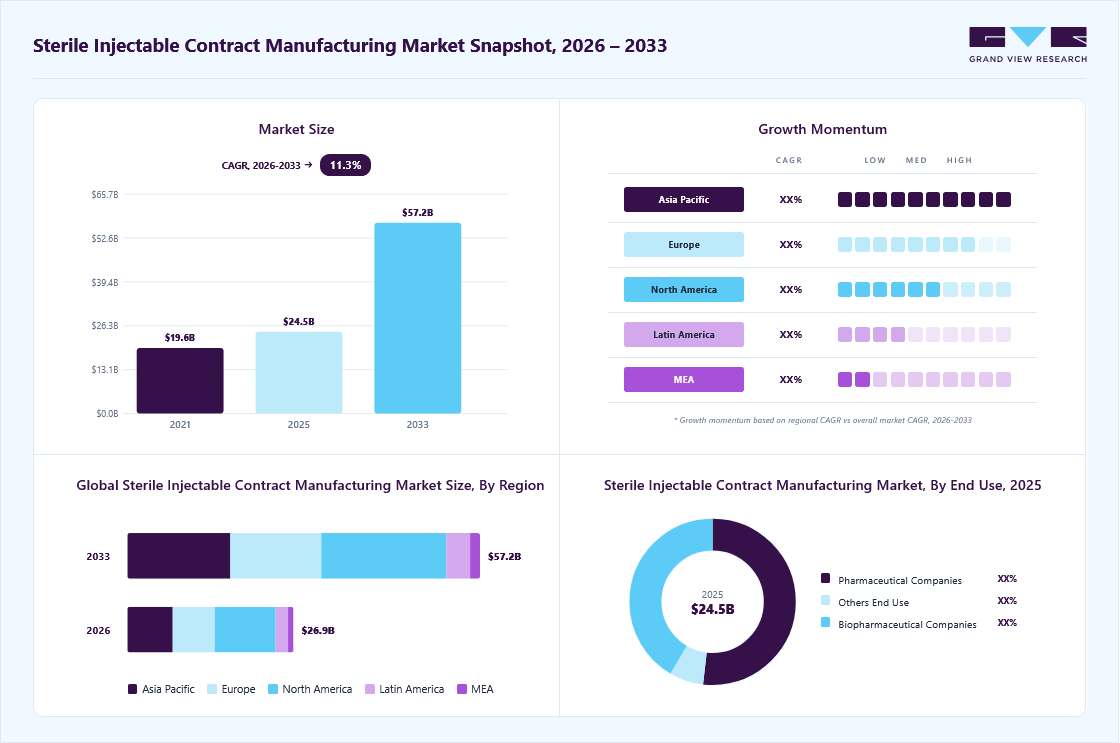
The global sterile injectable contract manufacturing market size was valued at USD 24.5 billion in 2025 and is projected to grow from USD 26.9 billion in 2026 to USD 57.2 billion by 2033, at a CAGR of 11.3% from 2026 to 2033. The North America held the largest share of 36.4% of the global market in 2025. The growth of the market is due to the increasing demand for biologics and biosimilars, along with the outsourcing trend among pharmaceutical companies seeking to reduce costs and enhance efficiency.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By molecule: Large molecule segment held the largest share of 61.16% in 2025.
- By product: Finished drug product segment held the largest share in 2025.
- By therapeutic area: CNS disease segment is anticipated to grow at the fastest CAGR from 2026 to 2033.
Regional Highlights
- Largest regional market: North America (36.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. led the North America market in 2025.
Market Size & Forecast
- Market size in 2025: USD 24.5 Billion
- Estimated market size in 2026: USD 26.9 Billion
- Projected market size by 2033: USD 57.2 Billion
- CAGR (2026-2033): 11.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, the rising prevalence of chronic illnesses, coupled with the quicker approval timelines for sterile injectables compared to other drug types, is further driving the demand for injectable formulations. The growing trend of outsourcing in the pharmaceutical industry is driving market growth. Several companies, particularly small to mid-sized firms, are increasingly seeking contract manufacturing organizations (CMOs) to reduce operational costs, enhance efficiency, and focus on their core competencies. By outsourcing sterile injectable production, these companies can leverage the expertise and advanced technologies of specialized manufacturers, thereby reducing time-to-market for new products.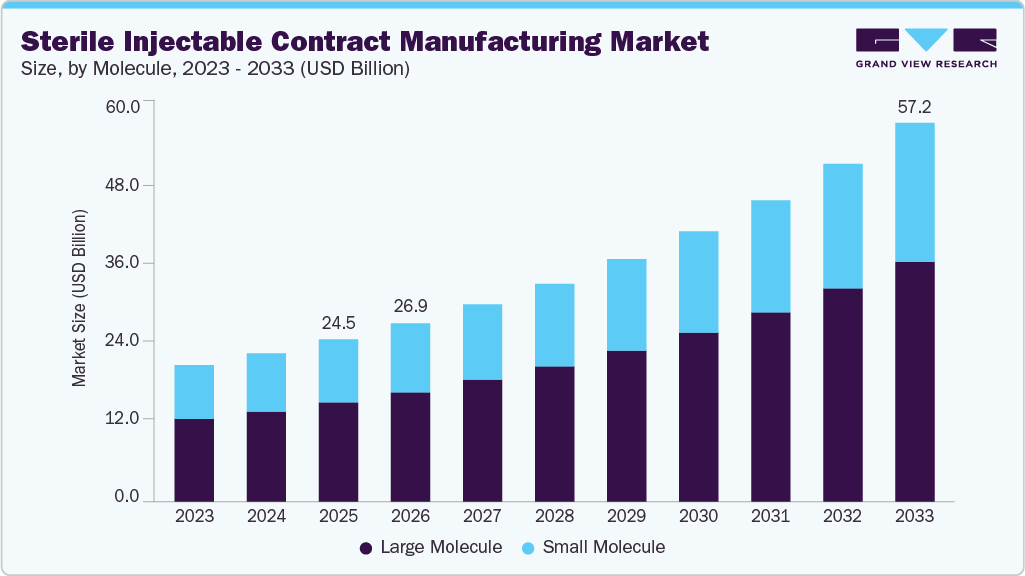 To learn more about this report, Download Free Sample Report
In addition, growing investments in pharmaceutical R&D activities are also driving the demand in the market. Companies are prioritizing innovation to develop new therapies, particularly in the sterile injectable segment. Thus, increased investment has accelerated the pipeline of injectable products, further meeting the needs of patients with chronic illnesses. Therefore, as R&D efforts rise, demand for sterile injectables is projected to grow.
Technological advancements in sterile manufacturing processes have enhanced production capabilities and efficiency. Innovations such as single-use systems, automation, and advanced containment technologies are making it easier to produce high-quality sterile injectables while minimizing contamination risks. These advancements have not only enhanced the safety and reliability of the manufacturing process but also allowed for greater customization and quicker turnaround times for clients. As companies increasingly seek to differentiate their products and optimize manufacturing operations, the integration of cutting-edge technologies into contract manufacturing services will remain a key driver of the market.
Opportunity Analysis
The market for sterile injectable CMOs offers significant scope for growth due to the rapid expansion of the biological sector, the rise in complex formulations, and the growing trend towards outsourcing in pharma and biotech firms. The drug developers' focus on speeding up development and cutting costs ultimately leads them to outsource production to CMOs, given the specialized capabilities required to manufacture such drugs, like aseptic fill-finish, lyophilization, or HPAPIs. Simultaneously, as the number of drugs in the pipeline increases, including monoclonal antibodies, biosimilars, and injectable drugs for oncology and other diseases, the demand for CMOs is expected to grow notably. In addition, the trend toward user-friendly dosage forms is boosting demand for CMO services.
The CMOs are likely to experience numerous growth opportunities in emerging markets as a result of cheaper manufacturing costs, better regulatory practices, and more investment in production infrastructure for pharmaceuticals. Simultaneously, increased regulatory demands have led companies to seek reliable contract manufacturers with strong compliance histories, technical capabilities, and robust quality control processes. The capacity limitations of sterile manufacturing plants, especially for highly valuable biologics and potent products, are driving investments in additional capacity through advanced technologies. The single-use technologies, automation through robotics, and isolators for aseptic fill and finish provide manufacturers with the ability to produce high-quality products and scale their manufacturing efficiently and economically. With the increasing complexity of injectable drugs and the flexibility required within the supply chain, CMOs can play an important role in this industry moving forward.
Impact of U.S. Tariffs on the Sterile Injectable Contract Manufacturing Market
The introduction of the tariffs by the U.S. on pharmaceutical raw material, packaging, and other components needed for sterile injectable manufacturing has had a considerable effect on the sterile injectable contract manufacturing organizations (CMOs) market. Higher tariffs on APIs, excipients, glass vials, stoppers, and special equipment used during the sterile injectable manufacturing process have driven up the cost of production, inducing the need for reevaluation of procurement and supplier networks. The contract manufacturing organizations rely heavily on cross-border procurement networks, where cost variations pose significant challenges. To offset such challenges, the pharmaceutical industry is diversifying its supply base.
Moreover, tariffs have led to short-term disruptions in the procurement process, stock management, and lead times, particularly for crucial sterile ingredients whose suppliers are limited globally. CMOs running manufacturing plants in the U.S. have an edge in terms of location, as clients increasingly prefer local production to avoid additional costs associated with duties and ensure supply. Meanwhile, firms have been developing strategies such as backward integration and business relationships to maintain access to materials while keeping prices stable.
Although tariffs have added layers of complexity, they have facilitated the process of developing resilient supply chains and geographic diversity. The firms possessing flexibility in their manufacturing operations, regulatory compliance, and localization capacity can benefit from changing preferences among clients. Thus, even if tariffs have imposed a challenge in the short run, they have created structural changes that will help CMOs in the long term.
Technological Advancements
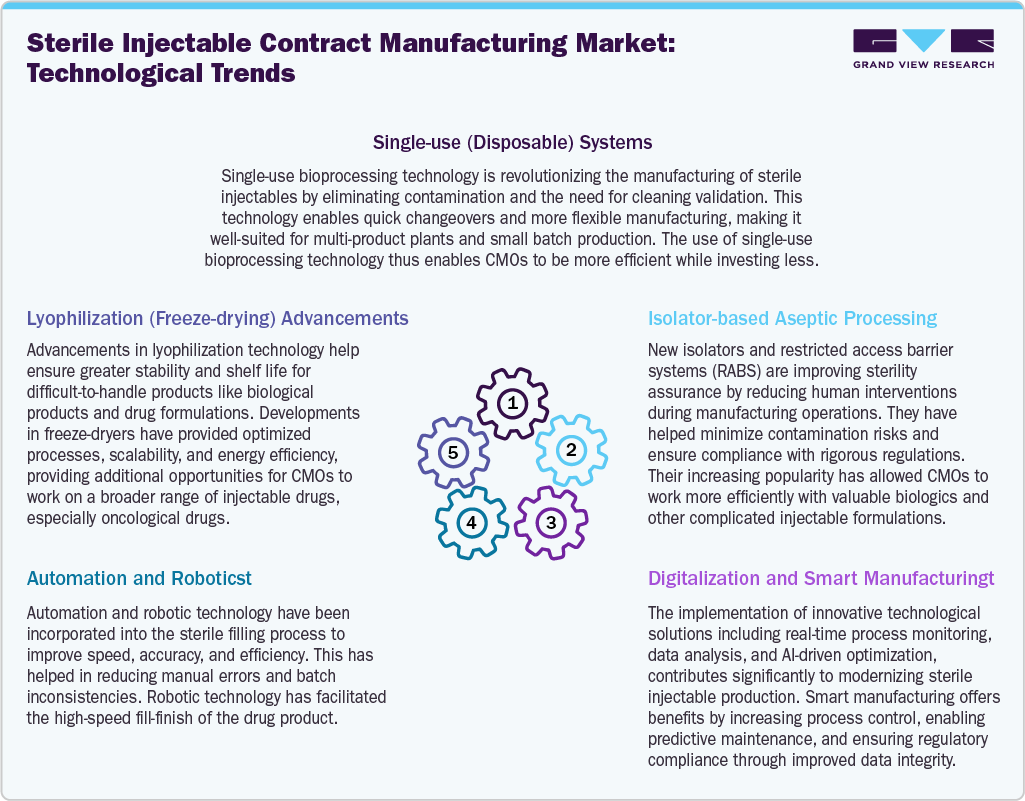
The technology landscape in the sterile injectables CMOs market is marked by continuous innovation and integration of advanced technologies across manufacturing, packaging, storage, and quality assurance. These technologies enhance efficiency and product quality while ensuring compliance with regulatory standards, ultimately contributing to the growth and competitiveness of the market. The manufacturing of sterile injectables relies immensely on advanced aseptic processing technologies to maintain sterility and prevent contamination. Automated fill-finish systems are utilized to fill vials, syringes, and cartridges under sterile conditions with high precision and minimal human intervention.
 To learn more about this report, Download Free Sample Report
Single-use technologies, such as disposable bioreactors and presterilized components, are increasingly adopted to enhance flexibility, reduce contamination risks, and streamline substitutions. In addition, the use of isolators in aseptic processing has made processes more efficient and more effective at ensuring sterility by reducing human intervention and meeting strict regulatory requirements. The use of automation and robotics in the fill-finish process has been significant in improving the accuracy and productivity of the process while at the same time reducing errors. In addition, advancements in lyophilization technology have enabled the manufacture of complex biological products and sensitive injectables, providing greater stability and shelf life.
Further, the adoption of smart manufacturing systems as well as analytics is helping optimize operations and comply with the relevant regulations. Owing to the increasing complexities involved in the production of injectables, innovation has become critical in handling the manufacturing processes. These technological advancements will thus help CMOs compete effectively and meet the rising needs of the pharmaceutical industry.
Pricing Model Analysis
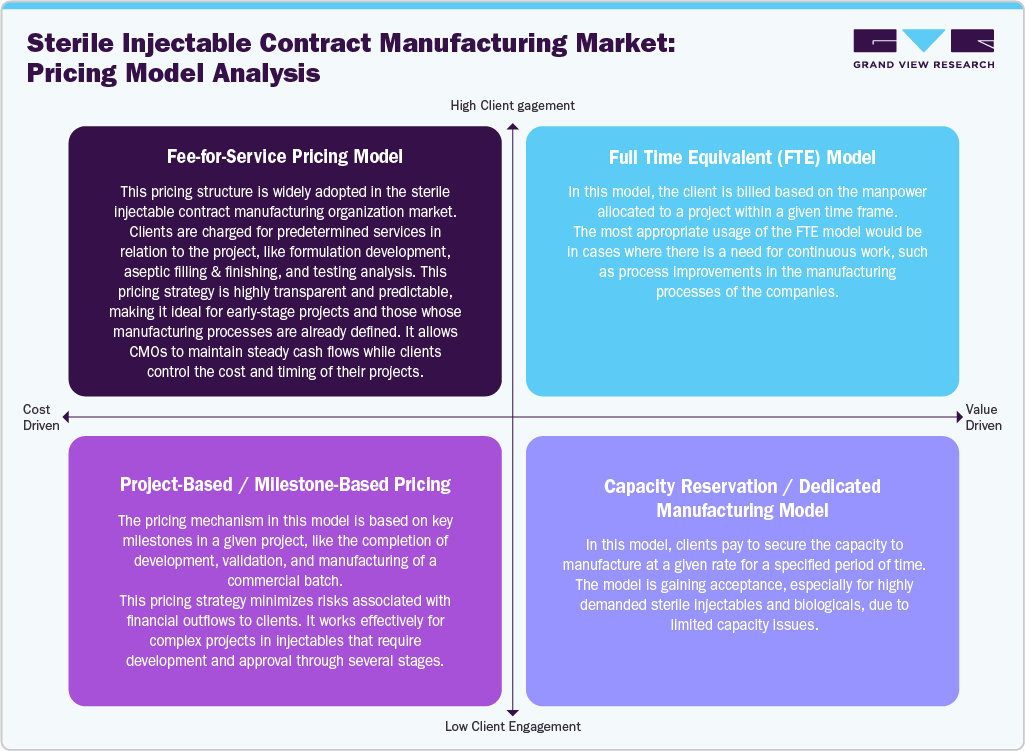
The pricing models employed in the sterile injectable contract manufacturing market aim to maximize cost-efficiency and flexibility while also adding strategic value. The milestone and project-based pricing in the sterile injectable contract manufacturing have proven effective at incentivizing CMOs while minimizing financial risk. The fee-for-service (FFS) pricing models provide cost-certainty and high transparency and are therefore appropriate when the nature of production and testing is predefined by the manufacturers. The capacity reservation and dedicated manufacturing pricing models are gaining acceptance due to rising capacity shortages in sterile manufacturing within a given time period. Moreover, the full-time equivalent (FTE) pricing models offer maximum flexibility for product development and technical assistance services and are entirely based on the personnel allocated to the project for a specified period of time.
 To learn more about this report, Download Free Sample Report
Furthermore, there are new trends such as hybrid and risk-sharing models that focus on pricing based on performance metrics like regulatory success and time-to-market. The adoption of such pricing models promotes greater collaboration between CMOs, manufacturers, and sponsors. With rising demands for injectable drugs, CMOs have to adopt innovative pricing strategies that can meet all the client requirements for customization and scalability.
Market Concentration & Characteristics
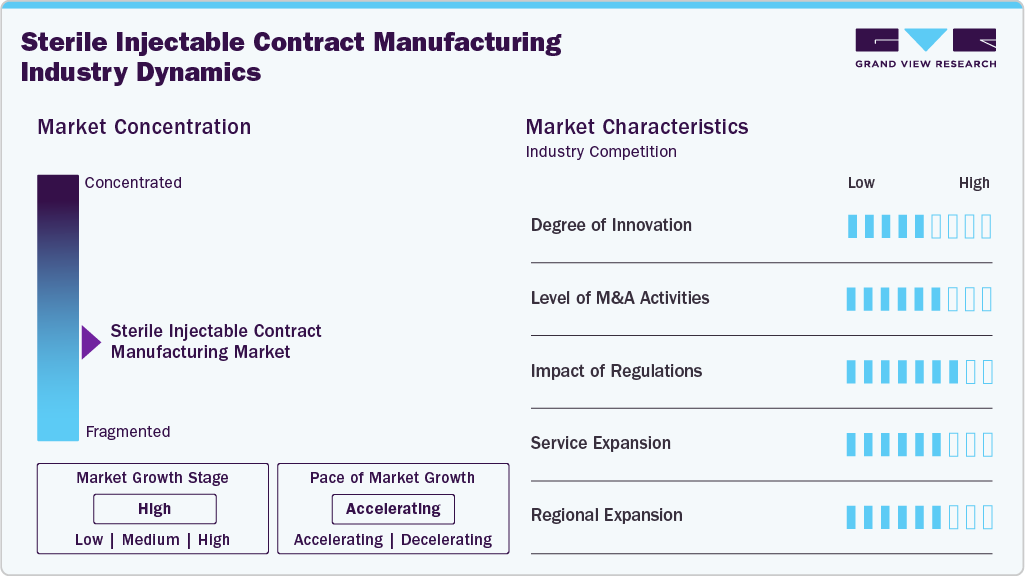
The sterile injectable contract manufacturing market is at a high growth stage, with growth accelerating. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion.
The sterile injectable contract manufacturing market is expanding through the application of cutting-edge aseptic technology, such as isolators, robotics, and automation, in fill-finish production lines. Besides, innovation in areas like disposable systems and lyophilization technology is ensuring increased adaptability and minimizing risks of contamination while promoting the stability of products derived from complex biological materials. Digital manufacturing, monitoring, and analysis tools are also playing crucial roles in the development of the sector in terms of efficiency, accuracy, and speed.
 To learn more about this report, Download Free Sample Report
Strict regulations from agencies like the FDA and EMA are significantly influencing the sterile injectable contract manufacturing market by requiring stringent sterility testing and data integrity measures. Such stringent regulation imposes numerous requirements for product validation, environmental monitoring, and compliance with GMP standards, increasing the complexity of manufacturing procedures. Hence, there is a growing preference among pharmaceutical companies for CMOs with strong regulatory compliance.
The market is seeing a growing number of mergers and acquisitions as players seek to expand capacity, enhance technology, and increase their global footprint. Companies are acquiring niche facilities, especially those with unique capabilities in biologics, high-potency substances, and sophisticated fill-and-finish operations. Through such moves, CMOs can integrate services, improve efficiency, and secure a competitive advantage amid limited capacity.
Expanding service offerings is one major way in which the CMOs are growing the market. Besides manufacturing, CMOs are integrating various other functions, such as formulation, sterile filling, packaging, and regulatory processes. Several CMOs are also expanding their portfolio to include niche services, such as working with high-potency substances, assembling prefilled syringes and autoinjectors, and cold chain logistics.
Geographical diversification will remain significant as CMOs establish facilities across various pharmaceutical clusters in North America, Europe, and the Asia-Pacific region to meet increased global demand. New markets like India and China have cost-effective labor, regulatory compliance, and expertise; these factors have resulted in the outsourcing of activities from major pharmaceutical companies around the globe.
Molecule Insights
On the basis of molecule, the large molecule segment dominated the market with the largest revenue share of 61.16% in 2025. The growth of the segment is mainly due to rising investments by contract manufacturers in developing large molecule-based therapeutics, an expanding pipeline of biologics injectables, and a notable increase in U.S. FDA approvals for biosimilars. Moreover, this segment is expected to experience significant growth during the forecasted period owing to the rising number of biologics approvals over the coming years.
The small molecule segment is expected to witness noteworthy growth over the forecast period as small molecule medicine discovery has substantially evolved over the past few years, leading to a well-established infrastructure for their production. These compounds are typically easier and less expensive to manufacture compared to large molecules, which often require complex biological processes. The existing expertise in small molecule synthesis allows CMOs to efficiently scale up manufacturing while maintaining quality and compliance with regulatory standards. Moreover, the increasing adoption of advanced technologies has driven the growth of small-molecule-based injectables over the last few years, thereby augmenting the segment’s growth.
Product Insights
The finished drug product segment accounted for the largest revenue share in 2025. The segment growth is driven by increasing demand for ready-to-administer injectables, growth in biologics and high-potency therapies, and the need for compliant, scalable fill-finish capacity. In addition, strategic expansions are boosting segment growth. For instance, in July 2025, Eramol announced a new sterile manufacturing facility in the UK scheduled for 2026, featuring EU GMP Annex 1-aligned cleanrooms, isolator technology, and scalable vial filling capabilities, strengthening global sterile injectable finished product capacity.
The API segment is likely to grow at a notable rate, owing to the rise in the demand for complex and high-value injectable drugs. The rapid growth and development of biologics, biosimilars, and HPAPIs, especially those used in oncology and specialty drugs, are further contributing to the growing interest in the API market segment. Moreover, the growing trend among pharmaceutical firms to outsource API manufacturing due to the need for substantial investments, rigorous containment protocols, and specialized expertise in manufacturing these products, is propelling the segment’s growth.
Service Insights
On the basis of service, the commercial manufacturing segment dominated the market in 2025, driven by an increase in the number of late-phase drug approvals and a shift of products from the development phase to the commercial phase. The increased number of commercially available injectables is also driving the growth of this segment, as there is an increased requirement for large-scale and compliant manufacturing processes that can be provided by CMOs. Besides, rising outsourcing activity, limited capacity in in-house units, and the need for global distribution are fueling the growth of the commercial manufacturing segment.
The aseptic fill-finish services segment is expected to grow at the second-fastest CAGR during the forecast period. The segment growth is driven by its importance in maintaining product sterility and safety. The aseptic fill-finish processes are responsible for the sterile packaging of drugs into different containers used to deliver the medication. Moreover, the growing outsourcing trend among pharmaceutical and biotech firms is expected to drive the market growth, as CMOs provide advanced technology and regulatory compliance at lower capital expenditure than manufacturing. The growing need for advanced, patient-friendly dosage forms, such as prefilled syringes and ready-to-use vials, is further driving demand for aseptic fill-finish services.
Therapeutic Area Insights
On the basis of therapeutic area, the oncology segment held the largest market share in the sterile injectables contract manufacturing market. This is mainly due to the large number of injectable oncology drugs available on the market, such as chemotherapeutics, immuno-oncology drugs, and targeted therapies, which must be administered in a sterile manner. Other factors contributing to the growth of the segment include the rising global incidence rate of cancers, the approval of several oncology biologics and biosimilars, and the increasing number of ADCs in the drug pipeline.
The CNS disease segment is anticipated to grow at the fastest CAGR during the forecast period. The rapid growth can be attributed to ongoing research & development initiatives aimed at developing therapies for neurological diseases like Alzheimer’s disease, Parkinson’s disease, and multiple sclerosis, most of which use injectables. Moreover, the growing incidence of neurological diseases, along with the development of biologics and injectable formulations, will boost the demand for customized manufacturing solutions. CMOs are increasingly engaged in facilitating the manufacture of complex CNS drug pipelines that involve peptides and biologics, which demand highly sterile processes. With innovations in neurotherapeutic drugs and their commercialization, the CNS disease segment is anticipated to grow over the coming years.
Route of Administration Insights
On the basis of route of administration, the intravenous (IV) segment accounted for the largest revenue share in the sterile injectables contract manufacturing market. The segment growth is attributed to its acceptance within hospital environments for faster drug delivery of antibiotics, cancer treatment drugs, and critical care drugs, among others. IV drug administration ensures the fastest delivery of the administered drug, making it ideal for cases requiring urgent attention.
The subcutaneous (SC) segment is expected to witness the fastest growth over the forecast period, due to the increased preference for patient-centric therapy delivery and self-administration of medications. Patients prefer the SC route for biologic drugs, such as insulin, mAbs, and autoimmune medications, because it offers ease of administration, reduced need for frequent hospital visits, and better compliance. The increasing use of prefilled syringes, autoinjectors, and wearables is also contributing to the rapid growth of this segment.
End Use Insights
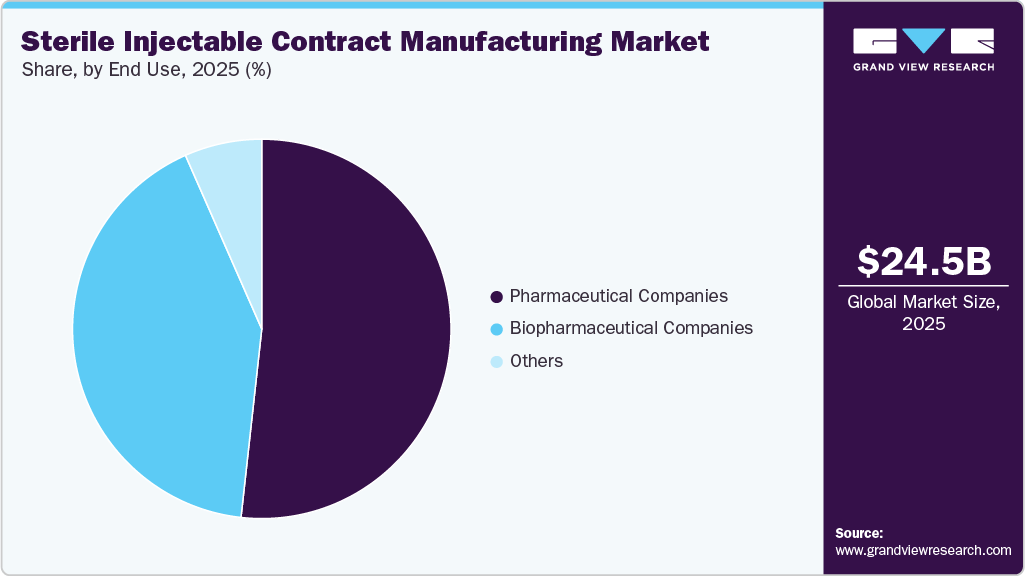
Pharmaceutical companies accounted for the largest revenue share in the sterile injectables contract manufacturing market in 2025. A range of injectable medicines in the portfolios of these companies, both generic and branded injectables, and those that are hospital-based and require sterile manufacturing, drives the segment growth. These companies tend to outsource production to contract manufacturers to keep costs low, address capacity constraints, comply with regulations, and meet production needs.
 To learn more about this report, Download Free Sample Report
The biopharmaceutical companies market segment is anticipated to grow at the fastest pace during the forecast period due to the growing demand for biologics, biosimilars, and advanced therapy products. Several biopharmaceutical companies do not have facilities for aseptic processing or biologics fill-finish services within their premises. This makes CMOs vital partners for biopharmaceutical companies, as the trend toward outsourcing is gaining momentum due to increasing demand for complex injectable biologics and growing investment in R&D.
Regional Insights
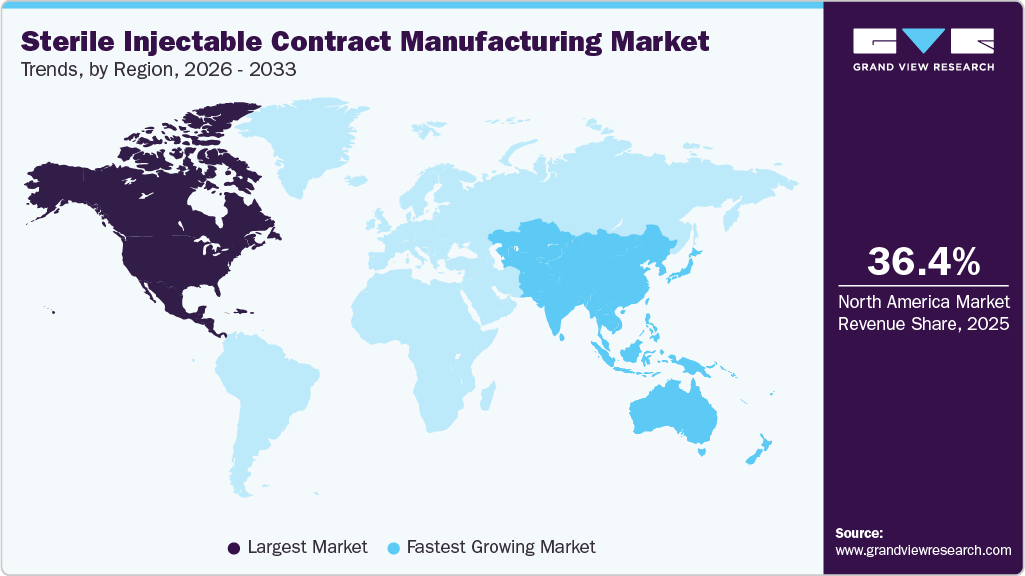
The North America sterile injectable contract manufacturing industry dominated the market, accounting for 36.41% share in 2025. The region's growth is attributed to advanced healthcare infrastructure, rising R&D investment, technological developments, and the presence of major players. In addition, the growing prevalence of chronic diseases and the increasing demand for biologics & biosimilars are expected to boost the demand for sterile injectable formulations.
 To learn more about this report, Download Free Sample Report
In addition, there is a growing combination of healthcare infrastructure, increased burden of diseases such as cancer, diabetes, and autoimmune disorders, advanced regulatory systems, and significant pharmaceutical innovation. In addition, the region is supported by the U.S. FDA, which emphasizes stringent quality standards that encourage investment in advanced sterile manufacturing technologies.
Furthermore, the growing availability of advanced technology in the region is expected to drive market growth. For instance, in October 2025, Jubilant Pharmova Limited strengthened its contract manufacturing in North America by commissioning a third sterile injectable production line at its Washington facility. The site is managed by its wholly owned subsidiary, Jubilant HollisterStier (JHS). The USD 132 million investment is designed to support complex injectable projects, improve manufacturing efficiency and precision, and expand output, to double the plant’s overall sterile production capacity in Spokane. Such growing strategic initiatives are anticipated to drive market growth.
U.S. Sterile Injectable Contract Manufacturing Market Trends
The sterile injectable contract manufacturing industry in the U.S. is the largest market in North America and is projected to hold a significant share over the forecast period. This growth is driven by a strong pipeline of new drug approvals and a commitment to innovative treatments, particularly in oncology and the management of chronic diseases. Further, the rise in approvals for innovative therapies, especially in oncology and chronic conditions, is expected to fuel market growth during the forecast period. Pharmaceutical companies are increasingly turning to CMOs to meet their manufacturing needs, benefiting from specialized knowledge, lower operational costs, and faster product launches. Thus, CMOs are making significant investments to enhance their service capabilities.
Furthermore, adherence to Good Manufacturing Practices (GMP) is crucial for ensuring that products are produced safely and consistently, ultimately leading to successful therapeutic outcomes. For instance, in May 2025, Amneal Pharmaceuticals, Inc. announced a strategic partnership to boost domestic production of Apiject’s BFS-based injectable platform at its New York facility. This collaboration is set to enable large-scale production of various sterile dosage forms, such as prefilled injectables, ophthalmic solutions, and inhalation products. It highlights the commitment to enhance the U.S. drug supply chain through local pharmaceutical manufacturing. The company employs approximately 2,500 individuals in the U.S., primarily focused on operations, quality, and research and development.
The Canada sterile injectable contract manufacturing market is expected to grow at a significant CAGR during the forecast period, as it has become a hub for outsourcing companies that serve the needs of sterile injectable CMOs. The market is expanding, driven by an increasing pipeline and approvals for injectables, as well as the growing demand for cell and gene therapies. One of the major growth drivers is the rising demand for biologics and complex injectable therapies. With the increasing prevalence of chronic diseases such as cancer, autoimmune disorders, and diabetes, pharmaceutical and biotech companies are focusing more on sterile injectables, particularly biologics, monoclonal antibodies, and biosimilars. Canada’s strong regulatory framework under Health Canada enhances global confidence in manufacturing quality, encouraging multinational firms to outsource production to Canadian CMOs.
Europe Sterile Injectable Contract Manufacturing Market Trends
The sterile injectable contract manufacturing industry in Europe is experiencing steady expansion, driven by the increasing demand for biologics, complex molecules, and personalized therapies. The region benefits from a strong pharmaceutical base, a supportive regulatory environment, and an advanced manufacturing infrastructure, enabling efficient production and regulatory compliance. Furthermore, the market growth is supported by a strategic positioning and a rising preference for outsourcing complex biologics and biosimilars. Investment in modular sterile filling and advanced aseptic capabilities strengthens production capacity, while BfArM and regional authorities enforce EU GMP and Annex 1 compliance with Qualified Person oversight.
The German sterile injectable contract manufacturing market is expected to witness significant growth, driven by the increasing demand for biopharmaceuticals and the rising prevalence of chronic diseases. The shift toward more complex drug formulations, particularly biologics and biosimilars, necessitated advanced manufacturing capabilities that several pharmaceutical companies prefer to outsource. This trend is further fueled by the need for cost-effective solutions and the ability to scale production quickly in response to market demands. In addition, stringent regulatory requirements compel companies to partner with specialized CMOs that possess the expertise and facilities necessary to ensure compliance with GMP.
The sterile injectable contract manufacturing industry in the UK is expected to grow significantly over the coming years. Growth can be attributed to the increasing focus on biologics and complex molecules, which often require sterile injectable delivery, thereby driving market growth in the country. In addition, the UK's supportive regulatory environment and the presence of EMA-approved R&D and manufacturing facilities attract foreign investment, boosting the market growth. Moreover, the rise in chronic diseases and an aging population is expected to propel the demand for injectable medications, emphasizing the importance of sterile injectables in modern healthcare.
Asia Pacific Sterile Injectable Contract Manufacturing Market Trends
The sterile injectable contract manufacturing industry in the Asia Pacific is expanding rapidly, driven by rising demand for biologics, specialty injectables, and complex formulations. The countries in the Asia Pacific have become a strategic hub due to their advanced technological infrastructure, robust R&D ecosystem, and regulatory efficiency, which support faster clinical trials and product approvals. Strong government incentives streamlined regulatory review processes, and a focus on supply chain reliability positions the region as a high-capability center for both domestic and global production. Furthermore, the market growth is fueled by the increasing investments in advanced fill-finish systems, lyophilization, and prefilled syringes, coupled with strong regulatory support for high-quality sterile manufacturing. Asian CMOs are leveraging technical expertise, regulatory compliance, and innovative platforms to serve both clinical and commercial-stage biologics manufacturers, enhancing the region’s competitiveness.
The China sterile injectable contract manufacturing market is growing on the back of expanding R&D activities, evolving regulatory frameworks, a diverse patient population, and rising demand for high-quality injectable therapies. Domestic and international pharmaceutical companies increasingly outsource manufacturing to Chinese CMOs, leveraging local expertise, advanced infrastructure, and cost efficiency to speed up development and commercial timelines. Government initiatives, foreign investments, and a strong focus on process innovation and quality assurance further support market expansion. Moreover, China has become an attractive destination for outsourcing activities due to its large population and cost-effectiveness.
The sterile injectable contract manufacturing industry in Japan is projected to witness considerable growth during the forecast period. The growth is supported by advanced technological infrastructure, policy reforms, and a developed R&D ecosystem that enables faster patient recruitment and clinical trial execution. Rising investment in pharmaceutical and biopharmaceutical R&D, alongside stringent quality and safety standards, has increased demand for sterile injectable CMO services. Regulatory support from the Pharmaceutical and Medical Devices Agency (PMDA), including streamlined drug review and approval processes, encourages both domestic and international CMOs to establish operations and speed up product launches.
The India sterile injectable contract manufacturing market is projected to grow considerably in the coming years. Growth is driven by cost competitiveness, a large pool of skilled professionals, and WHO-cGMP-compliant facilities. Increasing international investments and the “China Plus One” strategy have encouraged global pharmaceutical companies to diversify manufacturing to India, taking advantage of its operational efficiency, robust regulatory environment, and strategic geographic position for export to both developed and emerging markets. The country’s expanding healthcare infrastructure supports higher volumes of clinical and commercial manufacturing, while the growing emphasis on high-quality, technically sophisticated injectable therapies further strengthens India’s market.
Latin America Sterile Injectable Contract Manufacturing Market Trends
The sterile injectable contract manufacturing industry in Latin America is growing due to the expansion of innovative biologics manufacturing capabilities across key Latin American countries. Investments in GMP-compliant facilities, technology-enabled aseptic production, and integrated fill-finish operations are reducing import dependence while improving local access to high-complexity biologics and specialty injectable therapies. Moreover, the growing presence of contract manufacturing infrastructure supporting clinical batch production, biosimilar commercialization, and export-oriented supply chains is positioning Latin America as an emerging hub for sterile injectable manufacturing.
The Brazil sterile injectable contract manufacturing market is impacted by factors such as the development of advanced domestic biologics manufacturing capabilities, which is expected to significantly drive growth in the Brazil sterile injectables contract manufacturing market. As the drug pipeline grows, demand for aseptic manufacturing and fill-finish services will increase due to new developments in specialty injectables and high-potency products. Moreover, since such facilities require high investments along with strict regulation, companies are opting to collaborate with specialized CMOs in the country.
Middle East and Africa Sterile Injectable Contract Manufacturing Market Trends
The sterile injectable contract manufacturing industry in the Middle East and Africa is witnessing steady growth, largely driven by rising demand for biopharmaceuticals, vaccines, and other complex drug-delivery systems in the region. The market is still considered highly untapped, creating numerous opportunities as the government aims to manufacture its own medicines and reduce its reliance on imported drugs.
In addition, the establishment of integrated biopharma facilities and the expansion of regulatory approvals for advanced injectable medicines are expected to strengthen regional manufacturing capacity. As countries build infrastructure for biologics production, cold-chain distribution, and quality-controlled sterile processing, pharmaceutical companies increasingly rely on local CMO partners for cost-efficient and compliant production. These developments collectively position the Middle East and Africa as an emerging growth region for sterile injectables contract manufacturing, driven by expanding healthcare needs and supportive industrial policies.
The South Africa sterile injectable contract manufacturing market is growing at a steady pace due to the increasing approval and adoption of long-acting injectable therapies in South Africa, reflecting growing confidence in advanced sterile biologic manufacturing and regulatory capability, which strengthens the broader sterile injectables industry. As new complex injectables gain regulatory approval for public health programs, the demand for reliable manufacturing, fill-finish capacity, and supply chain coordination expands accordingly. For instance, according to an article published by University of Liverpool, in October 2025, the introduction of advanced long-acting injectables in South Africa reflects the country’s growing capacity to adopt and regulate complex biologic medicines, as proved by the registration of lenacapavir by the South African Health Products Regulatory Authority (SAHPRA). Such approvals demand compliance with stringent sterile manufacturing standards, validated production systems, and robust regulatory oversight, creating scope for local and regional CMO partners to support manufacturing, fill-finish operations, packaging, and sustained supply.
The sterile injectable contract manufacturing industry in the UAE is expected to witness significant growth due to the rising prevalence of several chronic diseases, a supportive regulatory environment, the entry of new players, and growing year-on-year investments of foreign pharmaceutical companies and CMOs. Moreover, the establishment of the first GMP biopharma manufacturing facility in Abu Dhabi, operated by Resilience in partnership with Mubadala, directly strengthens localized production capabilities for biologics and sterile injectables in the UAE. By creating dedicated infrastructure for manufacturing therapeutics and vaccines under a contract-based operational model, this initiative significantly expands regional CMO capacity for complex injectable products.
Key Sterile Injectable Contract Manufacturing Company Insights
The key players operating across the market are adopting strategic initiatives such as service launches, mergers & acquisitions, partnerships & agreements, and expansions to gain a competitive edge in the market. For instance, in December 2025, Alcami Corporation expanded sterile fill-finish capacity with a new GMP isolator vial line, strengthening global supply, supporting complex injectables, and enhancing scalability and competitiveness across the sterile injectables contract manufacturing market.
Key Sterile Injectable Contract Manufacturing Companies:
The following key companies have been profiled for this study on the sterile injectable contract manufacturing market.
- Baxter
- Catalent, Inc.
- Vetter Pharma
- Recipharm AB
- Aenova Group
- Fresenius Kabi AG
- Unither Pharmaceuticals
- FAMAR Health Care Services
- Cipla Inc.
- NextPharma Technologies
Recent Developments
-
In January 2026, Vetter Pharma announced its expansion to build a new manufacturing facility in the Saarland region (Southwest Germany) to strengthen its European footprint, supported by regional advantages. The company has invested ~567.99 million USD (480 EUR) in its first phase of construction.
-
In October 2025, Baxter BioPharma Solutions (Simtra BioPharma Solutions) adopted a dual-continent expansion strategy to meet the rising demand for complex therapies. The company has established a flexible clinical line for vials (liquid and lyophilized) and prefilled syringes at its U.S. site, catering to both new and existing customers. In addition, the company is also constructing a new production facility that will consist of three isolator commercial-scale sterile filling lines, further strengthening its presence in North America.
Sterile Injectable Contract Manufacturing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 24.5 Billion
Estimated market size in 2026
USD 26.9 billion
Projected market size by 2033
USD 57.2 billion
Growth rate
CAGR of 11.3% from 2026 to 2033
Actual Data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Molecule, product, service, therapeutic area, route of administration, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Thailand; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait; Oman; Qatar
Key companies profiled
Baxter; Catalent, Inc.; Vetter Pharma; Recipharm AB; Aenova Group; Fresenius Kabi; Unither Pharmaceuticals; Famar; Cipla Inc.; NextPharma Technologies
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Sterile Injectable Contract Manufacturing Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global sterile injectable contract manufacturing market report based on molecule, product, service, therapeutic area, route of administration, end use and region:
-
Molecule Outlook (Revenue, USD Million, 2021 - 2033)
-
Small Molecule
-
Large Molecule
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
API
-
Finished Drug Product
-
Prefilled Syringes
-
Vials and Ampoules
-
Specialty Injectables
-
Others
-
-
-
Service Outlook (Revenue, USD Million, 2021 - 2033)
-
Clinical Trial Manufacturing
-
Commercial Manufacturing
-
Aseptic Fill-Finish Services
-
Packaging & Labelling
-
Others
-
-
Therapeutic Area Outlook (Revenue, USD Million, 2021 - 2033)
-
Oncology
-
Cardiovascular Diseases
-
Central Nervous System Diseases
-
Infectious Disorders
-
Musculoskeletal Diseases
-
Hormonal Diseases
-
Others
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Subcutaneous (SC)
-
Intravenous (IV)
-
Intramuscular (IM)
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical Companies
-
Biopharmaceutical Companies
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Frequently Asked Questions About This Report
The global sterile injectable contract manufacturing market size was valued at USD 24.5 billion in 2025 and is estimated at USD 26.9 billion for 2026.
The global sterile injectable contract manufacturing market is expected to grow at a CAGR of 11.3% from 2026 to 2033, reaching USD 57.2 billion by 2033.
North America dominated with a 36.4% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The oncology segment held the largest revenue share in 2025, while CNS disease is the fastest-growing area.
Pharmaceutical companies segment held the largest share in 2025, while biopharmaceutical companies is the fastest-growing segment.
The intravenous (IV) segment held the largest revenue share in 2025, while subcutaneous (SC) is the fastest-growing segment.
The large molecule segment dominated the market with the largest revenue share of 61.2% in 2025. The growth of the segment is mainly due to rising investments by contract manufacturers in developing large molecule-based therapeutics and an expanding pipeline of biologics injectables.
Key players include Baxter; Catalent, Inc.; Vetter Pharma; Recipharm AB; Aenova Group; Fresenius Kabi; Unither Pharmaceuticals; Famar; Cipla Inc.; NextPharma Technologies.
The growth of the market is due to the increasing demand for biologics and biosimilars, along with the outsourcing trend among pharmaceutical companies seeking to reduce costs and enhance efficiency. Moreover, the rising prevalence of chronic illnesses, coupled with the quicker approval timelines for sterile injectables compared to other drug types, is further driving the demand for injectable formulations.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


