
- Home
- »
- Medical Devices
- »
-
Surgical Clips Market Size, Share & Growth Report, 2033GVR Report cover

Surgical Clips Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Ligating, Aneurysm), By Material (Titanium, Polymer), By Surgery (Automated/ Robotic Assisted Surgery, General Surgery), By End Use (Hospitals, Ambulatory Surgical Centers), By Region, And Segment Forecasts
Market Size, 2025
$1.2BMarket Estimate, 2026
$1.4BMarket Forecast, 2033
$3.4BCAGR, 2026–2033
16.3%Surgical Clips Market Summary
The global surgical clips market size was valued at USD 1.2 billion in 2025 and is projected to grow from USD 1.4 billion in 2026 to USD 3.4 billion by 2033, growing at a CAGR of 16.3% from 2026 to 2033. North America dominated the market, accounting for a largest revenue share of 43.0% in 2025. The growing adoption of minimally invasive techniques to reduce hospital stays, improve recovery time, and minimize post-surgery complications, even among the geriatric population, is one of the factors propelling market growth.
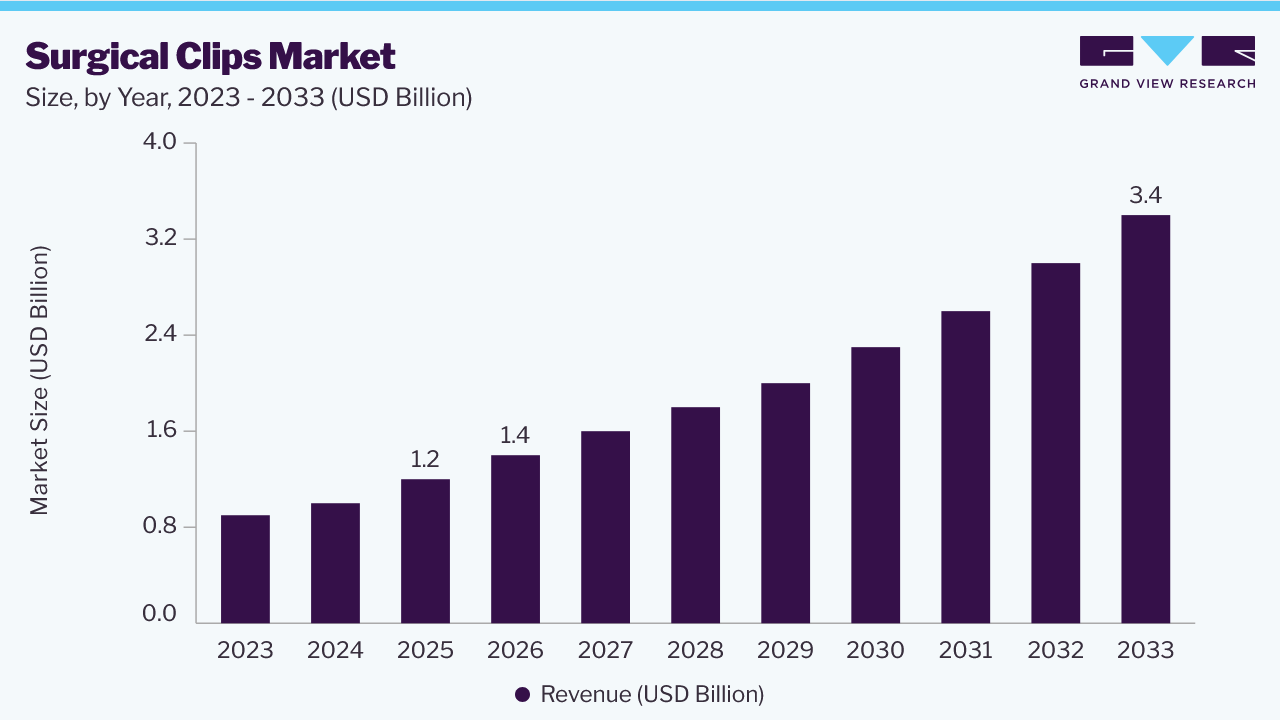 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The ligating clips segment dominated the market, with a revenue share of about 75.0% in 2025.
- By material: The titanium segment dominated the market in 2025.
- By surgery: The general surgery segment dominated the market, with a revenue share of about 74.0% in 2025.
- By end use: The hospital segment dominated the market, with a revenue share of about 65.0% in 2025.
Regional Highlights
- Largest regional market: North America (Approximately 43.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 1.2 Billion
- Estimated market size in 2026: USD 1.4 Billion
- Projected market size by 2033: USD 3.4 Billion
- CAGR (2026-2033): 16.3%
Prism AI by Grand View Research Free to tryAsk a question about the surgical clips marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The global surgical clips market is witnessing steady growth owing to the increasing volume of surgical procedures, the growing adoption of minimally invasive surgery (MIS), and continuous technological advancements in surgical instruments. Surgical clips are extensively used for vessel ligation, tissue approximation, and hemostasis across general surgery, cardiovascular surgery, gynecological procedures, urology, gastrointestinal surgery, and neurosurgery. Compared with conventional suturing techniques, surgical clips enable faster vessel closure, reduced operative time, consistent clip placement, and lower risks of blood and bile leakage, making them an integral component of modern surgical practice.
The rapid adoption of laparoscopic and robotic-assisted surgeries is one of the primary factors driving market expansion. As healthcare providers increasingly shift toward minimally invasive procedures to reduce postoperative pain, shorten hospital stays, and accelerate patient recovery, the demand for reliable ligation and closure devices continues to rise. Manufacturers are introducing advanced clip appliers and next-generation clip designs with improved locking mechanisms, enhanced biocompatibility, and greater compatibility with robotic surgical platforms to improve procedural efficiency and patient safety.
The rising prevalence of chronic diseases, including cardiovascular disorders, cancer, obesity, and gastrointestinal conditions, has contributed to an increasing number of surgical interventions worldwide. Simultaneously, the expansion of healthcare infrastructure, rising healthcare expenditure, and improved access to surgical care in emerging economies are supporting market growth. The growing preference for titanium- and polymer-based clips, owing to their strength, corrosion resistance, and compatibility with advanced imaging modalities, is further driving product adoption. Moreover, ongoing innovation in absorbable clip technologies, ergonomic clip appliers, and precision surgical devices is creating new growth opportunities for market participants. The increasing availability of skilled surgeons trained in minimally invasive and robotic procedures, coupled with stringent regulatory standards that emphasize surgical safety and clinical effectiveness, is expected to sustain demand for surgical clips during the forecast period.
Analyst Perspective
The surgical clips market is expected to grow steadily over the forecast period, driven by increasing adoption of minimally invasive and robotic-assisted surgeries, rising surgical procedure volumes, and ongoing advancements in surgical technologies. Surgical clips enable rapid vessel ligation, reduce operative time, minimize blood loss, and improve procedural efficiency, making them an essential component of modern surgical practice. Manufacturers are focusing on developing advanced clip designs, biocompatible materials, and precision clip appliers to enhance clinical outcomes and compatibility with robotic-assisted procedures. The market is expected to benefit from expanding surgical infrastructure, rising healthcare expenditure, the growing prevalence of chronic diseases, and the rising demand for advanced surgical care in emerging economies, thereby supporting sustained adoption of surgical clips over the forecast period.
Type Insights
The ligating clips segment accounted for the largest revenue share of 75.0% in 2025. Ligating clips are widely used owing to their secure vessel occlusion, high biocompatibility, compatibility with both open and laparoscopic clip applicators, and ability to reduce operative time while minimizing blood and bile leakage following surgical procedures. Their ease of application and reliable locking mechanism have made them the preferred choice for surgical ligation across general surgery, urology, gynecology, and gastrointestinal procedures. Ligating clips are available in multiple sizes to accommodate vessels and tissue structures of varying diameters. Widely used product families include the Weck Hem-o-lok Polymer Locking Ligation System and Hemoclip metal ligation system from Teleflex. The Hem-o-lok system features a secure locking mechanism, distinct tactile feedback, radiolucent non-absorbable polymer construction, and compatibility with both open and laparoscopic procedures, supporting its widespread adoption in minimally invasive surgery.
The aneurysm clips segment is expected to witness lucrative growth during the forecast period. The increasing prevalence of intracranial aneurysms and the rising number of neurovascular surgical procedures are driving the demand for aneurysm clips. Decreased post-operative brain contusions, the long-term durability of aneurysm clipping, and reduced risks of aneurysm recurrence and serious complications have further contributed to the adoption of aneurysm clipping procedures. In addition, continuous advancements in neurosurgical imaging, microsurgical techniques, and clip designs, along with the growing availability of specialized neurosurgical centers and skilled neurosurgeons, are expected to support segment growth over the forecast period.
Material Insights
The titanium segment held a significant share of the surgical clips market owing to the widespread use of titanium clips for vessel ligation and hemostasis across general, cardiovascular, thoracic, gynecological, and minimally invasive surgeries. Titanium clips are preferred for their excellent biocompatibility, corrosion resistance, mechanical strength, durability, and reliable performance in both open and laparoscopic procedures. Their compatibility with advanced imaging techniques and long-term clinical reliability have further supported their widespread adoption. The rising number of surgical procedures, growing demand for minimally invasive surgery, and continuous product innovations by medical device manufacturers are expected to drive segment growth during the forecast period. For instance, in February 2024, Peters Surgical obtained MDR for Class III titanium clips (including Clips 9 and Clips SLS). This approval was for the whole range of Peters’ titanium clips and appliers, which would boost their offerings for surgical ligation procedures.
The polymer segment is anticipated to grow at the fastest CAGR during the forecast period, driven by the increasing adoption of minimally invasive and robotic-assisted surgeries and the growing preference for advanced non-metallic surgical devices. Polymer surgical clips offer several advantages, including radiolucency, nonconductivity, MRI and CT compatibility, and minimal imaging artifacts, making them well-suited for postoperative diagnostic imaging. In addition, their secure locking mechanisms, high biocompatibility, and corrosion resistance contribute to improved surgical outcomes and patient safety. The rising use of laparoscopic procedures across general surgery, urology, and gynecology, coupled with continuous innovations in polymer clip designs and clip appliers, is expected to further support segment growth over the forecast period.
Surgery Insights
The general surgery segment accounted for the largest revenue share, at 74.0%, in 2025. Surgical clips are widely used in general surgical procedures, including vascular, thoracic, gynecological, urological, bariatric, and gastrointestinal surgeries, owing to their ability to provide rapid vessel ligation and secure tissue closure. Compared with conventional sutures, surgical clips offer a lower risk of infection, reduced operative time, faster wound healing, less noticeable scarring, and improved patient outcomes. They are commonly used to secure the cystic duct and cystic artery during cholecystectomy procedures. The rising global volume of general surgical procedures, increasing prevalence of chronic diseases requiring surgical intervention, and growing adoption of minimally invasive techniques are expected to continue driving demand for surgical clips in this segment over the forecast period.
The automated/robotic-assisted surgery segment is still in the initial growth phase. The lack of financial aid, infrastructure, and skilled personnel, and insufficient clinical evidence related to automated surgery are the major reasons behind its smaller market share. However, reduction in human errors and improved efficiency have led to the improved adoption of this surgery in economically developed countries. For instance, in March 2024, Intuitive Surgical, Inc. announced that its da Vinci 5 robotic-assisted surgical system received U.S. FDA 510(k) clearance. The system incorporates advanced imaging, Force Feedback technology, and enhanced computing capabilities to improve surgical precision and efficiency during minimally invasive procedures.
End Use Insights
The hospital segment held the largest share of 65.0% in 2025 due to the large procedural volume and preventive surgeries. Hospitals hold the largest market share as they perform surgeries in large volumes and have high footfall, requiring a variety of surgical clips for different procedures. With an increase in the number of surgical procedures, such as neurosurgery and abdominal laparoscopy, and the growing incidence of trauma, the demand for surgical clips has significantly increased in hospitals. In developed regions, medical bills containing ligature expenditure are reimbursed by insurance agencies. This led to an increase in surgical procedures performed using clipping equipment at hospitals, which positively impacted the segment growth.
Clinics are anticipated to register the fastest CAGR during the forecast period. The segment's growth can be attributed to lower treatment costs, shorter waiting times, improved patient accessibility, and the increasing shift toward outpatient surgical care. The growing adoption of minimally invasive procedures, which require shorter recovery periods and limited postoperative monitoring, is further supporting the demand for surgical clips in clinic-based settings.
Ambulatory Surgical Centers (ASCs) are anticipated to witness significant growth during the forecast period. The increasing preference for same-day surgical procedures, lower procedural costs compared to hospitals, and improved operational efficiency are driving the expansion of ASCs. In addition, rising investments in outpatient healthcare infrastructure, favorable reimbursement policies in developed markets, and the gradual expansion of ambulatory surgical facilities across emerging economies are expected to support segment growth over the forecast period.
Regional Insights
North America held the largest revenue share of 43.0% in 2025 and is expected to maintain its market leadership over the forecast period. The regional market is driven by high volumes of surgical procedures, widespread adoption of minimally invasive and robotic-assisted surgeries, advanced healthcare infrastructure, and rapid uptake of advanced surgical devices. The presence of leading medical device manufacturers, favorable reimbursement policies, and increasing investments in surgical innovation further support market growth. For instance, in June 2025, Johnson & Johnson MedTech launched the ETHICON 4000 Stapler in the U.S. The advanced surgical stapling system is designed for open and laparoscopic procedures and incorporates proprietary 3D Stapling Technology to enhance staple line integrity and improve surgical outcomes.
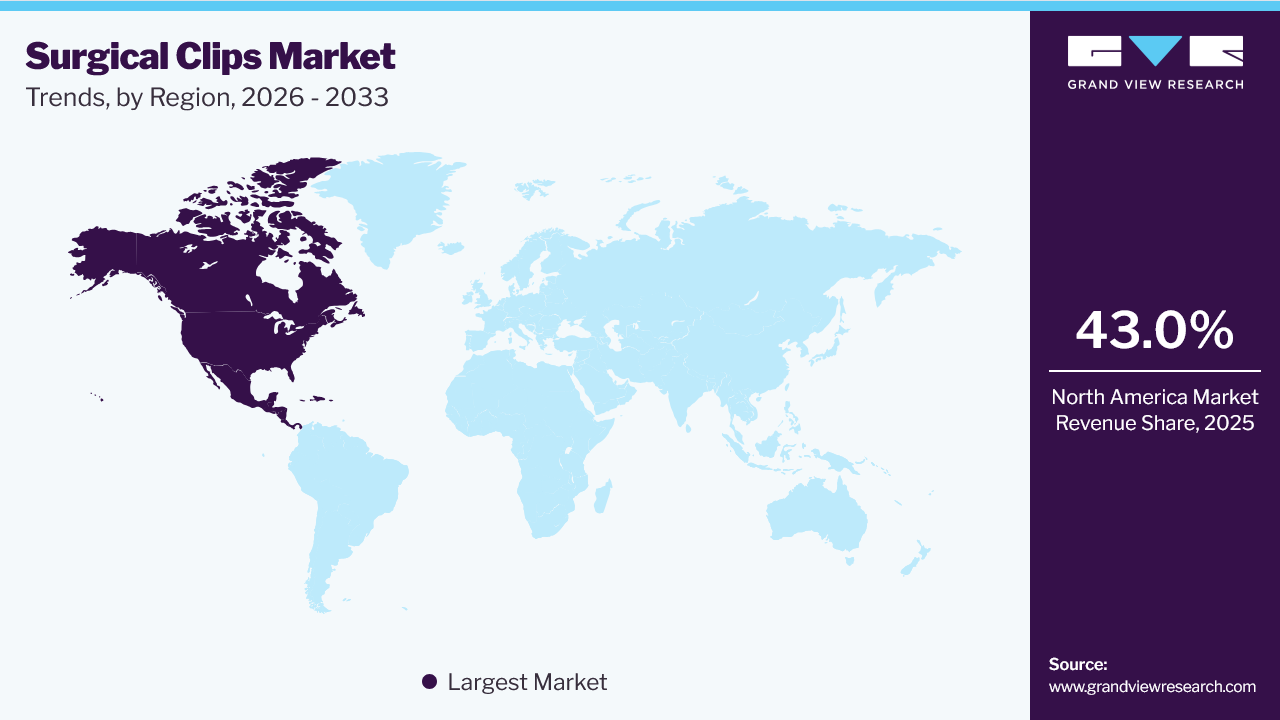 To learn more about this report, Download Free Sample Report
U.S. Surgical Clips Market Trends
Most market participants are based in the U.S., making it the hub of the market. With its sizable patient population and its advanced healthcare market, the region is projected to experience rapid market growth. According to the Journal of Infectious Disease Adviser, approximately 27 million surgical procedures are done in the U.S. annually.
Europe Surgical Clips Market Trends
The European region is expected to witness steady growth over the forecast period, fueled by the rise in prevalence of chronic diseases that require surgery, along with favorable payment schemes for surgical procedures. Furthermore, the increasing usage of minimally invasive surgeries, improvements in healthcare infrastructure, and increasing need for technologically sophisticated surgical equipment are expected to drive market growth in the region.
Asia Pacific Surgical Clips Market Trends
The Asia Pacific surgical clips market is expected to witness the fastest growth during the forecast period. The regional market is driven by a large and growing patient population, increasing surgical procedure volumes, rising healthcare expenditure, and continuous improvements in healthcare infrastructure. The growing adoption of minimally invasive and robotic-assisted surgeries, coupled with the expansion of medical tourism in countries such as India, Thailand, and Singapore, is further supporting market growth. In addition, the presence of cost-sensitive healthcare markets has encouraged local manufacturers to offer competitively priced products while attracting investments from leading global medical device companies. For instance, in February 2024, Medtronic expanded its Medtronic Engineering & Innovation Center (MEIC) in Hyderabad, India, to strengthen its global R&D capabilities and accelerate healthcare technology innovation. The expansion reflects the company's continued investment in the region's growing medical technology ecosystem and reinforces Asia Pacific's importance as a strategic hub for healthcare innovation.
Key Surgical Clips Company Insights
The surgical clips market is moderately fragmented, with several global medical device companies alongside numerous regional and local manufacturers. Companies compete by offering a broad portfolio of surgical clips in different materials, sizes, and designs tailored for specific surgical applications, including general, cardiovascular, neurosurgical, and minimally invasive procedures. Competition is driven by product quality, clinical performance, technological innovation, regulatory approvals, pricing, and long-term supply agreements with hospitals and healthcare providers. Manufacturers continue to focus on expanding their product portfolios, strengthening distribution networks, and investing in product innovation to enhance their competitive position in the global market.
Key Surgical Clips Companies
The following key companies have been profiled for this study on the surgical clips market:
-
Ackermann Medical Private Limited
-
B. Braun SE
-
Boston Scientific Corporation
-
Peters Surgical
-
Grena Limited
-
Johnson & Johnson Medical Pty Ltd.
-
John Scanlan
-
Teleflex Incorporated.
-
Meril Life Science
-
Anrei medical (hz) co., ltd.
-
Jiangsu Sanlian Xinghai Medical Device Co., Ltd.
Recent Developments
- In May 2025, Grena Limited introduced the Click’aV PLUS surgical clips, an advanced polymer clip solution designed to provide improved stability and secure tissue ligation during surgical procedures. The company highlighted the effectiveness of the product due to its anti-slip property and consistent performance.
- In March 2025, Olympus Corporation announced the launch of the Retentia HemoClip, a new single-use hemostasis clip designed for gastrointestinal endoscopic procedures. The clip provides features such as 360-degree rotation, one click deployable and multiple sizes for tissue closure and hemostasis.
Surgical Clips Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.2 billion
Estimated market size in 2026
USD 1.4 billion
Projected market size by 2033
USD 3.4 billion
Growth rate
CAGR of 16.3% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, material, surgery, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Norway; Sweden; Denmark; Japan; India; China; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Ackermann Medical Private Limited; B. Braun SE; Boston Scientific Corporation; Peters Surgical; Grena Limited; Johnson & Johnson Medical Pty Ltd.; John Scanlan; Teleflex Incorporated; Meril Life Science; Anrei Medical (HZ) Co., Ltd.; and Jiangsu Sanlian Xinghai Medical Device Co., Ltd.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Surgical Clips Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global surgical clips market report based on type, material, surgery, end use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Ligating
-
Aneurysm
-
-
Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Titanium
-
Polymer
-
Others
-
-
Surgery Outlook (Revenue, USD Million, 2021 - 2033)
-
Automated/ Robotic Assisted Surgery
-
General Surgery
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers
-
Clinics
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Norway
-
Sweden
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
Kuwait
-
UAE
-
-
02 Table of Contents no content detected Source
Frequently Asked Questions About This Report
The ligating clips segment accounted for the largest revenue share of approximately 75.0% in 2025.
The global surgical clips market is expected to grow at a CAGR of 16.3% from 2026 to 2033, reaching USD 3.4 billion.
North America dominated with an approximately 43.0% revenue share in 2025
Key players in the market include Ackermann Medical Private Limited; B. Braun SE; Boston Scientific Corporation; Peters Surgical; Grena Limited; Johnson & Johnson Medical Pty Ltd.; John Scanlan; Teleflex Incorporated; Meril Life Science; Anrei Medical (HZ) Co., Ltd.; and Jiangsu Sanlian Xinghai Medical Device Co., Ltd., and others.
The global surgical clips market size was valued at USD 1.2 billion in 2025 and is estimated at USD 1.4 billion for 2026.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


