
- Home
- »
- Distribution & Utilities
- »
-
Synchronous Condenser Market Size Report, 2026-2033GVR Report cover

Synchronous Condenser Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (New Synchronous Condenser, Refurbished Synchronous Condenser), By End-use (Electrical Utilities, Industrial), By Region (North America, Europe), And By Segment Forecasts
Market Size, 2025
$713.8MMarket Estimate, 2026
$732.6MMarket Forecast, 2033
$895.5MCAGR, 2026–2033
2.9%Synchronous Condenser Market Summary
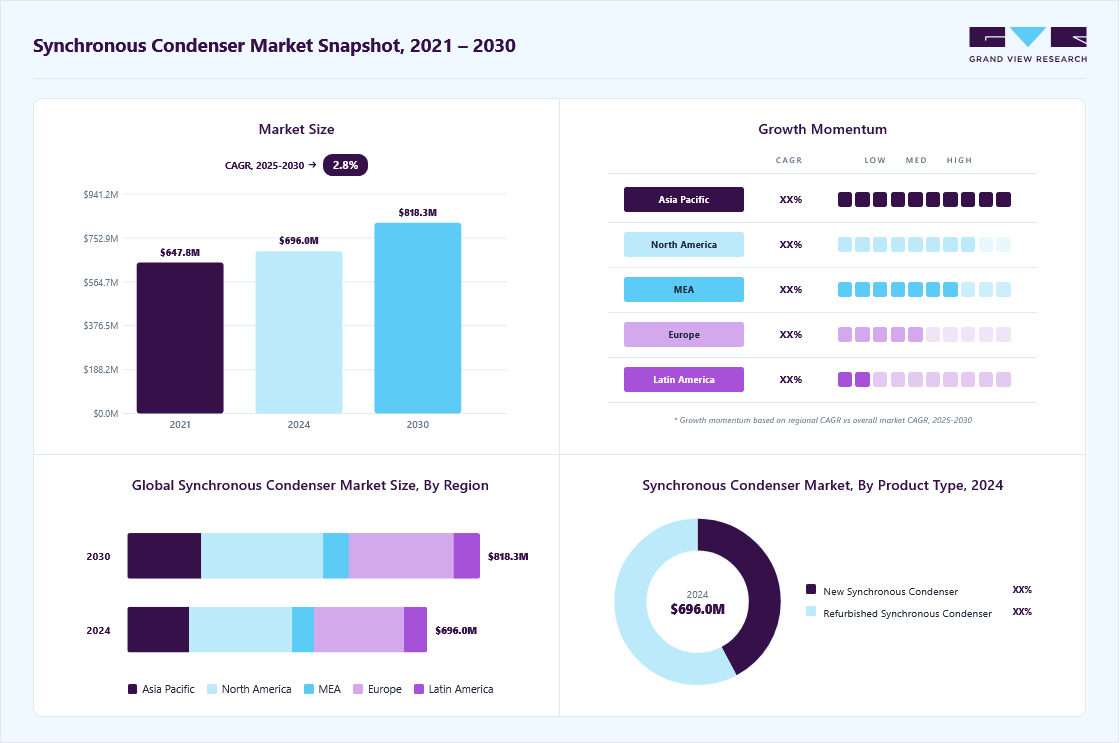
The global synchronous condenser market size was valued at USD 713.8 million in 2025 and is projected to grow from USD 732.6 million in 2026 to USD 895.5 million by 2033, at a CAGR of 2.9% from 2026 to 2033. The market in North America dominated with a revenue share of 34.4% in 2025. This growth is attributed to the growing complexity and variability in power generation across the globe.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: New synchronous condenser segment held the largest market share of 71.2% in 2025.
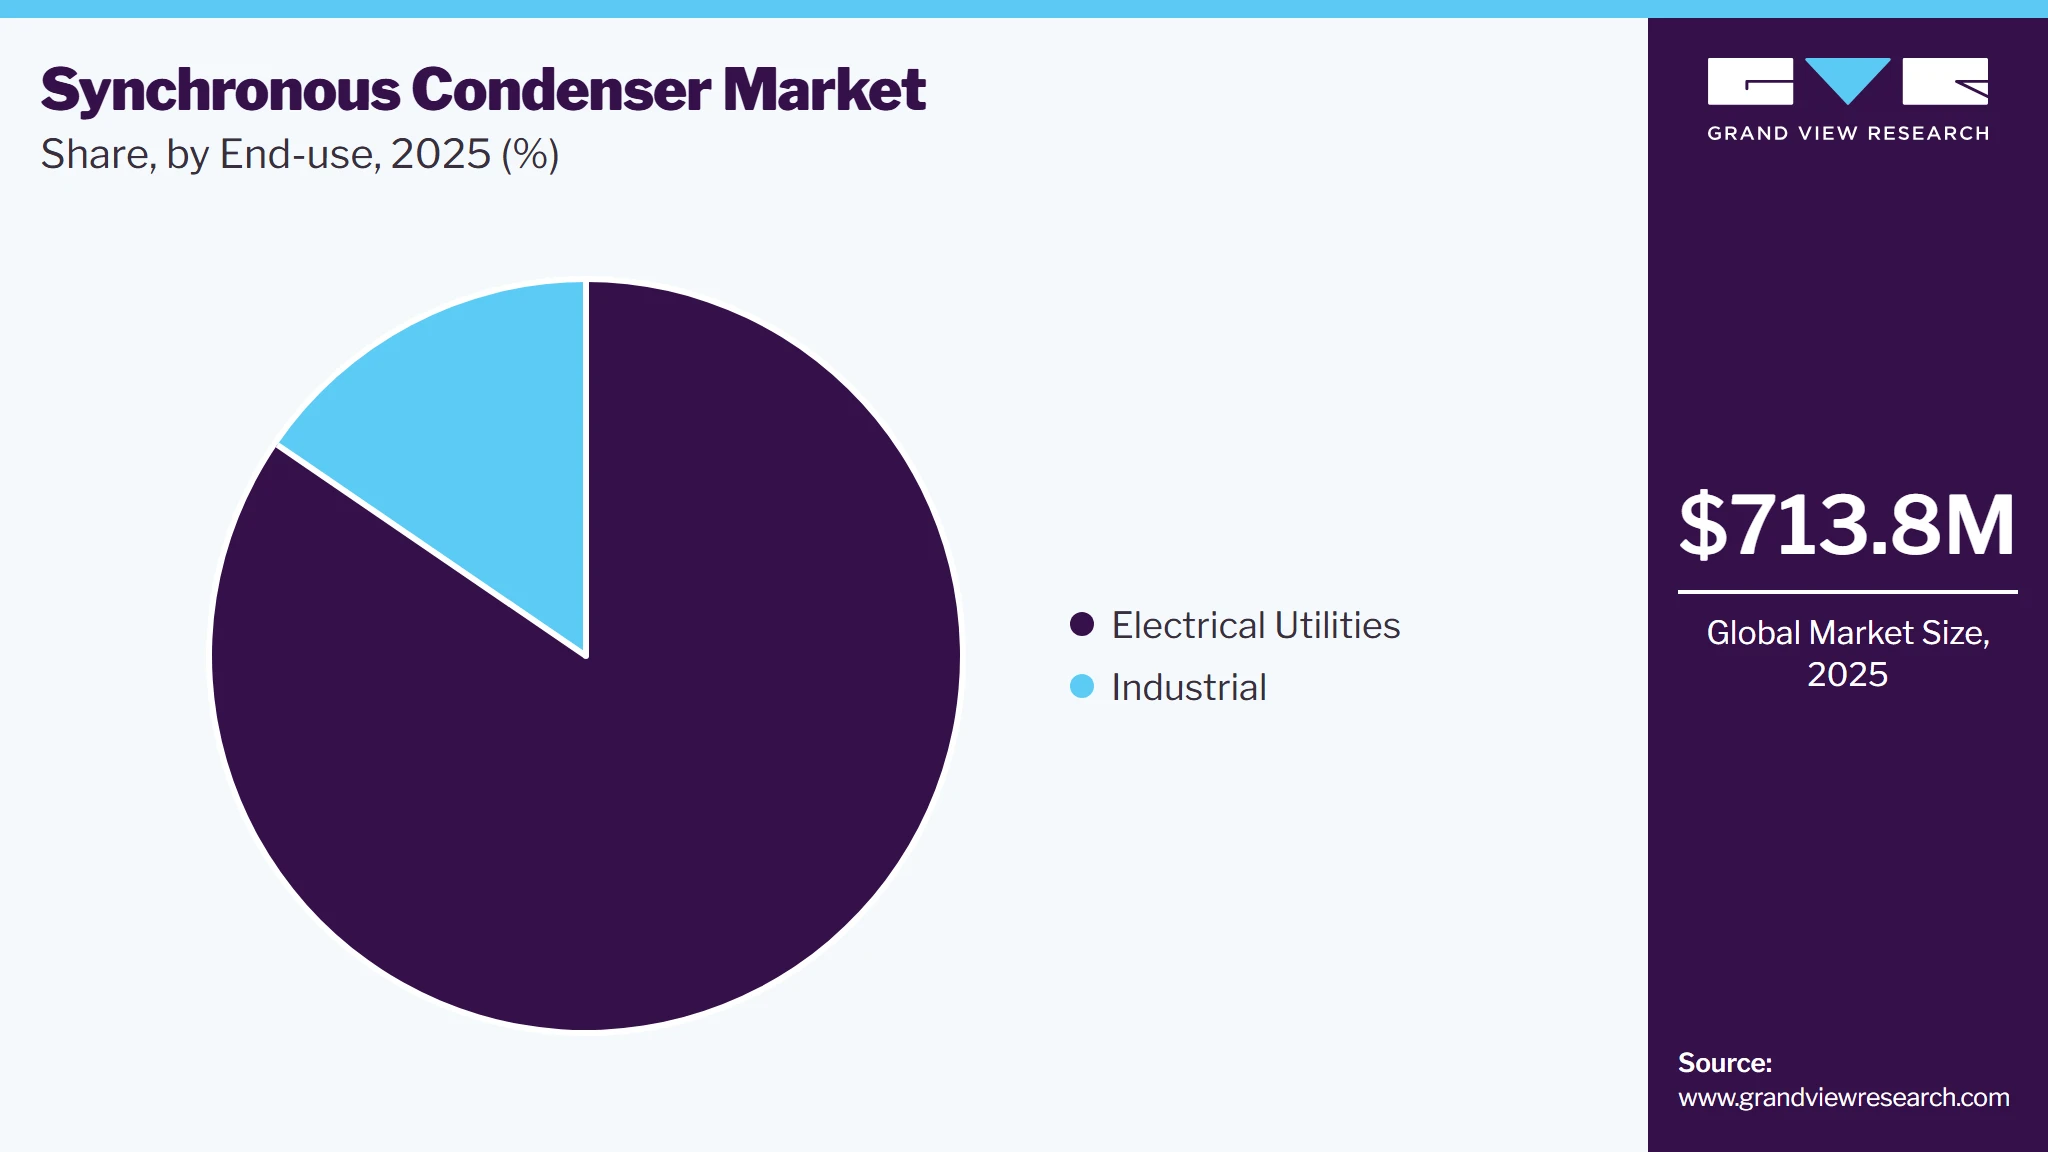
- By end-use: Electrical utilities segment held the largest market share of 84.5% in 2025.
Regional Highlights
- Largest regional market: North America (34.4% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 713.8 Million
- Estimated market size in 2026: USD 732.6 Million
- Projected market size by 2033: USD 895.5 Million
- CAGR (2026-2033): 2.9%
Prism AI by Grand View Research Free to tryAsk a question about the synchronous condenser marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Synchronous condensers help maintain grid stability by providing inertia and voltage support. Moreover, many power grids globally are aging, necessitating upgrades to ensure reliability and stability, where synchronous condensers play a crucial role.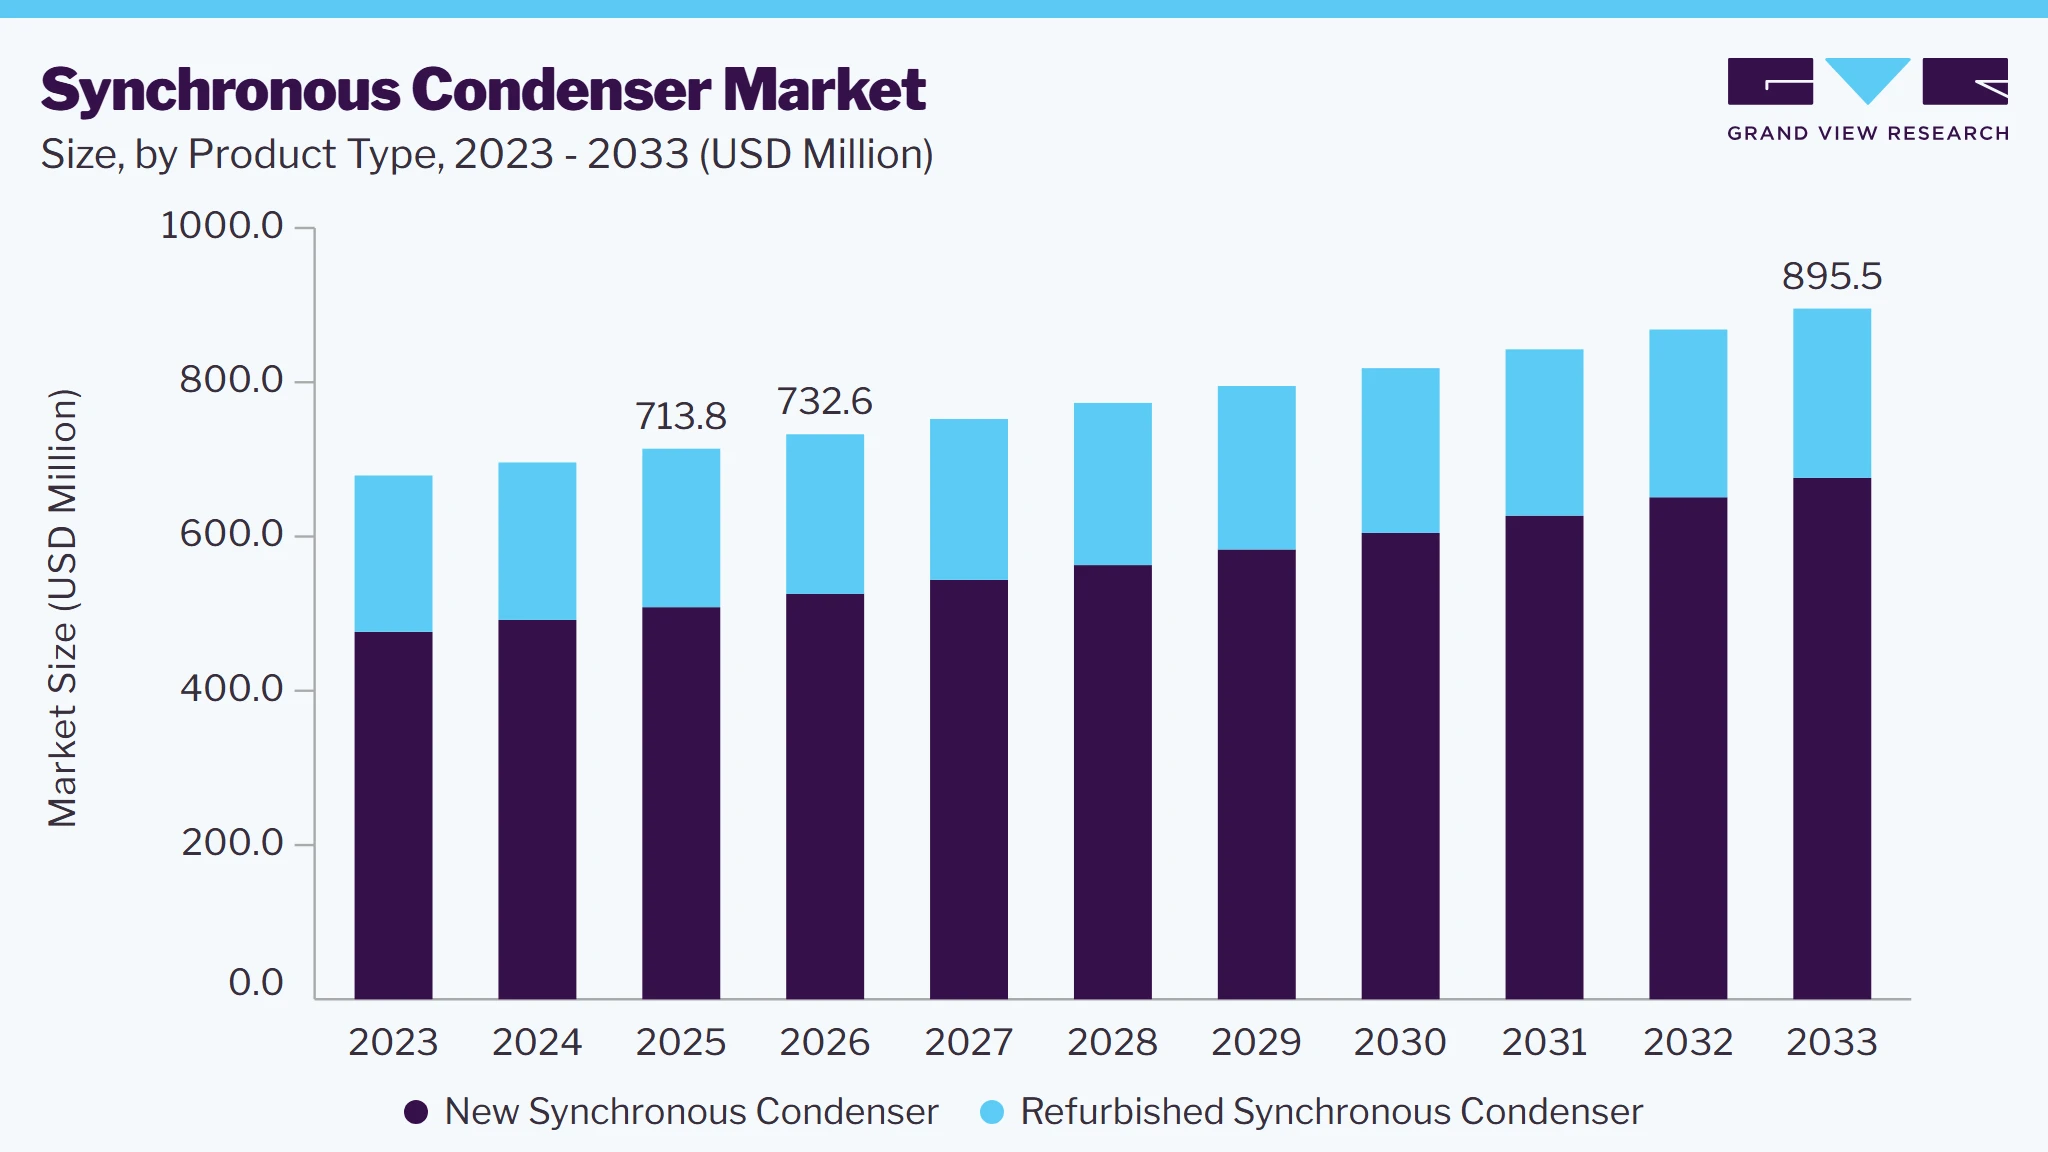 To learn more about this report, Download Free Sample Report
As renewable energy sources such as wind and solar become more prevalent, the need for synchronous condensers to provide grid stability and inertia support increases. Furthermore, supportive policies and incentives aimed at enhancing grid reliability and integrating renewable energy sources often drive investments in synchronous condenser technology. Thereby, boosting market growth. Moreover, advances in control systems, materials, and design have improved the efficiency and performance of synchronous condensers, making them more suitable for grid operators.
Synchronous condensers require significant capital investment compared to other grid stabilization technologies, which can restrict their adoption in some applications. Integrating synchronous condensers into existing grid infrastructures can be challenging due to compatibility issues and the need for retrofitting. Furthermore, this product has high operational costs depending on its maintenance, fuel, and periodic refurbishment, which further increases its overall expenditure.
However, increasing penetration of renewable energy sources creates a growing market for synchronous condensers to manage grid stability. Initiatives of infrastructure projects that are aimed at expanding and interconnecting power grids present opportunities for product growth. Furthermore, increasing government initiatives aimed at accelerating the energy transition towards cleaner sources can drive demand for synchronous condensers. In addition to this, continued innovation in synchronous condenser technology in terms of materials, controls, and maintenance practices can reduce costs and improve performance.
Market Dynamics
The synchronous condenser market is witnessing steady growth, driven by the increasing integration of renewable energy sources and the retirement of conventional thermal power plants, which has created a greater need for grid stability and voltage support. Investments in transmission network upgrades and grid modernization are further supporting market expansion. However, the high installation cost and long project implementation timelines remain key challenges, particularly in developing regions. A notable market trend is the growing deployment of hybrid grid stabilization solutions that combine synchronous condensers with battery energy storage systems to enhance power system reliability and flexibility.
The increasing deployment of wind and solar power is driving demand for synchronous condensers to maintain grid stability. Renewable energy plants connected through power electronic converters do not provide the rotational inertia and fault current required for stable grid operation. The retirement of coal- and gas-fired power plants is reducing the availability of conventional synchronous generation. Grid operators are installing standalone synchronous condensers to strengthen voltage control, improve frequency response, and support higher renewable energy integration.
In January 2026, ANDRITZ signed a contract with AXIA Energia to supply six 300 MVAr synchronous condensers for four substations in Brazil's National Interconnected System. The equipment will provide dynamic voltage control, additional inertia, and increased short-circuit capacity, strengthening grid reliability as wind and solar generation continue to expand. The project supports Brazil's long-term energy transition by enabling greater integration of renewable energy into the transmission network, demonstrating the growin
The high capital cost of synchronous condensers is a key restraint for market growth. Manufacturing these systems requires large quantities of copper, electrical steel, and other heavy-duty components, making them significantly more expensive than many alternative grid support technologies. Installation also involves civil works, grid integration, and specialized engineering, increasing the overall project cost. These high upfront investments can delay adoption, particularly for utilities in developing regions with limited infrastructure budgets.
The retirement of coal- and gas-fired power plants is creating a significant opportunity for the synchronous condenser market. Utilities are increasingly converting existing synchronous generators into synchronous condensers instead of constructing new units, reducing project costs and shortening deployment timelines. This approach allows operators to reuse existing grid infrastructure while providing inertia, voltage control, and short-circuit support needed for renewable energy integration. For example, several grid operators in Europe and Australia have successfully repurposed retired thermal power plant generators into synchronous condensers to support renewable-rich power systems, demonstrating the commercial viability of this approach.
Analyst Perspective
The synchronous condenser market is transitioning from a niche grid support segment to a strategic component of modern power systems as renewable energy penetration increases and conventional power plants are retired. Utilities are increasingly investing in synchronous condensers to provide inertia, reactive power compensation, and short-circuit strength, ensuring stable operation of renewable-dominated grids. Market competition is shifting beyond equipment supply toward integrated solutions that combine digital monitoring, predictive maintenance, and long-term service agreements. A key emerging trend is the conversion of retired thermal power plant generators into synchronous condensers, enabling utilities to enhance grid stability while reducing capital investment and accelerating project deployment.
Product Type Insights
Based on product type, the new synchronous condenser segment led the market with the largest revenue share of 71.2% in 2025. New synchronous condensers incorporate the latest technological advancements in terms of materials, design, and control systems. This includes improvements in rotor design, insulation materials, and advanced monitoring and control capabilities. Furthermore, they are designed to be more efficient in converting electrical energy into mechanical energy and vice versa. This efficiency contributes to better grid stability and management of reactive power, thereby, increasing their adoption in the market.
Refurbished product type is an older unit that has been overhauled, repaired, or upgraded to extend its operational life. They offer a cost-effective alternative to purchasing new equipment. Refurbishment can improve the performance and reliability of older synchronous condensers, bringing them closer to the efficiency levels of newer units. This includes enhancing control systems for better grid integration. However, refurbished units may have limitations in terms of customization compared to new synchronous condensers.
End-use Insights
Based on end-use, the electrical utilities segment led the market with the largest revenue share of 84.5% in 2025. Synchronous condensers are crucial for maintaining grid stability by providing inertia and reactive power support in electrical utility end use. They help stabilize voltage fluctuations and improve the overall reliability of electrical grids. Furthermore, as renewable energy sources like wind and solar power increase, this creates demand for synchronous condensers. This product plays a vital role in managing grid dynamics. They provide necessary inertia and help manage reactive power fluctuations, which are common with variable renewable sources.
 To learn more about this report, Download Free Sample Report
Industrial end use of synchronous condenser market is expected to grow at a significant CAGR of 1.5% over forecast period. In industrial sector, this product is used in steel industry, chemical plants, mining operations, pulp and paper mills, and oil & gas sector. The product helps in improve power factor and stabilize voltage in these industries, which is critical for maintaining operational efficiency and protecting equipment. Furthermore, it also helps in preventing fluctuations in power demand and supply, optimizing energy use, and reducing operational costs.
Regional Insights
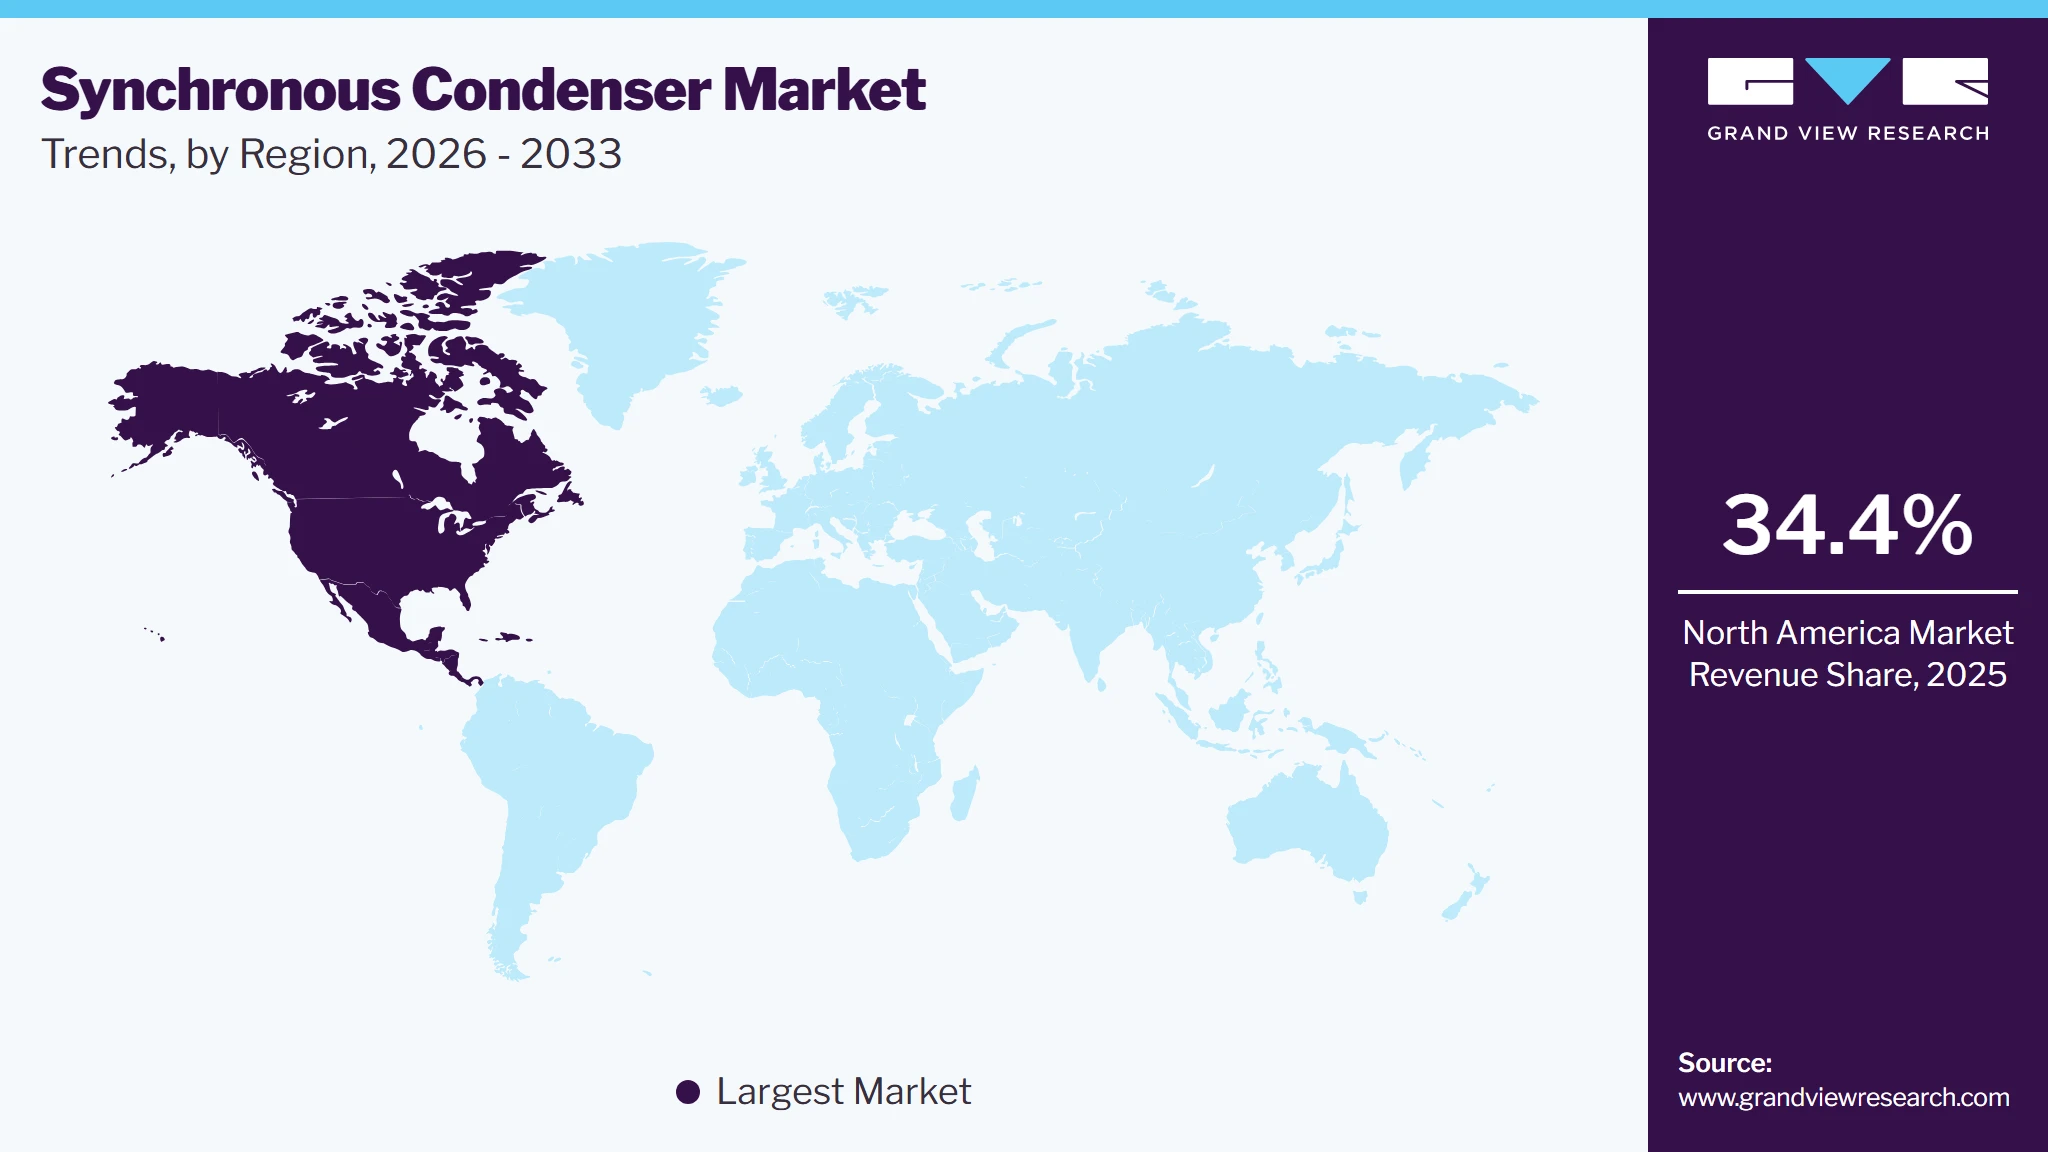
North America dominated the synchronous condenser market with the largest revenue share of 34.4% in 2025. North America is witnessing significant growth in renewable energy generation. Synchronous condensers help manage the variability of wind and solar power, ensuring grid stability and reliability. In addition to this, countries in North America have aging power infrastructures that require upgrades to meet current and future energy demands. This is further expected to increase product demand in region.
 To learn more about this report, Download Free Sample Report
U.S. Synchronous Condenser Market Trends
The synchronous condenser market in U.S. held the largest share in the North America region in 2025. Rising investments in grid reliability enhancements to mitigate power outages and improve overall system reliability is increasing product demand as this product helps in maintaining grid stability and supporting reliable electricity supply.
Europe Synchronous Condenser Market Trends
Demand for synchronous condenser in Europe is expected to grow at a significant rate over forecast period. Region is aggressively transitioning towards renewable energy sources like wind and solar. This product is essential here to stabilize grid frequency and voltage, manage intermittency, and support grid stability, thereby, boosting its adoption. Furthermore, demand is also driven by investments in modernizing grid infrastructure to enhance reliability and accommodate increasing renewable energy capacities.
Asia Pacific Synchronous Condenser Market Trends
Rapid industrialization and urbanization in countries like China and India are driving increased demand for electricity, which is increasing product use to support grid stability amidst this growing energy demand. Furthermore, governments across Asia Pacific are focusing on integrating renewable energy sources into their energy mix. This is further expected to drive product demand in region.
Key Synchronous Condenser Market Company Insights
Some of the key players operating in the market ABB and Siemens Energy:
-
ABB is Switzerland based leader in automation and electrification technology. The company provides a wide range of products under metallurgy products, electric drivetrains, motors & generators, industrial software, robotics, PLC automation, power converters and inverters, drives, control tool solutions, and low voltage products & systems. It offers these products for numerous industries, including oil & gas, automotive, cement, chemicals, mining, power generation, and pulp & paper products.
-
Siemens Energy is a leading energy technology provider for a wide range of industries, including oil & gas, power & heat generation, power transmission, marine, data centers, pulp & paper. Its product portfolio includes hybrid power plants operated with hydrogen, conventional and renewable energy technology, such as gas and steam turbines, and power generators and transformers. The company has approximately 99,000 employees who are working in more than 90 countries across the world.
IDEAL ELECTRIC POWER CO. and Ansaldo Energia S.p.A. are some of the emerging participants in the market.
-
IDEAL ELECTRIC POWER CO. was established in 1903 and headquartered in the U.S. It is a leading manufacturer of specialty electric motors and condensers, including synchronous generators, power systems and controls, and switchgear. The company is also one of the only U.S. producers to offer space-saving generator-mounted epicyclic gears.
-
Ansaldo Energia S.p.A. is an Italy-based manufacturer and service provider in the power generation industry. The company has expertise in conventional and next-generation technologies, from gas to nuclear energy and renewable energy. It offers its products and services under various segments, including power plants, equipment, and solutions for the energy transition, digital systems, nuclear, and services. The company employs approximately 3,300 people.
Key Synchronous Condenser Companies:
The following key companies have been profiled for this study on the synchronous condenser market.
-
ABB
-
Siemens Energy
-
IDEAL ELECTRIC POWER CO.
-
Ansaldo Energia S.p.A.
-
GE Vernova Inc.
-
Andritz AG
-
Voith
-
Fuji Electric
-
WEG
-
BRUSH
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ABB, Siemens Energy, Ansaldo Energia S.p.A., GE Vernova Inc., Andritz AG, Voith, Fuji Electric, WEG)
- Focus on expanding global manufacturing capacity and strengthening localized production to meet growing demand from utilities and grid modernization projects.
- Invest continuously in R&D to develop advanced synchronous condensers with higher reliability, greater reactive power capability, and improved operational efficiency.
- Strengthen market presence through long-term utility contracts, EPC partnerships, and expansion of grid stabilization and transmission equipment portfolios.
- Strong global brand recognition and long-standing relationships with utilities, grid operators, and EPC contractors.
- Comprehensive product portfolios covering synchronous condensers, generators, transformers, switchgear, and grid automation solutions.
- Extensive engineering expertise and proven experience in delivering large-scale, complex transmission and renewable integration projects.
- High manufacturing and operational costs compared to regional and niche competitors.
- Longer product development and project execution timelines due to complex organizational structures.
- Dependence on large utility and government infrastructure projects, which are often affected by lengthy approval cycles.
Emerging Players (IDEAL ELECTRIC POWER CO., BRUSH)
- Focus on customized synchronous condenser solutions tailored to specific grid stabilization and industrial power applications.
- Expand presence in regional markets through partnerships with EPC contractors, utilities, and local distributors.
- Invest selectively in product innovation to improve machine efficiency, compact designs, and retrofit capabilities.
- Greater flexibility in delivering customized solutions for specific customer and project requirements.
- Faster decision-making and shorter project execution timelines due to leaner organizational structures.
- Competitive pricing helps secure projects in cost-sensitive and developing markets.
- Limited global manufacturing footprint and lower production capacity compared to multinational competitors.
- Smaller R&D budgets restrict the pace of new product development and advanced technology adoption.
- Lower brand recognition and fewer long-term relationships with major utilities and transmission operators.
Recent Developments
-
In June 2024, GE Vernova Inc. announced the construction of two synchronous condenser facilities of 115 kV to improve grid stability in New York. This contract has been awarded by National Grid upstate New York business. With this, GE Vernova Inc. will able to support National Grid to meet the New York State’s goals to reduce carbon emissions by 85% by 2050.
Synchronous Condenser Market Report Scope
Report Attribute
Details
Market Definition
A synchronous condenser is a rotating machine used for voltage regulation and grid stability. The market size represents the revenue generated from the sales of new and refurbished synchronous condensers to electrical utilities and industrial end users.
Market size in 2025
USD 713.8 million
Estimated market size in 2026
USD 732.6 million
Projected market size by 2033
USD 895.5 million
Growth rate
CAGR of 2.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, End-use, Region
Regional scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, China, India, Japan, South Korea, Brazil, Argentina
Key companies profiled
ABB, Siemens Energy, IDEAL ELECTRIC POWER CO., Ansaldo Energia S.p.A., GE Vernova Inc., Andritz AG, Voith, Fuji Electric, WEG, BRUSH
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Synchronous Condenser Market Report Segmentation
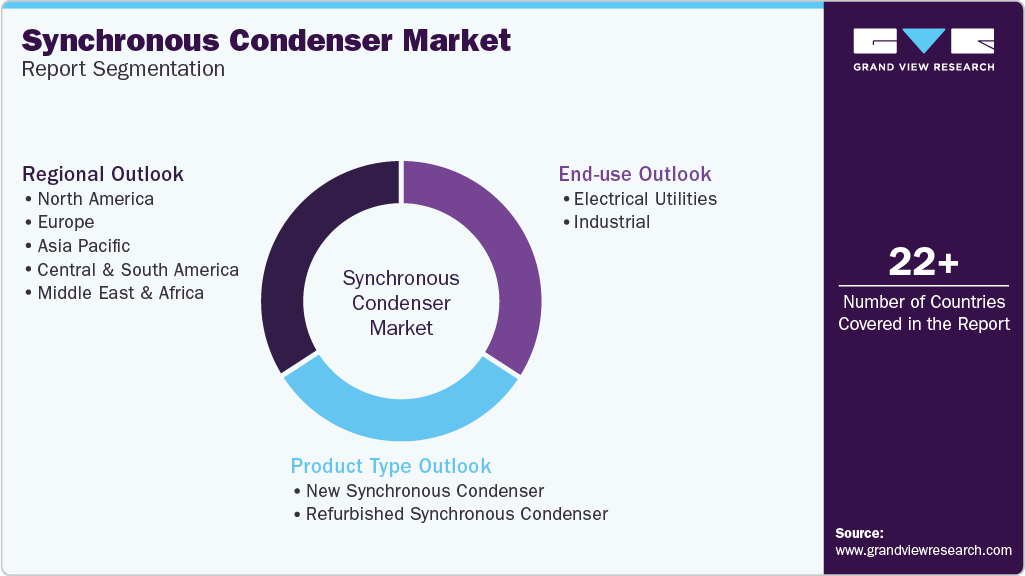
This report forecasts revenue growth at regional & country levels and provides an analysis of the industry trends in each of the segments from 2021 to 2033. For this study, Grand View Research has segmented the synchronous condenser market based on product type, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
New Synchronous Condenser
-
Refurbished Synchronous Condenser
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Electrical Utilities
-
Industrial
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Research Methodology
The synchronous condenser market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each synchronous condenser segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
New Synchronous Condenser
Revenue represents the sales of newly manufactured synchronous condensers installed to provide voltage regulation, reactive power compensation, and grid stability across utility and industrial power systems.
Refurbished Synchronous Condenser
Revenue represents the sales of refurbished or converted synchronous condensers, including retrofitted synchronous generators, deployed to deliver cost-effective grid stabilization and voltage support.
Segment - End-use
Revenue capture definition
Electrical Utilities
Comprises revenue from synchronous condensers deployed across power generation, transmission, and distribution networks to enhance grid stability, voltage regulation, and reactive power support.
Industrial
Includes revenue from synchronous condensers installed in manufacturing plants, mining operations, refineries, and other industrial facilities to improve power quality, voltage control, and system reliability.
Estimation Model
Layer Name
Key Question
Description
Synchronous Condenser Demand Layer
What drives the demand for synchronous condensers?
Identify the key demand drivers for synchronous condensers, including increasing renewable energy integration, retirement of conventional power plants, grid modernization initiatives, transmission network expansion, and rising investments in grid stability and reactive power compensation.
Product Type Layer
Which product types are widely adopted?
Analyze market adoption based on product type, including new and refurbished synchronous condensers. Assess demand based on installation costs, project requirements, asset repurposing initiatives, and utility investment strategies.
End Use Layer
Which end-use sectors generate the highest demand?
Evaluate demand across electrical utilities and industrial end users. Assess adoption based on grid stability requirements, renewable energy integration, power quality improvement, and investments in transmission, distribution, and industrial power systems.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sales of new and refurbished synchronous condensers supplied to electrical utilities and industrial end users. The overall market value is determined by revenue generated from equipment sales for grid stability, voltage regulation, and reactive power compensation.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Opportunity Assessment
A detailed country- and region-level assessment of the synchronous condenser market by analyzing renewable energy integration, transmission network expansion, utility investments, grid modernization initiatives, and evolving power system stability requirements. The study highlights demand potential, upcoming opportunities, and the regulatory environment influencing adoption across key regions.
Identifies high-growth markets, prioritizes expansion strategies, and supports investment decisions based on regional demand potential.
Competitive Benchmarking
A comprehensive comparison of leading synchronous condenser manufacturers based on product portfolio, technology capabilities, regional presence, project experience, strategic initiatives, and service offerings. The analysis also evaluates each company's competitive positioning, recent developments, and focus areas to identify key differentiators in the market.
Helps companies understand competitive dynamics, identify market gaps, benchmark performance, and develop effective growth and positioning strategies.
Cross-Segmentation Analysis
A detailed assessment of the adoption of new and refurbished synchronous condensers across the industrial segment. The analysis evaluates demand across industries such as mining, metals, oil & gas, and manufacturing by comparing purchasing preferences, replacement trends, and application requirements for each product type.
Enables manufacturers to identify high-potential industrial applications, align product offerings with customer requirements, and optimize sales and market entry strategies.
Frequently Asked Questions About This Report
North America is anticipated to register the second fastest CAGR of 3.0% over the forecast period.
Based on product type, the new synchronous condenser segment accounted for the largest revenue share of 71.2% in 2025.
Based on end-use, the electrical utilities segment accounted for the largest revenue share of 84.5% in 2025.
The key players operating in the synchronous condenser market are ABB, Siemens Energy, Ansaldo Energia S.p.A., GE Vernova Inc., Andritz AG, Voith, Fuji Electric, WEG, IDEAL ELECTRIC POWER CO., BRUSH, and others.
The key factors driving the synchronous condenser market include increasing renewable energy integration, grid modernization initiatives, expansion of transmission networks, and the rising need for voltage regulation, reactive power compensation, and grid stability.
The North America region dominated the synchronous condenser market with a revenue share of 34.4% in 2025.
The global synchronous condenser market size was valued at USD 713.8 million in 2025 and is estimated at USD 732.6 million for 2026.
The global synchronous condenser market is expected to grow at a CAGR of 2.9% from 2026 to 2033, reaching USD 895.5 million by 2033.
The U.S. dominated the North American market with a revenue share of 74.3% in 2025.
About the Author(s)
Distribution & Utilities Research Team
Energy & Power · Distribution & UtilitiesThis report was authored by the distribution & utilities research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the distribution & utilities segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


