
- Home
- »
- Advanced Interior Materials
- »
-
Tray Former Machines Market Size And Share Report, 2033GVR Report cover

Tray Former Machines Market (2026 - 2033)
Size, Share & Trends Analysis Report By Machine Type (Fully Automatic, Semi-Automatic), By Tray Type (Corrugated Trays, Paperboard Trays), By End Use (Pharmaceuticals, Food & Beverage), By Region, And Segment Forecasts
Market Size, 2025
$1.9BMarket Estimate, 2026
$2.0BMarket Forecast, 2033
$2.8BCAGR, 2026–2033
4.8%Tray Former Machines Market Summary
The global tray former machines market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 2.0 billion in 2026 to USD 2.8 billion by 2033, at a CAGR of 4.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 37.5% in 2025. Growth is driven by increasing industrialization, stricter environmental regulations, and rising wastewater treatment demands.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By machine type: Fully automatic segment led the market with the largest revenue share of 57.4% in 2025.
- By tray type: Corrugated trays segment led the market with the largest revenue share of 57.0% in 2025.
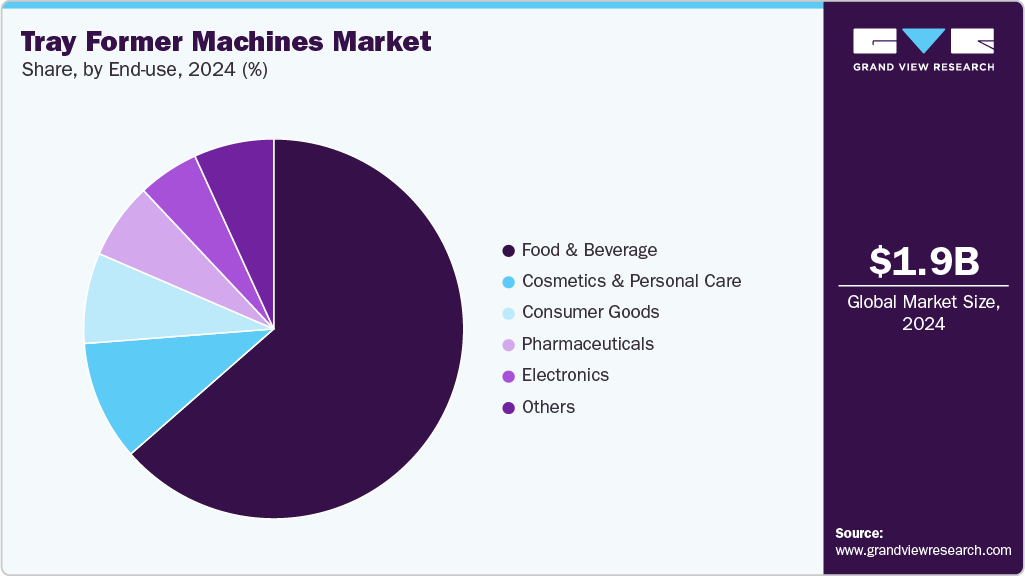
- By end use: Food & beverage segment led the market with the largest revenue share of 63.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (37.5% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 2.0 Billion
- Projected market size by 2033: USD 2.8 Billion
- CAGR (2026-2033): 4.8%
Prism AI by Grand View Research Free to tryAsk a question about the tray former machines marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →As consumers increasingly prefer ready-to-eat meals and convenience foods, manufacturers are turning to efficient, high-speed packaging solutions to meet this demand. In addition to the growing food sector, the push for automation and improved operational efficiency across industries is fueling the adoption of tray former machines. Companies are increasingly investing in automated packaging systems to enhance productivity, ensure consistent tray quality, and reduce human error. Tray formers offer precise, reliable performance and can be seamlessly integrated into existing production lines, supporting the shift toward smart manufacturing and Industry 4.0 initiatives. This demand for automation is expected to remain a strong growth factor in the global tray former machines industry.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The tray former machines market is shaped by the growing need for high-speed, automated packaging solutions that improve production efficiency, reduce labor dependency, and ensure consistent tray quality across manufacturing operations. Expansion of the food & beverage, e-commerce, consumer goods, pharmaceutical, and logistics industries continues to increase demand for corrugated trays used for product transportation and retail-ready packaging. Manufacturers are investing in flexible tray forming systems capable of handling multiple tray sizes and formats with minimal changeover time, while the integration of robotics, servo-driven controls, and smart monitoring technologies enhances equipment productivity and operational reliability. At the same time, increasing adoption of recyclable corrugated packaging, stringent packaging quality requirements, and the shift toward sustainable packaging practices are encouraging replacement of conventional manual processes with advanced tray former machines.
Manufacturers are investing in automated tray former machines to increase packaging throughput, reduce manual labor, and achieve consistent tray quality. The growing use of corrugated trays in food & beverage, e-commerce, consumer goods, and logistics has strengthened demand for high-speed tray forming equipment capable of handling multiple tray sizes with minimal changeover time. The expansion of retail-ready and shelf-ready packaging formats is further increasing the need for reliable tray forming solutions. Continuous investments in automated end-of-line packaging systems are also encouraging the deployment of advanced tray former machines across high-volume production facilities.
Tray former machines require substantial capital investment, particularly for fully automatic systems integrated with case packing, conveying, and palletizing lines. Installation, customization, and maintenance costs, along with production downtime during system integration, can discourage adoption among small and medium-sized manufacturers. In addition, the need for skilled personnel to operate, program, and maintain automated equipment increases operational expenses. Limited production volumes in smaller facilities often make it difficult to justify the return on investment for advanced tray former systems.
Demand for packaging flexibility is encouraging manufacturers to develop tray former machines with servo-driven controls, robotic integration, and digital monitoring capabilities. Equipment that supports rapid format changes, remote diagnostics, predictive maintenance, and efficient processing of recyclable corrugated materials is gaining preference as manufacturers seek to improve operational efficiency and accommodate diverse packaging requirements. The introduction of modular machine architecture that can be upgraded with additional automation features is creating new growth opportunities for equipment manufacturers.
Market Concentration & Characteristics
The global tray former machines industry is fragmented, characterized by the presence of numerous regional and international players. While a few large companies hold significant market share due to their broad product portfolios and global reach, many small and medium-sized manufacturers compete by offering customized or cost-effective solutions tailored to local markets. The diversity in application areas, ranging from food and beverages to pharmaceuticals and industrial packaging, also contributes to the fragmented nature of the market, allowing niche players to thrive alongside larger corporations.
The tray former machines industry exhibits a moderate to high degree of innovation, driven by the demand for faster, more energy-efficient, and automated packaging solutions. Innovations focus on improving machine flexibility to handle various tray sizes, enhancing user interfaces, and integrating smart technologies for predictive maintenance. Sustainability is also influencing innovation, with machines increasingly designed to accommodate eco-friendly materials.
 To learn more about this report, Download Free Sample Report
The level of M&A activity in the tray former machines industry is moderate, with strategic acquisitions primarily aimed at expanding technological capabilities and geographic presence. Larger players often acquire smaller firms to access new customer segments, specialized machinery, or innovative packaging technologies. These moves help companies strengthen their market positions and diversify product offerings. However, the fragmented nature of the market limits the frequency of large-scale mergers.
Regulations significantly impact the tray former machines industry, particularly in industries like food, pharmaceuticals, and consumer goods. Manufacturers must comply with strict hygiene, safety, and environmental standards, influencing machine design and material compatibility. In addition, increasing regulatory pressure to reduce plastic use and encourage sustainable packaging is shaping machine capabilities. Compliance with regional standards (e.g., FDA, EU directives) also affects market entry and competitiveness.
Analyst Perspective
The tray former machines market is growing steadily as manufacturers increasingly automate end-of-line packaging operations to improve productivity, reduce labor dependency, and enhance packaging consistency. Growing demand for packaged food, beverages, pharmaceuticals, cosmetics, and e-commerce shipments is driving investments in high-speed tray forming equipment capable of supporting continuous production environments. In addition, the increasing use of corrugated and paperboard trays as sustainable packaging alternatives is encouraging the adoption of flexible tray former machines that can accommodate multiple tray formats with minimal changeover time. Advancements in servo-driven systems, robotic integration, and smart controls are further improving machine efficiency, operational reliability, and production flexibility. As packaging manufacturers continue to prioritize automation, sustainability, and higher throughput, suppliers offering high-performance, fully automatic, and application-specific tray former machines are expected to benefit from sustained long-term market growth.
Machine Type Insights
Based on machine type, the fully automatic segment led the market with the largest revenue share of 57.4% in 2025, due to its high efficiency, speed, and minimal need for human intervention. They are ideal for large-scale operations that require consistent output and precision. Industries such as food processing and logistics prefer these machines for their ability to reduce labor costs and increase throughput. Their compatibility with advanced automation systems also supports their widespread adoption.
The semi-automatic segment is anticipated to grow at the fastest CAGR during the forecast period, particularly among small to medium-sized enterprises. These machines offer a balance between cost and functionality, making them attractive for operations with lower volume or limited budgets. They provide flexibility and ease of use while still enhancing productivity compared to manual methods. Their lower initial investment makes them suitable for businesses transitioning to automation.
End Use Insights
Based on end use, the food & beverage segment led the market with the largest revenue share of 63.6% in 2025, owing to the high demand for packaged and ready-to-eat products. The need for hygienic, efficient, and reliable packaging solutions to preserve freshness drives widespread adoption. In addition, the diversity of food products requires versatile tray-forming machines. Growing consumer preference for convenience foods further fuels this dominance.
 To learn more about this report, Download Free Sample Report
The pharmaceutical segment is anticipated to grow at the fastest CAGR during the forecast period, because of strict regulatory requirements for sterile and tamper-evident packaging. Tray former machines ensure precise and contamination-free packaging of medicines and medical devices. Increasing healthcare demand and the rise of personalized medicine also contribute to rapid market growth. Technological advancements tailored for pharma packaging enhance this expansion.
Tray Type Insights
Based on tray type, the corrugated trays segment led the market with the largest revenue share of 57.0% in 2025. Corrugated trays dominate the market because of their excellent strength, durability, and cushioning properties, making them ideal for transporting heavy and fragile goods. Their cost-effectiveness and recyclability further support widespread use across industries like food, electronics, and logistics. The versatility of corrugated material allows for customization in size and design.
The paperboard trays segment is anticipated to grow at the fastest CAGR during the forecast period, due to increasing consumer demand for sustainable and eco-friendly packaging solutions. Their lightweight nature reduces shipping costs and carbon footprint, aligning with environmental regulations and corporate sustainability goals. Advances in paperboard technology have improved durability and moisture resistance. This growing preference for green packaging drives rapid adoption in the food and retail sectors.
Regional Insights
The tray former machines market in North America held a significant share in 2024, due to advanced manufacturing infrastructure and high demand from the food, pharmaceutical, and consumer goods sectors. The region benefits from strong automation adoption and stringent regulatory standards that drive the need for efficient packaging solutions. Innovation and R&D investments by key players also support market growth. In addition, consumer preference for convenience foods boosts demand.
U.S. Tray Former Machines Market Trends
The tray former machines market in the U.S. is expected to grow at the fastest CAGR of 4.5% from 2025 to 2033. The market growth is driven by its advanced manufacturing infrastructure and high demand from the food, pharmaceutical, and consumer goods sectors. The robust food and beverage industry, coupled with a strong emphasis on automation and sustainability, propels the adoption of tray forming machines. Technological advancements and the need for efficient packaging solutions further contribute to the market's growth.
The Mexico tray former machines market is experiencing significant growth, fueled by increased demand for packaging machinery and materials. The country's strategic geographic location, participation in trade agreements like the USMCA, and rising consumption of packaged goods across industries contribute to this growth. Investments in food and beverage sectors, along with a shift towards sustainable and automated packaging solutions, further drive the adoption of tray forming machines.
Europe Tray Former Machines Market Trends
The tray former machines market in Europe holds a significant market share, driven by strict environmental regulations and a strong focus on sustainable packaging. The presence of well-established packaging manufacturers and growing automation trends fuels adoption. Demand from the pharmaceutical and food industries remains robust due to quality and safety standards. The region’s emphasis on reducing plastic use propels innovations in eco-friendly tray forming machines.
The Germany tray former machines market is experiencing steady growth, driven by the country's strong manufacturing sector and emphasis on automation. The food and beverage industry, a significant end-user, requires efficient and sustainable packaging solutions, propelling the demand for tray forming machines. In addition, Germany's commitment to environmental regulations encourages the adoption of eco-friendly packaging technologies.
The tray former machines market in the UK is witnessing notable growth, fueled by increasing demand for packaged goods and advancements in packaging technologies. The pharmaceutical sector's stringent packaging requirements drive the need for precise and reliable tray forming solutions.
Asia Pacific Tray Former Machines Market Trends
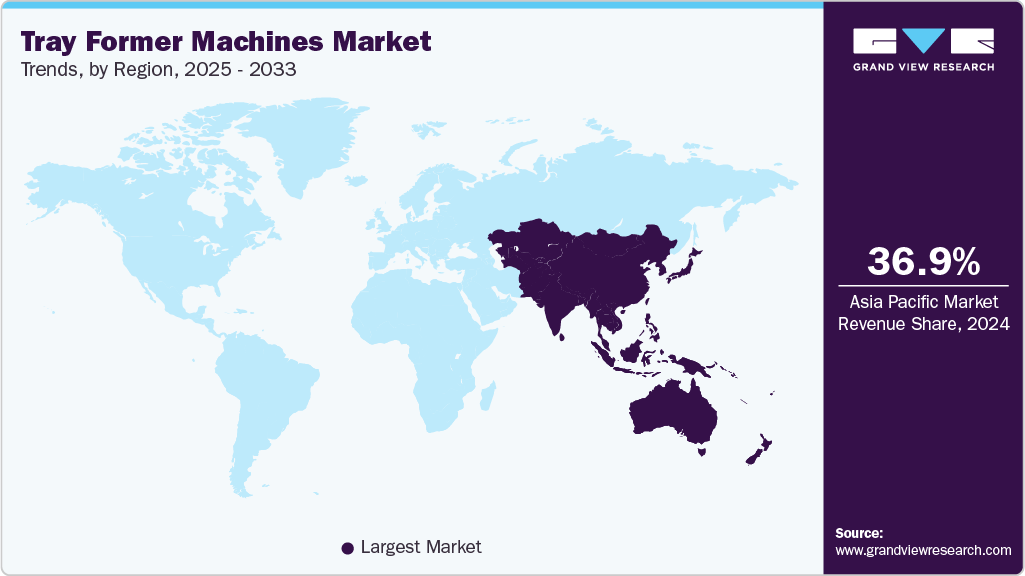
Asia Pacific dominated the tray former machines market with the largest revenue share of 37.5% in 2025, owing to rapid industrialization, urbanization, and rising disposable incomes, especially in countries like China and India. The expanding food processing and pharmaceutical sectors fuel demand for efficient packaging machinery. Growing awareness of automation benefits and government initiatives supporting manufacturing modernization further accelerate market growth. The region’s vast consumer base presents significant opportunities.
 To learn more about this report, Download Free Sample Report
The tray former machines market in China held the largest share in the Asia Pacific region in 2025. The tray former machines market in China accounted for the largest market revenue share in Asia Pacific in 2024, driven by its robust manufacturing capabilities and significant demand from the food and beverage industry. The nation's extensive industrial base and emphasis on automation have bolstered the adoption of tray forming technologies. In addition, China's commitment to sustainable packaging solutions has spurred the development and implementation of eco-friendly tray forming machines.
The India tray former machines market is witnessing rapid growth, fueled by increasing urbanization and a burgeoning food processing sector. The rising demand for packaged foods and beverages necessitates efficient and automated packaging solutions. Moreover, India's focus on sustainability and reducing plastic usage aligns with the adoption of recyclable and biodegradable tray forming technologies.
Middle East & Africa Tray Former Machines Market Trends
The tray former machines market in the Middle East and Africa trends are shaped by increasing demand for packaged food and pharmaceuticals amid growing populations and urbanization. Investments in industrial infrastructure and government support for manufacturing diversification are encouraging the adoption of advanced packaging machinery. However, slower automation uptake compared to other regions presents challenges. Rising awareness of sustainability is beginning to influence packaging preferences.
The United Arab Emirates (UAE) tray former machines market is experiencing significant growth, driven by its strategic position as a logistics and manufacturing hub in the Middle East. The establishment of the Khalifa Industrial Zone Abu Dhabi (KIZAD) underscores the UAE's commitment to industrial diversification and foreign investment, providing a conducive environment for packaging machinery.
Latin America Tray Former Machines Market Trends
The tray former machines market in Latin America is anticipated to grow at a significant CAGR during the forecast period, driven by increasing investments in food and beverage manufacturing and expanding pharmaceutical industries. Growing urban populations and rising demand for packaged goods create strong market potential. In addition, improving infrastructure and greater adoption of automation technologies contribute to rapid growth. Local manufacturers are also upgrading capabilities to meet international quality standards.
The Brazil tray former machines market is experiencing significant growth, driven by its status as the largest economy in South America and a rapidly expanding manufacturing sector. The country's vast consumer base, coupled with increasing urbanization and a rising middle class, is fueling the demand for packaged goods, particularly in the food and beverage industry. This surge in demand necessitates efficient and automated packaging solutions, propelling the adoption of tray forming technologies.
Key Tray Former Machines Company Insights
Some of the key players operating in the market include Wayne Automation, Wexxar Packaging, Inc., AFA Systems Inc.
-
Wayne Automation is a prominent player in the packaging machinery industry, known for its expertise in designing and manufacturing high-performance case and tray forming equipment. The company serves major sectors such as food, beverage, and consumer goods with a strong focus on automation and reliability. With decades of experience, it has built a solid reputation for delivering customized packaging solutions. Wayne Automation’s industry presence is marked by innovation and long-standing client relationships across North America.
-
Wexxar Packaging, Inc., a division of ProMach, specializes in case and tray forming, sealing, and packaging solutions, primarily for the food, beverage, and healthcare industries. The company is well regarded for its reliable and flexible machinery that supports both automatic and semi-automatic operations. With a strong footprint in North America and global reach through ProMach’s network, Wexxar emphasizes durability, serviceability, and integration into complex packaging lines. Its solutions cater to both high-volume manufacturers and small-scale operations.
Key Tray Former Machines Companies
The following key companies have been profiled for this study on the tray former machines market.
-
Wayne Automation
-
Wexxar Packaging, Inc.
-
AFA Systems Inc.
-
ADCO Manufacturing.
-
Combi Packaging Systems, LLC
-
Paxiom
-
Crown Packaging Corp.
-
Sacmi
-
DS Smith
-
Gietz
-
Econcorp
-
Boix Maquinaria, S.L.
-
Mibox
-
Heiber + Schröder Maschinenbau GmbH
-
W. H. Leary
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Wexxar Packaging Inc., Boix Maquinaria, S.L., Combi Packaging Systems, LLC, ADCO Manufacturing, Heiber + Schröder Maschinenbau GmbH)
Focus on manufacturing high-speed, fully automatic tray former machines and complete end-of-line packaging systems for food & beverage, consumer goods, and industrial applications.
Invest in automation technologies, servo-driven systems, product portfolio expansion, and global sales and service networks to strengthen market position and long-term customer relationships
Extensive engineering expertise, established manufacturing capabilities, and comprehensive product portfolios covering a wide range of tray formats and production capacities.
Strong global distribution and after-sales service networks, proven equipment reliability, and the ability to deliver customized turnkey packaging solutions.
High capital investment required for continuous product development, manufacturing expansion, and automation upgrades.
Longer sales cycles and dependence on industrial capital expenditure, making demand susceptible to economic slowdowns and supply chain disruptions.
Emerging & Regional Players (e.g., AFA Systems Ltd., Wayne Automation Corporation, Econocorp Inc., Paxiom Group, Mibox NV.)
Focus on customized tray former machines, application-specific packaging solutions, and flexible automation systems tailored to regional customer requirements.
Strengthen market presence through engineering innovation, customer collaboration, distributor partnerships, and cost-effective equipment offerings for niche applications.
Greater flexibility to develop customized tray forming solutions with faster project execution and shorter lead times.
Strong responsiveness to customer-specific packaging requirements and the ability to serve specialized industries with tailored automation systems.
Limited manufacturing scale, international distribution, and financial resources compared to established global competitors.
Lower global brand recognition and limited capability to undertake large turnkey projects or extensive investments in advanced automation technologies and worldwide service infrastructure.
Recent Developments
-
In April 2025, EndFlex has unveiled its Vassoyo tray forming machine, engineered specifically for corrugated beverage trays. This advanced equipment features a heavy-duty tubular frame and offers easy changeovers between various tray sizes, enhancing operational flexibility. Equipped with both 1-up and 2-up configurations, it caters to diverse production speeds. An intuitive touchscreen interface provides servicing guides and changeover instructions, streamlining operations and reducing downtime
-
In June 2024, At drupa 2024, Gietz AG demonstrated its advanced tray forming technology, including the HTF 940 model designed for efficient production of two-compartment trays and doggy bags. The machine operated using specially prepared paper blanks from Holmen Iggesund, with printing and die-cutting by PAWI Packaging Schweiz AG, and gluing by W.H. Leary.
Tray Former Machines Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 billion
Estimated market size in 2026
USD 2.0 billion
Projected market size by 2033
USD 2.8 billion
Growth rate
CAGR of 4.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Machine type, tray type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; China; Japan; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Wexxar Packaging Inc.; Boix Maquinaria, S.L.; Combi Packaging Systems, LLC; ADCO Manufacturing; AFA Systems Ltd.; Wayne Automation Corporation; Econocorp Inc.; Heiber + Schröder Maschinenbau GmbH; Paxiom Group; Mibox NV.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Tray Former Machines Market Report Segmentation
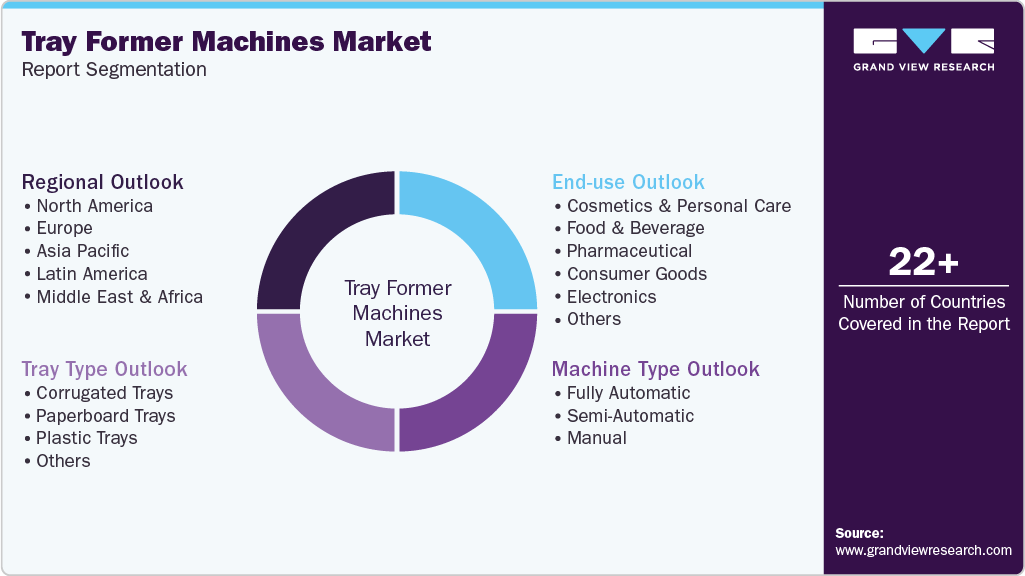
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global tray former machines market report based on machine type, tray type, end use and region.
 To learn more about this report, Download Free Sample Report
-
Machine Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Fully Automatic
-
Semi-Automatic
-
Manual
-
-
Tray Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Corrugated Trays
-
Paperboard Trays
-
Plastic Trays
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Cosmetics & Personal Care
-
Food & Beverage
-
Ready-to-eat meals
-
Meat, poultry & seafood
-
Dairy products
-
Fruits & vegetables
-
Bakery & confectionery
-
Others
-
-
Pharmaceutical
-
Consumer Goods
-
Electronics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The tray former machines Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each tray former machines Market segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Machine Type
Revenue Capture Definition
Fully Automatic
Revenue is generated from the sale of fully automatic tray former machines designed for high-speed, continuous tray forming with automated feeding, folding, gluing, and discharge operations.
Semi-Automatic
Revenue is generated from the sale of semi-automatic tray former machines that combine automated tray forming functions with manual loading or handling operations.
Manual
Revenue is generated from the sale of manually operated tray former machines used for low-volume production and small-scale packaging operations.
Segment - Tray Type
Revenue Capture Definition
Corrugated Trays
Revenue is generated from the sale of tray former machines designed to produce corrugated trays for transportation, retail-ready packaging, and industrial distribution.
Paperboard Trays
Revenue is generated from the sale of tray former machines used to manufacture paperboard trays for food, consumer goods, pharmaceuticals, and retail packaging applications.
Plastic Trays
Revenue is generated from the sale of tray former machines configured to produce plastic trays for applications requiring durable and protective packaging.
Others
Revenue is generated from the sale of tray former machines designed for specialty tray formats and alternative packaging materials used in niche applications.
Segment - End Use
Revenue Capture Definition
Cosmetics & Personal Care
Revenue is generated from the sale of tray former machines used to produce trays for cosmetics, skincare, personal care, fragrance, and toiletry packaging.
Food & Beverage
Revenue is generated from the sale of tray former machines used to manufacture trays for ready-to-eat meals, meat, poultry & seafood, dairy products, fruits & vegetables, bakery & confectionery products, beverages, and other food products requiring retail-ready and transit packaging.
Pharmaceutical
Revenue is generated from the sale of tray former machines used to produce trays for pharmaceuticals, medical devices, diagnostic kits, and healthcare products.
Consumer Goods
Revenue is generated from the sale of tray former machines used for packaging household products, cleaning products, toys, office supplies, and other consumer goods.
Electronics
Revenue is generated from the sale of tray former machines used to manufacture protective trays for electronic devices, electrical components, and accessories.
Others
Revenue is generated from the sale of tray former machines supplied to automotive, industrial manufacturing, logistics, agriculture, e-commerce, and other specialized industries requiring customized tray packaging solutions.
Estimation Model
Layer Name
Key Question
Description
Packaging Automation Demand Layer
Where are tray former machines required?
Analyze demand across food & beverage, cosmetics & personal care, pharmaceuticals, consumer goods, e-commerce, and other packaging-intensive industries. Assess production volumes, secondary packaging requirements, case packing operations, and automation needs to establish the addressable demand for tray former machines.
Manufacturing & Packaging Capacity Expansion Layer
Where is new equipment demand being created?
Evaluate investments in food processing plants, beverage production facilities, consumer goods manufacturing, pharmaceutical packaging lines, and logistics centers. Assess greenfield projects, production line expansions, packaging automation upgrades, and replacement of manual or semi-automatic systems that drive procurement of new tray former machines.
Product Adoption Layer
Which tray former machine technologies are being deployed?
Segment demand by machine type, tray type, end-use industry, and production capacity. Apply adoption rates based on packaging speed, tray material, production throughput, labor optimization, operational flexibility, and integration with existing packaging lines. Assess the increasing adoption of fully automatic and robotic tray forming systems to improve efficiency, consistency, and operational productivity.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of tray former machines by machine type, tray type, end-use industry, and region. Quantify revenues generated exclusively from the sale of new tray former machines supplied to packaging facilities, OEMs, system integrators, and contract packaging companies.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
A competitive benchmarking analysis was conducted by evaluating leading tray former machine manufacturers based on product portfolio, automation capabilities, manufacturing footprint, technological innovation, and competitive positioning.
This benchmarking enabled stakeholders to assess competitive strengths, identify product differentiation opportunities, understand evolving market strategies, and develop informed competitive positioning.
Regional Segmentation
A comprehensive regional analysis was conducted by assessing demand for tray former machines, packaging automation trends, manufacturing activity, and country-level market contributions across key regions.
The regional assessment enabled stakeholders to identify high-growth markets, optimize expansion strategies, and align product offerings with regional industry requirements.
Opportunity Assessment
A detailed opportunity assessment was conducted by evaluating automation trends, demand for corrugated tray packaging, technological advancements, and expanding end-use industries driving tray former machine adoption.
This assessment enabled stakeholders to identify high-growth investment opportunities, align product development with market demand, and capitalize on emerging automation and sustainable packaging trends.
Frequently Asked Questions About This Report
The fully automatic segment led the market with the largest revenue share of 57.4% in 2025.
The corrugated trays segment accounted for the largest revenue share of 57.0% in 2025.
The food & beverage segment led the market with the largest revenue share of 63.6% in 2025.
China held the largest share of the Asia Pacific tray former machines market in 2025.
The global tray former machines market size was estimated at USD 1.9 billion in 2025 and is expected to be USD 2.0 billion in 2026.
Asia Pacific dominated the tray former machines market with the largest revenue share of 37.5% in 2025.
Some of the key players operating in the global sludge dewatering equipment market include Wexxar Packaging Inc.; Boix Maquinaria, S.L.; Combi Packaging Systems, LLC; ADCO Manufacturing; AFA Systems Ltd.; Wayne Automation Corporation; Econocorp Inc.; Heiber + Schröder Maschinenbau GmbH; Paxiom Group; Mibox NV.
Key factors include increasing automation of packaging operations, rising demand for packaged food and beverages, growth in e-commerce and retail-ready packaging, expanding manufacturing capacity, and the need to improve packaging efficiency while reducing labor costs.
The global tray former machines market, in terms of revenue, is expected to grow at a compound annual growth rate of 4.8% from 2026 to 2033 to reach USD 2.8 billion by 2033.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


