
- Home
- »
- Automotive & Transportation
- »
-
Truck Refrigeration Unit Market Size Report, 2026-2033GVR Report cover

Truck Refrigeration Unit Market (2026 - 2033)
Size, Share & Trends Analysis Report By System Type (Diesel-engine TRUs, Electric TRUs (eTRUs)), By Sales Channel, By Vehicle Type, By Mount Location, By End-use Industry, By Region, And Segment Forecasts
Market Size, 2025
$7.2BMarket Estimate, 2026
$7.7BMarket Forecast, 2033
$13.1BCAGR, 2026–2033
7.8%Truck Refrigeration Unit Market Summary
The global truck refrigeration unit market size was valued at USD 7.2 billion in 2025 and is projected to grow from USD 7.7 billion in 2026 to USD 13.1 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.6% of the global revenue in 2025. The expansion of global cold-chain logistics and the rising demand for temperature-controlled transportation are major market drivers.
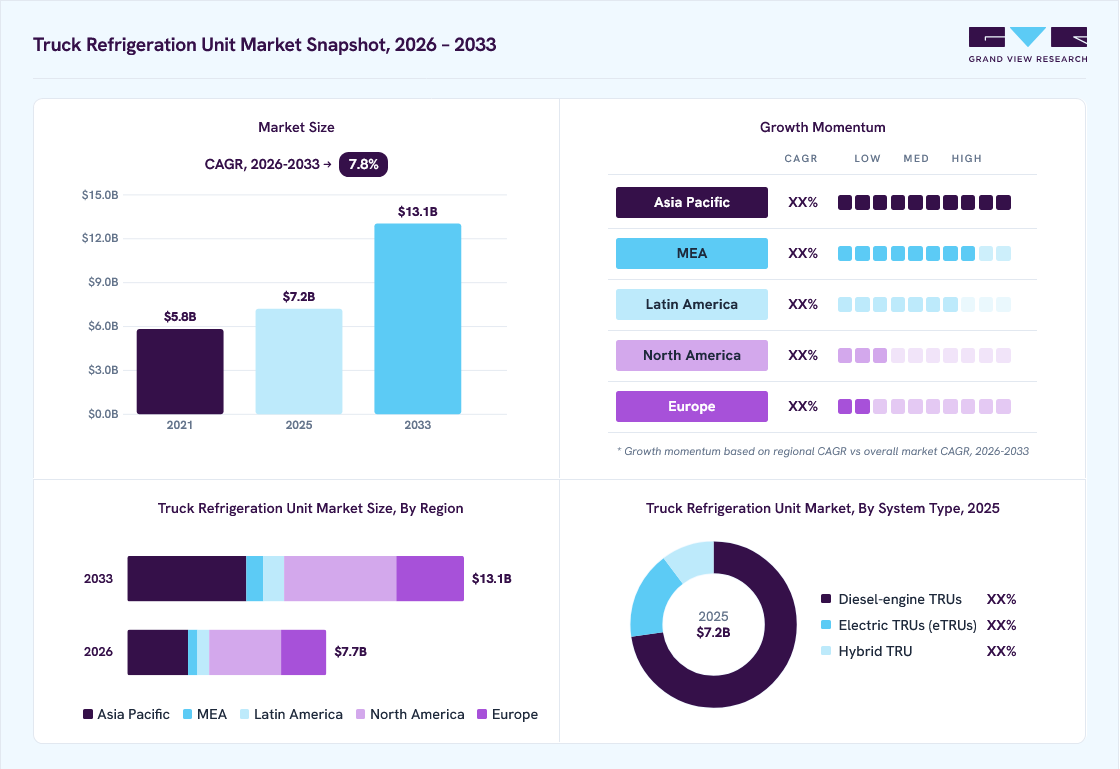 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By system type: Diesel-engine TRUs segment led the market and accounted for revenue share of 72.6% in 2025
- By sales channel: Factory-fit segment accounted for largest share of 76.3% in 2025
- By vehicle type: HCV segment accounted for the highest revenue share of 37.5% in 2025
- By mount location: Roof-mount segment held the largest market share in 2025
- By on end-use industry: Food & beverage logistics segment led the market in 2025
Regional Highlights
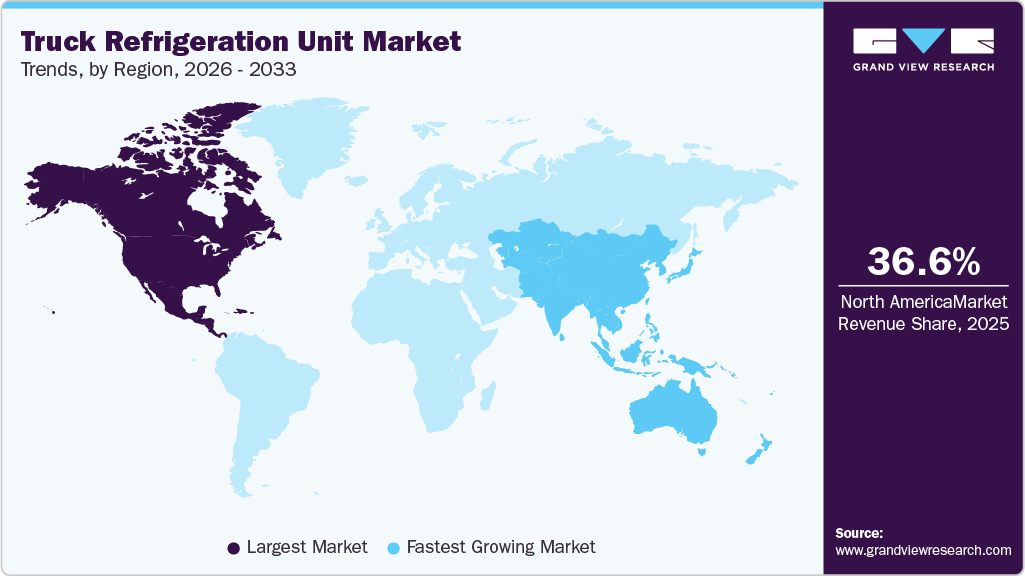
- Largest regional market: North America (36.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.2 Billion
- Estimated market size in 2026: USD 7.7 Billion
- Projected market size by 2033: USD 13.1 Billion
- CAGR (2025-2033): 7.8%
Prism AI by Grand View Research Free to tryAsk a question about the truck refrigeration unit marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Increased consumption of perishable food products, such as dairy, meat, seafood, and frozen foods, has been observed across both developed and emerging economies. The growing demand for temperature-sensitive pharmaceutical products has also led to the expansion of distribution networks that require strict temperature compliance. As a result, greater deployment of refrigerated transportation systems has been witnessed across global supply chains. Furthermore, the rapid expansion of organized retail and cross-border food trade has been supporting the demand for reliable refrigerated trucking solutions across long-haul and regional logistics networks.The increasing transition toward electric refrigeration systems is further propelling the growth of the market. Growing concerns regarding emissions from diesel-powered truck refrigeration units (TRUs) have led to the development and adoption of electric and hybrid refrigeration technologies. These systems are being integrated with battery-powered and electric commercial vehicles to reduce fuel consumption and operational emissions. With sustainability initiatives being prioritized across logistics operations, electric TRUs are increasingly being deployed, particularly in urban delivery fleets and low-emission zones.
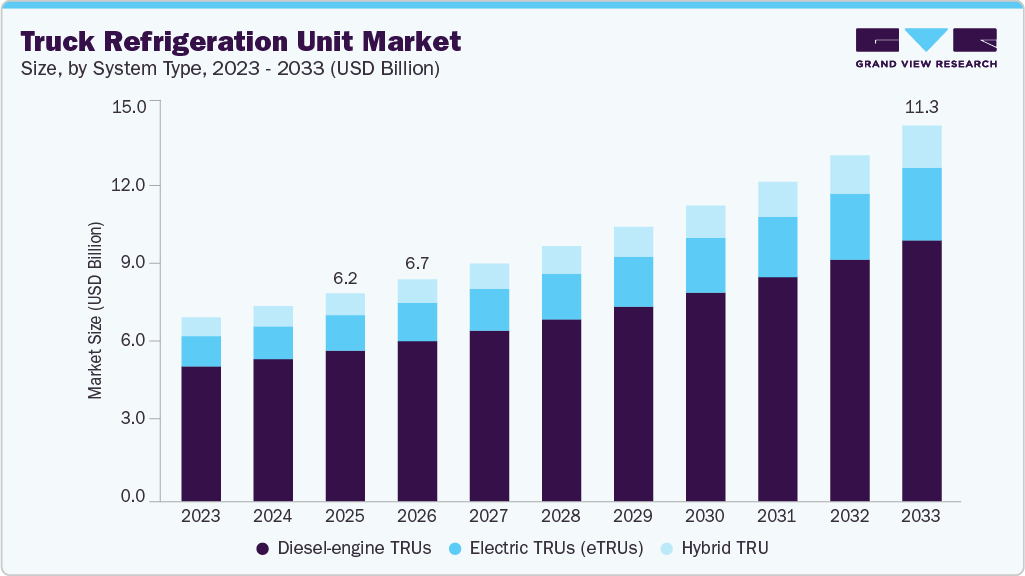 To learn more about this report, Download Free Sample Report
The integration of telematics and IoT-based monitoring solutions has been gaining significant traction within the TRU market. Advanced sensors and connected systems are being incorporated into refrigeration units to enable real-time temperature monitoring, performance tracking, and predictive maintenance. Through digital monitoring platforms, logistics operators are provided with improved visibility across the cold chain network. This trend has supported compliance with strict temperature-control requirements while enhancing operational efficiency and minimizing the risk of product spoilage during transit.
The global expansion of cold-chain logistics infrastructure is contributing to the demand for truck refrigeration units. Increasing investments in refrigerated warehouses, temperature-controlled transportation fleets, and integrated logistics networks have been observed across both developed and emerging markets. Rapid growth in e-commerce grocery delivery, pharmaceutical distribution, and international food trade has been driving the need for reliable refrigerated transportation solutions. As a result, the deployment of advanced TRUs across regional and long-haul logistics fleets has been steadily increasing.
Factors such as the high initial capital investment required for refrigerated trucks and advanced refrigeration systems could hinder market growth. Operational challenges related to energy consumption and maintenance costs are also expected to limit market expansion. Fluctuations in fuel prices further contribute to operational uncertainties for fleet operators. In addition, infrastructure limitations in developing regions, including insufficient cold-chain networks and limited availability of specialized service facilities, have been constraining the widespread adoption of advanced refrigeration units.
Market Dynamics
The truck refrigeration unit market is influenced by increasing demand for temperature-controlled transportation, expanding food and pharmaceutical distribution networks, and stricter requirements for maintaining product quality during transit. Advancements in electric refrigeration systems, energy-efficient compressors, improved temperature monitoring, and alternative power sources are reshaping product development. Growing cold-chain infrastructure investments are supporting adoption across commercial vehicle categories, while high equipment costs and operating expenses remain important barriers. The market is gradually shifting toward energy-efficient, digitally monitored, and lower-emission refrigeration solutions.
The expansion of cold-chain logistics is increasing the need to maintain controlled temperatures during the transportation of perishable goods. Food products, fresh produce, dairy items, frozen foods, and temperature-sensitive healthcare supplies require consistent storage conditions throughout distribution. Longer delivery distances, increasing urban consumption, and the expansion of organized food retail are placing greater importance on reliable refrigeration during transit. Temperature fluctuations during transportation increase the risk of spoilage, product rejection, and financial losses, creating demand for dependable refrigeration equipment across commercial vehicle fleets.
Truck refrigeration units support this requirement by maintaining the required cargo temperature throughout transportation and distribution. Modern systems provide improved cooling performance, temperature control, and operational reliability across a range of vehicle sizes and cargo requirements. Their use supports the movement of perishable products between processing facilities, warehouses, distribution centers, and retail locations. Growing investments in refrigerated transportation fleets are strengthening demand for refrigeration systems, particularly in applications involving frequent deliveries and long-distance transportation.
The high initial cost of refrigeration equipment remains a significant barrier to adoption, particularly for small logistics operators and independent transport businesses. The overall investment includes the refrigeration unit, vehicle integration, electrical components, installation, and temperature-monitoring equipment. Operating expenses associated with fuel or electricity consumption, scheduled servicing, refrigerant management, and component replacement further increase the total cost of ownership. These financial requirements create challenges for operators managing limited budgets or working with low-margin transportation contracts.
High ownership costs affect purchasing decisions, particularly among small fleet operators and businesses operating in price-sensitive regions. Some operators continue using older refrigeration equipment or delay fleet upgrades to avoid additional capital expenditure. The restraint is especially relevant in light commercial vehicle fleets, where individual vehicles carry lower cargo volumes and equipment costs represent a substantial share of the total investment. Slower replacement cycles and limited adoption of advanced electric systems consequently restrict revenue opportunities for suppliers, particularly in markets where financing and maintenance infrastructure remain underdeveloped.
The transition toward lower-emission commercial transportation is creating opportunities for electric truck refrigeration units. Conventional refrigeration systems frequently depend on diesel-powered operation, contributing to fuel consumption, operating expenses, and emissions. Increasing electrification of commercial vehicles, improvements in battery technology, and the development of electric power supply systems are supporting interest in refrigeration equipment that reduces dependence on separate diesel engines. Demand for quieter operation and lower local emissions in urban delivery environments is further strengthening this opportunity.
Electric refrigeration systems offer growth potential in urban grocery distribution, pharmaceutical transportation, and other applications requiring frequent deliveries and controlled cargo temperatures. Manufacturers developing battery-powered units, vehicle-integrated refrigeration systems, and energy-management technologies are positioned to benefit from this transition. Adoption is expected to depend on vehicle compatibility, battery capacity, charging access, and total operating costs. Suppliers offering scalable solutions for light, medium, and heavy commercial vehicles are positioned to address a wider range of fleet requirements as cold-chain operators modernize their transportation infrastructure.
Market Concentration & Characteristics
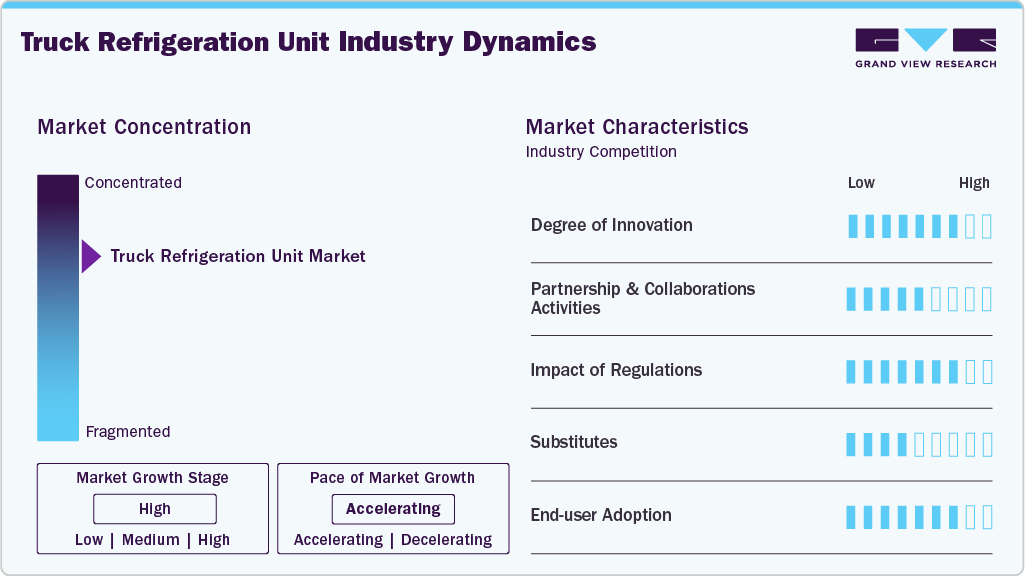
The truck refrigeration unit market is moderately consolidated, with established manufacturers holding strong positions through broad product offerings, established customer relationships, and extensive sales and service networks. At the same time, regional manufacturers and smaller suppliers compete by offering affordable refrigeration units and products suited to specific vehicle requirements. This combination of established companies and smaller competitors creates a competitive environment in which product reliability, pricing, service availability, and energy efficiency influence purchasing decisions. The market is in an accelerating growth stage, supported by increasing demand for temperature-controlled transportation across food distribution, pharmaceutical logistics, and grocery delivery. Established manufacturers benefit from their industry experience and wider reach, while smaller participants strengthen competition by addressing regional demand and price-sensitive customers.
 To learn more about this report, Download Free Sample Report
The market characteristics indicate a high degree of innovation, driven by the development of electric refrigeration units, energy-saving cooling systems, and improved temperature monitoring. Partnership and collaboration activities are at a medium level, as equipment manufacturers work with vehicle manufacturers and fleet operators to improve product suitability and expand customer reach. The impact of regulations is high because emission requirements, refrigerant rules, and temperature-control standards influence equipment design and purchasing decisions. The threat of substitutes is medium, as alternative cooling methods serve certain transportation needs, although dedicated refrigeration units remain important for maintaining controlled temperatures during road transport. End-user adoption is high, supported by the growing need to protect perishable goods, maintain product quality, and reduce losses during transportation. These factors support continued investment in improved refrigeration systems and stronger competition among manufacturers.
Analyst Perspective
The truck refrigeration unit market is supported by increasing cold-chain transportation requirements, expanding food distribution networks, and rising demand for temperature-sensitive healthcare logistics. Technological developments in electric refrigeration, energy-efficient cooling systems, and digital temperature monitoring are reshaping product development and fleet investment priorities. The outlook favors suppliers offering reliable cooling performance, lower operating costs, and solutions compatible with different commercial vehicle categories. Investment is expected to focus on electrification, improved energy management, and equipment modernization. Competitive positioning is increasingly influenced by product efficiency, after-sales service capabilities, geographic reach, and the ability to address changing fleet requirements.
System Type Insights
The diesel-engine TRUs segment dominated the market in 2025 and accounted for the largest share of 72.6%. Demand for diesel-engine truck refrigeration units has been driven by their strong cooling capacity and ability to operate independently from the vehicle’s primary powertrain. These systems have been widely deployed in long-haul transportation and heavy commercial vehicles where consistent temperature control is required over extended distances. The availability of established diesel fueling infrastructure and the reliability of diesel-powered systems have further supported their adoption across global cold-chain logistics networks. In addition, the large installed base of diesel-powered refrigerated trucks has continued to sustain demand for diesel TRUs in both new vehicle installations and replacement applications.
The electric TRUs (eTRUs) segment is expected to grow at the fastest CAGR over the forecast period. The adoption of electric truck refrigeration units has been driven by the increasing emphasis on sustainable transportation and emission reduction across logistics operations. Rising regulatory pressure to limit emissions from diesel-powered refrigeration systems has encouraged the deployment of electric alternatives in refrigerated fleets. Electric TRUs are increasingly used in urban distribution and last-mile delivery operations, where noise reduction and zero-emission operation are prioritized. In addition, improvements in battery technology and the growing availability of electric commercial vehicles have supported the gradual expansion of electric refrigeration solutions in the cold-chain transportation sector.
Sales Channel Insights
The factory-fit segment accounted for 76.3%, the largest share of global revenue in 2025 and is expected to grow at the fastest CAGR over the forecast period. The growth of the segment is driven by the increasing preference for fully integrated refrigeration systems installed during vehicle manufacturing. These systems are designed and optimized by original equipment manufacturers to ensure seamless compatibility with vehicle architecture and improved operational efficiency. Higher reliability, standardized installation, and reduced installation time have been key factors supporting the adoption of factory-installed refrigeration units. In addition, the growing production of refrigerated trucks for organized cold-chain logistics networks has been contributing to the expansion of the factory-fit segment.
The retrofits segment is expected to grow at a moderate CAGR during the forecast period. Growth in the retrofit segment has been supported by the large existing fleet of commercial trucks that require refrigeration capabilities. Many fleet operators have been upgrading conventional trucks with refrigeration units to extend vehicle utilization and support expanding cold-chain logistics operations. Retrofitting solutions have been widely adopted due to their cost-effectiveness compared to purchasing new refrigerated vehicles. In addition, increasing demand for flexible refrigeration solutions among small- and medium-sized logistics operators has been driving the installation of retrofit refrigeration systems.
Vehicle Type Insights
The HCV segment accounted for 37.5%, the largest share of global revenue in 2025. The demand for truck refrigeration units in heavy commercial vehicles has been driven by the increasing need for long-distance transportation of temperature-sensitive goods. These vehicles are widely utilized in large-scale food distribution networks, pharmaceutical logistics, and cross-border trade operations where consistent temperature control is required over extended transit distances. The expansion of global cold-chain logistics infrastructure has further supported the deployment of refrigeration systems in heavy-duty trucks. In addition, the rising volume of frozen and processed food transportation across regional and international routes has contributed to the continued growth of TRU installations in HCV fleets.
The LCV segment is expected to grow at the fastest CAGR during the forecast period. The growth of the segment is supported by the rapid expansion of urban distribution and last-mile delivery services. These vehicles are increasingly being utilized for short-distance transportation of perishable goods, including fresh food, dairy products, and pharmaceutical supplies. The growth of online grocery platforms and quick-commerce delivery networks has further accelerated the demand for refrigerated LCV fleets in urban areas. In addition, the flexibility, lower operational costs, and suitability of LCVs for dense city logistics have been encouraging the installation of refrigeration units in this vehicle category.
Mount Location Insights
The roof-mount segment accounted for the largest share of global revenue in 2025. Roof-mounted truck refrigeration units have gained significant adoption due to their efficient airflow distribution and ability to optimize space within refrigerated truck bodies. These systems are widely utilized in light and medium commercial vehicles where compact design and effective cooling performance are required. Installation on the roof allows greater cargo space within the vehicle while enabling uniform temperature control throughout the storage compartment. The increasing demand for refrigerated transport in urban distribution and food delivery operations has further driven the adoption of roof-mounted refrigeration systems.
The under-mount segment is expected to witness the fastest CAGR over the forecast period. Under-mount truck refrigeration units are widely utilized due to their suitability for heavy-duty transportation and large-capacity refrigerated trucks. These systems are typically installed beneath the truck chassis, allowing higher cooling capacity and improved weight distribution for long-haul transportation applications. Under-mount refrigeration units are widely preferred in large logistics fleets where durability and continuous operation are critical. The expansion of long-distance cold-chain transportation for frozen food, pharmaceuticals, and agricultural exports has been contributing to the increasing deployment of under-mounted refrigeration systems.
End-use Industry Insights
The food & beverage logistics segment dominated the market in 2025. The segment’s growth can be attributed to the increasing demand for temperature-controlled transportation of perishable products. Large volumes of dairy products, frozen foods, meat, seafood, and fresh produce require consistent refrigeration during storage and transit. Expansion of organized retail chains, supermarkets, and international food trade has further increased the need for reliable cold-chain transportation networks. In addition, the rapid growth of online grocery platforms and food distribution services has been supporting the deployment of refrigerated trucks across regional and urban logistics operations.
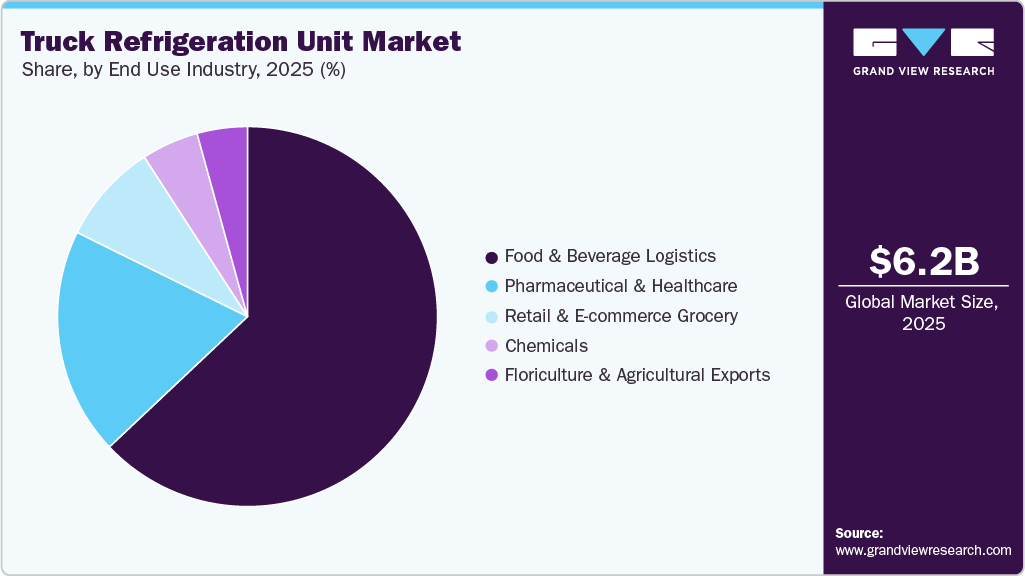 To learn more about this report, Download Free Sample Report
The pharmaceutical & healthcare segment is expected to witness the fastest CAGR over the forecast period. The pharmaceutical and healthcare sector has been significantly contributing to the demand for truck refrigeration units due to strict temperature control requirements for medical products. Many pharmaceuticals, vaccines, biologics, and specialty medicines must be transported within specific temperature ranges to maintain product efficacy and safety. Increasing global distribution of vaccines and temperature-sensitive drugs has led to the expansion of specialized pharmaceutical cold-chain logistics networks. Furthermore, stringent regulatory standards governing pharmaceutical transportation have been encouraging the use of advanced refrigerated transport solutions across healthcare supply chains.
Regional Insights
North America Truck Refrigeration Unit Market Trends
North America dominated the truck refrigeration unit industry and accounted for a share of 36.6% in 2025. North America is a mature, well-established market for truck refrigeration units, supported by a highly developed cold-chain logistics network. The transportation of large volumes of frozen, dairy, and processed foods has driven consistent demand for refrigerated trucking solutions.
 To learn more about this report, Download Free Sample Report
U.S. Truck Refrigeration Unit Market Trends
The U.S. truck refrigeration unit market held a dominant position in the region in 2025, due to its extensive refrigerated transportation infrastructure and strong food distribution networks. Large-scale transportation of perishable food products over long distances has sustained demand for refrigerated trucks.
Asia Pacific Truck Refrigeration Unit Market Trends
The Asia Pacific truck refrigeration unit market is expected to grow at the fastest CAGR during the forecast period. Rising consumption of perishable food products and the growth of organized retail networks have been contributing significantly to the demand for refrigerated transportation.
India’s truck refrigeration unit market is expected to grow at the fastest growth rate during the forecast period. Growth in pharmaceutical manufacturing and vaccine distribution has contributed to the adoption of refrigerated trucks across healthcare supply chains. Furthermore, government programs promoting agricultural exports and food preservation have been encouraging investments in refrigerated transport solutions.
The China truck refrigeration unit market held a significant market share in 2025. Increasing urbanization and rising demand for fresh food delivery services are driving the growth of refrigerated truck fleets across major cities. The expansion of the pharmaceutical industry and the strict temperature-control requirements for drug distribution have also contributed to market growth.
Europe Truck Refrigeration Unit Market Trends
Europe truck refrigeration unit market is expected to register a moderate CAGR from 2026 to 2033. The TRU market in Europe has been supported by well-established logistics infrastructure and strict regulatory standards governing the transportation of food and pharmaceuticals. The increasing demand for temperature-controlled transportation of fresh produce, dairy products, and frozen foods has contributed to market growth.
U.K. Truck Refrigeration Unit Market Trends
The U.K. truck refrigeration unit market is expected to grow at the significant growth rate during the forecast period. The country’s market growth is driven by the expansion of food retail chains and the increasing demand for temperature-controlled food distribution. Growth in online grocery delivery services has created additional demand for refrigerated transportation across urban and regional logistics networks.
Germany Truck Refrigeration Unit Market Trends
The Germany truck refrigeration unit market held a substantial market share in 2025, due to its strong logistics industry and advanced transportation infrastructure. High demand for refrigerated transportation has been observed in the distribution of dairy products, meat, frozen foods, and pharmaceutical products. The presence of large food processing industries and export-oriented agricultural supply chains has further supported the deployment of refrigerated truck fleets.
Key Truck Refrigeration Unit Company Insights
Some of the key companies in the truck refrigeration unit industry include Carrier Global Corporation, Daikin Industries, and Thermo King, among others. These companies focus on developing energy-efficient, hybrid, and electric refrigeration technologies to comply with evolving environmental regulations and sustainability goals.
-
Carrier Global Corporation is one of the major providers of truck refrigeration units through its transportation refrigeration brand Carrier Transicold. The company offers a wide portfolio of refrigeration systems designed for trucks, trailers, and vans used in cold-chain logistics. Its solutions are widely adopted across food distribution, pharmaceutical transportation, and refrigerated logistics fleets due to their reliability and advanced temperature control capabilities.
-
Thermo King is another prominent manufacturer of transport refrigeration systems for trucks, trailers, and intermodal containers. The company has established a strong global presence by offering a broad range of diesel, hybrid, and electric refrigeration solutions for temperature-controlled transportation. Its refrigeration systems are widely utilized by logistics providers, food distributors, and pharmaceutical supply chains requiring precise temperature management.
Key Truck Refrigeration Unit Companies
The following key companies have been profiled for this study on the truck refrigeration unit market
-
Carrier Global Corporation
-
Subros Limited
-
Daikin Industries
-
Thermo King
-
Guchen
-
Mitsubishi Heavy Industries, Ltd.
-
Webasto Group
-
TKT HVAC Co., Ltd.
-
Glen Refrigeration
-
PT Hwasung Thermoindo.
Company Categorization
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Carrier Global Corporation, Daikin Industries, Thermo King, Mitsubishi Heavy Industries, Ltd.
- Mature players in the parking occupancy sensing are focus on their refrigeration products and expand service coverage to meet the needs of different truck owners and transport businesses.
- Mature players gain a competitive advantage through their established presence builds customer trust, while broad dealer networks improve product availability and after-sales support across regions.
- These companies face challenges related to high product and service costs increase the overall cost of ownership, which makes their solutions less attractive to small transport businesses with limited budgets.
Emerging Players: Subros Limited, Guchen, TKT HVAC Co., Ltd.
- Emerging players in the parking occupancy sensing are focus on affordable refrigeration units and products suited to local customer needs to attract buyers seeking cost-effective solutions.
- Emerging players gain market traction through their competitive pricing helps them reach price-sensitive customers, while focused product offerings allow them to address specific truck refrigeration requirements.
- Emerging players face limitations due to limited service coverage in international markets makes it harder to support customers across regions, while fewer resources restrict product development and business expansion.
Recent Developments
-
In July 2025, Carrier Transicold expanded its Supra High Efficiency (HE) range of truck-mounted refrigeration units with the introduction of the Supra HE 13 Multi-Temperature (MT) and HE 11 MT models. These high-performance systems are designed with a compact structure while delivering improved fuel efficiency and reliable cooling performance. The new units have been engineered to support a wide variety of truck configurations used in temperature-controlled transportation. In addition, they are compatible with one of the most extensive ranges of evaporators available in the market.
-
In September 2025, Thermo King launched its TX-Series truck refrigeration units across Europe, the Middle East, and Africa. The new range replaces the previous T-Series and offers up to 17% higher cooling capacity, up to 7% improved fuel efficiency, and a weight reduction of up to 40 kg. The units also feature biofuel compatibility, digital monitoring, and extended maintenance intervals, supporting improved operational efficiency and reduced maintenance costs in refrigerated transportation.
Truck Refrigeration Unit Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.2 billion
Estimated market size in 2026
USD 7.7 billion
Projected market size by 2033
USD 13.1 billion
Growth Rate
CAGR of 7.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
System type, sales channel, vehicle type, mount location, end-use industry, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Carrier Global Corporation; Subros Limited; Daikin Industries; Thermo King; Guchen; Mitsubishi Heavy Industries, Ltd.; Webasto Group; TKT HVAC Co., Ltd.; PT Hwasung Thermoindo; Glen Refrigeration
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Truck Refrigeration Unit Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global truck refrigeration unit market report based on system type, sales channel, vehicle type, mount location, end-use industry, and region.
-
System Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Diesel-engine TRUs
-
Electric TRUs (eTRUs)
-
Hybrid TRU
-
-
Sales Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Factory-fit
-
Retrofits
-
-
Vehicle Type Outlook (Revenue, USD Million, 2021 - 2033)
-
LCV
-
MCV
-
HCV
-
-
Mount Location Outlook (Revenue, USD Million, 2021 - 2033)
-
Front-mount
-
Roof-mount
-
Under-mount
-
-
End-use Industry Outlook (Revenue, USD Million, 2021 - 2033)
-
Food & Beverage Logistics
-
Pharmaceutical & Healthcare
-
Retail & E-commerce Grocery
-
Chemicals
-
Floriculture & Agricultural Exports
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The truck refrigeration unit market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each truck refrigeration unit segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - System Type
Revenue capture definition
Diesel-engine TRUs
The segment revenue is generated from the sale of refrigeration units powered by dedicated diesel engines, including associated cooling components, temperature-control equipment, and replacement units sold as part of the refrigeration system.
Electric TRUs (eTRUs)
The segment revenue is generated from the sale of electrically powered refrigeration units, including battery-powered systems, electric compressors, power-conversion components, and integrated electrical cooling equipment.
Hybrid TRU
The segment revenue is generated from the sale of refrigeration units that combine two or more power sources, including diesel-electric and engine-electric configurations, along with associated power-management and refrigeration components.
Segment - Sales Channel
Revenue capture definition
Factory-fit
The segment revenue is generated from refrigeration units installed by vehicle manufacturers or authorized integration partners before the vehicle is delivered to the customer, including factory-integrated cooling systems and installation-related charges included in the equipment sale.
Retrofits
The segment revenue is generated from refrigeration units and conversion systems installed on vehicles already in service, including replacement installations, equipment upgrades, mounting modifications, and related integration services.
Segment - Vehicle Type
Revenue capture definition
LCV
The segment revenue is generated from refrigeration units designed for light commercial vehicles, including refrigerated vans and small delivery trucks, along with associated installation and vehicle-specific integration components.
MCV
The segment revenue is generated from refrigeration units designed for medium commercial vehicles used in regional distribution and intermediate-capacity refrigerated transportation, including cooling equipment and associated integration components.
HCV
The segment revenue is generated from refrigeration units designed for heavy commercial vehicles, including large refrigerated trucks and tractor-trailer combinations, along with high-capacity cooling systems and related installation components.
Segment - Mount Location
Revenue capture definition
Front-mount
The segment revenue is generated from refrigeration units installed at the front of the cargo body, including front-mounted condensers, compressors, evaporators, and associated temperature-control components supplied as part of the system.
Roof-mount
The segment revenue is generated from refrigeration units installed on the roof of the vehicle or cargo body, including roof-mounted cooling equipment, supporting structures, electrical components, and installation-related system components.
Under-mount
The segment revenue is generated from refrigeration units installed beneath the vehicle chassis or cargo body, including under-mounted refrigeration assemblies, protective housings, mounting equipment, and related cooling components.
Segment - End Use Industry
Revenue capture definition
Food & Beverage Logistics
The segment revenue is generated from truck refrigeration units purchased for transporting fresh produce, meat, seafood, dairy products, frozen foods, beverages, and other temperature-sensitive food products.
Pharmaceutical & Healthcare
The segment revenue is generated from refrigeration units used to transport medicines, vaccines, biological materials, medical supplies, and other healthcare products requiring controlled temperatures during distribution.
Retail & E-commerce Grocery
The segment revenue is generated from refrigeration units used in grocery distribution, supermarket replenishment, online grocery deliveries, and last-mile transportation of chilled and frozen products.
Chemicals
The segment revenue is generated from refrigeration units used to transport temperature-sensitive chemicals and specialty materials that require controlled thermal conditions, subject to vehicle and cargo compatibility requirements.
Floriculture & Agricultural Exports
The segment revenue is generated from refrigeration units used to transport cut flowers, ornamental plants, fresh fruits, vegetables, and other agricultural products requiring temperature management to preserve quality during domestic distribution and export logistics.
Estimation Model
Layer Name
Key Question
Description
Industry Demand Assessment
What drives demand for truck refrigeration units?
This layer evaluates demand for temperature-controlled transportation across food distribution, healthcare logistics, grocery delivery, chemical transportation, and agricultural exports. It considers refrigerated vehicle fleet expansion, cold-chain infrastructure, delivery volumes, and replacement requirements. The assessment identifies the major applications and vehicle categories contributing to demand. It establishes the underlying industry requirements for refrigeration equipment.
Product and Segment Mapping
Which products and configurations generate revenue?
This layer classifies truck refrigeration units by system type, sales channel, vehicle type, mounting location, and end-use industry. It distinguishes diesel-powered, electric, and hybrid systems according to their operating configurations. Factory-fit installations and retrofit demand are evaluated separately to identify different purchasing patterns. This classification establishes the segment-level structure used to estimate equipment revenue.
Revenue and Geographic Quantification
Where is revenue generated, and how large is the opportunity?
This layer estimates revenue by product configuration, vehicle category, application, and geography. It considers equipment selling prices, unit shipments, vehicle fleet requirements, replacement cycles, and regional adoption patterns. Regional differences in cold-chain infrastructure, operating costs, and regulatory requirements inform the assessment. Segment estimates are reconciled with the overall market total to maintain consistency.
Validation and Forecast Assessment
Are the estimates reliable, and what factors shape future growth?
This layer validates estimates against company disclosures, product portfolios, vehicle industry information, regulatory developments, and credible industry sources. It examines the adoption of electric refrigeration, fleet modernization, equipment efficiency, and changes in transportation requirements. Historical trends and identified demand drivers inform the assessment of future market direction. Sensitivity checks are used to review assumptions and maintain consistency across segments and regions.
Delivered Customization
We have successfully delivered the following deep-dive customizations:
Client Request
Customization Delivered
Value Adds
Regional Truck Refrigeration Unit Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Truck Refrigeration Unit Market
Criss-cross market analysis by system type, sales channel, vehicle type, mount location, and end-use industry
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted connectivity positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Truck Refrigeration Unit Market
Benchmarking of key competitors across connectivity, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The factory-fit held the largest revenue share in 2025.
The HCV held the largest share in 2025 and LCV segment is the fastest-growing.
The North America dominated with a 36.6% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global truck refrigeration unit market size was valued at USD 6.2 billion in 2025 and is expected to reach USD 6.7 billion in 2026.
The global truck refrigeration unit market is expected to grow at a compound annual growth rate of 7.8% from 2026 to 2033 to reach USD 11.3 billion by 2033.
The diesel-engine TRUs segment dominated the market in 2025 and accounted for the largest share of 72.6%.
Key players include Carrier Global Corporation, Subros Limited, Daikin Industries, Thermo King, Guchen, Mitsubishi Heavy Industries, Ltd., Webasto Group, TKT HVAC Co., Ltd., and Glen Refrigeration
The expansion of global cold-chain logistics and the rising demand for temperature-controlled transportation are major drivers of the truck refrigeration unit market.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


