
- Home
- »
- Homecare & Decor
- »
-
U.S. Home Bedding Market Size & Share Report, 2026-2033GVR Report cover

U.S. Home Bedding Market (2026 - 2033)
Size, Share & Trends Report By Product (Mattress, Bedroom Linen, Pillows & Cushions), By Product by Material (Mattress (Innerspring), Bedroom Linen (Cotton)), By Distribution Channel, And Segment Forecasts
Market Size, 2025
$39.3BMarket Estimate, 2026
$40.7BMarket Forecast, 2033
$52.5BCAGR, 2026–2033
3.7%U.S. Home Bedding Market Summary
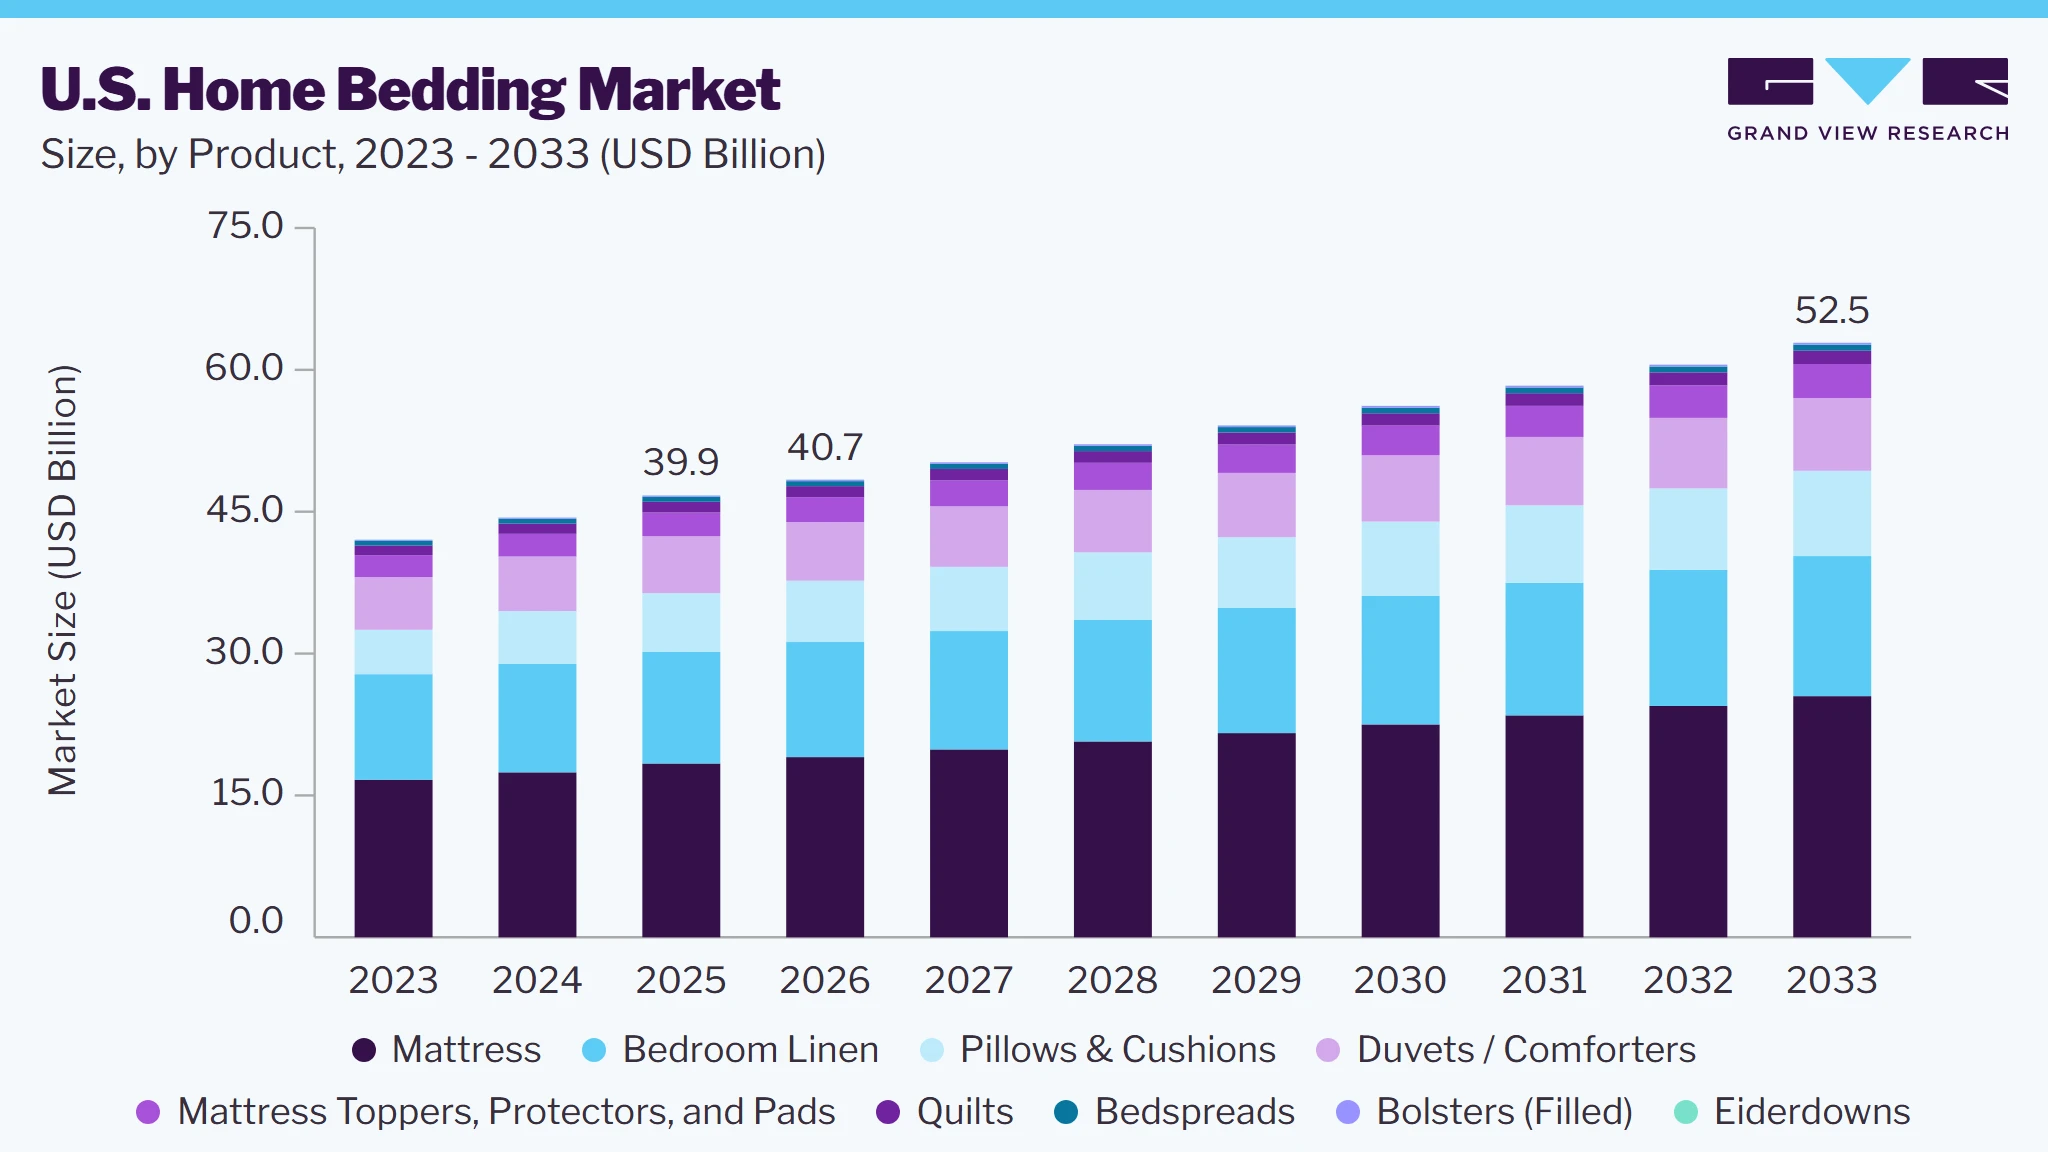
The U.S. home bedding market size was valued at USD 39.3 billion in 2025 and is projected to grow from USD 40.7 billion in 2026 to USD 52.5 billion by 2033, at a CAGR of 3.7% from 2026 to 2033. The market growth is driven by increasing consumer spending on sleep-focused products, higher replacement demand for mattresses and bedding accessories, and greater interest in comfortable, aesthetically appealing, and personalized bedroom environments.
Key Market Trends & Insights
- By product: Mattress segment accounted for the largest revenue share of 41.6% in 2025.
- By product by material: Innerspring mattress subsegment accounted for the largest revenue share of 42.1% in 2025.
- By distribution channel: Offline segment accounted for the largest revenue share of 71.5% in 2025.
Market Size & Forecast
- Market size in 2025: USD 39.3 Billion
- Estimated market size in 2026: USD 40.7 Billion
- 2033 Projected Market Size: USD 52.5 Billion
- CAGR (2026-2033): 3.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Additional factors include home renovation and remodeling activity, the premiumization of bedding products, demand for temperature-regulating and wellness-oriented materials, and the expansion of online and direct-to-consumer retail channels, which enhance product accessibility and broaden consumer choice. Expansion of the U.S. housing base is sustaining the underlying demand for home bedding products. The U.S. had approximately 148.3 million housing units as of July 2025, with an owner-occupied housing rate of 65.2% and approximately 129.2 million households during 2020–2024. The country also issued 1.43 million building permits in 2025, indicating continued residential construction and household formation. The expansion of occupied housing creates recurring requirements for mattresses, sheets and mattress covers, blankets, pillowcases and covers, bed pads, and pillows as households furnish new bedrooms and replace existing products.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Greater emphasis on sleep quality is encouraging consumers to evaluate bedding based on comfort, support, durability, and product features rather than price alone. The J.D. Power 2025 U.S. Mattress Satisfaction Study found that consumers purchasing mattresses online spent an average of USD 984 and recorded an overall satisfaction score of 878 out of 1,000. The study evaluated comfort, value for price paid, support, durability, variety of features, warranty, and customer service, highlighting the growing importance of functional and performance attributes in sleep-related purchases. This preference is encouraging manufacturers and retailers to introduce more differentiated and higher-value products across the U.S. market.
The growing adoption of online purchasing is improving accessibility to home bedding products and strengthening digital distribution. Online mattress buyers spent USD 258 less on average than consumers purchasing in stores, while reporting higher satisfaction, indicating that convenience and perceived value are strengthening consumers' willingness to purchase sleep products digitally. Industry developments are reinforcing this shift: Somnigroup International reported that consumers have become increasingly comfortable purchasing bedding products online and stated that more than 60% of its global sales were direct-to-consumer following the Mattress Firm acquisition. The expansion of online and DTC channels is therefore broadening product reach and allowing consumers to access premium and specialized bedding products without relying exclusively on physical stores.
A large residential base, continued housing construction, greater focus on sleep quality, adoption of digital purchasing, and premiumization are strengthening demand in the U.S. market. These developments are gradually shifting consumer purchases from basic replacement-oriented bedding toward home bedding products that offer enhanced comfort, functional performance, personalization, and convenience, creating opportunities for continued innovation across the bedding industry.
Market Dynamics
Growing consumer awareness of the relationship between sleep and overall well-being is driving demand for home bedding products that support a comfortable, supportive sleep environment. Consumers are increasingly viewing mattresses, pillows, bed linen, and other bedding products as important components of their daily wellness routines rather than purely functional household items. This shift is driving greater attention to factors such as comfort, temperature regulation, softness, material quality, and the overall bedroom environment. The growing focus on improving sleep quality is also encouraging consumers to upgrade and replace bedding products designed to enhance rest and everyday comfort.
IKEA expanded its emphasis on sleep solutions in 2025. The company has increasingly positioned the bedroom as a “sleep sanctuary” and highlighted the role of comfortable bedding, mattresses, pillows, temperature management, and the overall bedroom environment in improving sleep.
Home bedding manufacturers are exposed to fluctuations in the cost and availability of key inputs, particularly cotton and other textile materials, while global sourcing networks can also be affected by changes in trade policies, logistics conditions, and transportation costs. These factors can create uncertainty in procurement and production planning, particularly for manufacturers sourcing raw materials and finished products across multiple countries. Changes in cotton supply conditions can further affect the cost structure of bed sheets, pillowcases, duvet covers, and other cotton-based bedding products.
According to the World Bank, cotton prices jumped by 12% in April 2026, reversing the softening observed earlier in the year. The increase was attributed to tighter global supply conditions, with global cotton production projected to decline by 5% in the 2026–27 season. As cotton is a key raw material used in bed sheets, pillowcases, duvet covers, and other home bedding products, such price fluctuations can increase procurement uncertainty and create cost pressures for manufacturers.
Cooling and temperature-regulating bedding represents an attractive opportunity in the U.S. market as consumers increasingly prioritize sleep comfort and temperature management. Demand is driving growth in premium sheets, pillows, comforters, mattress toppers, and blankets made with breathable, moisture-wicking, phase-change, and cooling fibers that help regulate body temperature during sleep. The ability to address common issues such as night sweating and overheating also enables brands to differentiate products and command premium price points, making cooling technologies a particularly monetizable growth area within bedding.
A 2025 SleepScore Labs study of cooling bedding found that self-reported sleep quality improved by 74%, sleep satisfaction by 80%, and morning restedness by 91%; perceived night sweats declined by 61%. The study involved 30 women and 924 tracked nights.
Analyst Perspective
The U.S. market for home bedding is evolving toward comfort-, functionality-, and quality-oriented home bedding products, with consumers increasingly prioritizing sleep comfort, pressure relief, cooling, durability, and personalized support. Demand is supported by ongoing mattress and bedding replacement, household furnishing activity, and greater consumer attention to sleep quality. Manufacturers are responding by expanding product portfolios with advanced materials, cooling technologies, specialized support systems, and differentiated designs across mattresses, pillows, blankets, sheets, and protective bedding products.
Consumer Insights
The U.S. home bedding serves a broad consumer base that purchases mattresses, pillows, sheets, covers, blankets, bed pads, and other home bedding products for comfort, sleep quality, durability, and bedroom upgrades.
-
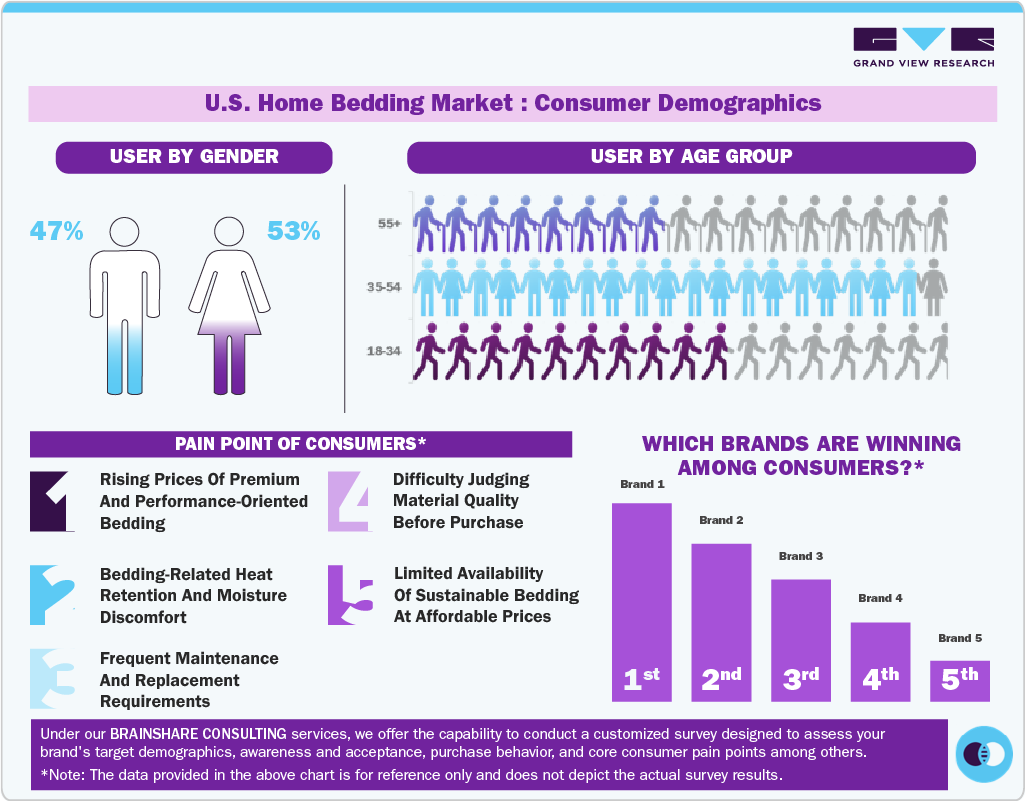
Female consumers account for 53%, representing the larger user group. Their higher participation reflects strong engagement in selecting and purchasing mattresses, sheets, pillowcases, blankets, and other bedding products, particularly where comfort, material quality, bedroom aesthetics, and maintenance requirements influence purchase decisions.
 To learn more about this report, Download Free Sample Report
In 2025, research cited by Ideal Home reported that 83% of perimenopausal and menopausal women experienced sleep problems, with 61% reporting night sweats and 41% experiencing insomnia. This has increased attention to breathable sheets, temperature-regulating duvets and comforters, cooling mattress protectors, and moisture-managing bedding materials.
-
Male consumers account for 47%, indicating substantial participation in bedding purchases. Their demand is supported by interest in functional attributes such as mattress comfort, durability, temperature regulation, ease of maintenance, and value for money. According to the American Academy of Sleep Medicine’s 2025 Sleep Prioritization Survey, 20% of men reported spending USD 200–500 on consumer sleep products during the previous year, compared with 12% of women. The survey covered 2,007 U.S. adults and included products such as pillows, weighted blankets, sleep trackers, and sleep technology, indicating stronger male spending in higher-value sleep-product categories.
Consumers aged 35–54 form the largest user group, representing established households and consumers with greater responsibility for purchasing and replacing mattresses, sheets, blankets, pillows, and other. This group is more likely to prioritize comfort, durability, material quality, temperature regulation, and overall sleep quality when selecting bedding. Consumers aged 18–34 represent younger adults who are more focused on affordability, convenience, bedroom aesthetics, online purchasing, and products suited to changing living arrangements. Consumers aged 55 and above primarily seek enhanced comfort, durability, ease of maintenance, and supportive bedding features, with replacement needs becoming an important factor in their purchasing decisions.
Consumers in the U.S. home bedding industry face several challenges that influence purchasing decisions:
-
Rising prices of premium and performance-oriented bedding can discourage consumers from upgrading to higher-quality mattresses and bedding products, particularly when advanced comfort or temperature-management features carry higher price points.
-
Difficulty judging material quality before purchase creates uncertainty around softness, durability, breathability, and overall product performance, especially when consumers purchase bedding through online channels.
-
Heat retention and moisture discomfort remain concerns for consumers seeking comfortable sleep, increasing the importance of breathable and moisture-managing bedding materials.
-
Limited availability of sustainable bedding at affordable prices creates a trade-off between environmental preferences and purchasing budgets, restricting adoption of sustainably produced bedding among price-sensitive consumers.
-
Frequent maintenance and replacement requirements add to the overall ownership burden, particularly for bedding products requiring regular washing, care, or replacement due to wear, staining, loss of loft, or declining comfort.
Product Insights
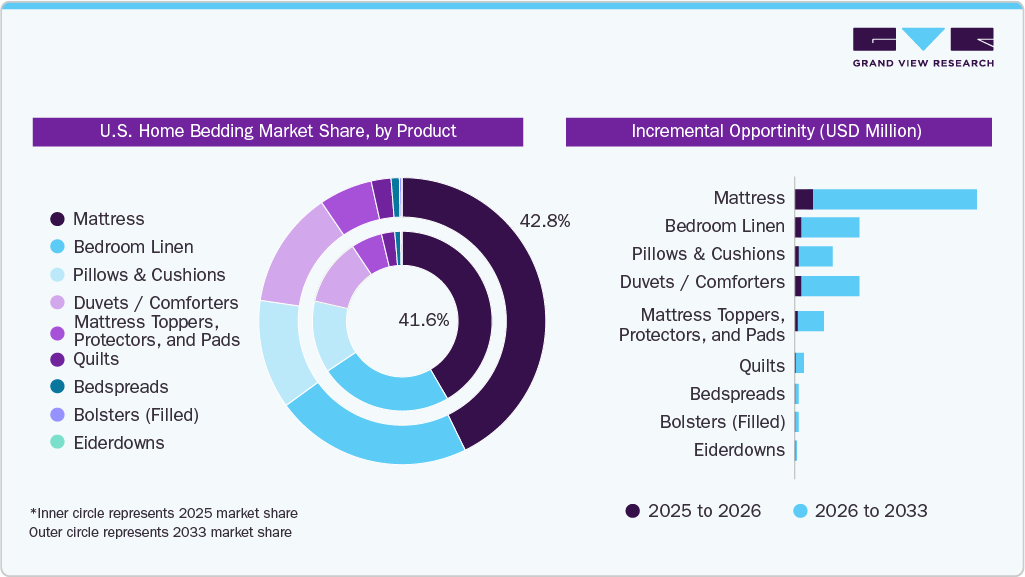
The mattress segment accounted for the largest revenue share of 41.6% in 2025. Increasing demand for mattresses that provide more precise body contouring and lower-back support is encouraging manufacturers to adopt zoned constructions and specialized coil systems. For instance, Serta’s July 2025 Perfect Day Mattress in a Box collection introduced 3-Zoned Body Support and individually wrapped coils, allowing the mattress to provide targeted support while maintaining a value-oriented positioning. This shift toward differentiated support features is encouraging the bedding industry to develop more specialized home bedding products aligned with consumers’ individual comfort and support requirements.
 To learn more about this report, Download Free Sample Report
Mattress toppers, protectors, and pads are expected to grow at a CAGR of 4.6% from 2026 to 2033. Consumers are increasingly using these products to address specific needs such as cooling, moisture protection, allergy management, and additional cushioning while extending the usable life of existing mattresses. For instance, Mattress Firm’s current U.S. assortment includes waterproof and encasement protectors, cooling protectors such as the Sleepy’s Deluxe Comfort Cool Mattress Protector, and comfort-focused products, including gel memory foam and zoned-support toppers. This expanding range of functional bedding accessories is encouraging the bedding industry to offer more specialized home bedding products.
Product by Material Insights
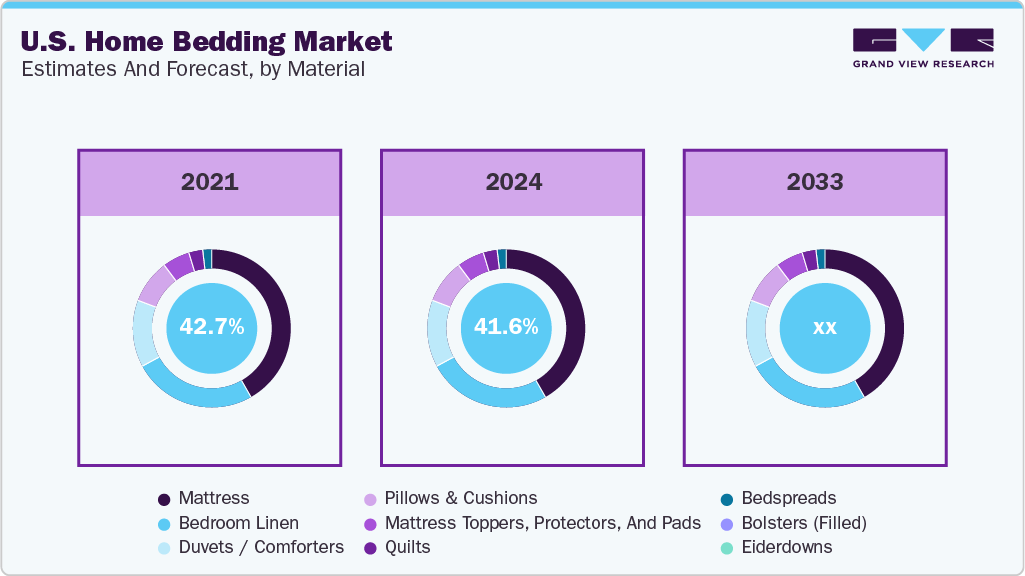
The innerspring mattress subsegment among the mattress segment accounted for the largest revenue share of 42.1% in 2025, it is differentiated by the materials used in their support cores and comfort layers, with manufacturers combining steel coils, foam, fiber, cotton, and other upholstery materials to deliver varying levels of support, pressure relief, responsiveness, and durability. In July 2026, Stearns & Foster introduced its new 2026 luxury mattress collections, including the Estate, Lux Estate, Legacy, and Reserve ranges. The new portfolio incorporates the brand's patented IntelliCoil innerspring technology, featuring a coil-in-coil design intended to provide adaptive support and pressure relief. The Reserve collection additionally features IntelliCoil HD, which incorporates a higher coil count, while PrecisionEdge technology provides reinforced edge support. The launch reflects continued innovation in innerspring mattress construction through advancements in coil configuration, targeted support, and comfort-layer integration.
 To learn more about this report, Download Free Sample Report
The pillows & cushions by material segment is expected to grow at a CAGR of 4.8% from 2026 to 2033, driven by increasing demand for materials that deliver differentiated comfort, support, resilience, and aesthetic appeal. Manufacturers are increasingly combining materials such as foam, latex, fiberfill, and natural fillings to provide varied loft, density, softness, and support characteristics across sleeping and decorative applications. For instance, in January 2026, Purecare introduced new cooling pillows incorporating multiple material configurations, including fiber fill, blended shredded foam and fiber, and shredded latex. The launch demonstrates material-level product differentiation within the pillows category.
Distribution Channel Insights
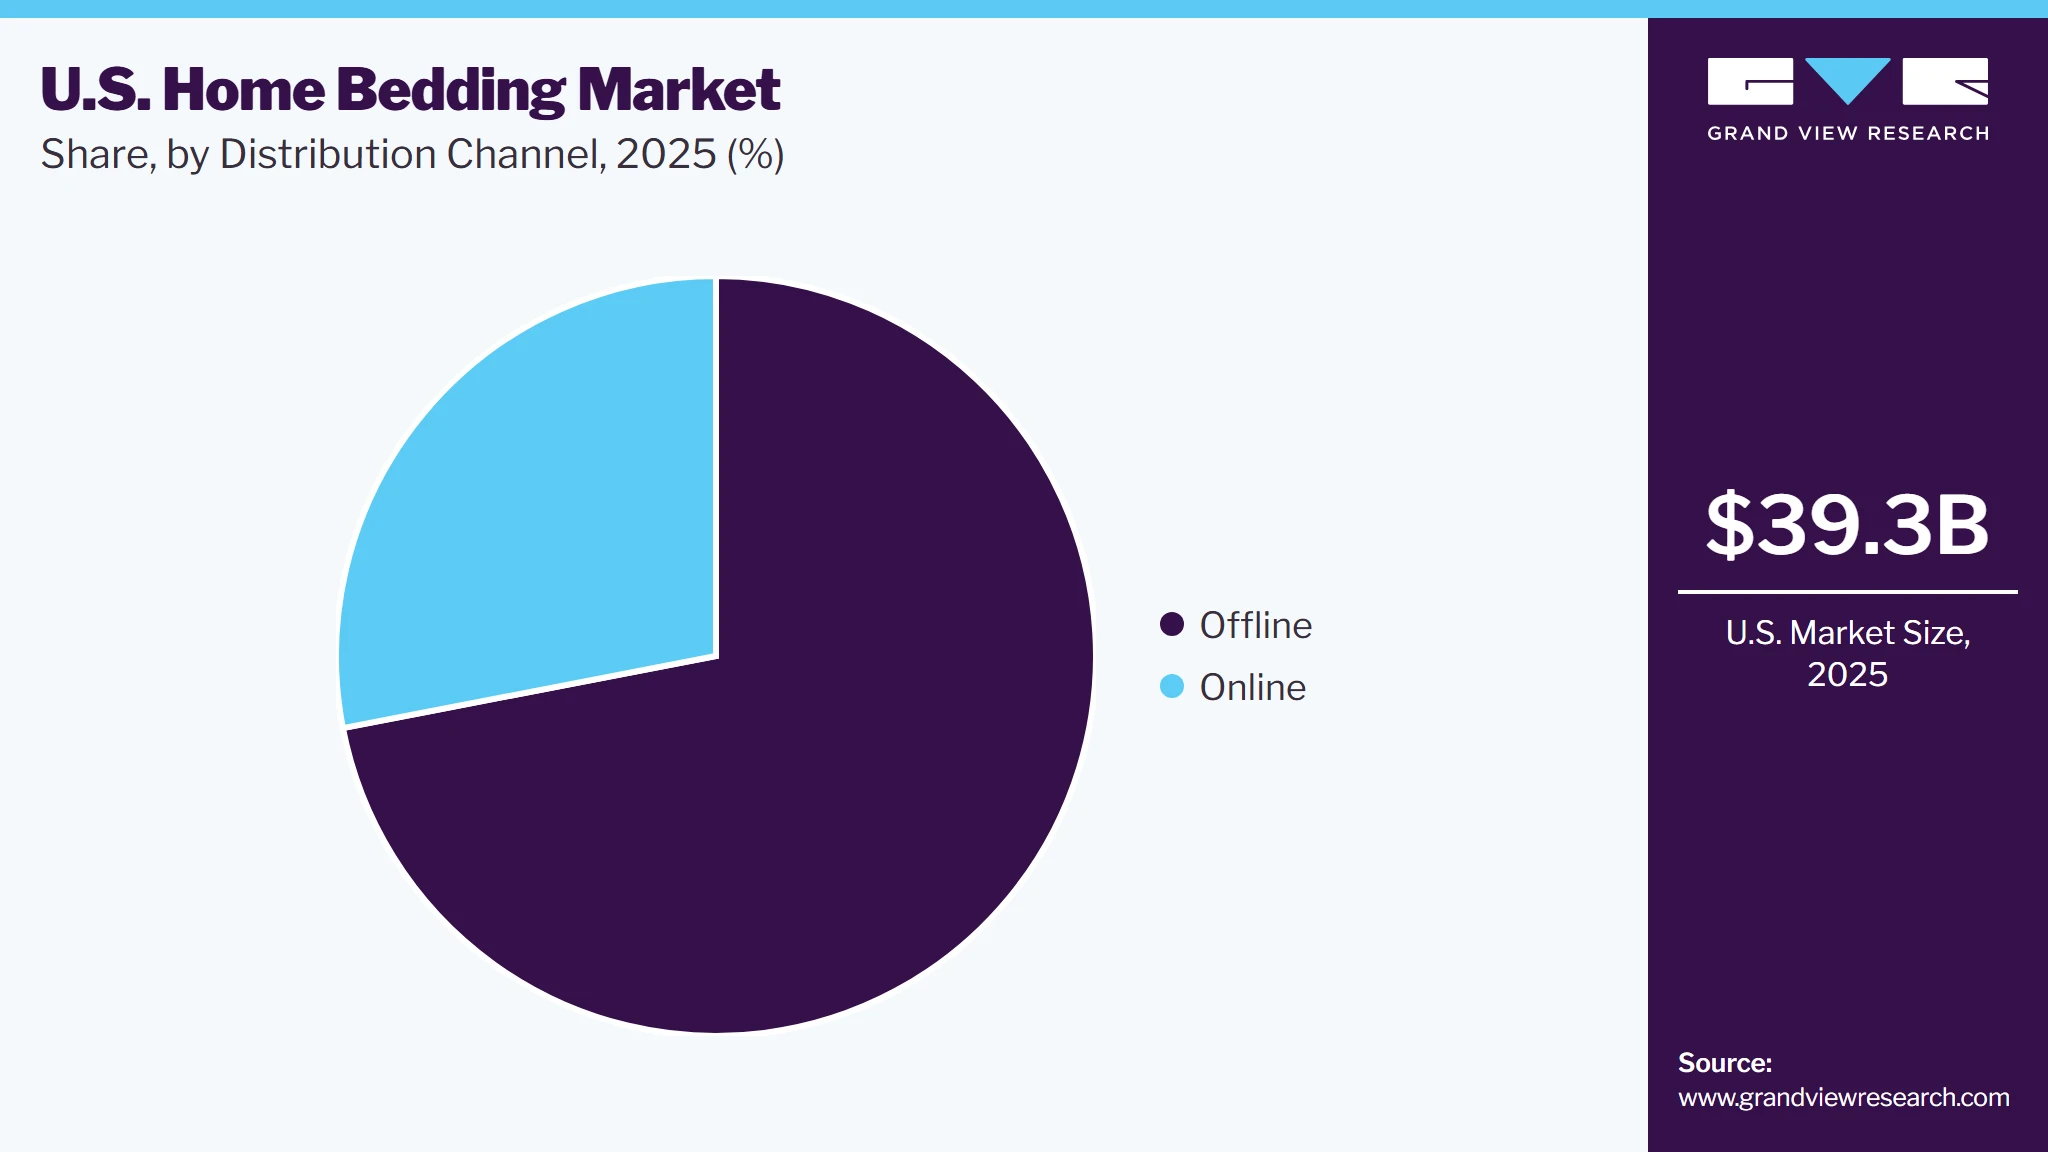
The offline distribution channel accounted for a share of revenue of 71.5% in 2025, driven by consumers’ preference to physically assess mattress comfort, firmness, material quality, and product features before purchase. This preference is encouraging retailers to maintain extensive brick-and-mortar networks and in-store trial experiences. For instance, in 2026, Mattress Firm continued expanding consumer access to mattresses, pillows, bedding, and adjustable bases through its U.S. store network, allowing shoppers to test products in physical locations before purchasing. This store-based evaluation experience is reinforcing the role of offline retail in the U.S. bedding industry.
 To learn more about this report, Download Free Sample Report
The online distribution channel is expected to grow at a CAGR of 5.3% from 2026 to 2033, driven by increasing consumer preference for convenient digital purchasing, broader product selection, and easy access to bedding products across e-commerce platforms. For instance, in April 2026, Target launched the Hot Wheels by Pillowfort collection on Target.com and in stores, featuring 42 kids’ bedding and décor products priced from USD 15 to USD 65. The availability of the collection through Target.com expands digital access to home bedding products, enabling consumers to browse and purchase bedding products online, thereby supporting the growth of the online distribution channel in the U.S. market.
Key U.S. Home Bedding Company Insights
The U.S. market is characterized by competition among established mattress manufacturers, digitally native bedding brands, vertically integrated retailers, and diversified home-furnishing companies. Competition is primarily shaped by product innovation, brand recognition, distribution reach, pricing, direct-to-consumer capabilities, sleep technologies, and the ability to address evolving consumer preferences for comfort, support, cooling, and personalized sleep solutions.
-
Leading Mattress Manufacturers: Companies such as Tempur Sealy International, Inc., Serta Simmons Bedding, LLC, Sleep Number Corporation, and Kingsdown, Inc. compete through established brand portfolios, broad retail networks, advanced mattress technologies, and extensive product offerings. These companies leverage proprietary sleep technologies and differentiated constructions to address varying preferences for pressure relief, firmness, temperature regulation, and personalized comfort.
-
Direct-to-Consumer & Digital-First Bedding Brands: Saatva, Inc., Resident Home LLC, Casper Sleep Inc., and Purple Innovation, Inc. strengthen competition through direct-to-consumer business models, e-commerce platforms, product innovation, and consumer-focused shopping experiences. Their strategies emphasize convenient online purchasing, trial periods, product education, and specialized mattress technologies, increasing the role of digital channels in the U.S. bedding industry.
-
Diversified Home-Furnishing & Mass-Market Players: Ashley Furniture Industries, LLC competes by leveraging its broad home-furnishing portfolio, extensive retail presence, and integrated consumer shopping experience. Its ability to offer mattresses alongside furniture and other home products enables cross-category purchasing and strengthens access to home bedding products through physical and digital retail channels.
-
Technology-Driven & Specialized Sleep Solutions: Sleep Number Corporation, Purple Innovation, Inc., Tempur Sealy International, Inc., and Saatva, Inc. differentiate their offerings through proprietary materials, adjustable technologies, pressure-relieving constructions, cooling features, and premium sleep solutions. This focus on product-level differentiation intensifies competition as consumers increasingly evaluate mattresses based on performance attributes rather than price alone.
-
Value-Oriented & Broad-Distribution Brands: Zinus, Inc., Serta Simmons Bedding, LLC, and Resident Home LLC compete by offering mattresses across multiple price points and distribution formats, including online retail and broader consumer channels. Their emphasis on accessible pricing, boxed-mattress formats, and convenient delivery expands consumer access to mattresses and supports competition across value and mid-market segments.
 To learn more about this report, Download Free Sample Report
Key U.S. Home Bedding Companies
-
Tempur Sealy International, Inc.
-
Serta Simmons Bedding, LLC
-
Sleep Number Corporation
-
Purple Innovation, Inc.
-
Saatva, Inc.
-
Resident Home LLC
-
Casper Sleep Inc.
-
Ashley Furniture Industries, LLC
-
Kingsdown, Inc.
-
Zinus, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Key Challenges
Established Players (Tempur Sealy International, Inc.; Serta Simmons Bedding, LLC; Sleep Number Corporation; Purple Innovation, Inc.; Ashley Furniture Industries, LLC; Kingsdown, Inc.; Zinus, Inc.)
- Expand product portfolios, strengthen retail and e-commerce distribution, and invest in sleep technologies, materials, and comfort features.
- Strong brand recognition, established distribution networks, broad product portfolios, and proprietary technologies.
- Intense competition, pricing pressure, rising input costs, and the need for continuous product innovation.
Emerging & Regional Players (Saatva, Inc.; Resident Home LLC; Casper Sleep Inc.)
- Focus on e-commerce, direct consumer engagement, online product education, trial programs, and convenient delivery.
- Strong digital presence, direct customer relationships, streamlined purchasing, and differentiated product offerings.
- High customer-acquisition costs, intense online competition, limited physical reach, and profitability pressures.
Recent Developments
-
In August 2026, The Home Depot expanded its Express Delivery service, targeting delivery of home-improvement products in under three hours. The company reported USD 47.9 billion in Q2 FY2026 sales, up 5.7% year over year, while U.S. comparable sales increased 1.3%. The expansion strengthens rapid fulfillment capabilities and improves convenience for consumers purchasing Home Improvement Products.
-
In December 2024, Lowe’s launched its first U.S. home-improvement product marketplace as part of its Total Home strategy, expanding its online assortment through third-party sellers without requiring Lowe’s to hold the inventory. The initiative broadens the availability of digital products and strengthens the company’s omnichannel capabilities.
U.S. Home Bedding Market Report Scope
Report Attribute
Details
Market size in 2025
USD 39.3 billion
Estimated market size in 2026
USD 40.7 billion
Projected market size by 2033
USD 52.5 billion
Growth rate
CAGR of 3.7% from 2026 to 2033
Base Year
2025
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, product by material, distribution channel
Key companies profiled
Tempur Sealy International, Inc.; Serta Simmons Bedding, LLC; Sleep Number Corporation; Purple Innovation, Inc.; Saatva, Inc.; Resident Home LLC; Casper Sleep Inc.; Ashley Furniture Industries, LLC; Kingsdown, Inc.; Zinus, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Home Bedding Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2026 to 2033. For this study, Grand View Research has segmented the U.S. home bedding market report based on product, product by material, and distribution channel.
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Mattress
-
Full Size (54" × 75")
-
King Size (76" × 80")
-
Queen Size (60" × 80")
-
Twin XL Size (38" × 80")
-
Twin Size (38" × 75")
-
Others [California King (72" × 84"), etc.]
-
-
Bedroom Linen
-
Sheets & Mattress Covers
-
Blankets
-
Pillowcases & Covers
-
Others (Bed Pads, etc.)
-
-
Pillows & Cushions
-
Filled
-
Non-filled
-
-
Bolsters (Filled)
-
Mattress Toppers, Protectors, and Pads
-
Quilts
-
Bedspreads
-
Eiderdowns
-
Duvets / Comforters
-
-
Product by Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
Mattress
-
Innerspring
-
Latex
-
Foam
-
Hybrid
-
Others (Airbeds, Waterbeds, etc.)
-
-
Bedroom Linen
-
Cotton
-
Polyester
-
Cotton-Polyester Blends
-
Linen
-
Silk
-
Bamboo/Viscose
-
Others (Modal, Hemp, Wool, etc.)
-
-
Pillows & Cushions
-
Down & Feather
-
Memory Foam
-
Latex
-
Polyester Fiberfill
-
Microfiber
-
Others (Buckwheat Hulls, etc.)
-
-
Bolsters (Filled)
-
Down
-
Feather
-
Others
-
-
Mattress Toppers, Protectors & Pads
-
Memory Foam
-
Latex
-
Polyester Fiberfill
-
Cotton
-
Waterproof/PU-Backed Materials
-
Others (Wool, Bamboo, etc.)
-
-
Quilts
-
Down
-
Feather
-
Polyester Fiberfill
-
Microfiber
-
Others
-
-
Bedspreads
-
Synthetic
-
Blended
-
Polyester Fiberfill
-
Microfiber
-
-
Eiderdowns
-
Down
-
Blended
-
Polyester Fiberfill
-
Microfiber
-
-
Duvets / Comforters
-
Down
-
Feather
-
Polyester Fiberfill
-
Microfiber
-
Others
-
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Offline
-
Hypermarkets and Supermarkets
-
Specialty Bedding & Furniture Stores
-
Department Stores
-
Independent Retailers
-
Factory Outlets & Brand Showrooms
-
-
Online
-
Brand-Owned Websites (DTC)
-
Online Marketplaces
-
-
Research Methodology
The U.S. home bedding market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. home bedding segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Distribution Channel
Revenue capture definition
Online
Revenue generated from home improvement products purchased through digital channels, including manufacturer websites, online marketplaces, retailer e-commerce platforms, and other internet-based sales channels where the transaction is completed online.
Offline
Revenue generated from home improvement products purchased through physical retail and traditional sales channels, including home improvement stores, specialty stores, mass retailers, dealers, distributors, and other brick-and-mortar outlets where the transaction is completed in person.
Estimation Model
01
02
03
04
Household & Housing Base Layer
Bedding Demand Layer
Product & Purchase Layer
Monetization Layer
Who purchases Home Bedding Products?
Who actively purchases bedding products?
Who actively purchases specific bedding products?
How much revenue is generated?
Identifies U.S. households and residential properties requiring bedding products, including mattresses, pillows, blankets, sheets, mattress covers, bed pads, and other bedding essentials. Includes homeowners, renters, and households furnishing or replacing bedding products.
Captures households purchasing or replacing bedding products based on factors such as product wear, household formation, bedroom furnishing, relocation, lifestyle preferences, and comfort requirements.
Segments demand by product type, material, size, price point, replacement cycle, and purchasing channel. Covers purchases of mattresses, pillows and cushions, sheets and mattress covers, blankets, bed pillowcases and covers, and bed pads.
Converts bedding product demand into market revenue using purchase frequency, average selling prices, replacement rates, household spending, and channel-specific purchasing behavior across Home Bedding Products.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
U.S. Home Improvement Market Demand, Consumer Preferences & Purchasing Behavior Analysis
Conducted a detailed assessment of consumer demand for home improvement products, covering renovation and repair activities, project types, spending priorities, DIY and professional-led projects, product preferences, and purchase considerations.
Helps stakeholders identify high-value consumer segments, understand evolving renovation and repair priorities, and align product offerings with demand for functional upgrades, convenience, durability, and aesthetic improvements.
U.S. Home Improvement Market Product Innovation, Smart Solutions & Sustainability Trends
Evaluated innovation across home improvement products, including smart home solutions, energy-efficient products, water-saving fixtures, advanced building materials, connected devices, and products incorporating sustainable materials and technologies.
Provides insights into evolving consumer expectations, supporting differentiation through technology-enabled solutions, energy efficiency, sustainability, improved functionality, and enhanced product performance.
U.S. Home Improvement Market Distribution & Market Opportunity Assessment
Assessed growth opportunities across home improvement retailers, home centers, specialty stores, online marketplaces, manufacturer websites, and professional distribution channels, while analyzing regional demand, housing characteristics, renovation activity, and key consumer markets.
Supports investment and expansion decisions by identifying high-potential customer segments, geographic markets, retail formats, digital sales opportunities, and distribution channels serving home improvement demand.
Frequently Asked Questions About This Report
The product by material, innerspring mattresses, accounted for the largest revenue share of 42.1% in 2025.
Emerging trends in the U.S. Home Bedding Market include growing demand for sustainable, organic, and temperature-regulating bedding materials that enhance sleep comfort. Smart bedding technologies, personalized designs, premium fabrics, and direct-to-consumer e-commerce platforms are gaining traction among consumers seeking convenience and improved sleep experiences.
Sales through offline channels accounted for the largest revenue share of 71.5% in 2025.
Mattress toppers, protectors, and pads are expected to grow at a CAGR of 4.6% from 2028 to 2033.
The U.S. home bedding market size was estimated at USD 39.3 billion in 2025 and is expected to reach USD 40.7 billion in 2026.
The U.S. home bedding market is expected to grow at a compound annual growth rate of 3.7% from 2025 to 2033 to reach USD 52.5 billion by 2033.
Key players in the U.S. home bedding market include Tempur Sealy International, Serta Simmons Bedding, Sleep Number, Purple Innovation, Saatva, Resident Home, Casper, Ashley Furniture, Kingsdown, and Zinus.
The U.S. home bedding market is driven by rising housing construction, home renovations, increasing consumer spending on bedroom comfort, and growing demand for premium and sustainable bedding products. Product innovation, e-commerce expansion, and consumer interest in sleep quality and wellness further support market growth.
Mattress dominated the U.S. home bedding market with a share of more than 41.6% in 2023.
About the Author(s)
Homecare & Decor Research Team
Consumer Goods · Homecare & DecorThis report was authored by the homecare & decor research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the homecare & decor segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


