
- Home
- »
- Electronic & Electrical
- »
-
U.S. Household Appliances Market Size Report, 2026-2033GVR Report cover

U.S. Household Appliances Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Major Appliances, Small Appliances), By Distribution Channel (Hypermarkets & Supermarkets, Electronic Stores, Online), And Segment Forecasts
Market Size, 2025
$102.5BMarket Estimate, 2026
$106.0BMarket Forecast, 2033
$140.7BCAGR, 2026–2033
4.1%U.S. Household Appliances Market Summary
The U.S. household appliances market size was valued at USD 102.5 billion in 2025 and is projected to grow from USD 106 billion in 2026 to USD 140.7 billion by 2033, at a CAGR of 4.1% from 2026 to 2033. The industry is primarily driven by strong replacement demand, supported by high household penetration and shorter upgrade cycles as consumers seek energy-efficient and technologically advanced products. Increasing awareness around energy conservation, along with regulatory standards such as Energy Star ratings, is encouraging the adoption of appliances with lower power consumption. Additionally, the growing integration of smart home ecosystems is accelerating demand for connected appliances with IoT-enabled features, offering convenience, automation, and remote control capabilities.
Key Market Trends & Insights
- Based on product, the major appliances accounted for a revenue share of 87.1% in 2025.
- The small household appliances segment is projected to grow at a CAGR of 5.9% from 2026 to 2033.
- Based on the distribution channel, the sales through electronic stores accounted for a revenue share of 40.9% in 2025.
Market Size & Forecast
- 2025 Market Size: USD 102.5 Billion
- 2033 Projected Market Size: USD 140.7 Billion
- CAGR (2026-2033): 4.1%
- North America: Largest market in 2025
- Asia Pacific: Fastest growing market
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Technological advancement is playing a central role in shaping purchasing behavior in the U.S. appliance landscape. The adoption of connected appliances enabled by IoT, AI, and voice-assistant compatibility is growing rapidly, with consumers seeking products that support remote operation, personalized settings, energy monitoring, and predictive maintenance. Smart appliances are increasingly viewed as part of the broader connected home ecosystem, reinforcing demand among higher-income and tech-oriented buyers. Manufacturers are also introducing innovations in noise reduction, faster cycle times, and sensor-based automation, helping appliances deliver both improved performance and user comfort. For instance, in January 2026, MOVA officially entered the U.S. market with a major product debut in Silicon Valley, showcasing its ambition to compete in the premium home cleaning segment through a connected ecosystem of intelligent appliances. The launch featured more than 20 products, including advanced robot vacuums, wet-and-dry floor cleaners, cordless stick vacuums, and even personal care devices, all built around AI-powered navigation, high-performance suction, and automated maintenance features. Flagship innovations highlighted include adaptive zone-based cleaning, modular mop-swapping systems, high-pressure mopping technology, edge-to-edge cleaning arms, and steam-based deep sanitization. With this expansion, MOVA is positioning itself as a next-generation whole-home cleaning brand focused on practical automation, smarter household coverage, and technology-driven convenience.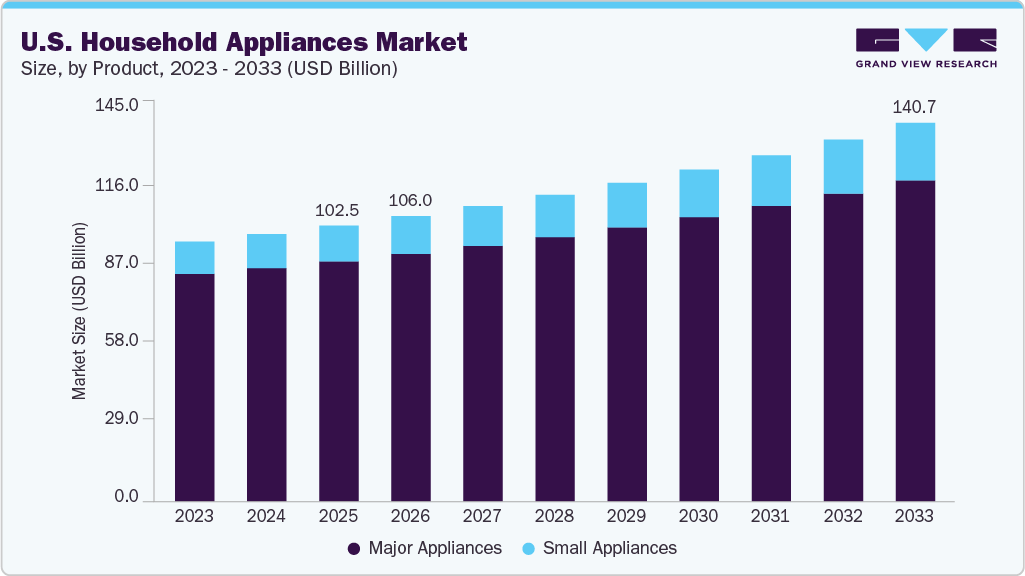 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
As consumers upgrade kitchens, bathrooms, and utility spaces, there is strong demand for aesthetically coordinated appliance suites, built-in models, and premium finishes. The market is also benefiting from a shift toward high-performance appliances that cater to cooking enthusiasts and health-conscious households, including steam-based ovens, air-fryer integrated ranges, and advanced refrigeration systems designed for fresher food preservation. Appliance replacement demand is further supported by the aging installed base, as consumers transition from older, less efficient models to modern high-efficiency alternatives.
Health, hygiene, and indoor wellness have also emerged as influential themes in appliance adoption. U.S. consumers are increasingly investing in air purification devices, water filtration systems, sanitizing dishwashers, and self-cleaning technologies that enhance household safety and cleanliness. Demand for appliances with antimicrobial coatings, improved filtration, and touchless operation is strengthening, particularly among families and urban households focused on healthier living environments. These trends are accelerating innovation in both major and small domestic appliance categories.
Sustainability and energy efficiency remain key decision drivers, as consumers become more attentive to electricity consumption, long-term operating costs, and environmental impact. ENERGY STAR-certified appliances continue to gain traction, supported by utility rebates, government efficiency standards, and rising consumer awareness around reducing household carbon footprints. In parallel, manufacturers are investing in eco-friendly refrigerants, improved insulation technologies, and water-saving wash systems to meet evolving regulatory and consumer expectations.
Retail and distribution dynamics are further accelerating market momentum. Omnichannel purchasing has become mainstream, with consumers combining online research, digital price comparison, and physical store evaluation before making purchases. Major retailers such as Best Buy, Home Depot, Lowe’s, and Walmart, alongside online platforms like Amazon, are expanding appliance accessibility through fast delivery, installation services, and flexible financing solutions, including zero-interest plans and buy-now-pay-later options. Brands such as Samsung, LG, Whirlpool, and GE Appliances are also strengthening customer engagement through experiential showrooms, interactive product demonstrations, and direct-to-consumer models.
Market Dynamics
The growing popularity of premium modular kitchens is emerging as an important factor driving the growth of the industry. Consumers are investing in modern kitchen layouts that combine aesthetics, space optimization, and advanced functionality, leading to higher demand for premium built-in household appliances. Modular kitchen concepts emphasize seamless integration of appliances such as built-in ovens, induction cooktops, smart refrigerators, dishwashers, and microwave systems, encouraging consumers to replace traditional standalone products with technologically advanced alternatives. Appliance manufacturers are also introducing premium product lines with features such as touch-screen controls, AI-enabled cooking assistance, voice connectivity, and minimalist built-in designs to align with evolving kitchen preferences. As consumers increasingly view kitchens as multifunctional lifestyle spaces rather than purely utility areas, demand for premium modular kitchen appliances is expected to continue supporting overall market growth.
The increasing durability and extended product lifespan of modern household appliances are emerging as key factors restraining the growth of the industry. Advances in manufacturing quality, energy-efficient technologies, and component reliability have enabled appliances such as refrigerators, washing machines, dishwashers, and air conditioners to operate efficiently for longer periods, reducing the frequency of replacement purchases among consumers. Many households are now retaining appliances for extended durations unless a major functional issue arises, limiting recurring sales opportunities for manufacturers and retailers. In addition, rising prices of premium and smart appliances are encouraging consumers to maximize the usage life of existing products before investing in replacements. Improved after-sales services, easier availability of repair parts, and growing access to maintenance support are further extending appliance usability across households. For instance, consumers are increasingly opting for repairs and minor upgrades instead of purchasing entirely new appliances, particularly during periods of economic uncertainty and inflationary pressure.
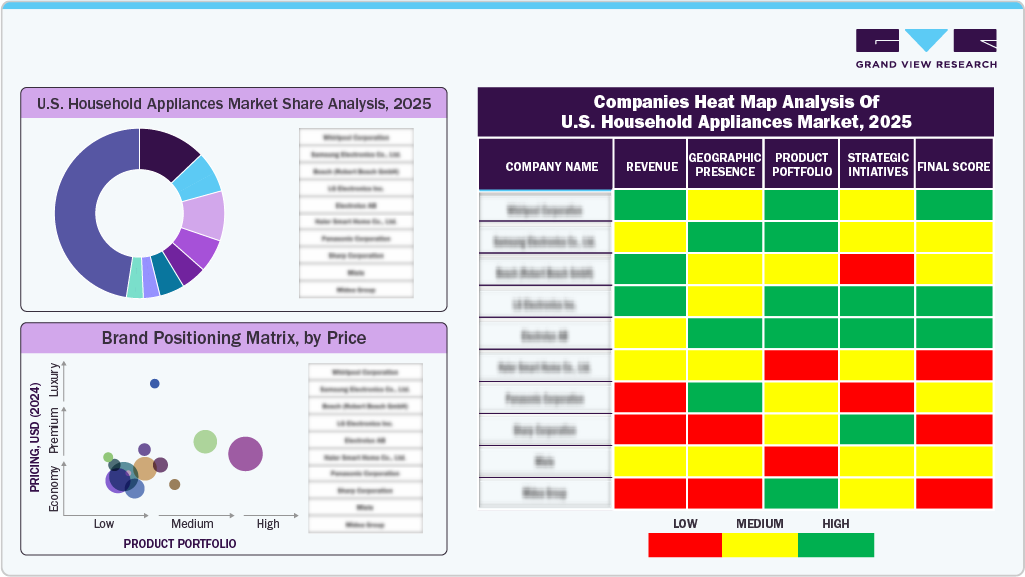
Brand Market Share Insights
Manufacturers are refining their portfolios to capture growth across major appliances, small domestic appliances, and smart-home integrated categories, reflecting the market’s diverse and evolving household needs. Premium appliance players are sharpening their focus on high-performance refrigerators, advanced laundry systems, and built-in cooking suites aimed at middle-to-upper income homeowners who prioritize durability, energy efficiency, and modern design aesthetics. Emphasis on ENERGY STAR compliance, larger capacity formats, quieter operation, and connected features such as remote monitoring and predictive maintenance continues to differentiate high-end appliance offerings in a competitive landscape shaped by strong brand loyalty and replacement-driven demand.
 To learn more about this report, Download Free Sample Report
Consumer Insights
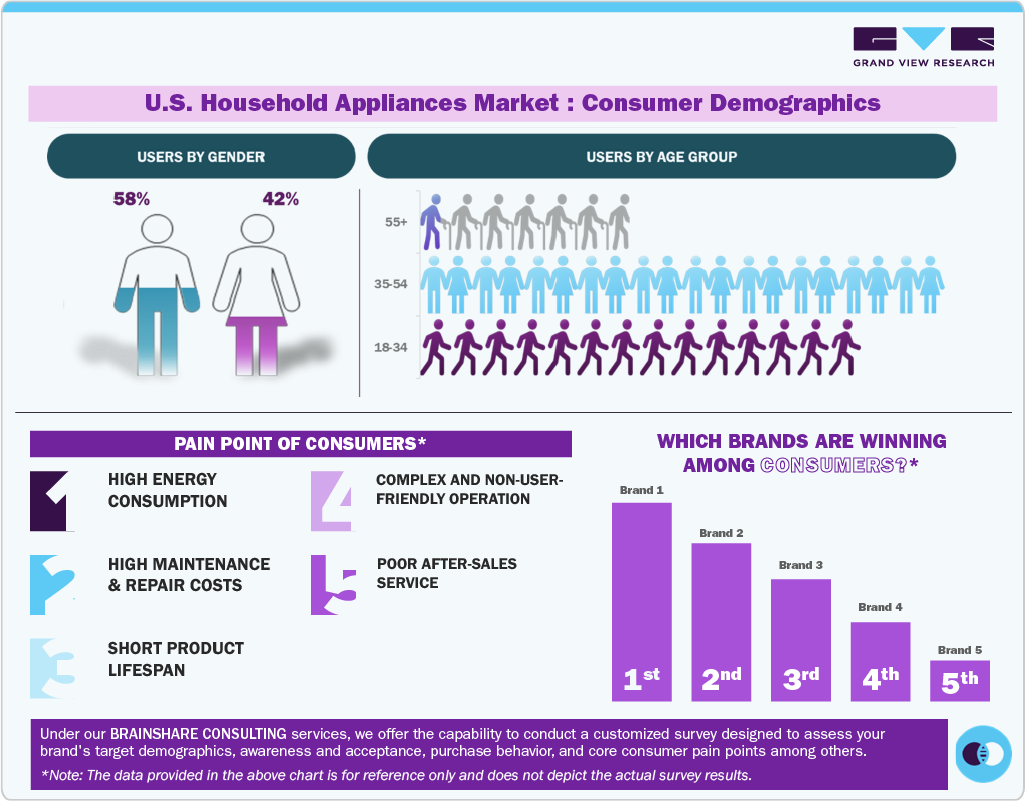
The consumer penetration of household appliances in the U.S. remains structurally high, as core appliances such as refrigerators, microwaves, and basic cooking devices are already present in most American homes. However, meaningful disparities persist across appliance categories, particularly for products tied to discretionary spending, advanced technology, or higher energy consumption. Lower-income households typically prioritize affordable, durable appliances that reduce daily workload without increasing utility bills, reinforcing demand for entry-level microwaves, drip coffee makers, compact toaster ovens, handheld vacuums, basic blenders, and low-watt heating or cooling devices, smart kitchen appliances. In these segments, purchase decisions remain highly price elastic and are strongly influenced by promotional discounting, warehouse-club pricing, and financing availability, highlighting the continued importance of affordability in shaping appliance consumption patterns.
Income and regional differences further sharpen adoption gaps in the U.S. appliance market. Household microdata from agencies such as the Energy Information Administration and Census Bureau consistently indicate that penetration of premium and smart appliances is significantly higher in high-income suburban counties and dual-income metropolitan households. In contrast, lower-income regions across parts of the Deep South, Midwest, and rural Appalachia continue to exhibit lower uptake of robotic vacuums, advanced air purification systems, premium countertop cooking appliances, and app-connected laundry devices. Limited exposure to brand showrooms, fewer specialty retail outlets, and reduced familiarity with premium categories constrain adoption. However, the rapid expansion of national e-commerce delivery networks and large-format retailers is gradually narrowing these gaps by bringing broader assortments and competitive pricing into underserved ZIP codes, supporting steady mid-tier upgrade momentum.
 To learn more about this report, Download Free Sample Report
Energy consumption and operating cost sensitivity remain decisive factors shaping appliance purchasing behavior nationwide. Residential electricity prices vary widely across states, with higher-cost markets such as California, New York, and Massachusetts creating stronger incentives for efficiency-focused appliance choices than lower-tariff regions in the Midwest or South. Efficiency-driven purchasing is reinforced by federal regulatory policy: U.S. appliance energy efficiency standards have been shown to reduce consumer energy bills while lowering pollution and greenhouse gas emissions, positioning ENERGY STAR-rated and standards-compliant appliances as increasingly preferred options for cost-conscious households. According to an article published in The Invading Sea from The Conversation in May 2025, appliance efficiency rules have historically delivered substantial consumer savings and public health benefits through reduced energy use and emissions. This combination of regional price pressures, federal standards, and rising awareness of lifetime operating costs continues to steer U.S. consumers toward appliances that balance upfront affordability with predictable long-term efficiency.
As omnichannel retail access expands and energy-conscious purchasing spreads, American households are steadily shifting from low-cost, generic appliances toward more durable, efficient mid-range models. Replacement-driven upgrades, broader digital availability, and stronger alignment between household budgets and energy-saving performance increasingly shape the market. While affordability remains central for many consumers, the ongoing transition toward compact, reliability-focused, and efficiency-optimized appliances is accelerating product refresh cycles across cooking, cleaning, air treatment, and everyday household convenience categories, supporting sustained evolution in the industry.
Product Insights
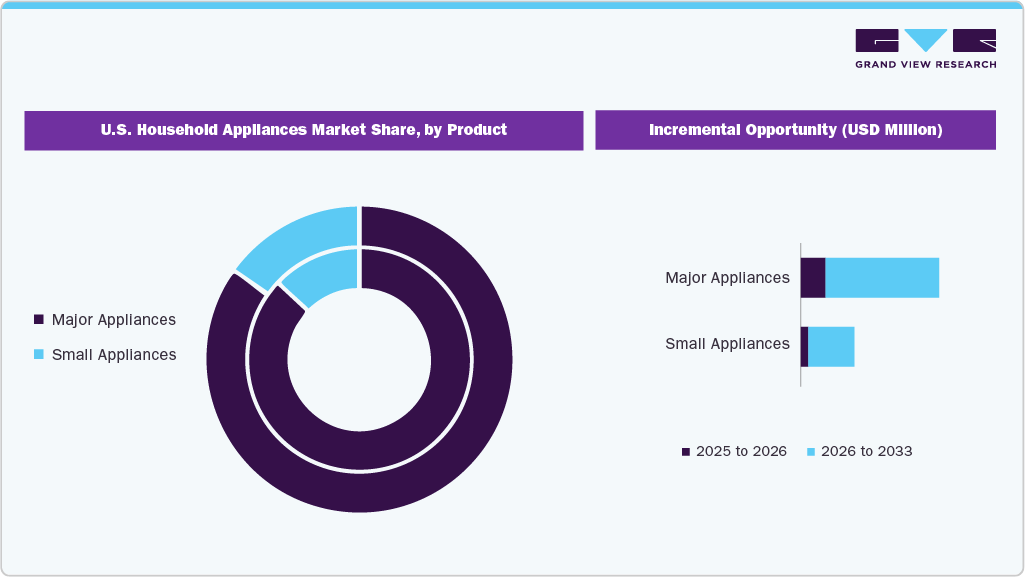
Major home appliances accounted for a revenue share of 87.1% in the year 2025. Demand is increasingly shaped by features such as larger capacity designs, quieter operation, smart connectivity, and advanced hygiene functions, which support busy dual-income lifestyles and higher expectations around home performance. The appeal of major appliances is further reinforced by shifting housing patterns and renovation-driven purchasing. Homeowners upgrading kitchens and utility spaces are seeking coordinated appliance suites, built-in configurations, and premium finishes that align with contemporary home aesthetics.
 To learn more about this report, Download Free Sample Report
The small household appliances segment is projected to grow at a CAGR of 5.9% from 2026 to 2033. American households are increasingly investing in small appliances that simplify cooking, cleaning, and personal-care routines, reflecting faster-paced lifestyles, hybrid work habits, and greater focus on home-based productivity. Categories such as air fryers, blenders, robotic vacuums, coffee machines, hand mixers, and portable steamers are gaining traction as consumers seek affordable upgrades that deliver immediate functional value without the cost and installation requirements of major appliances, smart kitchen appliances. Innovation and accessibility continue to strengthen adoption across income groups and living formats. Manufacturers are integrating smarter controls, sensor-based automation, quieter motors, and energy-efficient heating systems into mid-range price tiers, expanding demand beyond early adopters.
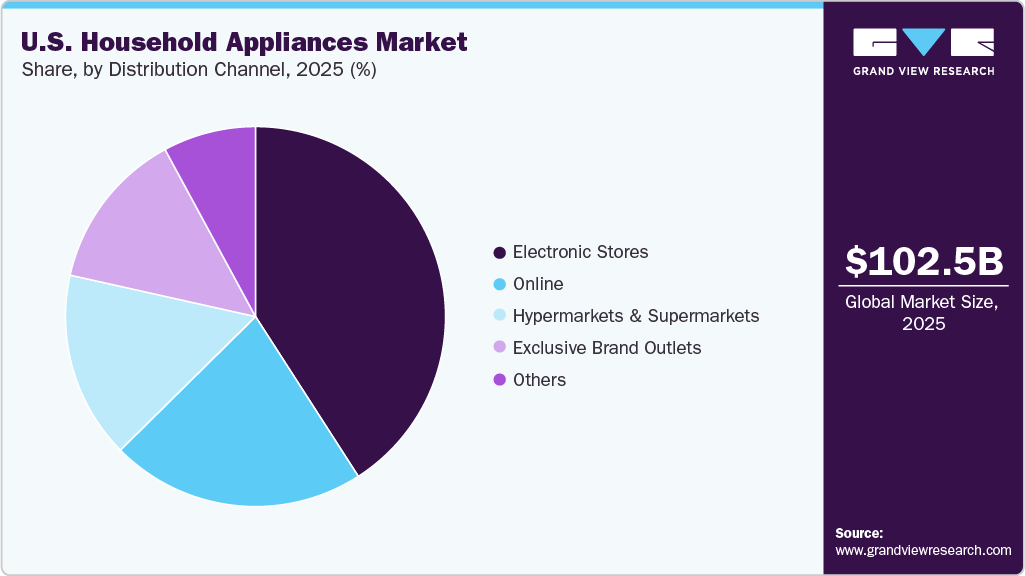
Distribution Channel Insights
Sales through electronic stores accounted for a revenue share of 40.9% in 2025. Electronics stores provide an enhanced purchasing environment through interactive displays, side-by-side product comparisons, and trained sales associates who guide consumers through specifications, feature trade-offs, and warranty considerations. Value-added services such as immediate financing options, extended protection plans, bundled accessory offers, delivery coordination, and post-sale technical support further reinforce consumer confidence.
 To learn more about this report, Download Free Sample Report
The online segment is projected to grow at a CAGR of 5.5% from 2026 to 2033. The U.S. industry is experiencing strong growth in online sales as consumer behavior shifts toward digital shopping. According to Adtaxi's 2024 Ecommerce Survey, 78% of Americans are now comfortable buying major appliances online, up from 73% the previous year. This rising preference aligns with broader e-commerce trends, where convenience and easy product and price comparisons are key drivers. With 93% of American adults shopping online and a growing number making daily purchases, the online channel has become an essential platform for major appliances, enabling brands to reach a wider audience efficiently.
Key U.S. Household Appliances Companies:
-
Whirlpool Corporation
-
Electrolux AB Group
-
Fisher & Paykel Appliances Holdings Ltd.
-
GE Appliances
-
Haier Group
-
LG Electronics
-
Panasonic Corporation
-
Robert Bosch GmbH
-
Samsung Electronics Co., Ltd.
-
SMEG S.p.A.
-
Miele & Cie. KG
-
iRobot Corporation
Recent Developments
-
In January 2026, GE Profile introduced a new smart refrigerator featuring its built-in Kitchen Assistant, designed to simplify grocery management and meal planning through advanced connected technology. The appliance supports features such as automated food tracking, personalized recipe support, and tools that help households organize shopping needs more efficiently. By combining modern refrigeration performance with AI-enabled assistance and smart home integration, GE Profile aims to transform the refrigerator into an interactive kitchen hub that reduces everyday effort and enhances convenience for consumers.
-
In August 2025,Instant Pot Brands launched a new “Mini” appliance line aimed at households with limited space yet still wanting full functionality. The range includes a 4-quart multi-cooker, a 4-quart air fryer with a transparent window for food monitoring, and a 4-slice toaster-oven/air-fryer hybrid that requires no pre-heating for most functions. Each model is sized for smaller kitchens but retains the performance expected from the brand. The collection will be available later in the month at major U.S. retailers, including Walmart, Target, and Amazon.
U.S. Household Appliances Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 102.5 billion
Market size value in 2026
USD 106.0 billion
Revenue forecast in 2033
USD 140.7 billion
Growth rate
CAGR of 4.1% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Volume, thousand units; revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Volume & revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel
Country scope
U.S.
Key companies profiled
Whirlpool Corporation; Electrolux AB Group; Fisher & Paykel Appliances Holdings Ltd.; GE Appliances; Haier Group; LG Electronics; Panasonic Corporation; Robert Bosch GmbH; Samsung Electronics Co., Ltd.; SMEG S.p.A.; Miele & Cie. KG; iRobot Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Household Appliances Market Report Segmentation
This report forecasts revenue growth at country level and provides an analysis on the latest trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. household appliances market report on the basis of product, and distribution channel.
-
Product Outlook (Volume Thousand Units, Revenue USD Billion, 2021 - 2033)
-
Major Appliances
-
Water Heater
-
Dishwasher
-
Refrigerator
-
Cooktop, Cooking Range, Microwave, and Oven
-
Vacuum Cleaner
-
Washing Machine and Dryers
-
Air Conditioner
-
-
Small Appliances
-
Coffee Makers
-
Toasters
-
Juicers, Blenders and Food Processors
-
Hair Dryers
-
Irons
-
Deep Fryers
-
Space Heaters
-
Electric Trimmers and Shavers
-
Air Purifiers
-
Humidifiers & Dehumidifiers
-
Rice Cookers & Steamers
-
Air Fryers
-
-
-
Distribution Channel Outlook (Volume Thousand Units, Revenue USD Billion, 2021 - 2033)
-
Hypermarkets & Supermarkets
-
Electronic Stores
-
Exclusive Brand Outlets
-
Online
-
Others
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Smart Appliance & IoT Adoption Analysis
Developed a tailored analysis of IoT and AI integration trends in U.S. household appliances, covering smart refrigerators, washing machines, and ovens. The study assessed consumer adoption of remote control and automation features, compatibility with virtual assistants such as Amazon Alexa and Google Assistant, and the role of mobile apps in enabling predictive maintenance alerts and energy consumption tracking.
Enables appliance manufacturers and technology providers to identify high-growth smart appliance segments, benchmark IoT feature sets against key competitors such as Samsung and LG, and prioritize R&D investments aligned with the growing smart home ecosystem and tech-savvy consumer expectations.
Energy Efficiency, Sustainability & Government Incentive Impact Assessment
Conducted a focused assessment of the role of energy efficiency and sustainability in shaping appliance purchasing decisions across the U.S. The analysis covered ENERGY STAR certification adoption, government incentive programs, consumer willingness to invest in eco-friendly appliances, manufacturer response in developing low-energy product lines, and the impact of rising environmental awareness on product development and marketing strategies.
Supports product development and market positioning by helping stakeholders understand the regulatory and consumer demand environment around sustainability, identify certification-driven purchase triggers, and develop eco-friendly product lines that align with government incentive frameworks and growing consumer preference for reduced utility bills and lower carbon footprints.
E-Commerce & Omnichannel Retail Behavior Analysis
Delivered a customized evaluation of shifting consumer purchasing behavior toward online and omnichannel retail channels for household appliances. The study analyzed platform performance of key retailers, including Amazon and Walmart, assessed the growing comfort of U.S. consumers with purchasing major appliances, and evaluated the role of competitive pricing and customer reviews.
Equips brands and retailers with actionable insights to optimize channel mix strategy, strengthen digital shelf presence, leverage omnichannel integration between online research and in-store purchase decisions, and capture the growing base of digitally influenced appliance buyers through targeted promotions and financing offers.
Frequently Asked Questions About This Report
Cooktops, cooking ranges, microwaves, and ovens dominated the U.S. household appliances market with a share of 31.6% in 2024. This is attributable to the swift pace of urbanization. rising income levels and spending power of consumers
Some of the key market players in the U.S household appliances market are Whirlpool Corporation; Electrolux AB Group; Fisher & Paykel Appliances Holdings Ltd.; GE Appliances; Haier Group; LG Electronics; Panasonic Corporation; Robert Bosch GmbH; Samsung Electronics Co., Ltd.; SMEG S.p.A.; Miele & Cie. KG; and iRobot Corporation
Key factors such as Home renovation and remodeling trends, along with a shift toward premium, high-performance products, drive the market growth. The rise of e-commerce and omnichannel retailing, led by platforms like Amazon and Best Buy, is influencing purchasing behavior through competitive pricing and convenience. Additionally, growing environmental awareness and government incentives, such as ENERGY STAR certifications, are pushing manufacturers to develop eco-friendly appliances. Changing lifestyles, urbanization, and the need for compact, multifunctional devices are also shaping innovation, while brands like Samsung and LG enhance in-store experiences with interactive displays and experiential retailing.
The U.S household appliances market size was estimated at USD 102.5 billion in 2025 and is expected to reach USD 106 billion in 2026.
The U.S household appliances market is expected to grow at a compound annual growth rate of 4.1% from 2026 to 2033 to reach USD 140.7 billion by 2033.
About the Author(s)
Electronic & Electrical Research Team
Consumer Goods · Electronic & ElectricalThis report was authored by the electronic & electrical research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic & electrical segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


