
- Home
- »
- Beauty & Personal Care
- »
-
U.S. Wearable LED Light Therapy Devices Market Report 2033GVR Report cover

U.S. Wearable LED Light Therapy Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (LED Face Masks, LED Hair Growth Caps/Helmets), By Light Technology (Blue Light, Red Light), By Price Tier, By End-user, By Distribution Channel, By State, And Segment Forecasts
Market Size, 2025
$657.1MMarket Estimate, 2026
$793.7MMarket Forecast, 2033
$1,556.9MCAGR, 2026–2033
10.1%U.S. Wearable LED Light Therapy Devices Market Summary
The U.S. wearable LED light therapy devices market was valued at USD 657.1 million in 2025 and is projected to grow from USD 793.7 million in 2026 to USD 1,556.9 million in 2033, at a CAGR of 10.1% from 2026 to 2033. The wearable LED light therapy devices industry in U.S. is developing as a consumer-facing segment within the broader aesthetics and home-use beauty technology landscape, supported by the migration of light-based treatments from dermatology practices and aesthetic clinics into convenient, wearable formats. Devices such as LED face masks allow consumers to undertake repeated treatments at home without the downtime typically associated with more invasive aesthetic procedures.
Key Market Trends & Insights
- By type: LED face masks held the largest market share of 59.0% in 2025.
- By light technology: Red light held the largest market share of 55.8% in 2025.
- By price tier: Premium (USD 301 to USD 600) held the largest market share of 32.3% in 2025.
- By end-user: Women held the largest market share of 70.8% in 2025.
- By distribution channel: Online held the largest market share of 68.5% in 2025.
Market Size & Forecast
- Market Size in 2025: USD 657.1 Million
- Estimated Market Size in 2026: USD 793.7 Million
- Projected Market Size by 2033: USD 1,556.9 Million
- CAGR (2026-2033): 10.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Consumer adoption is becoming increasingly visible across established wearable LED therapy brands. Omnilux reports more than 700,000 customers globally and supports its product portfolio with more than 40 peer-reviewed studies, while The Beauty Tech Group reported that its first CurrentBody Skin LED Series 1 mask sold more than 11,000 units during its first year. CurrentBody subsequently expanded its reach to more than 500,000 users across 80 countries, highlighting the growing international penetration of wearable LED technology.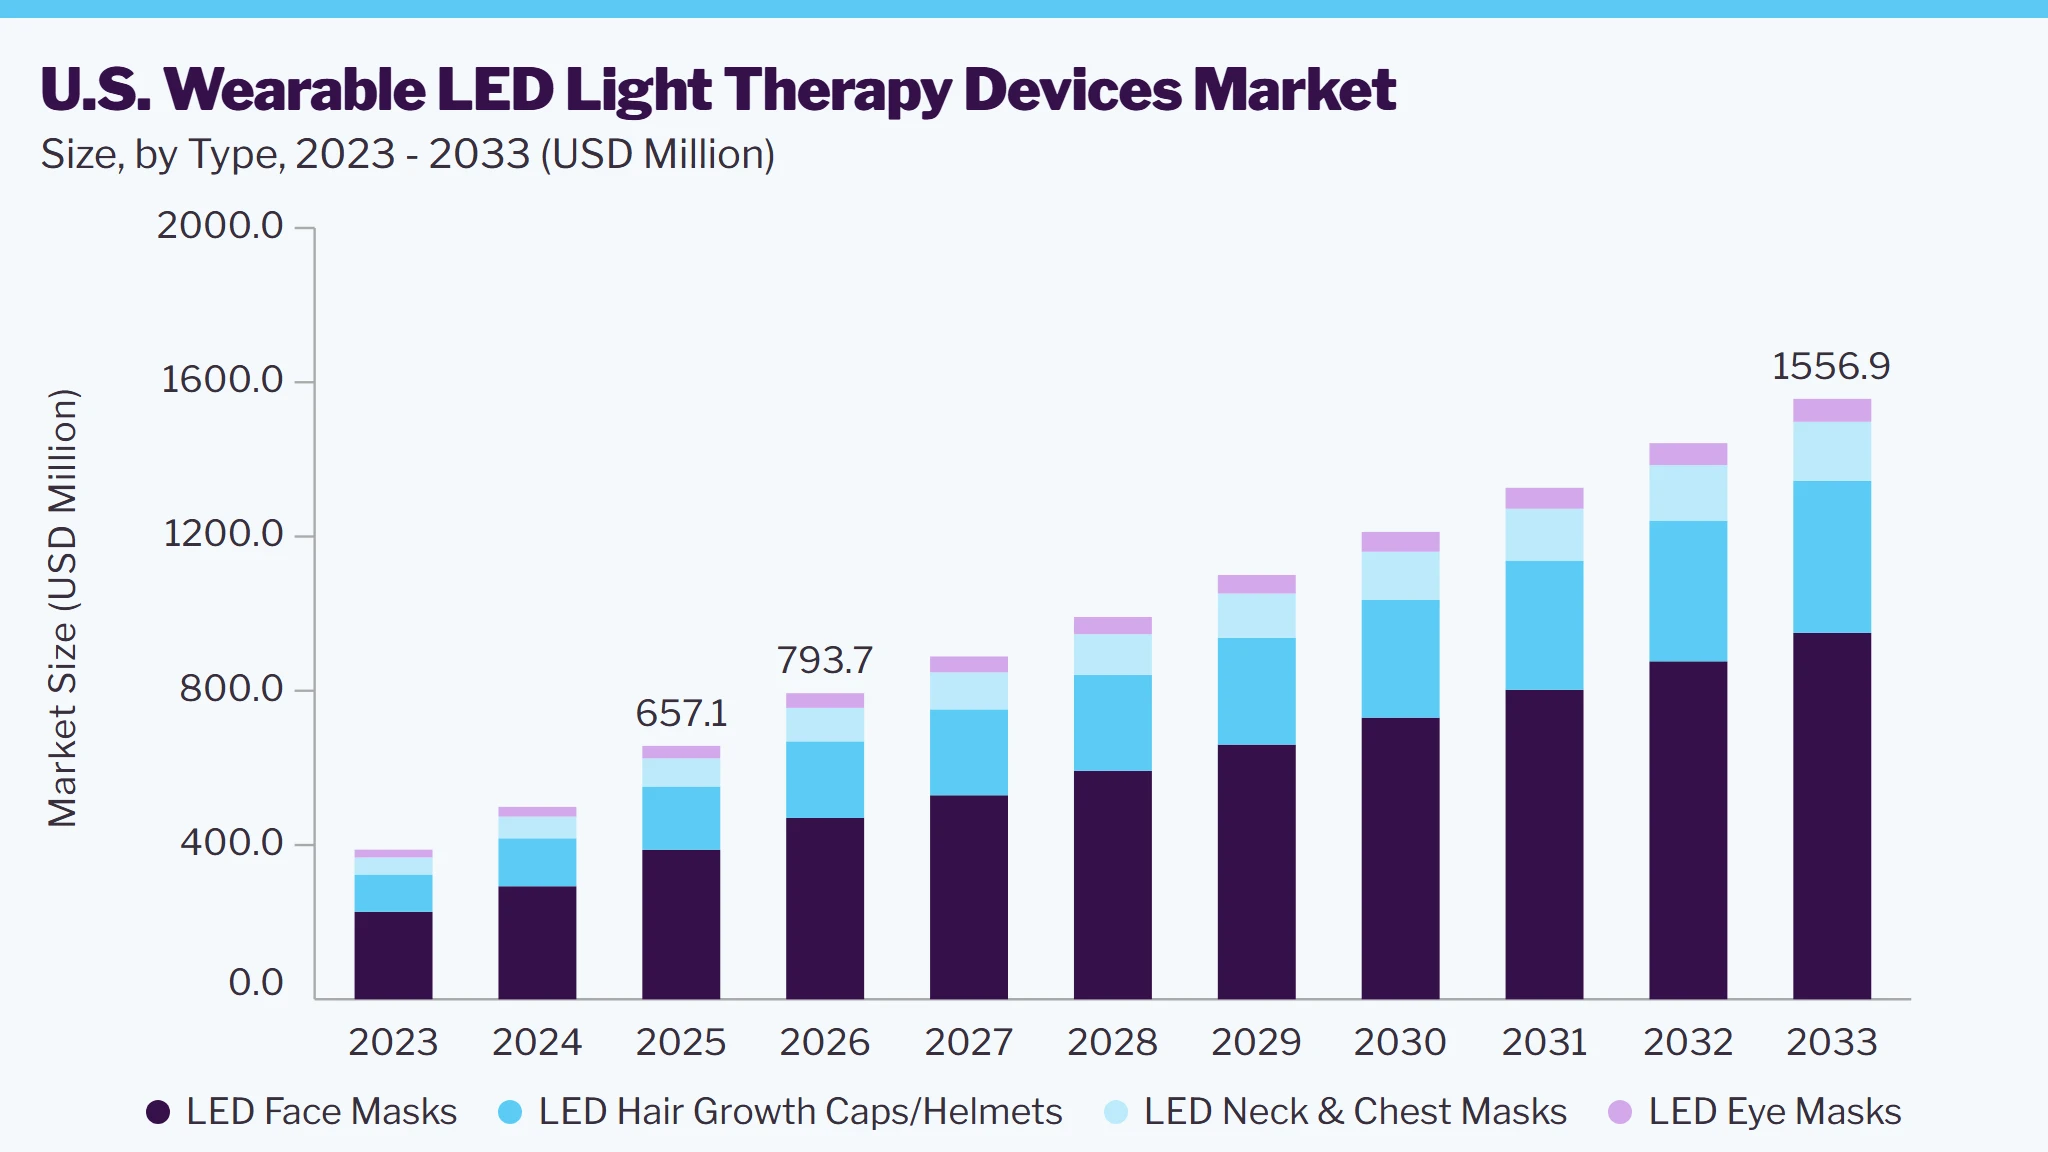 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Growing clinical evidence for at-home LED treatment is strengthening demand for wearable LED devices in the U.S. A 2025 systematic review and meta-analysis published in JAMA Dermatology evaluated six randomized clinical trials covering 216 participants with mild-to-moderate acne and found that at-home LED devices, particularly red- and blue-light combinations, were effective in reducing acne lesions.
More recently, a 2026 randomized controlled trial evaluating a 660-nm red/415-nm blue at-home LED device reported significant reductions in inflammatory acne lesions during 4 and 8 weeks of treatment. The combination of a large addressable acne population and increasing clinical validation of portable LED therapy is therefore strengthening acne as a key application area for wearable LED devices in the U.S. The American Academy of Dermatology reported in 2024 that acne affects nearly 50 million Americans annually, with approximately 85% of people aged 12–24 experiencing at least minor acne; adult acne also affects up to 15% of women.
Beyond acne management, the growing focus on skin rejuvenation and wrinkle management represents another major demand pool, particularly as consumers seek non-invasive approaches to visible signs of aging. The U.S. Census Bureau reported that the population aged 65 and older reached 61.2 million in 2024, accounting for 18.0% of the U.S. population, up from 12.4% in 2004. The expansion of this demographic base provides a growing addressable population for products positioned around wrinkles, skin texture, firmness, and overall skin appearance.
The growing addressable population for skin rejuvenation is further supported by device-specific clinical research on anti-aging and wrinkle management. A 2025 randomized, double-blind, sham-controlled study evaluated a home-use LED/IRED mask among 60 participants aged 30–65 years and reported improvements in crow's-feet measures after 16 weeks; the independent-rater improvement rate reached 86.2% in the full analysis set and 89.3% among participants who completed the protocol.
Separately, a 2025 randomized trial involving 95 women aged 45–60 years found significant reductions in selected periorbital and glabellar wrinkle measures following red-LED photobiomodulation, with participant satisfaction rates of 79.6% for three-weekly treatments and 73.4% for two-weekly treatments. These findings provide further clinical support for the use of at-home LED devices for anti-aging applications, particularly among consumers seeking non-invasive approaches to wrinkle management.
Market Dynamics
At-home skin rejuvenation is expanding demand for wearable LED devices as consumers seek non-invasive treatments that fit their routine skincare. A 2025 PubMed Central survey of 226 social media users found that 50.2% cited anti-aging as a motivation for red light therapy, while 37.9% sought improved skin texture, and 30.8% wanted to reduce dark spots. Face masks were the most considered device format at 34.4%, while 90.0% said they would consider purchasing an at-home red-light device. This indicates strong consumer interest in wearable formats for visible signs of skin aging. This broader application base helps LED therapy move into adjacent wearable formats, including hair-growth caps and helmets, neck and chest devices, and full- and partial-face masks.
The trend is increasingly penetrating the U.S. through broader retail availability and mainstream brand participation. In 2026, SharkNinja reported that the U.S. LED mask market was worth USD 35 million in 2024, while its own LED mask sales exceeded USD 70 million in 2025, indicating rapid category expansion. The company also highlighted the shift from LED masks being primarily online niche products in 2024 to availability through Costco in 2025. This wider distribution is improving physical access to full-face wearable masks and bringing LED-based skin rejuvenation into mainstream consumer beauty retail.
High upfront pricing remains a barrier to the adoption of wearable LED light therapy devices in the U.S., particularly since the category is positioned as a premium beauty-tech purchase rather than a routine skincare consumable. In 2025, Forbes Vetted reported that LED face-mask prices ranged from approximately USD 100 to more than USD 1,500, while the leading clinically positioned devices typically sit around USD 400. Omnilux Contour is priced at USD 395, while CurrentBody Series 2 is approximately USD 470. This premium pricing is evident across multiple leading products. Shark CryoGlow is priced at USD 349.99, Dr. Dennis Gross' SpectraLite FaceWare Pro at around USD 455, and Therabody's TheraFace Mask at USD 649.99. Allure's 2025 assessment similarly placed leading masks at USD 349-650, demonstrating that clinically positioned wearable LED products generally require several hundred dollars in upfront expenditure. This creates a higher entry threshold compared with conventional topical acne and anti-aging products.
Wearable LED devices can be positioned as post-treatment and maintenance products alongside dermatology, aesthetics, and skincare services rather than being sold only as standalone beauty devices. The American Academy of Dermatology notes that dermatologists may recommend at-home red-light devices to help maintain results after in-office treatments. This creates an opportunity for brands to build distribution partnerships with dermatologists, med-spas, aesthetic clinics, and skincare retailers, giving consumers a treatment-to-home-care pathway. Professional recommendations can also help address consumer uncertainty regarding device selection, treatment frequency, wavelength, and appropriate use, thereby improving confidence in at-home LED therapy. Clinics and med-spas can further incorporate wearable devices into post-procedure care packages, maintenance programs, memberships, and retail product assortments, creating additional revenue opportunities beyond professional services. Similarly, skincare retailers can cross-sell LED devices with serums, moisturizers, cleansers, and other complementary products, enabling brands to position light therapy as part of a broader skincare regimen. As consumers increasingly seek convenient solutions that extend professional skincare routines into the home, partnerships between wearable LED manufacturers and professional skincare providers can strengthen product credibility, consumer education, recurring engagement, and distribution reach, supporting greater adoption of wearable LED light therapy devices in the U.S. market.
Consumer Insights
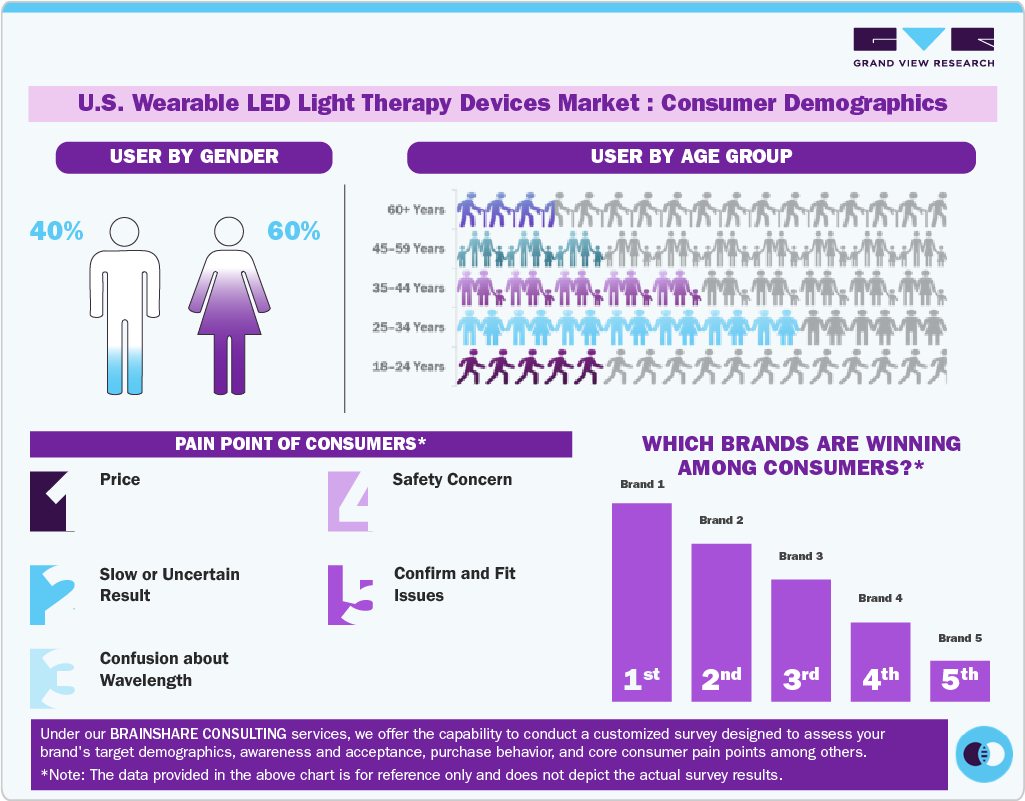
Consumer preferences in the U.S. wearable LED light therapy devices market are increasingly driven by convenience, treatment efficacy, skincare integration, and ease of use. Consumers tend to prefer hands-free devices that can be incorporated into existing skincare and wellness routines without requiring active holding or lengthy treatment sessions. Wearable formats, such as LED face masks, are particularly relevant because they provide a familiar and convenient treatment experience while allowing users to engage in other activities during sessions. Consumers also place increasing importance on demonstrated efficacy, clinical evidence, FDA clearance, treatment comfort, and visible results when evaluating higher-priced devices. However, limited consumer understanding of technical specifications such as wavelength combinations and light intensity creates a need for brands to provide clear, accessible, and evidence-based product information. This is encouraging manufacturers to emphasize simplified treatment modes, guided routines, and transparent explanations of wavelength-specific benefits.
 To learn more about this report, Download Free Sample Report
A notable difference in consumer participation is observed across gender groups, with women showing stronger engagement with skincare-focused LED treatments than men. A 2024 YouGov survey found that 8% of U.S. women had used LED light therapy as a skincare treatment, compared with 6% of men. Women's participation was also higher for other skincare technologies, including retinol and facial rollers, indicating greater integration of technology-enabled treatments into established skincare routines. Meanwhile, male consumers represent a meaningful opportunity for market expansion as brands increasingly position LED devices around acne, razor burn, skin recovery, hair growth, and anti-aging concerns. The introduction of men-specific products and multifunctional devices is helping to broaden the category beyond its traditional female-oriented skincare positioning, while digital content, social media demonstrations, and professional recommendations are supporting greater awareness among consumers less familiar with LED light therapy.
Analyst Perspective
The U.S. wearable LED light therapy devices market is increasingly shaped by the convergence of beauty technology, wellness, convenience, and clinically positioned skincare. Growing consumer interest in at-home treatments is supporting demand for wearable devices that combine multiple wavelengths, cordless designs, shorter treatment sessions, and multifunctional applications. Brands are increasingly differentiating their products through FDA clearance, clinical evidence, ergonomic designs, and targeted treatment modes that address concerns such as acne, wrinkles, redness, and skin rejuvenation. Meanwhile, DTC websites, specialty beauty retailers, pharmacies, and online marketplaces are expanding product accessibility and consumer education. Continued innovation in wavelength combinations, treatment precision, and professional-to-homecare integration is expected to further support adoption and market development.
Type Insights
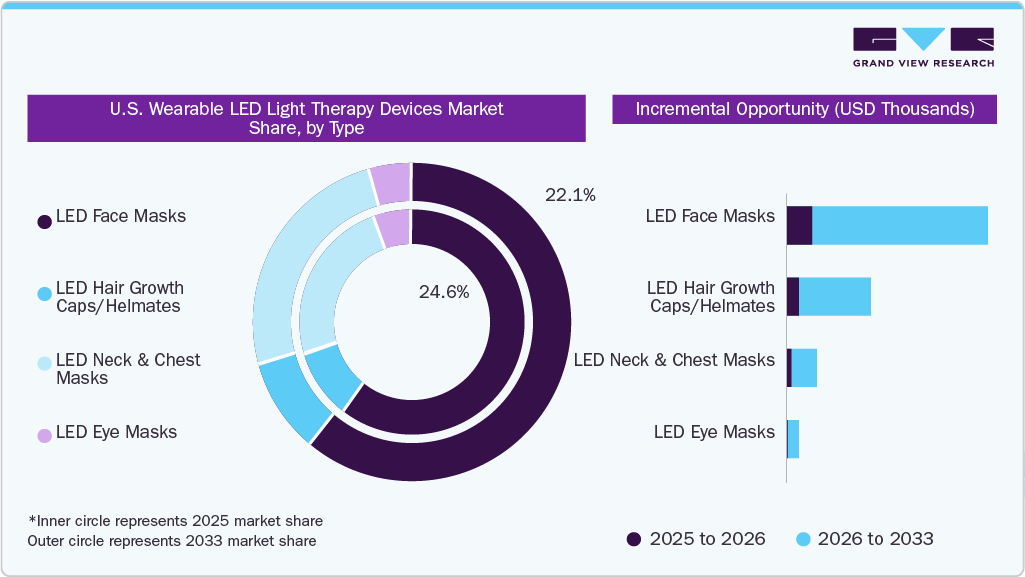
LED face masks accounted for the largest market share of 59.0% in 2025. Growing clinical validation and product innovation are strengthening the positioning of wearable LED devices as efficacy-focused at-home skincare solutions. For instance, Therabody’s 12-week clinical evaluation of the TheraFace Mask Glo assessed outcomes including radiance, skin-tone evenness, dark spots, fine lines, firmness, sagging, and skin texture, demonstrating the breadth of parameters being evaluated for LED face masks. In parallel, The Beauty Tech Group’s CurrentBody Skin pipeline includes 34 planned products spanning H2 2026 through 2029, indicating continued investment in product development and upgrades across its beauty technology portfolio. These developments reflect manufacturers’ increasing focus on clinically supported performance and continuous product innovation to differentiate wearable LED devices in the U.S. market.
 To learn more about this report, Download Free Sample Report
LED hair growth caps/helmets are anticipated to grow at a CAGR of 10.3% from 2026 to 2033, within the U.S. Rising consumer interest in convenient, non-invasive hair-growth solutions is encouraging manufacturers to offer wearable red-light therapy devices in cap and helmet formats that can be incorporated into regular at-home routines. In September 2026, Women’s Health evaluated several red-light hair-growth devices, highlighting products such as CurrentBody’s LED Hair Regrowth Device and HigherDOSE’s Red Light Hat. CurrentBody’s helmet uses 120 LEDs operating at 620–660 nm and provides 10-minute full-scalp treatments, while HigherDOSE offers a cordless 650-nm red-light cap designed for portability and on-the-go use. The comparison highlights increasing product differentiation based on scalp coverage, wavelength, treatment duration, portability, and wearable design, supporting the development of more convenient and specialized LED hair-growth devices in the market.
Light Technology Insights
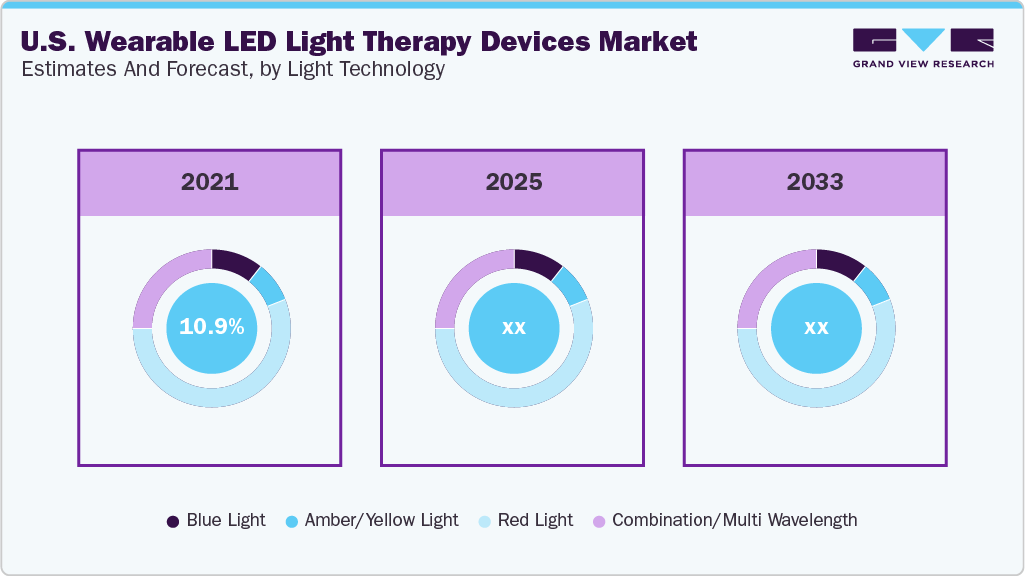
Red light dominated the U.S. wearable LED light therapy devices industry, accounting for a revenue share of 55.8% in 2025. Red light is one of the most widely incorporated wavelengths in wearable LED light therapy devices, primarily targeting fine lines, wrinkles, skin firmness, elasticity, texture, and overall skin rejuvenation. Red light penetrates deeper than blue and yellow light, enabling manufacturers to position it for anti-aging and skin-repair applications. Its broad applicability has made red light a core technology across face masks, neck and chest masks, and other wearable LED platforms. Manufacturers are increasingly combining red light with near-infrared (NIR) wavelengths to provide deeper tissue penetration and broader rejuvenation benefits within a single device.
 To learn more about this report, Download Free Sample Report
Combination/multi-wavelength products are anticipated to grow at a CAGR of 10.9% from 2026 to 2033. The U.S. is experiencing growing demand for multifunctional, user-friendly LED devices, which is driving the expansion of the wearable LED light therapy market. Consumers are increasingly presented with devices offering different wavelengths, light intensities, LED counts, and treatment modes, creating demand for products that simplify the selection process while addressing multiple skin concerns through a single wearable platform. In September 2026, Bob and Brad launched the PhysioFace LED Face Mask on Amazon U.S. at USD 179.99, marking the company's entry into at-home skincare. The device incorporates three treatment modes, including 630 nm red + 830 nm near-infrared light for smoother and firmer-looking skin and fine lines, 415 nm blue + 630 nm red light for blemish-prone skin, and 590 nm yellow light for visible redness and a more even-looking complexion. The launch demonstrates how manufacturers are combining multiple wavelengths with practical treatment formats to make wearable LED therapy more versatile and easier to incorporate into regular skincare routines.
Price Tier Insights
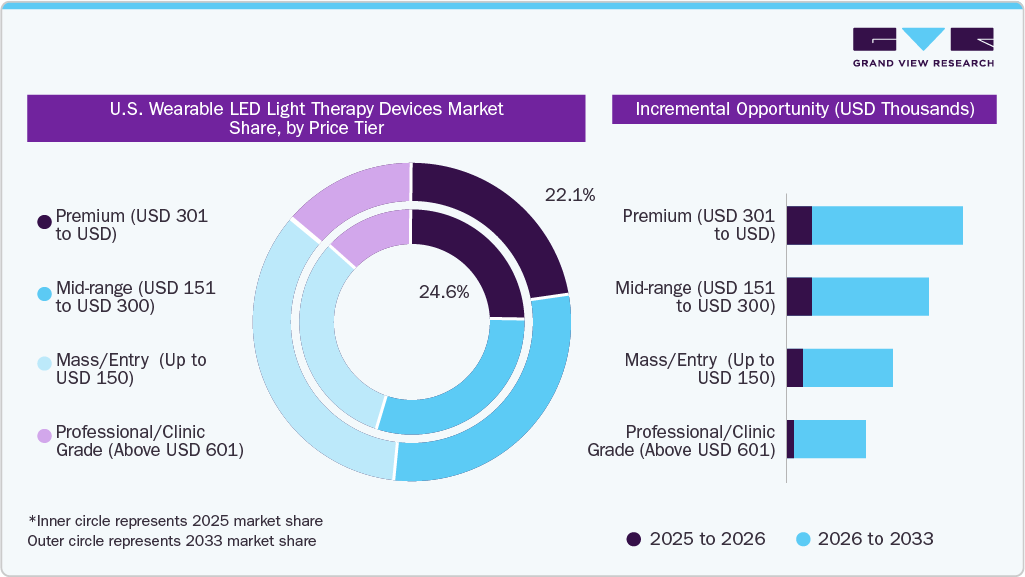
Premium (USD 301 to USD 600) dominated the U.S. wearable LED light therapy devices market, accounting for a revenue share of 32.3%in 2025. The premium segment is increasingly characterized by the integration of advanced LED configurations, clinical validation, and enhanced treatment convenience. For instance, Therabody's TheraFace Mask Glo, priced at USD 379.99, combines 504 medical-grade LEDs with 415 nm blue, 633 nm red, and 830 nm infrared wavelengths in a cordless 12-minute treatment platform. The device is FDA-cleared and incorporates vibration-based scalp massage, while a 12-week clinical study involving 104 participants provides additional support for its positioning around skin firmness, smoothness, radiance, and wrinkle-related concerns. This combination of multi-wavelength technology, high LED density, cordless usability, multifunctionality, and clinical evidence illustrates how premium wearable LED devices increasingly compete through treatment precision, convenience, and substantiation rather than wavelength count alone.
 To learn more about this report, Download Free Sample Report
Professional/clinic-grade (Above USD 601) is anticipated to grow at a CAGR of 11.8% from 2026 to 2033. The professional/clinic-grade segment is shifting toward high-value wearable LED platforms that combine regulatory clearance, multifunctionality, treatment precision, and professional-grade engineering. The launch of Celluma MYSTIQUE at a pre-order price of USD 795 and full retail price of USD 895 demonstrates the ability of manufacturers to command higher price points by integrating multiple treatment protocols and applications within a single wearable device. This trend is expected to support premiumization in the segment as clinics, aesthetic professionals, and high-intent consumers increasingly prioritize clinically supported performance, consistent light delivery, treatment versatility, and advanced device design over basic wavelength availability.
End-user Insights
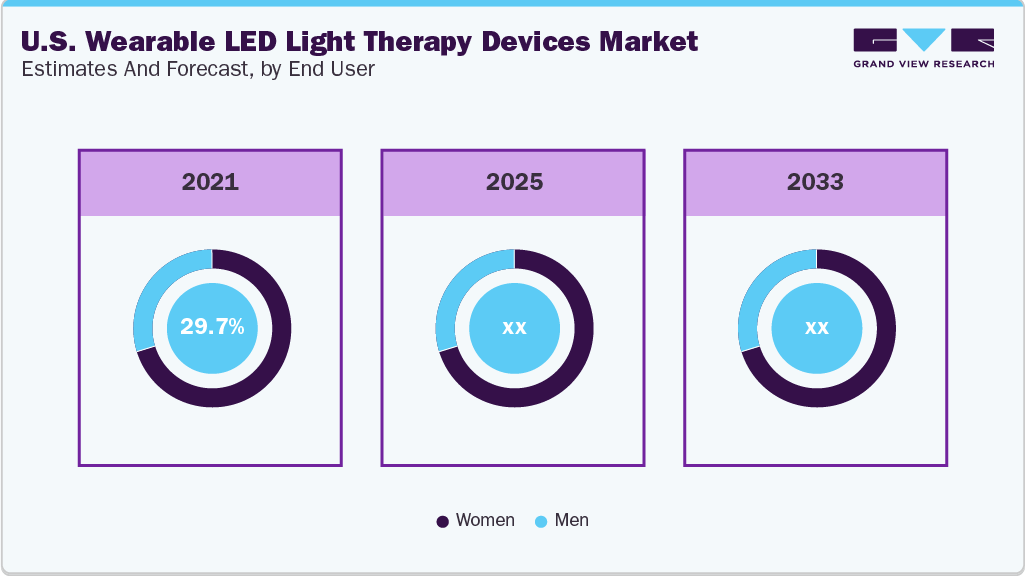
Women accounted for the largest market share of 70.8% in 2025. The women end-user segment is expected to remain a key contributor to the wearable LED light therapy devices market, supported by established skincare and beauty routines and growing interest in non-invasive solutions for anti-aging, acne management, skin tone, firmness, and overall skin health. The expansion of wearable formats such as face, eye, neck, and chest masks, combined with multi-wavelength technologies and clinically positioned products, is broadening the applications of LED therapy among women. The increasing integration of LED devices into daily skincare and longevity-focused routines is also expected to strengthen consumer awareness, product acceptance, and adoption in this segment.
 To learn more about this report, Download Free Sample Report
Men are anticipated to grow at a CAGR of 9.6% from 2026 to 2033. The men’s end-user segment comprises male consumers using wearable LED light therapy devices for concerns such as fine lines and wrinkles, acne, skin recovery, and hair thinning. Growing acceptance of skincare and grooming routines among men is increasing the relevance of non-invasive, at-home beauty technologies. Men represent an important consumer group for wearable LED devices, with applications spanning uneven skin tone, skin recovery, and hair thinning. The Beauty Tech Group’s consumer research recorded approximately 12 million annual searches for hair-regrowth solutions, with men accounting for 63% of the search audience, highlighting the relevance of male consumers to the hair-growth application. The hands-free and at-home nature of LED devices also allows treatments to be incorporated into existing grooming routines, while multifunctional devices addressing both facial and hair-related concerns can broaden their appeal among male consumers.
Distribution Channel Insights
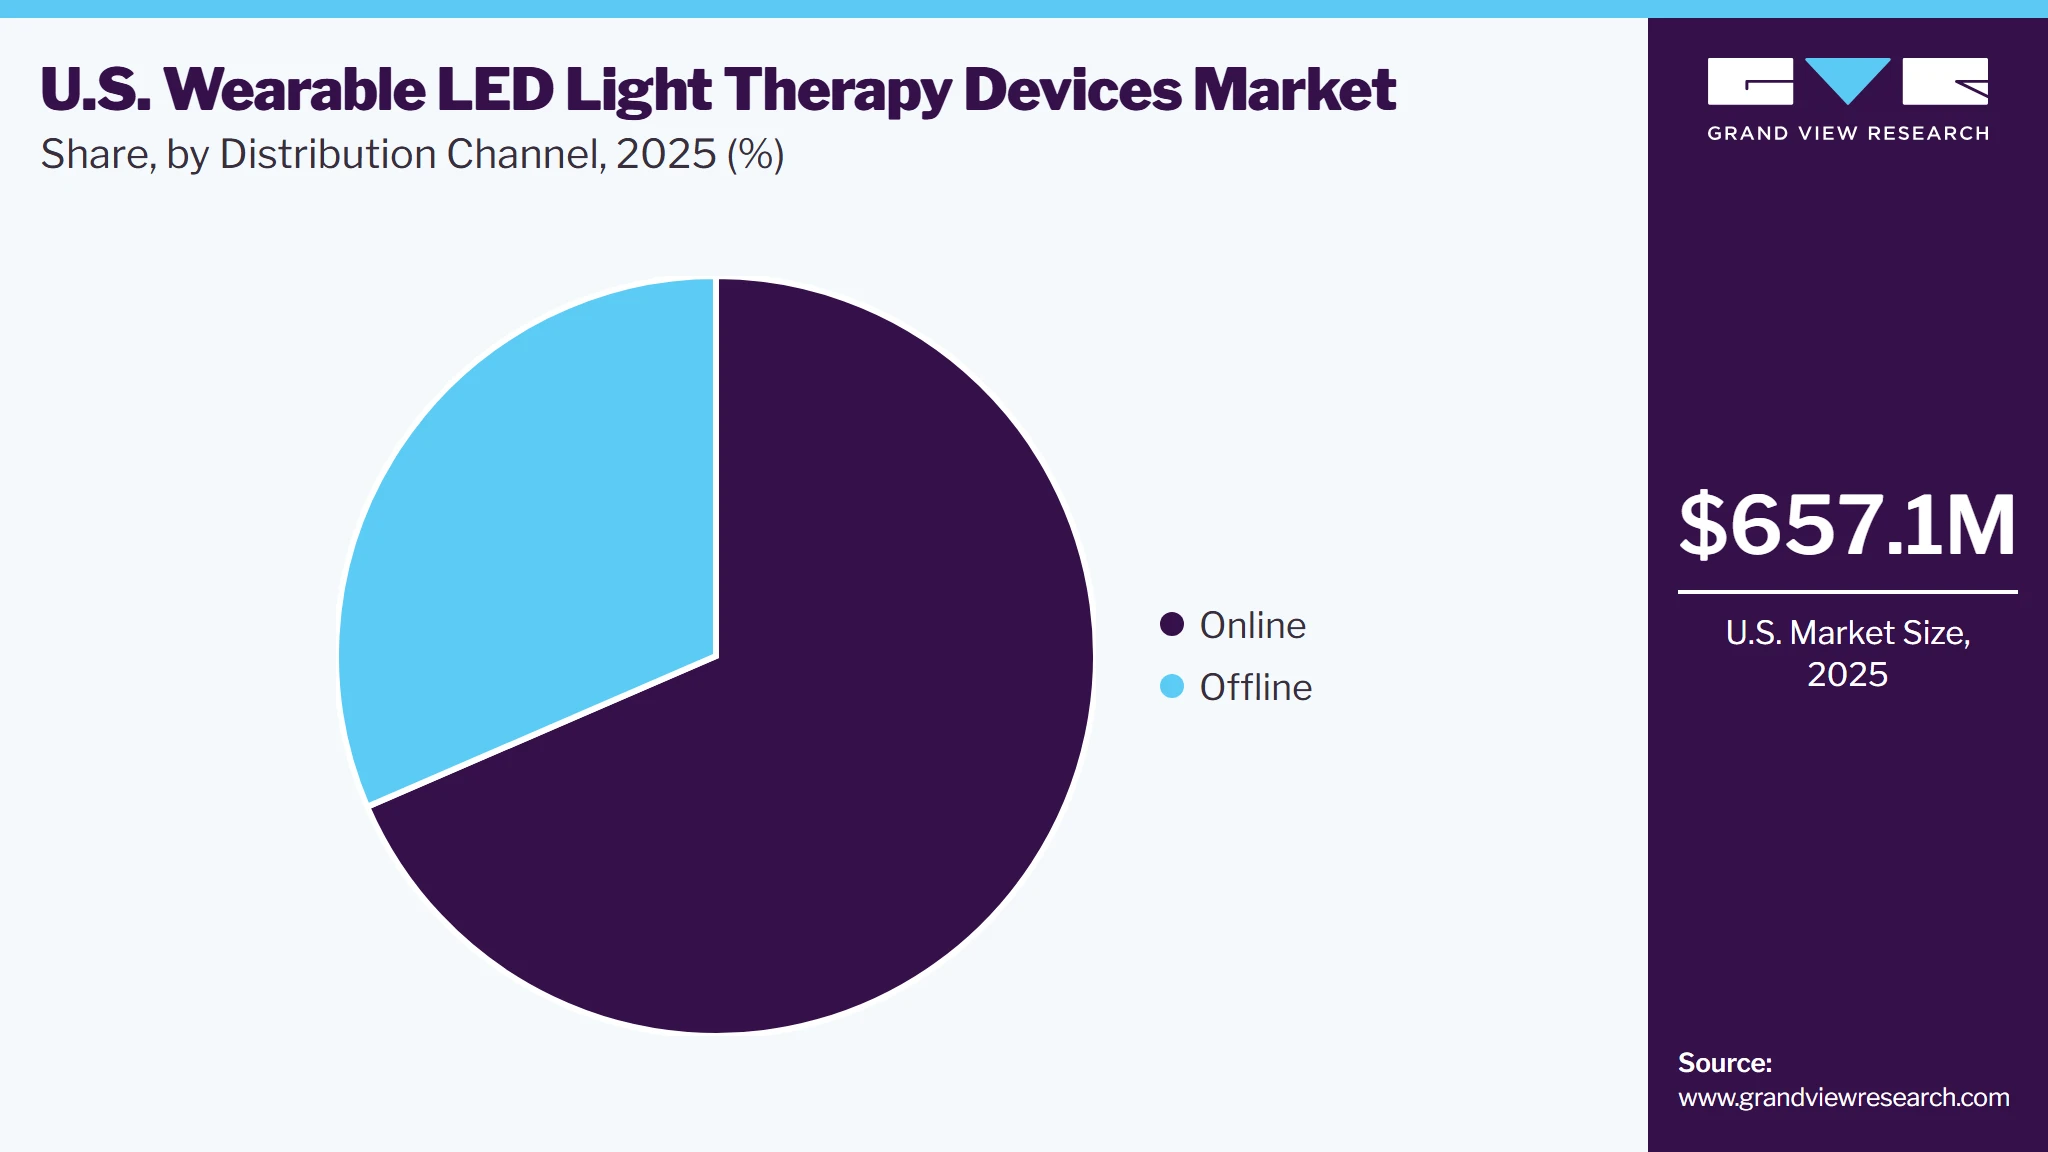
The online segment dominated the U.S. wearable LED light therapy devices industry, accounting for a revenue share of 68.5% in 2025. The online distribution channel comprises brand-owned websites (DTC) and online marketplaces & retailers, both of which are becoming increasingly important for wearable LED light therapy devices because consumers can research product specifications, compare technologies, review customer feedback, and purchase devices without visiting a physical store. Online channels represent a major distribution route for at-home beauty technology, particularly for brands with strong direct-to-consumer models. The Beauty Tech Group reported that eCommerce accounted for 91.2% of its sales, compared with 8.8% through wholesale channels, highlighting the importance of digital purchasing for beauty technology products. The company also maintains selective wholesale partnerships with retail partners to expand consumer reach, indicating that wearable LED brands can combine DTC channels with targeted physical retail distribution.
 To learn more about this report, Download Free Sample Report
The offline segment is anticipated to grow at a CAGR of 9.5% from 2026 to 2033. Offline distribution channels comprise supermarkets & hypermarkets, pharmacies & drugstores, specialty retailers, and other formats such as warehouse clubs, providing consumers with physical access to wearable LED light therapy devices. Offline retail remains relevant because consumers often want to assess the fit, flexibility, comfort, quality, and ease of use of wearable devices before purchasing, particularly for products worn directly on the face, eyes, neck, or head. Retail environments also allow brands to provide product demonstrations and staff-led education regarding wavelengths, treatment modes, treatment duration, and usage protocols.
Key U.S. Wearable LED Light Therapy Devices Company Insights
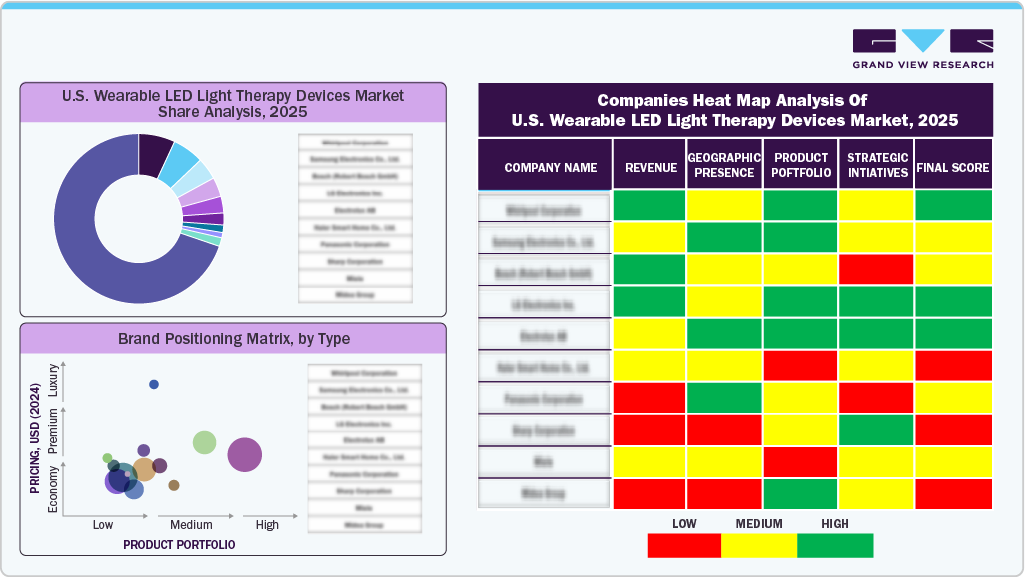
The U.S. wearable LED light therapy devices market is characterized by strong competition among specialized LED skincare brands, beauty-technology companies, and diversified consumer-device manufacturers. Major companies, including CurrentBody Skin, Shark Beauty, Omnilux, Therabody, Solawave, and Dr. Dennis Gross Skincare, compete through clinically positioned technologies, FDA clearances, multi-wavelength platforms, product innovation, and expanding retail and direct-to-consumer distribution. Market participants are increasingly introducing red, near-infrared, blue, amber, and multi-wavelength devices, while incorporating cordless designs, flexible materials, shorter treatment times, and multifunctional treatment modes to differentiate their products and strengthen consumer adoption.
 To learn more about this report, Download Free Sample Report
The market is also witnessing increasing emphasis on clinical validation, premium product positioning, direct-to-consumer channels, and professional-to-homecare integration. Companies such as FOREO Limited, Qure Skincare, HigherDOSE, Déesse PRO, and MZ SKIN Limited are leveraging specialized beauty-tech positioning and targeted skincare applications to differentiate their offerings. Meanwhile, Capillus and iRESTORE maintain more specialized positions in the wearable LED hair-growth device market. The expansion of specialty beauty retailers, pharmacies, online marketplaces, and social-commerce platforms is increasing product accessibility, while clinical studies, FDA 510(k) clearances, influencer marketing, and consumer education are strengthening brand credibility. CurrentBody provides a notable indication of the competitive scale achievable in this category, with CurrentBody Skin generating revenue, up 59% year over year, and accounting for 89.2% of The Beauty Tech Group's total revenue.
Key U.S. Wearable LED Light Therapy Devices Companies
-
Shark Beauty / SharkNinja
-
CurrentBody Skin
-
Omnilux
-
Therabody
-
Solawave
-
Dr. Dennis Gross Skincare
-
FOREO Limited
-
Qure Skincare
-
HigherDOSE
-
Capillus
-
iRestore
-
Déesse PRO
-
MZ SKIN Limited
Market Participant Categorization
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Omnilux, CurrentBody Limited, Dr. Dennis Gross Skincare, LLC, Therabody, Inc., Shark Beauty, Solawave Inc., HigherDOSE LLC, Qure Skincare Pty Ltd, Celluma, FOREO Limited, MZ SKIN Limited)
Focus on continuous product development across facial, neck, hair, and eye applications, as companies expand their wearable portfolios to address multiple skincare and wellness needs. Develop targeted products for specific consumer needs, including acne, anti-aging, men's skincare, hair growth, and under-eye concerns.
Broad product portfolios that span multiple treatment areas and consumer needs create opportunities for cross-selling and improved customer retention. Established brand recognition, clinical positioning, and regulatory clearances can increase consumer confidence in a category where efficacy and safety are important purchase considerations. Strong technical capabilities in wavelength selection, LED placement, treatment coverage, and device ergonomics support product differentiation.
Premium pricing can limit adoption among price-sensitive consumers, particularly as lower-cost LED masks and light therapy devices enter the market. Broad product portfolios and multiple technologies increase product development, manufacturing, regulatory, customer support, and inventory management complexity. Continued investment in clinical validation, regulatory compliance, software, and new device technologies can increase operating costs.
Emerging & Niche Players (Déesse PRO, iRESTORE, Curallux, LLC)
- Focus on specialized applications and targeted treatment areas rather than maintaining broad wearable LED portfolios.
- Differentiate through specialized device formats, targeted wavelengths, hands-free operation, portability, shorter treatment sessions, and multifunctional designs. Use direct-to-consumer channels and focused product launches to build awareness while minimizing the complexity associated with maintaining large product portfolios.
- Greater product specialization enables faster development of devices targeting specific consumer problems and treatment areas.
- Specialized expertise in light-based therapies can support differentiation in technically focused categories such as hair growth and advanced skincare. Smaller portfolios allow companies to concentrate marketing, R&D, and consumer education around a limited number of flagship devices.
- Narrower product portfolios can limit cross-selling opportunities and exposure across different wearable LED applications.
- Limited financial, R&D, clinical-testing, and marketing resources may constrain the pace of product development and geographic expansion. Lower brand recognition and smaller distribution networks can make customer acquisition more difficult compared with established LED brands.
Recent Developments
-
In September 2026, The Beauty Tech Group, the parent company of CurrentBody, officially launched the CurrentBody Skin Series 3 LED Mask, following two years of development. The wearable device introduces MyDose technology, which automatically adjusts the light dose based on the user's selected wavelength combination. The launch strengthens CurrentBody Skin's focus on personalized LED light therapy and advanced device technology, supporting product differentiation through greater treatment customization and LED coverage within the U.S. wearable LED light therapy devices market.
-
In April 2026, BioPhotas, Inc., the manufacturer of Celluma Light Therapy devices, launched the Celluma MYSTIQUE, an FDA-cleared wearable LED mask designed to simultaneously address acne, facial wrinkles, and scalp hair loss.
U.S. Wearable LED Light Therapy Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 657.1 million
Estimated market size in 2026
USD 793.7 million
Projected market size by 2033
USD 1,556.9 million
Growth rate
CAGR of 10.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, light technology, price tier, end-user, distribution channel, state
State scope
Alabama; Alaska; Arizona; Arkansas; California; Colorado; Connecticut; Delaware; Florida; Georgia; Hawaii; Idaho; Illinois; Indiana; Iowa; Kansas; Kentucky; Louisiana; Maine; Maryland; Massachusetts; Michigan; Minnesota; Mississippi; Missouri; Montana; Nebraska; Nevada; New Hampshire; New Jersey; New Mexico; New York; North Carolina; North Dakota; Ohio; Oklahoma; Oregon; Pennsylvania; Rhode Island; South Carolina; South Dakota; Tennessee; Texas; Utah; Vermont; Virginia; Washington; West Virginia; Wisconsin; Wyoming
Key companies profiled
Shark Beauty / SharkNinja; CurrentBody Skin; Omnilux; Therabody; Solawave; Dr. Dennis Gross Skincare; FOREO Limited; Qure Skincare; HigherDOSE; Capillus; iRestore; Déesse PRO; MZ SKIN Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Wearable LED Light Therapy Devices Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. wearable LED light therapy devices market report based on type, light technology, price tier, end-user, distribution channel, and state:
-
Type Outlook (Revenue, USD Million; 2021 - 2033)
-
LED Face Masks
-
Full Face LED Masks
-
Partial/Half Face LED Masks
-
-
LED Neck & Chest Masks
-
LED Hair Growth Caps/Helmets
-
LED Eye Masks
-
-
Light Technology Outlook (Revenue, USD Million; 2021 - 2033)
-
Blue Light
-
Amber/Yellow Light
-
Red Light
-
Combination/multi-wavelength
-
-
Price Tier Outlook (Revenue, USD Million; 2021 - 2033)
-
Mass/Entry (Up to USD 150)
-
Mid-range (USD 151 to USD 300)
-
Premium (USD 301 to USD 600)
-
Professional/Clinic Grade (Above USD 601)
-
-
End-user Outlook (Revenue, USD Million; 2021 - 2033)
-
Men
-
Women
-
-
Distribution Channel Outlook (Revenue, USD Million; 2021 - 2033)
-
Offline
-
Supermarkets & Hypermarkets
-
Pharmacies & Drugstores
-
Specialty Retailers
-
Others (Warehouse Clubs, etc.)
-
-
Online
-
Brand-Owned Websites (DTC)
-
Online Marketplaces & Retailers
-
-
-
State Outlook (Revenue, USD Million; 2021 - 2033)
-
Alabama
-
Alaska
-
Arizona
-
Arkansas
-
California
-
Colorado
-
Connecticut
-
Delaware
-
Florida
-
Georgia
-
Hawaii
-
Idaho
-
Illinois
-
Indiana
-
Iowa
-
Kansas
-
Kentucky
-
Louisiana
-
Maine
-
Maryland
-
Massachusetts
-
Michigan
-
Minnesota
-
Mississippi
-
Missouri
-
Montana
-
Nebraska
-
Nevada
-
New Hampshire
-
New Jersey
-
New Mexico
-
New York
-
North Carolina
-
North Dakota
-
Ohio
-
Oklahoma
-
Oregon
-
Pennsylvania
-
Rhode Island
-
South Carolina
-
South Dakota
-
Tennessee
-
Texas
-
Utah
-
Vermont
-
Virginia
-
Washington
-
West Virginia
-
Wisconsin
-
Wyoming
-
Research Methodology
The U.S. wearable LED light therapy devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. wearable LED light therapy devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
LED Face Masks
This segment includes wearable LED light therapy devices designed to cover and treat multiple areas of the face simultaneously. It includes full-face and partial/half-face formats but excludes dedicated eye-area devices and neck/chest devices.
LED Neck & Chest Masks
This segment includes wearable LED light therapy devices specifically designed to cover and treat the neck, décolletage, and/or upper-chest area. It includes neck-only and combined neck-and-chest wearable masks, as well as products designed for use independently or alongside facial LED devices.
LED Hair Growth Caps/Helmets
This segment includes wearable LED light therapy devices designed to be worn on the head and deliver therapeutic light to the scalp for hair-growth or hair-loss-related applications. It includes LED caps, helmets, domes, and similar head-worn devices, as well as hybrid devices combining LED and laser technologies. Laser-only hair-growth devices and non-wearable light panels are excluded.
LED Eye Masks
This segment includes wearable LED light therapy devices specifically designed to deliver LED treatment to the eyes and surrounding periorbital area, including the under-eye and crow 's-feet regions. These products are generally compact, eye-area-specific devices designed to target concerns such as fine lines, dark circles, puffiness, and other visible signs of aging around the eyes. Full-face LED masks that include the eye area as part of broader facial coverage are excluded.
Estimation Model
The image has been converted into a four-layer table format, preserving the key questions and process steps for each layer.
No.
Layer
Key Question
Process Steps
01
Consumer Need & Target Base Layer
Who has a need or interest in wearable LED light therapy?
Begin with the U.S. consumer population with relevant skincare, beauty, including consumers seeking solutions for fine lines and wrinkles, acne, redness, uneven skin tone, skin rejuvenation, and hair thinning. Consider consumers engaged in skincare and at-home beauty routines, as well as individuals interested in non-invasive and convenient alternatives to professional treatments.
02
Product Accessibility & Distribution Layer
Who has access to wearable LED light therapy products?
Filter the potential consumer base based on the availability of wearable LED devices through online marketplaces and retailers, pharmacies and drugstores, supermarkets and hypermarkets, and warehouse clubs. Consider product availability across LED face masks, neck and chest masks, hair-growth caps/helmets, and eye masks, as well as accessibility across different price tiers.
03
Active Purchasing & Engagement Layer
Who actively purchases and uses wearable LED light therapy devices?
Apply consumer awareness, purchase intent, willingness to pay, product suitability, and treatment engagement rates to identify active buyers. Consider factors such as awareness generated through social media and beauty content, consumer interest in at-home skincare, professional recommendations, product reviews, clinical positioning, FDA clearance, treatment convenience, and perceived efficacy.
04
Monetisation Layer
How much revenue is generated?
Multiply the estimated number of active purchasers by average selling price (ASP), purchase frequency, and replacement/upgrade rates across relevant product categories and price tiers. Consider revenue generated from LED face masks, LED neck and chest masks, LED hair-growth caps/helmets, and LED eye masks, segmented across entry-, mid-range, premium, and professional/clinic-grade products.
Customization Table
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
U.S. Wearable LED Light Therapy Devices Market & Product Trend Analysis
Conducted a detailed assessment of the U.S. wearable LED light therapy devices market across LED face masks, LED neck & chest masks, LED hair-growth caps/helmets, and LED eye masks, evaluating wavelength technologies, product formats, treatment modes, LED configurations, pricing, FDA clearances, clinical positioning, and recent product launches.
Helps stakeholders identify high-potential product categories and technology opportunities, understand the shift toward multi-wavelength and multifunctional wearable devices, and evaluate competitive positioning across skincare, acne, anti-aging, and hair-growth applications.
U.S. Consumer & Distribution Channel Analysis
Evaluated U.S. consumer behavior across DTC websites, online marketplaces, specialty retailers, pharmacies & drugstores, supermarkets & hypermarkets, and warehouse clubs, with assessment of consumer awareness, purchase intent, willingness to pay, treatment preferences, and product accessibility. Recent consumer research indicates that social media is a major source of awareness, while consumers show strong interest in at-home red-light devices and preference for mid-priced products.
Provides insights into channel-specific growth opportunities, consumer price sensitivity, purchase drivers, and the role of digital and physical retail in expanding wearable LED adoption. Supports channel strategy, pricing decisions, retail expansion, and consumer-targeting strategies
Technology, Distribution & Competitive Landscape Assessment
Assessed U.S. developments in red, near-infrared, blue, amber/yellow, and multi-wavelength technologies, alongside cordless designs, flexible materials, shorter treatment times, cooling features, and multifunctional treatment modes. The analysis also evaluated key companies, product launches, FDA-cleared devices, retail expansion, DTC strategies, and emerging consumer trends. Recent launches such as Shark CryoGlow demonstrate the integration of multi-wavelength LED technology, clinical testing, FDA clearance, and additional skincare functionality.
Supports product-development and competitive-positioning strategies by identifying emerging technologies, functional differentiators, pricing opportunities, distribution strategies, and consumer-driven innovation areas within the U.S. wearable LED light therapy devices market.
Frequently Asked Questions About This Report
Red light technology accounted for the largest revenue share of 55.8% in 2025.
Women accounted for the largest revenue share of 70.8% in 2025.
Premium (USD 301 to USD 600) accounted for the largest revenue share of 32.3% in 2025.
LED Face Masks accounted for the largest revenue share of 59.0% in 2025.
Online distribution channel accounted for the largest revenue share of 68.5% in 2025.
At-home skin rejuvenation is expanding demand for wearable LED devices as consumers seek non-invasive treatments that fit their routine skincare.
Key players in the U.S. homeware market, Shark Beauty / SharkNinja; CurrentBody Skin; Omnilux; Therabody; Solawave; Dr. Dennis Gross Skincare; FOREO Limited; Qure Skincare; HigherDOSE; Capillus; iRestore; Déesse PRO; MZ SKIN Limited.
The U.S. wearable LED light therapy devices market size was estimated at USD 657.1 million in 2025 and is expected to reach USD 793.7 million in 2026.
The U.S. wearable LED light therapy devices market is expected to grow at a compound annual growth rate of 10.1% from 2026 to 2033 to reach USD 1,556.9 million by 2033.
About the Author(s)
Beauty & Personal Care Research Team
Consumer Goods · Beauty & Personal CareThis report was authored by the beauty & personal care research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the beauty & personal care segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


