
- Home
- »
- Animal Health
- »
-
Veterinary API Market Size And Share Report, 2026-2033GVR Report cover

Veterinary API Market (2026 - 2033)
Size, Share & Trends Analysis Report By Animal (Production, Companion), By Service (In House, Contract Outsourcing), By Synthesis (Chemical Based API, Biological API, HPAPI), By Therapeutic Category, By Region, And Segment Forecasts
Market Size, 2025
$9.9BMarket Estimate, 2026
$10.6BMarket Forecast, 2033
$17.4BCAGR, 2026–2033
7.3%Veterinary API Market Summary
The global veterinary API market size was valued at USD 9.9 billion in 2025 and is projected to grow from USD 10.6 billion in 2026 to USD 17.4 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. The market in North America dominated with a revenue share of 39.0% in 2025. The market is propelling due to rising investments in outsourcing, R&D of new veterinary products, expanding livestock industry, and expenditure on animal health.
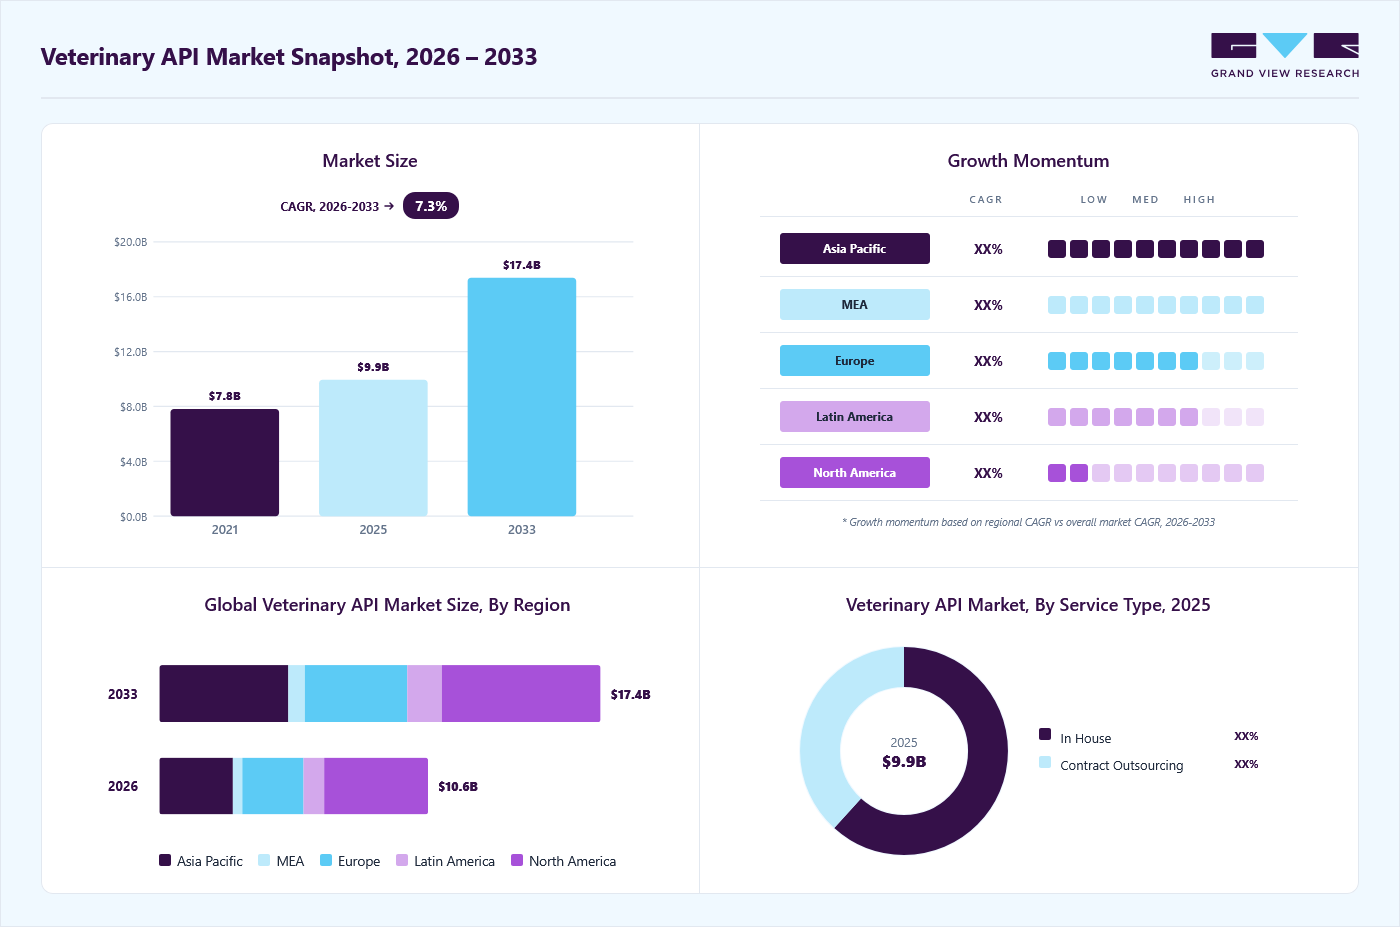 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By synthesis: Chemical-based API segment held the largest market share of 70.6% in 2025.
- By service: In house segment held the largest market share of 61.7% in 2025.
- By animal: Production animals segment held the largest market share of 59.0% in 2025.
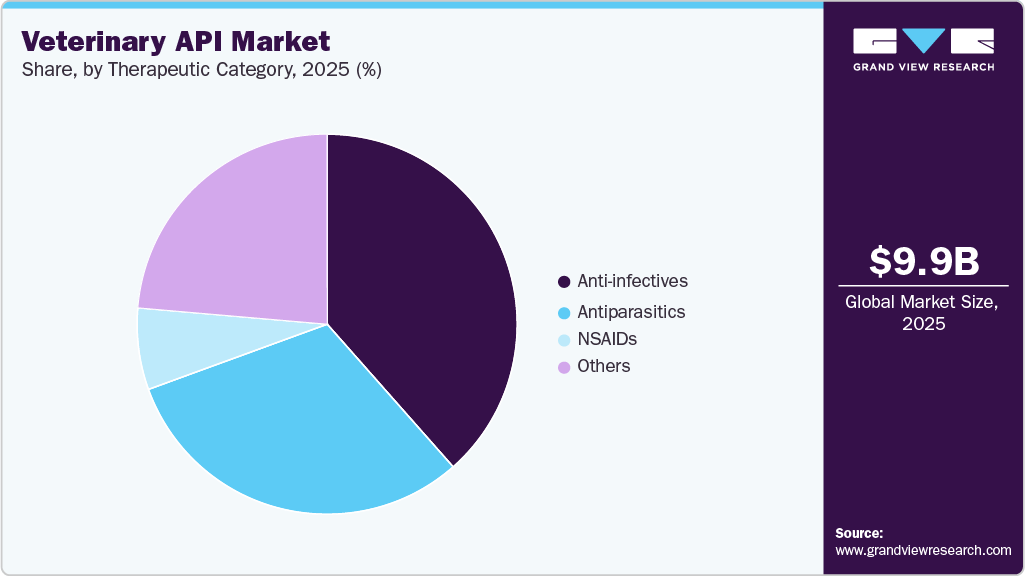
- By therapeutic category: Anti-infectives segment held the largest market share of 38.5% in 2025.
Regional Highlights
- Largest regional market: North America (39.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 9.9 Billion
- Estimated market size in 2026: USD 10.6 Billion
- Projected market size by 2033: USD 17.4 Billion
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Pharmaceutical companies increasingly outsource animal health API production to specialized contract manufacturing organizations (CMOs) to reduce costs, improve efficiency, and access advanced manufacturing capabilities. This outsourcing enables firms to focus on pharmaceutical R&D and marketing. This surges the demand for high-quality APIs with faster production timelines and enhanced scalability. For instance, in November 2025, SeQuent Scientific and Viyash Lifesciences received NCLT approval for their merger, creating a global animal health leader with integrated capabilities, 16 manufacturing facilities, strong R&D, and access to over 150 international markets. This merger is poised to strengthen their global presence, enhance manufacturing innovation, and deliver comprehensive solutions across the animal healthcare industry.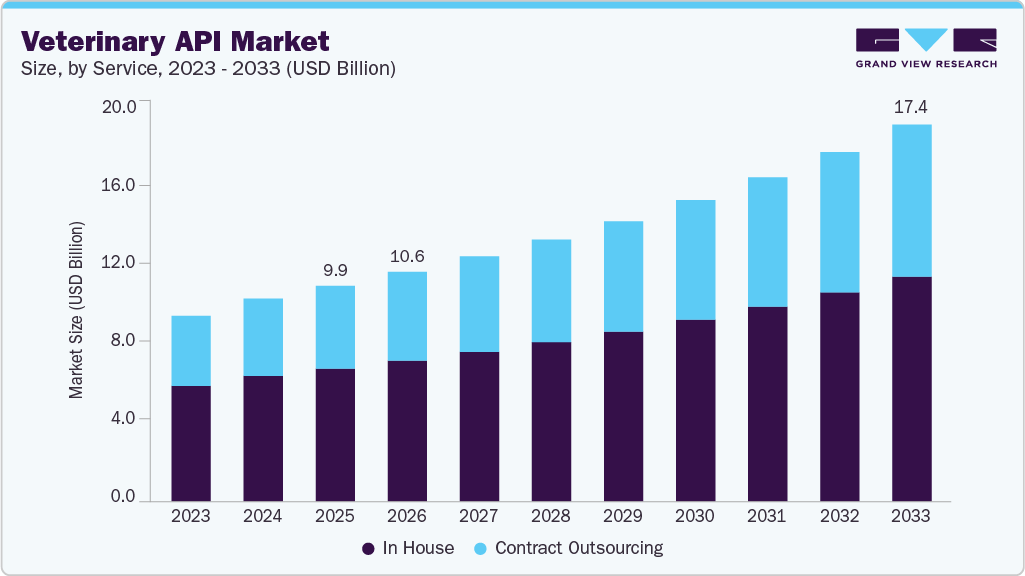 To learn more about this report, Download Free Sample Report
In addition, rising company investments in research and development to create innovative APIs, including novel medications and biologics, are boosting market growth. R&D focuses on efficacy, safety, and regulatory compliance, enabling differentiation in a competitive market. This leads to the development of high-value, specialized APIs, improved animal health outcomes, and enhanced market competitiveness.
The surge in livestock numbers for meat, dairy, and poultry production, combined with increasing pet populations, has propelled the need for animal health medications. Higher population sizes increase disease susceptibility, necessitating vaccines, antimicrobials, and supportive drugs. Manufacturers respond by producing larger volumes of APIs and expanding production facilities. The effect is a robust demand pipeline for APIs, stimulating innovation, technological adoption, and strategic collaborations.
Furthermore, rising veterinary healthcare spending, driven by higher disposable income, growing pet ownership, and the expansion of the livestock industry, increases demand for preventive and therapeutic medications. According to the American Pet Products Association's 2024 report, USD 152 billion was spent on pets for food, medicines, veterinary care products, and other services. This surge in spending has driven higher production and consumption of veterinary APIs, encouraging manufacturers to expand operations, adopt advanced technologies, and develop innovative products to meet growing market demand. Higher expenditure encourages investment in quality control, innovation, and regulatory compliance. Thus, rising animal health expenditure directly fuels the expansion and competitiveness of the veterinary API manufacturing market.
Major Livestock Diseases Incidents in India
Disease
Number of Outbreaks
Number of Deaths
Foot & Mouth Disease (FMD)
38
159
Hemorrhagic Septicemia (HS)
152
54
Black Quarter (BQ)
13
44
Anthrax
17
91
Fascioliasis
1
1
Sheep & Goat Pox
36
234
Blue Tongue
2
38
Contagious Caprine Pleuropneumonia (CCPP)
10
46
Classical Swine Fever
23
239
Salmonellosis
1
985
Ranikhet Disease (NCD)
92
7,688
Chronic Respiratory Disease (CRD)
11
26
Infectious Bursal Disease (IBD)
52
3,817
Rabies
5
12
Babesiosis
17
3
Peste des Petits Ruminants (PPR)
86
695
Brucellosis
8
0
Glanders
17
18
Market Dynamics
Zoonotic diseases are classified by causative agents into bacterial, viral, and parasitic infections and can spread through vectors such as ticks, mosquitoes, and fleas, as well as through direct animal contact. The rising incidence of these diseases, including rabies and Lyme disease, is expected to support demand for improved treatment options in companion animals and increase the need for related drugs and APIs. Global health bodies such as the WHO, in collaboration with organizations including WOAH and FAO, continue to support One Health initiatives focused on zoonotic disease control, food safety, and antimicrobial resistance. The CDC also remains active in zoonotic disease prevention, noting that a large share of emerging infectious diseases in humans are animal-borne.
Lack of awareness regarding animal health and limited availability of treatment options are expected to restrict market growth. In addition, high pet care costs are also expected to restrain market growth. Initial costs of adopting pets, including vaccinations and training, can be high. In addition, without insurance coverage, veterinary care becomes increasingly difficult to afford, especially in developed countries. Moreover, costs for routine checkups and food are significantly high. These factors are expected to restrain market growth. In addition, factors such as the absence of a proper regulatory framework and the unavailability of advanced information systems in emerging economies are creating a demand-supply gap, thereby limiting market growth.
The growing adoption of companion animals and increasing focus on preventive veterinary healthcare are expected to create significant growth opportunities for the veterinary API market. Rising trends in pet humanization, increasing spending on animal wellness, and greater awareness of preventive treatments such as vaccinations, parasiticides, and anti-infectives are supporting demand for veterinary pharmaceuticals and related APIs. In addition, expanding veterinary healthcare infrastructure, increasing pet insurance penetration, and rising investments in advanced animal therapeutics are expected to further strengthen global market growth opportunities.
Illegal veterinary medicines include counterfeit, falsified, unapproved, parallel-imported, and unregistered products. In addition, they include illegal autogenous vaccinations and compounded medications when they are not produced, used, or handled properly as per rules. Illegal drugs are risky, posing safety concerns and secondary effects on business reputation and costs, which may also result in distrust of veterinary medicines.
Market Concentration & Characteristics
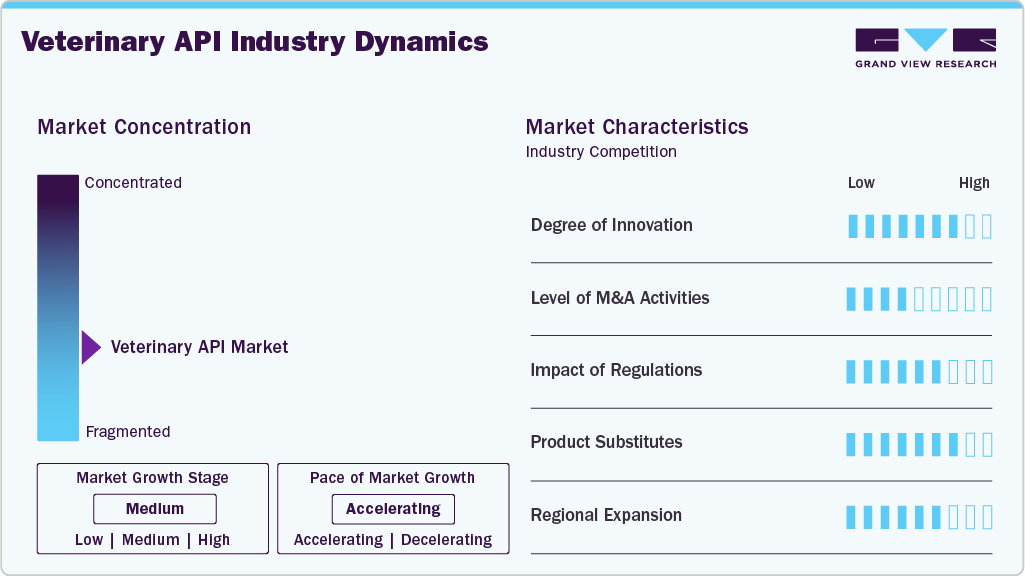
The Veterinary active pharmaceutical ingredients (API) market is moderately concentrated, and the pace is accelerating, due to the presence of diverse participants, including large pharmaceutical companies, contract manufacturing organizations (CMOs), and smaller niche players. This diversity contributes to a range of expertise, specialization, and product offerings. Large multinational corporations with a global reach hold a significant market share due to their extensive resources, diverse portfolios, and the ability to serve multiple markets. These companies influence market trends and competition. However, only some companies focus on API production, excelling in certain therapeutic areas to cater to specific species.
Rapid technological advancements, investments in R&D, and regulatory support and compliance influence the pace of market growth. This acceleration can lead to quicker development and production of APIs. Moreover, the market is witnessing increased innovation in terms of new therapeutic approaches, drug delivery systems, and preventive healthcare solutions. Companies are also expanding their production capacities to meet the rising demand for APIs.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions play a key role in market consolidation, enabling companies to expand product portfolios, access advanced technologies, and enter new geographies. Strategic acquisitions of niche API manufacturers or biotech firms help major players achieve economies of scale, optimize production capabilities, and strengthen their global supply chain presence. For instance, in November 2024, Elanco Animal Health acquired the Speke, UK, contract manufacturing facility from the insolvent TriRx Speke Ltd., securing a critical supply of farm animal products and strengthening its global supply chain.
Strict regulatory standards, including GMP compliance, ISO certifications, and country-specific veterinary drug regulations, significantly influence market operations. Regulatory oversight ensures product safety, quality, and consistency, but increases compliance costs. For instance, in September 2025, China tightened veterinary drug regulations, and in August 2025, the U.S. FDA PreCheck initiative spurred domestic production and compelled manufacturers to adopt advanced technologies and robust quality management systems.
The market faces limited substitution, but alternatives such as over-the-counter animal health products, herbal remedies, or novel digital veterinary solutions (e.g., sensors, smart collars) can affect demand for traditional APIs. Increasing adoption of biologics and integrated veterinary solutions encourages companies to diversify offerings while maintaining core API production
Companies are expanding regionally to capitalize on rising demand in emerging markets such as the Asia Pacific, Latin America, and the Middle East. Strategic investments in manufacturing facilities, partnerships with local firms, and regulatory alignment enable global API manufacturers to meet growing health needs across livestock, companion animals, and poultry while strengthening their international market presence.
Analyst Perspective
The veterinary API market is experiencing steady growth, supported by rising expenditure on animal health, expanding livestock production, increasing pet ownership, and growing demand for preventive and therapeutic medicines. The market is also benefiting from greater adoption of contract manufacturing, as veterinary pharmaceutical companies increasingly outsource API production to access specialized manufacturing capabilities, improve cost efficiency, and streamline supply chains. The antimicrobial stewardship and regulatory scrutiny are influencing API development, particularly for anti-infective products. The FDA's finalized 2026 guidance on antimicrobial resistance risks is expected to encourage greater emphasis on responsible antimicrobial development and alternative animal-health therapies.
Service Insights
On the basis of service, the in-house segment dominated the market with the largest revenue share of 61.7% in 2025. The segment is driven by major animal health companies producing APIs internally to maintain quality control, ensure supply chain reliability, and protect intellectual property. In-house production enables companies to optimize processes, implement advanced technologies, and meet regulatory standards efficiently. In-house manufacturing helps safeguard the unique aspects of pharmaceutical products, such as novel API compositions or innovative production methods, thus contributing to the high share of the segment.
The contract outsourcing segment is projected to grow at the fastest CAGR from 2026 to 2033. Companies from key markets, such as the U.S., outsource API manufacturing and raw material procurement to countries such as China and India. In addition, outsourcing allows firms to leverage specialized Contract Development and Manufacturing Organizations (CDMOs) with advanced technologies, regulatory expertise, and efficient supply chains. This outsourcing strategy enables faster product development, reduced capital investment, and access to global markets, making contract manufacturing meet increasing API demand.
Synthesis Insights
On the basis of synthesis, the chemical-based API segment dominated with a 70.6% share in 2025, driven by its extensive use in livestock and companion animal medications. These APIs offer proven efficacy, stability, and cost-effectiveness for treating diseases, enhancing productivity, and ensuring animal welfare. High demand for antibiotics, antiparasitics, and growth-promoting compounds further fuels growth.
The biological API segment is projected to be the fastest-growing segment over the forecast period of 2026 - 2033. The market is driven by increasing demand for vaccines, immunotherapies, and biologics for livestock and companion animals. Rising awareness of disease prevention, stringent regulatory requirements, and advancements in biotechnology encourage the development of safe, effective biological APIs. Manufacturers are investing in innovative production technologies, cell-based platforms, and scalable facilities, enabling faster development and commercialization.
Animal Insights
On the basis of animal, the production animals segment held the largest revenue share in 2025 with 59.0%, owing to high demand for veterinary drugs to maintain health, productivity, and disease prevention in livestock such as cattle, poultry, and swine. Rising global meat and dairy consumption, coupled with stringent animal health regulations, compels farmers and veterinary service providers to invest in APIs. Vetpharma, for instance, specializes in the development, registration, and marketing of APIs for both production and companion animals. APIs are essential in preventing and controlling various diseases that affect animals.
The companion animals segment is the fastest-growing in the market over the forecast period, with the highest CAGR, driven by increasing pet expenditure & pet humanization, a rising pet population, innovation in companion animal medicine, and the uptake of pet insurance. Demand for preventive care, vaccines, and specialized medications for dogs, cats, and other pets is accelerating. Manufacturers are investing in innovative APIs, advanced formulations, and scalable production to cater to this expanding segment.
Therapeutic Category Insights
On the basis of therapeutic category, anti-infectives constituted the largest revenue segment with 38.5% share in 2025. The segment’s dominance can be attributed to the critical role of anti-infective agents in ensuring the health and well-being of animals. Anti-infectives, including antibiotics, antivirals, and antifungals, are crucial for preventing and treating a variety of diseases in animals. Rising incidence of bacterial and viral diseases, coupled with stringent animal health regulations, fuels consistent use.
 To learn more about this report, Download Free Sample Report
The other segment, comprising oncology, diabetes, and other drugs, is estimated to be the fastest-growing segment in the market, fueled by rising awareness and advanced diagnostic capabilities in veterinary medicine, which have enabled the detection and treatment of conditions such as cancer and diabetes in animals. Increasing awareness among pet owners and veterinarians, along with an aging pet population, has led to a higher prevalence of chronic diseases, driving demand for pharmaceuticals, including APIs. These factors are expected to significantly propel growth in the veterinary API market.
Regional Insights
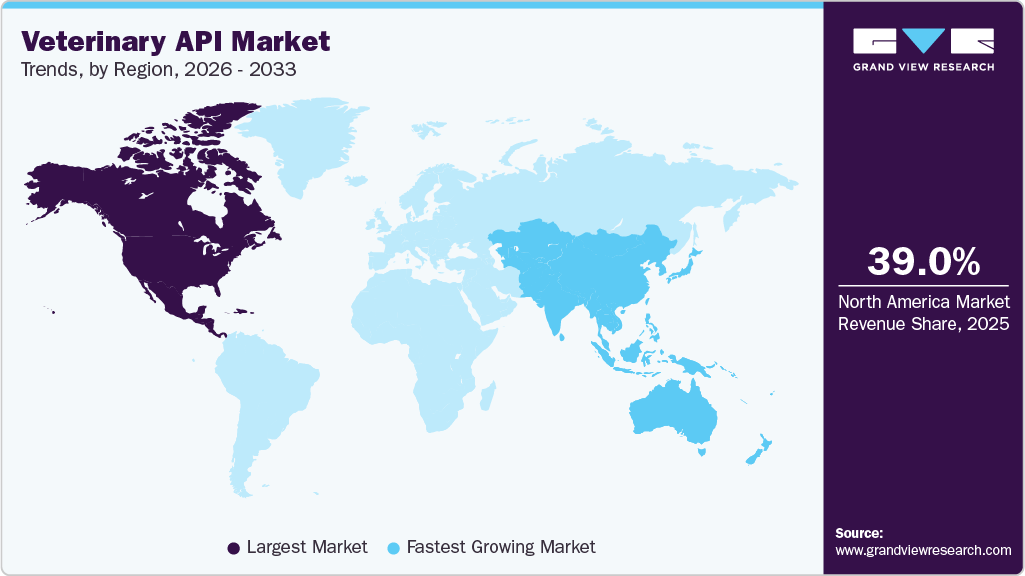
North America dominated the market with the largest revenue share of 39.0% in 2025. The market is driven by the presence of leading animal healthcare companies and a well-developed veterinary healthcare infrastructure. Major pharmaceutical players such as Zoetis and Elanco, headquartered in or with significant operations in the U.S., actively contribute to the development and production of veterinary APIs, further strengthening the region’s market position.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary API Market Trends
The veterinary API Market in the U.S. accounted for the largest share of the North America market, owing to strong R&D investments, rising pet ownership, and advanced biomanufacturing infrastructure. The country is witnessing innovations in precision fermentation and biotechnology that enhance cost efficiency. For instance, in October 2023, SUANFARMA collaborated with Willow Biosciences, using strain optimization to produce high-volume anti-infective APIs more sustainably and economically, thereby strengthening market competitiveness.
The Canada Veterinary API Market is expected to grow at a significant CAGR during the forecast period, propelled by government-backed life sciences initiatives, a robust biotechnology ecosystem, and growing investments in animal health research. Precision fermentation, sustainable API production, and collaborations between biotech firms and veterinary pharma manufacturers are driving competitiveness.
Europe Veterinary API Market Trends
The veterinary API market in Europe is expected to grow due to strong regulatory frameworks, a robust pharmaceutical base, and rising demand for high-quality animal health solutions. In May 2024, companies such as EUROAPI expanded through major CMO contracts, including its EUR 130–150 million veterinary product supply contract covering 2025–2029, reinforcing Europe’s position as a premium API hub and accelerating growth in hormones, prostaglandins, and complex molecules.
The veterinary API market in the UK is expected to grow significantly over the forecast period. The market is characterized by rising investment in innovation, biosynthesis, and sustainability-driven manufacturing, along with the presence of global players and contract manufacturing hubs that enhance competitiveness. Increasing demand for high-quality veterinary APIs further drives domestic and export-oriented production.
The Germany veterinary API Market held a significant share in 2025. The country’s growth is influenced by advanced capabilities in chemical synthesis and robust regulatory standards. The country's focus on animal welfare, rising demand for livestock health solutions, and sustained R&D investments fuel API innovation. Expansion opportunities and EU partnerships further strengthen Germany’s market role.
Asia Pacific Veterinary API Market Trends
Asia Pacific is expected to grow at the fastest CAGR over the forecast period. The region's growth can be attributed to rising animal health awareness, a large livestock base, higher disposable income, and growing veterinary spending. In addition, the region’s expanding number of veterinary API manufacturing facilities and increasing outsourcing by animal health companies are significantly boosting demand for veterinary pharmaceuticals, including APIs.
The veterinary API Market in China held the largest revenue share and is witnessing new growth opportunities due to its large livestock base, expanding pet ownership, and strong demand for feed additives and veterinary drugs. According to a report of September 2025, the global demand for feed additives and veterinary drugs in China is over 30%; thus, China is tightening regulatory controls from 2026, enforcing stricter GMP standards for the manufacturing of pharmaceuticals. This reform would enhance quality competitiveness, favoring well-capitalized domestic and multinational players.
The market for veterinary APIs in India is emerging as a competitive hub for production, supported by a strong pharmaceutical manufacturing ecosystem, company expansion, and cost-effective operations. For instance, in September 2025, Sai Life Sciences expanded with dedicated veterinary API facilities, strengthening India’s capabilities in high-value segments. Government support, increasing livestock populations, and global outsourcing trends further position India as a preferred veterinary API supplier.
Latin America Veterinary API Market Trends
The veterinary API market in Latin America is driven by its expanding livestock sector, growing meat export market, and increasing veterinary healthcare expenditure. Countries like Brazil are boosting local production through government support and foreign partnerships. Rising demand for cost-effective animal health products and increasing pharmaceutical investments are enhancing the region’s competitiveness in global veterinary API supply.
The veterinary API market in Brazil is gaining momentum, driven by growing domestic demand and partnerships with multinational companies. Advances in biomanufacturing, precision fermentation, and contract manufacturing capabilities are enhancing production efficiency and quality.
Middle East & Africa Veterinary API Market Trends
The veterinary API market in MEA is expanding due to investments in modern manufacturing facilities, technology adoption, and regulatory improvements, which are enhancing local production capabilities. Strategic partnerships with global pharmaceutical companies and government initiatives to improve animal health further drive competitiveness in the region.
The South African veterinary API market held the largest revenue share and is expanding, fueled by technological advancements in API synthesis, improved regulatory frameworks, and the adoption of contract manufacturing, which are enhancing production efficiency and quality. Some of the key players, such as Aspen Pharmacare and Cape Animal Health, are investing in advanced manufacturing technologies and precision fermentation.
The UAE veterinary API market is experiencing significant growth due to rising veterinary healthcare spending and supportive government policies. Major companies, such as Zoetis and Elanco, are utilizing advanced manufacturing technologies and GMP-compliant facilities. Investments in contract manufacturing and regulatory alignment with international standards are driving efficiency, quality, and competitiveness in the UAE’s veterinary API sector.
Key Veterinary API Company Insights
The veterinary API market is dominated by key players such as Zoetis, Elanco, Merck Animal Health, SUANFARMA, EUROAPI, and Sai Life Sciences. These companies hold significant market share through strong R&D capabilities, advanced manufacturing technologies, global distribution networks, contract manufacturing services, and strategic collaborations, driving innovation and industry growth. Large companies often have diverse portfolios that include APIs for both human and veterinary use. Their global reach allows them to serve a wide range of markets. Alongside major pharmaceutical companies, specialized contract manufacturing organizations (CMOs) focus on the human and animal health sectors or exclusively on veterinary API production.
These organizations are engaged in deploying various strategic initiatives to increase their market share. For instance, in March 2025, SeQuent Scientific and Viyash Lifesciences approved a strategic merger, creating a global animal health leader with integrated capabilities, 16 manufacturing facilities, strong R&D, and access to over 150 international markets.
Key Veterinary API Companies:
The following key companies have been profiled for this study on the veterinary API market.
-
Zoetis
-
Alivira Animal Health Ltd.
-
Ofichem Group
-
Chempro Pharma Pvt. Ltd.
-
Siflon Drugs
-
Qilu Animal Health Products Co., Ltd.
-
Vetpharma
-
SUANFARMA
-
MENADIONA
-
Excel Industries Ltd.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Player: Alivira Animal Health
- The established companies are increasingly focusing on research and development activities to develop innovative and advanced veterinary products.
- Market participants are entering into strategic partnerships with key stakeholders to strengthen their technological and operational capabilities.
- These companies possess expertise across a wide range of areas and segments, including both human and animal health.
- Market participants benefit from strong distribution networks that support broad market reach and efficient product delivery.
- The mature players operating across multiple geographies are subject to a stringent, complex regulatory landscape that may affect operational efficiency and compliance.
- Macroeconomic headwinds, including inflationary pressures and economic uncertainty, may adversely affect the financial performance of the market.
Emerging Player: SUANFARMA
- The emerging companies are increasingly focusing on key geographies to strengthen their market presence and capture high-growth opportunities.
- Market participants are prioritizing key product and service lines to enhance competitiveness and improve operational focus.
- Market participants are focused on providing innovative solutions to address evolving customer and industry requirements.
- Companies are implementing targeted strategies supported by portfolios that are focused on specific segments and product categories.
- Companies face intense competition from well-established and mature market players with strong market presence and brand recognition.
- Limited financial, operational, and technological resources may restrict the growth and expansion capabilities of smaller market participants.
Recent Developments
-
In September 2025, Sai Life Sciences opened Unit VI in Bidar, a dedicated veterinary API facility that enhances production capacity, regulatory compliance, and sustainability while meeting growing global demand for high-quality animal health pharmaceuticals.
-
In August 2025, the FDA announced the PreCheck program to enhance U.S. drug manufacturing by increasing regulatory predictability, supporting domestic API production, and reducing reliance on foreign pharmaceutical suppliers, thereby strengthening the national supply chain.
-
In January 2024, Huateng Pharma launched veterinary solutions, Fluralaner and Sarolaner, providing effective anti-parasitic treatments for pets. The company offered lab-to-commercial scale production, showcasing advanced technologies and a commitment to animal health innovation.
Veterinary API Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.9 billion
Estimated market size in 2026
USD 10.6 billion
Projected market size by 2033
USD 17.4 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, synthesis, animal, therapeutic category, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Qatar; Oman
Key companies profiled
Zoetis, Alivira Animal Health Ltd., Ofichem Group, Chempro Pharma Pvt. Ltd., Siflon Drugs, Qilu Animal Health Products Co., Ltd., Vetpharma, SUANFARMA, MENADIONA, Excel Industries Ltd.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary API Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary API market report based on service, synthesis, animal, therapeutic category, and region:
-
Veterinary API Animal Outlook (Revenue, USD Million, 2021 - 2033)
-
Companion Animals
-
Production Animals
-
-
Veterinary API Service Outlook (Revenue, USD Million, 2021 - 2033)
-
In House
-
Contract Outsourcing
-
Contract Development
-
Preclinical Development
-
Clinical Development
-
-
Contract Manufacturing
-
-
-
Veterinary API Synthesis Outlook (Revenue, USD Million, 2021 - 2033)
-
Chemical Based API
-
Biological API
-
HPAPI
-
-
Veterinary API Therapeutic Category Outlook (Revenue, USD Million, 2021 - 2033)
-
Antiparasitics
-
Anti-infectives
-
NSAIDs
-
Others
-
-
Veterinary API Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
The veterinary API market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary API segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Definition
Animal
Classification of veterinary API demand based on animal category served.
Companion Animals
Pets such as dogs, cats, horses, and other household animals receiving preventive and therapeutic care.
Production Animals
Livestock raised for food and agricultural output, including cattle, poultry, swine, sheep, and goats.
Service
Manufacturing model utilized for veterinary API production.
In-House
API manufacturing conducted internally by pharmaceutical or animal health companies.
Contract Outsourcing
API development or manufacturing is outsourced to third-party CDMOs/CMOs.
Contract Development
Outsourced process development, formulation support, and scale-up activities.
Preclinical Development
Early-stage development involving analytical methods, process optimization, and safety evaluation.
Clinical Development
Support services related to clinical-scale manufacturing and validation.
Contract Manufacturing
Commercial-scale API manufacturing is performed by third-party facilities.
Synthesis
Production technology for manufacturing veterinary APIs.
Chemical-Based API
APIs produced through conventional chemical synthesis routes.
Biological API
APIs derived from biological processes, including fermentation, cell culture, and biotechnology platforms.
HPAPI
Highly Potent Active Pharmaceutical Ingredients requiring specialized containment and handling.
Therapeutic Category
Disease area or treatment application served by the API.
Antiparasitics
APIs used to prevent or treat internal and external parasitic infections.
Anti-Infectives
Antibiotics, antivirals, antifungals, and related therapies used against infectious diseases.
NSAIDs
Non-steroidal anti-inflammatory drugs are used to manage pain and inflammation.
Others
Includes oncology, diabetes, endocrine, metabolic, and specialty veterinary therapeutics.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Product-to-API Mapping (Finished Formulation Intelligence)
Mapping of key finished veterinary vitamin/supplement products to their manufacturers or CDMOs, dosage forms (oral liquids, injectables, premixes, boluses, chewables), and associated vitamin APIs - including directional estimates where precise data is unavailable. Covers species-specific formulations across companion animals, poultry, swine, and ruminants.
Enables clients to identify which APIs underpin high-volume finished products, understand formulation trends by dosage form, evaluate CDMO partnerships, and uncover white-space opportunities in underserved product categories or species segments.
API Buyer Prioritization & Demand Concentration Analysis
Ranking and prioritization of top API buyers (veterinary pharmaceutical manufacturers, CDMOs, and compounders) based on estimated API procurement volumes, demand concentration by molecule or product category, and inferred purchasing patterns derived from production capacity, product portfolios, and market share data.
Helps clients identify the most commercially significant buyers for BD targeting, assess customer concentration risk, prioritize sales outreach, and tailor supply or pricing strategies to high-volume demand segments.
Regional Market Sizing & Regulatory Landscape (Europe Focus)
Dedicated market sizing and analysis of the veterinary API market across European geographies, covering market value and volume by API category, key demand drivers, regulatory environment (EMA, national VMAs, VICH guidelines), pharmacovigilance requirements, sourcing and import dynamics, and end-use breakdown by animal species and product type.
Supports market entry and expansion planning into Europe, enables compliance-aware product strategy, helps clients benchmark regional demand against global volumes, and identifies high-growth European markets for API supply or finished product positioning.
Frequently Asked Questions About This Report
The global veterinary API market size was valued at USD 9.9 billion in 2025 and is expected to reach USD 10.6 billion in 2026.
Some key players operating in the veterinary API market include Zoetis; Alivira Animal Health Limited; Ofichem Group; Chempro Pharma Private Limited; Siflon Drugs; Qilu Animal Health Products Co., Ltd.; Vetpharma; SUANFARMA; MENADIONA; Excel Industries Ltd.
Some of the key factors accounting for market growth include growing investments in outsourcing, facility expansion, R&D of new veterinary products and expenditure on animal health.
The global veterinary API market is expected to grow at a compound annual growth rate (CAGR) of 7.3% from 2026 to 2033 to reach USD 17.4 billion by 2033.
By region, North America dominated the market with the largest revenue share of 39.0% in 2025.
On the basis of service, in house segment dominated the market with largest revenue share of 61.7% in 2025.
On the basis of synthesis, chemical-based API segment dominated with 70.6% share in 2025, driven by its extensive use in livestock and companion animal medications.
On the basis of animal, production animals segment held the largest revenue share in 2025 with 59.0%, owing to high demand for veterinary drugs to maintain health, productivity, and disease prevention in livestock such as cattle, poultry, and swine.
On the basis of therapeutic category, anti-infectives constituted the largest revenue segment with 38.5% share in 2025.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


