
- Home
- »
- Animal Health
- »
-
Veterinary Hematology Analyzers Market Size Report, 2025-2030GVR Report cover

Veterinary Hematology Analyzers Market (2025 - 2030) Size, Share & Trends Analysis Report By Product (Table-top analyzers, Point-of-care analyzers), By Analysis Parameters, By Species, By End-use, By Region, And Segment Forecasts
Market Size, 2024
$1.2BMarket Estimate, 2026
$1.4BMarket Forecast, 2030
$2.1BCAGR, 2025–2030
10.0%Veterinary Hematology Analyzers Market Summary
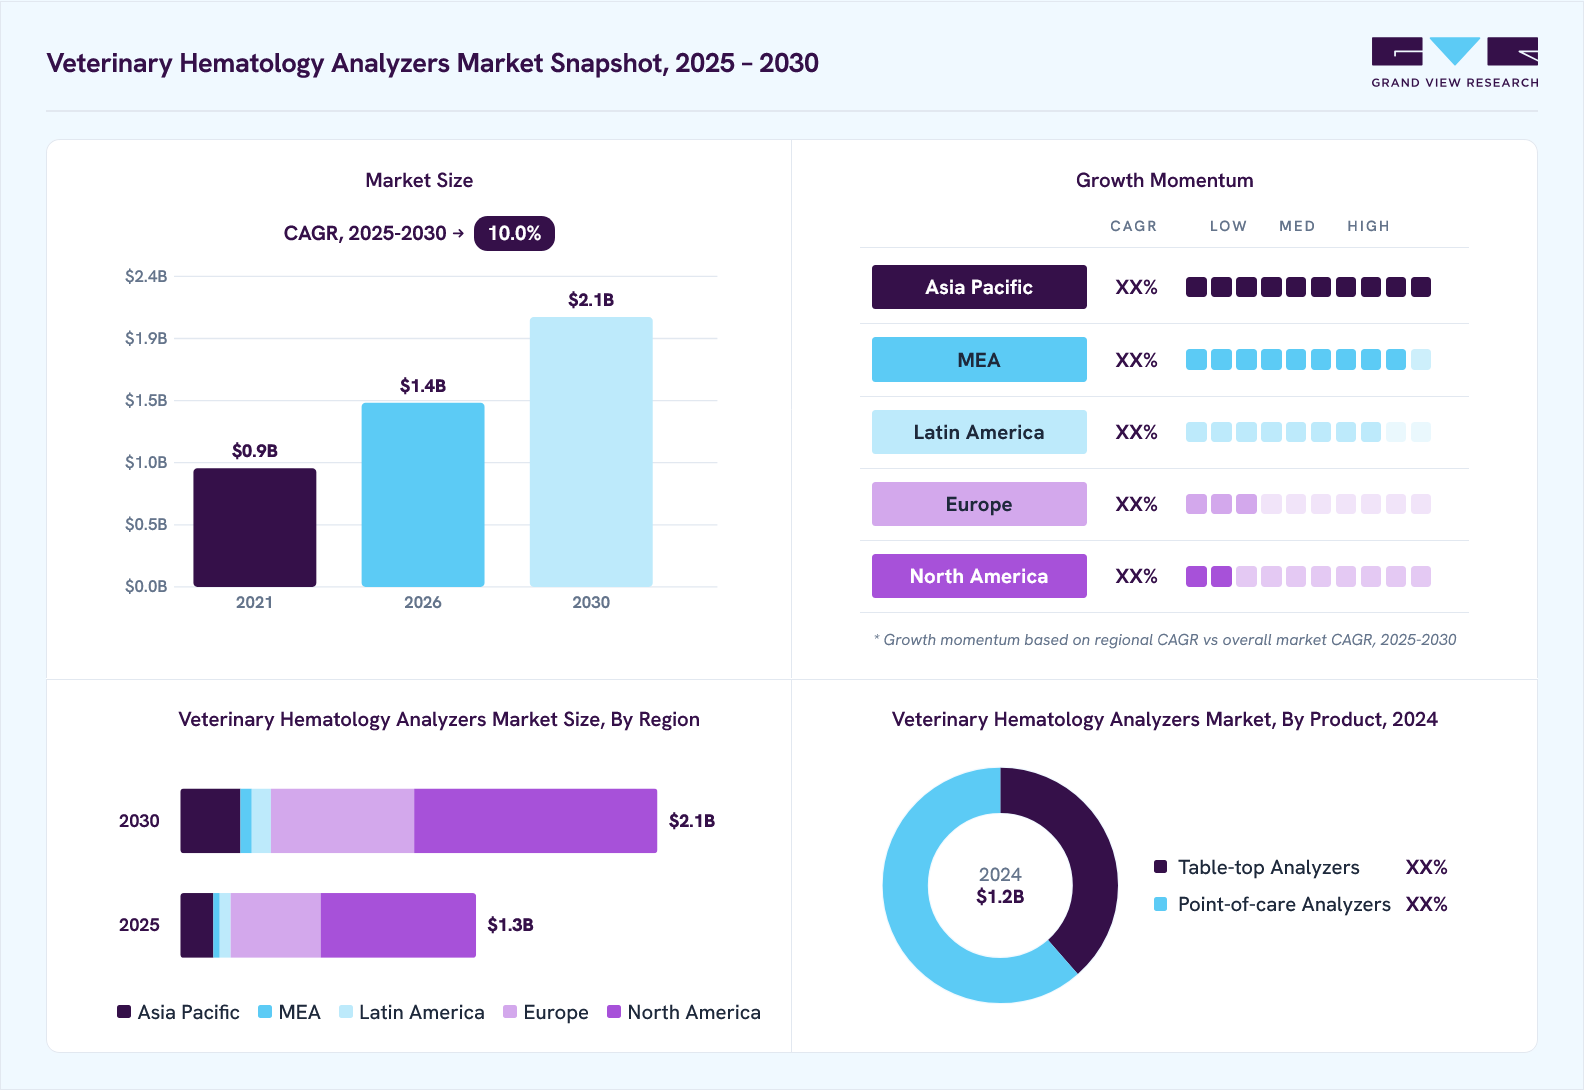
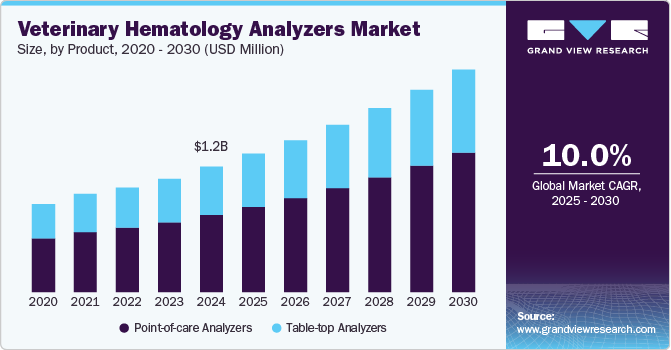
The global veterinary hematology analyzers market size was valued at USD 1.2 billion in 2024 and is projected to grow from USD 1.4 billion in 2026 to USD 2.1 billion by 2030, at a CAGR of 10.0% from 2025 to 2030. North America dominated the market, accounting for a revenue share of 52.9% in 2024. The rising prevalence of zoonotic diseases, growing pet ownership, and increased spending on animal healthcare are major drivers of the veterinary hematology analyzer industry. In addition, technological advancements in AI-powered diagnostics, demand for point-of-care testing (POCT), and the need for accurate and rapid blood analysis are boosting market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
For instance, in December 2025, Zoetis Inc. launched Vetscan OptiCell, a next-generation point-of-care hematology analyzer, at VMX 2025 in Orlando. The device uses viscoelastic focusing (VEF) and AI-powered algorithms to deliver fast, accurate, complete blood count (CBC) analysis. This launch will likely intensify competition and drive innovation in the veterinary diagnostic industry, encouraging a shift toward faster, low-maintenance hematology solutions.
 To learn more about this report, Download Free Sample Report
The rising pet population and growing veterinary expenditure fuel the veterinary hematology analyzer industry. According to Pet Keen (2024), the UK pet population in 2021 comprised 12.5 million dogs and 12.2 million cats, underscoring the growing number of companion animals. Similarly, in the U.S., a 2023-2024 study by the American Pet Products Association (APPA) revealed that 66% of households (around 86.9 million homes) own at least one pet. This surge in pet ownership, driven in part by the COVID-19 pandemic, has significantly boosted the demand for veterinary services, including diagnostic testing.
With pet owners becoming more willing to invest in their pets' healthcare, veterinary expenditure is rising steadily. The growing awareness of preventive care and the increasing availability of pet insurance drive higher spending on diagnostic testing. This trend fuels the adoption of advanced hematology analyzers in veterinary practices, as they offer faster, more accurate diagnostic results, enhancing patient outcomes.
Veterinary hematology analyzers are diagnostic instruments used to perform complete blood counts (CBCs) and analyze various blood parameters in animals. They provide accurate, rapid results for detecting conditions such as anemia, infections, inflammation, and hematologic disorders, aiding in effective disease diagnosis and treatment in veterinary practices.
Key Applications of Veterinary Hematology Analyzers
-
Disease Diagnosis: Hematology analyzers play a critical role in diagnosing infections, blood disorders, and chronic diseases by measuring white blood cell (WBC), red blood cell (RBC), and platelet counts. For example, identifying anemia in dogs or leukemia in cats.
-
Treatment Monitoring: Veterinarians use hematology analyzers to monitor the effectiveness of treatments such as antibiotics, chemotherapy, or immunosuppressants. They track WBC counts in pets receiving chemotherapy, ensuring the treatment does not excessively suppress the immune system.
-
Pre-Anesthetic and Post-Treatment Testing: Analyzers are used for pre-anesthetic bloodwork to detect abnormalities that may increase surgical risks and for post-treatment recovery monitoring. They are also used to check platelet counts before surgery to minimize bleeding risks.
-
Livestock and Herd Health Management: In large-animal practice, hematology analyzers help monitor herd health by detecting bloodborne diseases and assessing key health parameters. They are widely used to detect anemia or parasitic infections in cattle and sheep.
Evolution of Veterinary Hematology Analyzers And Testing
Year
Technology Used
Advancement
Examples/Models
Impact on Testing
Pre-2000s
Manual Microscopy
Blood smears and manual counting
Traditional hemocytometers
Time-consuming, prone to human error
2000s
3-Part Differential Analyzers
Automated counting of WBC, RBC, PLT
IDEXX VetAutoread Hematology Analyzer
Faster and more accurate than manual tests
2010-2015
5-Part Differential Analyzers
More precise WBC differentiation
Abaxis Vetscan HM5, IDEXX ProCyte Dx
Enhanced accuracy in detecting anomalies
2015-2020
AI-Powered Image Recognition
Morphological analysis with AI
Zoetis Vetscan Imagyst, ScopioVet
Faster, more accurate identification
2020-Present
Cartridge-Based POCT Analyzers
Compact, real-time diagnostics
Zoetis Vetscan OptiCell, Heska Element HT5
Real-time CBC results, improved efficiency
Future Trends
AI + Cloud Integration
Remote access & predictive insights
Virtual labs with cloud storage
Continuous monitoring, predictive diagnosis
Market Concentration & Characteristics
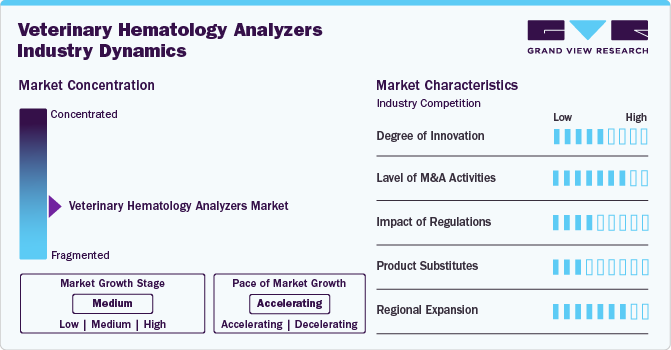
Higher degrees of innovation in veterinary hematology analyzers, such as AI-powered cell classification, viscoelastic focusing (VEF), and automated blood smear evaluations, significantly enhance diagnostic accuracy, speed, and efficiency. For example, Zoetis’ Vetscan OptiCell uses AI and VEF to provide fast, accurate CBC results with minimal maintenance, reducing labor costs and improving patient care. Such innovations drive market growth by boosting clinic efficiency and promoting preventive diagnostics.
The veterinary hematology analyzer industry is witnessing increased M&A activity as companies seek to expand diagnostic capabilities and gain market share. For example, Zoetis’ acquisition of Scandinavian Micro Biodevices strengthened its point-of-care diagnostics portfolio. In contrast, IDEXX Laboratories' acquisition of ezyVet enhanced its data management and diagnostic integration, reflecting a trend toward tech-driven consolidation.
 To learn more about this report, Download Free Sample Report
Regulatory standards impact the development, approval, and adoption of veterinary hematology analyzers by ensuring accuracy, safety, and compliance. For example, FDA and CE marking requirements mandate performance validation for devices such as IDEXX ProCyte Dx and Zoetis Vetscan OptiCell, thereby influencing market entry and adoption. Stricter regulations increase R&D costs and drive higher quality standards, boosting clinician confidence and market growth.
Product substitutes for veterinary hematology analyzers include reference laboratory services and multi-diagnostic platforms. For example, IDEXX Reference Labs offers comprehensive off-site CBC testing, which, although slower, may appeal to smaller clinics seeking cost-effective solutions. However, the convenience and speed of in-house analyzers, like Zoetis’ Vetscan OptiCell, make them a preferred choice for real-time diagnostics.
The veterinary hematology analyzer industry is experiencing rapid regional expansion, driven by growing pet ownership and demand for preventive care. For example, Zoetis’ Vetscan OptiCell is launching in the U.S., Canada, Australia, New Zealand, the UK, and Ireland in 2025, with further rollouts planned globally through 2026. This expansion is boosting market growth by increasing access to advanced diagnostic tools.
Product Insights
The market is segmented into table-top and Point-of-care analyzers. The point-of-care analyzers segment led the market with the largest revenue share of 61.45% in 2024 and is expected to grow at the fastest CAGR over the forecast period. This is attributed to their rapid on-site diagnostics, which enable immediate treatment decisions and improve patient outcomes. Their compact, portable design makes them ideal for small clinics, mobile vets, and field use. In addition, minimal maintenance, faster turnaround times (TAT), and AI-powered accuracy drive their growing adoption over traditional table-top analyzers.
Furthermore, Point-of-care analyzers are divided into Cartridge-based analyzers and Direct sample-based analyzers. Cartridge-based analyzers are expected to hold a higher market share due to their ease of use, minimal maintenance, and AI-driven automation. However, tabletop analyzers will continue to decline in use as clinics prioritize faster, space-efficient POC solutions.
Analysis Parameters Insights
Based on the analysis parameters, the 5-part WBC differential segment accounted for the largest market revenue share in 2024, due to its greater accuracy in differentiating white blood cell types, making it the preferred choice for detailed diagnostics. The increasing adoption of AI-powered POC analyzers (such as Zoetis Vetscan OptiCell) is further driving the dominance of 5-part WBC analyzers.
The other parameters segment (including reticulocyte counts, nucleated RBCs, and immature granulocyte detection) is expected to grow at the fastest CAGR of 10.3% during the forecast period, driven by the demand for more advanced diagnostic capabilities. The increasing use of AI-powered hematology analyzers is fueling the growth of this segment, especially in oncology, inflammatory diseases, and anemia diagnosis.
Species Insights
Based on species, the canine segment led the market with the largest revenue share of 39.23% in 2024, due to the large population of companion dogs, frequent veterinary visits for routine check-ups, and the rising prevalence of canine diseases such as anemia, leukemia, and tick-borne infections. Increasing pet insurance coverage and growing expenditure on canine healthcare further boosted the segment's dominance.
The feline segment is projected to grow at the fastest CAGR of 10.5% during the forecast period, driven by the rising adoption of cats as pets, increasing awareness about feline-specific diseases (e.g., feline leukemia virus, chronic kidney disease), and the growing demand for preventive diagnostic testing. The expanding range of feline-specific diagnostic panels also fuels the segment's growth.
End-use Insights
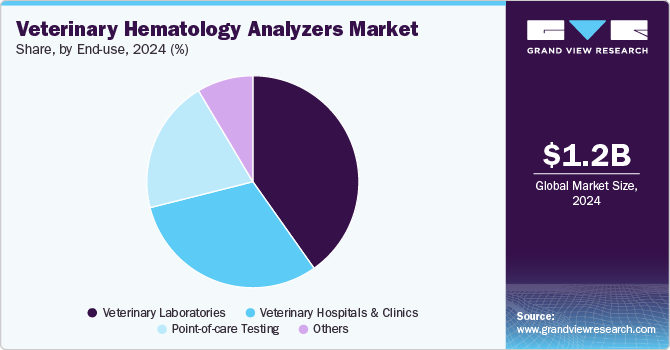
Based on end use, the veterinary laboratories segment led the market with the largest revenue share of 40.20% in 2024, primarily due to its high testing volume capacity, access to advanced diagnostic technologies, and expertise in complex analyses. These laboratories handle a wide range of hematology tests, including complete blood counts (CBCs), differential WBC counts, and morphological assessments, making them the preferred choice for accurate and comprehensive diagnostics. Their ability to process large sample batches efficiently makes them cost-effective for veterinary practices. In addition, veterinary labs are equipped with fully automated, high-throughput analyzers, ensuring greater accuracy and consistency, further strengthening their dominance.
 To learn more about this report, Download Free Sample Report
The Point-of-Care Testing (POCT) segment is expected to witness at the fastest CAGR during the forecast period, due to the rising adoption of compact, cartridge-based analyzers that offer rapid, on-site results. Veterinarians increasingly prefer POCT devices to enable faster clinical decision-making and timely treatment interventions. The convenience, portability, and ease of use of POCT analyzers make them ideal for veterinary clinics, hospitals, and mobile practices, driving their expanding adoption. In addition, advancements in AI-powered analyzers have improved diagnostic accuracy, making POCT solutions more reliable and appealing. The growing demand for immediate diagnostics and improved patient outcomes is expected to fuel the continuous expansion of this segment.
Regional Insights
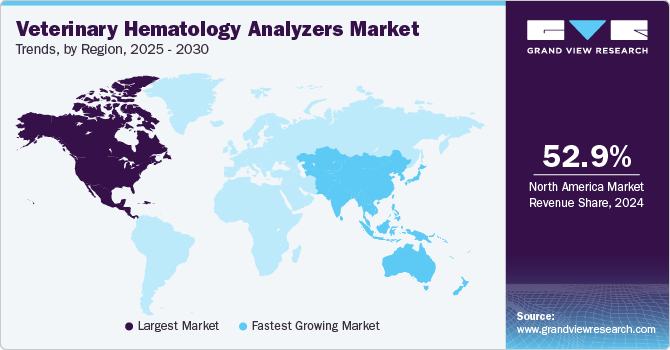
North America dominated the veterinary hematology analyzers market with the largest revenue share of 52.9% in 2024, driven by the rising prevalence of animal diseases and growing pet ownership. For example, canine Lyme disease and heartworm infections are increasingly common in the U.S., boosting the demand for accurate diagnostic tools. In addition, the rising expenditure on pet healthcare, according to the American Pet Products Association (APPA) spending reached $147 billion in 2024, is fueling the adoption of advanced point-of-care hematology analyzers in veterinary clinics and hospitals.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Hematology Analyzers Market Trends
The veterinary hematology analyzers market in the U.S. is growing rapidly due to rising pet ownership and increasing demand for point-of-care diagnostics. According to APPA, in 2024, around 66% of U.S. households owned a pet, boosting the need for advanced diagnostic tools. Additionally, the growing prevalence of zoonotic diseases like Leptospirosis and Ehrlichiosis is accelerating the adoption of rapid, in-clinic hematology analyzers for faster and more accurate diagnostics.
Europe Veterinary Hematology Analyzers Market Trends
The veterinary hematology analyzers market in Europe is driven by rising veterinary healthcare expenditure and the increasing prevalence of infectious diseases in animals. According to the European Food Safety Authority (EFSA), cases of bovine tuberculosis and bluetongue have surged, prompting increased demand for hematology testing. In addition, the adoption of advanced AI-powered analyzers by veterinary clinics is enhancing diagnostic accuracy and efficiency, fueling market growth.
The UK veterinary hematology analyzers market is driven by rising animal disease prevalence and growing veterinary care standards. According to the UK Animal and Plant Health Agency (APHA), canine parvovirus and feline leukemia cases have increased, boosting the need for hematology diagnostics. Furthermore, the expansion of veterinary referral centers offering advanced hematology testing is propelling market growth.
Asia Pacific Veterinary Hematology Analyzers Market Trends
The veterinary hematology analyzers market in the Asia Pacific is projected to grow at the fastest CAGR of 12.7% over the forecast period, due to increased livestock farming and rising pet adoption rates. According to the Food and Agriculture Organization (FAO), the region accounts for over 40% of global livestock production, driving demand for hematology testing in farm animals. In addition, the growing veterinary infrastructure in countries such as China, India, and Japan is boosting the adoption of POC analyzers for faster diagnostics.
The India veterinary hematology analyzers market is anticipated to witness at a notable CAGR during the forecast period, owing to expanding dairy and poultry industries, which contribute over 4% to the national GDP, as reported by the Economic Survey of India, 2023. The rise in companion animal ownership, with an estimated 31 million pet dogs in 2023, is also fueling demand for advanced diagnostics. In addition, government initiatives such as the National Animal Disease Control Program (NADCP) are driving investment in veterinary healthcare, boosting market expansion.
Latin America Veterinary Hematology Analyzers Market Trends
The veterinary hematology analyzers market in Latin America is driven by the rising prevalence of zoonotic diseases like bovine tuberculosis and brucellosis, which affect over 20% of cattle herds in some regions (PAHO, 2023). Increasing livestock farming and meat production, particularly in Brazil and Argentina, boosts demand for regular animal health diagnostics. Moreover, government initiatives such as Mexico's National Program for Animal Health and the expansion of veterinary infrastructure present significant growth opportunities. The growing trend of pet adoption in countries like Chile and Colombia further fuels the market, increasing the need for point-of-care analyzers.
The Brazil veterinary hematology analyzers market is experiencing steady growth, driven by the expanding livestock sector and rising pet ownership. According to USDA data published in 2024, Brazil has over 218 million cattle, the largest herd in the world, creating a high demand for routine hematology testing to monitor animal health. In addition, pet ownership has surged, with over 60 million dogs and 27 million cats in 2023 (Instituto Pet Brasil), boosting the need for companion animal diagnostics. The growing adoption of AI-powered analyzers in veterinary clinics is further enhancing diagnostic efficiency and accuracy.
Middle East & Africa Veterinary Hematology Analyzers Market Trends
The veterinary hematology analyzers market in the Middle East and Africa (MEA) is growing due to the expanding livestock sector and rising awareness of animal healthcare. Countries like Saudi Arabia and the UAE are investing in advanced veterinary diagnostics to support their livestock and poultry industries, which are vital for food security. According to the FAO, the region's livestock population surpassed 300 million in 2024, driving the demand for accurate hematology testing. In addition, the increasing pet adoption in urban areas is boosting the need for companion animal diagnostics.
The Saudi Arabia veterinary hematology analyzers market is driven by the growing government's focus on livestock health and growing pet ownership in urban areas. The Saudi Ministry of Environment, Water, and Agriculture (MEWA) launched multiple initiatives to enhance animal disease surveillance, supporting the demand for advanced diagnostic tools. In 2024, the country's livestock population exceeded 25 million, driving the need for accurate hematology testing. In addition, the rise of premium veterinary clinics in cities like Riyadh and Jeddah is fueling the adoption of point-of-care diagnostics.
Key Veterinary Hematology Analyzers Company Insights
The veterinary hematology analyzers industry is highly competitive, with key players focusing on product innovation, strategic collaborations, and regional expansions. Leading companies such as IDEXX Laboratories, Inc., Zoetis Inc., and Heska Corporation dominate the market. Emerging players like Mindray Medical International Limited and Scil Animal Care Company GmbH are expanding their footprint through affordable, compact analyzers and partnerships with veterinary clinics. Continuous R&D investments and the integration of AI and cloud-based platforms are shaping the competitive landscape, offering real-time data insights and improving diagnostic efficiency.
Key Veterinary Hematology Analyzers Companies:
The following are the leading companies in the veterinary hematology analyzers market. These companies collectively hold the largest market share and dictate industry trends.
- IDEXX Laboratories, Inc.
- Zoetis
- Mars Inc. (Heska Corporation)
- HORIBA Medical
- Shenzhen Mindray Animal Medical Technology Co., LTD.
- Chengdu Seamaty Technology Co., Ltd.
- Boule Medical AB
- Sysmex Corporation
- HemoCue AB
- Scitek Global Co., Ltd.
Prism AI by Grand View Research Free to tryAsk a question about the veterinary hematology analyzers marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Recent Developments
-
In September 2024, Zoetis Inc. introduced Vetscan OptiCell, a new cartridge-based hematology analyzer that employs AI-powered technology to deliver precise Complete Blood Count (CBC) analysis at the point of care, offering lab-quality results with time, cost, and space efficiencies for veterinary clinics.
-
In August 2023, Chengdu Seamaty Technology Co., Ltd. unveiled four new veterinary analyzers, including the VBC30 Vet 3-part and VBC50 5-part hematology analyzers, designed for rapid and precise CBC assessments.
Veterinary Hematology Analyzers Market Report Scope
Report Attribute
Details
Market size in 2024
USD 1.2 billion
Estimated market size in 2026
USD 1.4 billion
Projected market size by 2030
USD 2.1 billion
Growth rate
CAGR of 10.0% from 2025 to 2030
Base year for estimation
2024
Historical data
2018 - 2023
Forecast period
2025 - 2030
Quantitative units
Revenue in USD million/billion, and CAGR from 2025 to 2030
Report Coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
Product, species, analysis parameters, end-use, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
IDEXX Laboratories, Inc.; Zoetis; Mars Inc. (Heska Corporation); HORIBA Medical; Shenzhen Mindray Animal Medical Technology Co., LTD.; Chengdu Seamaty Technology Co., Ltd.; Boule Medical AB; Sysmex Corporation; HemoCue AB; Scitek Global Co., Ltd.
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Hematology Analyzers Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global veterinary hematology analyzers market report based on product, species, analysis parameters, end-use, and region.
-
Product Outlook (Revenue, USD Million, 2018 - 2030)
-
Table-top analyzers
-
Fully automatic analyzers
-
Semi-automatic analyzers
-
-
Point-of-care analyzers
-
Cartridge based analyzers
-
Direct sample-based analyzers
-
-
-
Species Outlook (Revenue, USD Million, 2018 - 2030)
-
Cattle
-
Canine
-
Feline
-
Caprine
-
Equine
-
Ovine
-
Porcine
-
Avian
-
Others
-
-
Analysis Parameters Outlook (Revenue, USD Million, 2018 - 2030)
-
3-part WBC differential
-
5-part WBC differential
-
Other parameters
-
-
End-use Outlook (Revenue, USD Million, 2018 - 2030)
-
Veterinary Laboratories
-
Veterinary Hospitals and Clinics
-
Point-Of-Care Testing
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
Rest of Europe
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
Rest of Asia Pacific
-
-
Latin America
-
Brazil
-
Argentina
-
Rest of Latin America
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Rest of the Middle East & Africa
-
-
Frequently Asked Questions About This Report
The global veterinary hematology analyzers market size was valued at USD 1.2 billion in 2024 and is estimated at USD 1.4 billion for 2026.
North America dominated the veterinary hematology analyzers market with a share of 52.9% in 2024. This is attributable to the rising prevalence of animal diseases and growing pet ownership. For example, canine Lyme disease and heartworm infections are increasingly common in the U.S., boosting the demand for accurate diagnostic tools.
Some key players operating in the veterinary hematology analyzers market include IDEXX Laboratories, Inc., Zoetis, Mars Inc. (Heska Corporation), HORIBA Medical, Shenzhen Mindray Animal Medical Technology Co., LTD., Chengdu Seamaty Technology Co., Ltd., Boule Medical AB, Sysmex Corporation, HemoCue AB, Scitek Global Co., Ltd.
Key factors that are driving the market growth include the rising prevalence of zoonotic diseases, growing pet ownership, and increased spending on animal healthcare. Additionally, technological advancements in AI-powered diagnostics, demand for point-of-care testing (POCT), and the need for accurate and rapid blood analysis are boosting market growth. For instance, in December 2025, Zoetis Inc. launched Vetscan OptiCell, a next-generation point-of-care hematology analyzer, at VMX 2025 in Orlando.
The global veterinary hematology analyzers market is expected to grow at a CAGR of 10.0% from 2025 to 2030, reaching USD 2.1 billion by 2030.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst -

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


