
- Home
- »
- Animal Health
- »
-
Veterinary Point Of Care Diagnostics Market Report, 2033GVR Report cover

Veterinary Point Of Care Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Animal, By Product (Consumables, Reagents, & Kits, Instruments & Devices), By Testing Category, By Indication, By Sample Type, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$2.8BMarket Estimate, 2026
$3.1BMarket Forecast, 2033
$6.2BCAGR, 2026–2033
10.5%Veterinary Point Of Care Diagnostics Market Summary
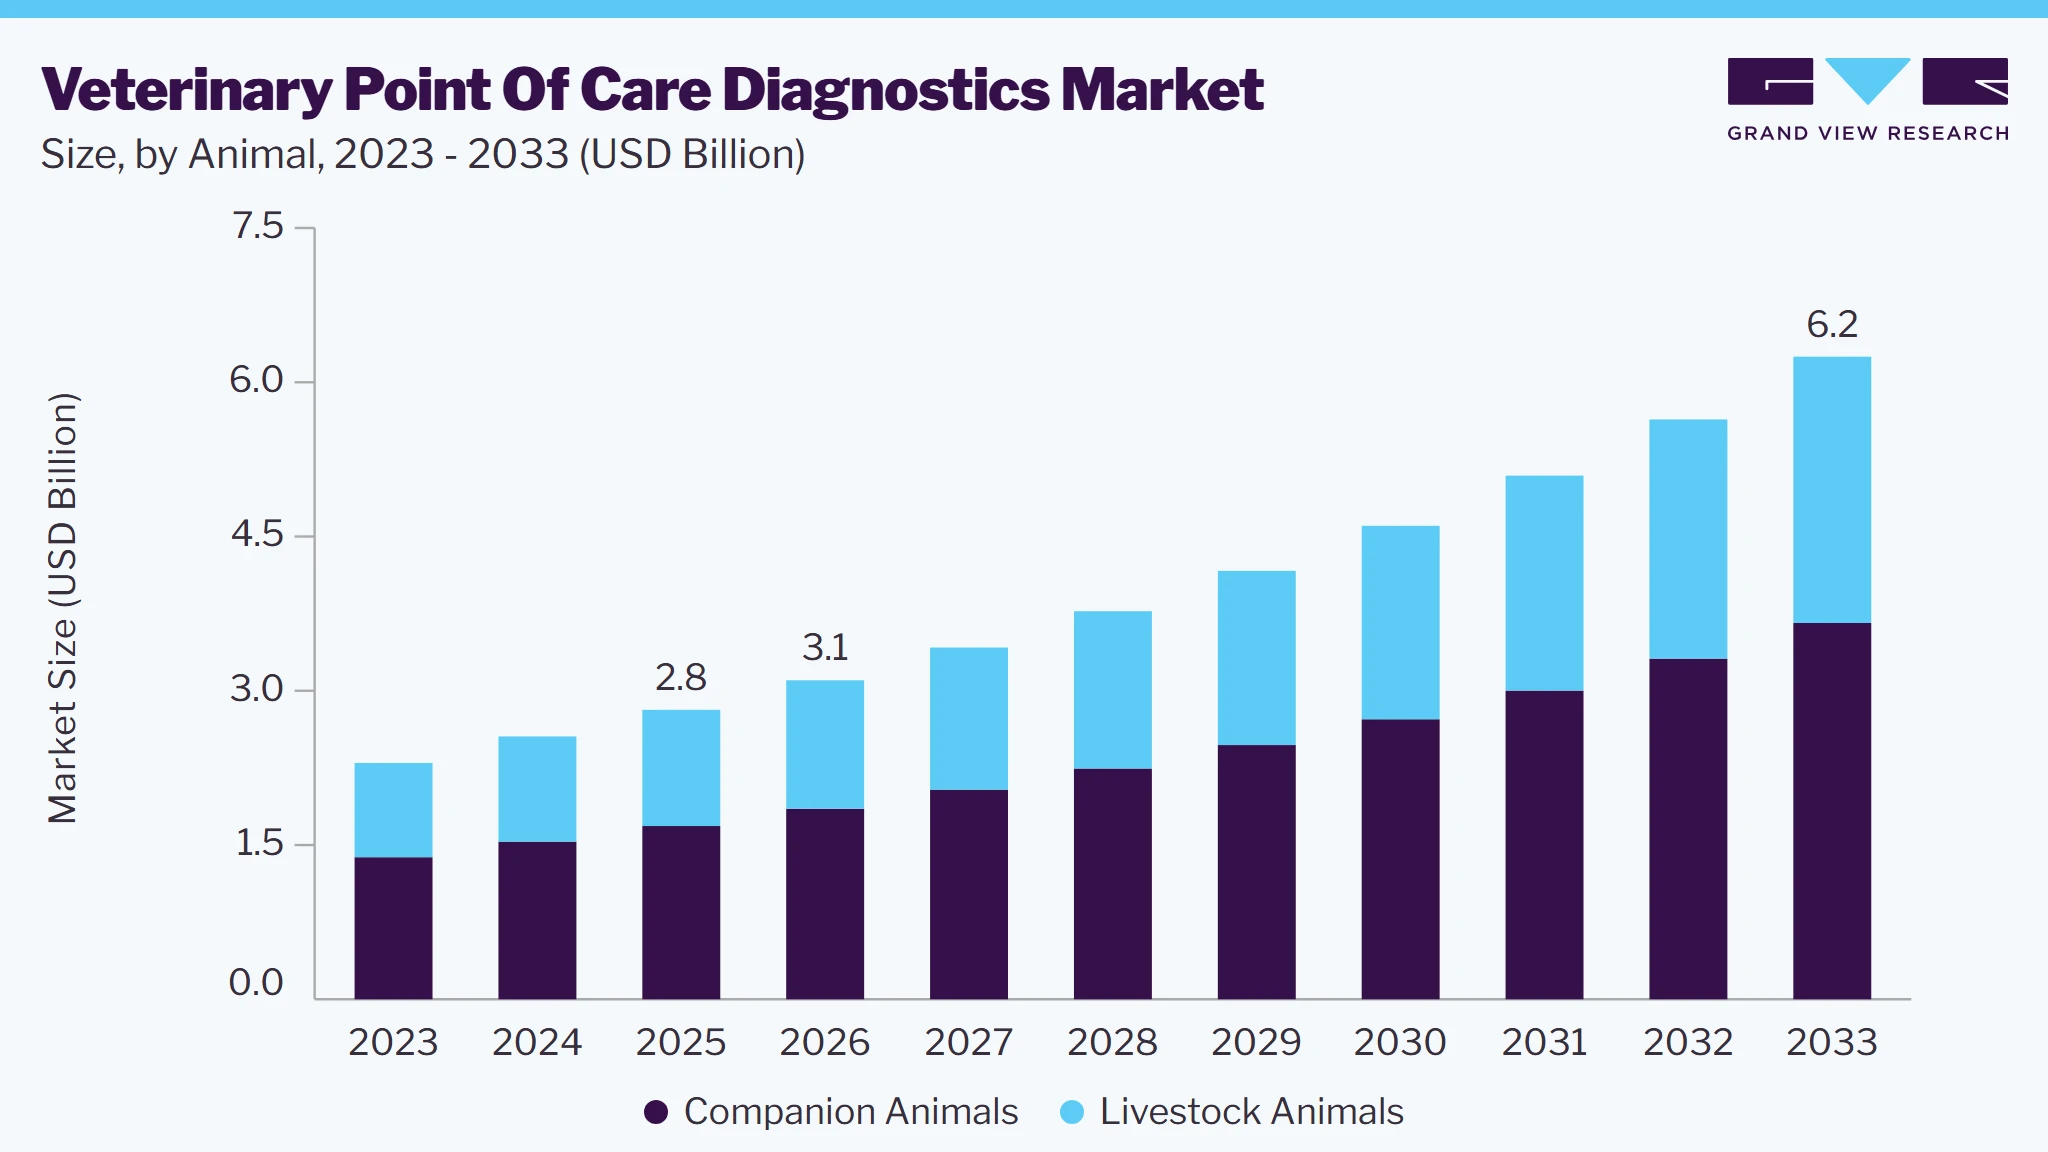
The global veterinary point of care diagnostics market size was valued at USD 2.8 billion in 2025 and is projected to grow from USD 3.1 billion in 2026 to USD 6.2 billion by 2033, at a CAGR of 10.5% from 2026 to 2033. North America market dominated, with a revenue share of 48.1% in 2025. Increased pet expenditures, advances in test kits and equipment for the rapid diagnosis of animal diseases, a rise in overall zoonotic diseases, the popularity of pet care, and a significant demand for point-of-care diagnostics are major factors driving this market.
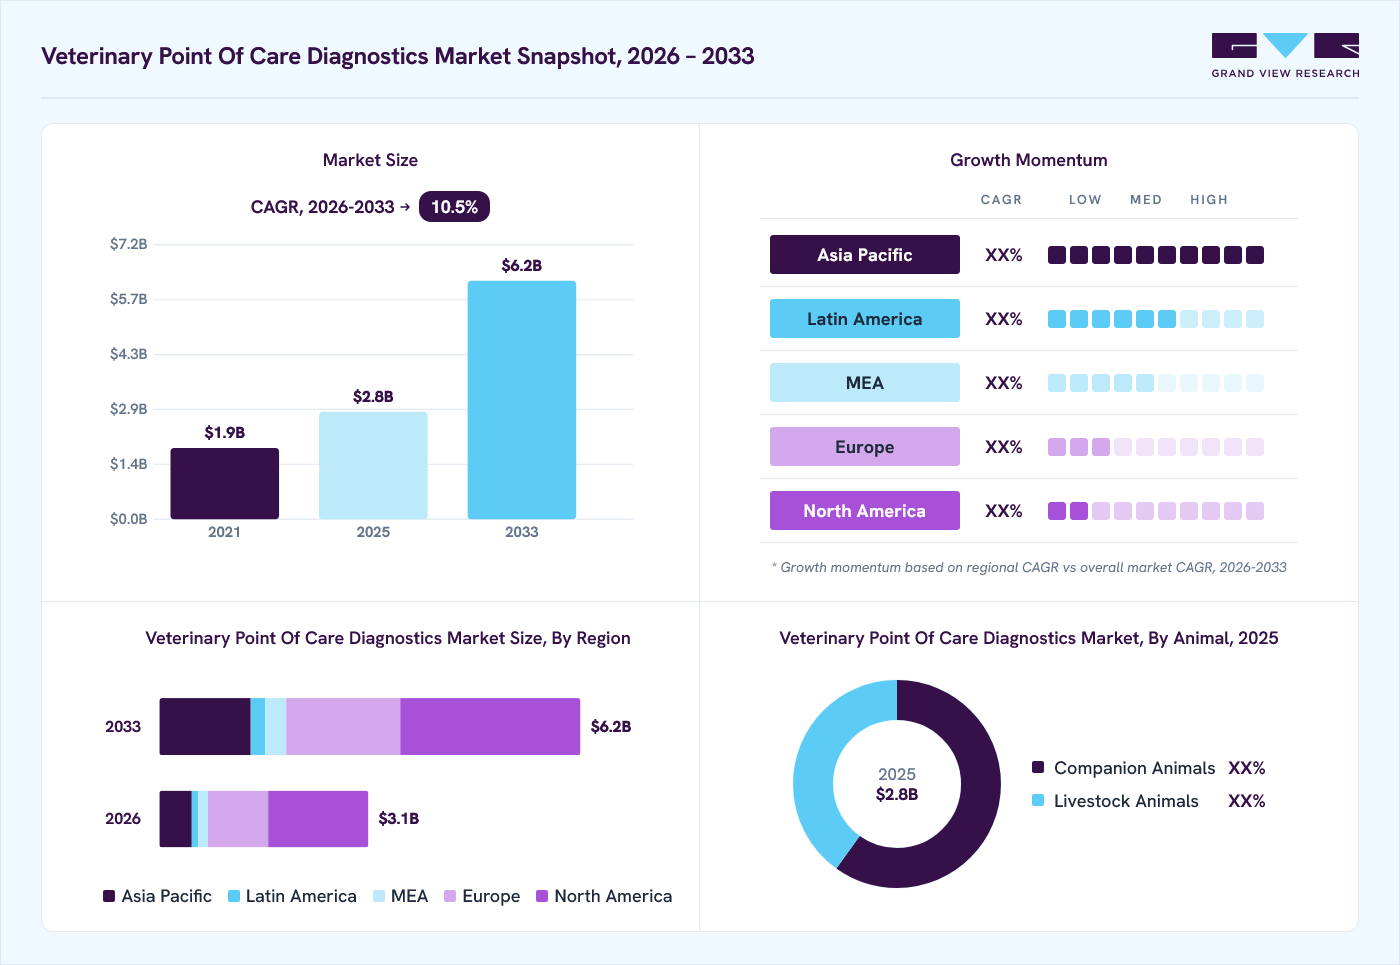 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By animal: Companion animals segment led the market with the largest revenue share of 59.9% in 2025.
- By product: Consumables, reagents, & kits segment led the market with the largest revenue share of 55.2% in 2025.
- By testing category: Parasitology segment led the market with the largest revenue share of 17.6% in 2025.
- By indication: Infectious disease segment led the market with the largest revenue share of 41.0% in 2025.
- By sample type: Blood/plasma/serum segment led the market with the largest revenue share of 39.7% in 2025.
Regional Highlights
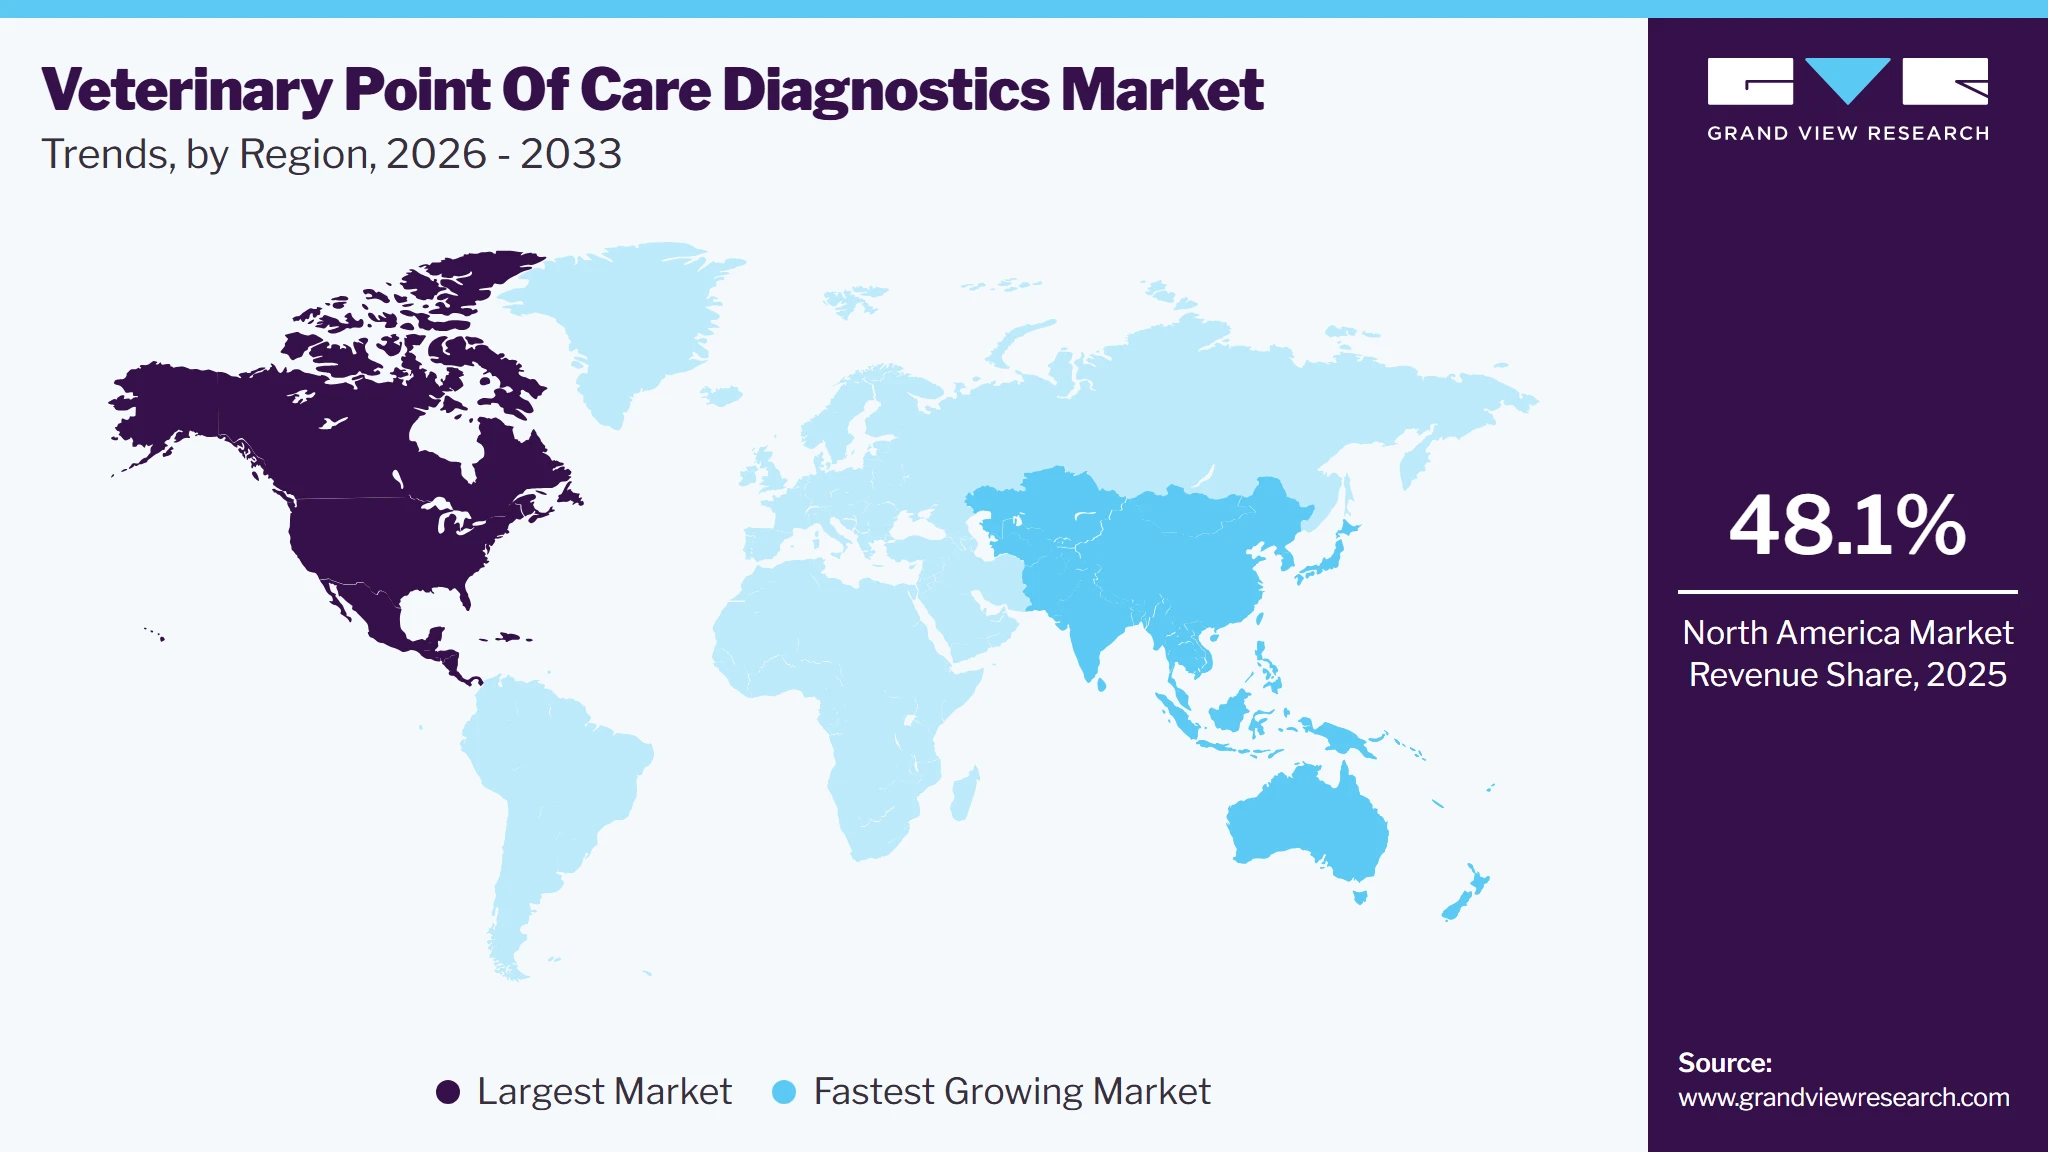
- Largest regional market: North America (48.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecasts
- Market size in 2025: USD 2.8 Billion
- Estimated market size in 2026: USD 3.1 Billion
- Projected market size by 2033: USD 6.2 Billion
- CAGR (2026-2033): 10.5%
Prism AI by Grand View Research Free to tryAsk a question about the veterinary point of care diagnostics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
For instance, businesses are investing in research and development to develop point-of-care diagnostic equipment. Overall, awareness about veterinary health is increasing globally, as it directly correlates with human health. For instance, dairy cattle struggling with an ailment will affect the yield and quality of the dairy products. This will further affect humans economically and in terms of their overall health.Industry leaders such as IDEXX Laboratories, Inc., Zoetis, Heska Corporation (Antech), Mindray, and FUJIFILM Corporation are investing significantly in the research and development of unique products specialized in point-of-care diagnostics of companion and livestock animals for a variety of indications.
 To learn more about this report, Download Free Sample Report
Increasing pet care expenditure on diagnostic services is a significant factor driving lucrative growth in the market. Point-of-care diagnostics help identify new risk factors for disease, allowing veterinarians to take earlier preventive action. Globally, spending on health-related costs has been on the rise. According to January 2025 statistics published by Dogster, health-related costs account for 19%-45.5% of overall dog-related costs and 15%-38.8% of overall cat-related costs. Furthermore, in the U.S. alone, pet owners are estimated to collectively spend over USD 136 billion annually on pets.
In addition, pet insurance ensures that diagnostic pet care expenses are reimbursed and that the pet owner is not responsible for the associated costs. Due to many factors, including the humanization of animals, rising animal numbers, increased initiatives by major corporations, escalating veterinary costs, and growing adoption among underprivileged communities, acceptance of pet insurance is on the rise. These pet insurances provide substantial coverage for Tests/diagnostics (such as X-rays, blood tests, MRIs, and more), Unexpected injuries/accidents, medications, etc.
In the United States, since 2018, as more owners look for ways to cope with rising veterinary care costs, there has been a 22.5% year-over-year increase in insured pets. According to the Consumer Price Index, between June 2022 and June 2023, veterinary service prices outpaced inflation by as much as 11.4% over the last decade. According to studies by Pawlicy Advisor, 2,438,795+ pets (dogs & cats) have pet insurance across the U.S.
Market Dynamics
The market is experiencing growth, driven by increasing pet expenditures, rising companion animal ownership, and growing awareness of preventive veterinary healthcare. In addition, advances in rapid diagnostic technologies, including portable analyzers, multiplex test kits, AI-enabled imaging, and cartridge-based molecular assays, are enabling veterinarians to deliver accurate results within minutes, improving treatment decisions and patient outcomes. For instance, in July 2026, Accelerated Diagnostics secured investment to advance its ultra-rapid, low-cost veterinary diagnostic platform capable of detecting infectious diseases from saliva samples in about one minute, supporting faster on-farm disease diagnosis, commercialization, and improved livestock disease surveillance.
In addition, increasing prevalence of zoonotic, infectious, and chronic diseases across companion and livestock animals has accelerated demand for timely in-clinic diagnostics. Furthermore, the expanding popularity of pet insurance, routine wellness screening, and point-of-care testing in veterinary hospitals, clinics, and mobile practices supports wider adoption. Livestock producers are also utilizing rapid diagnostics for disease surveillance and herd health management to minimize economic losses. Thus, continuous product launches, integration of digital connectivity with practice management systems, and expanding veterinary infrastructure across developed and emerging markets are strengthening market growth and creating long-term opportunities for manufacturers and healthcare providers.
One of the major drivers affecting market growth is continuous advancements in rapid diagnostic technologies. The market is also witnessing innovations such as portable analyzers, cartridge-based molecular assays, AI-enabled diagnostic platforms, multiplex testing, biosensors, and cloud-connected devices enable veterinarians to detect infectious, metabolic, and chronic diseases within minutes, facilitating faster clinical decision-making and timely treatment. For instance, in July 2026, Optiscan Imaging launched its InSpecta real-time microscopic imaging device in the U.S., enabling point-of-care cellular imaging that supports faster clinical decision-making, improved workflow efficiency, and expanded in-house diagnostic capabilities across veterinary practices. These technologies reduce dependence on centralized laboratories, improve workflow efficiency, and support immediate disease management in veterinary hospitals, mobile clinics, and livestock farms.
In addition, rapid diagnostics are also becoming increasingly important for livestock disease surveillance, helping producers contain disease outbreaks, minimize production losses, and improve herd health management. In companion animal care, the growing emphasis on preventive medicine and routine wellness screening has further increased the adoption of point-of-care testing. As diagnostic technologies continue to evolve, their expanding accessibility and clinical utility are expected to sustain long-term market growth.
The market faces a significant restraint due to the lengthy research and development (R&D) cycles and substantial capital investment required to develop advanced veterinary diagnostic technologies. Designing reliable point-of-care platforms involves extensive assay optimization, analytical validation, multi-species field testing, and compliance with stringent regulatory and quality standards. Furthermore, the integration of advanced technologies such as artificial intelligence (AI), molecular diagnostics, biosensors, and digital connectivity increases both technical complexity and development costs.
Manufacturers must also invest heavily in specialized equipment, clinical validation studies, manufacturing scale-up, and post-market support before commercialization. These high capital requirements create significant barriers for emerging companies, delay product launches, and limit innovation, ultimately slowing the adoption of next-generation veterinary diagnostic solutions, particularly in price-sensitive and developing markets where return on investment remains uncertain.
The growing integration of artificial intelligence (AI), digital health platforms, and connected diagnostic technologies presents a significant opportunity for the market. AI-assisted interpretation, cloud-based data management, and predictive analytics enable veterinarians to obtain faster, more accurate diagnoses while improving clinical decision-making and workflow efficiency. Connected point-of-care devices facilitate real-time data sharing, remote consultation, and integration with veterinary practice management systems, enhancing continuity of care. For instance, in June 2026, Saudi Arabia introduced an AI-powered Animal Health Platform that analyzes veterinary data to predict disease outbreaks, monitor infections, support early diagnosis, improve preventive care, and enhance livestock disease surveillance through real-time, data-driven decision-making These technologies also support disease surveillance, herd health monitoring, and early outbreak detection in livestock populations, improving productivity and biosecurity.
In addition, in companion animal care, digital diagnostics promote preventive healthcare through routine wellness screening and continuous health monitoring. As veterinary clinics increasingly adopt smart diagnostic solutions and governments invest in digital animal health infrastructure, manufacturers have substantial opportunities to develop innovative, software-integrated diagnostic platforms that enhance accessibility, operational efficiency, and long-term patient outcomes across both companion and production animal sectors.
Market Concentration & Characteristics
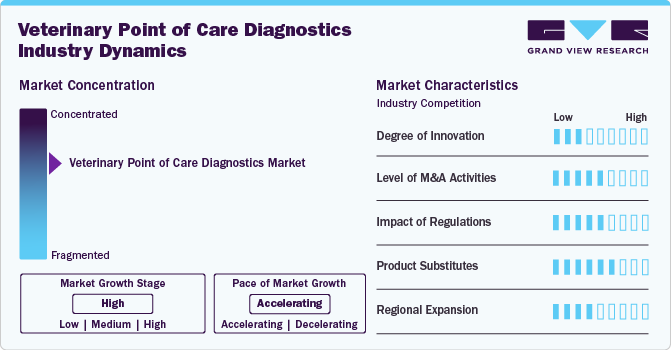
The market growth stage is high, and the pace of growth is accelerating. The market is characterized by a high degree of innovation, driven by advancements such as the emergence of specialized products and initiatives by market players to increase productivity in veterinary diagnostics and veterinary practice as a whole.
The market is also characterized by high levels of merger and acquisition (M&A) activity among leading and emerging players. In April 2023, Mars Incorporated acquired Heska Corporation, making it part of Mars Petcare's Science & Diagnostics division. This enables Mars Incorporated to ensure broader coverage across diagnostics and technology, accelerate R&D, and expand global access to pet healthcare solutions.
 To learn more about this report, Download Free Sample Report
The market faces challenges in quality assurance and control of POCT products. As technology advances, there is a rapid influx of POCT methods and equipment on the market. POCTs are frequently not subjected to the same regulations as traditional laboratory diagnostic tests or assays. Regulations or standards for evaluation are inadequate. Consequently, appropriate approval processes to guarantee the caliber of outcomes are lacking. Animal diagnostic tests, including POCT, are officially validated and certified by the World Organization for Animal Health (WOAH). In addition, WOAH maintains a register to track veterinary diagnostic kits, but WOAH does not administer this and is not required in most countries. Due to worries about costs and marketability, most small-scale POCT producers do not consider registering their products.
The market is characterized by a dearth of submitted validation studies, a lack of uniformity and openness in POCT validation data, and challenges in fully validating POCTs for specific pathogens.
Even though quality control in veterinary POCTs is an issue, there is not much reference material available. In this regard, quality assurance guidelines for veterinary POCT were created by the American Society for Veterinary Clinical Pathology (ASVCP) and released in 2013. Their primary suggestions were to adopt a formalized approach to POCT, use written policies, SOPs, forms, and logs, train operators, and periodically assess their skills, inquire about the instruments' analytical performance, use appropriately established or validated reference intervals, and guarantee accurate results reporting. These recommendations were intended to help veterinarians or technicians raise POCT standards in their clinical or research institutions; they were not intended to be all-inclusive.
Analyst Perspective
The market is witnessing robust growth, fueled by rising companion animal ownership, increasing pet healthcare expenditure, and growing awareness of early disease detection among pet owners and livestock producers alike. The shift toward preventive and personalized veterinary care is accelerating adoption of rapid, in-clinic diagnostic solutions, including immunoassay analyzers, hematology systems, blood gas/electrolyte analyzers, molecular diagnostics, and urinalysis devices, reducing dependency on centralized reference laboratories and enabling faster clinical decision-making. In addition, technological advancements such as miniaturized analyzers, cloud connectivity, AI-assisted result interpretation, and multiplexing capabilities are enhancing diagnostic accuracy and workflow efficiency within veterinary practices. Furthermore, the rising prevalence of zoonotic and chronic diseases in animals, coupled with expanding pet insurance penetration, is encouraging veterinarians to invest in advanced diagnostic infrastructure. The market competition is witnessing high competition as key players focus on strategic partnerships, product launches, and geographic expansion to strengthen their foothold. In addition, emerging players present lucrative opportunities due to improving animal healthcare infrastructure, positioning the point of care diagnostics segment for sustained, innovation-driven expansion globally.
Animal Insights
Based on animal, the companion animals segment led the market with the largest revenue share of 59.9% in 2025. This is likely linked to a rise in pet adoption during the pandemic, which is anticipated to drive market expansion during the projected period. For example, after COVID-19, private breeders, nonprofit rescues, and shelters in the U.S. reported high consumer demand. Heska Corporation, Zoetis, and IDEXX are expected to have robust product pipelines that will drive market expansion throughout the projection period.
Companion animals segment accounted for the largest share in the market, driven by rising pet ownership, increasing pet healthcare expenditure, and growing demand for rapid in-clinic diagnosis. According to the 2025 APPA National Pet Owners Survey, approximately 94 million U.S. households own at least one pet. Dog ownership increased to 68 million households, while cat ownership rose to 49 million households, demonstrating continued growth in companion animal ownership across the U.S. In addition, veterinarians are also adopting point-of-care diagnostic solutions for routine wellness screening, infectious disease detection, chronic disease management, and emergency care in dogs, cats, and horses.
Product Insights
Based on product, the consumables, reagents, & kits segment led the market with the largest revenue share of 55.2% in 2025. This is because many products are available, the sales model for reagents and consumables is subscription-based or recurring payments, and other major corporations have taken these steps. Consumables are becoming an essential component of diagnostic procedures used in many. Rising demand for veterinary diagnostics is driving up the consumption and usage of consumables and reagents in diagnosis.
The instruments and devices segment is projected to expand at the fastest CAGR of over 10.68% during the forecast period, driven by ongoing product enhancements and rising demand for these products. Growing demand for animal-derived foods is expected to increase the need for animal immunodiagnostic tests over the forecast period. Clinical chemistry and immunodiagnostic kits are significant products used in veterinary diagnostics. This is because of the increase in demand for detecting animals' general health profiles. On the other hand, advancements in immunodiagnostic kits for veterinary use are expected to drive their adoption over the forecast period.
Testing Category Insights
Based on testing category, the parasitology segment led the market with the largest revenue share of 17.6% in 2025. This is due to the high prevalence of parasitic infections, which is prompting the need for increased parasitological tests. A 2020 study in Veterinary Parasitology estimated that heartworm prevalence could be as high as 28% in dog populations, while testing in cats found 19% with evidence of active or previous infection. Tests for internal parasites typically involve examination of feces for parasite eggs. Whipworm, roundworm, Giardia, hookworm, and coccidia are the most frequently diagnosed internal parasites, according to the Companion Animal Parasite Council (CAPC), and are most commonly detected by fecal examination.
By testing category, the parasitology segment held the highest market share in 2025. This is due to the high prevalence of parasitic infections, which is probing for the need for increased parasitological tests. According to a study published in December 2025, for analyzing 15,899 fecal samples from dogs and cats, 26.0% of dogs and 21.4% of cats tested positive for at least one gastrointestinal parasite. These findings emphasize the need for routine fecal screening, regular deworming, standardized diagnostic protocols, and improved pet owner awareness to enhance animal and public health. In addition, tests for internal parasites typically involve examination of feces for parasite eggs. Whipworm, roundworm, Giardia, hookworm, and coccidia are the most frequently diagnosed internal parasites per the Companion Animal Parasite Council (CAPC) and are most commonly diagnosed by fecal examination.
Indication Insights
Based on indication, the infectious disease segment led the market with the largest revenue share of 41.0% in 2025. This can be attributed to the stark rise in contagious diseases among companion animals and livestock. For example, A devastating and highly transmissible viral disease affecting cattle, foot and mouth (FMD), has a substantial financial impact. Cattle, pigs, sheep, goats, and other ruminants with cloven hooves are susceptible to the disease. The disease is thought to affect 77% of the world's livestock population and populations in Africa, the Middle East, Asia, and a small portion of South America, according to the World Organization of Animal Health (WOAH).
The general ailments segment is estimated to show the fastest CAGR over 2025-2030. This can be attributed to an increase in diagnostic companies entering the market with innovative technologies to determine animal diseases. For instance, the Lab on a Chip technology analyzes electrolytic imbalance in the body fluids such as blood, urine, and milk. Similarly, IDEXX Laboratories offers a broad range of products integral to this market, widely used in key regions such as North America, Europe, Asia Pacific, Africa, and the Middle East.
End-use Insights
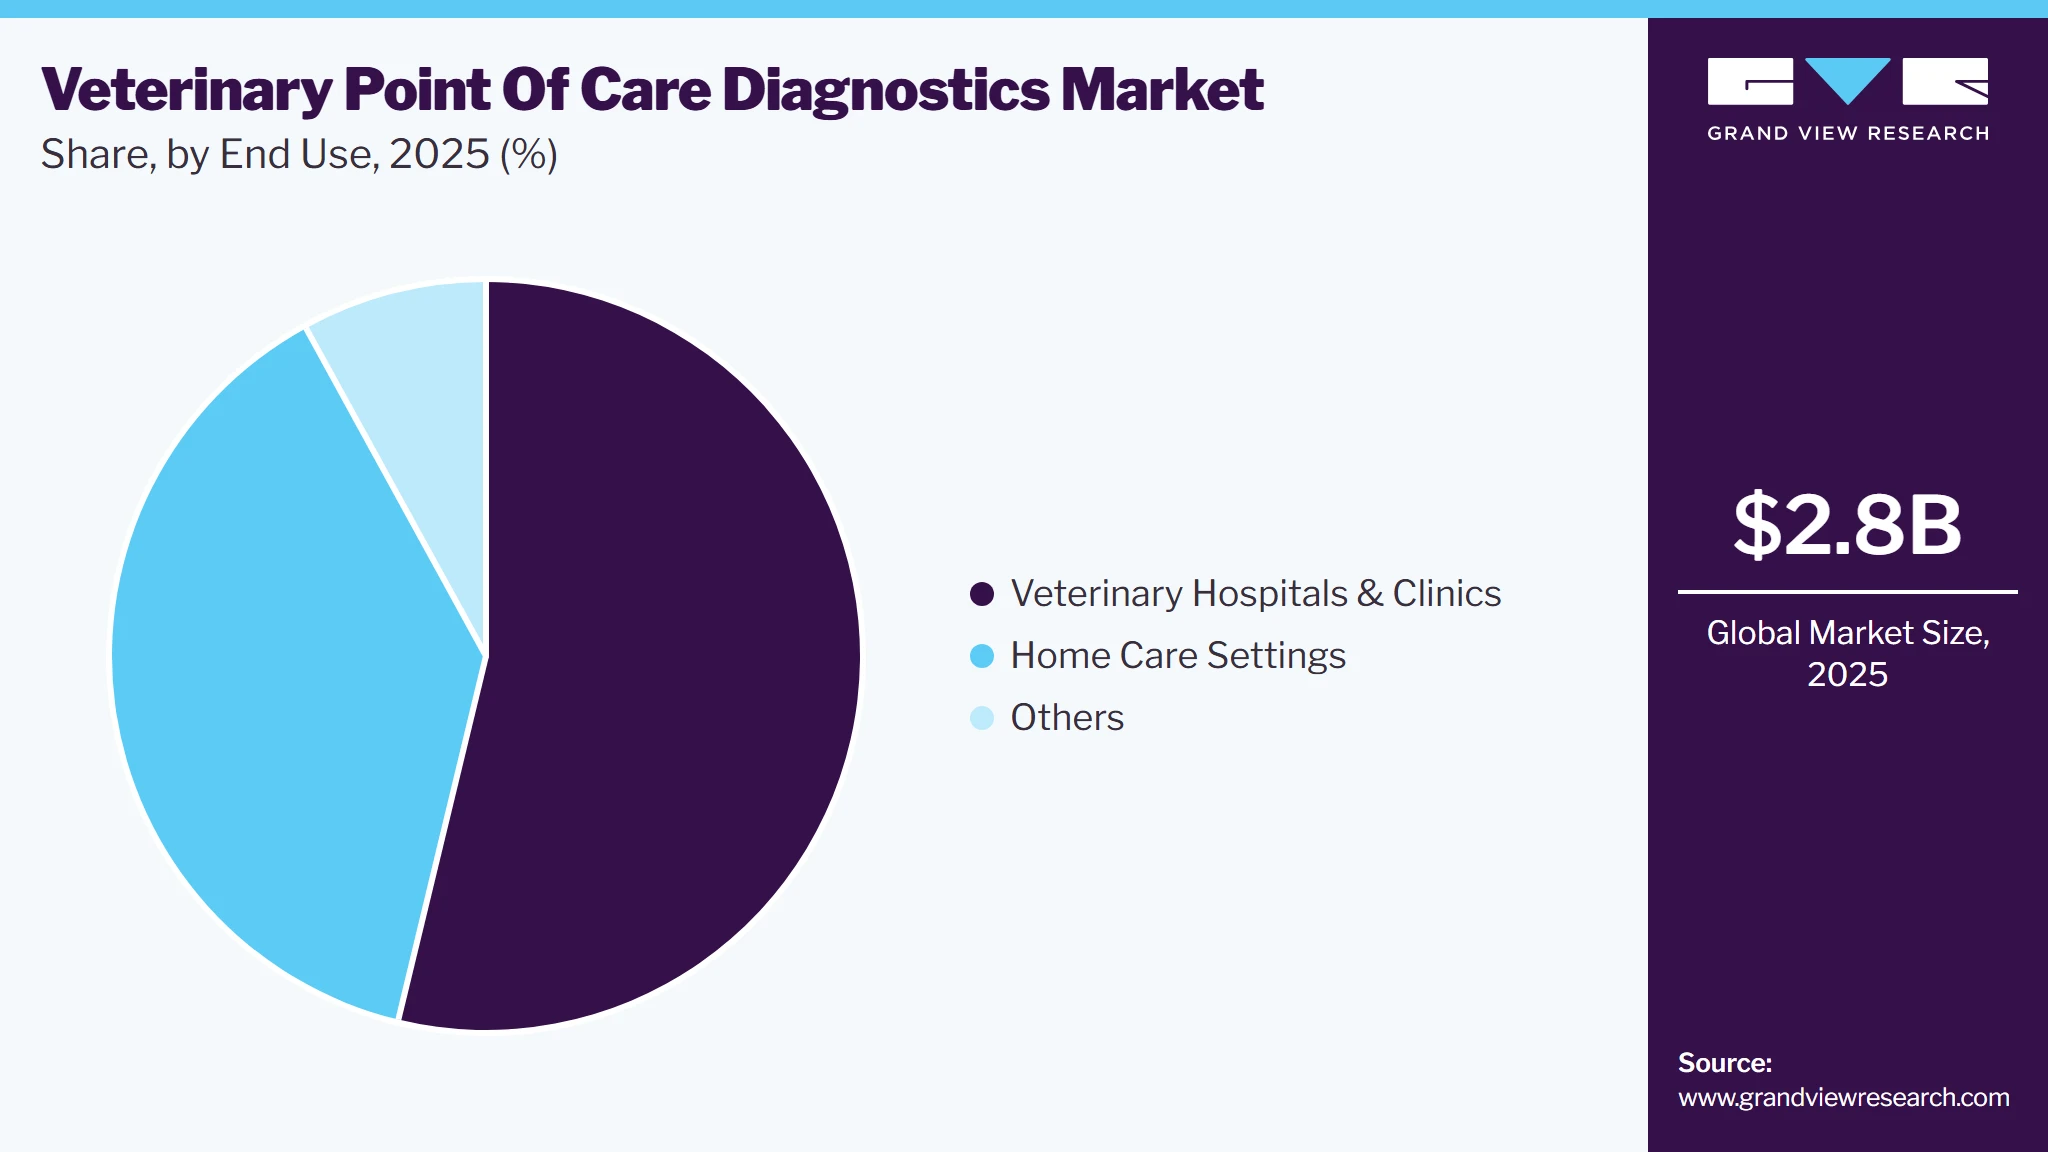
Based on end-use, the veterinary hospitals & clinics segment led the market with the largest revenue share of 53.8% in 2025. Because point-of-care diagnostics provide rapid results and enable prompt treatment decisions, they are widely used in veterinary clinics and hospitals. Minimizing the requirement for independent laboratories shortens turnaround times and enables veterinarians to attend to patient needs quickly. On-site testing's speed and convenience increase workflow overall, resulting in faster diagnosis and better patient care. Furthermore, point-of-care diagnostics enable prompt interventions, which are essential for emergencies and for tracking long-term medical issues in animals.
 To learn more about this report, Download Free Sample Report
Point-of-care diagnostics' ease of use and comfort make them highly likely to be adopted in homecare settings and are estimated to register the highest CAGR. The development of portable testing instruments has made it possible for people to monitor their health or the health of their pets from the comfort of their homes, eliminating the need for frequent trips to veterinary clinics or other healthcare facilities. Ease of use and the speed of results enable pet owners to take charge of their animals' health, encouraging early detection and preventive therapy. This move toward home-based diagnostics fits into a larger pattern of decentralized healthcare, improving pets' overall health through prompt, practical observation.
Sample type Insights
Based on sample type, the blood/plasma/serum segment led the market with the largest revenue share of 39.7% in 2025. Because blood, plasma, and serum samples provide valuable information about an animal's health, they are commonly used in veterinary point-of-care diagnostics. These samples contain biomarkers that reflect a variety of physiological factors, enabling minimally invasive, rapid assessment of both overall health and the presence of specific illnesses.
The urine segment is growing at the fastest CAGR over the forecast period. This sample type is used in the process of urinalysis, which is based on the evaluation of constituents of urine. It is an easy-to-use, cost-effective, and key initial diagnostic test. Complete urine analysis includes the examination of turbidity, volume, color, odor, pH, protein, glucose, specific gravity, ketones, blood, epithelial cells, casts, crystals, organisms, erythrocytes, and leukocytes.
Regional Insights
North America dominated the veterinary point of care diagnostics market with the largest revenue share of 48.1% in 2025, attributed to the presence of significant animal healthcare companies locally. Real-time diagnosis is now possible due to improvements in the veterinary healthcare infrastructure in the U.S. and Canada. This is expected to stimulate R&D and facilitate the creation of new products. The region's growing veterinary clinic and veterinarian population is also fueling the market's expansion. For instance, the American Veterinary Medical Association (AVMA) estimates that there were approximately 133,475 veterinarians employed in U.S. The market is highly competitive, with many large- and small-scale players. Most companies focus on R&D efforts. Mergers, acquisitions, collaborations, and partnerships to achieve a more significant market share.
 To learn more about this report, Download Free Sample Report
The veterinary point of care diagnostics market in the U.S. held the largest share in the North America region in 2025. Rising awareness about animal hygiene & health, coupled with an increasing number of pet owners, is likely to accelerate the U.S. Humanization of pets, which can also drive market growth across the country. Government organizations, such as the UN Food and Agriculture Organization, are actively supporting training programs to create awareness among field practitioners. Increasing pet and livestock animal populations is expected to boost the demand for veterinary healthcare services, such as diagnostic kits, further propelling the overall expenditure on pets.
Europe Veterinary Point-of-Care Diagnostics Market Trends
Europe accounted for the second-largest market share in 2024. The rapid adoption of advanced technologies in blood gas analyzers, growing ownership of companion animals, increasing expenditures on animal welfare, and rising awareness of animal health are among the major drivers of the regional market. The European Medicines Agency (EMA) and its regulatory network partners have identified an action plan to improve the availability of animal medicines and diagnostics tools & kits in Europe. Some action plans are being executed in the interest of animal & public health and welfare. The EMA has undertaken several initiatives to encourage timely access to animal medicines and products in the European market and respective countries. The rising number of pets in the region is expected to boost market growth.
The continuous regulatory oversight over the country's veterinary sector primarily drives the UK market. This ensures the minimization of malpractices and the maximum benefit to animal owners. For instance, in March 2024, the Competition & Markets Authority of the UK launched a formal market investigation into the veterinary sector owing to rising concerns about weak competition, potential overcharging for veterinary medicines, and an outdated regulatory framework. The initial review included over 56,000 responses from the public and industry, revealing that pet owners lack the information needed to make informed decisions and that large corporate groups might reduce choice and weaken competition.
The willingness of pet owners to opt for veterinary treatments, such as vaccinations, supplements, and diagnostic tests, for general ailments and diseases is improving the lives of pets and driving the market in Spain. Moreover, the increase in pet ownership has also fueled the growth of the veterinary POC diagnostic market. In addition, increasing initiatives undertaken by the Spanish government and non-government organizations in the field of veterinary health and increasing awareness among pet owners about animal health are driving the market in Spain.
Asia Pacific Veterinary Point-of-Care Diagnostics Market Trends
The veterinary point-of-care diagnostics market is expected to register the fastest CAGR in the Asia Pacific due to several factors. Firstly, the region has a growing awareness of and concern for animal health and well-being, leading to increased demand for veterinary services. In addition, the growth of the pet population, urbanization, and a high livestock animal population in the region contribute to a higher willingness to invest in veterinary care. The need for rapid and on-the-spot diagnostics is emphasized in regions with large rural areas where access to centralized veterinary laboratories may be limited. As the veterinary industry evolves and technology becomes more accessible, the Asia-Pacific region presents a significant market for the adoption of point-of-care diagnostics in veterinary care.
Advancements in technology to improve animal and veterinary care, along with the growing adoption of pets and the demand for practical solutions to maintain their health, are accelerating market growth. Accordingly, the market is expected to see notable growth, as veterinary point-of-care diagnostic tools help diagnose and detect diseases and general ailments in animals. Furthermore, the increasing number of veterinarians and rising incomes among people in developed countries will benefit the market.
Latin America Veterinary Point-of-Care Diagnostics Market Trends
The Latin America veterinary POC market includes the following countries: Brazil and Argentina. Technological developments are driving the market, the growing pet population and humanization, the need to reduce antimicrobial resistance, and the growth of service offerings by vet clinics. Furthermore, the market has been affected by the global trend of healthcare digitalization. Companies are investing in product development to improve testing accuracy, validate devices, broaden test menus, and automate as much of the process as possible, thereby reducing the difficulty of using these devices.
The increasing frequency of zoonotic illnesses among companion & livestock animals, growing demand for rapid diagnosis of these diseases, and advantages of POC tests over laboratory analysis will likely drive Brazil's market over the forecast period. Furthermore, the growing pet population can drive the market, as people have become more aware of their pets' conditions over the years. According to a Euromonitor survey, Brazilians own approximately 36 million puppies and small dogs, the most of any country in the world. On the other hand, the high cost of veterinary imaging tools is hampering the market growth.
MEA Veterinary Point-of-Care Diagnostics Market Trends
Technological and medical developments are significantly impacting animal care in the MEA. The market is likely to be driven by the increasing adoption of pets and the demand for better healthcare solutions. As a result, the market is expected to increase significantly as veterinary POCs aid in detecting infections, which has been vital amid the pandemic. In addition, the market can benefit from an increase in the number of veterinary doctors and the average income of people in developed economies. Furthermore, as the number of zoonotic diseases in animals and their transmission to people grows, so does the requirement for better diagnostics.
The primary factor driving Saudi Arabia's veterinary POC diagnostics market is the increased demand for pet insurance amid growing pet adoption. Furthermore, rising disposable income, increasing demand for animal-derived foods, and growing investments in animal healthcare spending will likely drive the country's market over the forecast period. The market is also expected to grow due to an increase in the prevalence of foodborne diseases in animals and zoonotic infections.
Key Veterinary Point Of Care Diagnostics Company Insights
The market is relatively competitive owing to the presence of many key manufacturers. This is expected to intensify the competition in the coming years. Some of the key players in the market are Zoetis, IDEXX, Virbac, Heska Corporation, Thermo Fisher Scientific, Inc., FUJIFILM Corporation, and others. To strengthen their market presence, these players are undertaking strategic initiatives, including partnerships, sales & marketing activities, mergers & acquisitions, product expansion, and product launches.
Key Veterinary Point Of Care Diagnostics Companies
The following key companies have been profiled for this study on the veterinary point of care diagnostics market.
-
IDEXX Laboratories, Inc.
-
Zoetis
-
Heska Corporation (Antech)
-
Virbac
-
Thermo Fisher Scientific, Inc.
-
Mindray
-
Woodley Equipment Company Ltd
-
FUJIFILM Corporation
-
Getein Biotech
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IDEXX Laboratories, Inc., Zoetis and others)
- Mature players strengthen market leadership through continuous product innovation, AI-enabled diagnostic platforms, integrated software ecosystems, strategic acquisitions, and expansion of consumables portfolios.
- They invest in R&D, automation, cloud connectivity, and veterinary education while establishing long-term partnerships with hospitals, clinics, distributors, and reference laboratories.
- Recurring revenue from reagents, service contracts, and digital platforms supports sustainable growth and customer retention.
- Established companies benefit from extensive product portfolios, globally recognized brands, strong regulatory expertise, and broad distribution networks.
- Their large installed instrument base generates recurring consumable sales, while advanced AI capabilities, validated diagnostic accuracy, and integrated laboratory information systems improve clinical confidence.
- Strong financial resources enable continuous innovation, premium customer support, and rapid commercialization of next-generation veterinary diagnostic technologies.
- Mature companies often face slower innovation cycles due to complex organizational structures and extensive regulatory requirements.
- Premium product pricing may restrict adoption among smaller veterinary clinics and emerging markets.
Emerging Players (Getein Biotech and other regional pet hygiene brands)
- Emerging players focus on developing compact, AI-enabled, and user-friendly point-of-care diagnostic platforms that deliver rapid, accurate results in veterinary settings.
- They prioritize niche disease panels, cloud-based data integration, strategic collaborations with veterinary clinics, and partnerships with distributors to expand market reach.
- Investment in affordable consumables, digital workflow solutions, and continuous product innovation enables these companies to strengthen adoption while addressing evolving diagnostic needs across companion and livestock animals.
- Emerging companies gain a competitive advantage through innovative technologies such as AI-assisted diagnostics, portable analyzers, multiplex testing, and smartphone-enabled connectivity.
- Their flexible product development, faster commercialization, and ability to address underserved clinical applications allow quicker market penetration.
- Cost-effective solutions, simplified workflows, minimal maintenance requirements, and integration with digital veterinary practice management systems improve operational efficiency, making their offerings attractive to small clinics and mobile veterinary practitioners.
- Emerging players often face challenges including limited brand recognition, smaller distribution networks, and constrained financial resources compared to established diagnostic companies.
- Restricted manufacturing capacity, fewer long-term customer relationships, and limited after-sales service infrastructure can slow market expansion.
Recent Developments
-
In December 2024, Zoetis announced the launch of Vetscan OptiCell, a point-of-care hematology analyzer, at the Veterinary Meeting & Expo (VMX).
-
In November 2023, Antech Diagnostics opened its brand-new reference laboratory in Warwick. The launch marks the arrival of Antech’s first complete and flexible portfolio in the UK, which includes the reference lab, in-house diagnostics, imaging, and software solutions.
-
In November 2023, Adopt a Pet and Zoetis partnered to improve access to care for shelter pets and deploy educational resources for shelter veterinary healthcare teams and pet owners nationwide.
-
In June 2023, IDEXX Laboratories, Inc. announced the launch of the first veterinary diagnostic test for detecting kidney injury in cats and dogs. The Test panels evaluating kidney health will incorporate the IDEXX Cystatin B Test, providing fresh clinical information for an anticipated two million patient visits yearly. Later in the year, these tests were conducted at IDEXX Reference Laboratories in the United States and Canada. The test is scheduled to be introduced in Europe in 2024.
Veterinary Point Of Care Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.8 billion
Estimated market size in 2026
USD 3.1 billion
Projected market size by 2033
USD 6.2 billion
Growth rate
CAGR of 10.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Animal, product, testing category, indication, sample, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
IDEXX Laboratories, Inc.; Zoetis; Heska Corporation (Antech); Virbac; Thermo Fisher Scientific, Inc.; Mindray; Woodley Equipment Company Ltd; FUJIFILM Corporation; Getein Biotech
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Point Of Care Diagnostics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary point of care diagnostics market report based on animal type, product, testing category, indication, sample type, end-use, and region:
-
Animal Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Companion Animals
-
Dogs
-
Cats
-
Horses
-
Others
-
-
Livestock Animals
-
Cattle
-
Swine
-
Poultry
-
Others
-
-
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Consumables, Reagents, & Kits
-
Instruments & Devices
-
-
Testing Category Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hematology
-
Diagnostic Imaging
-
Bacteriology
-
Virology
-
Cytology
-
Clinical Chemistry
-
Parasitology
-
Serology
-
Others
-
-
Sample Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Infectious Disease
-
General Ailments
-
Others
-
-
Indication Outlook (Revenue, USD Billion, 2021 - 2033)
-
Blood/Plasma/Serum
-
Urine
-
Fecal
-
Others
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Veterinary Hospitals & Clinics
-
Home Care Settings
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
Rest of EU
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
Rest of APAC
-
-
Latin America
-
Brazil
-
Argentina
-
Rest of LA
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Rest of MEA
-
-
Research Methodology
The veterinary point of care diagnostics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary point of care diagnostics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Animal
Revenue Capture Definition
Companion Animals
It includes pets receiving rapid in-clinic diagnostic testing for disease detection, health monitoring, and treatment decisions. Growth is driven by rising pet ownership, preventive healthcare, and increasing veterinary visits worldwide.
Dogs
Dogs represent the largest companion animal segment, utilizing point-of-care diagnostics for infectious diseases, hematology, clinical chemistry, endocrine disorders, and wellness screening in veterinary clinics and hospitals.
Cats
It covers diagnostic testing for feline infectious diseases, kidney disorders, diabetes, thyroid diseases, and routine wellness monitoring. Growing feline healthcare awareness supports increasing adoption of rapid diagnostic technologies.
Horses
It includes point-of-care diagnostics for equine infectious diseases, metabolic disorders, musculoskeletal injuries, reproductive health, and performance monitoring. Rapid testing supports timely clinical decisions in equine veterinary practice.
Others
It encompasses companion animals such as rabbits, ferrets, birds, reptiles, and exotic pets requiring rapid diagnostic testing for infectious diseases, wellness evaluation, and specialized veterinary healthcare management.
Livestock Animals
It includes farm animals undergoing point-of-care testing for disease surveillance, herd health management, reproductive monitoring, and food safety. Rapid diagnostics improve productivity while minimizing disease outbreaks and economic losses.
Cattle
It covers rapid diagnostics for mastitis, bovine respiratory disease, reproductive disorders, metabolic diseases, and parasitic infections. Point-of-care testing improves herd management, treatment decisions, and overall production efficiency.
Swine
It includes diagnostic testing for African swine fever, PRRS, influenza, bacterial infections, and reproductive diseases. Rapid diagnostics support biosecurity, disease containment, and efficient commercial swine production management.
Poultry
It covers rapid diagnostic solutions for avian influenza, Newcastle disease, salmonellosis, coccidiosis, and flock health monitoring. Early detection minimizes production losses and enhances poultry farm biosecurity measures.
Others
It includes sheep, goats, aquaculture species, and other food-producing animals requiring rapid diagnostic testing for infectious diseases, reproductive monitoring, and preventive healthcare across commercial farming operations.
Segment - Product
Revenue Capture Definition
Consumables, Reagents, & Kits
It includes disposable cartridges, assay kits, reagents, test strips, and calibration materials used with point-of-care diagnostic systems. These products generate recurring revenue through routine veterinary diagnostic testing.
Instruments & Devices
It covers analyzers, handheld diagnostic devices, imaging systems, readers, and portable testing platforms designed for rapid veterinary diagnosis, enabling immediate clinical decision-making across diverse healthcare settings.
Segment - Testing Category
Revenue Capture Definition
Hematology
It includes complete blood count analyzers and hematological testing used to evaluate blood cell abnormalities, anemia, infections, inflammation, and immune disorders, supporting rapid veterinary diagnosis and treatment planning.
Diagnostic Imaging
It covers portable ultrasound, digital radiography, and other imaging technologies used for rapid visualization of internal organs, musculoskeletal injuries, pregnancy, tumors, and disease diagnosis at the point of care.
Bacteriology
It includes rapid identification of bacterial pathogens causing respiratory, urinary, gastrointestinal, skin, and wound infections. Point-of-care bacteriology supports targeted antimicrobial therapy and improved infection management in animals.
Virology
It covers rapid detection of viral pathogens including parvovirus, feline leukemia virus, avian influenza, and PRRS. Early diagnosis enables prompt treatment, disease control, and outbreak prevention across veterinary settings.
Cytology
It includes microscopic examination of cells collected from tissues, fluids, or aspirates for diagnosing inflammation, infections, tumors, and other pathological conditions, enabling quick clinical evaluation and treatment decisions.
Clinical Chemistry
It covers biochemical analysis of blood and body fluids to assess liver, kidney, pancreatic, and metabolic function. Supports diagnosis, disease monitoring, and routine wellness screening in veterinary patients.
Parasitology
It includes diagnostic testing for internal and external parasites using fecal examinations, antigen tests, and microscopy. Supports parasite control programs and improves animal health and productivity across species.
Serology
It covers antibody and antigen detection tests used for infectious disease diagnosis, immunity assessment, vaccination monitoring, and epidemiological surveillance in companion animals and livestock populations.
Others
It includes molecular diagnostics, endocrine testing, coagulation analysis, biomarker assays, toxicology, and emerging point-of-care diagnostic technologies supporting comprehensive veterinary disease diagnosis and patient management.
Segment - Indication
Revenue Capture Definition
Infectious Disease
It covers rapid diagnosis of bacterial, viral, fungal, and parasitic infections affecting companion animals and livestock. Early detection enables timely treatment, improved biosecurity, and reduced disease transmission.
General Ailments
It includes diagnostics for metabolic disorders, endocrine diseases, organ dysfunction, inflammatory conditions, nutritional deficiencies, and routine health screening, supporting comprehensive veterinary clinical decision-making and patient monitoring.
Others
It encompasses oncology, reproductive health, cardiovascular disorders, neurological diseases, toxicology, and specialized diagnostic applications requiring rapid testing for effective veterinary disease management and treatment planning.
Segment- Sample Type
Revenue Capture Definition
Blood/Plasma/Serum
It represents the most widely used sample type for hematology, chemistry, serology, and immunoassays. Provides comprehensive clinical information for diagnosing systemic diseases and monitoring treatment response.
Urine
It includes urine samples analyzed for kidney function, urinary tract infections, diabetes, electrolyte disorders, and metabolic abnormalities. Urinalysis provides rapid, non-invasive diagnostic information in veterinary practice.
Fecal
It covers stool samples used for detecting intestinal parasites, gastrointestinal pathogens, digestive disorders, and microbiological abnormalities. Fecal testing supports preventive healthcare and disease surveillance in veterinary medicine.
Others
It includes saliva, tissue biopsies, nasal swabs, milk, synovial fluid, cerebrospinal fluid, and other biological specimens utilized for specialized point-of-care veterinary diagnostic testing applications.
Segment - Distribution Channel
Revenue Capture Definition
Veterinary Hospitals & Clinics
It represents the primary end users performing rapid diagnostic testing for disease detection, treatment monitoring, emergency care, and preventive health programs using advanced point-of-care diagnostic platforms.
Home Care Settings
It includes diagnostic devices used by pet owners or veterinarians outside clinical settings for chronic disease monitoring, wellness assessment, and telemedicine-supported healthcare, improving convenience and patient compliance.
Others
It includes veterinary diagnostic laboratories, research institutions, academic centers, livestock farms, mobile veterinary units, and animal shelters utilizing point-of-care diagnostics for disease surveillance, research, and routine healthcare management.
Estimation Model
Estimation Model
Methodology
Bottom-Up Market Estimation
The bottom-up approach estimates the market by aggregating revenues from manufacturers of point-of-care analyzers, consumables, reagents, and diagnostic kits across major regions.
Company revenues are validated through annual reports, product portfolios, distributor networks, and primary interviews with veterinarians, diagnostic laboratories, and industry experts.
Segment-level revenues are calculated by animal type, testing category, sample type, indication, and distribution channel, then consolidated to derive the global market size.
Top-Down Market Estimation Model
The top-down approach begins with the global veterinary diagnostics market and determines the proportion represented by point-of-care diagnostics. Shares are allocated using adoption rates, diagnostic procedure volumes, veterinary clinic penetration, livestock healthcare expenditure, companion animal ownership, and regional healthcare investments.
Historical trends, technological advancements, regulatory approvals, and macroeconomic indicators are incorporated to estimate revenues across products, testing categories, indications, animal types, and geographic markets.
Demand-Side Market Estimation Model
The demand-side model estimates market size based on diagnostic test volumes conducted in veterinary hospitals, clinics, and mobile practices.
Revenue calculations consider the number of veterinary visits, disease prevalence, diagnostic frequency, average selling prices of consumables and instruments, and replacement cycles.
Companion animal adoption, livestock disease surveillance, preventive healthcare programs, and increasing demand for rapid in-clinic diagnosis are integrated to forecast segment-wise and regional market growth.
Supply-Side & Utilization-Based Estimation
This model evaluates market size by assessing manufacturing capacity, product shipments, distribution coverage, installed instrument base, and consumable utilization rates.
Sales data from leading manufacturers, distributor inventories, import-export statistics, and procurement patterns are combined with instrument replacement and recurring reagent consumption.
The analysis also incorporates technological innovation, product launches, service contracts, and regional adoption rates to validate market estimates and long-term growth projections.
The Market Is Estimated Using A Combination Of Bottom-Up, Top-Down, Demand-Side, And Supply-Side Models. Bottom-Up Analysis Aggregates Company Revenues, While Top-Down Evaluates The Market From The Overall Veterinary Diagnostics Industry. Demand-Side Assessment Considers Diagnostic Testing Volumes And Veterinary Visits, Whereas Supply-Side Analysis Examines Product Shipments, Installed Instrument Base, Manufacturing Capacity, Consumable Utilization, And Regional Adoption Trends To Validate Market Estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Technology & Innovation Assessment
Detailed evaluation of emerging technologies including AI-enabled diagnostics, multiplex testing, portable analyzers, cloud connectivity, biosensors, digital imaging integration, and molecular point-of-care platforms, along with commercialization trends and adoption rates.
Helps stakeholders prioritize high-growth technologies, optimize R&D investments, identify future innovations, and align product development with evolving veterinary diagnostic requirements.
Market Opportunity Analysis
Customized analysis of emerging applications, underserved diagnostic segments, investment opportunities, market forecasts, regulatory developments, and future demand drivers supported by scenario-based forecasting models and primary industry insights.
Facilitates informed strategic decision-making, investment prioritization, risk mitigation, and long-term business planning while identifying sustainable revenue opportunities across the Veterinary Point-of-Care Diagnostics market.
Competitive Benchmarking
Comprehensive benchmarking of leading manufacturers based on product portfolio, technological platforms, pricing strategy, geographic presence, innovation pipeline, strategic partnerships, distribution network, and recent product launches across veterinary point-of-care diagnostics.
Enables identification of competitive positioning, technology gaps, differentiation opportunities, partnership prospects, and strategic initiatives to strengthen market entry, product development, and long-term competitive advantage.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
Key factors that are driving the veterinary point of care diagnostics market growth include increased pet expenditures, advances in test kits and equipment related to the rapid diagnosis of animal diseases, rise in overall zoonotic diseases, popularity of pet care, and a significant demand for point-of-care diagnostics are major factors driving this market.
North America market dominated, with a revenue share of 48.1% in 2025.
Key players include IDEXX Laboratories, Inc., Zoetis, Heska Corporation (Antech), Virbac, Thermo Fisher Scientific, Inc., Mindray, Woodley Equipment Company Ltd, FUJIFILM Corporation, Getein Biotech
Companion animals segment led the market with the largest revenue share of 59.9% in 2025.
Consumables, reagents, & kits segment led the market with the largest revenue share of 55.2% in 2025.
Parasitology segment led the market with the largest revenue share of 17.6% in 2025.
The global veterinary point of care diagnostics market size was valued at USD 2.8 billion in 2025 and is estimated at USD 3.1 billion in 2026.
The global veterinary point of care diagnostics market is expected to grow at a CAGR of 10.5% from 2026 to 2033 to reach USD 6.2 billion by 2033.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


