
- Home
- »
- Biotechnology
- »
-
Virus Filtration Market Size And Share Report, 2026-2033GVR Report cover
![Virus Filtration Market (2026 - 2033)Report]()
Virus Filtration Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Consumables, Instruments, Services), By Application (Biologicals, Medical Devices, Air Purification, Water Purification), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$6.1BMarket Estimate, 2026
$6.9BMarket Forecast, 2033
$16.9BCAGR, 2026–2033
13.6%Virus Filtration Market Summary
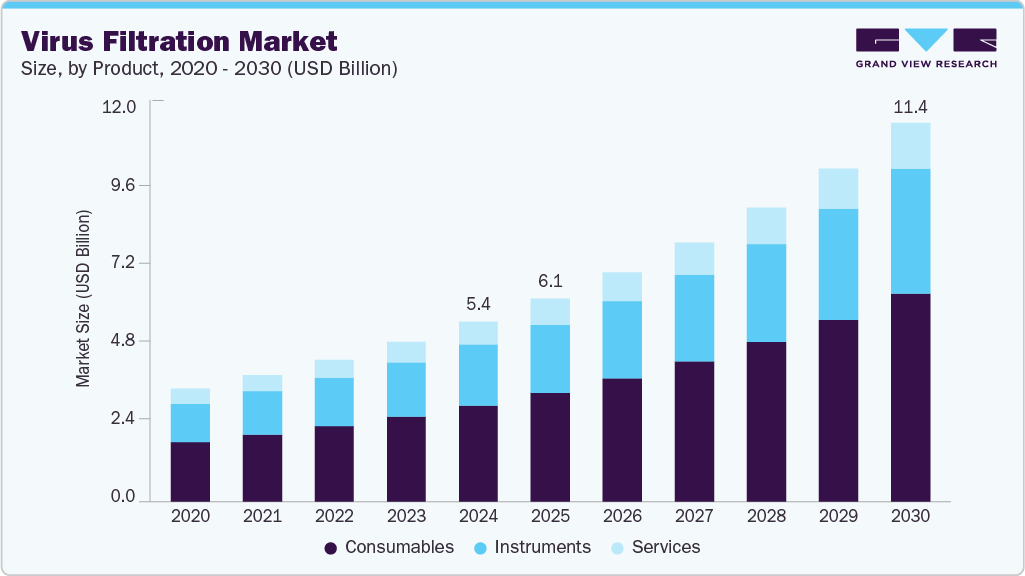
The global virus filtration market size was valued at USD 6.1 billion in 2025 and is projected to grow from USD 6.9 billion in 2026 to USD 16.9 billion by 2033, at a CAGR of 13.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.3% in 2025. The rising prevalence of chronic diseases such as cancer, diabetes, and autoimmune disorders is anticipated to propel the demand for biologics.

Key Market Trends & Insights
- By product: Consumables segment held the largest revenue share of over 53.6% in 2025.
- By application: Biologicals segment held the largest revenue share of over 57.6% in 2025.
- By end use: Biopharmaceutical & biotechnology companies segment held the largest revenue share of over 47.1% in 2025.
Regional Highlights
- Largest regional market: North America (42.3% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.1 Billion
- Estimated market size in 2026: USD 6.9 Billion
- Projected market size by 2033: USD 16.9 Billion
- CAGR (2026-2033): 13.6%
According to the World Health Organization (WHO), around 422 million people globally are affected by diabetes. The rising prevalence of chronic diseases such as cancer, diabetes, and autoimmune disorders is anticipated to propel the demand for biologics.The other significant factor anticipated to increase market growth is adherence to regulatory frameworks for drug development and production, such as Current Good Manufacturing Practice (cGMP) regulations. The manufacturers guarantee these products' virus safety through various quality control procedures, including monitoring and quality checking of raw materials, validating and implementing effective virus clearance technology, and validating the finished product for the absence of virus contamination. As a result, there is a huge market for these products in manufacturing and R&D.
Clinical Research Organizations (CROs) are collaborating with biotechnology and biopharmaceutical companies to develop novel drugs and therapies, which is also expected to support market growth. For instance, in May 2023, CRO firm IQVIA announced its partnership with RED, which aims to fight AIDS and strengthen the laboratory system. Biologics, such as biopharmaceutical drugs, require more time and money and are more complex to develop than chemical medications. Producing the same drug as the original is challenging, as every biopharmaceutical is distinct. The efficacy, quality, and safety of medicine could change due to a minor protein structure change.
Market Dynamics
The virus filtration market is witnessing robust growth, driven by increasing demand for biologics and biosimilars, stringent regulatory requirements for viral safety, and the expanding adoption of biopharmaceutical manufacturing. Rising investments in cell and gene therapies, coupled with advancements in filtration technologies and growing applications in vaccine production and plasma-derived therapeutics, are further supporting market expansion over the forecast period.
Technological advancements in virus filtration systems and membranes are driving market growth by improving viral clearance efficiency, process scalability, and product recovery rates. Manufacturers are developing advanced filtration membranes with higher throughput, enhanced fouling resistance, and superior virus retention capabilities to meet stringent biopharmaceutical safety requirements. In addition, the increasing adoption of single-use technologies and continuous bioprocessing is accelerating demand for advanced virus filtration solutions that offer greater operational flexibility, reduced contamination risks, and improved manufacturing efficiency.
For instance, in October 2024, Asahi Kasei Corporation announced the launch of the Planova FG1, a next-generation virus removal filter designed for biotherapeutic manufacturing. The newly introduced filter offers higher filtration flux, enhanced virus removal performance, and improved process robustness, enabling biopharmaceutical manufacturers to increase productivity while maintaining stringent viral safety standards. Such advancements are expected to support efficient large-scale biologics production and drive the adoption of advanced virus filtration technologies over the forecast period.
Membrane fouling and the limited lifespan of virus filters remain key challenges for the virus filtration market. The accumulation of proteins, cell debris, and other impurities on membrane surfaces can reduce filtration flux and process efficiency, necessitating frequent filter replacement and additional processing steps. These issues are particularly significant in the production of high-concentration biologics and complex biotherapeutics, where consistent filtration performance is essential.
Moreover, the limited durability of virus-filtration membranes increases operational costs and may lead to process interruptions, thereby affecting overall manufacturing productivity. As a result, biopharmaceutical manufacturers must invest in regular filter validation, monitoring, and replacement to ensure product quality and regulatory compliance, thereby increasing manufacturing costs and restraining market growth.
Analyst Perspective
The virus filtration market is expected to witness steady growth, driven by the increasing production of biologics, biosimilars, vaccines, and cell & gene therapies. Stringent regulatory requirements for viral safety and the growing emphasis on ensuring product purity in biopharmaceutical manufacturing are fueling demand for advanced virus filtration technologies. Continuous advancements in filtration membranes and process optimization, coupled with rising investments in bioprocessing and biomanufacturing, are expected to support long-term market expansion. Market participants are focusing on developing high-performance filtration solutions that enhance viral clearance efficiency, scalability, and overall manufacturing productivity.
Product Insights
Based on product, the consumables segment held the largest revenue share of over 53.6% in 2025, and it is expected to grow with the fastest CAGR over the forecast period. The demand for consumables such as reagents, kits, and membranes is anticipated to increase the production of vaccines, protein therapeutics, blood-related products, cellular therapy products, genetic therapy products, tissue products, and embryonic stem cell products. Several leading vendors, including Merck KGaA, Danaher, and Sartorius AG, provide a broad range of reagents, kits, and other consumables for virus filtration.
The instruments segment is expected to grow at a significant CAGR of 12.9% over the forecast period. The demand for instruments is increasing, fueled by the critical role of filtration systems in the growing production of vaccines and therapeutics. This rise is largely in response to the surge in illnesses that, if left untreated, could result in serious complications, hospitalizations, or even death. These systems are critical for purifying and clarifying materials, helping to remove impurities, ensure product safety, and support the manufacture of effective treatments. Filtration technologies often involve various filters, including membrane filtration, which uses a thin, semi-permeable membrane to separate molecules based on size and charge. Common techniques include microfiltration and tangential flow filtration (TFF).
The services segment is expected to grow from 2025 to 2030. This is due to biotechnology companies' increased outsourcing of R&D and drug development services from CROs. In addition, CROs are collaborating with biotechnology and biopharmaceutical companies to develop novel drugs and therapies, which is expected to support the segment's growth.
Application Insights
Based on application, the biologicals segment held the largest revenue share of over 57.6% in 2025, and it is expected to grow with the fastest CAGR over the forecast period. Biologicals are medicines from living organisms, including microorganisms, plants, and animals. They are increasingly important in the pharmaceutical industry due to their ability to provide targeted, precise, and personalized treatments, often with fewer side effects than traditional drugs. Key biological vaccines treat diseases such as measles, diphtheria, tetanus, mumps, hepatitis B, rubella (MMR), smallpox, polio, chickenpox, and influenza. According to the World Health Organization in 2022, around 254 million individuals were living with chronic hepatitis B, with approximately 1.2 million new cases reported each year. These rising health challenges have significantly increased the demand for biologicals, which in turn is driving the growing need for virus filtration solutions.
The medical devices segment is expected to grow significantly over the forecast period. The growth is driven by the increasing demand for medical devices due to the increasing aging global population, a rising incidence of chronic diseases, advancements in medical technology, and improved healthcare awareness and accessibility.
End-use Insights
Based on end use, the biopharmaceutical & biotechnology companies segment held the largest revenue share of over 47.1% in 2025. The increasing R&D activities, production of biologics, and growth in the biopharmaceutical industry drive the demand. Some drivers are increasing demand for innovative drugs and vaccines, scientific research and development advancements, and supportive governmental schemes and policies.
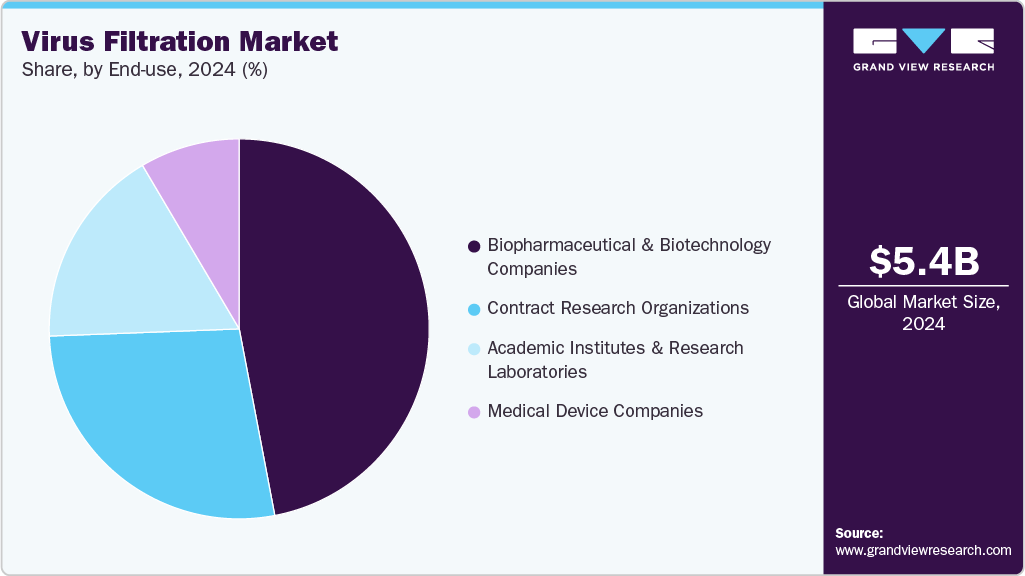
The Contract Research Organizations (CRO) sector is expected to grow at the fastest CAGR over the forecast period. The demand is driven by pharmaceutical, biotechnology, and medical device companies that opt for specialized research services on a contractual basis as it leverages cost savings, accesses specialized expertise, and gains flexibility in their research and development (R&D) processes. The medical device companies segment is projected to witness a significant CAGR during the forecast period. Viral removal products are widely used in various medical devices, including anesthesia systems and ventilators.
Regional Insights
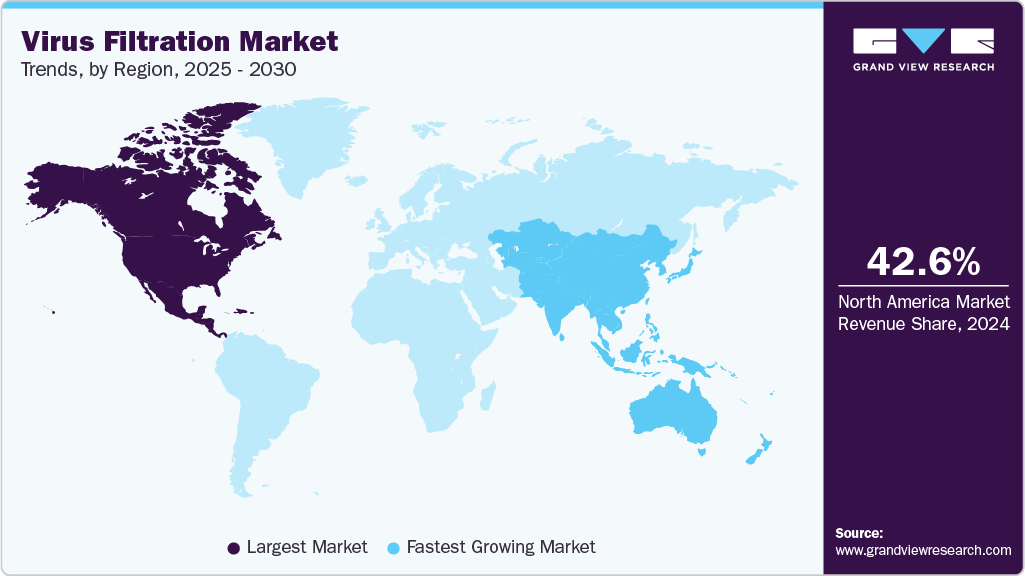
North America dominated the virus filtration market with the largest revenue share of 42.3% in 2025. The established biotechnology and biopharmaceutical sectors in the U.S. have increased the region's demand for advanced virus filtration products for research and development and biologics manufacturing. The increasing prevalence of chronic diseases further drives the market growth in the region.
U.S. Virus Filtration Market Trends
The virus filtration market in the U.S. held the largest share in the North America region in 2025. Major research and advancements by biopharmaceutical companies in the country drive the demand for virus filtration. For instance, in February 2025, Gilead Sciences revealed that the FDA had accepted its New Drug Applications for lenacapavir, an injectable HIV-1 capsid inhibitor for preventing HIV as PrEP,
Europe Virus Filtration Market Trends
The Europe Virus Filtration Market held a substantial market share in 2024. The demand is largely driven by the growing biopharmaceutical industry, the rising need for viral safety in biologics production, and better protection from chronic diseases. This is further supported by a strong emphasis on R&D, especially in countries such as Germany, the UK, and France.
Asia Pacific Virus Filtration Market Trends
The Asia Pacific virus filtration market is expected to grow at the fastest CAGR of 15.0% over the forecast period. The presence of untapped growth opportunities in the rapidly growing Asian economies such as China, India, Japan, and Indonesia is estimated to propel regional growth. Rising government support for industrialization, the growing presence of CROs, the availability of labor at low cost, and a relatively less stringent regulatory environment are attracting manufacturers of biologics and medical devices for market expansion in these regions. For instance, in April 2025, a Japan-based company, Asahi Kasei Corporation, launched, unifying its bioprocess operations under one entity, including virus removal filters such as Planova and BioOptimal Microfilters, CDMO services from Bionova Scientific, CRO testing services from ViruSure, and Bionique Testing Laboratories.
The China virus filtration market led the Asia Pacific market with the largest revenue share in 2024. China is making substantial investments in research and development, driving rapid growth in its biopharmaceutical sector. This expansion has heightened the need for virus filtration to maintain the safety and efficacy of its products.
Key Virus Filtration Company Insights
Some major companies in the virus filtration market are Merck KGaA; Danaher, Sartorius AG; and Thermo Fisher Scientific Inc.; among others. The rise in competition is leading to rapid technological advancements and companies are constantly working towards the improvement of their products with a major focus on research and development. The market players are indulging in developing new and better virus filtration. Major manufacturers provide advanced products through strong distribution channels across the globe.
-
Merck KGaA provides virus filtration solutions, offering advanced membrane filters and integrated systems for biopharmaceutical manufacturing. Its technologies ensure viral safety, regulatory compliance, and process efficiency, supporting the production of vaccines, monoclonal antibodies, and other biologics globally.
-
Danaher, through its life sciences subsidiaries such as Pall Corporation and Cytiva, provides virus filtration technologies essential for ensuring the safety of biopharmaceutical products. Its solutions support efficient, scalable filtration processes for producing vaccines, biologics, and gene therapies.
Key Virus Filtration Companies:
The following key companies have been profiled for this study on the virus filtration market.
-
Merck KGaA
-
Danaher
-
Sartorius AG
-
Thermo Fisher Scientific Inc.
-
GE HealthCare
-
Charles River Laboratories
-
Asahi Kasei Medical Co., Ltd.
-
WuXi AppTec
-
Lonza
-
Clean Biologics
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Merck KGaA, Danaher, Sartorius AG, Thermo Fisher Scientific, etc.)
- Focus on expanding virus filtration portfolios through advanced membrane technologies, integrated bioprocessing solutions, and end-to-end biologics manufacturing support.
- Extensive expertise in regulatory compliance, process validation, and high-performance virus filtration technologies for commercial-scale production.
- Exposure to stringent regulatory requirements, supply chain disruptions, and increasing competition from specialized filtration technology providers.
Emerging Players (Clean Biologics, Asahi Kasei Medical Co., Ltd., WuXi AppTec )
- Focus on specialized virus safety testing, filtration validation, and contract development and manufacturing services for biologics developers.
- Flexible and customer-centric service model tailored to early-stage and mid-sized biopharmaceutical companies.
- Limited global scale and financial resources compared to large integrated bioprocessing companies.
Recent Developments
- In May 2025, Duoning Biotech acquired a controlling stake in Conwell Solution to strengthen its presence in the virus filtration segment and expand its bioprocessing capabilities. The acquisition enhanced the company's integrated one-stop bioprocessing platform and broadened its downstream product portfolio.
Virus Filtration Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.1 billion
Estimated market size in 2026
USD 6.9 billion
Projected market size by 2033
USD 16.9 billion
Growth rate
CAGR of 13.6% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, and Kuwait
Key companies profiled
Merck KGaA; Danaher; Sartorius AG; Thermo Fisher Scientific Inc.; GE HealthCare; Charles River Laboratories; Asahi Kasei Medical Co., Ltd.; WuXi AppTec; Lonza; Clean Biologics
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Virus Filtration Market Report Segmentation
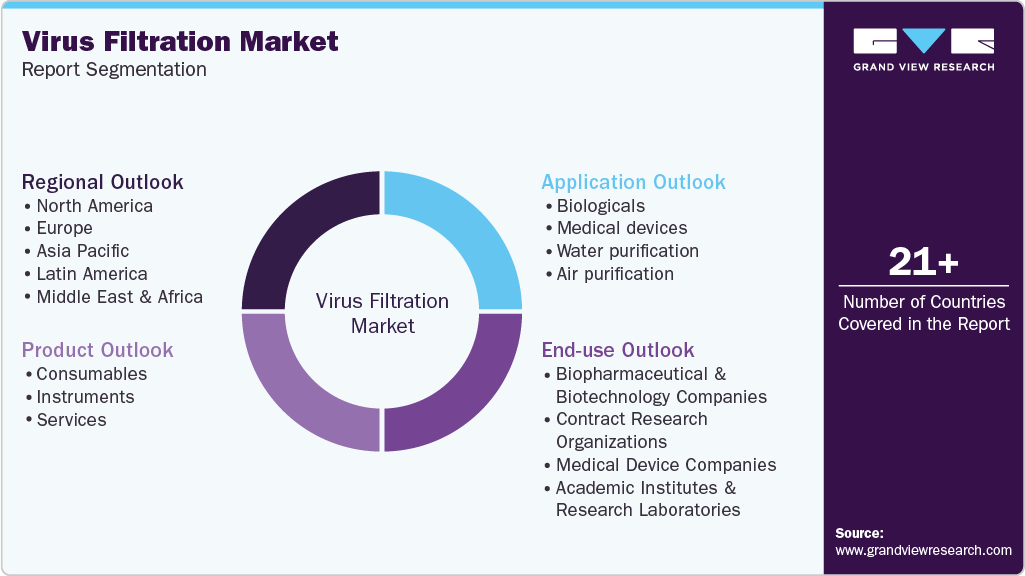
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global virus filtration market report based on product, application, end-use, and region:
-
Product Outlook (Revenue, USD Million; 2021 - 2033)
-
Consumables
-
Kits and reagents
-
Others
-
-
Instruments
-
Filtration systems
-
Chromatography systems
-
-
Services
-
-
Application Outlook (Revenue, USD Million; 2021 - 2033)
-
Biologicals
-
Vaccines and therapeutics
-
Blood and blood products
-
Cellular and gene therapy products
-
Tissue and tissue products
-
Stem cell products
-
-
Medical devices
-
Water purification
-
Air purification
-
-
End-use Outlook (Revenue, USD Million; 2021 - 2033)
-
Biopharmaceutical & biotechnology companies
-
Contract research organizations
-
Medical device companies
-
Academic institutes & research laboratories
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The virus filtration market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each virus filtration segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Product
Revenue Capture Definition
Consumables
Revenue generated from single-use products routinely employed during virus filtration workflows to ensure viral clearance, product purity, and process efficiency. This segment includes kits and reagents used for virus removal, validation, integrity testing, and process optimization, as well as other consumable products such as filtration membranes, cartridges, filter assemblies, and related disposable components utilized across biopharmaceutical manufacturing and research applications.
Instruments
This segment captures income from equipment used to perform, monitor, and optimize virus filtration processes during biologics manufacturing. The segment encompasses filtration systems designed for virus removal and retention, along with chromatography systems employed in downstream purification workflows to enhance viral safety, product quality, and regulatory compliance.
Services
Market value in this category stems from contract and support services associated with virus filtration, including process development, viral clearance studies, validation testing, filtration optimization, analytical testing, and regulatory support services provided to biopharmaceutical manufacturers and research organizations.
Segment
Revenue Capture Definition
Biologicals
Revenue originates from the use of virus filtration products and services in the manufacturing and purification of biologic products to ensure viral safety and compliance with regulatory standards. This segment includes applications involving vaccines and therapeutics, blood and blood products, cellular and gene therapy products, tissue and tissue-derived products, and stem cell-based products, all of which require robust viral clearance processes during production.
Medical Devices
This segment reflects earnings from virus filtration technologies utilized in the manufacturing and sterilization processes of medical devices to minimize the risk of viral contamination and ensure product safety for clinical use.
Water Purification
Demand within this category is driven by the adoption of virus filtration systems for the removal of viral contaminants from water used in pharmaceutical manufacturing, laboratory operations, healthcare facilities, and other industrial applications requiring high-purity water.
Air Purification
Revenue generated from virus filtration solutions incorporated into air purification and environmental control systems to capture and remove airborne viral particles in biopharmaceutical facilities, healthcare settings, cleanrooms, and research laboratories.
Segment- End Use
Revenue Capture Definition
Biopharmaceutical & Biotechnology Companies
Revenue generated from virus filtration products and services utilized by biopharmaceutical and biotechnology companies during the development, manufacturing, and commercialization of biologics, vaccines, cell and gene therapies, and other advanced therapeutic products.
Contract Research Organizations
This segment captures income from virus filtration technologies employed by contract research organizations (CROs) and contract service providers offering viral safety testing, process development, analytical services, and outsourced bioprocessing support to life sciences companies.
Medical Device Companies
Market value in this category stems from the use of virus filtration solutions by medical device manufacturers to ensure product sterility, minimize contamination risks, and comply with regulatory quality requirements.
Academic Institutes & Research Laboratories
Revenue originates from virus filtration products and services used by universities, government laboratories, and research institutions engaged in virology, biologics research, vaccine development, and other life science investigations requiring viral containment and purification capabilities.
Estimation Model
Top-Down
Parent Market
Segmentation
Validation
Forecasting
Commodity Flow Analysis
Parent Market & Penetration-Based Analysis
Country-Level Segment Share Modeling
Data Traingulation & Validation Model
Forecasting & CAGR Modeling
Market size was estimated by analyzing revenues generated by key manufacturers of virus filtration products, including providers of filtration membranes, consumables, systems, and related services. Data were collected from company annual reports, investor presentations, product portfolios, and premium industry databases. Revenue contributions from private and regional companies were assessed through secondary research and validated through primary interviews to derive the overall market value.
The virus filtration market was evaluated within the broader life science tools market. Adoption rates of virus filtration technologies across biopharmaceutical manufacturing, vaccine production, blood and plasma processing, cell and gene therapy manufacturing, and research applications were analyzed to estimate the addressable market and segment-level opportunities.
Market shares for product, application, and end-use segments were derived using country-specific biopharmaceutical manufacturing capacity, life science research expenditure, biologics production volumes, regulatory compliance requirements, and adoption of advanced filtration technologies. Weighted average calculations were applied to determine regional and global segment distributions.
Market estimates were validated through triangulation of secondary research, primary interviews, company-level revenue assessments, biopharmaceutical production analysis, and end-user adoption trends to ensure consistency and accuracy across all market segments and geographies.
Market forecasts were developed using historical trends in biologics and vaccine production, growth in cell and gene therapy pipelines, increasing biopharmaceutical R&D investments, stringent regulatory requirements for viral safety, and technological advancements in filtration systems. Regression-based analysis and trend modeling were applied to project future market growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis for Virus Filtration Applications Across End-use Industries
Detailed cross-segmentation analysis across virus filtration applications including vaccines & therapeutics, blood & blood products, cellular and gene therapy products, tissue products, and stem cell products across biopharmaceutical companies, CROs, medical device companies, and academic research institutes. Analysis includes adoption trends, outsourcing patterns, and end-user demand dynamics by geography.
Enables clients to identify the highest-growth application-end-use combinations, evaluate commercialization opportunities in emerging biologics segments, prioritize target customer groups, and uncover whitespace opportunities across the virus-safety value chain.
Competitive Benchmarking & Technology Assessment for Virus Filtration Providers
Comprehensive benchmarking of key market participants based on virus filtration portfolio, membrane and filtration technologies, manufacturing footprint, pricing strategies, regulatory compliance capabilities, service offerings, strategic partnerships, and innovation pipelines. Assessment includes benchmarking across consumables, instruments, and service capabilities.
Helps clients assess competitive positioning, identify technology gaps and differentiation opportunities, benchmark best practices, evaluate partnership or acquisition prospects, and refine market entry and expansion strategies.
Regional Demand Assessment for Biologics Manufacturing & Virus Filtration Capacity
Customized regional and country-level assessment covering biologics manufacturing capacity, biopharmaceutical R&D investments, regulatory requirements for viral safety, CDMO/CRO ecosystem development, and adoption of virus filtration technologies across North America, Europe, Asia Pacific, Latin America, and MEA. Includes country-level demand forecasting for selected high-growth markets.
Supports identification of high-growth regional markets, assessment of manufacturing expansion opportunities, prioritization of geographic investments, and alignment of commercial strategies with evolving biologics production and regulatory trends.
Frequently Asked Questions About This Report
The global virus filtration market size was valued at USD 6.1 billion in 2025 and is expected to reach USD 6.9 billion in 2026.
Some key players operating in the virus filtration market include Sartorius AG, Merck KGaA, Parker Hannifin, Rad Source Technologies, Clean Cells, WuXi PharmaTech (Cayman) Inc., and Danaher.
Key factors that are driving the virus filtration market growth include the global rise in the number of pharmaceutical and biopharmaceutical companies, increasing investment in the life sciences sector, rise in the number of drug launches & approvals, increase in funding by government for the development of pharmaceutical and biopharmaceutical industries.
The biologicals segment held the largest revenue share of over 57.6% in 2025, and it is expected to grow with the fastest CAGR over the forecast period.
The biopharmaceutical & biotechnology companies segment held the largest revenue share of over 47.1% in 2025.
North America dominated with a 42.3% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Based on product, the consumables segment dominated the market with a share of 53.6% in 2025, and it is expected to grow with the fastest CAGR over the forecast period. This is attributable to their continuous usage by pharmaceutical and biopharmaceutical companies and rises in R&D spending for the purpose of new drug development.
The global virus filtration market is expected to grow at a compound annual growth rate of 13.6% from 2026 to 2033 to reach USD 16.9 billion by 2033.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs — add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


