
- Home
- »
- Advanced Interior Materials
- »
-
Water Quality Sensor Market Size, Share Report, 2026-2033GVR Report cover

Water Quality Sensor Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (TOC Sensor, Chlorine Residual Sensors, Turbidity Sensor, Conductivity Sensor, PH Sensor), By End-use (Industrial, Wastewater Management), By Region, And Segment Forecasts
Market Size, 2025
$6.2BMarket Estimate, 2026
$6.6BMarket Forecast, 2033
$11.5BCAGR, 2026–2033
8.3%Water Quality Sensor Market Summary
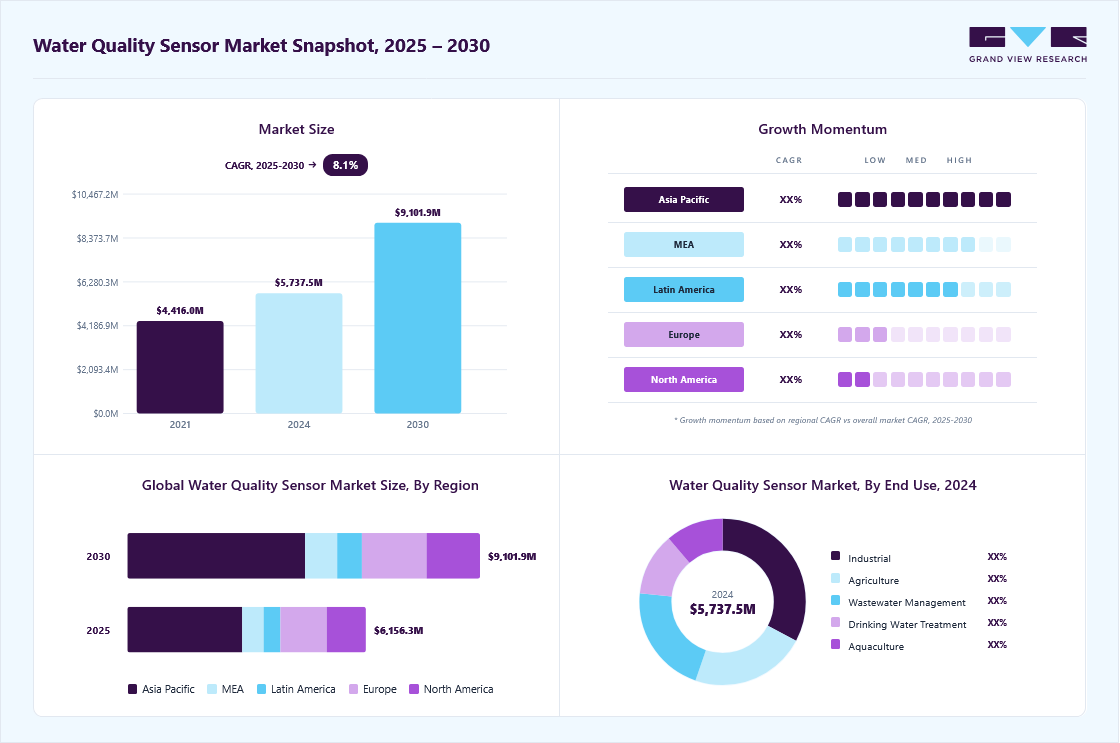
The global water quality sensor market size was valued at USD 6.2 billion in 2025 and is projected to grow from USD 6.6 billion in 2026 to USD 11.5 billion by 2033, at a CAGR of 8.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 48.2% in 2025. The market is witnessing robust growth, primarily fueled by increasing global awareness about environmental conservation and the critical importance of water quality monitoring for both human health and ecosystem sustainability.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: TOC Sensor segment led the market with the largest revenue share of 24.9% in 2025.
- By end use: Industrial segment led the market with the largest revenue share of 32.5% in 2025
Regional Highlights
- Largest regional market: Asia Pacific (48.2% revenue share, 2025)
- By country: China held the largest share in 2025
Market Size & Forecast
- Market size in 2025: USD 6.2 Billion
- Estimated market size in 2026: USD 6.6 Billion
- Projected market size by 2033: USD 11.5 Billion
- CAGR (2026-2033): 8.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Factors such as stricter government regulations regarding water pollution control, advancements in sensor technologies, and the rising demand from industries such as wastewater treatment, pharmaceuticals, and food and beverage are also contributing significantly to market expansion. This surge in demand for water quality sensors signifies a collective move towards more sustainable water resource management practices, reflecting an overarching trend towards environmental stewardship and the implementation of smart, technology-driven solutions to address global water quality challenges.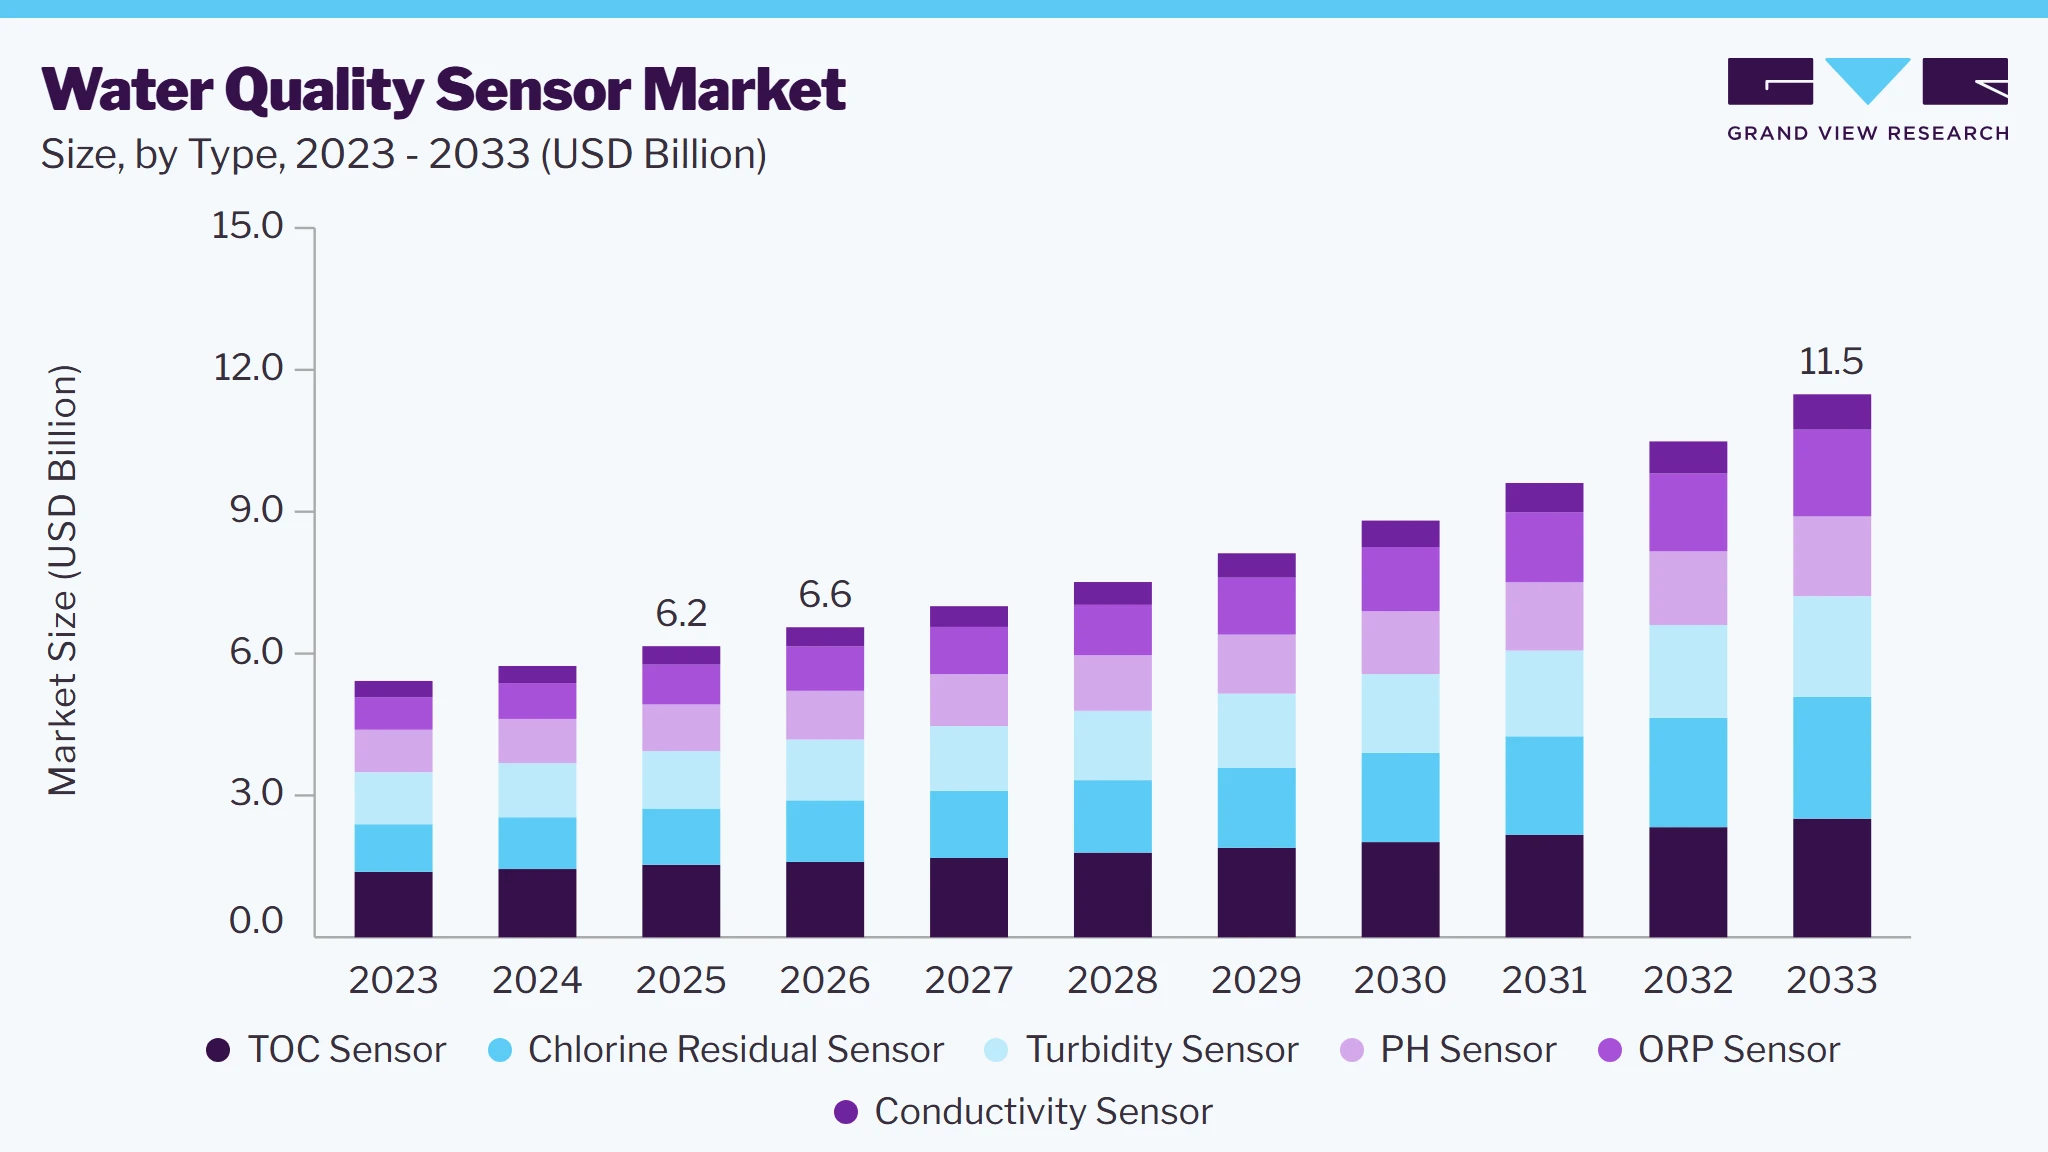 To learn more about this report, Download Free Sample Report
Water quality sensors play a crucial role in monitoring the conditions of various water bodies, ensuring that the water remains safe for drinking, recreational activities, and habitat for aquatic life. These sensors measure parameters such as temperature, pH levels, dissolved oxygen, turbidity, and the presence of harmful chemicals or pathogens. Employing advanced technologies, water quality sensors provide real-time data, enabling immediate responses to pollution incidents and helping in the effective management of water resources. This not only aids in preventing health hazards but also supports the sustainability of ecosystems by maintaining the balance and cleanliness of water environments.
Market Dynamics
The water quality sensor market is driven by the increasing need for continuous monitoring of water parameters across municipal, industrial, environmental, and commercial applications. Stringent water quality regulations and growing investments in water and wastewater infrastructure are accelerating the deployment of sensor-based monitoring systems. Industries such as pharmaceuticals, food & beverage, chemicals, and power generation are adopting advanced water quality sensors to ensure regulatory compliance and optimize process performance. Technological advancements, including multi-parameter sensors, IoT connectivity, wireless communication, and cloud-based data analytics, are improving monitoring accuracy and operational efficiency. The expanding focus on smart water management, environmental protection, and real-time data-driven decision-making continues to create growth opportunities for the water quality sensor market.
The growing need for continuous measurement of water quality parameters is driving the demand for water quality sensors across industrial, municipal, and environmental applications. Regulatory agencies are mandating continuous monitoring to ensure compliance with water quality and wastewater discharge standards. Utilities and industries are replacing conventional sampling methods with sensor-based monitoring systems to improve operational efficiency. The ability of advanced sensors to provide accurate, real-time data supports faster decision-making and preventive maintenance. This transition toward automated monitoring systems continues to strengthen market demand.
Water quality sensors are exposed to challenging operating conditions, including biofouling, scaling, chemical contamination, and fluctuating temperatures, which can affect measurement accuracy. Frequent calibration, cleaning, and maintenance are required to ensure reliable sensor performance. These requirements increase operational costs and system downtime, particularly in large-scale monitoring networks. Budget constraints among smaller utilities and industrial facilities can further limit the adoption of advanced sensor technologies. Such operational challenges remain a constraint for market growth.
Growing investments in smart water infrastructure are creating significant opportunities for the water quality sensor market. The integration of sensors with IoT platforms, cloud computing, and AI-based analytics enables remote monitoring, predictive maintenance, and improved water resource management. Governments and utilities are modernizing water distribution and wastewater treatment systems with connected monitoring technologies. Increasing smart city initiatives and digital transformation across water utilities are further expanding the adoption of intelligent sensor networks. These developments are expected to support long-term market growth.
Analyst Perspective
The global water quality sensor market is being influenced by increasing investments from governments, utilities, and industrial operators in continuous water quality monitoring to ensure regulatory compliance and efficient water resource management. Demand is being driven by expanding water and wastewater treatment infrastructure, increasing industrial water reuse, and growing concerns over water contamination across municipal, industrial, and environmental applications. In addition, the adoption of smart water management systems, IoT-enabled sensors, and real-time data analytics is enabling continuous monitoring, faster detection of water quality variations, and improved operational efficiency. Manufacturers are focusing on developing multi-parameter sensors with enhanced accuracy, durability, low maintenance requirements, and wireless connectivity to support remote monitoring applications. As water conservation, environmental sustainability, and digitalization of water infrastructure continue to gain importance globally, suppliers offering reliable, intelligent, and high-performance water quality sensing solutions are expected to benefit from sustained long-term market growth.
Type Insights
Based on type, the TOC Sensor segment led the market with the largest revenue share of 24.9% in 2025. TOC sensors are pivotal in assessing the organic matter in water, serving crucial roles in environmental monitoring, wastewater treatment, and ensuring the safety of drinking water. The demand is further propelled by technological advancements that have enhanced sensor accuracy, reliability, and cost-effectiveness, making them accessible for both industrial and municipal applications.
The market for chlorine residual sensors is experiencing significant growth due to the critical role these sensors play in water treatment and distribution systems. Chlorine residual sensors are essential for monitoring and controlling the levels of chlorine in water, ensuring it remains safe for consumption while preventing over or under-chlorination. This need spans across municipal water treatment plants, swimming pools, and various industrial water treatment applications.
End-use Insights
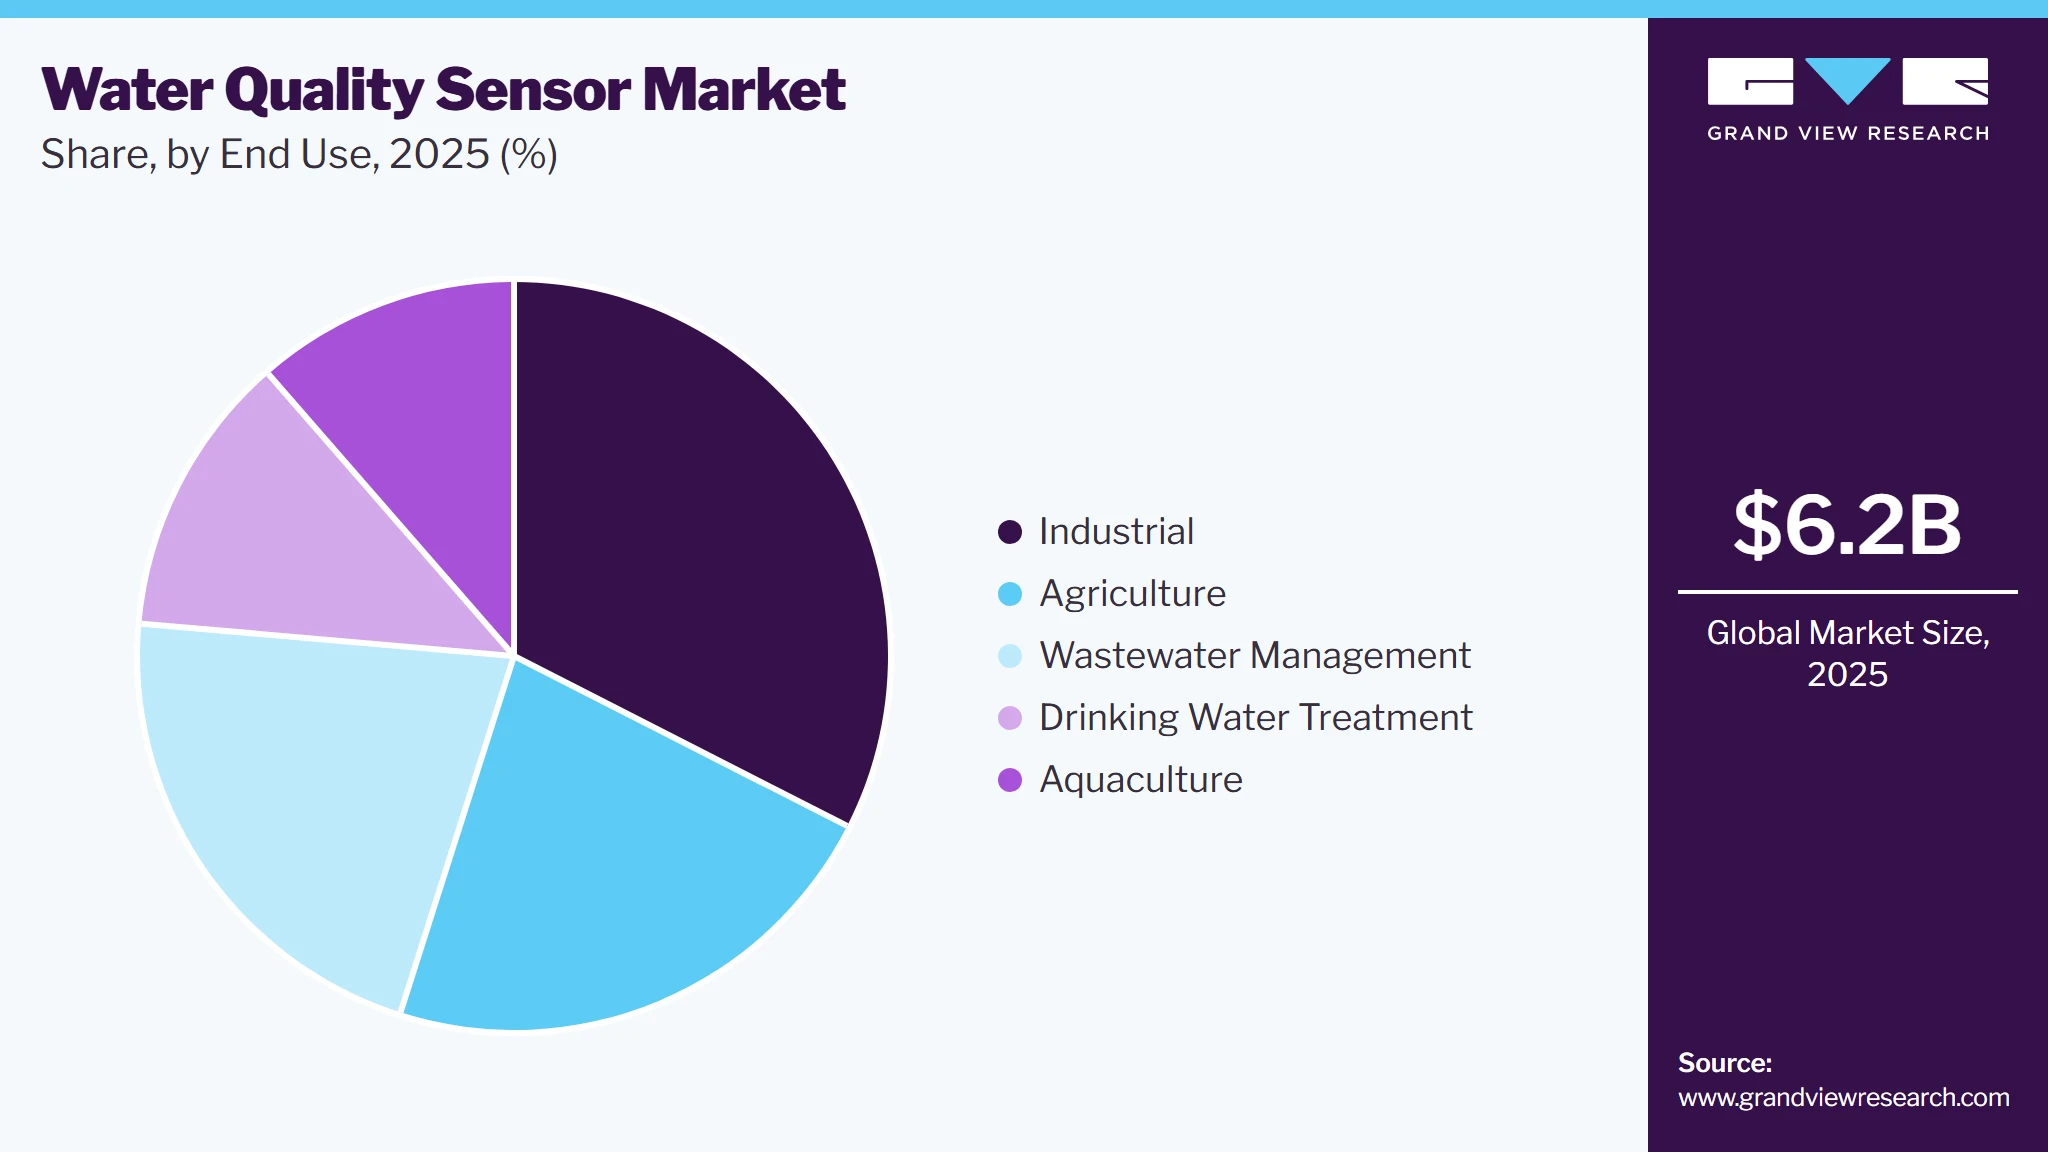
Based on end use, the industrial segment led the market with the largest revenue share of 32.5% in 2025. This segment is witnessing substantial growth, fueled by the pressing need for maintaining stringent water quality standards in various industrial processes. Industries such as pharmaceuticals, chemicals, food and beverage, and semiconductors, where water purity is critical, are increasingly investing in advanced water quality sensors. These sensors are essential for monitoring numerous parameters, including pH levels, dissolved oxygen, turbidity, and specific contaminants, ensuring the water used in processes meets the required standards and regulations.
 To learn more about this report, Download Free Sample Report
The wastewater management end-use segment is experiencing significant expansion, driven by the global emphasis on environmental sustainability and the need for effective wastewater treatment solutions. As urbanization and industrial activities surge, so does the volume of wastewater generated, necessitating advanced sensor technologies for monitoring and treating this water before discharge or reuse. Water quality sensors play a crucial role in this process, offering precise and continuous monitoring of various contaminants and parameters such as chemical oxygen demand (COD), biological oxygen demand (BOD), pH, and temperature.
Regional Insights
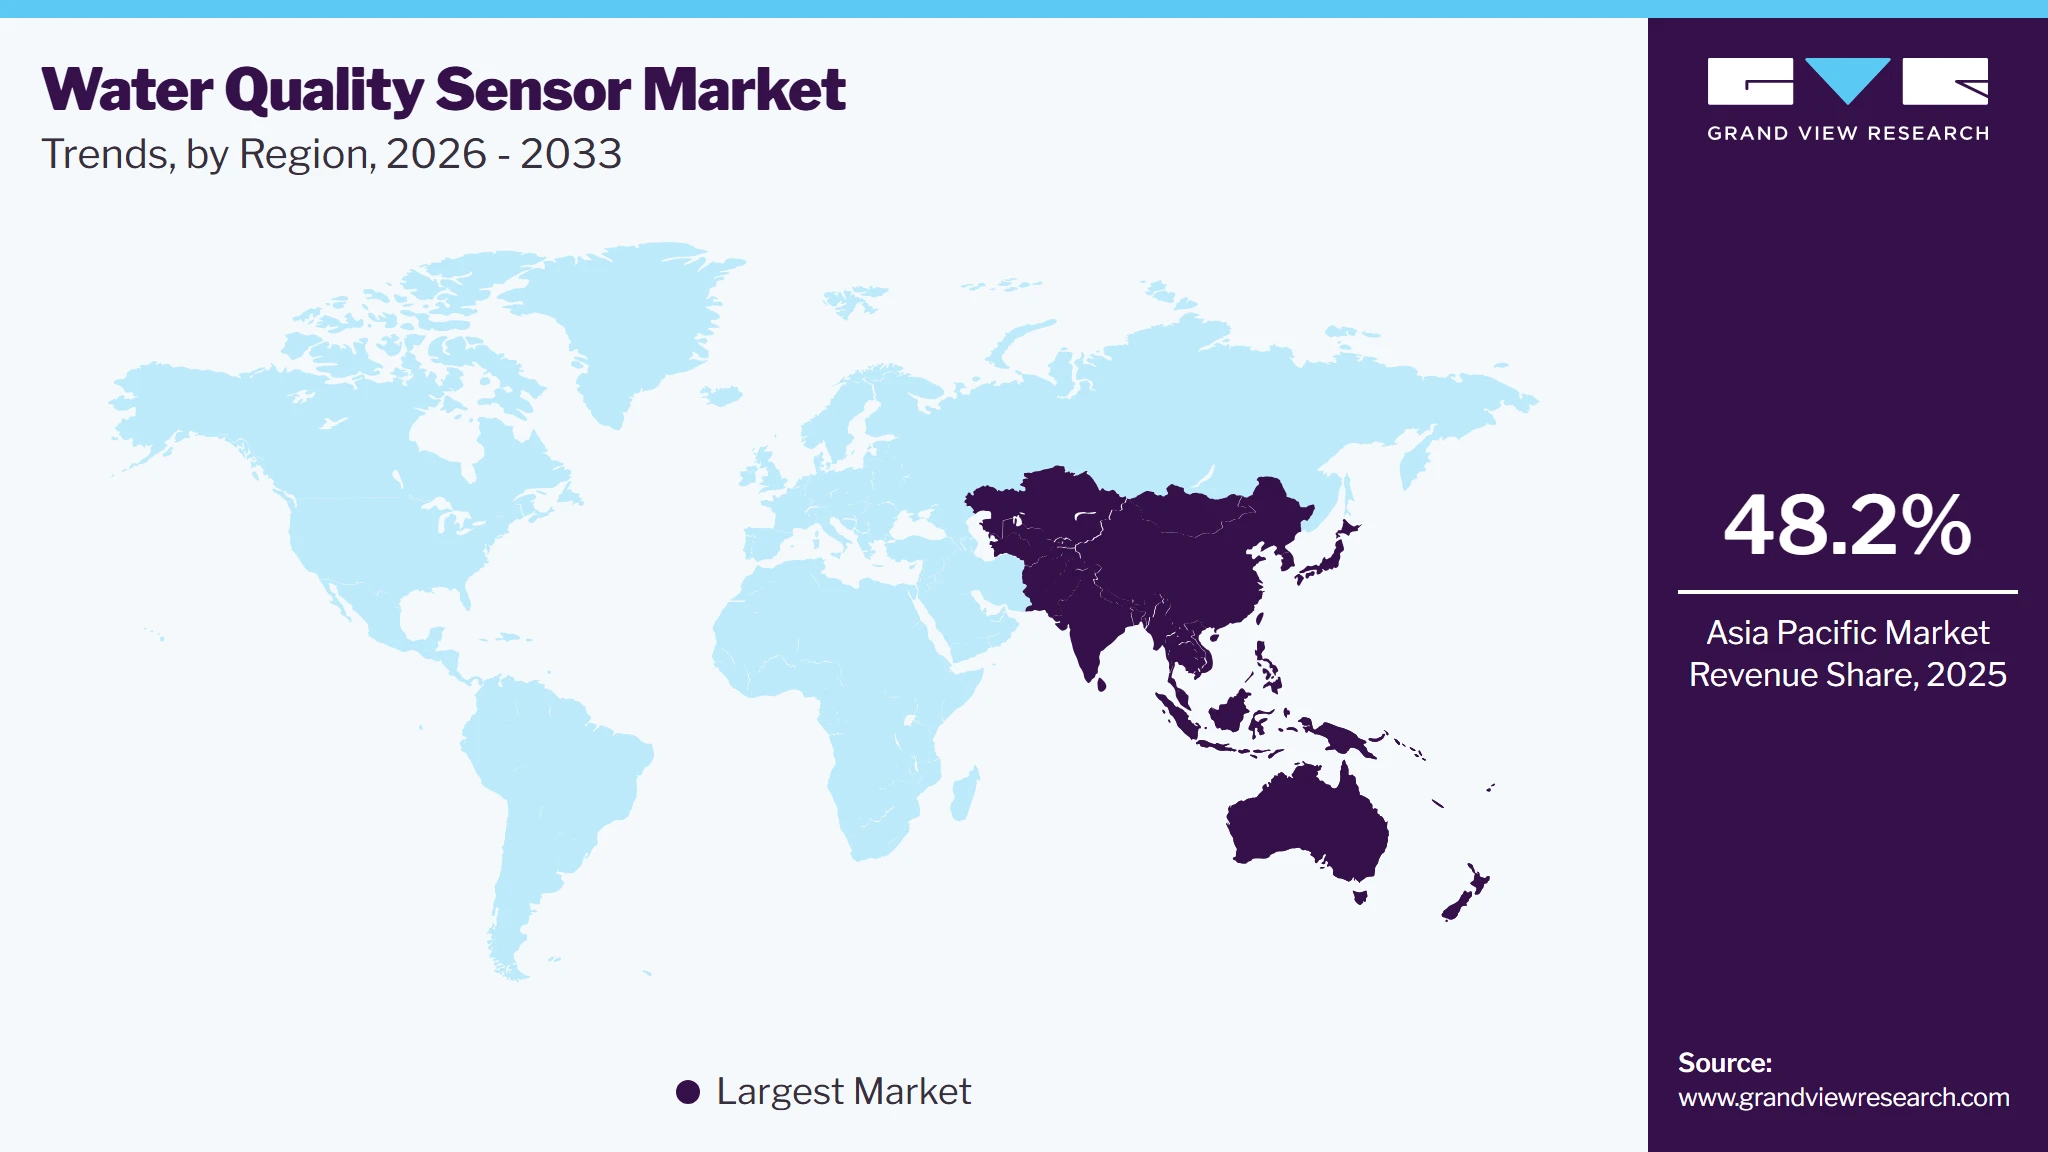
Asia Pacific dominated the water quality sensor market with the largest revenue share of 48.2% in 2025. The Asia Pacific region holds a significant share of the global market, primarily due to rapid industrialization, urbanization, and the growing awareness of environmental concerns in densely populated countries such as China and India. This region's vast agricultural activities, coupled with its formidable manufacturing and industrial sectors, generate substantial demand for water quality monitoring to prevent pollution and ensure the safety of water resources. Which will drive the demand for water quality sensors over the forecast period.
 To learn more about this report, Download Free Sample Report
China Water Quality Sensor Market Trends
The water quality sensor market in China held the largest share in the Asia Pacific region in 2025. China's water quality sensor market is experiencing substantial growth, underscored by the country's intensive efforts to tackle water pollution and enhance water resource management. The Chinese government has introduced stringent water quality standards and regulations to protect its water bodies, driving the demand for advanced water quality sensors across various sectors. These sensors are crucial for real-time monitoring and assessment of water quality, aiding in the detection and control of pollutants in diverse applications ranging from municipal wastewater treatment to industrial effluent management.
North America Water Quality Sensor Market Trends
The North America water quality sensor market is significantly driven by stringent regulatory standards, growing environmental concerns, and the need for efficient water management across various sectors. Industries such as oil and gas, pharmaceuticals, food and beverage, and agriculture, along with municipal water treatment facilities, are major contributors to the demand for these sensors. Their need for precise and real-time data to ensure compliance with water quality standards and to optimize water usage efficiently supports the market's expansion in North America.
Europe Water Quality Sensor Market Trends
The water quality sensor market in Europe is experiencing steady growth, largely driven by the region's stringent environmental regulations, high awareness regarding water conservation, and advanced technological landscape. Countries across Europe are increasingly investing in smart water management systems that incorporate advanced sensors for monitoring parameters such as pH, dissolved oxygen, turbidity, and various contaminants. This surge in demand is further supported by the growing need for efficient wastewater treatment processes, and the maintenance of high-quality standards for drinking water.
Key Water Quality Sensor Company Insights
Some of the key players operating in the market include Xylem Inc., Thermo Fisher Scientific Inc., and ABB Ltd. among others.
-
Xylem Inc. is committed to solving critical water and infrastructure challenges through innovation. The company wide range of products and services, including water pumps, treatment systems, and analytics solutions. Xylem offers an array of water quality sensors designed to address diverse needs across various sectors, including municipal, industrial, and environmental monitoring. The company plays a pivotal role in addressing the full cycle of water from collection, distribution, and usage, to the return of water back into the environment, focusing on the areas of water productivity, quality, and resilience.
-
Thermo Fisher Scientific Inc. specializes in manufacturing and distributing analytical instruments, equipment, reagents, consumables, software, and services tailored for research, manufacturing, analysis, discovery, and diagnostics. The company serves a broad spectrum of sectors, such as pharmaceuticals and biotechnology, academia and government, healthcare, and environmental industries.
Atlas Scientific LLC, TriOS Mess- und Datentechnik GmbH, and Eksoy Ltd., are some emerging market players.
-
Atlas Scientific LLC is engaged in the development of high-quality sensors and equipment designed for precision monitoring of pH, dissolved oxygen (DO), oxidation-reduction potential (ORP), electrical conductivity (EC), and various other water quality parameters. Atlas Scientific focuses on delivering innovative solutions that cater to both hobbyists and professional scientists, setting industry standards with its easy-to-integrate sensors and robust software interfaces.
Key Water Quality Sensor Companies:
The following key companies have been profiled for this study on the water quality sensor market.
- Thermo Fisher Scientific Inc.
- Hach Company (Danaher Corporation)
- Xylem Inc.
- Honeywell International Inc.
- ABB Ltd.
- Siemens AG
- Endress+Hauser Group
- Atlas Scientific LLC
- TriOS Mess- und Datentechnik GmbH
- OTT Hydromet (Hach Company)
- Libelium Comunicaciones Distribuidas S.L.
- Eksoy Ltd.
- SUEZ Water Technologies & Solutions
- Thames Water Utilities Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Thermo Fisher Scientific Inc., Hach Company (Danaher Corporation), Xylem Inc., ABB Ltd., Siemens AG, Endress+Hauser Group, Honeywell International Inc., SUEZ Water Technologies & Solutions)
- Focus on continuous innovation in multi-parameter water quality sensors, digital monitoring platforms, and integrated water analytics solutions.
- Expand global presence through strategic partnerships, acquisitions, and investments in smart water infrastructure and industrial automation.
- Strong global distribution networks, broad product portfolios, and established customer relationships across municipal and industrial sectors.
- Extensive R&D capabilities, proven sensor accuracy, regulatory expertise, and comprehensive after-sales service.
- Higher product and maintenance costs compared to regional competitors.
- Longer product development and commercialization cycles for advanced sensing technologies.
Emerging & Regional Players (e.g., Atlas Scientific LLC, TriOS Mess- und Datentechnik GmbH)
- Focus on specialized water quality sensing technologies for niche industrial, environmental, and research applications.
- Emphasize product customization, rapid innovation, and partnerships with regional distributors and system integrators.
- High flexibility in product development and strong expertise in application-specific sensing solutions.
- Ability to respond quickly to evolving customer requirements and emerging monitoring applications.
- Limited global market presence and smaller distribution networks than established manufacturers.
- Lower financial resources for large-scale expansion, marketing, and long-term R&D investments.
Recent Developments
-
In January 2024, ABB Ltd. announced its strategic acquisition of Real Tech Inc., a pioneering firm specializing in real-time water quality monitoring technology. This acquisition marks a significant expansion of ABB's portfolio into the burgeoning water quality management sector.
-
In February 2021, Yokogawa Electric Corporation announced the expansion of its water quality monitoring portfolio with the introduction of two innovative chlorine sensor units, FC800D and RC800D, which a reagent-type residual chlorine sensor unit tailored for precise.
Water Quality Sensor Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.2 billion
Estimated market size in 2026
USD 6.6 billion
Projected market size by 2033
USD 11.5 billion
Growth rate
CAGR of 8.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; UK; Spain; China; Japan; India; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Thermo Fisher Scientific Inc.; Hach Company (Danaher Corporation); Xylem Inc.; ABB Ltd.; Siemens AG; Endress+Hauser Group; Honeywell International Inc.; Atlas Scientific LLC; TriOS Mess- und Datentechnik GmbH; SUEZ Water Technologies & Solutions.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Water Quality Sensor Market Report Segmentation
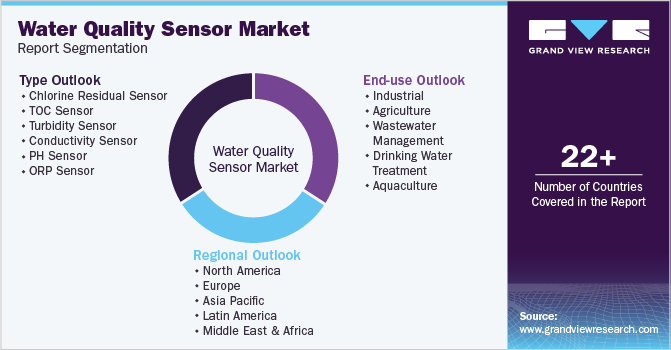
This report forecasts revenue growth at global, regional & country levels and analyzes the industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global water quality sensor market based on the type, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Chlorine Residual Sensor
-
TOC Sensor
-
Turbidity Sensor
-
Conductivity Sensor
-
PH Sensor
-
ORP Sensor
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Industrial
-
Agriculture
-
Wastewater Management
-
Drinking Water Treatment
-
Aquaculture
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The water quality sensor market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each water quality sensor segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue Capture Definition
Chlorine Residual Sensor
The segment refers to water quality sensors designed to measure free, total, or combined chlorine concentrations for water disinfection monitoring. The segment captures revenue generated from the sale of chlorine residual sensors across all end-use industries.
TOC Sensor
The segment refers to water quality sensors that measure total organic carbon (TOC) levels to assess organic contamination in water. The segment captures revenue generated from the sale of TOC sensors across all end-use industries.
Turbidity Sensor
The segment refers to water quality sensors used to measure the concentration of suspended particles and water clarity. The segment captures revenue generated from the sale of turbidity sensors across all end-use industries.
Conductivity Sensor
The segment refers to water quality sensors that measure the electrical conductivity of water to determine ionic concentration and water purity. The segment captures revenue generated from the sale of conductivity sensors across all end-use industries.
pH Sensor
The segment refers to water quality sensors designed to measure the acidity or alkalinity of water for process control and water quality assessment. The segment captures revenue generated from the sale of pH sensors across all end-use industries.
ORP Sensor
The segment refers to water quality sensors that measure oxidation-reduction potential (ORP) to evaluate disinfection efficiency and chemical activity in water. The segment captures revenue generated from the sale of ORP sensors across all end-use industries.
Segment - End Use
Revenue Capture Definition
Industrial
The segment captures revenue generated from water quality sensors supplied for industrial water treatment, process monitoring, cooling water systems, and wastewater management applications across manufacturing industries.
Agriculture
The segment captures revenue generated from water quality sensors supplied for irrigation water monitoring, hydroponics, livestock water management, and other agricultural applications.
Wastewater Management
The segment captures revenue generated from water quality sensors supplied for municipal and industrial wastewater collection, treatment, and discharge monitoring applications.
Drinking Water Treatment
The segment captures revenue generated from water quality sensors supplied for drinking water treatment plants, potable water distribution networks, and water quality compliance monitoring.
Aquaculture
The segment captures revenue generated from water quality sensors supplied for aquaculture applications, including fish farming, shrimp farming, hatcheries, and other aquatic cultivation systems.
Estimation Model
Layer Name
Key Question
Description
Water Quality Monitoring Demand Layer
Where are water quality sensors required?
Analyze demand across municipal water treatment, wastewater treatment, industrial processing, aquaculture, environmental monitoring, agriculture, food & beverage, pharmaceuticals, and other water-intensive industries. Assess water quality monitoring requirements, regulatory compliance, process control needs, and environmental protection initiatives to establish the addressable demand for water quality sensors.
Water Infrastructure & Environmental Investment Layer
Where is new equipment demand being created?
Evaluate investments in water treatment plants, wastewater facilities, industrial water management systems, desalination plants, environmental monitoring programs, and smart water infrastructure. Assess greenfield projects, capacity expansions, infrastructure modernization, and regulatory compliance initiatives that drive procurement of new water quality sensors.
Product Adoption Layer
Which water quality sensing technologies are being deployed?
Segment demand by sensor type, measurement parameter, installation type, monitoring application, and end-use industry. Apply adoption rates based on measurement accuracy, response time, operating environment, connectivity, maintenance requirements, and regulatory standards.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of water quality sensors by sensor type, application, end-use industry, and region. Quantify revenues generated exclusively from the sale of new water quality sensors supplied to utilities, industrial facilities, environmental agencies, OEMs, and system integrators.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
A competitive benchmarking analysis was conducted by evaluating established market participants based on product portfolio, sensor technologies, measurement capabilities, manufacturing footprint, strategic initiatives, financial strength, innovation focus, and competitive positioning within the global water quality sensor market.
This benchmarking enabled stakeholders to assess competitive strengths, identify product and technology differentiation opportunities, understand evolving industry strategies, and develop effective competitive positioning within the global water quality sensor market.
Regional Segmentation
A comprehensive regional analysis was conducted across major markets, highlighting water quality sensor adoption trends, regulatory frameworks, water infrastructure development, industrial demand, environmental monitoring initiatives, and country-level contributions influencing the global water quality sensor market.
The regional assessment enabled stakeholders to identify high-growth markets, refine expansion strategies, optimize resource allocation, and align product offerings with regional application requirements and regulatory standards.
Opportunity Assessment
A detailed opportunity assessment was conducted by evaluating advancements in water quality sensing technologies, increasing deployment of smart water quality sensing solutions, digital water management initiatives, expanding water and wastewater infrastructure, and emerging industrial and environmental monitoring applications across the global water quality sensor market.
This assessment enabled stakeholders to identify high-potential investment areas, align product development with evolving market requirements, and capitalize on growing demand for intelligent water quality sensing solutions across municipal, industrial, and environmental applications.
Frequently Asked Questions About This Report
Asia Pacific dominated the water quality sensor market with the largest revenue share of 48.2% in 2025
Some of the key players operating in the water quality sensor market include Thermo Fisher Scientific Inc., Hach Company (Danaher Corporation, Xylem Inc., Honeywell International Inc., ABB Ltd., Siemens AG, Endress+Hauser Group, Atlas Scientific LLC, TriOS Mess- und Datentechnik GmbH, OTT Hydromet (Hach Company), Libelium Comunicaciones Distribuidas S.L., Eksoy Ltd., SUEZ Water Technologies & Solutions, Thames Water Utilities Limited.
The water quality sensor market is witnessing robust growth, primarily fueled by the increasing global emphasis on water conservation and the need to monitor and control water pollution. Growing awareness regarding the health impacts of contaminated water and stringent government regulations regarding water quality standards have also significantly contributed.
The global water quality sensor market size was estimated at USD 6.2 billion in 2025 and is projected to grow from USD 6.6 billion in 2026.
The global water quality sensor market, in terms of revenue, is expected to grow at a compound annual growth rate of 8.3% from 2026 to 2033 to reach USD 11.5 billion by 2033.
Based on type, the TOC Sensor segment led the market with the largest revenue share of 24.9% in 2025.
Based on end use, the industrial segment led the market with the largest revenue share of 32.5% in 2025.
Based on end use, the wastewater management segment is expected to register the highest CAGR of 9.3% from 2026 to 2033.
Based on type, the chlorine residual sensor segment is expected to register the highest CAGR of 10.3% from 2026 to 2033.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


