
- Home
- »
- Organic Chemicals
- »
-
Acetone Market Size, Share And Trends Report, 2026-2033GVR Report cover

Acetone Market (2026 - 2033)
Size, Share & Trends Analysis Report By Grade, By Application (Solvents, Methyl Methacrylate, Bisphenol A), By Distribution Channel (Manufacturer to Distributor, Manufacturer to End User), By Region, And Segment Forecasts
Market Size, 2025
$6.9BMarket Estimate, 2026
$7.5BMarket Forecast, 2033
$13.4BCAGR, 2026–2033
8.7%Acetone Market Summary
The global acetone market size was valued at USD 6.9 billion in 2025 and is projected to grow from USD 7.5 billion in 2026 to USD 13.4 billion by 2033, at a CAGR of 8.7% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 47.8% in 2025. The increasing use of acetone in the production of personal care products, along with the growth of end-use industries such as paints and coatings and pharmaceuticals in emerging economies in the Asia Pacific region, is expected to drive market growth during the forecast period.
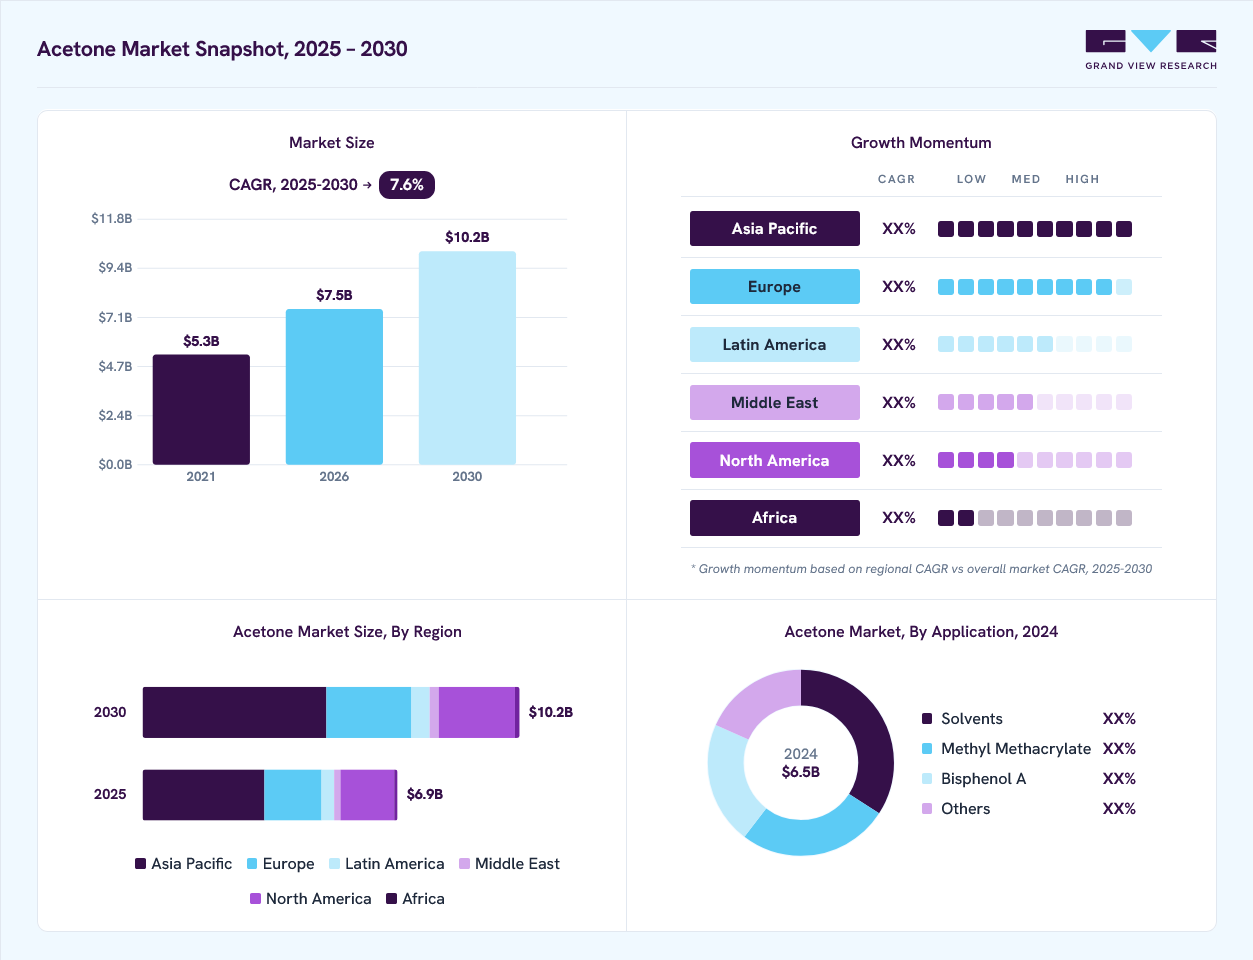 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By grade: Technical grade segment dominated the market, with a revenue share of 97.1% in 2025.
- By application: Solvents segment held the largest market share of 33.7% in 2025.
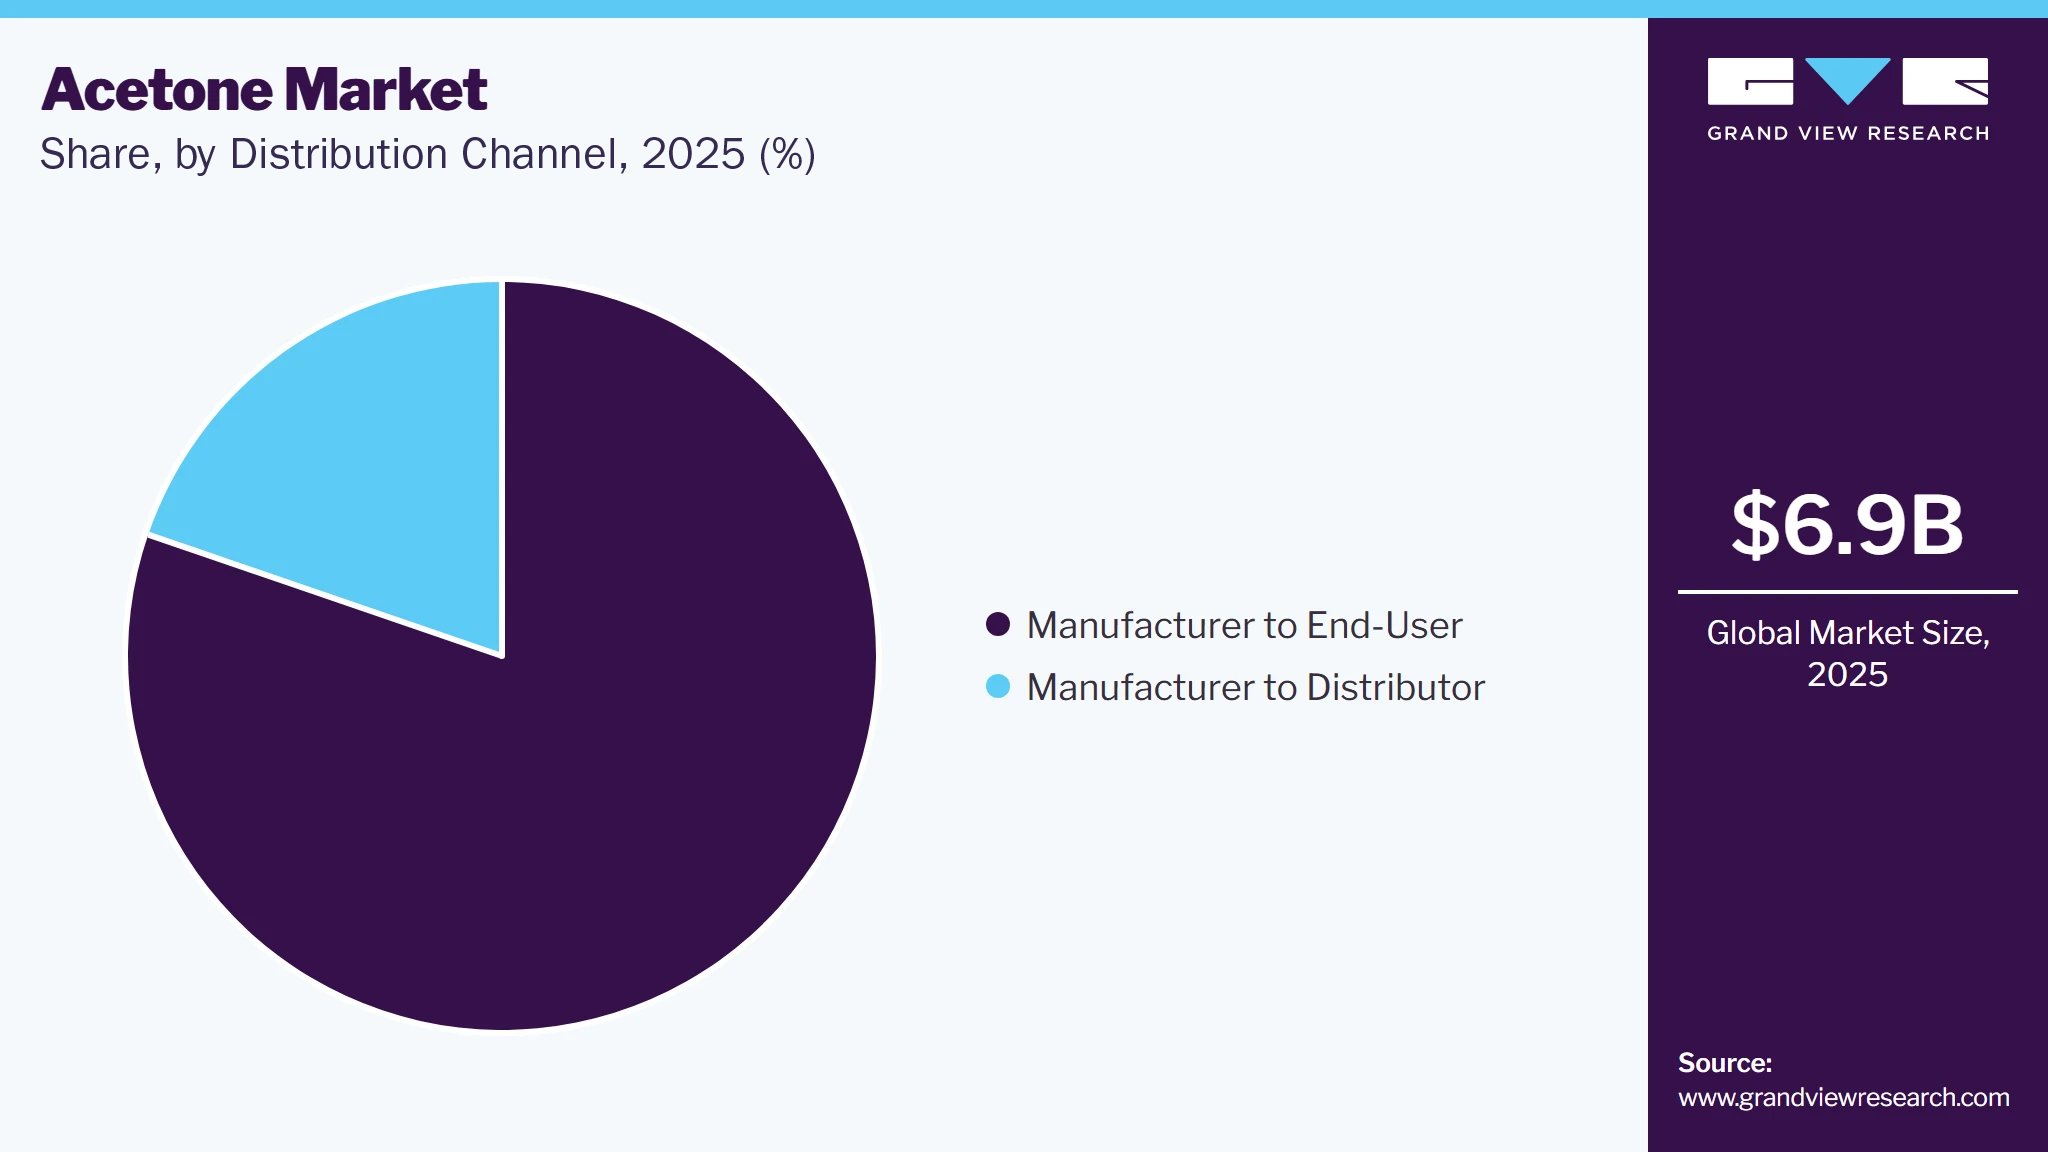
- By distribution channel: Manufacturer to end-user segment held the largest revenue share of 80.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (47.8% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.9 Billion
- Estimated market size in 2026: USD 7.5 Billion
- Projected market size by 2033: USD 13.4 Billion
- CAGR (2026-2033): 8.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The most common and significant aliphatic ketone is 2-propanone, known as acetone or dimethyl ketone. Acetone is produced by alkylating benzene with propylene to form cumene, which is then subjected to an air oxidation process that yields acetone and phenol. Typically, facilities that produce acetone also integrate phenol production. Acetone is widely used to manufacture bisphenol-A (BPA), methyl methacrylate (MMA), and solvents for rubber, oils, lacquers, resins, fats, cement, and waxes.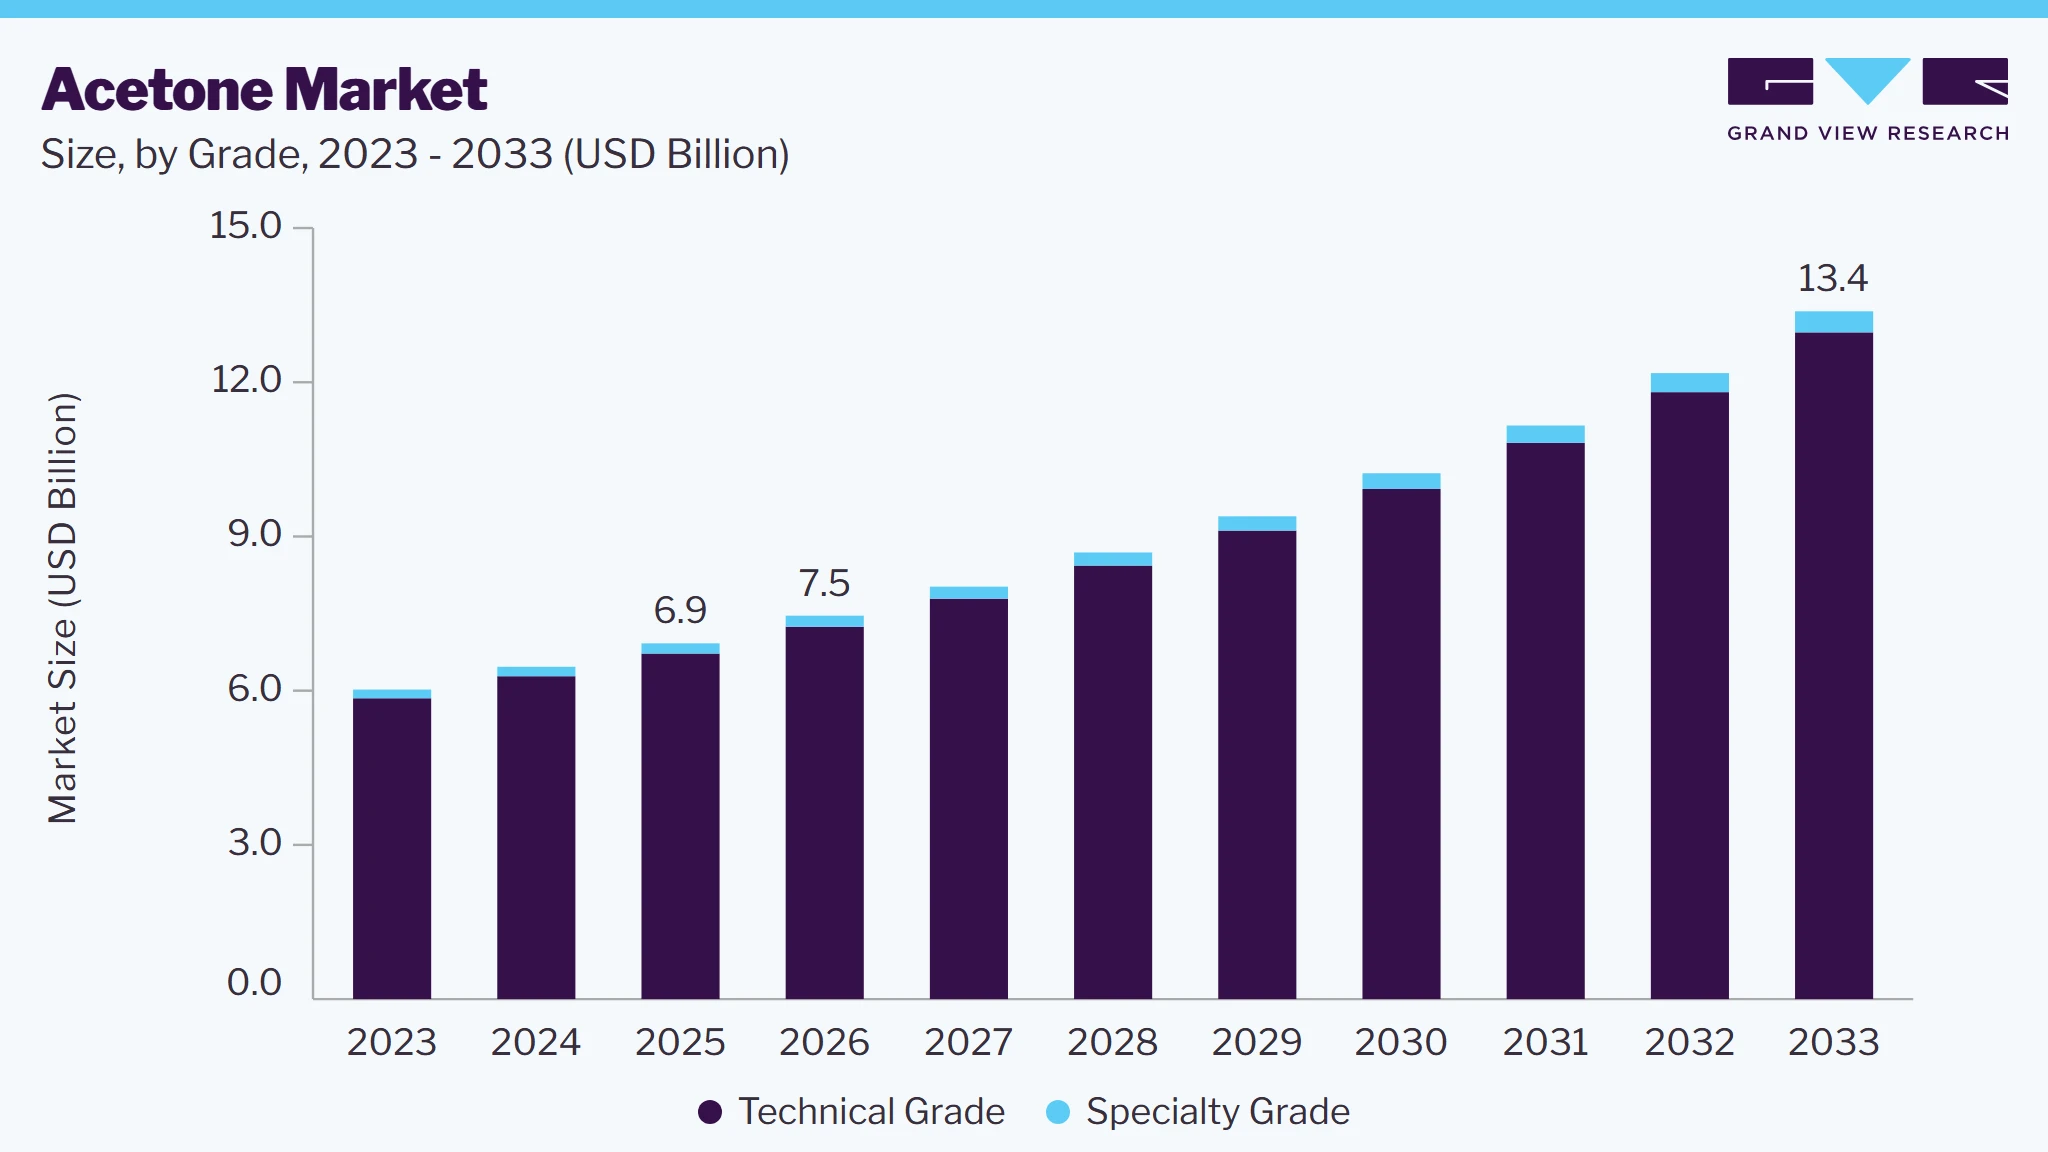 To learn more about this report, Download Free Sample Report
The product is used to manufacture BPA, which is then used to produce polycarbonate. Polycarbonate has various applications in the automotive industry, including windows, sunroofs, headlights, and taillights. The increasing demand for polycarbonates is expected to drive up the production of BPA.
Acetone is widely used in the industrial sector for various applications, including paints and coatings, adhesives, disinfectants, and thinners. It serves as a solvent in pharmaceutical products, such as hand sanitizers, and acts as an excipient in medications. Acetone is primarily employed as a solvent for plastics, resins, varnishes, lacquers, fats, oils, rubber cement, and waxes. Additionally, it is utilized as an intermediate in producing polymethyl methacrylate (PMMA) within the industrial sector.
Acetone is a solvent commonly used in the cosmetics industry. It is the primary ingredient in nail polish remover and various skin cream products. Additionally, it is utilized in skin peeling treatments to help combat acne. The growing demand for acetone in these applications will drive market growth in the coming years.
Market Dynamics
The acetone market is supported by its critical role as an intermediate and solvent across multiple industrial value chains. Demand continues to rise due to increasing consumption of bisphenol A and methyl methacrylate, which serve as essential raw materials for manufacturing polycarbonate plastics, epoxy resins, and acrylic products used in automotive, construction, electronics, and consumer goods. Expanding pharmaceutical production and the growing use of acetone in paints, coatings, adhesives, and personal care formulations further strengthen market demand. However, market performance remains influenced by fluctuations in feedstock prices, particularly propylene, as well as changing energy costs that affect production economics. Environmental regulations governing volatile organic compound emissions are encouraging manufacturers to adopt cleaner production processes and improve operational efficiency. At the same time, investments in sustainable manufacturing technologies, including bio-based acetone production, are creating new growth opportunities. Rapid industrialization, infrastructure development, and increasing chemical manufacturing capacity in emerging economies are expected to support long-term market expansion while enhancing supply chain resilience and product innovation.
The increasing consumption of bisphenol A (BPA) and methyl methacrylate (MMA) remains one of the primary factors driving the acetone market. Acetone serves as a critical feedstock in the production of BPA and MMA, both of which are extensively used in manufacturing polycarbonate plastics, epoxy resins, and acrylic materials. These materials are widely adopted across automotive, construction, electrical and electronics, medical devices, and consumer goods industries due to their strength, transparency, durability, and lightweight characteristics. As manufacturers continue to prioritize high-performance materials that improve product functionality and reduce overall weight, the demand for acetone-based intermediates continues to expand.
Rapid industrialization, urban infrastructure development, and increasing investments in transportation and electronics manufacturing are further accelerating the consumption of BPA- and MMA-derived products. The growing adoption of electric vehicles, advanced electronic components, and modern construction materials has significantly increased the need for engineering plastics and specialty resins. Chemical producers are expanding production capacities and strengthening supply networks to meet rising downstream demand, reinforcing acetone's strategic importance within the global petrochemical value chain.
The increasing availability of alternative solvents and raw materials presents a significant restraint to the growth of the acetone market. Several industries, including paints and coatings, pharmaceuticals, electronics, and chemical processing, are gradually adopting substitute solvents such as ethyl acetate, methyl ethyl ketone (MEK), isopropyl alcohol (IPA), and water-based formulations, depending on application requirements and regulatory considerations. Advances in formulation technologies have enabled manufacturers to reduce dependence on acetone in certain industrial processes while maintaining product performance, particularly in applications where lower emissions, improved safety profiles, or enhanced compatibility with specific materials are required.
The transition toward sustainable chemical manufacturing presents a significant growth opportunity for the acetone market. Increasing corporate commitments to carbon reduction, circular economy initiatives, and environmental stewardship are encouraging manufacturers to invest in bio-based acetone production technologies that utilize renewable feedstocks instead of conventional fossil-derived raw materials. These innovations help reduce greenhouse gas emissions while addressing evolving customer preferences for sustainable chemical products across pharmaceuticals, cosmetics, coatings, and specialty chemicals.
Supportive government policies promoting green chemistry, coupled with advancements in industrial biotechnology and fermentation processes, are improving the commercial viability of renewable acetone production. As downstream industries integrate sustainability objectives into procurement strategies, demand for environmentally responsible solvents and intermediates is expected to increase steadily. Companies that successfully commercialize low-carbon production methods, enhance process efficiency, and establish sustainable supply chains will be well positioned to strengthen their competitive advantage, access premium market segments, and capitalize on the growing global emphasis on environmentally compliant chemical manufacturing.
Analyst Perspective
The acetone market is driven by robust demand from bisphenol A, methyl methacrylate, and industrial solvent applications. Rising investments in automotive, construction, electronics, and pharmaceutical manufacturing continue to strengthen long-term consumption. Manufacturers are emphasizing production efficiency, capacity expansion, and supply chain optimization to enhance competitiveness amid fluctuating feedstock costs. Sustainability initiatives and the development of low-carbon production technologies are also reshaping industry strategies. Asia Pacific is expected to remain the primary growth hub, driven by expanding petrochemical infrastructure and increasing downstream manufacturing activities.
Grade Insights
Based on grade, the technical grade segment accounted for the highest market share, representing 97.1% of total revenue in 2025 and is expected to continue to dominate the industry over the forecast period. The increase in the consumption of technical products for MMA (methyl methacrylate) and BPA (bisphenol A) is notable. The widespread availability of these technical-grade products at lower costs contributes to their more significant market share. Technical-grade materials are primarily used in applications such as lacquers, adhesives, and floor polishing, among others.
The increasing construction activities are expected to drive demand for technical-grade acetone due to its use in adhesive cement and concrete admixtures. As construction activities resume worldwide following the lockdown, this trend will likely continue to boost demand for acetone in the construction sector during the forecast period.
Application Insights
By application, solvents held a dominant position, contributing 33.7% of total revenue in 2025. The increase in demand for acetone can be attributed to its role as a key ingredient in the production of hand sanitizer and as an excipient in pharmaceuticals. Active fillers use acetone as a solvent to ensure that each dose of medication contains the correct amount. Additionally, isopropyl alcohol (IPA), also used in hand sanitizer manufacturing, is expected to further drive the demand for acetone as a raw material in the production of IPA.
Methyl methacrylate is projected to experience a CAGR of 8.2% during the forecast period. This growth is primarily due to its application in the automotive industry for manufacturing various components. Acetone serves as a key raw material in the production of methyl methacrylate, which is subsequently utilized in exterior car coatings, auto glazing, and essential car parts, including headlamps, bulletproof glass, windows, taillights, and sunroofs.
Distribution Channel Insights
Based on distribution channel, the manufacturer to end-user segment accounted for the highest market share, representing 80.3% of total revenue in 2025. Manufacturers produce acetone in large quantities and may supply it directly to end users, such as chemical companies or manufacturers in various industries, thereby eliminating intermediaries. This direct channel facilitates better pricing and quicker delivery times and fosters strong relationships between manufacturers and end users. Additionally, this approach allows for tailored solutions to meet specific customer needs and promotes efficient inventory management. The direct distribution channel enhances the supply chain's effectiveness, benefiting both parties.
 To learn more about this report, Download Free Sample Report
The distribution channel from manufacturer to distributor and end-user plays a vital role in product distribution. Manufacturers produce acetone in bulk and often sell it to distributors, who then handle the logistics of delivering it to various end users, such as chemical companies and manufacturers across different sectors. This intermediary step allows distributors to manage inventory and provide localized support, ensuring that acetone is readily available where it's needed. Additionally, this channel can enhance market reach and provide end users with various options, thus improving overall service and responsiveness to demand. Furthermore, it enables manufacturers to focus on production while leveraging distributors' expertise in distribution and customer relationships.
Regional Insights
Asia Pacific Acetone Market Trends
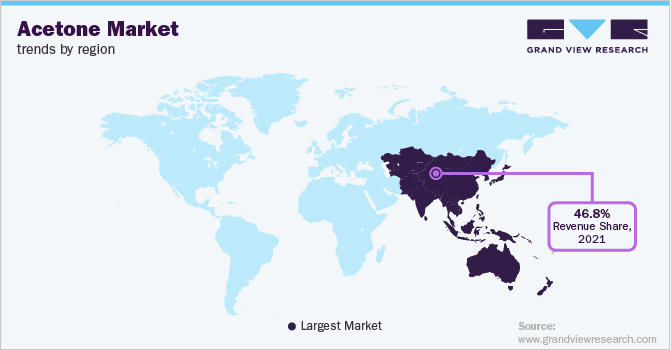
Asia Pacific dominated the acetone market with the highest revenue share of 47.8% in 2025. China accounted for 52.1% of the Asia Pacific acetone market in 2025. Acetone market in the Asia Pacific is growing due to high demand from various end-user industries, including pharmaceuticals, personal care and cosmetics, and automotive. This demand has been particularly strong in China, India, and Japan. China is the largest consumer of acetone and is expected to further boost product consumption due to growth in its pharmaceutical and electronics sectors.
 To learn more about this report, Download Free Sample Report
China Acetone Market Trends
China accounted for 52.1% of the Asia Pacific acetone market in 2025. China is supported by its extensive petrochemical infrastructure and expanding downstream chemical manufacturing base. Increasing production of bisphenol A, methyl methacrylate, coatings, solvents, and other chemical intermediates continues to sustain domestic consumption. The country's growing electronics and semiconductor industries are also creating additional demand for high-purity acetone used in precision cleaning and specialized processing. Meanwhile, new domestic production capacities are strengthening supply availability and reducing reliance on imports. However, periodic oversupply, fluctuations in plant operating rates, and uneven downstream purchasing activity continue to influence pricing and producer margins.
North America Acetone Market Trends
Acetone market in North America is witnessing demand from solvent manufacturing companies. The United States is a major hub for automotive manufacturers, producing 9.2 million vehicles in 2022, a 4.0% increase compared to 2021. This growth is expected to boost the demand for acetone within the automotive industry. The increasing demand for personal care, skincare, and beauty products is anticipated to drive product demand in Canada and the U.S.
Europe Acetone Market Trends
Acetone market in Europe is growing due to the rising demand from sectors like skincare, lifestyle, and cosmetics. Increasing awareness of skin and beauty care among the population is expected to further boost European demand for these products.
Latin America Acetone Market Trends
Acetone market in Latin America is witnessing a significant growth of the cosmetic and personal care industry, mainly in Brazil, due to the increasing demand for cosmetics and personal care products. Brazil and other regional countries are likely to enhance the personal care industry in Latin America during the forecast period.
Middle East & Africa Acetone Market Trends
Middle East & Africa acetone market has diverse climates and environmental conditions contribute to varying skincare needs, prompting consumers to seek effective moisturizing solutions that can address issues like dryness and irritation.
Key Acetone Company Insights
Some of the key players operating in the market include INEOS, Honeywell International Inc, and CEPSA Quimica, S.A.
-
INEOS is a British multinational conglomerate that manufactures chemicals, oil products, and other goods for a wide range of industries, including chemicals, operations, fuel, packaging, food, construction, and automotive. INEOS' products are used in many industries that touch our daily lives, including medicines, mobile phones, agriculture, automotive, construction, technology, and textiles.
-
Shell Plc, formerly Royal Dutch Shell Plc, is an integrated oil and gas company. It explores and produces oil and gas from both conventional fields and unconventional sources, such as tight rock, shale, and coal formations. Shell operates refining and petrochemical complexes worldwide and offers a variety of products, including lubricants, bitumen, liquefied petroleum gas, and petrochemical products that serve as raw materials for plastics, coatings, and detergents. The company is also a significant producer of biofuels in Brazil and is interested in various liquefied natural gas (LNG) and gas-to-liquids (GTL) projects. Shell is vital in the energy sector and has a global presence.
Key Acetone Companies:
The following key companies have been profiled for this study on the acetone market.
-
INEOS
-
Shell plc
-
Honeywell International Inc
-
Mitsui Chemicals, Inc.
-
CEPSA Quimica, S.A.
-
SABIC
-
Arkema
-
Solvay
-
DOMO Chemicals
-
Kumho P&B Chemicals
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (INEOS, Shell plc, Honeywell International Inc., Mitsui Chemicals, Inc., CEPSA Quimica S.A., SABIC, Arkema, Solvay)
- Operate integrated petrochemical complexes to optimize feedstock utilization and production efficiency.
- Secure long-term supply contracts with major downstream manufacturers across multiple industries.
- Invest in process optimization, digitalization, and energy-efficient manufacturing technologies.
- Expand production capacity through strategic investments, acquisitions, and regional manufacturing facilities.
- Strong global manufacturing and distribution networks ensure consistent product availability.
- Diversified product portfolios reduce dependence on a single end-use industry.
- Robust financial capabilities support continuous R&D and capacity expansion.
- Established customer relationships and brand reputation strengthen market positioning.
- High exposure to fluctuations in petrochemical feedstock prices.
- Significant capital requirements for plant maintenance and environmental compliance.
- Complex organizational structures may slow strategic decision-making.
- Lower growth potential in mature markets compared to developing regions.
Emerging Players (DOMO Chemicals, Kumho P&B Chemicals)
- Expand presence in regional markets through targeted sales and distribution partnerships.
- Focus on high-value applications in specialty chemicals and electronics.
- Form strategic alliances to strengthen market reach and customer access.
- Upgrade manufacturing processes to improve operational efficiency and product quality.
- Greater flexibility to respond quickly to evolving customer requirements.
- Specialized offerings enable differentiation in niche market segments.
- Lean organizational structures facilitate faster execution of business strategies.
- Strong regional presence supports customized products and technical services.
- Limited global manufacturing and distribution footprint.
- Smaller production capacities reduce economies of scale.
- Restricted financial resources may delay expansion and technology investments.
- Lower brand visibility can make it difficult to compete for large-scale supply agreements
Recent Developments
-
In January 2024, Haldia Petrochemicals Ltd, located in Kolkata, launched a significant phenol plant in India. The plant is expected to be completed by the first quarter of 2026. Once operational, the plant will produce 185,000 tons per annum (KTPA) of acetone and 300,000 tons of phenol yearly.
-
In December 2023, PTT Global Chemical (PTTGC), based in Thailand, announced its plans to resume acetone and phenol production at 90% capacity by the end of the month. This initiative aims to enhance resource allocation and improve operational efficiency. The company's manufacturing facility has an annual production capacity of 150,000 tons of acetone and 250,000 tons of phenol.
Acetone Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.9 billion
Estimated market size in 2026
USD 7.5 billion
Projected market size by 2033
USD 13.4 billion
Growth rate
CAGR of 8.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/billion, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Grade, application, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Belgium; CIS Nations; China; India; Japan; South Korea; Taiwan; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
INEOS; Shell plc; Honeywell International Inc.; Mitsui Chemicals, Inc.; CEPSA Quimica S.A.; SABIC; Arkema; Solvay; DOMO Chemicals; Kumho P&B Chemicals.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Acetone Market Report Segmentation
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global acetone market report based on grade, application, distribution channel, and region.
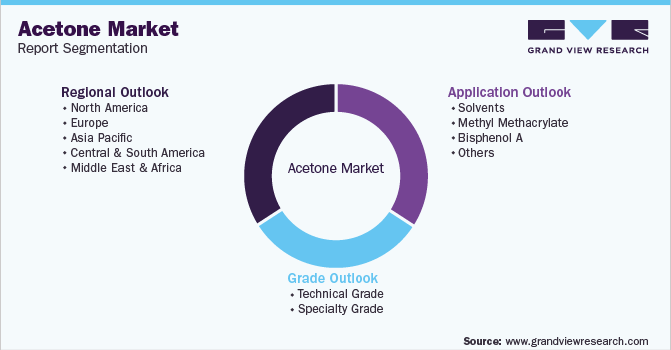 To learn more about this report, Download Free Sample Report
-
Grade Outlook (Volume, Kil0tons; Revenue, USD Million, 2021 - 2033)
-
Technical Grade
-
Specialty Grade
-
-
Application Outlook (Volume, Kil0tons; Revenue, USD Million, 2021 - 2033)
-
Solvents
-
Methyl Methacrylate
-
Bisphenol A
-
Other Applications
-
-
Distribution Channel Outlook (Volume, Kil0tons; Revenue, USD Million, 2021 - 2033)
-
Manufacturer to Distributor
-
Manufacturer to End User
-
-
Regional Outlook (Volume, Kil0tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Belgium
-
CIS Nations
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Taiwan
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The acetone market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each acetone segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Grade
Revenue capture definition
Technical Grade
Income is secured from supplying industrial-grade acetone for chemical processing, coatings, adhesives, and surface cleaning operations. Extensive utilization in high-volume manufacturing activities ensures sustained commercial demand.
Specialty Grade
Earnings originate from high-purity acetone supplied to pharmaceutical production, electronics fabrication, analytical laboratories, and personal care manufacturing. Premium quality specifications and stringent purity requirements enhance the value of this segment.
Segment - Application
Revenue capture definition
Solvents
Commercial returns stem from acetone consumption in paints, coatings, inks, degreasers, and formulation processes where rapid evaporation and effective dissolving properties are essential. Broad industrial acceptance strengthens market contribution.
Methyl Methacrylate
Value creation is driven by acetone serving as a primary raw material for methyl methacrylate manufacturing, supporting acrylic products used in transportation, construction, signage, and consumer applications. Growing preference for lightweight materials reinforces demand.
Bisphenol A
Financial contribution arises from acetone utilization during bisphenol A synthesis, enabling production of polycarbonate plastics and epoxy resins for engineering, electrical, automotive, and infrastructure applications. Continuous downstream consumption sustains segment performance.
Other Applications
Market income is supported by acetone usage in pharmaceutical formulations, cosmetic manufacturing, specialty chemical synthesis, laboratory reagents, and metal treatment processes. Expanding industrial applications continue to diversify revenue sources.
Segment - Distribution Channel
Revenue capture definition
Manufacturer to Distributor
Business proceeds are generated through wholesale partnerships that facilitate regional product availability, inventory optimization, and efficient delivery across diverse industrial customer networks.
Manufacturer to End User
Sales value is realized through direct procurement arrangements with large industrial consumers seeking dependable supply, customized contracts, and streamlined sourcing for continuous production operations.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Examine the global production of acetone primarily through the cumene process, where benzene and propylene serve as the principal feedstocks. Assess feedstock availability, manufacturing technologies, purification techniques, integrated petrochemical operations, production capacities, trade flows, and key manufacturing locations that ensure a stable supply of acetone for chemical, pharmaceutical, coatings, electronics, and industrial applications.
Application Adoption Layer
Where is acetone consumed?
Evaluate acetone deployment across major end-use industries including bisphenol A, methyl methacrylate, solvents, pharmaceuticals, paints and coatings, adhesives, cosmetics, electronics, and specialty chemicals. Demand trends are shaped by industrial expansion, infrastructure development, rising polymer consumption, healthcare manufacturing, and increasing production of high-performance materials.
Consumption Intensity Layer
How much acetone is utilized?
Quantify acetone usage across downstream sectors by analyzing production output, process requirements, material conversion ratios, and operational consumption patterns. The assessment covers resin manufacturing, acrylic production, solvent-based formulations, pharmaceutical processing, laboratory applications, and electronic component cleaning to determine annual volume requirements across regional markets.
Revenue Layer
How is market revenue generated?
Market value is created through the commercial sale of technical-grade and specialty-grade acetone supplied to manufacturers of bisphenol A, methyl methacrylate, solvents, pharmaceuticals, electronics, and specialty chemicals. Revenue performance is influenced by product purity, contractual supply agreements, production efficiency, downstream industrial demand, pricing dynamics, regulatory compliance, and capacity expansion across global petrochemical value chains.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study provides comprehensive country-level analysis across key acetone manufacturing and consumption markets. It evaluates production capacities, feedstock availability, downstream industrial demand, regulatory landscape, import-export trends, and growth prospects across solvents, bisphenol A, methyl methacrylate, pharmaceuticals, and specialty chemicals.
Supports strategic expansion by identifying high-growth geographies, comparing regional supply-demand balances, evaluating manufacturing competitiveness, and recognizing investment opportunities across rapidly developing industrial markets.
Competitive Benchmarking
The study delivers a comprehensive competitive benchmarking analysis of leading acetone manufacturers based on production capacity, product portfolio, geographic presence, feedstock integration, pricing strategies, distribution network, strategic initiatives, technological capabilities, and recent capacity expansions. It also evaluates each company's competitive positioning across major end-use industries and regional markets.
Enables stakeholders to compare competitor strengths, identify market gaps, evaluate strategic positioning, benchmark operational performance, and formulate effective growth, partnership, and competitive differentiation strategies.
Opportunity Assessment
The study examines emerging growth opportunities across solvents, bisphenol A, methyl methacrylate, pharmaceuticals, electronics, paints and coatings, adhesives, and specialty chemical applications. It also assesses opportunities arising from sustainable production technologies, capacity additions, expanding industrial manufacturing, and increasing demand for high-performance chemical intermediates.
Enables businesses to prioritize attractive investment segments, formulate long-term growth strategies, accelerate product portfolio expansion, and capitalize on evolving demand trends across global downstream industries.
Frequently Asked Questions About This Report
The global acetone market size was valued at USD 6.9 billion in 2025 and is estimated at USD 7.5 billion in 2026.
The global acetone market is expected to grow at a CAGR of 8.7% from 2026 to 2033, reaching USD 13.4 billion by 2033.
Asia Pacific dominated the acetone market with the highest revenue share of 47.8% in 2025.
Based on grade, technical grade segment dominated the market, with a revenue share of 97.1% in 2025.. Its widespread adoption across chemical manufacturing, paints and coatings, adhesives, and cleaning applications continues to reinforce the segment's dominant position in the global acetone market.
Solvents held a dominant position, contributing 33.7% of total revenue in 2025 while methyl methacrylate segment is second fastest growing market
Based on distribution channel, the manufacturer to end-user segment accounted for the highest market share, representing 80.3% of total revenue in 2025.
Asia Pacific is the fastest growing region with a CAGR of 9.1% in the forecast period.
Some key players operating in the acetone market include INEOS; Shell plc; Honeywell International Inc.; Mitsui Chemicals, Inc.; CEPSA Quimica S.A. and others.
The acetone market is primarily driven by rising demand for bisphenol A (BPA) and methyl methacrylate (MMA), which are essential intermediates for manufacturing polycarbonate plastics, epoxy resins, and acrylic products. Expanding applications in paints and coatings, pharmaceuticals, adhesives, and electronics, coupled with growing industrialization and infrastructure development, continue to support market growth.
About the Author(s)
Organic Chemicals Research Team
Bulk Chemicals · Organic ChemicalsThis report was authored by the organic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the organic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


