
- Home
- »
- Medical Devices
- »
-
Angiography Equipment Market Size Report, 2026-2033GVR Report cover

Angiography Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Angiography Systems, Catheters), By Technology, By Procedure, By Application, By Region, And Segment Forecasts
Market Size, 2025
$11.7BMarket Estimate, 2026
$12.4BMarket Forecast, 2033
$16.4BCAGR, 2026–2033
4.1%Angiography Equipment Market Summary
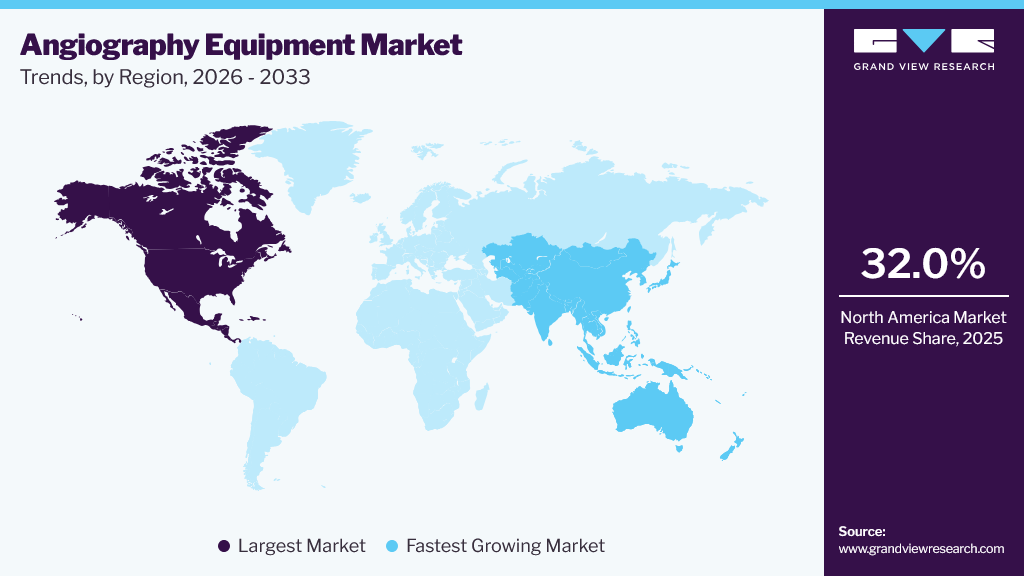
The global angiography equipment market size was valued at USD 11.7 billion in 2025 and is projected to grow from USD 12.4 billion in 2026 to USD 16.4 billion by 2033, at a CAGR of 4.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 32.0% in 2025. The increasing scope of applications and technological innovations are expected to be the key growth-driving factors for the market.
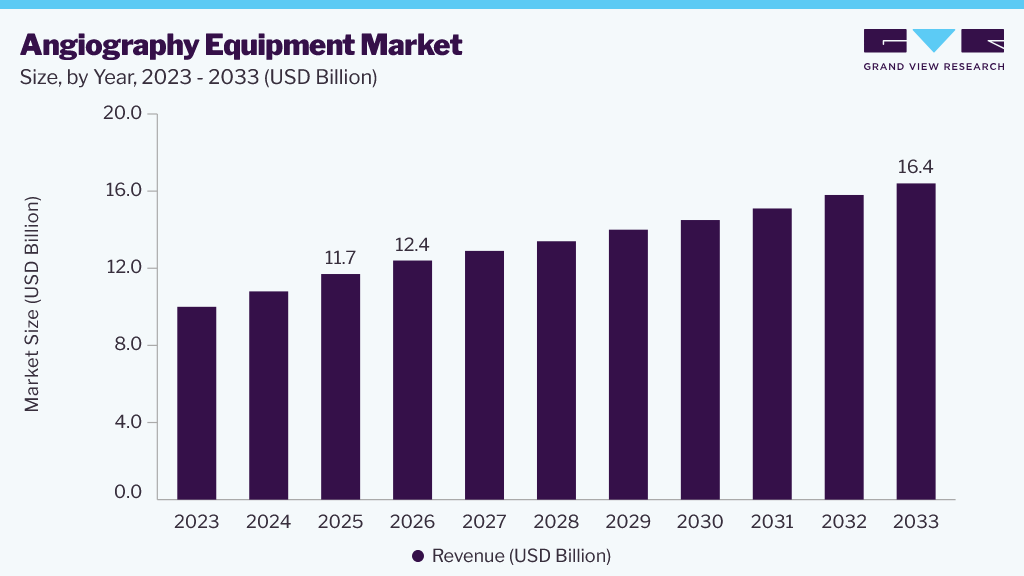 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The angiography systems segment held the largest market share of around 26.0% in 2025.
- By technology: The X-Ray segment held the largest market share of around 35.0% in 2025.
- By procedure: The coronary segment held the largest market share in 2025.
- By application: The diagnostic segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (32.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 11.7 Billion
- Estimated market size in 2026: USD 12.4 Billion
- Projected market size by 2033: USD 16.4 Billion
- CAGR (2026-2033): 4.1%
Prism AI by Grand View Research Free to tryAsk a question about the angiography equipment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Investments in the healthcare sector, the increasing geriatric population, and the rising prevalence of Cardiovascular Diseases (CVDs) are other prominent factors responsible for market growth. According to the World Health Organization (WHO), more than 75% of CVD deaths occur in low-income and middle-income countries due to the lack of easy access to primary healthcare programs for early detection and treatment.The rising prevalence of cardiovascular diseases (CVD) is a major driver for the growth of the healthcare market, particularly in the therapeutic and endovascular sectors. Factors such as unhealthy diets, sedentary lifestyles, smoking, and rising stress levels contribute to the global surge in conditions such as hypertension, heart disease, and stroke. As cardiovascular diseases become more widespread, the demand for diagnostic tools, treatment options, and endovascular procedures such as angioplasties, stent placements, and bypass surgeries continues to grow. According to the report published by CDC in February 2026, heart disease accounted for 683,491 deaths in 2024, maintaining its position as the nation's leading cause of death.
Technological advancements in healthcare are transforming medical treatments, driving efficiency, and improving patient outcomes. Innovations such as minimally invasive endovascular procedures, advanced imaging technologies, robotic surgeries, and AI-powered diagnostic tools enable quicker, more accurate treatments with less risk and shorter recovery times.
The aging population is one of the most significant factors driving the growth of the healthcare market. As life expectancy rises worldwide, particularly in developed countries, the elderly population increases, leading to higher demand for healthcare services, including those focused on cardiovascular health. In September 2024, the World Population Data Sheet indicates a global fertility rate of 2.2 births per woman and that 10% of the population is aged 65 and older, with some regions exceeding 20%. There are 800 million older adults, surpassing the entire population of Latin America and the Caribbean. This aging population is expected to lead to increased noncommunicable diseases and a rising demand for caregiving.
Market Concentration & Characteristics
The degree of innovation in the angiography equipment industry is high. Technological advancements such as 3D imaging, AI-based diagnostics, and enhanced fluoroscopy systems have revolutionized angiograms, improving diagnostic accuracy and procedural efficiency. These innovations cater to the growing demand for more precise and effective cardiovascular care.
The level of merger and acquisition activities is moderate in this market. While large players often pursue strategic alliances and collaborations to expand their product offerings, mergers and acquisitions are less frequent. Companies typically focus on strengthening their R&D and technology portfolios through partnerships rather than large-scale consolidation.
Regulation has a high impact, with stringent medical device regulations governing the development, approval, and commercialization of angiography equipment. Regulatory bodies, such as the FDA and EMA, enforce rigorous standards that ensure patient safety, which can significantly affect product timelines, costs, and market access. In August 2024, the US Centers for Medicare & Medicaid Services (CMS) announced a proposed increase in reimbursement rates for hospitals and outpatient clinics providing cardiac computed tomography angiography (CCTA), following years of declining payments. CMS reimburses approximately USD 175 for CCTA, which is part of a class 1 recommendation for ruling out obstructive coronary disease according to the latest clinical guidelines for both stable and acute chest pain.
Product expansion is high in the market, driven by the demand for more advanced, compact, and cost-effective solutions. Companies continuously introduce new products, such as portable angiography systems and low-dose radiation technologies, to meet diverse clinical needs, enabling broader adoption in both developed and emerging markets.
Regional expansion is moderate, as companies seek to enter emerging markets in the Asia-Pacific and Latin America, with growing healthcare infrastructure and demand. However, challenges such as regulatory differences, market maturity, and economic factors in various regions often hamper expansion.
Analyst Perspective
The global angiography equipment market is expected to expand steadily, supported by the rising prevalence of cardiovascular and other vascular diseases, increasing demand for minimally invasive image-guided procedures, and continued advances in angiography technologies. X-ray remains the leading technology, owing to its widespread use for vascular imaging and interventional procedures in hospitals and catheterization laboratories. Technological developments focused on improved image quality, radiation-dose reduction, three-dimensional visualization, AI-assisted image processing, and hybrid imaging configurations are enhancing procedural precision and workflow efficiency. In addition, continued investment in catheterization laboratories, hybrid operating rooms, and structural heart and neurovascular interventions is expected to create further growth opportunities for market participants.
Product Insights
The angiography systems segment held the largest market share of around 26.0% in 2025, driven by ongoing investments, technological advancements, and the expanding scope of applications. These systems have evolved from catheter-based minimally invasive procedures to digitalized procedures. For instance, in March 2026, Siemens Healthineers introduced its latest Artis angiography platforms at the European Congress of Radiology in Vienna, Austria. The systems integrate AI-powered applications for embolization procedures, automated motion correction for 3D cone-beam CT, AI-assisted treatment planning and device navigation, and real-time image processing to enhance image quality while maintaining radiation dose, supporting precise minimally invasive interventions.
The contrast media segment is anticipated to grow at the fastest CAGR over the forecast period. These products are commonly used to enhance the visibility of blood vessels in imaging modalities such as CT angiography, MRA, and X-ray. They are also employed in projectional radiography and fluoroscopy. Different radiocontrast agents include iodine, barium sulfate, and gadolinium. In July 2024, MEDTRON AG unveiled the MR syringe adapter CM Type E, specifically crafted for Guerbet's pre-filled Elucirem syringe, which utilizes the contrast media gadopiclenol.
Technology Insights
The X-Ray segment held the largest market share of around 35.0% in 2025. Based on technology, the market is segmented in X-ray, MRA, and CT segments. Companies are investing heavily in developing new technologies, which are expected to support market growth. The need to reduce radiation dose, improve image quality, and emerging trends in the cath lab are expected to drive market growth. For instance, in May 2026, Philips introduced SmartIQ for its Azurion image-guided therapy platform, incorporating advanced image-processing technology for coronary procedures.
The MRA segment is expected to register the fastest CAGR over the forecast period, driven by its ability to diagnose heart disease without exposing patients to ionizing radiation. MRA offers 3D capabilities to acquire images in any anatomical plane with excellent soft tissue contrast. The emergence of 3.0T MR imaging has significantly enhanced the diagnosis of coronary artery disease. These factors are also said to boost the segment growth. In October 2024, a study in Science Advances emphasized the vital role of magnetic resonance angiography (MRA) in diagnosing panvascular diseases. It noted the limitations of single-modality MRA and the need for contrast agents that combine T1 and T2 effects for multiparameter MRA. The research developed a highly sensitive MRA technique using dual-modality NaGdF4 nanoparticles.
Procedure Insights
The coronary segment dominated the market with the largest market share in 2025 and is expected to grow at the fastest CAGR during the forecast period. The increasing rates of coronary artery disease (CAD) are boosting the demand for coronary angiography in emerging countries like China and India. In October 2024, the CDC reported that approximately 1 in 20 adults aged 20 and older has coronary artery disease (CAD), which accounts for roughly 5%. Advances in imaging methods, notably the transition from single-slice to multislice Computed Tomography (CT), have significantly improved diagnostic capabilities. Presently, diagnostic options include coronary computed tomography angiography, cardiac magnetic resonance imaging (MRI), single photon emission computed tomography (SPECT), and positron emission tomography (PET).
The endovascular segment emerged as the second-largest in 2025 due to the growing preference for minimally invasive procedures that offer shorter recovery times, lower complication risk, and improved patient outcomes. Endovascular procedures, such as stent placements, angioplasties, and embolization techniques, are increasingly used to treat vascular conditions such as aneurysms, peripheral artery disease, and deep vein thrombosis, further driving the growth of this segment.
Application Insights
The diagnostic segment dominated the market with the largest share in 2025 and is anticipated to grow at the fastest CAGR over the forecast period. Developments in CTA and MRA provide appropriate information in cardiology and neurology, such as cerebral aneurysms, acute stroke, brain arteriovenous malformation, dural arteriovenous fistula, suspected cerebral vasculitis, and occlusive diseases. The growing awareness of cardiovascular diseases (CVDs) and their risk factors is expected to drive market growth. In March 2024, Siemens Healthineers revealed that the CIARTIC Move, a mobile C-arm with autonomous driving capabilities, received clearance from the FDA. This innovative system enhances the efficiency and standardization of 2D fluoroscopic and 3D cone-beam CT imaging for surgical teams in hospitals and outpatient surgeries, leading to quicker imaging processes.
The therapeutic segment emerged as the second largest in 2025, due to the growing demand for advanced treatments across various medical conditions. This segment includes targeted therapies for cancer, cardiovascular disorders, and neurological diseases. The rise in chronic conditions, increasing aging populations, and the demand for personalized treatments have contributed to the expansion of this segment, making it a key focus for medical advancements and investments.
Regional Insights
The angiography equipment industry in North America held the predominant position with a share of approximately 32.0% in 2025, due to its advanced healthcare infrastructure, high healthcare expenditures, and strong presence of leading medical device manufacturers and pharmaceutical companies. The region's emphasis on research and development and high adoption rate of innovative medical technologies further drive growth. In October 2024, the Society for Cardiovascular Angiography and Interventions (SCAI) released a new expert consensus statement on STEMI management for primary PCI, published in JSCAI. The statement provides practical guidance for physicians, addressing complex clinical scenarios like large thrombus burden and no-reflow phenomena. It emphasizes the need for specific equipment in cardiac catheterization labs and recommends advanced imaging tools and mechanical support for challenging cases.
 To learn more about this report, Download Free Sample Report
U.S. Angiography Equipment Market Trends
The angiography equipment industry in the U.S. accounted for North America's largest share of the market in 2025. The U.S. leads in the medical and healthcare sectors because of its substantial investment in healthcare R&D, robust regulatory frameworks, and presence of major healthcare institutions. In January 2024, Summa Therapeutics, LLC announced that its Finesse Injectable balloon catheter was successfully used in first-in-human procedures for injectable angioplasty in patients with below-the-knee peripheral artery disease (PAD). This hybrid device combines diagnostic and therapeutic functions to improve treatment for patients at risk of limb loss while minimizing equipment and contract requirements.
Europe Angiography Equipment Market Trends
The angiography equipment industry in Europe is anticipated to grow significantly over the forecast period. Europe dominates due to its well-established healthcare systems, government-funded healthcare models, and a strong emphasis on innovation in medical technology. Countries such as Germany, France, and the UK invest heavily in healthcare infrastructure, supporting public and private growth.
The UK angiography equipment industry is expected to grow over the forecast period. The UK benefits from a strong National Health Service (NHS) that ensures wide access to cutting-edge medical technologies. The country's focus on medical research and development, along with partnerships between public institutions and private companies, drives the adoption of innovative treatments. In November 2024, the Canadian Association of Radiologists Journal reported equipment failures in interventional radiology divisions at tertiary academic hospitals in the UK and Canada. It highlighted the importance of organizational resilience, emphasizing the stages of anticipation, coping, and adaptation.
The angiography equipment industry in Germany is expected to grow over the forecast period. Germany is a leader in the European healthcare market due to its highly developed healthcare system, strong medical device manufacturing industry, and significant investments in healthcare research.
France’s angiography equipment industry is expected to grow over the forecast period. France dominates due to its universal healthcare system, significant government funding, and a high standard of medical care. France's focus on innovation and its investment in medical technologies ensures continued growth in the healthcare and therapeutic segments.
Asia Pacific Angiography Equipment Market Trends
The angiography equipment industry in Asia Pacific is expected to experience rapid growth from 2026 to 2033. Asia-Pacific is a rapidly growing region in the healthcare sector, driven by a large and diverse population, improving healthcare infrastructure, and increasing healthcare expenditure. The rise in chronic diseases, the expanding middle class, and government initiatives to improve healthcare access contribute to the growth of the medical market, particularly in countries such as China, Japan, and India.
China’s angiography equipment industry is anticipated to grow over the forecast period. China dominates the Asia-Pacific region due to its massive population, expanding healthcare industry, and significant government investments in healthcare reforms. In November 2024, Beijing's municipal government unveiled a plan to expand the city's medical device industry to 50 billion yuan (around 7 billion U.S. dollars) by 2026. The strategy involves creating industrial clusters focused on high-end medical equipment, high-value consumables, and efficient diagnostic products through 2026.
The angiography equipment industry in Japan is expected to grow rapidly over the forecast period. Japan has one of the most advanced healthcare systems in the world, with cutting-edge medical technologies and a robust regulatory framework. In June 2024, JAMA Network Open published an article detailing a cohort study that analyzed 2,147 patients from the International Post-PCI FFR registry, incorporating data from Japan, Korea, and China. The findings indicated weak correlations between angiographic results and post-PCI fractional flow reserve (FFR).
India’s angiography equipment industry is anticipated to grow rapidly over the forecast period. India is seeing rapid growth in its healthcare sector, driven by increasing healthcare needs due to a large aging population and a growing middle class. In March 2024, A J Hospital & Research Center launched advanced cardiac facilities, including Optical Coherence Tomography (OCT), advanced Cardiac MRI & CT, and a 4D Echocardiogram machine. These technologies improve diagnostics and treatment options, making the hospital one of the region's most advanced cardiac care centers.
Latin America Angiography Equipment Market Trends
The angiography equipment industry in Latin America is witnessing a significant trend. Due to its expanding population and increasing demand for healthcare services, Latin America is growing as a key region in the healthcare sector. In November 2024, the IDB approved a loan to Buenos Aires for acquiring four angiography machines as part of a broader initiative to modernize the city’s public health system. This equipment will help improve diagnostic accuracy and reduce waiting times for over one million public health users, contributing to better healthcare service delivery in the city.
Brazil’s angiography equipment industry is expected to grow over the forecast period. Brazil is the largest healthcare market in Latin America, and it is significantly focused on improving its healthcare infrastructure, including access to advanced medical treatments and devices. The country’s large population and growing demand for medical innovations make it a key player in the region’s healthcare market.
Middle East & Africa Angiography Equipment Market Trends
The angiography equipment industry in the Middle East and Africa is poised to grow in the near future. The region is becoming increasingly important in the global healthcare landscape, with a rise in demand for healthcare services driven by an aging population and an increase in chronic diseases. In February 2024, Neusoft Medical Systems presented its state-of-the-art medical imaging solutions at Arab Health 2024, featuring technologies like CT, MRI, and more, all powered by AI. The standout exhibit was the NeuViz ACE UP CT, a groundbreaking system that improved healthcare efficiency and patient satisfaction, providing remarkable flexibility and precision that surpasses the typical 64-slice options.
The angiography equipment industry in Saudi Arabia is expected to grow over the forecast period. Saudi Arabia leads the Middle East in healthcare development, with substantial investments in healthcare infrastructure, medical technology, and research. In July 2024, an article published in the Journal of Contemporary Medical Sciences stated that the incidence of contrast-induced acute kidney injury (CI-AKI) in patients undergoing coronary procedures was 8.1%, with higher rates in those over 70. The study suggests that while CI-AKI is a concern, its occurrence is lower than expected, and preventive measures can mitigate the risk.
Kuwait’s angiography equipment industry is anticipated to grow over the forecast period. Kuwait invests heavily in its healthcare sector, improving medical services, expanding hospitals, and incorporating advanced medical technologies. The government’s efforts to provide high-quality healthcare to its citizens are driving growth in the region's therapeutic and endovascular sectors.
Key Angiography Equipment Company Insights
Some of the key players operating in the angiography equipment industry include Medtronic plc, Boston Scientific Corporation, Abbott, and ANGIODYNAMICS. These companies are making significant infrastructure investments, which enable them to develop, manufacture, and commercialize a high volume of drugs worldwide. In addition, to increase their presence globally, companies engage in several strategic partnerships with distributors and other companies.
Key Angiography Equipment Companies
The following key companies have been profiled for this study on the angiography equipment market:
-
Medtronic
-
Boston Scientific Corporation
-
Angiodynamics
-
Abbott
-
MicroPort Scientific Corporation
-
B. BRAUN SE
-
Koninklijke Philips N.V.
-
GE HealthCare
-
Cardinal Health
-
Siemens Healthineers AG
-
Shimadzu Corporation
Recent Developments
-
In November 2025, Canon Medical Systems announced the global launch of the Alphenix 4D CT with Aquilion ONE / INSIGHT Edition, an advanced hybrid Angio-CT system that combines angiography and CT imaging in a single intervention suite. The system aims to improve procedural efficiency, reduce patient transfers, and increase precision in complex interventional radiology and cardiology procedures, supporting the adoption of next-generation angiography equipment.
-
In October 2024, Shimadzu Corporation unveiled SMART Voice, a voice recognition feature for its Trinias angiography systems, aimed at improving efficiency and reducing the workload for healthcare professionals. The technology will be demonstrated at upcoming events in Kobe, Washington D.C., and the RSNA exhibition in Chicago, enhancing catheterization procedures without diverting attention from the affected area.
-
In June 2024, NIDEK CO., LTD. introduced the RS-1 Glauvas Optical Coherence Tomography (OCT). This cutting-edge system features a scanning speed of up to 250 kHz, enabling fast and accurate imaging. It is designed to enhance workflow efficiency and diagnostic confidence for glaucoma and retinal vascular diseases. It offers improved clarity in B-scan imaging and advanced AngioScan OCT-Angiography for better evaluation of chorioretinal microvasculature.
-
In February 2024, Koninklijke Philips N.V. unveiled the Philips CT 5300 system, which incorporates cutting-edge AI technology for diagnostics, interventional procedures, and screening applications. This versatile X-ray CT system enhances diagnostic accuracy, improves workflow efficiency, and maximizes equipment availability, ultimately benefiting patient outcomes. During #ECR2024, Philips works alongside healthcare providers to enhance productivity and promote more sustainable healthcare solutions.
Angiography Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.7 billion
Estimated market size in 2026
USD 12.4 billion
Projected market size by 2033
USD 16.4 billion
Growth rate
CAGR of 4.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, procedure, application, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia, UAE; Kuwait
Key companies profiled
Medtronic; Boston Scientific Corporation; Angiodynamics; Abbott; MicroPort Scientific Corporation; B. BRAUN SE; Koninklijke Philips N.V.; GE HealthCare; Cardinal Health; Siemens Healthineers AG; Shimadzu Corporation
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Angiography Equipment Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global angiography equipment market report based on product, technology, procedure, application, and region:
- Product Outlook (Revenue, USD Billion, 2021 - 2033)
- Angiography Systems
- Catheters
- Guidewire
- Balloons
- Contrast Media
- Vascular Closure Devices
- Angiography Accessories
- Technology Outlook (Revenue, USD Billion, 2021 - 2033)
- X-Ray
- MRA
- CT
- Procedure Outlook (Revenue, USD Billion, 2021 - 2033)
- Coronary
- Endovascular
- Neurovascular
- Application Outlook (Revenue, USD Billion, 2021 - 2033)
- Diagnostic
- Therapeutic
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Denmark
- Sweden
- Norway
- Asia Pacific
- Japan
- China
- India
- South Korea
- Australia
- Thailand
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
The global angiography equipment market size was valued at USD 11.7 billion in 2025 and is estimated at USD 12.4 billion for 2026.
The global angiography equipment market is expected to grow at a CAGR of 4.1% from 2026 to 2033, reaching USD 16.4 billion.
North America dominated with an approximately 32.0% revenue share in 2025.
Key players in the market include Medtronic; Boston Scientific Corporation, Angiodynamics, Abbott, MicroPort Scientific Corporation, B. BRAUN SE, Koninklijke Philips N.V., GE HealthCare, Cardinal Health, Siemens Healthineers AG, Shimadzu Corporation, and others.
The angiography systems segment held the largest market share of around 26.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


