
- Home
- »
- Plastics, Polymers & Resins
- »
-
Battery Packaging Market Size, Share & Growth Report, 2033GVR Report cover

Battery Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Cardboard, Metal), By Packaging (Corrugated Packaging, Blister Packaging), By Casing (Cylindrical, Prismatic), By Level of Packaging, By Battery, By Region, And Segment Forecasts
Market Size, 2025
$36.8BMarket Estimate, 2026
$41.2BMarket Forecast, 2033
$91.9BCAGR, 2026–2033
12.1%Battery Packaging Market Summary
The global battery packaging market size was valued at USD 36.8 billion in 2025 and is projected to grow from USD 41.2 billion in 2026 to USD 91.9 billion in 2033, at a CAGR of 12.1% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 42.0% in 2025. The growing adoption of electric vehicles, driven by rising awareness of the environmental impact of traditional fuel-powered vehicles, technological advancements, and favorable government initiatives, is strengthening demand for new battery packs, leading to significant growth in the battery pack industry.
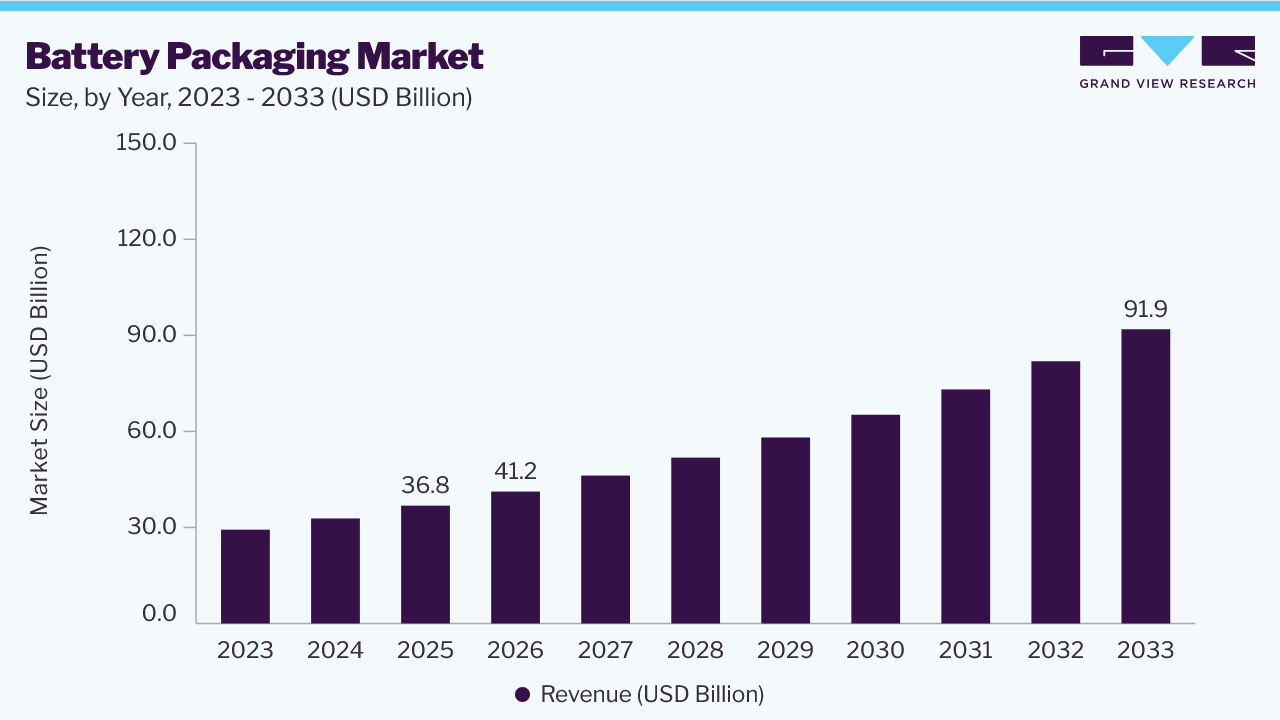 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: The cardboard segment held the largest market share of over 60.0% in 2025.
- By packaging: The corrugated packaging segment held the largest market share of over 70.0% in 2025.
- Bycasing: The cylindrical segment held the largest market share of over 55.0% in 2025.
- Bylevel of packaging: The cell & pack packaging segment held the largest market share of over 65.0% in 2025.
- Bybattery: The lithium-ion batteries segment held the largest market share of over 40.0% in 2025.
Regional Highlights
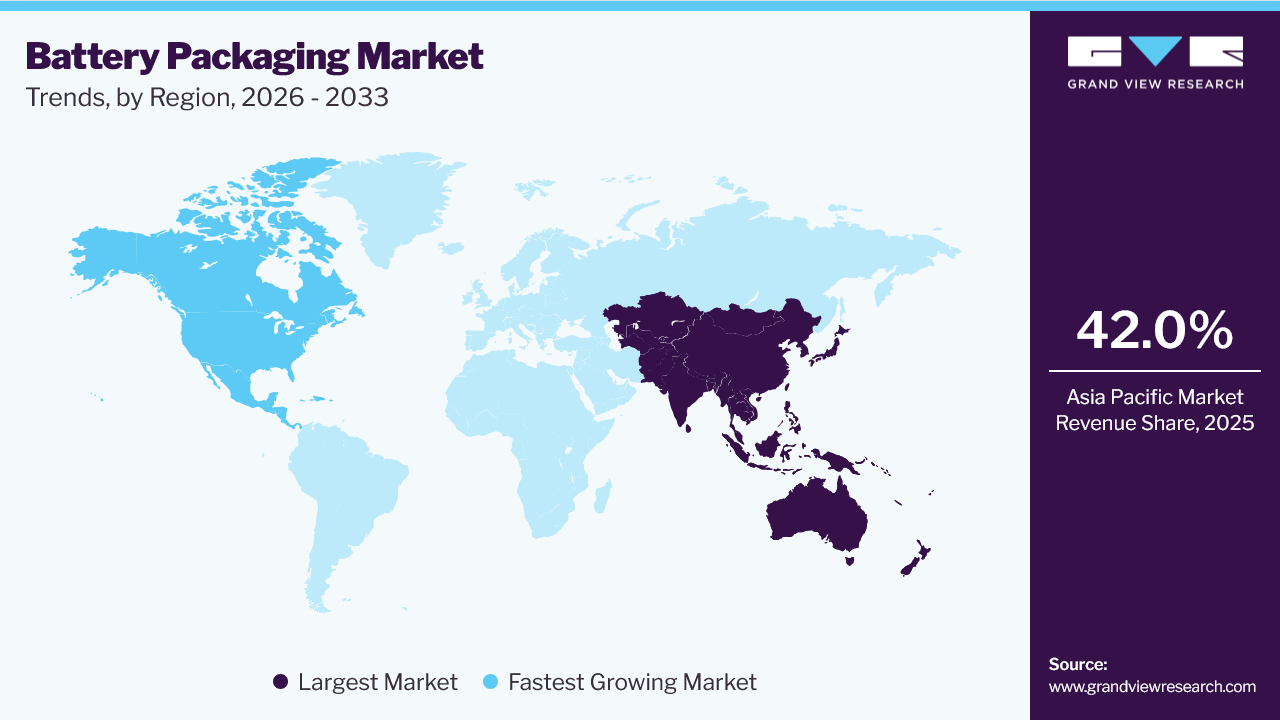
- Largest regional market: Asia Pacific (Approximately 42.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 36.8 Billion
- Estimated market size in 2026: USD 41.2 Billion
- Projected market size by 2033: USD 91.9 Billion
- CAGR (2026-2033): 12.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The surging demand for electric vehicles (EVs) and renewable energy storage systems is a primary driving force for the market. As governments worldwide implement stricter emission regulations and incentivize the adoption of clean energy technologies, the need for efficient and reliable battery solutions has skyrocketed in recent years. Lithium-ion batteries, in particular, have become the preferred choice for powering EVs and energy storage systems, necessitating robust packaging solutions to ensure safety, performance, and longevity.
The consumer electronics industry's relentless pursuit of portable and compact devices has further fueled the demand for battery packaging. Smartphones, laptops, tablets, and wearable technologies rely heavily on high-performance batteries, which require specialized packaging materials and designs. These packaging solutions must strike a balance between protecting the battery from external factors and optimizing space utilization within the device's compact form factor.
Advances in battery chemistry and technologies have also contributed to the growth of the market. Innovations such as solid-state batteries, lithium-sulfur batteries, and sodium-ion batteries present unique packaging challenges and opportunities. Manufacturers must adapt their packaging solutions to accommodate the specific requirements of these emerging battery technologies, ensuring safe handling, transportation, and integration into various applications.
Moreover, the increasing emphasis on sustainability and environmental responsibility has led to a surge in demand for eco-friendly battery packaging solutions. Manufacturers are exploring biodegradable and recyclable materials, as well as implementing circular economy principles in their packaging designs. This not only aligns with regulatory requirements but also caters to the growing consumer preference for environmentally conscious products.
Analyst Perspective
The global battery packaging industry has been experiencing significant growth, driven by strong EV adoption trends, increasing utilization of electric vehicles in industrial and warehouse operations, and a growing inclination toward autonomous mobility solutions among businesses and customers. This market is also influenced by innovation in the materials industry, as a shift toward polymer composites, aluminum, and fiber-based solutions enables lighter weight and improved thermal safety. Some factors, such as specific precision requirements, the high cost of innovation-based materials, and the complexities associated with thermal management, may pose challenges to growth; however, key companies invest substantial resources in R&D activities, collaborations, and partnerships to navigate these challenges. In addition, the emergence of Cell-to-Pack (CTP) and Cell-to-Chassis (CTC) technologies is expected to present novel opportunities for this industry in the coming years.
Material Insights
Cardboard dominated the overall market with a revenue share of over 60.0% in 2025 and is anticipated to withstand the growth at the fastest CAGR from 2026 to 2033. Cardboard is an inexpensive and readily available material, making it a cost-effective choice for battery packaging compared to other materials like plastics or metals. In addition, cardboard offers a good surface for printing product information, branding, and labeling, allowing manufacturers to convey important details and comply with regulatory requirements.
On the other hand, plastics can be easily molded, extruded, or thermoformed into various shapes and sizes required for battery packaging. This flexibility in manufacturing processes makes it easier and more cost-efficient to produce a wide range of packaging solutions for different batteries and sizes.
Packaging Insights
The corrugated packaging segment dominated the market and accounted for the largest revenue share of over 70.0% in 2025, and is also projected to experience the fastest growth from 2026 to 2033. Corrugated cardboard provides excellent cushioning and protection for batteries during transportation and handling. The fluted (corrugated) layer between the two liners creates an air cushion that absorbs impacts and prevents damage to the batteries inside during transit and handling.
Compared to corrugated packagings, blister packs are relatively inexpensive to produce, especially for small to medium-sized battery packs. This cost-effectiveness contributes to their widespread adoption in the battery packaging industry. In addition, they are designed for effective product display and merchandising on retail shelves. Their compact size and ability to be hung or stacked make them space-efficient and visually appealing for retailers.
Casing Insights
The cylindrical segment dominated the market and accounted for the largest revenue share of over 55% in 2025 and is projected to experience the fastest growth from 2026 to 2033. The cylindrical shape provides excellent mechanical stability and resistance to external forces, making these cells less susceptible to swelling or deformation during charging and discharging cycles. This robustness is particularly important in applications where batteries are subjected to vibrations or impacts.
On the other hand, the prismatic casing is expected to witness robust growth in the foreseeable future due to its extensive usage for packaging batteries employed in consumer electronics such as laptops, tablets, and smartphones.
Level of Packaging Insights
The cell & pack packaging segment dominated the market and accounted for the largest revenue share of over 60.0% in 2025 and is projected to experience the fastest growth from 2026 to 2033. Cell & pack packaging allows customized designs to accommodate different battery chemistries, sizes, and configurations. This flexibility enables battery manufacturers to optimize packaging solutions for their specific requirements.
Batteries, especially lithium-ion batteries, are classified as hazardous materials during transportation. Robust and specialized transportation packaging is necessary to ensure the safe and secure transport of batteries, preventing any leakage, short-circuiting, or damage during transit. Hence, transportation packaging is designed to protect batteries from external factors such as shock, vibration, temperature fluctuations, and moisture during the shipping process. This is crucial to maintain the integrity and performance of the batteries.
Battery Insights
Lithium-ion batteries accounted for the largest revenue share of over 40.0% in 2025 and are expected to withstand robust growth from 2026 to 2033. Lithium-ion batteries can store a large amount of energy per unit weight and volume, making them ideal for applications where size and weight are critical factors, such as portable electronics and electric vehicles. This positive demand outlook for the lithium-ion batteries drives the demand for the specialized battery packaging.
Lead-acid batteries are relatively inexpensive to manufacture compared to other batteries, making them an economical choice for automotive applications. The automotive industry is a major consumer of lead-acid batteries, as they are used in almost every vehicle for starting the engine and providing power to electrical systems. The consistent demand from this sector drives the need for battery packaging.
Regional Insights
The battery packaging industry in Asia Pacific accounted for the largest revenue share of over 42.0% in 2025. Asia Pacific countries such as China, Japan, South Korea, and India have a massive consumer base and are major manufacturing hubs for consumer electronics products such as smartphones, laptops, and tablets. These devices require batteries, driving the demand for battery packaging solutions in the region.
 To learn more about this report, Download Free Sample Report
Several leading battery manufacturers, such as Contemporary Amperex Technology Co. Limited (CATL), LG Chem, Samsung SDI, and Panasonic are headquartered or have major manufacturing facilities in the Asia Pacific region. These companies require advanced battery packaging solutions to protect their products during transportation and storage.
China battery packaging industry is a global leader in battery production, particularly for lithium-ion batteries used in electronics and electric vehicles. The significant presence of a domestic battery manufacturing industry creates a high demand within China. Moreover, it is the world's largest EV market. The increasing production and sales of EVs have fueled the demand for high-performance battery packaging solutions to ensure the safe and efficient transportation of EV battery packs.
North America Battery Packaging Market Trends
The North America battery packaging industry held a significant market share in 2025. The region's dominance is attributed to major battery producers such as Tesla, Panasonic, and LG Chem, which are driving market expansion. In addition, the increasing demand for lithium-ion batteries in various applications such as consumer electronics, electric vehicles, and energy storage systems is fueling growth in the market.
Government initiatives promoting the use of renewable energy sources like solar and wind energy are also contributing to the region's market share growth. Furthermore, the rapid adoption of electric vehicles in North America, supported by environmental concerns, government incentives, and improved charging infrastructure, is a significant driver of the region's battery packaging market expansion.
The battery packaging industry in the U.S. is growing due to a strong R&D ecosystem and the growing demand for EVs. The U.S. is home to many leading research institutions and universities focused on energy storage technologies. This fosters a robust ecosystem for research and development, leading to the emergence of cutting-edge battery packaging techniques and materials.
Key Battery Packaging Company Insights
The market comprises a significant number of companies producing battery packaging. The battery packaging industry has witnessed significant acquisitions and expansions over the past few years. In addition, companies have been investing in improving R&D efforts and expanding their portfolios by adding advanced materials-based solutions to meet modern energy industry requirements.
Key Battery Packaging Companies
The following key companies have been profiled for this study on the battery packaging market:
-
NEFAB GROUP
-
Wellplast AB
-
C.L. Smith
-
DGM
-
Söhner Kunststofftechni GmbH
-
GWP Group Limited
-
Manika Plastech Ltd.
-
Covestro AG
-
Labelmaster
-
VIKING PLASTICS
-
Trinseo
-
CHEP
-
EaglePicher Technologies
-
Anchor Bay Packaging
-
TOPPAN Inc.
-
Corplex
-
Air Sea Containers (US)
-
Econovus
-
Epec, LLC
-
Great Northern Corporation
-
Amperex Technology Limited
Recent Developments
- In July 2026, FORVIA HELLA announced launch of Lithium-Ion battery pack. This newly designed 12-volt pack expanded FORVIA’s portfolio associated with electro mobility, and it’s expected to strengthen its position in integrated system solutions for energy management.
- In April 2026, Rebattex AB partnered with NEFAB Packaging Sweden AB, aimed at integration of packaging solutions in Rebattex exchange platform for EV batteries. With initial roll out in Sweden, Rebattex announced its plan to expand the service to other markets over coming years.
- In April 2026, NEFAB GROUP announced acquisition of Vallos, s.r.o., strengthening its presence in Slovakian market, with added capabilities to cater specific requirements of customers from Lithium-ion Batteries (LiB), energy and others.
Battery Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 36.8 billion
Estimated market size in 2026
USD 41.2 billion
Projected market size by 2033
USD 91.9 billion
Growth rate
CAGR of 12.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material; packaging; casing; level of packaging; battery; region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; Argentina; South Africa; UAE
Key companies profiled
NEFAB GROUP; Wellplast AB; C.L. Smith; DGM; Söhner Kunststofftechnik GmbH; GWP Group Limited; Manika Plastech Ltd.; Covestro AG; Labelmaster; VIKING PLASTICS; Trinseo; CHEP; EaglePicher Technologies; Anchor Bay Packaging; TOPPAN Inc.; Corplex; Air Sea Containers (US); Econovus; Epec, LLC; Great Northern Corporation; Amperex Technology Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Battery Packaging Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global battery packaging market report based on material, packaging, casing, level of packaging, battery, and region:
-
Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cardboard
-
Plastics
-
Polypropylene (PP)
-
Acrylonitrile Butadiene Styrene (ABS)
-
Polyamide (PA)
-
Polyethylene Terephthalate (PET)
-
Others
-
-
Metal
-
Aluminum
-
Steel
-
-
Others
-
-
Packaging Outlook (Revenue, USD Billion, 2021 - 2033)
-
Corrugated Packaging
-
Blister Packaging
-
-
Casing Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cylindrical
-
Prismatic
-
Pouch
-
Others
-
-
Level of Packaging Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cell & Pack Packaging
-
Transportation Packaging
-
-
Battery Outlook (Revenue, USD Billion, 2021 - 2033)
-
Lead Acid Battery
-
Lithium Ion Battery
-
Nickel Metal Hydride Battery
-
Nickel Cadmium Battery
-
Lithium Titanate Oxide (LTO) Battery
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia & New Zealand
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
UAE
-
South Africa
-
-
Frequently Asked Questions About This Report
Key players in the market include NEFAB GROUP; Wellplast AB; C.L. Smith; DGM; Söhner Kunststofftechnik GmbH; GWP Protective; Manika Plastech Pvt. Ltd.; Covestro AG; Labelmaster; VIKING PLASTICS; Trinseo; CHEP; EaglePicher Technologies; Anchor Bay Packaging; TOPPAN Inc.; Corplex; Air Sea Containers (US); Econovus; Epec, LLC; Great Northern Corporation; Amperex Technology Limited, and others.
The cardboard battery packaging segment accounted for the largest revenue share of over 60.0% in 2025.
Asia Pacific dominated with an approximately 42.0% revenue share in 2025.
The global battery packaging market size was valued at USD 36.8 billion in 2025 and is estimated at USD 41.2 billion for 2026.
The global battery packaging market is expected to grow at a CAGR of 12.1% from 2026 to 2033, reaching USD 91.9 billion.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


