
- Home
- »
- Plastics, Polymers & Resins
- »
-
Bio-PET Film Market Size And Share Report, 2026-2033GVR Report cover

Bio-PET Film Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Laminating Film, Universal Film, Electrical Insulating Film, Capacitor Film), By Application (Packaging, Printing, Decoration, Electrical & Electronics), By Region, And Segment Forecasts
Market Size, 2025
$86.2MMarket Estimate, 2026
$96.8MMarket Forecast, 2033
$228.8MCAGR, 2026–2033
12.6%Bio-PET Film Market Size & Trends
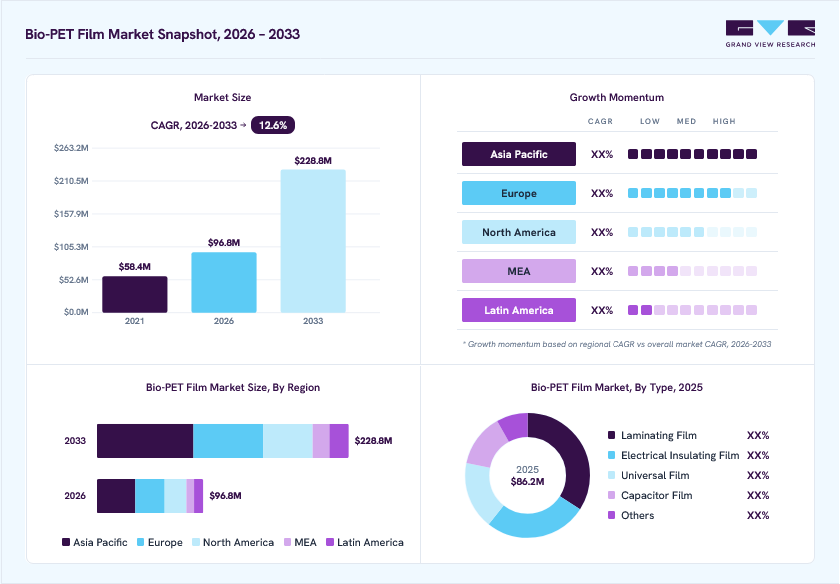
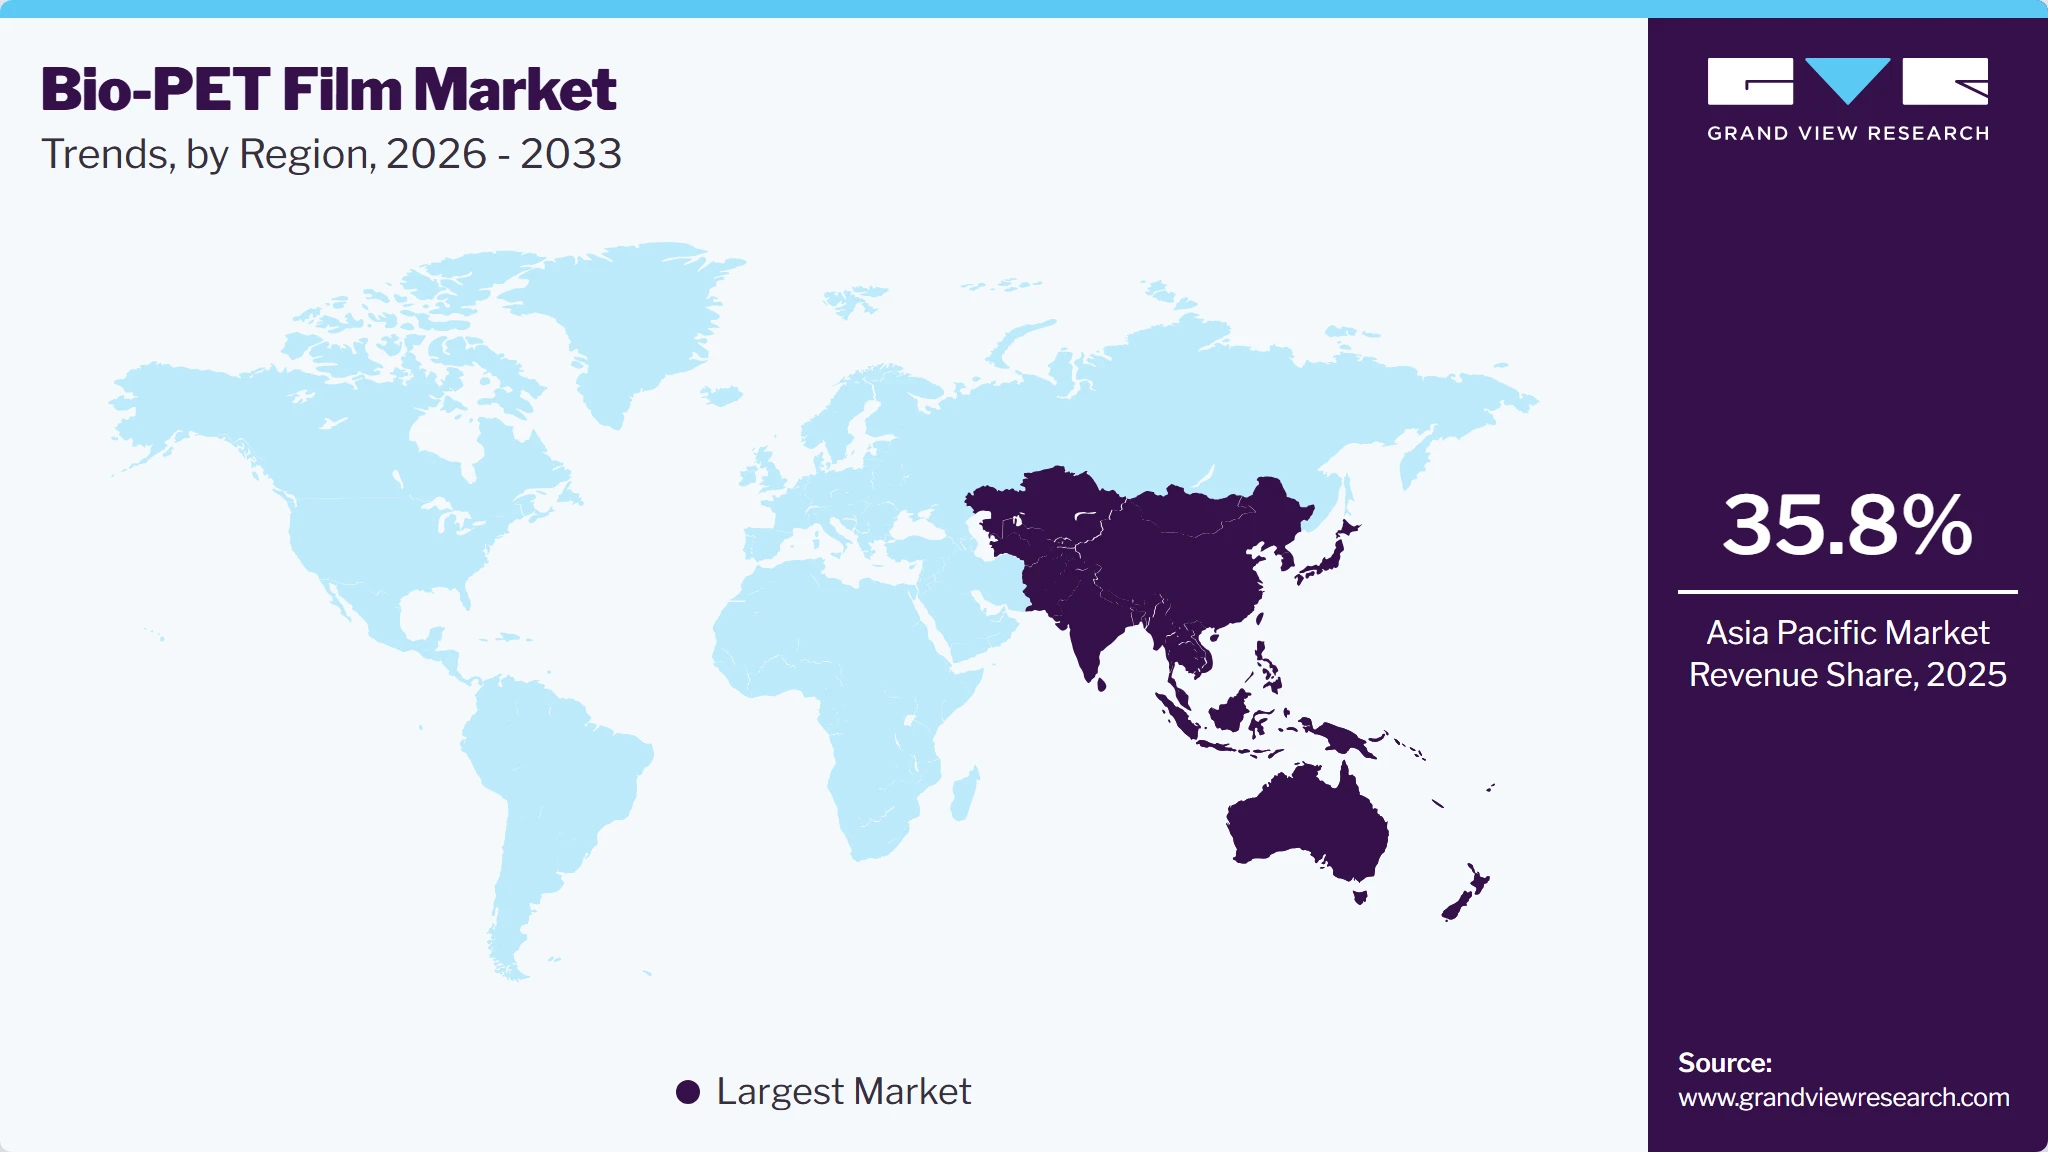
The global bio-PET film market size was valued at USD 86.2 million in 2025 and is projected to grow from USD 96.8 million in 2026 to USD 228.8 million by 2033, at a CAGR of 12.6% from 2026 to 2033. Asia Pacific dominated the bio-PET film market with the largest revenue share of 35.8% in 2025. The rising sustainability and environmental concerns among people across the globe are positively influencing the market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Laminating film segment held the largest market share of 36.4% in 2025.
- By application: Packaging segment held the largest market share of 37.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.8% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 86.2 Million
- Estimated market size in 2026: USD 96.8 Million
- Projected market size by 2033: USD 228.8 Million
- CAGR (2026-2033): 12.6%
Prism AI by Grand View Research Free to tryAsk a question about the Bio-PET film marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Moreover, factors such as the inclination toward bioplastics, favorable government policies, and increasing application of bio-polyethylene terephthalate (PET) films in packaging, printing, electrical & electronics, pharmaceutical, and cosmetic sectors are driving the demand for bio-PET films.Asia Pacific bio-PET film market is characterized by various manufacturing industry, as a result of the increased emphasis on research and development, combined with favorable government initiatives towards sustainability, is likely to result in regional market expansion. Growing concern about environmental sustainability has resulted in a trend toward bio-based products. The market is projected to expand as government limitations on conventional plastics tighten and demand for plastic packaging grows. Moreover, automotive sales and manufacturing in Asia Pacific countries are likely to expand, so will market demand for these films.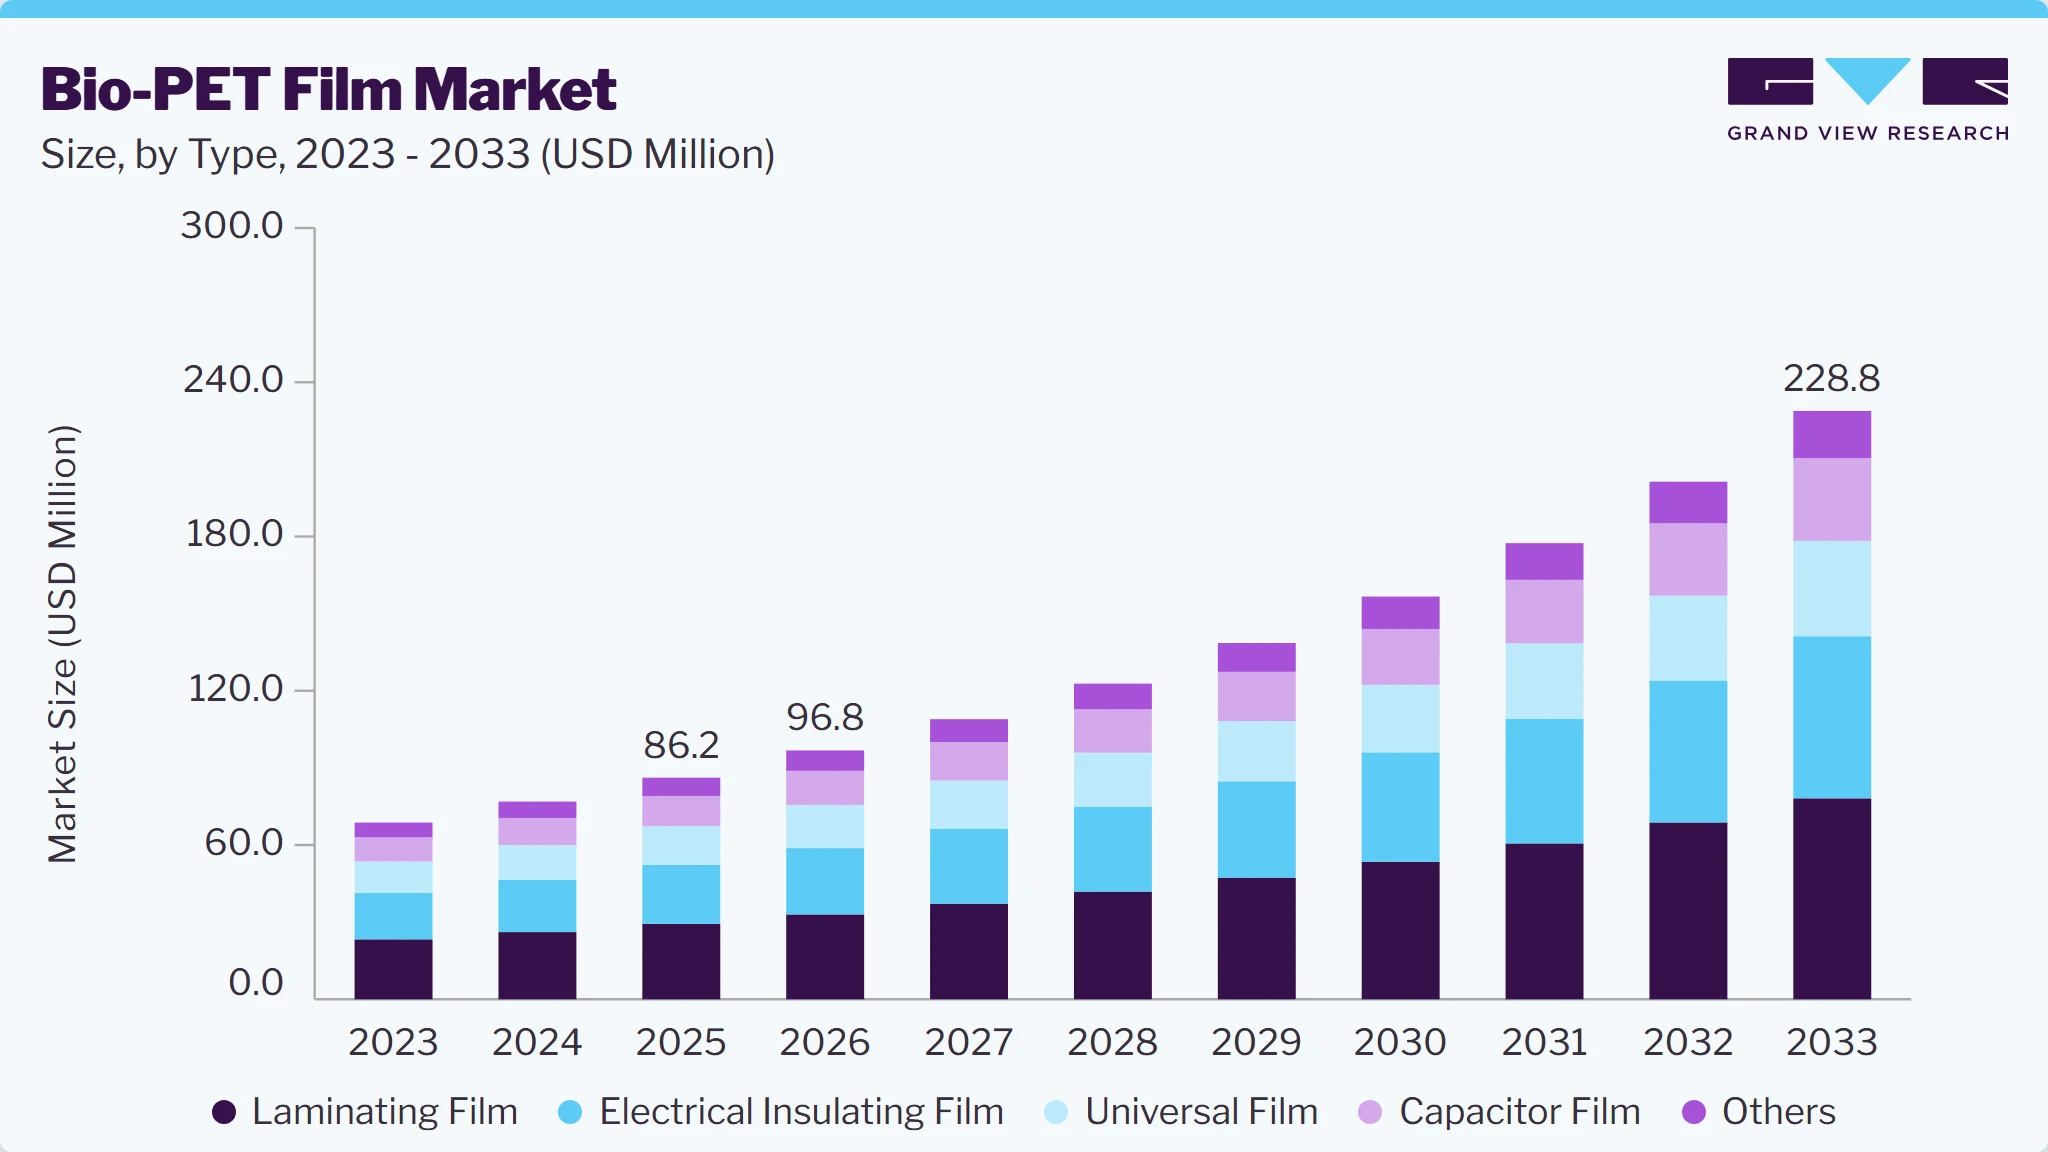 To learn more about this report, Download Free Sample Report
Moreover, the increase in ongoing research and development in the region to improve the performance and properties of bio-PET films is expected to drive the market growth. China is one of the prominent consumers of non-alcoholic beverages across the globe, which, in turn, contributes to the demand for bio-PET film in the packaging sector. The country is also one of the biggest consumers of packaged food products including fresh food, ready-to-eat food, and processed food, which further paves way for the use of bio-PET film in packaging applications.
In addition, growing concerns about plastic waste among the public is a major factor driving the bio-PET film market in the region. Government initiatives to reduce the use of single-use plastics in the country are anticipated to augment the demand for bio-PET film over the forecast period. Under the “Clean India Mission” initiative, the government intends to end the use of single-use plastic films by 2022.
Market Dynamics
The bio-PET film market is evolving from a niche sustainable packaging material into a strategically important component of the broader circular plastics economy. Rising consolidation among manufacturers is driving mergers, acquisitions, and technology partnerships as companies seek access to advanced production capabilities, scale efficiencies, and sustainable innovation platforms. At the same time, increasing regulatory oversight surrounding recyclability, waste management, and chemical safety is influencing product development and compliance strategies. While bio-PET offers a renewable alternative to conventional plastics, higher production costs and limited substitute technologies continue to shape competitive dynamics. Demand remains concentrated across packaging, consumer goods, and industrial applications, creating both growth opportunities and intense competition among solution providers.
The Bio-PET film market is experiencing strong growth due to increasing demand for sustainable, lightweight, and high-performance packaging materials across food & beverage, pharmaceutical, personal care, and consumer goods industries. Bio-PET films are widely utilized in food wrappers, beverage labels, laminating films, cosmetic pouches, and flexible packaging applications owing to their excellent transparency, mechanical strength, barrier performance, and recyclability. The rapid expansion of e-commerce and quick-commerce distribution channels is further supporting market growth, as brands increasingly require durable and environmentally responsible packaging solutions that can withstand transportation and storage requirements.
Food and beverage packaging remains a major demand generator for the market, particularly for food-grade certified applications requiring product safety, extended shelf life, and regulatory compliance. The increasing consumption of packaged goods, pharmaceutical items, and functional beverages, such as energy drinks, ready-to-drink teas, soy drinks, fruit juices, yogurt drinks, and sports drinks, is driving the growth of Bio-PET film usage. Additionally, growing demand from the alcoholic beverage and beer industries for sustainable labels and packaging formats is contributing to increased consumption, as manufacturers seek packaging materials that combine environmental benefits with strong aesthetic and performance characteristics.
High manufacturing costs remain a significant restraint on the bio-PET film market. Producing bio-PET films requires costly bio-based feedstocks and complex conversion processes that demand advanced manufacturing technologies and stringent process controls. Compared with conventional petroleum-based PET, bio-PET production entails higher raw material procurement costs and additional processing expenses, leading to elevated overall manufacturing costs. In many cases, bio-PET films can cost 10-15% more than their fossil-based counterparts, limiting adoption among price-sensitive end-use industries, particularly in packaging applications where cost competitiveness remains a critical purchasing factor.
The growing adoption of solar energy systems is creating significant growth opportunities for the Bio-PET film market. Rising demand for lightweight, flexible, and environmentally friendly materials in photovoltaic applications is driving the use of Bio-PET films as solar panel backsheets, electrical insulating layers, and substrates for organic photovoltaic (OPV) technologies. Bio-PET films offer excellent durability, transparency, insulation performance, and compatibility with advanced printing processes, making them suitable for building-integrated photovoltaics (BIPV) and next-generation energy solutions. As industries pursue clean-energy goals and sustainable manufacturing practices, collaboration among solar technology developers, film manufacturers, and material innovators is expected to accelerate the development of high-performance Bio-PET film applications.
Market Concentration & Characteristics
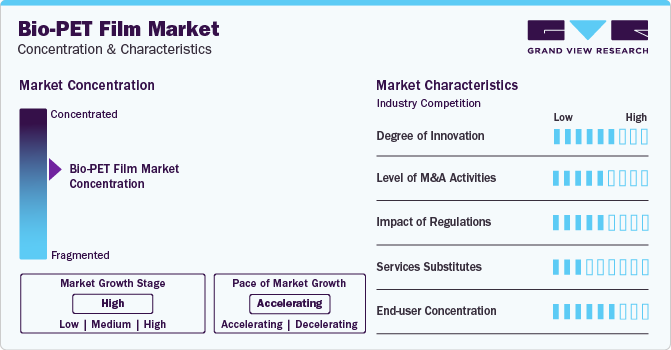
Market growth stage is high, and pace of the market growth is accelerating. The bio-PET film market is characterized by a high degree of innovation owing to the rapid technological advancements along with the shift towards sustainability driven by factors such as advancements in the production of bio-PET film, the availability of raw materials, and increasing plastics consumptions across several applications including packaging, electrical & electronics, printing, among others. Subsequently, innovative bio plastics applications are constantly emerging, disrupting existing industries and creating new ones.
 To learn more about this report, Download Free Sample Report
The bio-PET film market is also characterized by a high level of merger and acquisition (M&A) activity by the leading players. This is due to several factors, including the desire to gain access to new production technologies and talent, need to consolidate in a rapidly growing market, and increasing strategic initiatives of bio-PET film.
The market is also subject to increasing regulatory scrutiny. The global bio-PET film market is subject to numerous regulations, guidelines, and restrictions regarding plastic recycling and its applications owing to the toxic nature of raw materials coupled with certain health hazards of improperly disposed products and over-exposure to chemicals contained in these films.
There are a limited number of direct product substitutes for bio-PET film. However, there are only few number of technologies that can be used to achieve sustainable outcomes to bio-PET film. While these materials offer environmental benefits by reducing dependence on fossil fuels, their production tends to be more expensive compared to traditional petrochemical-based plastics.
End-user concentration is a significant factor in the market. Since there are a number of end-user industries that are driving demand for bio-PET film. The concentration of demand in a small number of end-user industries creates opportunities for companies that focus on developing bio-PET film solutions. However, it also creates challenges for companies that are trying to compete in a crowded market.
Analyst Perspective
The market for Bio-PET films is rapidly growing as brands and packaging manufacturers increasingly look for eco-friendly alternatives that can lower carbon emissions without interfering with current processing and recycling systems. The primary driver of this market growth is the rising demand for bio-based packaging materials in sectors such as food and beverage, consumer products, and industrial uses, where Bio-PET provides performance attributes like traditional PET while incorporating renewable feedstock. The shift towards adoption is further bolstered by corporate sustainability goals and regulatory measures that encourage the use of bio-based materials. Nonetheless, the expansion of the market is still contingent on the availability of feedstock, the cost-effectiveness compared to conventional PET, and the speed at which end-use industries move from sustainability goals to broader material replacement.
Type Insights
Based on type, the laminating film segment led the market with the largest revenue share of 36.4% in 2025. Bio-PET films are extensively used for laminating applications owing to their excellent optical properties, providing high transparency and clarity. This makes them ideal for laminating applications where maintaining the visibility and appearance of the underlying material is crucial, such as laminated cards, photos, and documents. In addition, bio-PET films have low shrinkage, allowing them to maintain their original size and shape even when exposed to heat or moisture. This dimensional stability is crucial in laminating to prevent warping or distortion of laminated items. Furthermore, these films are strong and durable, resistant to chemicals and temperature variations, and environmentally friendly.
The electrical insulating film segment is expected to grow at the fastest CAGR of 13.1% over the forecast period. The increasing adoption of bio-PET films in electrical insulation can be linked to the expansion of the electrical industry and the rising need for effective insulating materials.Bio-PET films have excellent dielectric properties, they are highly effective at insulating against electrical current. They have a high dielectric strength, making them suitable for use in high-voltage applications. These films exhibit a low dissipation factor, indicating that they have minimal energy loss when subjected to alternating electrical current. In addition, these films can withstand a wide range of temperatures, they have low thermal expansion and maintain their shape and size over a wide temperature range, these films are flexible and can be easily molded or shaped to fit the specific needs of electrical components.
Application Insights
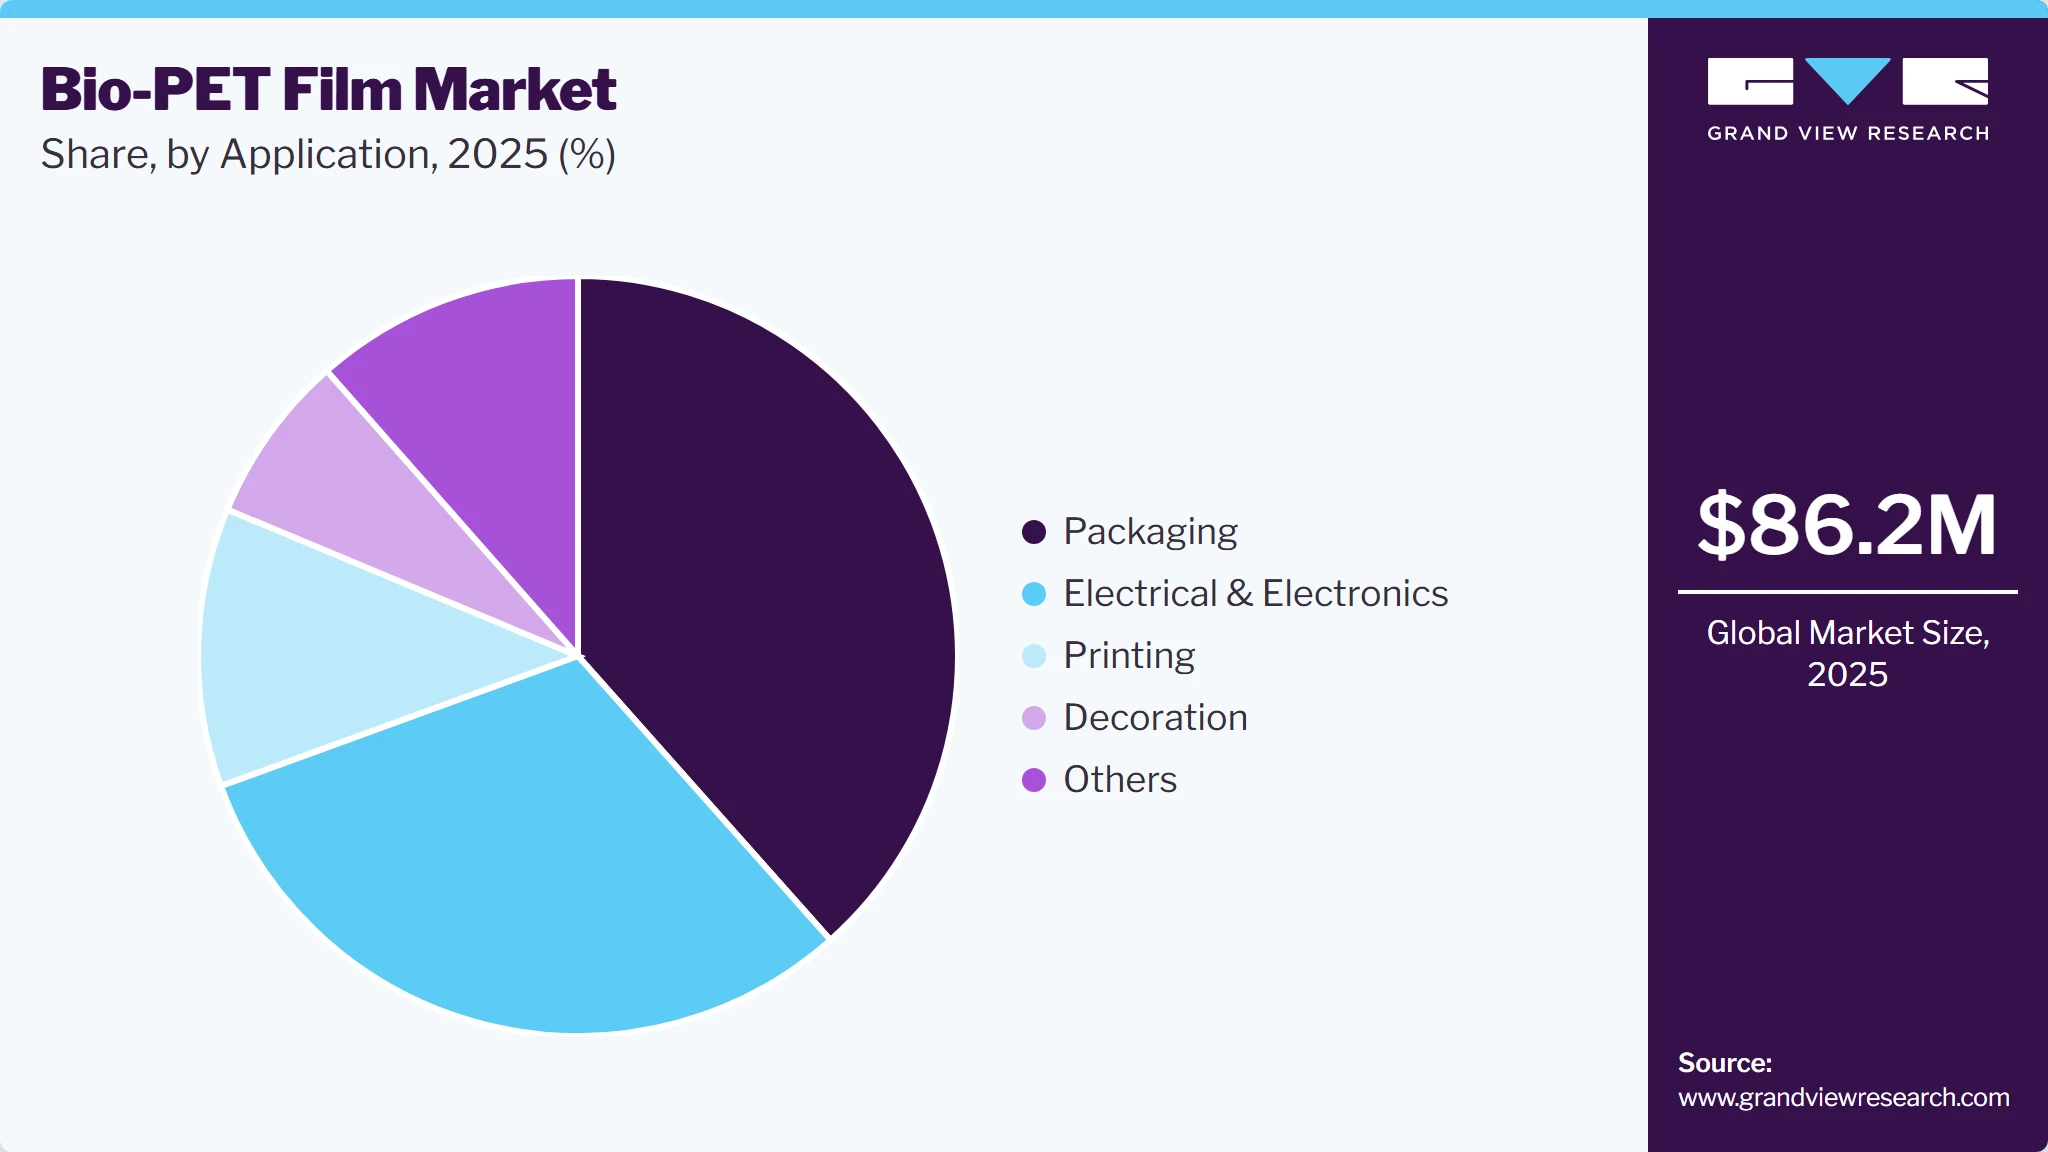
Based on the application, the packaging segment led the market with the largest revenue share of 37.8% in 2025. The increasing demand for packaging, especially in the food sector, is driving the demand for bio-based food packaging plastics. This, in turn, is expected to propel the bio-PET market. Rising environmental concerns and regulations on single-use plastics are driving the demand for bio-based plastics in the packaging sectors. For instance, in July 2022, the government of India banned the manufacture, sale, use, import, stocking, and distribution of single-use plastic items. Such regulations are expected to drive the demand for alternative plastics, such as bio-PET, which can be degradable and environmentally friendly compared to the conventional plastics.
 To learn more about this report, Download Free Sample Report
The electrical & electronics application segment is projected to grow at a significant CAGR over the forecast period. Consumer preferences for environmentally friendly products, as well as growing awareness of environmental issues, fuel demand for sustainable electronics. The increasing demand for electronic devices and growing concerns about plastic waste are encouraging manufacturers to incorporate bioplastics into various electrical and electronic devices.
Printing application segment is also anticipated to witness substantial upsurge in adoption of bio PET Films.Bio-PET films are used in the printing industry for several packaging applications. Due of their superior barrier qualities against moisture and gases, they can be utilized as primary packaging for food products, pharmaceuticals, cosmetics, and other consumer goods, providing product protection and shelf life extension. Growing environmental concerns and laws concerning the use of traditional polymers in printing applications are driving demand for eco-friendly alternatives such as bio-PET films.
Regional Insights
Asia Pacific dominated the bio-PET film market with the largest revenue share of 35.8% in 2025. The increased demand for packaged food owing to lifestyle changes, rising disposable income, and consumer preference for fast food is likely to fuel demand for bio-PET films in the region. Furthermore, the rising environmental concerns related to single-use plastics and the government’s initiatives to reduce global warming and greenhouse gas emissions are expected to provide lucrative opportunities for market growth in the coming years.
 To learn more about this report, Download Free Sample Report
China Bio-PET Film Market Trends
The bio-PET film market in China accounted for the largest market revenue share in the Asia Pacific in 2025.
Europe is anticipated to witness significant growth in the market. Europe has a strong focus on sustainability and environmental protection. With a growing awareness of plastic pollution and its impact on the environment, there is a heightened demand for alternatives to traditional plastics. Bioplastics, such as bio-PET, are viewed as a more environment-friendly option because they contain renewable, non-fossil components. According to European Bioplastics e.V., Europe is the second-largest market for bioplastics in terms of production, accounting for around 26.5% of the global bioplastics production capacity.
Key Bio-PET Film Market Company Insights
Some of the key players operating in the market include TORAY INDUSTRIES, INC. and KURARAY CO., LTD.
-
TORAY INDUSTRIES, INC., operates in various business segments, including fibers and textiles, performance chemicals, carbon fiber composite materials, environment and engineering, life science, and others. In addition, it has a global presence in 29 countries around the world
-
KURARAY CO., LTD. operates in three business segments, namely resins and chemicals, fibers, and others. The resins and chemicals segment involves the production and sale of polyvinyl butyral (PVB) resin and film, isoprene chemicals, methacrylic resin, polyvinyl alcohol (PVOH) resin and film, polyamide resin, elastomer, ethylene vinyl alcohol (EVOH) resin and film, and medical products. Furthermore, the fibers segment involves the production and sale of polyester fibers, man-made leather, PVA fiber, hook-and-loop fasteners, and nonwoven fabrics. Moreover, the other segment encompasses the production and sale of activated carbon and high-performance membranes and systems for water treatment
-
PLASTIPAK HOLDINGS, INC. and UFlex Limited are some of the emerging market participants in the global market.
-
PLASTIPAK HOLDINGS, INC. specializes in the design and production of plastic containers for the food, beverage, and consumer products sectors. Its primary focus lies in providing comprehensive services that encompass labeling, packaging design, filling, and delivery. Besides, it offers a wide range of products, including resins, blow moldings, injection moldings, thermoshaping solutions, filling and capping products, extrusion systems, and direct printing services. These offerings cater to various markets, including aerosol, carbonated soft drinks and water, consumer cleaning products, juice, food and dairy items, automotive products, industrial goods, agricultural products, personal care items, and alcoholic beverages
-
UFlex Limited operates in seven business segments, namely flexible packaging, packaging films, chemicals, printing cylinders, holography, engineering, and aseptic liquid packaging. It provides flexible packaging solutions to a wide range of sectors, including FMCG, automobile, pharmaceuticals, building materials, and others. The company serves customers across 150 countries, including the U.S., Canada, South America, Europe, CIS countries, the UK, South Africa, other African countries, and the Middle East, as well as South Asian countries
Key Bio-PET Film Companies
The following key companies have been profiled for this study on the bio-PET film market.
-
TORAY INDUSTRIES, INC.
-
Polyplex
-
TEIJIN LIMITED
-
KURARAY CO., LTD.
-
Qingdao Kingchuan Packaging
-
Far Eastern New Century Corporation
-
PLASTIPAK HOLDINGS, INC.
-
Anellotech
-
Indorama Ventures Public Company Limited
-
Carbios
-
NatureWorks LLC
-
UFlex Limited
-
FKuR
-
Saipet Samartha Private Limited
-
Iwatani Corporation
-
LOTTE Chemical Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (TORAY INDUSTRIES, INC.; Polyplex; TEIJIN LIMITED; KURARAY CO., LTD.; Far Eastern New Century Corporation; PLASTIPAK HOLDINGS, INC.; Indorama Ventures Public Company Limited; NatureWorks LLC; UFlex Limited; Iwatani Corporation; LOTTE Chemical Corporation)
- Broad portfolios of Bio-PET films serving packaging, printing, decoration, electrical & electronics, and specialty industrial applications.
- Significant investment in bio-based polymers, recycled PET integration, sustainable packaging technologies, and advanced film processing capabilities.
- Integrated manufacturing operations, resin production expertise, and global distribution networks supporting large-scale commercial adoption across multiple end-use industries.
- Strong expertise in polymer science, film engineering, and sustainable material development.
- Established global production footprints, diversified customer bases, and long-term relationships with packaging converters, brand owners, and industrial users.
- Vertical integration across raw materials, resin production, and film manufacturing enhances supply chain control, product consistency, and cost competitiveness.
- High capital expenditure requirements for bio-based feedstock integration, production expansion, and sustainability-focused innovation.
- Exposure to fluctuations in raw material availability, bio-feedstock costs, and global packaging demand cycles can affect profitability.
- Regulatory compliance requirements, evolving sustainability standards, and competitive pricing pressures may impact margins and limit flexibility in rapidly changing market conditions.
Established Players (Qingdao Kingchuan Packaging; Anellotech; Carbios; FKuR; Saipet Samartha Private Limited)
- Focus on the development and commercialization of bio-based and sustainable PET film solutions for packaging, printing, industrial, and specialty applications.
- Significant investment in renewable feedstock technologies, recycling innovations, circular economy initiatives, and environmentally responsible polymer production.
- Emphasis on strategic partnerships, technology licensing, and expansion of bio-based material portfolios to support global sustainability objectives.
- Strong positioning in sustainable materials and bio-based polymer innovation. Growing expertise in circular economy technologies, renewable raw materials, and advanced recycling processes.
- Ability to address increasing regulatory and consumer demand for low-carbon, environmentally responsible film solutions across multiple end-use industries.
- Commercialization of emerging bio-based technologies requires substantial capital investment and long development cycles.
- Dependence on feedstock availability, regulatory support, and evolving sustainability standards may impact market adoption.
- Higher production costs compared to conventional PET materials can create pricing challenges in cost-sensitive applications.
Recent Developments
-
In September 2023, LOTTE Chemical introduced a new environmentally friendly material brand called 'ECOSEED'. ECOSEED encompasses physically and chemically recycled materials, including post-consumer recycled materials and bioplastics, such as Bio-PET. This strategic initiative is anticipated to assist the company in reaching its target of supplying 1 million tons of the resource circulation material 'ECOSEED' by 2030.
-
In June 2023, Indorama Ventures Public Company Limited, a leading global sustainable chemical producer, and Carbios, a biotech company focused on developing biological solutions for plastic and textile recycling, signed a non-binding Memorandum of Understanding (MOU) to establish a joint venture. The purpose of this partnership is to build the world's first PET biorecycling plant in France. The estimated capital investment for the construction of this innovative facility is approximately USD 245.7 million.
-
In May 2023, Origin Materials, Inc., a company specializing in carbon-negative materials, and Indorama Ventures Public Company Limited, a leading producer of virgin and recycled PET resins, formed a strategic partnership to expedite the large-scale production of bio-based materials. These materials have the potential to be utilized in a wide range of applications including packaging, automotive components, films, and textiles. The partnership is aimed at developing bio-PET, advanced bio-based chemical furan-dicarboxylic acid, bio-PTA, and co-polyesters that offer advantages over conventional PET plastics.
Bio-PET Film Market Report Scope
Report Attribute
Details
Market size in 2025
USD 86.2 million
Estimated market size in 2026
USD 96.8 million
Projected market size by 2033
USD 228.8 million
Growth rate
CAGR of 12.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/thousand, volume in kilotons/tons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; Netherlands; Norway; China; Japan; India; South Korea; Australia; Malaysia; Indonesia; Thailand; Brazil; Argentina; Saudi Arabia; UAE; South Africa.
Key companies profiled
TORAY INDUSTRIES, INC.; Polyplex; TEIJIN LIMITED; KURARAY CO., LTD.; Qingdao Kingchuan Packaging; Far Eastern New Century Corporation; PLASTIPAK HOLDINGS, INC.; Anellotech; Indorama Ventures Public Company Limited; Carbios; NatureWorks LLC; UFlex Limited; FKuR; Saipet Samartha Private Limited; Iwatani Corporation; LOTTE Chemical Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Bio-PET Film Market Report Segmentation
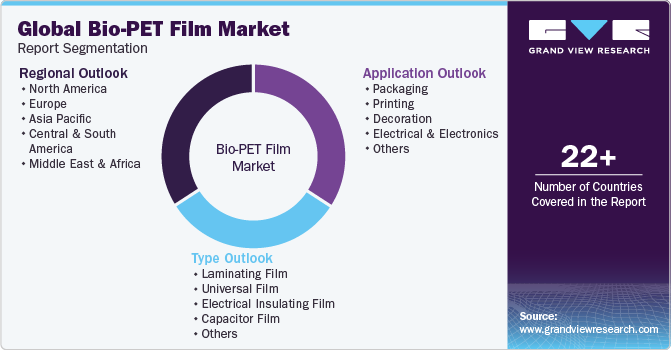
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global bio-PET film market report based on type, application, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Laminating Film
-
Universal Film
-
Electrical Insulating Film
-
Capacitor Film
-
Others
-
-
Application Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Packaging
-
Printing
-
Decoration
-
Electrical & Electronics
-
Others
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Netherlands
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
Indonesia
-
Malaysia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The Bio-PET film market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Bio-PET film segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Laminating Film
Revenue is captured through the sale of bio-PET laminating films used in packaging, labels, protective laminates, and industrial applications requiring strong adhesion, optical clarity, and durability. Demand is supported by their ability to enhance surface protection, printability, and sustainable packaging performance across consumer and commercial end uses.
Universal Film
Revenue is captured through the supply of versatile bio-PET universal films used across multiple applications, including packaging, graphics, insulation, and converting operations. Sales are driven by the film’s flexibility, processability, transparency, and compatibility with a wide range of coating, printing, and lamination requirements.
Electrical Insulating Film
Revenue is captured through bio-PET films designed for electrical insulation in batteries, capacitors, motors, cables, and other electronic components. Demand is supported by their thermal stability, dielectric strength, mechanical reliability, and suitability for high-performance and sustainability-focused electronic applications.
Capacitor Film
Revenue is captured through the use of bio-PET capacitor films in energy storage and electronic devices that require stable dielectric performance and precise dimensional control. Growth is driven by demand for reliable, lightweight, and environmentally responsible materials in advanced electrical and power applications.
Others
Revenue is captured through niche and emerging bio-PET film formats, including specialty coated films, technical films, and customized variants serving medical, industrial, renewable energy, and research applications. These sales are typically driven by material innovation, application-specific performance needs, and sustainability initiatives that extend beyond core film categories.
Segment - Application
Revenue Capture Definition
Packaging
Revenue is captured through the sale of bio-PET films used in flexible packaging, food and beverage packaging, consumer goods packaging, and specialty packaging applications. Demand is supported by their excellent barrier properties, transparency, mechanical strength, and ability to enhance sustainability objectives while maintaining product protection and shelf-life performance.
Printing
Revenue is captured through the use of bio-PET films in printing applications, including graphic arts, labels, advertising materials, and specialty printed products. Sales are driven by the film’s superior printability, dimensional stability, surface quality, and compatibility with various printing technologies that support high-quality visual presentation and branding requirements.
Decoration
Revenue is captured through bio-PET films utilized in decorative applications such as furniture finishes, interior décor, automotive trims, consumer products, and surface enhancement solutions. Demand is supported by their aesthetic appeal, durability, scratch resistance, and ability to provide premium visual effects while supporting environmentally responsible material choices.
Electrical & Electronics
Revenue is captured through the supply of bio-PET films used in electrical insulation, electronic displays, flexible circuits, batteries, capacitors, and other electronic components. Growth is driven by demand for materials offering thermal stability, dielectric performance, mechanical reliability, and sustainability benefits in advanced electronic and electrical applications.
Others
Revenue is captured through niche and emerging applications of bio-PET films across medical devices, renewable energy systems, industrial products, construction materials, and research-oriented technologies. These sales are typically supported by application-specific performance requirements, ongoing material innovation, and increasing adoption of sustainable film solutions beyond mainstream end-use sectors.
Estimation Model
Layer Name
Key Question
Description
Top-Down Bio-PET Film Demand Scan Layer
What defines market boundaries?
This layer starts with global Bio-PET film demand across packaging, printing, decoration, electrical & electronics, and other industrial applications, then filters consumption intensity based on sustainable packaging adoption, consumer goods production, electronics manufacturing activity, renewable energy investments, and regulatory support for bio-based materials.
Application Mix Validation Layer
Where is demand generated?
This layer evaluates the demand split between packaging, printing, decoration, electrical & electronics, and specialty applications to align market revenue with performance requirements, sustainability objectives, barrier property needs, aesthetic enhancement functions, and application-specific film specifications.
Film Consumption Conversion Layer
Who captures market revenue?
This layer converts end-product production volumes into Bio-PET film revenue by applying film consumption rates, adoption levels of bio-based materials, film thickness specifications, multilayer packaging requirements, printing and lamination usage patterns, and qualification standards across end-use industries.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing Asia Pacific’s packaging and electronics manufacturing base, North America’s sustainable consumer goods and renewable energy investments, and Europe’s circular economy initiatives and bio-based material adoption trends to verify regional market assumptions and growth forecasts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed breakdown of the Bio-PET Film market across North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa, including country-level demand assessment, consumption trends, regulatory influences, sustainability adoption, and end-use industry concentration.
Enables identification of high-growth regional markets, investment priorities, expansion opportunities, and region-specific demand drivers influencing Bio-PET film adoption.
Cross-Segmentation
Comprehensive analysis of market intersections by Film Type (Laminating Film, Universal Film, Electrical Insulating Film, Capacitor Film, Others) and Application (Packaging, Printing, Decoration, Electrical & Electronics, Others) across key geographic regions.
Provides deeper visibility into high-value growth pockets, application-specific demand trends, and strategic product positioning opportunities within target markets.
Trade Assessment
Analysis of global import-export trends, major supplying and consuming countries, trade flows, tariff structures, regulatory requirements, and supply chain dependencies affecting Bio-PET film markets.
Assists in supply chain optimization, sourcing decisions, risk assessment, market entry planning, and identification of trade-driven growth opportunities.
Frequently Asked Questions About This Report
The bio-pet film market is expected to grow at a compound annual growth rate of 12.6% from 2026 to 2033 to reach around USD 228.8 million by 2033.
The key players in the bio-pet film market are TORAY INDUSTRIES, INC.; Polyplex; TEIJIN LIMITED; KURARAY CO., LTD.; Qingdao Kingchuan Packaging; Far Eastern New Century Corporation; PLASTIPAK HOLDINGS, INC.; Anellotech; Indorama Ventures Public Company Limited; Carbios; NatureWorks LLC; UFlex Limited; FKuR; Saipet Samartha Private Limited; Iwatani Corporation; LOTTE Chemical Corporation.
The rising sustainability and environmental concerns among people across the globe are positively influencing the market growth. Moreover, factors such as the inclination toward bioplastics, favorable government policies, and increasing application of bio-polyethylene terephthalate (PET) films in packaging, printing, electrical & electronics, pharmaceutical, and cosmetic sectors are driving the demand for bio-PET films.
Packaging segment held the largest market share of 37.8% in 2025.
The Asia Pacific Bio-PET film market accounted for the largest revenue share of 35.8% market size in 2025.
India Bio-PET film market is expected to grow at the fastest compound annual growth rate of 15.0%.
Based on type, the laminating film segment accounted for the largest share of 36.4% market size in 2025. Growing demand for sustainable packaging, premium labeling, and protective surface applications is driving the adoption of Bio-PET laminating films due to their excellent clarity, durability, adhesion performance, and reduced environmental footprint.
The electrical insulating film segment based on type is expected to grow at a CAGR of 13.1% for the forecast period.
The bio-pet film market was estimated at around USD 86.2 million in the year 2025 and is expected to reach around USD 96.8 million in 2026.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


