
- Home
- »
- Medical Devices
- »
-
Biological Skin Substitutes Market Size, Share Report, 2033GVR Report cover

Biological Skin Substitutes Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Human Donor Tissue-derived Products, Acellular Animal-derived Products), By Application (Acute Wound, Chronic Wound), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$376.9MMarket Estimate, 2026
$409.4MMarket Forecast, 2033
$764.0MCAGR, 2026–2033
9.3%Biological Skin Substitutes Market Summary
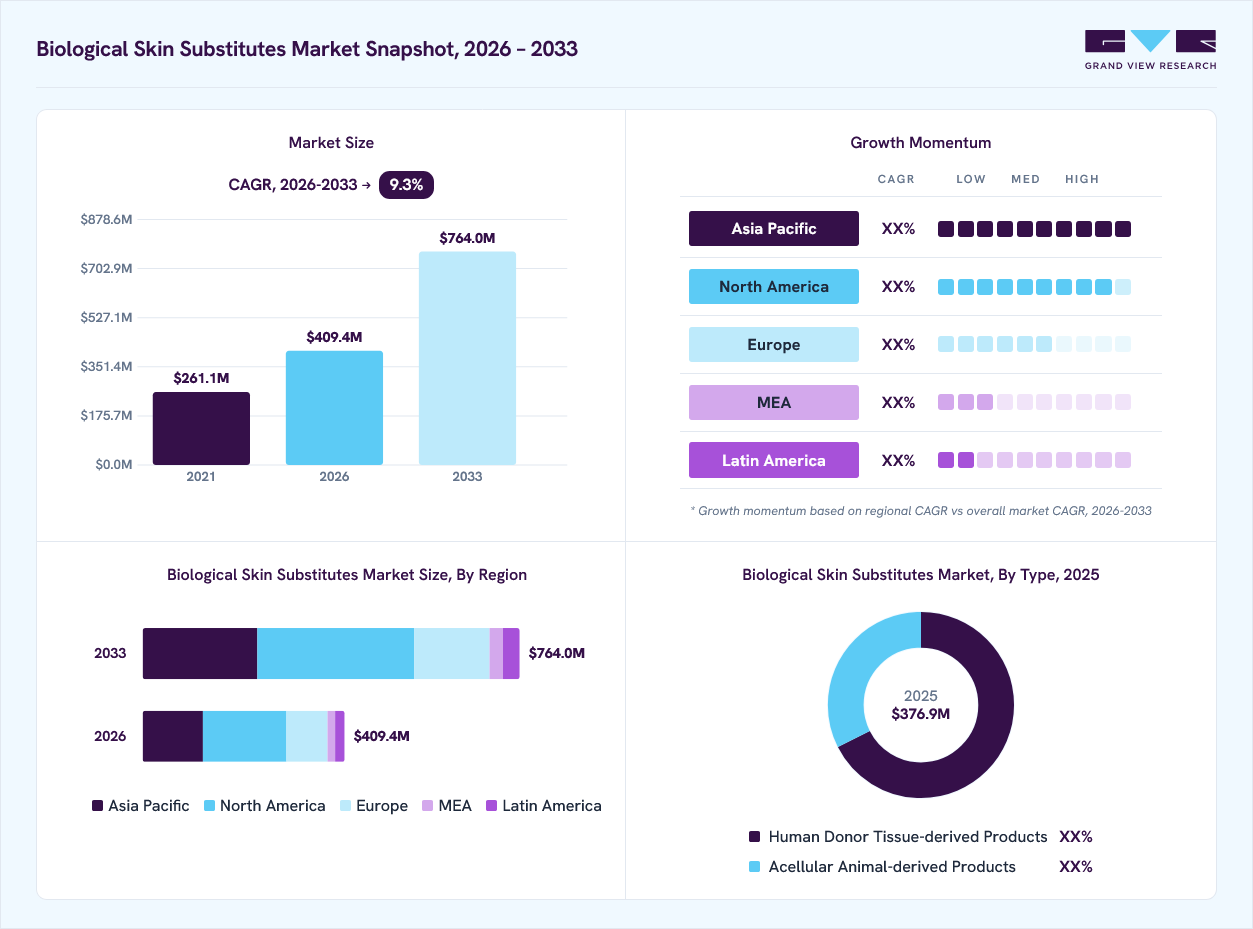
The global biological skin substitutes market size was valued at USD 376.9 million in 2025 and is projected to grow from USD 409.4 million in 2026 to USD 764.0 million by 2033, at a CAGR of 9.3% from 2026 to 2033.North America dominated the market, accounting for a revenue share of 41.3% in 2025. The market is driven by the rising prevalence of chronic wounds, such as ulcers and burn injuries, medical technology advancements, the geriatric population, and surgical procedures.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Human donor tissue-derived products segment dominated the market, with a revenue share of 67.5% in 2025.
- By application: Acute wound segment held the largest market share of 57.7% in 2025.
- By end use: Hospitals segment accounted for the largest revenue share of 54.9% in 2025.
Regional Highlights
- Largest regional market: North America (41.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 376.9 million
- Estimated market size in 2026: USD 409.4 million
- Projected market size by 2033: USD 764.0 million
- CAGR (2026-2033): 9.3%
Prism AI by Grand View Research Free to tryAsk a question about the biological skin substitutes marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
These products are materials used to temporarily or permanently act as an alternative and cover open wounds. They can be made from a variety of biological or biosynthetic materials. The prevalence of chronic wounds such as diabetic foot ulcers, pressure ulcers, and venous leg ulcers has increased in recent years, which is anticipated to increase the demand for effective treatment options. For instance, according to the data published by Uintah Basin Healthcare in June 2024, there are about 7 million people affected by chronic wounds in America, out of which nearly 2 million people have diabetic foot ulcers. It is noted that among every four families, there is at least one member living with chronic wounds.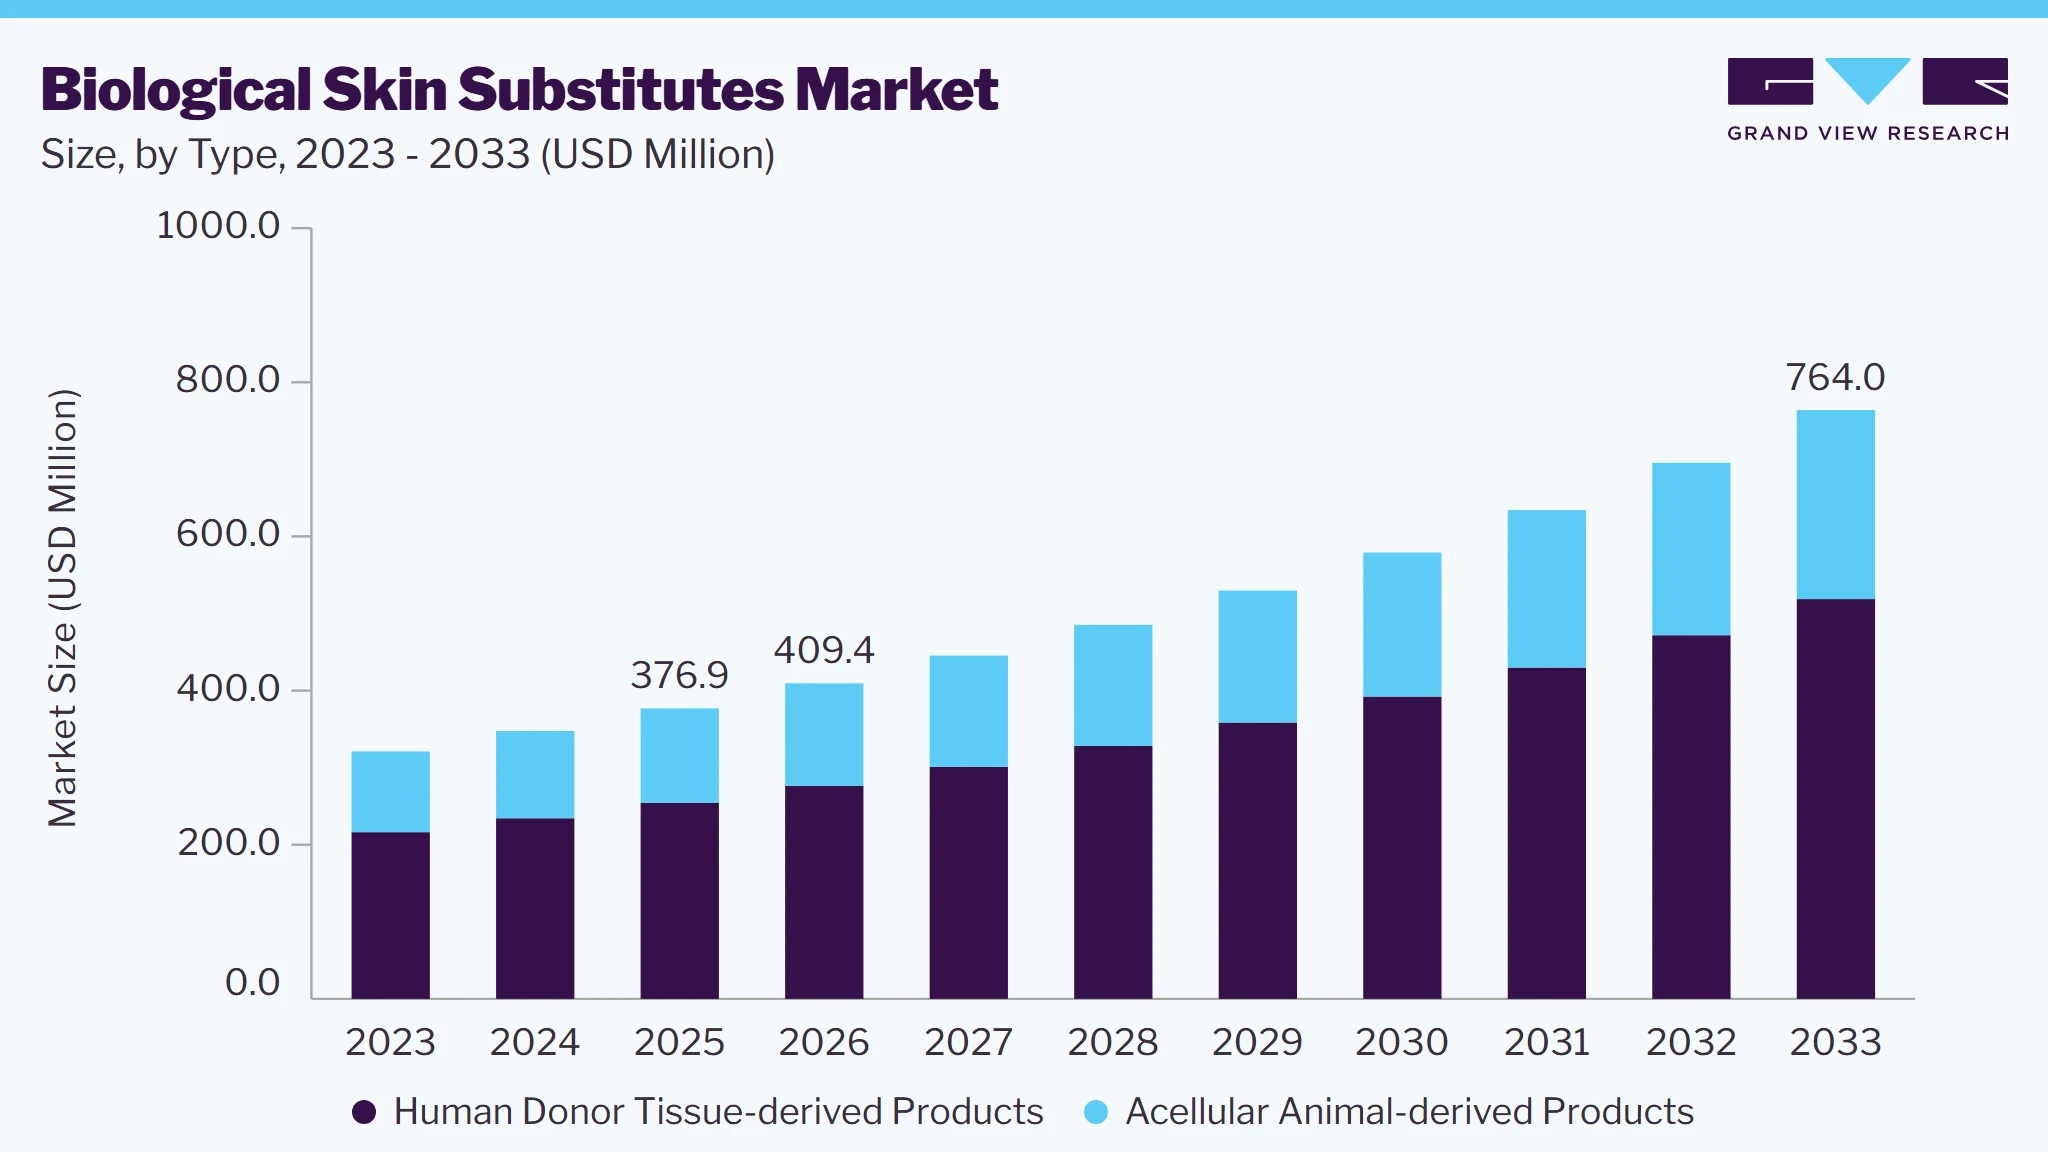 To learn more about this report, Download Free Sample Report
Moreover, as per the review published by John Wiley & Sons, Inc. in February 2024, venous leg ulcer has a prevalence of 1 %, followed by 22% recurrence of the condition within 3 months, which increases to 78 % in a span of 3 years. This high prevalence upsurges the demand for advanced wound care products, such as biological dermal substitutes, to promote healing & reduce complications associated with chronic wounds and drive the market growth.
The growing burden of trauma across the world is anticipated to fuel the demand for wound care products, including skin substitutes. According to the factsheet the World Health Organization presented in October 2023, approximately 18,000 deaths occur annually, especially in low and middle-income countries. Females are slightly at higher risk of burns, as per recent findings. Furthermore, burns can lead to severe complications, such as infections, scarring, and loss of dermal function, necessitating advanced wound care solutions like biological skin substitutes and thus fueling the adoption.
The advent of innovative dermal substitutes, including bioengineered skin grafts, marks a significant milestone in medical treatments and offers more advantages over conventional materials. Many companies are undertaking studies to provide novel skin substitutes for wound management. For instance, in May 2024, as per the article published by the European Patent Organization, Fertram Sigurjonsson and his team designed a product utilizing fish skin, which offers numerous advantages over other wound-healing products. Such developments in the market will increase revenue in the coming decade
Market Dynamics
The rising incidence of burns and traumatic injuries is a significant driver of the biological skin substitutes market. Burn wounds, surgical trauma, and accident-related injuries often require advanced wound care products that support tissue regeneration and accelerate healing. Collagen dressings help maintain a moist wound environment, promote granulation tissue formation, and reduce healing time, making them well-suited for managing complex wounds. As the global burden of trauma and burn injuries continues to increase, demand for collagen-based wound care solutions is expected to grow significantly.
Burn Care Statistics in the U.S. (2020-2024)
Metric
Value
Burn injury cases in 2024
32,993
Total burn cases (2020–2024)
162,799
Number of burn centers
114
Geographic coverage
38 states and the District of Columbia
Source: American Burn Association
Limited reimbursement coverage is exemplified by several payer restrictions that affect the use of biological skin substitutes. In the U.S., the Centers for Medicare & Medicaid Services (CMS) requires chronic wounds to demonstrate inadequate healing after a defined period of standard care before skin substitutes become eligible for reimbursement, and coverage is often restricted to specific products and limited to a few applications. Local Coverage Determinations (LCDs) issued by Medicare Administrative Contractors may further vary by region, creating inconsistencies in access. Similarly, in many low- and middle-income countries, the absence of dedicated reimbursement pathways for advanced wound care shifts treatment costs to hospitals or patients, thereby limiting the routine use of biological skin substitutes despite their clinical benefits.
Advances in tissue engineering and three-dimensional (3D) bioprinting offer significant growth opportunities for the biological skin substitutes market. These technologies enable the fabrication of skin constructs that more closely replicate the native architecture of human skin by precisely placing cells, biomaterials, and bioactive components. Improved vascularization, customization to patient-specific wound characteristics, and the potential integration of multiple skin layers could enhance therapeutic outcomes and expand clinical applications. As research advances toward scalable, commercially viable products, next-generation bioengineered skin substitutes are expected to drive innovation and open new avenues for market expansion.
Market Concentration & Characteristics
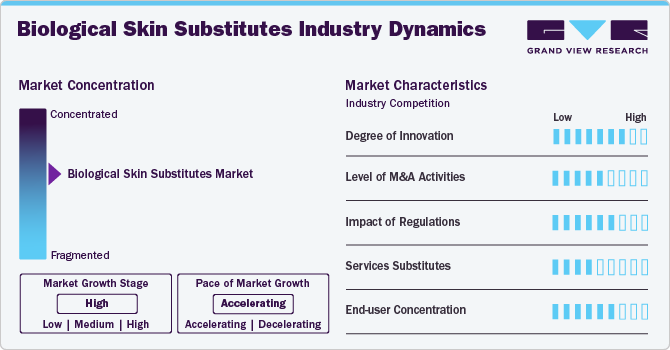
The market growth stage is high, and the pace is accelerating. The market is characterized by high growth due to the increasing prevalence of chronic conditions such as diabetic foot ulcers, venous ulcers, trauma injuries, and others.
The market is experiencing high levels of innovation driven by advancements in procedures, tissue engineering, and novel material technologies. Continuous research and development efforts focus on enhancing product safety, precision, and patient outcomes. Innovations, such as next-generation skin substitutes, address unmet needs, offering more effective treatment options for skin conditions. For instance, in September 2022, MiMedx Group, Inc. launched AXIOFILL, an Extracellular matrix (ECM) derived from human placental tissue useful for surgical recovery procedures.
Regulatory authorities, such as the European Medicines Agency (EMA) and the U.S. Food and Drug Administration (FDA), play a vital role in shaping the market. Stricter requirements for clinical trials and post-market surveillance ensure patient safety and product efficacy but can pose challenges for companies seeking approvals. This provides patients' safety and encourages companies to maintain good standards while developing products.
 To learn more about this report, Download Free Sample Report
The market is poised to experience mergers and acquisitions (M&A) activity as companies seek to expand their product portfolios, leverage partnerships, and enter new markets. Established players are acquiring smaller innovators to gain access to cutting-edge technologies, while strategic collaborations are emerging to enhance distribution networks. For instance, in March 2023, BioTissue expanded its distribution and manufacturing facility in Doral, Florida, to meet the growing demand for biologics.
The availability of product substitutes is less; however, it slightly impacts the market, with alternatives such as artificial skin substitute dressings. Although devices like allografts and xenografts are preferred for severe skin conditions, temporary dressings may offer viable solutions in early-stage interventions.
Market players are actively pursuing regional expansion to capitalize on emerging market opportunities. Growth in Asia-Pacific, North America, and Europe is robust, driven by increasing healthcare investments, rising awareness of chronic disorders, and improving access to advanced medical technologies. Companies are also establishing local manufacturing units and forging partnerships with regional distributors to navigate market-specific challenges and regulatory frameworks.
Analyst Perspective
The biological skin substitutes market is experience significant growth, driven by the rising burden of chronic wounds, the increasing incidence of burns and traumatic injuries, and the growing demand for advanced wound care solutions that promote faster healing and reduce complications. Continuous advancements in regenerative medicine and tissue engineering are driving the development of more effective, biologically active products with improved clinical outcomes. The expanding adoption of these products in hospitals, outpatient wound care centers, and home healthcare settings, along with favorable reimbursement policies in developed markets, is further strengthening market expansion. However, high product costs and stringent regulatory requirements remain key challenges, encouraging manufacturers to focus on innovation, strong clinical evidence, and strategic partnerships to enhance market competitiveness.
Regulatory And Reimbursement Trends
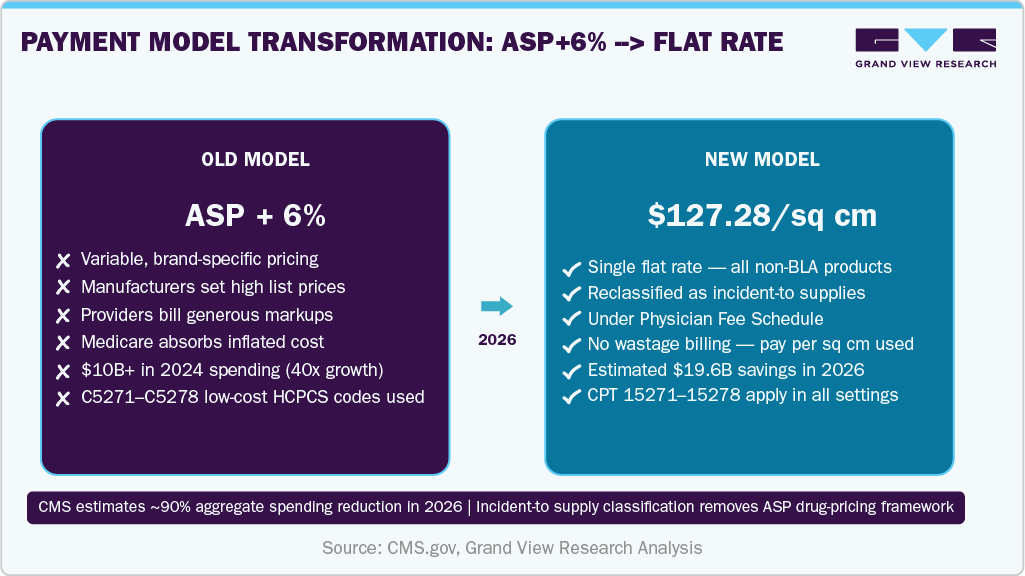
The regulatory and reimbursement landscape for biological skin substitutes is evolving significantly as healthcare payers and regulators seek to balance innovation with cost containment. In the U.S., the Centers for Medicare & Medicaid Services (CMS) has implemented reimbursement reforms under the CY 2026 Medicare Physician Fee Schedule (PFS) to improve payment accuracy and ensure appropriate utilization of skin substitute products. Under the revised framework, many skin substitutes used in chronic wound management are reimbursed as incident-to supplies rather than biological products, reflecting CMS’s efforts to align payments more closely with clinical value and resource utilization. These changes follow a substantial increase in Medicare expenditures on skin substitutes over recent years, prompting greater scrutiny of product pricing, clinical effectiveness, and utilization patterns. In addition, CMS is emphasizing evidence-based coverage decisions, requiring manufacturers to generate strong clinical and health-economic data to support favorable reimbursement. As a result, companies operating in the biological skin substitute market are facing strengthened regulatory oversight while also being encouraged to demonstrate superior clinical outcomes and cost-effectiveness to maintain market access and reimbursement eligibility.
 To learn more about this report, Download Free Sample Report
Type Insights
Based on type, the human donor tissue-derived products segment dominated the biological skin substitutes market with a market share of 67.5% in 2025 and is expected to grow at the fastest CAGR during the forecast period. These products are more common as they are derived from human tissues such as skin, bone, tendons, etc. As humans are a common source, patients’ bodies readily accept and minimize the chance of rejection by the immune system. Extensive research in the field, followed by the introduction of new products in the market, is anticipated to boost the segment growth. For instance, in October 2024, BioLab Sciences launched “Tri-Membrane Wrap,” a triple-layered human tissue allograft constructed from the amniotic membrane, which perfectly protects deep wounds and poorly located areas. This product is designed to be robust and provide optimum tensile strength for easy sutures, thus exhibiting better protectant covering.
The acellular animal-derived products segment is anticipated to grow from 2025 to 2030. These biomaterials created from animal tissues, such as porcine or bovine sources, have undergone decellularization. Due to the absence of cellular components, they support tissue regeneration without triggering an immune response. Several studies are focusing on the effectiveness of acellular animal-derived skin substitutes over other alternatives. For instance, according to the review published in April 2024, acellular fish skin grafts are regarded as more suitable for treating diabetes wounds of different depths. Such positive results from the studies using acellular animal-derived products for wound management are anticipated to boost segment growth in the coming years.
Application Insights
Based on application, the acute wound segment dominated the biological skin substitutes market with a market share of 57.7% in 2025. The segment is primarily driven by the increasing incidence of traumatic injuries, burns, and surgical wounds, which require rapid and effective healing solutions. In addition, the growing demand for effective and efficient wound-healing solutions is anticipated to boost the segment growth during the study period. For instance, AlloSkin RT is a human tissue-derived meshed[AP3] [SP4] allograft for dermal and epidermal acute wound healing. Cytal Burn Matrix, derived from a porcine source, is indicated for treating burns. Thus, the availability of both allografts and xenografts for treating acute wounds is expected to contribute to segment growth.
The chronic wound segment is expected to witness the fastest growth of CAGR over the forecast period owing to the increasing prevalence of chronic wounds such as diabetic foot ulcers, venous leg ulcers, pressure ulcers, etc. For instance, according to the article published by Springer Nature Limited[AP3] [SP4] in January 2024, diabetic individuals have a 25% chance to encounter diabetic foot, which increases the risk of amputation. Such conditions attract the focus of physicians to provide better living to patients by using biological skin substitutes. Furthermore, the technological advancements in the development of allografts and xenografts, such as stem cells, growth factors, and other biomaterials, have led to the production of more effective wound-healing solutions for chronic wounds.
End Use Insights
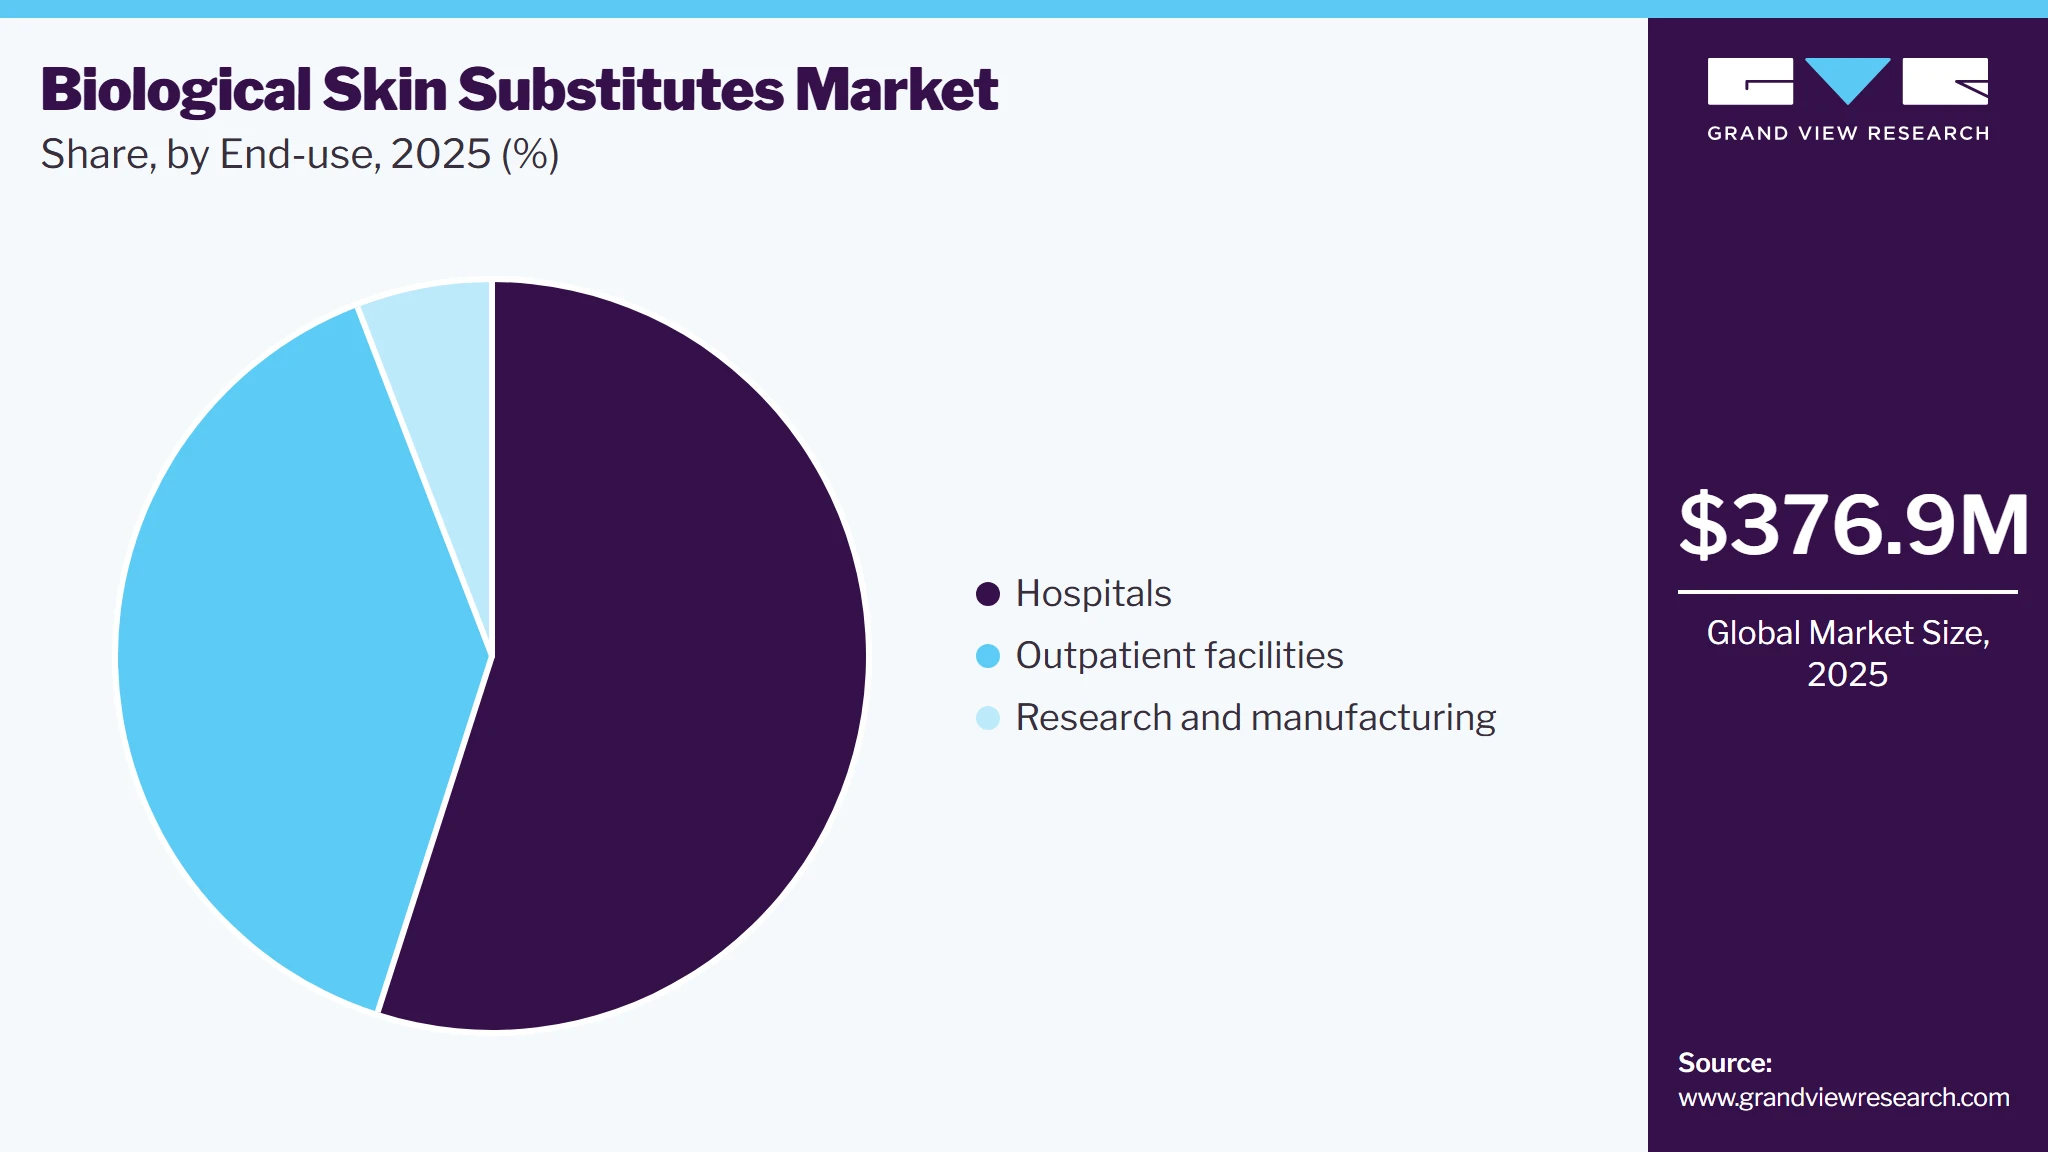
Based on end-use, the hospitals segment dominated the biological skin substitutes market with a market share of 54.9% in 2025. The segment’s growth can be attributed primarily to the increasing patient pool suffering from severe injuries such as burns, surgical cases, and others. For instance, according to the data published by Stewarts Law LLP in October 2023, around 2, 50,000 [people suffer from burn injuries every year in the UK, out of which 16,000 people are severely burnt and are hospitalized. Majority of the severely burnt patients are children below the age of 5 years. Moreover, according to the article published by the Journal of Burn Care & Research in October 2024, a cohort stu dy was performed to find out that patients who were hospitalized due to burns had a median admission time of 55 hours. Furthermore, hospitals are preferred over other healthcare settings as they provide comprehensive care to patients with complex medical needs. Also, as the number of hospitals is increasing, the segment is expected to contribute more revenue to the biological skin substitute market in the coming years.
 To learn more about this report, Download Free Sample Report
The outpatient facilities segment is expected to witness the fastest growth of CAGR over the forecast period. These include ambulatory surgery centers and specialty facilities outside the hospital. The advantages associated with outpatient facilities, including shorter procedure time, comparatively low cost, and same-day discharge compared to hospitals, are anticipated to support the segment growth in the coming years. The growing number of outpatient facilities is expected to boost the segment growth.
Regional Insights
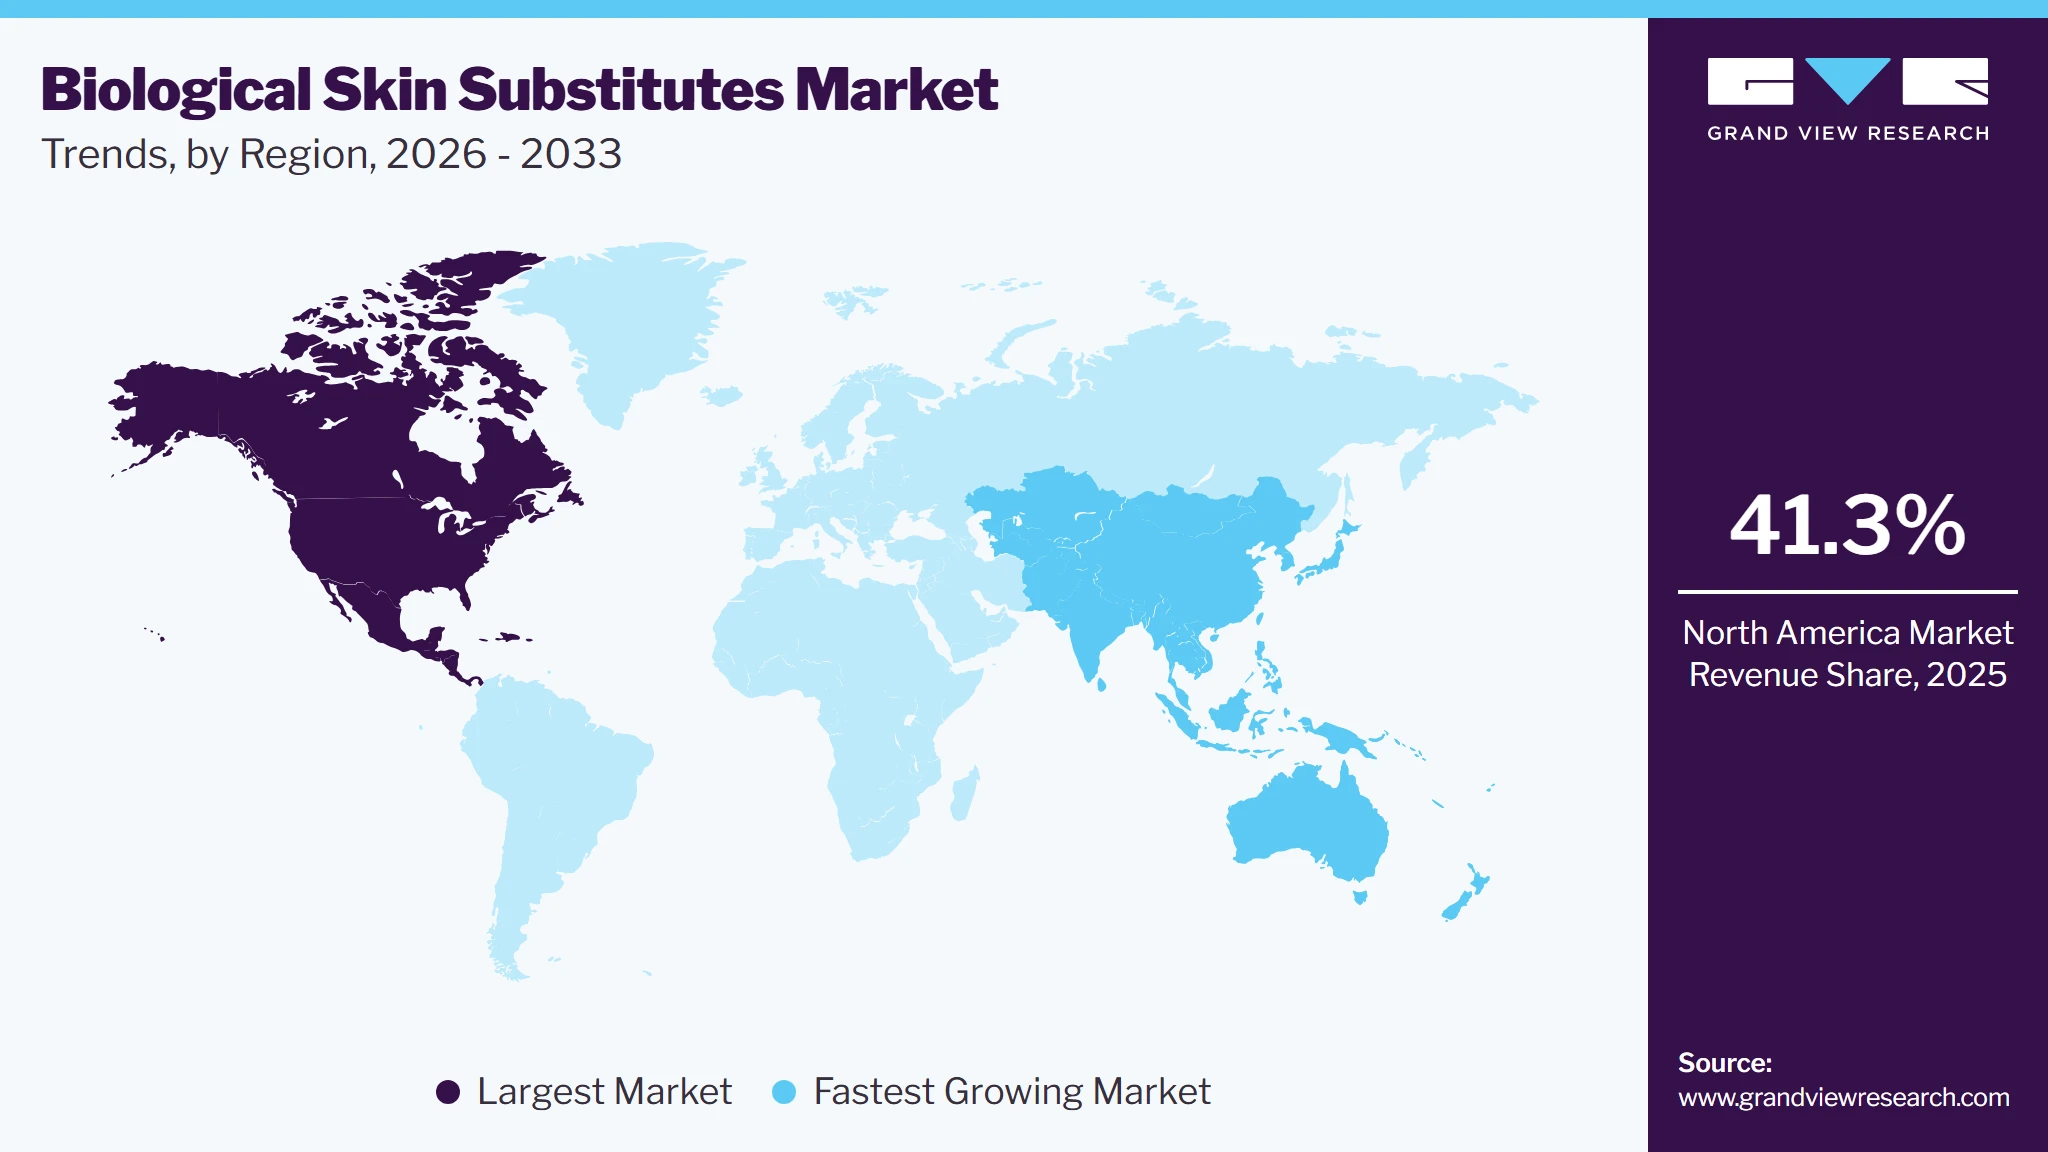
NNorth America dominated the biological skin substitutes market with the largest revenue share of 41.3% in 2025 owing to the increasing demand for Advanced Wound Care (AWC) products and the rising incidence of burn injuries & chronic wounds. The market is dominated by a few major players, including companies such as Integra LifeSciences Corporation, Smith+Nephew, Stryker, and 3M. These companies and other organizations are investing heavily in R&D to improve the quality and efficacy of their products. For instance, as per the news published in January 2024, MTF Biologics- a non-profit organization has awarded a funding of more than USD 930,000 to six different organizations under its 2023 Innovation in Allograft Translational Research Grant Program. Such grants will further expand the allograft technology and support the growth of North America's biological skin substitute market in the coming years.
 To learn more about this report, Download Free Sample Report
U.S. America Biological Skin Substitute Market Trends
The biological skin substitutes market in the U.S. held the largest share in the North America region in 2025, driven by the increasing burden of chronic diseases. The growth in this region is supported by consistent research and product launches that increase the product portfolio in the sector and drive market growth biological skin substitutes. For instance, in September 2023, MiMedx Group, Inc., headquartered in the U.S., announced the launch of EPIEFFECT, a skin substitute product under its AWC products portfolio. Such developments and strategic activities in the region accelerate market growth.
The biological skin substitute market in Canada is anticipated to grow significantly over the forecast period. The country's healthcare coverage and compulsory insurance enable the adoption of advanced technologies. Many government organizations and other institutions undergo strategic activities to educate more people about new technologies and emphasize several wound management techniques and biological skin substitutes. For instance, according to the data presented in WoundsCanada.ca. on October 2024, the Wounds Canada National Hybrid Conference is going to be held in October 2024, which brings together various expert healthcare professionals to support healthcare professionals who treat wounded patients. Such meetings influence healthcare education and are expected to give rise to new ideas in the biological skin substitute market, further increasing market growth in the region.
Europe Biological Skin Substitute Market Trends
The Europe biological skin substitute market is driven by the increasing geriatric population in the region, growing incidences of chronic diseases, and increasing demand for innovative treatments for skin wounds, burns, and other dermatological conditions. For instance, according to the data extracted from Eurostat published in February 2024, 21.3% of the European population was 65 years old or more in January 2023. This large geriatric population increases the chances of chronic disorders such as diabetes and further boosts the market growth.
The biological skin substitute market in Germany contributed to a significant revenue share in the European market in 2024 owing to a rapid increase in diabetic population in the country; for instance, as per the article published in the journal Diabetologia in February 2024, it is projected that the number of patients having type 2 diabetes would increase by 54% to 77% by 2040 in Germany. In addition, 16% of deaths that occur in the country are caused due to diabetes. This increasing prevalence of chronic diseases will further increase the market demand and propel market growth during the forecast period.
Asia Pacific Biological Skin Substitute Market Trends
The Asia Pacific biological skin substitutes market is experiencing rapid growth due to the rising prevalence of skin-related disorders, chronic diseases, and trauma patients. Rapid economic growth in the region is expected to drive the demand for innovative, improved technologies and attempts to create treatments and products suitable for managing wounds. Improving healthcare infrastructure in the highly populous nations in APAC, such as India, China, and Japan, is providing potential market opportunities and attracting stakeholders to expand their portfolios in the Asia Pacific market.
For instance, as per the study reported in the Chinese Journal of Traumatology, approximately 1.7% of patients in China require hospitalization due to chronic wounds, with the majority being individuals aged 40-60 years old (31%) and 60-80 years old (38%). Rising geriatric population, increased life expectancy, and significant presence of nonprofit organizations, such as the Japan Society for Surgical Wound Care, the Japanese Society for Wound Healing, and the Japanese Society for Burn Injuries, are further contributing to market growth in Asia Pacific region.
Latin America Biological Skin Substitutes Market Trends
The biological skin substitute market in Latin America is experiencing significant growth, primarily driven by growing investments and increasing free-trade agreements with major countries, such as the U.S., Canada, Japan, & several European countries. Due to the lower costs of medical treatments in the region and the availability of advanced treatment options at reasonable prices, medical tourism is anticipated to rise in the coming years. This will create lucrative opportunities for market growth in the region.
Middle East and Africa Biological Skin Substitutes Market
The Middle East and Africa biological skin substitute market is experiencing significant growth, primarily driven by growing investments and increasing free-trade agreements with major countries, such as the U.S., Canada, Japan, & several European countries. Due to lower costs of medical treatments in the region, and availability of advanced treatment options at reasonable prices, medical tourism is anticipated to rise in the coming years. This will create lucrative opportunities for market growth in the region.
The biological skin substitute market in Saudi Arabia is growing due to growing geriatric population, increasing number of surgeries, and severe injuries in the region. Various unmet healthcare needs in low-income countries in the region increase the demand for better treatment options. Saudi Arabia is focusing on technological advancements such as the digitalization of the healthcare industry through AI, big data, cloud computing, and others. These advancements are resulting in shorter hospital stays and a rise in the number of surgical procedures, driving the demand for wound care supplies.
Key Biological Skin Substitute Company Insights
Key market players are focusing on research studies to bring innovative types of biological skin substitutes, growth strategies, and collaborations. For instance, MiMedx Group, Inc. c formed an agreement with TELA Bio, Inc. in March 2024 to acquire the rights to commercialize bovine-derived collagen matrix particulates for exudating wound management.
Key Biological Skin Substitute Companies:
The following key companies have been profiled for this study on the biological skin substitute market.
-
Organogenesis Inc.
-
Integra LifeSciences Corporation
-
Smith+Nephew
-
Tissue Regenix
-
MIMEDX Group, Inc.
-
Essity Aktiebolag (publ))( Essity Health & Medical)
-
Stryker
-
Vericel Corporation
-
3M
-
BioTissue
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Organogenesis Inc., Integra LifeSciences Corporation, Smith+Nephew, MIMEDX Group, Inc.)
- Focus on expanding product portfolios through line extensions and next-generation graft technologies.
- Invest heavily in clinical trials to strengthen evidence supporting product efficacy and reimbursement.
- Strong brand recognition and physician trust built through extensive clinical use.
- Well-established reimbursement pathways and regulatory expertise.
- Higher product prices compared to newer alternatives.
- Large organizational structures slow innovation and decision-making.
Emerging Players (Tissue Regenix Group, New Horizon Medical Solutions LLC., BioTissue)
- Focus on niche technologies such as 3D bioprinting, stem cell-based constructs, and advanced biomaterials.
- Target unmet clinical needs and underserved indications with differentiated products.
- Greater agility and faster product development cycles.
- Ability to introduce disruptive and technologically advanced solutions.
- Limited commercial infrastructure and distribution capabilities.
- Lower brand awareness and restricted market penetration.
Recent Developments
- In October 2023, Tissue Regenix obtained authorization from the Irish Health Products Regulatory Authority (HPRA), which permitted it to set up a logistics hub in Ireland and distribute its allograft products in Europe, to facilitate market expansion.
- In May 2023, BioTissue entered in to a partnership with Dakota Lions Sight & Health to expand the birth tissue donation program in several hospitals and provide them an opportunity to donate placenta, which in turn increases the chances to develop and utilize placental derived dermal substitutes for regenerative treatments.
Biological Skin Substitute Market Report Scope
Report Attribute
Details
Market size in 2025
USD 376.9 million
Estimated market size in 2026
USD 409.4 million
Projected market size by 2033
USD 764.0 million
Growth rate
CAGR of 9.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Organogenesis Inc., Integra LifeSciences Corporation, Smith+Nephew, Tissue Regenix Group, MIMEDX Group, Inc., Stryker, New Horizon Medical Solutions LLC., Vericel, AlloSource, PolyNovo Limited, Zimmer Biomet, BioTissue, GUNZE LIMITED, Essity, Kerecis (Coloplast)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Biological Skin Substitute Market Report Segmentation
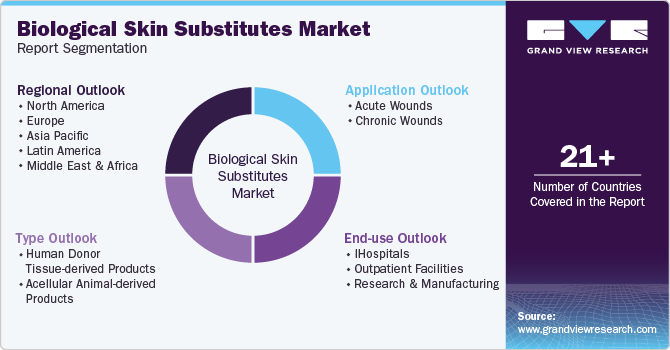
This report forecasts revenue growth at global, regional and country levels and provides an analysis on the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global biological skin substitute market report based on the type, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Human Donor Tissue-derived Products
-
Acellular Animal-derived Products
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Acute Wounds
-
Chronic Wounds
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Outpatient Facilities
-
Research & Manufacturing
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The biological skin substitutes market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each biological skin substitutes segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Human Donor Tissue-derived Products
Human donor tissue-derived products include biological skin substitutes derived from donated human tissues, such as amniotic membranes, placental tissues, and cadaveric skin. Revenue for this segment represents sales of these allogeneic products used in wound care, burn treatment, and reconstructive procedures.
Acellular Animal-derived Products
Acellular animal-derived products include biological skin substitutes manufactured from decellularized animal tissues, primarily porcine or bovine sources. Revenue for this segment comprises sales of these commercially available products used in the management of chronic wounds, burns, traumatic injuries, and reconstructive procedures.
Estimation Model
Modeling Approach
Description
Bottom-Up: Epidemiological & Procedure Volume Modeling
This approach models the precise clinical patient pathway by evaluating the total diagnosed prevalence of conditions like diabetes and cardiovascular diseases to establish an at-risk baseline for Diabetic Foot Ulcers (DFUs), Venous Leg Ulcers (VLUs), and severe burns. It filters the specific subset of chronic wounds that fall under standard-of-care conventional dressings and applies clinical adoption rates, average units consumed per treatment cycle, and penetration rates across wound severity grades to derive total market volume.
Top-Down: Vendor Revenue Triangulation
This approach establishes the absolute market ceiling and competitive landscape baseline by aggregating the supply-side revenues of leading, mid-tier, and emerging advanced wound care and biologic manufacturers. Data is extracted from corporate financial reports, investor day presentations, regulatory disclosures, and distributor-level sales tracking. The model cleanses the data by separating general wound care portfolios to purely isolate advanced biological skin substitutes and tissue-engineered grafts.
Demand-Side: Care-Setting & Institutional Modeling
This approach captures market value from the point of purchasing authority by tracking localized procurement budgets, order volumes, and buying patterns across key healthcare channels. It segments market demand by specific clinical environments. The model further factors in patient acuity, institutional treatment protocols, group purchasing organization (GPO) contracts, and specialty physician alignment.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Next-Generation Product Pipeline Analysis
Provided a comprehensive structural mapping of clinical-stage biologic skin substitutes currently under development (Phase I, II, and III pipeline assessment). Strategized an Expected Commercialization Timeline (2028–2030) detailing regulatory milestones and market-entry windows.
Identifies upcoming market disruptors and shifts in treatment paradigms. Empowers R&D teams and strategic planners to anticipate competitive threats, optimize clinical trial designs, and pinpoint high-value in-licensing or investment opportunities before product launch.
Competitive Product Benchmarking Dashboard
Developed an interactive benchmarking dashboard comparing leading commercialized biologic skin substitutes. Evaluated products head-to-head across cross-functional parameters: healing efficacy, average time to wound closure, cost per treatment, reimbursement coverage, clinical evidence strength (RCT data density), and cleared indications.
Equips product managers and commercial teams with a definitive tool to address product gaps, optimize pricing models against therapeutic value, and formulate high-targeted value propositions for hospital value analysis committees (VACs).
Country-Level Market Deep Dive
Delivered hyper-localized, country-specific market assessments across key mature and emerging geographies. Analyzed country-specific variables including local wound prevalence data, national healthcare reimbursement policies, localized pricing variations, and regional clinician adoption preferences.
Mitigates international expansion risks by highlighting specific structural barriers (e.g., restrictive reimbursement or tender processes) while uncovering high-growth, untapped geographies tailored to the client’s specific product profile.
Frequently Asked Questions About This Report
North America dominated the biological skin substitutes market with the largest revenue share of 41.3% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The human donor tissue-derived products segment dominated the biological skin substitutes market with a market share of 67.5% in 2025
The acute wound segment dominated the biological skin substitutes market with a market share of 57.7% in 2025.
The hospitals segment dominated the biological skin substitutes market with a market share of 54.9% in 2025.
The global biological skin substitute market was valued at USD 376.9 million in 2025 and is expected to reach USD 409.4 million by 2026.
The global biological skin substitute market is estimated to grow at a CAGR of 9.3% from 2026 to 2033 to reach USD 764.0 million by 2033.
Some key players operating in the biological skin substitutes market include Organogenesis Inc., Integra LifeSciences Corporation, Smith+Nephew, Tissue Regenix Group, MIMEDX Group, Inc., Stryker, New Horizon Medical Solutions LLC., Vericel, AlloSource, PolyNovo Limited, Zimmer Biomet, BioTissue, GUNZE LIMITED, Essity, Kerecis (Coloplast)
The increasing prevalence of chronic wounds and the rising number of burn & trauma cases are expected to drive the market growth.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


