
- Home
- »
- Medical Devices
- »
-
Biopharmaceutical Third-party Logistics Market Report, 2033GVR Report cover

Biopharmaceutical Third-party Logistics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Supply Chain (Cold Chain Logistics, Non-cold Chain Logistics), By Service Type (Transportation, Warehousing & Storage), By Region, And Segment Forecasts
Market Size, 2025
$152.0BMarket Estimate, 2026
$161.4BMarket Forecast, 2033
$258.4BCAGR, 2026–2033
6.9%Biopharmaceutical Third-Party Logistics Market Summary
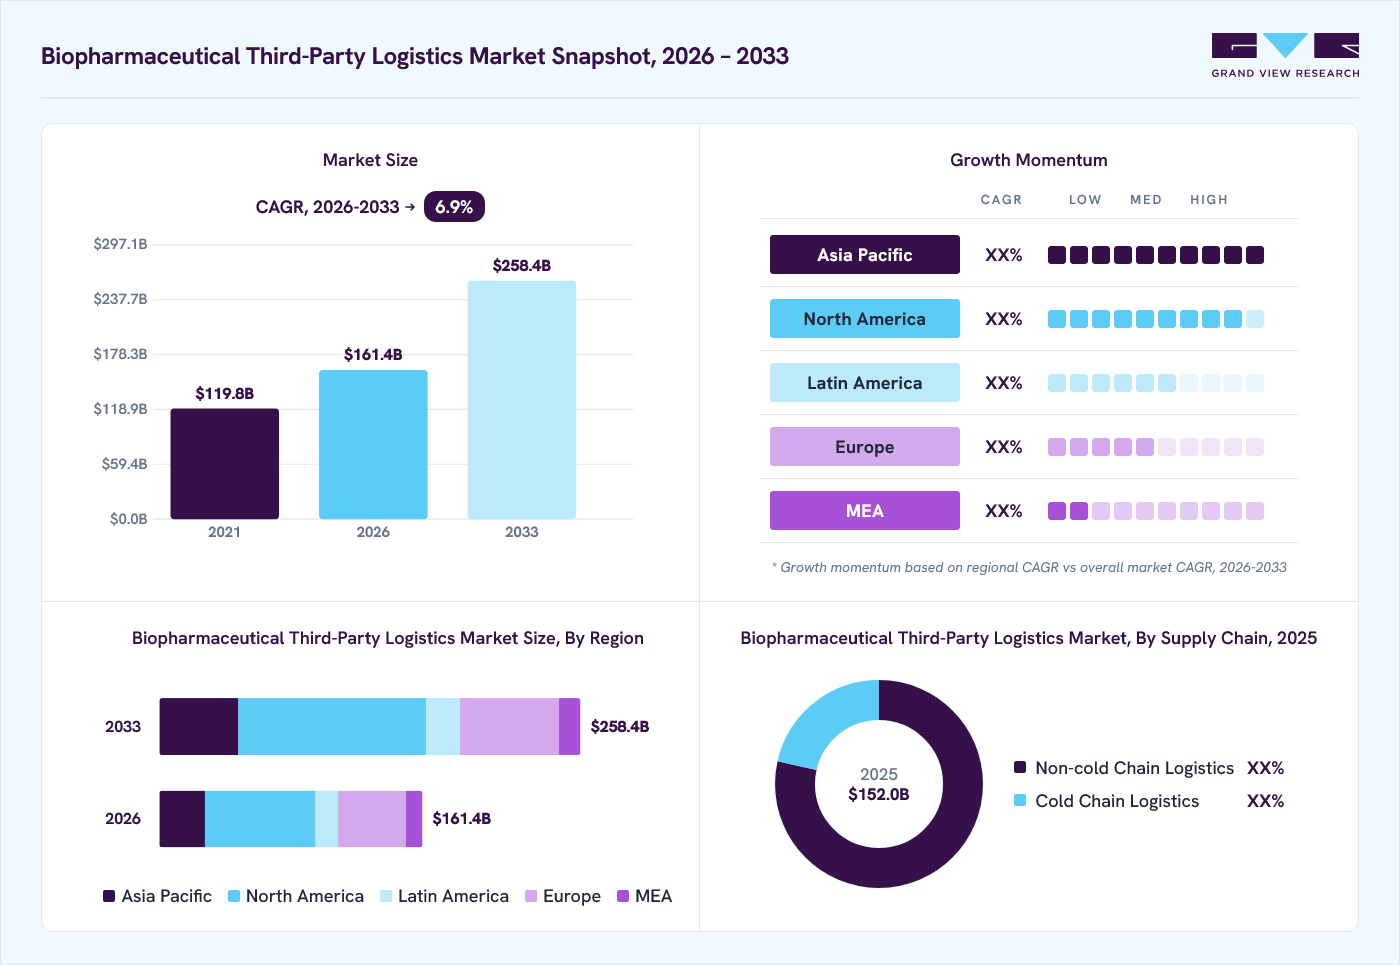
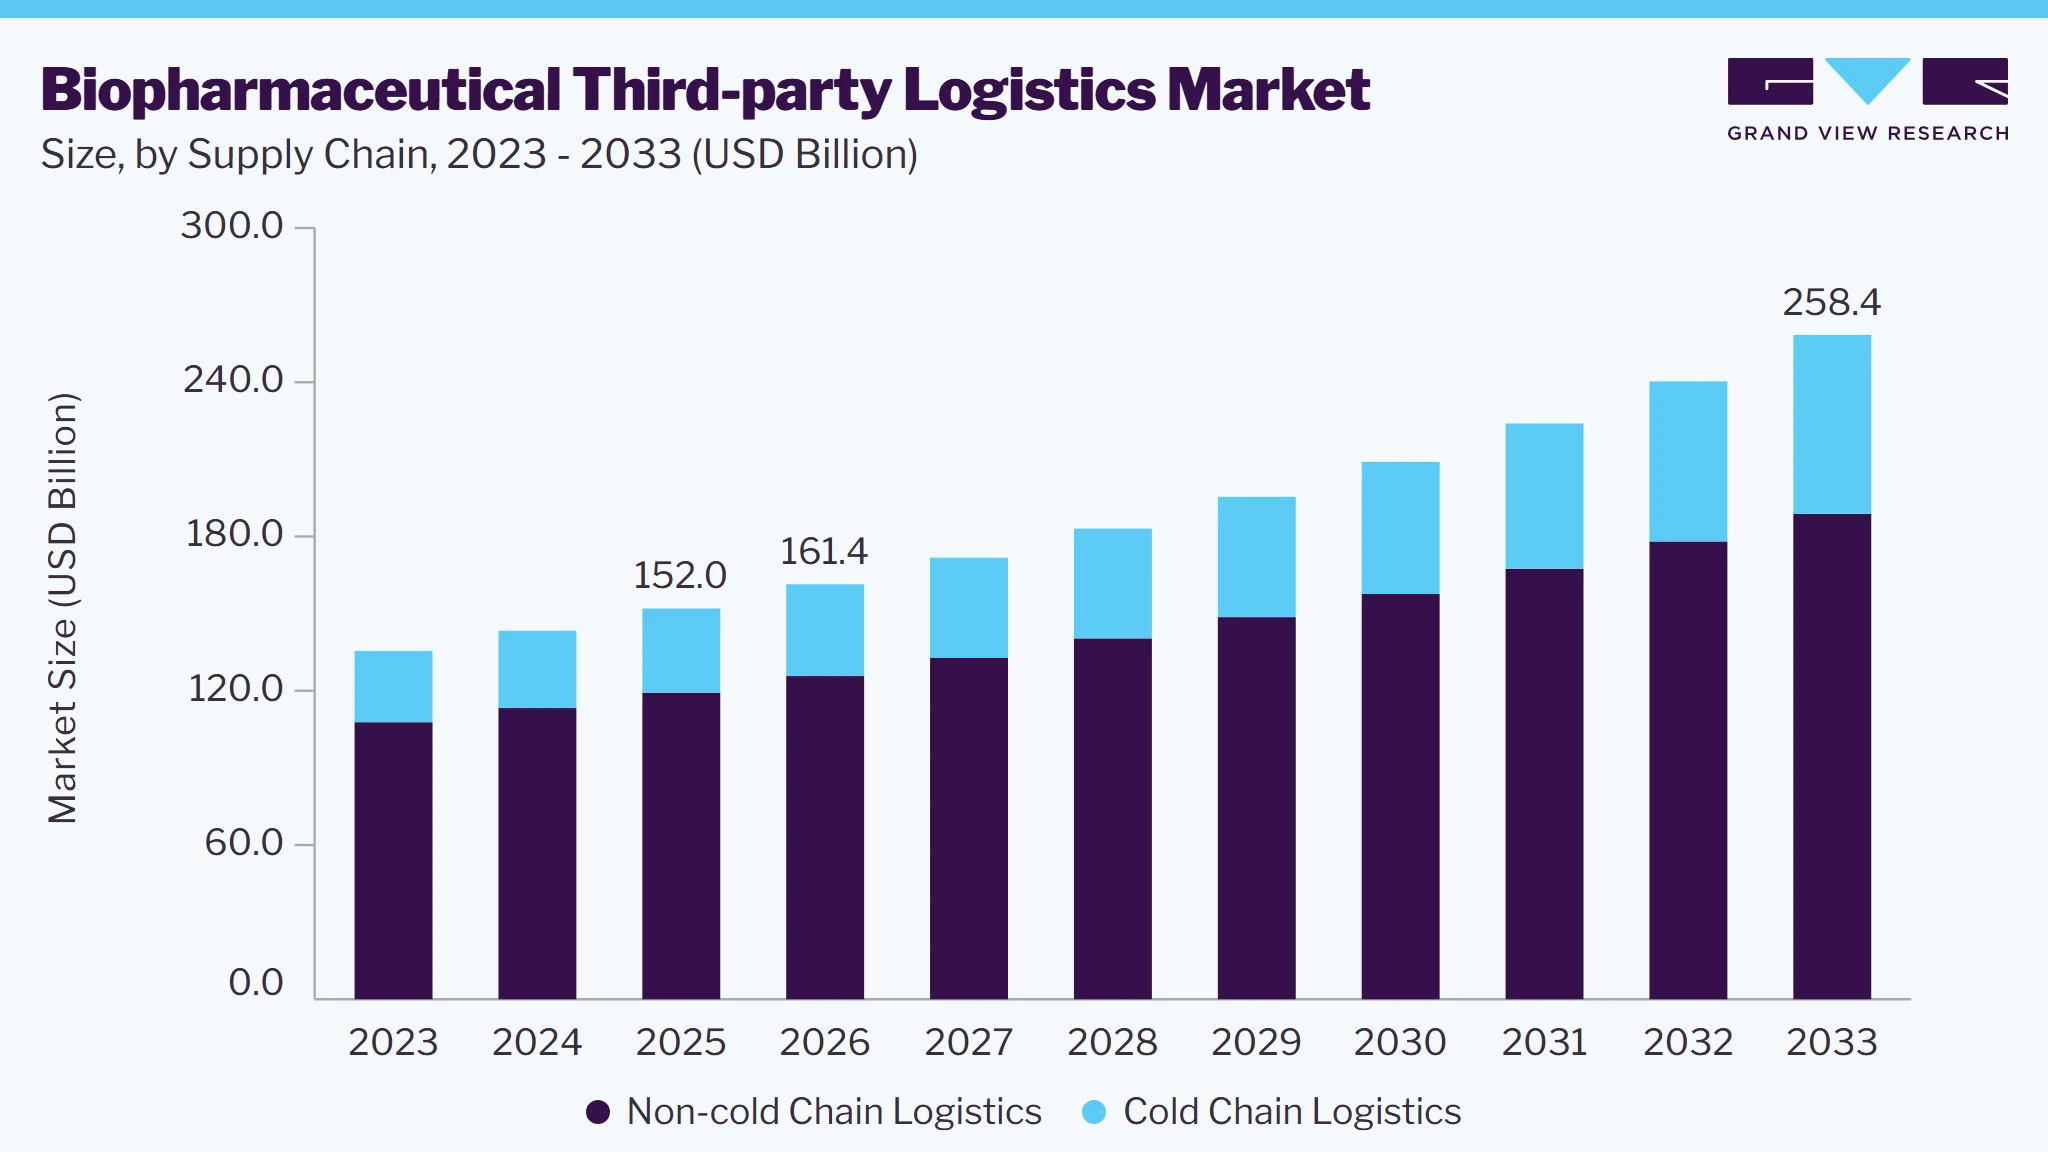
The global biopharmaceutical third-party logistics market size was valued at USD 152.0 billion in 2025 and is projected to grow from USD 161.4 billion in 2026 to USD 258.4 billion by 2033, at a CAGR of 6.9% from 2026 to 2033. North America dominated the market, accounting for the largest share of 41.7% in 2025. The biopharmaceutical third-party logistics (3PL) industry is experiencing robust growth, driven by the expanding commercialization of biologics and biosimilars, increasing demand for temperature-controlled and GDP-compliant logistics infrastructure, rising outsourcing of supply chain operations by pharmaceutical and biotechnology companies, growth in clinical trials and advanced therapies including cell and gene therapies, and continuous investments in digital supply chain technologies for end-to-end product visibility and regulatory compliance.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By supply chain: Non-cold chain logistics held the largest revenue share of 78.5% in 2025.
- By service type: Warehousing and storage held the largest revenue share of 43.1% in 2025.
Regional Highlights
- Largest regional market: North America (41.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest share in 2025.
Market Size & Forecast
- Market Size in 2025: USD 152.0 Billion
- Estimated Market Size in 2026: USD 161.4 Billion
- 2033 Projected Market Size: USD 258.4 Billion
- CAGR (2026-2033): 6.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increasing complexity of global biopharmaceutical distribution, combined with stringent handling requirements for temperature-sensitive products and growing cross-border pharmaceutical trade, is encouraging manufacturers to partner with specialized third-party logistics providers offering integrated transportation, warehousing, packaging, inventory management, and cold chain capabilities.The rapid expansion of biologics, biosimilars, and advanced therapies remains one of the primary factors driving market growth. Unlike conventional pharmaceuticals, biologics require specialized transportation, temperature-controlled storage, validated packaging, and continuous monitoring throughout the supply chain to preserve product efficacy and regulatory compliance. The growing commercialization of monoclonal antibodies, vaccines, recombinant proteins, and cell and gene therapies has significantly increased the demand for specialized logistics providers with GDP-certified infrastructure and global distribution networks.
 To learn more about this report, Download Free Sample Report
Furthermore, increasing outsourcing of pharmaceutical supply chain operations is another major driver supporting market expansion. Pharmaceutical and biotechnology companies are increasingly relying on specialized third-party logistics providers to optimize distribution efficiency, improve regulatory compliance, reduce operational costs, and enhance supply chain resilience across global markets. Managing highly regulated biopharmaceutical supply chains requires specialized expertise in cold chain management, customs clearance, serialization, inventory control, and last-mile delivery, making outsourcing a cost-effective and scalable solution. Strategic investments and acquisitions across the logistics industry further demonstrate this trend. For instance, in March 2025, DHL announced the acquisition of specialty pharmaceutical logistics provider CryoPDP to strengthen its capabilities in clinical trial logistics, biopharma distribution, and cell and gene therapy transportation, further expanding its integrated healthcare logistics portfolio and specialized cold chain network.
However, the market growth is constrained by the high capital investment required for temperature-controlled infrastructure, stringent global regulatory compliance requirements, and the operational complexity associated with transporting highly sensitive biopharmaceutical products across international markets. Nevertheless, increasing commercialization of advanced therapies, expanding biologics pipelines, growing adoption of digital supply chain technologies, and continued investments in GDP-compliant cold chain infrastructure are expected to create substantial long-term opportunities for biopharmaceutical third-party logistics providers. The market is expected to maintain steady growth as pharmaceutical manufacturers increasingly outsource complex logistics operations to specialized partners capable of delivering secure, compliant, and globally integrated supply chain solutions.
Market Dynamics
The increasing commercialization of biologics, biosimilars, vaccines, and advanced therapies is a major driver of growth in the biopharmaceutical third-party logistics (3PL) market. These products require highly specialized transportation, temperature-controlled storage, validated packaging, and continuous monitoring to maintain product integrity throughout the supply chain. As pharmaceutical and biotechnology companies expand global distribution networks and launch more temperature-sensitive products, they are increasingly partnering with specialized 3PL providers that offer GDP-compliant warehousing, cold chain transportation, inventory management, and end-to-end supply chain visibility. The growing complexity of global biopharmaceutical distribution, combined with stringent regulatory requirements and rising cross-border trade, is encouraging logistics providers to invest in multi-temperature storage facilities, advanced monitoring technologies, and integrated healthcare logistics infrastructure.
Stringent regulatory compliance remains a significant restraint for the biopharmaceutical third-party logistics (3PL) market. Logistics providers handling biopharmaceutical products must comply with multiple international Good Distribution Practice (GDP) regulations, product traceability requirements, serialization mandates, quality management standards, and country-specific import and export regulations. Compliance requirements vary across regions, requiring continuous monitoring of evolving regulatory frameworks and frequent updates to operational procedures and documentation. In addition, providers must maintain validated quality systems, comprehensive audit trails, staff training programs, and regulatory certifications to ensure product integrity throughout the supply chain. Failure to comply with these requirements can result in shipment delays, product recalls, regulatory penalties, or market access restrictions. The increasing complexity of global regulatory standards raises compliance costs and creates operational challenges for logistics providers managing international biopharmaceutical distribution networks, particularly as pharmaceutical manufacturers expand into multiple regulated markets.
The expanding pipeline of cell and gene therapies, biologics, and next-generation specialty pharmaceuticals presents significant opportunities for the biopharmaceutical 3PL market. Increasing investments in precision medicine, rare disease therapies, and personalized healthcare are generating sustained demand for specialized logistics services capable of handling highly sensitive products with strict temperature and time requirements. Many pharmaceutical and biotechnology companies are outsourcing logistics operations to specialized 3PL providers to improve supply chain efficiency, reduce capital expenditure, and accelerate global market access. Growing demand for clinical trial logistics, direct-to-patient delivery models, and real-time supply chain visibility is creating additional opportunities for providers with advanced cold chain capabilities, digital monitoring platforms, and integrated global distribution networks. Furthermore, ongoing investments in GDP-certified warehouses, temperature-controlled transportation fleets, and regional healthcare logistics hubs are strengthening the ability of 3PL providers to support the expanding commercialization of advanced biopharmaceutical products worldwide.
Market Concentration & Characteristics
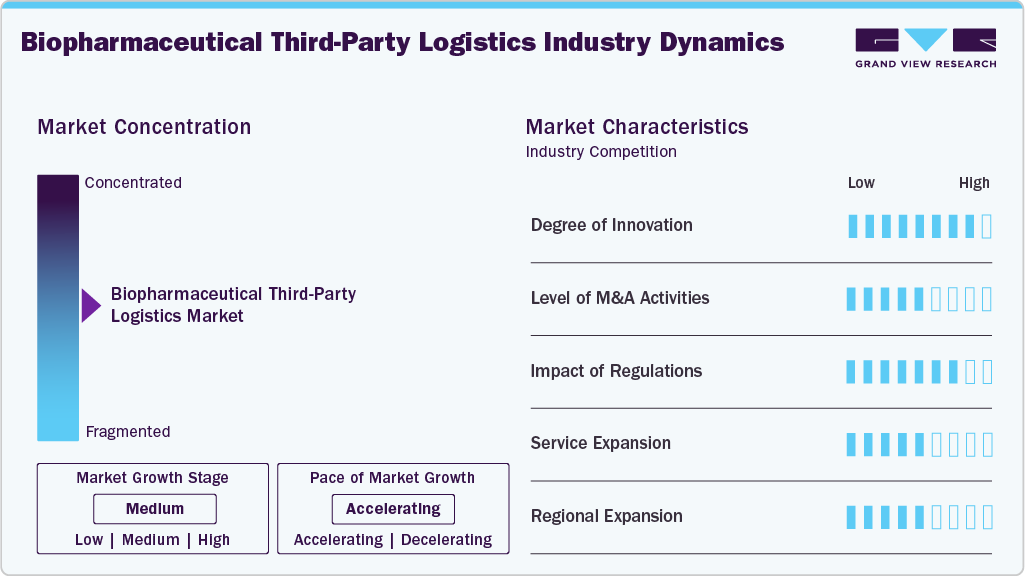
The biopharmaceutical third-party logistics market growth stage is medium, and the pace of growth is accelerating. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion.
Innovation remains a critical competitive factor in the biopharmaceutical third-party logistics industry, with logistics providers investing in advanced cold chain technologies, Internet of Things-based monitoring systems, artificial intelligence-driven supply chain analytics, warehouse automation, and digital visibility platforms. The growing distribution of biologics, biosimilars, vaccines, and advanced therapies is driving the adoption of technologies that enhance shipment monitoring, inventory accuracy, regulatory compliance, and product integrity. The continued advancement of intelligent logistics solutions enables service providers to improve operational efficiency, reduce distribution risks, strengthen traceability, and support the growing demand for specialized healthcare logistics services.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions continue to influence the biopharmaceutical 3PL market by expanding healthcare logistics networks, strengthening cold chain capabilities, and broadening integrated supply chain service offerings. Strategic acquisitions enable logistics providers to enhance expertise in temperature-controlled transportation, clinical trial logistics, warehousing, packaging, customs management, and last mile distribution while extending their global operational footprint. The transactions further improve service capacity, strengthen customer relationships, and increase access to high-growth pharmaceutical markets across major regions.
Regulatory compliance remains a major factor shaping the biopharmaceutical 3PL industry. Logistics providers are required to comply with Good Distribution Practice guidelines, product serialization requirements, temperature-monitoring standards, quality management systems, and import and export regulations established by health authorities in different countries. The increasing focus on product traceability, validated transportation processes, documentation accuracy, and quality assurance increases operational complexity while creating competitive advantages for providers with established regulatory expertise and globally compliant logistics infrastructure.
The biopharmaceutical third-party logistics providers are expanding their service portfolios to deliver integrated supply chain solutions across the pharmaceutical distribution lifecycle. Many providers now offer temperature-controlled transportation, warehousing, inventory management, packaging, labeling, customs brokerage, clinical trial logistics, direct-to-patient delivery, and digital shipment monitoring through a single platform. The integrated service approach improves operational efficiency, simplifies supply chain management, and enables pharmaceutical and biotechnology companies to optimize global distribution activities while maintaining regulatory compliance.
Regional expansion continues to strengthen the global presence of biopharmaceutical third-party logistics providers. Companies are establishing new GDP-compliant distribution centers, temperature-controlled warehouses, and healthcare logistics hubs across North America, Europe, Asia Pacific, Latin America, and the Middle East to address the increasing demand for biologics and specialty pharmaceuticals. The geographic expansion improves supply chain flexibility, strengthens regional distribution capabilities, supports local regulatory compliance, and enables logistics providers to deliver faster and more reliable pharmaceutical distribution services across global markets.
Impact of U.S. Tariffs on the Global Biopharmaceutical Third-Party Logistics (3PL) Market
The imposition of U.S. tariffs on imported pharmaceutical packaging materials, refrigeration equipment, monitoring devices, transportation components, and specialized logistics infrastructure has increased capital and operating costs across the biopharmaceutical 3PL industry. Higher prices for cold storage systems, insulated packaging, temperature monitoring equipment, and transportation assets have elevated investment requirements for logistics providers expanding healthcare distribution networks. In addition, tariffs on certain imported materials and equipment have contributed to procurement delays and supply chain disruptions, affecting infrastructure deployment and operational efficiency.
Pharmaceutical and biotechnology companies may face higher logistics costs for the transportation and storage of biologics, vaccines, and advanced therapies that require specialized cold chain handling. In response, many logistics providers have diversified supplier networks, increased regional sourcing of equipment and consumables, and strengthened inventory management practices to improve supply continuity. Investments in domestic cold chain infrastructure, regional distribution centers, and digital supply chain technologies are also helping to mitigate tariff-related cost pressures.
Demand for specialized biopharmaceutical logistics services remains strong, supported by the continued expansion of biologics pipelines, increasing commercialization of advanced therapies, and growing outsourcing of pharmaceutical supply chain operations. Long-term logistics contracts, strategic infrastructure investments, and the development of localized healthcare distribution networks are expected to partially offset the impact of higher input costs. Consequently, the expansion of regional cold chain hubs, digital visibility platforms, and GDP-compliant logistics infrastructure is likely to improve supply chain resilience while supporting sustained growth in the global biopharmaceutical third-party logistics market.
Analyst Perspective
The biopharmaceutical third party logistics market is experiencing steady growth, driven by the increasing commercialization of biologics, biosimilars, vaccines, and advanced therapies, along with rising outsourcing of pharmaceutical supply chain operations. Growing demand for temperature-controlled transportation, GDP-compliant warehousing, inventory management, packaging, customs management, and integrated distribution services is speeding up the adoption of specialized logistics providers with advanced cold chain infrastructure and digital supply chain capabilities. Furthermore, the companies with integrated logistics solutions, regulatory expertise, advanced digital capabilities, and extensive global distribution networks are expected to strengthen their competitive position and support market growth over the forecast period.
Technological Advancements
 To learn more about this report, Download Free Sample Report
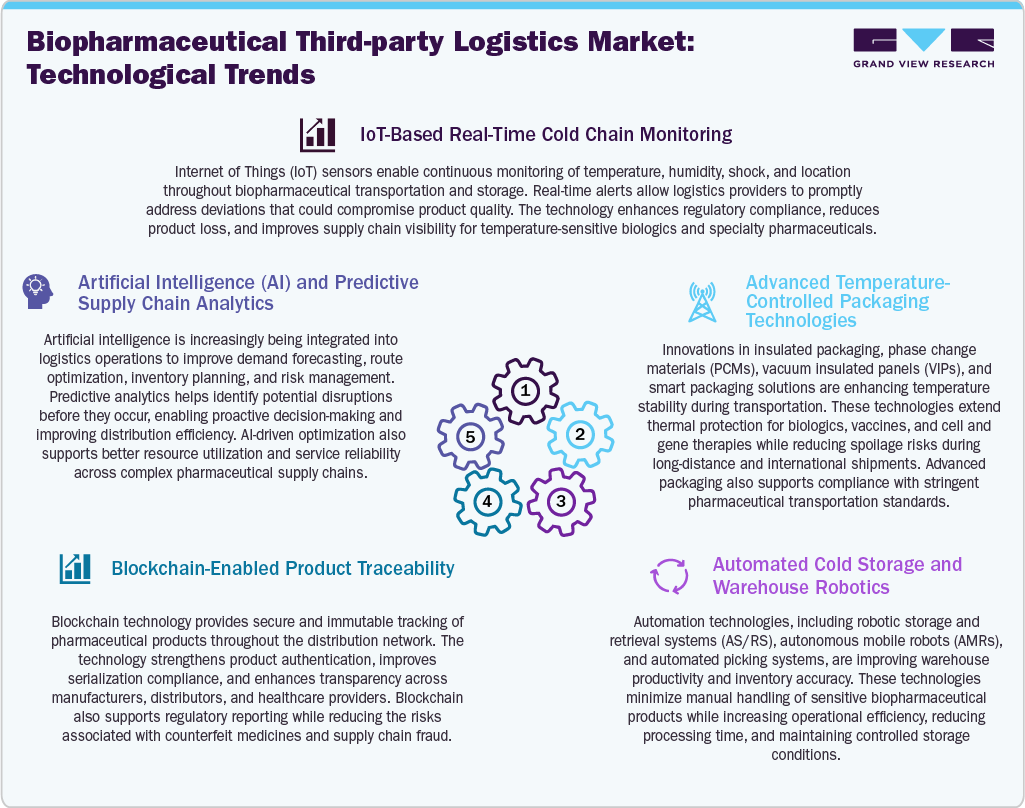
Technological innovation continues to reshape the biopharmaceutical third-party logistics market by improving supply chain visibility, operational efficiency, regulatory compliance, and product integrity across global distribution networks. The growing adoption of digital monitoring systems, intelligent analytics, automated warehousing, blockchain-enabled traceability, and advanced temperature-controlled packaging is enabling logistics providers to manage increasingly complex biopharmaceutical supply chains with greater precision and reliability. These technologies support continuous monitoring of high-value pharmaceutical products, strengthen quality assurance processes, and improve responsiveness to operational disruptions while facilitating compliance with evolving global regulatory requirements. Digital transformation is also enhancing inventory optimization, transportation planning, and end-to-end shipment visibility, enabling pharmaceutical manufacturers to reduce distribution risks and improve supply chain performance. At the same time, warehouse automation and advanced cold chain technologies are increasing operational scalability and supporting the safe handling of biologics, biosimilars, vaccines, and advanced therapies with stringent temperature requirements.
As pharmaceutical companies continue expanding global commercialization activities and outsourcing logistics operations, investments in next-generation digital infrastructure and smart logistics technologies are expected to remain a key competitive differentiator. Continued technological modernization across transportation, warehousing, packaging, and supply chain management is anticipated to strengthen service capabilities, improve distribution resilience, and support the long-term expansion of the global biopharmaceutical third-party logistics industry.
Pricing Model Analysis
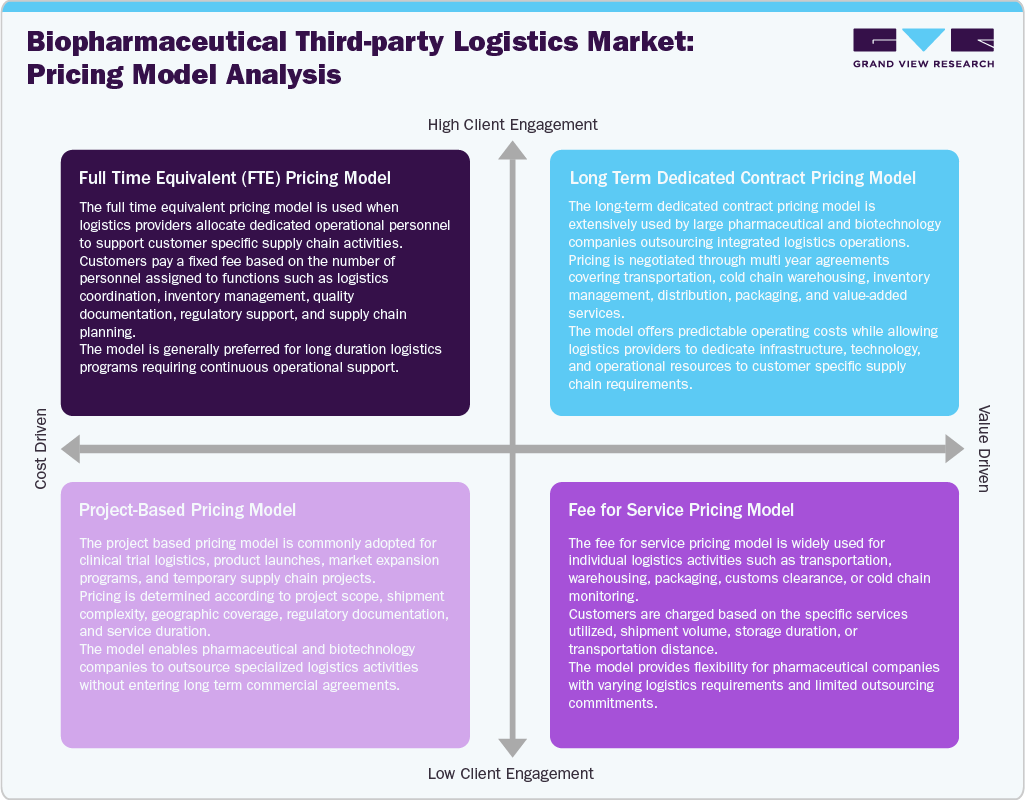
The pricing structure in the biopharmaceutical 3PL market is primarily determined by the scope of outsourced services, operational complexity, shipment volumes, regulatory requirements, and contract duration. The fee for service model remains suitable for customers requiring individual logistics services with flexible engagement terms, while project-based pricing addresses short-term commercial and clinical distribution requirements. The full-time equivalent model supports organizations that require dedicated logistics personnel for ongoing operational activities, particularly during large-scale commercialization and supply chain expansion programs. The long-term dedicated contract model continues to account for a considerable share of outsourcing agreements as pharmaceutical manufacturers increasingly consolidate multiple logistics functions under strategic partnerships.
 To learn more about this report, Download Free Sample Report
The increasing distribution of biologics, biosimilars, vaccines, and advanced therapies is encouraging logistics providers to offer flexible commercial structures that align with varying customer requirements across clinical and commercial supply chains. The continued expansion of global pharmaceutical outsourcing, increasing regulatory complexity, and growing demand for integrated cold chain solutions are expected to support the adoption of multiple pricing models across the biopharmaceutical 3PL industry over the forecast period.
Supply Chain Insights
The non-cold chain logistics segment led the market with the largest revenue share of 78.5% in 2025. The segment growth is attributed to the large volume of conventional pharmaceuticals, over-the-counter medicines, oral solid dosage forms, and medical products that do not require temperature-controlled transportation or storage. These products account for a significant share of global pharmaceutical distribution and are transported through established logistics networks with lower operating costs than cold chain services. The increasing production of generic medicines, the expansion of pharmaceutical manufacturing, and the rising international trade in non-temperature-sensitive products continue to support demand for non-cold-chain biopharmaceutical logistics services.
The cold chain logistics segment is expected to grow at the fastest CAGR during the forecast period. The growth is driven by the increasing commercialization of biologics, biosimilars, vaccines, cell and gene therapies, and other temperature-sensitive pharmaceuticals requiring specialized storage and transportation conditions. Pharmaceutical manufacturers are increasingly outsourcing cold chain logistics to specialized providers offering GDP-compliant infrastructure, real-time temperature monitoring, validated packaging, and integrated distribution services. Furthermore, expanding biologics pipelines, increasing global vaccine distribution, and growing investment in advanced healthcare logistics infrastructure are expected to further support the growth of the cold chain logistics segment over the forecast period.
Service Type Insights
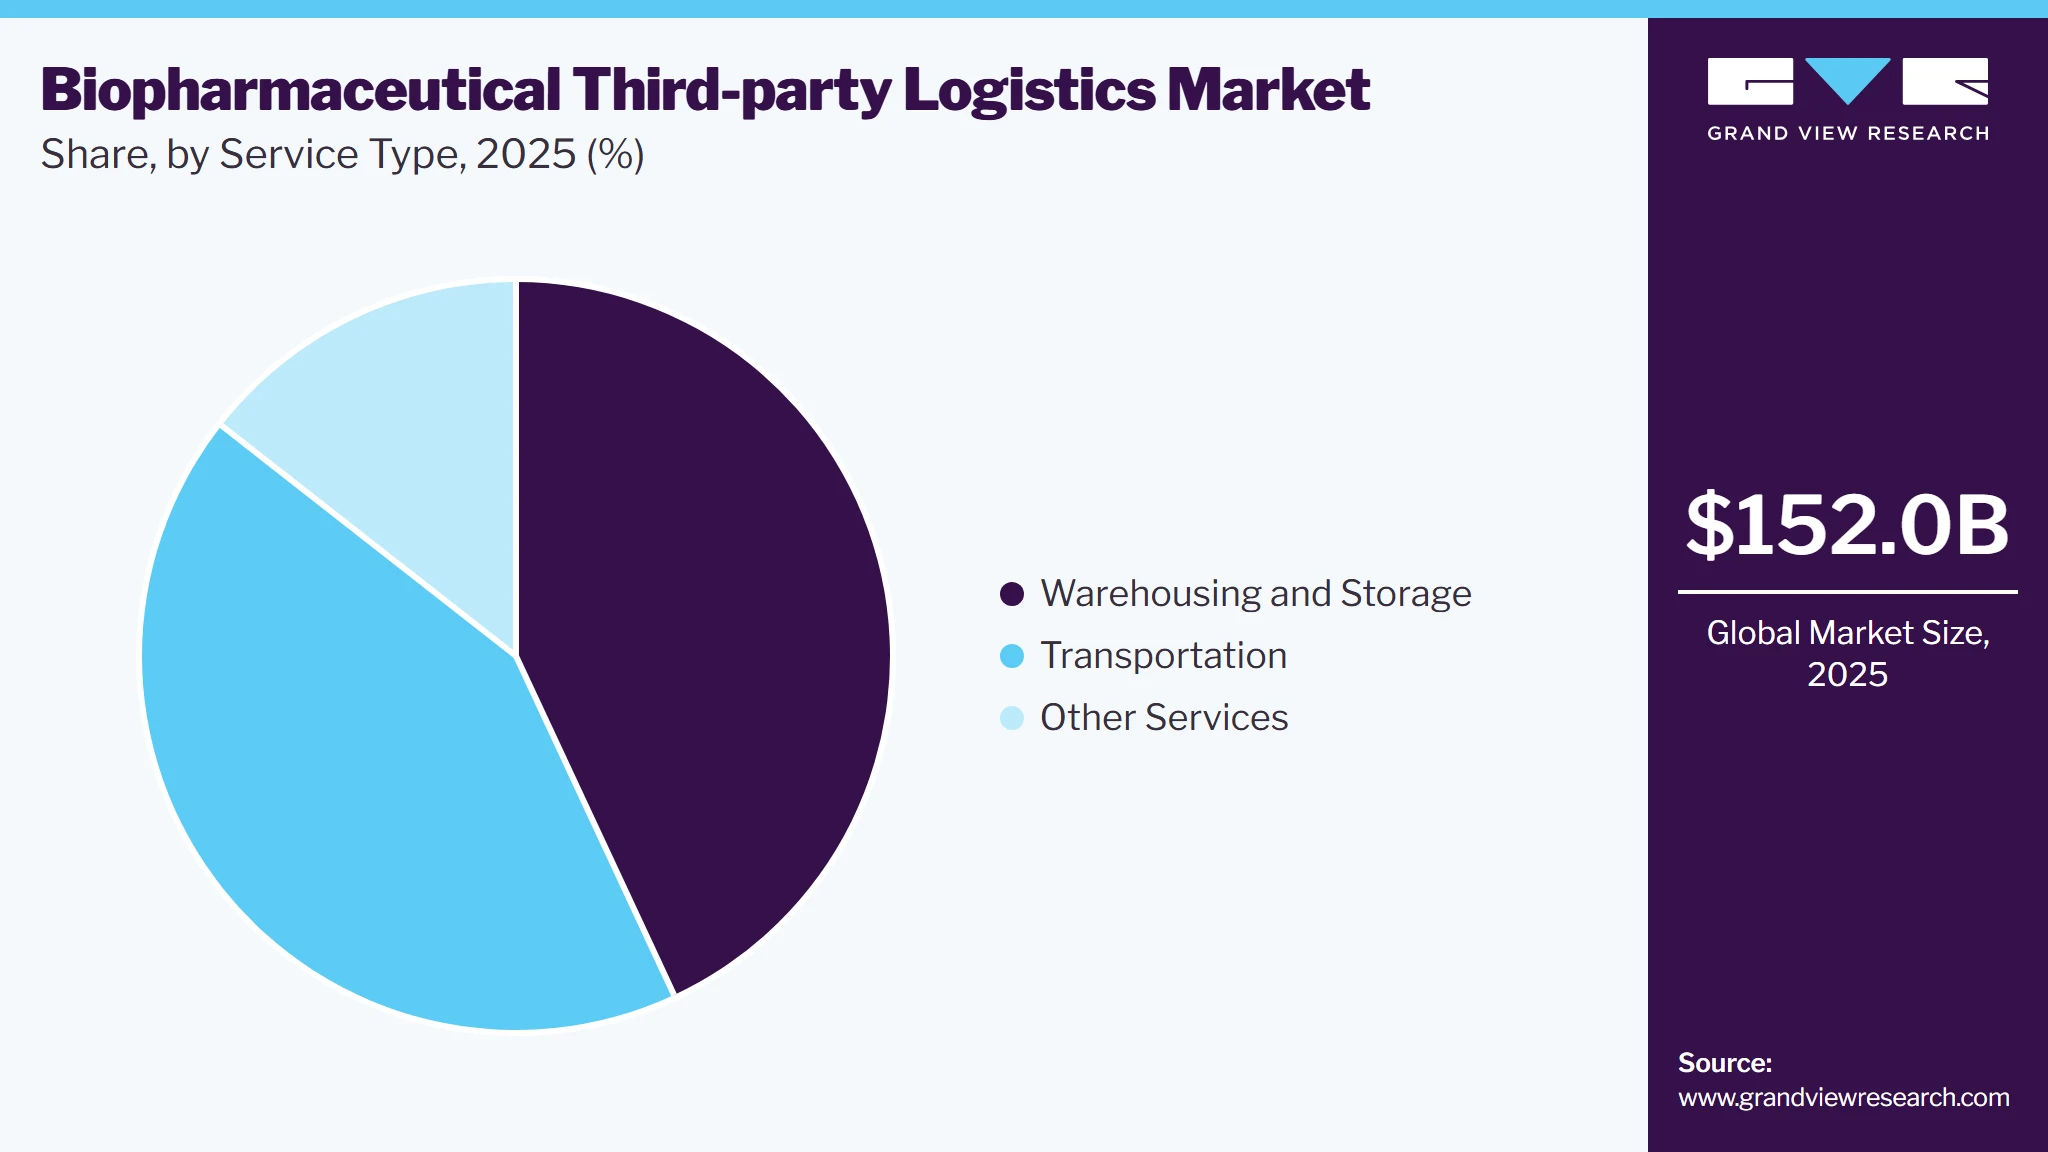
The warehousing and storage segment led the biopharmaceutical third-party logistics market with the largest revenue share of 43.1% in 2025. The growth of this segment is attributed to the increasing demand for GDP-compliant storage facilities for biologics, biosimilars, vaccines, and specialty pharmaceuticals across global supply chains. Pharmaceutical manufacturers increasingly outsource warehousing operations to specialized logistics providers offering temperature-controlled storage, inventory management, order fulfillment, and quality-controlled handling. The expansion of pharmaceutical manufacturing, increasing commercialization of high-value therapies, and growing need for regional distribution centers to support global product availability continue to strengthen demand for specialized biopharmaceutical warehousing and storage services.
 To learn more about this report, Download Free Sample Report
The transportation segment is projected to grow at the second-fastest CAGR during the forecast period. The growth is driven by the increasing global distribution of biologics, specialty pharmaceuticals, and advanced therapies that require secure and compliant transportation solutions. Pharmaceutical companies are expanding international distribution networks while increasing outsourcing of transportation activities to specialized logistics providers with expertise in cold chain management, real-time shipment monitoring, and regulatory compliant distribution. Furthermore, rising cross-border pharmaceutical trade, growing demand for faster product delivery, and continued investments in temperature-controlled transportation infrastructure are expected to support the sustained growth of the transportation segment over the forecast period.
Regional Insights
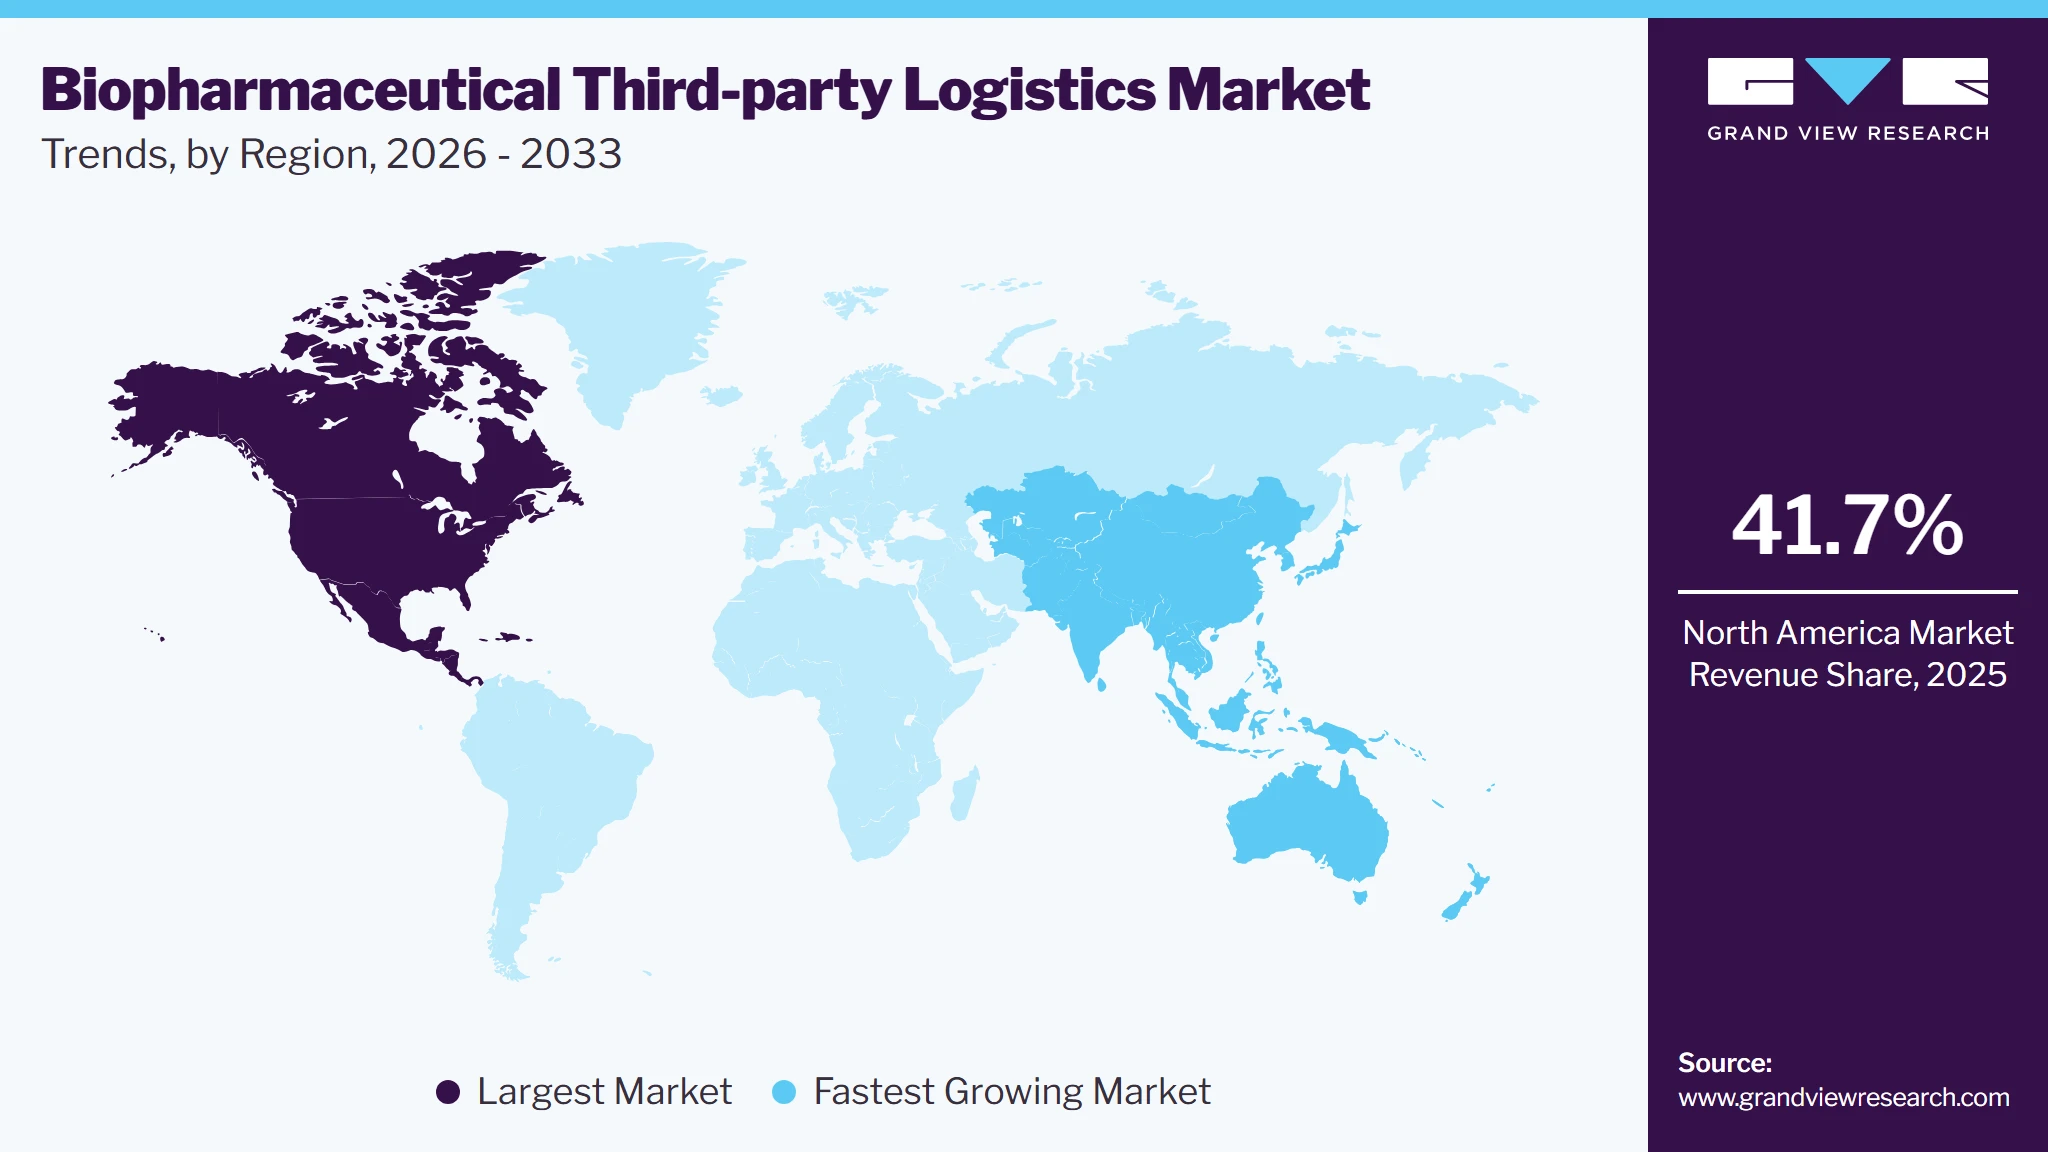
North America dominated the biopharmaceutical third-party logistics market with the largest revenue share of 41.7% in 2025. The market is experiencing significant growth, supported by a well-established pharmaceutical and biotechnology industry, the increasing commercialization of biologics and specialty pharmaceuticals, and advanced healthcare logistics infrastructure. The growing demand for temperature-controlled transportation, GDP-compliant warehousing, and integrated supply chain solutions is encouraging pharmaceutical manufacturers to expand outsourcing activities. The region benefits from strong investments in cold chain infrastructure, digital logistics technologies, and healthcare distribution networks. Continued growth in biologics production, clinical research activities, and advanced therapy commercialization is expected to support market expansion over the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. Biopharmaceutical Third-party Logistics Market Trends
The U.S. biopharmaceutical third-party logistics industry is expected to grow significantly over the forecast period. The market growth is supported by the country's large pharmaceutical manufacturing base, increasing biologics production, and rising demand for specialized cold chain logistics services. The growing number of cell and gene therapies, expanding clinical trial activities, and increasing outsourcing of healthcare supply chain operations are contributing to demand for integrated logistics solutions. In addition, investments in automated distribution centers, digital supply chain technologies, and temperature-controlled transportation networks are expected to support continued market growth.
The Canada biopharmaceutical third-party logistics market is expected to grow at a significant CAGR during the forecast period.The market is anticipated to witness steady growth owing to increasing pharmaceutical manufacturing activities, expanding biologics distribution, and continued investment in healthcare infrastructure. The rising demand for temperature-controlled logistics, regulatory compliant warehousing, and efficient cross-border distribution is encouraging pharmaceutical companies to strengthen outsourcing partnerships. Furthermore, increasing clinical research activities and government support for life sciences are expected to contribute to market expansion.
Europe Biopharmaceutical Third-party Logistics Market Trends
The European biopharmaceutical third-party logistics industry is experiencing steady growth, supported by a mature pharmaceutical industry, increasing biologics production, and stringent Good Distribution Practice requirements. The growing commercialization of biosimilars, vaccines, and advanced therapies is increasing demand for specialized cold chain logistics and integrated distribution services. The region benefits from an established healthcare logistics network, advanced transportation infrastructure, and the presence of leading pharmaceutical manufacturers. Continued investments in GDP-compliant warehousing and regional distribution hubs are expected to support market growth over the forecast period.
The Germany biopharmaceutical third-party logistics market is anticipated to experience significant growth owing to the country's strong pharmaceutical manufacturing industry and strategic position within the European healthcare supply chain. The increasing production of biologics, specialty pharmaceuticals, and biosimilars is driving demand for specialized warehousing, transportation, and cold chain logistics services. In addition, continued investment in automated logistics facilities and advanced distribution infrastructure is expected to support market expansion.
The UK Biopharmaceutical Third-party Logistics market is expected to grow significantly over the forecast period. The market is supported by a strong biotechnology sector, increasing pharmaceutical exports, and expanding clinical research activities. The growing demand for temperature-controlled logistics, clinical trial distribution, and integrated healthcare supply chain services is encouraging logistics providers to expand service capabilities. Furthermore, investments in digital logistics technologies and healthcare infrastructure are expected to support long-term market growth.
Asia Pacific Biopharmaceutical Third-party Logistics Market Trends
Asia Pacific is expected to grow at a fatest CAGR over the forecast period. Market growth is supported by expanding pharmaceutical manufacturing, increasing biologics production, rising healthcare expenditure, and growing pharmaceutical exports. The increasing outsourcing of logistics operations by pharmaceutical companies and continued investments in cold chain infrastructure are supporting regional market expansion. The development of healthcare logistics networks and increasing regulatory compliance requirements are further contributing to market growth.
The China biopharmaceutical third-party logistics market is anticipated to grow rapidly owing to expanding pharmaceutical manufacturing, increasing biologics commercialization, and rising investments in healthcare infrastructure. The increasing export of pharmaceutical products and growing demand for GDP-compliant cold chain logistics are encouraging logistics providers to expand warehousing and transportation capacity. Moreover, government initiatives supporting pharmaceutical innovation are expected to contribute to market expansion.
The biopharmaceutical third-party logistics market in Japan is expected to witness stable growth supported by a well-established pharmaceutical industry, increasing biologics demand, and advanced healthcare infrastructure. The growing distribution of specialty pharmaceuticals and rising adoption of temperature-controlled logistics solutions are increasing demand for specialized logistics providers. Furthermore, continued investment in digital supply chain management and quality compliant logistics services is expected to support future growth.
The India biopharmaceutical third-party logistics market is expected to witness strong growth over the forecast period. The increasing pharmaceutical production, expanding vaccine manufacturing, and growing exports of biologics and biosimilars are driving demand for specialized logistics services. The continued expansion of temperature-controlled warehousing, healthcare logistics infrastructure, and pharmaceutical distribution networks is expected to support sustained market growth. Furthermore, increasing outsourcing by domestic and multinational pharmaceutical companies is contributing to market expansion.
Latin America Biopharmaceutical Third-party Logistics Market Trends
The Latin America biopharmaceutical third-party logistics industry is experiencing gradual growth supported by increasing pharmaceutical imports, expanding healthcare access, and growing investments in cold chain infrastructure. The rising demand for biologics, vaccines, and specialty pharmaceuticals is encouraging logistics providers to strengthen temperature-controlled transportation and warehousing capabilities. Continued improvements in pharmaceutical distribution networks are expected to support market growth over the forecast period.
The Brazil Biopharmaceutical Third-party Logistics market accounted for the largest share of Latin America in 2025. The country's market growth is supported by increasing pharmaceutical manufacturing, expanding vaccine distribution, and rising biologics demand. The growing requirement for compliant healthcare logistics services and increasing investments in temperature-controlled distribution infrastructure are supporting market expansion. In addition, continued growth in pharmaceutical imports and exports is expected to strengthen demand for specialized third-party logistics services.
Middle East & Africa Biopharmaceutical Third-party Logistics Market Trends
The Middle East and Africa biopharmaceutical third-party logistics industry is expected to experience steady growth supported by increasing pharmaceutical imports, expanding healthcare infrastructure, and growing investment in healthcare logistics. The rising demand for temperature-controlled distribution of biologics, vaccines, and specialty medicines is encouraging the development of specialized logistics capabilities across the region. Continued modernization of pharmaceutical supply chains is expected to support market growth.
The UAE biopharmaceutical third-party logistics market is expected to witness significant growth over the forecast period. The market is supported by the country's strategic location as a regional trade and distribution hub, expanding pharmaceutical imports and exports, and increasing investment in healthcare infrastructure. The development of advanced logistics facilities, free trade zones, and temperature-controlled warehousing is strengthening pharmaceutical distribution capabilities. Furthermore, government initiatives to establish the UAE as a regional life sciences and healthcare logistics hub are expected to support sustained market growth.
Key Biopharmaceutical Third-party Logistics Company Insights
The key players operating across the market are adopting strategic initiatives such as service launches, mergers & acquisitions, partnerships & agreements, and expansions to gain a competitive edge in the market. For instance, in April 2025, DHL Group announced an investment of ~USD 2.3 billion (EUR 2 billion) by 2030 to strengthen its DHL Health Logistics business, expanding GDP-certified pharma hubs, temperature-controlled warehousing, multi-temperature transportation, specialized cooling infrastructure, and digital visibility solutions to support increasing demand from the global biopharmaceutical and advanced therapy sectors.
Key Biopharmaceutical Third-party Logistics Companies
The following key companies have been profiled for this study of the biopharmaceutical third-party logistics market.
-
DHL International GmbH
-
SF Express
-
FedEx
-
United Parcel Service of America, Inc.
-
Cencora, Inc.
-
DB Schenker
-
Kuehne and Nagel
-
Kerry Logistics Network Limited
-
Agility Public Warehousing Company K.S.C.P.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (DHL Group, Kuehne+Nagel)
- Mature companies focus on expanding GDP-compliant warehousing, temperature-controlled transportation networks, integrated supply chain management, and end-to-end healthcare logistics services.
- These companies continue investing in digital supply chain platforms, warehouse automation, cold chain infrastructure, clinical trial logistics, customs brokerage, inventory management, and global distribution capabilities to strengthen their presence across pharmaceutical and biotechnology supply chains.
- Established players benefit from extensive global logistics networks, advanced cold chain infrastructure, strong regulatory expertise, and integrated healthcare logistics capabilities.
- Their ability to provide transportation, warehousing, packaging, customs management, inventory control, and digital shipment visibility through a single platform enables them to secure long-term contracts with leading pharmaceutical and biotechnology companies.
- Established players face challenges associated with high infrastructure investment, rising operating expenses, increasing regulatory compliance requirements, and continuous investment in digital technologies and cold chain facilities.
- Large operational networks may also reduce flexibility when responding to customer-specific logistics requirements and rapidly changing distribution patterns.
Emerging Players (Cencora, Inc.)
- Emerging companies primarily focus on expanding healthcare logistics, regional cold chain networks, specialty pharmaceutical distribution, and clinical logistics services.
- Many invest in temperature-controlled warehousing, digital tracking solutions, last mile delivery, and strategic partnerships to strengthen their presence in regional pharmaceutical supply chains and improve service capabilities.
- Emerging players gain competitive advantages through flexible service offerings, faster operational execution, strong regional distribution networks, and customized healthcare logistics solutions.
- Their focused investments in cold chain infrastructure, digital shipment monitoring, and specialty pharmaceutical logistics enable them to address the growing outsourcing requirements of pharmaceutical and biotechnology companies.
- Emerging players often face limitations in global network coverage, international regulatory experience, and large-scale cold chain infrastructure.
- Limited geographic presence, lower financial resources, and increasing competition from multinational logistics providers may restrict their ability to secure large multinational outsourcing contracts and expand across multiple regulated markets.
Recent Developments
-
In December 2025, Cencora announced investments to enhance its global pharmaceutical third-party logistics services and cold chain capabilities across the U.S. and Europe. The expansion includes the addition of NextPharma Logistics to strengthen its pan-European 3PL network, the establishment of a new 3PL facility in Italy in 2026, and a highly automated 500,000-square-foot 3PL facility in Texas. The investment also expands refrigerated, frozen, ultra-low temperature, and cryogenic storage capacity to support biologics, specialty pharmaceuticals, and cell and gene therapies.
-
In March 2025, Kuehne+Nagel partnered with Sanofi to provide fulfillment, handling, and value-added logistics services for healthcare products, including pharmaceuticals in Türkiye. The agreement expands Kuehne+Nagel's healthcare contract logistics capabilities through integrated warehousing, inventory management, and distribution services, supporting efficient regional pharmaceutical supply chains.
Biopharmaceutical Third-party Logistics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 152.0 billion
Estimated market size in 2026
USD 161.4 billion
Projected market size by 2033
USD 258.4 billion
Growth rate
CAGR of 6.9% from 2025 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Supply chain, service type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar
Key companies profiled
DHL International GmbH; SF Express; FedEx; United Parcel Service of America, Inc.; Cencora, Inc.; DB Schenker; Kuehne and Nagel; Kerry Logistics Network Limited; Agility Public Warehousing Company K.S.C.P.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Biopharmaceutical Third-party Logistics Market Report Segmentation
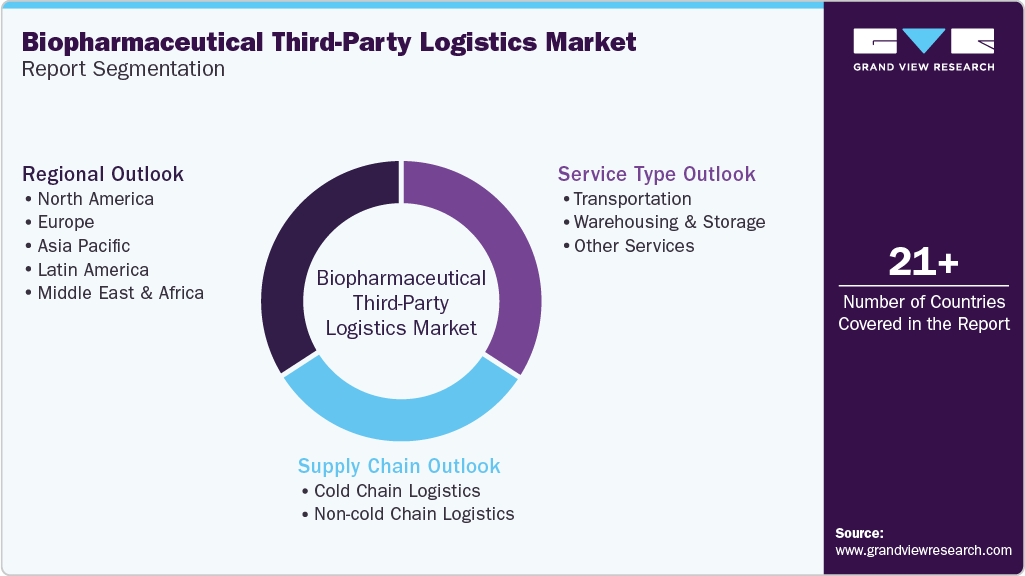
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global biopharmaceutical third-party logistics market report based on supply chain, service type, and region:
 To learn more about this report, Download Free Sample Report
-
Supply Chain Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Cold Chain Logistics
-
Non-cold Chain Logistics
-
-
Service Type Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Transportation
-
Air Freight
-
Sea Freight
-
Overland
-
-
Warehousing and Storage
-
Other Services
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Thailand
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
The biopharmaceutical third-party logistics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each biopharmaceutical third-party logistics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Supply Chain
Revenue Capture Definition
Cold Chain Logistics
The segment captures revenue generated by third-party logistics services provided for temperature sensitive biopharmaceutical products requiring controlled storage and transportation conditions. Revenue includes cold chain transportation, refrigerated and frozen warehousing, ultra-low temperature storage, validated packaging, temperature monitoring, inventory management, and distribution services for biologics, biosimilars, vaccines, cell and gene therapies, and other specialty pharmaceuticals.
Non cold Chain Logistics
The segment captures revenue generated by third-party logistics services provided for biopharmaceutical and pharmaceutical products that do not require temperature-controlled storage or transportation. Revenue includes standard transportation, warehousing, inventory management, packaging, order fulfillment, customs clearance, and distribution services for conventional pharmaceuticals, oral solid dosage forms, medical products, and healthcare supplies.
Service - Type
Revenue Capture Definition
Transportation
The segment captures revenue generated by third-party transportation services provided for the movement of biopharmaceutical products across domestic and international supply chains. Revenue includes temperature-controlled and ambient transportation, shipment management, route planning, customs handling, tracking, and distribution services supporting pharmaceutical manufacturers, biotechnology companies, healthcare providers, and distributors.
Air Freight
The segment captures revenue generated by air transportation services for biopharmaceutical products requiring rapid, secure, and time sensitive delivery. Revenue includes domestic and international air freight, temperature-controlled shipping, priority handling, customs documentation, and specialized transportation services for biologics, vaccines, clinical trial materials, and other high value pharmaceutical products.
Sea Freight
The segment captures revenue generated by ocean freight logistics services for biopharmaceutical shipments transported through international maritime trade routes. Revenue includes containerized transportation, refrigerated container services, customs clearance, shipment coordination, and distribution support for pharmaceutical products requiring cost-effective international transportation.
Overland
The segment captures revenue generated by road and rail transportation services provided for domestic and cross border distribution of biopharmaceutical products. Revenue includes temperature-controlled trucking, last mile delivery, route optimization, shipment tracking, and regional distribution services supporting pharmaceutical manufacturers, wholesalers, hospitals, and healthcare facilities.
Warehousing and Storage
The segment captures revenue generated by third-party warehousing and storage services for biopharmaceutical products. Revenue includes GDP-compliant storage, cold rooms, refrigerated and frozen storage, inventory management, order fulfillment, stock monitoring, packaging, labeling, and distribution preparation for biologics, biosimilars, vaccines, and specialty pharmaceuticals.
Other Services
The segment captures revenue generated by value-added third-party logistics services supporting biopharmaceutical supply chains. Revenue includes packaging, labeling, customs brokerage, regulatory documentation, inventory optimization, order processing, reverse logistics, supply chain consulting, digital shipment monitoring, and other specialized logistics services provided alongside transportation and warehousing operations.
Estimation Model
Approach
Description
Bottom-Up Revenue Model
- Market size is estimated by identifying major global and regional third-party logistics providers offering transportation, warehousing, cold chain logistics, inventory management, and integrated supply chain services for biopharmaceutical products.
- Revenue attributable to the biopharmaceutical third-party logistics business is derived from annual reports, investor presentations, company disclosures, healthcare logistics business updates, management commentary, and industry publications.
- Company-level healthcare and life sciences logistics revenues are aggregated and validated by evaluating service portfolios, geographic presence, cold chain infrastructure, customer base, and industry benchmarks to estimate the overall market value.
Healthcare Logistics Infrastructure Model
- Market value is estimated by assessing the available healthcare logistics infrastructure dedicated to biopharmaceutical distribution across major regions.
- Key parameters evaluated include GDP-compliant warehousing capacity, cold storage infrastructure, refrigerated transportation fleets, temperature-controlled distribution centers, shipment volumes, warehouse utilization rates, and average logistics pricing for transportation and storage services.
- The effective logistics capacity is translated into potential annual revenue and validated using route utilization rates, infrastructure expansion projects, customer contracts, and pharmaceutical distribution volumes.
Biopharmaceutical Distribution Demand Model
- Market size is derived by evaluating the commercial distribution volumes of biologics, biosimilars, vaccines, cell and gene therapies, plasma-derived products, and other specialty pharmaceuticals requiring third-party logistics services.
- Average logistics expenditure is assigned across transportation, warehousing, cold chain distribution, inventory management, packaging, customs management, and value-added logistics services based on product characteristics and distribution requirements.
- The commercial distribution volume is multiplied by the estimated outsourced logistics expenditure and aggregated across major biopharmaceutical product categories and geographic regions to estimate the overall market value.
Outsourcing Penetration Model
- Market size is estimated by assessing the proportion of pharmaceutical and biotechnology companies outsourcing logistics operations to specialized third-party logistics providers instead of managing distribution through internal logistics networks.
- Outsourcing rates are determined through primary interviews, industry publications, company disclosures, logistics partnership announcements, and pharmaceutical supply chain outsourcing trends.
- The addressable market is calculated by applying outsourcing penetration rates to total spending on transportation, warehousing, cold chain logistics, inventory management, packaging, customs brokerage, and related distribution services, thereby estimating the overall third-party logistics market opportunity.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Industry Outlook, Value Chain, and Business Model Assessment
Conducted a comprehensive evaluation of the biopharmaceutical third-party logistics ecosystem, covering packaging suppliers, cold chain packaging providers, transportation service providers, freight forwarders, customs brokers, GDP-compliant warehousing providers, distribution partners, digital supply chain solution providers, healthcare logistics companies, and pharmaceutical and biotechnology manufacturers. Assessed prevailing business models, outsourcing trends, revenue streams, pricing structures, supply chain dependencies, and value creation opportunities across transportation, warehousing, inventory management, cold chain distribution, packaging, customs clearance, and last mile delivery.
Provides a comprehensive understanding of the industry structure, revenue generation models, outsourcing trends, and supply chain dynamics, enabling stakeholders to identify growth opportunities across the biopharmaceutical logistics value chain while supporting strategic investment, partnership, and expansion decisions.
Competitive Benchmarking and Service Capability Analysis
Performed an in-depth benchmarking of leading biopharmaceutical third-party logistics providers based on cold chain capabilities, GDP compliance, transportation and warehousing capacity, geographic coverage, digital supply chain capabilities, inventory management services, clinical trial logistics expertise, temperature monitoring technologies, value-added services, and strategic partnerships. Included comparative positioning of global healthcare logistics providers and regional specialists serving biologics, biosimilars, vaccines, cell and gene therapies, and specialty pharmaceuticals.
Enables identification of competitive gaps, service differentiation opportunities, strategic partnership targets, acquisition prospects, and best practice logistics capabilities to support long-term competitive positioning and business expansion.
Global Regulatory Landscape and Compliance Assessment
Conducted a comprehensive assessment of regulatory requirements governing biopharmaceutical logistics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The analysis covered Good Distribution Practice requirements, cold chain compliance standards, product traceability, serialization requirements, transportation validation, storage standards, import and export regulations, and inspection expectations established by major health authorities. The assessment also evaluated regional regulatory differences and their impact on logistics operations, cross-border distribution, and outsourcing strategies.
Enables logistics providers, pharmaceutical manufacturers, and investors to understand evolving regulatory requirements, reduce compliance risks, strengthen quality management systems, and develop regional expansion strategies aligned with global healthcare logistics standards.
Frequently Asked Questions About This Report
The global biopharmaceutical third-party logistics market size was valued at USD 152.0 billion in 2025 and is estimated at USD 161.4 billion in 2026.
The global biopharmaceutical third-party logistics market is expected to grow at a CAGR of 6.9% from 2026 to 2033, reaching USD 258.4 billion.
By supply chain, the non-cold chain logistics segment led with a 78.5% revenue share in 2025.
Key players include DHL International GmbH; SF Express; FedEx; United Parcel Service of America, Inc.; Cencora, Inc.; DB Schenker; Kuehne and Nagel; Kerry Logistics Network Limited; Agility Public Warehousing Company K.S.C.P., among others.
Key factors include expanding commercialization of biologics and biosimilars, increasing demand for temperature-controlled and GDP-compliant logistics infrastructure, rising outsourcing of supply chain operations by pharmaceutical and biotechnology companies, growth in clinical trials and advanced therapies, including cell and gene therapies, and continuous investments in digital supply chain technologies for end-to-end product visibility and regulatory compliance.
North America dominated with a 41.7% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The warehousing and storage segment led with a 43.1% revenue share in 2025.
The air freight segment held the largest revenue share of 56.6% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


