
- Home
- »
- Medical Devices
- »
-
Breast Implants Market Size, Share & Trends Report, 2033GVR Report cover

Breast Implants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Silicone Breast Implants, Saline Breast Implants), By Shape (Round, Anatomical), By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$2.1BMarket Estimate, 2026
$2.2BMarket Forecast, 2033
$3.2BCAGR, 2026–2033
5.1%Breast Implants Market Summary
The global breast implants market size was valued at USD 2.1 billion in 2025 and is projected to grow from USD 2.2 billion in 2026 to USD 3.2 billion by 2033, at a CAGR of 5.1% from 2026 to 2033. The market in North America dominated with a revenue share of 32.7% in 2025. The market's growth is driven by rising demand for aesthetic enhancement procedures, technological advancements in implant materials, and increased awareness of body contouring solutions.
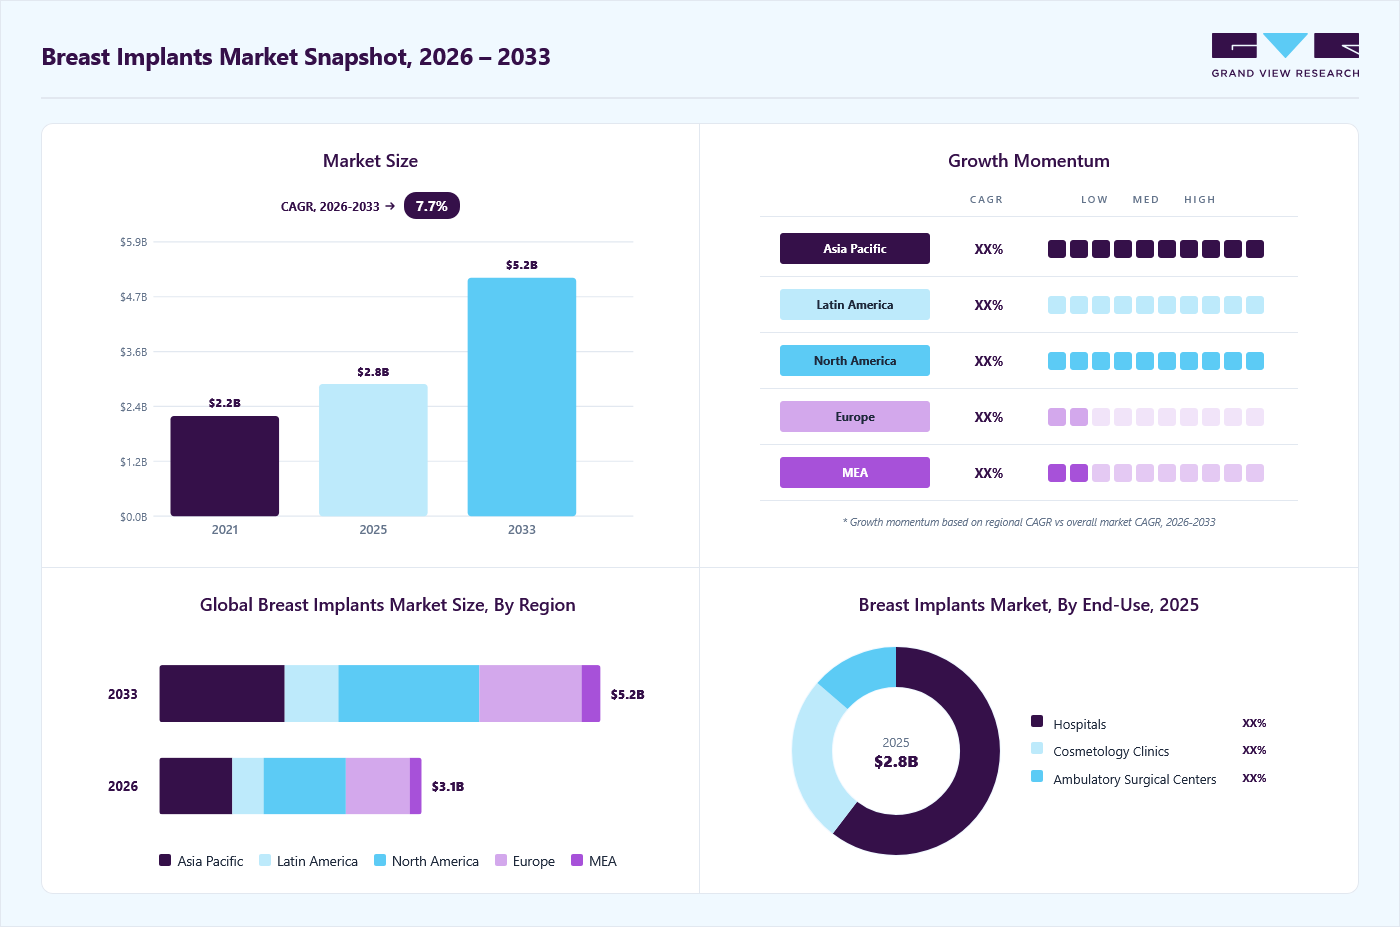 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Silicone breast implants segment held the largest market share of 84.0% in 2025.
- By shape: Round segment held the largest market share of 80.1% in 2025.
- By application: Cosmetic surgery segment held the largest market share of 76.2% in 2025.
- By end use: Hospitals segment held the largest market share of 59.3% in 2025.
Regional Highlights
- Largest regional market: North America (32.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 2.1 Billion
- Estimated market size in 2026: USD 2.2 Billion
- Projected market size by 2033: USD 3.2 Billion
- CAGR (2026-2033): 5.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Growing social acceptance of cosmetic surgeries, coupled with the effect of media and celebrity culture, has encouraged more women to opt for breast augmentation. In addition, the availability of minimally invasive techniques and improved implant safety profiles has significantly reduced the hesitation around undergoing such procedures. The latest innovations in breast implant technology are significantly driving market growth by offering improved aesthetic outcomes and enhanced safety. Advanced implants in 2025 feature highly cohesive silicone gels that provide a more natural shape, better feel, and increased durability, reducing the risk of rupture and the likelihood of revision surgeries. Newer designs also incorporate thinner, customizable shells that conform more naturally to the body, resulting in better mobility and a more lifelike appearance. These improvements enhance patient satisfaction and broaden the appeal of breast augmentation procedures.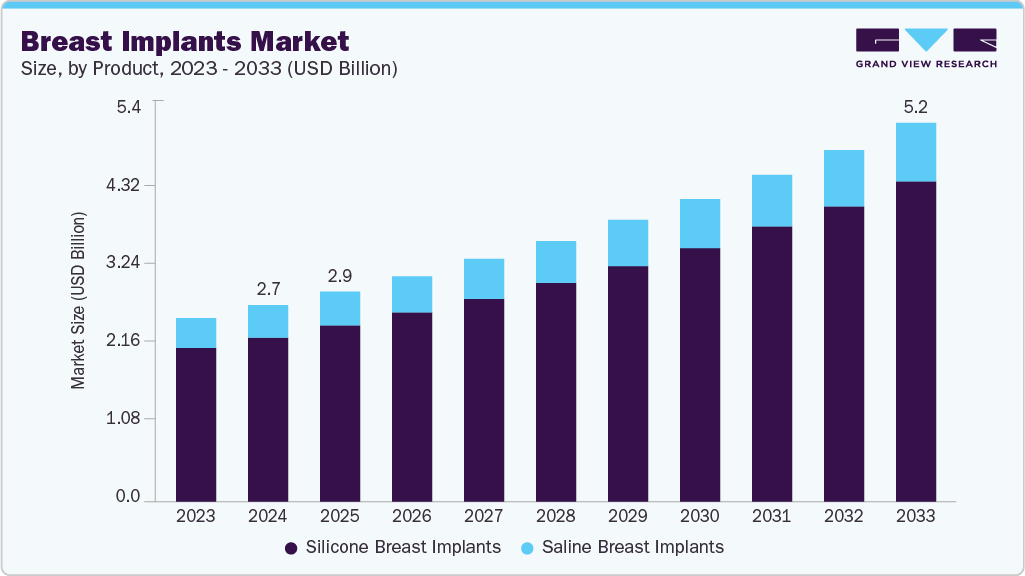 To learn more about this report, Download Free Sample Report
The increasing number of breast reconstruction surgeries is playing a significant role in driving the growth of the breast implants market. This trend is largely driven by the rising incidence of breast cancer, which requires mastectomy procedures, creating a strong need for reconstructive solutions to restore breast shape and appearance. As awareness about post-mastectomy reconstruction improves, more patients are opting for implant-based procedures to enhance their physical recovery and psychological well-being. In addition, advancements in surgical techniques and implant design have made reconstruction procedures safer, more effective, and aesthetically appealing, encouraging higher adoption. Supportive healthcare policies and improved access to reconstructive care in hospitals and specialized centers have further strengthened this trend, positioning breast implants as a critical component in comprehensive breast cancer treatment and recovery pathways.
“Although it is elective, aesthetic cosmetic surgery is an actual surgery that involves risks and possible side effects. Safety should be the priority, and we encourage patients to choose a board-certified, specialized plastic surgeon, trained and experienced in the procedure.”-Dr. Naveen Cavale, Chair of the ISAPS Communications Committee and plastic surgeon in the UK
 To learn more about this report, Download Free Sample Report
The rising prevalence of breast cancer is a key driver fueling the growth of the breast implants market, as it directly increases the demand for reconstructive surgeries following mastectomy. As breast cancer remains one of the leading causes of cancer-related morbidity among women globally, the number of women undergoing mastectomies has grown, resulting in a higher adoption of breast reconstruction procedures using implants. With improved survival rates due to early diagnosis and advanced treatment, more patients are opting for reconstruction to restore their physical appearance and emotional well-being. In addition, increasing awareness about reconstructive options and favorable reimbursement policies in many regions supports the use of implants as a restorative solution, thereby significantly driving market expansion.
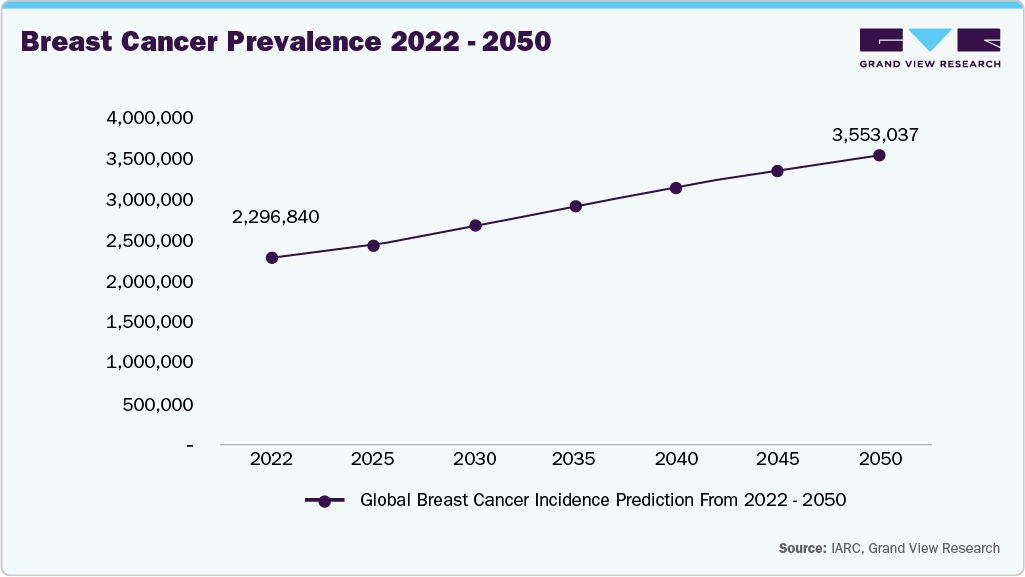 To learn more about this report, Download Free Sample Report
The multiple benefits of breast implants drive market growth. Beyond aesthetic enhancement, breast implants contribute significantly to a woman's physical and emotional well-being. They help boost self-confidence and restore breast shape and size that may have changed due to aging, pregnancy, hormonal shifts, or previous surgeries, such as a mastectomy. In addition, breast implants offer a reliable solution for correcting asymmetry between breasts and allow individuals to achieve their desired breast size, tailored to personal preferences. As awareness of these benefits grows and surgical techniques become safer and more refined, more women are considering breast augmentation and reconstruction, thereby fueling the demand for breast implants.
Comparison of The Major Breast Implant Brands
Brand
Founded / Origin
Key Features
Variety
Warranty
Mentor
1969 / USA (Johnson & Johnson)
- 4-layer shell to reduce rupture- Specialized surface to minimize capsular contracture
1,000+ options
Lifetime (rupture/deflation), 10 years (complications)
Motiva
2010 / USA (Establishment Labs)
- Ergonomix shape mimics natural feel- SilkSurface for low complication- Qid safety tech
500+ options
Lifetime (rupture), 10 years (capsular contracture)
Nagor
1979 / UK
- British-made with multi-layer silicone shell- Complies with EU & Int'l safety standards
270+ options
Lifetime (rupture & capsular contracture)
Polytech
1986 / Germany
- B-Lite range is 30% lighter- Cohesive gel resists deformation- Approved in 80+ countries
2,000+ options
Lifetime (rupture), 10 years (capsular contracture)
Silimed
1978 / Brazil (Latin America)
- Biodesign range tailored to patient anatomy- Treated cohesive gel prevents rupture/leakage
Extensive (customizable)
Up to 10 years (capsular contracture, depending on implant)
Source: Cadogan Clinic, Grand View Research
The launch of new breast implant products is a significant driver of market growth, as it brings innovation, enhanced safety, and broader customization options to meet diverse patient needs. Advanced breast implants now offer features such as high-strength cohesive gels, ergonomic designs, lightweight materials, and improved biocompatibility, enhancing both aesthetic outcomes and patient comfort. These new offerings appeal to a broader demographic, including women seeking more natural results or undergoing post-mastectomy reconstruction.
Technological Advancements
Company Name
Product Launch
KOLs
Johnson & Johnson MedTech
In May 2025, Johnson & Johnson MedTech announced the U.S. launch of its MENTOR MemoryGel Enhanced Breast Implants, addressing a significant need in the continuum of breast cancer care. These implants are specifically designed to support women who have undergone a mastectomy, offering advanced reconstruction options that combine aesthetic appeal with safety and comfort.
"Johnson & Johnson MedTech is delivering on our promise to make breast reconstruction more inclusive, supportive, and empowering for every woman,” said Alenka Brzulja, Worldwide President, Aesthetics & Reconstruction, Johnson & Johnson MedTech. “Too many women have been left without options that helped them achieve their desired outcomes. The availability of MemoryGel Enhance Implants brings us closer to addressing this gap – because every woman deserves access to reconstruction options that reflect her body and her goals.”
Establishment Labs Holdings Inc.
In September 2024, Establishment Labs Holdings Inc. received approval from the U.S. Food and Drug Administration (FDA) for its Motiva SmoothSilk Ergonomix and Motiva SmoothSilk Round breast implants. This approval allows their use in both primary and revision breast augmentation procedures, marking a significant milestone in expanding safe and advanced implant options for patients in the U.S.
“Today’s approval is transformative for breast aesthetics in the United States. This is a new era, in which women now have a choice of highly differentiated technology that is backed by rigorous scientific and clinical research,” commented Juan José Chacón-Quirós, Founder and Chief Executive Officer. “Motiva implants have changed the paradigm by proving that women do not have to compromise when it comes to their aesthetic goals. We have never wavered in our commitment to women’s health, and our entire organization is ready to bring this passion and technology to the United States.”
POLYTECH Health & Aesthetics GmbH
In April 2025, POLYTECH Health & Aesthetics GmbH, addressing growing concerns about unnatural-looking breast augmentation results and the increasing rate of revision surgeries, supported the launch of a new expert initiative: The Global Consensus on 'Natural Breast Beauty'. Introduced by a group of prominent plastic surgeons from around the world, this initiative was officially presented at Palazzo Turati in Milan, highlighting the industry's shift toward achieving more natural, aesthetically pleasing outcomes in aesthetic breast procedures.
"The demand for aesthetic surgery is rising, but too often shaped by unrealistic expectations," says Prof. Roy De Vita, Plastic Surgeon and Department Head at the Istituto dei Tumori Regina Elena in Rome. "Many women walk into their first consultation asking for a specific brand or implant shape they saw on Instagram. But implants are medical devices just like orthopedic or cardiac implants - not accessories. You wouldn't choose a heart valve that way."
Source: Johnson & Johnson MedTech, Establishment Labs Holdings Inc., POLYTECH Health & Aesthetics GmbH, Grand View Research
Market Dynamics
The breast implants market is experiencing substantial growth driven by the increasing demand for cosmetic breast augmentation and post-mastectomy breast reconstruction procedures worldwide. Rising aesthetic awareness, growing acceptance of cosmetic surgery, increasing disposable incomes, and the influence of social media and beauty standards are encouraging more individuals to opt for breast enhancement procedures. The rising incidence of breast cancer and the growing number of mastectomy procedures are further accelerating demand for reconstructive breast implants. Continuous advancements in implant technology, including highly cohesive silicone gel implants, improved shell designs, enhanced safety profiles, and minimally invasive surgical techniques, are improving clinical outcomes and patient satisfaction. The market is also benefiting from expanding access to board-certified plastic surgeons, increasing availability of specialized aesthetic clinics and ambulatory surgical centers, favorable healthcare infrastructure in developed countries, and growing medical tourism for cosmetic procedures. Furthermore, ongoing regulatory approvals, product innovations, and increasing awareness regarding breast reconstruction options are expected to support sustained market growth throughout the forecast period.
Rising aesthetic awareness, greater acceptance of cosmetic surgery, higher disposable incomes, and continuous improvements in implant safety and surgical techniques have encouraged more women to undergo breast augmentation. In addition, increasing availability of board-certified plastic surgeons, specialized cosmetic clinics, and financing options for elective procedures has improved access to breast implant surgeries. The expanding influence of social media, celebrity culture, and personalized aesthetic goals has also contributed to sustained demand, particularly among younger adults and middle-aged women.
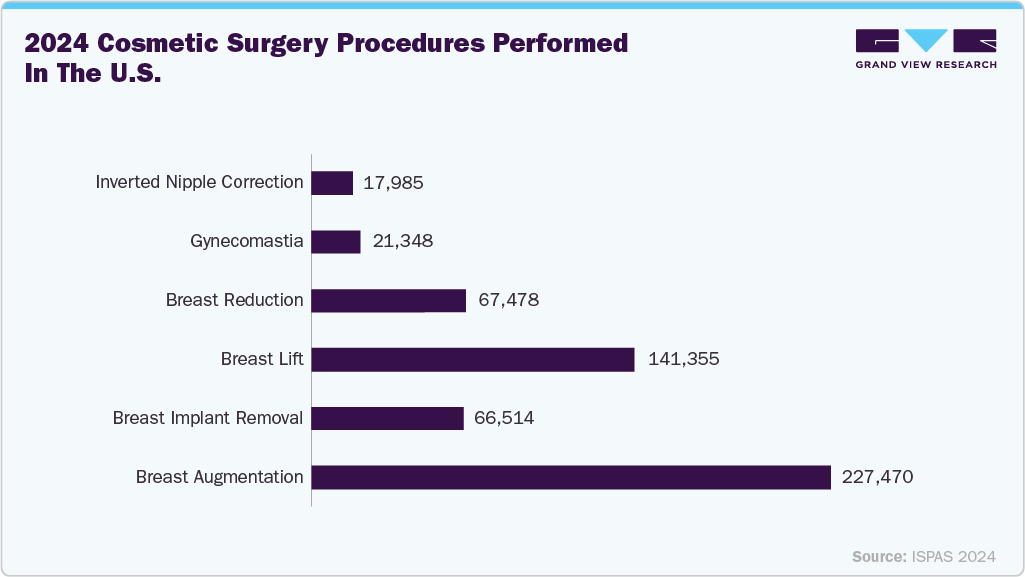
According to the International Society of Aesthetic Plastic Surgery, approximately 1.6 million breast augmentation procedures were performed globally in 2024, making it one of the most frequently performed aesthetic surgical procedures worldwide. Also, the American Society of Plastic Surgeons reported that 306,196 breast augmentation procedures were performed in the U.S. in 2024, reflecting continued demand for cosmetic breast enhancement despite economic fluctuations. The steady rise in procedural volumes directly supports the growing adoption of silicone and saline breast implants, thereby driving revenue growth in the global breast implants market.
The high cost of breast implant procedures remains a significant restraint on the growth of the breast implants market. Breast augmentation and breast reconstruction surgeries involve substantial expenses, including the cost of implants, surgeon fees, anesthesia, operating room charges, pre-operative evaluations, post-operative care, and potential revision surgeries. In many countries, cosmetic breast augmentation is considered an elective procedure and is generally not covered by public or private health insurance, requiring patients to pay out of pocket. Even for reconstructive procedures, reimbursement policies vary across regions, and patients may still incur additional expenses for follow-up treatments or implant replacement over time. These financial barriers can limit the adoption procedure, particularly in low- and middle-income countries and among price-sensitive populations.
The rising demand for cosmetic procedures presents a significant growth opportunity for the breast implants market. Increasing emphasis on physical appearance, growing awareness of aesthetic treatments, rising disposable incomes, and greater social acceptance of cosmetic surgery are encouraging more individuals to seek breast enhancement procedures. Advancements in implant technology, improved surgical techniques, shorter recovery times, and personalized treatment planning have further enhanced patient confidence and satisfaction. In addition, the expansion of specialized aesthetic clinics, the availability of procedure financing, and the growth of medical tourism are making cosmetic breast augmentation more accessible across both developed and emerging markets.
Market Concentration & Characteristics
The breast implants market demonstrates high innovation, driven by ongoing advancements in materials, implant design, and surgical techniques. Manufacturers are investing in R&D to develop implants with improved biocompatibility, lighter weight, and more natural anatomical movement, such as ergonomically shaped implants and high-strength cohesive gels. Technologies such as 3D imaging for surgical planning, microtextured surfaces to reduce complications, and embedded RFID chips for implant traceability reflect the industry’s push toward personalized, safer solutions. These innovations enhance aesthetic outcomes, improve patient safety, reduce reoperation rates, and broaden acceptance among patients and surgeons. For instance, in April 2025, POLYTECH Health & Aesthetics GmbH, addressing growing concerns about unnatural-looking breast augmentation results and the increasing rate of revision surgeries, supported the launch of a new expert initiative: the Global Consensus on 'Natural Breast Beauty'. Introduced by a group of prominent plastic surgeons from around the world, this initiative was officially presented at Palazzo Turati in Milan, highlighting the industry's shift toward achieving more natural, aesthetically pleasing outcomes in aesthetic breast procedures.
Regulations are critical in shaping the breast implants market by ensuring patient safety, product quality, and market transparency. Regulatory bodies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) set stringent guidelines for clinical trials, manufacturing practices, and post-market surveillance. These regulations have led to the withdrawal of substandard products, enhanced the development of next-generation implants, and prompted companies to adopt more transparent labeling and data-tracking systems, such as unique device identifiers (UDIs) and RFID-enabled implants. While compliance may increase time-to-market and costs, it promotes greater patient trust, drives innovation in safer designs, and encourages standardization across regions, ultimately influencing market growth and global adoption.
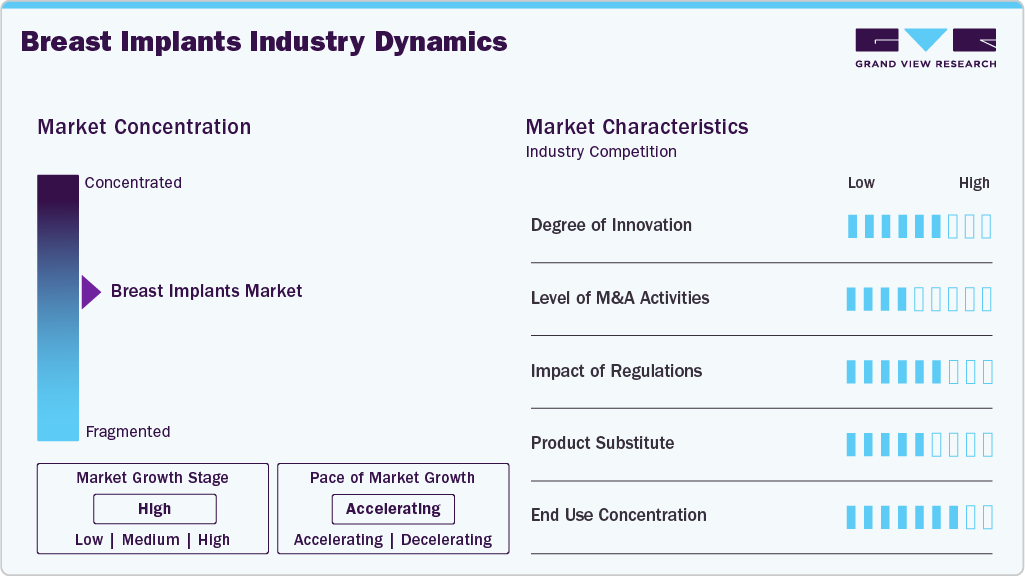 To learn more about this report, Download Free Sample Report
-
In September 2024, the FDA approved for marketing Motiva USA, LLC’s SmoothSilk Round and Round Ergonomix Silicone Gel-Filled Breast Implants, indicated for breast augmentation for patients of at least 22 years of age. The device approval is supported by an open-label, prospective study of 560 patients followed up to three years at more than 20 U.S. and European study sites.
The breast implants market has experienced a moderate to high level of mergers and acquisitions (M&A) in recent years, driven by the need for portfolio diversification, geographical expansion, and technological enhancement. Larger medical device companies acquire innovative startups or smaller manufacturers specializing in advanced implant designs, surface textures, or integrated safety technologies. These M&A activities aim to streamline R&D pipelines, enhance market competitiveness, and meet the rising demand for customized, safe breast augmentation and reconstruction solutions.
-
In October 2024, Hologic, Inc. announced that it had signed a definitive agreement to acquire Gynesonics, Inc., a privately held firm specializing in minimally invasive solutions for women’s health. The acquisition, valued at approximately USD 350 million, is subject to customary closing adjustments and regulatory approvals.
In the breast aesthetics and reconstruction space, several product substitutes pose a potential challenge to traditional breast implants. These include autologous fat grafting, external breast prostheses, and tissue flap reconstruction (like TRAM or DIEP flaps). Among these, fat grafting, which involves transferring the patient's fat from one body area to the breasts, is gaining popularity due to its natural feel and minimal risk of foreign body complications. External prostheses offer a non-surgical option for breast volume enhancement, especially for post-mastectomy patients. While these alternatives provide certain benefits, such as reduced surgical risks and natural appearance, they may not match implants' volume control, predictability, or longevity, especially in augmentation procedures.
The breast implants market exhibits a high end-user concentration, with most of the demand stemming from hospitals, specialized plastic surgery clinics, and ambulatory surgical centers. Among these, private plastic surgery clinics account for a significant share due to the high volume of elective cosmetic augmentation procedures. Hospitals and reconstructive surgery centers are key end-users for post-mastectomy breast reconstruction procedures, driven by the rising incidence of breast cancer. In addition, ambulatory surgical centers (ASCs) are preferred for outpatient breast implant surgeries due to their cost-efficiency and shorter recovery time. This concentrated end-user landscape impacts manufacturers to target marketing, training, and product development efforts toward high-volume surgical centers and top-performing cosmetic surgeons.
Analyst Perspective
The breast implants market is expected to grow steadily, driven by rising demand for cosmetic breast augmentation, increasing breast cancer prevalence requiring reconstructive surgery, and greater awareness of post-mastectomy reconstruction. Advancements in implant technology, including cohesive silicone gel, improved shell designs, and enhanced safety features, are supporting patient satisfaction and surgeon confidence. Expanding aesthetic surgery centers, greater access to skilled plastic surgeons, and medical tourism are further improving access across developed and emerging markets. Manufacturers focusing on product innovation, clinical evidence, regulatory approvals, and global distribution expansion are better positioned to strengthen their market presence. Investments in next-generation implants, surgeon training, digital patient engagement, and collaborations with hospitals and aesthetic clinics are expected to enhance competitiveness. Rising disposable incomes, growing acceptance of aesthetic procedures, and advances in reconstructive surgery are also expected to create sustained growth opportunities.
Product Insights
Based on product, the silicone breast implants segment led the market with the largest revenue share of 84.0% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The growth is attributed to a greater preference for silicone implants owing to their superior characteristics, such as properties similar to natural breast tissue and biocompatibility. For instance, a gummy implant makes the reconstructed organ look more natural than an artificial one. This product segment also does not cause immune system disorders. Due to their soft texture, silicone implants are expected to continue their dominance over the forecast period. Moreover, this feature reduces the risk of hard scar tissue formation and wrinkling around the implantation site.
The saline implants segment is expected to grow significantly over the forecast period. Owing to the saline implants are filled with sterile saltwater, which can be safely absorbed by the body in case of rupture, enhancing patient safety perception. In addition, saline implants require smaller incisions, as they are filled after insertion, making the procedure less invasive and more customizable. Moreover, there is a growing preference for natural and easily detectable implants, especially among patients seeking transparency and a lower risk of hidden rupture.
Shape Insights
Based on shape, the round segment led the market with the largest revenue share of 80.1% in 2025. The growth is due to their round shape, which makes them ideal for breast augmentation. These implants look such as compressed spheres, which created a huge demand and contributed to the market growth. Round-shaped implants are proportional and don't cause problems during implant rotation, so surgeons recommend them. Laboratories Arion offers a wide-ranging portfolio comprising round-shaped implants.
Anatomical segment is expected to witness the fastest CAGR over the forecast period. This growth can be attributed to the rising patient preference for natural-looking breast augmentation. Anatomical implants, also known as teardrop-shaped implants, are specifically designed to replicate the natural slope and contour of the breast, offering a more realistic appearance than round implants. This makes them a popular choice among individuals undergoing reconstructive surgeries post-mastectomy or those seeking subtle cosmetic enhancements. As the trend toward personalized, aesthetically natural results gains momentum, demand for anatomical implants is expected to grow substantially.
Application Insights
Based on application, the cosmetic surgery segment led the market with the largest revenue share of 76.2% in 2025 and is expected to register the fastest CAGR over the forecast period. This growth is primarily driven by rising aesthetic consciousness, increasing disposable incomes, and broader societal acceptance of cosmetic enhancements. According to the American Society of Plastic Surgeons, breast augmentation remained one of the top cosmetic surgical procedures in the U.S. in 2024, with a surge in demand among women in their 20s and 30s seeking enhancement to boost body confidence and achieve proportional symmetry. The availability of advanced implant options, such as anatomically shaped, highly cohesive gel, and lighter-weight implants, has further fueled the segment's popularity. In addition, advancements in minimal incision techniques and safer surgical practices continue to attract a broader demographic, reinforcing cosmetic surgery's dominance and future growth in the breast implants market.
End Use Insights
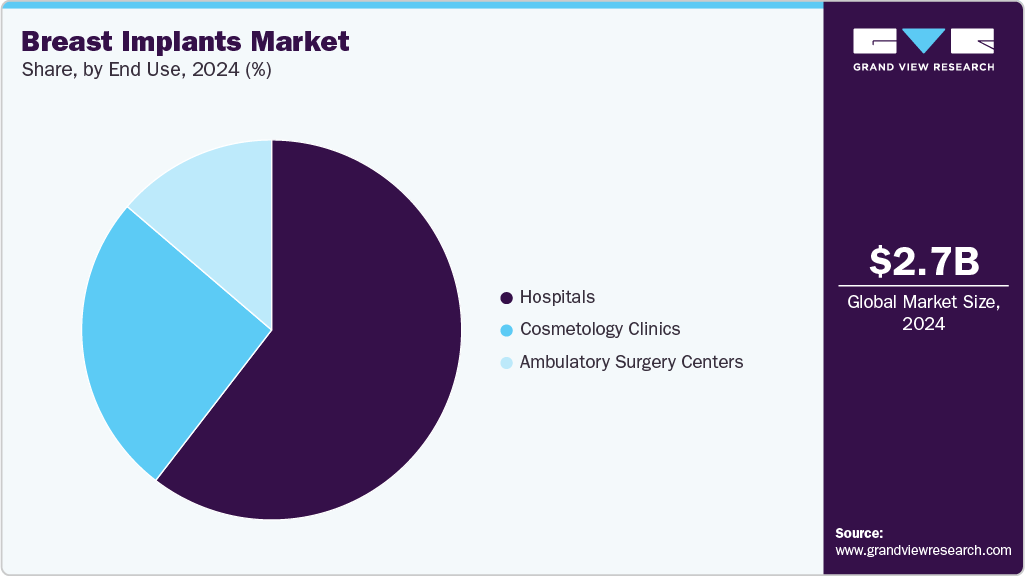
Based on end use, the hospital segment dominates the breast implants market in 2025. This growth can be attributed to the increasing number of breast reconstruction surgeries post-mastectomy and a rise in cosmetic augmentation procedures performed in hospital settings. Hospitals offer comprehensive care with access to advanced surgical technologies, skilled plastic surgeons, and post-operative monitoring, making them a preferred choice for both aesthetic and reconstructive breast surgeries. In addition, hospitals collaborate with cancer care centers for breast reconstruction following mastectomy, which has become more common due to rising breast cancer prevalence. The availability of FDA-approved implants, insurance reimbursements in reconstructive cases, and multidisciplinary teams further reinforce hospitals' leading role in the breast implants market.
 To learn more about this report, Download Free Sample Report
However, the cosmetology clinics segment is projected to witness the fastest growth rate over the forecast period. This can be attributed to the increasing demand for minimally invasive aesthetic procedures and growing public awareness about cosmetic enhancements. These clinics are becoming popular among individuals seeking breast augmentation for purely aesthetic purposes, as they offer personalized services, shorter waiting times, and cost-effective packages compared to hospitals. In addition, the rising social acceptance of cosmetic surgery, the effect of social media, and the availability of advanced implant technologies are encouraging more patients, especially younger demographics, to opt for procedures in cosmetology clinics.
Regional Insights
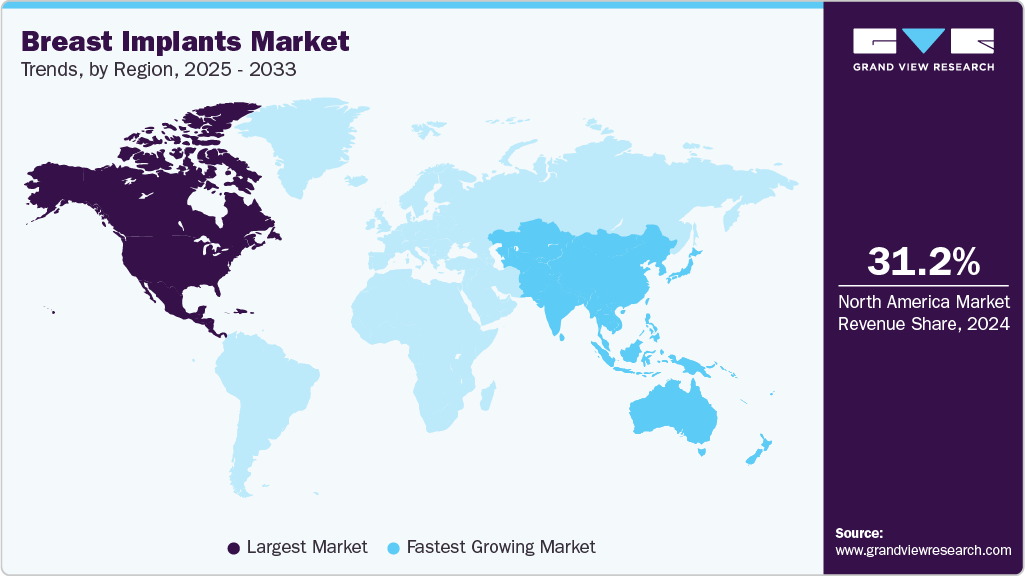
North America dominated the breast implants market with the largest revenue share of 32.7% in 2025. The growth is attributed to increasing demand for cosmetic procedures, rising awareness of reconstructive surgeries after mastectomy, and technological advancements in implant materials. The U.S. holds the largest share, owing to the presence of many board-certified plastic surgeons, a well-established healthcare infrastructure, and a strong presence of leading manufacturers. In addition, favorable reimbursement policies for breast reconstruction under acts as the Women’s Health and Cancer Rights Act (WHCRA) support procedural volumes. The growing trend toward personalization in cosmetic surgery and FDA approvals for advanced implants, such as Motiva and MemoryGel Enhance, further contribute to regional market expansion.
 To learn more about this report, Download Free Sample Report
U.S. Breast Implants Market Trends
The breast implants market in the U.S. held the largest share in the North America region in 2025. The U.S. breast implants market is experiencing growth, driven by rising demand for aesthetic enhancement procedures and the growing number of breast reconstruction surgeries post-mastectomy. An increasing prevalence of breast cancer has led to a surge in reconstructive surgeries, which are supported by favorable insurance coverage under federal mandates. In addition, technological advancements in implant materials, such as cohesive gel implants and lightweight designs, are attracting a broader patient population. The presence of a large pool of board-certified plastic surgeons and FDA-approved, high-quality implant options further fuels patient confidence and procedure uptake nationwide.
 To learn more about this report, Download Free Sample Report
Europe Breast Implants Market Trends
The Europe breast implants market is growing, driven by increasing cosmetic awareness, a growing number of aesthetic procedures, and supportive healthcare infrastructure. Countries similar to Germany, France, and the UK are leading in procedural volume due to high standards in surgical expertise and access to advanced implant technologies. The region is also shifting toward anatomically shaped and lightweight implants that offer a more natural look and reduced post-operative complications. In addition, the rise in breast reconstruction surgeries post-mastectomy, driven by cancer awareness programs and public health initiatives, is boosting market demand.
The UK breast implants market is primarily driven by a rising demand for cosmetic enhancement procedures and increasing acceptance of aesthetic surgery among a broader demographic, including older adults. Growing awareness of post-mastectomy breast reconstruction options, supported by the NHS and cancer charities, is further propelling implant adoption. Technological advancements, such as ergonomic and lightweight implants with improved safety profiles, are attracting more patients. The presence of well-regulated clinical standards and a highly skilled workforce in plastic surgery fosters consumer confidence. Social media effects and celebrity culture continue to normalize cosmetic augmentation, strengthening market growth in the UK.
 To learn more about this report, Download Free Sample Report
The breast implants market in Germany is growing due to a mix of medical necessity and evolving aesthetic preferences. A key driver is the country’s strong focus on breast reconstruction following cancer treatment, where implants are widely used as part of post-surgical care supported by public and private healthcare systems. Increasing acceptance of cosmetic procedures and rising interest in body image enhancement are contributing to higher demand for breast augmentation in private clinics. Germany’s highly regulated medical environment, overseen by authorities such as the Federal Institute for Drugs and Medical Devices, ensures strict safety and quality standards that help build patient confidence and encourage the adoption of newer implant technologies. Continuous advancements in implant design, including improved silicone formulations and anatomically shaped implants, are also influencing patient preferences toward safer, more natural-looking outcomes.
Aesthetic breast surgical procedures performed in Germany in 2024
Procedure
Number
Breast Augmentation
70,128
Breast Implant Removal
12,510
Breast Lift
29,778
Breast Reduction
32,068
Gynecomastia
17,444
Inverted Nipple Correction
4,405
Source: ISPAS 2024
Asia Pacific Breast Implants Market Trends
The Asia Pacific breast implants market is experiencing fastest CAGR from 2026 to 2033. Fueled by increasing disposable incomes, rising awareness of cosmetic procedures, and shifting beauty standards. Countries such as China, Japan, South Korea, and India are emerging as key markets, driven by the growth of medical tourism destinations and a surge in aesthetic consciousness among younger demographics. Minimally invasive procedures and the demand for natural-looking augmentation are also gaining popularity, driving product innovation toward ergonomic, lightweight implants.
The China breast implants market is being driven by an increasing disposable income and evolving beauty standards among the younger population. Urbanization and greater exposure to Western aesthetics through social media have led to a growing acceptance of body-enhancement surgeries, including breast augmentation. Moreover, China's rapidly expanding medical aesthetics industry and the availability of advanced surgical techniques are further accelerating market growth. The country's large population and increasing focus on appearance, particularly among millennials and Gen Z women, are expected to continue driving demand for breast implants in the coming years.
The breast implants market in India is growing, supported by rising awareness of aesthetic procedures and changing perceptions around cosmetic surgery. Increasing acceptance of body enhancement treatments, particularly among younger and middle-income populations, is contributing to higher demand for breast augmentation. The growing incidence of breast cancer is driving the need for reconstructive surgeries, where implants are widely used as part of post-mastectomy care. Improvements in healthcare infrastructure and the expansion of specialized plastic surgery centers are making these procedures more accessible nationwide. In addition, the availability of skilled surgeons and the adoption of advanced implant technologies with improved safety and natural outcomes are enhancing patient confidence. The country is also emerging as a preferred destination for medical tourism, thanks to cost-effective treatment options and quality care, further supporting the expansion of the breast implants market.
 To learn more about this report, Download Free Sample Report
Latin America Breast Implants Market Trends
The Latin America breast implants market is growth-driven by increasing demand for cosmetic procedures. Brazil, in particular, remains one of the world leaders in aesthetic surgeries, including breast augmentation. Cultural acceptance of plastic surgery, along with a high emphasis on physical appearance, is contributing to the widespread adoption of breast implants. In addition, the availability of skilled plastic surgeons, cost-effective procedures compared to those in North America and Europe, and the growing number of medical tourists further support market expansion. Technological advancements and rising awareness of reconstructive breast surgery post-mastectomy are also key factors shaping the regional market trends.
Aesthetic breast surgical procedures performed in Brazil in 2024
Procedure
Number
Breast Augmentation
232,593
Breast Implant Removal
42,231
Breast Lift
137,736
Breast Reduction
115,647
Gynecomastia
44,180
Inverted Nipple Correction
9,096
Source: ISPAS 2024
Middle East Africa Breast Implants Market Trends
The breast implants market in the Middle East and Africa is experiencing gradual but consistent growth, driven by improving healthcare infrastructure and rising awareness of both cosmetic and reconstructive procedures. Increasing acceptance of aesthetic surgery, particularly in more urbanized and higher-income parts of the region, is contributing to growing demand for breast augmentation. The rising incidence of breast cancer is supporting the need for reconstructive surgeries, where implants are commonly used as part of post-treatment care. Governments and private healthcare providers are investing in advanced medical facilities and training, which is enhancing access to specialized plastic surgery services.
In addition, the expansion of private clinics and the entry of international medical device companies are introducing advanced implant technologies with better safety profiles and outcomes. For instance, under Saudi Vision 2030, the Saudi Arabian Government plans to invest over USD 65 billion to develop the country's healthcare infrastructure, reorganize and privatize health services and insurance, launch 21 health clusters across the country, and expand the provision of e-health services. In addition, it aims to increase the private sector's contribution from 40 percent to 65 percent by 2030, targeting the privatization of 290 hospitals and 2,300 primary health centers.
Key Breast Implants Company Insights
The breast implants market is extremely fragmented, with both major and local market competitors. As current market players step up their efforts to gain a majority share in the breast implants market, fierce competition is anticipated, with the level of competition perhaps rising further. Many market participants are pursuing various strategic initiatives, such as product launches, mergers and acquisitions, and geographic expansion, to gain a competitive edge over rivals. Thus, with various strategies adopted by the market players, the breast implants market is predicted to impel during the forecast period.
Key Breast Implants Companies:
The following key companies have been profiled for this study on the breast implants market.
- ALLERGAN (AbbVie)
- GC Aesthetics
- SEBBIN
- Mentor Worldwide LLC (Johnson & Johnson)
- Sientra Inc. (Tiger Aesthetics Medical, LLC)
- POLYTECH Health & Aesthetics GmbH
- Establishment Labs S.A.
- Shanghai Kangning Medical Supplies Ltd.
- Guangzhou Wanhe Plastic Materials Co., Ltd.
- HansBioMed
- Bimini Health Tech.
 To learn more about this report, Download Free Sample Report
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ALLERGAN (AbbVie), Establishment Labs S.A., GC Aesthetics)
- Focus on expanding premium silicone breast implant portfolios through continuous product innovation, clinical research, regulatory approvals, and global commercialization.
- Strengthen market presence by collaborating with plastic surgeons, hospitals, aesthetic clinics, and distributor networks while investing in surgeon education and post-market surveillance programs.
- Strong global brand recognition, extensive regulatory approvals, diversified product portfolios, and well-established distribution networks.
- Significant R&D capabilities, manufacturing expertise, and long-standing relationships with plastic surgeons provide a competitive advantage and high customer confidence.
- High R&D expenditure, stringent regulatory requirements, product liability risks, and costs associated with long-term clinical studies.
- Market growth is also affected by product recalls, safety concerns, and increasing competition from regional manufacturers offering lower-priced alternatives.
Emerging Players (SEBBIN,Sientra Inc. (Tiger Aesthetics Medical, LLC), Shanghai Kangning Medical Supplies Ltd.)
- Focus on expanding regional market presence through competitively priced breast implants, customized product offerings, distributor partnerships, and entry into emerging markets.
- Many companies emphasize niche product development, localized manufacturing, and regulatory expansion into Asia-Pacific, Latin America, and the Middle East.
- Competitive pricing, greater operational flexibility, faster product customization, and strong regional distribution networks enable these companies to penetrate price-sensitive markets.
- Their ability to respond quickly to local demand and establish partnerships with aesthetic clinics supports market expansion.
- Limited global brand recognition, smaller product portfolios, fewer regulatory approvals, and comparatively lower investment in clinical research and innovation than multinational companies.
- Expansion is often constrained by limited financial resources, distribution capabilities, and intense competition from established global manufacturers.
Recent Developments
-
In January 2026, Johnson & Johnson announced the U.S. launch of the Arbrea Breast Simulator Surgeon App for Mentor, a digital consultation tool designed to support breast augmentation for patients. The mobile application enables plastic surgeons to provide real-time 3D simulations, allowing patients to visualize potential outcomes on their own bodies during consultations.
-
In March 2025, Establishment Labs Holdings Inc. announced the launch of its Preservé breast augmentation technology in Brazil, marking the first step in its global rollout. Preservé is part of the company’s minimally invasive platform and builds on innovations developed through Mia Femtech. The technology is designed to preserve breast tissue during surgery, helping maintain structural integrity and delivering more natural outcomes than traditional augmentation techniques.
-
In March 2025, BD announced that the first patient had been treated in an Investigational New Drug (IND) clinical trial aimed at supporting its Premarket Approval (PMA) application to the U.S. Food and Drug Administration (FDA). The trial evaluates the use of the GalaFLEX LITE Scaffold to reduce the recurrence of capsular contracture (CC) during breast revision surgery, marking a critical step in advancing breast implant safety and surgical outcomes.
-
In March 2025, POLYTECH Health & Aesthetics announced the launch of its direct subsidiary in the UK, marking a significant strategic investment. This move underscores the company’s commitment to delivering high-quality aesthetic and breast reconstruction solutions while strengthening its presence in one of Europe’s key markets.
-
In May 2025, Johnson & Johnson MedTech announced the U.S. launch of its MENTOR MemoryGel Enhance Breast Implants, addressing a significant need in the continuum of breast cancer care. These implants are specifically designed to support women who have undergone a mastectomy, offering advanced reconstruction options that combine aesthetic appeal with safety and comfort.
Breast Implants Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 2.1 billion
Market size value in 2026
USD 2.2 billion
Revenue forecast in 2033
USD 3.2 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, shape, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; Thailand; South Korea, Brazil; Argentina; Columbia; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
ALLERGAN (AbbVie); GC Aesthetics; SEBBIN; Mentor Worldwide LLC (Johnson & Johnson); Sientra Inc. (Tiger Aesthetics Medical, LLC); POLYTECH Health & Aesthetics GmbH; Establishment Labs S.A.; Shanghai Kangning Medical Supplies Ltd.; Guangzhou Wanhe Plastic Materials Co., Ltd.; HansBioMed; Bimini Health Tech.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Breast Implants Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global breast implants market report on the basis of product, shape, application, end use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Silicone Breast Implants
-
Saline Breast Implants
-
-
Shape Outlook (Revenue, USD Million, 2021 - 2033)
-
Round
-
Anatomical
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Reconstructive Surgery
-
Cosmetic Surgery
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Cosmetology Clinics
-
Ambulatory Surgical Centers
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The breast implants market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each breast implants segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Silicone Breast Implants
Revenue generated from the sale and use of breast implants filled with cohesive silicone gel for cosmetic breast augmentation and post-mastectomy breast reconstruction. This segment includes smooth and textured silicone implants available in various shapes, sizes, and projection profiles designed to provide a natural look and feel.
Saline Breast Implants
Revenue generated from breast implants filled with sterile saline solution for breast augmentation and reconstructive procedures. These implants are inserted empty and filled during surgery, allowing adjustable volume, smaller incisions, and easier detection of implant rupture. The segment includes various sizes and shell designs used in cosmetic and reconstructive applications.
Estimation Model
Stage
Description
Bottom-Up Estimation
The market size is estimated by assessing the annual number of breast implant procedures performed for both cosmetic breast augmentation and post-mastectomy breast reconstruction across hospitals, cosmetic surgery clinics, and ambulatory surgical centers. Procedure volumes are analyzed at the country level and aggregated to regional and global estimates. The calculation incorporates the adoption rates of silicone and saline breast implants, and average implant utilization per procedure.
Top-Down Approach
The estimation begins with the broader global market for aesthetic and reconstructive medical devices and narrows down to the breast implants segment using procedure statistics, manufacturer revenues, and industry adoption rates. The analysis evaluates the contribution of cosmetic and reconstructive applications by considering breast augmentation volumes, breast cancer incidence requiring reconstruction, and mastectomy rates.
Supply-Side Analysis
The supply-side assessment evaluates the commercial performance of leading breast implant manufacturers by analyzing production capabilities, annual sales, geographic revenue distribution, product portfolios, manufacturing footprints, and regulatory approvals across key markets. The analysis also considers product innovation, launch of next-generation silicone implants, distribution partnerships with hospitals and aesthetic clinics, inventory management.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Breast Implants Product Portfolio & Application Analysis
Conducted a comprehensive assessment of the breast implants product portfolio, including silicone and saline breast implants, along with round and anatomical implant types. Evaluated product adoption across cosmetic breast augmentation and post-mastectomy breast reconstruction procedures while assessing utilization trends across hospitals, cosmetology clinics, and ambulatory surgical centers. The analysis also examined implant selection based on patient preferences, surgical techniques, safety profile, and technological advancements.
Helps stakeholders identify high-growth product categories, understand application-specific demand, evaluate implant adoption trends across healthcare settings, and optimize product portfolios based on evolving clinical and aesthetic requirements.
End-user Adoption & Procedure Volume Analysis
Analyzed the utilization of breast implants across hospitals, cosmetology clinics, and ambulatory surgical centers. Assessed procedure volumes, patient demographics, surgeon preferences, reimbursement landscape for reconstructive procedures, and the influence of healthcare infrastructure and medical tourism on market demand. The study also evaluated regional variations in cosmetic and reconstructive breast implant adoption.
Enables manufacturers to identify high-value end-user segments, strengthen commercial strategies, optimize distribution channels, improve demand forecasting, and expand market presence across developed and emerging regions.
Product Positioning & Manufacturer Competitiveness Assessment
Evaluated leading breast implant manufacturers based on product portfolio breadth, implant technology, regulatory approvals, manufacturing capabilities, pricing strategies, clinical evidence, distribution networks, and innovation initiatives. The assessment also analyzed recent product launches, strategic partnerships, investments in R&D, and competitive differentiation across the global breast implants market.
Supports competitive benchmarking, identifies opportunities for product innovation and portfolio expansion, strengthens go-to-market strategies, and enables companies to enhance their competitive position through technological advancements, regulatory compliance, and expansion into high-growth markets.
Frequently Asked Questions About This Report
The global breast implants market size was valued at USD 2.1 billion in 2025 and is estimated at USD 2.2 billion for 2026.
North America dominated with a 32.7% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The round shape held the largest share of 80.1% in 2025, while anatomical is the fastest-growing segment over the forecast period.
The cosmetic surgery held the largest share of 76.2% in 2025 and is the fastest-growing segment over the forecast period.
The hospitals held the largest share of 59.3% in 2025, while cosmetology clinics is the fastest-growing segment over the forecast period.
The silicone breast implants segment held the largest share of 84.0% in 2025 and is the fastest-growing segment over the forecast period.
The global breast implants market is expected to grow at a CAGR of 5.1% from 2026 to 2033, reaching USD 3.2 billion by 2033.
Key players include ALLERGAN (AbbVie); GC Aesthetics; SEBBIN; Mentor Worldwide LLC (Johnson & Johnson); Sientra Inc. (Tiger Aesthetics Medical, LLC); POLYTECH Health & Aesthetics GmbH; Establishment Labs S.A.; Shanghai Kangning Medical Supplies Ltd.; Guangzhou Wanhe Plastic Materials Co., Ltd.; HansBioMed; Bimini Health Tech.
The growth of breast implants is driven by rising demand for aesthetic enhancement procedures, technological advancements in implant materials, and increased awareness of body contouring solutions. Growing social acceptance of cosmetic surgeries, coupled with the effect of media and celebrity culture, has encouraged more women to opt for breast augmentation. In addition, the availability of minimally invasive techniques and improved implant safety profiles has significantly reduced the hesitation around undergoing such procedures.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


