
- Home
- »
- Plastics, Polymers & Resins
- »
-
Bulk Chemical Packaging Drums for Agrochemicals Market Report, 2033GVR Report cover

Bulk Chemical Packaging Drums For Agrochemicals Market (2026 - 2033)
Size, Share & Trends Analysis Report By Capacity (100-250 Liters, 250-500 Liters, Above 500 Liters), By Product Type (Plastic Drums, Steel Drums, Fiber/Composite Drums), By Region And Segment Forecasts
Market Size, 2025
$1.6BMarket Estimate, 2026
$1.7BMarket Forecast, 2033
$2.4BCAGR, 2026–2033
5.0%Bulk Chemical Packaging Drums For Agrochemicals Market Summary
The global bulk chemical packaging drums for agrochemicals market size was valued at USD 1.6 billion in 2025 and is projected to grow from USD 1.7 billion in 2026 to USD 2.4 billion by 2033, at a CAGR of 5.0% from 2026 to 2033. Asia Pacific dominated the bulk chemical packaging drums for agrochemicals market with the largest revenue share of 39.9% in 2025. The market encompasses large-capacity industrial containers, primarily HDPE drums, composite drums, steel drums, and intermediate bulk drums.
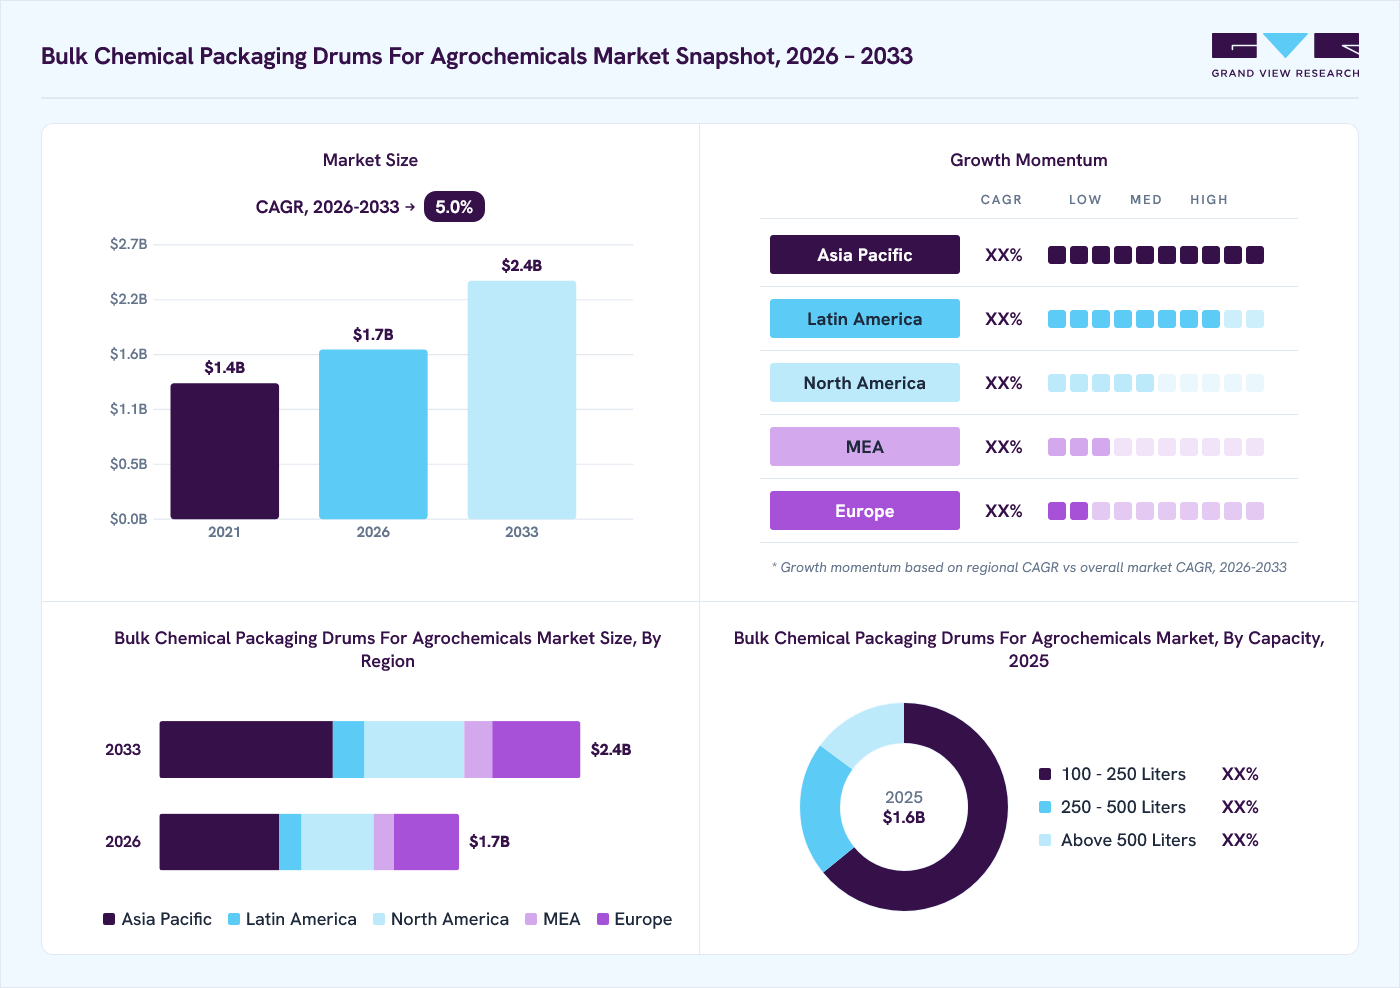 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By capacity: 100-250 liters segment held the largest market share of 64.1% in 2025.
- By product type: Plastic drums segment held the largest market share of 59.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (39.9% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.6 Billion
- Estimated market size in 2026: USD 1.7 Billion
- Projected market size by 2033: USD 2.4 Billion
- CAGR (2026-2033): 5.0%
Prism AI by Grand View Research Free to tryAsk a question about the bulk chemical packaging drums for agrochemicals marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
These are designed to store and transport pesticides, herbicides, fungicides, liquid fertilizers, and bio-stimulants. The drums must meet strict chemical-resistance, UV-stability, permeation control, and safety standards due to the hazardous and reactive nature of agricultural chemicals. The market is strongly tied to agrochemical production output, global crop protection demand, and the expansion of agricultural trade, as many chemicals are shipped across borders in large volumes. To learn more about this report, Download Free Sample Report
Product demand is particularly driven by the shift toward bulk procurement by distributors and agrochemical formulators, who seek reliable long-haul packaging solutions that prevent contamination and ensure regulatory compliance. With agricultural modernization accelerating in Asia-Pacific, Latin America, and Africa, chemical suppliers increasingly rely on robust drum packaging to support export flows and reduce product losses. As sustainable packaging expectations rise, manufacturers are also introducing recyclable HDPE drums and multi-use drum systems to align with circular economy models.
Market Dynamics
The bulk chemical packaging drums for agrochemicals market is witnessing steady growth, supported by rising demand for crop protection chemicals, fertilizers, and other agricultural inputs requiring safe bulk storage and transportation. Increasing regulations related to hazardous chemical handling and product safety are driving the adoption of durable HDPE and steel drums. Moreover, growth in large-scale agriculture, expanding agrochemical trade, and the demand for leak-resistant, reusable, and sustainable packaging solutions continue to support market development.
The increasing global demand for agrochemicals is a primary driver of the bulk chemical packaging drums for agrochemicals market. Rising food consumption, shrinking arable land per capita, and the need to improve agricultural productivity have led to greater use of pesticides, herbicides, fungicides, and fertilizers. With continuous growth in the agrochemical production and distribution volumes, manufacturers require reliable bulk packaging solutions that can safely store, transport, and handle large quantities of chemicals across domestic and international supply chains.
Bulk chemical packaging drums play a critical role in maintaining product integrity, preventing leakage, and ensuring compliance with stringent transportation and safety regulations. HDPE and steel drums are widely preferred due to their durability, chemical resistance, and suitability for hazardous materials. The expansion of commercial farming activities and increasing agrochemical trade, particularly in emerging agricultural economies, are further boosting demand for high-performance bulk packaging drums, making agrochemical consumption growth a key market driver.
Stringent environmental regulations related to plastic waste management, chemical packaging disposal, and recycling requirements pose a significant restraint to the bulk chemical packaging drums for agrochemicals market. Governments and regulatory bodies across various regions are imposing stricter guidelines on the use, recovery, and disposal of industrial packaging materials, increasing compliance costs for manufacturers and end users. Furthermore, growing concerns regarding the environmental impact of discarded chemical containers and challenges associated with cleaning, recycling, and reconditioning contaminated drums may limit market growth and create operational complexities across the agrochemical supply chain.
The growing focus on sustainability and circular economy practices presents a significant opportunity for the bulk chemical packaging drums for agrochemicals market. Agrochemical manufacturers and distributors are increasingly seeking reusable, recyclable, and reconditioned drum solutions to reduce packaging waste, lower transportation costs, and meet evolving environmental regulations. This trend encourages packaging suppliers to invest in advanced drum reconditioning services, recycled material integration, and eco-friendly packaging innovations. As sustainability becomes a key purchasing criterion across the agricultural value chain, demand for environmentally responsible bulk packaging solutions is expected to create new growth opportunities for market participants.
Market Concentration & Characteristics
The market growth stage of the bulk chemical packaging drums for agrochemicals market is medium, and the pace is accelerating. Degree of innovation in this market is moderate, with most advancements focused on material optimization, reconditioning technologies, and integration of RFID/IoT trackers for supply-chain visibility. Significant R&D is also directed at developing drums compatible with aggressive agrochemical formulations while reducing material usage and improving recyclability.
M&A activity is moderate, driven by large industrial packaging companies acquiring regional drum manufacturers, reconditioning firms, and specialty composite drum producers to expand geographic presence and secure captive capacity. Consolidation is common in markets like Europe and North America, while Asia-Pacific sees strategic joint ventures for capacity expansion and regulatory alignment.
 To learn more about this report, Download Free Sample Report
Regulations have a strong impact as transport compliance rules, chemical-handling standards, and extended producer responsibility mandates for plastic waste heavily influence drum design and supply-chain practices. Many markets are increasingly mandating recycling, traceability, and proper disposal of chemical containers, pushing manufacturers toward sustainable, reconditionable, or rHDPE drums.
Substitutes include intermediate bulk containers (IBCs), jerry cans, and bulk flexitanks, which can replace drums for certain liquid agrochemical formats. However, drums remain the preferred choice for high-hazard liquids, corrosive formulations, and decentralized distribution systems due to superior durability, cost efficiency, and regulatory acceptability.
End-user concentration is moderate, with a mix of large global agrochemical manufacturers, regional formulators, and agrochemical distributors. The top global agrochemical companies account for a large share of bulk drum demand, while a long tail of local formulators ensures steady baseline consumption across developing agricultural markets.
Analyst Perspective
The bulk chemical packaging drums for agrochemicals market is expected to grow steadily, driven by increasing demand for crop protection chemicals, fertilizers, and other agricultural inputs requiring safe bulk storage and transportation. Stringent regulations for hazardous chemical handling and growing agrochemical trade are supporting the adoption of durable HDPE and steel drums. The market is also benefiting from expanding commercial farming activities and rising focus on sustainable packaging solutions. Companies investing in recyclable materials, drum reconditioning, and regulatory-compliant packaging are likely to gain a competitive advantage in the coming years.
Capacity Insights
Based on capacity, the 100-250 liters segment led the market with the largest revenue share of 64.1% in 2025. The 100-250-liter drums are widely preferred for mid-volume agrochemical formulations such as emulsifiable concentrates, liquid fertilizers, and biological inputs that require manageable handling and regional distribution. Additionally, these drums are extensively used by small and mid-sized agrochemical formulators serving domestic markets, as they strike a balance between portability and cost efficiency.
250-500-liter drums are the backbone of large-scale bulk packaging for agrochemicals, especially for export shipments across Asia-Pacific, Europe, and Latin America. These drums reduce per-liter logistics costs, improve storage density, and are highly compatible with palletized transport systems. This capacity range is favored by major agrochemical manufacturers who supply concentrated pesticides or liquid fertilizers to international distributors.
The above 500 liters segment is anticipated to grow at a substantial CAGR of 6.7% through the forecast period. Drums above 500 liters are used primarily for high-volume, industrial-grade agrochemical production and long-term warehouse storage. Their large capacity optimizes bulk supply to major distributors, blending facilities, and large agricultural estates using mechanized dosing systems. While less flexible for last-mile distribution, these drums significantly reduce packaging frequency and handling labor, appealing to companies involved in high-output blending operations and cross-border bulk exports.
Product Type Insights
Based on product type, the plastic drums segment led the market with the largest revenue share of 59.6% in 2025. Plastic drums, especially HDPE and multilayer variants are widely used in packaging segment due to their chemical resistance, lightweight construction, and cost-effectiveness. They are suitable for a wide range of pesticide formulations, liquid fertilizers, and biochemicals.
Steel drums serve high-hazard and high-reactivity agrochemical applications where strength, impact resistance, and superior barrier properties are critical. They are preferred for corrosive formulations, solvent-rich pesticides, and agrochemical intermediates that cannot be safely stored in conventional plastics. Although heavier and costlier, steel drums remain indispensable for regulatory compliance in export shipments and for buyers demanding maximum safety assurance.
 To learn more about this report, Download Free Sample Report
Fiber/composite drums offer a lightweight, cost-effective alternative for agrochemicals that pose lower chemical compatibility challenges. Typically constructed with fiber exteriors and plastic/foil liners, they are increasingly adopted for dry agrochemical powders, dispersible granules, and bio-based formulations. While not suitable for the most aggressive chemicals, their sustainability advantages and favorable handling characteristics are driving steady adoption in environmentally regulated markets.
Regional Insights
Asia Pacific dominated the bulk chemical packaging drums for agrochemicals market with the largest revenue share of 39.9% in 2025. The market is expanding due to expanding agrochemical manufacturing bases in China, India, and Southeast Asia. Export-driven producers rely heavily on UN-certified HDPE and steel drums for large-volume shipments to global markets. Rapid agricultural modernization, rising fertilizer demand, and government support for high-efficiency farming inputs continue to accelerate drum consumption across this region.
 To learn more about this report, Download Free Sample Report
China Bulk Chemical Packaging Drums For Agrochemicals Market Trends
The bulk chemical packaging drums for agrochemicals market in China held the largest share in the Asia Pacific region in 2025. China is a global powerhouse in agrochemical manufacturing and exports, leading to very high consumption of bulk HDPE and steel drums for international shipping. Domestic demand is also strong due to the scale of national agricultural activities. Increasing environmental regulations and the shift towards higher-value formulations continue to accelerate adoption of compliant, high-performance drum packaging.
The India bulk chemical packaging drums for agrochemicals market’s demand is driven by its large pesticide manufacturing industry, expanding agricultural exports, and rising adoption of bulk packaging by regional distributors. HDPE drums dominate due to cost advantages, while steel drums are used for high-hazard formulations. Growing regulatory enforcement around safe pesticide handling is pushing formulators to upgrade to UN-certified drum formats.
North America Bulk Chemical Packaging Drums For Agrochemicals Market Trends
North America shows strong demand for bulk agrochemical drums due to extensive commercial farming, high agrochemical consumption per acre, and strict hazardous materials transport regulations. Large agriculture businesses, centralized distribution networks, and advanced storage infrastructure drive significant uptake of steel and HDPE drums. Sustainability regulations and chemical stewardship programs also push adoption of reconditioned and recycled-content drums.
The U.S. bulk chemical packaging drums for agrochemicals market is supported by large-scale row-crop farming, high agrochemical usage, and well-established distribution networks. Bulk drums are widely used for both domestic distribution and export shipments, with strong adoption of reconditioned HDPE drums driven by sustainability mandates. Compliance with DOT, EPA, and UN transport rules makes high-integrity drums a procurement priority for agrochemical majors.
Europe Bulk Chemical Packaging Drums For Agrochemicals Market Trends
Europe’s market is influenced by stringent regulatory compliance (ADR, REACH), growing demand for eco-safe packaging materials, and rising use of precision agriculture inputs. Demand is particularly strong in countries with high agricultural export activity, such as Germany, France, and the Netherlands. The region favors high-quality, fully certified drums with traceability features, recyclability attributes, and multi-use potential.
Germany Bulk Chemical Packaging Drums For Agrochemicals Market Trends
The Germany bulk chemical packaging drums for agrochemicals market is shaped by strict chemical handling regulations, high adoption of precision farming solutions, and a strong domestic chemical manufacturing sector. German agrochemical producers increasingly demand high-specification drums with superior chemical resistance and track-and-trace capabilities. A strong focus on circular economy initiatives supports demand for reconditioned and recyclable drum systems.
Latin America Bulk Chemical Packaging Drums For Agrochemicals Market Trends
Latin America is a high-potential market driven by large-scale cash crop production in Brazil, Argentina, and Chile. Increasing agrochemical imports and regional formulation units boost the demand for durable drums capable of withstanding extreme climates and long-distance distribution. Adoption is particularly strong for steel and high-strength HDPE drums used in pesticide-intensive agricultural segments.
Middle East & Africa Bulk Chemical Packaging Drums For Agrochemicals Market Trends
The market is shaped by agricultural expansion in Africa and growing agrochemical import reliance in the Middle East. Drums are widely used for safe storage and transport of liquid fertilizers and pesticides in hot climates where UV-resistant and anti-permeation packaging is essential. Rising investments in commercial farming and regional blending facilities amplify the need for reliable bulk chemical drums.
The Saudi Arabia bulk chemical packaging drums for agrochemicals market demand is driven by increasing agricultural sector diversification and agrochemical imports supporting greenhouse and desert farming initiatives. Drums are essential for transporting fertilizers and pesticides across long distances in harsh desert climates, driving preference for UV-resistant HDPE and steel formats. Government-backed agricultural expansion programs continue to support market growth.
Key Bulk Chemical Packaging Drums For Agrochemicals Market Company Insights
The bulk agrochemical drum market is a mix of a few large, multinational industrial-packaging suppliers and a long tail of regional specialists and niche converters. Global leaders compete on product certification, chemical compatibility, supply reliability and increasingly on sustainability features. Regional players, especially in China, India, and Brazil, compete on price, fast lead times, and local regulatory know-how, while specialty vendors focus on composite/liner technologies and turnkey reconditioning services.
Key Bulk Chemical Packaging Drums For Agrochemicals Manufacturers Companies:
The following key companies have been profiled for this study on the bulk chemical packaging drums for agrochemicals market.
-
Greif, Inc.
-
Mauser Packaging Solutions
-
SCHÜTZ GmbH & Co. KGaA
-
Snyder Industries, Inc.
-
Time Technoplast
-
Balmer Lawrie & Co. Ltd.
-
Sonoco Products Company
-
Crown Holdings, Inc.
-
Fibrestar
-
JSK Plastic
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Greif, Inc.; Mauser Packaging Solutions; SCHÜTZ GmbH & Co. KGaA; Snyder Industries, Inc.; Time Technoplast; Balmer Lawrie & Co. Ltd.; Sonoco Products Company; Crown Holdings, Inc.)
- Focus on large-scale manufacturing and global distribution networks to serve multinational agrochemical producers across multiple regions.
- Invest in product innovation, sustainability initiatives, and closed-loop packaging solutions to meet evolving regulatory and customer requirements.
- Strong brand recognition, extensive customer relationships, and diversified portfolios covering plastic, steel, and fiber/composite drums.
- Advanced manufacturing capabilities, regulatory compliance expertise, and well-established supply chain infrastructure that ensure consistent product availability.
- Higher operational and compliance costs associated with maintaining global manufacturing facilities and extensive distribution networks.
- Longer decision-making processes and reduced agility when responding to emerging market trends or customized customer requirements.
Emerging Players (Fibrestar; JSK Plastic)
- Concentrate on regional markets and niche customer segments, offering flexible production volumes and customized drum solutions.
- Expand market presence through distributor partnerships and target investments in production capacity and product quality enhancements.
- Greater operational flexibility, enabling faster response to customer-specific requirements and changing market demands.
- Competitive pricing and localized customer support that strengthen relationships with regional agrochemical manufacturers.
- Limited geographic reach, production capacity, and financial resources compared to established global competitors.
- Lower brand visibility and weaker bargaining power with large agrochemical companies and raw material suppliers.
Recent Developments
-
In January 2024, SCHÜTZ GmbH & Co. KGaA launched production of PE tight-head drums at a new facility in Dahej, Gujarat, India. The site also plans to support their global IBC (intermediate bulk container) system and includes reconditioning capacity. This expansion signals SCHÜTZ’s strategy to serve both domestic and export-oriented chemical/agrochemicals markets with globally certified drums.
Bulk Chemical Packaging Drums For Agrochemicals Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.6 billion
Estimated market size in 2026
USD 1.7 billion
Projected market size by 2033
USD 2.4 billion
Growth rate
CAGR of 5.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Capacity, product type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Greif, Inc.; Mauser Packaging Solutions; SCHUTZ GmbH & Co. KGaA; Snyder Industries, Inc.; Time Technoplast; Balmer Lawrie & Co. Ltd.; Sonoco Products Company; Crown Holdings, Inc.; Fibrestar; JSK Plastic
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Chemical Packaging Drums For Agrochemicals Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the bulk chemical packaging drums for agrochemicals market report on the basis of capacity, product type, and region:
 To learn more about this report, Download Free Sample Report
-
Capacity Outlook (Revenue, USD Million, 2021 - 2033)
-
100-250 Liters
-
250-500 Liters
-
Above 500 Liters
-
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Plastic Drums
-
Steel Drums
-
Fiber/Composite Drums
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The bulk chemical packaging drums for agrochemicals market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each bulk chemical packaging drums for agrochemicals segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Capacity
Revenue capture definition
100–250 Liters
Revenue generated from the sale of bulk chemical packaging drums with a storage capacity ranging from 100 to 250 liters, designed for the storage and transportation of agrochemicals such as pesticides, herbicides, fungicides, and specialty crop protection chemicals. This segment includes medium-capacity plastic, steel, and composite drums used by agrochemical manufacturers, distributors, and agricultural service providers.
250–500 Liters
Revenue generated from the sale of bulk chemical packaging drums with a storage capacity ranging from 250 to 500 liters, used for handling larger volumes of agrochemicals requiring secure storage, distribution, and regulatory compliance. This segment includes drums utilized across commercial farming operations, agrochemical distribution networks, and industrial agricultural applications.
Above 500 Liters
Revenue generated from the sale of bulk chemical packaging drums with capacities exceeding 500 liters, intended for high-volume storage and transportation of agrochemicals. This segment includes large-capacity drums and related bulk containment solutions used by large-scale agrochemical producers, contract manufacturers, and agricultural supply chains where efficient bulk handling is critical.
Segment - Product Type
Revenue capture definition
Plastic Drums
Revenue generated from the sale of plastic bulk chemical packaging drums, primarily manufactured from high-density polyethylene (HDPE) and other chemical-resistant polymers. This segment includes drums designed to provide corrosion resistance, leak prevention, and safe transportation of liquid and solid agrochemicals.
Steel Drums
Revenue generated from the sale of steel bulk chemical packaging drums used for storing and transporting hazardous and non-hazardous agrochemicals. This segment includes carbon steel and stainless-steel drums valued for their durability, structural strength, and suitability for demanding storage and transportation conditions.
Fiber/Composite Drums
Revenue generated from the sale of fiber and composite bulk chemical packaging drums that combine lightweight construction with protective barrier properties. This segment includes fiberboard and multi-material drums used for selected agrochemical formulations where reduced packaging weight and cost efficiency are important considerations.
Others
Revenue generated from the sale of other bulk chemical packaging drum types not classified under plastic, steel, or fiber/composite categories. This segment includes specialized drums manufactured from alternative materials or designed for niche agrochemical storage, handling, and transportation requirements.
Estimation Model
Layer Name
Key Question
Description
Agrochemical Consumption Layer
What drives demand for packaging drums?
Identify global consumption volumes of agrochemicals, including pesticides, herbicides, fungicides, insecticides, fertilizers, and specialty crop protection products across major agricultural regions. This layer establishes the total addressable agrochemical volume requiring storage, handling, and transportation, forming the foundation for packaging drum demand.
Bulk Packaging Penetration Layer
How much agrochemical volume is transported in drums?
Estimate the proportion of agrochemical products packaged and distributed through bulk chemical drums versus alternative packaging formats such as intermediate bulk containers (IBCs), tanks, pails, and flexible packaging. Assess drum utilization across different chemical types, transportation modes, and regional agricultural supply chains.
Capacity & Product Mix Layer
What types of drums are utilized?
Analyze demand distribution by drum capacity (100–250 Liters, 250–500 Liters, and Above 500 Liters) and product type (Plastic Drums, Steel Drums, Fiber/Composite Drums, and Others). Demand is influenced by chemical compatibility, hazardous material regulations, transportation requirements, storage conditions, and cost considerations across end users.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of bulk chemical packaging drums used for agrochemical storage and transportation. Revenue is generated from new drum sales, specialized chemical-resistant drum solutions, regulatory-compliant packaging products, and value-added services such as drum reconditioning, recycling, logistics support, and customized packaging solutions provided to agrochemical manufacturers and distributors.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation Analysis
Detailed market size, growth rate, demand trends, and consumption analysis for North America, Europe, Asia Pacific, Central & South America, and Middle East & Africa. The assessment includes regional agrochemical manufacturing activity, packaging regulations, agricultural output trends, and demand for bulk chemical packaging drums across key countries.
Enables clients to identify high-growth regions, evaluate regional demand dynamics, and prioritize market expansion and investment strategies.
Cross-Segmentation Analysis
Comprehensive analysis across Capacity (100–250 liters, 250–500 liters, above 500 liters), Product Type (Plastic Drums, Steel Drums, Fiber/Composite Drums, Others), and Region. Market size, growth potential, adoption trends, and revenue contribution are evaluated for each segment combination to identify the most attractive opportunities.
Provides actionable insights into high-growth segment intersections, supports portfolio optimization, and helps target the most profitable customer and application segments.
Opportunity Assessment
Identification of growth opportunities across specific capacity ranges and product types driven by increasing agrochemical production, demand for safe chemical transportation, sustainability initiatives, regulatory compliance requirements, and agricultural expansion in emerging economies.
Enables informed investment decisions by highlighting high-potential market segments, emerging demand pockets, innovation areas, and long-term growth opportunities.
Frequently Asked Questions About This Report
The plastic drums segment led the bulk chemical packaging drums for agrochemicals market with a 59.6% revenue share in 2025.
Above 500 liters segment is the fastest-growing in the bulk chemical packaging drums for agrochemicals market with a CAGR of 6.7% over the forecast period.
The 100-250 liters segment led the bulk chemical packaging drums for agrochemicals market with a 64.1% revenue share in 2025.
Key players in the bulk chemical packaging drums for agrochemicals market include Greif, Inc.; Mauser Packaging Solutions; SCHUTZ GmbH & Co. KGaA; Snyder Industries, Inc.; Time Technoplast; Balmer Lawrie & Co. Ltd.; Sonoco Products Company; Crown Holdings, Inc.; Fibrestar; JSK Plastic.
The global bulk chemical packaging drums for agrochemicals market size was valued at USD 1.6 billion in 2025 and is estimated at USD 1.7 billion for 2026.
The global bulk chemical packaging drums for agrochemicals market is expected to grow at a CAGR of 2.4% from 2026 to 2033, reaching USD 5.0 billion by 2033.
Key factors driving the bulk chemical packaging drums for agrochemicals market include rising agrochemical consumption, increasing demand for safe bulk transportation, stringent hazardous chemical handling regulations, growth in commercial farming, expanding agrochemical trade, and the adoption of durable, leak-resistant packaging solutions.
Asia Pacific dominated the bulk chemical packaging drums for agrochemicals market with a 39.9% revenue share in 2025.
Asia Pacific is the fastest-growing region in the bulk chemical packaging drums for agrochemicals market with a CAGR of 5.4% over the forecast period.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


