
- Home
- »
- Consumer F&B
- »
-
Canada Bagel Market Size, Share, Growth Report 2026-2033GVR Report cover

Canada Bagel Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Plain Bagel, Flavored Bagel, Protein Bagel, Whole Wheat Bagel, Egg Bagel, Gluten-free Bagel), By Distribution Channel (Foodservice, Retail), And Segment Forecasts
Market Size, 2025
$266.9MMarket Estimate, 2026
$279.5MMarket Forecast, 2033
$398.9MCAGR, 2026–2033
5.2%Canada Bagel Market Summary
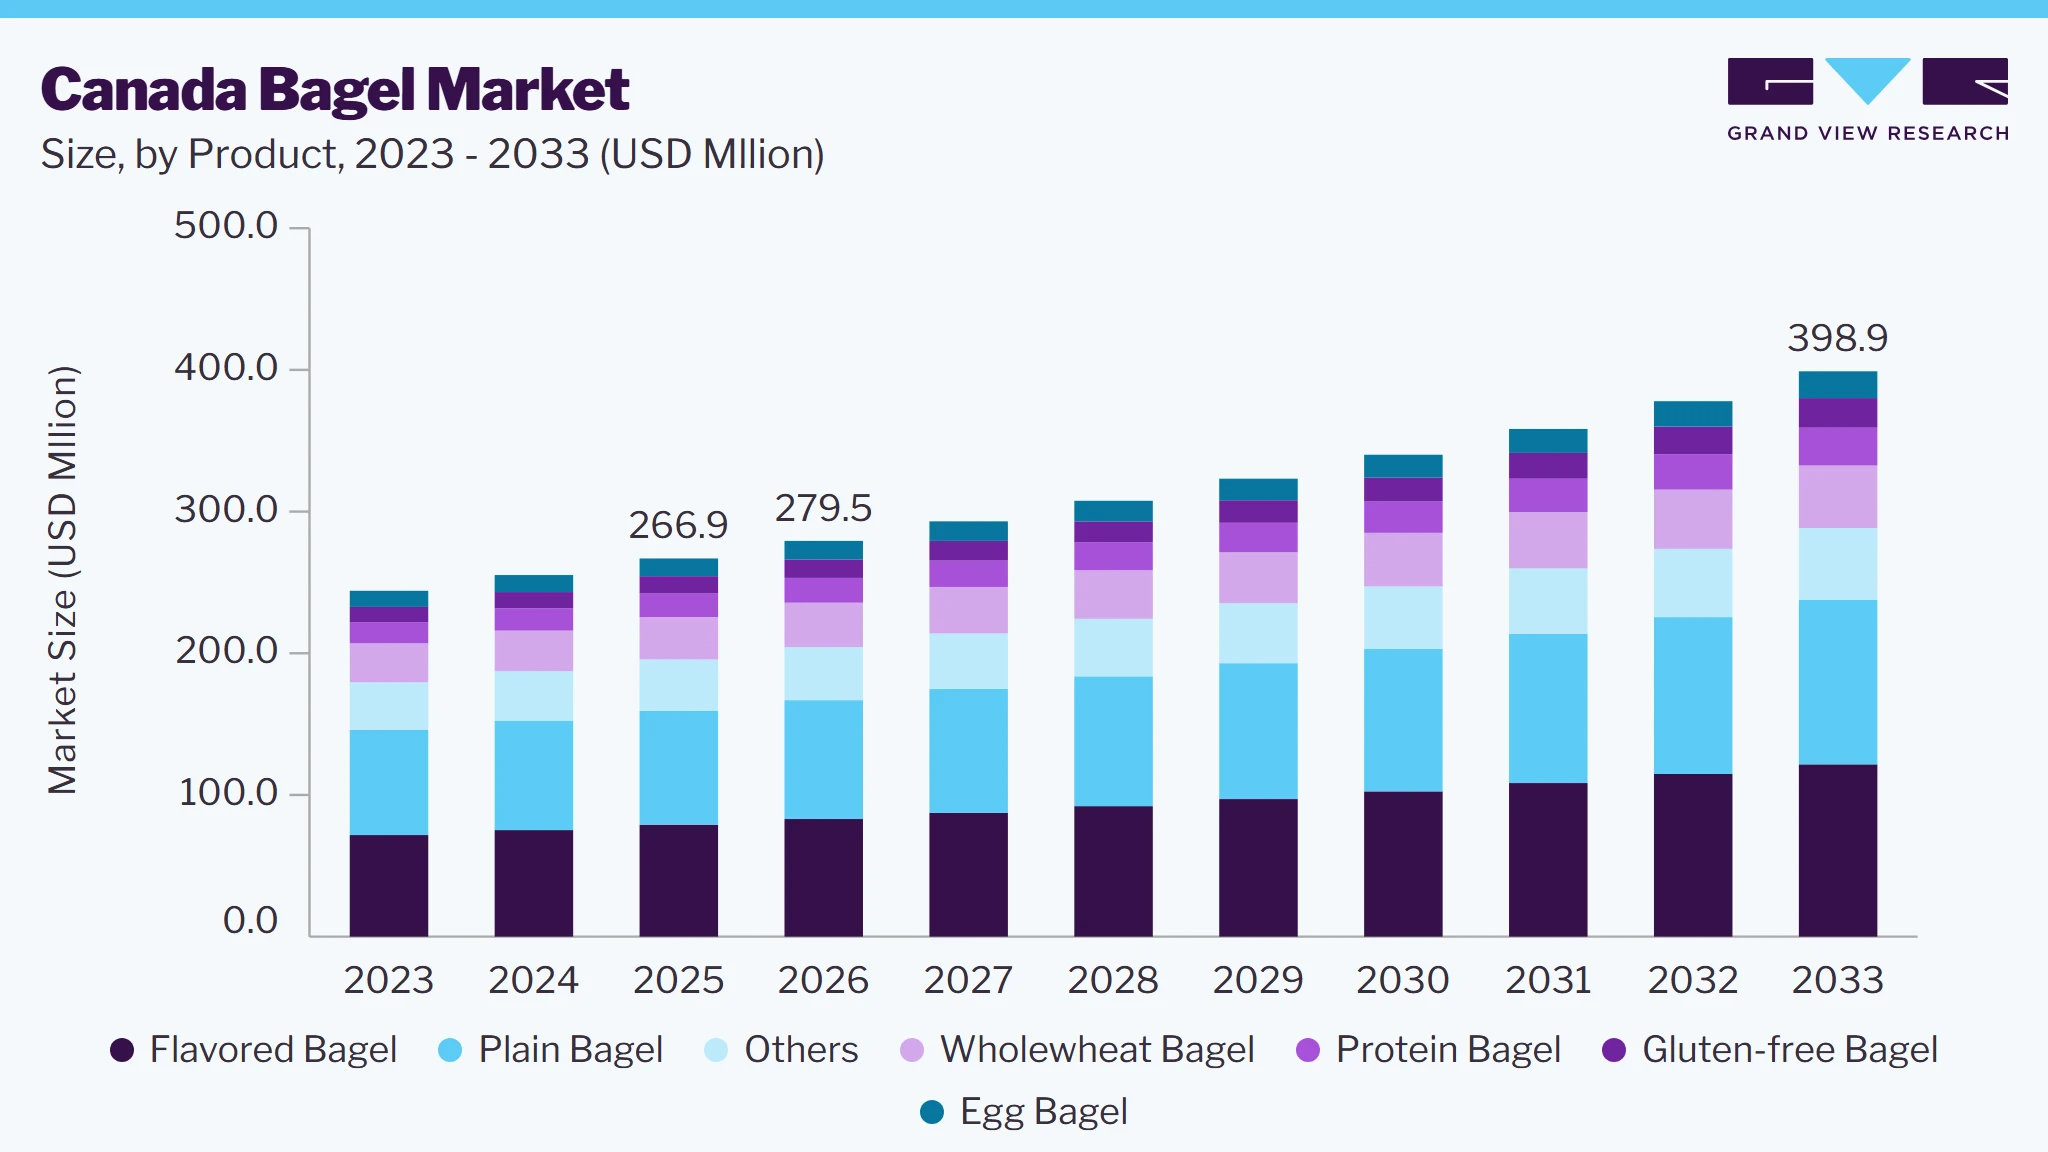
The Canada bagel market size was valued at USD 266.9 million in 2025 and is projected to grow from USD 279.5 million in 2026 to USD 398.9 million by 2033, at a CAGR of 5.2% from 2026 to 2033. The market is supported by the established role of bagels within Canada’s broader bread and bakery culture, particularly the country’s distinctive Montreal-style bagel tradition, alongside widespread availability of packaged bagels through grocery retail.
Key Market Trends & Insights
- By product: Plain bagels led the market with a 30.2% revenue share in 2025.
- By distribution channel: Retail Channel accounted for 57.7% of Canada bagel market revenue in 2025.
Market Size & Forecasts
- Market Size in 2025: USD 266.9 Million
- Estimated Market Size in 2026: USD 279.5 Million
- Projected Size by 2033: USD 398.9 Million
- CAGR (2026-2033): 5.2%
Prism AI by Grand View Research Free to tryAsk a question about the canada bagel marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Canadian demand is increasingly shaped by a combination of traditional products, flavor variety, dietary preferences, and convenient consumption occasions. While plain bagels remain the largest product segment in 2025, flavored varieties are projected to become the leading segment by 2033. At the same time, specialty formulations are gaining importance, particularly gluten-free products. For example, Canadian bagel operator Kettlemans introduced a gluten-free Everything bagel produced in a dedicated facility and made available both in retail packs and as a sandwich option, demonstrating how established bagel operators are adapting traditional offerings to changing dietary requirements.The Canada bagel market benefits from the product’s established position across both household consumption and freshly prepared bakery occasions. Bagels are consumed as traditional breakfast products but also function as convenient bases for sandwiches, snacks, and light meals, supporting demand across different times of the day. The market is further distinguished by the presence of traditional Montreal-style bagels alongside packaged varieties sold through mainstream retail. This combination of traditional preparation, convenient packaged formats, and flexible usage occasions gives bagels a distinctive position within Canada’s broader bakery landscape.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
At the same time, Canada retains a strong artisanal and independent bakery ecosystem. Artisanal bakers accounted for 34% of Canadian baked-goods retail sales value in 2023, according to Agriculture and Agri-Food Canada. This is particularly relevant to bagels because Canada has a well-established fresh-bagel culture alongside packaged retail products. The coexistence of large packaged bakery manufacturers and specialty bagel bakeries provides consumers with access to traditional, fresh-baked, packaged, and increasingly specialized bagel offerings.
Market Dynamics
The Canada bagel market is benefiting from consumers’ growing interest in bakery products that combine familiarity with differentiated nutritional attributes. Bagels provide manufacturers with a flexible platform for incorporating whole grains, seeds, higher fiber content, protein, and alternative ingredients while retaining the convenience of a traditional bakery product. This creates opportunities for brands to extend beyond conventional varieties and address consumers seeking products aligned with specific nutritional preferences.
Farm Credit Canada’s 2025 Food and Beverage Report highlights the opportunity for Canadian bakery manufacturers to use different grains, functional ingredients, and flavors to refresh traditional bread and bun products. The report specifically identifies consumer demand for nutritional properties such as gluten-free, high-protein, and high-fiber, indicating a favorable environment for differentiated bagel formulations. This shift is expected to encourage product innovation and broaden the range of bagels available across Canadian retail and foodservice channels.
Elevated food prices can restrain growth in the Canadian bagel market by increasing consumer sensitivity to the price of everyday bakery products. Consumers facing higher grocery bills may become more selective, shift toward lower-priced products, purchase on promotion, or trade down from premium and specialty bagels. Agriculture and Agri-Food Canada specifically reports that high prices are leading Canadian baked-goods consumers to seek cost-saving options and turn to discount retailers, while affordability remains a key concern in the category. In addition, the Bank of Canada reported that grocery prices had increased by about 22% since 2022, compared with 13% for other consumer prices, and food inflation reached 5% in December 2025. These pressures can make it more difficult for bagel manufacturers to increase prices or encourage consumers to trade up to premium offerings.
Growing consumer interest in protein and functional nutrition creates an opportunity for bagel manufacturers to develop products that provide benefits beyond traditional bakery offerings. High-protein, whole-grain, seed-based, and nutritionally differentiated bagels can help manufacturers address consumers seeking convenient foods with enhanced nutritional value. Agriculture and Agri-Food Canada reported in 2026 that bakery was the fastest-growing Canadian category for new products carrying high/added-protein claims, increasing 600% between Q2 2025 and Q2 2026. The same analysis identified gluten-free, low/no/reduced allergen, and no-additives/preservatives among prominent claims associated with high-protein products launched in Canada. This creates opportunities for bagel manufacturers to combine familiar formats with protein and other health-oriented attributes to reach a broader consumer base.
Analyst Perspective
The Canada bagel market is expected to maintain steady growth as bagels continue to address a broad range of consumption occasions and evolving dietary requirements. While traditional varieties provide a stable foundation for the category, future growth is likely to increasingly come from differentiated products and channels that improve convenience and address specific consumer needs. Faster growth in gluten-free bagels and online distribution indicates that the market is gradually broadening beyond conventional product and purchasing patterns. Over the forecast period, manufacturers and bakery operators that balance familiar bagel offerings with targeted product innovation and improved accessibility are expected to be better positioned to capture incremental demand.
Product Insights
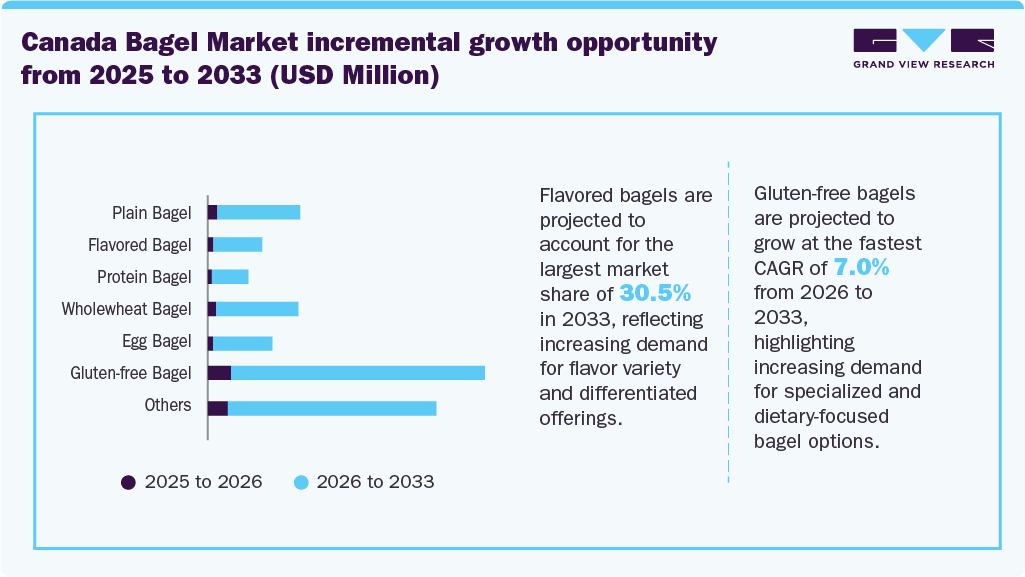
The plain bagel segment accounted for the largest share of approximately 30.2% of Canada bagel market revenue in 2025. Plain bagels maintain broad appeal due to their familiar taste profile and versatility across breakfast, snacking, and light-meal occasions. Their neutral flavor allows consumers to combine them with sweet or savory spreads, toppings, and sandwich fillings, supporting consumption across both households and foodservice establishments. Their availability through packaged retail as well as fresh bakery formats further strengthens accessibility. The broader Canadian bakery environment also provides a substantial consumer base for bread-based products. Agriculture and Agri-Food Canada’s forecast data places Canadian bread retail sales at approximately CAD 7.07 billion in 2025, within a baked-goods market of approximately CAD 11.85 billion.
 To learn more about this report, Download Free Sample Report
The gluten-free bagel segment is projected to grow at the fastest CAGR of 7.0% from 2026 to 2033. Growth is supported by demand for suitable bakery alternatives among consumers who need to avoid gluten, together with increasing availability of specialized bakery formulations. Health Canada states that celiac disease affects nearly 1% of the population and that maintaining a strict gluten-free diet is currently the only treatment for the condition. This provides an identifiable consumer base for gluten-free bakery products, while broader product availability can extend their reach beyond specialist outlets. These factors create opportunities for manufacturers to expand gluten-free bagel assortments across Canadian retail and foodservice channels.
Distribution Channel Insights
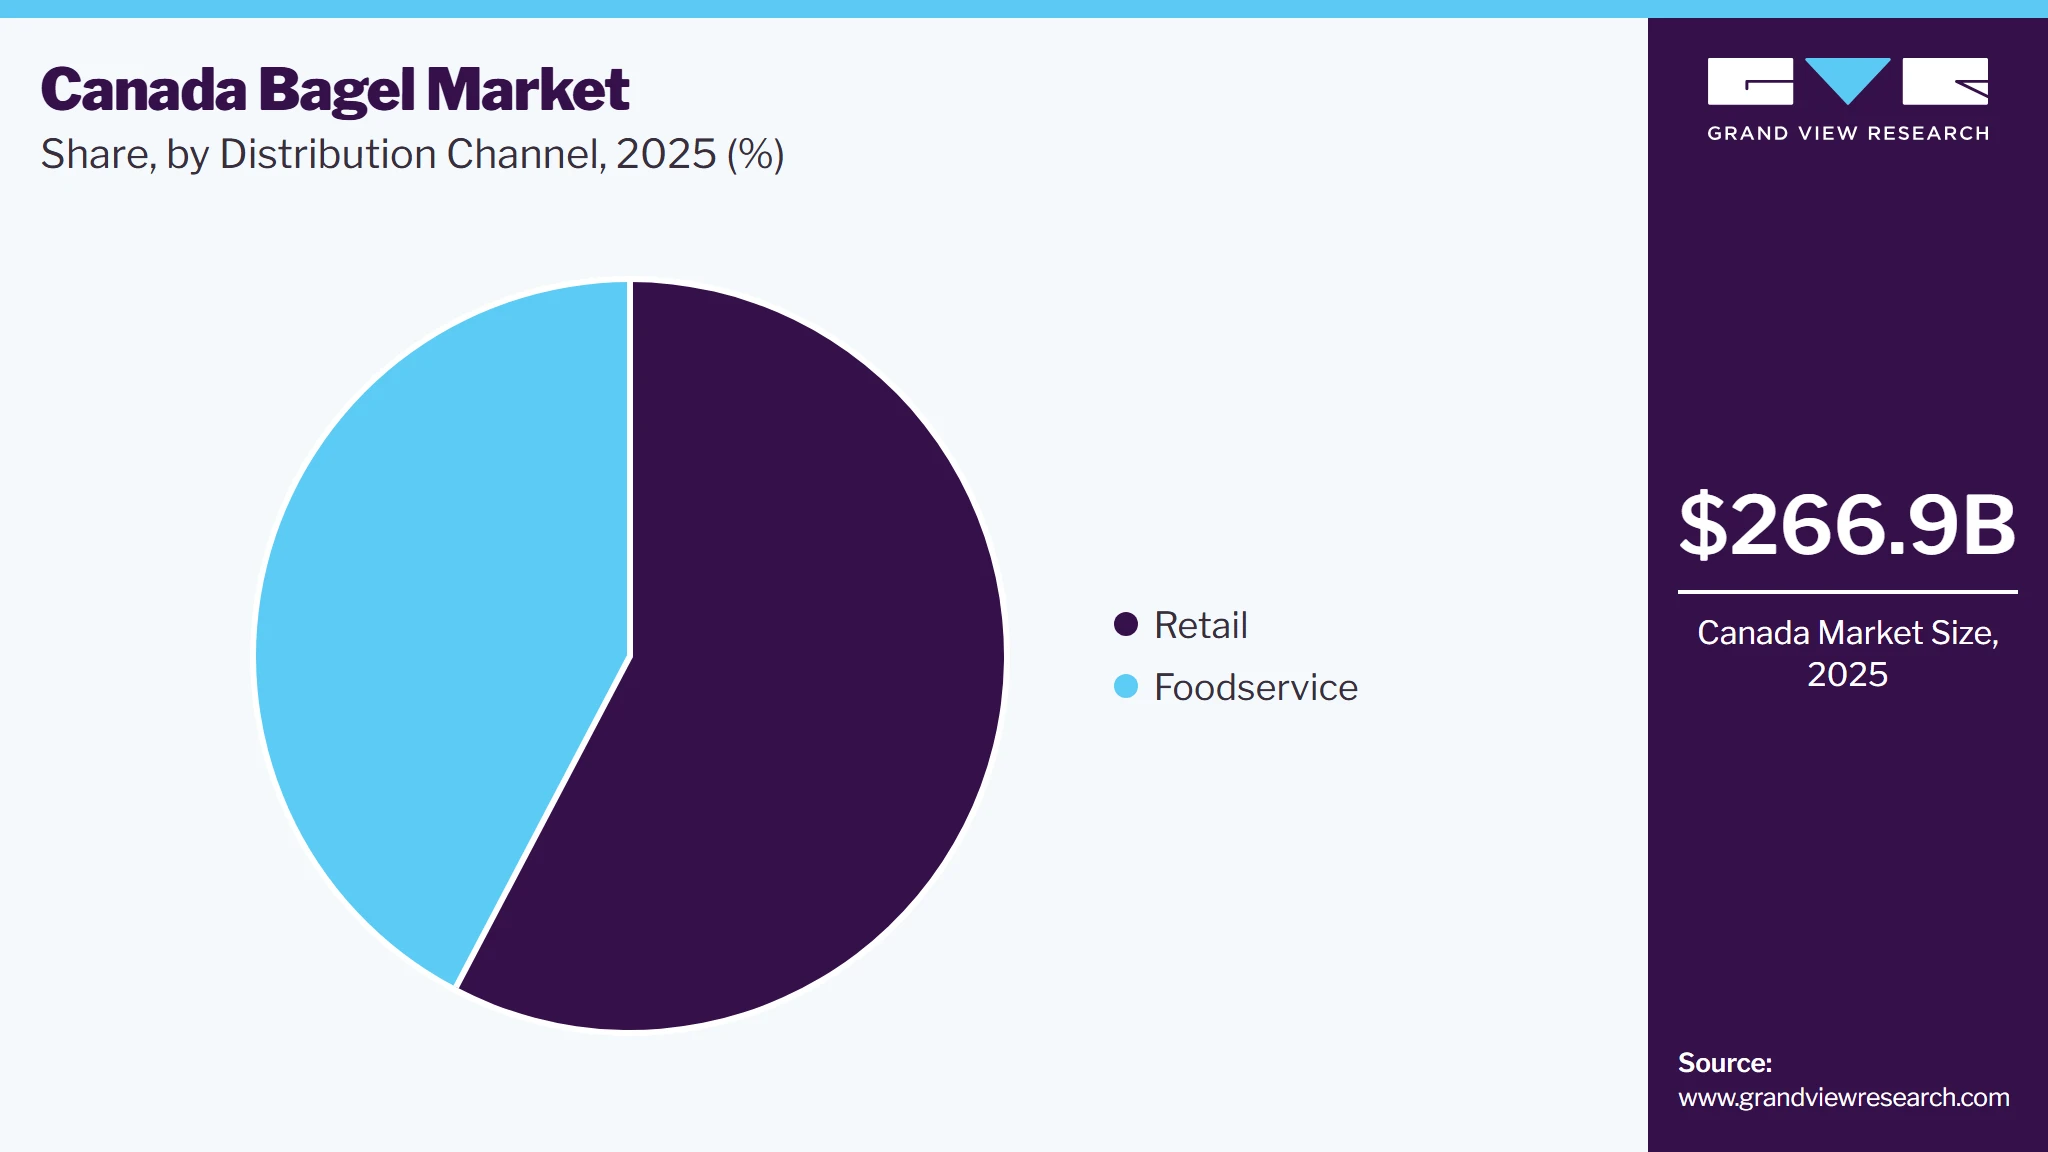
The retail channel accounted for the largest share of 57.7% of Canada's bagel market revenue in 2025. Retail benefits from the widespread availability of packaged and fresh bagels through supermarkets, hypermarkets, convenience stores, and other grocery formats. Supermarkets and other grocery retailers remain central to Canadian food purchasing; Statistics Canada reported that sales at supermarkets and other grocery retailers increased 2.0% in 2024. Fresh foods, including baked goods, also continue to account for a substantial portion of sales through food and beverage retailers.
 To learn more about this report, Download Free Sample Report
The online channel is projected to grow at the fastest CAGR of 6.9% from 2026 to 2033. Growth is supported by increasing consumer adoption of digital grocery shopping and the expansion of retailer delivery and pickup services across Canada. Online platforms allow consumers to compare bagel brands, varieties, pack sizes, prices, and nutritional attributes before purchasing, while home delivery improves convenience for routine grocery purchases. The broader expansion of Canadian e-commerce provides a supportive environment for this channel. Statistics Canada reported that Canadian retail e-commerce operating revenue reached CAD 73.7 billion in 2024, increasing 9.0% year over year, indicating continued adoption of digital purchasing channels.
Key Canada Bagel Company Insights
The Canada bagel market is characterized by a mix of large commercial bakery manufacturers and established specialty bagel operators. Large-scale companies compete through broad retail distribution, manufacturing capabilities, brand recognition, and extensive product portfolios, while specialty bakeries differentiate through fresh preparation, traditional baking methods, regional heritage, and foodservice presence. Grupo Bimbo has a particularly established Canadian bakery footprint through Bimbo Canada, with Dempster’s among its Canadian brands and bagels forming part of the company’s broader bakery portfolio.
Product differentiation is becoming an important competitive strategy, particularly around whole grains, protein, fiber, specialty ingredients, and distinctive bagel varieties. Silver Hills Bakery, for example, offers sprouted whole-grain bagels in Canada across Plain, Everything, Cinnamon Raisin, and Sesame Sunflower varieties, with several products positioned around whole-grain, protein, and fiber content. At the same time, traditional operators such as St-Viateur Bagel combine direct bakery sales with online ordering, catering, and wholesale distribution to merchants in Canada, illustrating the multiple routes through which specialist companies participate in the market.
Expansion of specialty bagel concepts is also contributing to competitive activity. Kettlemans Bagel announced its expansion into franchising, allowing the company to take its Montreal-style bagel concept into additional neighborhoods while retaining its traditional hand-rolled, honey-water-boiled, wood-fired preparation method.
 To learn more about this report, Download Free Sample Report
Key Canada Bagel Companies
-
Grupo Bimbo, S.A.B. de C.V.
-
The Great Canadian Bagel, Ltd.
-
St-Viateur Bagel
-
Kettlemans Bagel
-
O'Doughs
-
Silver Hills Bakery
-
Fairmount Bagel Bakery Inc.
-
The Bagel House
-
Bagel World
-
Panera Bread
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Grupo Bimbo, S.A.B. de C.V.; The Great Canadian Bagel, Ltd.; St-Viateur Bagel; Kettlemans Bagel; Silver Hills Bakery; Panera Bread)
- Expand bagel assortments and formats, strengthen retail and foodservice availability, grow store/franchise networks, and introduce differentiated and health-oriented offerings.
- Strong brand recognition, established Canadian presence, broader distribution or store networks, and greater resources for product development and expansion.
- Larger operating structures can reduce flexibility, while competition across packaged retail and fresh-bagel channels creates pressure on pricing and differentiation.
Emerging & Regional Players (O'Doughs; Fairmount Bagel Bakery Inc.; The Bagel House; Bagel World)
- Focus on specialty and fresh bagels, differentiated formulations, traditional preparation methods, regional expansion, and strengthening local customer relationships.
- Strong regional identity, specialization, product authenticity, customer loyalty, and flexibility in addressing local and niche consumer preferences.
- Smaller geographic footprint, comparatively limited distribution and production scale, and lower resources for expansion and marketing than larger participants.
Recent Developments
-
In November 2025, Panera Bread unveiled its “Panera RISE” transformation strategy, focused on strengthening the brand, improving the guest experience, enhancing value, and driving growth. At the time of the announcement, Panera reported operating bakery-cafés in Ontario, confirming that Canada remains within its operating footprint.
-
In August 2024, Bimbo Canada’s Dempster’s introduced a new brand platform focused on consumer well-being, with the company indicating that the initiative would expand further in 2025. Bimbo Canada remains Canada's largest bakery, with a national manufacturing and distribution infrastructure supporting brands including Dempster’s.
Canada Bagel Market Report Scope
Report Attribute
Details
Market size in 2025
USD 266.9 million
Estimated market size in 2026
USD 279.5 million
Projected market size by 2033
USD 398.9 million
Growth rate (Revenue)
CAGR of 5.2% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel
Key companies profiled
Grupo Bimbo; S.A.B. de C.V.; The Great Canadian Bagel, Ltd.; St-Viateur Bagel; Kettlemans Bagel; O'Doughs; Silver Hills Bakery; Fairmount Bagel Bakery Inc.; The Bagel House; Bagel World; Panera Bread
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Canada Bagel Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021-2033. For this study, Grand View Research has segmented the Canada bagel market report on the basis of product & distribution channel:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Plain Bagel
-
Flavored Bagel
-
Protein Bagel
-
Whole Wheat Bagel
-
Egg Bagel
-
Gluten-free Bagel
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Foodservice
-
Retail
-
Hypermarkets & Supermarkets
-
Convenience Stores
-
Online
-
Others
-
-
Research Methodology
The Canada bagel market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Canada bagel segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Distribution Channel
Revenue Capture Definition
Foodservice
Revenue from bagels sold as prepared food through bagel shops, bakery cafés, coffee shops, restaurants, QSRs, institutional foodservice, and similar outlets. Covers individual bagels, bagels with spreads or toppings, and bagel-based sandwiches or meals intended for immediate consumption.
Retail
Revenue from bagels sold as retail products for at-home or later consumption through supermarkets & hypermarkets, convenience stores, online channels, and other retail outlets. Covers packaged, fresh, refrigerated, and frozen bagels sold under branded or private-label offerings.
Hypermarkets & Supermarkets
Revenue from packaged, fresh, refrigerated, and frozen bagels purchased through supermarkets, hypermarkets, supercenters, and large-format grocery stores, including products sold through packaged bakery aisles and in-store bakery sections.
Convenience Stores
Revenue from bagels purchased through convenience stores, gas-station convenience outlets, and similar small-format retailers, including packaged, single-serve, multipack, and applicable grab-and-go bagels.
Online
Revenue from retail bagel purchases made through online grocery platforms, retailer websites and apps, marketplaces, and direct-to-consumer channels for home delivery or store pickup. Prepared bagel meals ordered from foodservice establishments are captured under foodservice.
Others
Revenue from retail bagel sales through channels not separately classified above, including independent grocery stores, specialty food stores, warehouse clubs, natural/health-food stores, and other applicable retail formats.
Estimation Model
Layer
Key Question
Description
Consumption Profile Layer
Who consumes Bagel?
Captures consumers across age groups, household types, lifestyles, and dietary preferences while assessing bagel consumption across breakfast, snacking, lunch, and other meal occasions.
Market Reach Layer
Where and how do consumers access Bagel?
Covers bagel availability across supermarkets, convenience stores, bakeries, bakery cafés, foodservice outlets, and online channels, highlighting differences between at-home purchases and freshly prepared consumption.
Purchase & Retention Layer
What drives trial, repeat purchase, and brand switching?
Examines factors such as taste, freshness, texture, flavor variety, price, convenience, nutritional attributes, promotions, and brand familiarity that influence bagel selection, repeat purchases, and switching behavior.
Value Generation Layer
How is value created across the Bagel market?
Assesses value creation through premium offerings, specialty flavors, nutritional differentiation, convenient formats, bagel-based meals, multipacks, private-label products, and differentiated brand positioning.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Canada Bagel Consumer & Consumption Occasion Assessment
Assessed consumer profiles, consumption frequency, breakfast versus all-day usage, purchase drivers, and at-home versus on-the-go consumption patterns.
Identifies high-potential consumer groups and opportunities to expand bagel consumption across different eating occasions.
Canada Bagel Pricing & Competitive Benchmarking
Benchmarked key bagel companies and brands across pricing, product assortment, pack sizes, positioning, distribution presence, and product innovation.
Supports pricing decisions, competitive positioning, and identification of portfolio gaps and differentiation opportunities.
Canada Bagel Flavor & Ingredient Assessment
Assessed demand for traditional and emerging flavors, grains, seeds, toppings, inclusions, and ingredients, along with attributes such as high-protein, whole-grain, gluten-free, and clean-label positioning.
Identifies flavor and ingredient opportunities for product innovation, differentiation, and development of offerings aligned with evolving consumer preferences.
Frequently Asked Questions About This Report
The Canada bagel market was valued at USD 266.9 million in 2025 and is estimated at USD 279.5 million for 2026
The Canada bagel market is expected to grow with a CAGR of 5.2% from 2026 to 2033, reaching USD 398.9 million by 2033
The plain bagel segment accounted for the largest share of approximately 30.2% of Canada bagel market revenue in 2025
The retail channel accounted for the largest share of 57.7% of Canada's bagel market revenue in 2025
Gluten-free bagels are projected to record the fastest product CAGR of 7.0% from 2026 to 2033
The key players in the Canadian bagel market are Grupo Bimbo, S.A.B. de C.V., The Great Canadian Bagel, Ltd., St-Viateur Bagel, Kettlemans Bagel, O'Doughs, Silver Hills Bakery, Fairmount Bagel Bakery Inc., The Bagel House, Bagel World, Panera Bread.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


