
- Home
- »
- Clinical Diagnostics
- »
-
Cancer Biopsy Market Size And Share Report, 2026-2033GVR Report cover

Cancer Biopsy Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Instruments, Kits And Consumables, Services), By Type (Tissue Biopsies, Liquid), By Application (Breast Cancer, Colorectal Cancer, Cervical Cancers), By Region, And Segment Forecasts
Market Size, 2025
$34.8BMarket Estimate, 2026
$37.6BMarket Forecast, 2033
$65.7BCAGR, 2026–2033
8.3%Cancer Biopsy Market Summary
The global cancer biopsy market size was valued at USD 34.8 billion in 2025 and is projected to grow from USD 37.6 billion in 2026 to USD 65.7 billion by 2033, at a CAGR of 8.3% from 2026 to 2033. The market in North America dominated with a revenue share of 41.2% in 2025. The market growth is attributed to the increasing prevalence of cancer, which is propelling the need for innovative diagnostics to provide early and effective diagnostic solutions to patients.
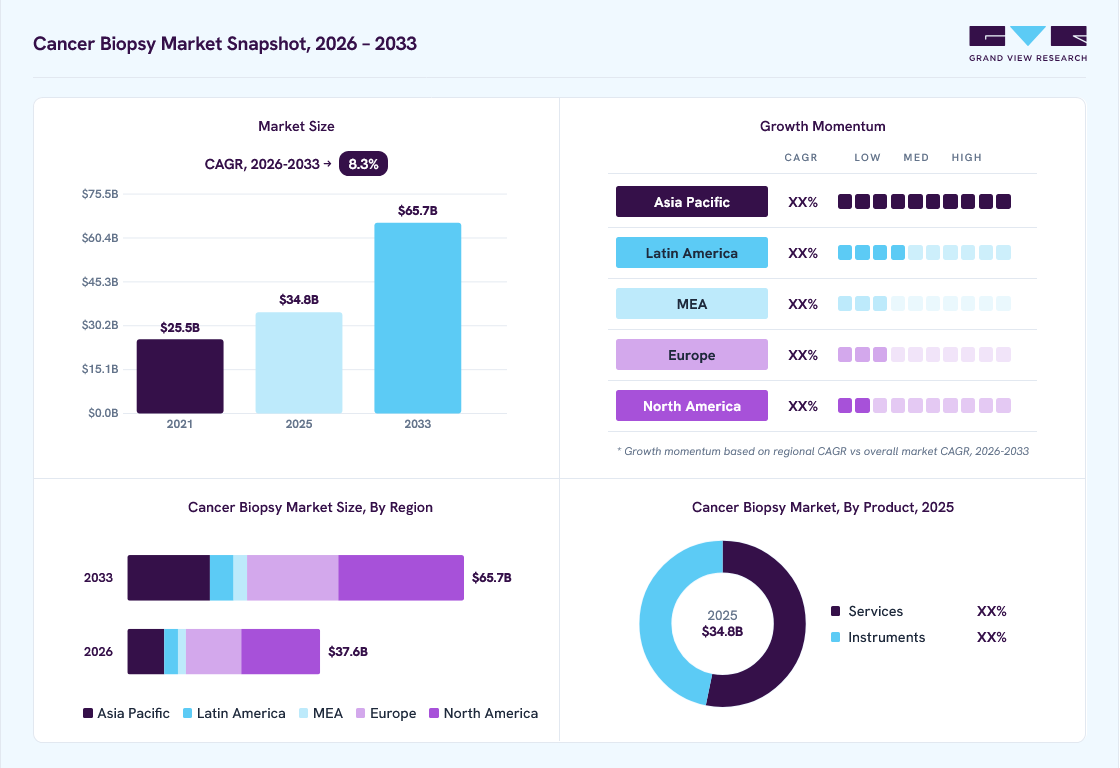 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Kits and consumables segment held the largest market share of 62.4% in 2025.
- By type: Tissue biopsies segment held the largest market share of 61.3% in 2025.
- By application: Breast cancer segment held the largest market share of 16.8% in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 34.8 Billion
- Estimated market size in 2026: USD 37.6 Billion
- Projected market size by 2033: USD 65.7 Billion
- CAGR (2026-2033): 8.3%
Prism AI by Grand View Research Free to tryAsk a question about the cancer biopsy marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Moreover, the rising awareness of inherited oncology disorders and the rise in genetic testing are further anticipated to drive the growth of the cancer biopsy industry. The National Cancer Institute (NCI) 2022 update highlights that in the U.S. alone, there were approximately 20 million new cases, resulting in deaths of almost 9.7 million cancer-related deaths worldwide. These substantial figures highlight the growing cancer burden and present a significant growth opportunity for the market.Due to the advantages of liquid biopsy technologies, massive parallel or NGS has emerged as a rapidly growing and evolving technology with increasing applications in various human Products. An increase in alterations of molecules in various types supports the usage of NGS in clinical settings, as it provides a cost- and time-effective way of detecting cancer. Tumor heterogeneity (evaluating different genes at the same time), along with the need for gene profiling, has increased the use of liquid biopsy, which is expected to propel market growth. Moreover, for various applications, such as prostate, breast, non-small-cell lung, colorectal, and ovarian cancer, liquid biopsy is used for diagnostic & screening, making it an important tool.
 To learn more about this report, Download Free Sample Report
The increasing incidence of disease is propelling the demand for the diagnosis of cancers at early stages. For instance, as per Global Cancer Statistics 2024, reported by the American Cancer Society, approximately 20 million cancer cases were newly diagnosed in 2022, and 9.7 million people died from it globally. Moreover, the number of cancer cases is predicted to reach 35 million by 2050. When cancer is discovered early and is contained to the organ of origin before it has a chance to spread, survival rates drastically increase, and it is more likely to be effectively cured. Early detection is crucial for lowering cancer-related mortality, especially through efficient screening programs. Early detection increases patient survival rates by 5 to 10 times more than late detection. The 5-year cancer-specific survival rate is only 21% when cancer is discovered after it has spread, as opposed to 89% when it is found early & still localized.
Furthermore, the increasing number of initiatives by various organizations to raise awareness is a major reason for the growing demand for diagnostic products worldwide. Collaborations and partnerships undertaken by CDC, WHO, the National Cervical Cancer Coalition, the U.S. Preventive Services Task Force, & others are expected to drive market growth by increasing cervical cancer screening rates. In addition, major market players are undertaking initiatives to increase awareness about cervical, vulvar, and vaginal cancer, which is likely to encourage people to opt for screening at regular intervals.
For instance, in 2024, India, the U.S., Australia, and Japan launched the Quad Cancer Moonshot Initiative, which was specifically focused on eliminating cervical cancer across the Indo-Pacific region. Similarly, in October 2024, the University of New South Wales (UNSW) Sydney received a donation of USD 25.9 million from the Swire Group. This funding allowed the Kirby Institute at UNSW Sydney to screen 130,000 women in seven Pacific countries, including Fiji, Kiribati, the Republic of Marshall Islands, Samoa, Solomon Islands, Tonga, and Vanuatu, for cervical cancer.
Moreover, awareness among people about early diagnosis and available treatment options and advancements in treatments has substantially improved patient outcomes. According to a Cancer Progress Report published by the American Association for Cancer Research, it was expected that in the U.S., around 2,001,140 new cases of cancer would be diagnosed in 2024, and approximately 611,720 people might die from the Disease.
However, the high cost of diagnostic tests is anticipated to hamper the overall market growth. Diagnostic cancer tests are expensive, increasing the financial burden on families of patients. The government insurance framework is less well-defined in developing countries than in developed countries. Thus, the middle-class patient population who are uninsured cannot afford these tests. In addition, many private insurance players do not cover costs associated with diagnosis in developing countries. As a result, the high cost of diagnosis is limiting the adoption of screening tools, especially in developing countries. However, the scenario is expected to change in the coming years due to booming medical tourism in countries such as India and Malaysia, wherein healthcare treatments & diagnostic solutions are becoming affordable.
Market Dynamics
The cancer biopsy market is experiencing growth driven by the rising global burden of cancer, increasing adoption of precision medicine, and expanding use of molecular diagnostics in oncology care. Biopsy procedures continue to represent a fundamental component of cancer diagnosis and management by enabling disease confirmation, tumor characterization, and biomarker identification for targeted treatment selection. Growing clinical acceptance of liquid biopsy technologies is further supporting market expansion, as these approaches provide a minimally invasive method for tumor profiling and longitudinal disease monitoring. In addition, the integration of genomic profiling and advanced molecular testing into routine diagnostic workflows is enhancing the clinical value of biopsy based testing and supporting more personalized treatment strategies. Investments in advanced diagnostic pathways by healthcare systems are also improving access to precision oncology solutions. For instance, in May 2025, NHS England implemented a nationwide rollout of liquid biopsy testing for eligible lung and advanced breast cancer patients to facilitate faster identification of actionable mutations and support timely treatment selection. Such developments are accelerating the adoption of advanced biopsy technologies and contributing to the expansion of the cancer biopsy market.
The increasing adoption of precision oncology is a key growth driver for the cancer biopsy market as healthcare providers increasingly emphasize personalized treatment strategies. Biopsy procedures serve a critical role in identifying molecular alterations, biomarker expression profiles, and genetic mutations that support treatment selection and patient stratification. The expanding use of targeted therapies and immunotherapies has increased the demand for accurate molecular characterization, thereby strengthening the importance of both tissue and liquid biopsy technologies. Furthermore, the integration of next generation sequencing and companion diagnostics into routine oncology practice is enhancing the clinical utility of biopsy based testing and supporting broader implementation of precision medicine approaches. Market participants are actively expanding their oncology diagnostic capabilities to address the growing demand for comprehensive tumor profiling solutions. This trend is reinforced by strategic industry collaborations aimed at advancing biomarker driven cancer care. For instance, in April 2025, Guardant Health and Pfizer announced a strategic collaboration to expand the application of liquid biopsy and comprehensive genomic profiling across oncology research and clinical development programs. Such initiatives are supporting the adoption of advanced biopsy technologies and contributing to the expansion of the cancer biopsy market.
The cancer biopsy market is restrained by the substantial costs associated with advanced diagnostic technologies and the limited reimbursement support available across several healthcare systems. The expanding use of liquid biopsy, comprehensive genomic profiling, and next generation sequencing has strengthened the role of precision oncology; however, widespread adoption remains dependent on significant investments in laboratory infrastructure, specialized equipment, and technical expertise. These requirements can create financial barriers for healthcare providers, particularly in markets with constrained healthcare budgets. Furthermore, reimbursement frameworks for advanced molecular diagnostics are evolving at a slower pace than technological advancements, which can affect test adoption and utilization across clinical settings. Market participants are also required to allocate considerable resources toward clinical validation, regulatory approval processes, and health economic assessments to establish the value proposition of innovative biopsy solutions. As a result, cost pressures and reimbursement challenges continue to influence market accessibility, limit the uptake of advanced testing modalities, and moderate the pace of expansion within the cancer biopsy market.
The expanding application of liquid biopsy in cancer monitoring and recurrence detection represents a significant opportunity for the cancer biopsy market. Healthcare providers are increasingly incorporating blood based diagnostic approaches into oncology care pathways to support treatment response assessment, minimal residual disease evaluation, and early identification of disease recurrence. Compared with conventional tissue biopsy procedures, liquid biopsy offers advantages through its minimally invasive nature and ability to enable serial testing throughout the patient management continuum. The growing focus on precision oncology and longitudinal disease surveillance is increasing demand for technologies capable of delivering actionable molecular insights across multiple stages of cancer care. Furthermore, advancements in circulating tumor DNA analysis, biomarker detection, and genomic profiling are expanding the clinical utility of liquid biopsy across a broad range of cancer indications. A notable industry development reflects the expanding role of blood-based cancer assessment technologies in oncology diagnostics. For instance, in September 2025, Exact Sciences launched Cancerguard MCED, a blood based multi-cancer early detection test designed to identify signals associated with multiple cancer types from a single blood sample. Such developments are broadening the clinical applications of liquid biopsy technologies and creating new growth opportunities within the cancer biopsy market.
Market Concentration & Characteristics
The degree of innovation is high in the cancer biopsy market, particularly in innovations such as liquid biopsy, Next-Generation Sequencing (NGS), and molecular imaging technologies. Liquid biopsy technology has emerged as a major development in the market, allowing the detection of cancer-related biomarkers from blood samples. This minimally invasive approach facilitates early detection, monitoring of treatment responses, and detection of recurrence. Companies like Guardant Health and Foundation Medicine are some of the leading players in this innovation, utilizing tests for circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), and exosomes.
The merger and acquisition activities are moderate in the cancer biopsy industry, driven by strategic expansion, technological advancement, consolidation, and financial investment. Companies are actively adopting M&A to diversify their product portfolios, integrate innovative technologies, enhance market leadership, and accelerate research and development. This trend reflects the ongoing evolution of diagnostics and the growing importance of advanced biopsy solutions in improving detection and treatment.
 To learn more about this report, Download Free Sample Report
Regulations largely impact the use of biopsies. However, they play a crucial role in ensuring patient safety and maintaining high-quality standards. However, they also present challenges, including increased costs, market access barriers, and variability across global markets.
In diagnosis, several alternatives to traditional biopsy procedures offer valuable options for reducing invasiveness and enhancing accuracy. Liquid biopsy is a leading alternative, analyzing biomarkers like circulating tumor DNA (ctDNA) or circulating tumor cells (CTCs) from blood samples, which facilitates early cancer detection and monitoring without the need for invasive tissue sampling. Advanced imaging techniques, such as PET and MRI, provide detailed insights into tumor characteristics and can sometimes reduce the immediate need for biopsy by guiding diagnosis through non-invasive methods.
The concentration of end users in the market reflects the diversity of healthcare settings and specialties that utilize biopsy solutions for diagnosis. End users in this market typically include hospitals, diagnostic laboratories, research institutions, and specialized centers. The concentration of these end users is influenced by various factors, including the type of biopsy technology, the healthcare infrastructure in a region, and the specific needs of patients.
Analyst Perspective
The cancer biopsy market is expected to maintain a growth trajectory, driven by the increasing global cancer burden, expanding utilization of precision oncology, and growing demand for biomarker guided treatment strategies. The market is undergoing a gradual shift toward advanced molecular diagnostic approaches, with liquid biopsy gaining clinical acceptance for cancer detection, treatment monitoring, and minimal residual disease assessment. However, tissue biopsy continues to represent a fundamental component of oncology diagnostics due to its established role in disease confirmation and tumor characterization. Advancements in genomic profiling, next generation sequencing, and companion diagnostics are enhancing the clinical value of biopsy-based testing. Furthermore, ongoing investments, strategic collaborations, and product innovation initiatives are expected to support technology adoption and strengthen the long-term growth outlook of the cancer biopsy market.
Product Insights
Based on product, the kits and consumables segment led the market with the largest revenue share of 62.4% in 2025, driven by the rising adoption and usage of kits for effective screening and diagnosis solutions. Technological advancements in biopsy technologies are also contributing to market growth. Innovations such as advanced biopsy needles, specialized collection containers, and improved tissue preservation solutions are enhancing the efficiency and accuracy of biopsy procedures. Additionally, the trend toward personalized medicine, which often requires detailed molecular and genetic analysis, is increasing the need for advanced biopsy kits and consumables.
The instruments segment is expected to register the fastest CAGR of 9.5% during the forecast period. The segment's growth is expected to be driven by advancements in technology and the increasing demand for precise diagnostic tools. This growth is largely driven by the rising incidence, which accelerates the need for advanced biopsy instruments used in detecting and analyzing tumors. Innovations in biopsy technologies, such as automated tissue processors, advanced imaging systems, and precision-guided biopsy needles, are enhancing the accuracy and efficiency of cancer diagnostics. Moreover, technological advancements, including the integration of digital pathology and robotics, are further accelerating market growth.
Type Insights
Based on type, the tissue biopsies segment led the market with the largest revenue share of 61.3% in 2025, driven by increasing cancer incidence and advancements in biopsy technology. The shift towards personalized medicine, which requires detailed molecular and genetic profiling of tumors, is increasing the need for sophisticated tissue biopsy methods. The development of minimally invasive biopsy techniques also contributes to market growth by offering patients less discomfort and faster recovery times. The expansion of healthcare infrastructure and increased awareness about the importance of early detection are further boosting the demand for tissue biopsies.
The liquid biopsies segment is expected to register the fastest CAGR of 9.2% during the forecast period. Liquid biopsy is an innovative testing technology for diagnosing tumor-related genetic alterations. It has also been used to stratify tumors and provide appropriate precision oncology treatment. For instance, in January 2023, Guardant Health received FDA approval for Guardant360 CDx, its liquid biopsy assay as a companion diagnostic for the diagnosis of ESR1 mutant breast cancer. These recent advancements, expansions, and innovations in the industry promoting the use of liquid biopsy are driving the market. Due to the advantages of liquid biopsy technologies, NGS or massive parallel sequencing is the fastest-growing and evolving technology with increasing applications in various human Products. An increase in alterations of molecules in different types supports the usage of NGS in clinical settings, as it provides a cost- and time-effective way of detecting. For instance, in June 2025, Altum Sequencing developed a liquid biopsy technology, which can detect breast cancer relapse up to 6 months before symptoms become apparent through traditional diagnostic methods.
Application Insights
Based on applications, the breast cancer segment led the market with the largest revenue share of 16.8% in 2025. Increasing R&D in advanced screening tools is anticipated to boost the segment significantly. A research study published in The Institute of Cancer Research in June 2024 stated that a new type of blood test can predict breast cancer recurrence in high-risk patients, years/months before they relapse.
 To learn more about this report, Download Free Sample Report
The kidney cancer segment is expected to grow at significant CAGR of 10.4% during the forecast period. An increase in research activities conducted by various players operating in the cancer biopsy industry is anticipated to boost segment growth soon. In March 2024, Elypta announced results from the international AURORAX-0087A (AUR87A) study. The study was conducted across 29 hospitals in the UK, the U.S., the EU, and Canada. It showed the possible transformative impact of a urine-based test in the monitoring of kidney cancer patients’ recurrent disease.
Regional Insights
North America dominated the Cancer Biopsy Market with the largest revenue share of 41.2% in 2025. The region's dominance is attributed to the presence of advanced healthcare infrastructure and substantial healthcare expenditure in North America, driving the widespread adoption of diagnostic technologies. In addition, several product launches and funding are further anticipated to drive market growth in the region. For instance, in February 2024, Freenome, a biotechnology company focused on developing blood tests for early detection, secured USD 254 million in funding from new and existing investors. This funding is expected to help Freenome advance its single-cancer and tailored Multicancer Early Detection (MCED).
 To learn more about this report, Download Free Sample Report
U.S. Cancer Biopsy Market Trends
The Cancer Biopsy Market in the U.S. held the largest share in the North America region in 2025, due to the high cancer prevalence in the country and consequent rapid adoption of biopsies. Furthermore, rapid technological advancements, recent FDA approvals, and intense competition between companies are expected to boost market growth over the forecast period. In July 2025, NeoGenomics, Inc. announced the launch of a blood-based comprehensive genomic profiling (CGP) test, Neo PanTracer LBx. It enhances NeoGenomics' clinical portfolio and offers new revenue streams in trial matching, therapy selection, and disease monitoring.
Europe Cancer Biopsy Market Trends
The cancer biopsy industry in Europe accounted for a significant revenue share in 2025. This can be attributed to increased approvals by regulatory bodies, intense competition between companies to increase market share, a rise in government initiatives, and improved reimbursement scenarios.
The UK cancer biopsy market is growing primarily due to commercial partnerships between the government and key players for the country's routine use of cancer biopsies. For instance, in August 2025, Nonacus, an early cancer testing company, announced two West Midlands-based trials to analyze a new way of monitoring for bladder cancer recurrence, using a novel test developed in collaboration with University of Birmingham researchers.
The cancer biopsy market in France is expected to grow over the forecast period. This growth can be attributed to the strong presence of well-established and emerging product manufacturers, who are expected to adopt continuous organic and inorganic growth strategies to support the market.
The Germany cancer biopsy market is expected to witness substantial growth over the forecast period. The increasing number of companies striving to enter the market and the government-sponsored aid for developing these tests are some of the key factors that can be attributed to the growth of the market.
Asia Pacific Cancer Biopsy Market Trends
The Asia Pacific cancer biopsy industry is expected to witness the fastest CAGR over the projected period, driven by healthcare reforms. Other factors contributing to market growth are an increasing population, improving healthcare infrastructure, and the entry of new players. The Asia Pacific region has a large population and a high prevalence of cancer. According to Global Cancer Statistics, the estimated number of new cases in Asia in 2022 was 10.5 million. Government initiatives, such as free screening for breast cancer, cervical cancer, & lung cancer, and improved collaborations between the government, research institutes, & companies for the distribution & supply of these tests for screening cancers, have increased in the past few years.
The China cancer biopsy market is expected to grow over the forecast period, due to lifestyle changes, dietary habits, and an aging population. Moreover, the demand for liquid biopsy in China is propelled by a large patient pool, government spending on oncology diagnostics, and robust deployment of high-throughput next-generation sequencing platforms.
The cancer biopsy market in Japan is expected to witness growth over the forecast period. This growth can be attributed to the substantial government investments and approvals specifically aimed at reducing incidence.
Latin America Cancer Biopsy Market Trends
The cancer biopsy industry in Latin America is expected to grow during the projected period. This growth of the regional market can be attributed to the increased prevalence of various types of cancer in Latin America. Several surveys by different governments and nonprofit organizations revealed that overall cancer mortality in Latin America is almost twice that of high-income countries.
The Brazil cancer biopsy market is expected to grow over the forecast period. The market has observed high growth in the adoption of cancer biopsy techniques owing to increasing collaborations of key market players and various initiatives being undertaken by various organizations for cancer care.
Middle East & Africa Cancer Biopsy Market Trends
The cancer biopsy industry in the Middle East & Africa is witnessing significant growth opportunities, as most of the market is untapped due to the absence of structured screening programs in underdeveloped African economies has impeded early detection efforts.
The Saudi Arabia cancer biopsy market is expected to grow over the forecast period. This growth can be attributed to the increasing involvement of the government and the rising awareness about the benefits of noninvasive diagnostic procedures.
Key Cancer Biopsy Company Insights
Some of the leading players operating in the market include QIAGEN; Illumina Inc.; and Thermo Fisher Scientific, Inc. These players are involved in developing liquid biopsy technologies. These methods analyze circulating tumor DNA (ctDNA) or other biomarkers in blood samples, providing a less invasive alternative to traditional biopsies. This approach aims to facilitate early detection and ongoing monitoring with minimal discomfort for patients. Moreover, by using these advanced technologies, companies are able to obtain more detailed insights into the genetic mutations and characteristics of tumors.
CureMetrix, Tempus, and Inivata are some of the emerging participants in the cancer biopsy industry. These players are collaborating with other major & local players to gain a competitive edge. These players focus on regional expansion by exploring possibilities to develop innovative diagnostic solutions. This expansion aims to make advanced biopsy technologies more accessible to a broader patient population.
Key Cancer Biopsy Companies
The following key companies have been profiled for this study on the cancer biopsy market.
-
QIAGEN
-
Illumina, Inc.
-
ANGLE plc
-
BD (Becton, Dickinson and Company)
-
Myriad Genetics, Inc.
-
Hologic, Inc.
-
Biocept, Inc.
-
Thermo Fisher Scientific, Inc.
-
Danaher
-
F. Hoffmann-La Roche Ltd.
-
Lucence Health Inc.
-
GRAIL, Inc.
-
Guardant Health Inc.
-
Exact Sciences Corporation
-
Freenome Holdings, Inc.
-
Biodesix (Integrated Diagnostics)
-
Oncimmune
-
Epigenomics AG
-
HelioHealth (Laboratory for Advanced Medicine)
-
Genesystems, Inc. (Genesys Biolabs)
-
Chronix Biomedical, Inc.
-
Personal Genome Diagnostics Inc.
-
Natera, Inc.
-
Personalis Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well-Established Players (QIAGEN, Illumina, Inc., Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche Ltd., Danaher, BD, Hologic, Inc., Guardant Health Inc., Exact Sciences Corporation, GRAIL, Inc.)
- Focus on expanding cancer biopsy portfolios through liquid biopsy platforms, next generation sequencing technologies, companion diagnostics, genomic profiling solutions, and biomarker-based testing.
- Emphasize strategic partnerships, acquisitions, clinical validation programs, and integration of biopsy testing with precision oncology workflows.
- Strengthen market presence through global commercialization, regulatory approvals, and collaborations with healthcare providers and cancer centers.
- Broad product portfolios, strong technological capabilities in molecular diagnostics and genomic analysis, extensive global distribution networks, established relationships with healthcare institutions, and significant investment capacity for research and development.
- Strong clinical evidence and regulatory expertise support widespread adoption of their biopsy solutions.
- High research and development expenditures, lengthy regulatory approval processes, and dependence on reimbursement coverage for advanced diagnostic tests.
- Large organizational structures may also reduce flexibility in responding to rapidly evolving niche market opportunities.
Emerging Players (ANGLE plc, Lucence Health Inc., Freenome Holdings, Inc., Biodesix, Oncimmune, Epigenomics AG, HelioHealth, Chronix Biomedical, Natera, Inc., Personalis Inc., Personal Genome Diagnostics Inc., Biocept, Inc., Myriad Genetics, Inc.)
- Concentrate on developing specialized liquid biopsy technologies, circulating tumor DNA assays, minimal residual disease testing, multi-cancer early detection platforms, and artificial intelligence enabled oncology diagnostics.
- Focus on clinical collaborations, regional expansion, strategic partnerships, and innovation driven product development to enhance market penetration.
- Specialized expertise in emerging biopsy applications, strong focus on innovation, agility in technology development, and ability to address unmet needs in early cancer detection, disease monitoring, and personalized oncology.
- Greater flexibility in targeting specific cancer indications and novel diagnostic applications.
- Limited commercial scale, narrower product portfolios, smaller geographic reach, and lower financial resources compared with established competitors.
- Dependence on external funding, partnership networks, and successful clinical validation outcomes may affect long term market expansion and commercialization efforts.
Recent Developments
-
In August 2024, Illumina, Inc. received approval for in vitro diagnostic (IVD) TruSight Oncology (TSO), cancer biomarker tests with its two companion diagnostic indications to rapidly match patients to targeted therapies.
-
In June 2024, Guardant Health, Inc. announced the launch of an updated version of the Guardant360 TissueNext test with an expanded identification of genes in tissue samples to 498. This helps enable oncologists to identify treatment strategies and targeted therapies for patients with advanced cancer.
-
In May 2024, VESICA HEALTH, INC. announced the launch of the AssureMDX test as an LDT for the diagnosis of bladder cancer.
Cancer Biopsy Market Report Scope
Report Attribute
Details
Market size in 2025
USD 34.8 billion
Estimated market size in 2026
USD 37.6 billion
Projected market size by 2033
USD 65.7 billion
Growth rate
CAGR of 8.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, Type, Application, Regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
QIAGEN, Illumina, Inc., ANGLE plc, BD (Becton, Dickinson and Company), Myriad Genetics, Inc., Hologic, Inc., Biocept, Inc., Thermo Fisher Scientific, Inc., Danaher, F. Hoffmann-La Roche Ltd., Lucence Health Inc., GRAIL, Inc., Guardant Health Inc., Exact Sciences Corporation, Freenome Holdings, Inc., Biodesix, Oncimmune, Epigenomics AG, HelioHealth (Laboratory for Advanced Medicine), Genesystems, Inc. (Genesys Biolabs), Chronix Biomedical, Inc., Personal Genome Diagnostics Inc., Natera, Inc., and Personalis Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cancer Biopsy Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global cancer biopsy market report based on product, type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Instruments
-
Kits & Consumables
-
Services
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Tissue Biopsies
-
Needle Biopsies
-
Surgical Biopsies
-
-
Liquid Biopsies
-
Fine Needle Aspiration (FNA)
-
Core Needle Biopsy (CNB)
-
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Breast Cancer
-
Colorectal Cancer
-
Cervical Cancers
-
Lung Cancers
-
Prostate Cancers
-
Skin Cancers
-
Blood Cancers
-
Kidney Cancers
-
Liver Cancers
-
Pancreatic Cancers
-
Ovarian Cancers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The cancer biopsy market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each cancer biopsy segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Instrument
Revenue is primarily captured through sales of biopsy guidance systems, automated tissue processing platforms, sample preparation instruments, imaging systems, and molecular diagnostic equipment utilized for cancer biopsy collection, processing, and analysis across clinical and laboratory settings.
Kits and Consumables
Revenue flows from recurring purchases of biopsy needles, collection tubes, reagents, assay kits, cartridges, sample preservation products, and laboratory consumables required for routine cancer biopsy collection, preparation, testing, and diagnostic workflows.
Services
Revenue accrues from pathology interpretation, genomic profiling, molecular testing, sample analysis, laboratory processing, outsourced diagnostic services, and reporting activities performed on cancer biopsy specimens for clinical decision making and research applications.
Segment - Type
Revenue capture definition
Tissue Biopsies
Revenue is primarily captured through procedures involving the removal and pathological examination of solid tissue samples obtained from suspected tumor sites for cancer diagnosis, staging, biomarker assessment, and treatment planning across healthcare settings.
Liquid Biopsies
Revenue flows from blood based and other body fluid-based testing procedures used to detect circulating tumor DNA, circulating tumor cells, and cancer related biomarkers for diagnosis, treatment selection, and disease monitoring.
Others
Revenue accrues from specialized cancer biopsy procedures, including bone marrow, endoscopic, skin, and image guided biopsy techniques, utilized for cancer detection, characterization, and clinical evaluation in specific disease indications.
Segment - Application
Revenue capture definition
Breast Cancer
Revenue is primarily captured through biopsy procedures, pathological assessment, and molecular testing performed on breast tissue or blood samples for cancer detection, subtype classification, biomarker evaluation, and treatment planning.
Colorectal Cancer
Revenue flows from biopsy collection, histopathological examination, and molecular analysis of colorectal tissue samples obtained for cancer diagnosis, staging, mutation assessment, and therapeutic decision making.
Cervical Cancers
Revenue accrues from cervical biopsy procedures, cytological evaluation, histological testing, and biomarker analysis conducted to detect, confirm, and characterize cervical malignancies.
Lung Cancers
Revenue is derived from tissue and liquid biopsy procedures, pathological examination, and genomic profiling used to identify lung cancer subtypes, actionable mutations, and treatment selection criteria.
Prostate Cancers
Revenue is generated through prostate tissue sampling, pathological interpretation, and molecular diagnostic testing utilized for cancer detection, risk stratification, disease characterization, and therapy planning.
Skin Cancers
Revenue is primarily captured through skin biopsy procedures, histopathological evaluation, and biomarker testing performed to diagnose and classify melanoma and non-melanoma skin cancers.
Blood Cancers
Revenue flows from bone marrow biopsy, liquid biopsy, cytogenetic analysis, and molecular testing conducted for the diagnosis, classification, and monitoring of hematological malignancies.
Kidney Cancers
Revenue accrues from biopsy procedures, tissue analysis, and molecular characterization services used to diagnose renal malignancies and support treatment selection and disease management.
Liver Cancers
Revenue is derived from liver tissue biopsy, pathological assessment, and biomarker testing performed for cancer confirmation, disease characterization, and therapeutic planning.
Pancreatic Cancers
Revenue is generated through pancreatic biopsy procedures, cytological and histological evaluation, and molecular testing used to detect, classify, and monitor pancreatic malignancies.
Ovarian Cancers
Revenue is primarily captured through tissue sampling, pathological examination, and biomarker analysis performed for ovarian cancer diagnosis, characterization, and treatment guidance.
Others
Revenue flows from biopsy procedures and associated diagnostic testing conducted across additional cancer indications, including bladder, gastric, esophageal, head and neck, and other less prevalent malignancies.
Estimation Model
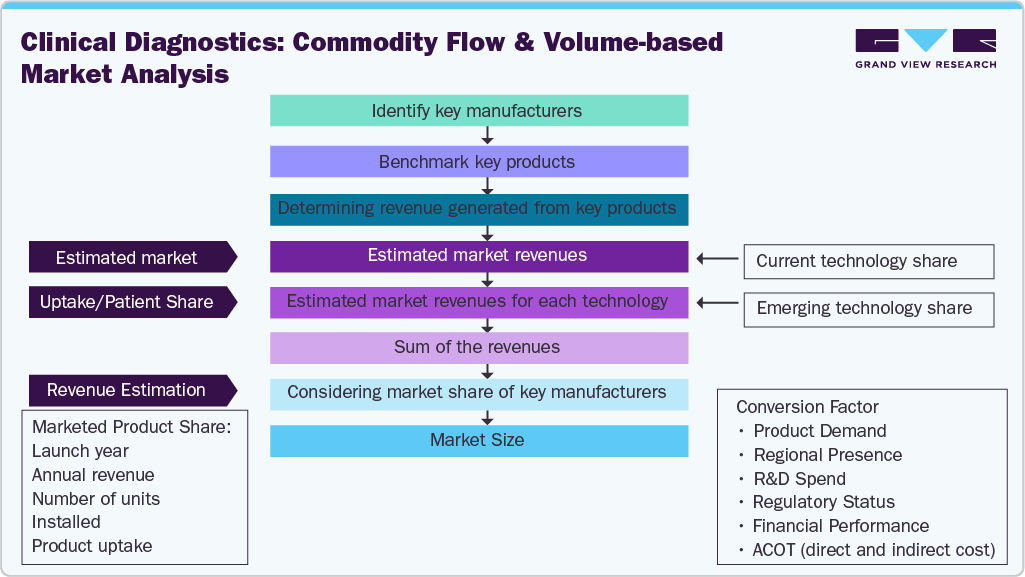
The Cancer Biopsy Market was estimated using a bottom-up methodology that involved identifying leading market participants and benchmarking their cancer biopsy related product portfolios across instruments, kits and consumables, and diagnostic services. Market assessment was conducted by evaluating product level revenues, procedure volumes, technology adoption rates, patient utilization patterns, and company specific financial performance across key applications. Segment level market values were derived by estimating revenues associated with individual biopsy technologies and validating the findings through adoption trends, market penetration rates, and competitive positioning of major industry participants. The final market size was established through the aggregation of segment revenues and further validated using the market share distribution of key companies operating within the cancer biopsy ecosystem.
 To learn more about this report, Download Free Sample Report
Customization Table
Client Request
Customization Delivered
Value Adds
Cancer Biopsy Competitive Landscape & Technology Assessment
Assessed the global cancer biopsy market landscape across tissue biopsy, liquid biopsy, genomic profiling, circulating tumor DNA analysis, companion diagnostics, and molecular testing platforms. Evaluated leading participants, technology adoption trends, regulatory developments, and competitive positioning across hospitals, cancer centers, and diagnostic laboratories.
Helped the client identify growth opportunities across biopsy technologies, benchmark competitive capabilities, evaluate market positioning, and prioritize investments in precision oncology, liquid biopsy platforms, and molecular diagnostic solutions.
Cancer Biopsy Technology & Product Benchmarking Study
Delivered a comprehensive benchmarking of cancer biopsy technologies across tissue biopsy systems, liquid biopsy assays, next generation sequencing platforms, biomarker testing solutions, and molecular diagnostics. Evaluated technology performance, clinical utility, workflow efficiency, scalability, diagnostic accuracy, and product differentiation among key market participants.
Enabled the client to assess technology competitiveness, identify innovation gaps, benchmark product development strategies, and prioritize investments in advanced biopsy technologies, genomic profiling, and precision medicine applications.
Cancer Biopsy Laboratory Infrastructure & Commercialization Feasibility Assessment
Assessed oncology diagnostic laboratory infrastructure, cancer care networks, pathology laboratories, reference laboratories, reimbursement frameworks, regulatory pathways, and commercialization models supporting cancer biopsy services. Evaluated testing volumes, adoption patterns, laboratory capabilities, and operational requirements across major markets.
Supported commercialization planning by identifying market access opportunities, evaluating laboratory partnerships and service models, assessing reimbursement and regulatory considerations, mitigating operational risks, and strengthening long term scalability within the cancer biopsy market.
Liquid Biopsy Adoption & Market Expansion Strategy Assessment
Analyzed adoption trends for liquid biopsy technologies across early cancer detection, treatment monitoring, minimal residual disease testing, and recurrence assessment. Evaluated clinical integration, physician adoption patterns, payer coverage trends, and competitive dynamics across regional markets.
Assisted the client in identifying high growth application areas, optimizing market entry strategies, prioritizing target indications, and evaluating expansion opportunities in emerging liquid biopsy segments.
Frequently Asked Questions About This Report
Some key players operating in the cancer biopsy market include Illumina, Inc., ANGLE Plc, BD (Becton, Dickinson, And Company), Myriad Genetics, Hologic, Inc., Biocept, Inc., Thermo Fisher Scientific, Inc. (Qiagen N.V.), Danaher, and F. Hoffmann-La Roche Ltd.
Key factors that are driving the cancer biopsy market growth include the emerging significance of cancer biopsy and tissue sectioning in providing important information with respect to oncology-based molecular profiling coupled with the advent of non-invasive liquid biopsies.
North America dominated the Cancer Biopsy Market with the largest revenue share of 41.2% in 2025.
The Asia Pacific cancer biopsy industry is expected to witness the fastest CAGR over the projected period, driven by healthcare reforms.
The kits and consumables segment led the market with the largest revenue share of 62.4% in 2025, driven by the rising adoption and usage of kits for effective screening and diagnosis solutions.
Based on applications, the breast cancer segment led the market with the largest revenue share of 16.8% in 2025.
The global cancer biopsy market size was valued at USD 34.8 billion in 2025 and is estimated at USD 37.6 billion for 2026.
The global cancer biopsy market is expected to grow at a CAGR of 8.3% from 2026 to 2033, reaching USD 65.7 billion by 2033.
The tissue biopsy segment dominated the cancer biopsy market with a share of 61.3% in 2025. Tissue biopsy is the only test that confirms the onset of lung cancer in patients and is a preferred biopsy technique across the diagnosis of different cancer types.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


