
- Home
- »
- Plastics, Polymers & Resins
- »
-
Cenospheres Market Size And Share Report, 2026-2033GVR Report cover

Cenospheres Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Gray Cenospheres, White Cenospheres), By End Use (Oil & Gas, Construction, Automotive, Aerospace, Refractory), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$697.3MMarket Estimate, 2026
$769.3MMarket Forecast, 2033
$1,717.1MCAGR, 2026–2033
12.2%Cenospheres Market Summary
The global cenospheres market size was valued at USD 697.3 million in 2025 and is projected to grow from USD 769.3 million in 2026 to USD 1,717.1 million by 2033, at a CAGR of 12.2% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 83.0% in 2025. The market growth is expected to grow due to the diverse applications of cenospheres. The product market is added to drilling fluids in the oil and gas industry to enhance their performance.
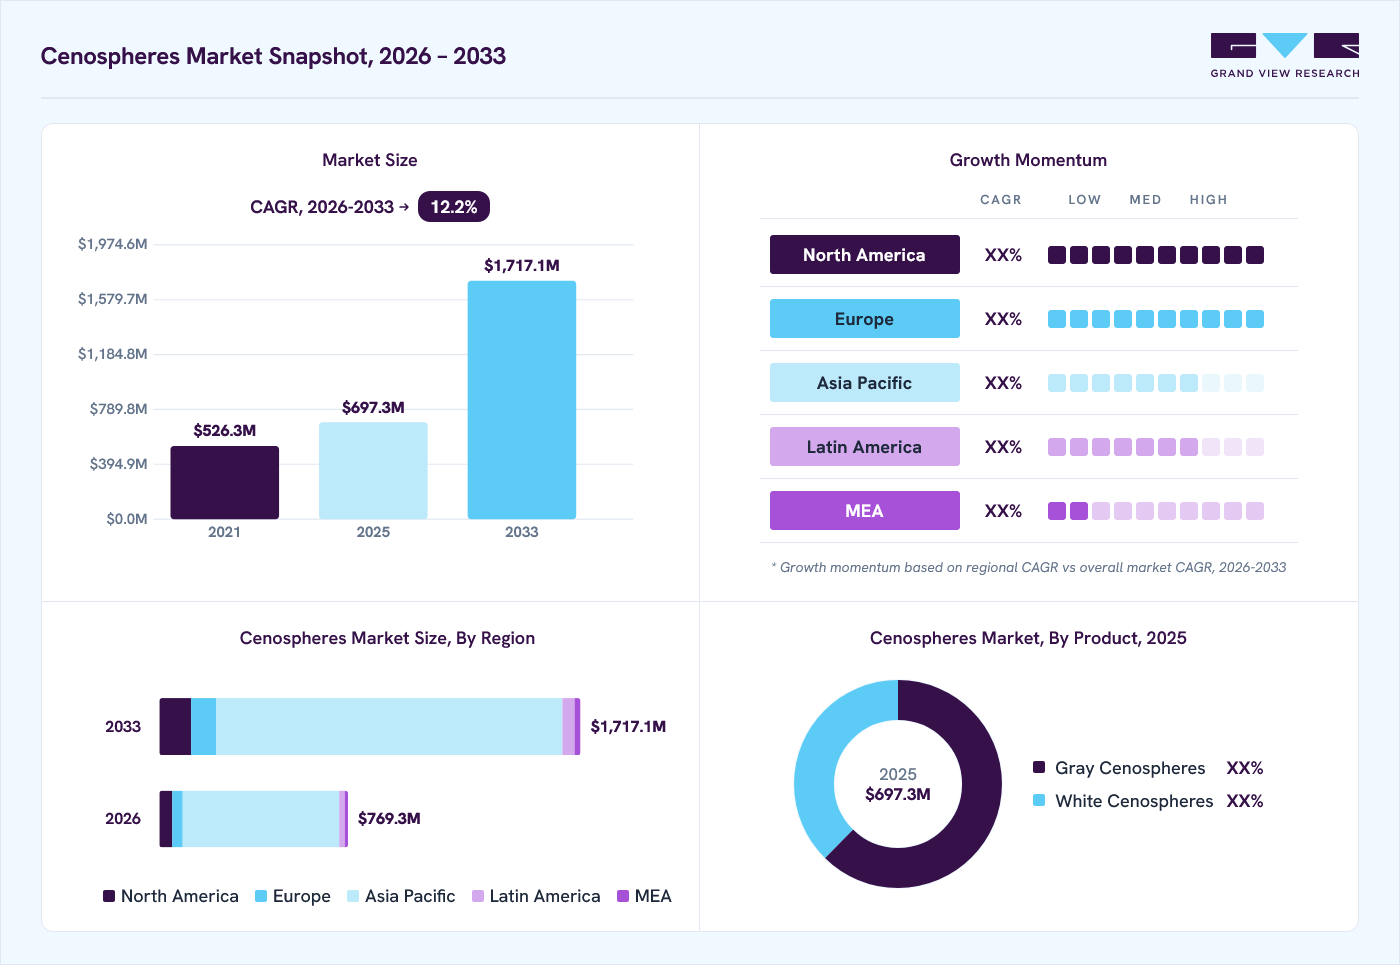 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Gray cenospheres segment held the largest market share of 62.4% in 2025.
- By end use: Construction segment held the largest market share of 24.7% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (83.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 697.3 Million
- Estimated market size in 2026: USD 769.3 Million
- Projected market size by 2033: USD 1,717.1 Million
- CAGR (2026-2033): 12.2%
Prism AI by Grand View Research Free to tryAsk a question about the cenospheres marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
These lightweight, inert particles aid in controlling and reducing friction & fluid density and prevent blowouts during drilling operations. The product market is expected to grow due to its application in gas and oil exploration activities, driving demand for drilling fluids and related additives. Cenospheres prevent well blowouts by enhancing drilling efficiency and pressure balance, displaying the product market's crucial role in the industry.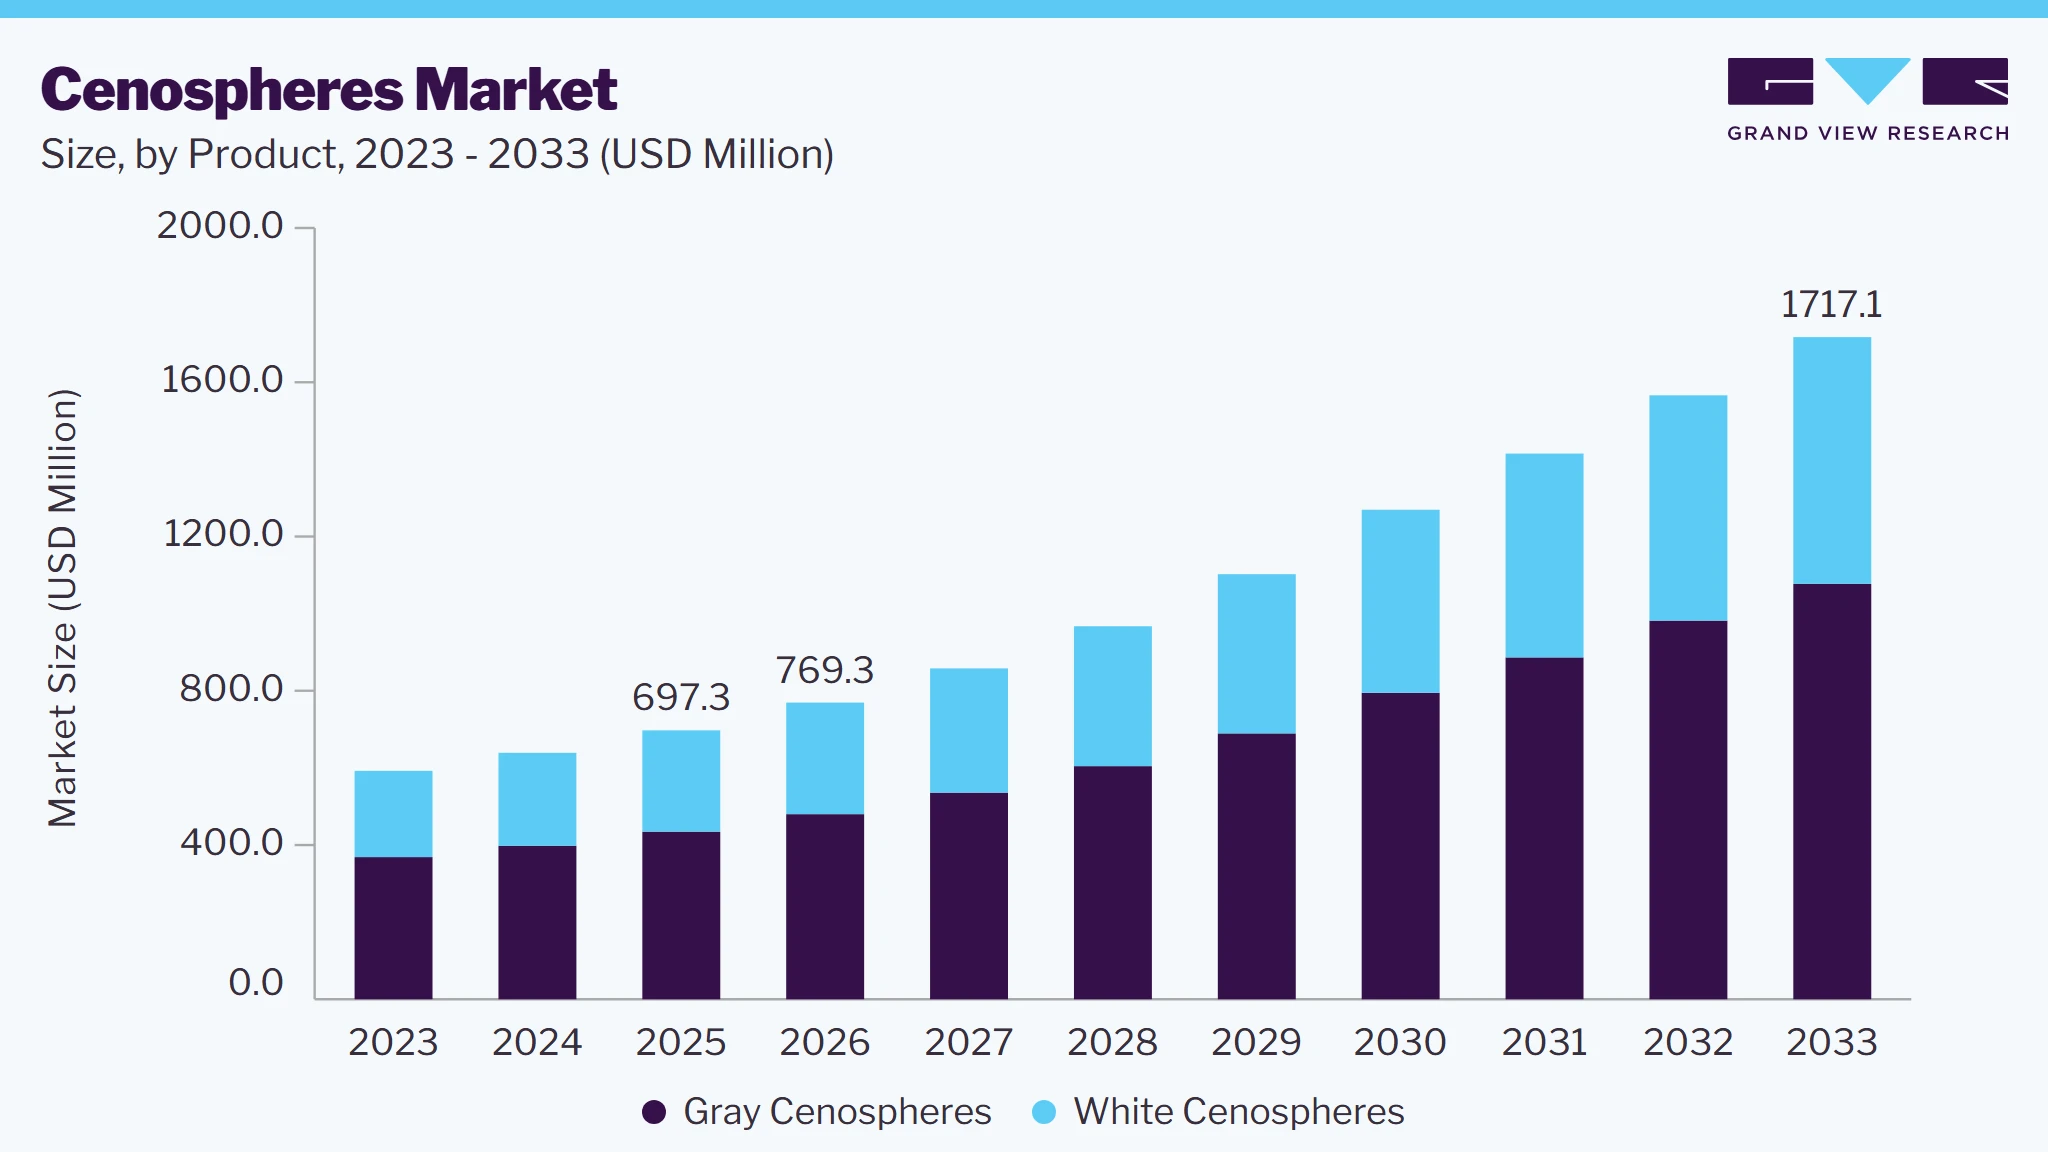 To learn more about this report, Download Free Sample Report
Market Dynamics
The cenospheres Market is driven by the increasing demand for lightweight, high-strength materials across construction, automotive, oil & gas, and aerospace industries. Growing adoption of cenospheres as a cost-effective filler to improve durability, thermal insulation, and mechanical performance is supporting market growth. Rising investments in infrastructure development and the emphasis on sustainable utilization of coal combustion by-products are further contributing to market expansion. However, fluctuations in fly ash availability due to the gradual transition toward renewable energy sources may pose challenges to long-term supply.
The growing adoption of lightweight materials across industries such as construction, automotive, aerospace, oil & gas, and refractories is a key driver of the cenospheres market. Owing to their low density, high compressive strength, and excellent thermal insulation properties, cenospheres are increasingly used as functional fillers to reduce product weight while maintaining structural integrity and performance.
Manufacturers are also utilizing cenospheres to improve product efficiency, lower raw material consumption, and enhance overall cost-effectiveness. Rising infrastructure development, increasing production of lightweight automotive components, and the growing focus on sustainable material utilization are further supporting the demand for cenospheres across diverse industrial applications.
The availability of high-quality cenospheres is directly dependent on the generation and processing of fly ash from coal-fired power plants, making the supply chain susceptible to regional variations and production constraints. Differences in fly ash quality and recovery efficiency can limit the consistent availability of premium-grade cenospheres required for industrial applications.
The ongoing transition toward cleaner energy sources and the gradual reduction in coal-based power generation in several countries are further impacting the long-term availability of raw materials. These supply challenges can lead to price fluctuations and create procurement difficulties for manufacturers relying on a stable supply of cenospheres.
The increasing use of advanced composites and specialty materials across aerospace, automotive, marine, and renewable energy industries present significant growth opportunities for the cenospheres market. Their lightweight structure, high strength-to-weight ratio, and thermal resistance make cenospheres an attractive filler for manufacturing high-performance composite materials.
Growing investments in lightweight engineering, energy-efficient construction materials, and innovative industrial applications are expected to create new avenues for market expansion. Continuous product innovation and the development of value-added cenosphere-based formulations are further enhancing their adoption across emerging high-value applications.
Analyst Perspective
The cenospheres Market is expected to witness steady growth, supported by increasing demand for lightweight, high-performance materials across construction, automotive, oil & gas, and aerospace industries. Growing emphasis on improving material efficiency, reducing product weight, and enhancing thermal insulation is accelerating the adoption of cenospheres in a wide range of industrial applications. Continued product innovation, expanding end-use applications, and rising investments in sustainable material solutions are expected to create long-term growth opportunities, although supply availability remains a key factor influencing market dynamics.
Product Insights & Trends
By product, gray cenospheres held a dominant position, contributing 62.4% of total revenue in 2025. The segment's growth is fueled by high demand from Europe and North America. The increasing oil & gas and construction industries in countries like India, China, and Japan are expected to further bolster the segment's growth. Gray cenospheres are a byproduct of coal combustion in thermal power plants. These are lightweight, inert, hollow spheres composed primarily of silica and alumina and filled with air or inert gas. Typically, their color ranges from gray to light gray. These spheres are used in various applications due to their low density, thermal insulation, and fire resistance properties, making them valuable in the construction, oil and gas, and automotive industries, among others.
White cenospheres are lightweight, inert, hollow spheres composed primarily of silica and alumina and filled with air or inert gas. They are typically a byproduct of coal combustion in thermal power plants. Owing to their low density and high strength, white cenospheres are often used as fillers in cement, ceramics, paints, and plastics, improving the material properties without significantly increasing the weight. Their thermal insulation properties also make them valuable in various applications, from insulating materials to flame retardants.
End-use Insights & Trends
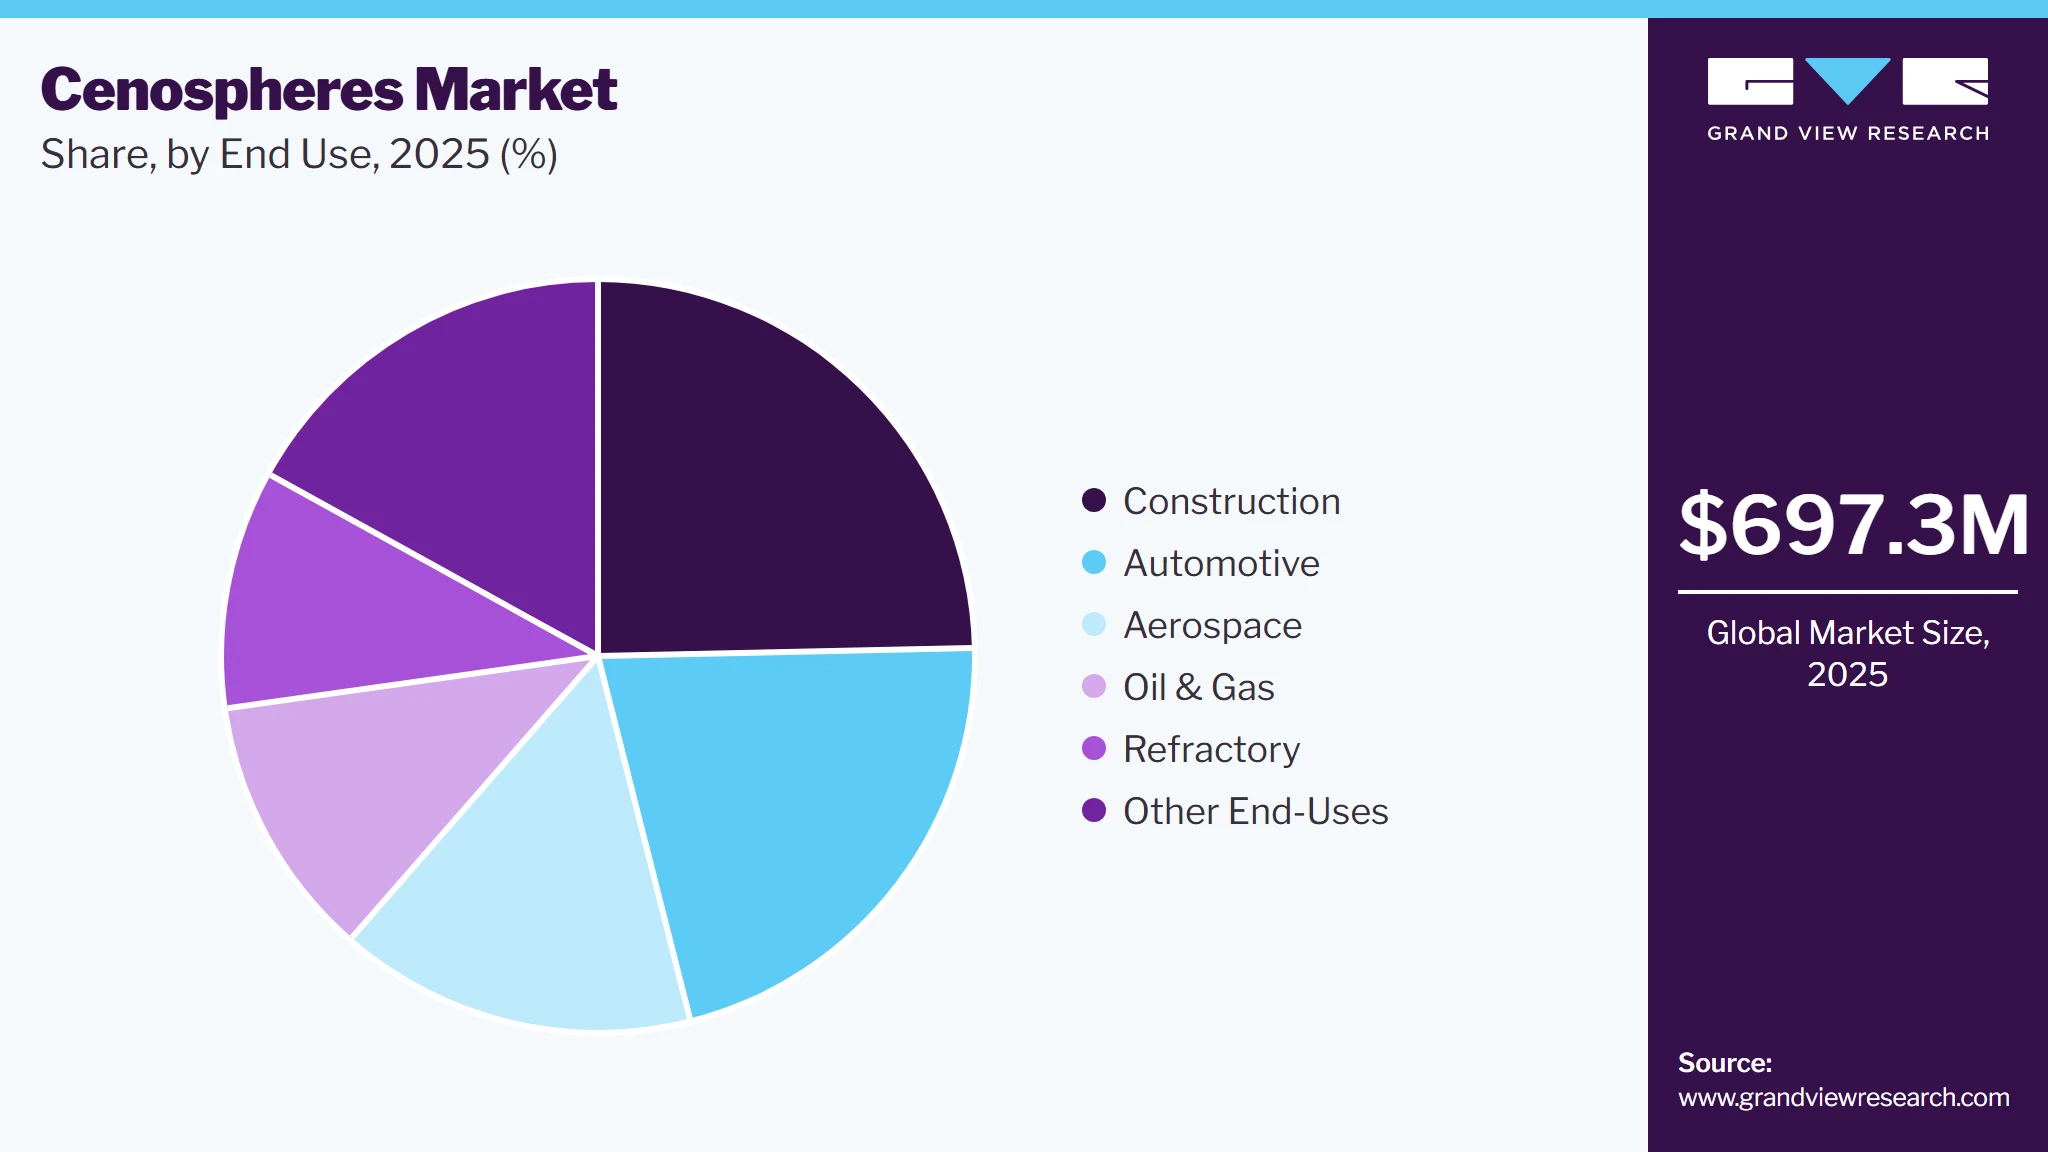
By end use, construction segment accounted for the largest revenue share of 24.7% in 2025. Cenospheres, particularly the gray variety produced from coal combustion, are increasingly incorporated into the construction industry due to their unique properties. Their low density makes them an ideal additive for lightweight concrete, reducing the overall weight of structures while maintaining strength. The intrinsic thermal insulation and fire resistance of cenospheres enhance buildings' energy efficiency and safety. Moreover, their use in cement and concrete improves workability and durability and contributes to more environmentally friendly construction practices by recycling a byproduct of industrial processes.
 To learn more about this report, Download Free Sample Report
The automotive emerged as the fastest growing end use with a CAGR of 12.9% over the forecast period. Cenospheres are being increasingly utilized in the automotive industry, primarily due to their ability to enhance the properties of materials while reducing weight. Their inclusion in automotive components results in lighter vehicles, improving fuel efficiency and reducing carbon emissions. Moreover, the cenospheres' thermal resistance and durability contribute to the longevity and performance of automotive parts. Manufacturers can balance strength, weight reduction, and environmental sustainability in vehicle production by incorporating cenospheres.
Regional Insights & Trends
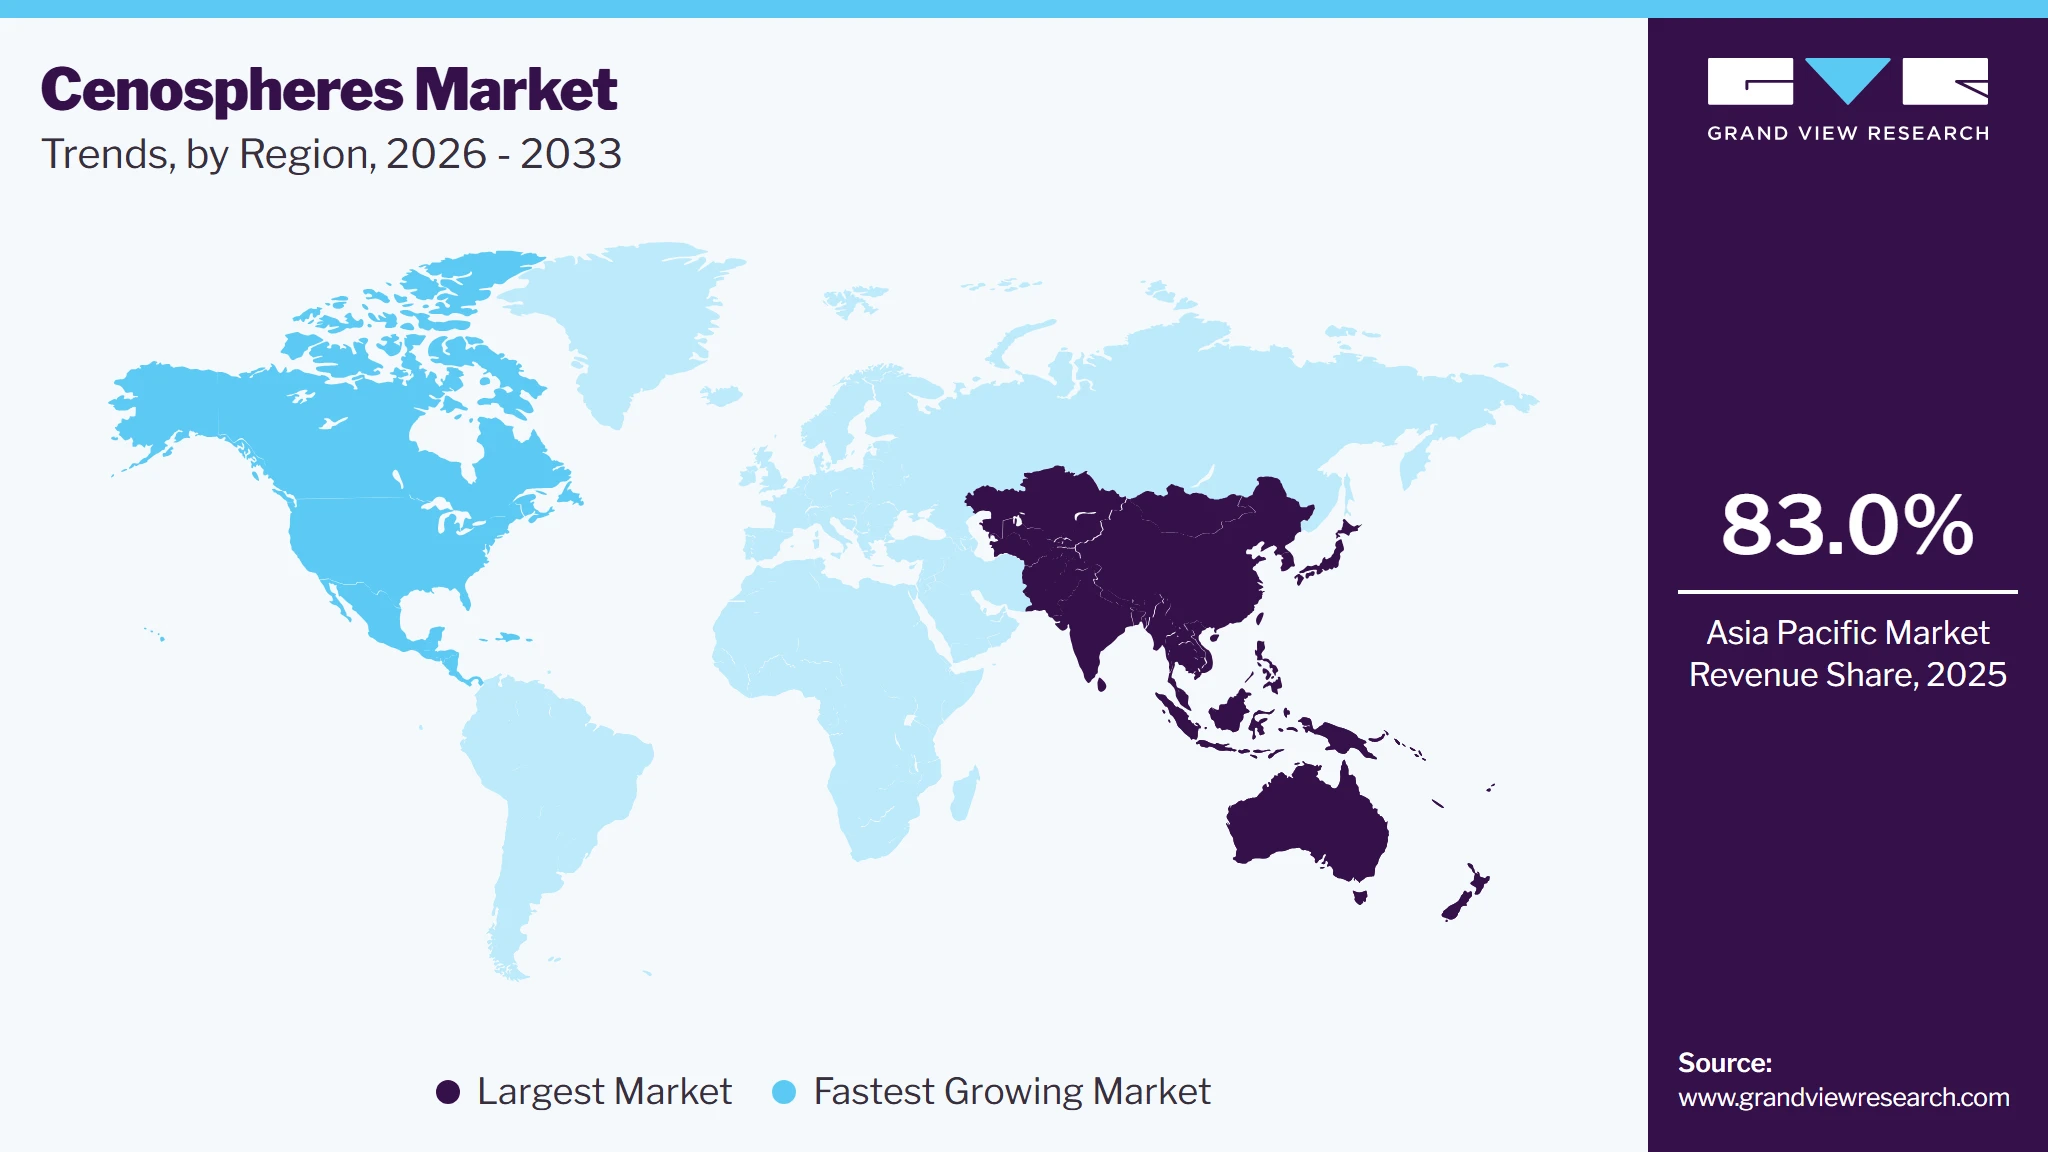
The cenospheres market in North America is expected to grow at the fastest CAGR of 13.6% over the forecast period This growth is attributed to the increasing usage of the product market for construction purposes. North American construction activities are also increasing due to the growing number of construction activities in Canada, Mexico, and the U.S.
U.S. Cenospheres Market Trends
U.S. dominated the market and accounted for a market share of 64.6% in 2025. This growth is attributed to increasing demand for the construction industry in the country. The U.S. is one of the cities with the highest construction activities, leading to a rise in demand for the products market in the region.
Aisa Pacific Cenospheres Market Trends
Asia Pacific dominated the cenospheres market with the highest revenue share of 83.0% in 2025. The Asia Pacific market is expected to grow due to the growing automotive manufacturing plants in the region. This growth will lead to a rise in demand for the product which is used in the automotive sector leading to a rise in demand for the product market.
 To learn more about this report, Download Free Sample Report
China Cenospheres Market Trends
China dominated the Asia Pacific cenospheres market in 2025. China’s cenospheres market is supported by demand from construction, oil and gas, and automotive industries, where cenospheres are used as lightweight fillers in cement, coatings, plastics, and composite materials. The availability of fly ash from coal-fired power plants provides a key raw material advantage, while growing demand for lightweight, high-strength materials is supporting adoption.
Europe Cenospheres Market Trends
Europe plays a significant role in the cenospheres market, with countries such as Germany, the UK, France, Italy, Spain, Russia, Netherlands, and Belgium being key contributors to the market. The region's market dynamics are influenced by factors such as the rise in demand for electronics in the region leading to increased demand for the product market.
Key Cenospheres Company Insights
Some of the key players operating in the global cenospheres market include
-
CAMEX GmbH is a company specializing in the distribution and production of specialty chemicals and raw materials. With a focus on industries such as textiles, pharmaceuticals, and food, the company provides tailored solutions to meet the specific needs of its clients. CAMEX GmbH operates within international markets, leveraging its extensive industry expertise and supply chain capabilities. The company emphasizes quality control and regulatory compliance, ensuring that its products meet industry standards. Its operational strategy includes close collaboration with clients to deliver customized, efficient, and sustainable solutions.
-
Wolken is a company that offers cloud-based enterprise software solutions, focusing on service management and customer support. The company's platform is designed to help organizations streamline their processes, enhance customer interactions, and improve overall efficiency. Wolken's solutions are utilized across various industries, providing customizable and scalable tools that cater to different business needs. The company emphasizes data security, reliability, and compliance, ensuring that its software meets industry standards and regulations. Wolken operates globally, serving a diverse client base with its innovative technology offerings.
Frilite SA and Cenosphere India Pvt. Ltd. are some of the emerging market participants in the global cenospheres market.
-
Frilite SA specializes in the production and distribution of lightweight aggregates and industrial minerals. The company's products are primarily used in the construction, automotive, and refractory industries, offering solutions that enhance material performance and energy efficiency. Frilite SA emphasizes innovation in its product development, ensuring that its offerings meet the evolving needs of its customers. The company operates with a strong commitment to quality and sustainability, adhering to industry standards and regulations across its global operations.
-
Cenosphere India Pvt. Ltd. is a company focused on the manufacturing and export of cenospheres, which are lightweight, hollow spheres primarily composed of silica and alumina. These cenospheres are utilized in a variety of industries, including construction, automotive, and oil and gas, due to their properties such as low density, thermal insulation, and high strength. The company emphasizes quality control and consistency in its production processes, ensuring that its products meet international standards. Cenosphere India Pvt. Ltd. serves both domestic and international markets, catering to the specific needs of its clients.
Key Cenospheres Companies:
The following key companies have been profiled for this study on the cenospheres market.
-
PRIMA CHEM INTERNATIONAL CO., LIMITED
-
Gimpex
-
CAMEX GmbH
-
Wolkem
-
Xingtai Kehui Trading Co., Ltd.
-
China Beihai Fiberglass Co., Ltd.
-
Frilite SA
-
Ashtec India
-
Cenosphere India Pvt. Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Gimpex, CAMEX GmbH, Wolkem, Frilite SA, Ashtec India, Cenosphere India Pvt. Ltd.)
- Focus on expanding global distribution networks, strengthening long-term supply agreements, investing in processing capabilities, maintaining stringent quality standards, and serving diversified end-use industries such as construction, oil & gas, automotive, and refractories.
- Strong brand recognition, established customer relationships, broad product portfolios, consistent product quality, robust manufacturing capabilities, and extensive international market presence.
- Higher operating costs, dependence on fly ash availability, exposure to fluctuations in raw material supply, and relatively slower response to niche market opportunities.
Emerging Players (PRIMA CHEM INTERNATIONAL CO., LIMITED, Xingtai Kehui Trading Co., Ltd., China Beihai Fiberglass Co., Ltd.)
- Emphasize regional market expansion, competitive pricing, customized product offerings, and strategic partnerships with distributors and industrial customers to strengthen market presence.
- Operational flexibility, cost-competitive manufacturing, ability to serve regional customers efficiently, and growing focus on specialized applications.
- Limited production capacity, lower global brand visibility, narrower distribution networks, fewer long-term customer contracts, and comparatively lower investment in research and product development.
Recent Developments
-
In March 2022, Omya AG announced the acquisition of Prima Inter-Chem, a specialty chemical distributor in Malaysia. This acquisition is part of Omya's strategy to expand its presence in Southeast Asia, enhancing its regional distribution network and product offerings. Prima Inter-Chem's established market position and customer base will complement Omya's existing operations, allowing for a broader range of services and products to be offered to customers in various industries. The integration aims to strengthen Omya's footprint in the Southeast Asian market.
-
In May 2021, Omya International AG, a significant company in cenosphere manufacturing, introduced a new line of functionalized calcium carbonate products for PET applications. This cost-effective opacifier is primarily used to produce white opaque PET bottles. The innovation is designed to enhance product appeal and efficiency, which is expected to drive demand and create new opportunities for market growth.
Cenospheres Market Report Scope
Report Attribute
Details
Market size in 2025
USD 697.3 million
Estimated market size in 2026
USD 769.3 million
Projected market size by 2033
USD 1,717.1 million
Growth rate
CAGR of 12.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kiloton, revenue in USD million/billion, and CAGR from 2025 to 2030
Report coverage
Volume forecast, revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; South Africa.
Key companies profiled
PRIMA CHEM INTERNATIONAL CO., LIMITED; Gimpex; CAMEX GmbH; Wolkem; Xingtai Kehui Trading Co., Ltd.; China Beihai Fiberglass Co., Ltd.; Frilite SA; Ashtec India; and Cenosphere India Pvt. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cenospheres Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global cenospheres market report based on product, end-use, and region.
-
Product Outlook (Volume, Kiloton; Revenue, USD Million, 2021 - 2033)
-
Gray Cenosphere
-
White Cenosphere
-
-
End-use Outlook (Volume, Kiloton; Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Construction
-
Automotive
-
Refractory
-
Aerospace
-
Other End-uses
-
-
Regional Outlook (Volume, Kiloton; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The cenospheres market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each cenospheres segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Gray Cenospheres
Revenue generated from the sale of gray cenospheres used as lightweight fillers in construction materials, oil well cementing, refractories, plastics, and other industrial applications.
White Cenospheres
Revenue generated from the sale of premium-grade white cenospheres used in high-performance composites, coatings, aerospace components, automotive parts, and specialty industrial applications requiring superior purity and aesthetics.
End Use
Revenue capture definition
Oil & Gas
Revenue generated from the use of cenospheres in drilling fluids, oil well cementing, insulation materials, and other oilfield applications to improve operational efficiency and reduce material density.
Construction
Revenue generated from the use of cenospheres in lightweight concrete, cement, wall putty, insulation materials, grouts, and other construction products to enhance strength, durability, and thermal performance.
Automotive
Revenue generated from the incorporation of cenospheres into automotive components, plastics, composites, sealants, and coatings to reduce vehicle weight and improve fuel efficiency.
Refractory
Revenue generated from the use of cenospheres in refractory bricks, castables, insulation products, and high-temperature industrial materials requiring low density and thermal resistance.
Aerospace
Revenue generated from the application of cenospheres in aerospace composites and lightweight structural materials to improve strength-to-weight ratio and thermal insulation.
Other End Uses
Revenue generated from the use of cenospheres across marine, paints & coatings, polymers, rubber, ceramics, electronics, and other industrial applications where lightweight and performance-enhancing fillers are required.
Estimation Model
Layer Name
Key Question
Description
Parent Market
What is the size and outlook of the global lightweight fillers and industrial fillers market?
The global lightweight fillers/industrial fillers market serves as the parent market, providing the overall addressable opportunity for cenospheres across industrial applications.
Source Market
How much of the parent market is represented by hollow inorganic fillers?
The addressable market is refined by assessing the demand for hollow inorganic fillers, including cenospheres, based on material performance requirements and end-use adoption.
Product Penetration
What proportion of hollow fillers is occupied by gray and white cenospheres?
Market estimates are derived by evaluating the penetration of gray and white cenospheres across major industrial applications, supported by production, consumption, and pricing trends.
End-use Assessment
Which industries generate demand for cenospheres?
Demand is distributed across key end-use industries including oil & gas, construction, automotive, refractory, aerospace, and other industrial applications based on consumption patterns.
Customization Table
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
The relationship between cenosphere product type and end-use industries was assessed to determine the adoption of gray and white cenospheres across construction materials, drilling fluids, lightweight automotive components, refractory products, and aerospace composites. The analysis highlighted application-specific performance requirements and evolving consumption patterns.
Enables identification of high-value product and application combinations. Supports portfolio optimization, product positioning, and targeted commercialization across key industrial sectors.
Competitive Benchmarking
Leading cenosphere manufacturers were benchmarked based on product quality, processing capabilities, manufacturing capacity, supply chain integration, geographic presence, distribution network, and strategic developments. The assessment also evaluated competitive positioning across construction, energy, automotive, and advanced materials applications.
Helps identify competitive strengths, operational advantages, and market positioning gaps. Facilitates strategic differentiation, partnership evaluation, and long-term business planning.
Opportunity Assessment
Growth opportunities were assessed across lightweight construction materials, oilfield drilling operations, electric vehicle components, aerospace composites, refractory insulation, and sustainable material applications utilizing fly ash derivatives. The analysis also examined opportunities arising from increasing demand for lightweight, high-strength, and environmentally sustainable industrial materials.
Enables identification of high-growth application areas and emerging investment opportunities. Supports innovation planning, product portfolio expansion, and long-term business growth strategies.
Frequently Asked Questions About This Report
By product, gray cenospheres held a dominant position, contributing 62.4% of total revenue in 2025. This dominance is attributed to their widespread availability from coal combustion processes, cost-effectiveness, and broad applicability across construction, oil & gas, automotive, and refractory industries.
Construction segment accounted for the largest revenue of 24.7% in 2025, driven by the increasing use of cenospheres in lightweight concrete, cement, insulation materials, and prefabricated building components to reduce structural weight while improving compressive strength, thermal insulation, and durability.
Asia Pacific dominated the cenospheres market with the highest revenue share of 83.0% in 2025.
The cenospheres market is constrained by its dependence on fly ash generated from coal-fired power plants, whose output is declining in several regions due to the transition toward renewable energy sources. This limits the availability of high-quality raw materials and creates supply challenges.
Increasing adoption of lightweight composites across the automotive, aerospace, construction, and oil & gas industries is creating new opportunities for cenosphere manufacturers. Their ability to reduce product weight while enhancing thermal insulation and mechanical performance aligns with the growing focus on fuel efficiency, lower emissions, and sustainable material usage.
Some of the key players operating in the global cenospheres market include PRIMA CHEM INTERNATIONAL CO., LIMITED; Gimpex; CAMEX GmbH; Wolkem; Xingtai Kehui Trading Co., Ltd.; China Beihai Fiberglass Co., Ltd.; Frilite SA; Ashtec India; and Cenosphere India Pvt. Ltd.
The cenospheres market is added to drilling fluids in the oil and gas industry to enhance their performance. These lightweight, inert particles aid in controlling and reducing friction & fluid density and prevent blowouts during drilling operations.
The global cenospheres market size was valued at USD 697.3 million in 2025 and is estimated at USD 769.3 million for 2026.
The global cenospheres market is expected to grow at a CAGR of 12.2% from 2026 to 2033, reaching USD 1,717.1 million by 2033.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


