
- Home
- »
- Plastics, Polymers & Resins
- »
-
Conductive & EMI Shielding Plastics For 5G & IoT Market Report, 2033GVR Report cover

Conductive & EMI Shielding Plastics For 5G & IoT Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Conductive Polymers, Metal-Filled Plastics, Carbon-Based Plastics), By Application (Antennas & Base Stations), By Region, And Segment Forecasts
Market Size, 2025
$1.5BMarket Estimate, 2026
$1.7BMarket Forecast, 2033
$3.5BCAGR, 2026–2033
11.1%Conductive & EMI Shielding Plastics For 5G & IoT Market Summary
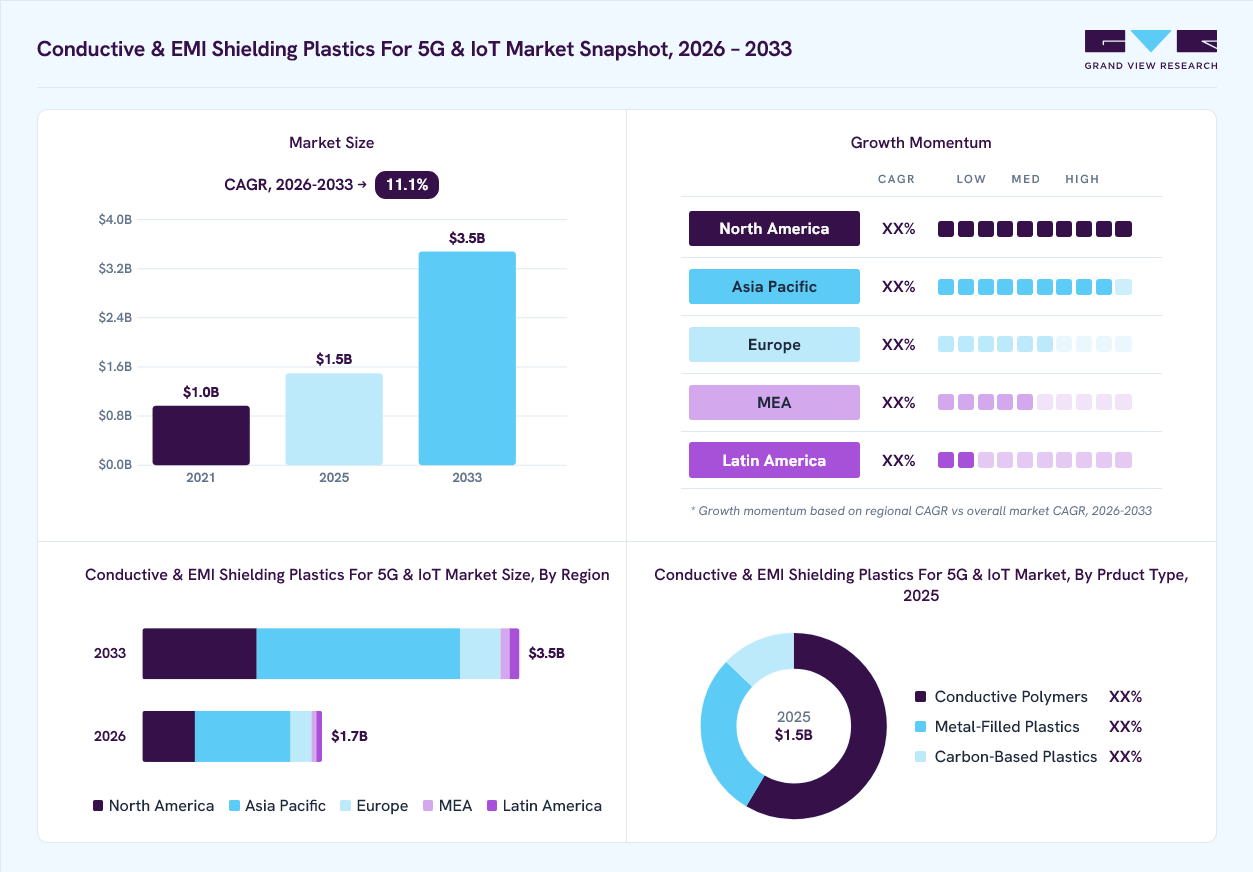
The conductive & EMI shielding plastics for 5G & IoT market size was valued at USD 1.5 billion in 2025 and is projected to grow from USD 1.7 billion in 2026 to USD 3.5 billion by 2033, at a CAGR of 11.1% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 53.0% in 2025. Growing deployment of 5G infrastructure and increasing adoption of connected consumer electronics, including smartphones, wearables, and AR/VR devices, are accelerating demand for conductive and EMI shielding plastics.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Conductive polymers segment led the conductive & EMI shielding plastics for 5G & IoT market with the largest revenue share of 58.4% in 2025.
- By application: Antennas and base stations segment led the market with the largest revenue share of 32.1% in 2025.
Regional Highlights
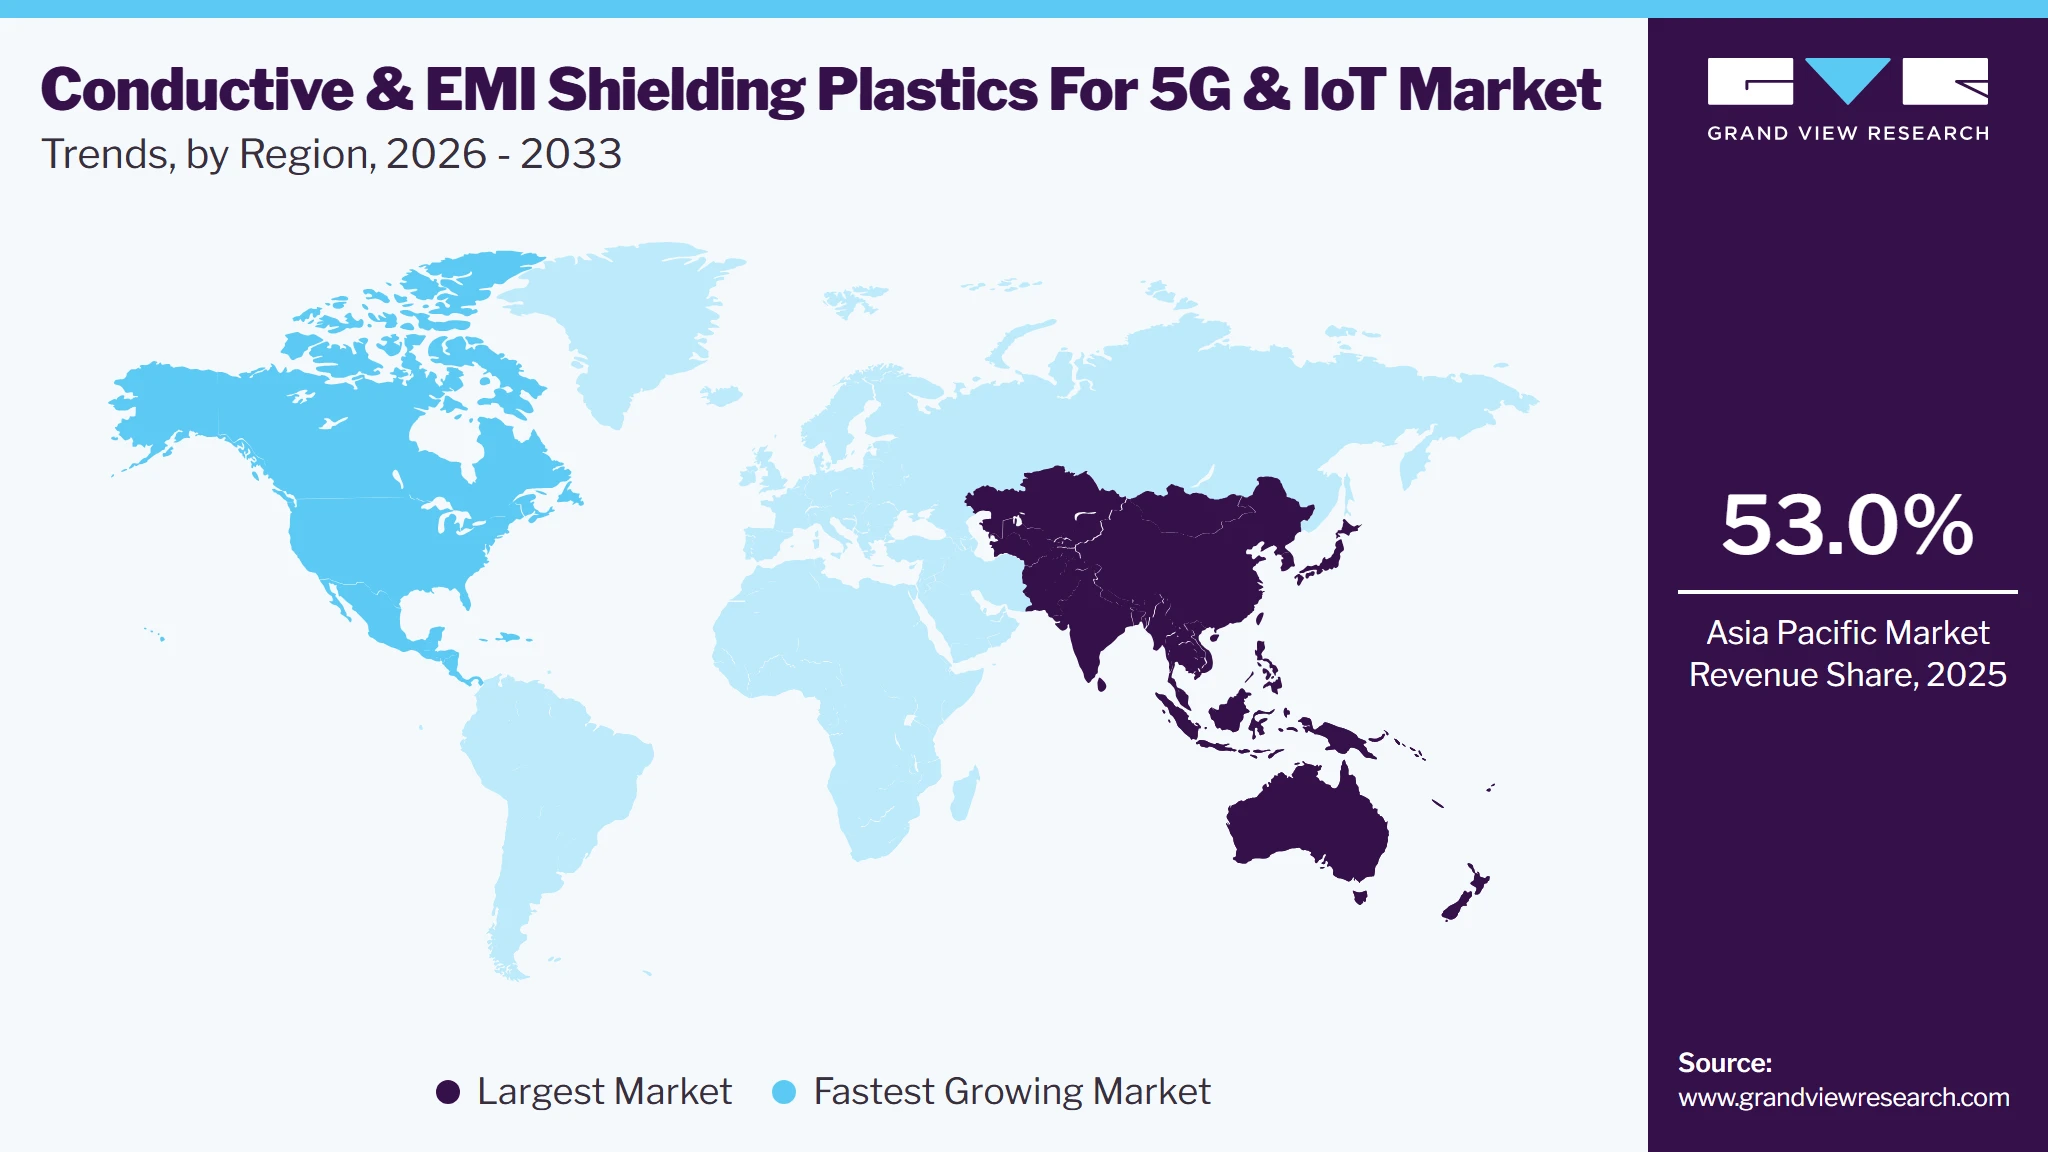
- Largest regional market: Asia Pacific (53.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.5 Billion
- Estimated market size in 2026: USD 1.7 Billion
- Projected market size by 2033: USD 3.5 Billion
- CAGR (2026-2033): 11.1%
Prism AI by Grand View Research Free to tryAsk a question about the conductive & EMI shielding plastics for 5G & IoT marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Rising mm Wave network expansion, coupled with the need for lightweight, high-performance shielding materials that ensure signal integrity, reduce electromagnetic interference, and replace conventional metal components, is further driving market growth across telecom infrastructure and IoT applications. The growing adoption of 5G-enabled consumer electronics, such as smartphones, AR/VR devices, and wearables, is increasing the need for lightweight EMI shielding plastics to ensure signal stability and prevent interference. The increasing deployment of mmWave (millimeter-wave) 5G networks is driving demand for high-performance conductive and EMI shielding plastics.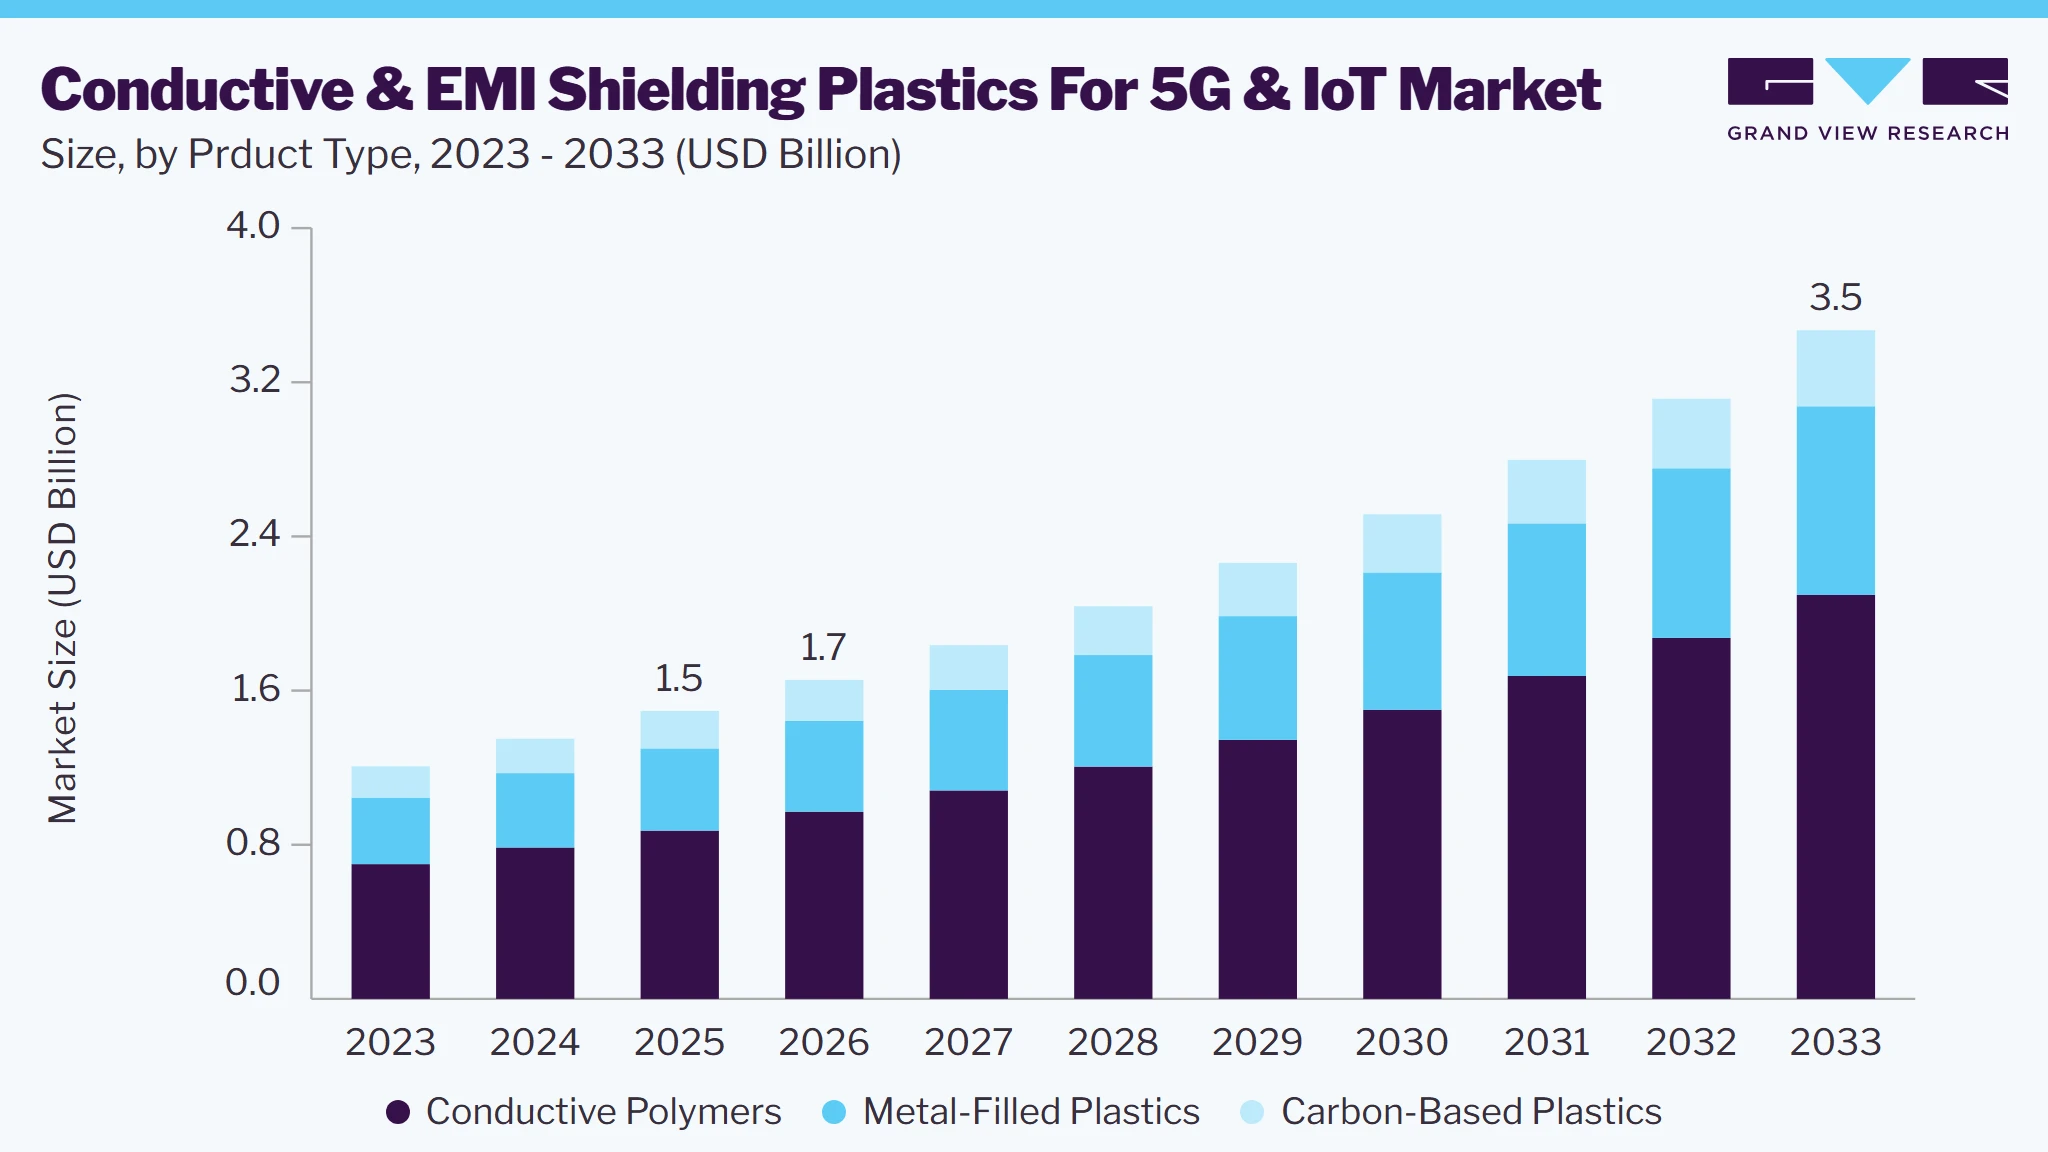 To learn more about this report, Download Free Sample Report
Unlike sub-6 GHz 5G, which operates at lower frequencies, mmWave technology enables ultra-fast data transfer but is highly susceptible to signal interference and attenuation. This necessitates the use of advanced EMI shielding materials in base stations, antennas, and IoT devices to maintain signal integrity and reduce electromagnetic interference. As telecom infrastructure providers scale up the adoption of mmWave-based 5G in urban environments, the demand for lightweight, high-conductivity shielding solutions is expected to grow, replacing traditional metal shielding with polymer-based alternatives that offer superior design flexibility and reduced weight.
Market Dynamics
The market is shaped by rising use of lightweight conductive and EMI shielding plastics in 5G infrastructure and connected devices, especially where metal housings create design and weight constraints. Demand is concentrated in Asia Pacific, where telecom equipment, consumer electronics, and IoT manufacturing are clustered. Metal-filled plastics remain the main commercial workhorse, while carbon-based grades are gaining traction in cost-sensitive and sustainability-led designs. Commercial activity is driven by OEM qualification, specification-based sourcing, and application-linked integration across antennas, base stations, smart home devices, and industrial IoT systems.
The rollout of densified 5G networks is a primary growth catalyst because mmWave and multi-band deployments require stronger interference control, better signal stability, and compact enclosures. This is increasing demand for conductive plastics in antennas, base stations, small cells, and repeaters, where lightweight materials help reduce design complexity without sacrificing shielding performance. Telecom operators and infrastructure vendors are replacing conventional metal housings with molded polymer-based solutions that support thinner walls, easier geometry, and lower assembly burden.
The same logic is extending into connected consumer and industrial devices, where miniaturization raises the need for materials that combine conductivity, thermal stability, and processability. Wearables, smart home devices, and industrial IoT modules increasingly require EMI shielding in confined spaces, creating recurring demand for formulated plastics rather than one-time hardware substitution. This supports premium pricing for suppliers that can qualify with OEMs and deliver application-specific grades.
The market remains constrained by the cost of advanced conductive formulations, especially grades that rely on silver, nickel, copper, graphene, carbon nanotubes, or coated fibers. These additives raise compound cost and increase technical complexity during processing, testing, and qualification. Performance consistency is also difficult to maintain at scale, which slows adoption in price-sensitive electronics and limits substitution away from conventional metal shielding in lower-margin assemblies.
Carbon-based plastics are creating a clear opportunity as device makers seek lighter, lower-cost, and more sustainable shielding solutions. Their appeal is strongest in wearables, smart home devices, and industrial IoT systems where battery life, design flexibility, and recyclability matter. Suppliers that can balance conductivity, molding efficiency, and regulatory compliance will be better positioned to win programs outside traditional telecom hardware.
Analyst Perspective
The conductive and EMI shielding plastics market is moving from a volume-led substitution story to a value-led materials platform for 5G and IoT hardware. Demand will remain anchored in antennas, base stations, and densified network nodes, but growth will broaden into wearables, smart home devices, and industrial IoT as electronic assemblies become smaller, denser, and more interference sensitive. The strongest suppliers will combine formulation IP, regional compounding capacity, and OEM qualification depth with the ability to support thinner walls, higher conductivity, and lower weight. Carbon-based systems should gain share where cost, sustainability, and battery efficiency matter, while metal-filled grades will continue to lead high-performance telecom use. Competitive pressure will intensify around filler cost, supply chain reliability, and pricing discipline, especially as customers compare performance against metal housings and alternative shielding structures. Over the next several years, leaders will be defined by application expertise, speed to qualify, and scalable technical support.
Product Insights & Trends
Based on product, the conductive polymers conductive & EMI shielding plastics for 5G & IoT segment led the market with the largest revenue share of 58.4% in 2025. Metal-filled plastics dominated the conductive & EMI shielding plastics for 5G & IoT market across the Product segmentation in terms of revenue, accounting for a market share of 58.19% in 2024. The increasing complexity of 5G network components and high-frequency IoT applications is accelerating the demand for metal-filled plastics, which offer high conductivity and robust EMI shielding while maintaining design flexibility.
As next-generation telecom equipment requires enhanced thermal stability and electromagnetic shielding, traditional metal enclosures are being replaced with polymer-based composites infused with silver, nickel, or copper particles to achieve superior performance. In addition, regulatory compliance with electromagnetic compatibility (EMC) standards is becoming more stringent, pushing manufacturers to adopt lightweight yet highly effective shielding materials that can be molded into intricate designs for improved integration into compact electronic assemblies.
The growing emphasis on sustainable and cost-effective EMI shielding solutions is fueling demand for carbon-based conductive plastics, particularly in the IoT and edge computing industries. These materials, incorporating graphene, carbon nanotubes, or carbon black, offer an optimal balance of electrical conductivity, lightweight properties, and recyclability, making them a preferred choice for applications requiring high-frequency shielding without adding excessive weight.
As the industry moves toward low-power, battery-operated IoT devices in industrial automation, wearables, and smart infrastructure, carbon-based plastics provide a cost-efficient alternative to metal-filled polymers while also contributing to environmental sustainability goals in electronics manufacturing.
Application Insights & Trends
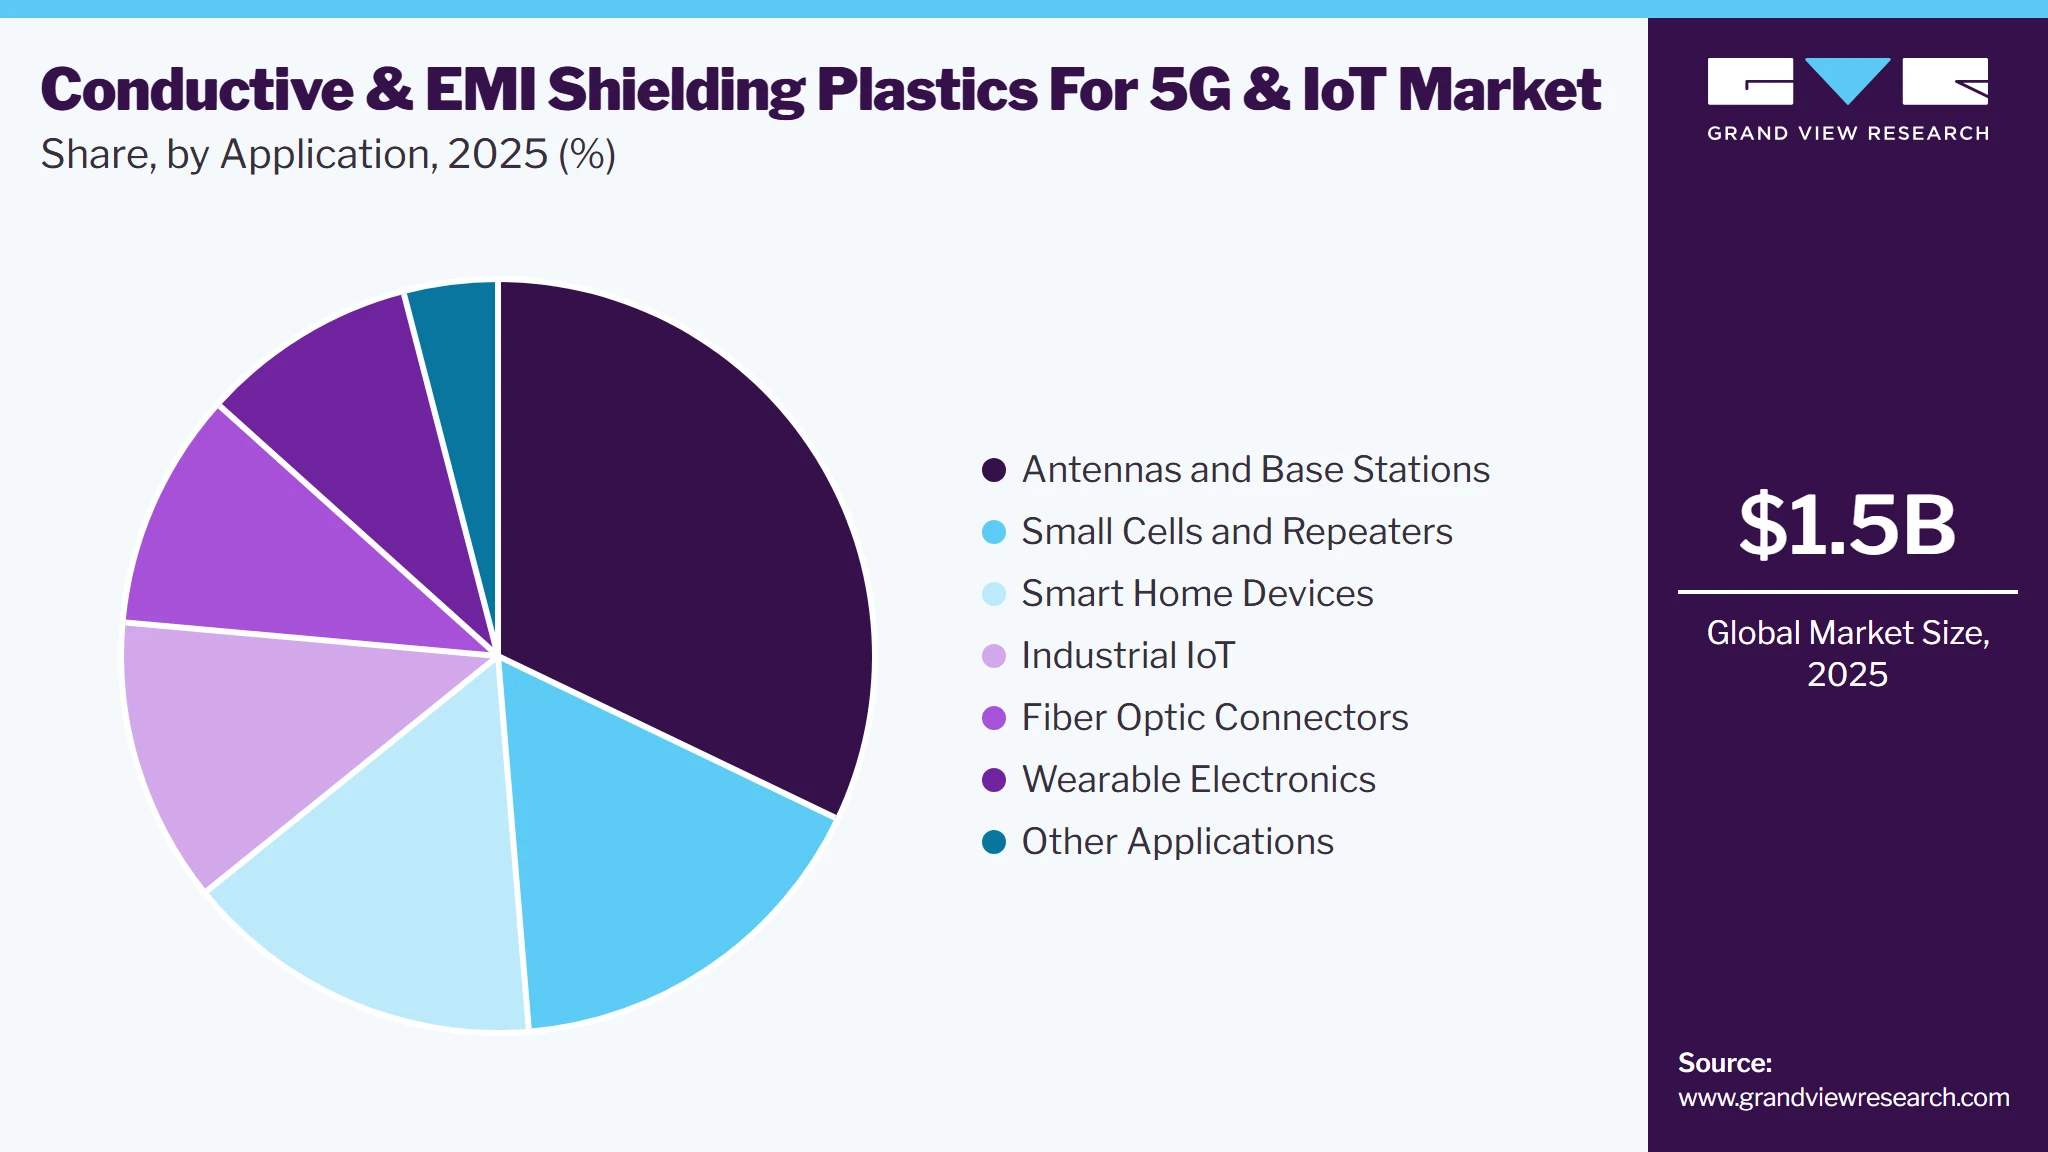
Based on application, the antennas and base stations segment led the market with the largest revenue share of 32.1% in 2025. Antennas and base stations dominated the conductive & EMI shielding plastics for 5G & IoT market across the recycling process segmentation in terms of revenue, accounting for a market share of 31.90% in 2024. The deployment of 5G small cells and massive MIMO (Multiple Input Multiple Output) antennas is driving demand for conductive and EMI shielding plastics to maintain network efficiency in high-density urban environments.
Unlike traditional macro towers, small cell networks require compact, lightweight, and thermally stable enclosures that can effectively shield against interference while supporting seamless data transmission. As telecom operators roll out densified 5G infrastructure, the adoption of high-performance shielding plastics in antennas and base stations is becoming critical to reducing signal loss, enhancing operational reliability, and minimizing electromagnetic leakage, especially in multi-band spectrum deployments.
 To learn more about this report, Download Free Sample Report
The rapid proliferation of voice-controlled assistants, AI-integrated smart home ecosystems, and wireless IoT-enabled appliances is driving the demand for efficient EMI shielding solutions in consumer electronics. With the increasing number of connected devices operating within close proximity, interference between Bluetooth, Wi-Fi, and 5G signals is a growing challenge, necessitating the use of lightweight conductive polymers that can enhance signal clarity and prevent crosstalk.
Additionally, as smart home brands compete to reduce device weight and improve aesthetic appeal, thin, flexible shielding plastics are emerging as a preferred solution over bulky metal enclosures, ensuring seamless wireless communication without compromising design or performance.
Regional Insights & Trends
Asia Pacific dominated the conductive & EMI shielding plastics for 5G & IoT market with the largest revenue share of 53.0% in 2025. The explosive growth of consumer electronics and telecom infrastructure development in the Asia Pacific region is creating a strong demand for conductive and EMI shielding plastics, particularly in smartphones, 5G base stations, and IoT devices.
 To learn more about this report, Download Free Sample Report
Countries such as India, South Korea, and Japan are heavily investing in 5G rollout and smart city initiatives, driving the adoption of high-frequency shielding solutions to ensure uninterrupted network performance.
China Conductive & EMI Shielding Plastics For 5G & IoT Market Trends
The conductive & EMI shielding plastics for 5G & IoT market in China accounted for the largest market revenue share in the Asia Pacific in 2025. China’s aggressive 5G expansion and leadership in AI-powered IoT ecosystems are propelling the demand for high-performance EMI shielding plastics, especially in industrial automation, connected healthcare, and smart manufacturing. With state-backed investments in 6G research and large-scale urban digitization projects, the need for lightweight, scalable shielding materials is growing, as the country aims to maintain its dominance in telecom infrastructure and edge computing technologies.
North America Conductive & EMI Shielding Plastics For 5G & IoT Market Trends
The rapid expansion of private 5G networks and industrial IoT deployments is significantly driving demand for conductive and EMI shielding plastics across North America. With leading telecom providers and cloud service companies investing heavily in 5G-enabled smart factories, logistics automation, and AI-driven edge computing, there is a growing need for lightweight, high-performance shielding materials that can maintain signal integrity in dense electromagnetic environments.
The U.S. market is experiencing a surge in demand for conductive and EMI shielding plastics due to the federal push for semiconductor manufacturing under the CHIPS Act, which is accelerating domestic production of 5G chips, IoT sensors, and high-frequency communication modules. With the Biden administration focusing on reshoring critical electronics supply chains, manufacturers are prioritizing advanced shielding materials that offer both high conductivity and cost-effective scalability for next-generation devices.
Europe Conductive & EMI Shielding Plastics For 5G & IoT Market Trends
The fast-growing 5G deployment in industrial automation and automotive sectors is fueling demand for EMI shielding plastics across Europe, particularly in Germany, France, and the UK. With automakers transitioning towards connected EVs and software-defined vehicles (SDVs), the need for lightweight, thermally efficient shielding solutions has intensified, as modern vehicles integrate multiple high-frequency sensors, radar systems, and over-the-air (OTA) communication modules.
Conductive & EMI Shielding Plastics For 5G & IoT Market Companies Share & Insights
The Conductive & EMI Shielding Plastics For 5G & IoT Market is highly competitive, with several key players dominating the landscape. Major companies include RTP Company, Laird Performance Materials, Parker Hannifin, Premix, Celanese, Dow Inc., Sabic, and Avient Corporation.
The conductive & EMI shielding plastics for 5G & IoT market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their material Products.
Key Conductive & EMI Shielding Plastics For 5G & IoT Companies:
The following key companies have been profiled for this study on the conductive & EMI shielding plastics for 5G & IoT market.
-
RTP Company
-
Laird Performance Materials
-
Parker Hannifin
-
Premix
-
Celanese
-
Dow Inc.
-
Sabic
-
Avient Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Dow Inc., SABIC, Parker Hannifin, Avient Corporation, Laird Performance Materials, Celanese.)
- Expand application-specific conductive compounds for telecom, electronics, and industrial device platforms.
- Use global manufacturing, technical service teams, and OEM qualification support to defend major accounts.
- Bundle shielding materials with broader polymer and performance material portfolios to raise account stickiness.
- Strong integration across resins, compounding, and downstream application support.
- Wider geographic presence and better access to multinational OEM programs.
- Established validation history for high-reliability electronics and infrastructure uses.
- Slower product customization cycles compared with niche compounding specialists.
- Higher overhead and longer approval cycles in fast-moving device programs.
- Greater exposure to pricing pressure in large-volume, specification-driven contracts.
Emerging Players (RTP Company, Premix.)
- Focus on targeted conductive formulations and custom compounding for specific device platforms.
- Build growth through technical collaboration, fast sampling, and design-in support.
- Concentrate on niche programs where performance tuning matters more than scale.
- Faster adaptation to application changes and custom shielding requirements.
- Stronger ability to serve specialized customer needs with shorter development cycles.
- Better positioning in niche projects that require formulation flexibility.
- Lower scale and narrower production footprint than global material suppliers.
- Limited leverage in raw material procurement and multinational account coverage.
- Higher dependence on a smaller number of programs and customer wins.
Recent Developments
-
In February 2025, PolyJoule, Inc. introduced its second-generation conductive polymer battery, the Energy Reservoir, designed to improve safety, reduce costs, extend lifecycles, and increase energy densities. According to CEO Eli Paster, the Energy Reservoir addresses customer demands for higher energy density and system flexibility while maintaining sustainability and safety, making it suitable for 5G & IoT applications.
-
In June 2023, Toray Industries, Inc. announced the development of a new ion-conductive polymer membrane with ten times the ion conductivity of previous versions. This innovation had the potential to speed up the adoption of solid-state and lithium metal batteries, improving the range of electric vehicles, industrial drones, and urban air mobility systems and other IoT devices.
Conductive & EMI Shielding Plastics For 5G & IoT Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.5 billion
Estimated market size in 2026
USD 1.7 billion
Projected market size by 2033
USD 3.5 billion
Growth rate
CAGR of 11.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain, China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
RTP Company; Laird Performance Materials; Parker Hannifin; Premix; Celanese; Dow Inc.; Sabic; Avient Corporation
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase—addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Conductive & EMI Shielding Plastics For 5G & IoT Market Report Segmentation
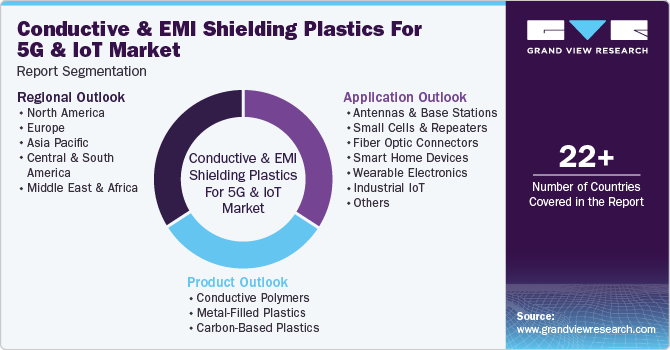
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented conductive & EMI shielding plastics for 5G & IoT market report on the basis of product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Conductive Polymers
-
Metal-Filled Plastics
-
Carbon-Based Plastics
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Antennas and Base Stations
-
Small Cells and Repeaters
-
Fiber Optic Connectors
-
Smart Home Devices
-
Wearable Electronics
-
Industrial IoT
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The conductive & EMI shielding plastics for 5G & IoT market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each conductive & EMI shielding plastics for 5G & IoT segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Conductive Polymers
Revenue is captured through sales of engineered conductive resin systems used in thin-wall housings, antenna parts, and electronic enclosures that require stable shielding with design flexibility.
Metal-Filled Plastics
Revenue is generated from compounded plastics loaded with metal particles for high-shielding applications in telecom hardware, base station parts, connectors, and dense IoT assemblies.
Carbon-Based Plastics
Revenue is captured through graphene, carbon black, and carbon nanotube based grades sold for lightweight, cost-sensitive shielding in consumer electronics, wearables, and compact IoT devices.
Segment - Application
Revenue capture definition
Antennas and Base Stations
Revenue is earned from high-volume qualified materials used in antenna bodies, radio housings, base station enclosures, and network equipment requiring strong EMI control.
Small Cells and Repeaters
Revenue is captured through materials supplied for compact network nodes, repeaters, and distributed antenna systems that need lightweight shielding and thermal stability.
Fiber Optic Connectors
Revenue is generated from shielding plastics used in connector housings, module frames, and related telecom components where signal integrity and dimensional precision are critical.
Smart Home Devices
Revenue is captured from consumer electronics applications such as routers, hubs, speakers, and connected appliances that need interference control in crowded wireless environments.
Wearable Electronics
Revenue is earned from slim, flexible, and low-weight shielding materials used in smartwatches, fitness bands, health trackers, and similar battery-operated devices.
Industrial IoT
Revenue is captured through materials used in gateways, sensors, controllers, and industrial communication modules operating in harsh electromagnetic environments.
Other Applications
This residual segment includes all remaining use cases where shielding plastics are sold into specialized electronics, custom modules, and niche communication components.
Estimation Model
Layer Name
Key Question
Description
Demand Screening
Why assess market demand?
The first layer maps telecom rollout, consumer electronics output, and IoT device shipments to establish the core demand pool for shielding plastics.
Material Mix Calibration
Why allocate material mix?
The second layer allocates revenue by conductive polymer, metal-filled, and carbon-based grades according to shielding intensity, cost position, and moldability needs.
Application Weighting
Why prioritize applications?
The third layer assigns demand to antennas, small cells, wearables, and industrial IoT based on qualification depth and end-use penetration.
Regional Reconciliation
Why reconcile regional demand?
The final layer balances Asia Pacific, North America, Europe, and other regions against manufacturing hubs, telecom investment, and sourcing concentration.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country-level telecom demand view
Added country-wise demand framing for key 5G and IoT markets, with emphasis on Asia Pacific manufacturing hubs, North American private 5G demand, and European electronics qualification patterns.
Improves regional targeting and helps align sales strategy with end-use concentration.
Application-level revenue logic
Added commercial revenue capture definitions for antennas, small cells, connectors, wearables, smart home devices, and industrial IoT, linking each segment to qualification and sourcing behavior.
Strengthens segment clarity and supports sharper TAM interpretation.
Sustainability positioning
Added a sustainability angle for carbon-based shielding plastics, focusing on lightweight design, lower material intensity, and fit with recyclable electronics material strategies.
Supports ESG-aligned product positioning and differentiation.
Frequently Asked Questions About This Report
The Asia Pacific conductive & EMI shielding plastics for 5G & IoT market accounted for the largest share of 53.0% market size in 2025.
North America is the fastest-growing region over the forecast period.
The conductive & EMI shielding plastics for 5G & IoT market was estimated at around USD 1.5 billion in 2025 and is expected to reach around USD 1.7 billion in 2026.
The conductive & EMI shielding plastics for 5G & IoT market is expected to grow at a compound annual growth rate of 11.1% from 2026 to 2033 to reach around USD 3.5 billion by 2033.
The key players in the conductive & EMI shielding plastics for 5G & IoT market are RTP Company, Laird Performance Materials, Parker Hannifin, Premix, Celanese, Dow Inc., Sabic, and Avient Corporation
Based on application, the antennas and base stations segment accounted for the largest share of 32.1% market size in 2025. Growing 5G network deployment, increasing mobile data traffic, and rising telecom infrastructure investments, together with advances in conductive polymer compounding and EMI shielding technologies, are accelerating conductive plastics adoption for antennas and base stations, enabling lightweight, high-performance, and interference-resistant communication systems.
Growing deployment of 5G infrastructure and increasing adoption of connected consumer electronics, including smartphones, wearables, and AR/VR devices, are accelerating demand for conductive and EMI shielding plastics. Rising mm Wave network expansion, coupled with the need for lightweight, high-performance shielding materials that ensure signal integrity, reduce electromagnetic interference, and replace conventional metal components, is further driving market growth across telecom infrastructure and IoT applications.
The conductive polymers conductive & EMI shielding plastics for the 5G & IoT industry led the conductive & EMI shielding plastics for 5G & IoT product type market in 2025 with a 58.4% share. Growing demand from 5G infrastructure, advanced consumer electronics, and industrial IoT applications, coupled with advances in intrinsically conductive polymer formulations and compounding technologies, is accelerating the adoption of conductive polymers for lightweight EMI shielding, antenna housings, electronic enclosures, and high-performance communication components.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


