
- Home
- »
- Biotechnology
- »
-
Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Report 2033GVR Report cover

Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market (2026 - 2033)
Size, Share & Trends Analysis Report By Therapeutics Type, By Application (End Product Manufacturing, API Manufacturing), By Formulation, By Scale, By Mode, By Product, By Region, And Segment Forecasts
Market Size, 2025
$1.5BMarket Estimate, 2026
$1.7BMarket Forecast, 2033
$3.4BCAGR, 2026–2033
11.0%Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Summary
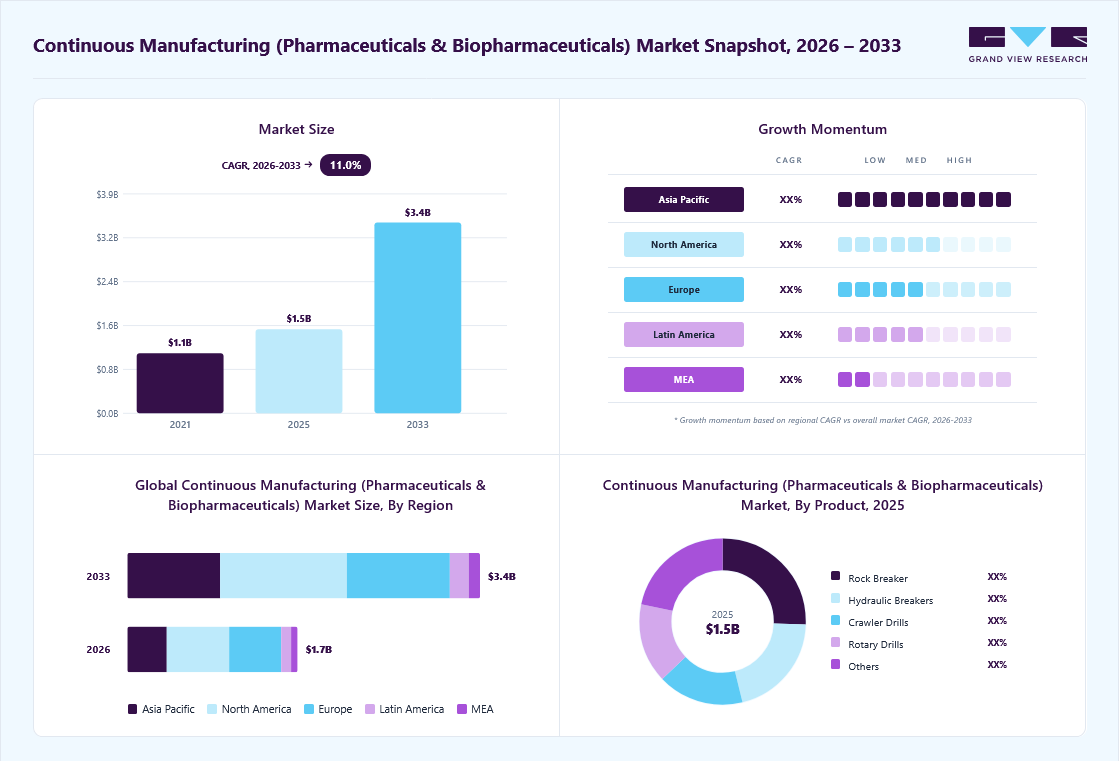
The global continuous manufacturing (pharmaceuticals & biopharmaceuticals) market size was valued at USD 1.5 billion in 2025 and is projected to grow from USD 1.7 billion in 2026 to USD 3.4 billion by 2033, at a CAGR of 11.0% from 2026 to 2033. North America dominated the market, accounting for the revenue share of 36.8% in 2025.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By therapeutic type: Large molecules segment held the largest market share of 79.5% in 2025.
- By application: End product manufacturing segment held the largest market share of 53.7% in 2025.
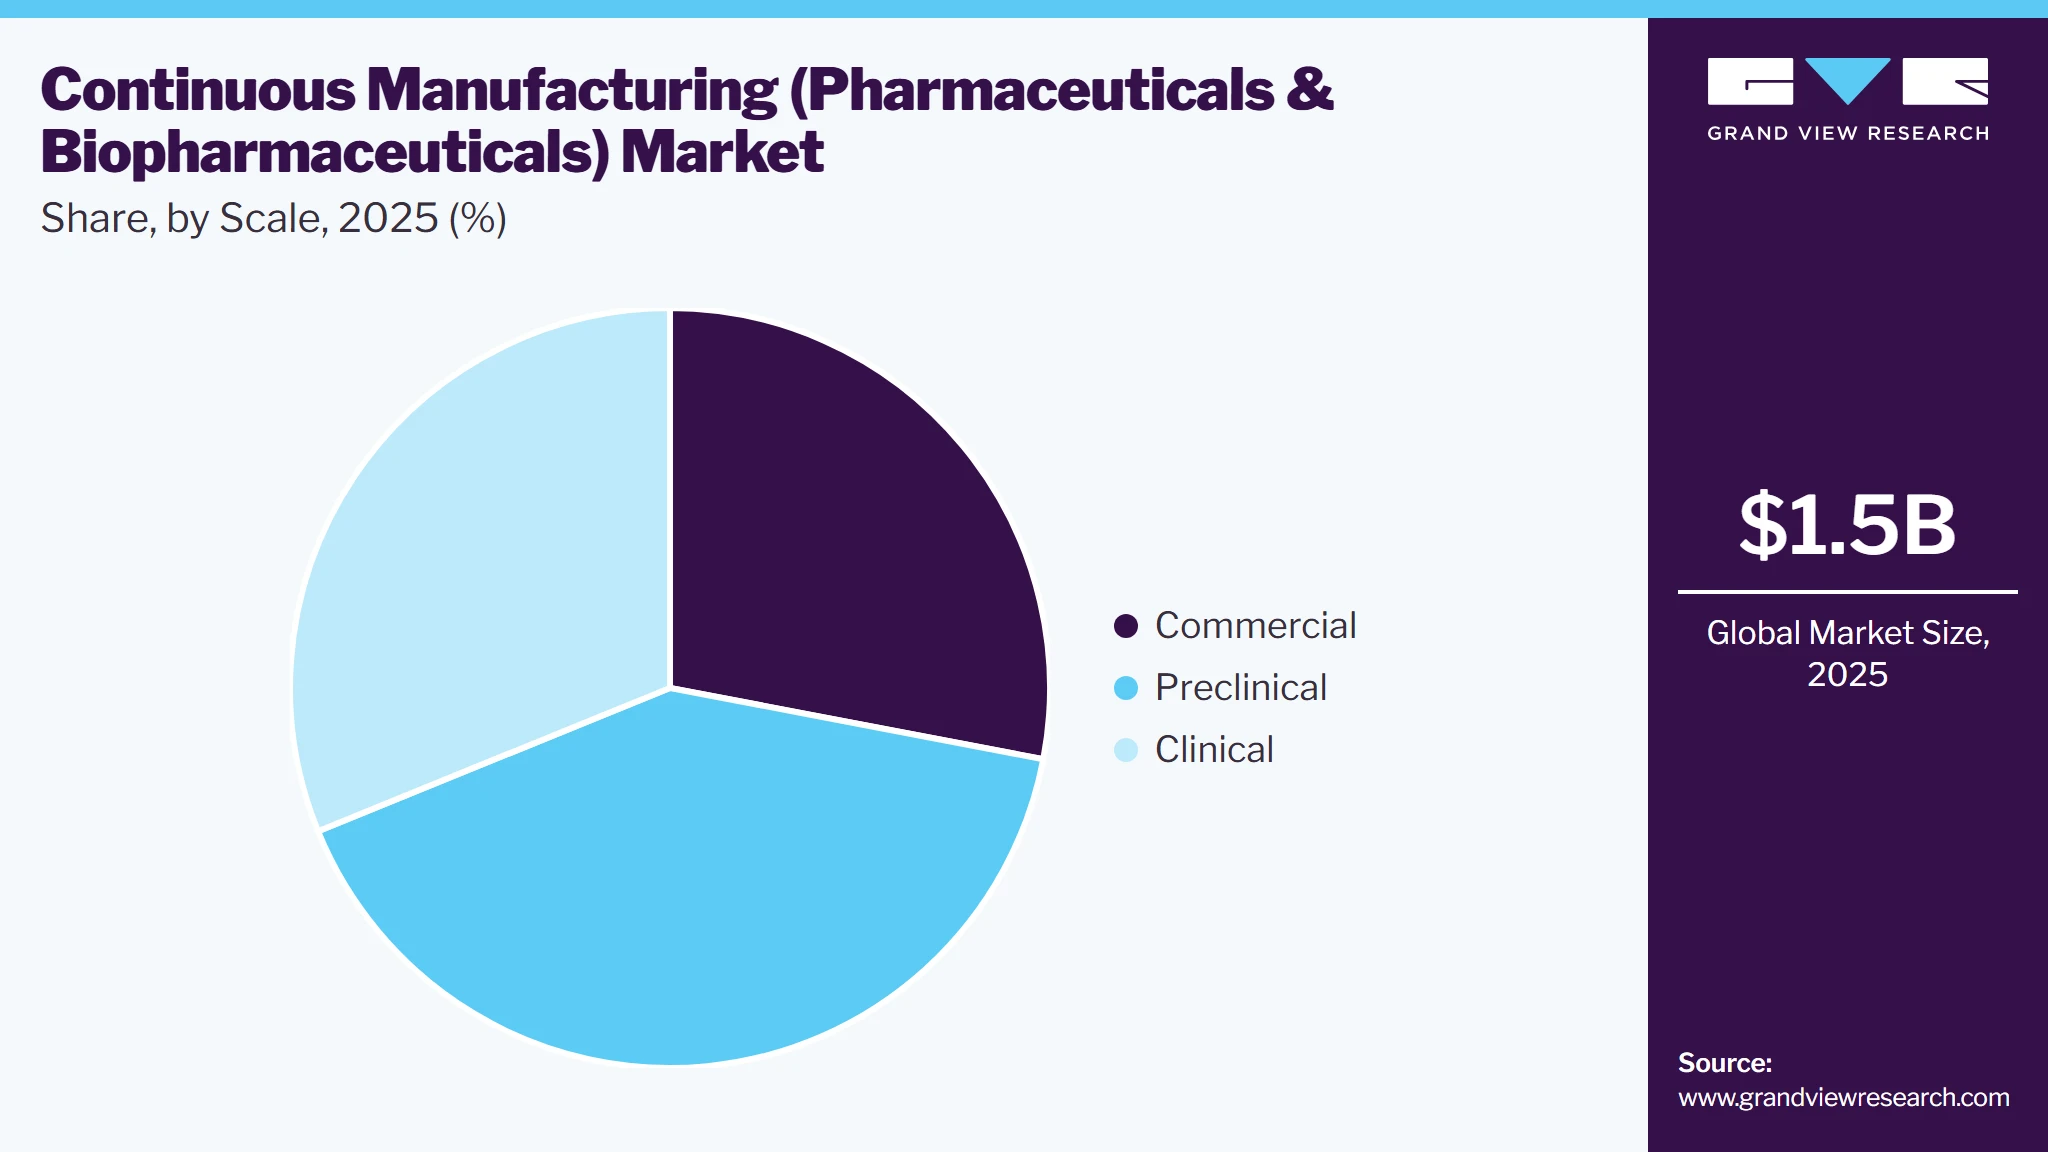
- By scale: Preclinical segment held the largest market share of 40.9% in 2025.
- By mode: Contract segment held the largest market share of 59.6% in 2025.
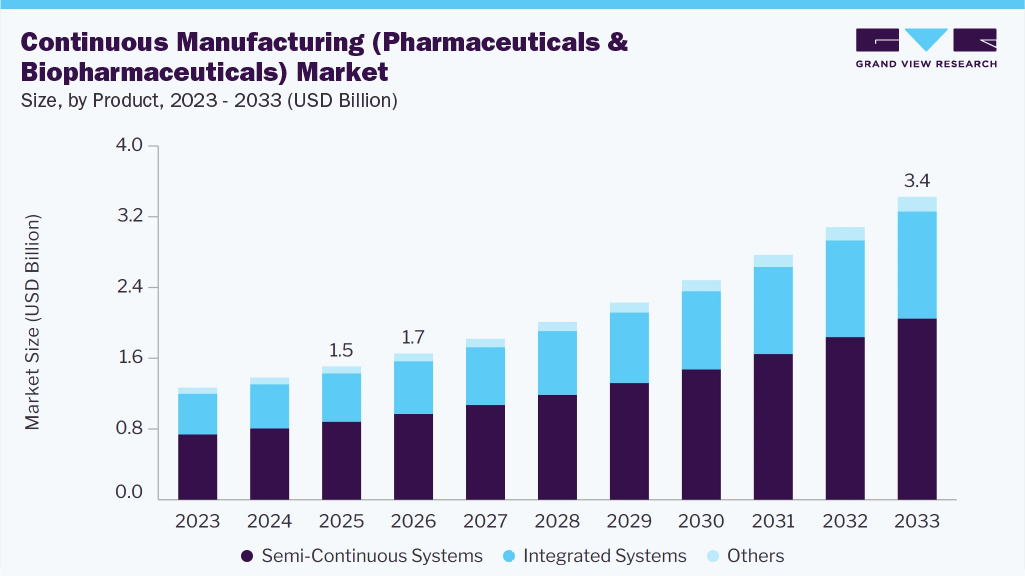
- By product: Semi-continuous systems segment held the largest market share of 58.5% in 2025.
- By formulation: Solid dosage manufacturing segment held the largest market share of 66.3% in 2025.
Regional Highlights
- Largest regional market: North America (36.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. dominated North America with the largest revenue share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.5 Billion
- Estimated market size in 2026: USD 1.7 Billion
- Projected market size by 2033: USD 3.4 Billion
- CAGR (2026-2033): 11.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market growth is driven by regulatory support for advanced manufacturing technologies, including ICH Q13 and the U.S. FDA Advanced Manufacturing Technologies designation program, the need to cut manufacturing cost, footprint, and time-to-market, and growing investment by drug makers and CDMOs in continuous API synthesis, continuous oral solid dose lines, and intensified biologics processing.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The continuous manufacturing (pharmaceuticals & biopharmaceuticals) market is experiencing steady growth as manufacturers move from batch processing to integrated and semi-continuous production to improve product quality, shorten development timelines, and reduce operating costs. Continuous processes combined with process analytical technology (PAT) allow real-time monitoring and control, smaller facility footprints, and faster scale-up, while regulators in the U.S., Europe, and Japan have established clear pathways for their adoption. In addition, rising investment by CDMOs in continuous flow chemistry, continuous direct compression, and intensified bioprocessing is supporting market growth.
Regulatory support for advanced manufacturing is driving the continuous manufacturing (pharmaceuticals & biopharmaceuticals) market, as agencies provide harmonized guidance and faster review pathways for companies adopting these technologies. The ICH Q13 guideline sets out scientific and regulatory expectations for continuous manufacturing of drug substances and drug products, and in December 2024, the U.S. FDA issued final guidance on its Advanced Manufacturing Technologies (AMT) designation program, offering early engagement and prioritized assessment for eligible technologies. According to an FDA official in May 2026, 17 drugs had been approved using continuous manufacturing, and 72 continuous manufacturing technologies had been accepted into the agency's Emerging Technology Program.
In addition, continuous manufacturing offers clear operational advantages over conventional batch processing, including consistent product quality, lower material and energy use, and a smaller manufacturing footprint. A comparison of batch, semi-continuous, and integrated continuous manufacturing highlights differences in process flow, quality control, scale-up, and flexibility.
Comparison of Batch And Continuous Manufacturing Approaches
Feature
Batch Manufacturing
Semi-Continuous Manufacturing
Integrated Continuous Manufacturing
Process flow
Discrete steps withhold times between unit operations
Selected unit operations (e.g., granulation, drying) run continuously
All unit operations linked in one uninterrupted line
Quality control
End-of-batch testing; limited in-process data
In-process monitoring for continuous steps
Real-time release supported by PAT and advanced process control
Scale-up
Requires larger equipment and re-validation
Partly addressed by longer run times
Volume adjusted by run time on the same equipment
Footprint & cost
Large facilities, high inventory of intermediates
Moderate reduction in space and inventory
Smallest footprint, lower material, energy, and labor use
Flexibility
High for multi-product sites; slow changeover
Moderate
Lower product flexibility, high capital cost, and integration complexity
Source: U.S. FDA, Secondary Research, Grand View Research Analysis
High upfront investment and the complexity of integrating equipment, PAT, and control systems may restrain the continuous manufacturing (pharmaceuticals & biopharmaceuticals) market, particularly for companies with existing, fully depreciated batch facilities. Moving a product from batch to continuous processing also requires new process development, validation, and regulatory filings, which many manufacturers find difficult to justify for legacy products. As a result, adoption remains concentrated in a limited number of products; according to the U.S. Pharmacopeia, only a little more than 15 drug products were being manufactured using continuous manufacturing as of mid-2025, despite strong interest across the industry. The perceived need for highly trained staff to run continuous lines is a further barrier, particularly for smaller manufacturers.
The extension of continuous processing to biologics, mRNA, and other advanced modalities is creating opportunities for the continuous manufacturing (pharmaceuticals & biopharmaceuticals) market. Intensified and continuous bioprocessing, including perfusion cell culture and multi-column chromatography, can increase productivity and reduce facility size for monoclonal antibodies and other proteins. For instance, in January 2025, ReciBioPharm received a three-year grant from the Bill & Melinda Gates Foundation to deploy continuous RNA manufacturing in low- and middle-income countries, building on a process that cut mRNA production time from 21-25 days to 5 days. Such initiatives are expected to open new applications for continuous systems beyond small-molecule oral solid-dose manufacturing.
Market Concentration & Characteristics
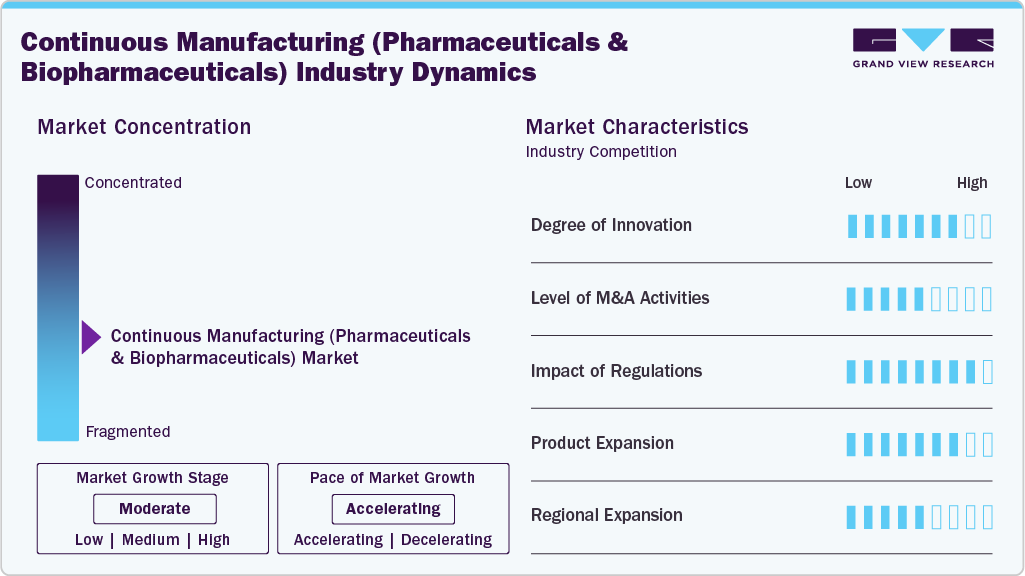
The degree of innovation in the global market is high, driven by advances in flow chemistry, modular processing equipment, real-time analytics, and AI-driven process control. For instance, in September 2026, the European PIPAC consortium, including De Dietrich, Alysophil, Bruker, and Novalix, validated a continuous manufacturing platform for active pharmaceutical ingredients that integrates continuous-flow chemistry, real-time analytical monitoring, and AI-based process control. In the same month, SK Pharmteco launched its Catalyst Kit, a structured program that guides companies from catalyst screening to commercial-scale continuous manufacturing using fixed-bed reactor technology.
The industry is witnessing moderate M&A activity, as suppliers acquire technologies that support process monitoring and control in continuous and intensified processes.
“Repligen's leadership in commercializing innovative solutions that advance bioprocessing is a great fit for our novel desktop devices.”
- Kevin J. Knopp, CEO and Co-founder, 908 Devices
 To learn more about this report, Download Free Sample Report
The global market is strongly influenced by regulatory frameworks that define how continuous processes are developed, controlled, and approved. The ICH Q13 guideline, adopted by regulators in the U.S., Europe, and Japan, provides a common basis for batch definition, process control, and lifecycle management
The continuous manufacturing industry in pharmaceuticals & biopharmaceuticals is witnessing product expansion as suppliers introduce platforms that make continuous processing easier to develop and scale. For instance, in February 2026, DFE Pharma launched a continuous manufacturing platform at its C2F Center of Excellence in Hyderabad, India, developed with Gericke, combining CM-enabled excipients, a Gericke Formulation Skid for non-GMP testing, and analytical support in line with ICH Q13.
“Continuous Manufacturing is reshaping how medicines are developed and produced, but success depends on making the right choices at every stage.”
- Sven Abend, CEO, DFE Pharma
The market is witnessing regional expansion as CDMOs and suppliers add continuous processing capacity and training infrastructure outside their home markets. For instance, in August 2025, Asymchem commissioned a new flow chemistry suite at its Sandwich, UK, facility, and in September 2026, Sartorius and the National Institute for Bioprocessing Research and Training (NIBRT) announced a dedicated training center for intensified and continuous bioprocessing in Dublin, Ireland, expected to train more than 1,000 professionals annually.
“We will give biopharma professionals the chance to gain first-hand experience with cutting-edge technologies that drive process efficiency.”
- Darrin Morrissey, CEO, NIBRT
Analyst Perspective
The continuous manufacturing (pharmaceuticals & biopharmaceuticals) market is expected to witness steady growth, supported by clear regulatory pathways under ICH Q13 and FDA advanced manufacturing programs, the need to lower manufacturing cost and footprint, and growing CDMO investment in continuous processing. Semi-continuous systems remain the entry point for most manufacturers, while integrated lines are gaining ground for high-volume products. Adoption at commercial scale is expected to grow fastest as more continuously manufactured drugs reach the market. Market participants are focusing on modular equipment, PAT and advanced process control, partnerships with CDMOs, and workforce training to make continuous manufacturing easier to adopt.
Therapeutics Type Insights
The large molecules segment dominated the market, with the largest revenue share of 79.5% in 2025, supported by the widespread use of perfusion cell culture, continuous chromatography, and integrated downstream processing in the manufacture of monoclonal antibodies and other biologics. High product value and the need to increase output from existing facilities make intensified and continuous processing attractive for biologics developers. For instance, in September 2026, Sartorius and NIBRT announced a training center equipped with Sartorius's Pionic platform to prepare engineers and operators for intensified and continuous bioprocessing.
The small molecules segment accounted for a revenue share of 20.5% in 2025 and is expected to grow at a significant CAGR over the forecast period. Growth is supported by the established use of continuous flow chemistry for API synthesis and continuous direct compression and granulation lines for oral solid-dose products. These processes improve reaction control, yield, and scalability. For instance, in April 2026, Eurofins CDMO Alphora added custom-built continuous flow equipment to API manufacturing at its Mississauga, Canada facility, to intensify complex processes that are difficult to scale in batch mode."
Application Insights
The end product manufacturing segment led the market with the largest revenue share of 53.7% in 2025 and is expected to grow at the fastest CAGR of 11.1% over the forecast period, supported by the adoption of continuous granulation, drying, blending, and compression lines for finished dosage forms.
The API manufacturing segment is expected to grow at a significant CAGR of 10.8% during the forecast period, driven by the growing use of continuous flow chemistry to improve safety, yield, and scalability of API synthesis. For instance, in September 2026, SK Pharmteco launched a Catalyst Kit that takes customers from catalyst screening through optimization to commercial-scale continuous manufacturing of APIs.
Formulation Insights
The solid dosage manufacturing segment accounted for the largest revenue share of 66.3% in 2025, as tablets and capsules were the first products approved using continuous manufacturing and remain the main application for continuous granulation, drying, and compression equipment. Launches such as L.B. Bohle's QbCon 1 continuous granulation and drying system, showcased at INTERPHEX in April 2025, are supporting adoption from development to commercial scale.
The liquid dosage manufacturing segment is expected to grow at the fastest CAGR of 10.9% over the forecast period, driven by the adoption of continuous processing for biologics, parenteral products, and liquid formulations, as well as growing interest in continuous RNA manufacturing.
Scale Insights
The preclinical segment dominated the market with the largest revenue share of 40.9% share in 2025, making it the leading scale segment, as drug developers increasingly build continuous processes early in development to avoid later process changes. Regulators encourage this approach; in May 2026, an FDA official advised companies to begin engaging with the agency early in the development process, even before a drug candidate has been identified.
 To learn more about this report, Download Free Sample Report
The commercial segment is projected to grow at the fastest CAGR of 16.0% during the forecast period, supported by a growing number of approved products made using continuous processes and the move of products from clinical to commercial continuous production. For instance, Thermo Fisher Scientific's Greenville, North Carolina facility moved its first continuously manufactured product from clinical to commercial production in 2025.
Mode Insights
The contract segment led the market with the largest revenue share of 59.6% in 2025 and is expected to grow at the fastest CAGR of 11.1% over the forecast period, as many drug developers prefer to access continuous manufacturing capacity through CDMOs rather than invest in dedicated lines. CDMOs such as Hovione, Asymchem, and SK pharmteco are expanding continuous tableting and flow chemistry capabilities to serve this demand.
The in-house segment is expected to grow at a significant CAGR of 10.8% during the forecast period, supported by large pharmaceutical companies that are converting high-volume products to continuous processes in their own facilities to lower cost and strengthen supply chain resilience.
Product Insights
The semi-continuous systems segment led the market with the largest revenue share of 58.5% in 2025 and is expected to grow at the fastest CAGR of 11.3% over the forecast period, as manufacturers often adopt continuous unit operations step by step before investing in fully integrated lines. Within this segment, continuous granulators held the largest share of 29.6% in 2025, supported by launches such as L.B. Bohle's QbCon 1, which combines dosing, twin-screw wet granulation, and drying in one module.
The integrated systems segment is expected to grow at a significant CAGR of 10.6% during the forecast period, driven by end-to-end continuous lines that support real-time release and by platforms such as GEA's ConsiGma range, which link feeding, blending, granulation, drying, and compression.
Regional Insights
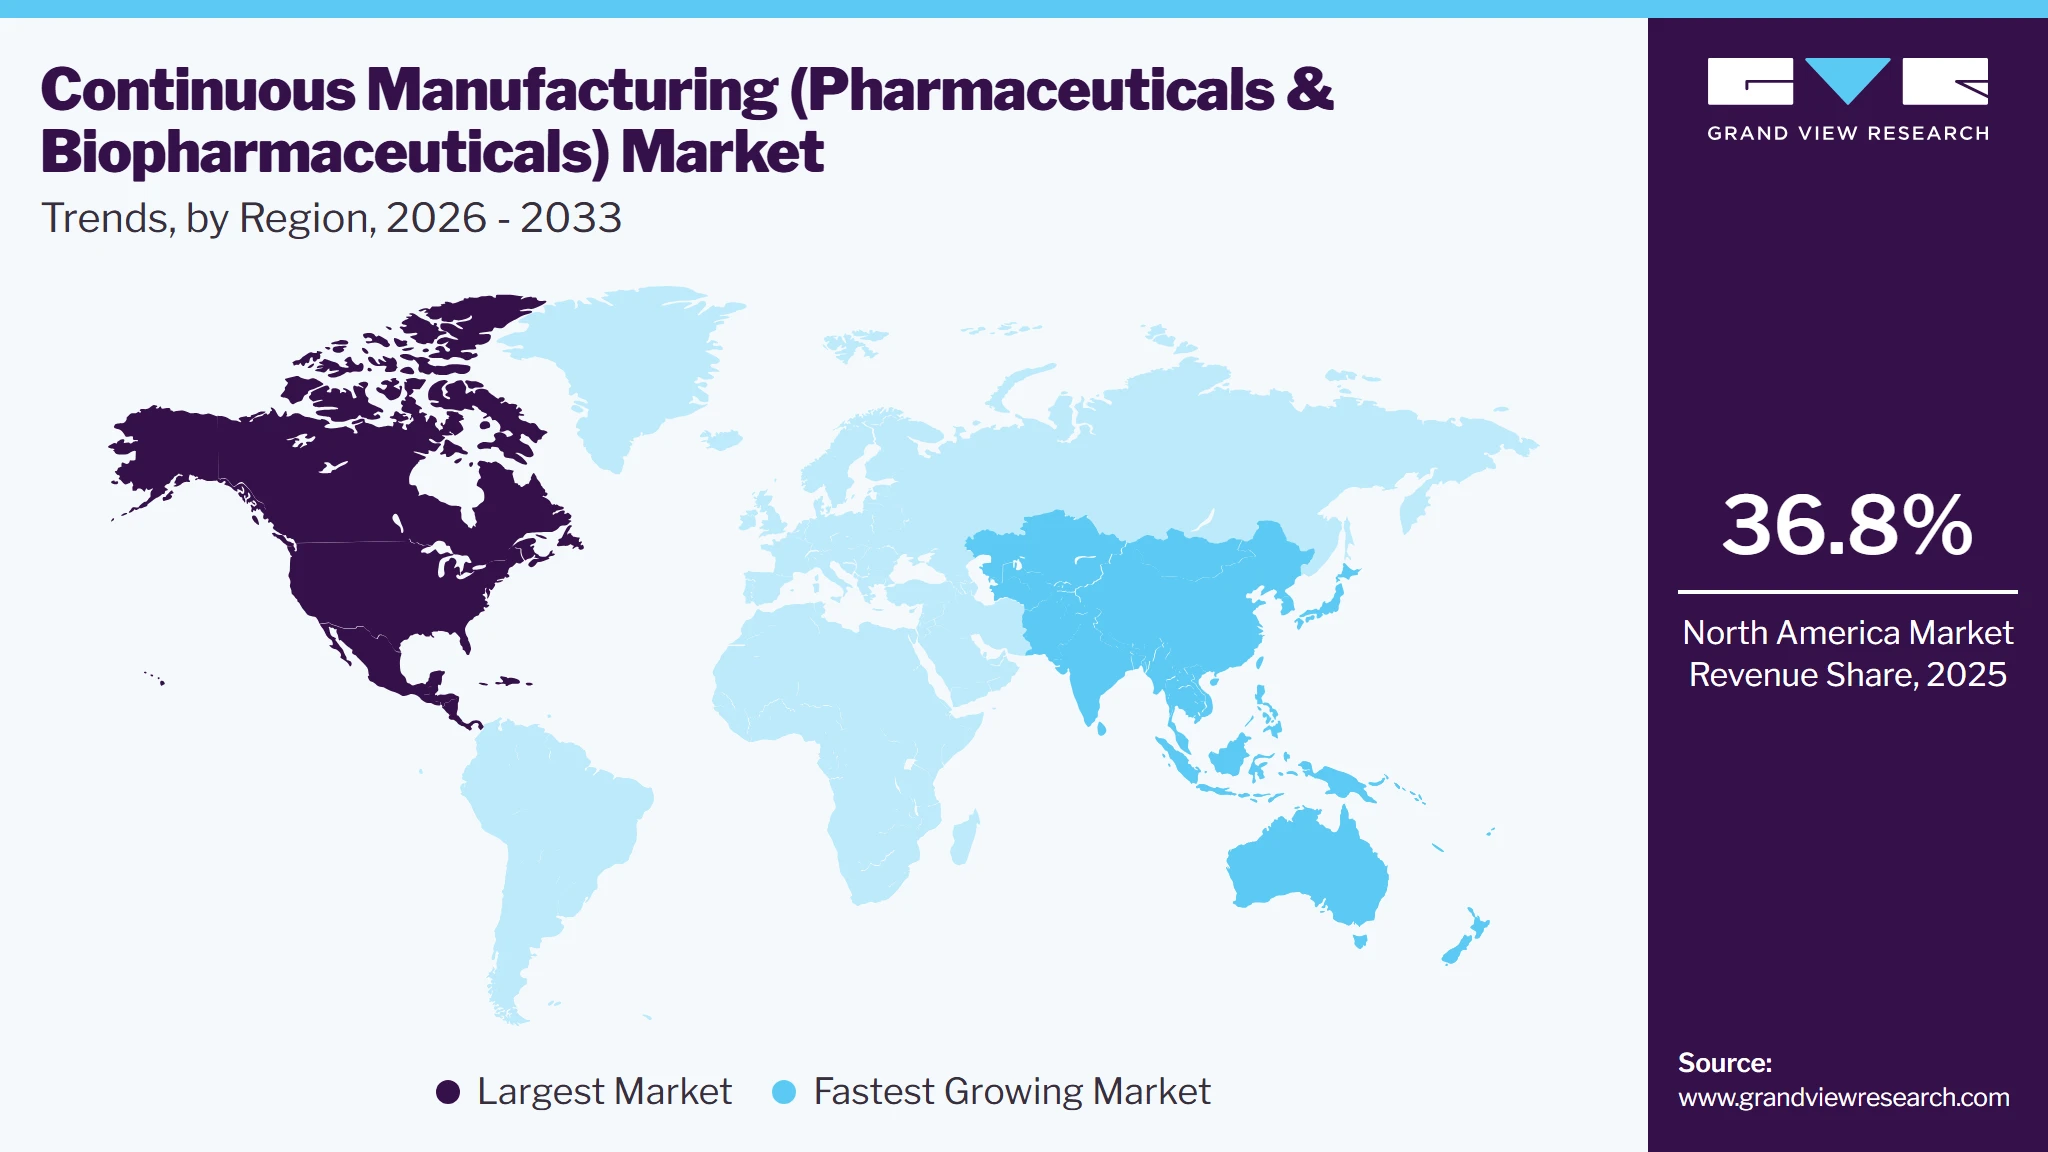
The North America continuous manufacturing (pharmaceuticals & biopharmaceuticals) market held the largest revenue share of 36.8% in 2025, supported by the presence of major pharmaceutical companies and equipment suppliers, a large number of products approved using continuous manufacturing, and active FDA programs for emerging and advanced manufacturing technologies.
 To learn more about this report, Download Free Sample Report
U.S. Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Trends
The continuous manufacturing market for pharmaceuticals & biopharmaceuticals in the U.S. accounted for the largest revenue share in North America in 2025, supported by FDA initiatives that encourage the adoption of advanced manufacturing. According to an FDA official in May 2026, the agency's Emerging Technology Program had accepted 191 applications, including 72 continuous manufacturing technologies, and 17 drugs had been approved using continuous manufacturing.
Europe Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Trends
The continuous manufacturing (pharmaceuticals & biopharmaceuticals) market in Europe is anticipated to grow significantly over the forecast period, supported by a strong base of equipment suppliers, research consortia, and bioprocessing training infrastructure. For instance, in September 2026, the PIPAC consortium of De Dietrich, Alysophil, Bruker, and Novalix demonstrated a continuous manufacturing platform for active pharmaceutical ingredients combining continuous-flow chemistry, real-time analytics, and AI-based process control.
The UK continuous manufacturing (pharmaceuticals & biopharmaceuticals) market is expected to grow over the forecast period, driven by investment in flow chemistry and advanced medicines manufacturing capabilities. For instance, in August 2025, Asymchem commissioned a new flow chemistry suite at its Sandwich, UK, facility, equipped with plug-flow reactors and heterogeneous hydrogenation, biocatalysis, and Grignard reaction platforms, with plans for future pilot- and commercial-scale expansion.
The Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market in Germany is anticipated to grow significantly over the forecast period, supported by the presence of leading equipment manufacturers such as GEA, Glatt, and L.B. Bohle. For instance, the GEA and Hovione ConsiGma CDC Flex continuous direct compression platform was showcased at CPHI Frankfurt in October 2025, and L.B. Bohle, headquartered in Ennigerloh, offers the QbCon 1 system for continuous granulation and drying, available in high-containment configurations up to OEB 5.
Asia Pacific Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Trends
The continuous manufacturing (pharmaceuticals & biopharmaceuticals) market in the Asia Pacific is expected to grow at the fastest CAGR of 13.0% during the forecast period, supported by expanding pharmaceutical manufacturing, growing CDMO capacity, and rising adoption of advanced manufacturing technologies. For instance, in February 2026, DFE Pharma launched a continuous manufacturing platform at its Center of Excellence in Hyderabad, India, to help pharmaceutical companies develop, optimize, and manage continuous processes.
The China continuous manufacturing (pharmaceuticals & biopharmaceuticals) market is expected to grow substantially over the forecast period, supported by the country's large API manufacturing base and the use of continuous flow chemistry by leading CDMOs. China-based Asymchem has built extensive flow chemistry capabilities and is extending them to its international sites, reflecting the growing role of Chinese CDMOs in continuous API manufacturing.
The continuous manufacturing (pharmaceuticals & biopharmaceuticals) market in Japan is expected to grow steadily, supported by regulatory and industry initiatives to promote advanced manufacturing. The Pharmaceuticals and Medical Devices Agency (PMDA) has established an Innovative Manufacturing Technology Working Group to address continuous manufacturing, and the industry-led Consortium on Continuous Pharmaceutical Manufacturing in Japan supports its adoption by domestic drug makers.
Latin America Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Trends
The Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market in Latin America is expected to grow steadily over the forecast period, supported by the modernization of pharmaceutical manufacturing in Brazil and Argentina, growing local production of generics and biosimilars, and increasing interest in technologies that improve quality and reduce production costs.
MEA Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Trends
The Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market in the Middle East & Africa is growing steadily, supported by the localization of pharmaceutical and biologics manufacturing under national industrial strategies. For instance, in August 2025, MS Pharma inaugurated a USD 50 million biologics manufacturing facility in Saudi Arabia, the region's first SFDA-approved biologics facility, supporting demand for advanced manufacturing technologies in the region.
“This launch is a defining milestone for MS Pharma and the MENA biopharmaceutical landscape.”
- Ghiath Sukhtian, Chairman, MS Pharma
Key Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Company Insights
The market is moderately fragmented, with established equipment suppliers, bioprocessing companies, and CDMOs competing alongside specialized technology providers. Leading players include Thermo Fisher Scientific Inc., Danaher Corporation (Pall, Cytiva), GEA Group AG, Sartorius Stedim Biotech S.A., Merck KGaA, Repligen Corporation, Glatt GmbH, L.B. Bohle Maschinen und Verfahren GmbH, Lonza Group AG, and Corning Incorporated. These companies focus on integrated continuous lines, modular semi-continuous equipment, process analytical technology, and contract manufacturing services, and are expanding through product launches, partnerships with CDMOs, acquisitions, and training initiatives that make continuous processing easier to adopt.
Key Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Companies
The following key companies have been profiled for this study on the continuous manufacturing (pharmaceuticals & biopharmaceuticals) market.
-
Thermo Fisher Scientific Inc.
-
Danaher Corporation (Pall, Cytiva)
-
GEA Group AG
-
Sartorius Stedim Biotech S.A.
-
Merck KGaA
-
Repligen Corporation
-
Glatt GmbH
-
L.B. Bohle Maschinen und Verfahren GmbH
-
Lonza Group AG
-
Corning Incorporated
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Thermo Fisher Scientific Inc., Danaher Corporation, GEA Group AG, Sartorius Stedim Biotech S.A., Merck KGaA)
- Expanding integrated continuous lines, intensified bioprocessing platforms, and PAT, supported by partnerships with CDMOs and acquisitions of complementary technologies.
- Broad portfolios covering equipment, consumables, and software, global service networks, and long-standing relationships with large drug makers.
- High system cost and long sales cycles; continuous manufacturing is a small share of overall revenue for most of these players.
Emerging Players (Repligen Corporation, Glatt GmbH, L.B. Bohle Maschinen und Verfahren GmbH, Lonza Group AG, Corning Incorporated)
- Focusing on specialized unit operations, flow reactors, perfusion systems, and contract continuous manufacturing services.
- Deep process expertise in specific unit operations, flexibility, and ability to customize systems for individual products.
- Narrower portfolios and smaller scale than large suppliers; dependence on a limited number of customers and projects.
Recent Developments
-
In September 2026, Sartorius and the National Institute for Bioprocessing Research and Training (NIBRT) announced a partnership to establish a dedicated training center for intensified and continuous bioprocessing in Dublin, Ireland. The center, equipped with Sartorius's Pionic platform, is scheduled to open in Q4 2026 and is expected to train more than 1,000 professionals annually.
“Training current and future engineers and operators is critical to making the change a reality.”
- René Fáber, Head of Bioprocess Solutions Division, Sartorius
-
In December 2025, GEA and Hovione introduced the ConsiGma CDC Flex, a next-generation continuous direct compression platform that runs in low- and high-throughput continuous modes or in batch mode, with a production capacity of 1-200 kg/h and R&D batches as small as 1.5 kg.
“The CDC Flex is designed to be a truly multipurpose system, capable of low-throughput and high-throughput production within one integrated platform.”
- Dr. Jim Holman, Senior Director of Technology Management, GEA Pharma Solids-
In March 2025, Repligen purchased the bioprocessing analytics portfolio of 908 Devices, including the MAVERICK, MAVEN, REBEL, and ZipChip technologies, for USD 70 million in cash, adding real-time upstream process monitoring and control to its downstream analytics portfolio.
“They are the perfect complement to our downstream analytics portfolio and will enable Repligen to further penetrate a broad set of modalities.”
- Olivier Loeillot, President and CEO, Repligen
Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.5 billion
Estimated market size in 2026
USD 1.7 billion
Projected market size by 2033
USD 3.4 billion
Growth rate
CAGR of 11.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Therapeutics type, application, formulation, scale, mode, product, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
Thermo Fisher Scientific Inc.; Danaher Corporation (Pall, Cytiva); GEA Group AG; Sartorius Stedim Biotech S.A.; Merck KGaA; Repligen Corporation; Glatt GmbH; L.B. Bohle Maschinen und Verfahren GmbH; Lonza Group AG; Corning Incorporated
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Continuous Manufacturing (Pharmaceuticals & Biopharmaceuticals) Market Report Segmentation
This report forecasts revenue growth and provides an analysis on the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global continuous manufacturing (pharmaceuticals & biopharmaceuticals) market report based on the therapeutic type, application, formulation, scale, mode, product, and region:
-
Therapeutics Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Large Molecules
-
Small Molecules
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
End Product Manufacturing
-
API Manufacturing
-
-
Formulation Outlook (Revenue, USD Billion, 2021 - 2033)
-
Solid Dosage Manufacturing
-
Liquid Dosage Manufacturing
-
-
Scale Outlook (Revenue, USD Billion, 2021 - 2033)
-
Preclinical
-
Clinical
-
Commercial
-
-
Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
Contract
-
In-house
-
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Semi-Continuous Systems
-
Continuous Granulators
-
Other Semi-Continuous Systems
-
Continuous Dryers
-
Continuous Coaters
-
Continuous Blenders
-
Continuous Compressors
-
-
Integrated Systems
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The continuous manufacturing (pharmaceuticals & biopharmaceuticals) market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each continuous manufacturing (pharmaceuticals & biopharmaceuticals) segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Therapeutics Type
Revenue Capture Definition
Large Molecules
Revenue generated from continuous and intensified systems used to manufacture biologics such as monoclonal antibodies, recombinant proteins, vaccines, and nucleic acid products, including perfusion and continuous downstream processing.
Small Molecules
This segment captures income from continuous systems used to manufacture chemically synthesized drugs, including flow chemistry for APIs and continuous oral solid dose lines.
Segment- Application
Revenue Capture Definition
End Product Manufacturing
Revenue generated from continuous systems used to produce finished dosage forms, including granulation, drying, blending, compression, and coating.
API Manufacturing
Market value in this category stems from continuous systems used for drug substance synthesis, purification, and isolation.
Segment- Formulation
Revenue Capture Definition
Solid Dosage Manufacturing
Revenue generated from continuous systems used to manufacture tablets, capsules, and other solid dosage forms.
Liquid Dosage Manufacturing
This segment captures income from continuous systems used to manufacture liquid, semi-solid, and parenteral formulations.
Segment- Scale
Revenue Capture Definition
Preclinical
Revenue generated from continuous systems used in process development and preclinical manufacturing.
Clinical
This segment captures income from continuous systems used to supply clinical trial material.
Commercial
Market value in this category stems from continuous systems used for commercial-scale production of approved drugs.
Segment- Mode
Revenue Capture Definition
Contract
Revenue generated from continuous systems operated by contract development and manufacturing organizations (CDMOs) and contract manufacturers.
In-house
This segment captures income from continuous systems operated by drug makers in their own facilities.
Segment- Product
Revenue Capture Definition
Semi-Continuous Systems
Revenue generated from stand-alone continuous unit operations, including continuous granulators, blenders, compressors, coaters, dryers, and other semi-continuous systems.
Integrated Systems
This segment captures income from end-to-end continuous manufacturing lines that link multiple unit operations with integrated control and PAT.
Others
Market value in this category stems from other continuous manufacturing systems and related equipment not covered above.
Estimation Model
Category
Title
Description
Top-Down
Commodity Flow Analysis
Market value was estimated by assessing revenues from integrated continuous manufacturing lines, semi-continuous systems such as continuous granulators, blenders, compressors, coaters and dryers, and related continuous processing equipment for small and large molecules. Company financials, product portfolios, installed base, pricing, and commercial offerings were analyzed to quantify market revenue across therapeutics type, application, formulation, scale, and mode.
Benchmark
Secondary Source & Company Share Benchmarking
Published estimates for the continuous manufacturing market were compiled, normalized to a common base year, and compared with company share analysis of leading equipment and bioprocessing suppliers. Adoption of continuous processing across API synthesis, oral solid dose, and biologics manufacturing was evaluated to establish the addressable opportunity.
Segmentation
Country-Level Segment Share Modeling
Country-level shares were estimated using pharmaceutical and biopharmaceutical manufacturing output, installed continuous manufacturing capacity, CDMO activity, regulatory support for advanced manufacturing, and capital investment in new facilities. Differences in drug development pipelines, manufacturing modernization, and technology adoption were incorporated to determine country and regional distributions across all segments.
Validation
Data Triangulation & Validation Model
Market estimates were reconciled using company revenues, equipment installations, published secondary estimates, pricing, and facility investments. The results were cross-checked across product, therapeutics type, application, scale, mode, country, and region to ensure consistency between supply-side and demand-side calculations.
Forecasting
Forecasting & CAGR Modeling
Future demand was projected using approvals of continuously manufactured drugs, adoption of ICH Q13, investment in advanced manufacturing facilities, CDMO capacity additions, and the move of pipelines from clinical to commercial scale. Wider use of process analytical technology was incorporated into segment-level growth assumptions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Batch-to-Continuous Cost & ROI Analysis
Comparison of capital, operating, and validation costs for batch and continuous lines across API, oral solid dose, and biologics processes.
Helps clients build investment cases and prioritize products for conversion to continuous manufacturing.
Equipment & Technology Benchmarking
Assessment of integrated lines and semi-continuous systems (granulators, blenders, compressors, coaters, dryers) by throughput, containment, PAT integration, and price.
Helps clients select suppliers and technologies aligned with their product portfolio and scale requirements.
Regulatory Pathway & Adoption Assessment
Review of ICH Q13, FDA AMT designation, EMA, and PMDA requirements and approvals of continuously manufactured products.
Helps clients plan filings, reduce regulatory risk, and benchmark adoption against peers.
Frequently Asked Questions About This Report
The global continuous manufacturing market in pharmaceuticals and biopharmaceuticals size was estimated at USD 919.7 million in 2020 and is expected to reach USD 1.07 billion in 2021.
The global continuous manufacturing market in pharmaceuticals and biopharmaceuticals is expected to grow at a compound annual growth rate of 13.8% from 2021 to 2027 to reach USD 2.3 billion by 2027.
Pharmaceuticals/small molecule dominated the continuous manufacturing market in pharmaceuticals and biopharmaceuticals with the largest share of 76% in 2020. This is attributable to the increasing shift in focus from batch processing to continuous manufacturing for drug development.
Some key players are Thermo Fisher Scientific, Inc., Danaher Corporation, Applikon Biotechnology, Sartorius SA, GEA Group aktiengesellschaft, Corning Incorporated, Merck KGaA, Repligen Corporation, Eppendorf AG, Electrolab Biotech Ltd, Solesis medical, and Lonza Group AG.
Key factors driving the continuous manufacturing market in pharmaceuticals and biopharmaceuticals growth include rising demand for biologics; increasing investment in biotherapeutics R&D, and rising market competition to gain maximum revenue share in the market.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


