
- Home
- »
- IT Services & Applications
- »
-
Data Preparation Tools Market Size Report, 2026-2033GVR Report cover

Data Preparation Tools Market (2026 - 2033)
Size, Share & Trends Analysis Report By Platform (Self Service, Data Integration), By Deployment (On-premise, Cloud), By Functions (Data Collection, Data Cataloging, Data Quality), By Vertical, By Region, And Segment Forecasts
Market Size, 2025
$8.5BMarket Estimate, 2026
$9.6BMarket Forecast, 2033
$21.3BCAGR, 2026–2033
12.0%Data Preparation Tools Market Summary
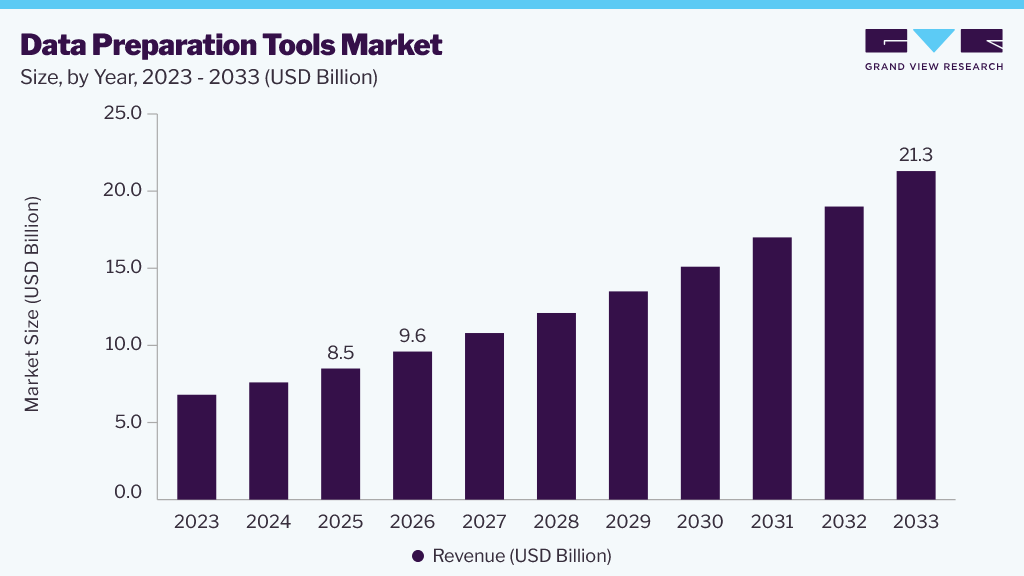
The global data preparation tools market was valued at USD 8.5 billion in 2025 and is projected to grow from USD 9.6 billion in 2026 to USD 21.3 billion in 2033, at a CAGR of 12.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.0% in 2025. Data preparation tools are mainly used for combining data from multiple sources and preparing the data for analysis.
Key Market Trends & Insights
- By platform: The data integration segment led the market with the largest revenue share of around 52.0% in 2025.
- By deployment: The cloud segment led the market with the largest revenue share of around 53.5% in 2025.
- By functions: The data cataloging segment is expected to grow at a CAGR of over 14.5% during the forecast period.
- By vertical: The IT and telecom segment is expected to grow at a CAGR of over 14.0% during the forecast period.
Regional Highlights
- Largest regional market: North America (34.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 8.5 Billion
- Estimated market size in 2026: USD 9.6 Billion
- Projected market size by 2033: USD 21.3 Billion
- CAGR (2026-2033): 12.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Data preparation tools have been in the market for a long time; however, there was a high need for expert assistance earlier. Data preparation finds greater acceptance in data-driven markets such as Information Technology (IT) and Banking, Financial Services, and Insurance (BFSI). These tools' primary function is to efficiently find the right data at the right time.Demand for self-service data preparation tools is increasing rapidly as enterprises and organizations continue to adopt advanced analytics and Business Intelligence (BI) platforms. Adopting a combination of a cloud platform and a self-service data preparation platform is a growing trend among data-driven IT companies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The rising demand for data analytics is expected to augment the demand for cloud-based data preparation tools in various data-driven verticals. In addition, a rising focus on the self-service platform is anticipated to enhance the operations within the organizations. It is expected to propel the demand for data preparation tools. The rising demand for analytics in enterprises has encouraged various data-driven organizations to invest in the research and development of the data preparation market.
The market is expected to witness a surge in technology adoption, driven by benefits such as extracting business insights from social media posts and automatically organizing untagged photo collections. Also, it helps to offer enhanced safety features in autonomous vehicles, such as emergency vehicle detection, terrain detection, wear detection, and condition monitoring, among others. Machine learning, powered by data gathering, has been embedded in several fields, such as robotics & drones, automated image organization of visual websites, and face identification on social networking websites, among others.
Market Dynamics
Data preparation tools are gaining strong traction in the global data management and analytics market, driven by their growing adoption as essential solutions for improving data quality, accessibility, and analytics readiness across organizations. These tools are widely preferred for their ability to simplify data cleansing, transformation, integration, and enrichment, helping businesses generate faster, more accurate insights for decision-making. Increasing enterprise focus on data-driven strategies, coupled with the rising adoption of cloud computing, artificial intelligence, and business intelligence platforms, is significantly boosting demand. In addition, the expansion of digital transformation initiatives and the growing need for seamless handling of large and complex datasets across industries are further strengthening market growth.
The data preparation tools market is driven by the growing focus on data-driven decision-making and the demand for high-quality, analytics-ready data in organizations. Businesses are increasingly adopting data preparation solutions to simplify data cleansing, transformation, integration, and enrichment processes. This helps achieve more accurate insights, improve operational efficiency, and speed up decision-making. The rising use of artificial intelligence (AI), machine learning (ML), business intelligence (BI), and analytics platforms has increased the need for reliable and well-structured data. According to Eurostat, 20.0% of EU enterprises with 10 or more employees used AI technologies in 2025. This marks a significant rise from 13.5% in 2024 and nearly triples from 7.7% in 2021. This rapid growth highlights the increasing use of data-driven technologies that depend on accurate and well-prepared data.
In addition, Eurostat reported that in 2025, 41% of small enterprises and 89% of large enterprises across the EU used enterprise resource planning (ERP) applications. The adoption of business intelligence software varied from 11% among small enterprises to 69% among large enterprises. The widespread use of these digital business applications shows the rising dependence on data analytics and integrated information systems for strategic decision-making. This creates a larger need for strong data preparation capabilities to ensure data quality, consistency, and usability. As enterprises continue to push digital transformation efforts and expand AI-driven operations, the demand for data preparation tools is expected to keep growing.
The data preparation tools market is restrained by concerns related to data security, privacy, and the complexity of integrating data from multiple sources. Many organizations handle sensitive business and customer information, creating challenges around regulatory compliance, governance, and secure data management. In addition, integrating legacy systems, cloud platforms, and diverse data formats often requires significant technical expertise and infrastructure investments. These complexities can increase implementation costs and slow adoption, particularly among small and medium-sized enterprises with limited IT resources.
Analyst Perspective
The data preparation tools market is supported by strong long-term growth drivers, including the rapid expansion of enterprise data volumes, increasing adoption of cloud-based analytics, and growing emphasis on data-driven decision-making across industries. Organizations are increasingly prioritizing efficient data cleansing, transformation, and integration to improve the accuracy and speed of business insights. However, the market is also influenced by challenges such as data security concerns, complex integration across legacy and modern systems, and rising regulatory compliance requirements, which can impact adoption and implementation speed. Demand for AI-driven, automated, and self-service data preparation tools is steadily increasing, particularly as enterprises focus on improving operational efficiency and enabling non-technical users to access and analyze data.
Platform Insights
The data integration segment dominated the market in 2025, accounting for around 52.0% of the total market share. This dominance is primarily driven by the increasing need for organizations to consolidate data from multiple heterogeneous sources into a unified and consistent format for advanced analytics and business intelligence. As enterprises continue to operate across hybrid IT environments, including cloud platforms, on-premises systems, and third-party applications, data integration tools have become essential for ensuring seamless data flow and real-time accessibility. The rising adoption of AI, machine learning, and self-service analytics is further strengthening the demand for efficient data integration capabilities, enabling organizations to improve decision-making speed and operational efficiency.
The self-service segment is expected to grow at the fastest CAGR of around 15.0% during the forecast period. The growth of the segment is driven by the increasing demand for user-friendly, low-code/no-code data preparation platforms that enable business users to independently access, clean, transform, and analyze data without heavy reliance on IT teams. The rising adoption of cloud-based analytics and business intelligence tools is further accelerating this shift, as organizations seek faster time-to-insight and improved operational agility. In addition, the proliferation of big data across enterprises and the need for real-time decision-making are encouraging companies to deploy self-service solutions that simplify complex data workflows.
Function Insights
The data collection segment accounted for the largest share of around 25.0% in the data preparation tools market due to the increasing volume of data generated from multiple sources such as enterprise applications, IoT devices, social media platforms, and transactional systems. Organizations are prioritizing robust data collection capabilities to ensure comprehensive data availability before processing, cleansing, and transformation activities. The rising adoption of digital business models and real-time analytics is further driving the need for continuous and automated data ingestion. In addition, growing emphasis on building centralized data pipelines and improving data accuracy at the source is strengthening the dominance of the data collection segment across industries.
The data cataloging segment is expected to experience a notable shift in demand, with a CAGR of over 14.5% over the forecast period. The increasing need for enterprises to improve data discoverability, governance, and metadata management across complex and distributed data environments is expected to drive the growth of the segment. As organizations generate large volumes of structured and unstructured data from multiple sources, data cataloging tools are becoming essential for creating a unified view of enterprise data assets and enabling efficient data search and access. The rising adoption of self-service analytics and data democratization initiatives is further accelerating demand, as business users require easy access to trusted and well-documented datasets.
Vertical Insights
Based on vertical, the IT and telecom segment led the market with the largest revenue share of around 36.5% in 2025 and is expected to grow at a CAGR of over 14.0% over the forecast period. The growth of the segment is driven by the massive generation of structured and unstructured data from network operations, customer interactions, digital services, and cloud-based applications. Organizations in this sector increasingly rely on advanced data preparation tools to process, clean, and integrate high-velocity data streams for real-time analytics, network optimization, and customer experience enhancement. The rapid adoption of 5G technology, cloud computing, and AI-driven operations is further intensifying the need for efficient data management and preparation capabilities.
The retail & e-commerce segment is experiencing significant growth during the forecast period, driven by the increasing adoption of data-driven decision-making across retail and e-commerce platforms. Retailers are leveraging advanced data preparation tools to integrate and analyze large volumes of customer, sales, and inventory data to improve demand forecasting, pricing strategies, and personalized marketing. The rapid expansion of omnichannel retailing, along with rising consumer expectations for personalized shopping experiences, is further accelerating demand for analytics-ready data.
Deployment Insights
Based on deployment, the cloud segment led the market with the largest revenue share of around 53.5% in 2025 and is expected to grow at a CAGR of over 14.5% during the forecast period. The growth of the segment can be attributed to the rapid shift of enterprises toward scalable, flexible, and cost-efficient data management solutions. Increasing adoption of cloud-based analytics platforms and the growing need for real-time data access across geographically distributed teams are further strengthening this dominance. Cloud deployment enables seamless integration with multiple data sources, faster implementation, and reduced infrastructure overhead compared to on-premise systems. In addition, the rising adoption of hybrid and multi-cloud environments, along with the growing reliance on AI and machine learning workloads, is accelerating demand for cloud-based data preparation tools across industries.
The on-premise segment is expected to witness significant growth during the forecast period, driven by increasing concerns among enterprises regarding data security, privacy, and regulatory compliance, particularly in highly regulated industries such as BFSI, healthcare, and government. Organizations handling sensitive and mission-critical data often prefer on-premise deployment to maintain greater control over their data infrastructure and reduce exposure to external cyber risks. In addition, the need for customized data architecture, legacy system compatibility, and strict internal governance policies further supports the adoption of on-premise data preparation solutions.
Regional Insights
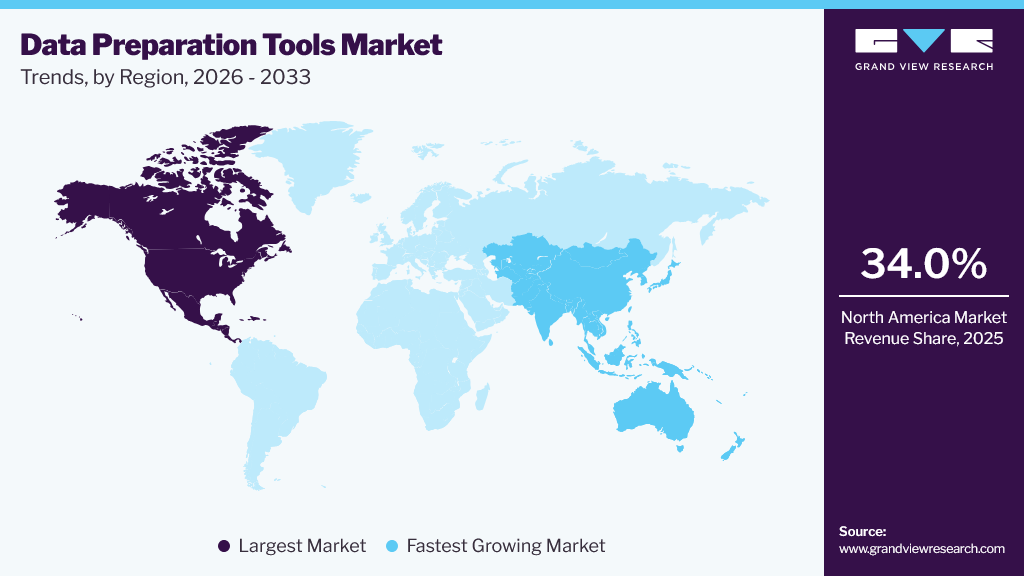
North America dominated the market with a share of around 34.0% in 2025 and is anticipated to dominate the market over the forecast period. The emphasis on self-service analytics within organizations has propelled the adoption of user-friendly data preparation solutions. These tools enable business users, data analysts, and data scientists to manipulate and prepare data without extensive technical knowledge, thereby fostering a culture of data-driven decision-making within enterprises. Moreover, the increasing complexity of data sources, including data from diverse channels, requires agile and adaptable Data Preparation Tools capable of handling various data formats and sources.
 To learn more about this report, Download Free Sample Report
Asia Pacific Data Preparation Tools Market Trends
Asia Pacific is expected to grow at the fastest CAGR of over 13.5% during the forecast period, supported by the rapid digital transformation across emerging economies such as China, India, Japan, and South Korea. The region is witnessing strong adoption of cloud computing, big data analytics, and artificial intelligence technologies, which is significantly increasing the demand for efficient data preparation solutions. According to CCI (Competition Commission of India), India is among the first group of countries ready for AI. It is making steady progress across all five layers of AI architecture including applications, models, chips, infrastructure, and energy. In addition, growing investments in smart infrastructure, rising enterprise focus on data-driven strategies, and increasing adoption of self-service analytics tools are strengthening the dominance of the Asia Pacific region in the global market.
Key Data Preparation Tools Company Insights
The competitive environment of the data preparation tools market is moderately fragmented, with the presence of global technology providers, cloud service vendors, and specialized data management and analytics companies. Key players compete based on platform scalability, automation capabilities, integration efficiency, and support for end-to-end data workflows across cloud and hybrid environments. Increasing focus on AI-driven data preparation, self-service analytics, and low-code/no-code platforms is intensifying competition. In addition, mergers, acquisitions, and strategic partnerships are gradually driving consolidation as companies expand their product portfolios and strengthen their positions across enterprise data ecosystems.
-
In January 2026, Alteryx announced the launch of a data preparation tool for Google Cloud BigQuery as part of a broader partnership with Google Cloud. The collaboration aims to improve the accessibility, usability, and AI readiness of BigQuery for business users. It does this by embedding governed analytics workflows directly into the platform. This integration helps customers transition from data to insights and actions more efficiently, while ensuring governance, trust, and scalability across their analytics operations.
-
In November 2025, Salesforce completed its acquisition of Informatica for approximately USD 8 billion, integrating Informatica’s data integration, data cataloging, governance, and Master Data Management (MDM) capabilities into its AI-powered platform.
Key Data Preparation Tools Companies:
The following key companies have been profiled for this study on the data preparation tools market.
-
SAS Institute Inc.
-
Tibco Software Inc.
-
Strategy Inc.
-
Microsoft Corporation
-
International Business Machines Corporation
-
SAP SE
-
Salesforce, Inc.
-
Qlik Technologies Inc.
-
Alteryx, Inc.
-
Oracle Corporation
Data Preparation Tools Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.5 billion
Estimated market size in 2026
USD 9.6 billion
Projected market size by 2033
USD 21.3 billion
Growth rate
CAGR of 12.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Platform, deployment, functions, vertical, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; UK; Germany; France; China; Japan; India; Australia; South Korea; Brazil; Mexico; Saudi Arabia; South Africa; UAE
Key companies profiled
SAS Institute Inc.; Tibco Software Inc.; Microsoft Corporation; International Business Machines Corporation; SAP SE; Salesforce, Inc.; Qlik Technologies Inc.; Alteryx, Inc.; Oracle Corporation; Strategy Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Data Preparation Tools Market Report Segmentation
This report forecasts revenue growth at the regional, and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global data preparation tools market report on the basis of platform, deployment, functions, vertical and region:
-
Platform Outlook (Revenue, USD Billion, 2021 - 2033)
-
Self service
-
Data integration
-
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
On-premise
-
Cloud
-
-
Functions Outlook (Revenue, USD Billion, 2021 - 2033)
-
Data Collection
-
Data Cataloging
-
Data Quality
-
Data Governance
-
Data Ingestion
-
Data Curation
-
-
Vertical Outlook (Revenue, USD Billion, 2021 - 2033)
-
IT and Telecom
-
Retail and E-commerce
-
BFSI
-
Government
-
Healthcare
-
Energy and Utilities
-
Transportation
-
Manufacturing
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Frequently Asked Questions About This Report
Key players include SAS Institute Inc.; Tibco Software Inc.; Microsoft Corporation; International Business Machines Corporation; SAP SE; Salesforce, Inc.; Qlik Technologies Inc.; Alteryx, Inc.; Oracle Corporation; Strategy Inc.
The global data preparation tools market is expected to grow at a CAGR of 12.0% from 2026 to 2033, reaching USD 21.3 billion.
The global data preparation tools market is expected to grow at a CAGR of 16.1% from 2023 to 2030, reaching USD 16.8 billion by 2030.
North America dominated with a 34.0% revenue share in 2025.
Cloud dominated the data preparation tools market with a share of 53.5% in 2025.
About the Author(s)
IT Services & Applications Research Team
Technology · IT Services & ApplicationsThis report was authored by the it services & applications research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the it services & applications segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


