
- Home
- »
- Medical Devices
- »
-
Dental Consumables Market Size, Share Report 2026-2033GVR Report cover

Dental Consumables Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Dental Implants, Crowns & Bridges, Dental, Orthodontic, Endodontic, Periodontic, Dentures), By Specialty (General, Pediatric, Endodontics, Oral Surgery), By End-use, By Region, And Segment Forecasts
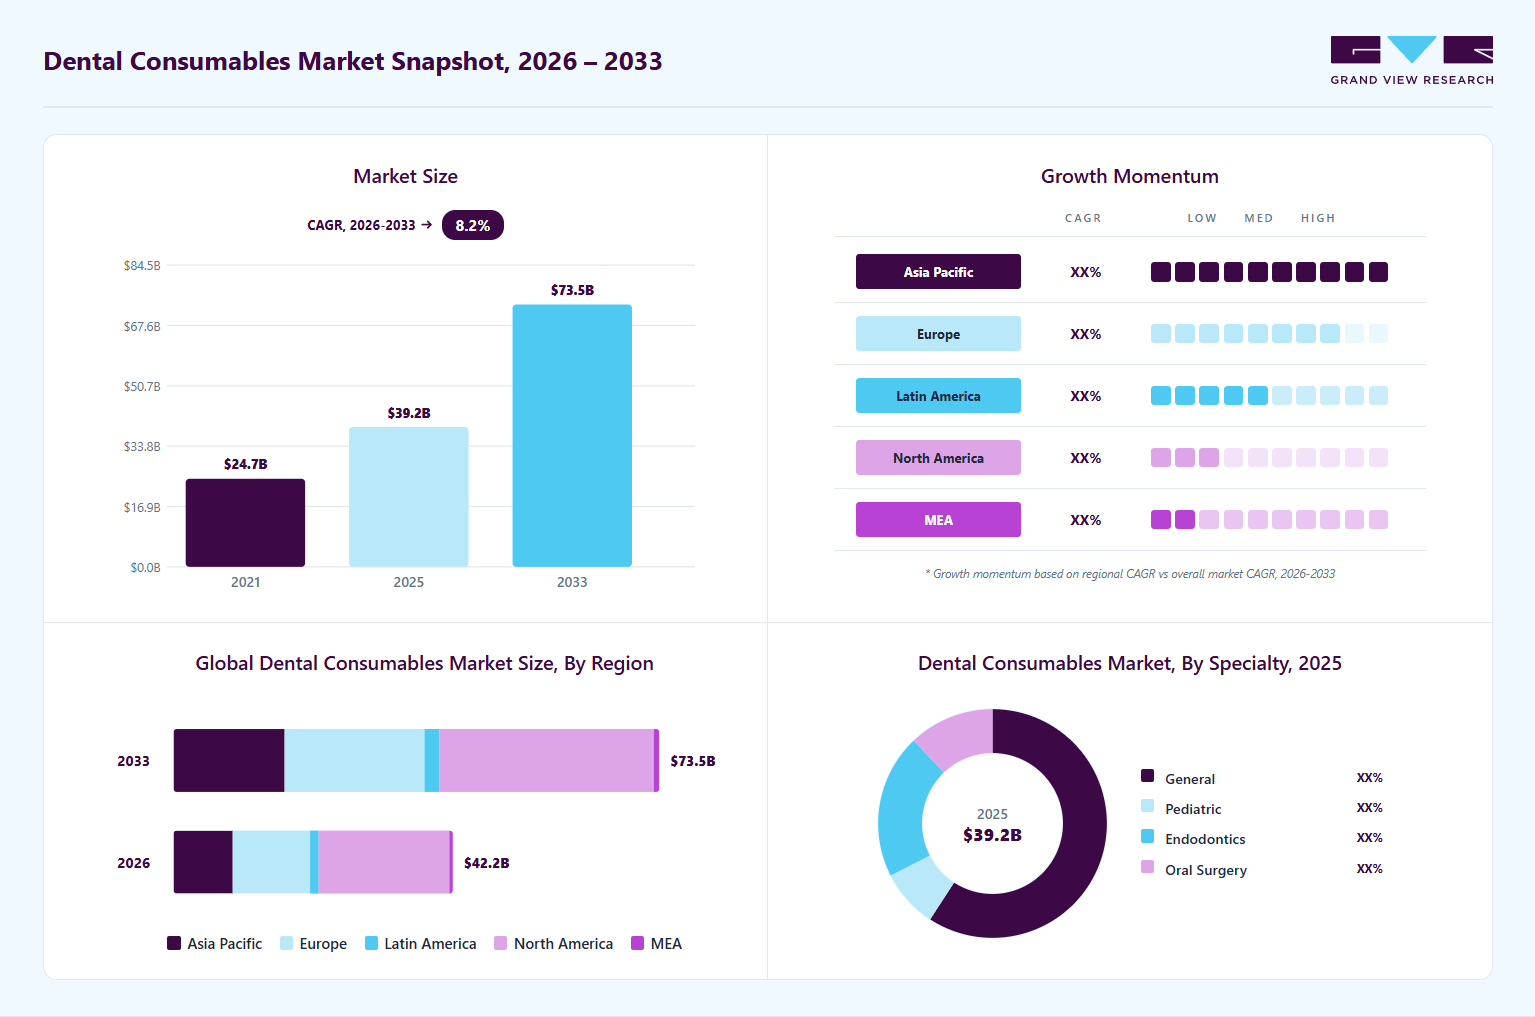
Market Size, 2025
$39.2BMarket Estimate, 2026
$42.2BMarket Forecast, 2033
$73.5BCAGR, 2026–2033
8.2%Dental Consumables Market Summary
The global dental consumables market size was valued at USD 39.2 billion in 2025 and is projected to grow from USD 42.2 billion in 2026 to USD 73.5 billion by 2033, growing at a CAGR of 8.23% from 2026 to 2033. North America dominated the dental consumables market with the largest revenue share of 47.17% in 2025. This growth is attributed to the rising prevalence of dental disorders, increasing awareness about oral hygiene, technological advancements in dental materials, a growing elderly population, and higher demand for cosmetic dentistry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: The dental implants segment led the market with the largest revenue share of 17.3% in 2025.
- By specialty: The general segment led the market with the largest revenue share of 59.2% in 2025.
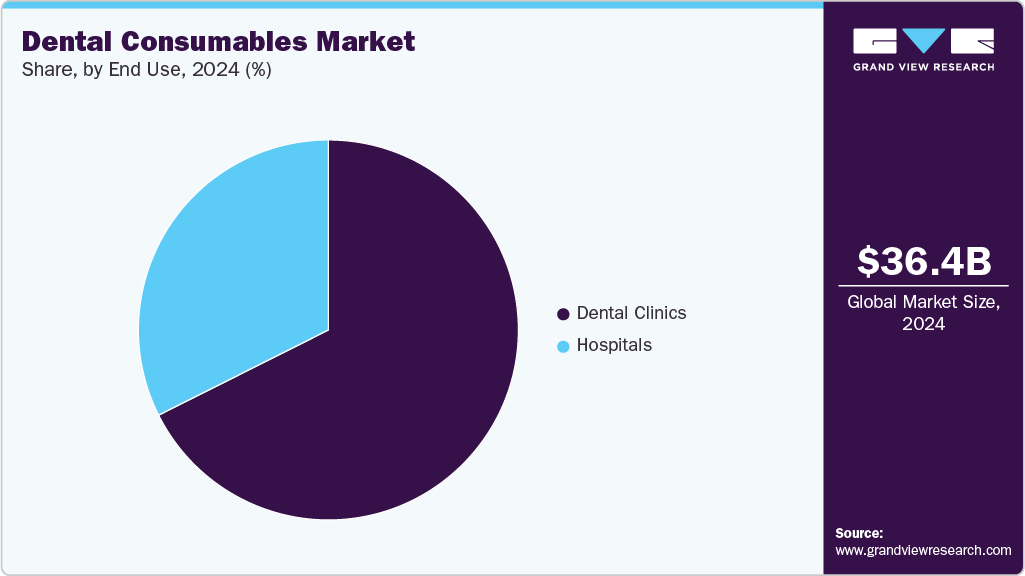
- By end use: The dental clinics segment led the market with the largest revenue share of 67.8% in 2025.
Regional Highlights
- Largest regional market: North America (47.17% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The dental consumables industry in the U.S. held the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 39.2 Billion
- Estimated market size in 2026: USD 42.2 Billion
- Projected market size by 2033: USD 73.5 Billion
- CAGR (2026-2033): 8.23%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, expanding dental tourism, particularly in emerging economies, and increased investments in dental infrastructure further support market expansion. According to data published by the WHO in March 2025, oral diseases affect an estimated 3.7 billion people. The increasing prevalence of dental caries and tooth decay is a key driver of growth in the global dental consumables market. Dental decay remains one of the most widespread chronic conditions, affecting billions worldwide, particularly children, adolescents, and older adults.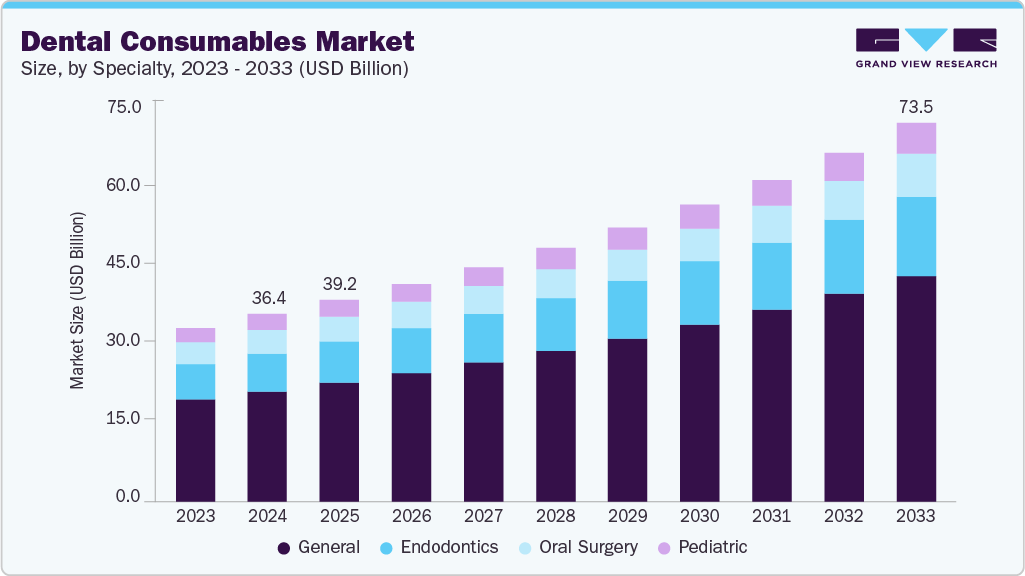 To learn more about this report, Download Free Sample Report
Factors such as poor dietary habits, high sugar consumption, inadequate oral hygiene, and limited access to preventive dental care in low- and middle-income countries have contributed to a surge in untreated dental cavities. This rising burden of dental disease has led to greater demand for restorative dental procedures, such as fillings, crowns, root canal treatments, and extractions, which require a high volume of consumables, including dental cements, bonding agents, composite resins, impression materials, and dental amalgams. Furthermore, the growing awareness of oral health and its link to systemic health has driven increased use of preventive consumables, such as fluoride varnishes, sealants, and desensitizing agents, as the number of patients requiring treatment increases. For instance, according to data published by the CDC in May 2024, over 50% of children between the ages of 6 and 8 have at least one cavity in their primary teeth, a trend that persists into adolescence, with a similar percentage of 12 to 19-year-olds experiencing cavities in their permanent teeth.
“Women, as the primary caregivers to children, have a great influence on their development. With the right empowerment tools, women have the potential to play a positive role in yielding desirable oral health outcomes”. Dr Khabiso Ramphona, a specialist in community dentistry at the University of the Western Cape and the Chair of the Public Health Association of South Africa, Dental Public Health Special Interest Group.
Projected Oral Health Trends in the UK
Condition / Population Group
2050 (Projected)
People living with gum disease
54% of the population
People with signs of gum disease (gum pockets, tissue loss)
28 million
People with gum tissue loss alone
~21 million
Adults aged 16-59 with tooth decay
15.5 million
Adults aged 60+ with tooth decay
9.6 million
Source: Adult Dental Health Survey (ADHS)
Technological advancements driving the market include developing next-generation dental implant systems for improved osseointegration, surgical efficiency, and immediate loading protocols. Innovations such as deep conical connections, enhanced macro designs, and proprietary implant-abutment interfaces enable greater primary stability, even in challenging bone conditions. These advancements support minimally invasive procedures, reduce treatment time, and improve long-term prosthetic outcomes - thereby increasing the adoption of advanced implants and associated consumables across diverse clinical settings.
-
In July 2024, BioHorizons recently introduced the Tapered Pro Conical implants, marking the company's first dental implant line with a deep conical connection. These new implants are built on the macro design of the Tapered Pro series and incorporate the patented CONELONG connection, designed to streamline surgical procedures.
“Backed by more than 30 years of research, Tapered Pro Conical’s unique Laser-Lok microchannels create a connective tissue attachment and retain crestal bone, thus allowing better control of clinical and esthetic outcomes,” said Steve Boggan, President & CEO, BioHorizons. “We recognize the importance of immediate and predictable solutions for implant therapy and are pleased to deliver enhanced functionality with this new implant.”
The increase in dentists worldwide contributes to expanding the dental consumables market. As more dental professionals enter the workforce, particularly in emerging economies and urban areas, the volume of dental procedures performed rises, leading to higher consumption of materials such as restorative products, preventive consumables, and infection control items. Furthermore, new dental clinics and practices are being established to accommodate growing patient demand, increasing the procurement of single-use items and diagnostic tools, all of which are part of the consumables market. In developed regions, the trend toward practice consolidation and group dental practices also promotes bulk purchasing of advanced consumables and adoption of digital dentistry, thereby boosting demand for high-quality, tech-compatible materials.
Registration in Dental Care by Type in UK (2025)
Registration Type
Male
Female
Gender Unknown
Total
Orthodontic Therapist
70
1,096
0
1,166
Dentist
21,339
24,276
5
45,620
Dental Therapist
1,106
6,303
0
7,409
Dental Technician
3,502
1,522
0
5,024
Dental Nurse
1,158
64,098
0
65,256
Dental Hygienist
937
9,578
0
10,515
Clinical Dental Technician
373
69
0
442
Total
28,485
106,942
5
135,432
Source: GDC UK
As a result, the rising burden of dental diseases, continuous technological advancements in treatment solutions, and the expanding global dental workforce are collectively accelerating demand for dental consumables. Increased awareness of oral health, along with growing access to dental care services, is further strengthening procedure volumes and supporting sustained market growth.
Market Dynamics
The dental consumables market is driven by the increasing prevalence of dental disorders, such as dental caries, periodontal diseases, and tooth loss, as well as by growing awareness of oral health and preventive dental care. The rising demand for cosmetic and restorative dentistry procedures, including teeth whitening, crowns, bridges, implants, and orthodontic treatments, is further driving market growth. Technological advancements in dental materials, such as biocompatible restoratives, digital dentistry solutions, and advanced impression materials, are enhancing treatment outcomes and patient satisfaction. In addition, expanding access to dental services, increasing healthcare expenditure, and the growing adoption of minimally invasive dental procedures are contributing to market expansion.
The increasing prevalence of dental caries and tooth decay is a key driver of growth in the global dental consumables market. Dental decay remains one of the most widespread chronic conditions, affecting billions worldwide, particularly children, adolescents, and older adults. Factors such as poor dietary habits, high sugar consumption, inadequate oral hygiene, and limited access to preventive dental care in low- and middle-income countries have contributed to a surge in untreated dental cavities. This rising burden of dental disease has led to greater demand for restorative dental procedures, such as fillings, crowns, root canal treatments, and extractions, which require a high volume of consumables, including dental cements, bonding agents, composite resins, impression materials, and dental amalgams. Furthermore, the growing awareness of oral health and its link to systemic health has driven increased use of preventive consumables, such as fluoride varnishes, sealants, and desensitizing agents, as the number of patients requiring treatment increases. For instance, according to data published by the CDC in May 2024, over 50% of children ages 6 to 8 have at least one cavity in their primary teeth, a trend that persists into adolescence, with a similar percentage of 12- to 19-year-olds experiencing cavities in their permanent teeth.
The high cost of dental treatments is a significant factor restraining the growth of the dental consumables market, as it reduces the affordability and accessibility of dental care for a large patient population. Procedures that rely on advanced consumables, such as dental implants, crowns, bridges, orthodontic aligners, and aesthetic restorations, involve substantial treatment costs. In many countries, dental services are only partially covered or excluded from health insurance plans, requiring patients to pay out of pocket. Thus, many individuals postpone or avoid non-emergency, cosmetic, and even restorative dental procedures due to financial constraints. This limits the consumption of dental materials and products used by dental professionals. The challenge is particularly evident in developing and low-income regions, where cost sensitivity remains high, ultimately restricting procedure volumes and slowing market growth.
Technological advancements in dental materials and digital dentistry are creating substantial growth opportunities for the dental consumables market by enhancing the quality, efficiency, and precision of dental treatments. Innovations such as computer-aided design and computer-aided manufacturing (CAD/CAM) systems, intraoral scanners, 3D printing technologies, and digital treatment planning software are transforming dental workflows and increasing the demand for advanced consumables. Modern restorative materials, including high-strength ceramics, bioactive materials, advanced composite resins, and improved dental adhesives, offer greater durability, aesthetics, and biocompatibility, leading to better clinical outcomes and higher patient satisfaction. In addition, the growing adoption of clear aligners, customized prosthetics, and digitally manufactured crowns and bridges is driving the need for specialized dental consumables. Continuous research and development by manufacturers are yielding innovative products that reduce treatment time, improve procedural accuracy, and support minimally invasive dentistry.
For instance, In July 2024, BioHorizons recently introduced the Tapered Pro Conical implants, marking the company's first dental implant line with a deep conical connection. These new implants are built on the macro design of the Tapered Pro series and incorporate the patented CONELONG connection, designed to streamline surgical procedures.
Market Concentration & Characteristics
The market is consolidated, with a few leading manufacturers accounting for a substantial share due to their extensive product offerings, strong brand presence, and established distribution channels. However, the market also includes numerous regional and niche players, creating a competitive environment in which innovation, pricing strategies, and product differentiation are key to maintaining and expanding market share.
The market shows a moderate to high degree of innovation, primarily driven by advancements in materials science, digital technology, and patient-centric care. Manufacturers incorporate bioactive and nanomaterials into restoratives and cements to enhance biocompatibility, durability, and aesthetics. Integrating CAD/CAM systems and 3D printing has revolutionized the customization of crowns, bridges, and prosthetics, significantly improving treatment efficiency and precision. In addition, innovation in regenerative materials, such as scaffolds and growth factor-based products, is expanding the scope of periodontal and surgical procedures. Preventive care is also evolving, with the development of antimicrobial coatings and enhanced formulations in hygiene products aimed at reducing infection risks and improving patient outcomes. For instance, in January 2024, Dbridge India, a subsidiary of South Korea’s Dental Bridge Co., introduced the ‘DoctorBridge’ platform to connect medical device manufacturers directly with end-users, particularly healthcare professionals.
 To learn more about this report, Download Free Sample Report
The level of M&A activity in the market is moderate but increasing, driven by the need for portfolio expansion, technological advancement, and global market reach. Major industry players are actively acquiring smaller firms specializing in digital dentistry, implant systems, and biocompatible materials. These acquisitions help consolidate market presence and offer access to innovative technologies. In January 2026, Benco Dental strengthened its collaboration with Dentsply Sirona to expand access to advanced dental technologies in the U.S. market. Through this partnership, Benco began providing a broad portfolio of Dentsply Sirona’s connected solutions, including CEREC systems and blocks, Primescan and Primescan 2 intraoral scanners, as well as imaging systems such as Axeos and Orthophos, enhancing digital dentistry capabilities for clinicians.
“We welcome our customers to experience Dentsply Sirona with the premium shopping experience that only Benco Dental’s CenterPoint showrooms can provide,” said Katy Cohen, President of Benco Dental. “Our relaxed, no-pressure, fully interactive demonstration facilities are enhanced by the unparalleled knowledge of our Benco Dental Equipment Specialists who are dedicated to inspiring, educating and engaging doctors with world-class possibilities.”
“We’re excited to expand our successful partnership with Benco Dental. This new agreement underscores our commitment to meeting customers where they are, supporting their digital journey, and ensuring they have easy access to integrated, high-quality solutions and fast, reliable support to help them grow and advance their practices with confidence,” said Aldo Denti, Executive Vice President and Chief Commercial Officer, Dentsply Sirona.
Regulations significantly impact the market, influencing product development, approval timelines, and market entry strategies. In regions such as the European Union, the introduction of the Medical Device Regulation (MDR) has increased compliance requirements, especially for Class IIa and IIb dental materials, leading to higher costs and extended approval processes. Similarly, in markets such as the U.S., FDA regulations mandate strict safety and efficacy standards, particularly for materials in direct contact with oral tissues. These regulatory frameworks ensure patient safety but can also pose barriers for smaller manufacturers and delay the launch of innovative products.
The threat of product substitutes in the market is moderate, varying by product category and technological advancement. For instance, traditional amalgam fillings face substitution from composite resins and glass ionomer cements due to growing patient preference for aesthetic and mercury-free alternatives. In orthodontics, clear aligners replace conventional braces, while digital impressions gradually substitute traditional impression materials.
Analyst Perspective
The dental consumables market benefits from recurring demand fundamentals that are largely independent of capital equipment replacement cycles. Growth is supported by increasing dental procedure volumes, expanding access to oral healthcare, rising adoption of implantology and aesthetic dentistry, and the continuous need for consumable replenishment across clinical settings. Unlike dental equipment markets, consumables generate repeat purchasing driven by treatment activity rather than capital budgets. The most advantaged manufacturers will be those that build comprehensive product portfolios spanning restorative, preventive, endodontic, orthodontic, and implant procedures while strengthening distribution reach and clinician loyalty. As treatment volumes continue to expand globally, market leadership will increasingly depend on product breadth, supply reliability, and integration across the clinical workflow.
Product Insights
Based on product type, the dental implants segment led the market with the largest revenue share of 17.3% in 2025, and dental biomaterials are expected to grow at the fastest CAGR over the forecast period. Dental implants are medical devices designed to replace missing tooth roots by being surgically embedded into the jawbone. Made from biocompatible materials like titanium, they provide a sturdy foundation for attaching artificial teeth, such as crowns or bridges. These implants mimic the function and structure of natural tooth roots, offering a permanent and stable solution for tooth replacement, enhancing both functionality and appearance.
The dental biomaterials segment is expected to grow at the fastest CAGR, driven by rising demand for advanced restorative and regenerative dental procedures. Increasing patient preference for aesthetic, durable, and biocompatible materials has accelerated the adoption of bioactive ceramics, composites, and bone graft substitutes. Technological advancements in tissue engineering and the growing use of biomaterials in implantology, periodontics, and oral surgery further fuel this growth. In addition, the shift toward minimally invasive procedures and personalized dental care is boosting the development and utilization of next-generation biomaterials, positioning this segment for expansion in the forecast years.
Specialty Insights
Based on specialty, the general segment led the market with the largest revenue share of 59.2% in 2025. General dentistry plays a vital role in educating patients about oral hygiene practices. They guide brushing, flossing, and dietary choices, promoting oral health. In addition, they manage chronic conditions that may affect oral health, such as diabetes or cardiovascular diseases. Technological advancements drive the growth of the market. In March 2024, Desktop Health, the 3D printing division of Desktop Metal, introduced ScanUp, a new initiative to assist dentists in streamlining the adoption of digital dentistry technologies. This program is designed to enhance practice efficiency and elevate patient care.
The endodontics segment is expected to grow at the fastest rate, driven by the increasing prevalence of dental caries and a rising number of root canal procedures globally. Advances in endodontic materials such as bio-ceramic sealers, nickel-titanium files, and enhanced irrigation systems have significantly improved treatment outcomes, safety, and efficiency. The growing demand for tooth preservation, along with greater patient awareness and accessibility to specialist care, is further propelling the segment's expansion. In addition, technological integration - such as digital imaging and rotary instrumentation is streamlining endodontic workflows, making these procedures more precise and appealing to practitioners and patients.
End-use Insights
Based on end-use, the dental clinics segment led the market with the largest revenue share of 67.8% in 2025. The increasing prevalence of dental disorders such as tooth decay, gum disease, and tooth loss drives demand for restorative treatments, including fillings, crowns, and implants. Moreover, the surge in funding and investments in dental care infrastructure, especially in emerging economies, has enabled clinics to adopt advanced techniques. For instance, in 2023, the Wisconsin Department of Health Services (DHS) allocated USD 5.1 million in grants to 14 safety net dental clinics not federally qualified health centers to improve access to dental care nationwide. The total grant funding is USD 1.7 million annually, with individual clinic awards ranging from USD 59,000 to USD 150,000 over three years.
The hospitals segment is expected to grow at a significant CAGR during the forecast period, due to several key factors. The rising incidence of dental diseases globally necessitates advanced solutions within hospitals to manage patient care effectively. Hospitals are often equipped with advanced technology and skilled professionals who can provide comprehensive care, making them the preferred choice for patients seeking dental consumables. Moreover, emergency hospital visits for avoidable oral health issues have surged significantly over the past years, with most of these visits occurring among young adults and low-income individuals. For instance, according to the American Dental Association, there are around 2 million hospital emergency department visits in the U.S. In addition, the growing emphasis on patient safety and comfort during dental procedures is influencing the operational strategies of dental hospitals. With a focus on minimizing patient anxiety and ensuring successful outcomes, hospitals are investing in high-quality dental consumables that offer better results and usability. Furthermore, many dental hospitals now offer a range of services, including periodontics and orthodontics, allowing for coordinated treatment plans that address various aspects of oral health.
Regional Insights
North America dominated the dental consumables market with the largest revenue share of 47.17% in 2025, owing to an increased prevalence of dental diseases and the rising demand for dental procedures among the aging population. As per dental statistics by the Centers for Disease and Prevention (CDC) in October 2024, around 10% of adolescents, 12 to 19 years of age, possess at least one untreated cavity in their permanent teeth, whereas nearly 20% of adults 20 to 64 aged have at least single unprocessed cavity as well. The occurrence of untreated cavities is often more pronounced in specific demographic groups, influenced by factors such as race and ethnicity, income levels, and smoking behaviors.
 To learn more about this report, Download Free Sample Report
U.S. Dental Consumables Market Trends
The dental consumables market in the U.S. held the largest share in the North America region in 2025. The dental consumables market in the U.S. is experiencing significant growth, supported by strong demand for preventive, restorative, and cosmetic dental procedures. In addition, increasing adoption of advanced materials, digital workflows, and a growing focus on aesthetic dentistry are driving continuous product innovation and market expansion.
Number of Dentist in U.S.
Year
Total Number of Dentists
Dentists per 100,000 Population
2023
202,304
60.4
2022
202,536
60.8
2021
201,927
60.8
2020
201,117
60.7
Source: American Dental Association & Grand View Research
The growing number of dentists in the U.S. is a key driver of the dental consumables market, as it directly increases the demand for a wide range of dental materials and supplies used in daily practice. As more dentists enter the workforce, particularly in urban and suburban areas, the number of dental procedures performed including restorative, preventive, and cosmetic treatments - correspondingly rises. This expansion supports higher consumption of composites, adhesives, impression materials, and endodontic supplies.
Europe Dental Consumables Market Trends
The dental consumables market in Europe is showing stable growth, supported by strong awareness of oral health and consistent demand for preventive, restorative, and cosmetic dental treatments. Additionally, the increasing use of advanced materials and digital workflows in dental practices is driving evolving product demand and significant market growth. For instance, in August 2021, Botiss Biomaterials GmbH received CE approval for the dental magnesium biomaterial NOVAMag. The product will enhance the capabilities of bioresorbable, enabling the replacement over time with natural bone.
The UK dental consumables marketheld a significant share in 2024. The rise in dental caries highlights the need for continued innovation and advancements in healthcare technology to reduce this trend effectively. As more patients seek dental care and awareness of oral health grows, the demand for effective endodontic solutions is rising. For instance, in July 2024, between January and March 2024, 2.56 million adults participated in the GP Patient Survey, sharing their perspectives on NHS dentistry. Advances in technology, such as the development of high-precision instruments and improved imaging techniques, enhance treatment outcomes and patient comfort, further propelling market growth.
Key company initiatives in the UK are significantly driving growth in the dental consumables market by enhancing product accessibility, strengthening distribution networks, and promoting clinical education. For instance, in December 2024, Komet Dental, a global dental innovation company, launched a dedicated sales company to strengthen customer support and deliver customized solutions specifically for the UK market. This strategic step builds on the company's successful dealer collaborations and reinforces its commitment to addressing the distinct requirements of dental professionals.
“The establishment of Komet UK marks a significant milestone in our global growth journey, reinforcing our position as a leading international partner for innovative solutions in the dental sector. As part of the Brasseler Group, we are committed to direct customer engagement to deliver unparalleled support and expertise,” - Carsten Cieslik, Director of the Komet Dental business unit.
Asia Pacific Dental Consumables Market Trends
The dental consumables market in Asia Pacific is witnessing strong growth, supported by increasing awareness of oral hygiene and rising demand for preventive and restorative dental care. In addition, expanding dental infrastructure, rising disposable incomes, and the broader adoption of advanced dental materials are driving sustained market growth across the region. According to DCI figures, in April 2024, India hosts 323 colleges offering Bachelor of Dental Surgery degrees and 279 providing Master of Dental Surgery degrees. In addition, nine institutions offer postgraduate diplomas in various dental specialties, including dental consumables. Furthermore, 111 colleges focus on dental hygiene and mechanics.
China dental consumables market is growing rapidly, driven by rising oral health awareness and demand for restorative and aesthetic dental procedures. In addition, the expansion of private dental clinics and the growing adoption of advanced materials and digital technologies are driving continuous market development. For instance, in March 2024, the Hong Kong Dental Association (HKDA) launched a series of activities to promote oral health in conjunction with World Oral Health Day. As part of these efforts, HK Oral Health Week takes place from May 9 to 14, 2024, during which local dentists provide free oral check-ups and consultations to the public. This initiative, supported by prominent dental organizations, aims to raise public awareness of primary oral healthcare and aligns with the HKSAR Government's commitment to primary health and FDI Vision 2030.
The dental consumables market in Japan is experiencing growth, supported by an aging population and sustained demand for restorative, preventive, and maintenance dental care. In addition, the growing preference for high-quality materials and the gradual shift toward digital, minimally invasive dental procedures are influencing product adoption and market development. For instance, in June 2024, Fujitsu Japan Limited and Kamoenai Village in Hokkaido launched an initiative to enhance dental care awareness. On June 27th and 28th, 2024, they conducted oral checkups for around 40 students, utilizing Fujitsu's Preventive Dentistry Cloud Service to support a proactive dental health approach. This service detects the risk of tooth decay, enabling students and their guardians to track results on their smartphones and encouraging personal oral health awareness. Furthermore, the Japanese dental industry's commitment to high standards of care and the integration of digital dentistry are enhancing the precision and success rates of dental consumables procedures.
The India dental consumables market is experiencing significant growth. The surge in dental disorders and growing awareness about oral hygiene primarily drive the need for advanced dental consumables treatments. With its increasing disposable income, India's burgeoning middle class is more inclined to invest in healthcare, including elective dental procedures. The rise in dental tourism further supports this demographic shift. According to a Medical Buyer article published in July 2024, medical tourism in India is expected to reach approximately 7.3 million visitors in 2024, up from 6.1 million in 2023. Ranked 10th among 46 countries on the Medical Tourism Index for 2021-22, India is already the second-largest medical tourism hub in Asia. This growth presents a significant opportunity for expanding the market as more international patients seek dental care. Consequently, these dynamics foster a conducive environment for the proliferation of dental consumables.
Latin America Dental Consumables Market Trends
The dental consumables market in Latin America is growing and is primarily driven by the increasing prevalence of dental diseases and a growing dental health awareness among the population. For instance, in November 2023, as per a study on Global excellence in dental medicine: South America, 18,172 scientific articles in Dentistry were published globally. Brazil contributed the highest number at 1,698 followed closely by the U.S. with 1,682. Of these, 2,321 articles originated from Latin America, with Brazil representing 73.15% of this output across 23 countries. Regarding the H-index, Brazil ranks 3rd among the top 50 countries in Dentistry with an H-index of 158. Other South American nations include Chile at 35th (H-index 56), Colombia at 39th (H-index 48), and Argentina at 44th (H-index 42).
Middle East & Africa Dental Consumables Market Trends
The dental consumables market in the MEA region is experiencing gradual growth, supported by rising awareness of oral health and increasing demand for preventive and restorative dental treatments. Improving access to dental care and ongoing investments in healthcare infrastructure, particularly in Gulf countries, are driving product adoption. In addition, the growing presence of private dental clinics and a shift toward aesthetic dentistry are contributing to significant market expansion. For instance, in May 2024, the Saudi Dental Society announced various activities during World Oral Health Day (WOHD) 2024 in Saudi Arabia to enhance the general public's understanding of oral health and promote the proactive management of chronic oral conditions and diseases. These initiatives, coupled with the growing prevalence of dental disorders among the Saudi population, are propelling the demand for endodontic services and, consequently, the devices associated with them.
Key Dental Consumables Company Insights
Some of the key players operating in the industry include Dentsply Sirona, Straumann Holding, and Henry Schein, Inc. The company’s key strategies include understanding the strengths and weaknesses of major market participants, anticipating future market trends, opportunities, and challenges, and making proactive decisions based on insights into emerging technologies and changing consumer preferences. For instance, Ivoclar and Benco Dental are emerging players in dental consumables.
Key Dental Consumables Companies
The following key companies have been profiled for this study on the dental consumables market.
-
Dentsply Sirona
-
Straumann Holding
-
Septodont Holding
-
Komet Dental (Brasseler GmbH & Co. KG group)
-
3M
-
Zimmer Biomet
-
Ivoclar
-
Coltene Group
-
Prime Dental Products Pvt. Ltd.
-
Envista Holdings Corporation (Danaher Corporation)
-
GC Asia Dental
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Dentsply Sirona, Straumann Holding, Septodont Holding, 3M, Zimmer Biomet)
- Expand integrated digital dentistry ecosystems through collaborations with dental clinics, laboratories, academic institutions, and digital workflow technology providers to enhance treatment efficiency and patient outcomes.
- Invest in AI-enabled treatment planning, CAD/CAM solutions, 3D printing technologies, and advanced dental materials while strengthening distribution networks and expanding presence across emerging dental care markets.
- Strong brand recognition, extensive global distribution networks, and long-standing relationships with dental professionals, clinics, and laboratories.
- Advanced research and development capabilities, diversified product portfolios spanning restorative, orthodontic, implant, and digital dentistry solutions, and continuous innovation in dental materials and technologies.
- High operational and manufacturing costs, leading to premium product pricing that may limit adoption in price-sensitive and emerging markets.
- Complex organizational structures and extensive product portfolios can slow decision-making, reduce agility in responding to market changes, and delay the commercialization of innovative dental solutions.
Emerging Players (Prime Dental Products Pvt. Ltd.)
- Focus on niche and high-growth segments such as cosmetic dentistry, digital orthodontics, preventive oral care, and cost-effective restorative solutions to build strong market entry points.
- Leverage digital marketing channels, distributor partnerships, and direct-to-dentist engagement models, supported by competitive pricing strategies and localized product offerings to accelerate adoption in emerging and price-sensitive markets.
- Faster product development cycles and a strong focus on underserved and niche dental segments, enabling quicker adaptation to evolving clinical needs and market gaps.
- High operational agility with rapid adoption of digital technologies, enabling cost-effective, user-centric solutions and improved responsiveness to changing customer and practitioner demands.
- Limited brand recognition and a smaller global footprint can erode trust among dental professionals and limit adoption in established healthcare networks.
- Constrained financial resources and weaker R&D capabilities limit their ability to scale innovation, expand product portfolios, and compete with established multinational companies.
Recent Developments
-
In January 2026, Benco Dental, one of the largest family-owned dental companies in the U.S., expanded its partnership with Dentsply Sirona, a global company in professional dental products and technologies. As part of this collaboration, Benco Dental began offering Dentsply Sirona’s comprehensive range of connected technology solutions to U.S. customers, including the CEREC system and blocks, intraoral scanners such as Primescan and Primescan 2, and advanced imaging systems like Axeos and Orthophos.
-
In April 2025, DD Products and Services Ltd. announced the acquisition of Eli-Dent, a prominent dental consumables supplier based in Borgo San Lorenzo, Tuscany. Eli-Dent serves over 7,000 dental professionals across Italy, offering various products including consumables, pharmaceuticals, and small equipment. The acquisition strengthens DD Group’s presence in the European market. It enhances its portfolio by adding a trusted local player with deep market reach and established relationships with leading dental brands.
-
In January 2025, Septodont Inc. and Premier Dental launched BufferPro, an 8.4% sodium bicarbonate buffering solution designed to streamline the administration of local anesthetics in dental procedures. BufferPro offers a one-step, sterile, single-use capsule containing 0.1 mL sodium bicarbonate, which raises the pH of anesthetic cartridges to near physiological levels, enhancing onset time and reducing procedural discomfort.
-
In April 2024, Ivoclar Group, a key manufacturer of integrated solutions for high-quality dental treatments, revealed its partnership with SprintRay, a U.S.-based technology company. This collaboration aims to establish new benchmarks in 3D printing within the dental industry, enhancing the capabilities available to dentists, dental technicians, and hygienists.
-
In August 2024, Dentsply Sirona introduced the X-Smart Pro+ and Reciproc Blue in the U.S., offering a streamlined, one-file solution for endodontic procedures. This launch aims to simplify root canal treatments by providing a highly efficient and reliable system.
Dental Consumables Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 39.18 billion
Estimated Market Size in 2026
USD 42.24 billion
Projected market size by 2033
USD 73.46 billion
Growth rate
CAGR of 8.23% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, end-use, specialty, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Dentsply Sirona, Straumann Holding, Septodont Holding, Komet Dental (Brasseler GmbH & Co. KG Group), 3M, Zimmer Biomet, Ivoclar, Coltene Group, Prime Dental Products Pvt. Ltd., Envista Holdings Corporation, GC Asia Dental, among others
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dental Consumables Market Report Segmentation
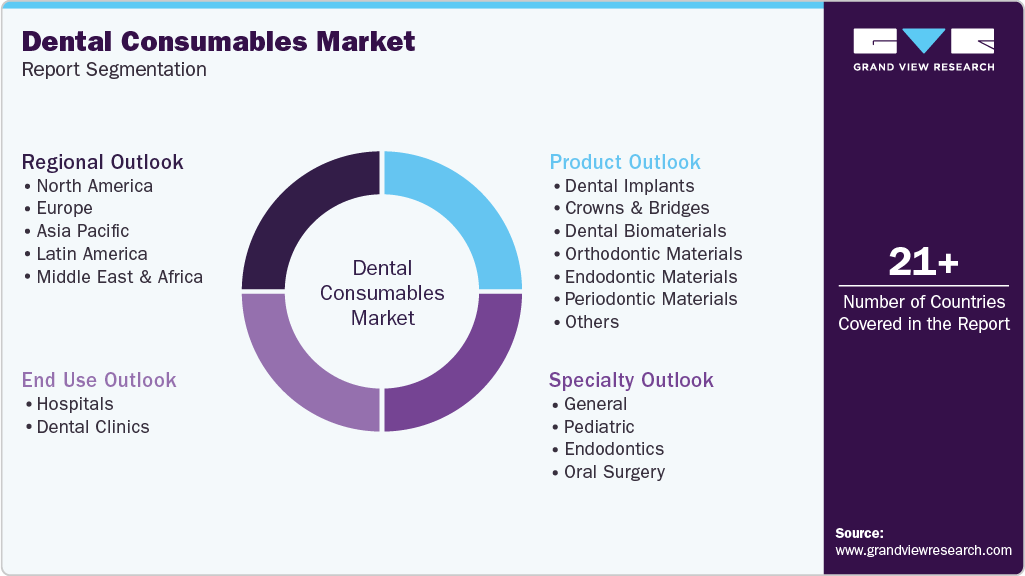
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dental consumables market report based on product, specialty, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Dental Implants
-
Crowns & Bridges
-
Dental Biomaterials
-
Orthodontic Materials
-
Endodontic Materials
-
Periodontic Materials
-
Dentures
-
CAD/CAM Devices
-
Retail Dental Hygiene Essentials
-
Others
-
-
Specialty Outlook (Revenue, USD Million, 2021 - 2033)
-
General
-
Pediatric
-
Endodontics
-
Oral Surgery
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Dental Clinics
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
Segment Definition
Segment - Type
Revenue capture definition
Dental Implants
Revenue is generated from the sale of implant fixtures, abutments, prosthetic attachments, and related accessories used in permanent tooth replacement procedures. Demand is supported by increasing adoption of implant-based restorations, growing aesthetic dentistry preferences, and the rising prevalence of tooth loss among adults and elderly populations.
Crowns & Bridges
Revenue is generated from crowns, bridges, and associated restorative materials used to repair damaged teeth and replace missing teeth. Growth is driven by increasing restorative dental procedures, advancements in prosthetic materials, and rising demand for durable, functional, and aesthetically appealing dental restorations worldwide.
Dental Biomaterials
Revenue is earned from composites, cements, adhesives, liners, bone grafts, and regenerative materials used in restorative and surgical dentistry. Market demand is supported by technological advancements in materials science, rising dental treatment volumes, and the need for durable, biocompatible, and aesthetically pleasing dental solutions.
Orthodontic Materials
Revenue is earned through brackets, archwires, clear aligners, bands, retainers, and other consumables used in orthodontic treatments. Growth is fueled by rising awareness of dental aesthetics, increasing cases of malocclusion, and expanding adoption of advanced orthodontic correction methods among patients of all ages.
Endodontic Materials
Income is derived from files, sealers, obturation materials, irrigants, and related consumables used in root canal therapy and endodontic procedures. Demand is driven by the increasing prevalence of dental caries and pulp infections, as well as a growing preference for tooth-preserving treatments and procedures.
Periodontic Materials
Revenue is generated from membranes, graft substitutes, tissue regeneration products, and other consumables used in periodontal therapies. Market growth is supported by rising gum disease incidence, increasing awareness of oral health, and growing adoption of regenerative techniques for periodontal treatment and recovery.
Dentures
Revenue is earned from full dentures, partial dentures, denture bases, artificial teeth, and related products used for removable tooth replacement. Growing edentulous populations, an aging population, and the continued need for cost-effective restorative dental solutions across healthcare settings support demand.
CAD/CAM Devices
Revenue is generated from digital dentistry systems and related consumables used to design and manufacture dental restorations. Adoption is increasing due to improved workflow efficiency, enhanced treatment precision, reduced turnaround times, and growing demand for customized crowns, bridges, implants, and prosthetic solutions.
Retail Dental Hygiene Essentials
Revenue is earned from the sale of toothbrushes, toothpaste, mouthwash, dental floss, interdental cleaners, whitening products, and other oral care essentials. Growth is driven by rising oral hygiene awareness, preventive dental care practices, expanding retail availability, and increasing consumer spending on personal healthcare.
Others
Revenue is derived from various specialized dental consumables used in preventive, diagnostic, surgical, and restorative applications that are not included within the major product categories. Market growth is supported by continuous innovations in dental care, increasing procedure volumes, and the expanding range of treatment options available to dental professionals.
Estimation Model
Bottom-Up Estimation
Top-Down Approach
Supply-Side Analysis
Revenue generated from dental consumables is aggregated at country, regional, and global levels. Procedure volumes across restorative, endodontic, implant, orthodontic, preventive, and prosthodontic treatments are analyzed. Product utilization rates and average selling prices (ASPs) are mapped to each procedure, then adjusted based on product mix, treatment penetration, and market share analysis to derive overall market value.
The overall dental care market or oral healthcare expenditure is identified first, and the percentage contribution of dental consumables is estimated through secondary research and expert validation. Product penetration rates, treatment volumes, expenditure patterns, and reimbursement dynamics are analyzed to determine the share attributable to consumables and derive the market value.
Assesses total dental consumables sales, production volumes, distribution networks, average selling prices (ASPs), and manufacturer revenues. Key manufacturers, distributors, private-label suppliers, and regional participants are analyzed using annual reports, company disclosures, import-export statistics, and industry databases to estimate market size and competitive positioning.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Restorative, Preventive & Endodontic Consumables Analysis
Conducted a focused assessment of restorative materials, preventive products, endodontic consumables, impression materials, and infection control products, including utilization trends, product adoption, and procedure-level demand patterns.
Helps stakeholders identify high-demand product categories, evaluate consumption drivers, and assess commercial opportunities across routine and specialty dental procedures.
Dental Procedure Volume & Utilization Trends
Evaluated procedure trends across restorative, orthodontic, implant, prosthodontic, and preventive dentistry, including treatment penetration, product utilization rates, and consumable consumption patterns across care settings.
Provides insights into procedure-driven demand, evolving treatment preferences, and commercially attractive segments to support portfolio planning and market expansion strategies.
Dental Infrastructure & Market Opportunity Assessment
Assessed demand across dental clinics, hospitals, DSOs, academic institutions, and specialty centers, along with distribution channels, procurement dynamics, competitive landscape, and market access considerations.
Supports investment and growth strategies by identifying underserved opportunities, evaluating channel dynamics, and highlighting long-term demand drivers across the dental consumables value chain.
Frequently Asked Questions About This Report
The global dental consumables market size was estimated at USD 39.2 billion in 2025 and is expected to reach USD 42.2 billion in 2026.
The global dental consumables market is projected to grow at a CAGR of 8.2% from 2026 to 2033 to reach USD 73.5 billion by 2033.
Key companies in the global dental consumables market include Dentsply Sirona, Straumann Holding, Septodont Holding, Komet Dental (Brasseler GmbH & Co. KG group), 3M, Zimmer Biomet, Ivoclar are some of the major players in the dental consumables market
Key factors that are driving the market growth include rising prevalence of dental disorders, increasing awareness about oral hygiene, technological advancements in dental materials, a growing elderly population, and higher demand for cosmetic dentistry.
North America dominated the dental consumables market with a 47.2% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The dental implants segment led with a 17.5% revenue share in 2025, while dental biomaterials is the fastest-growing segment.
Dental clinics held the largest revenue share in 2025, while hospitals is the significant-growing end use.
The general segment held the largest revenue share in 2025, while endodontics is the fastest-growing specialty.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


